Aldi - Good news(?)
10 January 2017
Subscribe to this service here.
Much excitement this week, with the 'big' week in retail with results from Morrisons (very shortly), followed by Sainsbury's, M&S and then Tesco at the end of a busy week.
Kantar comes out at 8am too!
Aldi, determined to not to be over shadowed released a press story yesterday about their performance over Christmas, no mention of the like for like performance so the wider figures aren't really worth a great deal.
It's interesting that Aldi felt the need to issue any PR, surely just get on with the core job and continue growing and doing what they do well?
To dispute Clive Black's findings in the Mail seemed odd; just no need to fan the flames so to speak. Analysts are commenting on the market and that will not change, it cannot all be good news.
If Aldi want parity with their larger retailers and want to push their tale of growth in the UK food market, then they have to release the same types of figures across a set period a la the major retailers.
That's the only way to split out growth from the new space versus older space and show true growth. The fact is that growth is slowing in the core estate despite all the new space being put down is significant.
Not only new stores to consider, but a point missed entirely is the impact of store extensions to their estate. A significant number of Aldi stores have been expanded to cope with demand - driving more space growth.
The Aldi premium range Christmas sales growth was another notable tale in the release, a little like 'growth in Turkey sales for Christmas' and 'surprising growth in frozen fruit for Smoothies in January'.
The premium range sales growth tale is nice PR but within context it's perhaps relatively unremarkable.
Firstly, there was a significant number of premium lines ranged for Christmas 2016, the Exquisite range grew to c.30+ lines from 3/4 the year before.
Secondly, the fresh range benefitted from a number of premium products merchandised within the core chilled run for 5/6 weeks - party food, accompaniments and a wide range of Dips (etc) alongside Desserts too.
Ambient, with a great number of premium lines in the Christmas bakery and Confectionery ranges meant the assortment grew further, with that means more space is required too - therefore a sales rise is surely expected.
Given their strong premium work in Frozen and indeed Fresh this year (arguably their best year yet for it) alongside strong sales growth, Is +27% a good result?
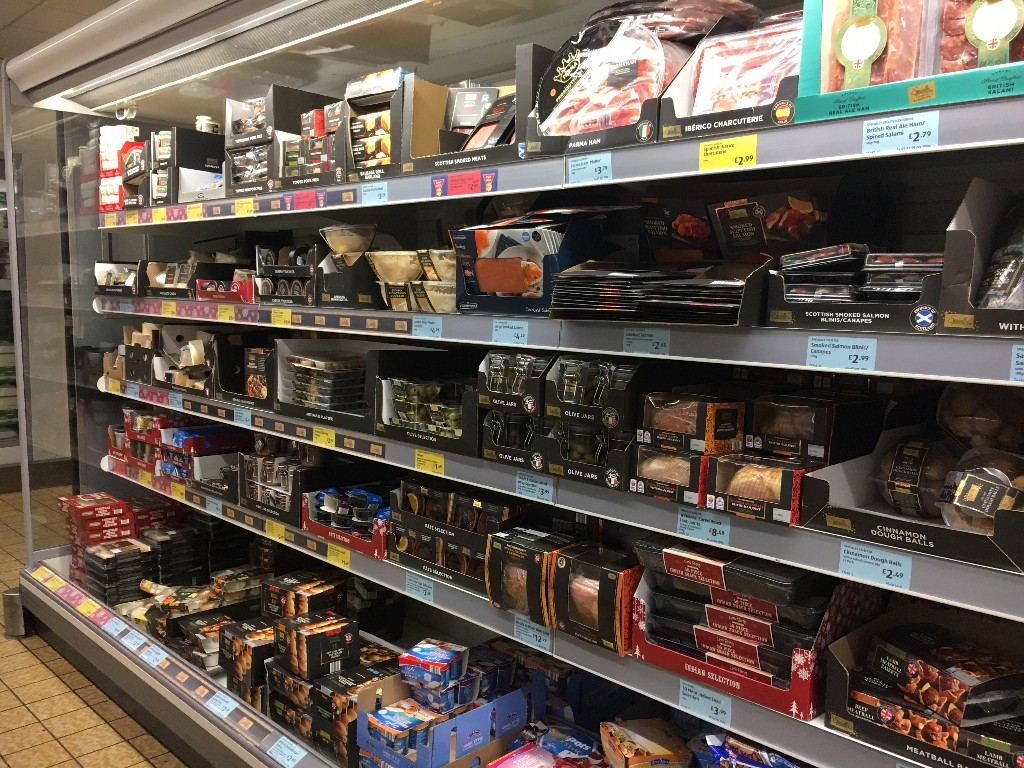
Fair old chunk of premium (black packaging) here in the fresh assortment, again product innovation was strong and they did a good job.
But to bang the drum about a rise in premium is akin to highlighting the rise in sales of Sherry and Port in December. Especially with the focus on the range and also the space given over by Aldi, particularly in Fresh. It's a big space taker.
These lines above are not permanent lines, they're added like seasonal lines are, entirely appropriate of course given the trade levels for Christmas.
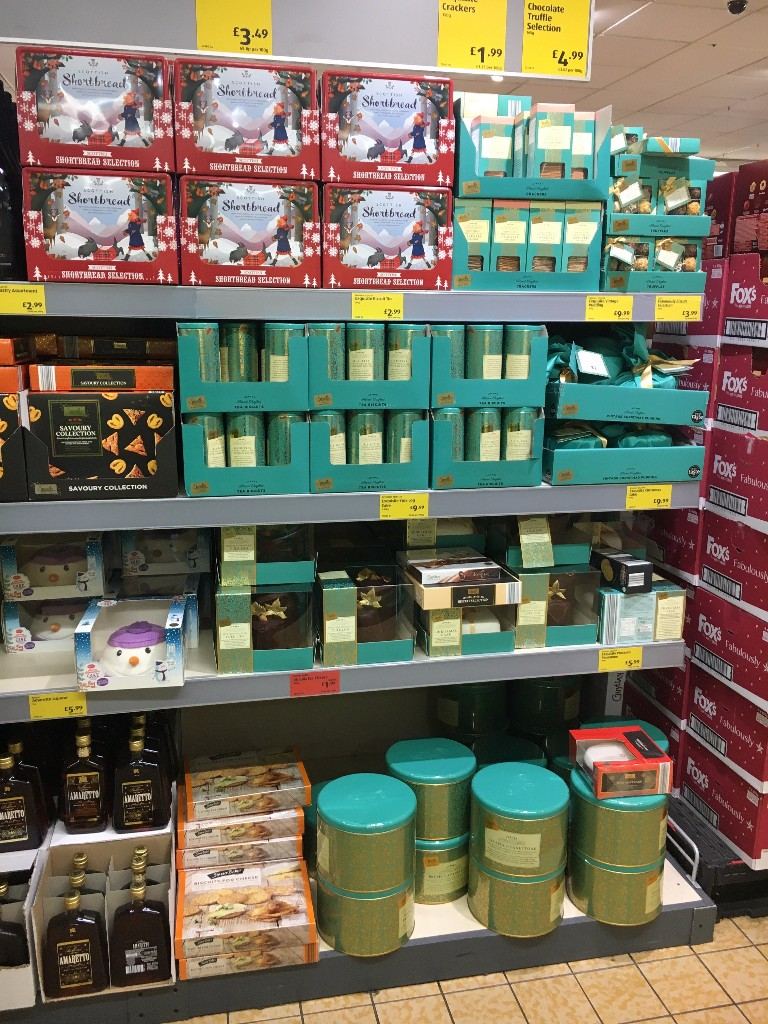
The green/gold based products are the Exquisite range and aligned with Fortnum and Mason and other high end retailers. Some lines appeared to sell well, but in the stores near me - some lines remain on sale well into January.
A step too far perhaps? Again; a representation of where they're aiming for but also again, to highlight just how much their premium ranges grew over the festive period.
Talking of range growth, the premium range for Aldi (Specially Selected) is due to exceed £750m in 2017, again a great achievement but as tracked on here. The range has grown significantly in the past 2/3 years, particularly on fresh foods, where premium pizza can also be accompanied by premium doughballs.
The range creep continues in ambient too, the pillar of simplicity is the limited range choice in Aldi. The branded product existing where there isn't an obvious own label alternative or they're popular lines (Tunnocks Caramel Wafers / Marmite etc).
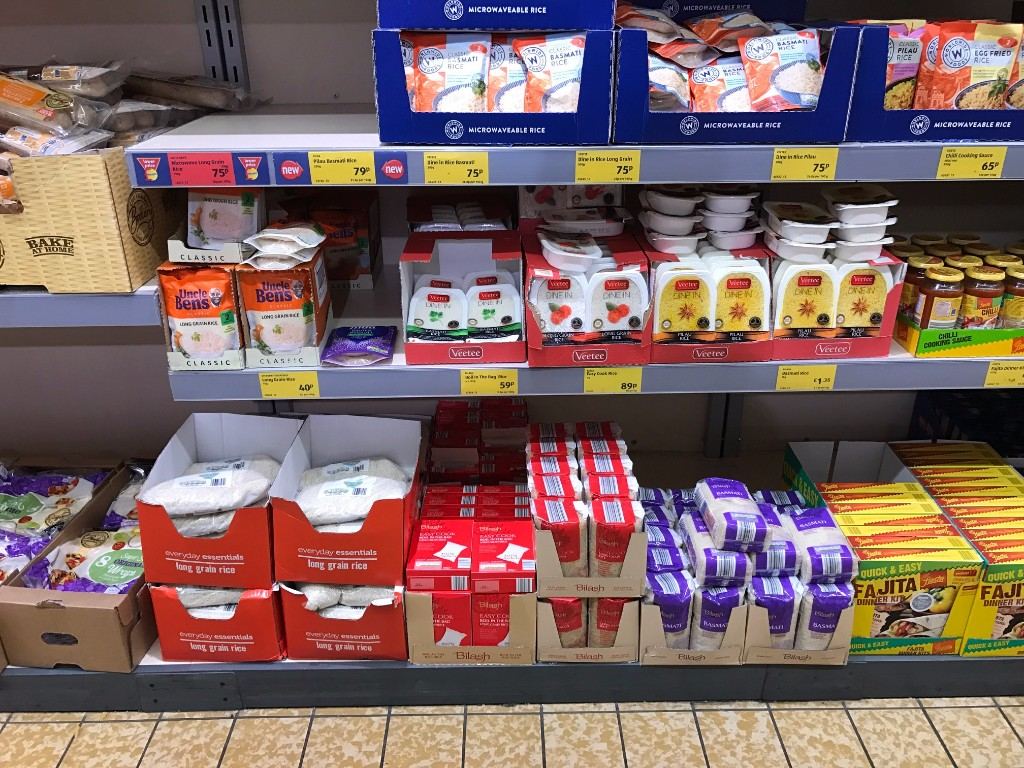
However Uncle Bens, Veetee and even Tilda (new line) point to issues in Rice. Why are so many brands ranged here?
You can buy long grain Rice under everyday essentials value tier, Bilash (own label) with Tilda and Uncle Bens also having one. 4 (four) different ways to buy long grain rice.
Why?
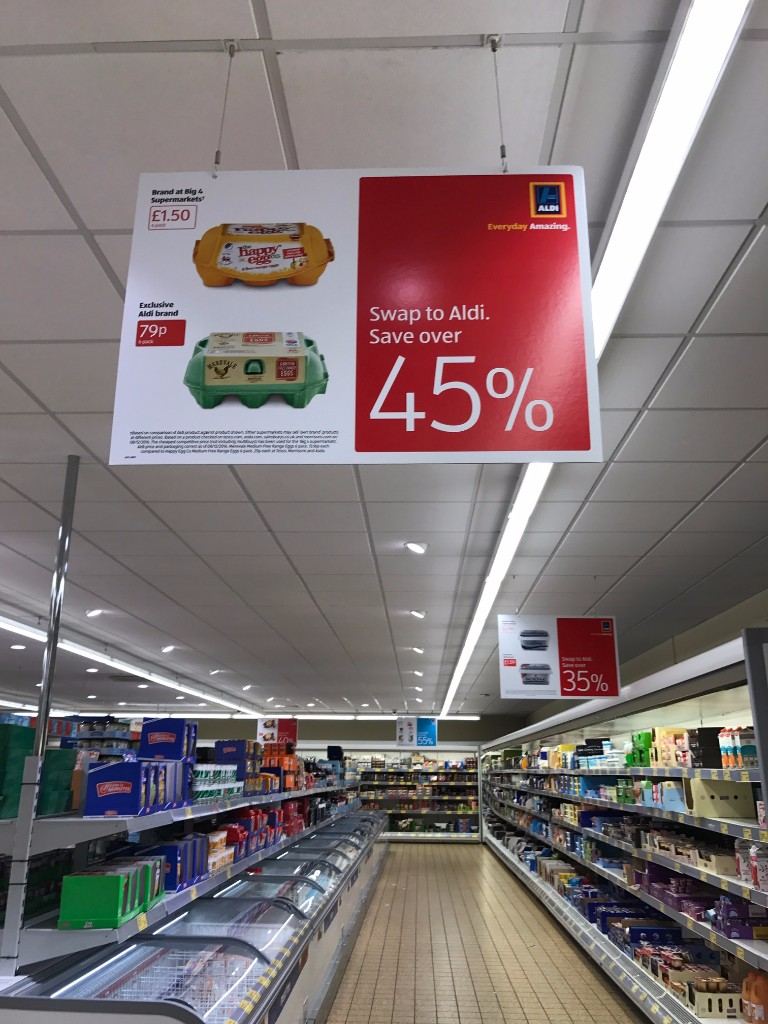
Getting back to the day job, unsurprisingly Aldi have considered their tactics and gone back to the price comparisons again in store, the usual brand versus own label posters.
However they now use the 'big four' as a term to compare the larger supermarkets, meaning it's not actually clear who has price leadership in the 'big four', who are Aldi comparing themselves to?
It's a stretch in itself to compare Norpak to Lurpak but it does resonate with the customers, the Eggs one isn't strictly right though. Happy Eggs as a brand does exist, but the big selling lines in major supermarkets are the own label Eggs, like Aldi.
However, the price gap is narrower. Asda sell 6 free range eggs for 85p. A mere 7.5% more expensive, that wouldn't look as good on the posters....
So fair enough from Aldi; their press story pointed out a lot of good. However one can deduce from their reaction to critique in the press and the release today that this may be stinging a little - but why?
On the face of it, they're putting on decent numbers and their own released figures (not date adjusted notably, so they've taken the entire month of December. Not calendar weeks to purely adjudicate sales performance) are good.
But competition remains fierce in the market, Tesco recovering and pushing back will affect Aldi, I felt it was arguably the strongest in store Christmas feel for Aldi yet - but until they release figures on a like for like basis, adjusted for new space then people will continue to speculate and form judgements based on their own visits to stores.
Why do they want parity with larger supermarket groups in any case? Just crack on with the day job!
Sort that Rice fixture out too.
Email forwarded? Click here to request a service trial.
From the Grocery Insight newsletter archive, first sent to subscribers on 10 January 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.