M&S - Results and plans
10 November 2017
Hot on the heels of the M&S release was an intriguing set of results from Sainsbury’s this week, more on their performance on Monday, where the results will be dissected alongside adding some images too. Of course we have already seen signs of the cost cutting in stores, with a discernible downturn in standards and availability. Not to mention top stocking added in to their model too.....
However for M&S, the results on Wednesday were refreshing in that they finally seem to have someone who is a realist at the helm. Someone who will resolve the fundamental issues within the business, namely, online. For years they ploughed on regardless, adding sub brands, taking sub brands away, adding them in to clothing again and then stop start with online and indeed distribution with the closure of numerous sites and consolidation in to larger units.
Stores were broadly left unchanged, although like everyone else, they added space in the boom, and continued to do so... Not to mention the central costs for the Paddington basin site and the various issues around space there too.
Steve Rowe is a retailer first and foremost, having a real grip of challenges and crucially, a plan for the future. Where clothing will lurch from good to bad, season to season as is their right seemingly. GM/Home proves a struggle in a fragmented market and their under performance here is puzzling.
Kids is another interesting segment. They lead the market on uniform, yet lag the market on kids clothing. Undercut by the likes of George at one end, and the high street retailers at the other end. The focus has been in the wrong areas for many years now around clothing, the slides later via M&S show their potential focus here.
Space is a major challenge for many retailers, particularly Tesco, Sainsbury’s in food and also M&S have issues of their own.
A mixed strategy around which sites to take in the past - whether they were retail park, shopping centre sites with good footfall but expensive rents. The balance of keeping the traditional high street operation despite falling customer numbers, footfall and sales as the shift towards out of town took hold.
The high street operation isn't helped by over zealous council and older units needing more money spending on them too. In the days of tight margins and capital expenditure under massive scrutiny, no one spends on a failing store in the 'hope' a refit will bring people in.... You just impair the store even further.
So for M&S, their store estate programme will be closely looked at, more closures expected? Certainly there is space repurposing going on, where 'full size' stores can still be too big. They're slowing their rate of food openings which is wise, given the near absence of growth there.
Food itself is a puzzle as the product ranges have been good and their Summer range was well thought out and landed well for customers in store.
However the prices were higher this year via inflation and their fresh food exposure meant they were more exposed to the commodity price pressure too. Leading to 'expensive' multibuys across the store....
Given it was Summer, ultimately this was discretionary spend in many cases, especially if the weather wasn't favourable (which it wasn't there was barely a Summer to mention)....
Availability remains improved from some historic lows it has to be said, but it still remains off the pace. Great availability kills waste was a mantra we had at Sainsbury's, and it was vital on fresh to get the availability right, which would drive the right stock forecast and mean you weren't lumbered with, or indeed, out of stock at key times.
The food business isn't broken by any stretch, but the wider reasons to believe need aligning. Whilst the price campaign initially was a slow burner and didn't have a huge impact, a wider message around prices being in focus. Either matched with Sainsbury's or indeed, lower now will help.
Consumer confidence is against them though, as behaviour conditioned in the credit crunch / recession is driving customers to discounters to save money... Discounters who range far more premium now than they ever have, which leads them to directly compete with M&S, amongst others.
But, that aside. There's a lot of work to do 'digging up the drains' so to speak, so slide review from the analyst pack often yields further thoughts.... So on with the show.....
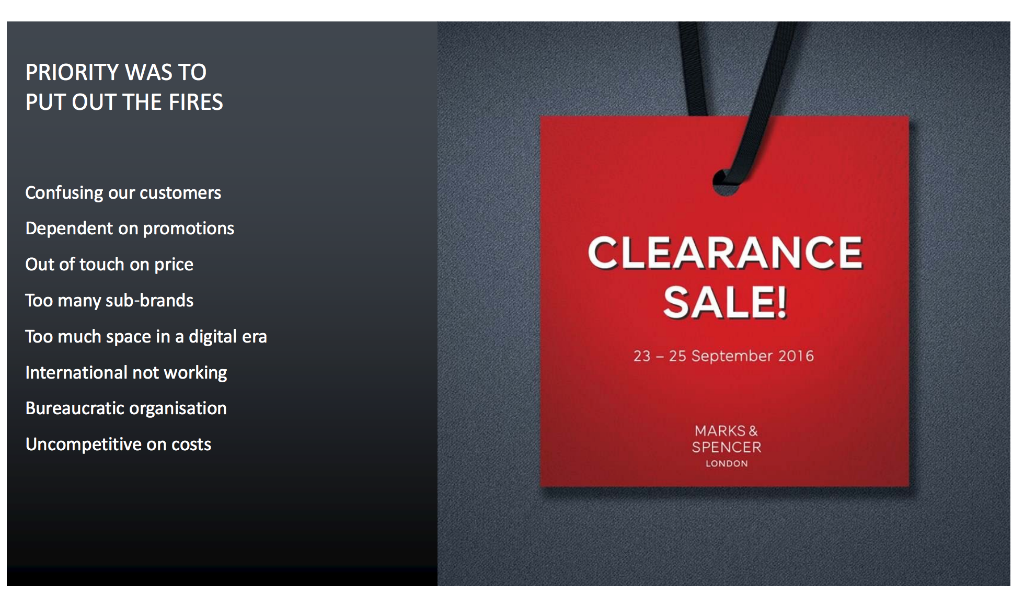
Despite the fact that Steve Rowe did an admirable job on food for many years, one of his other roles was to run other elements of the business, like GM and Clothing too.
Therefore his slides do split the business and it's important to retain this focus, given the food division being spread across franchised sites, stand alone food outlets and the larger units within a wider M&S store.
A lower number of sales in the clothing and GM categories has aided full price sales rates, but does that reduced footfall (how many customers go for a look at a sale?) then impact the food business?
Customer confusion was abound with sub brands going, then returning en masse as M&S went back and forth and could never get off the drug of deal but also the need to add sub brands back in time after time.
Pricing is still out of line in many areas, the fact that M&S are often appealing to a demographic that is both ageing and also not particularly native to digital / online means that they're on a slow boat to oblivion really.
I don't think anyone is thinking that M&S should immediately start imitating the likes of ASOS, Primark and the likes. But the customer perception of value in the lower demographics will change and not necessarily be just about price.
Style forms a part of it, must have and all that. Plus supermarkets are also increasingly entering the fashion arena and affordable everyday clothing is a must. M&S can't do everything but they should be excelling in some areas on clothing.... It's hard to see where they do.
Sub brands are reduced but they still exist and the meaning of them remains a difficult one to grasp. As a stand alone brand, would Per Una work?
Navigation around clothing is often messy and whilst it's currently Paddington, there are examples where a customer walking in to a focus end / 'get the look' display and be forgiven for thinking they were clearing down given the fashion......
One has to wonder where they are with maternity fashion given the focus on kids fashion, M&S isn't a place that expectant mums mention at all.... Even Baby is adrift versus the likes of Next.
Space is a point covered but it's correct, they are over spaced and have spent a fair amount on new stores and builds in recent times, some of which will be expensive and sizeable. Are they getting the rewards here?
Some of the older stores in the high street both close at 6, and have a food outlet attached too. The footfall won't be huge here anyway, but the large shop is a hard one to attain given the customer will arrive to the store on foot for the most part.
International just seemed to be an idea that they had to satisfy the City for the most part. It was never going to be a 'take over' the world effort as the costs are too high.
The time to adapt to local market tastes, find sites, accept costs on sites that won't work and then continue to expand becomes a distraction, an expensive distraction.
When you consider the efforts of Waitrose who both sell online and franchise their name to native operators, there are more effective ways to do things here.
Costs and bureaucracy are the enemy of many businesses in retail, and the amount of barriers to the truth and colleague views always surprises me. You have to tell the 'unvarnished truth' and that culture has to be encouraged, whoever the retailer is.
You might well open that door and have all kinds thrown at you, but once the colleagues know the door is open and people are accountable for some of the 'ideas' that land in stores. Service improves and everyone feels like they're heading someplace better.
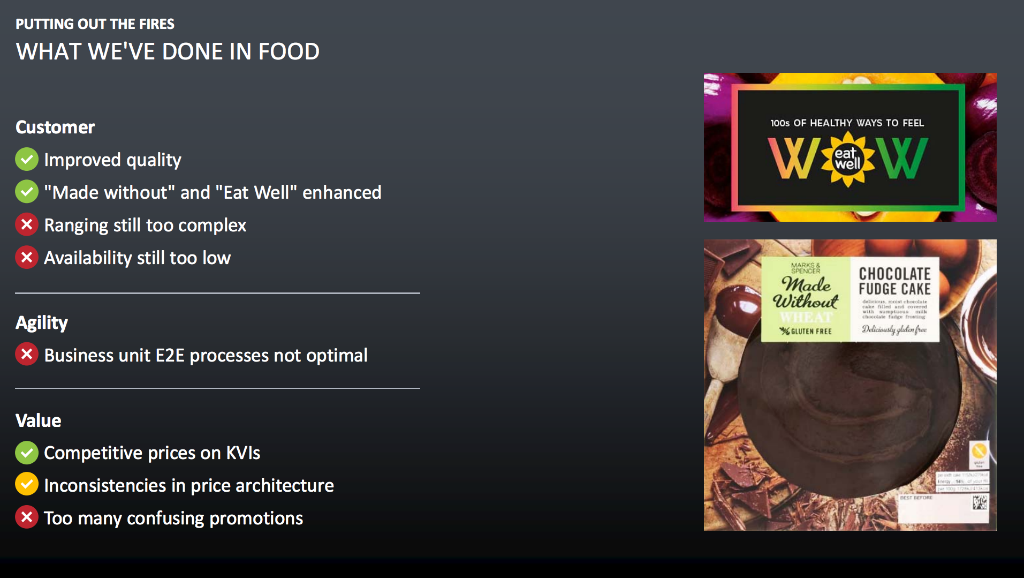
As discussed, the food performance was harder work, but the trading has been strong for many years so it's a case of levelling out here perhaps....
Lots of activity in Food, quality is improved (already well regarded in the industry of course) and Free From / Health have been in focus, I'm not a seasoned shopper of healthy foods(!) but the Free From work has been noted and their innovation has extended nicely here.
Still questions over whether some of the lines should sit together, or within the host category (Biscuits with Biscuits etc) perhaps. It's still difficult in store to find the fixture of free from occasionally, it can be tucked away at the back of the shop.
Ranging is complex, there are numerous brands in food, ready meals particularly that can be a struggle. Sometimes it feels like limes are developed, just because here. The addition of the premium range 'Collection' means that even more lines are now around the store too.
Simply as a basic tier has been sharpened but can still confuse in areas like Soup, does the value tier / core tier exist in selected categories? Or should it be in more categories to provide an element of price security?
Availability can be patchy, their space splits towards Fresh Foods mean there is a balancing act, ensuring that waste costs don't spiral out of control. Ambient availability is broadly good but seasonal collections have been slow to launch.
They have to be very sharp on their availability given the frequency in which their ranges change. A limited window to sell Summer lines means you can't afford a gap on the range for the first two weeks....... Later night availability can be hard work too in stores, it's always a challenge.
Unclear what their end to end processes are or should be, would assume this links with the futuristic depots that now appear to be not that futuristic as more money needs to be spent on them.
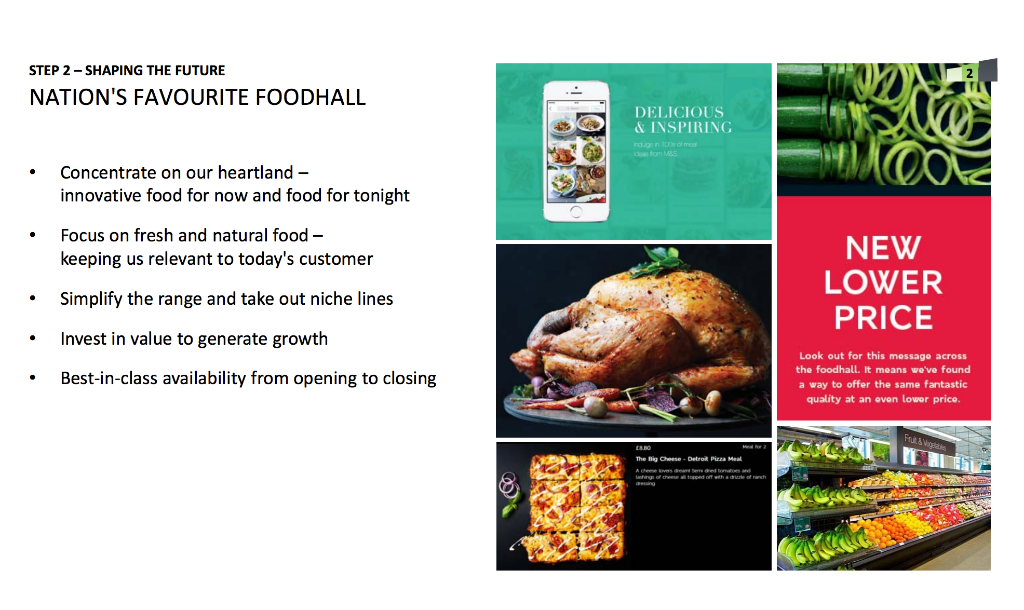
Competitive pricing on the KVI (known value item), IE customers will know the price of Milk 4pt, a bag of Carrots etc. I also think in M&S all brands should be included as the customer will know what they're charged elsewhere for these. Some lines are cut in price, others are matched with Sainsbury's.
Still challenges around pricing in the categories, where 'Simply' M&S core tier exists, how does that work when there is a mid tier product too? What should the price gap be?
Lots of deals around too, many have gone for 3 for £10 when a 2 for £xx should be included too I feel. The meal deal is simple to understand when you look at this in isolation, however they have had 3 running at one time recently which can reduce the impact of the deal, when it's run too often.....
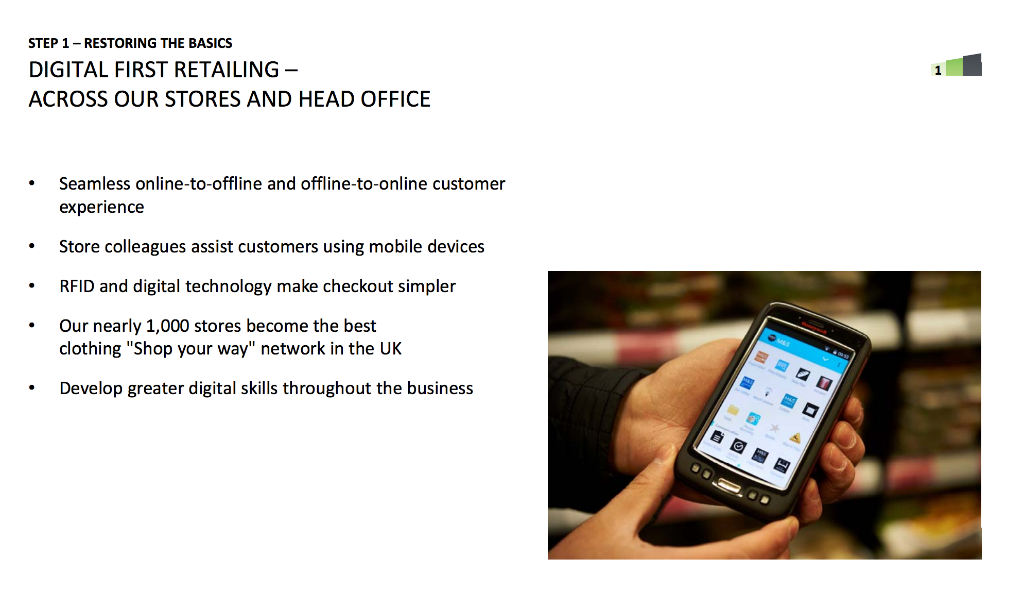
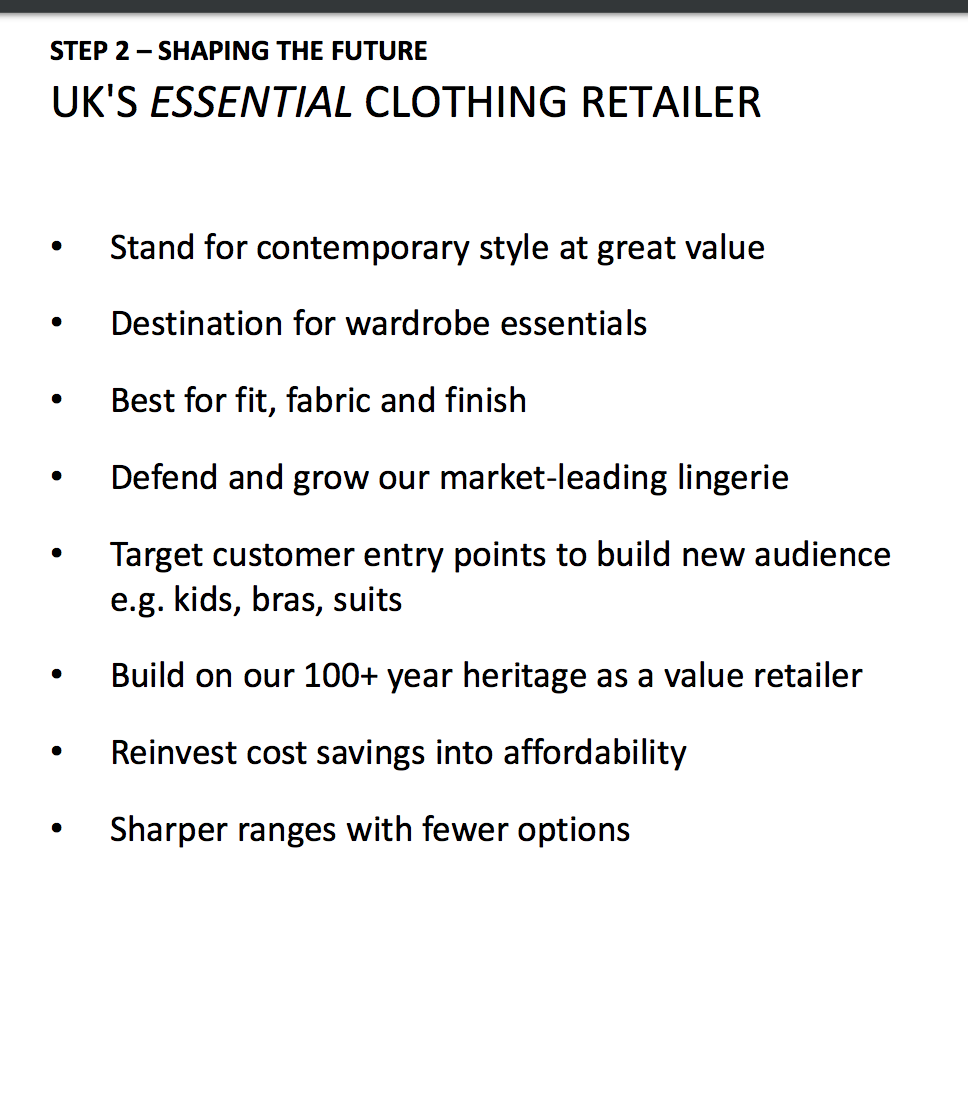
Digital is a must, enabling colleagues with devices alongside RFID all sounds like it will enhance the customer journey and also make things easier in store.
Similarly the clothing mission statement looks aligned, but written down on paper means nothing until that reality hits the shop floor. They do need to be famous for things again, the suit measuring is a good idea for example.
Whilst everyone talks about fashion within Women's, even the Suits are relatively uninspiring for Men. Price is important here, all the quality improvements in the world will mean nothing if the price isn't brought down at the same time....
A tough balance.
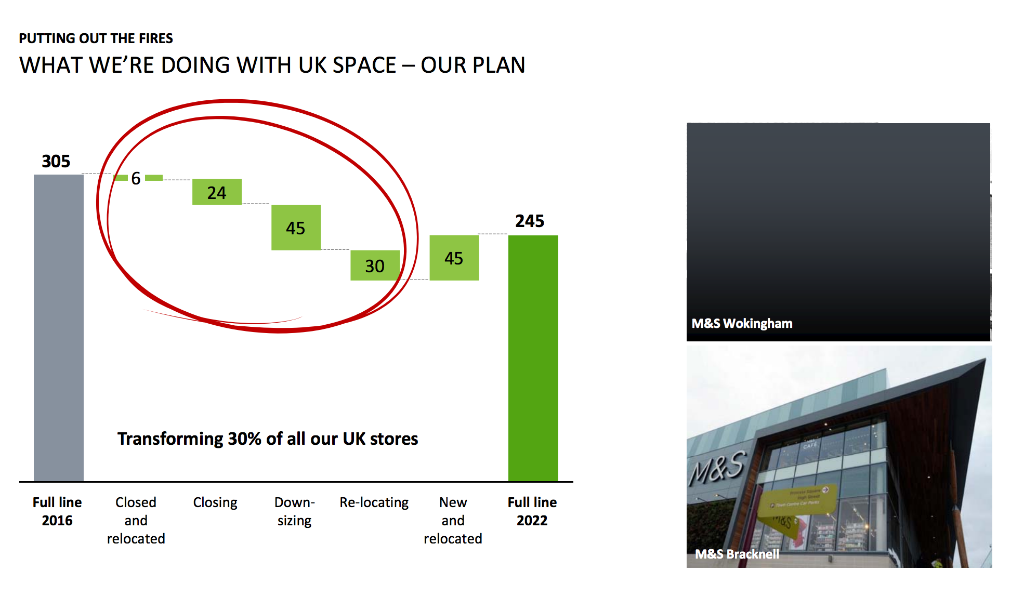
More than just closing shops of course, a few have been repurposed, or moved to a better location.
One larger store near me has been repurposed with the area they expanded in to, some 10+ years ago closed down. However the moves that the chain made to accomodate this are baffling.
The store has two floors, and downstairs housed the GM range which was over spaced and looked bizarre.
However the moves saw Kids clothing move downstairs, alongside some non food categories. This means any parent with a pushchair, or indeed trolley has to queue for 1 of 2 lifts to make their way downstairs.
It's a hard one to understand that. Doesn't strike me as a customer friendly move, and one to watch out for when M&S are carving stores up, ensuring that it meets the 'common sense' test, otherwise it'll harm sales.
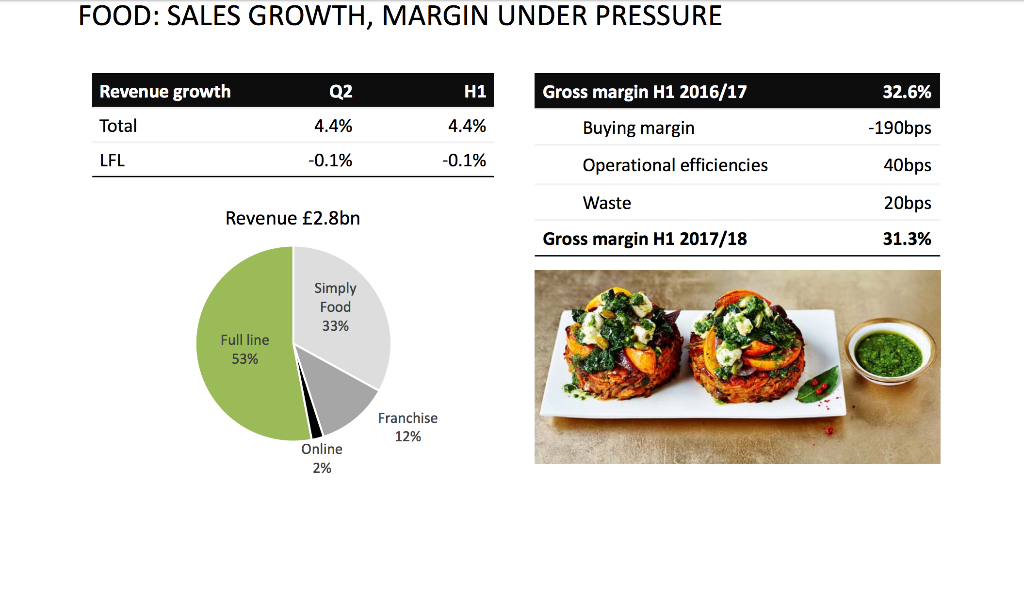
Sales growth, but barely on a like for like basis in Food, online is a tiny part of the mix but could feasibly grow as the trials get underway.
Deliveroo link up feels like it'll make sense across other bigger cities and the click/collect operation too is another one that makes sense at a high level, given the business strength in meal solutions and the like.
Margin is under pressure, but money is found in waste and operational efficiencies.
Waste is a fine balance, any focus on waste can lead to the wrong behaviour - IE pulling back on orders / forecasts to save waste. This invariably leads to a lack of ambition centrally and sales being harmed to save pennies on waste.
The niche range removal means the flavours from around the world is likely to disappear. £14+ from a bottle of genuine Maple Syrup is too much of a stretch one suspects.
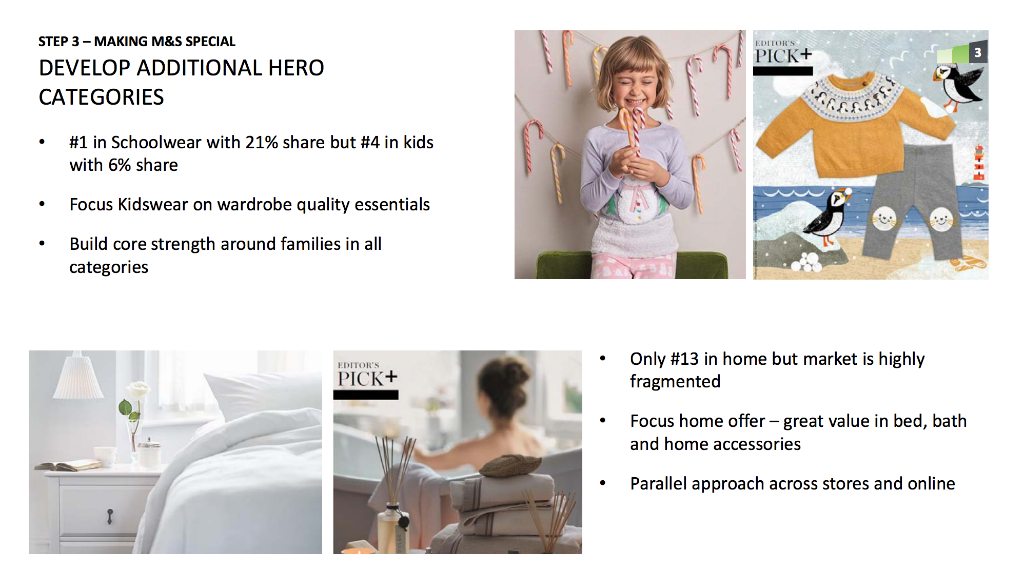
Surprisingly adrift in Kids clothing and also Homeware. Their GM collection should be far sharper than it is, often in store it's uninspiring and hard to shop.
In some cases it's downstairs in a two floor store which means customers don't travel to it. The lack of a discernible online offer harms M&S here, although improvements have been made to the site - it's still hard work versus other rivals.
The next logical step for M&S would be to reduce the need for customers to wait for click/collect non food, and instead offer live feeds to the availability position online.
Then a customer could see if their local stores had a Knives / a clock etc in stock, reserve it, and go to store to have it brought to them and pay for it. Would drive footfall and also reduce the waiting time, and fulfilment costs whilst ensuring stock turn.
You could do similar for clothing, especially essentials and even tilt this for seasonality - IE all Party dresses online at set times of the year.
Their ambition on Kids is clear and makes sense, but their position is perhaps reflective of the fact that seniors (55+) are their broad customer and buy clothes for the grandchildren, rather than families who are buying the entire wardrobes.
M&S isn't a place that families will visit at the minute, given prices and indeed the lack of fashion options for the mum/dad in reality. However a better Kids department, especially within non-food (one should only look at newer Mothercare and Mamas/Papas to see what can be done) could help to turn the tide.
Families know the rough price of clothing but will pay for quality, again you feel that M&S has to bring pricing down to sustain volumes, but still offer the great party clothing range too.
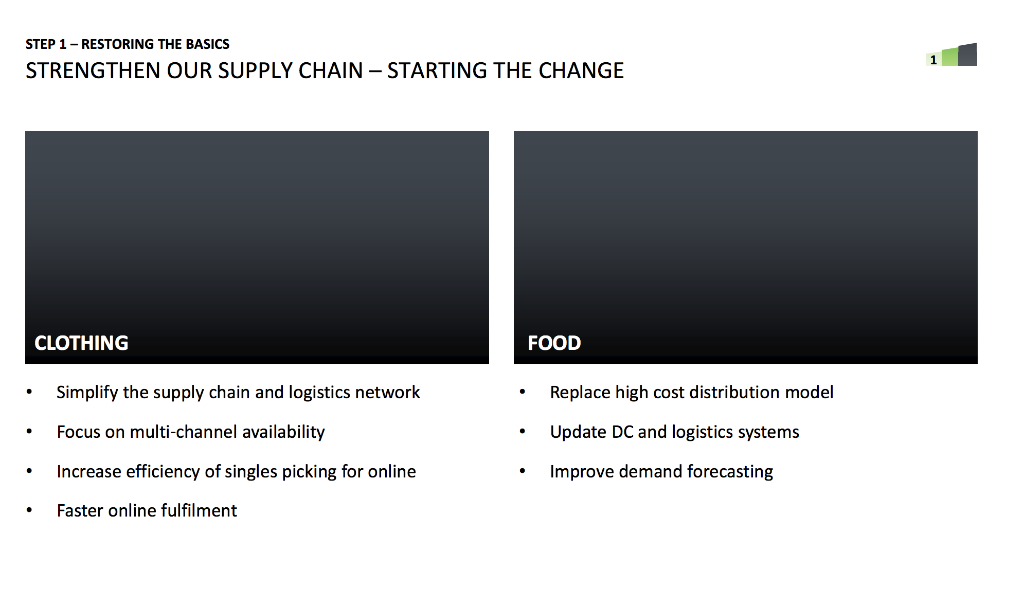
Given Morrisons are still in their IT transformation programme (kicked off by Marc Bolland in 2008, for 3 years, full upgrade) some 9 years on.... There perhaps needs to be questions asked around the DC strategy given the work needed once again.
Bolland replaced 110 legacy depots with 3 major hubs near the motorways in Leicester and Bradford namely, with the predictable issues around availability, systems and the general failure in one depot which led to gaps on shelves.
The depot in Castle Donington was set to allow a push on GM and Clothing now the logistics were sorted. However, this hasn't happened and now the focus on further simplification of the network and replacing a high cost model in food will lead investors to wonder what went on previously.
The focus on multi channel is also a concern given the new depots should have been fitted with capability for singles picking and had multi channel in mind given the way the world was changing. Online isn't going to go away after all......
So it's another headache for Steve Rowe but one that is being highlighted, and rightly so. But it would have been advantageous to tackle this when rebuilding the depot network one suspects.....
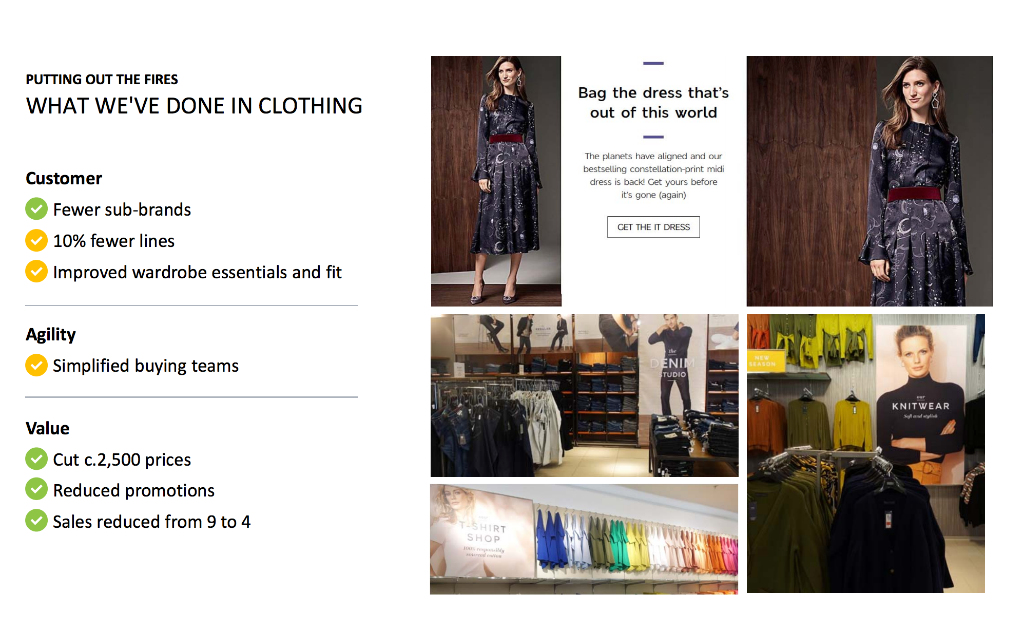
Ah female clothing.
It's hard for M&S to get a foothold here, they know their market, that is abundantly clear when reviewing the ranges at a high level. However with that market ageing and not using digital in a 'big' way, there are huge market segments to get after who are beneath the seniors.
So there has to be a balance, sure the older ranges need to be maintained to ensure the core is happy. But front and centre has to inspire and the 'must haves' are always good for footfall.
Archie Norman was outspoken on the mustard recently, I was in store yesterday and was struck when I looked at just how much there was.... It was everywhere...
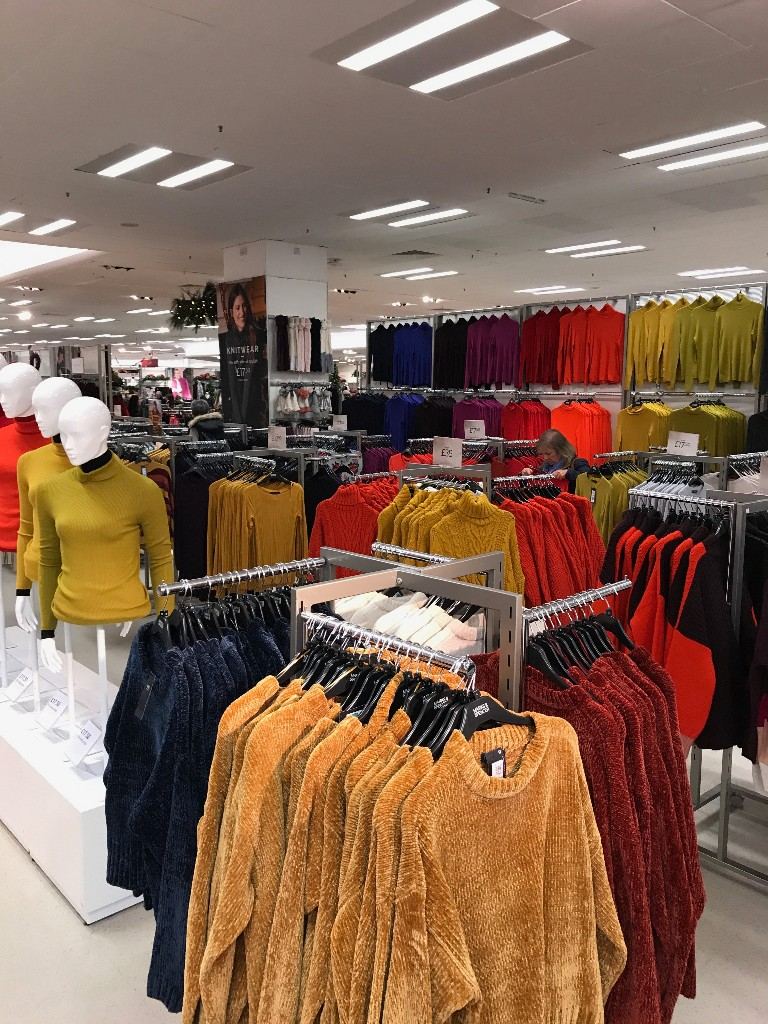
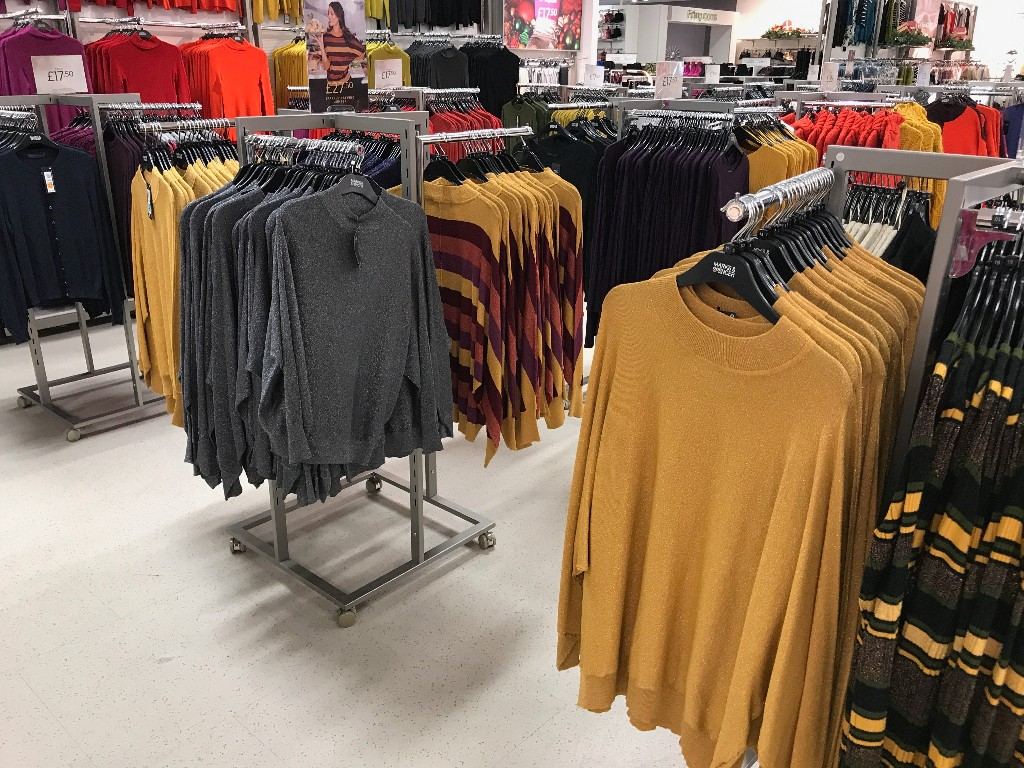
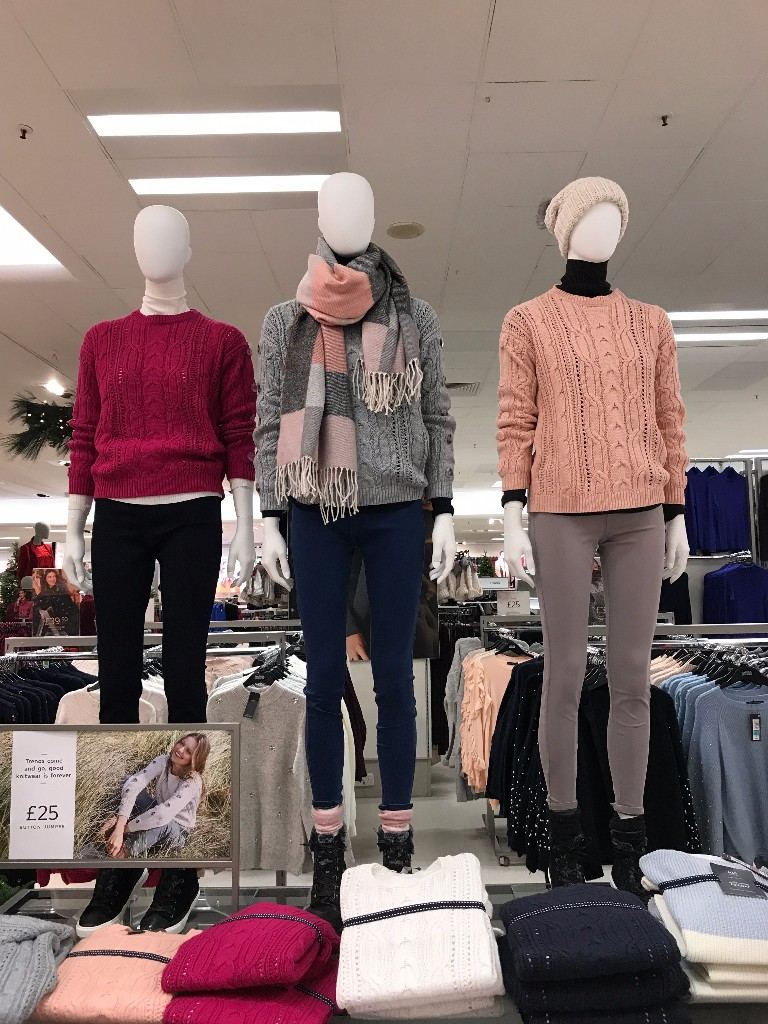
Even when a 'look' is built up in store for customers to see and be inspired, the scarf (a lower priced component) wasn't featured within the range to buy.... Why?
Lovely work for Paddington with some really good range extensions like his Coat.
As we can see, downstairs in the store features Kidswear, meaning parents with a Pushchair, or Trolley have to travel downstairs in a lift to visit the category......
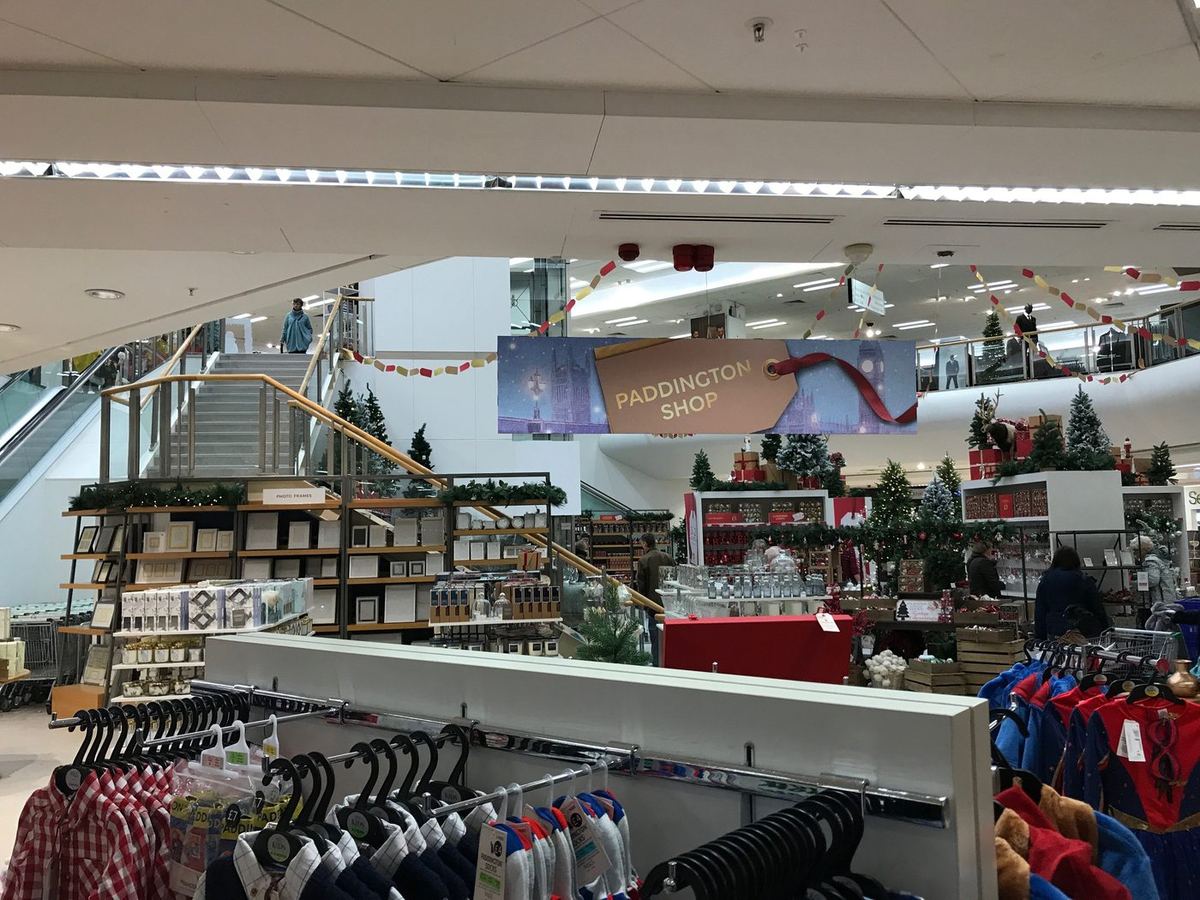
Also downstairs were the Christmas trees.... Not the cheapest tree in the world by any stretch here.
Lots of market activity in Trees too, numerous retailers and the supermarkets sell a great number of faux Trees.
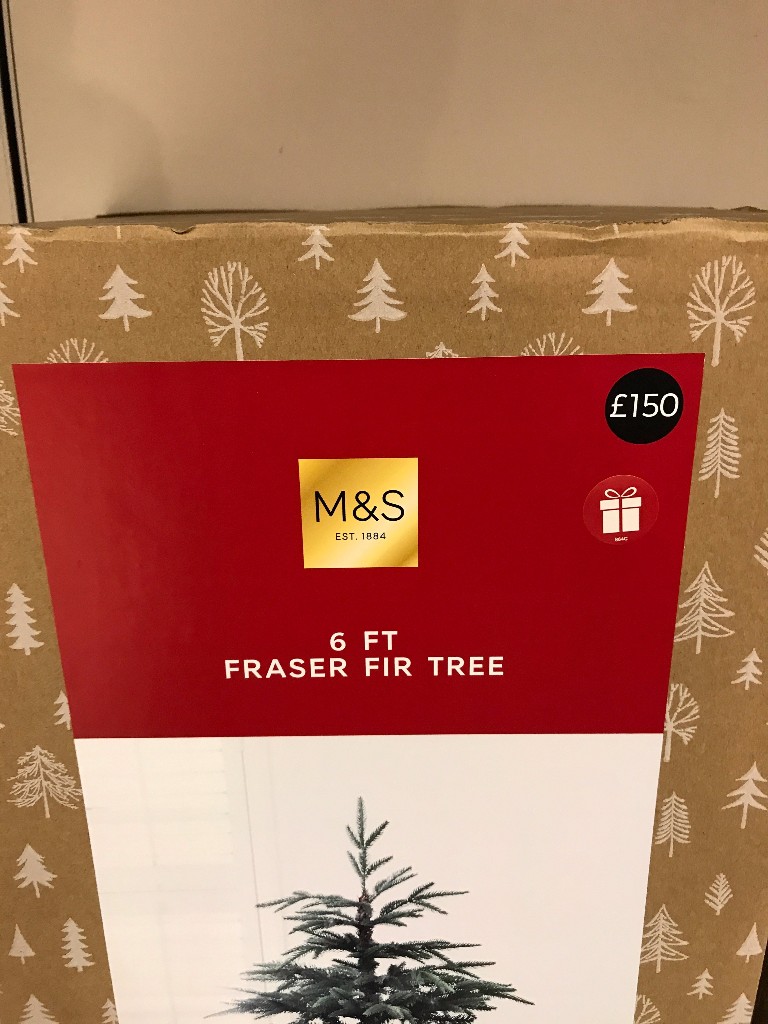
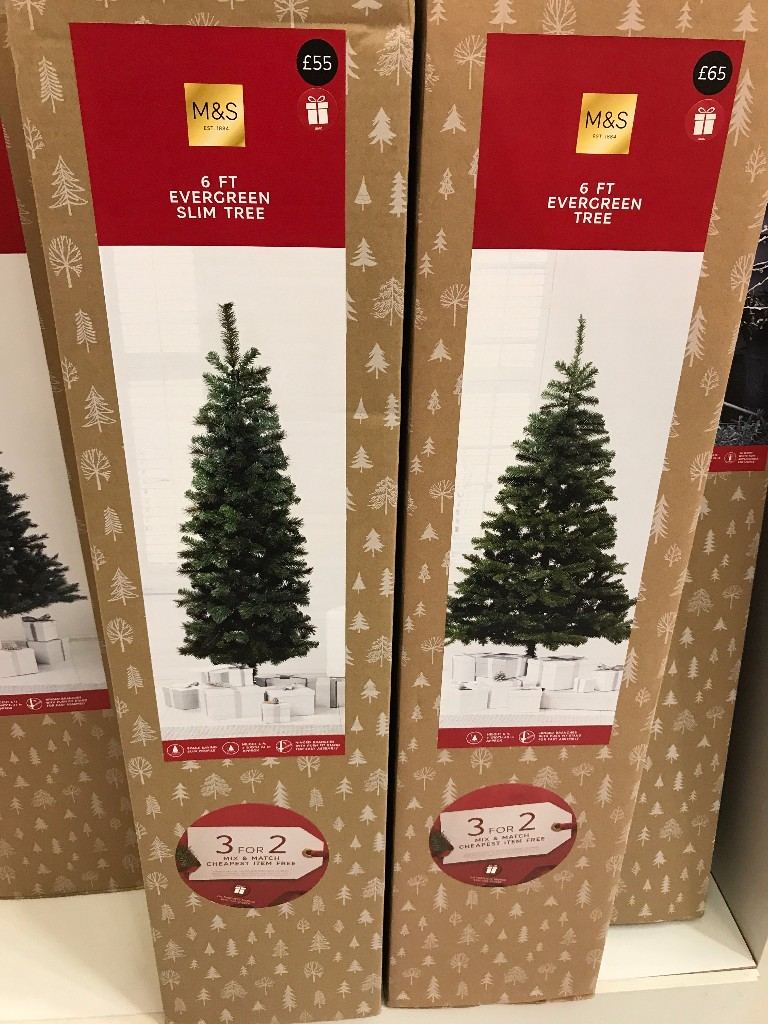
Still, at least the trees are included in their 3 for 2 deal(!) Too many promotions(?) However the big Tree is called Fraser which is a nice touch.
So, M&S are by no means on the critical list, but they have a grasp on the future now and a longer term plan, which is sorely needed.
They can't afford to ignore online in the main, continue to under perform in womenswear, or have many more Mustard coloured garments around the category........
From the Grocery Insight newsletter archive, first sent to subscribers on 10 November 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.