Retail by Email - Issue 476 - USA (17 June 2022)
17 June 2022
View this email in your browser
This is an example of an email sent to our subscribers, why not join today? Issue 476 - Retail by Email - USAA few things we spotted in stores last week.
It was great to get back to the US after COVID and aside from Disney, Universal and the rest of it. It was also great to get in to stores and see how the US market had changed and adapted both during and post (we hope) COVID.
It’s clear that there are huge parallels with ourselves and our US cousins in terms of the rapid shift to online, mobile app orders and “order ahead” tech alongside rampant inflation too.
Orlando, Florida is never a place to go and save money, far from it. But the increase in various things around Disney was a good barometer of what was to come in general retail.
The key headline is the price of fuel. We paid 239c per gallon when we were last there, in 2019 and it was grabbing headlines that it had tipped over $2! This time, we arrived with it at 419c and left with it at 475c per gallon.
It rose so much that the typical “robbery” price the car hire people charge you for fuel when returning below the full marker. That ended up being cheaper than the price at the pump by the end of the two weeks.
That’s a big impact for the Americans, who love their big cars but also almost, “have to” drive given the availability of public transport and the location of their homes.
For retail, there were numerous common themes, the growth in online and thus, pickup was stark, as were a number of other things. Let’s dive in:
Everyone is recruiting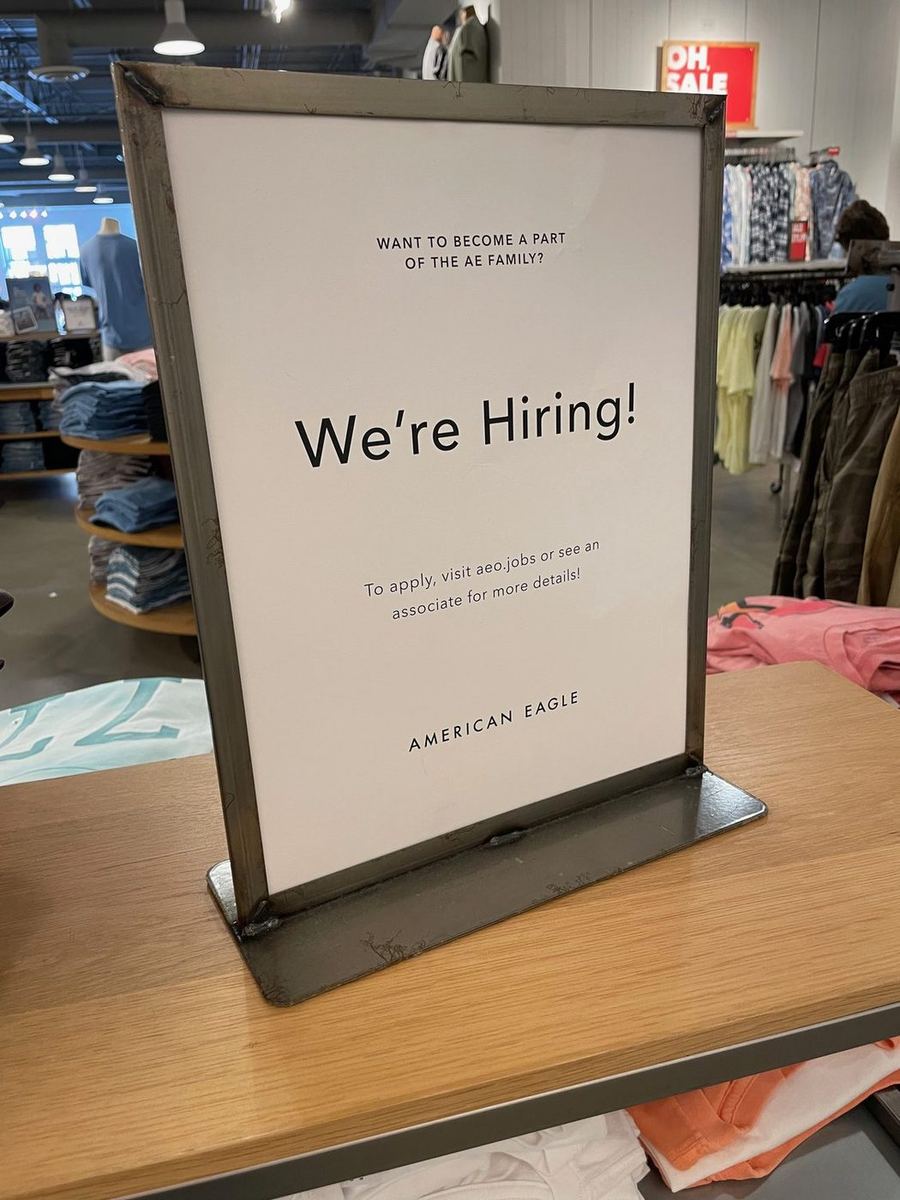
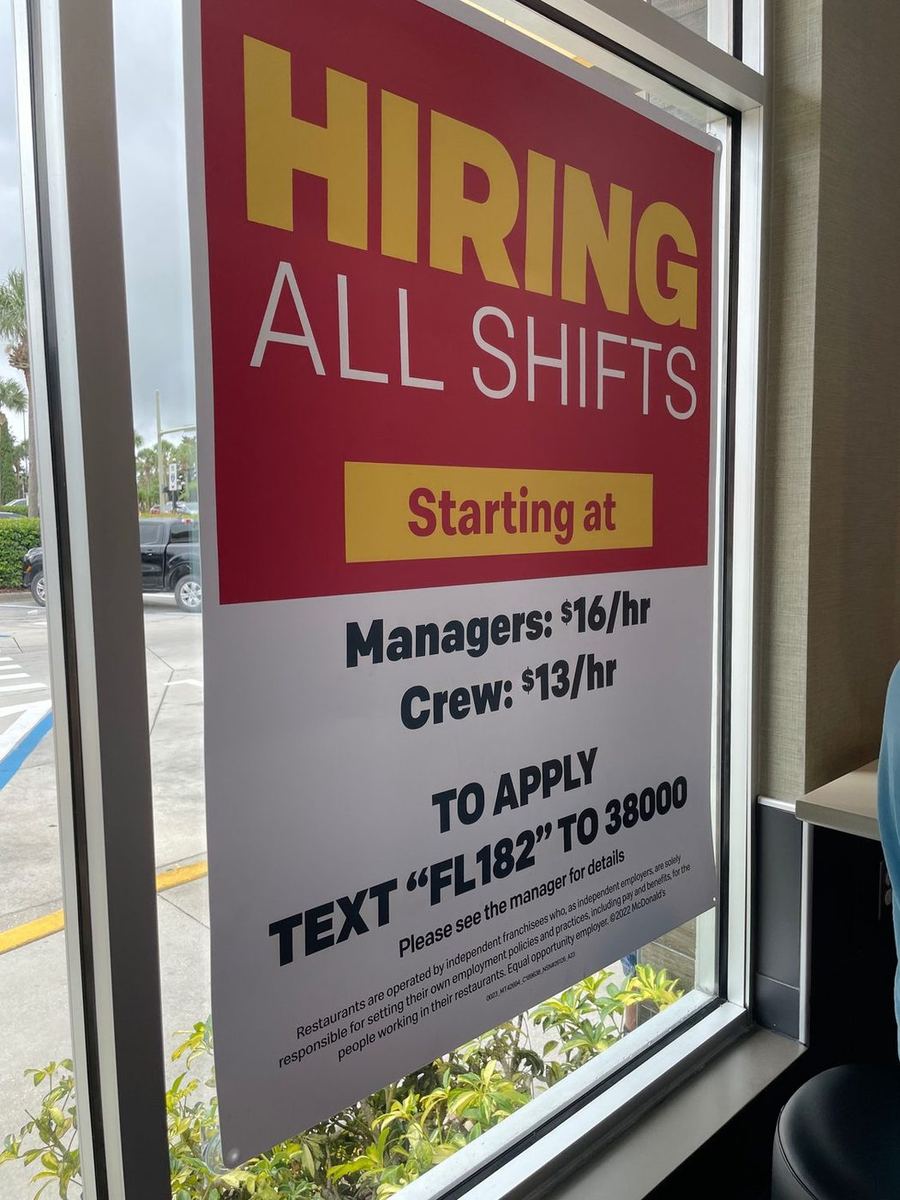
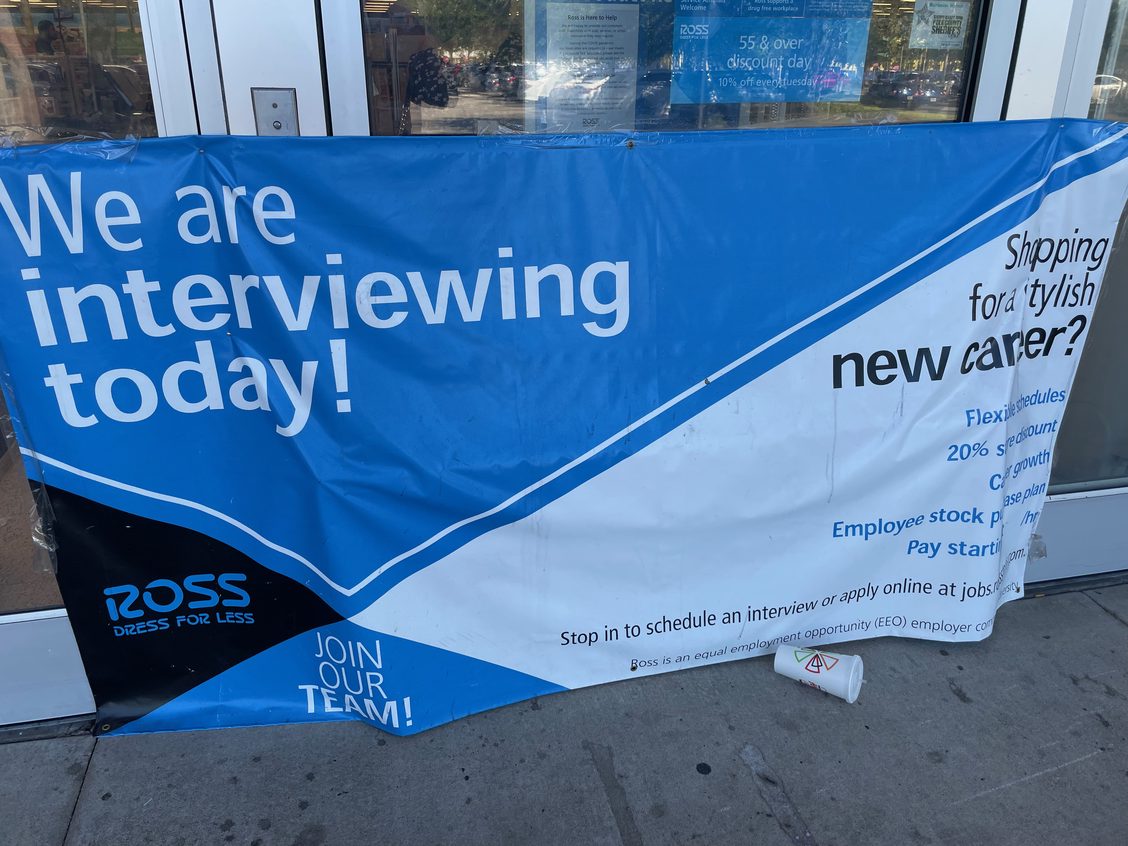
It seems everyone is recruiting, the pandemic saw people uprooted from their roles, or indeed, wanting to find new ones due to the nature of working in retail / food service and the general public = higher risk of infection etc.
So there’s been a degree of displacement and as such, there was recruitment absolutely everywhere. Ross even offered interviews on the day, Disney were also recruiting heavily and often had inductions in and around the parks too.
The challenge? You can’t replace that lost experience, or know-how quite as quickly.
2. The rise (and rise) of pickup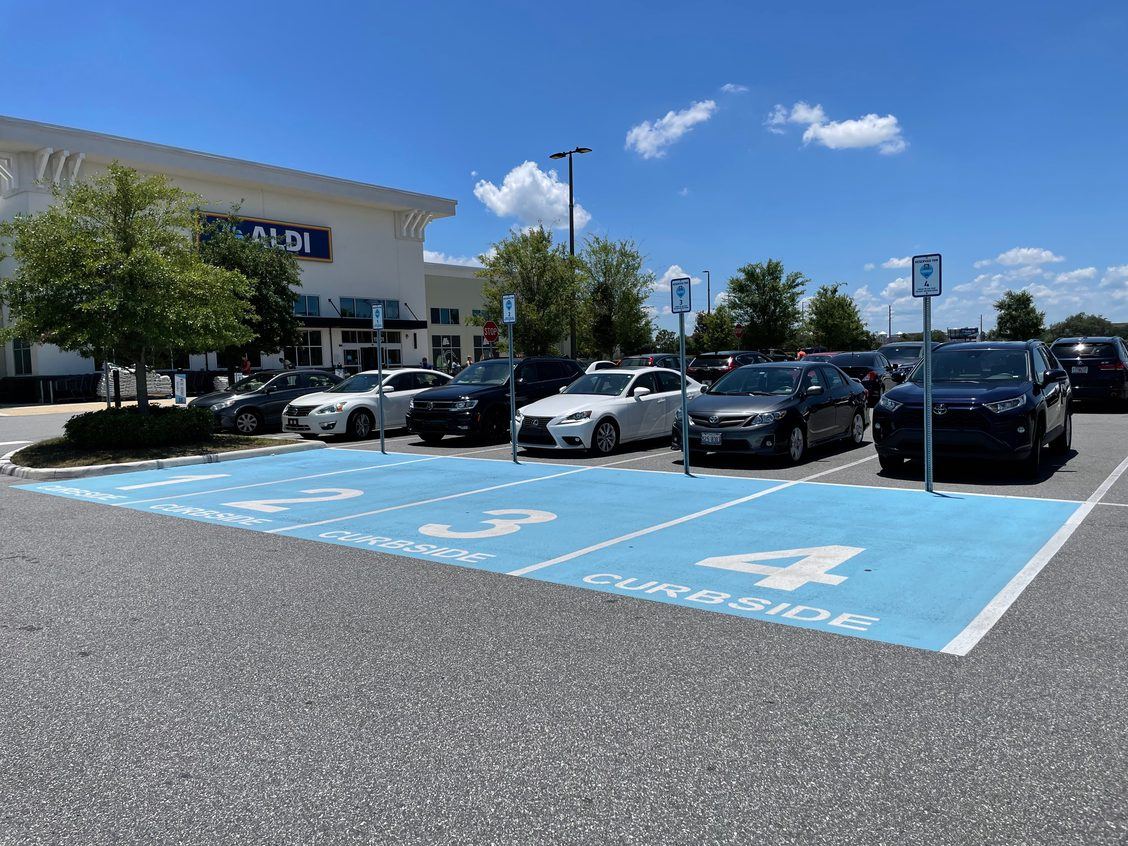
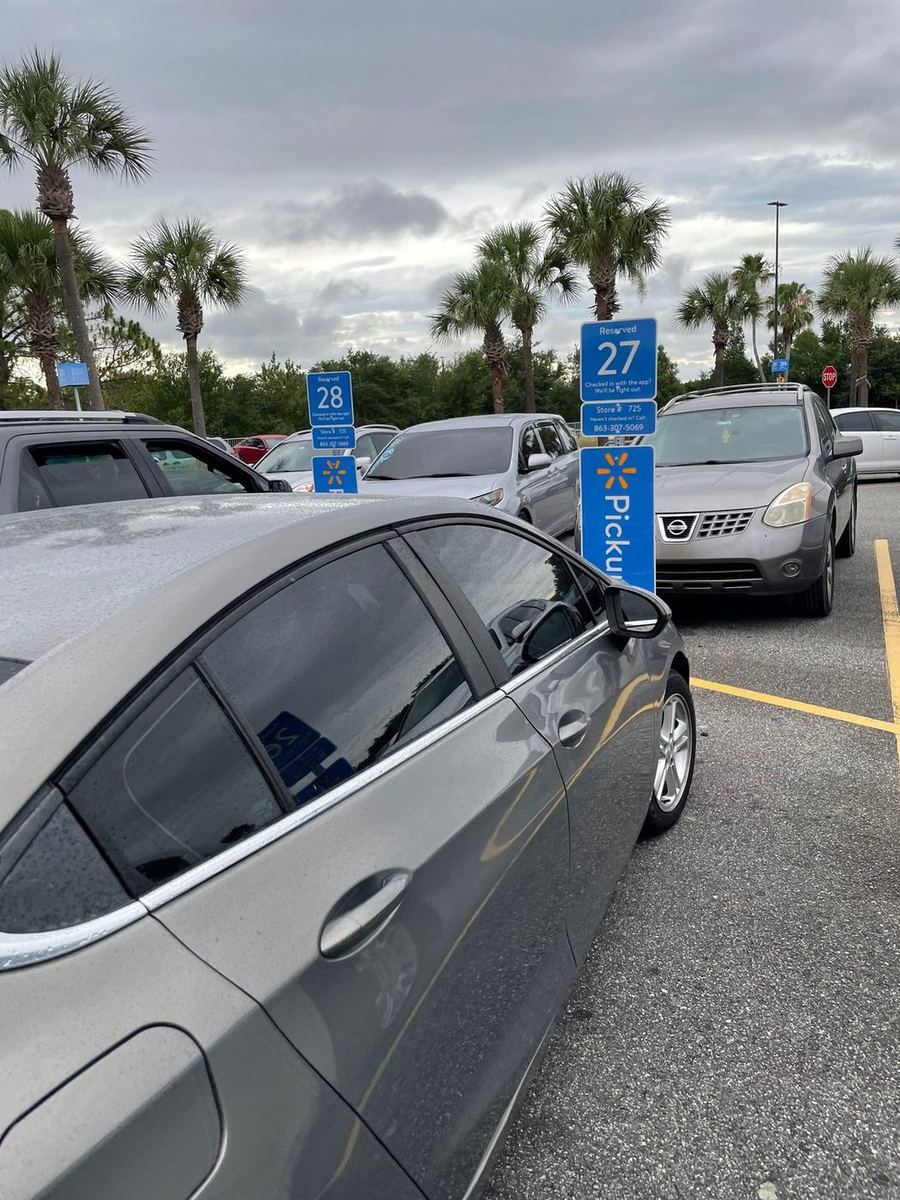
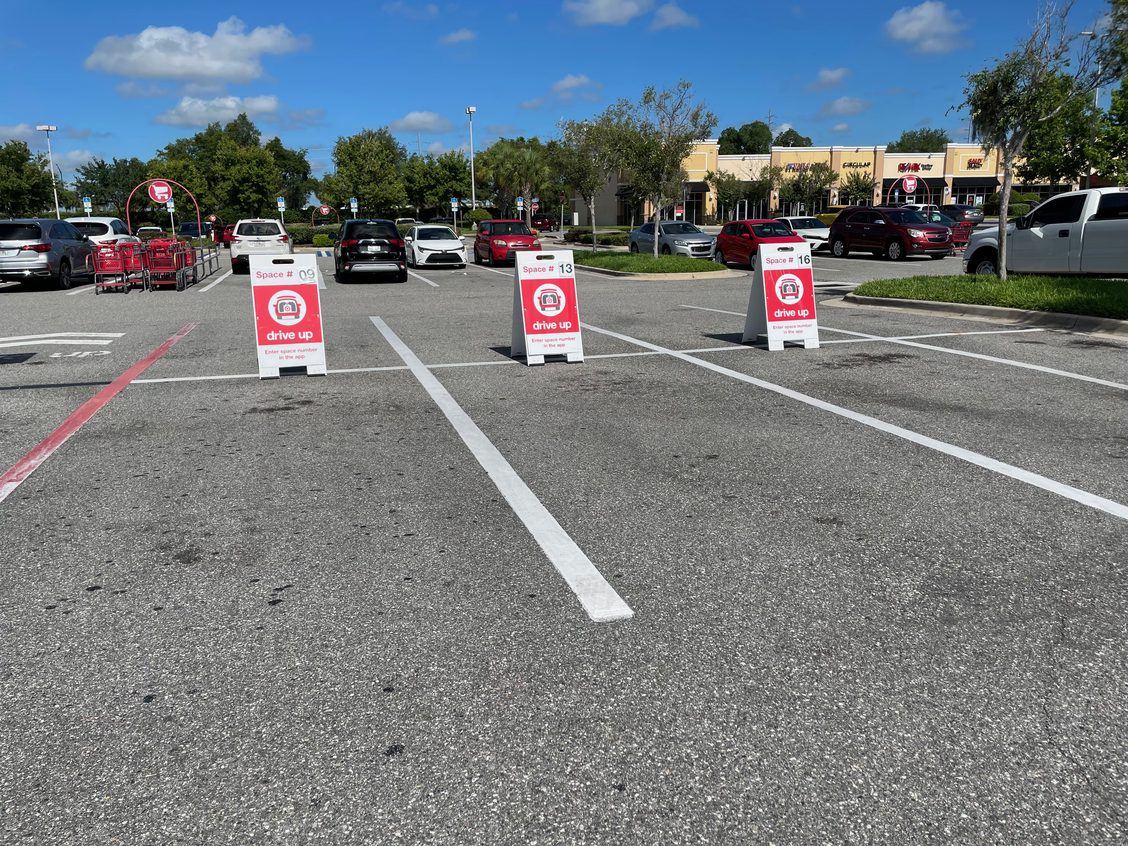
Pickup was growing pre pandemic with the US retailers wisely side stepping the zero sum game that is delivery. However there has been developments there, with Target acquiring Shipt long before the pandemic and Walmart offering Amazon Flex style driver shifts too.
But pickup has grown significantly. The Walmart near us was the only Supercenter for a while and their Pickup area had 28 (twenty eight) signposted parking bays and in truth, there were more customers waiting than that, each time.
Target have been strong in this area too with their recent addition of returns and Starbucks added to their service offering. Temporary additions to some of their store pickup locations were noted too.
Even Aldi were offering “curbside”.
This is an example of an email sent to our subscribers, why not join today?3. Delivery next?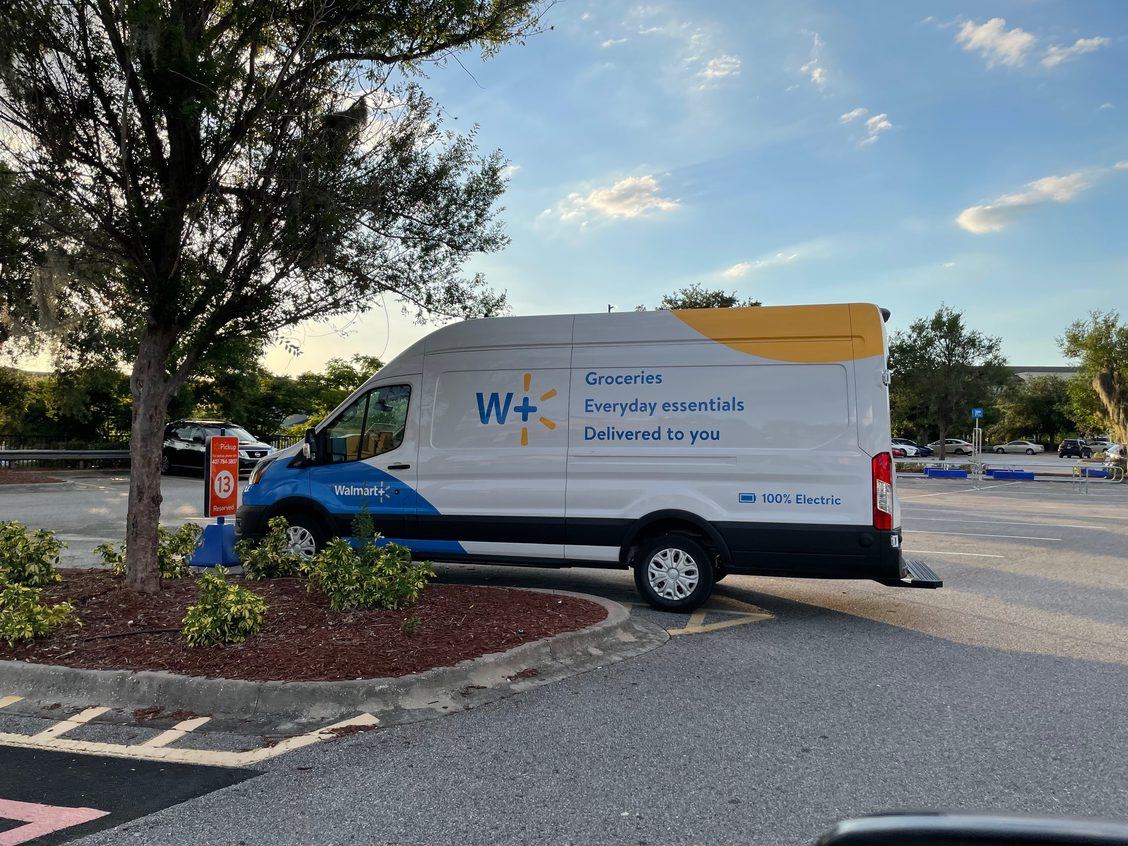
I noted this electric Walmart+ branded van in a store car park too, with deliveries fulfilled using this van (presumably) alongside the various other fulfilment options available to the chain.
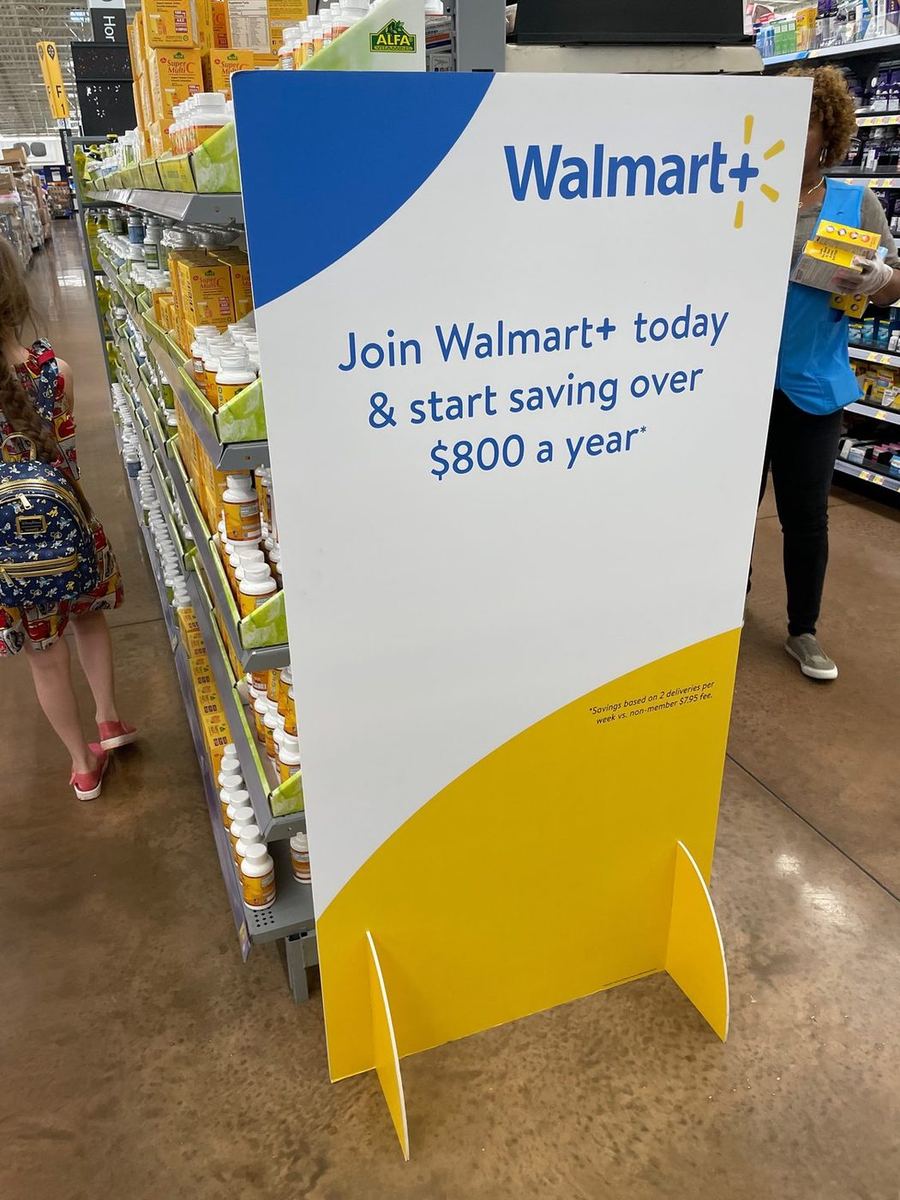
At just $12.95 a month or $98 a year, it’s a no brainer for regular shoppers.
Walmart + is notably strong in store too. With dedicated lanes for customers and the ability to use your mobile phone to scan and shop is only reserved for Walmart+ customers.
You also get free grocery delivery, 10c saving per gallon on fuel with no order minimums for free shipping either. It’s a great loyalty service for customers and again, locks them in to the chain, due to the investment customers are making.
The ability to offer savings on fuel is also another benefit of having a physical store network and the associated gas stations (whether they’re Walmart or otherwise).
Baby Milk shortages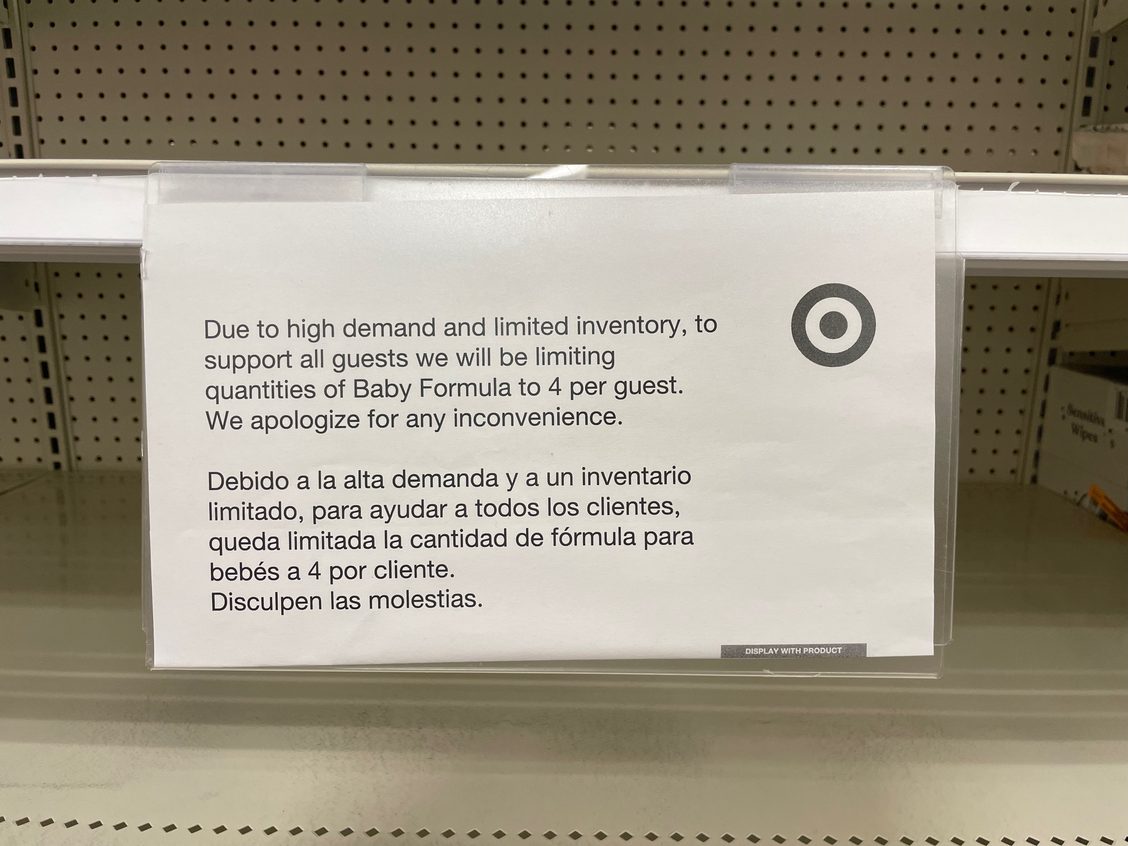
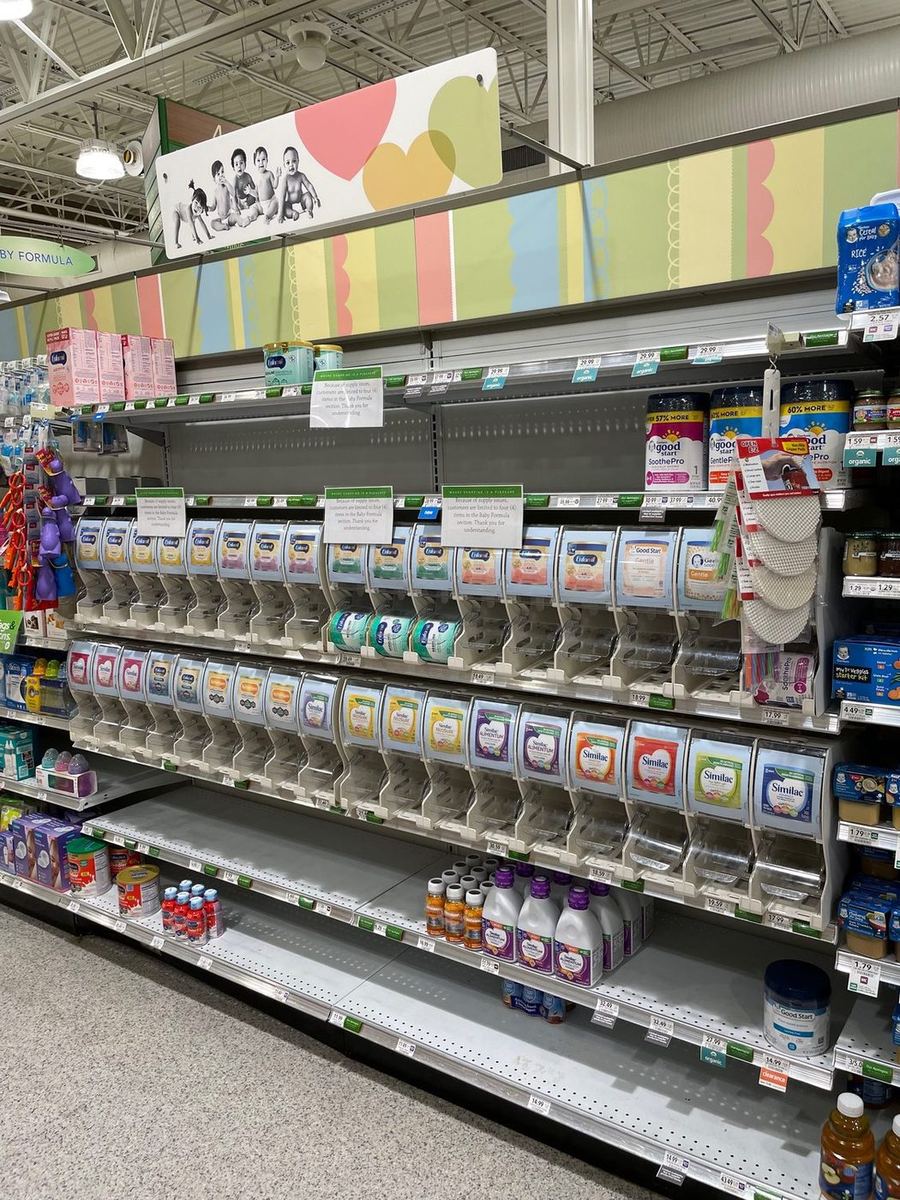
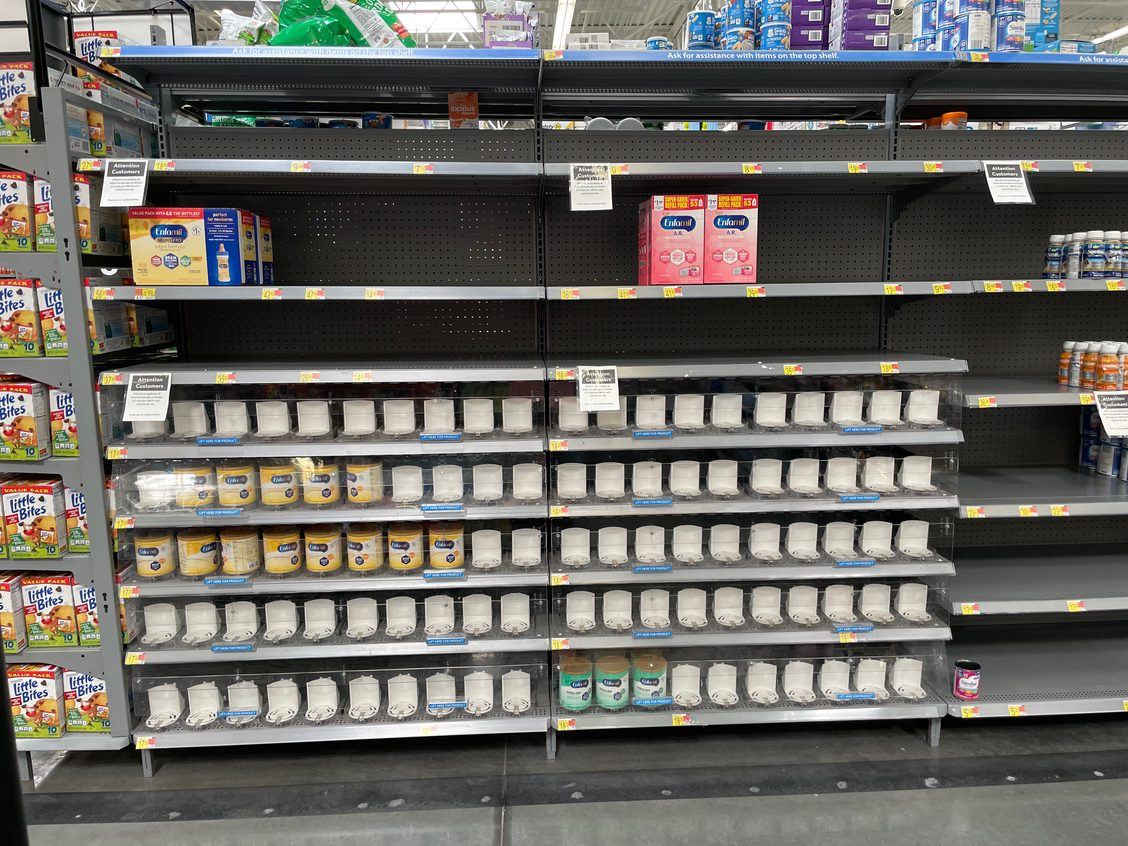
Issues with the closure of a factory, then shipping from Europe via Air and then the reopening of the factory (not without risk, it has to get to capacity, quality won’t be right first time initially etc etc) meant that numerous shelves were empty of infant formula across the States.
It’s a real challenge because it drove some parents to desperate measures, mixing formula and all manner of ideas, some of which were specifically called out and highlighted as being a major risk to baby by the CDC.
But shelves were bare, stock did return towards the end of our trip but the shelves were essentially emptied before stock could be really “felt” as being there for customers.
There were buying limits in place across all retailers but it was a desperate situation and the air freighted stock should be arriving / arrived. This will be distributed as the factory gets back online and can then start to produce normally.
Either way - it’s not a good picture and it will be some time before the picture returns to normal here.
The newest Walmart formats are good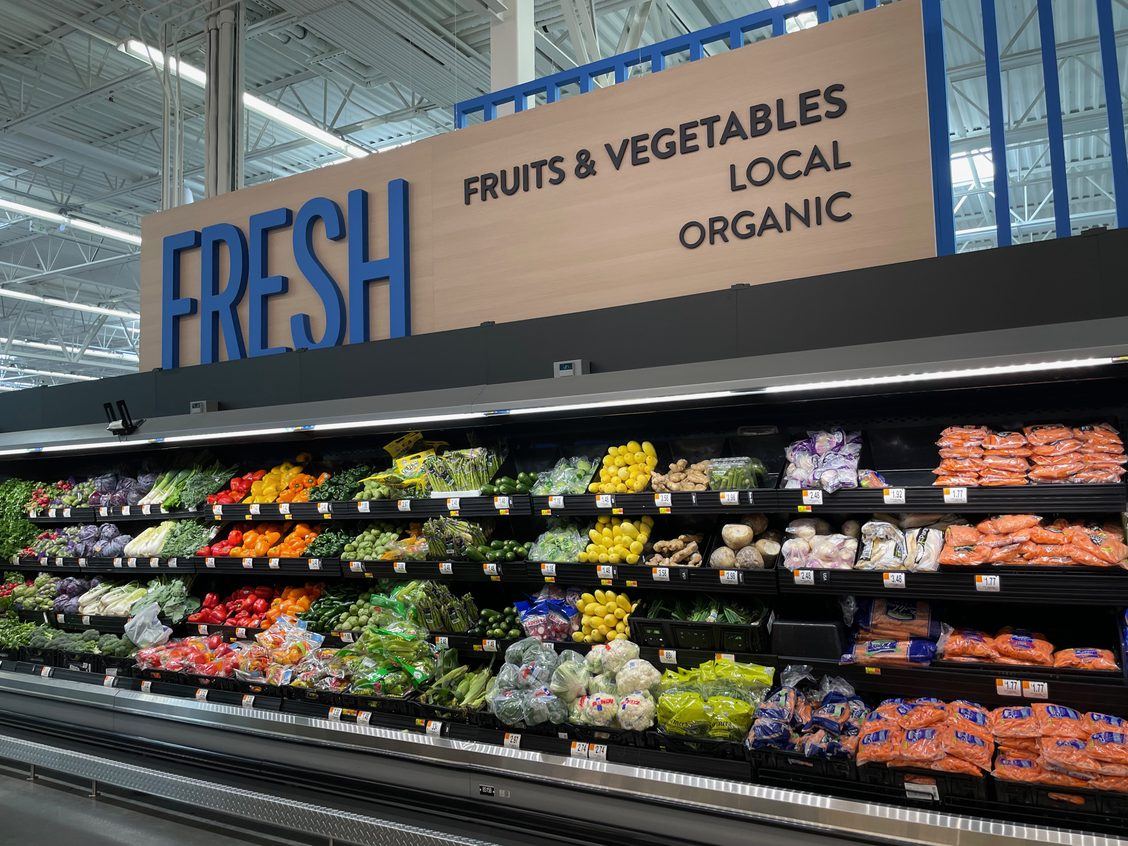
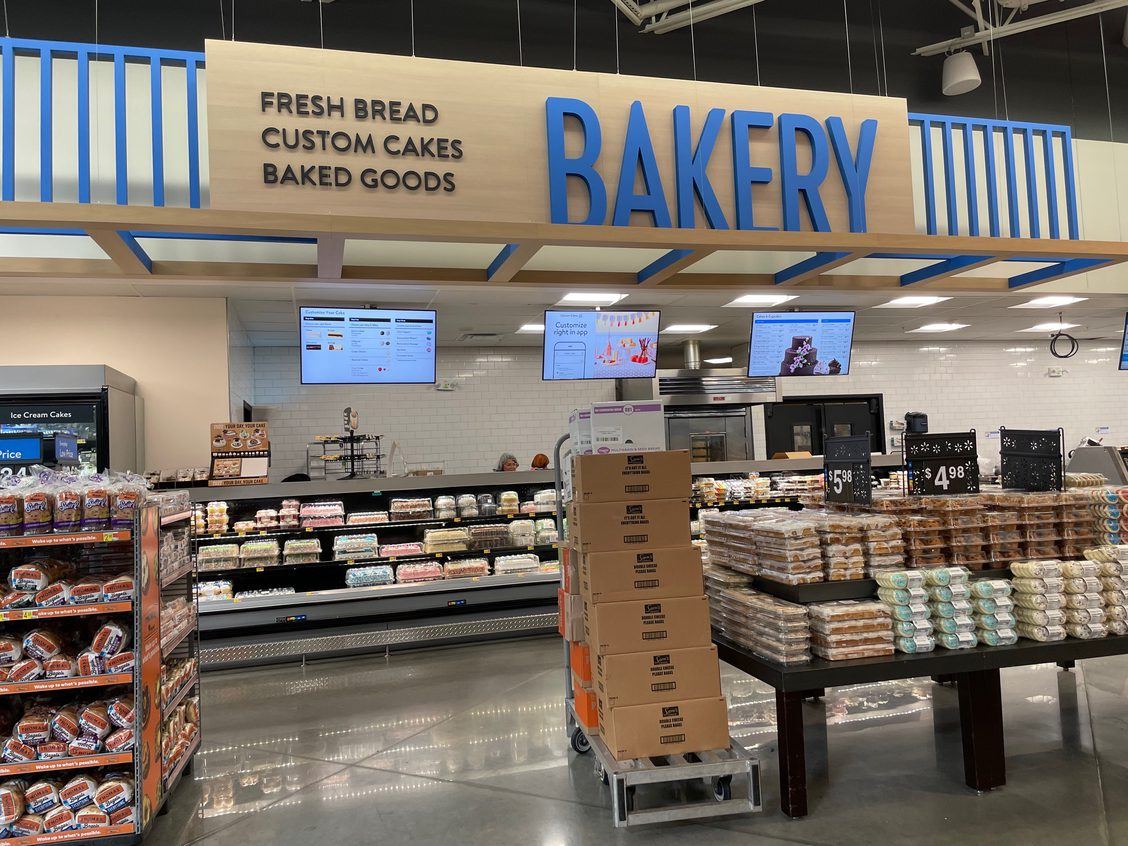
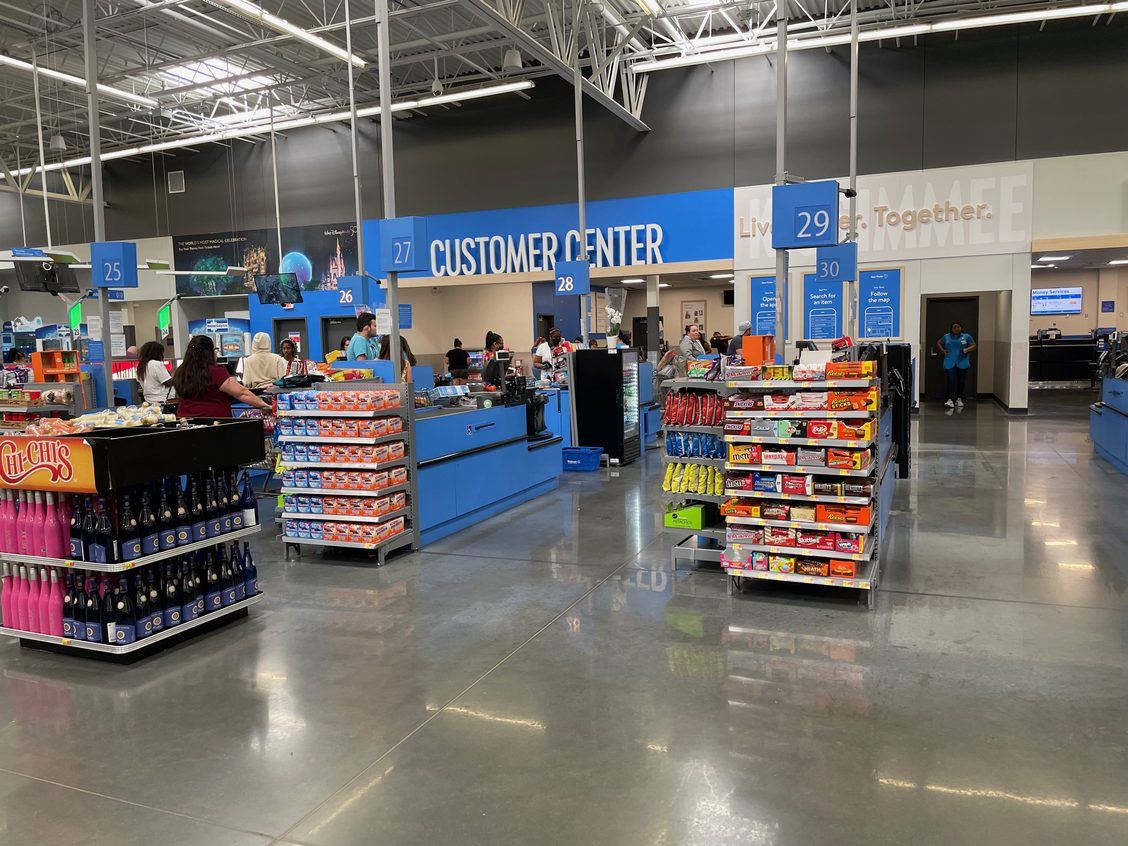
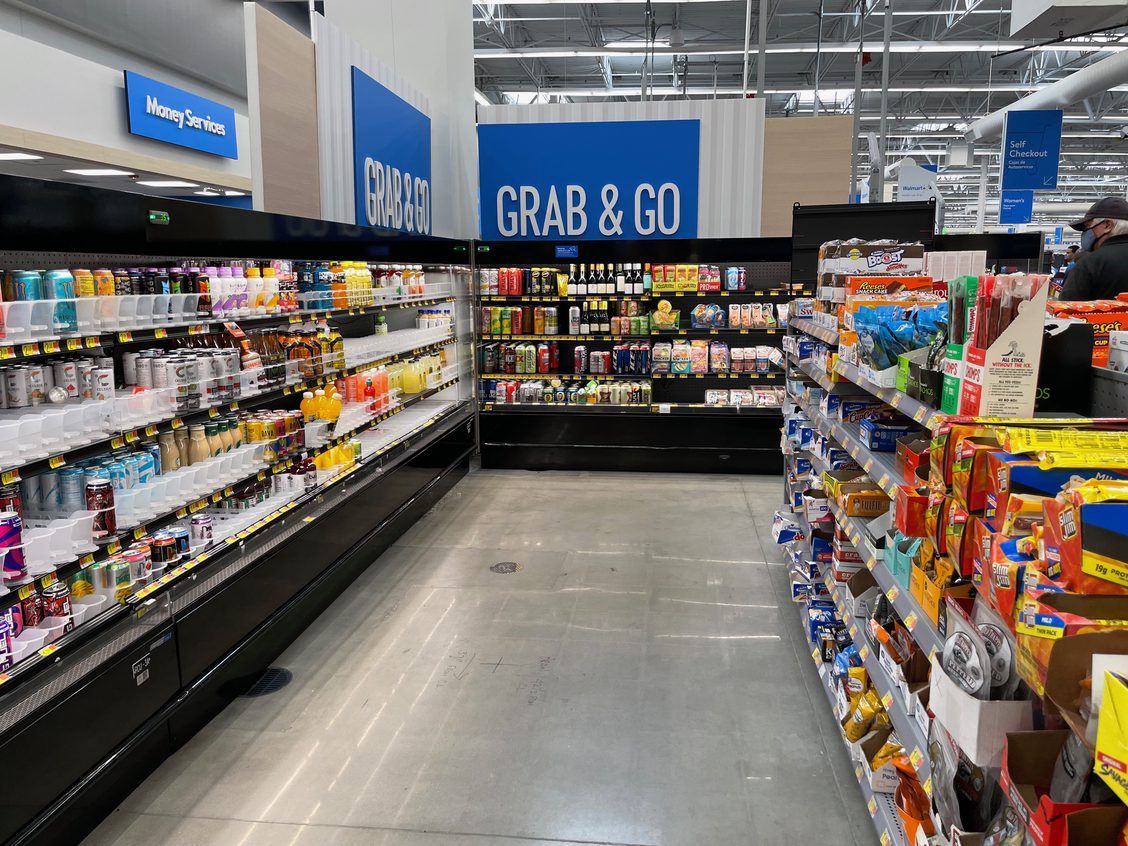
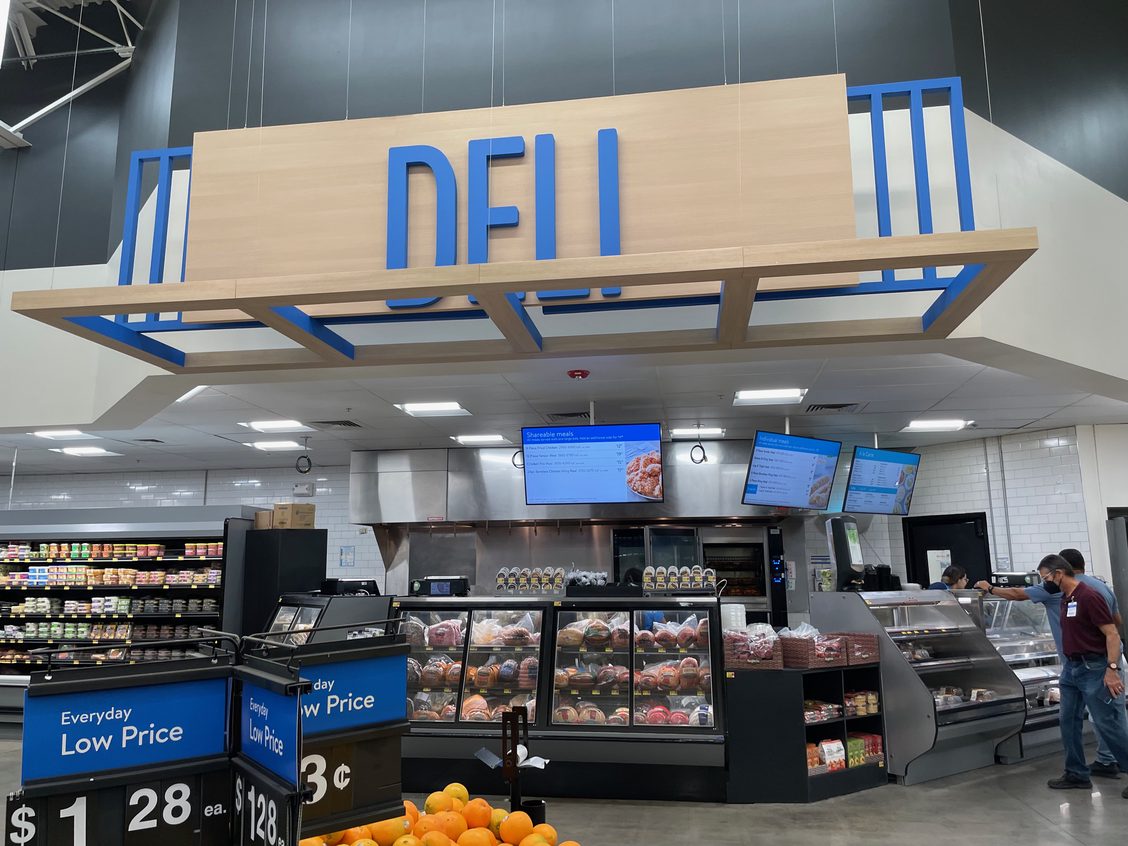
A lot of work has been undertaken at Walmart and since my first visit back in 2015, stores are unrecognisable from the relatively dreary surroundings that used to be the norm for the world’s largest retailer.
The latest change sees new bulkhead signage across the perimeter of the store in Fresh and better layouts in terms of Produce too. More way-finding signage around the store is also noted, with navigational aids at the top of the aisle, rather than the middle.
There is signage at the front of the store for their app, highlighting key categories and how the App can help customers find things (without the need for an associate, presumably).
The new surroundings do a great job of elevating the store (and chain) and store standards were generally sharper too.
The rise in self service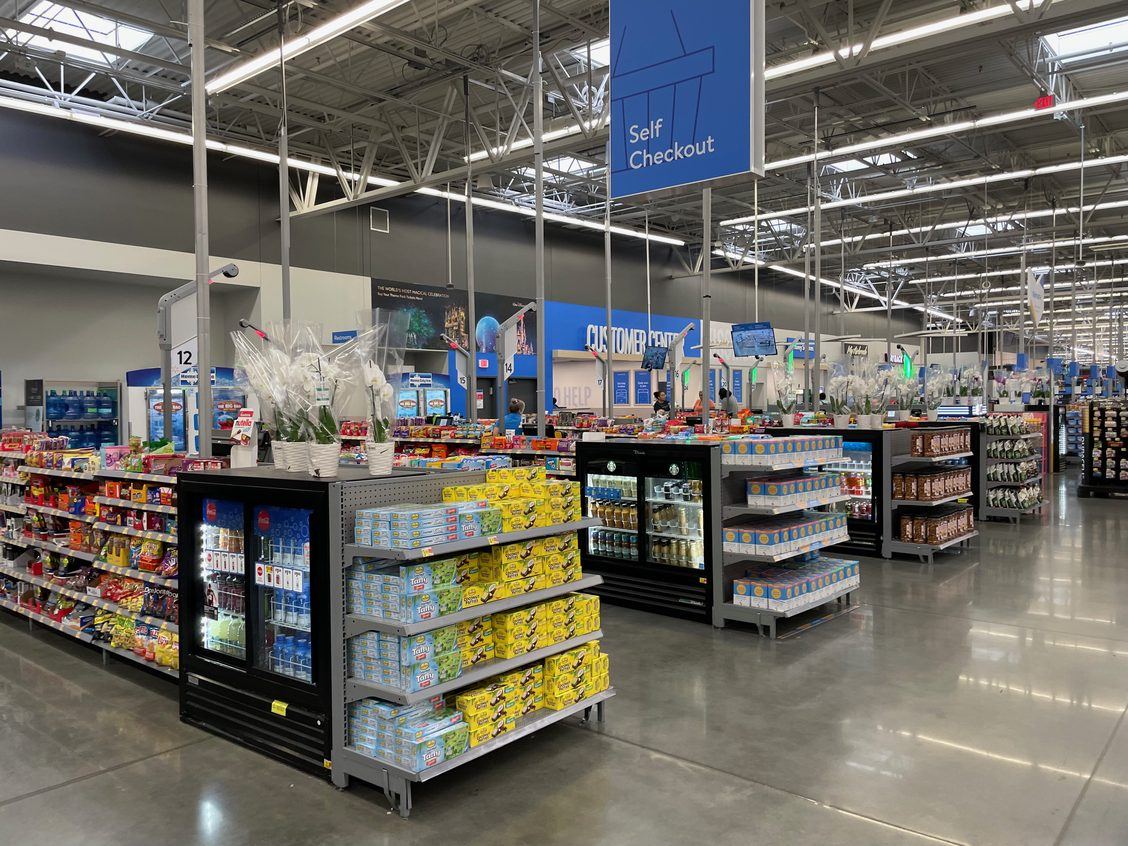
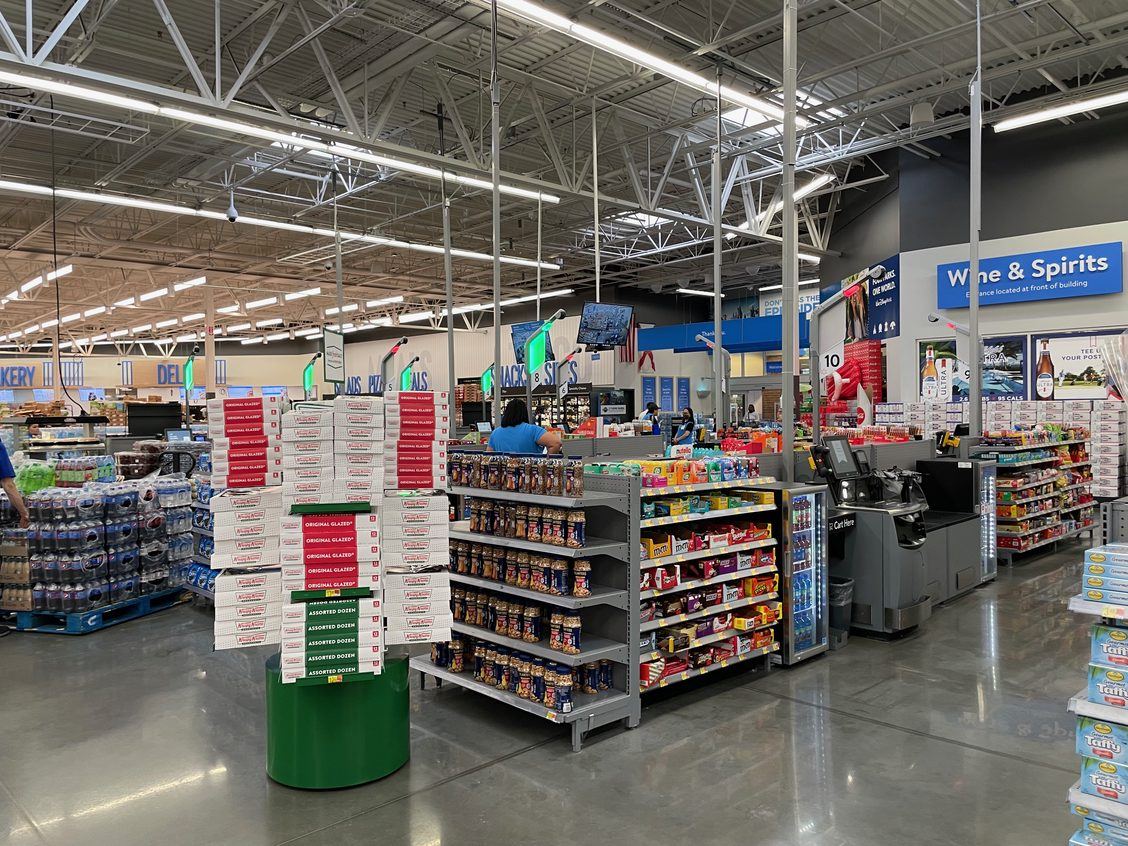
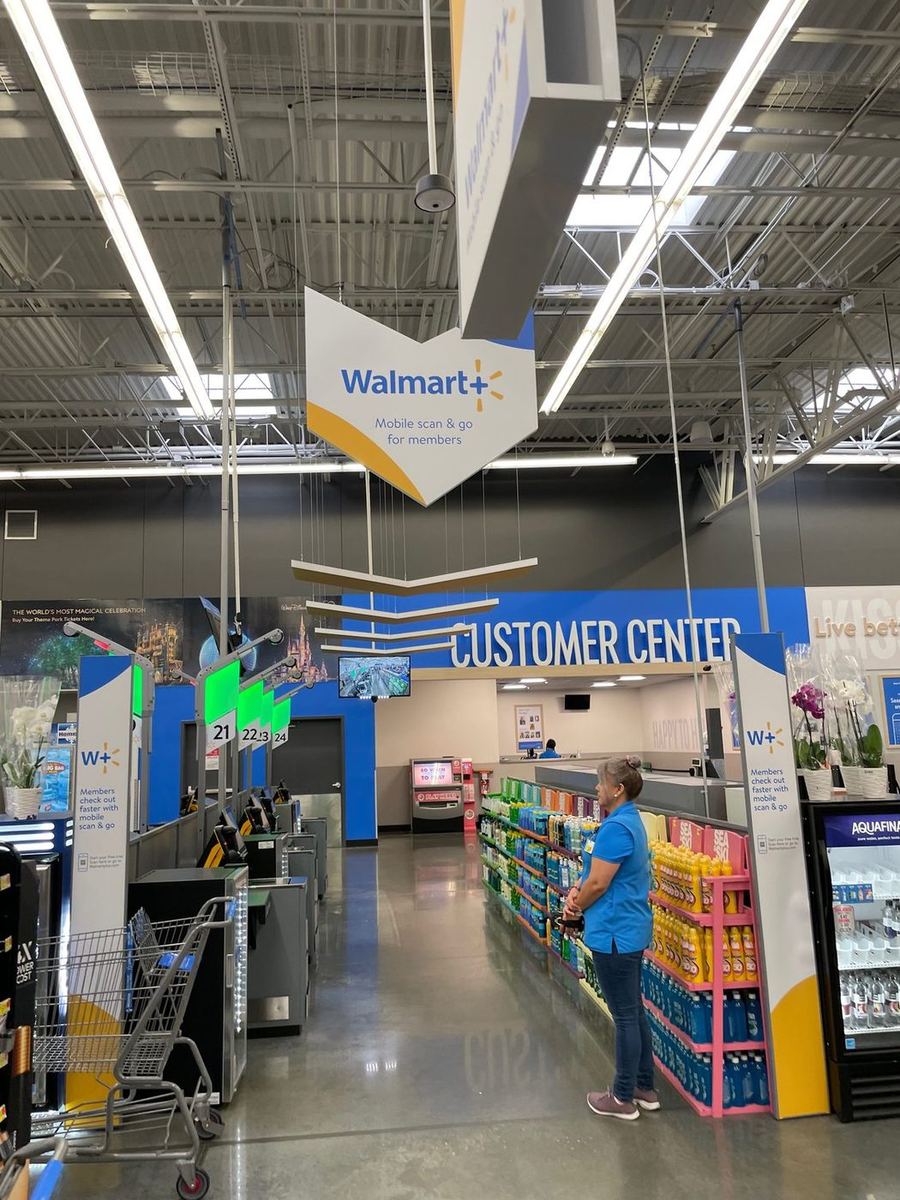
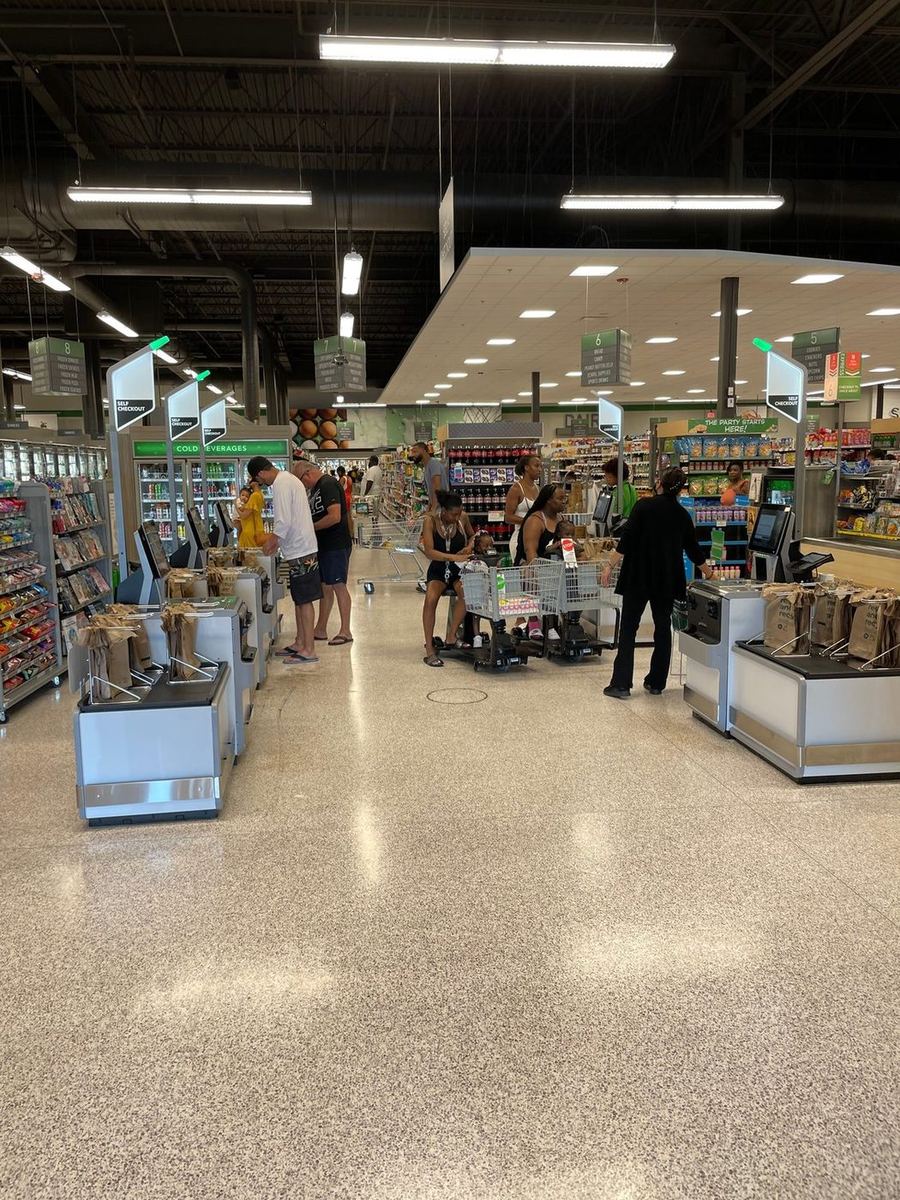
Even Publix (bottom picture) have added self service (on a trial basis one presumes) given their checkout operation being a point of difference from the market. They still have bag packers (for example).
Walmart are leading the way here and there were some stores that were hugely self service oriented with a reduced manned checkout operation to boot.
Of course Walmart+ customers had their own line and could use mobile scan too, but the self service operation (for a Brit) was a positive.
One negative for the self checkouts and how late Walmart (et al) are to them, is that the shrinkage issue via light fingered customers, honest errors and the rest of it becomes apparent.
It’s a big factor and inaccurate scanning affects all kinds of things, leading to poorer availability too. Not to mention a cash loss, technology is getting better at identifying problem transactions and the rest however.
Mobile on the rise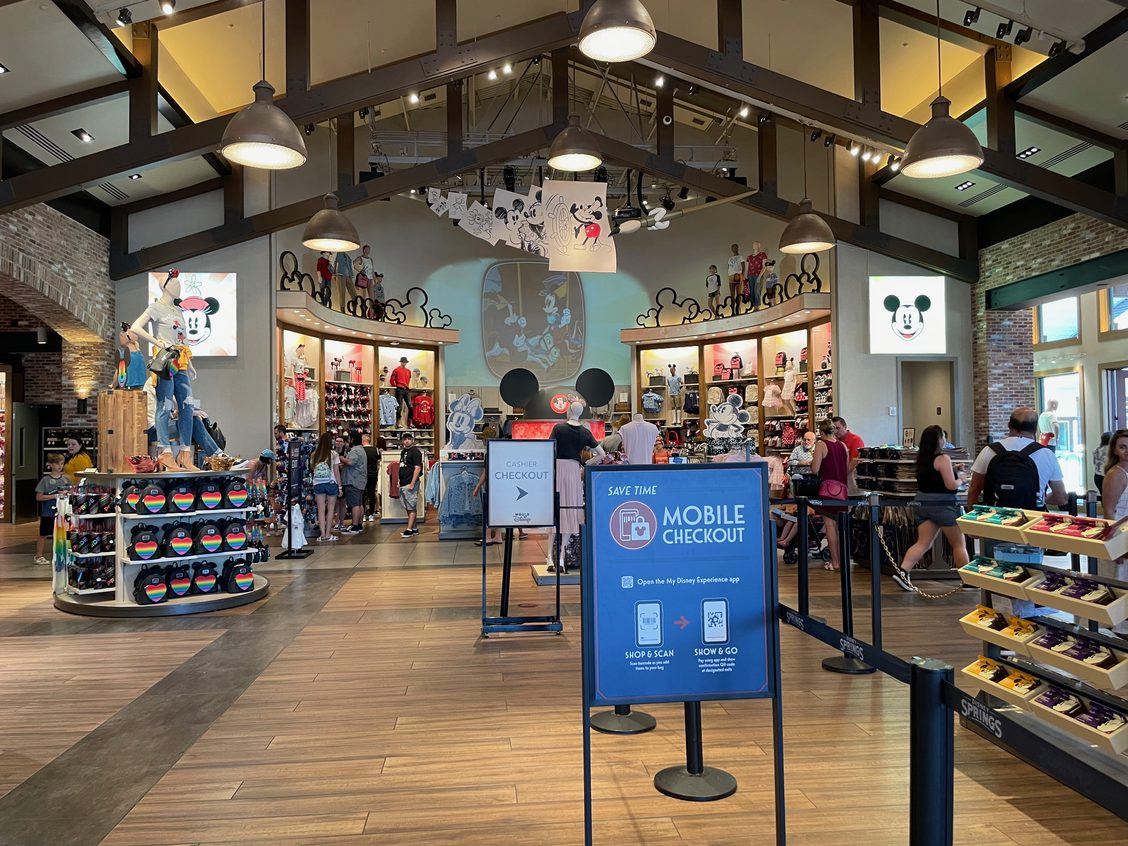
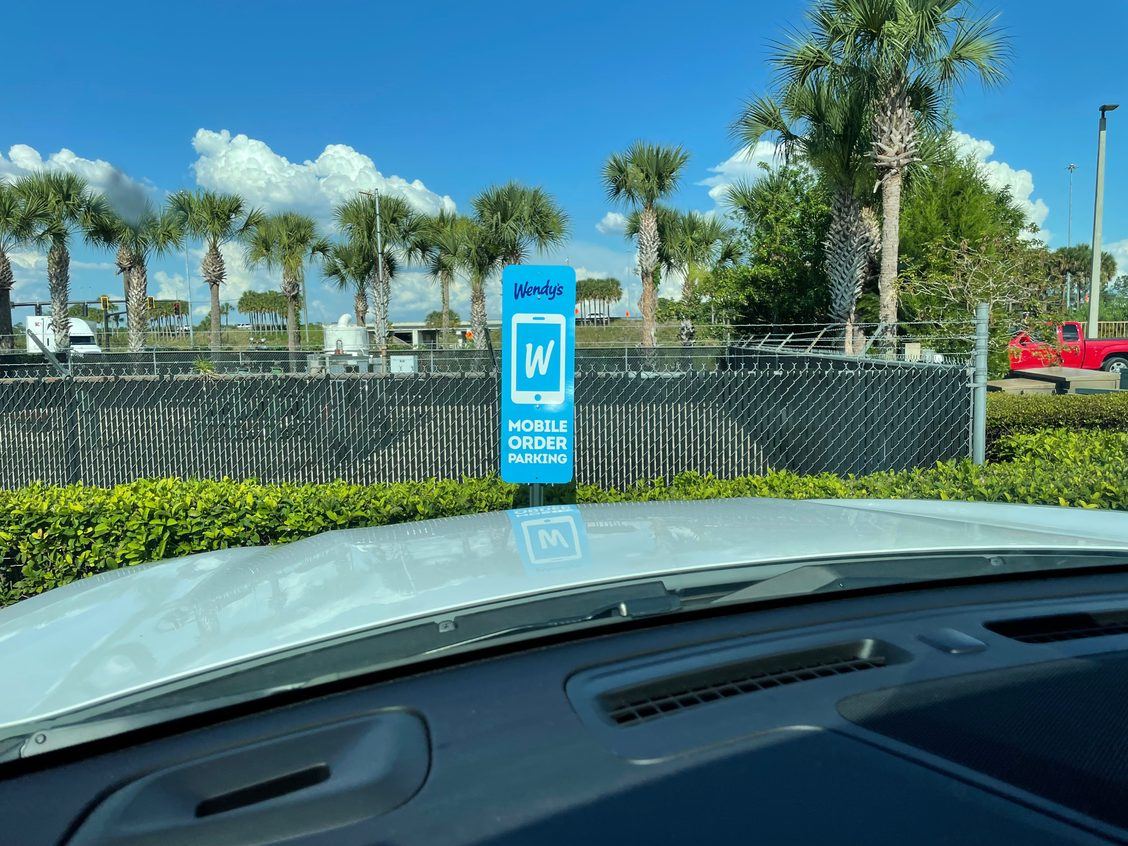
As we have touched upon; the pandemic has seen a great acceleration in tech and online, with mobile devices (already popularly used for pickup etc) really accelerating in all areas.
Mobile order pickup was noted at numerous food service outlets, often the servers would come out of the car, saving you even going inside.
Additionally Disney themselves were trailing a (somewhat) clunky version of mobile scan & go too in their stores. This allowed guests to scan their shopping then visit a strategically placed cast member for the shopping to be bagged and checked (presumably).
Target clearing inventory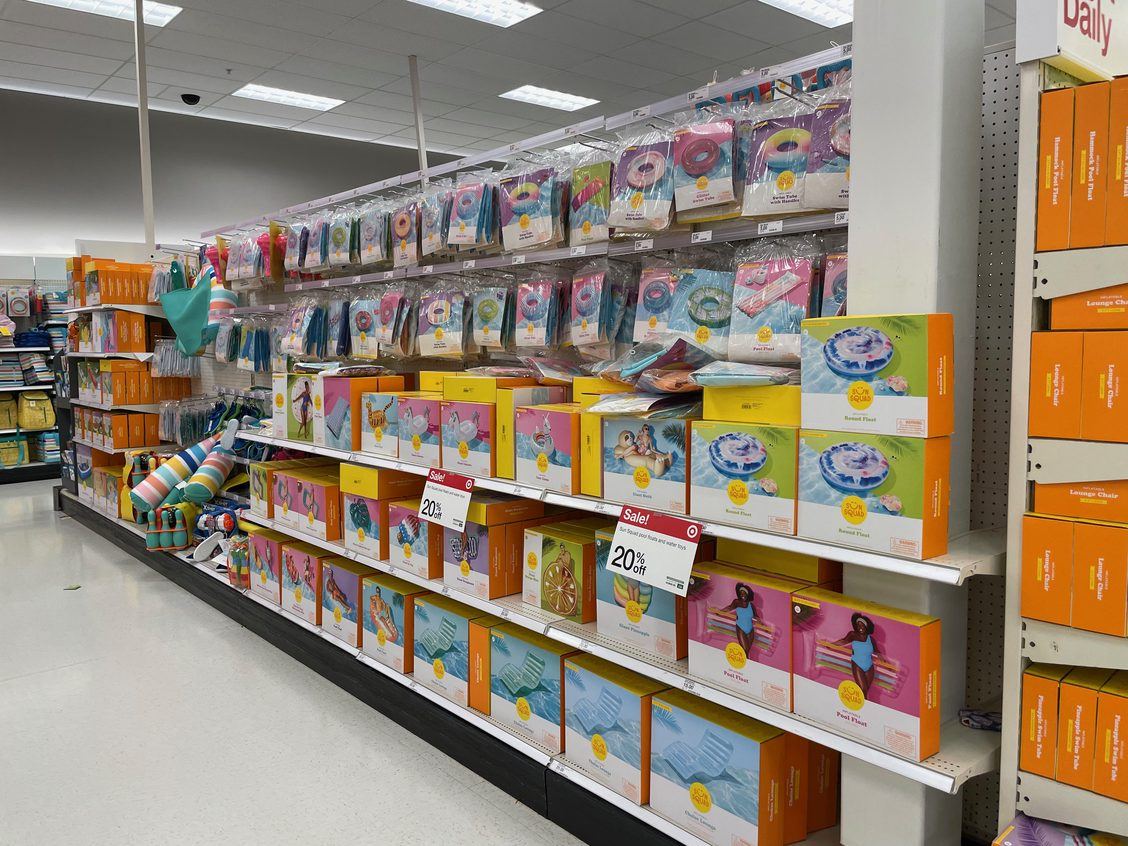
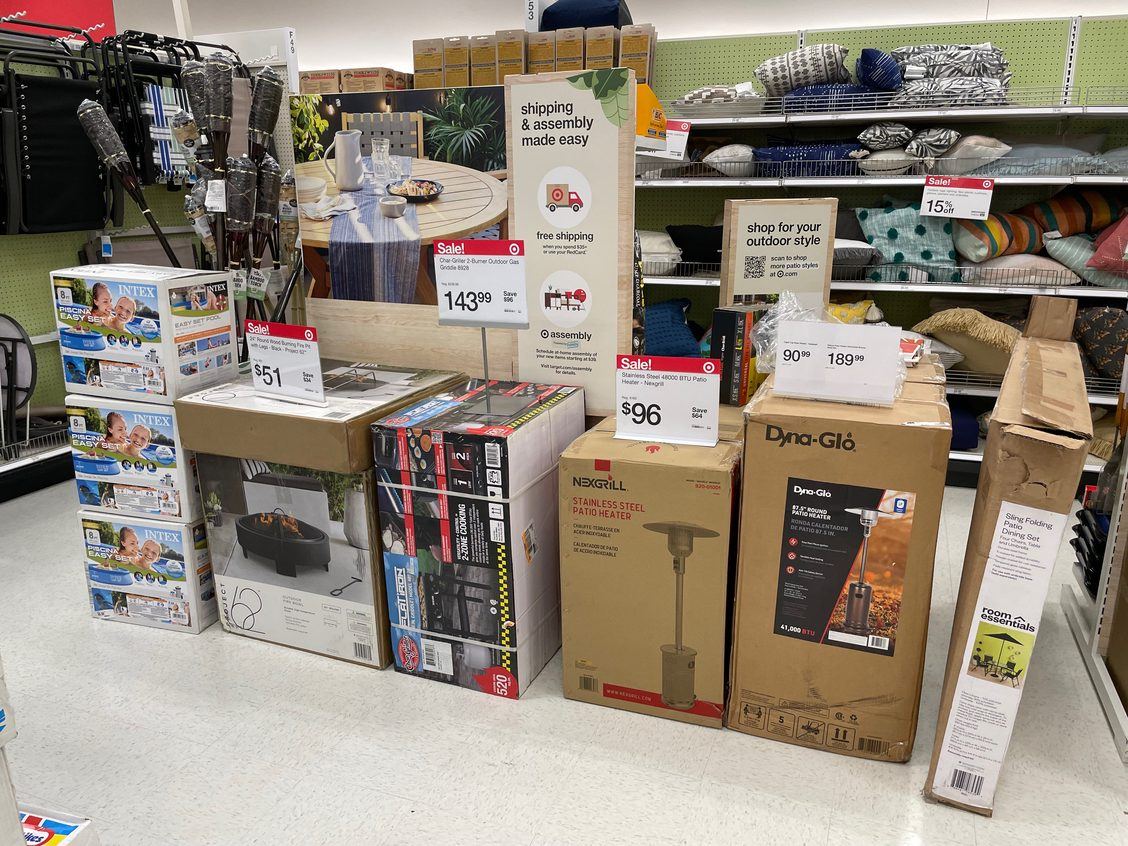
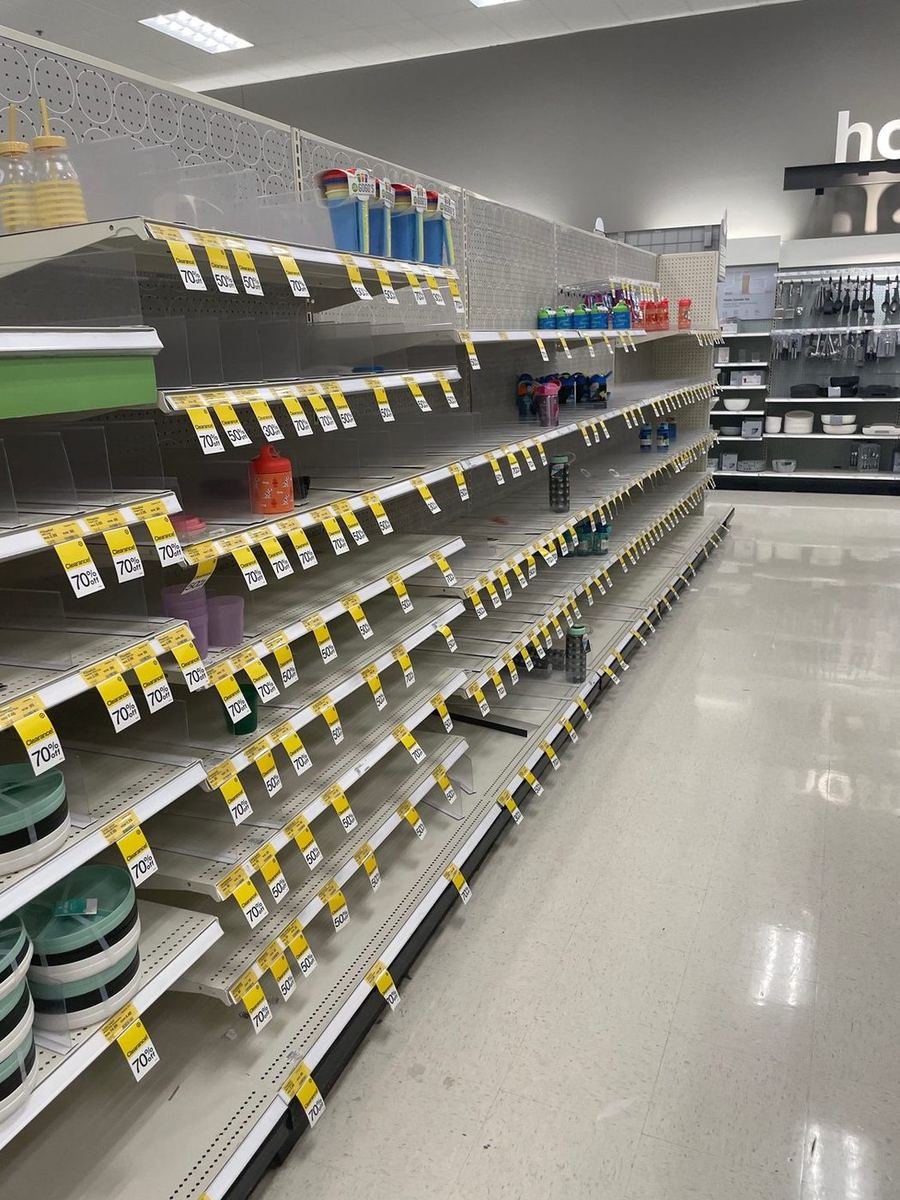
Even ahead of their announcement yesterday about the hit to margin for Q2, leading to further clearance and an improvement thereafter, it was clear that Target were relatively heavy in certain areas.
Clearance was actioned in non-food/homewares to the extreme here, but their Summer range of outdoor toys and the like felt very hefty with unilateral discounts applied.
In addition; BBQ/Grills were 40% off throughout the time we were there, so there was action being taken to sell the stock through.
But like anything - self help is what they need the most.
We bought a few things that were far cheaper at the register than they were on the shelf edge, great news for consumers but how many are put off by the high price that turns to out not to be?
Plaudits to them for taking action in a decisive way, it’s just one of those things post COVID where no one knew where we’d be. Boats on the water with stock turning up whenever and wherever. It all has to land somewhere, then it’ll be sorted.
So there we have it, some observations from our recent US trip, of course, much more to come around the specifics of what we saw, but as a “starter for ten” it certainly sets the scene well.
From the Grocery Insight newsletter archive, first sent to subscribers on 17 June 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.