Boots - would you invent it today?
11 June 2021
Benefit from our insight, today.
Want to pay monthly? No problem!
Do you want our expert eye to help your business?
Boots is a business that has branches everywhere and the smaller branches don't appear to have any less range than the larger ones in some categories, with a mass of product on dated shelves and an in store look, in many stores, that is also near historic.
Their reason for being is also a question - would you invent it today? They're a successful pharmacy but one would argue they're more well known for their work in larger stores with make up and cosmetics, their no.7 range (also seen in Target) and their relatively wide range of products.
3 for 2 on gifting is a byword for Boots at Christmas, but the market continues to shift and there are instances where this deal looks poor value versus work by the larger supermarkets.
Indeed, clearance levels post Christmas in some stores are hefty and there are justifiable questions about 3 for 2 and the value that it brings in this more modern world.
There is some positive work though; their cosmetics are strong but versus Superdrug (who we'll consider next week) there is a definite capturing of the younger market that needs to take place.
The accusation that the newer cosmetics halls are just window dressing with the rest of the store left to broadly the same is fair, the press will go take a look at Piccadily Circus Boots and other such concepts and leave broadly pleased.
An elevated cosmetics area generates great impact for the customer too; especially first impressions, but there remains an issue that beyond that, what else is there to show for their efforts.
Ranges are often hefty without a great deal of editing, there's a lot of product but no real assistance for the customer trying to find what they need. Some adjacencies are baffling, with sexual health next to smoking cessation e.g.
Some of their categories have a number of products that warrant further explanation and guidance is then needed, via signage, to explain and 'demystify' the category. However, this is also lacking and the merchandising and layouts don't help either.
We just see too many areas that are not thought through from a customer perspective, rather a spreadsheet and a layout, all important of course. But spreadsheet management means that we are sleepwalking towards a poorer retail experience for the customer.
In this space, there is ample competition too. Online is a major element with online pharmacies and the challenge for Boots in too many stores is that they excel at precisely nothing.
We have mentioned Superdrug already (who claim the younger crowd) but also the likes of supermarkets do a good job in this space, especially Sainsbury's with their newer look / feel in cosmetics.
It's another area for Amazon to also be watched closely; especially given their ambitions in the US to open drug stores, $6 prescriptions and the rest of it.
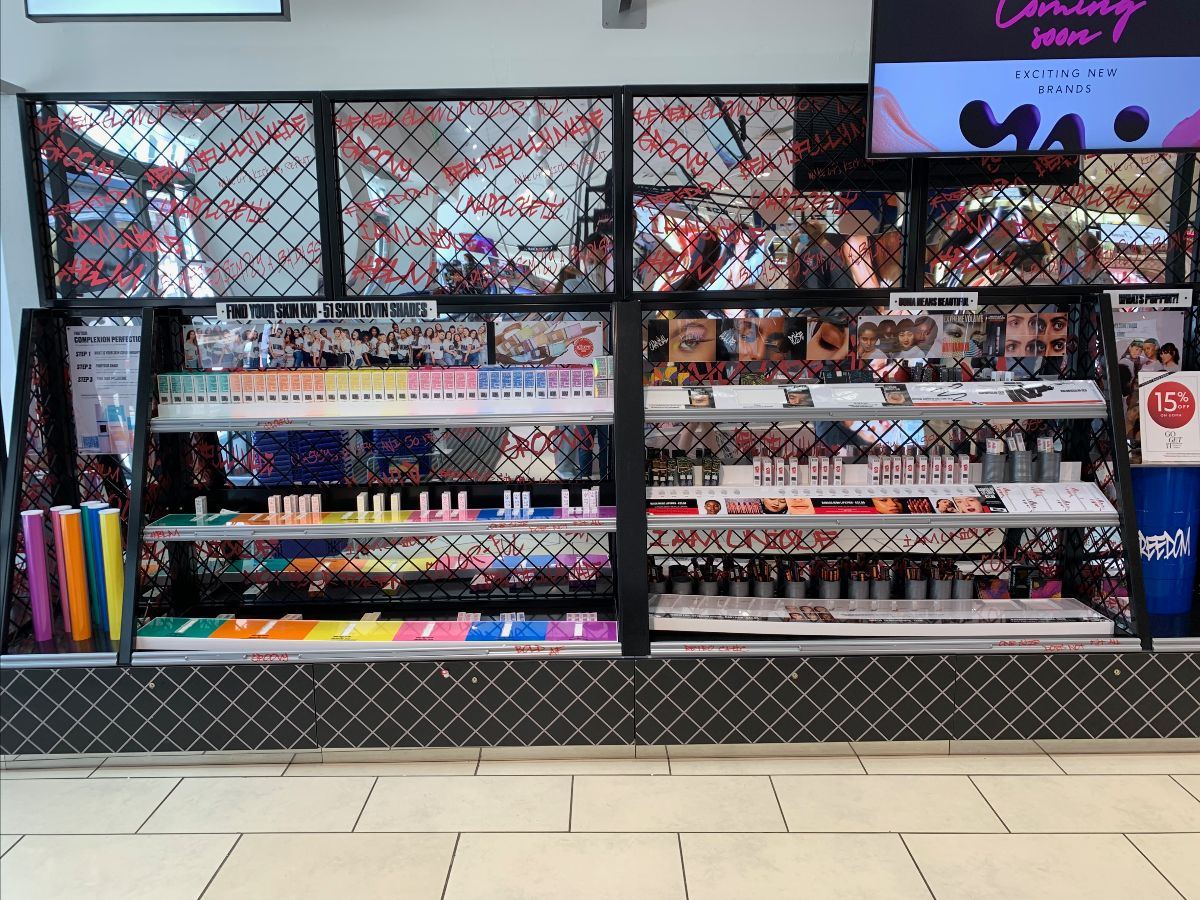
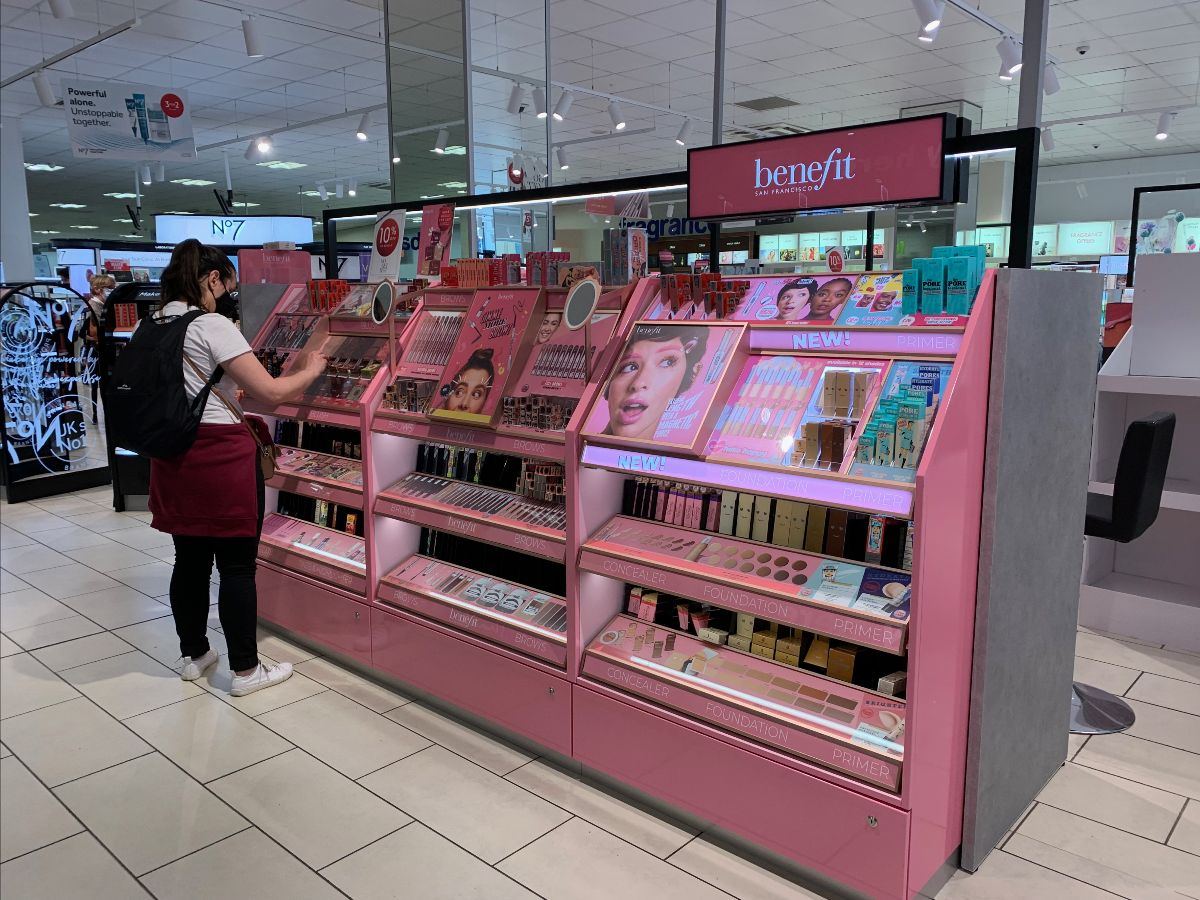
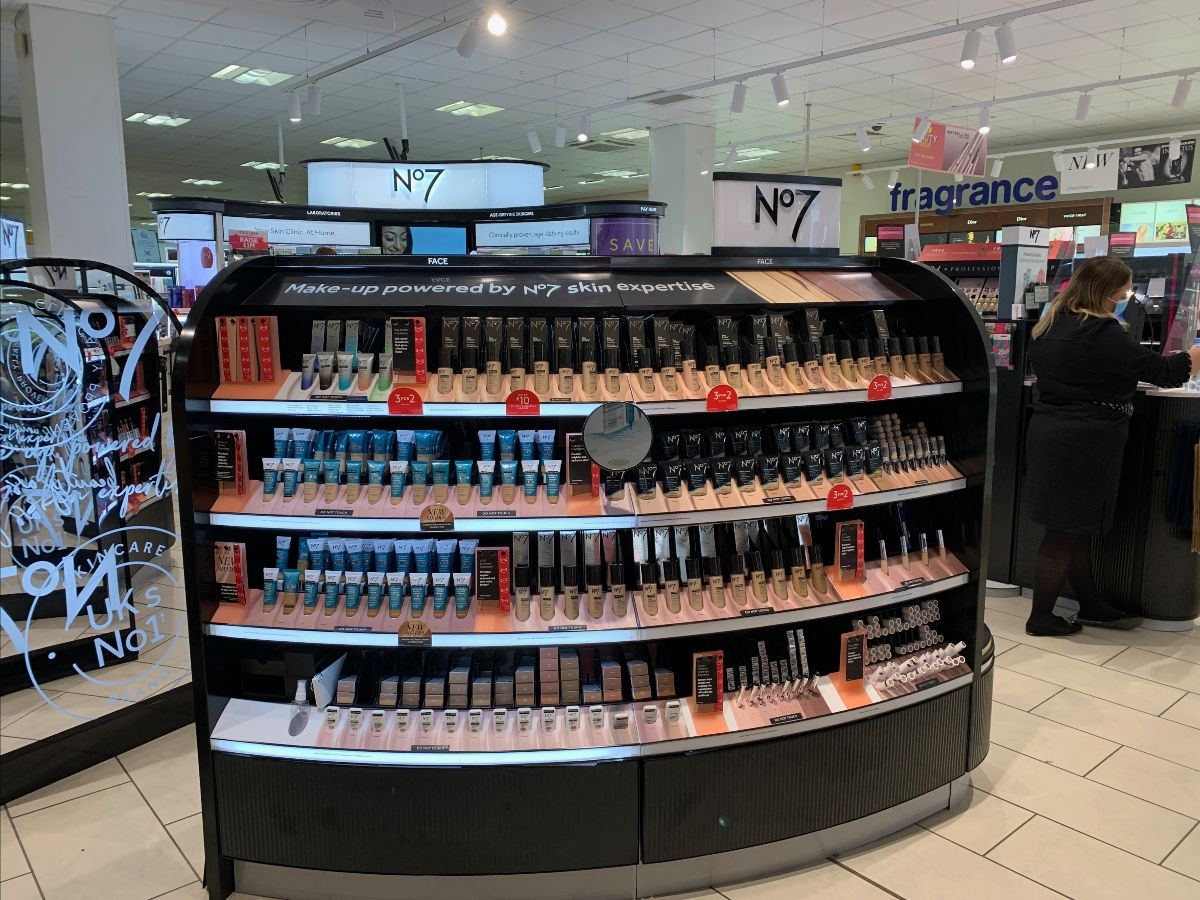
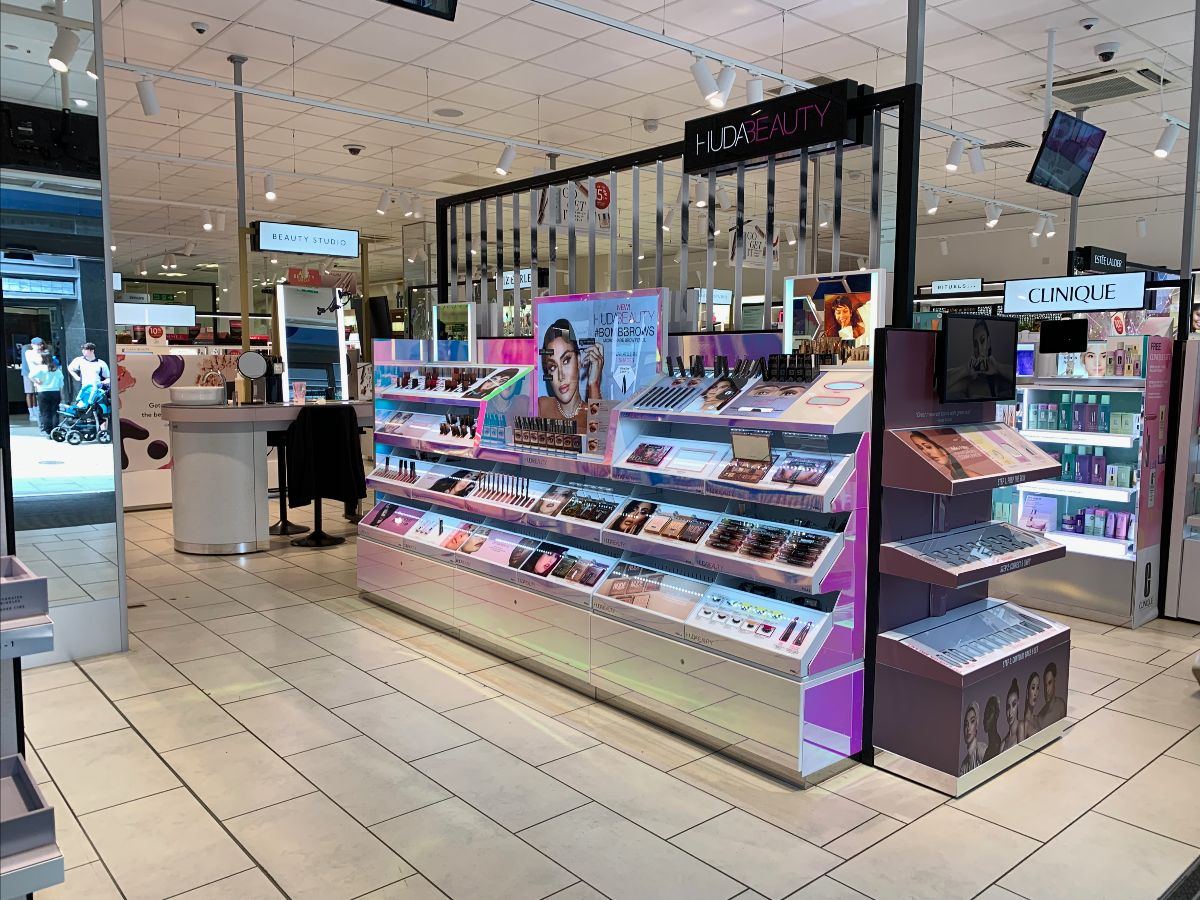
There is no doubt that the newer cosmetics kit is good, far stronger than what we have seen previously, however Superdrug are far less focused on the people aspect and instead, just have a long row of cosmetics displays down the side of the store wall.
Whereas Boots have a few colleagues about from Liz Earle and whoever else, which in COVID times remains questionable around customer sentiment and the safety aspect.
However those folks are a god send for people who come in with a problem, IE what product do I need, this is no good with my mask on etc etc.
The colleagues there are brilliant and it's a balance, and probably, a different customer to what Superdrug has, however, the younger customer base is more educated perhaps and more attuned to trends, with the socials aspect.
As that generation get older, where are they going to go for make up? Probably not Boots.
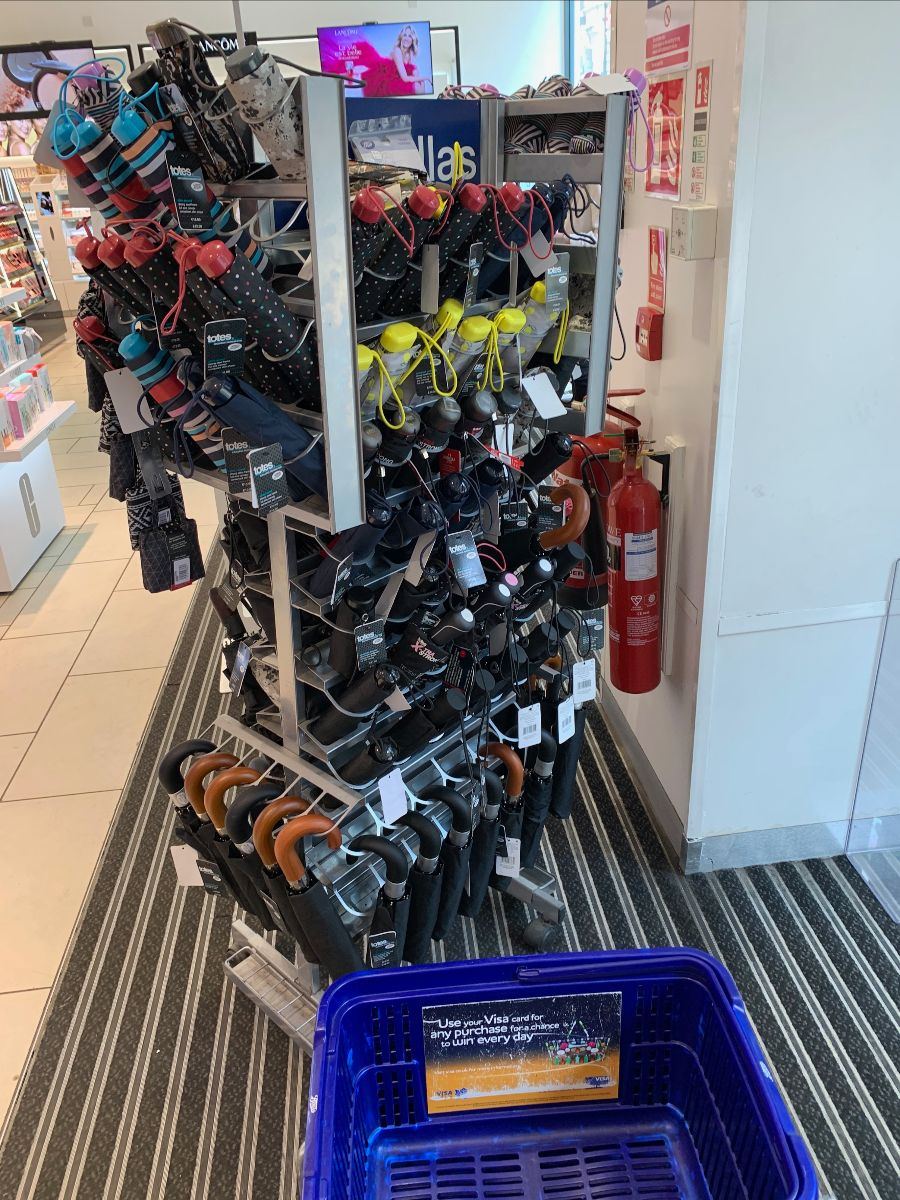
I raged about this on socials, with the weather comfortably over 20 degrees, the store still had Umbrellas on display outside, very poor trading, every customer was either asking where the sunglasses were, or had a pair apiece for their family members.
Opportunity missed there, every penny counts too!
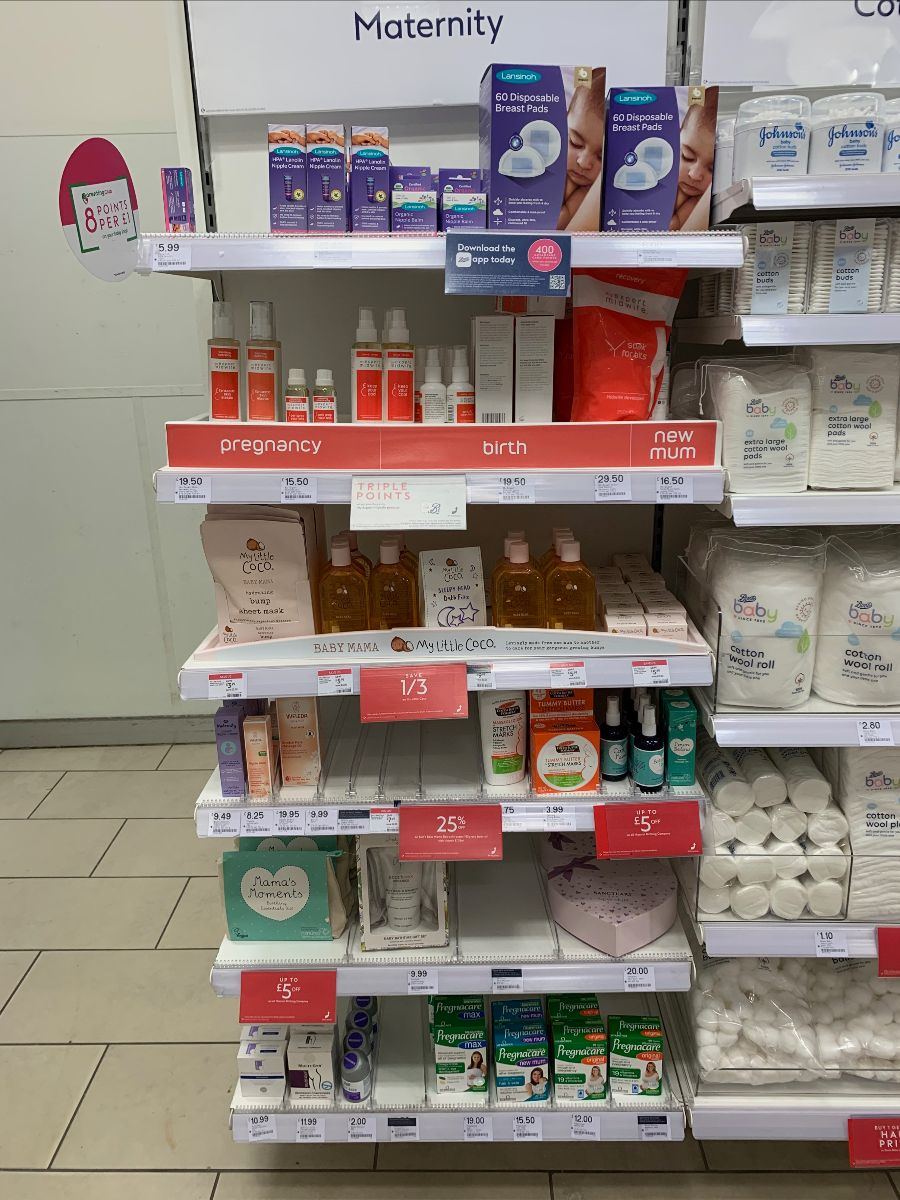
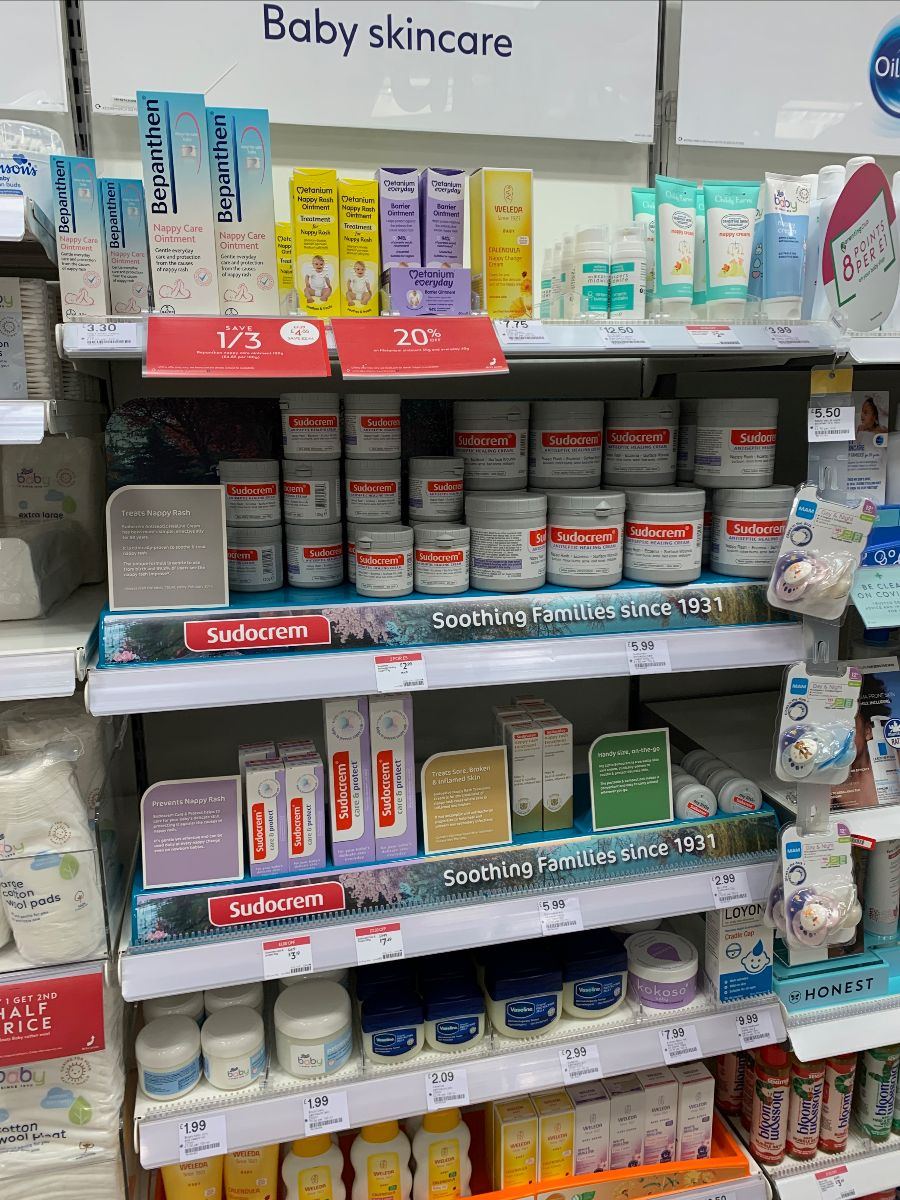
The plethora of products in some of the categories suffered the same fate as the ranges in John Lewis, they were categorised by how they were bought and what they did, rather than solving a mission per se.
Deals were also all over the place with both percentages and fractions used (a personal hate of mine) alongside ££ savings too. Too much!
There's some good product here and great range depth, however how do you navigate it? As a new parent or someone wanting to help by buying a few things, it's so hard to try and navigate for customers.
Why so many types of one product too(?)
Also top picture, note Pregnacare vitamins on the bottom shelf! Lost entirely!
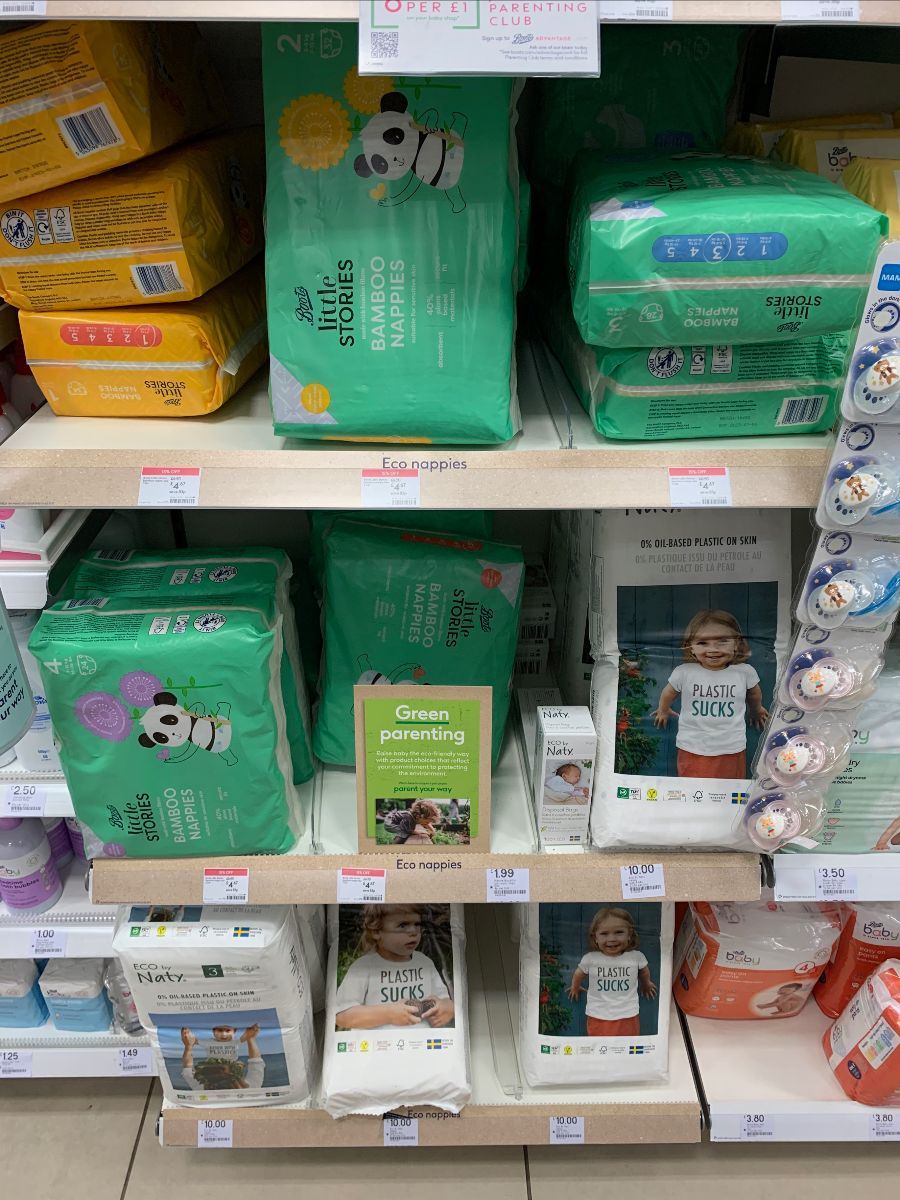
Some strong work in Nappies with their own label but also these bamboo nappies that contain no plastic and are better for the planet.
The ultimate in nappy work for the planet are cloth nappies but alas, this is not an easy balance to strike in terms of range and ability to communicate, notably, Boots do sell these.
Their Bamboo nappies for green parenting are a step fin the right direction. More comms needed, i've barely seen a mention bar in store.
Are they the same absorbency? Customers won't necessarily take the risk at £6/£7 that they're as good as conventional, some form of guarantee or information is needed.
Because at 3am, changing another non-absorbent, leaking nappy...The last thing on one's mind is saving the planet.
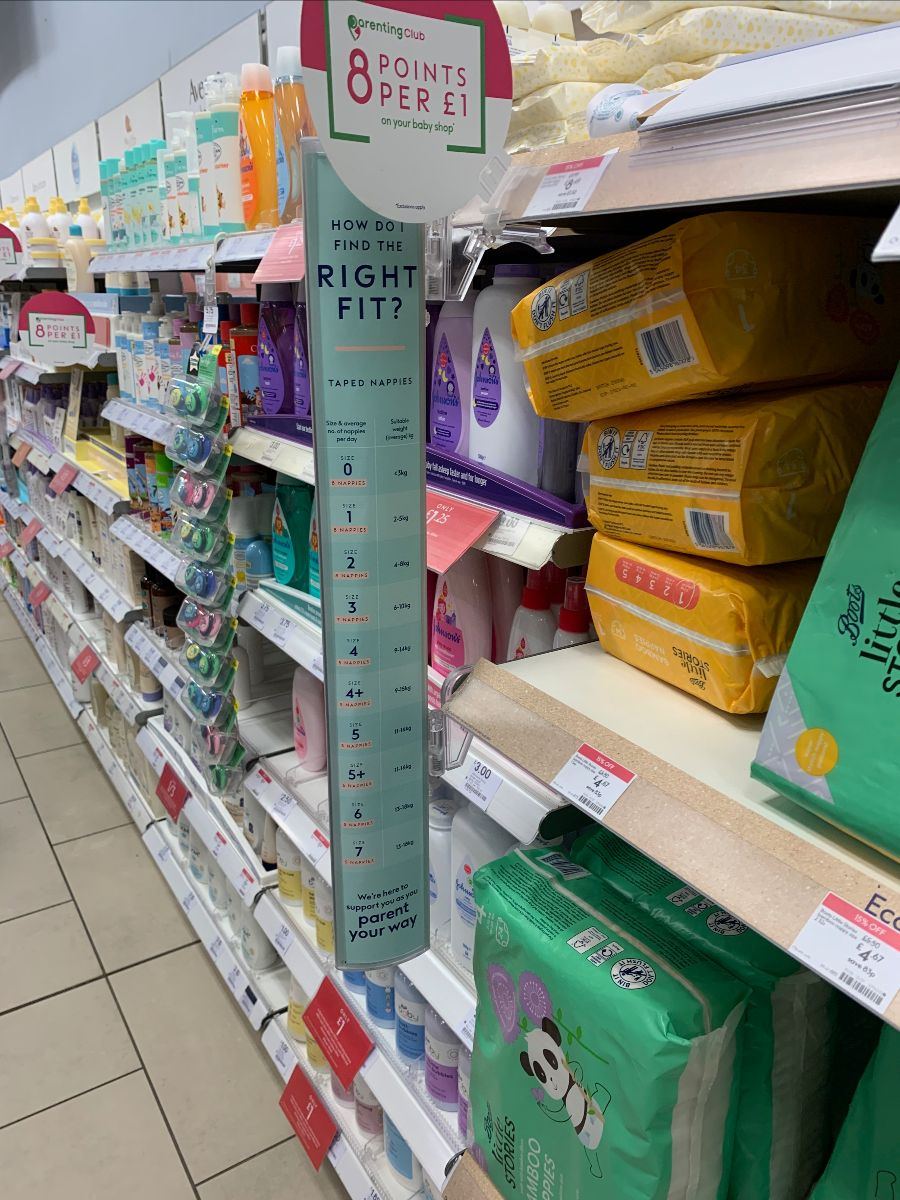
Their points are chucked around for the Parenting club card holders, with the Boots card still popular with the various offers they trade. Although the booths that were in store have long gone, replaced by the app no doubt.
The right fit signage was too hard to navigate for a customer, near pointless.
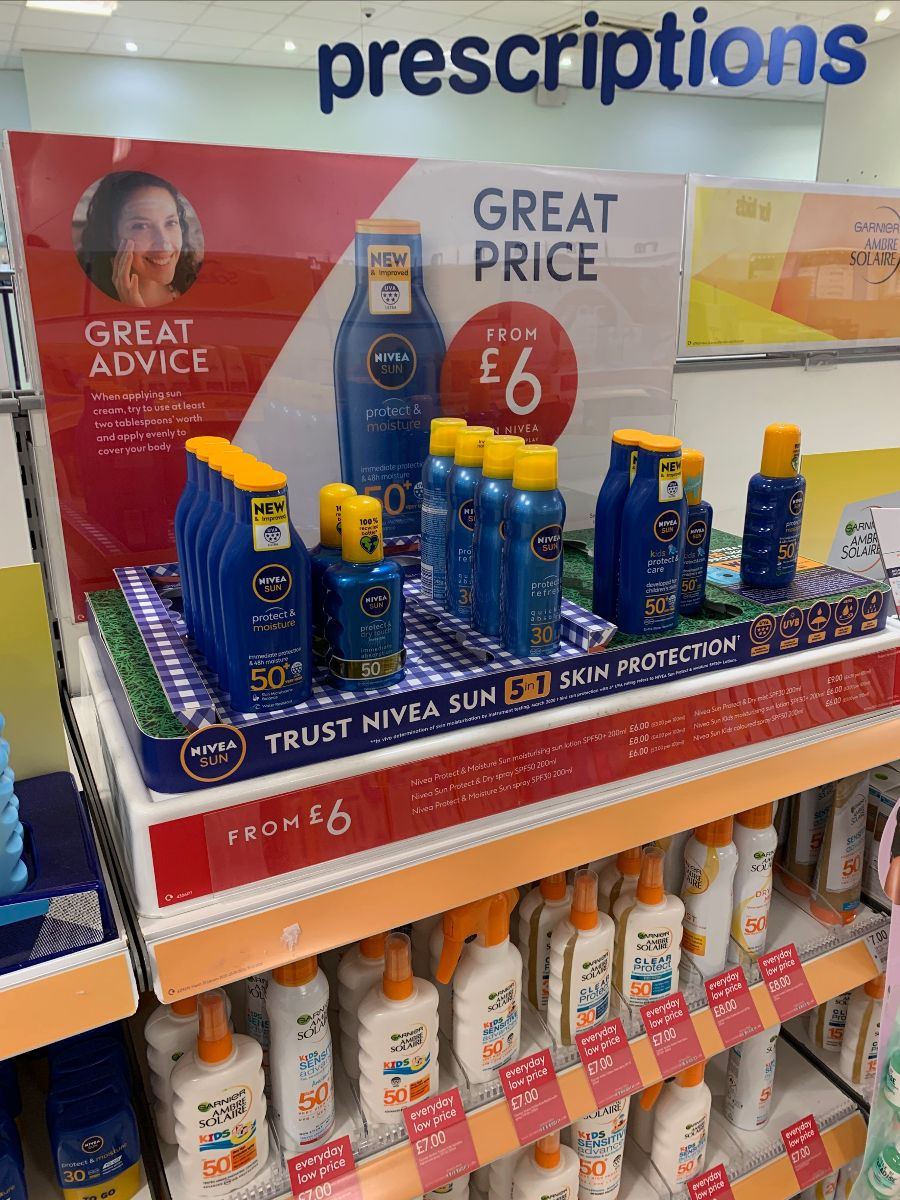
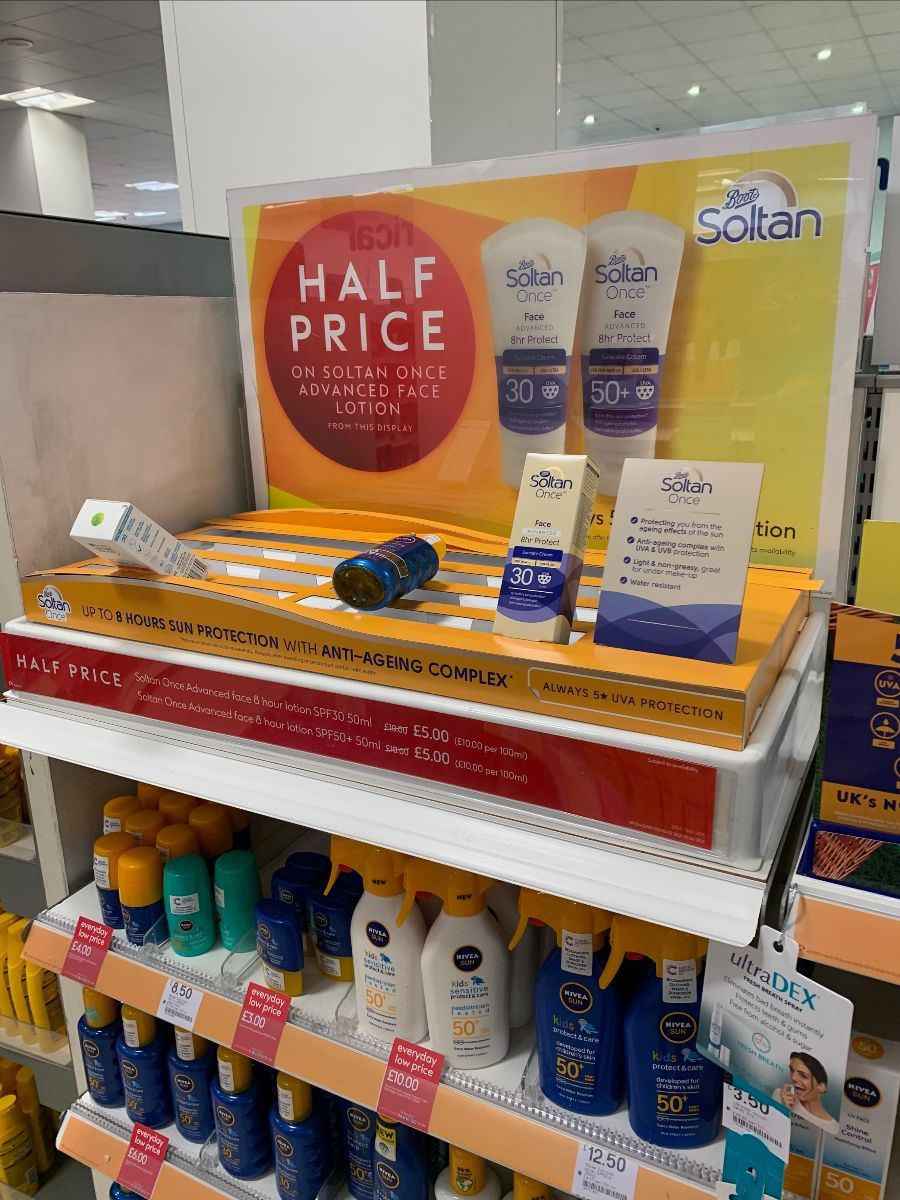
Unclear where the value is in Sun Care here; the own label is the bigger prize of course with Lidl pushing hard with theirs again and Tesco (run by ex Boots man Ken Murphy of course) also pushing hard with their own label equivalents.
Boots do push the branded signage in and around the categories, nothing wrong with that per se. However, it can detract from the message around value on shelf, as you end up with about 12 competing messages.
Even the everyday low price signage is overworked and just becomes blinding.
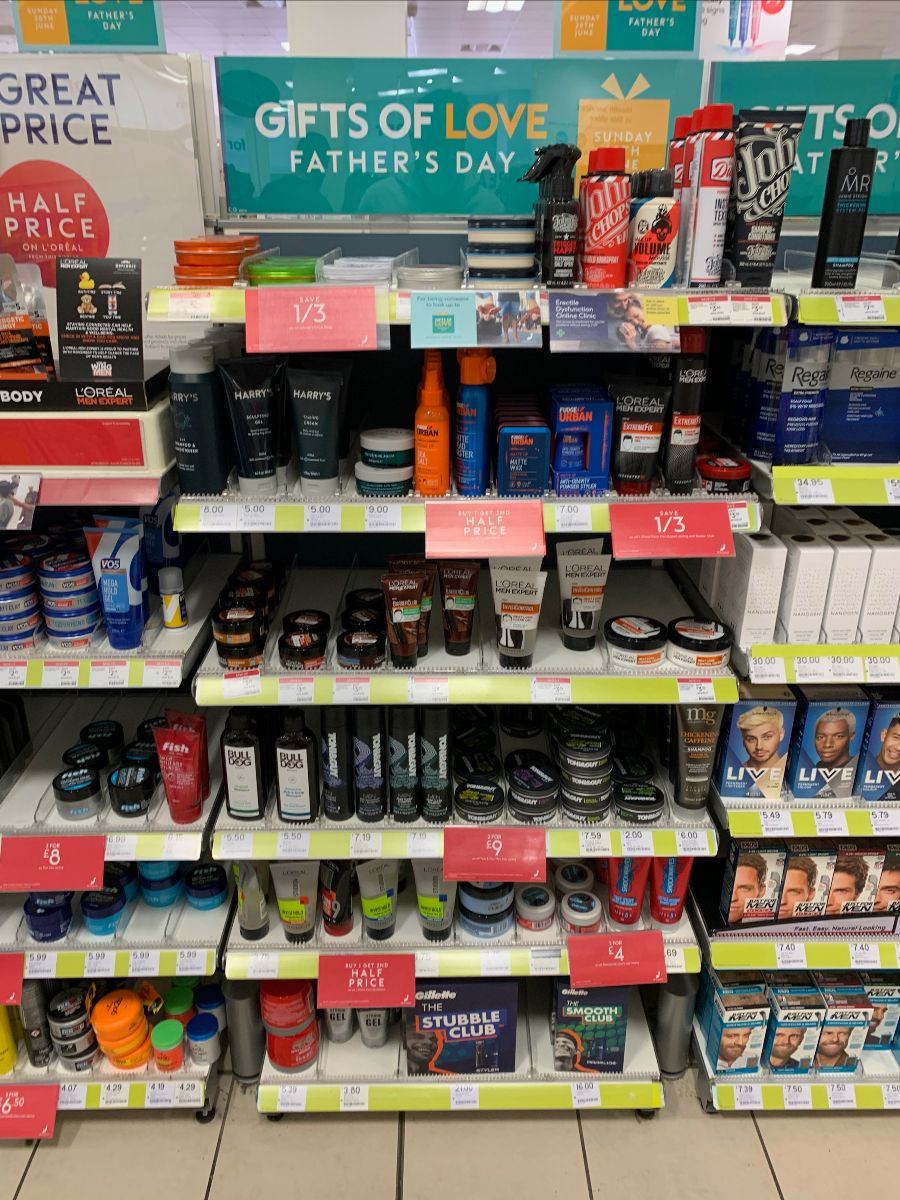
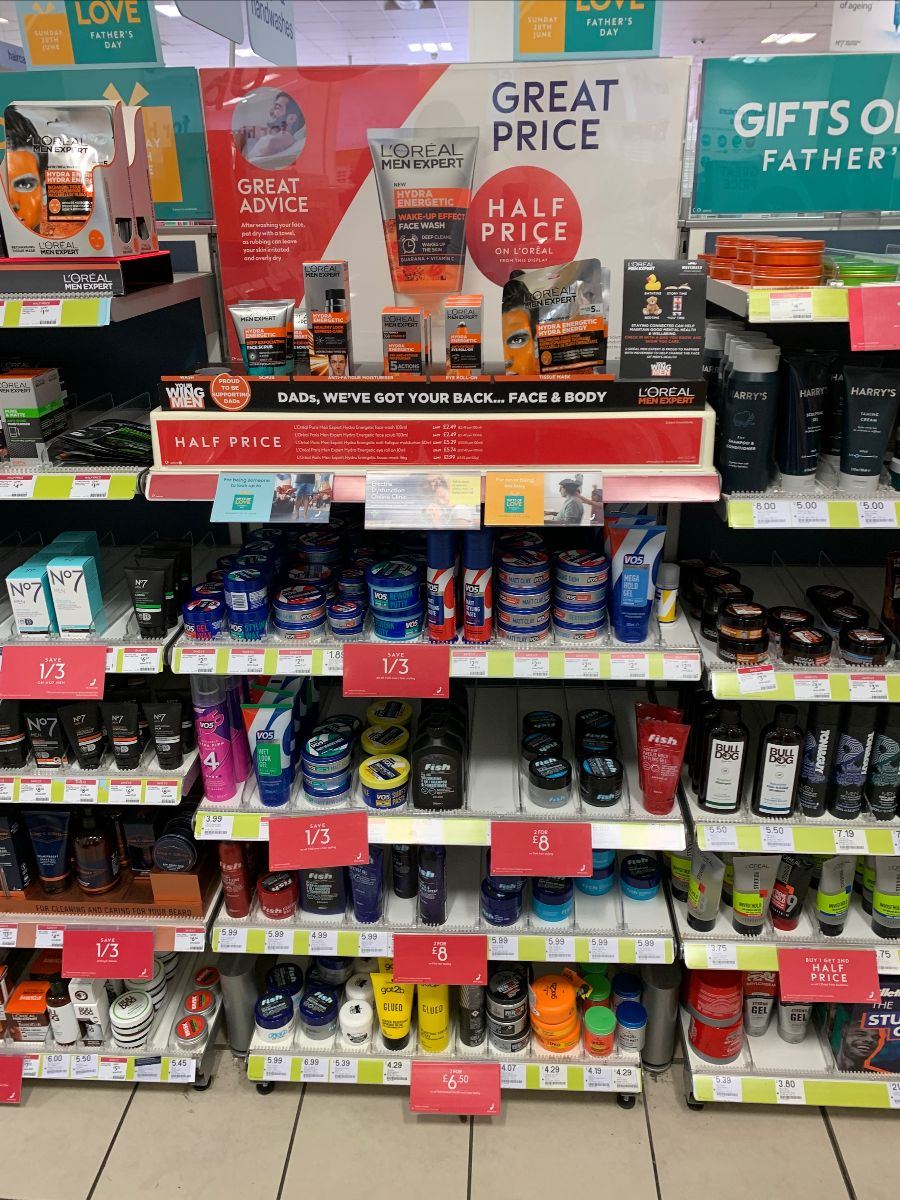
More overload of signage and messages here; sure - looking ahead of Father's Day, this isn't perhaps typical but there are a lot of comms here, what do customers look for first?
We have Save 1/3, Save (£) based messages alongside half price too, another bay features fractions with Save 1/3 and better than half price too.
It's a lot to take in and the construction of the bay often just ends up looking confused. Where is the value - it's so hard to tell.
Which means that must make the numbers hard to both forecast and achieve, thus some deals will perform worse than others, leading to overstocks in some lines and availability issues driving frustration in others.
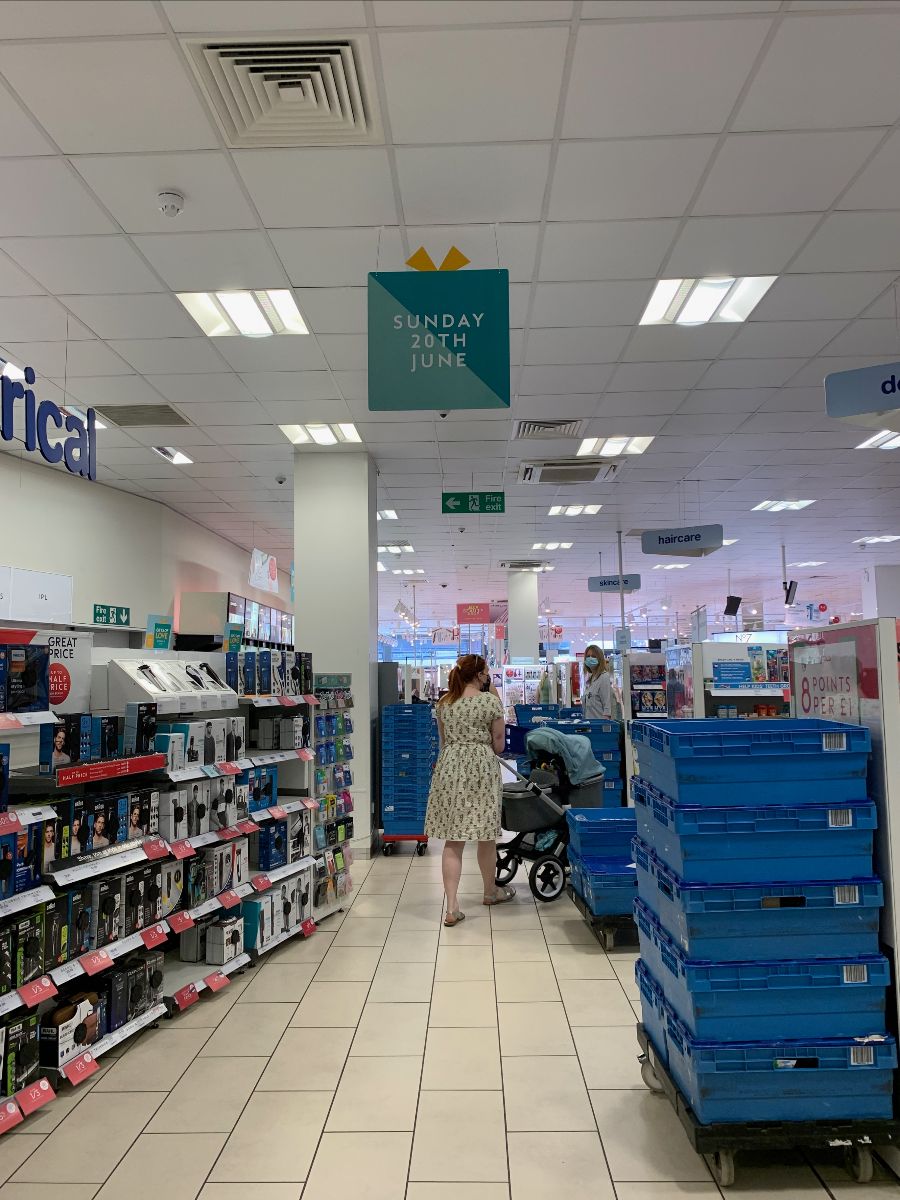
Saturday morning at 10:30 am - still lots of stacks out and about as colleagues replenished. However the aisles are tight and if anyone is down there shopping, you're almost pushing yourself past, right against the side of the shelving.
They were parked neatly enough but still caused some degree of aisle congestion.
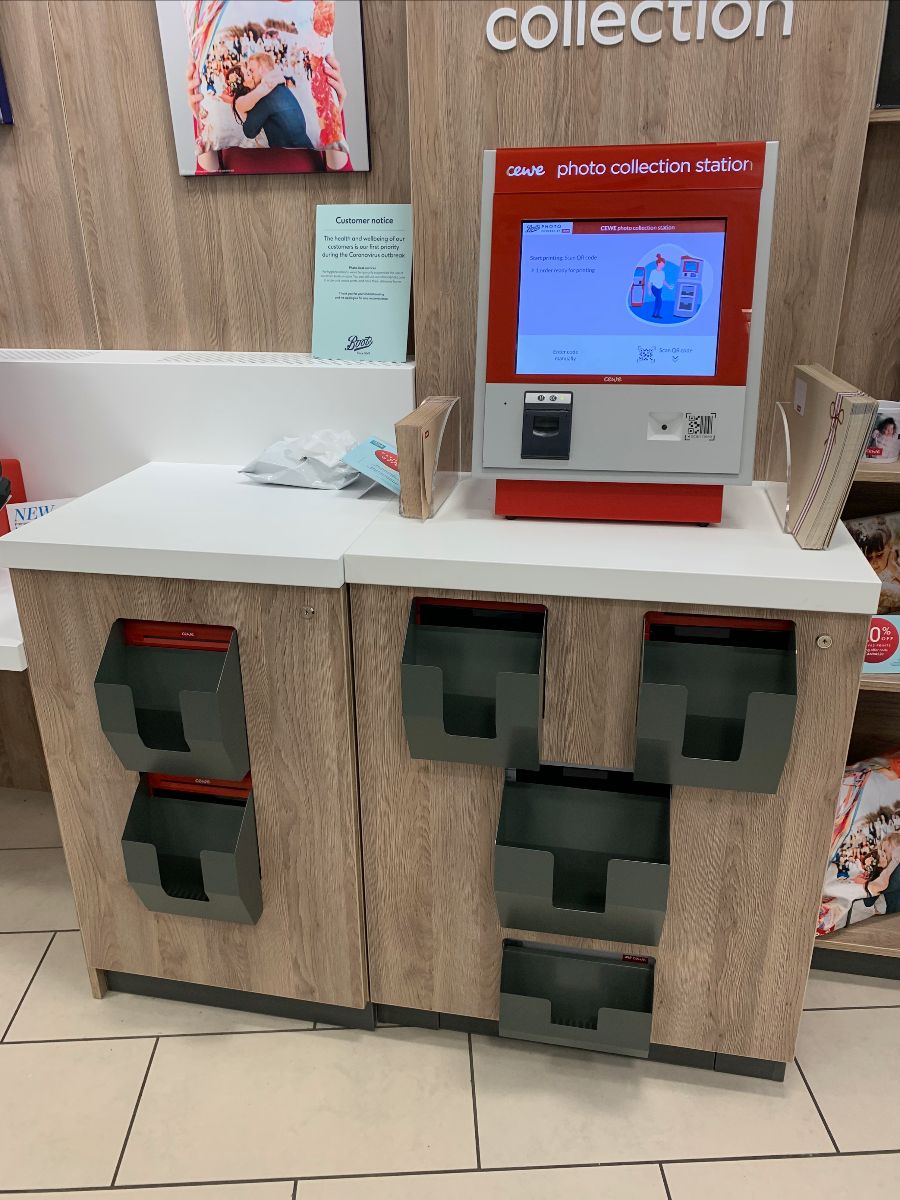
Despite the store being refitted at the front, and in some cases, it seemed at the back with this new photo shop / lab area. The middle of the store remained the land that time forgot, with the same shelving, category management issues and poor adjacencies that plague Boots stores up and down the land.
The photo shop was a fair effort but these are dying a death given the plethora of online photo labs that can turn product around in 24 hours. Alongside this, COVID means a number of machines were out of service due to social distancing too.
There were a number of holders that were empty though and other areas that had things just left around, not a great impression to customers at all.
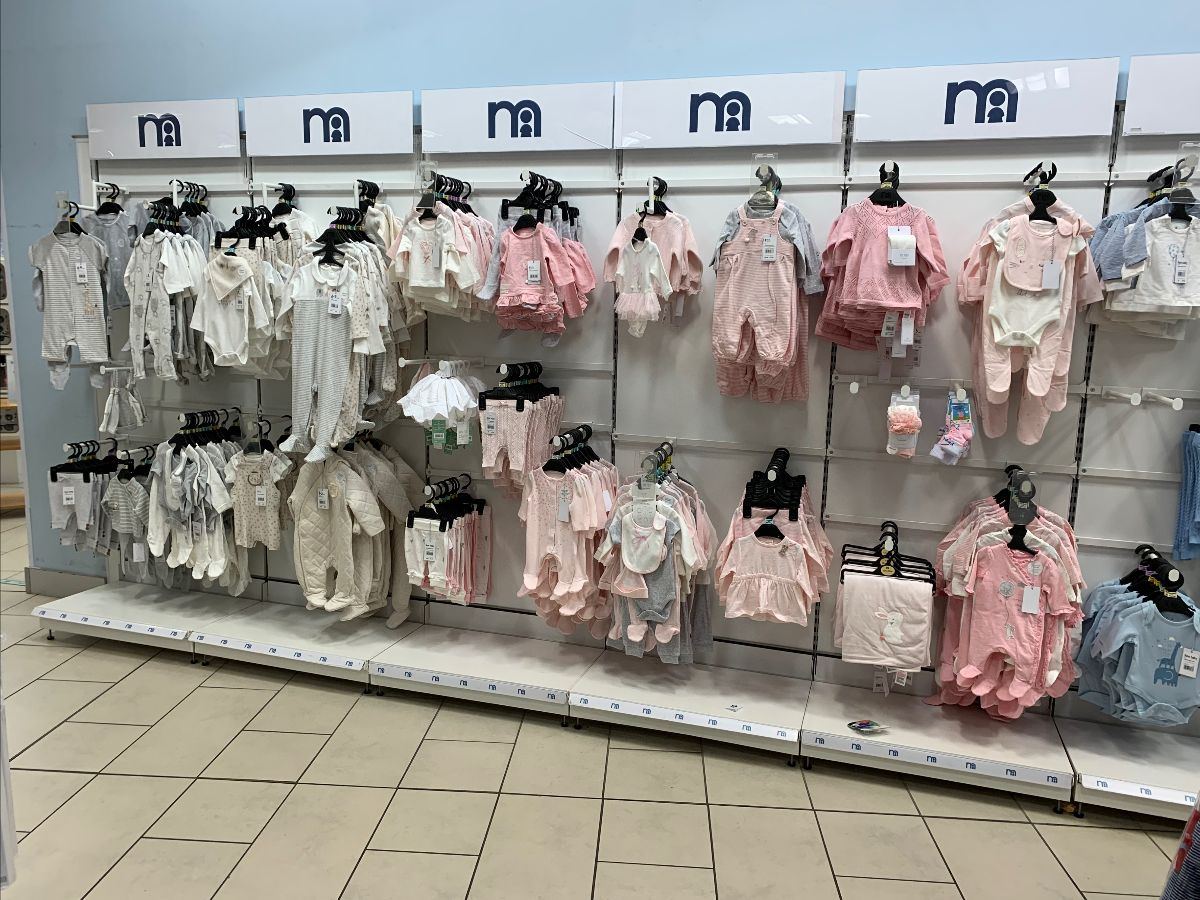
Mothercare clothing too, my word. The signage is poor, as is the range and the look/feel is akin to the early 90's.
There are so many others that do a better job in this space.
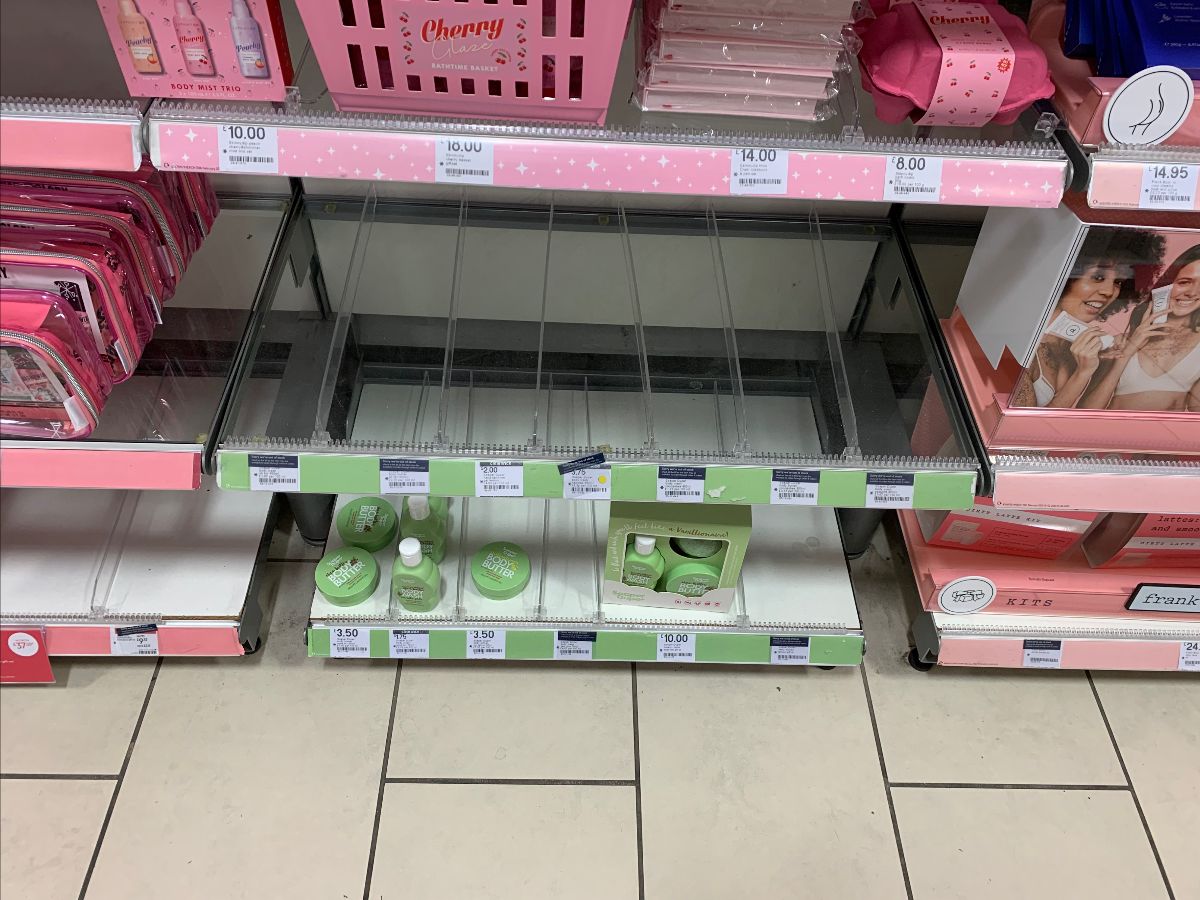
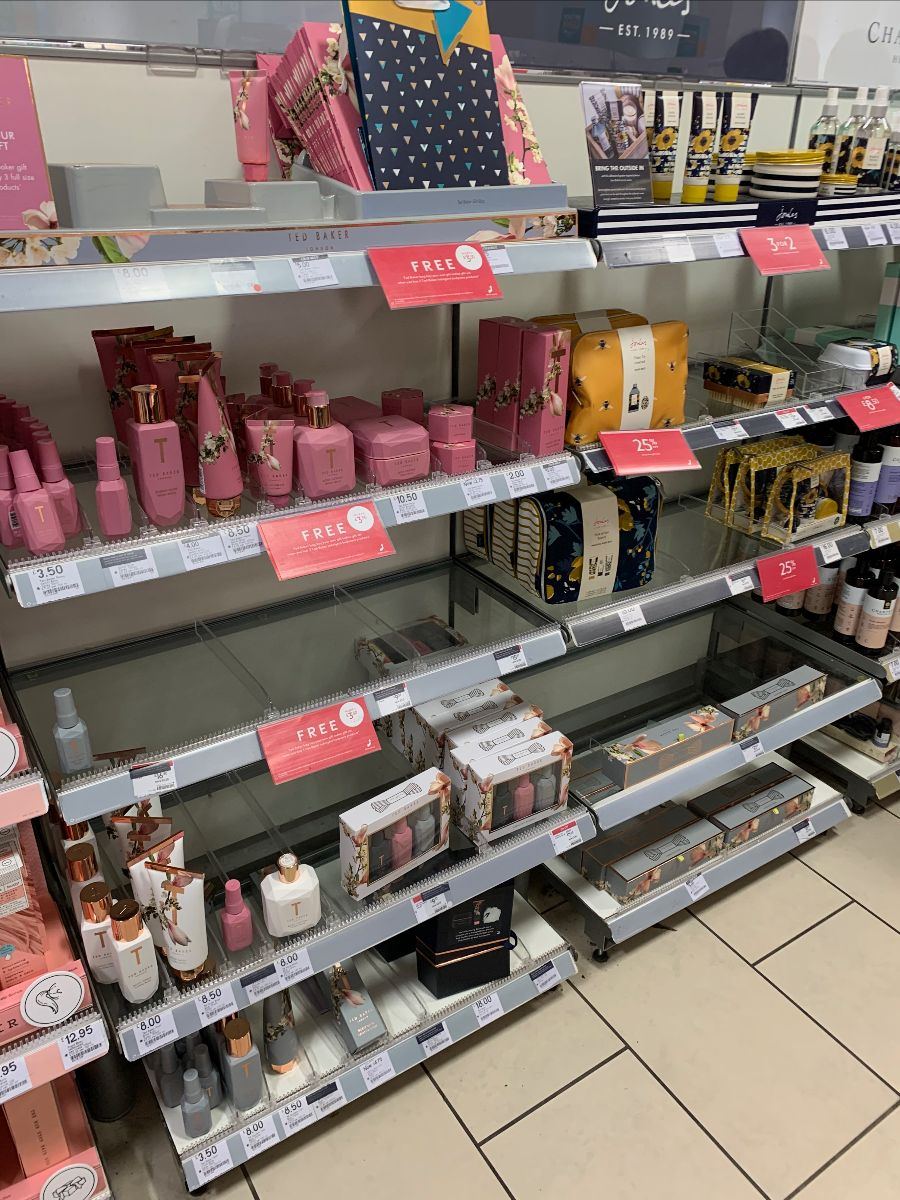
Numerous gaps were opening up too in key areas; gifting notably, alongside some other key brands in cosmetics, never ideal and pointed to some supplier issues perhaps.
The secondary image features another deal which could have driven trade without necessarily helping the availability picture.
Cross category deals are never easy to manage; given they encompass a wide range of product and therefore it's hard to accurately forecast who will buy what, across the range.
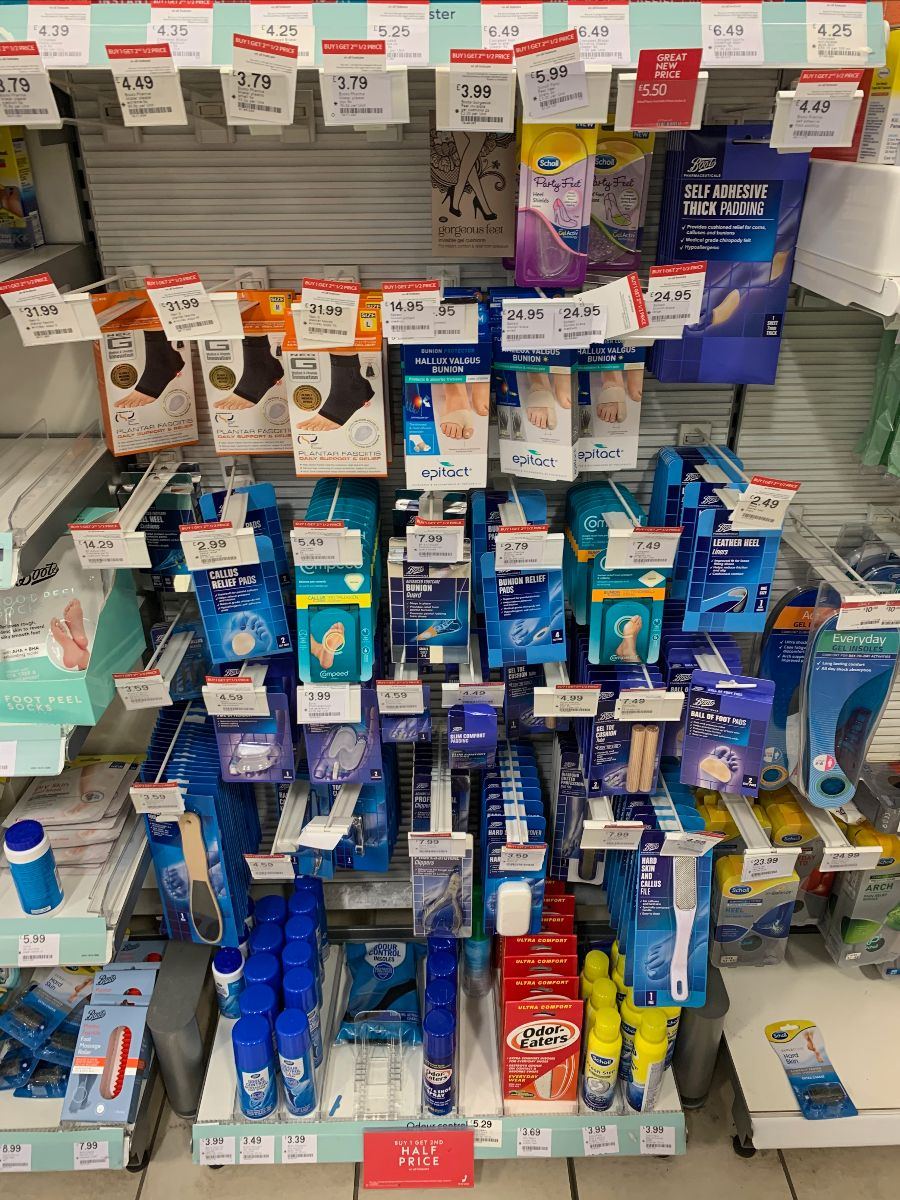
A great example of a huge, huge range without any real effort to demystify this for a customer. Where do you start?
What are you looking for?
How do we find it?
The merchandising plan is all wrong with hanging product too, just a mess and near impossible to navigate and find what you need.
A few gaps and deals were also present but hard to communicate due to the smaller nature of the range / labels.
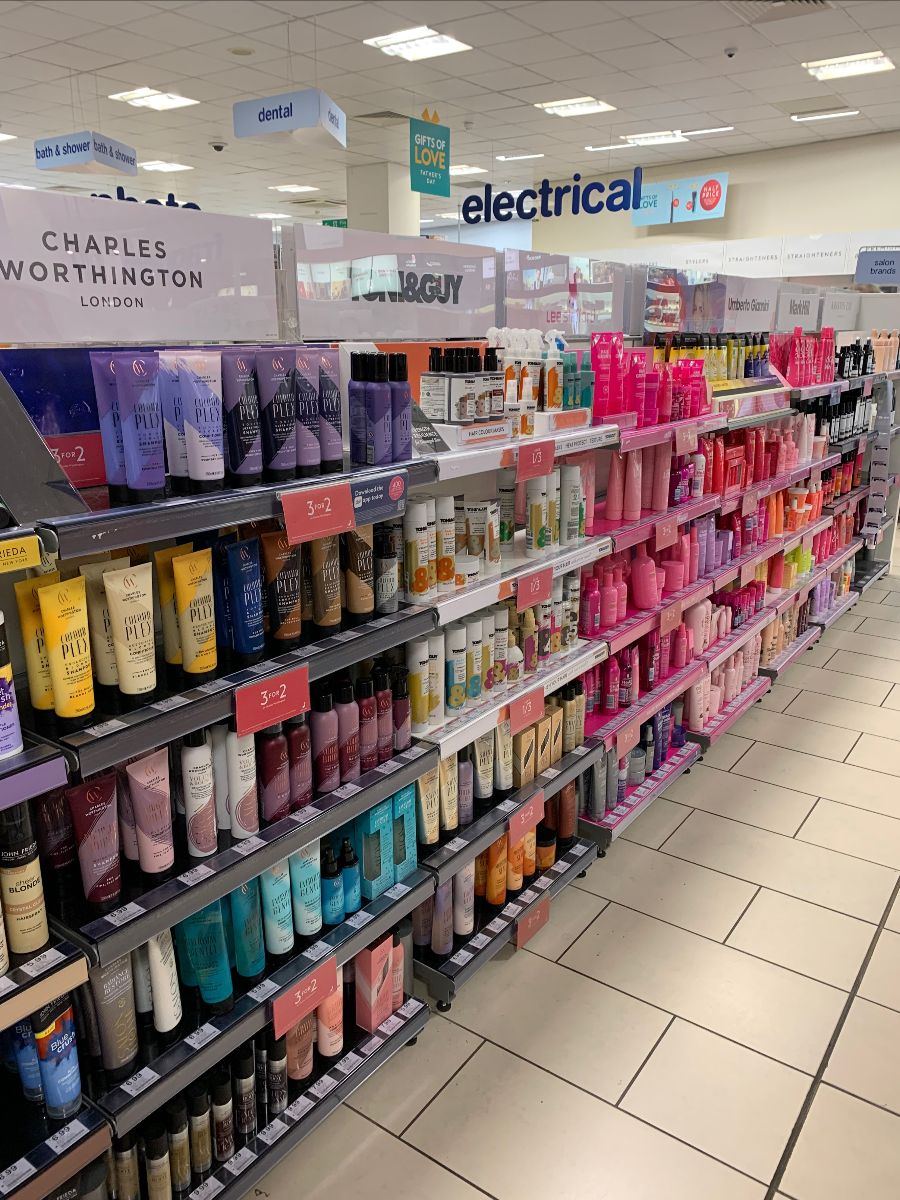
A huge range of Shampoo and Conditioner which is done via brands and looks well; however is the space just rented to the brands?
It's hard to navigate. For loyalists to brands it's easier, one suspects, but the rest?
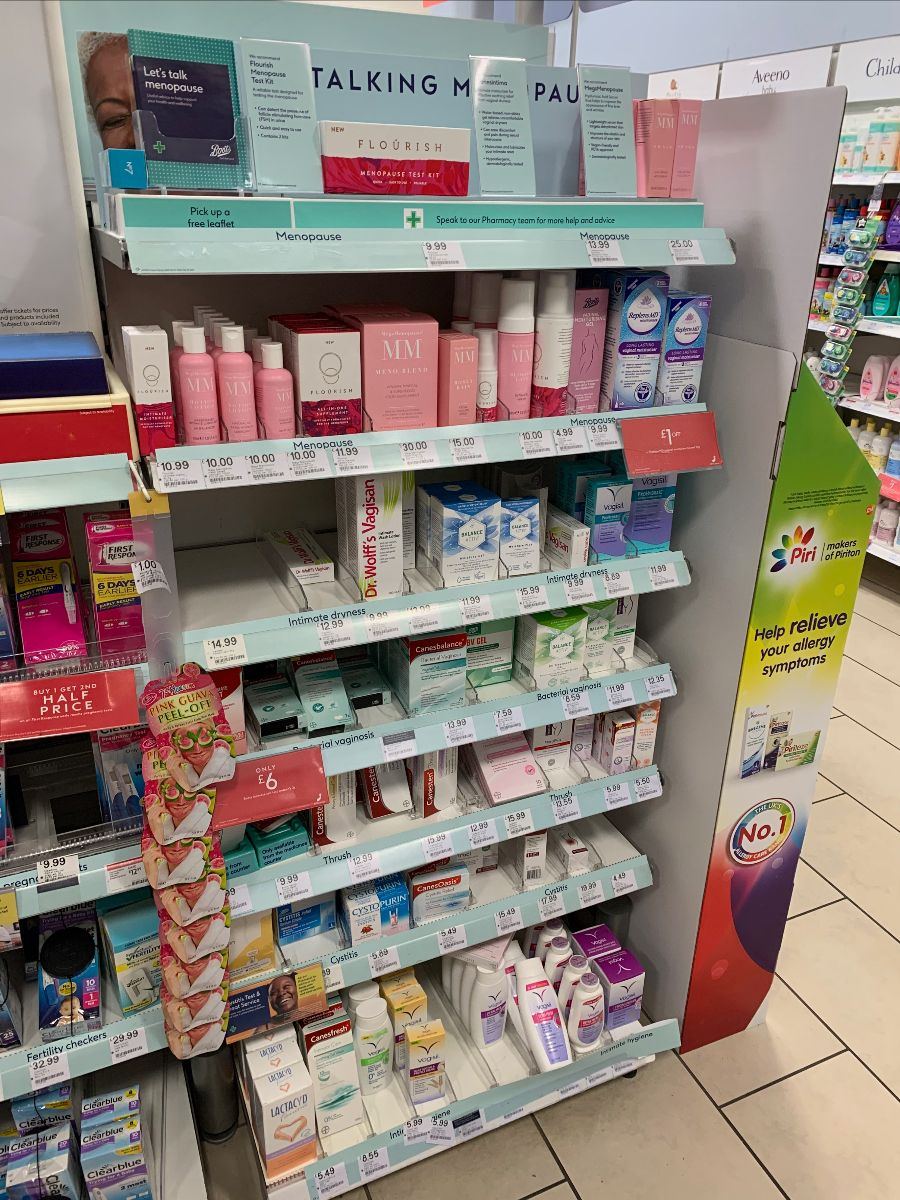
Feminine care too; there are a number of products here that are lost, some, one assumes are pharmacy only but this isn't the case necessarily....
But finding what you need here? No chance, just impossible.
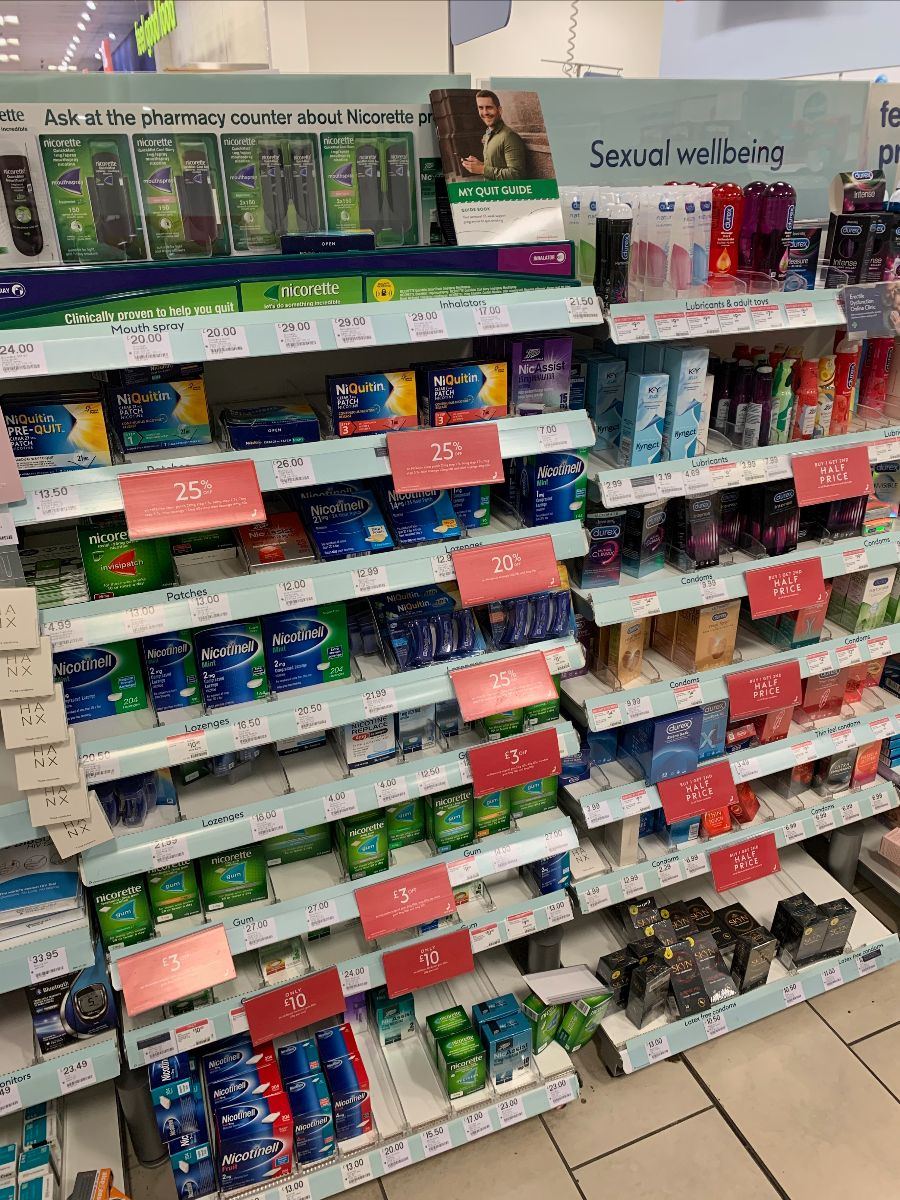
How many deals in stop smoking? Note the location next to Sexual health too (?!!?)
25% / 20% / Save £10 / price point advertised. All manner of confusion, again, customers may know what they want here. There is some category management on the shelf edge (mouth sprays, patches etc) but it's too small to be really meaningful.
More space is needed for these categories to let them breathe, the store still trades irrelevance like photo frames that take up space, sell slowly, impact working capital and add little to the customer journey.
Whilst categories in growth, like smoking cessation and all that comes with it, gets the range expanded to keep pace, whilst not expanding the space.
Leading to a cluttered fixture that's hard to shop, hard to fill and thus leads to poorer availability and lost sales.
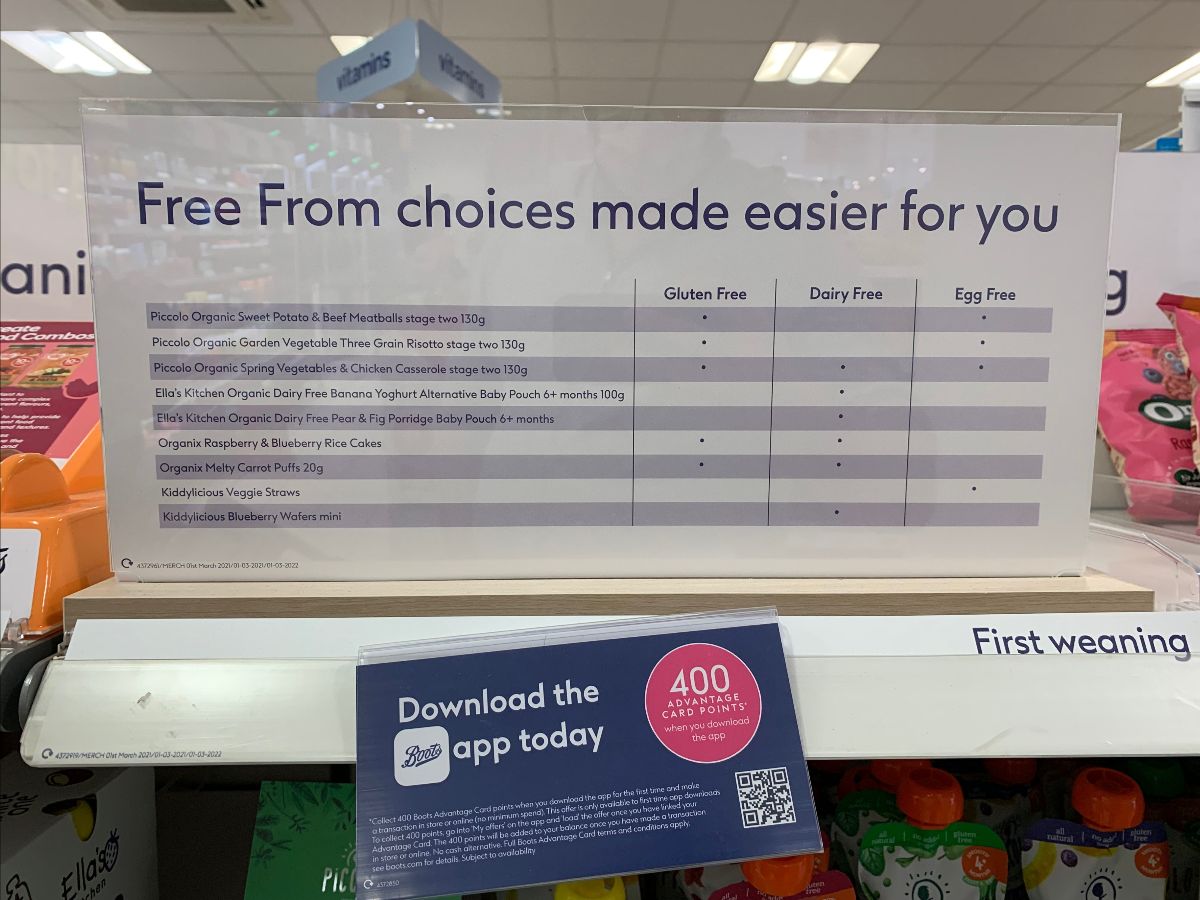
Some positives in free from with a clear piece of signage highlighting which lines are suitable for allergy sufferers who are children.
This worked well and providing it was maintained, it would help customers immeasurably too.
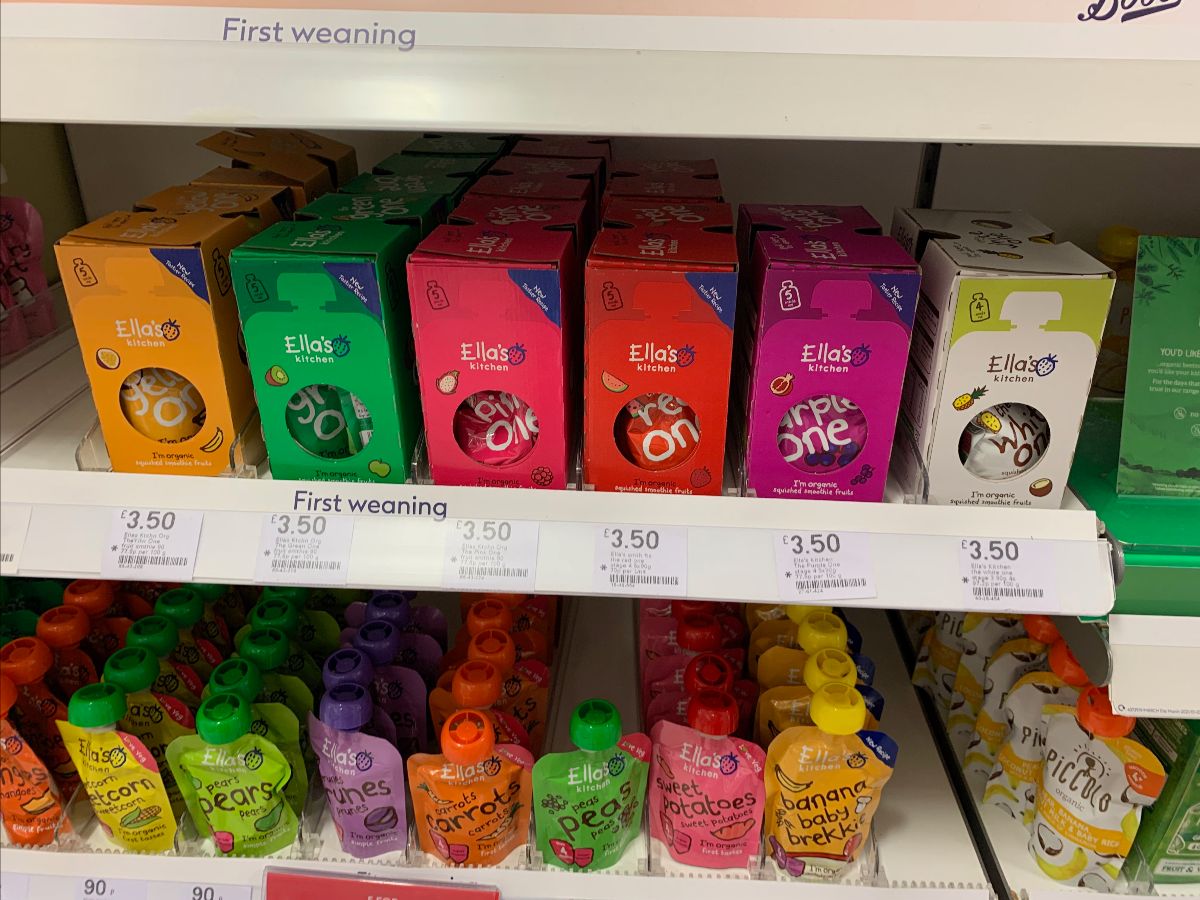
Another prime examples of the space issue? These lines are opened and automatically see some go to overstocks (in loose form) as the case size must be bigger than the 1/2 that can be fitted on to the shelf.
Is there ever a need for these in a city centre store? When Boots already ranges so many pouches (below?)
As ever, there's so much work to do on the basics, and you'd hope someone was looking at this and pulling together some form of plan regarding the mere shoppability of the store.
There is a challenge with commercial monies of course, because there are numerous big brands in the space and they want to feature lines, utilise shippers, brand their fixtures and highlight deals, sure, nothing wrong with that.
But it has to be done in way that makes overall sense. Not just another half price bay in Sun care to add to the 310 other deals that are active, alongside 'everyday low price' which is then undercut anyway, thus losing its edge.
The market is moving ever faster and the competition is rising, just to be everywhere isn't enough as you, as a retailer, must be a business that people want to be seen doing business with.
Not somewhere customers go because they have to, because there's nowhere else.
Because guess what! Where somewhere else opens, the customers depart as they have no real affinity with your chain in the first place.
You have to do more, and whilst these suggestions and fixes are not life changing, or indeed, overly difficult, they just make things that little bit easier for everyone.
Although, pointing out umbrellas are perhaps not a great line to feature on a day where the weather tops 20 degrees with bright Sunshine..... We've still some way to go.
Next week - We take a look at Superdrug
Book a call to discuss your project
Sign up to our service, today.
From the Grocery Insight newsletter archive, first sent to subscribers on 11 June 2021. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.