Asda / Sainsbury's & Argos - A few wider thoughts (4 May 2018) [2]
4 May 2018

We offer in depth briefings on Asda, Sainsbury's & the deal.
This deal / merger will run and run and Grocery Insight will offer in depth analysis and perspectives not seen elsewhere.
This newsletter service is the only place to hear our perspectives and our 'running order' below shows the planned 'dissection' of the deal and the thoughts for the future.
Our 'rollback' offer on subscriptions will not last forever. This 'free' service will revert to the fortnightly market summary based email shortly.
Join today!
Next up:
The deal: The Merger & How did we end up here?
The deal: A perspective for Sainsbury's
The deal: A perspective for Walmart & Asda
The future: What do each bring to the table?
The future - A whole new world.
As a member of our free newsletter service, you will receive around 1 email every 2 weeks on the industry and news relating to the sector at large.
Of course the big news for what will be about 18 months will be Asda / Sainsbury's.... Our coverage will be extensive and feature many perspectives that are both store focused and due to our unique work, different to what has been covered already.
A number of thoughts on the future, the deal and what it means for stakeholders. These are detailed below, with subscribers benefitting from sectoral analysis, a breakdown of the bid and what that means for the retailers.
Also, perhaps sliding under the radar were the Sainsbury's results and there are a number of lines and thoughts in there that seem to make this deal work for all parties, including Walmart.
Much more to come and as ever, it's a unique perspective and one that I proud to deliver. It's big news! We are planning some 2-3 emails per week over the coming weeks to analyse Asda/Sainsbury's.
To join our service, please visit the link above to subscribe and pay online if that's what you would like to do. We also are happy to accept payment via invoice too.
If you quote 'Rollback' when subscribing (via email) you will receive some 33% off a yearly subscription to our service. Which brings the price down to £995 for a full year's worth of access (inclusive of VAT too.)
Generous corporate discounts are also available for multiple users as these rates are for individual users only. However our rates are significantly reduced when adding 10 or more users, so it makes sense to allow your team to benefit from our unique insight.
For any further questions, please don't hesitate to ask.
Key Summary:
This deal works for all parties.
The customer is key and we won't know what they think just yet.
Argos looks crucial and would be very strong in the US.
Northern Ireland looks a sticking point; both have stores there.
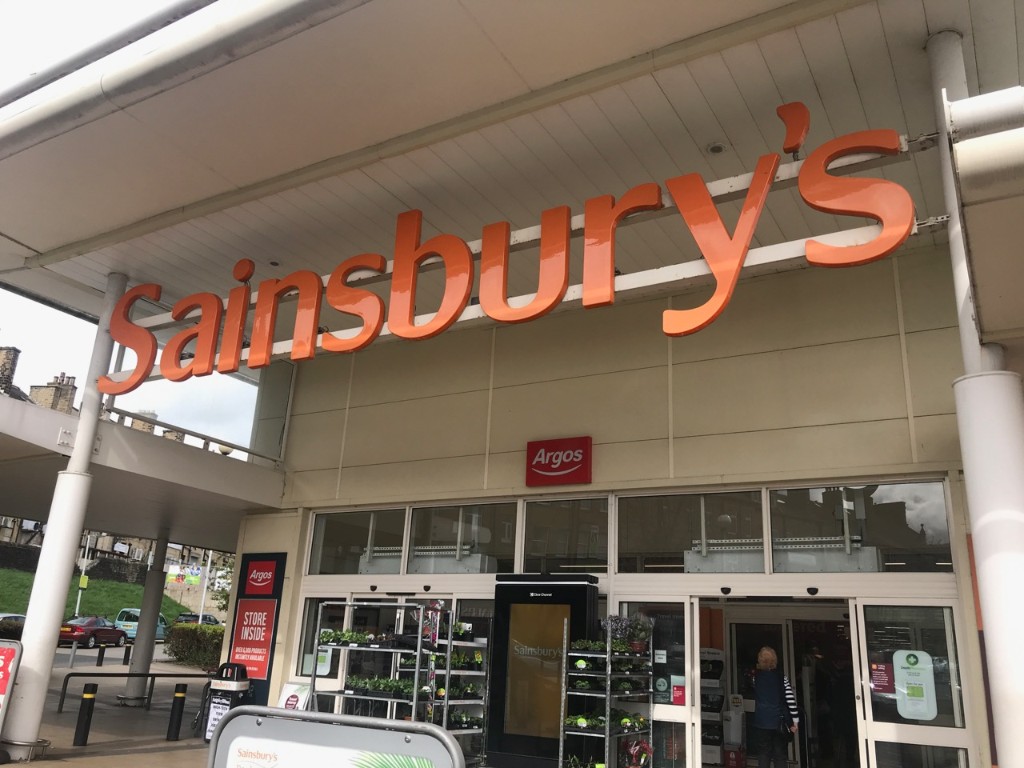
Who would have thought that Argos would be a key part of a deal with the world's largest retailer? A funny old world, but WalMart and Judith McKenna pointed to the benefit of Argos and how they can utilise the chain to pop up around the world.
Even in the US? Well, potentially. It would add complexity to their last mile logistics. However the possibility of that know how with Argos and taking that model, of hub and spoke to the US market is a huge Amazon defeater.
Especially with the collection option currently available in those big stores on selected lines. There is nothing to say that the delivery couldn't be added, it's a compelling proposition.
Same day delivery as an option would make it difficult for Amazon to compete given the sheer scale of the WalMart stores empire, some 4500 stores with their own logistics/trucks and ability to deliver same day (given the ranges in stores) is a powerful proposition indeed.
Even better for Walmart and Judith McKenna if they can expand that to other territories like the Far East and South Africa. With Walmart able to reduce their exposure to the UK market at the same time as picking up £3bn. They can still learn from Asda and tap in to the Sainsbury's know how, especially in Food.
A 1% rise in sales for WalMart US food via ideas from UK and beyond would translate to a significant increase for the business given the size.
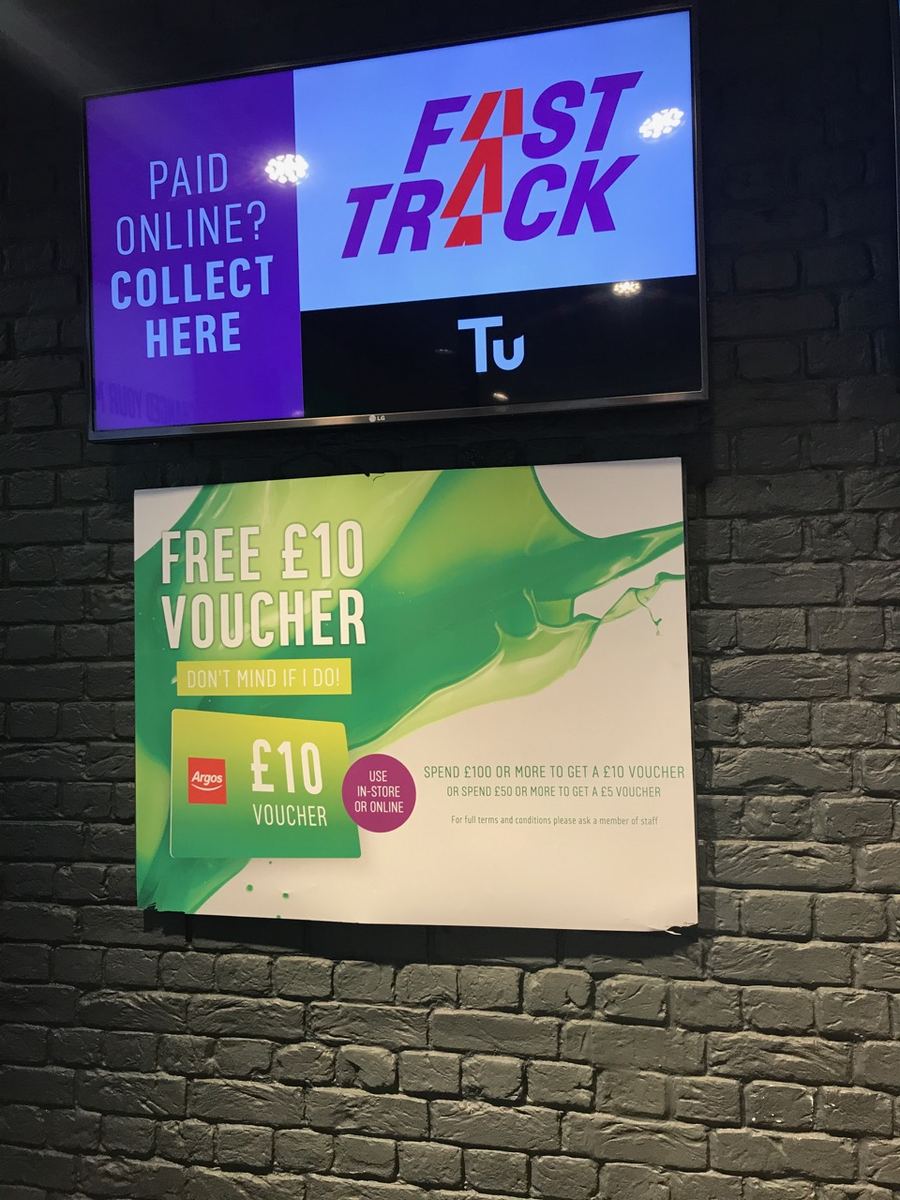
On the face of it, the Argos business doesn't make a great deal of sense in the digital world. Why would you approach a smaller 'store in store' and buy something using a staged process of checking stock, order, then await someone to bring it forth for you?
With the advent of click/collect, the customer does the work at home then comes to the store, knowing that stock is available for them. The market has almost come around again to Argos with technology...
It's a powerful proposition and ideal for those 'must need' purchases and the ability to have lines delivered for an extra fee, same day delivery is significant for the US market.
It can even lead to a Prime style membership situation whereby customers are able to sign up for x number of Fast Track deliveries per month for a monthly fee.... Suddenly it all starts to stack up.
Imagine a partnership between Netflix and Walmart too......
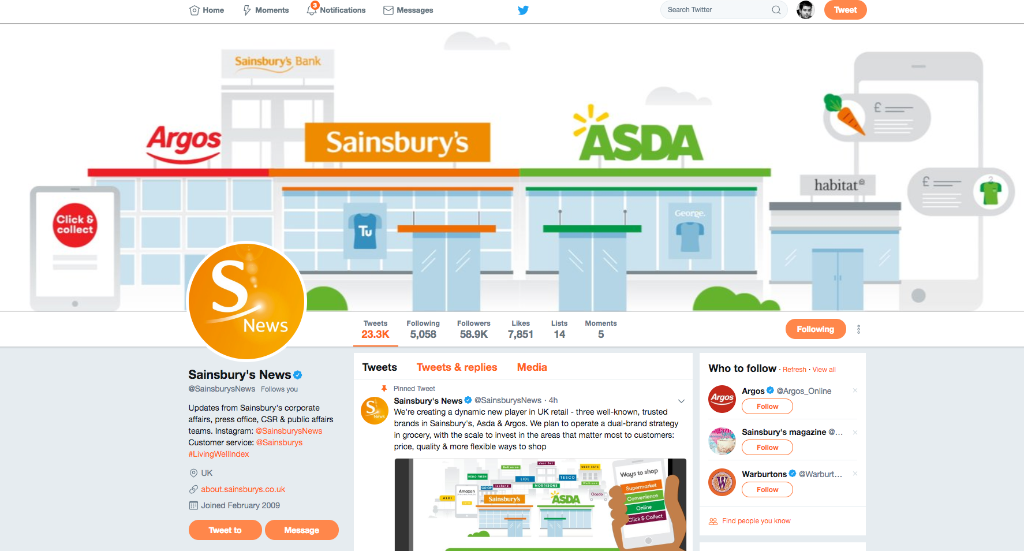
The enlarged Sainsbury's / Asda business means that Argos will be able to be in more stores thus expand the reach of the chain too.
Even if they are compelled by the CMA to shed stores, the roll out of Argos in to Asda stores would align well with the core Argos customer. The Argos customer is likely to be as close as you can be to an Asda customer.
It feels like a good fit; the question is what about the store network? Assuming the deal ducks past without a great deal of CMA / divestment (whatever those divestments may be and whatever 'not a great deal' means). There are some Sainsbury's stores have the Argos inside already.
Does the Argos move to the Asda too? Or is it a case of filling in the gaps in the network? Repurposing space? All three?
That same day delivery option is the key element here and it seems likely that George at Asda will roll in to Argos as well.
There are some big Asda hangars that would benefit from the Argos offer as a concession within store and not lead to any range reduction in the Asda stores, as we have seen with Sainsbury's.
Essentially a big store could retain a fuller range as Argos and provide a complementary service to the Asda store. Almost as if a 3rd party owned the store.
However would Asda lines then make their way in to the Argos world as a 'dream team' GM/Toys offering?
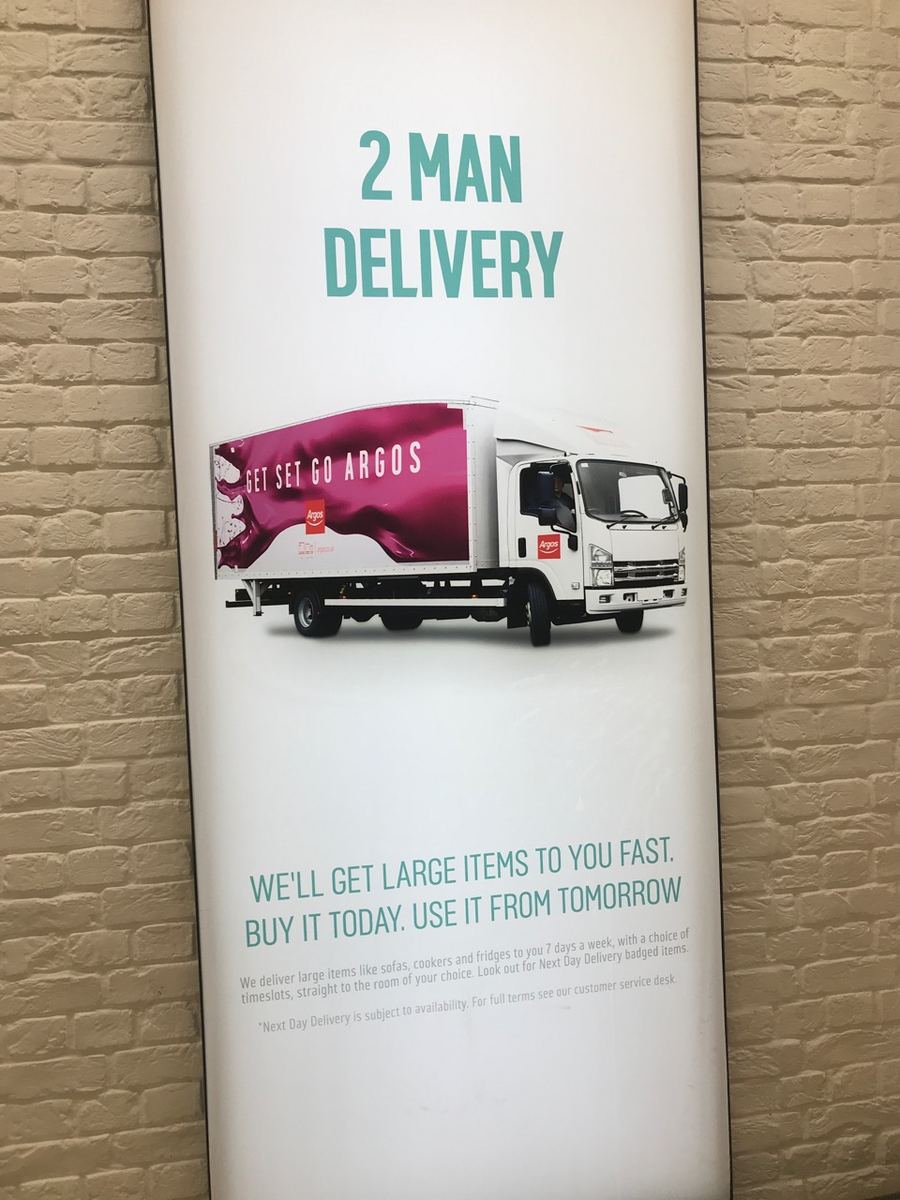
Larger items, such as Sofa's, Cookers and other white goods are available on next day delivery in Argos, with the '2 man' (Not Roger and Mike btw) delivery service.
This spells trouble for the likes of AO and even Dixons Carphone as the expanded Asda / Sainsbury's = Argos offer means they're able to enhance this offering further, even offering same day.
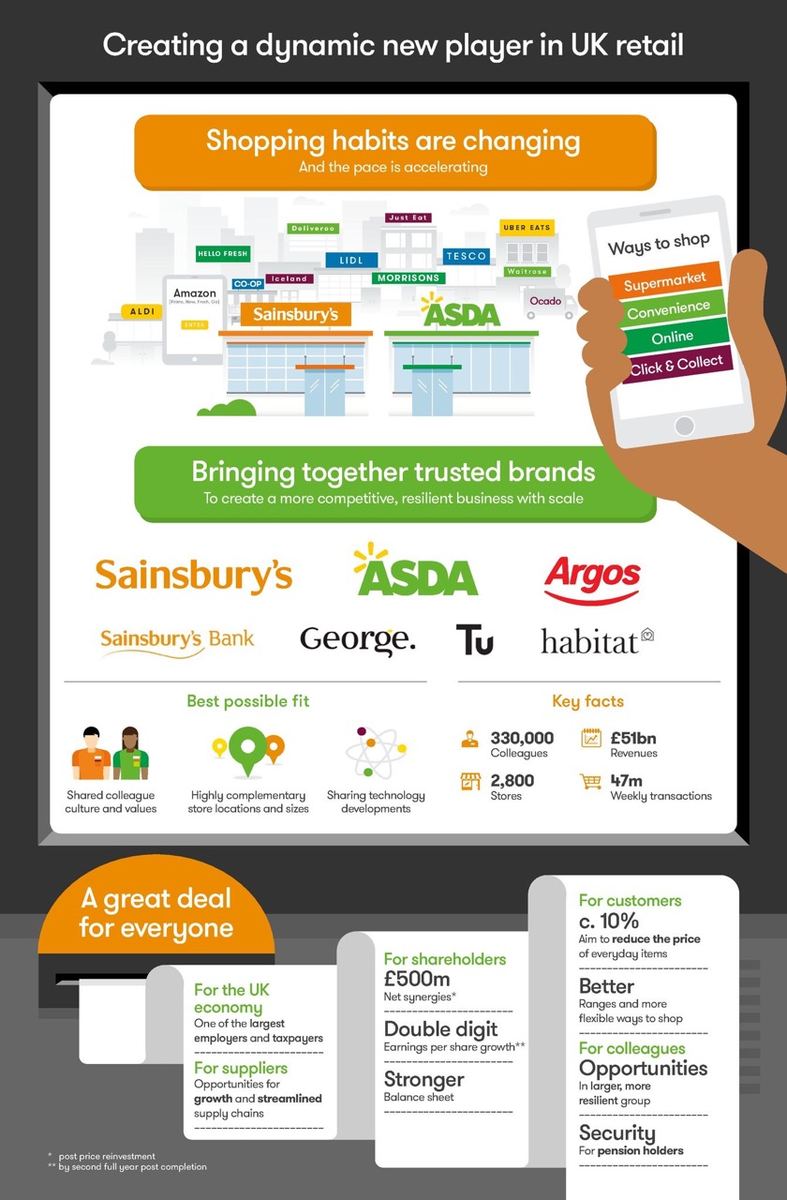
The bid on the page is a useful document, looks lovely. One for the grandkids to look at no doubt.
Anyway - the usage of the old Asda logo is notable, the sparks were prosaically phased out on refitted stores and packaging in 2017 without a great deal of fanfare. The sparks never made a great deal of sense anyway and meant nothing to the UK consumer.
But this document used the former logo, which was curious.
Habitat feels like it has more road to run, but isn't an Asda brand at all, far too middle England. It seemingly struggles in the Sainsbury's stores given the level of discounts and sales in the units too.
This brand needs some work and this deal could free up JS to feature more Habitat in stores and Argos can sit in the Asda down the road perhaps.
Thus spelling bad news for Waitrose / John Lewis....
This assumes the CMA don't force the sale of all nearby stores...
Tu and George are huge clothing brands in their own right now and joint buying of material will be important here. Walmart are huge in 'apparel' and will help drive a great deal of scale for both businesses.
Coupled with an online offer being cohesive and ability to market the ability to get some clothing lines on Fast Track or otherwise via Argos will help the cause here.
Technology developments are highlighted too; these will truly benefit all three retailers in tandem. You have the WalMart system of course, but will Asda go on to the modern, UK developed Sainsbury's platform?
There will be logistical, AI (Robots!) and Blockchain (sourcing particularly) improvements that Walmart can offer, Sainsbury's benefit from the clicl/collect opportunities, software and infrastructure that Asda have.
Sainsbury's are nowhere with click/collect in terms of scale, presence, physical kit or process however. Whereas Asda have been on a journey with lockers, drive thru collection and all manner of initiatives since 2011 and beyond.
So there are clear synergies and benefits to the group of interlocking these benefits, however it won't, presumably, be the case that you can pick up Sainsbury's groceries at Asda(?) That would undermine the respective offer but a link in with Argos and enhancing George via this channel would make sense.
In terms of the UK economy benefitting. The profits for the enlarged company (once integration and any restructuring costs are accounted for etc) are likely to lead to higher tax returns for the treasury.
Currently, Asda pay royalties and other licensing costs to Walmart leading to a lower profit. Under the new co this will cease, as Walmart will be a shareholder, rather than ultimate owner of the firm.
Whilst store locations, the offer and target market of the respective retailers are at a polar opposite, this could work in favour of both retailers in a curious fashion.......
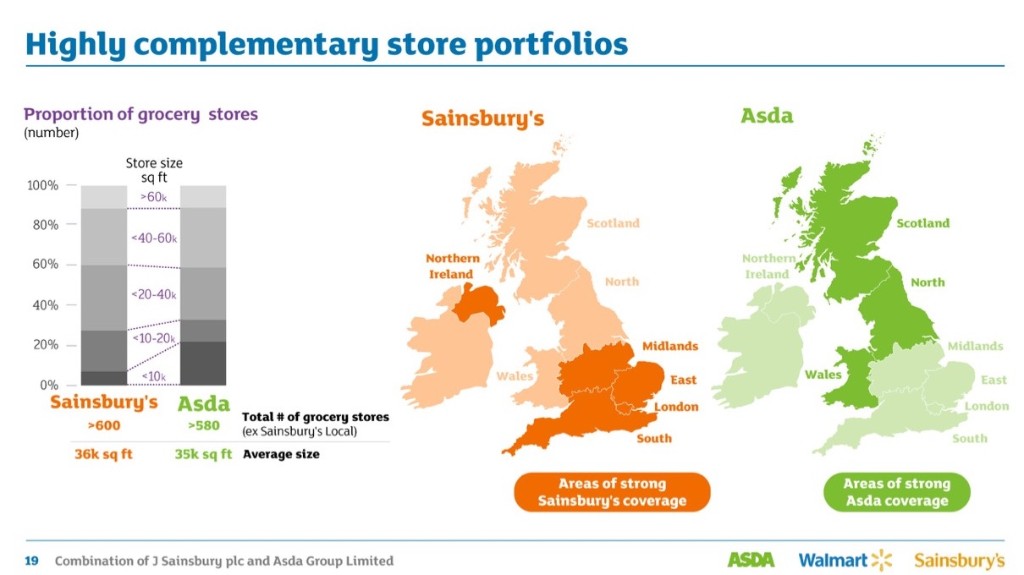
On average in terms of store numbers. They are nearly identical store sizes, with the average size having nothing more than 1k sq.ft between the two outlets.
We have seen that Aldi, Lidl and Iceland have improved their wider perception around quality and this has aided their cause significantly.
The reality of a link between Sainsbury's and Asda is that it could improve price perception at Sainsbury's (allied with Asda, a known low price operator) and help Asda (allied with Sainsbury's, a known quality operator).
The overlap on the map also sums things up - it's quite literally perfect with the strong coverage in the South and Northern Ireland for Sainsbury's, seeing Asda fill in the gaps in Wales and the North.
The overriding question has to be around space swaps, is there opportunity to swap stores over between Sainsbury's and Asda where the group decide certain fascia's will suit which location?
Certainly Tesco did that when they retained One Stop within the c-store estate, whilst many were existing stores, there was the opportunity to switch Express in to this format where the sales were limited to Cigs, Booze and not a great deal else.
One minor point I felt was interesting, Sainsbury's are flagged as being stronger in Northern Ireland, however they have less stores (according to a couple of articles on Google) so perhaps it's size of store(?) Asda are very strong in the territory.
It seems Northern Ireland is a potential challenge for the bid, as c.13 Sainsbury's stores play c.19 Asda stores, so it will be interesting to see what happens there.
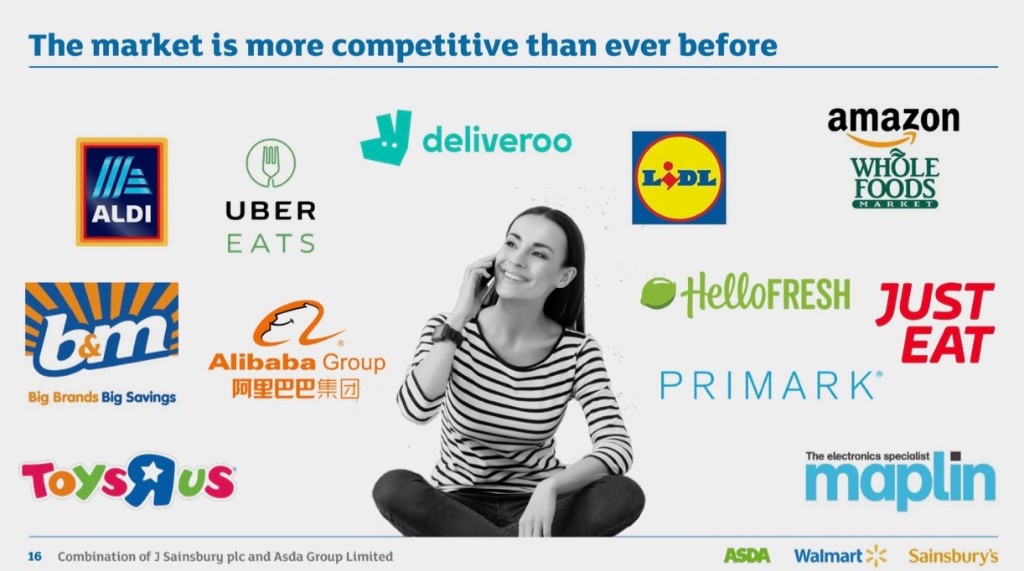
A nice slide here from all covers the wider competitive world and it showcases the differing focus of the chains, whilst noting that there are common competitors as well.
Aldi, B&M, Lidl impact both retailers, as do Primark but the likes of Alibaba (WMT) and Amazon are definitely US centric competitors.
A nice nod for Toys R Us and Maplin. A reminder to change or die presumably. Both retailers crucified by online.
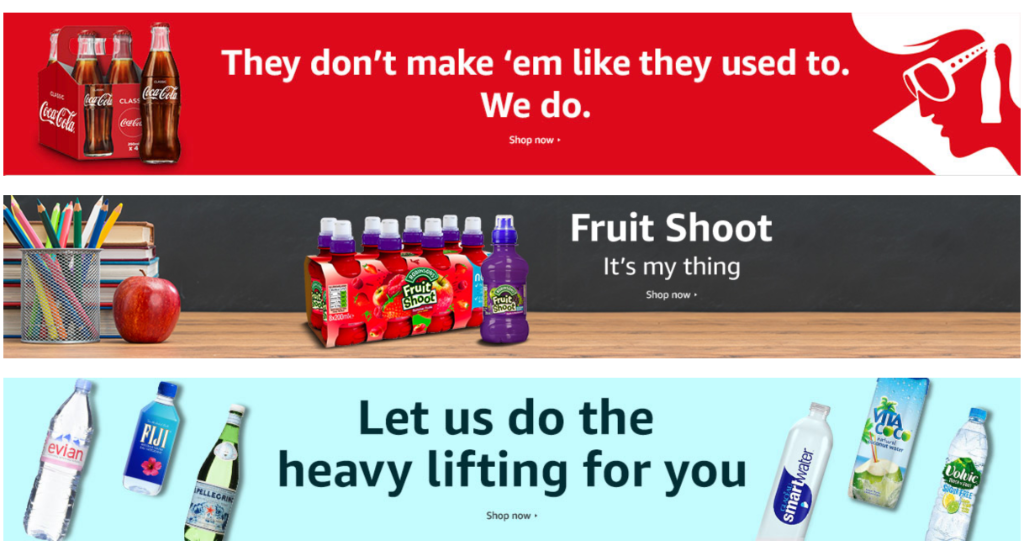
Amazon pushing on is another consideration of course, their grocery efforts are still in their infancy in the UK and their regime at Whole Foods in the US is still rather 'new' as well.
However Amazon are numerous things. Disruptive, incredibly focused on the customer with market leading pricing and service. Unpredictable, don't really seem to care about profit.
As a result and this frightens the big retailers, especially with them yet to hit the UK in a meaningful way.
Mergers / alliances are often defensive in their nature, often looking ahead at potential concerns and becoming bigger to defend against a new entrant or even, from a takeover themselves.
Scale makes sense and brings with it clear better buying prices and there are numerous savings to be made in the back offices where services are harmonised whilst retaining individuality.
However the proof of the any pudding is always in the eating. Tesco had plenty of scale under Phillip Clarke but that didn't help them as the stores failed and the customer offer fell off a cliff.
This deal looks to work for all parties, but the most important party yet to make their decision is the customer.
We will only find out in the fullness of time what they truly think of this deal.
Sign up to our newsletter service today and save.
From the Grocery Insight newsletter archive, first sent to subscribers on 4 May 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.