Sainsbury's & Asda
30 April 2018

Subscribe to our email newsletter service
Reporting: Mother's Day 2018 Event Review for sale
I was sat in Nando's as it goes, picking up my order when a kind soul tweeted me a screenshot of the merger / takeover / buyout / alliance between Sainsbury's and Asda, rumoured to be £10bn / £12bn / £15bn depending on which reports you believe. Amazing....
A very much 'where were you when' moment.
Then a further bun fight emerged on Twitter that showed Bloomberg were the first to the 'exclusive' line by a whole minute, revealing that talks had been taking place for some time and banks were advising the two chains too.
A sign that things were progressing well? It would seem so as there is a presentation to analysts today at 930am from Sainsbury's. As they're based in the UK, they are telling the City of their plans at 7am. Red lights aplenty on the share prices once the markets open?
Nothing from Wal-Mart, but they're on a time delay so any news would arrive at about 12pm, but it's unclear what would be added, other than the news from Sainsbury's.
The intriguing things are around the deal make up itself, what the overall newco will look like and who owns what? Who has control? Will Wal-Mart retain 40% as reported, which means they take over really as biggest shareholder?
Investors will be interested to understand what this means for their shares (JS owners) but also the wider market and the players within, especially Morrisons who would be a much smaller no.3 in the marketplace if such a deal goes through.
However this could play in to their hands too; it'll leave Morrisons room to do their bit in the market whilst retaining the focus on fresh foods and having being truly different for customers with Market Street alongside the Fresh Food production facilities.
There is a school of thought that Amazon may look at Morrisons as an acquisition target, given their alliance on Pantry and the fledgling food operation in the UK.
However all water under the bridge? The UK is a cash furnace when it comes to Grocery retail and that hasn't improved with the discounters on the territory and expanding at rapid pace...
So what does all this mean?
Well....
Asda as things stand, along with Sainsbury's are at a standstill in terms of their share and growth prospects. Booker adding a huge amount of scale to Tesco has changed everything really,
Hard to see how Sainsbury's they can change anything else, their debt is higher post Argos with no prospect of a change in the mid term and their margin has fallen considerably over the past 4 years or so.
Therefore any shift isn't going to come to protect themselves against Amazon and Tesco/Booker. Sure there is a defensive nature to the Argos deal and looking to close off Amazon with the prospect of same day deliveries - but it won't solve the ills with regard to competitiveness on food.
It's small movements with no margin to invest.
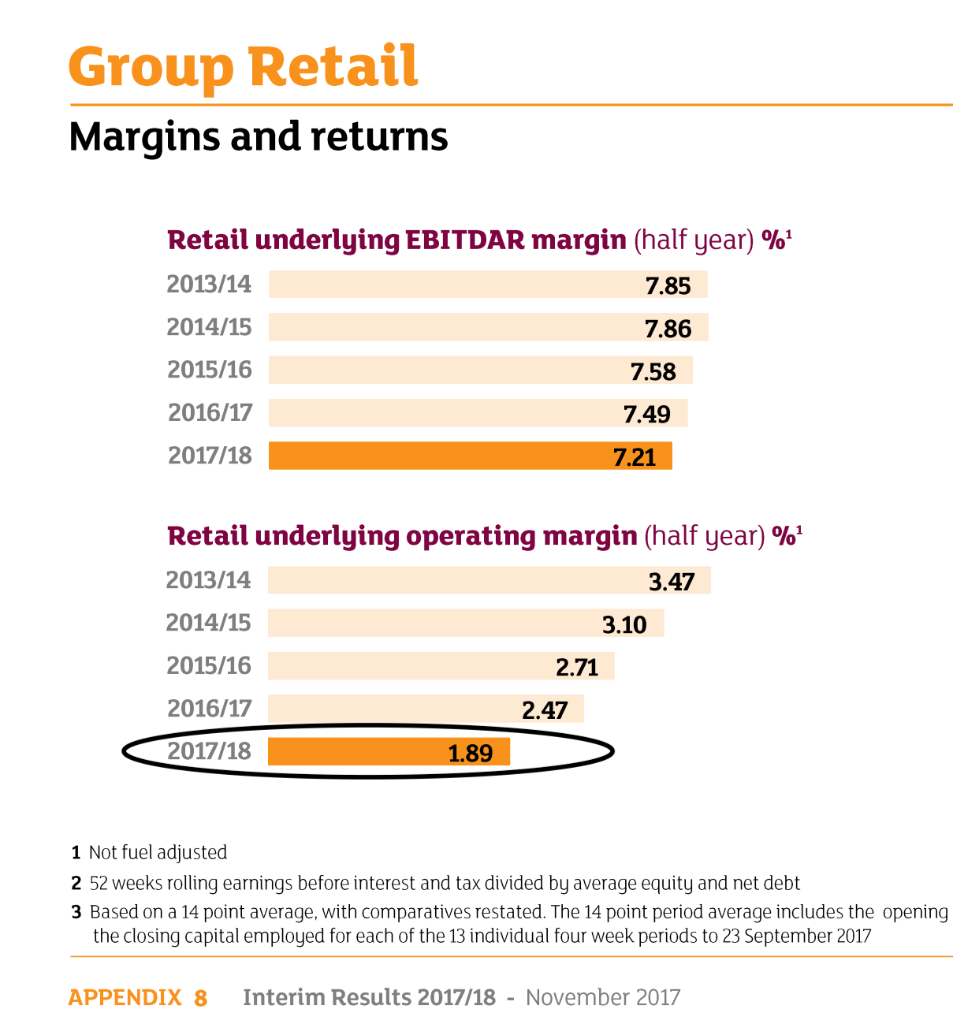
Therefore the deal, however it shapes up will presumably bring scale and aid the Sainsbury's cause significantly in this instance.
Otherwise they are landlocked. It's important to note that Mike Coupe hasn't been shy in terms of strategically adjusting the retailer and also being hot on the acquisition trail....
They have purchased Argos and began to roll out this offer in to their stores, alongside closing down the Argos sites in town centres, in favour of driving foot traffic to the Sainsbury's store.
One of Coupe's first deals was the Netto alliance that saw Dansk provide support and assistance in a JV to roll out the 'new' Netto to the UK market. However this format remained in the North (like old Netto) and went no further.... The JV was then pulled with some valuable lessons learnt, but no future format forthcoming.
Recently Sainsbury's tried to buy Nisa but pulled out on competition concerns (or perhaps, more accurately, this deal on the horizon?) and were rumoured to be looking at Mothercare too.
£60m was spent on acquiring Nectar as sole owners which again could be a precursor to the enlarged group, giving Sainsbury's sole control over the loyalty scheme.
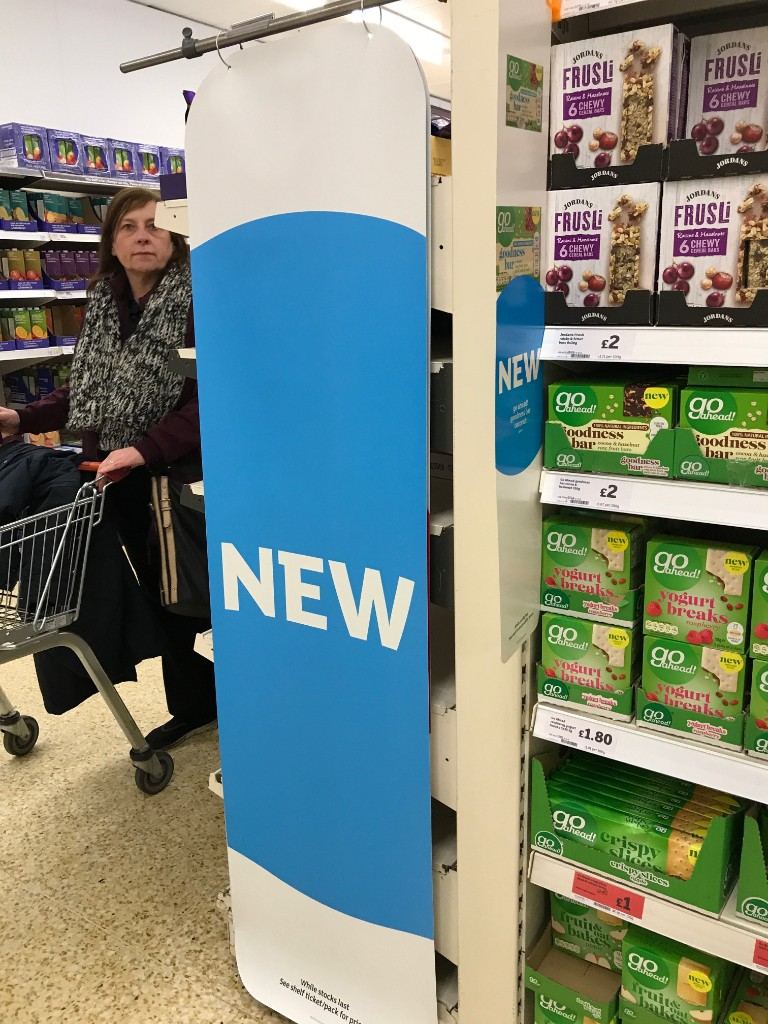
The picture for Asda remains similarly balanced in terms of their future prospects, growth avenues and position in the market. Where Sainsbury's are positioned quite middle market, Asda are towards the value end of the sector and therefore right in with Aldi and Lidl.
Sainsbury's suffer with discount too, but Asda have had a tough few years with falling market share, like for likes being a 'nadir' and worse but now on a stable footing, but difficult to see how the chain would get to growth and what that would look like longer term.
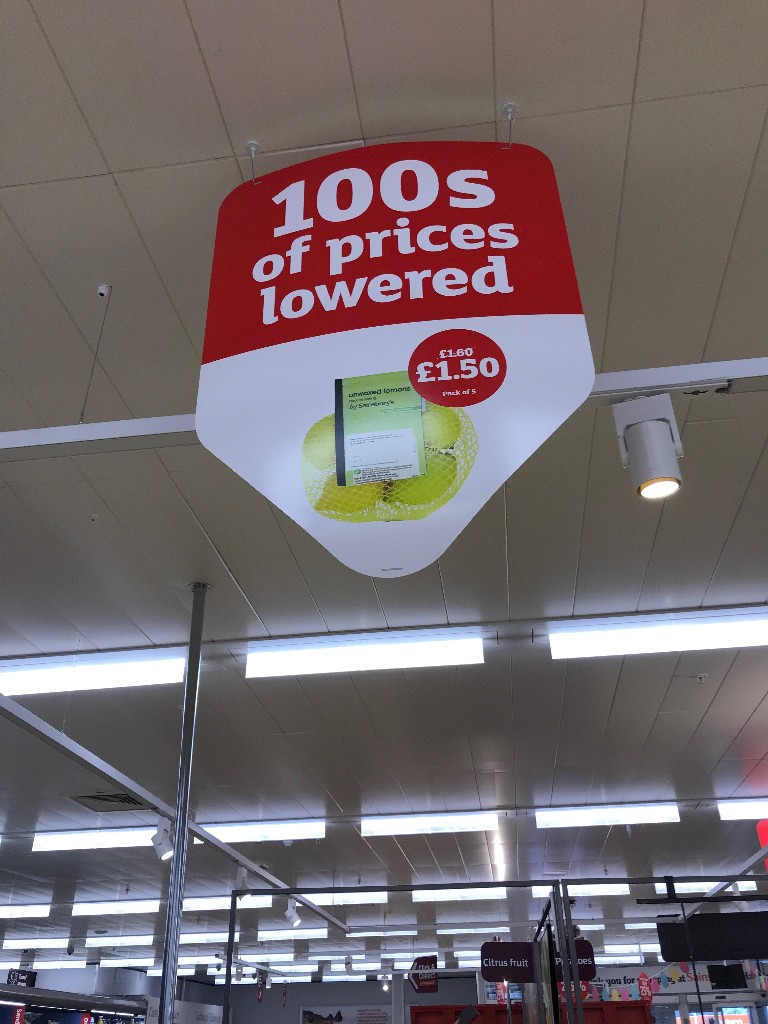
Dropping some margin in to price is a zero sum game as there's no realistic opportunity of a recovery to offset the margin... Not with such competitive forces around the marketplace.
We are in a depressed market now, post discount and margins are thinner with sales ever harder to come by. Any growth channel like online is worse as it does bring loyalty and big basket spends... But this is at slimmer margins given delivery, picking costs and the rest...
It's a fascinating deal in prospect but it doesn't come without risk.
Does anything? No.....
However, given the scrutiny that any deal would get from investors, shareholders not to mention the CMA, then the Groceries adjudicator who won't allow any changes that impact suppliers once done... It will be utterly fascinating to see how all this plays out.
Whilst all this is going on in the background, there are two businesses that have to trade in a very competitive market.
Not to mention the thrills and spills on the way; rival bids, market movers, Brexit, store divestments and everything else in between.
One thing is for certain, given the nature in which these deals are done, with open books and everyone poring over every detail.... There has to be more than a realistic chance that this deal will get over the line...
This humble service will keep you abreast of every development and will be an essential tool when navigating the presentations from the retailers, what the prospects for the chains are, what the implications are for the wider sector and what everything means for everyone.
Least of all, the customer...
With all planning out of the window for this week; there will be countless email based notes flying out and if you'd like to see a man essentially debate with himself for two days and also work in a comparison of Mike Coupe to Harry Redknapp (given their fondness for a 'deal') then you should check out my twitter feed.
A fuller bid analysis / document and thoughts for the sector to come this week (a full A-Z guide no less).
But far more analysis, throughout and as ever, Grocery Insight stand ready to offer advisory on the sector with a unique blend of insight and store imagery to illustrate just what current trading is really like....
What are the upsides, downsides to a deal and what are the missing links to any such deal? Implications for the sector and what about other retailers, like Wilko for example.
Not to mention a longer term view that whilst a bigger sized company and scale can bring good, it didn't do Philip Clarke a lot of good at Tesco....
All to come this week on the newsletter service, strap yourself in. It's going to be a bumpy old ride....
Subscribe to our email newsletter service
Reporting: Mother's Day 2018 Event Review for sale
From the Grocery Insight newsletter archive, first sent to subscribers on 30 April 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.