A marriage of convenience? (2 May 2018) [2]
2 May 2018

Subscribe to our email newsletter service
Want in depth reporting and briefings on Asda / Sainsbury's?
Sign up to our newsletter service today and Save 33%!
As a member of our free newsletter service, you will receive around 1 email every 2 weeks on the industry and news relating to the sector at large.
Of course the big news for what will be about 18 months will be Asda / Sainsbury's.... Our coverage will be extensive and feature many perspectives that are both store focused and due to our unique work, different to what has been covered already.
A number of thoughts on the future, the deal and what it means for stakeholders. These are detailed below, with subscribers benefitting from sectoral analysis, a breakdown of the bid and what that means for the retailers.
Also, perhaps sliding under the radar were the Sainsbury's results and there are a number of lines and thoughts in there that seem to make this deal work for all parties, including Walmart.
Much more to come and as ever, it's a unique perspective and one that I proud to deliver. It's big news! We are planning some 2-3 emails per week over the coming weeks to analyse Asda/Sainsbury's.
To join our service, please visit the link above to subscribe and pay online if that's what you would like to do. We also are happy to accept payment via invoice too.
If you quote 'Rollback' when subscribing (via email) you will receive 33% off a yearly subscription to our service. Which brings the price down to £1005 for a full year's worth of access (inclusive of VAT.)
Generous corporate discounts are also available for multiple users as these rates are for individual users only. However our rates are significantly reduced when adding 10 or more users, so it makes sense to allow your team to benefit from our unique insight.
For any further questions, please don't hesitate to ask.
Sign up to our newsletter service today and Save 33%!
Reporting: Mother's Day 2018 Event Review for sale
There is so much to write up, it's hard to know where to start with everything. We're aiming for around 1-2 emails per day this week covering most of the angles of the takeover, but this will run and run, and run....
Amazon are the key disruptor potentially in the background and will this availability of Sainsbury's attract Jeff Bezos and co? Certainly not Asda, as Walmart won't sell up, quite rightly to a rival.
Rumours of Morrisons / Sainsbury's alliance is short sighted perhaps, given the cultural challenges and the deal not then working for Morrisons, or Sainsbury's really.
The benefit of the deal for all three parties is that it works perfectly for all of them. Equally, without a downside seemingly.....
In terms of their control base that is, if we consider the wider picture. The 'uncontrollables' such as the CMA, then the GCA who won't allow any unfair supplier treatment. It seems a hard one to try and work out the future for...
The headline concerns for the merger are:
*Stores - How many stores will need to be divested to satisfy the regulator? What will their interpretation be of the deal? Of competition factors? Online?
*Competition - Online was a fledgling operation back in 2003, with most people barely having a computer, let alone shopping online. Mobile was all about Snake and sticking to 140 characters on a text message. Not shopping.
*Space - Any consideration of the bid (but not for the CMA) is what happens to that space assuming a sale is forced. What happens to a large hangar, there will always be takers you'd suspect but Aldi/Lidl will not want large stores.
*Prices - The wide reaching investigation will focus on the customer and if they will pay higher prices as a result of this deal. Naturally even if the CMA waved every site through, the chance that Asda / Sainsbury's could collude and charge higher prices is surely near zero. The chances of me, or anyone else rocking up and seeing this would result in such negative PR it wouldn't be worth it.
*Customers - What does it mean for customers? Seemingly easier to run two firms, with different identities and geographical reaches? However two firms means double the challenges and how is the dividing line effectively drawn to retain each company's identity whilst preserving the reason for the deal - better buying prices and synergies to make savings.
The interesting thing is that the preconceptions we have on the deal, in terms of overlap of stores actually could work against the CMA and in favour of the deal. The competition is so fierce these days.
There is no 'test case' as nothing is worthwhile in terms of comparatives, Morrisons/Safeway was an age ago and discounters didn't exist to any scale versus what / where they are now.
Even the ranges were markedly different with a mere 750-1000 products stocked in both Aldi and Lidl. Now it's 1750 (labels on shelf) with the physical products numbering 2000+ and that's before special buys.
Sign up to our newsletter service today and Save 33%!
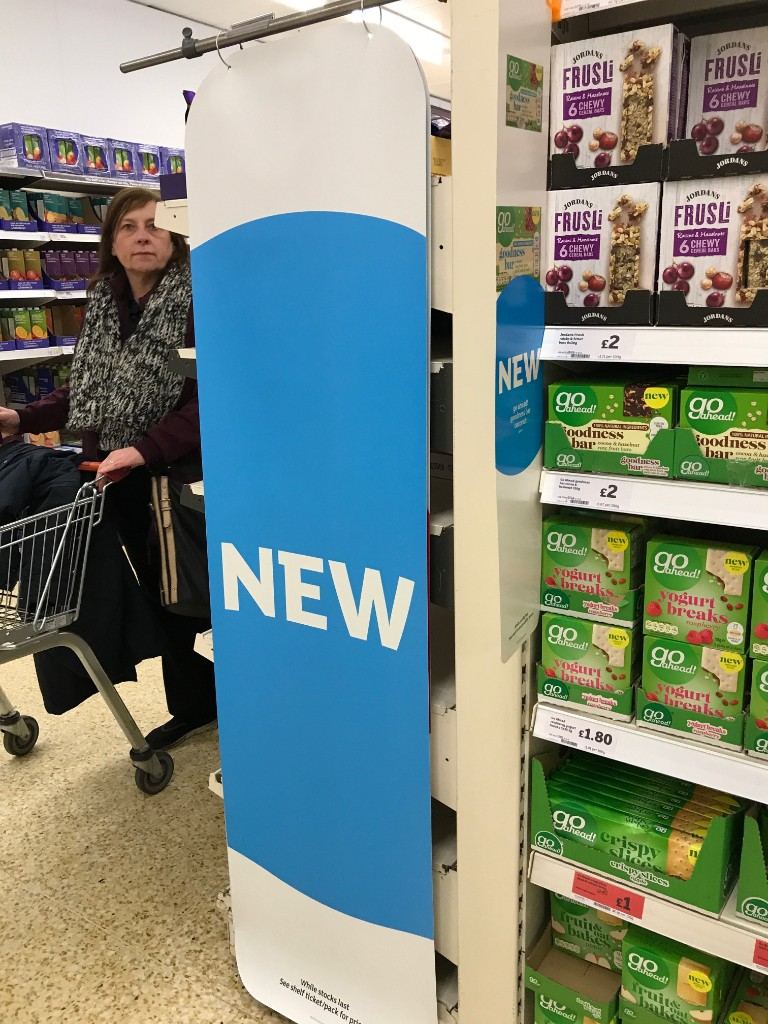
In terms of the deal and retailers themselves, there will be a fuller digest of the bid documents, rationale and what we expect at a shop floor level. This level of granularity is what you come to expect from the service after all(!)
For this email however, we continue to look at the high level questions and thoughts around the deal.
Both retailers are at the opposite ends of the market in terms of customer offer, geographies but similar in terms of culture, sure there are differences but a cultural mix up between Morrisons and Sainsbury's would be stark and too much of a jump.
We saw similar issue with Morrisons and Safeway for example. The cultures were hugely different, not to mention other issues and this led to a dramatic slowdown at the core chain as more drains were dug up, uncovering all manner of issues.
This wouldn't necessarily happen in this case, as the deal looks to be very complimentary to all three parties, including WalMart.
Clear that the Tesco/Booker deal has kicked this off, in more ways than one. Not only was it a deal that immediately changed the landscape, but the ease of approval alerted people.
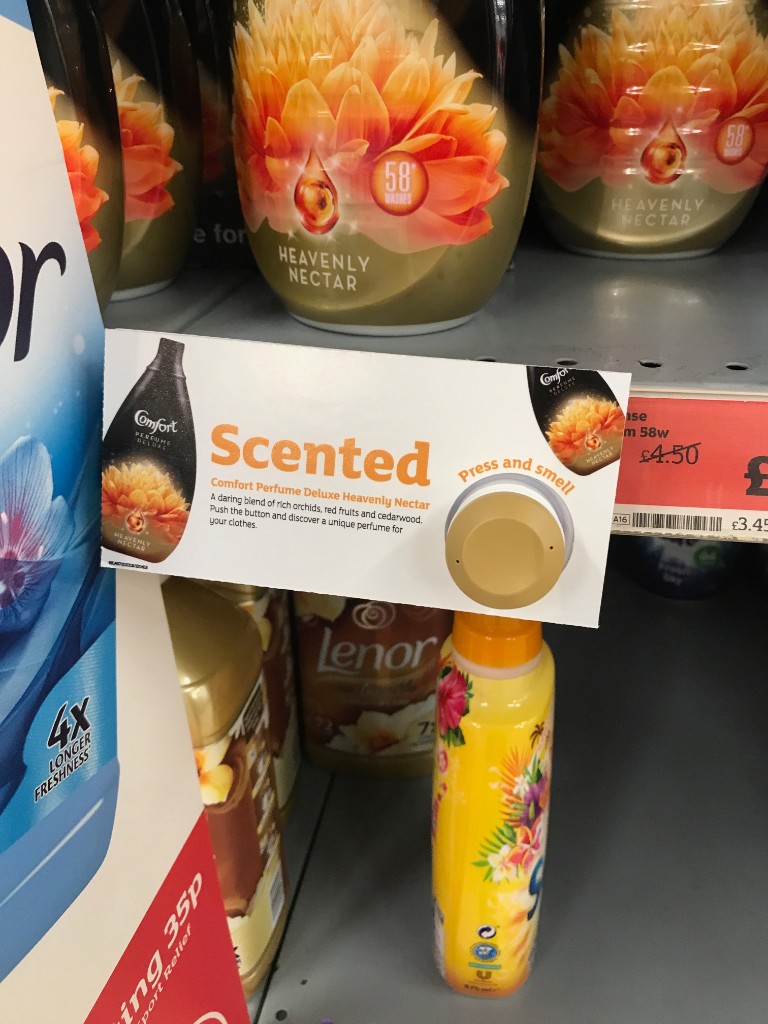
For Sainsbury's, the deal makes perfect sense, as it does for Asda and its then facilitated by WalMart who want to reduce exposure to the UK market whilst retaining their role as the largest shareholder.
WalMart are able to get some cash back in to their business (some £3bn) and whilst not having full control (why do they need it?) they still have the largest role in the new enlarged company.
For Asda, it means that they too are able to enhance their reach and scale within the new group. It seems almost obvious that any 'windfall' via the new, enlarged group with buying power means they're looking to lower prices.
The magical 10% figure is unclear, as a 10% drop in respective positions would still leave Asda cheaper by a fair way versus Sainsbury's. So what does that mean?
For the customer it's good news presumably, however there are likely to be confusions over the respective positions for the supermarkets. The 'punters' all read the news and will be looking out for signs of change, indeed, some will already think that Sainsbury's / Asda have taken over the chain (as customers often do.....)
The question over prices remain; if a 10% cut comes down the track, then does this mean that brands are the same level in each retailer? Or is it a broad brush 10% on favoured goods? Does this go deeper in Sainsbury's given their price position versus Asda?
The obvious pitfalls will have been worked through but the CMA doing their work is the obvious one. The logic we often default to relates to the postcodes and dominance.
However customers have never had more choice, with online now a real option for customers and discounters - barely worth mentioning in the older days are now both everywhere and also a compelling alternative for customers.
There are pockets where there would be 'dominance' for the two chains, particularly local to me, but the phrase dominance is a difficult one. As physical dominance is one thing but online can change that slightly...
Assuming the business gets the CMA approval, and Tesco/Booker did get approval but, the crucial difference was that Tesco were able to show that they were buying a wholesaler who franchised stores and they had no control over pricing......
Sainsbury's / Asda are trying to do the same presumably with their two chains approach, but benefitting from better buying, better scale and the combined back office functions in areas like IT, where costs can be great but also, the solutions developed can save a lot of money too.
Sign up to our newsletter service today and Save 33%!
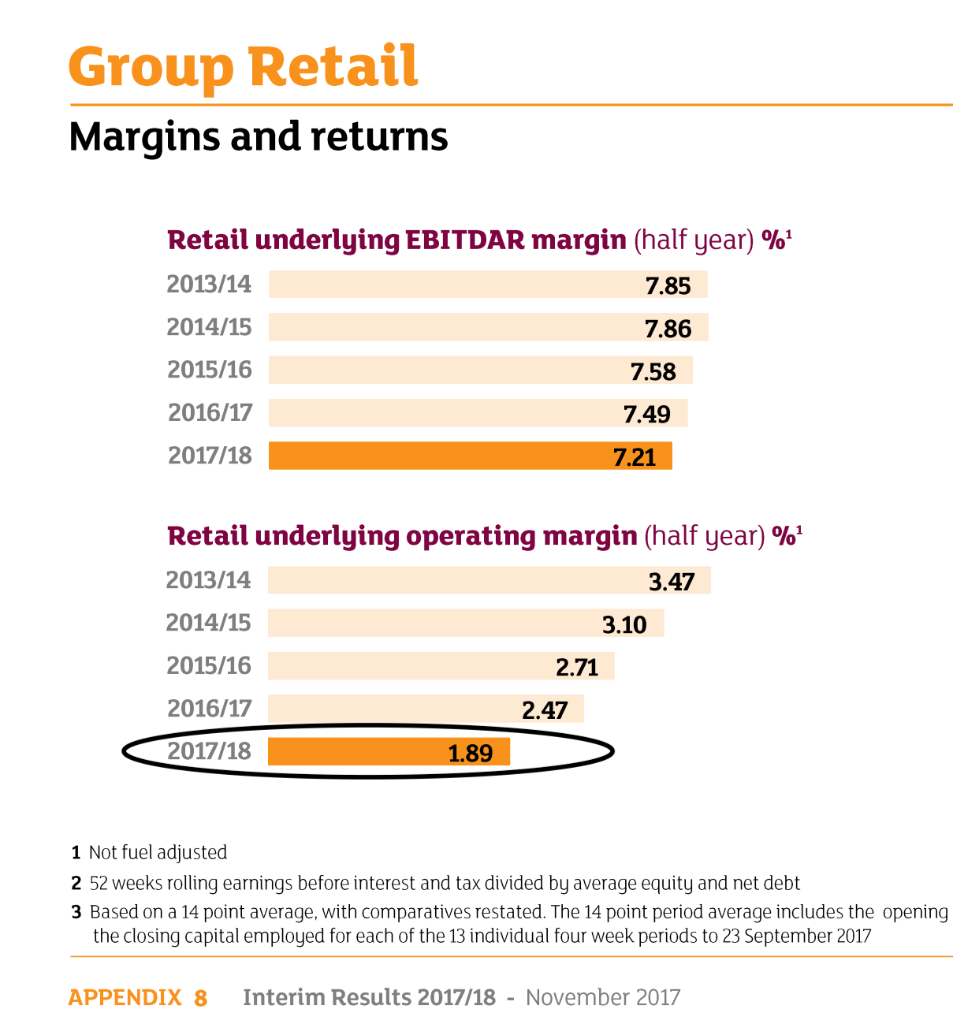
There is so much to cover here with this deal, the permutations and just what it may mean for everyone in the industry.
What if someone else bids for Sainsbury's as an example? What does the future look like? What if the CMA demand a large number of divestments? Does that mean that the deal could be under threat? Or is it happening regardless?
In terms of our reporting:
What Sainsbury's offer Asda, what Asda offer Sainsbury's and what Walmart both offer the two retailers and what Sainsbury's offer Walmart too. All to be considered. Alongside the deal makeup.
Alongside a view on each retailer and 'where they are now'. Why this deal, why now?
What about the other retailers? Morrisons? Iceland? Wilko? What is the wider impact here?
Speculation and thoughts on the future for both chains. Assuming Mike Coupe's timeline on H2 2019 is accurate without too many divestments, then we could be in the midst of Brexit and who knows what.
Is there to be a 'super' Sainsbury's/Asda where both fascia's co-exist and feature the best of George, Tu Clothing, Argos and Food?
Does this bid / announcement mean there's a degree of stagnation from both retailers as this merger/takeover now takes time and focus to work through and get right?
The Walmart 42% shareholding is important in the larger company, are there are any 'red lines' in the new world?
There is a note on the Morrisons / Safeway deal. This is the 'last big' deal that people are relying on, but there are differences this time in the marketplace, channels and population too.
Massive differences. That's the view the new enlarged company will be hoping the CMA take, which will benefit this major deal.
Sign up to our newsletter service today and Save 33%!
Reporting: Mother's Day 2018 Event Review for sale
As you'd expect, Grocery Insight and myself (the royal 'we') have been featured on mainstream press and TV over the past few days (FT, BBC Breakfast and 5 live to name but three).
As ever, our unique perspectives and foresight are always in demand and we are happy to share our in depth reports and presentations with interested parties to try and map out the future.
What does it mean for your business? Your investment? Category? For the customer as a whole?
We can provide a unique perspective on the deal, informed by our countless store visits, knowledge of both businesses and the wider marketplace too.
Our insight can be delivered in person too, which makes for an 'entertaining' (one attendee at a lunch I hosted said he'd heard the jokes were good....) event and the Q&A is always incredibly useful for everyone with questions to ask.
Please don't hesitate to get in touch to discuss by clicking the button below or simply replying to this email.
Sign up for this service today and receive a 33% discount on a year's subscription. Saving £495!
A bit more than the 10% pledged by Mike Coupe.........
Sign up to our newsletter service today and Save 33%!
Web: Subscribe to our email newsletter service
Want in depth reporting and briefings on Asda / Sainsbury's?
From the Grocery Insight newsletter archive, first sent to subscribers on 2 May 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.