Asda - Rolled Back...
17 January 2018
Did you enjoy this email? Join our service

I'd like some help with Events / Images / Insight....
We have a 'huge' Christmas report available soon
Express Checkout - Asda
Asda performed well at Christmas, a deeper review to follow.
Price has been stronger for Asda, a 12wk winning run on Grocer 33.
Some on pack signage is black/white to advertise Price/EDLP.
Rollback is extensive across the store in the new year.
A further price initiative has recently hit stores too.
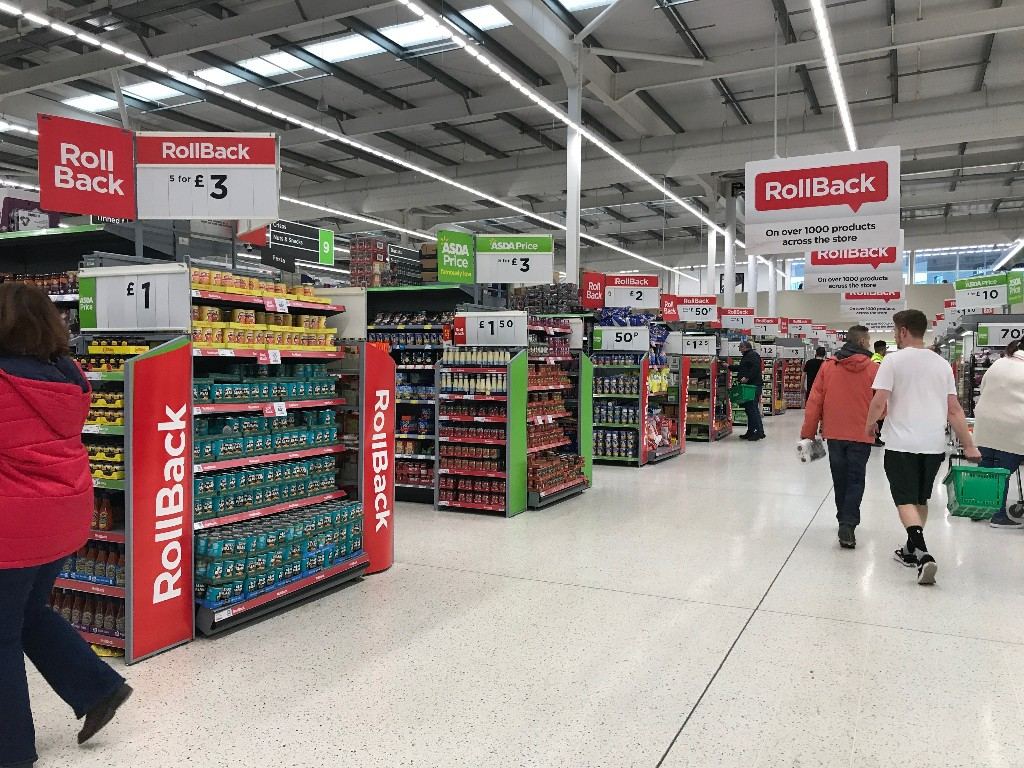
Asda have seemingly done well at Christmas, but haven't yet released results via Wal-Mart (that will be in Feb sometime)...They did look in good shape in the run up to Christmas with a focus on premium ranges and also sharpening on price too.
Christmas was always a season that historically, Asda lost a little on and under performed in the same way that perhaps the discounters used to (and perhaps still do with some people switching away in December).
Customers grateful for the money saved throughout the year would then go to Sainsbury's, M&S et al to buy their premium goods and treat themselves somewhat.
However the market has changed and Asda may well tempt discounter shoppers back to themselves over the festive period with the 'big shop' on offer with the brands, Gifts and Toys.
A sharper premium offer has been noted over the past two Christmas periods but the challenge for Asda is getting "Extra Special" as part of their 'mix' all year round and not just at Christmas and Easter.
Their improvement in own label has come via the discounters as the market now both understands, and expects a better own label offering. Therefore premium is a logical next step for many customers and retailers not entirely renowned for premium, or indeed own label are able to take advantage of this.
More to come on their Christmas review alongside the others left (discounters, Waitrose and the Co-Op) to come next week.
Alongside Rollback which relaunched as a major campaign in August of last year (first time in a while too), it has returned for the new year with the classic '1000 items lower in price'. Usual focus on big brands like Heinz alongside some healthier lines too, including their Slimming world imitation 'Slim Zone'.
A traditional January campaign from them and one that's appreciated by customers as they struggle along with little cash until payday, and even then... Post Christmas...
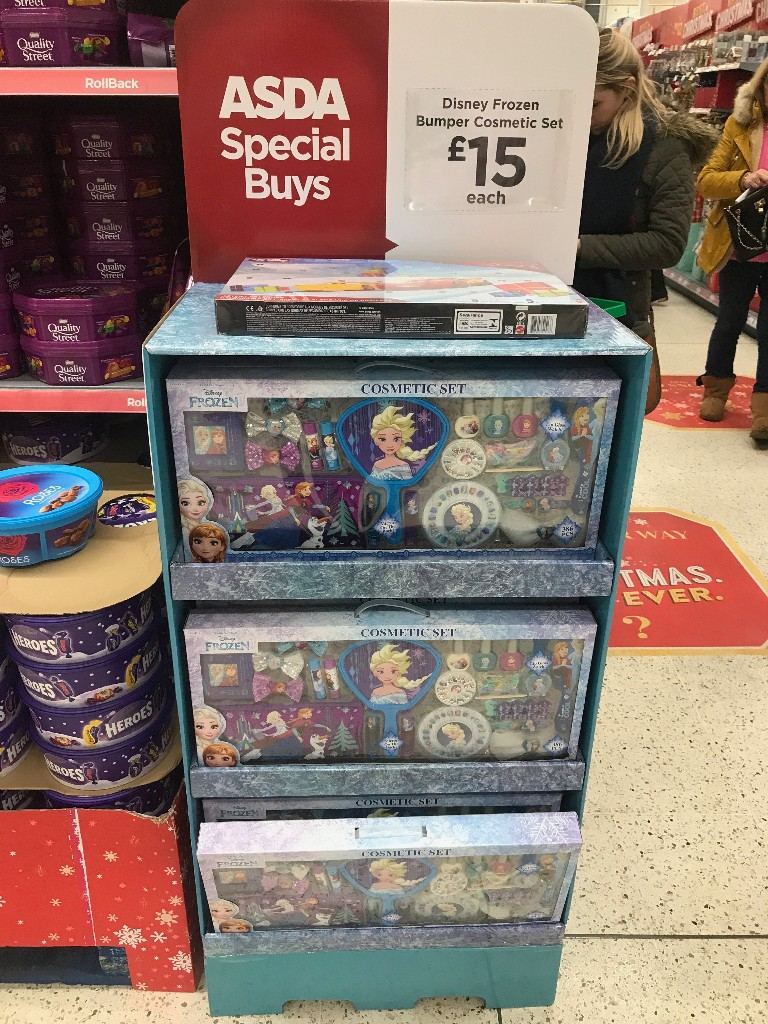
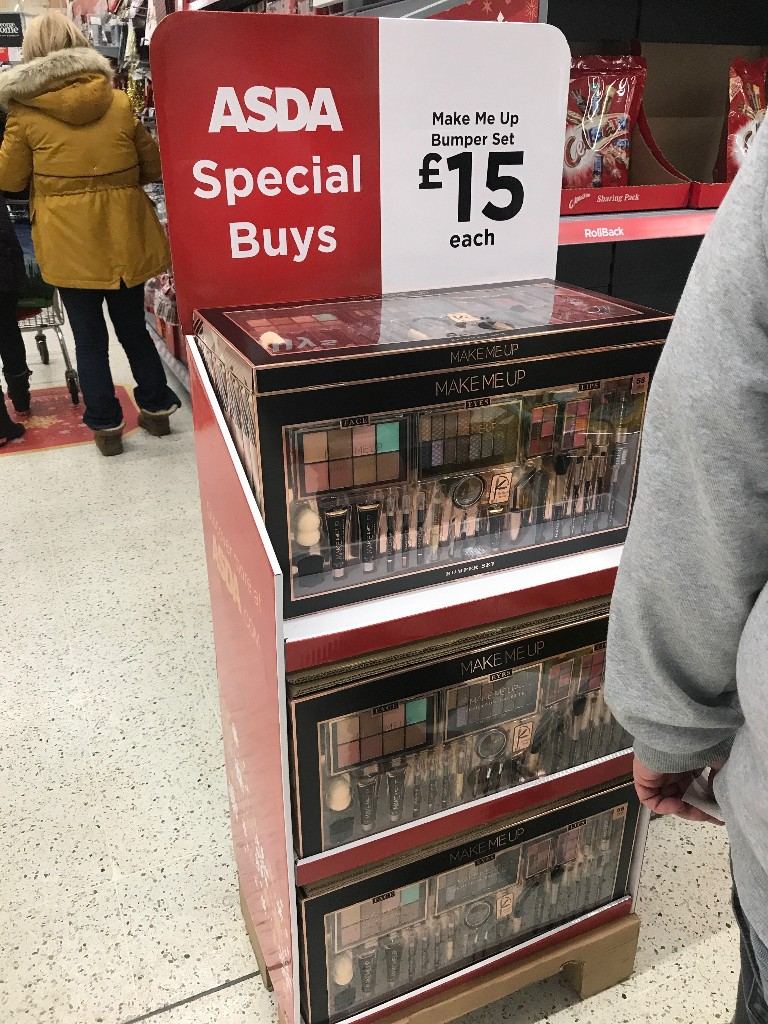
Also noted before Christmas was the 'Asda Special Buys'. These appeared to be 'when its gone it's gone' based lines in time for Christmas, focusing on larger, non standard packs of cosmetics for £15.
Asda have just had their winning streak broken for the lowest priced shop in the Grocer, they were cheapest for 12 weeks and only the appearance of Aldi as the guest retailer saw them lose out. Before that, the G33 was all over with different winners each week.
However the winning gap for Aldi was narrowed it was only around £4 and Morrisons were not far behind Asda either. This rather than the usual £8/£9 gap as discounters, unsurprisingly cheaper on selected items given their operating model....
That price gap is all important though, a narrower price gap means that customers, whilst still visiting discounters may well note that Asda aren't necessarily massively more on comparable items. Therefore a secondary shop in a larger store for other items, non food, wider Baby ranges etc becomes possible.
A cucumber is a good example where Tesco were perhaps 90p vs. Aldi at 50p in the recession, immediately a large price gap. The price gap between discount and big four on Produce has narrowed demonstrably. A cucumber is just that to a customer....
Whilst there is no data from us (although I am working on this from a tracking viewpoint), a difference of a few pence is noted on some lines and on Warburtons Bread last week, the price was level at £1.05 in both Asda and Aldi.
Generally discounters stay 1p/2p below the 'market' price to retain their price gap, but not on every line.. Lidl were £1 on Warburtons at the weekend.
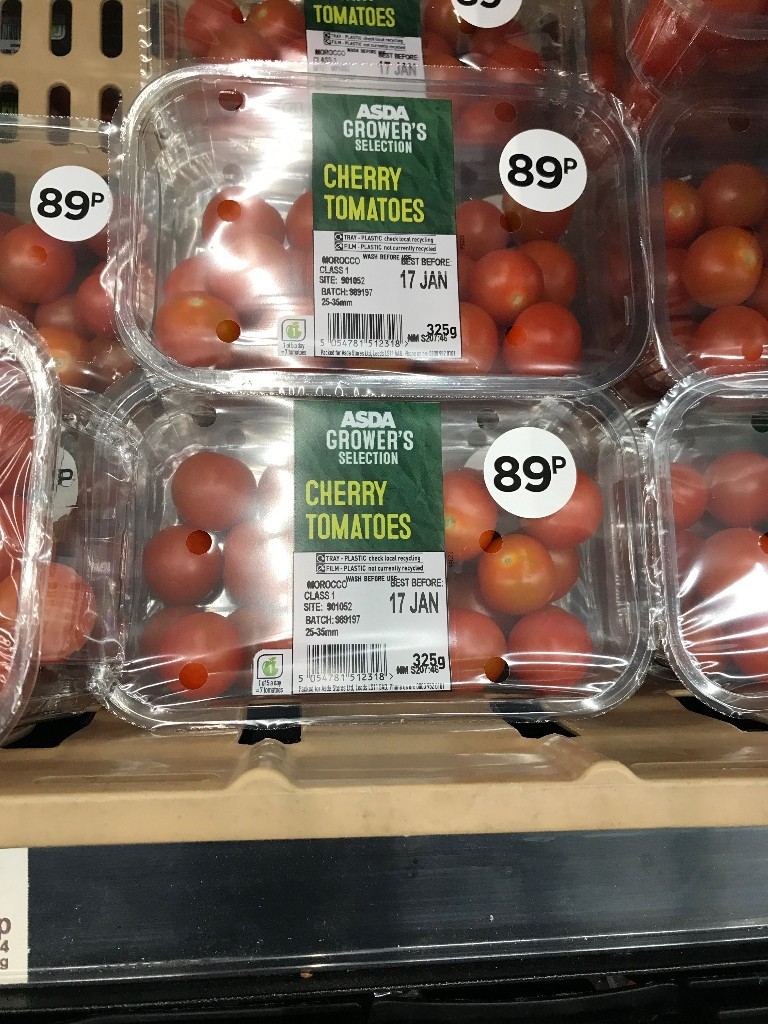
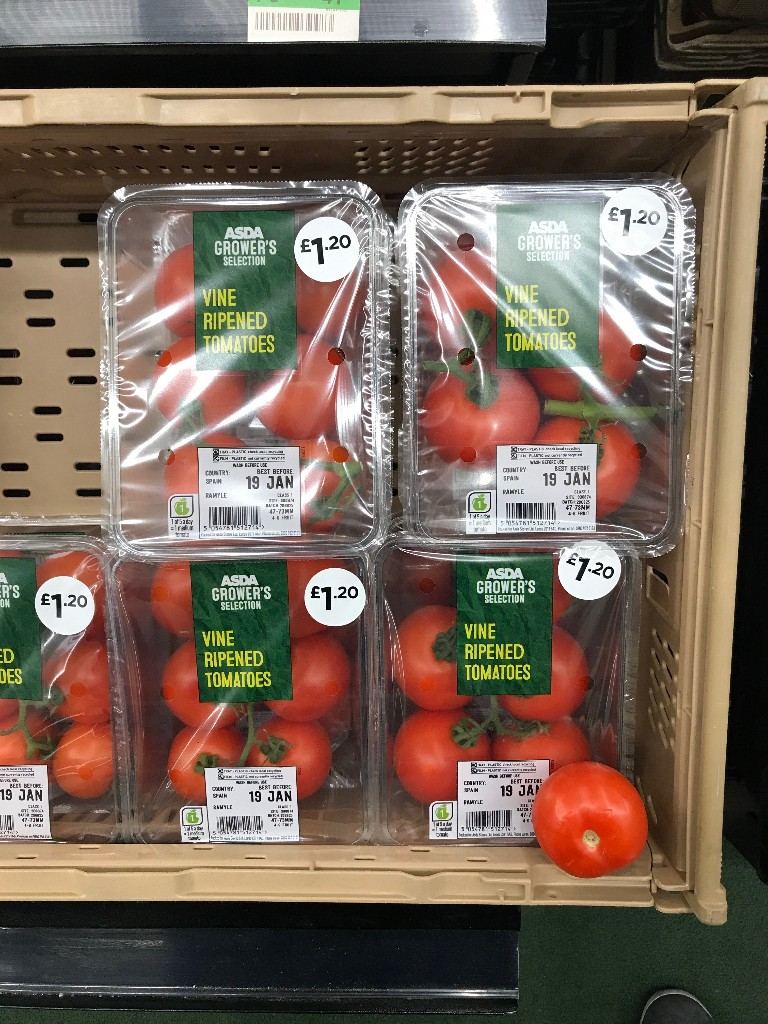
The on pack stickers do help to call out prices to customers, so you'd assume that these prices are competitive.
Certainly online, Morrisons are £1.24, Tesco £1.25 and Asda £1.20 on Tomatoes. Unclear with Sainsbury's as only premium ones pop up, but one would assume they'd be in the ballpark.
However Waitrose with their classic Vine Tomatoes are at £2.......
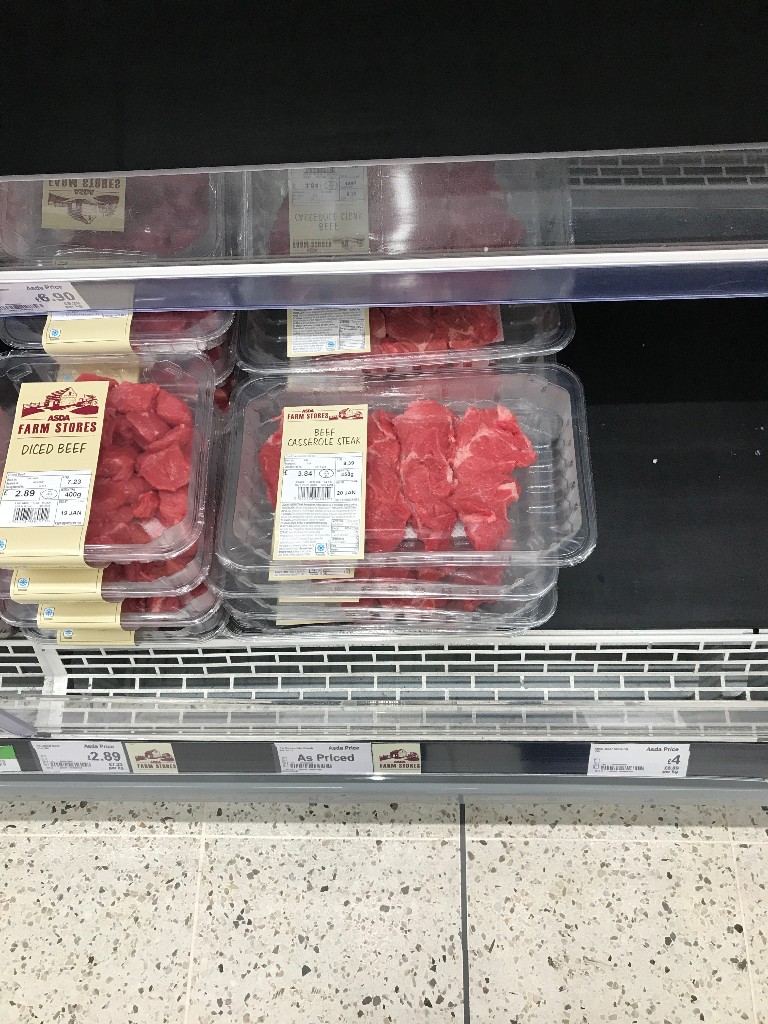
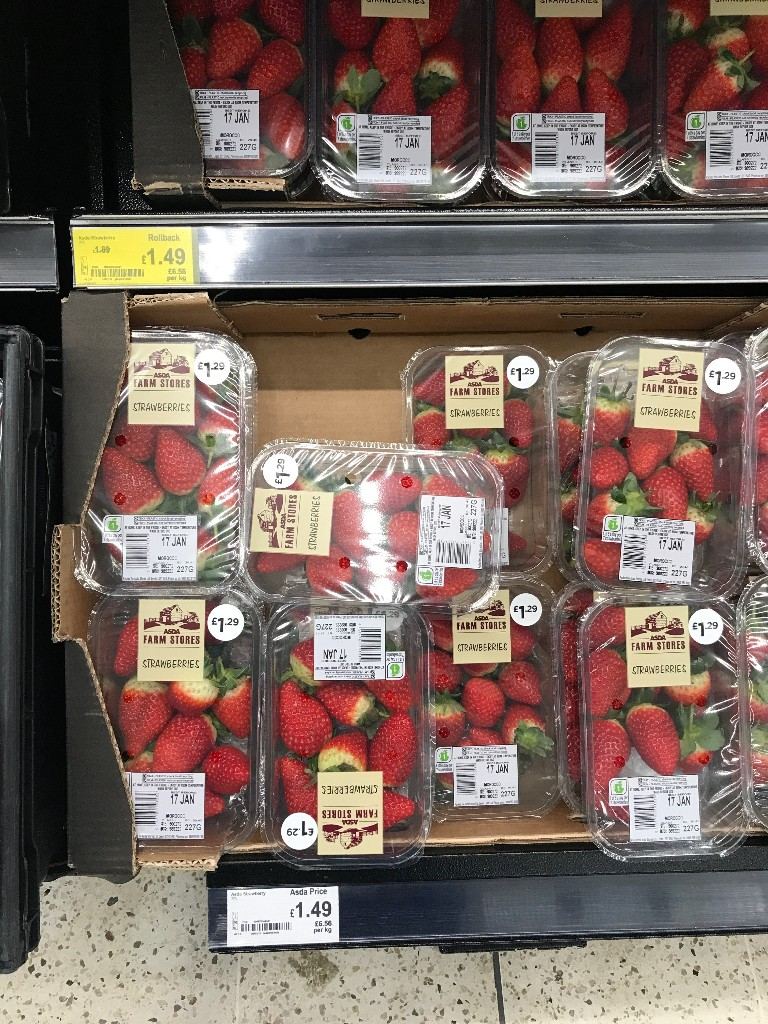
The Asda 'discounter brand' Farm stores appears to have landed well having been in the mix for around a year or so now.
It's designed to imitate the work that Tesco have done on neutralising the price gap on Produce and Meat vs. discount, but it is deflationary.
The rights and wrongs of 'brands' is a debate that runs and runs, but Asda bringing back an old value tier brand was notable. The range seems to sit in the mix quite happily without much fanfare but does exist for those super price sensitive customers.... Coming without the 'stigma' of buying Smartprice or other value labels.
There is a slight issue with the label versus the on pack price on Strawberries... It seemed to indicate that the core own label should have been here, not Farmstores.
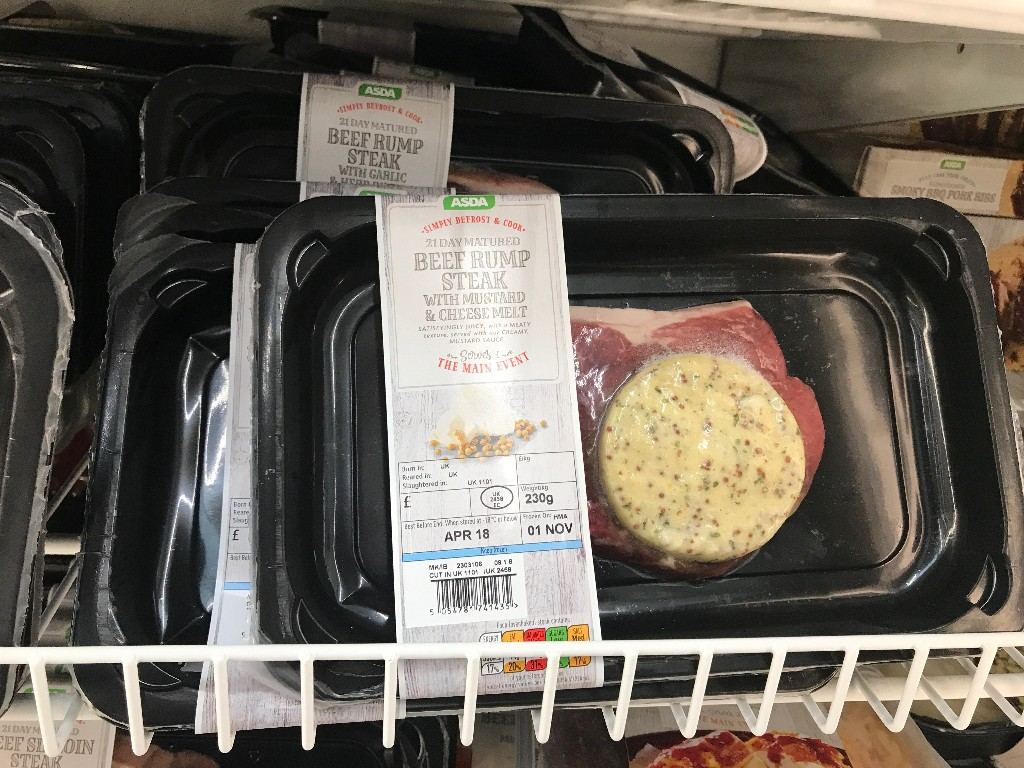
Iceland are another retailer to be in focus in the coming weeks as they continue to progress well with the "English Discounter" label. Expanding fresh foods and focusing on value is serving them well, alongside a growing premium range too.
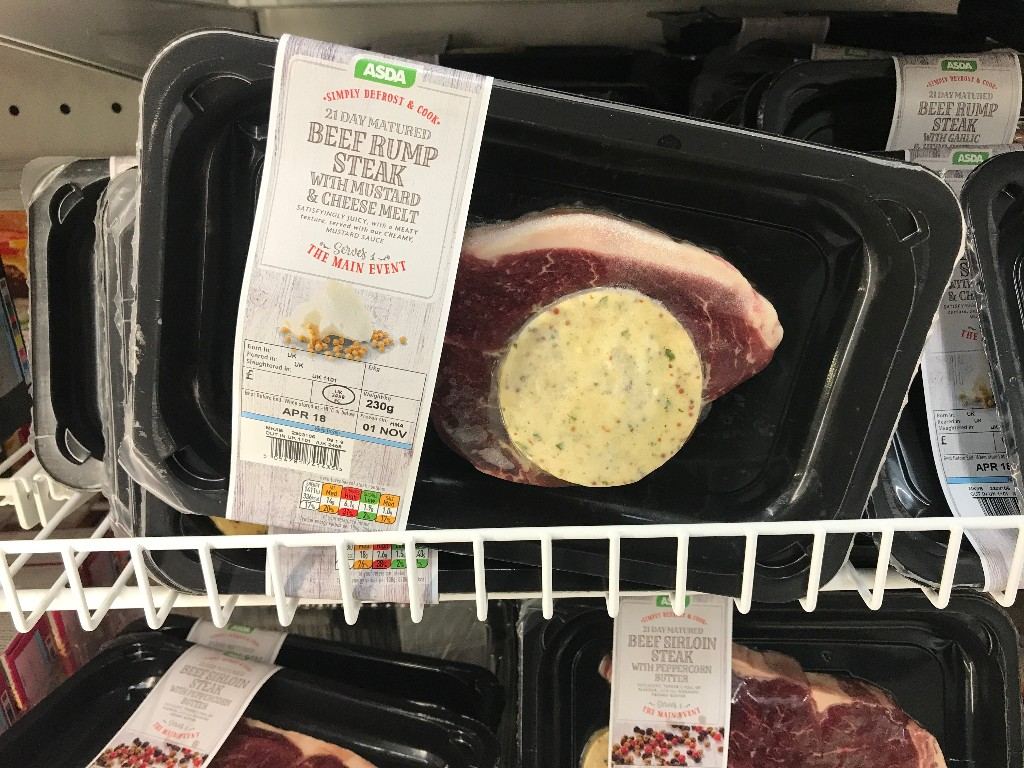
Asda will be able to identify customer overlap here and where they lose to Iceland will be on Frozen Foods, so it was interesting to note some pushback with Iceland imitation Steak products.
These products looked good at the shelf edge, with added value in the way of Butter too.
Own label growth remains the golden goose in the marketplace given the controls that this strategy gives, both over price and also the quality of own label products.
The customer is open to buying own label products, however this isn't a one way street of benefit. Any focus on own label and a 'lower price' whilst great for the long term has a deflationary benefit in the short term.
Should you as a buyer be happily selling £2 Handwash to the masses until Aldi come along at 99p, taking this sale alongside about 50 other items via a customers weekly shop. Of course, a buyer can run a special offer and pull other levers to maintain the sales line on branded goods.
Or to focus on own label, perhaps at £1, or £1.09 would close the gap demonstrably versus discounters but would deflate the category on a sales value basis. You have to sell two bottles of own label at £1 versus a brand at £2, and that's just to stand still....
It's not easy, long term is the right play and 'winning together' is another one to think about. Everyone doing the same or similar.
It's Ok for the buyer on Handwash to do his bit on pricing and own label until he's fired out of a cannon for losing (£), despite gaining some volume inside a year with his new strategy.....
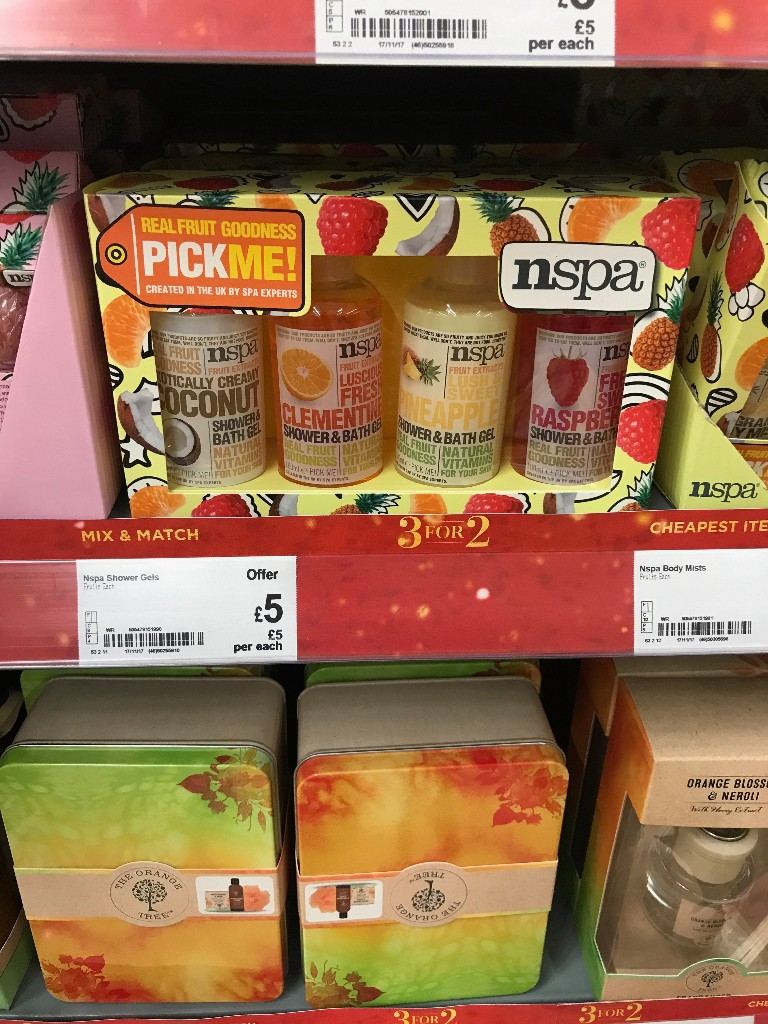
Branding is all important for own label, the NSpa line is Asda own and they are strong in this category. Cosmetics are also strong with George with both 'brands' appearing in gifting for Christmas.
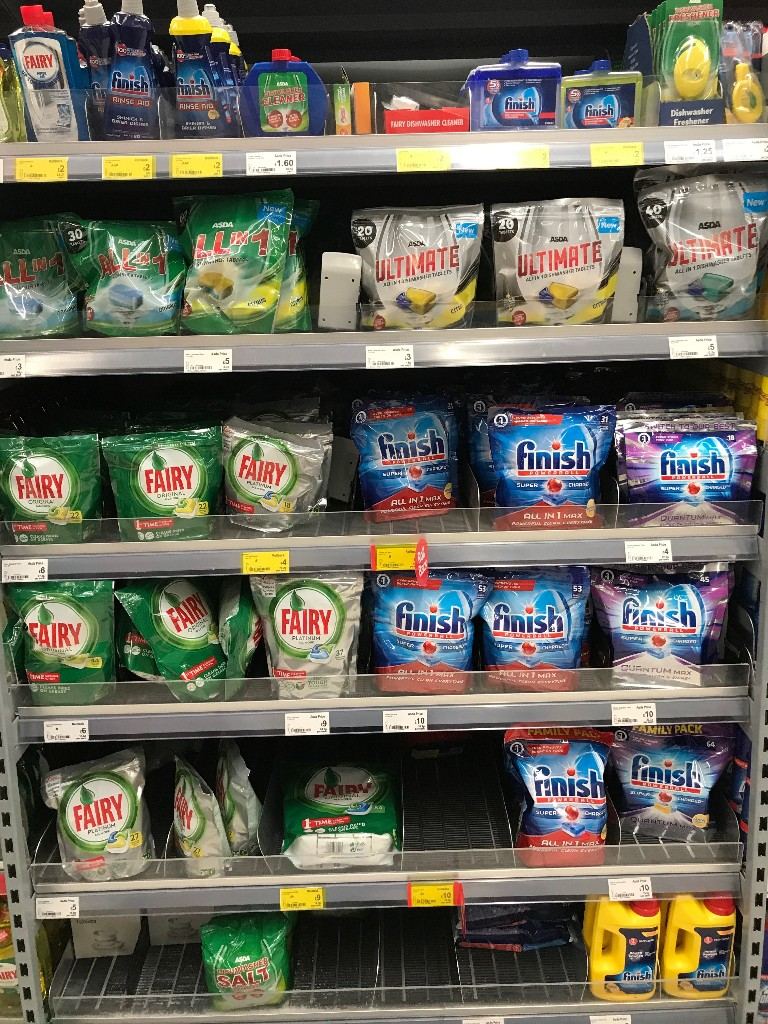
Shelf placement is all important, whilst Tesco weren't the first to dishwasher pricing (Sainsbury's in fact beat them by about a year with regular prices / no hi/lo). Tesco have blazed a trail across their categories with own label focus on at eye level in fixture.
Asda are getting there, an example is dishwasher which is a real 'hi/lo' category at the best of times, it's all deals via Finish and Fairy.
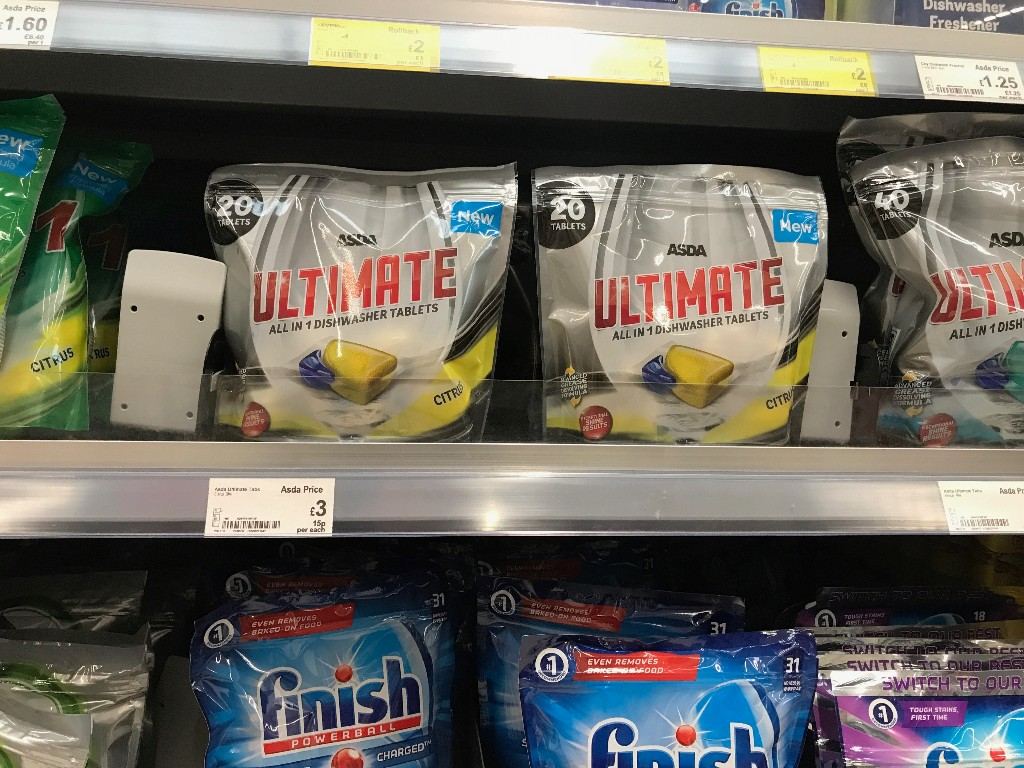
Asda have launched their own equivalent tablets with different pack sizes to close the gap and ensure the customer has a choice.
The product also occupies the crucial shelf in the fixture, far more prevalent than the base shelf which would have been the place for own label some years ago.
The challenge for all retailers (and we see it more and more) is where Home Bargains / B&M who sell Household and other Impulse, FMCG branded lines succeed.
Assuming Asda are out of stock on a deal, or don't have a low enough price on Finish for a customer. The customer decamps to B&M / Home Bargains to have a look there. They'll generally find something and then buy other things such is the effective pricing and product mix of a variety discounter store.
Variety is another channel that steal customers from the big four, perhaps under the radar a little due to their eclectic ranging and haphazard (in some cases) retailing.
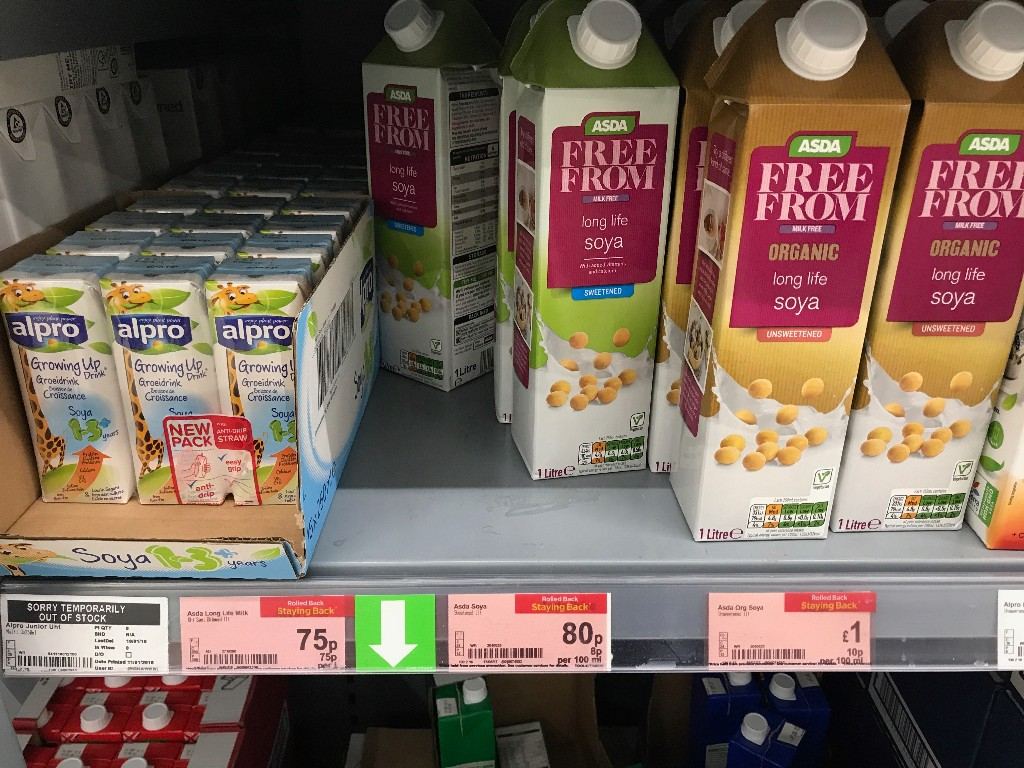
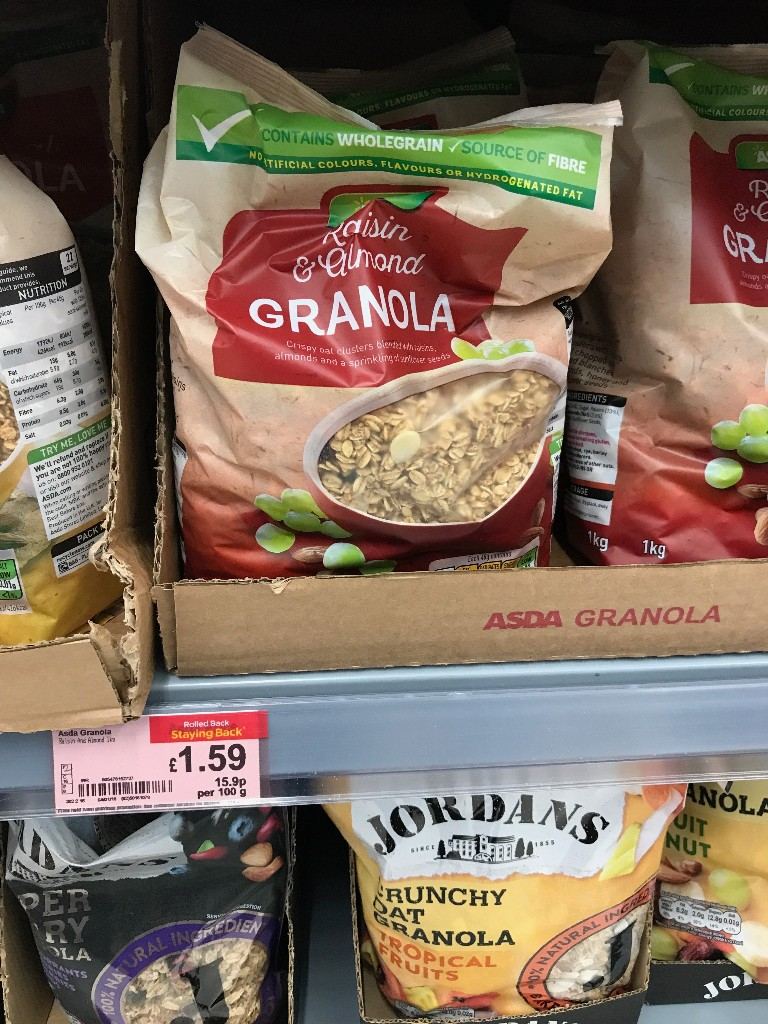
So the crux of the email, after that brief walk around Asda is their new campaign. Rolled Back, Staying Back.
It's not advertised in any discernible way anywhere but the shelf edge, with this pink overlay denoting that relevant lines are 'rolled back, staying back'. In itself it looks very Wal-Mart in its presentation.
The basic premise is to reduce the volatility that occurs when a line goes on deal then reverts back to the pre promotional price.
Stability in prices is everything these days and something I've written about for a few years now. There are countless attractions with Aldi and Lidl to a customer, from the smaller store, reduced shopping time, limited ranges that don't bamboozle, great quality etc.
A key attraction is not just the EDLP, but also the stability of said prices. You could buy the same things in Aldi, or Lidl for 6 weeks and pay generally the same amount, give or take a few pence.
However if you did a big shop in any of the big four and bought the same things (including brands and remained loyal), you could well go from £80 to £120 as promotional cycles changed. It's better now than it once was, but a gap would still occur...
Therefore with customers watching prices like hawks in 2017/2018, they immediately notice when things rise. Even if there is always a rise (change in supply for Produce e.g.)
So "Rolled back, staying back" denotes said lines are not going up and are staying at their promotional price. Reducing volatility without 'locking' a price point down.
Like any campaign or idea, nothing is new in food retail, it's just the execution is better, or worse....
This campaign from Asda works well at the shelf edge, but it's similar to the Morrisons 'Way Down Price Crunch' which highlighted price cuts pre Christmas alongside the length of time said products had been dropped.
Some had remained at the lower price for over a year, at which point the message can change and be advertised as a lower price.
We have seen no real commitment from Tesco around this but they have generally cut own label prices whenever they revisit a category for its relay. This is presumably to pass any volume based benefit to customers around the own label whilst maintaining momentum.
Taking items away from hi/lo deals and in to regular pricing was something Sainsbury's were doing first, starting with Dishwasher and moving around the store.
It still occurs with a number of Health/Beauty lines, including TreSemme Shampoo lines taken out of promotions and pegged at a 'regular price'.
Everyone has reduced their promotional participation but value remains a mix. It is about promotions and low prices and own label together, as one.
Asda still have a lot to do as they recover, but a commitment to lower prices, every day is where the market has headed... Asda need to follow in this regard, whilst still doing Rollback......
Did you enjoy this email? Join our service
Seasonal reports are available, email for a sample
From the Grocery Insight newsletter archive, first sent to subscribers on 17 January 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.