Asda - Turning the corner
19 November 2018

Forwarded this email? Subscribe today for more!
Our Halloween seasonal overview is coming soon.
It appears to be clear that Sainsbury's are pinning their hopes on their combination with Asda and of course, Walmart. It would make perfect sense for Argos as they can then benefit from the wider Walmart scale and the better buying terms, plus Sainsbury's will be able to improve their margin from a standing start overnight with the better buying terms that Asda no doubt have.
However; what does Sainsbury's bring to the table for Asda within the combination?
The benefit to their parent of course is that Judith McKenna is able to show that there are no sacred cows in her international world, even though she grew up within the Asda business, our market is built up and there is limited potential for organic growth..... Allowing a focus on India or other areas.
The benefit to Walmart of course is that they are able to potentially cherry pick some of the Sainsbury's talent to benefit the US business too, very much the engine room of the chain of course. Assuming the inter company rules work the same. (Whilst not an email service on US immigration law, as someone with a business that would want to expand to the US, it's far from easy, this is pre Trump too!)
Sainsbury's bring £3bn to the Walmart coffers and Walmart still retain 42% of a company that is virtually double in size (assuming all goes to plan). Bringing a more competitive retailer and one that has the ability to compete in the market.
Growth has been the last topic on the mind in Asda in the last two years or so, they never really made enough of the Netto acquisition and are left with a number of awkward looking 'supermarkets' that were never quite convenience stores but never quite a big shop either......
Their boon was in 2013 and 2014 where they read the nation, price locked numerous items and capitalised on woes at Morrisons, Tesco and the state of broad flux at Sainsbury's to be effective against the discounters. However, WalMart were just getting around (under Doug McMillon) to begin sorting the US business out and investment was sorely needed.
Thus Asda pledged to return x in profit and delivered that which meant (initially at least) there was no real impact as the business was trading well, but as recoveries started to take hold at both Morrisons, and more importantly, Tesco, the business was found wanting.
Especially given the discounters continued growth and their expansion in to new areas, larger stores and also a wider fresh foods / premium range. This impacted Asda and hamstrung by delivering a profit number, they were unable to compete and 'step on'....
Leading to the 'nadir' of -6% Christmas sales, commercial signage popping up all over and an offer that was lightweight at best with stores that were creaking due to a tightening of hours and a restructure that was aggressive and well ahead of the curve, but caused problems. Mark Ibbotson (COO at the time) pointed that everyone else would have to do this. He was right.
Sean Clarke came in of course to steady the ship as Andy Clarke departed (despite anointing Roger Burnley as successor ahead of time). Burnley then took charge around a year later and has had quite an impact on the chain with continued strong performances on a like for like basis and interestingly, Kantar has also noted their stronger performance on a number of consecutive months.
Asda surprised a few last Christmas with their performance for the Christmas period; especially in areas like Premium, however it's clear that the discounters resetting perceptions and price links means that Asda (historically, not a great premium based retailer) can capitalise and by enhancing their premium range - drive sales for customers who may otherwise go elsewhere.
This then spells bad news for Sainsbury's, where a customer may go for those 'special bits' at Christmas, instead spending at discounters and Asda.... Equally customers who go to discounters may well go to Asda for brands (strong for Asda) and the larger pack Beers etc.
So whilst in a narrow battleground on price; Asda have sharpened up demonstrably in stores alongside their "rolled back, staying back" campaign has aided price perception....
Whilst Asda will never lead the market in the UK; they are simply unable to do so given Tesco have more shops, being a strong and effective number two is more than in their reach. Especially with a drip feed of investment from Walmart International...
Given Sainsbury's obvious woes, declining store standards and various challenges around margins, these things are not easily reversed out of either..... There is the potential that the enlarged group inherits a Sainsbury's business that is deeply out of sync in store standards, availability and the general environment. It feels like Asda could make a go of it on their own given the momentum they currently have, they'll never lead the market, but what is the expectation?
The deal makes sense for Walmart. But as time passes - Asda look stronger and are getting back to something resembling what made them great under Archie and Allan many moons ago and indeed in the not too distant past where they felt relevant for their customers. However Sainsbury's look further away than ever from their heritage at the shelf edge.
Given that more space and stores is the antithesis of a great many things in UK retail; you just wonder in another, parallel universe, had Asda moved to buy someone like Wilko for example... Would give a boost across their non food and clothing (added in to these stores under a Living style banner) volumes and enable further investment in the food pricing. However it goes against the grain with online....
One sees what Sainsbury's & Asda brings for Walmart, one sees what benefits it brings to Sainsbury's but what benefit does a deal bring to Asda(?) Always difficult when one is trading well of course, if they were -7% it would be an entirely different question.
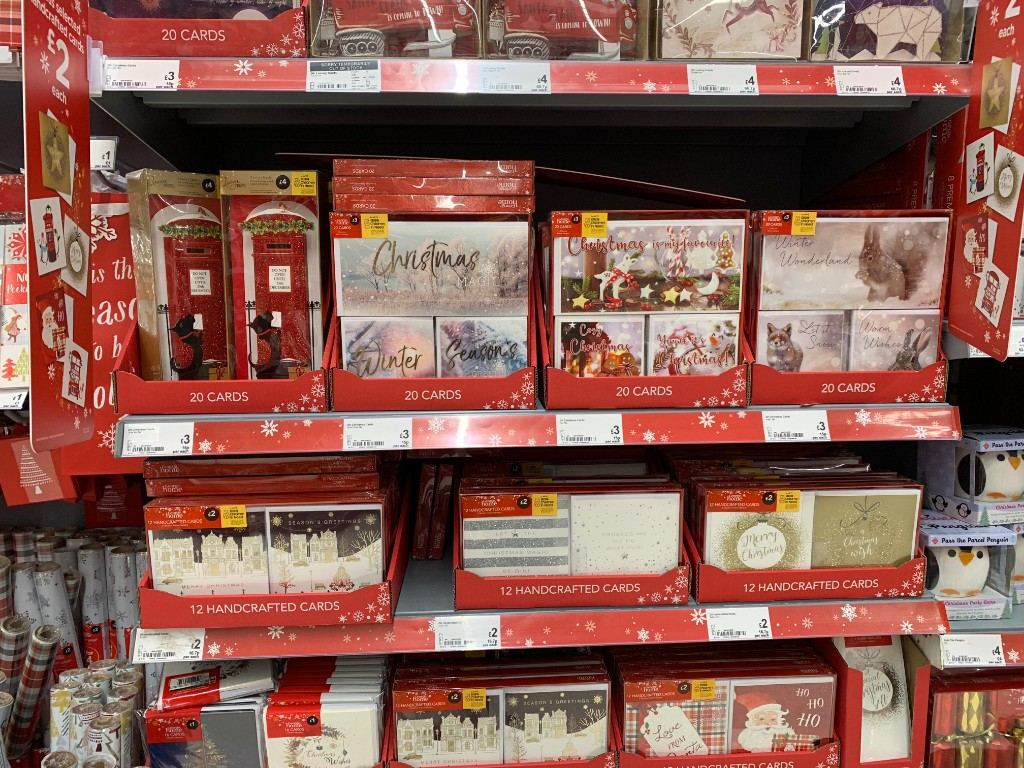
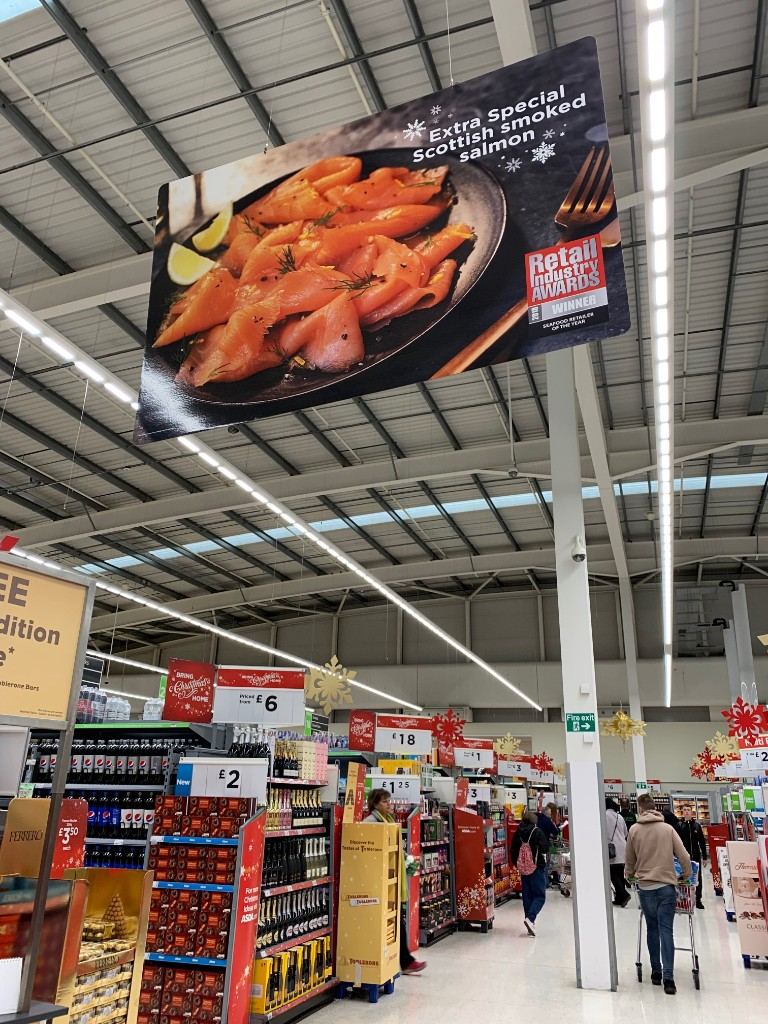
Ahead of Christmas; Asda look the best set up in the market with a strong mix between food and non food too. Their non food continues to impress, it is often the case that most of their range could be found in Next (e.g.) for a higher price.
They are always on trend too, capitalising on the unicorn craze, pushing novelty items (iridescent cutlery, multi coloured to you and I) alongside various Santa cups, mugs and the Christmas "tree" shaped pot.
Areas such as Greetings cards are strong; an area that offers fierce competition in the main supermarkets. £2 is the leading price point and notable that Aldi particularly are strong in this area this year too.
Wrap is also clearly advertised and well merchandised; works well for the shopper looking at these fixtures.
Overhead; signage points to award winning lines / ranges and their premium Mince Pies recently came top of the league with Which? (Waitrose were bottom....)
It's a battle for quality and again, the discounters reset this barometer with quality and re-educating the customers that own label could be market leading on quality and also lead the way on price too.
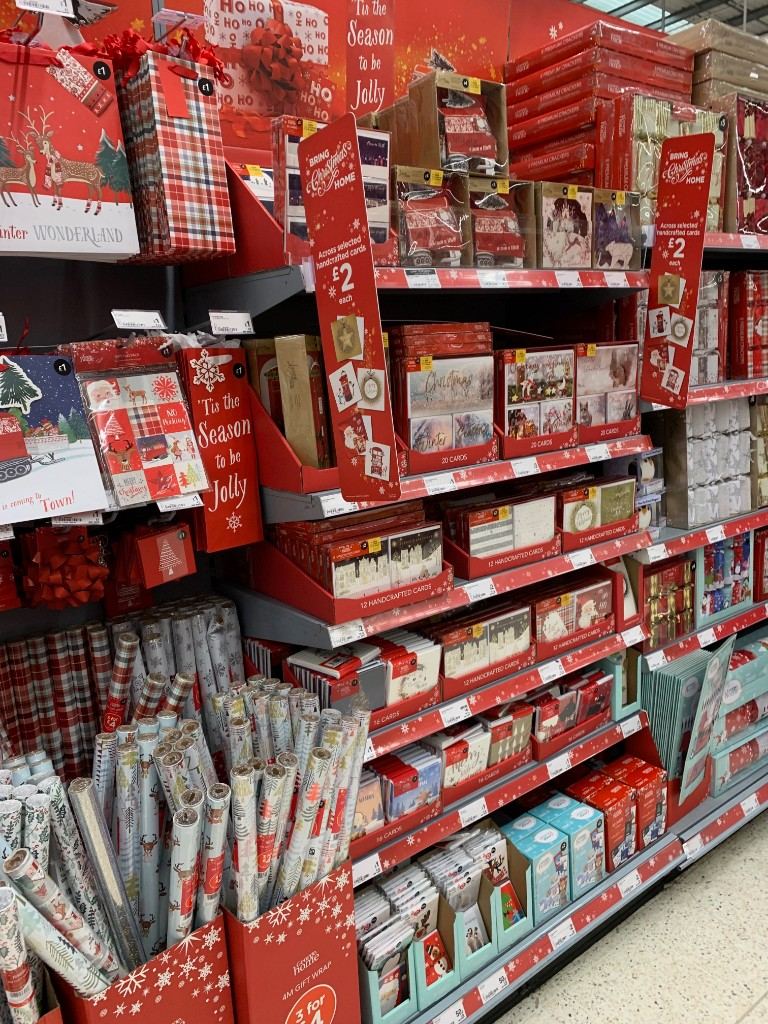
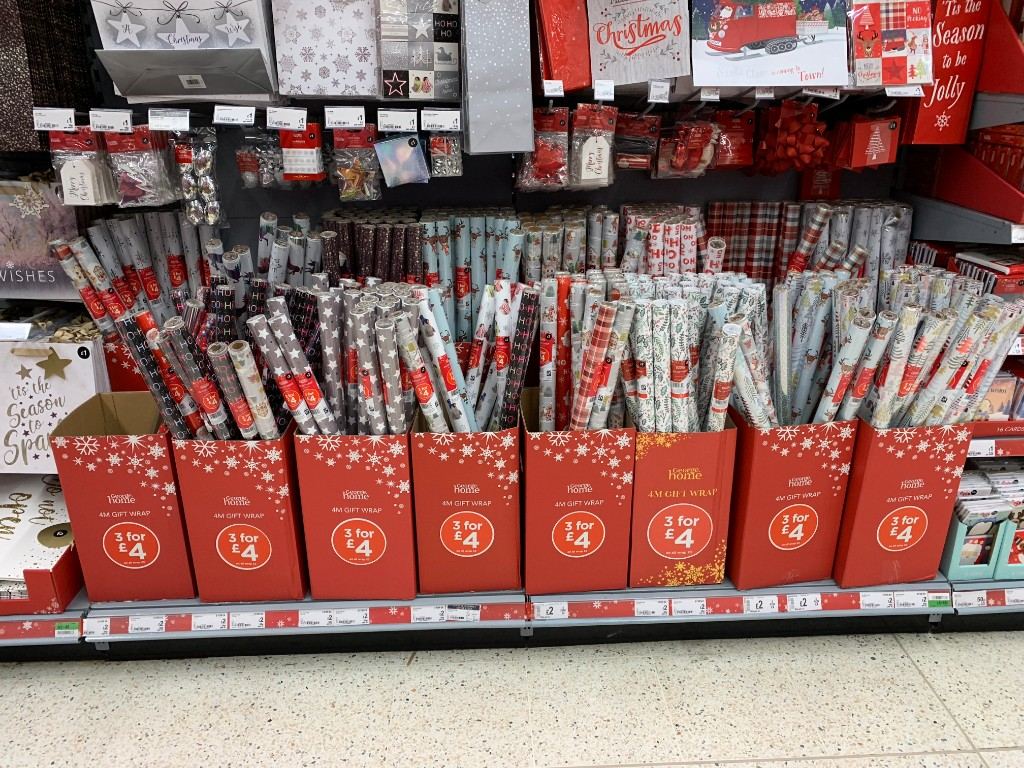
The range of 'mad' Christmas GM / Non food lines are great examples of where spend can be obtained from customers, purely for the novelty effect.
A strong range of products and these 'mad' Christmas products always fare well on social media.
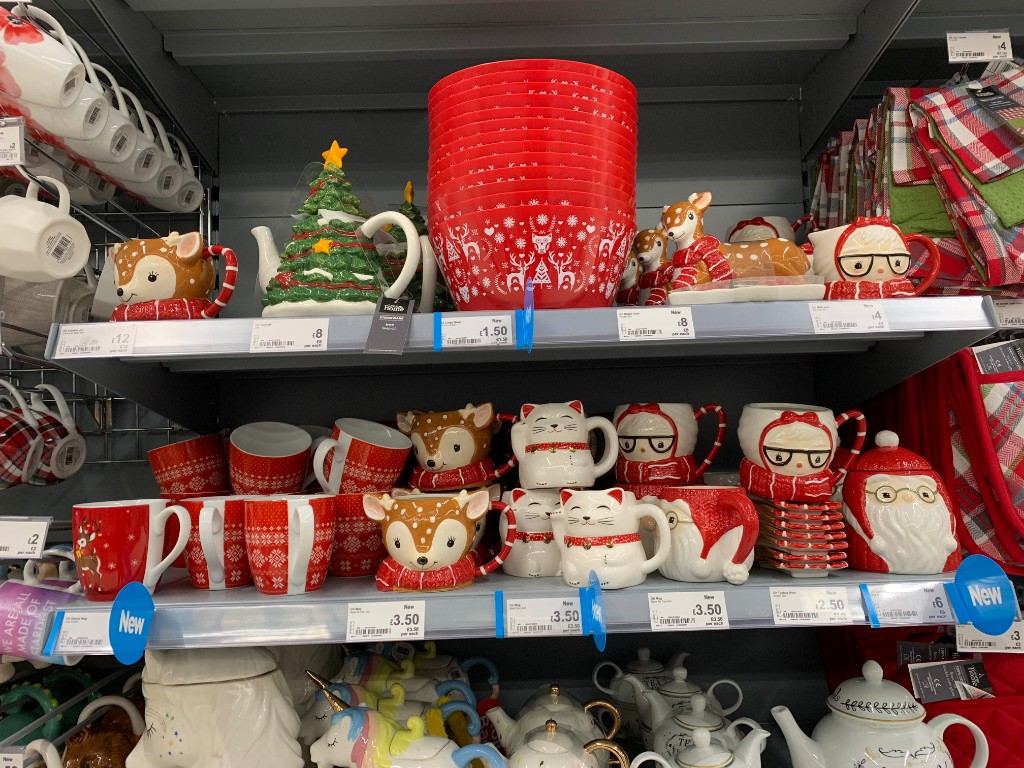
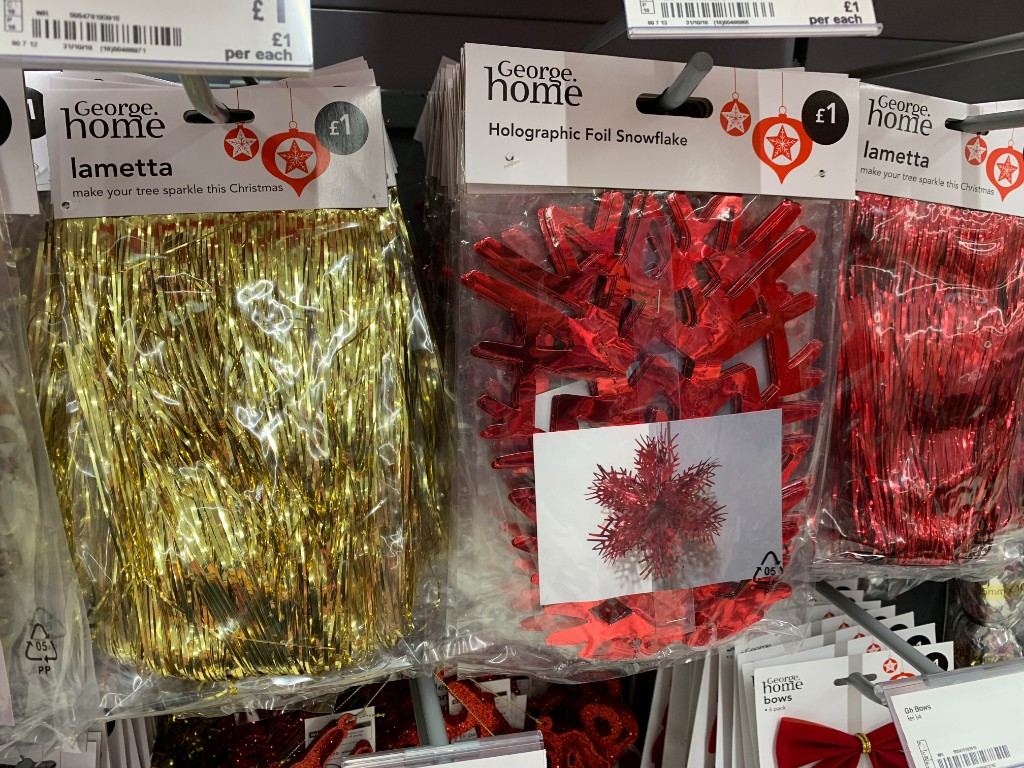
Remember hanging tinsel based decorations around your house when you were a kid? Silently cursing as the large accordion style hanging decorations fell from one corner of the living room.
Well, they're back! Asda has a range of these at £1. Plays right in to the retro trend given most of the kids who experienced these will be c. 25-35 now and also, retro remains ever important.
Of course Black Friday was incepted by Asda before they backed away from it, both margin concerns but also the scenes of brawling customers, fighting over a TV that cost £40 less were unpalatable and not great for the PR element.
So the last couple of years have seen Asda back away from Black Friday despite the growth in popularity elsewhere. There were some 'deals' of sorts last year but nothing like the Black Friday of old.
Indeed the event appears to be getting longer in terms of deal duration around retail.
For me, it remains the largest act of self harm the retail industry in the UK has done to itself since time began. Let's discount stock we'd sell anyway, 5 weeks before Christmas! Amazing.
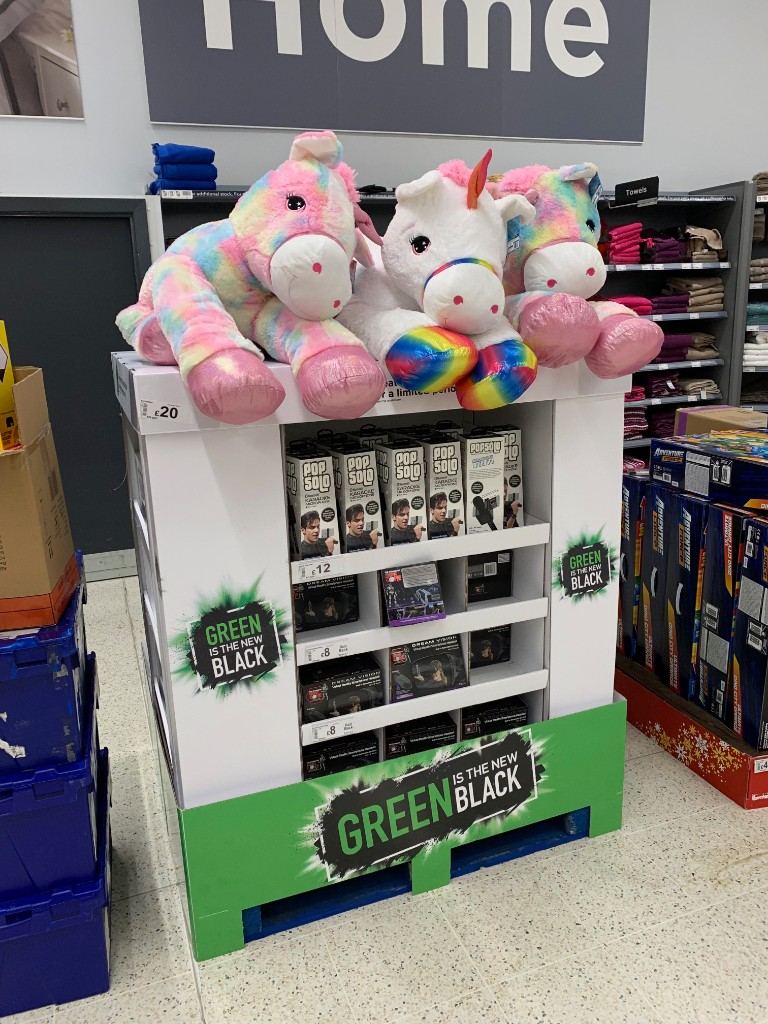
However Asda are back in the mix this year but narrowing the scope to a few lines with their 'Green is the new Black' strapline for large Unicorns (trends!) and numerous electrical lines too.
These are designed to be more frequent as deals and span more products, a la Morrisons who have done well with their "Black Five Days" campaign; however that too has started early this year.
Price is a key part of the Asda armoury and rivals talking about price can down Asda out, given their laser focus on price and the general messaging centring on price.
That said, their work on the wider marketing of the business has been less about price in recent months. They still have rollback and the repeated drum beat around price and "Asda" price.
However they have changed the marketing and generally spoken about quality in the stores, some price elements but not the only message at all. This has aided the chain to reposition slightly and talk about more than price and nothing more.
Their Christmas advert (a real favourite in the house) is a good example of the classic Asda 'craziness' almost alongside numerous products that can be bough in store, clothing, toys, food and matching pyjama's etc.
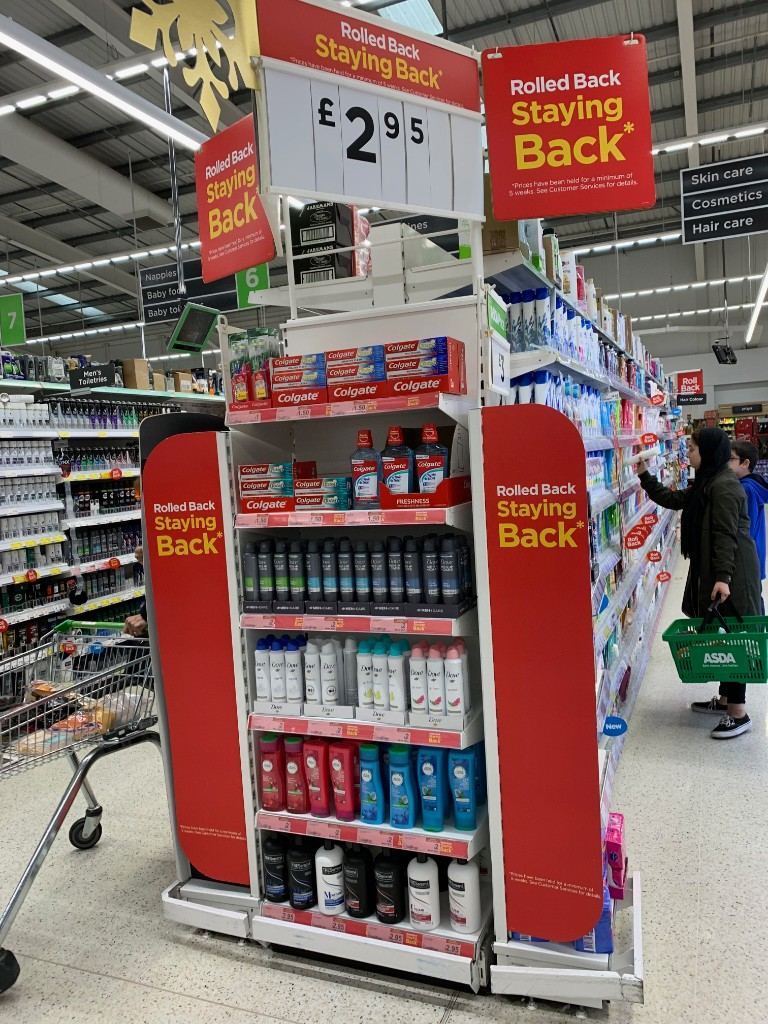
Rolled back, Staying back is something that has been added to over the year as products go on to rollback, then remain at that price. Thus taking a number of products out of the hi/lo game (branded ones notably) and providing a level of stability for the customer.
Vital for Asda who were guilty whenever Watchdog came on for having too many products yo/yo'ing and not providing that stable value that customers wanted. That campaign hasn't really been advertised to the wider world but remains a fixture in the aisle on the relevant products.
A vital piece of work and one that contributes to emphasise value without requiring a promotion necessarily.
Of course, more to come for Christmas with Asda and we'll take a look at premium as a whole for the market, but it's a growing area for Asda and again, piggy backing on the discounters strength in premium and rebasing the price / premium / quality argument too.
This has worked well for Asda and seen them pick up some decent figures in the deeper Kantar data, noting that premium does very well at Christmas when it's sited everywhere and there are numerous opportunities for customers to 'trade up' with some genuinely good looking (and tasting) products....
Intriguingly; not focusing marketing on price and price alone also aids this message around premium.
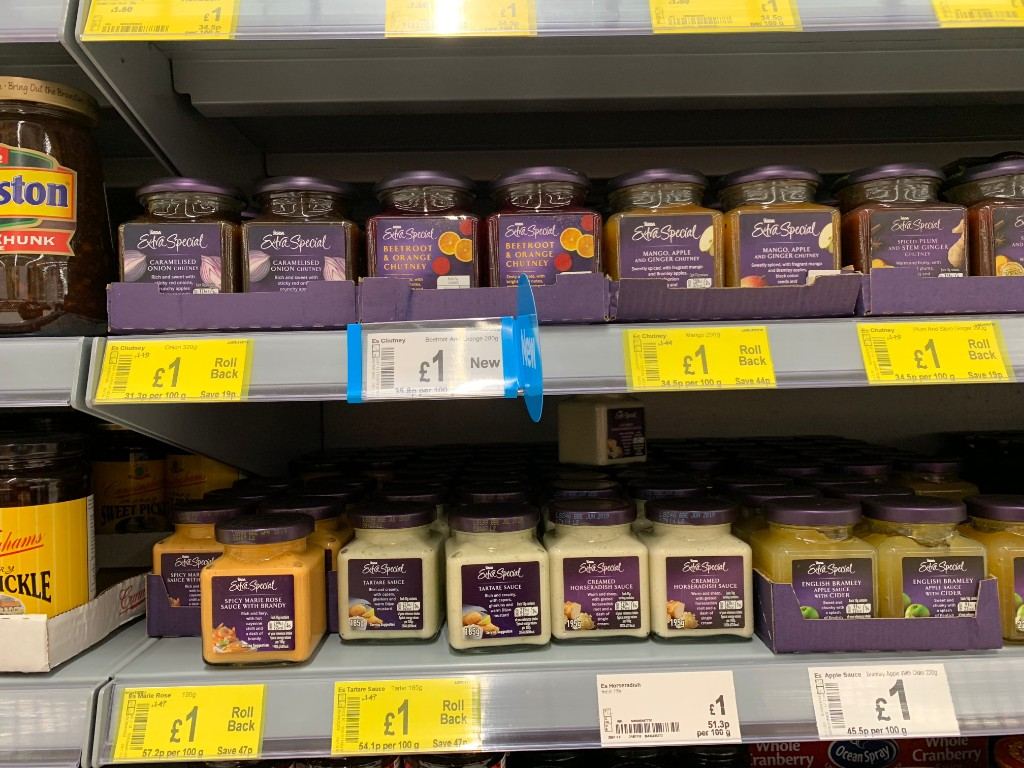
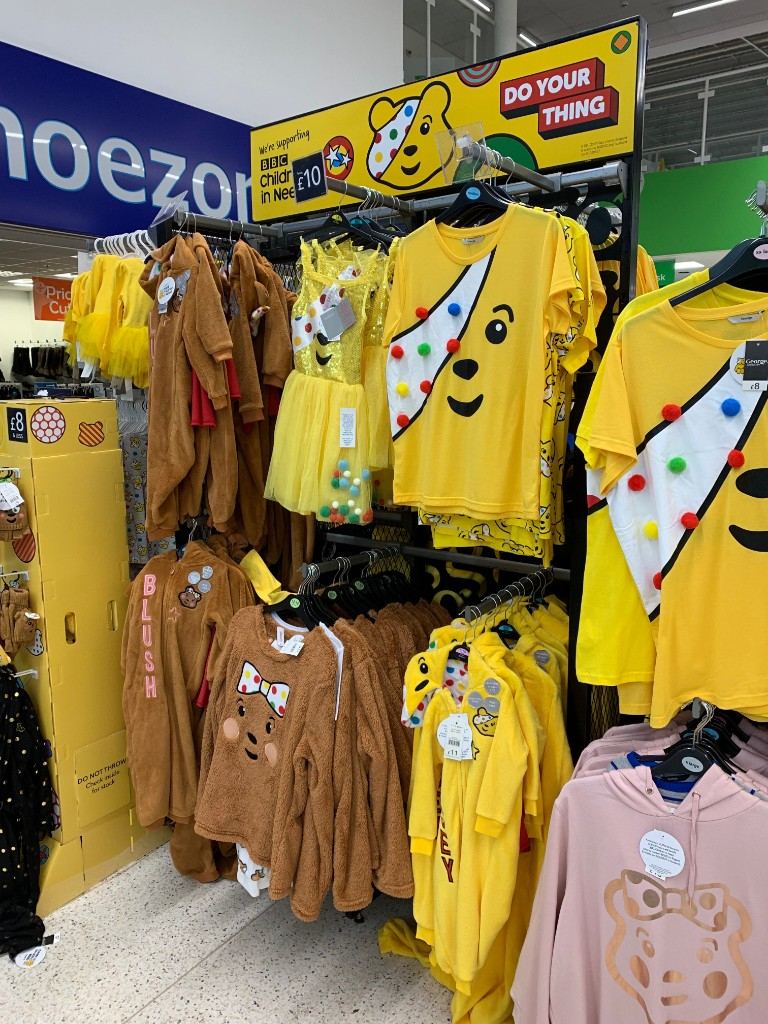
Of course, their charitable work is always noted with Ticked Pink and also, Children in Need which was featured here ahead of the event last week.
This is where the Asda business does differentiate, although Sainsbury's are strong on charitable partners themselves (to be fair all retailers do a great job here and have snuffed discounters out of this arena really).
The wider combination and merger looks set to run and run, Sainsbury's were noted in the Q&A for analysts talking about potential legal action, if necessary which was always on the table I'm sure.... However that wouldn't be good for Sainsbury's.
However for Asda; in store performance, set up for Christmas and execution all look solid and they appear to be as consistent as they ever have been.....
The longer this run of form goes on for Asda, the more questions will be asked about Sainsbury's and why their performance isn't improving despite the addition and success (seemingly) of Argos.
From the Grocery Insight newsletter archive, first sent to subscribers on 19 November 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.