A busy old week - Sainsbury's
9 November 2018

Forwarded this email? Subscribe today for more!
Our Halloween seasonal overview is coming soon.
An interesting set of results from Sainsbury's and despite the challenges we see in stores (beyond core availability where their performance is often similar to the pack, although Produce and Fresh are worse) there are definite issues around standards, cafe waiting times and queues at checkouts too.
Of course these issues are not unique to Sainsbury's, but that isn't really what this is about. In retail, you are for the most part in control of your own destiny and with it, store standards, your 4 walls and what you can control starts and ends there.
It's no good saying we're as bad, or good as Tesco, Waitrose or Morrisons when customers are wanting a better level of shopkeeping, or availability than those rivals. Sainsbury's had that but have dispensed with that advantage as they restructured retail teams in stores and the management structures were changed significantly.
In some cases, this means a manager who looked after Bakery in the old world may now have to oversee fresh food counters and the customer cafe (alongside another manager) but it must blur the lines of accountability and crucially, control?
It's a difficult balance, there is a need to turn a profit and margins are dangerously thin in Sainsbury's (now nudging over 2% but were as low as 1.8%) but to give up a stores based advantage is baffling.
The structures haven't landed, we have seen time and again on this very service where examples exist around cages being left on the shop floor or pallets being left on the shop floor - this remains challenging for the business and experience isn't what it once was in many cases.
However as easily as you coach customers in to coming to your store, training them effectively that you have what they want, queues are managed (IE if busy most checkouts are open etc) and the store is relatively clean and tidy.
Customers trust the retailer, in the same way that they may do on price, or quality even. However Sainsbury's displaying variable standards and indeed, being as ropey as everyone else (seemingly) means they are then asking customers for further reasons to shop with them.
Be it price, quality, range, assortment, even service. These areas are very, very competitive in the UK market... For Sainsbury's to be merely like everyone else isn't always enough.
It's not where you were that people remember; it's the fall from said lofty position that people remember.
Then very quickly; it turns to the 'new normal'.
So, to the slides!
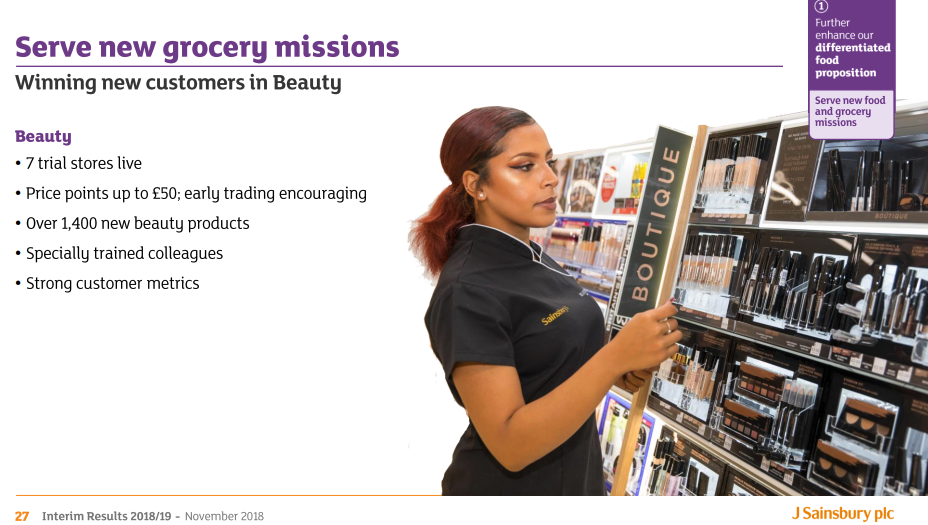
In terms of the beauty store; there are (as noted) 7 trial stores now live, I have seen one in terms of the set up (albeit nearly completed) and it's good for the margins clearly.
Sainsbury's had no real presence in this area previously so to bring in cosmetics is beneficial and dedicated staff are a must here, keeping the area clean/tidy and deterring thieves too. Shrinkage is the obvious worry given the high value nature of the product on sale, the main challenge is ensuring that the wider store lives up the beauty area with its fancy lights and displays....
It's no good having that if just across from the beauty area, aisle 7 looks like it hasn't been filled in a week.
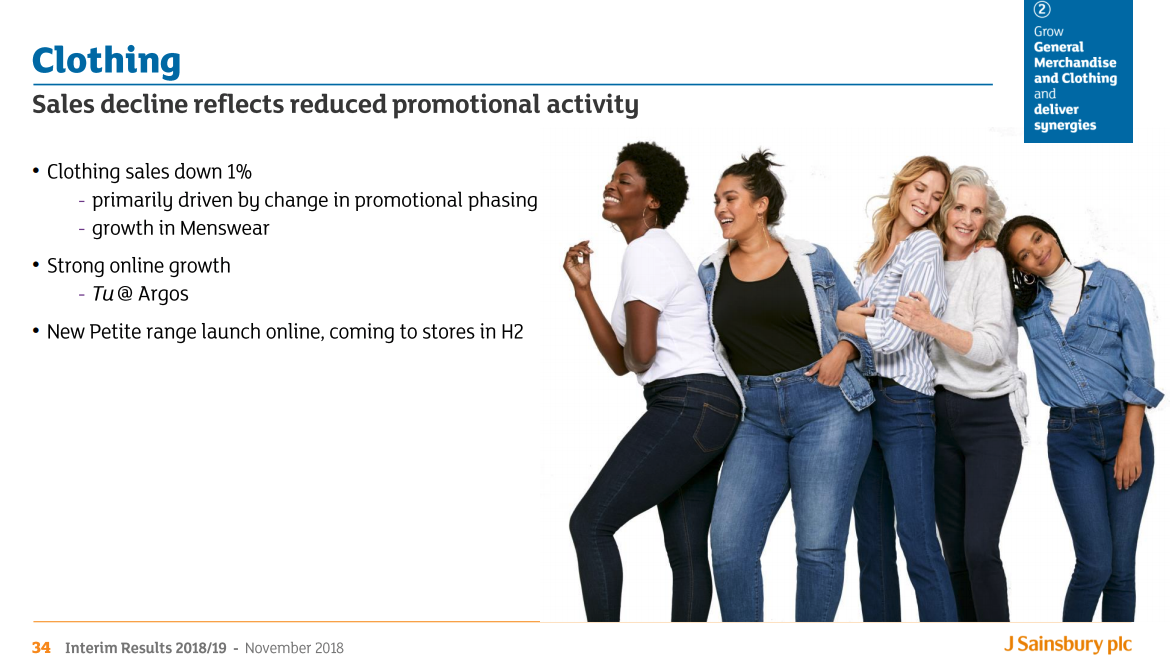
I must admit that whilst tracking the market weekly in terms of store visits, I wasn't aware that Sainsbury's had materially changed anything in terms of Clothing promotions, the half year results weren't bad but the -3.4% drop in Q2 was alarming.
Especially when you consider their half year end (22/9) would have included Back to School and Argos are also now selling Tu clothing....
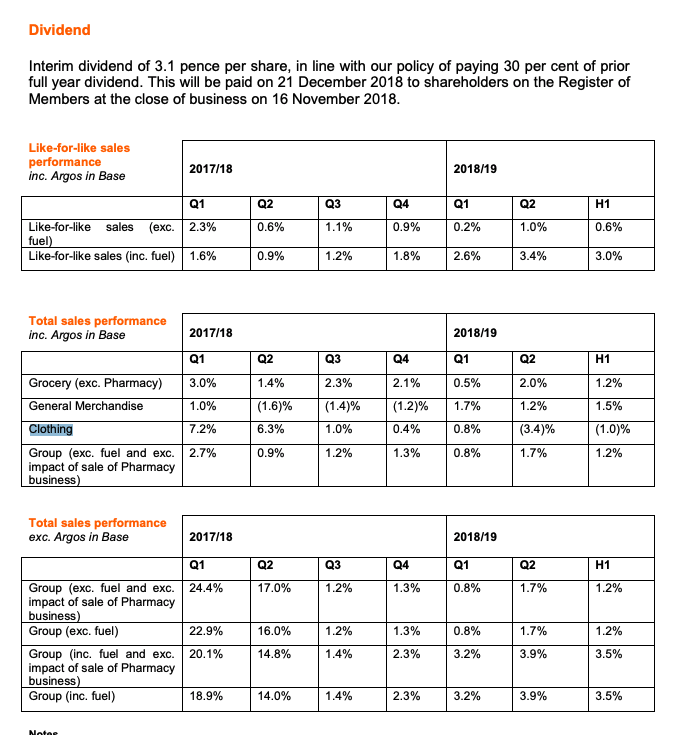
The overall figures were not that bad given the strong Summer; although for a retailer with such obvious quality credentials, it was perhaps a surprise that there wasn't more business in the BBQ / Argos landscape...
Of course these sales performances include VAT too, they don't exclude like the other retailers so there is that to consider, especially for Non Food and also some elements of Grocery (Spirits e.g.?)
Including Argos in the GM base etc is interesting as those results slowed down last year but have improved this year, still fragile returns and the wider economy and consumer confidence is probably playing a part here.
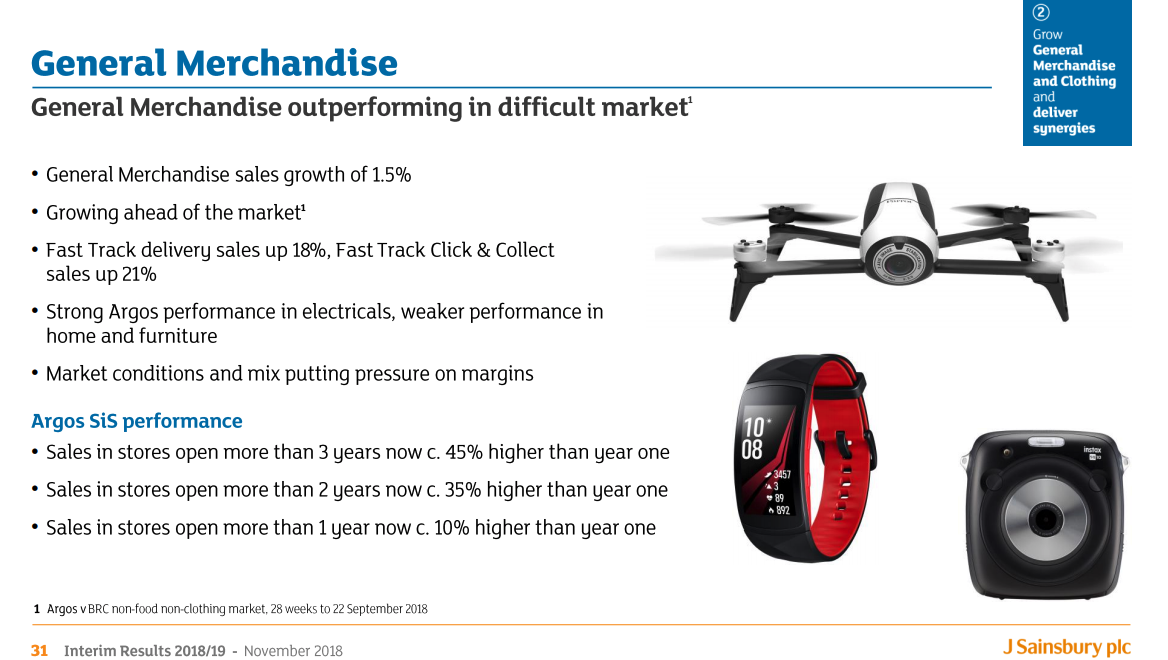
The GM market has slowed alarmingly as the shift continues online, alongside this there is a consideration that customers are not spending the money in this area any longer as things tighten ahead of Brexit.
Fast track is a great service and is a positive versus Amazon and Click/Collect also performs well. Good for Argos and the rationale for the deal of course.
Performing well in electricals is a slight concern for two reasons; given the hot Summer one would have expected outdoor and toys to perform notably well. This isn't called out specifically however.
Electricals are thin margin, John Lewis highlight their good performance here but typically speaking it's not a huge money maker so being strong there isn't necessarily great for the bottom line.
Home and furniture weakness is concerning; again indicative of the slowdown and customers 'waiting and seeing' regarding Brexit as there is uncertainty around. Next are strong in this arena and appear to have tightened up on clothing pricing, especially in Kids.
Their homeware range continues to grow of course and they remain a compelling choice for customers. Argos is a place that one doesn't generally link with said GM / Homeware.
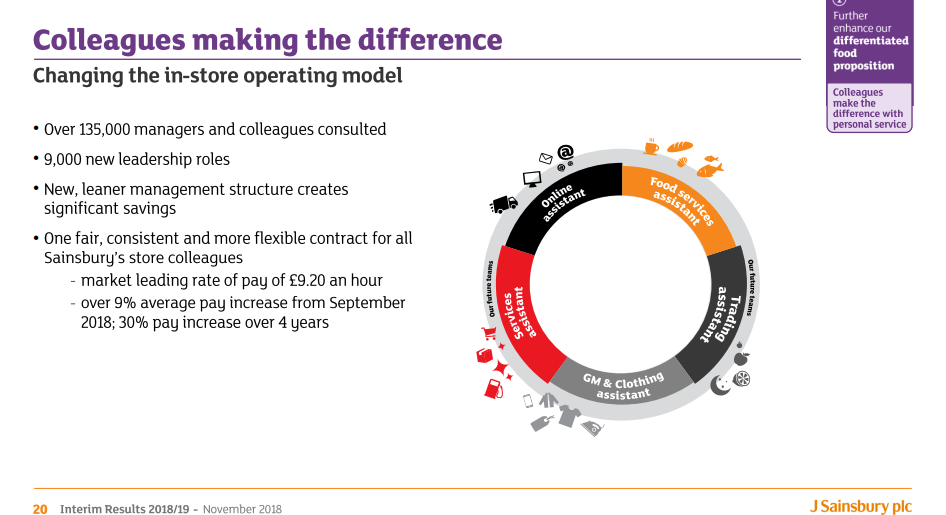
As touched upon; we know the operating model has changed as we have seen it in the stores unfortunately; this wheel is a nice representation of the new world and what the colleagues are paid to do.
The national minimum wage has had a lot to do with this switch; meaning the likes of Sainsbury's who count labour as their biggest cost in any case, paying people even more....
Leaner structure does create significant savings but could a more fatter structure still have delivered savings but kept the shops in a decent state of presentation for customers?
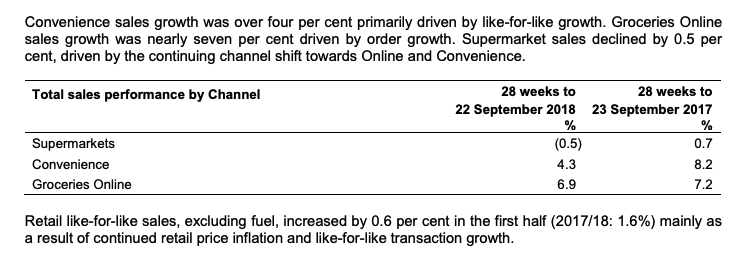
Supermarkets being down 0.5% in sales is not a good sign; admittedly the weather was hot which did point to people visiting convenience stores. The c-stores were +4.3% versus +8.2% in the same half period last year.
Online continues the strong growth despite profitability being entirely unclear and the same day delivery service will be popular; it's a good way to extract revenue from customers for an improvement in service - IE not just delivery, but the same day turnaround etc.
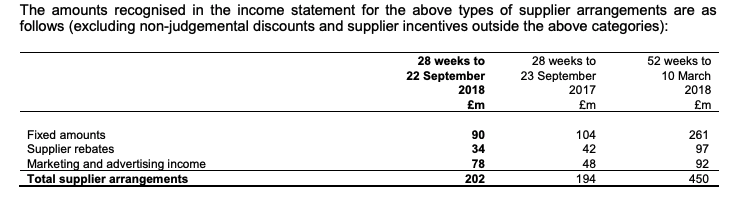
We can see from the numbers that commercial monies are rising, rebates are behind last year (could be a number of reasons) but marketing/advertising income is up some £30m year on year.
I have touched on the stores stepping up their signage packages to include more and more branded signage, shippers and campaigns that include the brands.
Nothing wrong with that but Sainsbury's were often focused on themselves and allowed the brands to get involved but would preserve stores at all costs. We have seen too many examples of where commercial monies run out of control and it becomes a drug.
It's hard to back away from as to swing sales back to recoup millions is not easy, it's also too easy to keep taking the commercial monies....
Used well they are effective but Sainsbury's have been running more and more loyalty / Nectar campaigns with the chance to win huge amounts of points if they buy Kenco Coffee e.g.
Ironically, the antithesis of loyalty.
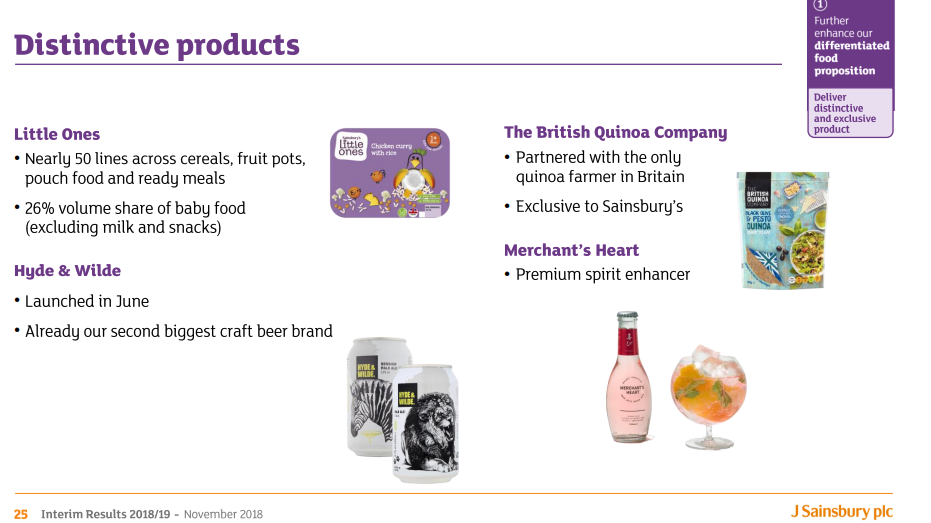
That focus on brands and the commercial monies can come at the expense of own label in terms of product placement in the fixture, or even on the ends.
Own label remains ever important and everyone in the market, post discounter now focuses extensively on own label as a way to compete on quality and price. Sainsbury's have always been very strong on the own label side of things, but now find their heritage hard to proclaim in a very crowded market with claims all over.
There has been some good work around the categories with various exclusive house brands and work in health/beauty (notably) to develop a range of house brands that sit in the own label space.
Baby has been a beneficiary of this work with the Little Ones baby milk launching, following Aldi of course. A difficult market to get in to given the brand equity in this space, trust is everything as we know... However there is no better way to drive loyalty than via own label baby milk.
Work in Spirits, Quinoa and they have out M&S'd M&S in areas like Flexitarian and Veggie alternatives too. As ever, reactions will be incoming as you can't have anything for too long in this space, the challenge is to keep reinventing and bringing those customers in.
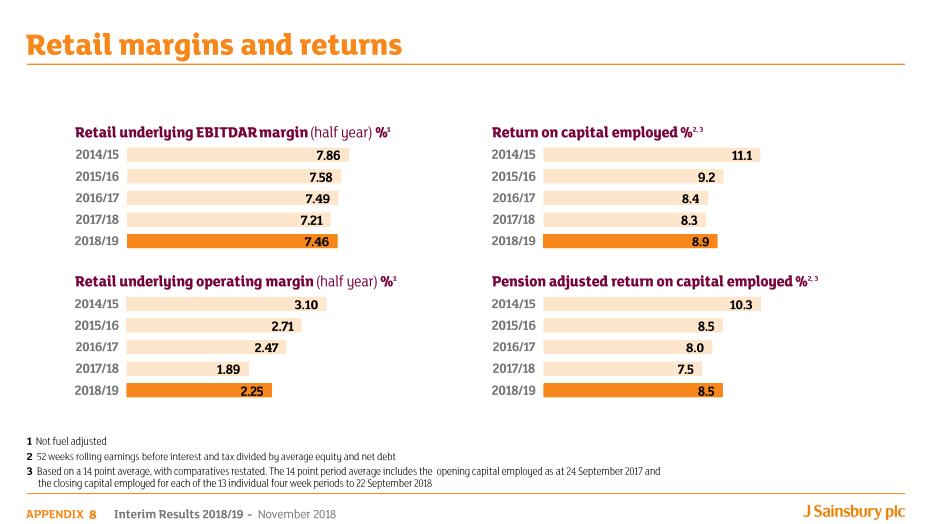
Margins were improved to 2.25% from 1.89%. However this is with £8m extra in the commercial money pot (although down elsewhere / £22m adrift y-o-y on fixed/rebates) and a huge cost saving attributed to retail operations. IE the stores that have fallen backwards in many cases.
The margin has only just moved above 2.2%. Difficult times indeed.
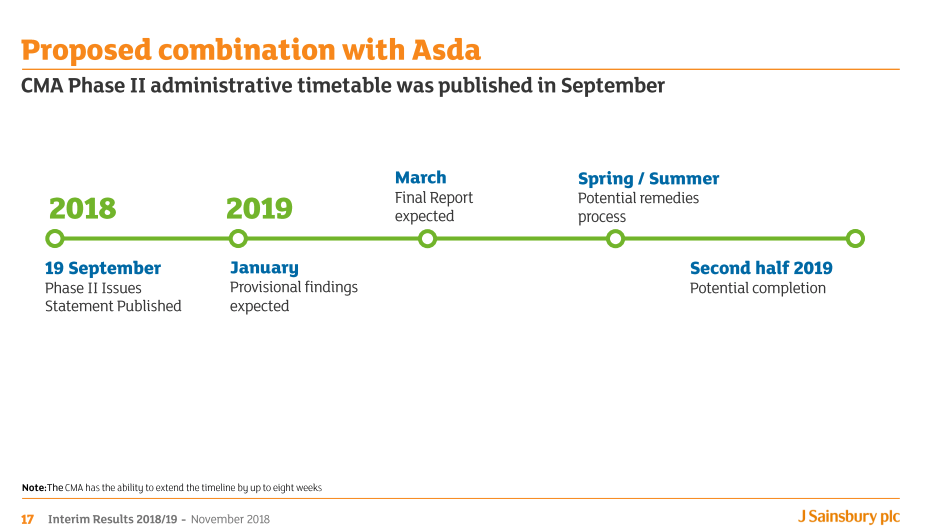
Potential completion for the Asda / Sainsbury's deal is marked as second half 2019 with the remedies process now flagged for Spring/Summer.
We haven't seen as much detail before but it was difficult without a CMA timetable. We have seen that now so the next steps suddenly become clearer. Only once completed does further hard work start with IT migration and the assimilation of product ranges and the like so they're at the start of a long, long journey.
Certainly talk in the Q&A yesterday around potentially having to go to court and the like which would turn this in to something like Brexit, not good for either party.
That said; having visited over the weekend, I was struck by how strong their Christmas package was and indeed, how busy the store was too. It feels like a business that is really getting back to what it should be about in terms of fun, seasonal events and value.
Conversely; Sainsbury's look to be heading the other way. A reminder of difficult times ahead for consumers and concerns in Clothing, Non Food and also a slowdown in supermarket sales.
It's a funny old world.
More to come on Sainsbury's in the coming weeks. Next week focus will turn to M&S Food, Morrisons and also Asda and their current improvements.
From the Grocery Insight newsletter archive, first sent to subscribers on 9 November 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.