Lidl - A bit up and down
29 March 2017
Click here for a free 1 week trial to this service.
Subscribe to this service here!
Lidl have been flying under the radar somewhat in recent months, with the focus being on Aldi and their Christmas success and also their press drive on price and everything else.
Lidl have pulled back a bit from the press with their new German CEO (35, but looks about 19) just seemingly cracking on with the day job in typical Lidl fashion.
Of course the US is far different, with a lot of focus and press attention on the incoming launch for Lidl US. Grocery Insight will have their own take on the launch and what it means for the US retailers. Alongside what's expected from Lidl, given their work in UK and Ireland.
I hasten to add I wouldn't normally deliver a report for a launch like this (although perhaps I should!) but I've read some 'insight' that misses the point but it's to be expected, given discounters don't have an online presence. That flummoxes most who don't like to visit shops at the best of times!
The stores are where it matters and Lidl have been weakening a little in recent times in the UK. Nowhere near solid enough versus their previous standards, yet they continue to trade well, on Kantar at least. However as we know, those figures are heavily skewed by their new space programme.
Are they pushing back on delivering all three components? Those bring Quality, Price and Time? Common logic dictates you can't have all three; good quality delivered in a short time means the price has to go up. Low prices and good quality means the time cannot be 100%. IE you cannot find things on sale every single time....
Their labour cost feels higher versus their core model where they stripped back hours more than Aldi did (who have added hours in for their expanded range and service levels). But Lidl have seemingly pulled back a touch and level of fill isn't quite what it once was.
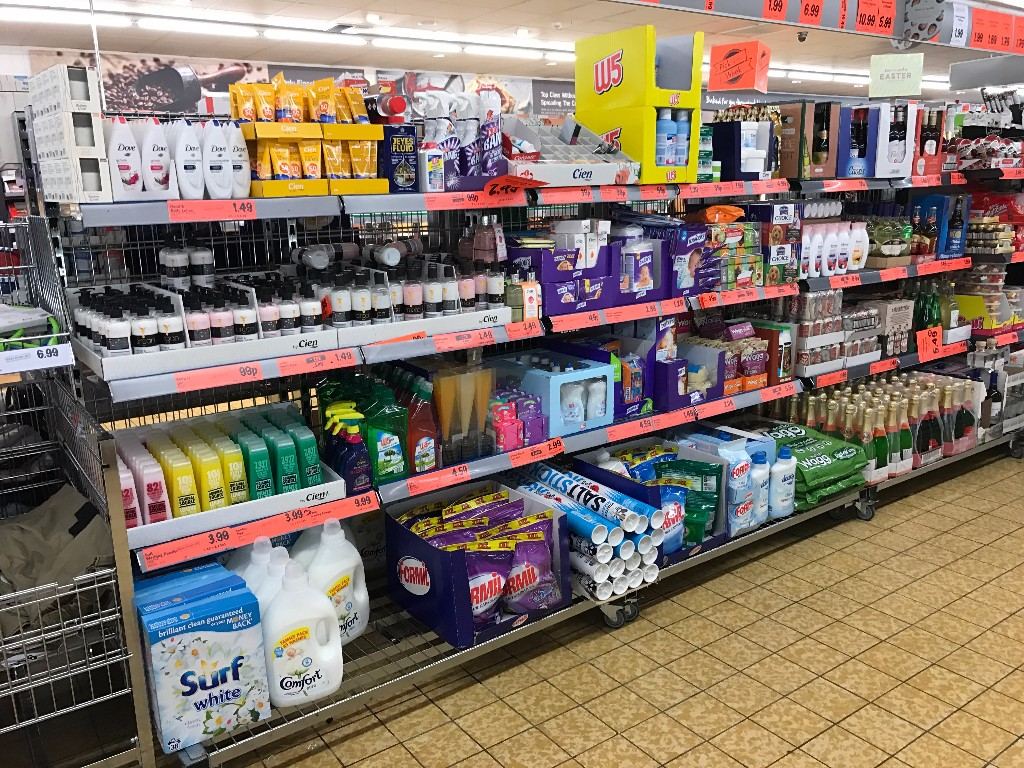
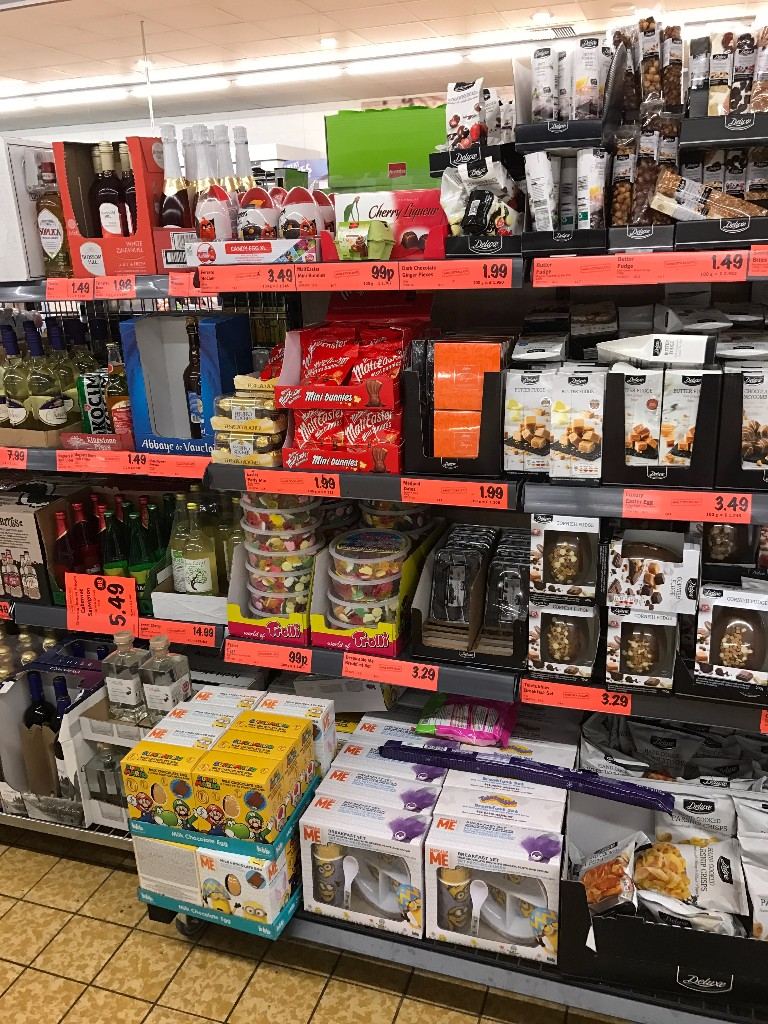
An interesting move for Lidl is their work to add smaller shelving fixtures to their seasonal run, Aldi have done this for some time now too, It enables them to trade Easter Eggs and other lines that are to be displayed individually, like Spirits and other seasonal grocery lines.
Lidl have added the shelves with branded stock to add further depth to their range, via the various events that they run. Some of the lines will be current event products, whereas others will be older event stock.
They're not as efficient as their wire bins in terms of fill though, but they are more effective to trade stock.
The dividing line between Easter and the core range of specials needs some work though. It's a bit of a mess here, but shelving is more effective to trade specials and premium lines.
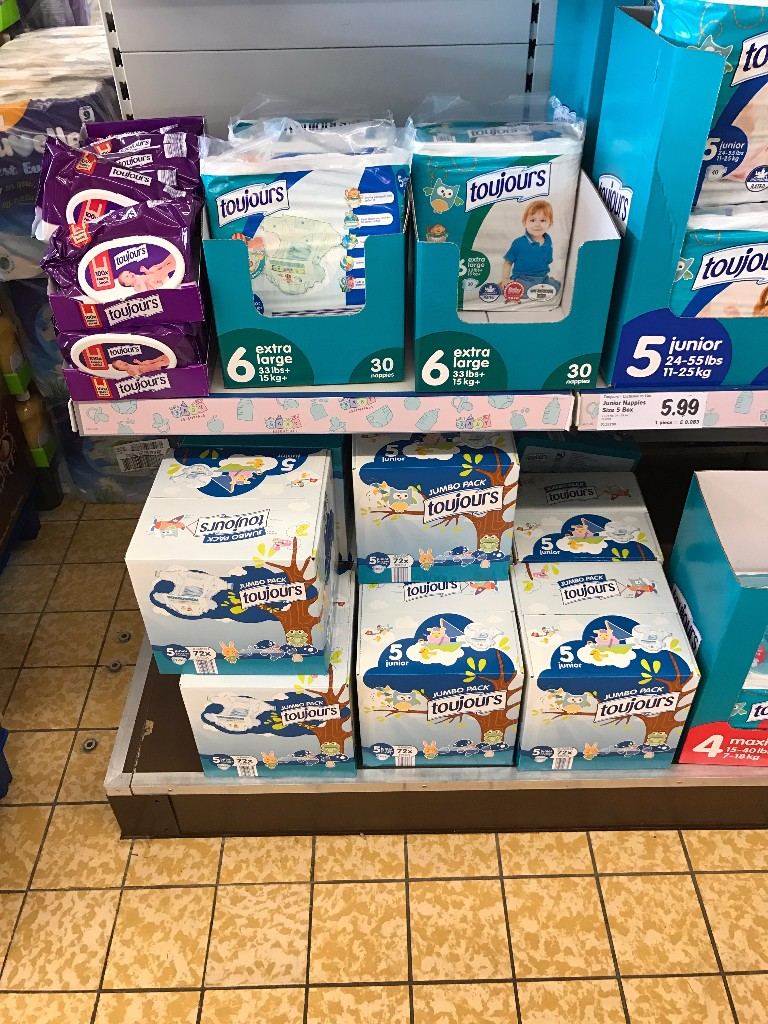
Boxed Nappies have also been introduced to their range, very popular in Aldi when they used to range them for special events, then they were ranged permanently.
Lidl have added a larger pack to their range too, but their Lidl'uns baby range has been slow to launch, it's still landing in store but seems a slow burner. Change in strategy perhaps?
Certainly losing out here to Aldi who have steadily expanded their range and recently, as we saw on the newsletter service - added Baby Milk (own label) to the range.
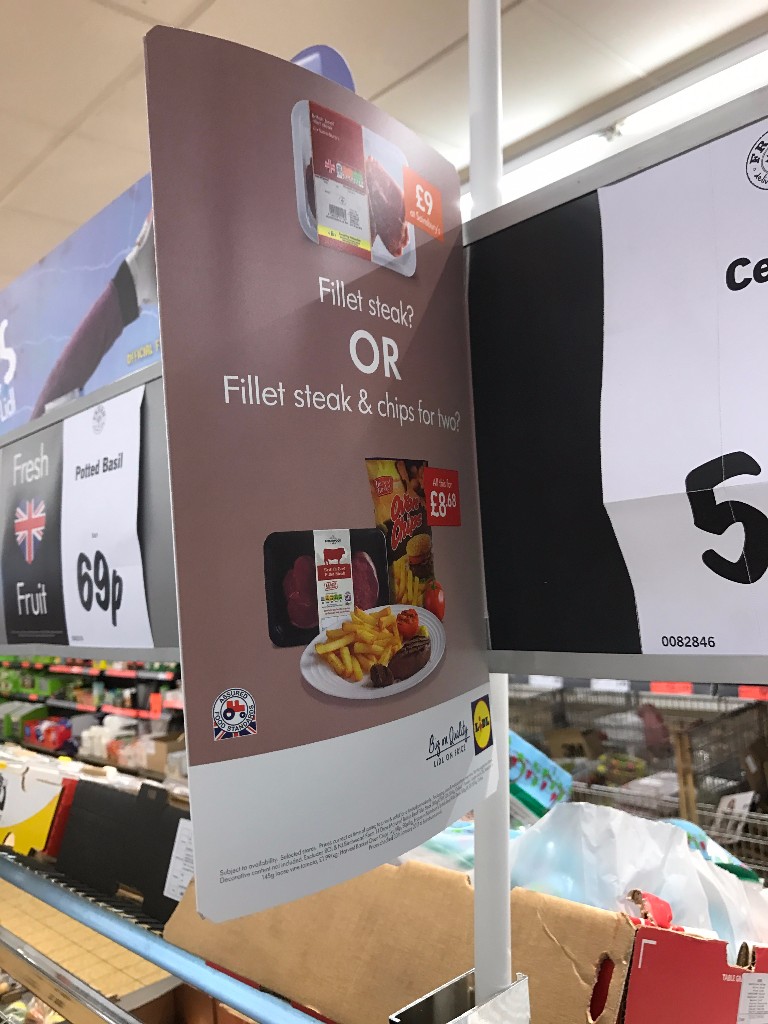
The Lidl price campaign of their meal versus one line in a competitor continues, every major multiple has had a product cherry picked and then a meal at Lidl that's 4/5p cheaper for the full meal.
Powerful message; although a bit disingenuous perhaps. Nappies at £8 in Morrisons (3 for £15) but Lidl had 2 packs of Nappies and 2 packs of Wipes for £7.98.
It becomes the whole brand vs. own label argument once again.....
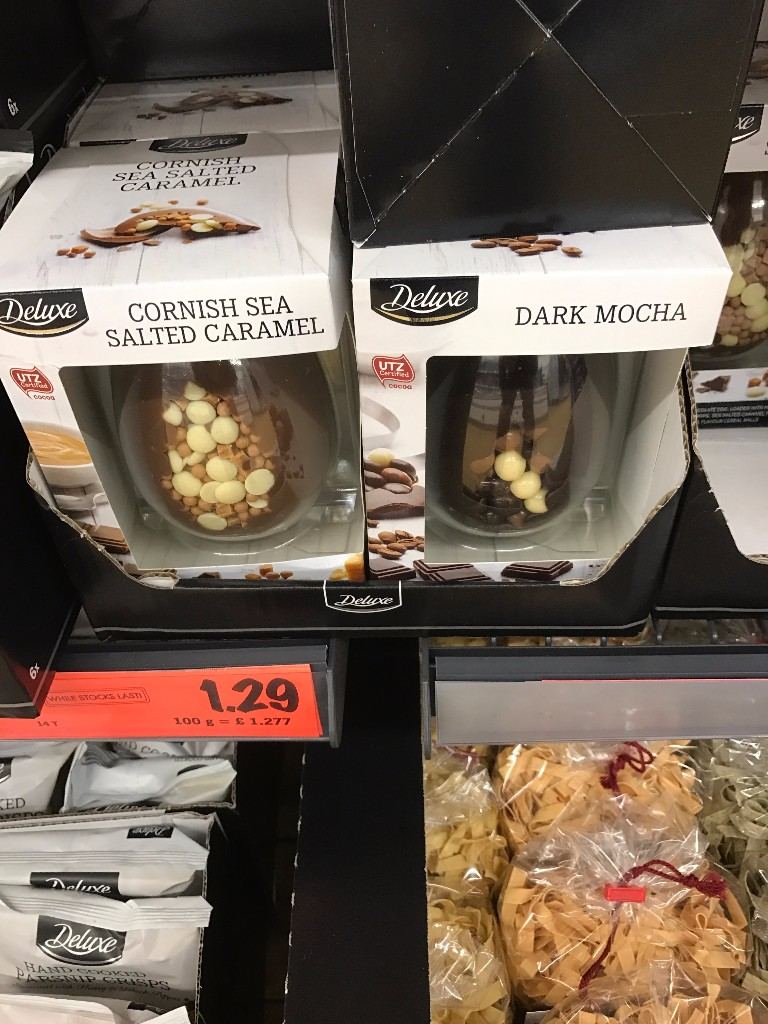
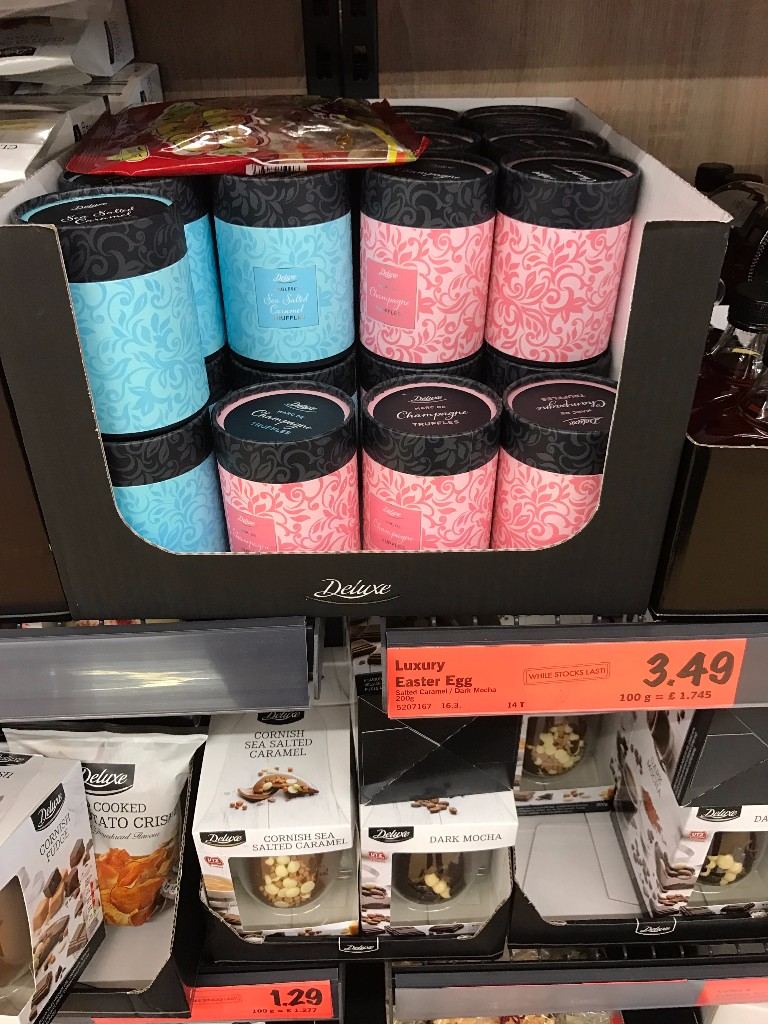
Their Easter range looks strong though; the premium Deluxe range is smart but wasn't so good at Christmas. The range looked a bit stale and was poor versus Aldi and their wider party food range under their premium range.
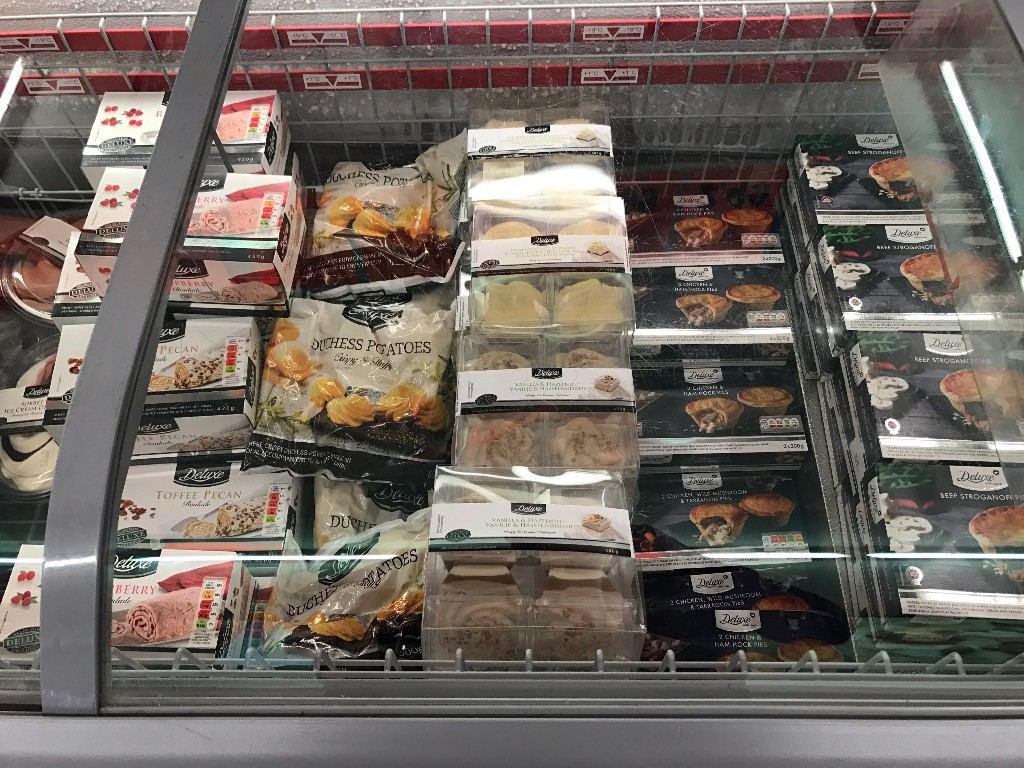
Frozen continues to look strong within the premium tier; lower risk of course as the shelf life is longer, but nevertheless. Packaging looks good and the range is often fairly strong - lots of focus in Desserts and meals like Pies.
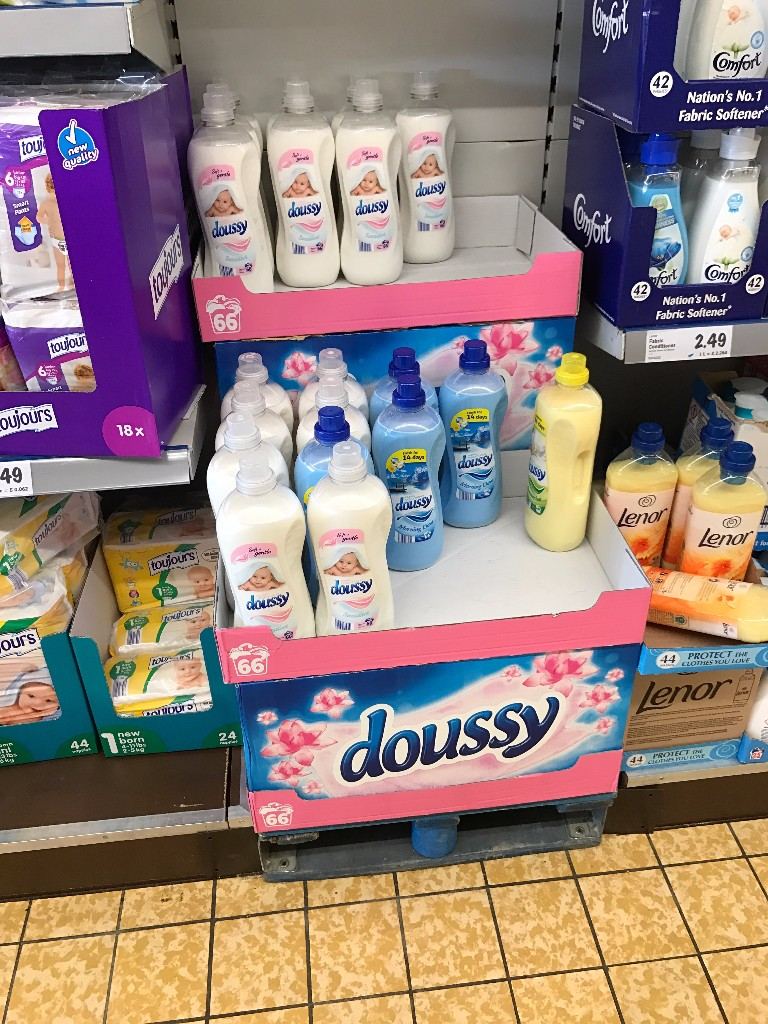
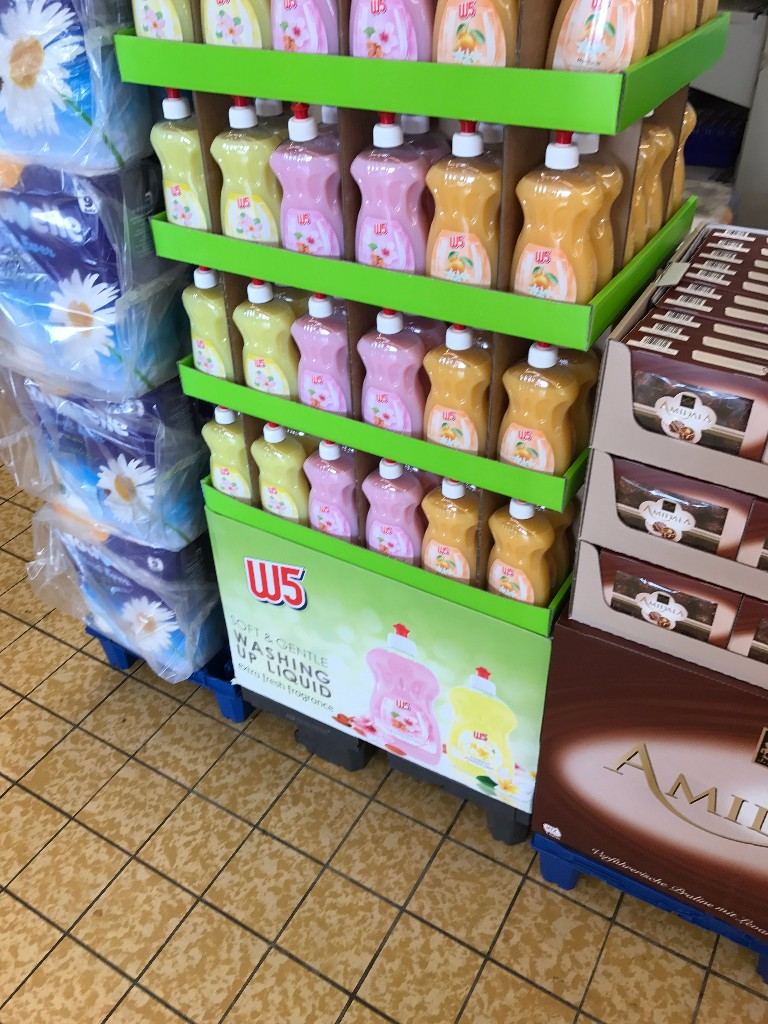
Lidl are good at building their brands too; Doussy is their own label fabric conditioner and branded with the shelf ready trays showing the logo until that layer is opened for sale. W5 washing up liquid was also branded in the same way a leading brand would be.
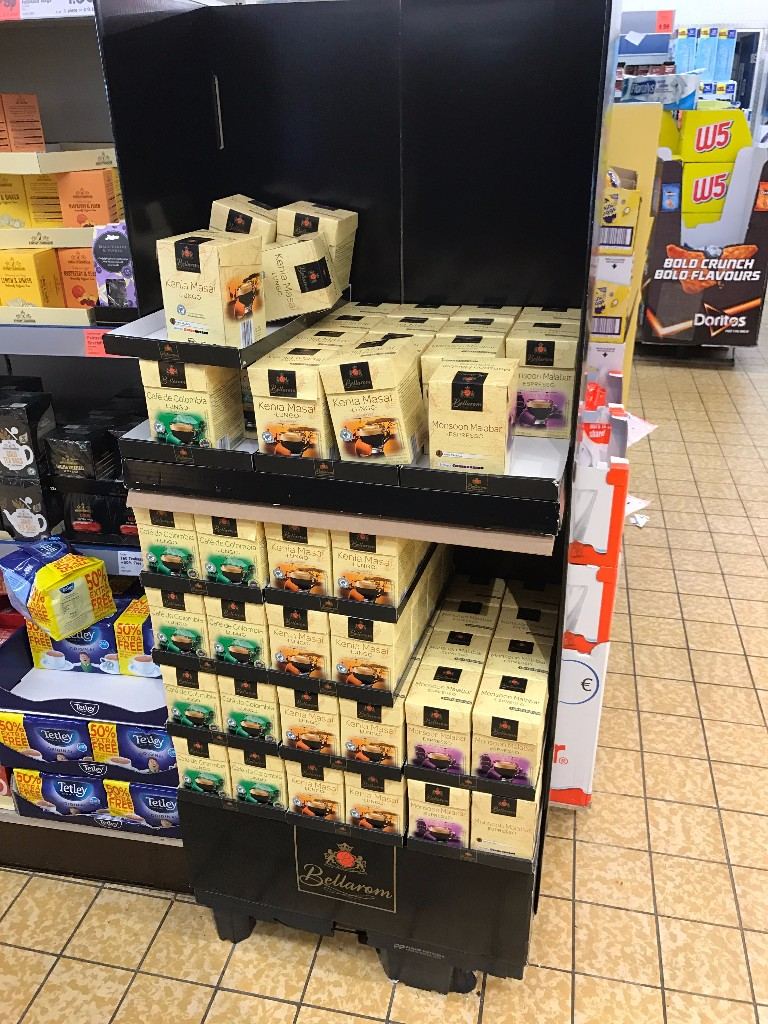
Similarly they also use shippers around the store for their own label lines in Coffee and Cosmetics. Bellarom is their own label Coffee and a shipper was seen with the Nespresso equivalent capsules - another interesting range extension.
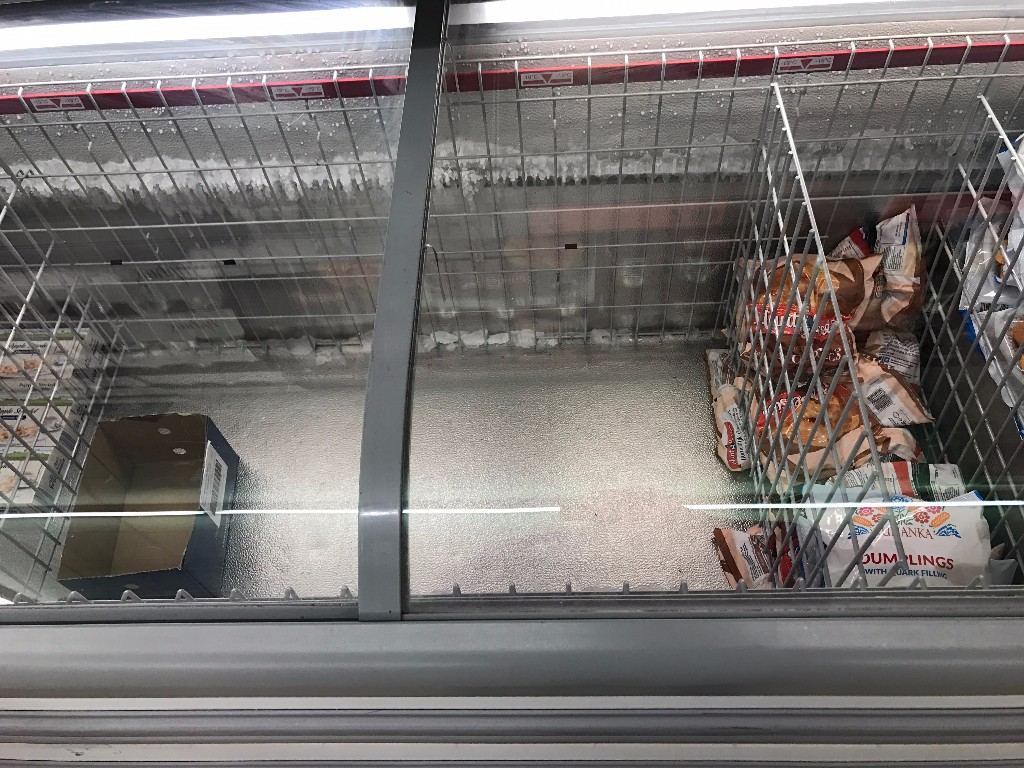
As for standards... Have seen them go backwards with general levels of fill and presentation. Frozen was hard hit here, barely any stock on sale and ultimately disappointing for the customers.
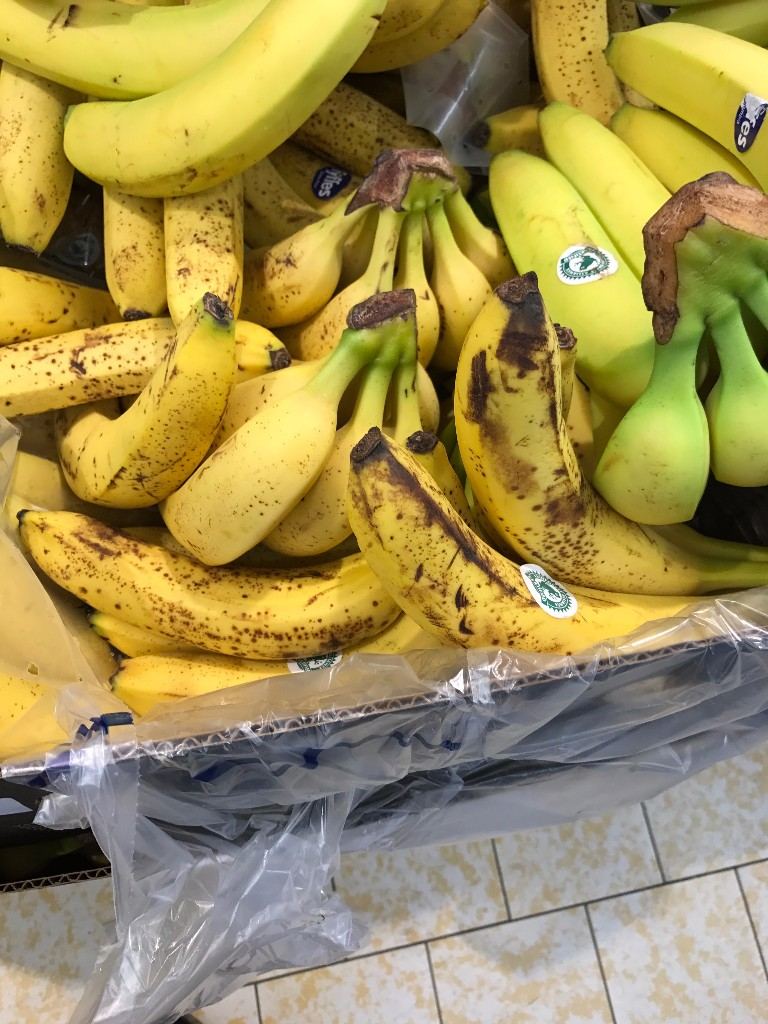
Questionable quality too.....
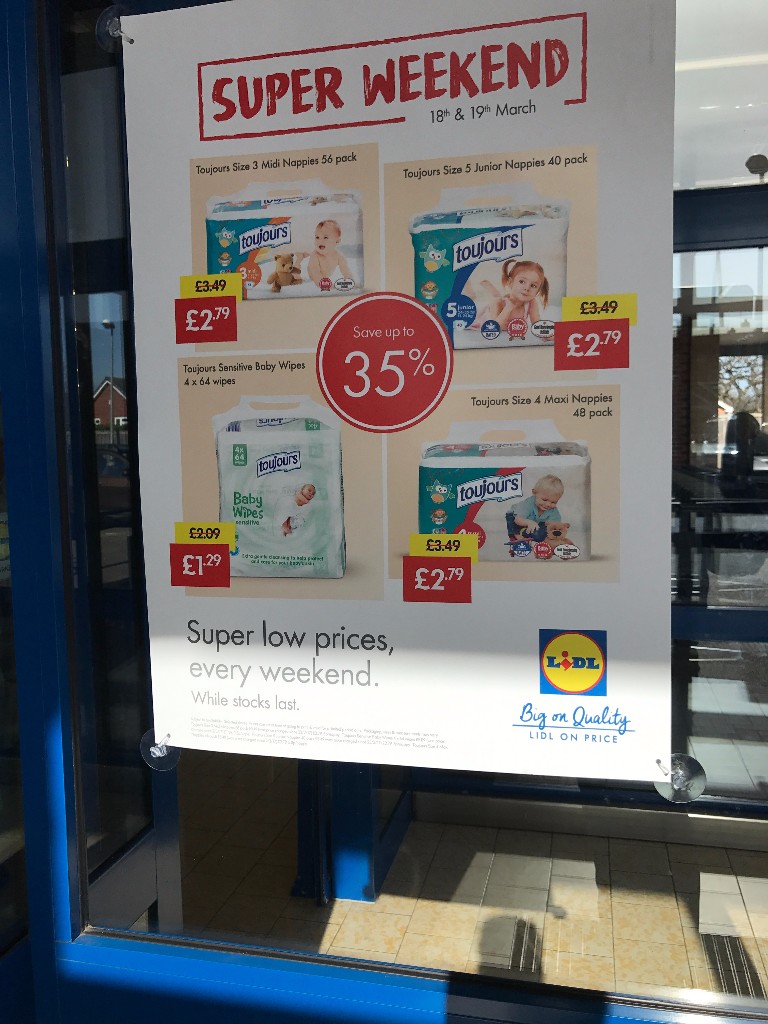
There have been a few subtle changes with the new guard at Lidl, I haven't yet seen any press with the new boss and their general PR tales have been relatively thin on the ground.
Their marketing remains sharp and they've unified behind the 'Big on quality, Lidl on price' message alongside the adverts using tweets and Facebook comments as a basis to bust myths about the chain.
The re-introduction of super weekend deals has been notable, this is what they used to do in the old days of course... Put a few deals on selected lines over a weekend to drive traffic, they've gone back to this and have featured various products recently.
Nappies were featured here; with 35% off the range over Saturday and Sunday. Valuable footfall driver but is it necessary?
It strikes me as something to do when footfall is flagging, yet Kantar looked positive for them recently. They continue to progress in the market but they should be careful of allowing standards to fall backwards too much.
They've brought customers up on good quality products, low prices and an excellent marketing campaign. Not to mention that stores are their cornerstone, well merchandised, attractive stores with minimal queues (or at least, every checkout open).
However to let standards drift too much would be unwise, customers are spoilt for choice. Major retailers are cheaper and Aldi are nearby in many cases now as discounters start to open up near each other to get more sites down.
Yes it's better for the profitability if labour is reduced, however it does drive perception downwards around quality if the shop is a disaster. With all profits presumably heading towards the US venture, they cannot afford to take their eye off the ball in the UK.
More on the US adventure soon; with a relatively detailed report due out from Grocery Insight to detail what to expect from discount and how their offer has evolved. It won't feature much talk around forecasting market share and other vague irrelevance. It'll be about the shops, and what their entry to the market will mean for the US retailers at large.
From the Grocery Insight newsletter archive, first sent to subscribers on 29 March 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.