Lidl - Ongoing banality
19 May 2017
Lidl continue to confuse me when visiting stores, they don't quite feel as busy as they once did in the local areas and perhaps that's a sign of Aldi recovering their position, but also perhaps self inflicted woe by Lidl.
Where Lidl were excellent in the past was centred heavily on marketing and stores; their Lidl Surprises campaign was brilliant, featuring tweets resulting in mock surprise of how good something was from Lidl worked ever so well. Signage was good and customers flocked to the stores.
The marketing was well timed as they were just starting to come to prominence in the wider market, sharper tactics helped them generate a positive perception by customers. Their stores were often a bit Soviet Union in the 70's to say the least.
The addition of an in store Bakery in numerous stores helped dial the quality perception up and encouraged more customers in to the wider ranges.
However the departure of Ronny Gottschlich as CEO last year was a surprise to many given that he had presided over a period of real growth for the chain, seeing them move in to high street London format stores. These appeared infinitely more successful than the Aldi Kilburn High Road trial) but has that roll out paused?
There is little doubt that the economics of discount are finely balanced and any changes to the model means that things change considerably. A high street location, especially in Greater London may make sense from a footfall viewpoint, however it does impact the numbers.
The basket size is lower impacting the checkout operation and delivery times are then restricted too which impacts availability and subsequent costs to operate. Higher rents too of course in these initially attractive locations.
"Lidl of the future" was a major success as a store format and continues to be rolled out, both with refitted stores, rebuilds and new openings. The stores look efficient, retaining plenty of bulk stacks and wide aisles, Bakeries are popular but staff are needed to fill the ovens and the shelves.... Plus a bigger floorspace means more special buy baskets to fill and more checkouts to potentially operate.
Either way, Lidl decided to make the change and a German CEO came in, he looks young and is clearly going to run the business within the core guidelines set down by the German HQ.
This means that more profit is generated by sticking to the core and this can be diverted (presumably) to the fledgling US operation that will require lots of capital and people.
The Lidl US operation and potential challenges for the chain is being considered by Grocery Insight, and a full overview will be available very soon. I will share on this service once it's completed.
Their first stores go live soon (15th June) so it will be interesting to see how it all comes together.
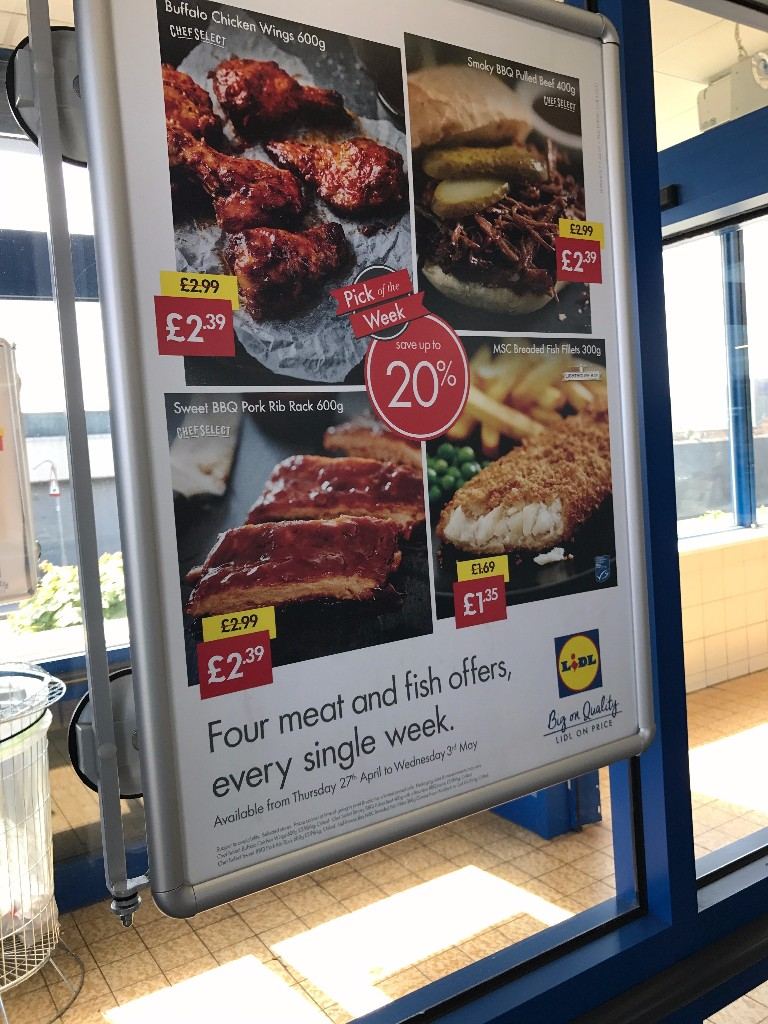
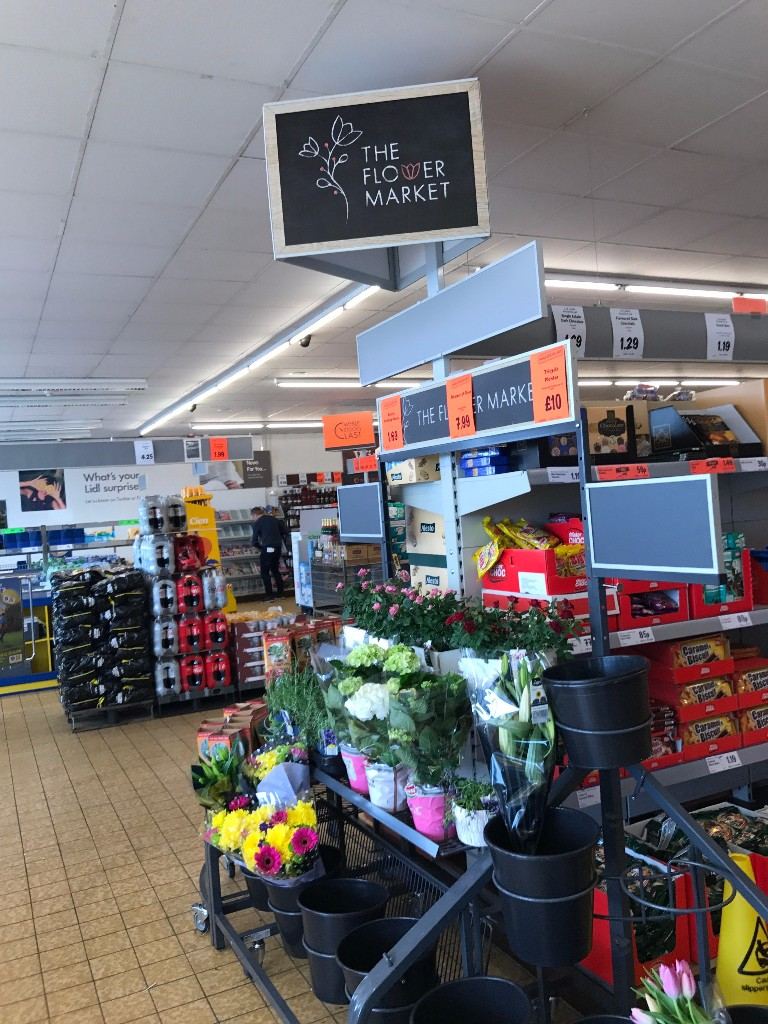
For the UK business, they're adopting the Aldi Super 6 deals with 4 deals of their own inside Produce and 4 inside Meat too, the strength of these deals does vary though.
Their Meat one offers 20% off at the minute which barely seems worth bothering with, Produce can be stronger though with a good range of produce generally featured.
Their flower range was talked about excitedly by customers as Lidl came in to the mainstream, but even this range has been dampened down in recent months. A functional range, if nothing else but one would feel that Floral is a good place to set the quality and price barriers high and low respectively.
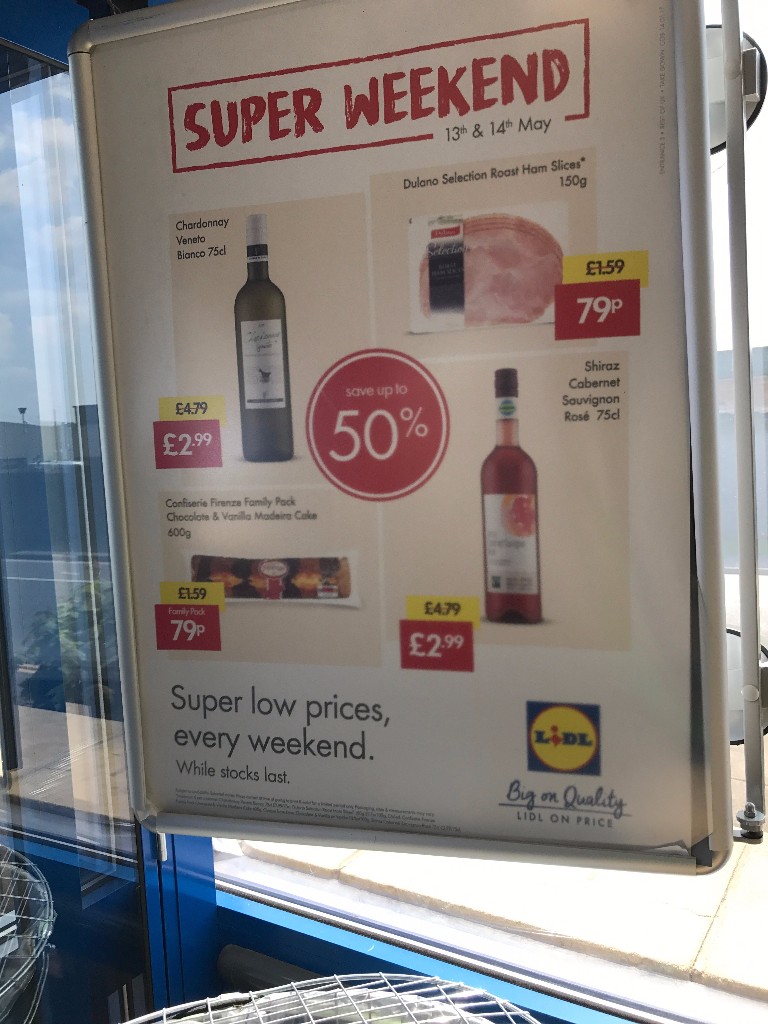
One notable difference with Lidl under the new regime is the re-introduction of Super weekend deals, used to drive footfall at peak times - presumably when customers may visit other retailers...
These offer decent price cuts on various lines, usually built around a theme, 35% off Nappies not so long back and these are effective promotions to disrupt things.
However with the business that Ronny left behind in relatively good shape, is there still a need to do such stunt based deals? Given the strong footfall and sales growth?
If anything, you could argue it could upset the core customers who find Nappies blown out by sales at midday as the bargain hunters flocked in early on for the 35% off deals.
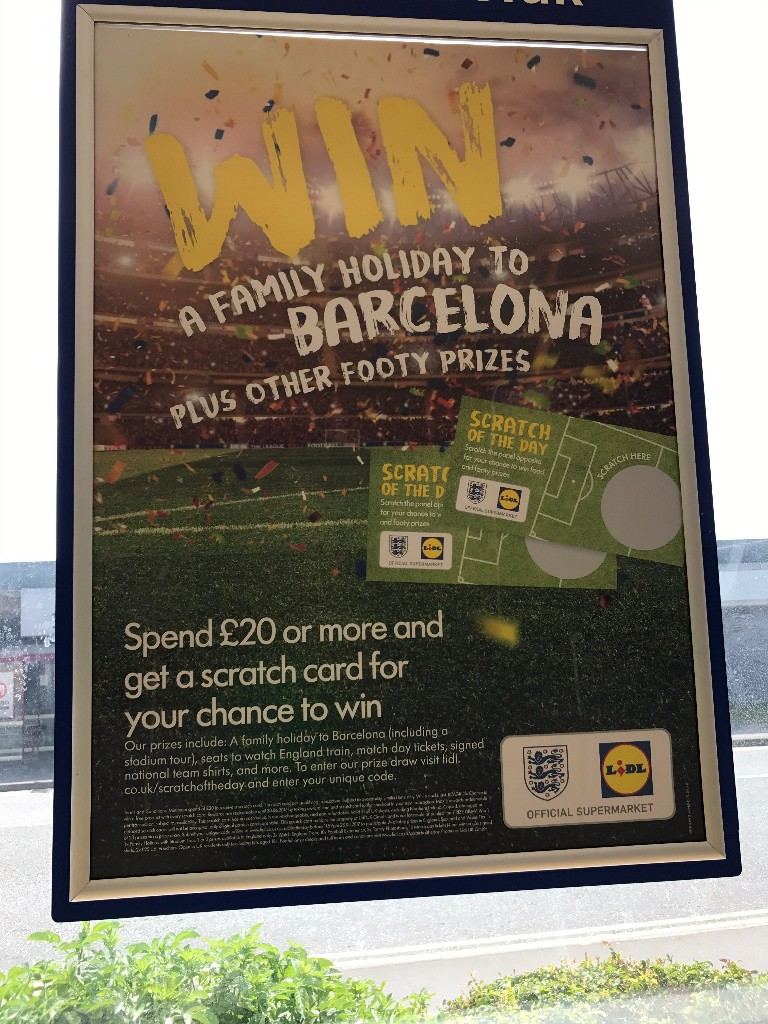
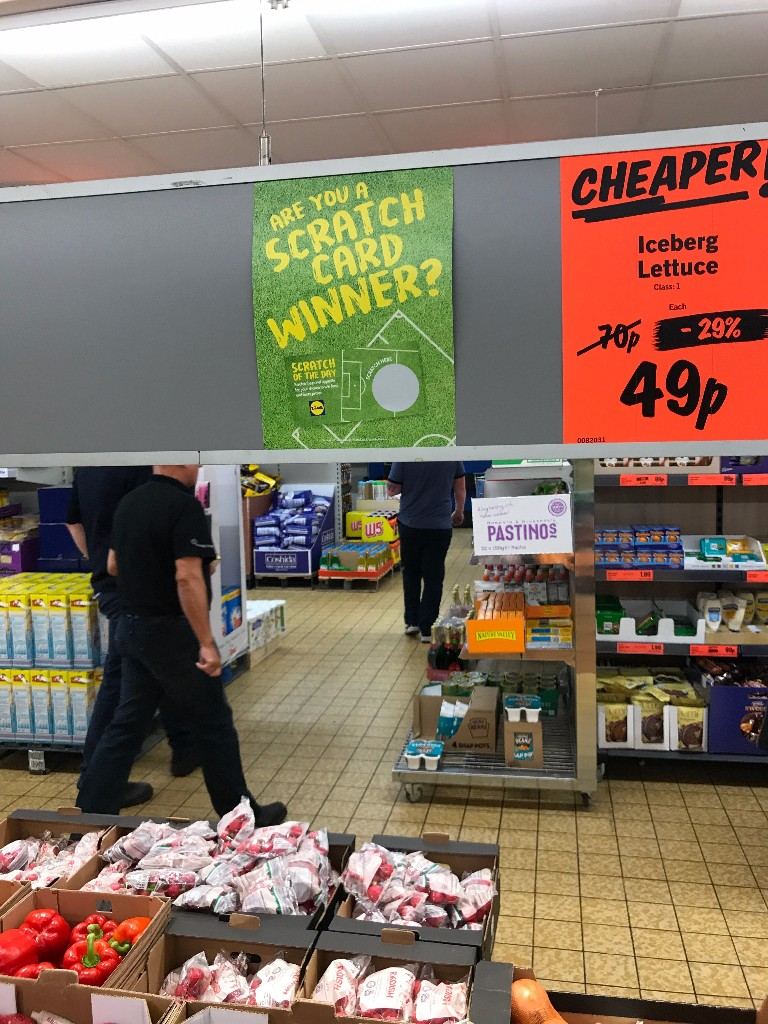
Lidl currently have this slightly baffling promotion running at the minute which rewards customers for spending over £20 by giving a scratchcard which is themed around football, given the links between the FA and Lidl. Prizes vary, it's unclear what they are.
The signage is strange though; the explanatory poster is sited at checkouts, after you have completed your shopping. Hard Cheese if you've only spent £19......
I saw virtually no signage around the store for the promotion, what it meant or how to qualify. There was a small bit of exposure in Produce and Fresh but nothing comprehensive, it all seemed so half baked and confusing.
This signage in Produce meant little as there was no trigger spend information, or indeed any wider details. Where are the scratchcards? Are they hidden around the store?
This was the opportunity to flag the £20 spend, which would encourage customers to drive their spending up to the level and give a purpose to the deal.
(Interesting note on the Lettuce price featured above, Lidl flag this as a was 70p, however the market has gone back to 50p as British Produce swings back in to season).
With Lidl growing well (with/without new space) but in store it's starting to feel like Aldi are edging away once more. Promotions like Scratchcards and their weekend deals coming back feel like an attempt to boost their sales line.
All very well, but does it point to a bit of a slump in sales over the short term? Certainly their standards aren't quite as strong, are customers happy with the low prices and good quality enough to tolerate a poor store experience and queues at the checkout?
Unclear, but customers who are 'newer' to Lidl will have only ever known good times, great stores, staff on duty and queues... But checkouts open to deal with the backlog.
Based upon visits now, the opposite is true, shelves are emptier, the store shows signs of being 'shopped' and queues are certainly more commonplace.
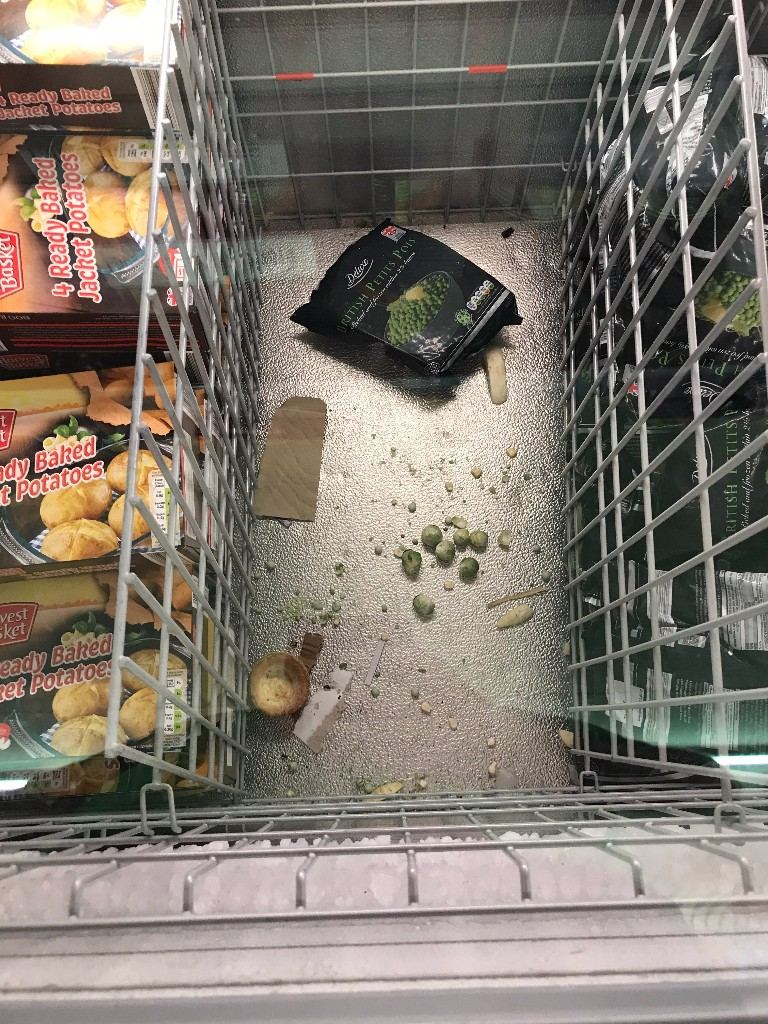
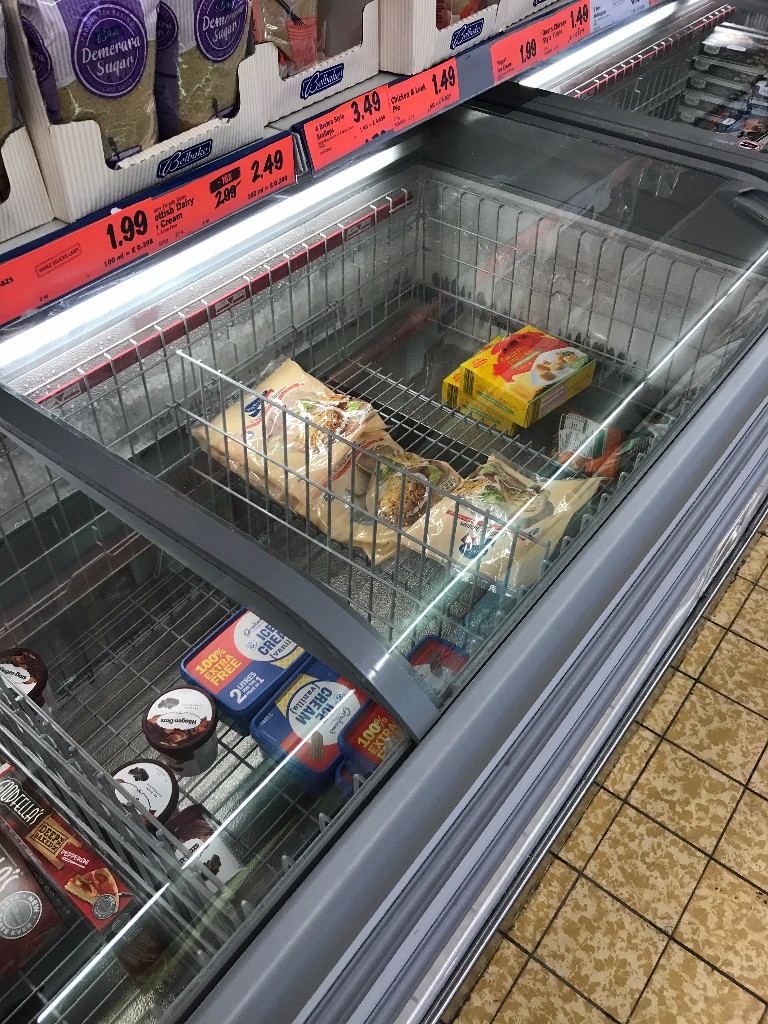
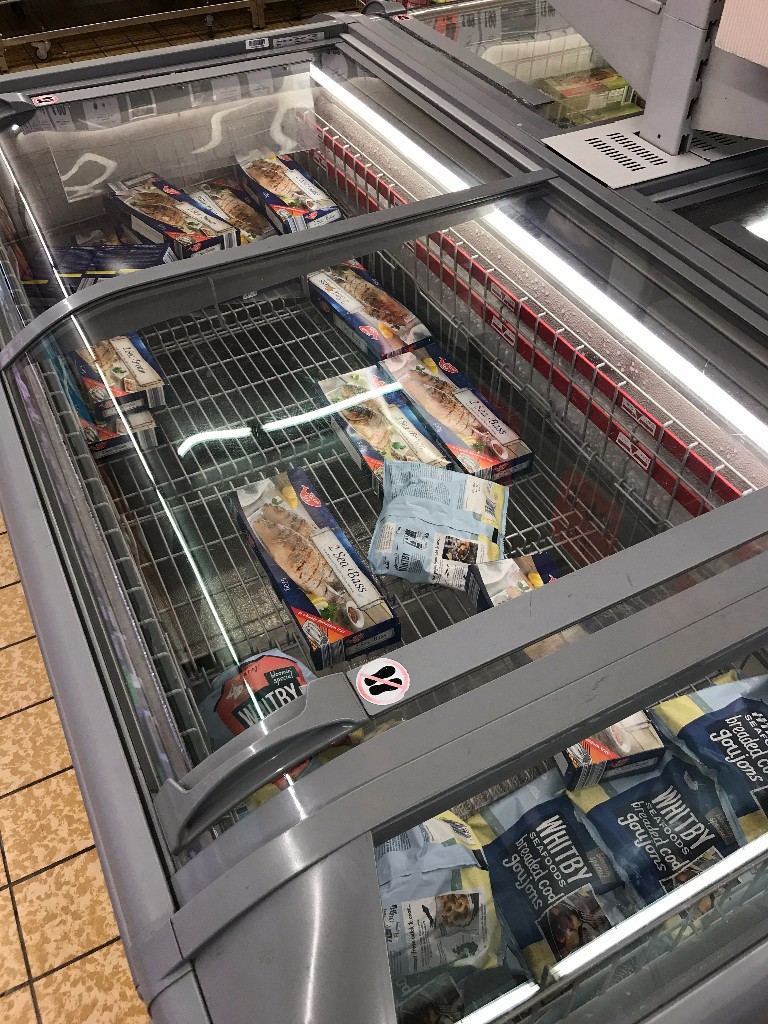
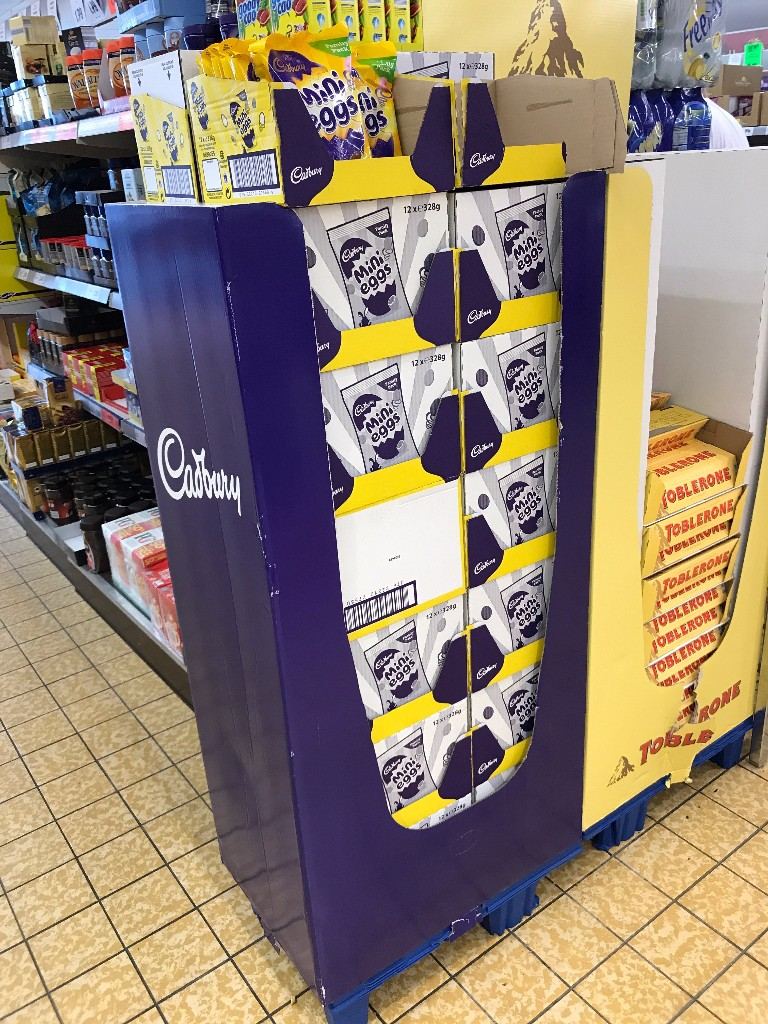
Poor old Frozen is often hard hit, a poor level of fill and debris on the units too. Mini Eggs (full shipper) to be still on sale 3 weeks post Easter was a surprise.
What made the frozen section in Lidl worse was the fact that Iceland were located next door. Just giving sales away and they're resurgent too - Iceland are in great shape.
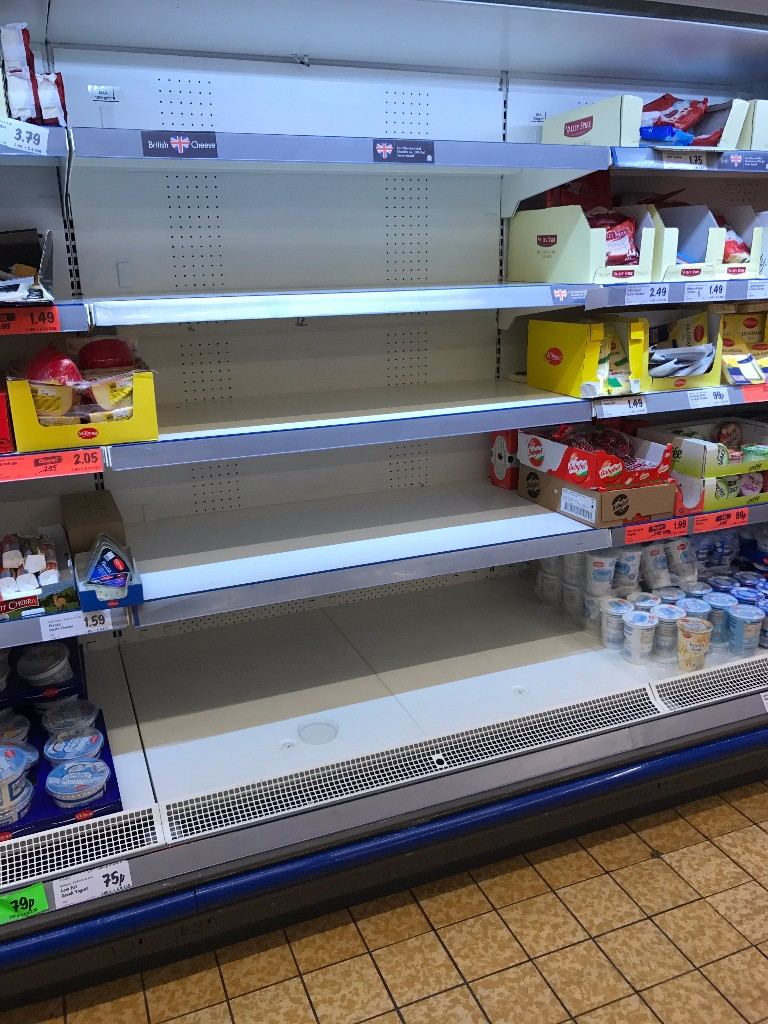
No idea. Cabinet breakdown?
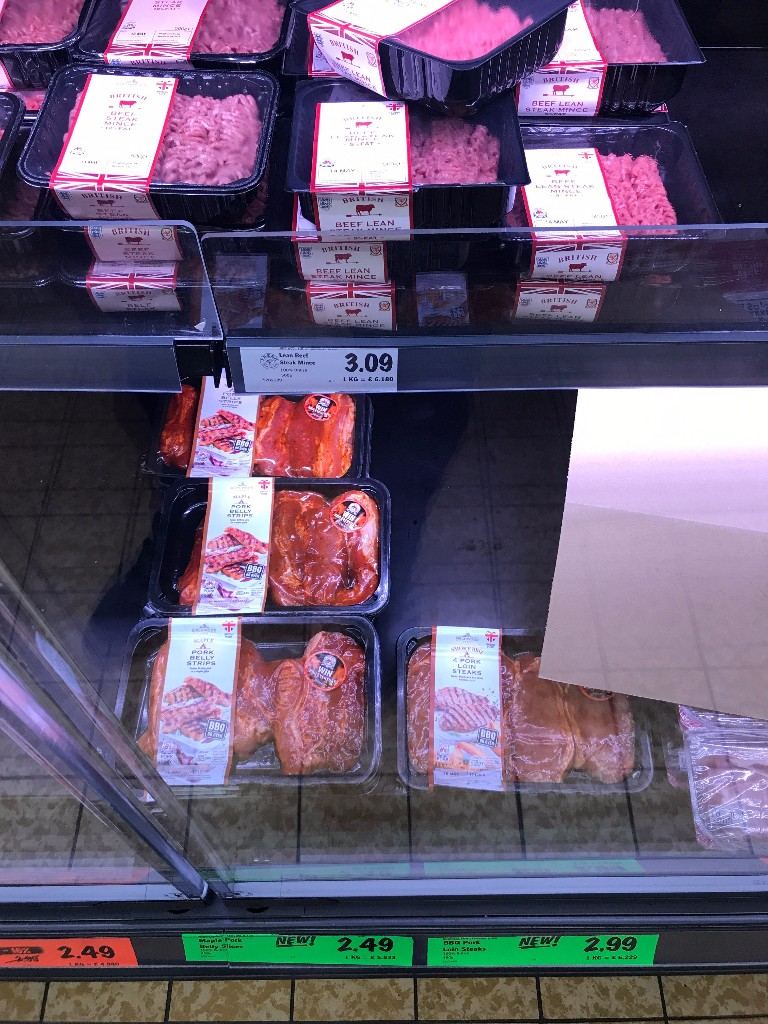
Some decent BBQ lines have been added for the range switch ahead of Summer. Again though, they feel behind Aldi in this regard, which is not something I'd have said last year.
Continues to feel a bit of a mixed bag for Lidl, trying to go back to tried and tested methods (weekend deals) which customers don't mind... They never mind a lower price....
But it feels that they don't need to do that, and should instead focus on the core shopping experience and in particular, filling the shelves. If anything, those stunt deals will disrupt the core customer and their shopping trip.
The scratchcard deal could well be a former management commitment that Lidl are fulfilling, but the change in leadership was some time ago... It doesn't feel like it's been executed with any real vigour.
The focus for Lidl is now on the US, that is clear given their commitment on expansion and the costs sunk in to developing the business there. The UK will have to contribute as a result, but if that results in standards going backwards in stores....
How long will customers be happy with low prices and quality product if the store experience remains behind the curve?
They may decide they can get the same elsewhere but for slightly more money? But be happy with that trade off as time remains vitally important, and customers don't like queuing.....
From the Grocery Insight newsletter archive, first sent to subscribers on 19 May 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.