Big suppliers - need to do more?
28 June 2017
In the new world in food, 2017 AD (after discount) is the year and the market is in a strange place.
The large retailers have adjusted their model largely and whilst not perfect, are certainly leaner than they were, helping to combat discount and their low price, high quality and British mix.
However Brexit comes along and throws a spanner in the works, the effects haven't been felt initially but as hedging now reflects the lower valuation of sterling and prices start to rise across the board.... The playing field is tilted again and the customer is thinking about price first and foremost.
This is due to inflation of course, alongside it being holiday season and shifts meaning the customer is looking to save money. The media tales of inflation and the very reality of that at the shelf edge too don't help. This is why the last couple of Kantar reports have seen discounters rising rapidly and putting on their best growth for some 4 years in May.
It's not that the big four have become poorer value overnight, rather that discount is the safe outpost for customers who want to save money and/or concerned about the future.
It is holiday season too let's not forget; the kids break up soon and that brings with it 6 weeks of expense in terms of days out, food shopping and activities. Customers could be switching their shopping now to save for an expensive August particularly.
In addition, with the DFS warning last week, it shows that Brexit and the associated woe (read, total waste of time) is starting to impact customer behaviour and that means good news for the discounters(?)
The generation of customers are conditioned towards discounters when they need to save money, indeed if they ever moved away from discount as times improved... Some must have done given the improvement in like for likes at Morrisons and Tesco....
However in the midst of all the to-ing and fro-ing around discount, big stores and own label focus... What about the branded suppliers?
They're in the middle of the epicentre of the storm arguably and are fighting on 2/3 fronts, which are a direct consequence of each other.
1) Discounters have volume growth and are rapidly growing, yet as we know, they stock very few brands.
2) In response to discounter growth, larger retailers are reducing ranges and in many cases, putting branded lines under pressure.
3) Not just that, but supermarket own label is becoming a key weapon in the fightback versus discounters. We have seen evidence from Tesco around prime placement on shelf and lower prices too for their own brand products.
Not easy for leading brands in this climate at all. The one growth engine in the sector don't really want brands involved over the long term, unless they're a 'stable' brand - IE Marmite. Even then. there'll be no category input etc, they're included for the customer and don't play a strategic role.
Some brands feature in discounters without being stocked directly, with their branding and price point used by discounters on their own products. Piggy backing with their familiar design but charging significantly less than the leading brand.
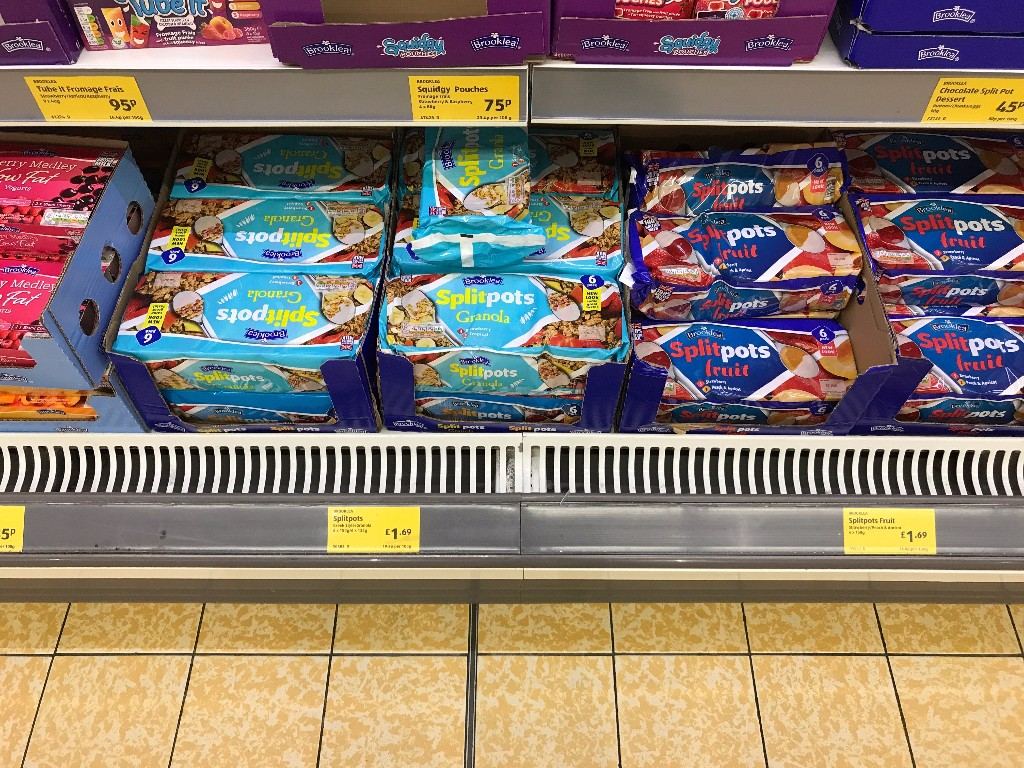
Muller? Nope, these are the Aldi own label equivalents of course. Significantly cheaper than Muller (c. £3.50 / 2 for £5) with these a mere £1.69.
A demonstrable pricing gap which immediately brings the cost of shopping down for the customer.
Where it took retailers far too long to react to discounters, before eventually putting a price lock / price down campaign together... It has taken leading suppliers even longer, some suppliers of course may produce the lines for discounters which is a consideration...
But why did it take P&G so long to react to Mamia Nappies? Pampers were being compared to Mamia for years, not in a good way(!) before Pampers reacted with better pack sizes and also flagged that Pampers were out performing Mamia nappies in their own blind tests.
But why wait so long? Discounters have levelled the playing field and actively made consumers think that the Aldi own label is of equivalence to the household brands.
It may well be, the benchmarking, branding etc - but the reality is that the Aldi 'brands' are still own label - they're developed, owned and sold by Aldi.
Therefore brands should be far more protective over what they have, and seek to protect their own business in the first instance by considering their own action plan versus the discounters.
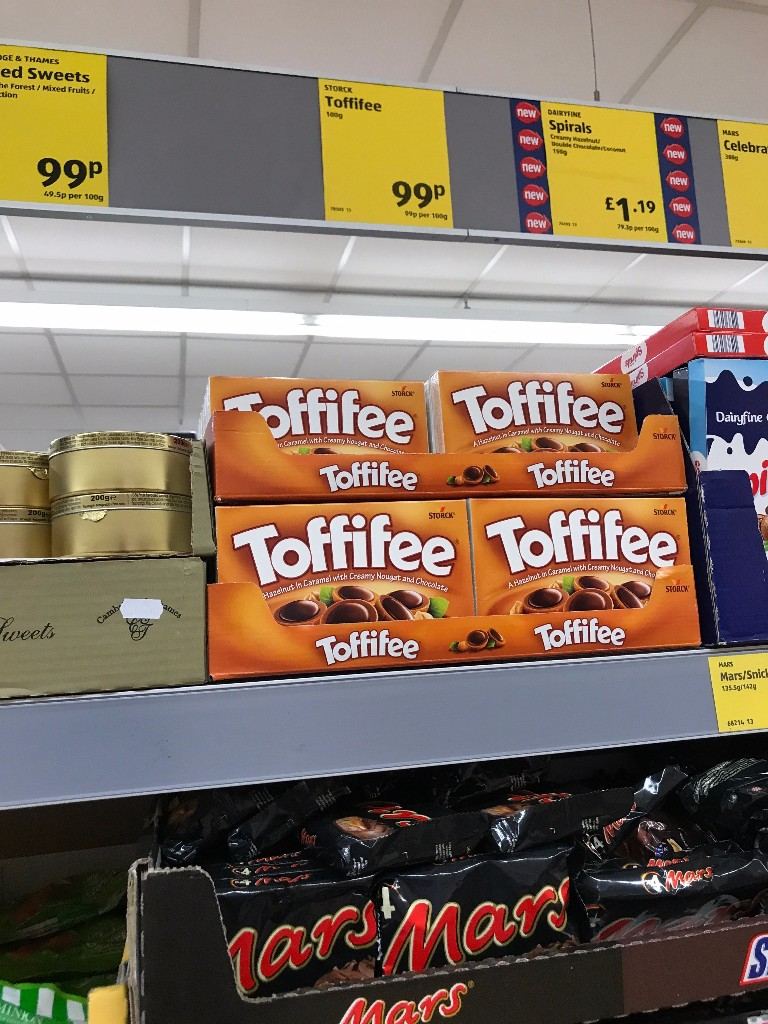
We know that discounters don't range lots of brands, they were on the rise in some categories, but appear to have receded a little. The Mars Bars just in shot feature a smaller bar than the core multipack, however the price is lower and that's sometimes enough for customers..
Too many brands in the discounters can clutter things and make it unclear for customers, at best it switches sales from own label to brands (which customers can buy anywhere), at worst it becomes confusing and clutters their value proposition.
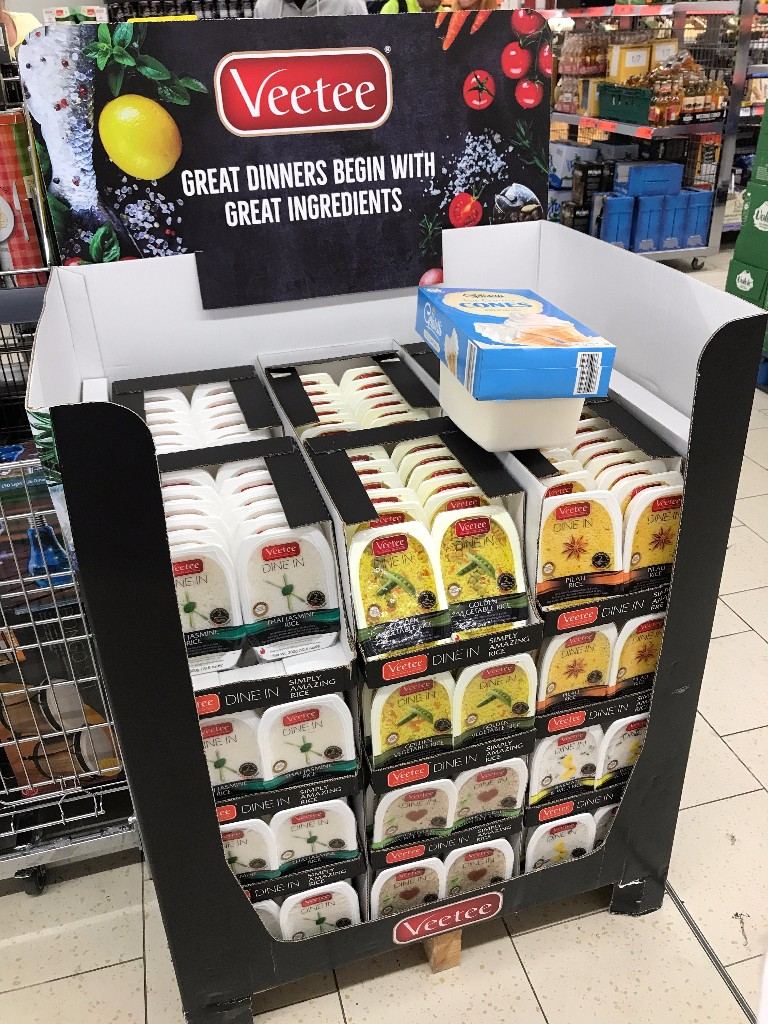
Or worse, the brand ends up confusing their own position. Veetee rice drops in and out of Aldi in any case so this is perhaps understandable given the shipper in Lidl.
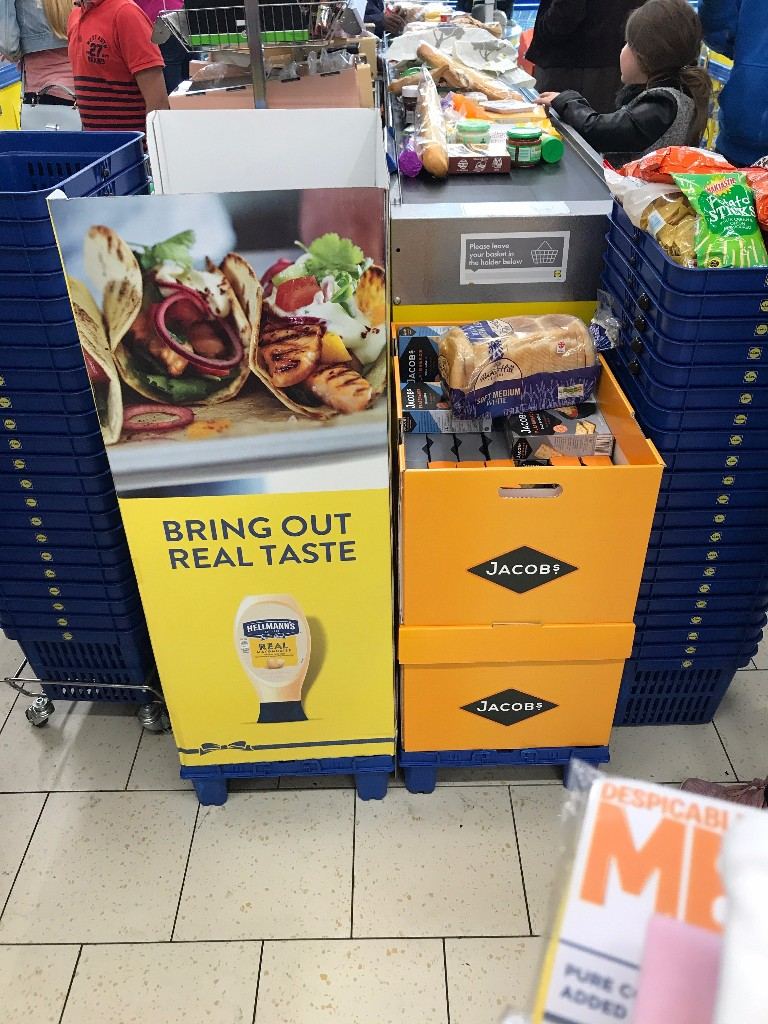
However Lidl have recently displayed numerous branded shippers at the checkouts which, again I understand for Summer and trying to drive sales.
But for the brands, they can undercut themselves by going in at a low price, on branded shippers in order to try get some of the volume...
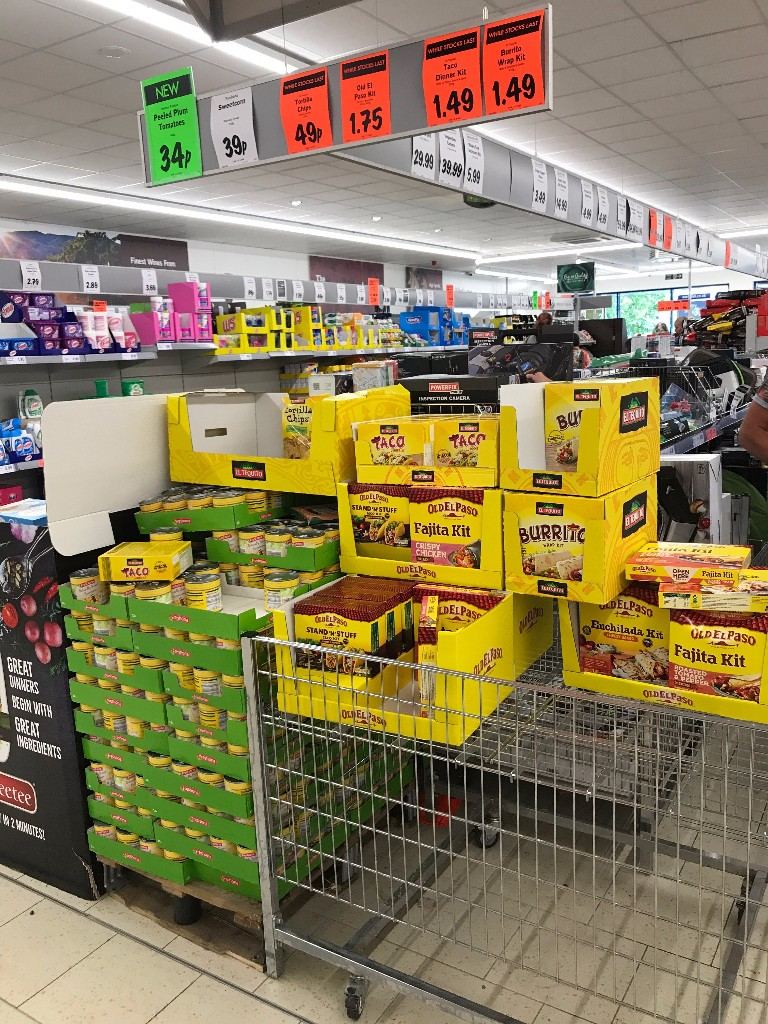
Old El Paso often have deals on around the marketplace, with £2 price points currently around in Morrisons alongside the other retailers too.
However they recently dropped a range of their lines in to every Aldi store as part of the Specials - Mexican event. This occupied the aisle/shelving space within the limited buys - which looks more like an extension in the Aldi ranges each month in truth.. Albeit on a limited buy, rotating basis.
Lidl too dropped Old El Paso in on their 'ends' as part of an event or indeed, just part of the weekend specials. Are seeing their stunt deals become more of a part of their armoury, like the older days.
Whereas under Ronny, they were much more about the core trading and putting hours in to the stores....
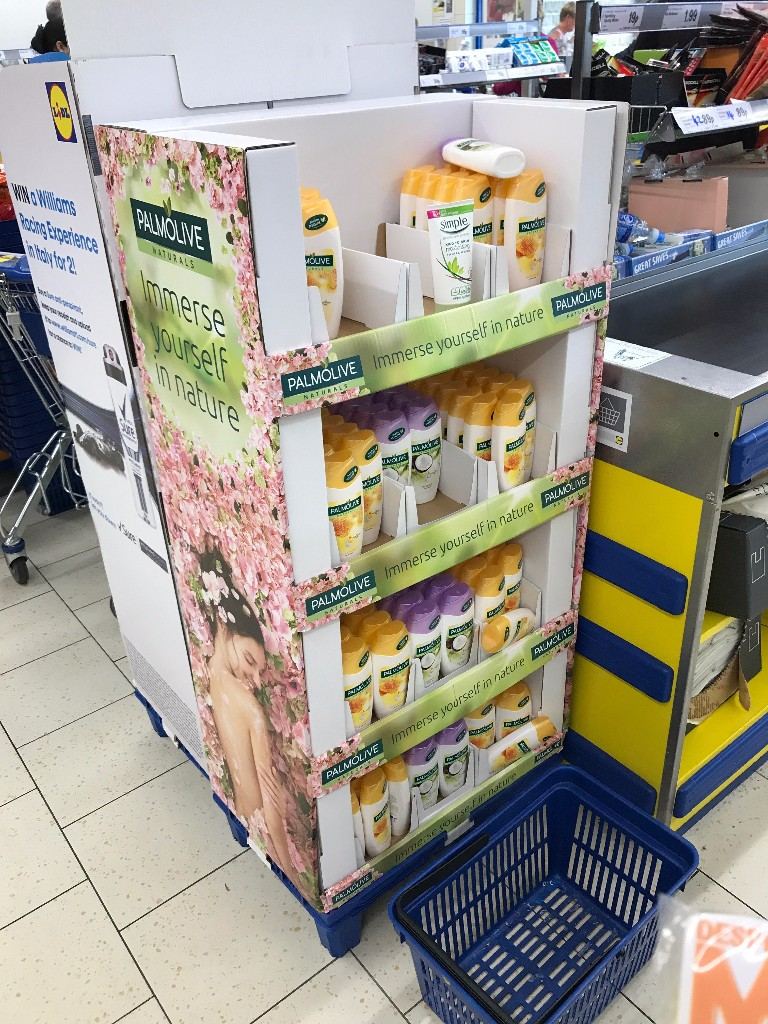
Health/Beauty suppliers are a group who must find the going harder given B&M and Home Bargains heavily featuring in Health/Beauty, we have also seen numerous brands drop in to Aldi and Lidl, sometimes in the fixture which is bizarre in itself.
Years upon years of branding and developing the label with advertising to be an exclusive brand, renowned for haircare or improving hair quality, only to end up being located on a fixture alongside the imitation brand which is much lower in price and virtually looks the same anyway.
Talk about crucifying yourself...
More brands in the mix in Lidl at the weekend, shippers at the checkouts also featured Palmolive...
I do understand leading FMCG folk getting in to the Health/Beauty sector in discount as the growth is there. To an extent you can understand the suppliers trying to grow in discount (indeed some have a team dedicated to it)...
However there needs to be a longer term play, the discounters do like brands being in their mix but I often wonder if they do it to re-emphasise their own price gaps versus said brands, or indeed have a look at B&M / Home Bargains and try to stop the leakage to those retailers on leading brands.
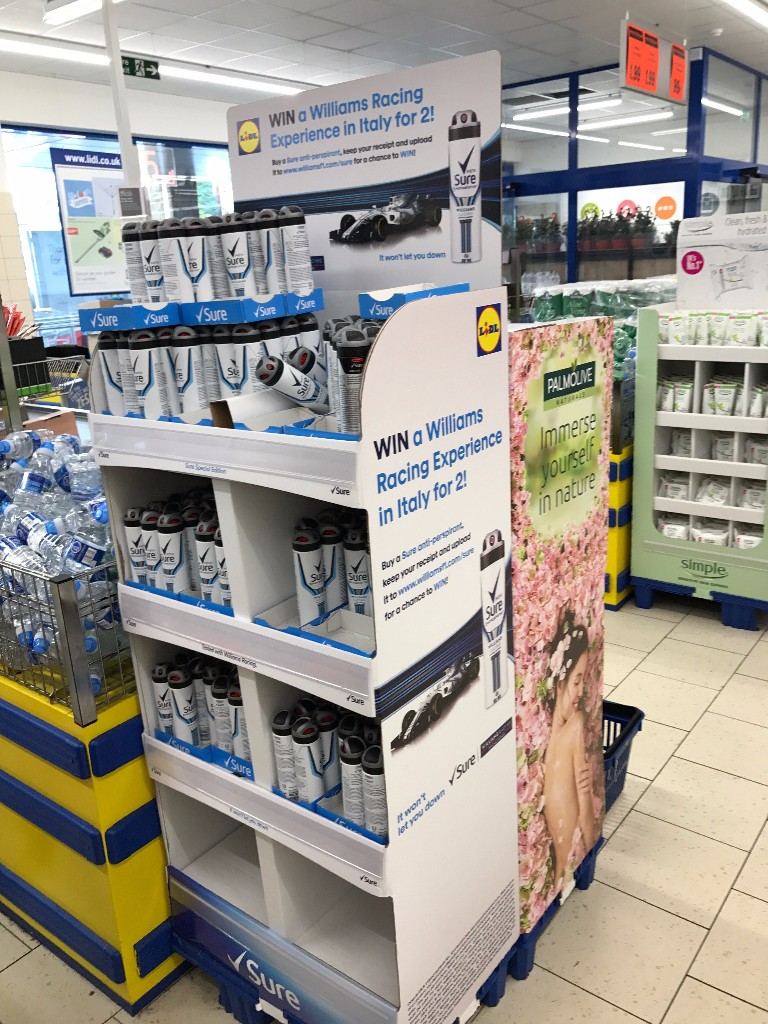
Unilever have certainly had a bit of a go in Lidl, with a branded shipper complete with promotion for the BMW F1 team, again understandable but why would you drive brand loyalty in a discounter? It is curious.
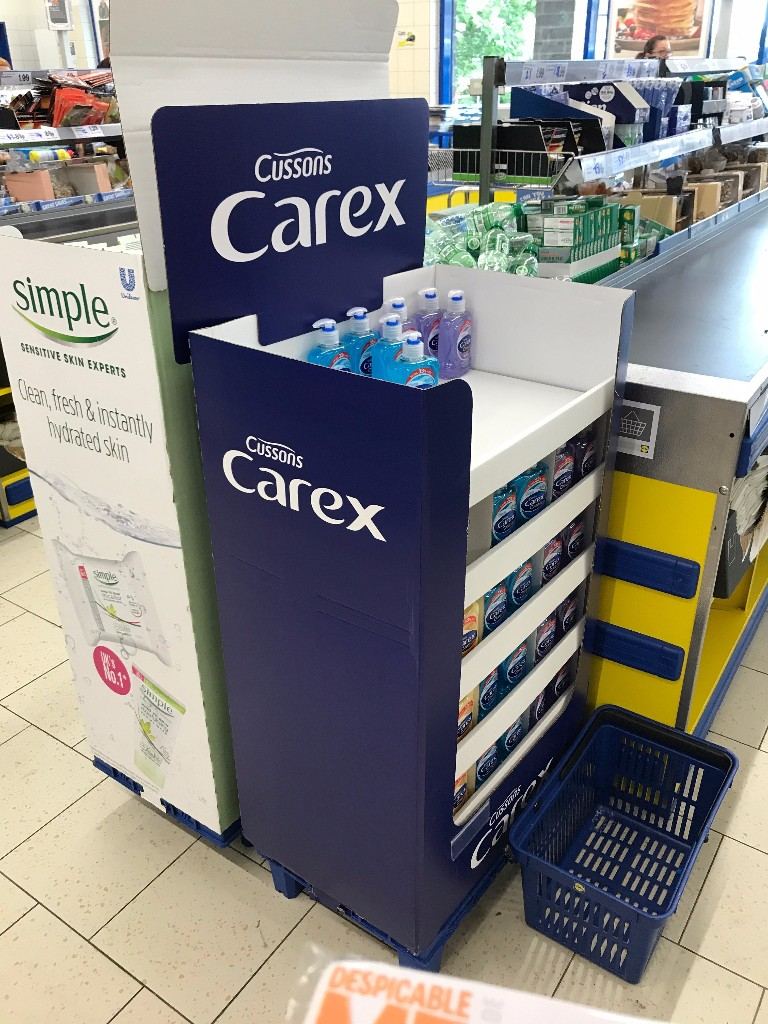
Further evidence of Health/Beauty shippers from Carex and Simple also noted at the checkout area. Ideal for sales as they're high traffic areas and great for pick up lines.
However unless it's a limited special buy basis, it seems odd. Lidl adding these in seems odd too; they're not in core fixture which obviously makes sense, so there'll be no switching necessarily to brands out of own label.
It could say more about the Lidl business, trying to get some sales boosts / becoming more spot line based which obviously works really well for Home Bargains and B&M et al.
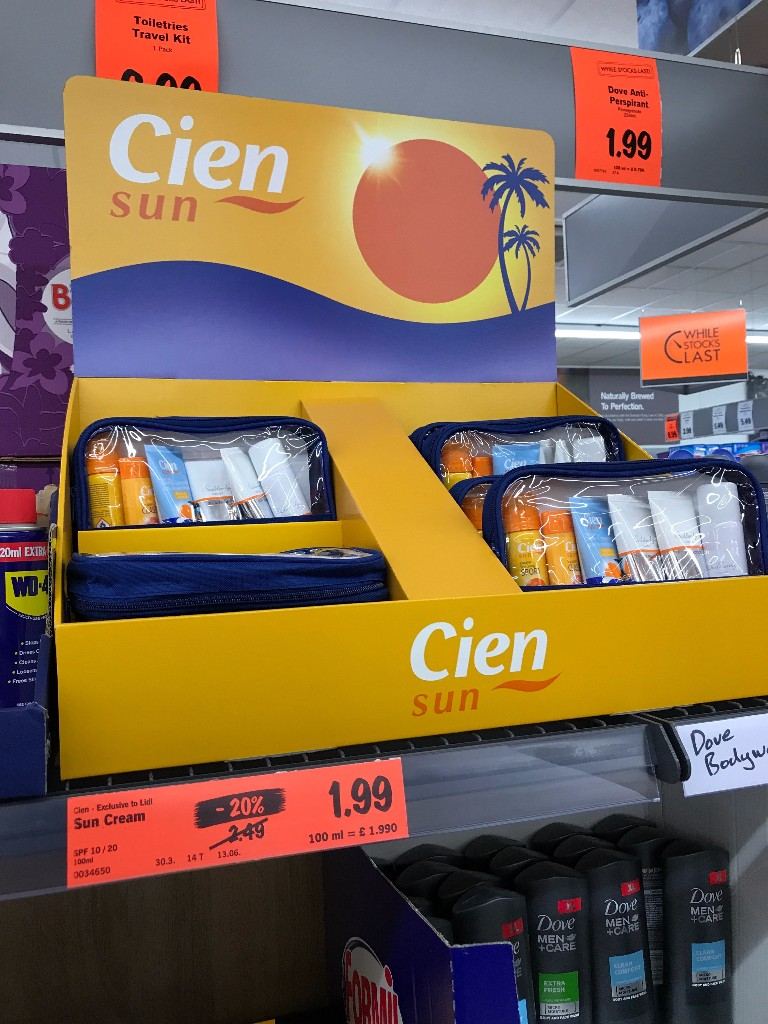
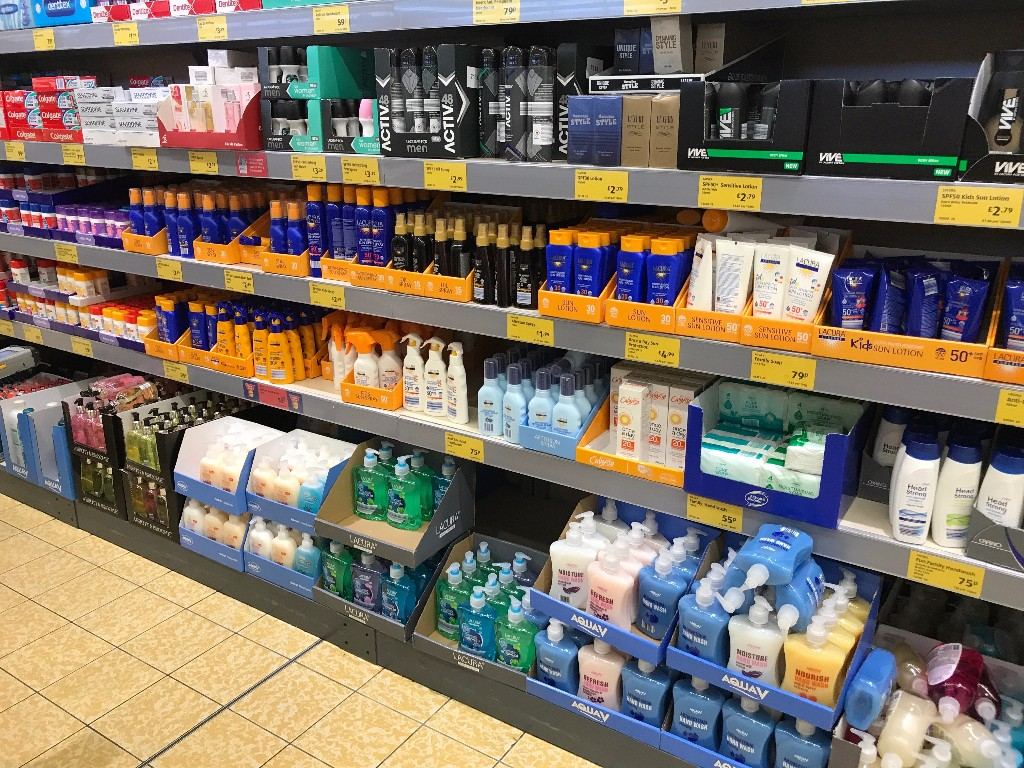
The latest battle given the season, not necessarily the weather this week... Is Sun Cream. It's such a hi/lo product, sold on deal almost exclusively and can become one of those lines that customers end up buying as they've forgotten... But then the price becomes prohibitively high, 2 for £12 etc.
Prices are lower now as retailers react to weather but discounters are always low, as we know. Aldi dropped their entire sun range 'front and centre' in their plan for Health/Beauty. Raising awareness amongst customers who have likely tried most lines and liked them; 'so why not Sun Cream?'.
Branding is similar and a 40% off board vs. Nivea helped matters too. Lidl have a great travel range in their special buys which was clever, smaller bottles ideal for travelling.
This is where their own label and also their special buys work so well for them. They are all over what is occurring and when. This enables them to be 'in and out' of non food ranges. Take Despicable Me 3 - for those with kids, or even just fans of the film - it's out now and a big event in the film world...
Discounters have character based T-Shirts, PJ's, Headphones and other lines, all low price and bang on trend. This sort of closeness makes it far easier for them to drive basket spend up.
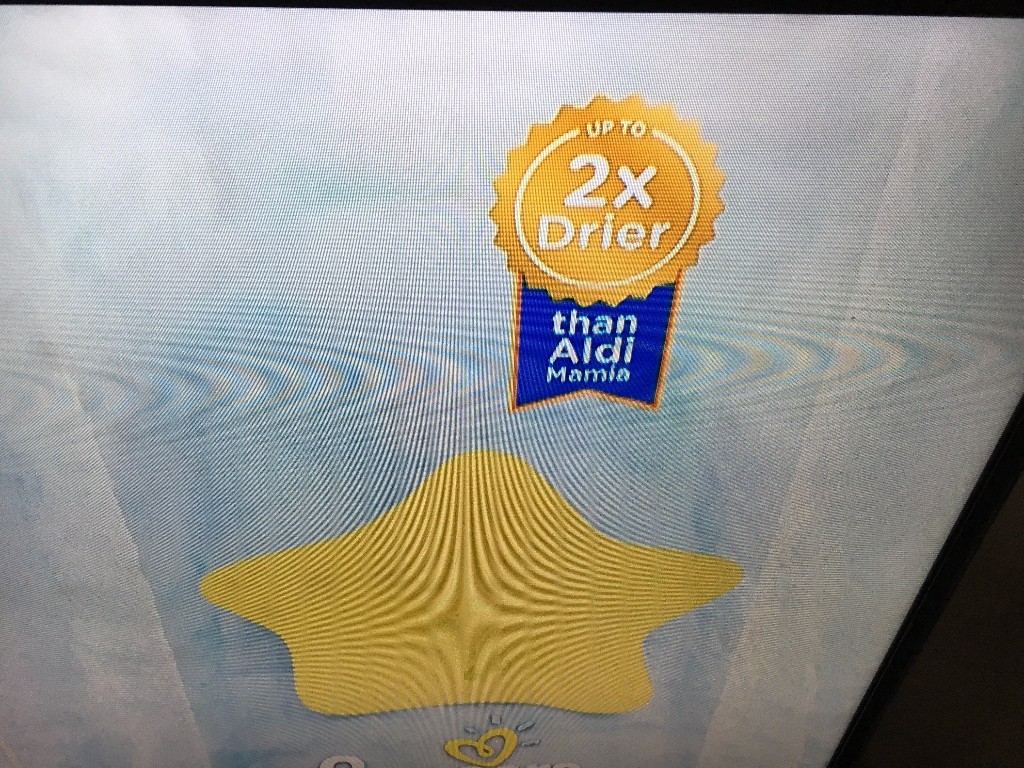
Leading brands have to do more of this; where it took retailers about 3 years to fully react to discount and start to push back on Produce and some own label... (even then, too late and failed to understand the wider shift....)
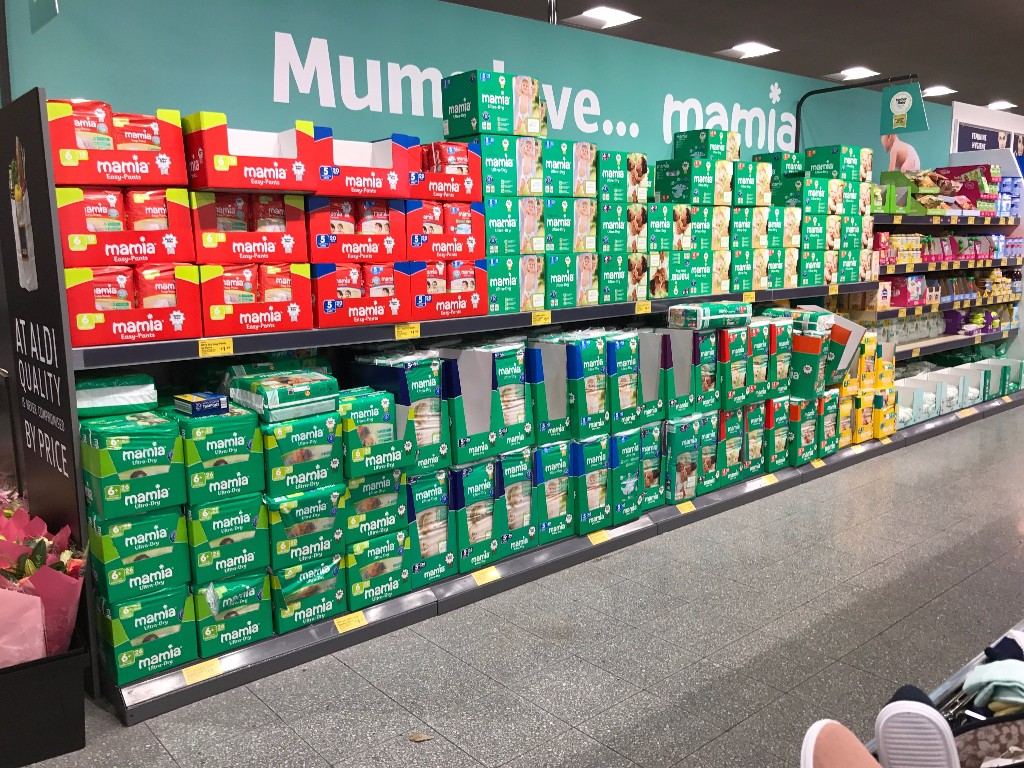
It took until 2016 for a discernible reaction from P&G on Pampers, this is despite Aldi winning share on Nappies, then adding their boxed pack to the permanent range due to the popularity of the product on the baby event.
The battle for share isn't just one for retailers, it's for suppliers too and they have to rise to the challenge too. Admittedly their battle is harder as they've also got to consider the larger retailers and their ambitions to reduce ranges.
All that alongside growing brands, bringing in new products in a climate where retailers are wanting to take ranges out and also the growth engine being a model where there are very few brands and no range growth either!
The rules of the game have changed and brands are absolutely not immune and have to consider what their next steps should be. They may not be the next Polaroid necessarily.... But you're never too big to fail.
Bar the reaction from P&G / Pampers above, there's been little else, save brands trying to get in to discount (which does make some sense), they're never going to be permanently ranged and could arguably only seek to devalue their brands further by having to go in at a discount to get a listing in special buys......
For every advert pushing back versus Mamia, like Pampers way back when in 2016.. There's further advancement from Aldi....
From the Grocery Insight newsletter archive, first sent to subscribers on 28 June 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.