Aldi - XL packs and Special Buys
5 February 2020
Visit the Retail Bible - our new platform for imagery and insight
The Bulletin
Our shorter emails will be entitled 'The Bulletin' and cover shorter, snappier elements from around the market, today we look at discounters and their moves into branded lines and also XXL based equivalents of their own label.
For a number of years, Lidl have run XXL events which were essentially 24 packs of their core toilet roll (e.g.) which of course, are not justifiable to carry permanently in a limited range discounter, however for the special event - it's perfectly fine to add own label packs in a bigger size to drive purchases from customers who prefer to buy bulk.
The benefits of this are that customers may be locked into their own label as a result due to the great value of a big pack, alongside this the 'share of basket' metrics are key. We know that customers can't do a full shop with a discounter and as a result go off to another retailer to complete their shopping and buy products they like, brands, free from and other areas where the choice can't be offered via a limited range model such as Aldi and Lidl.
However, by stocking larger packs, aligned with an event (cleaning, or baby for example) means that customers are less likely to need to go elsewhere, for as much shopping. Thus the rising threat from retailers like Home Bargains and B&M can be nullified to an extent.
The variety stores like B&M are threats to Aldi and Lidl, the more you think about it, they're a threat to everyone but their larger stores and random nature of products mean they're very much a 'treasure hunt' based store where customers will gravitate to, just for a look around to see what they've got in store...
Alongside this, there is a location overlap (many share retail park sites e.g.) and whilst they're all pushing hard in the space of saving money and being great value for customers.
Their respective ethos is entirely different in terms of variety stores being heavily focused on branded goods whereas Aldi and Lidl are own-label focused. Primarily food for discounters where fresh foods (Certainly) is relatively new for Home Bargains and B&M and they're not remotely authoritative in this space.
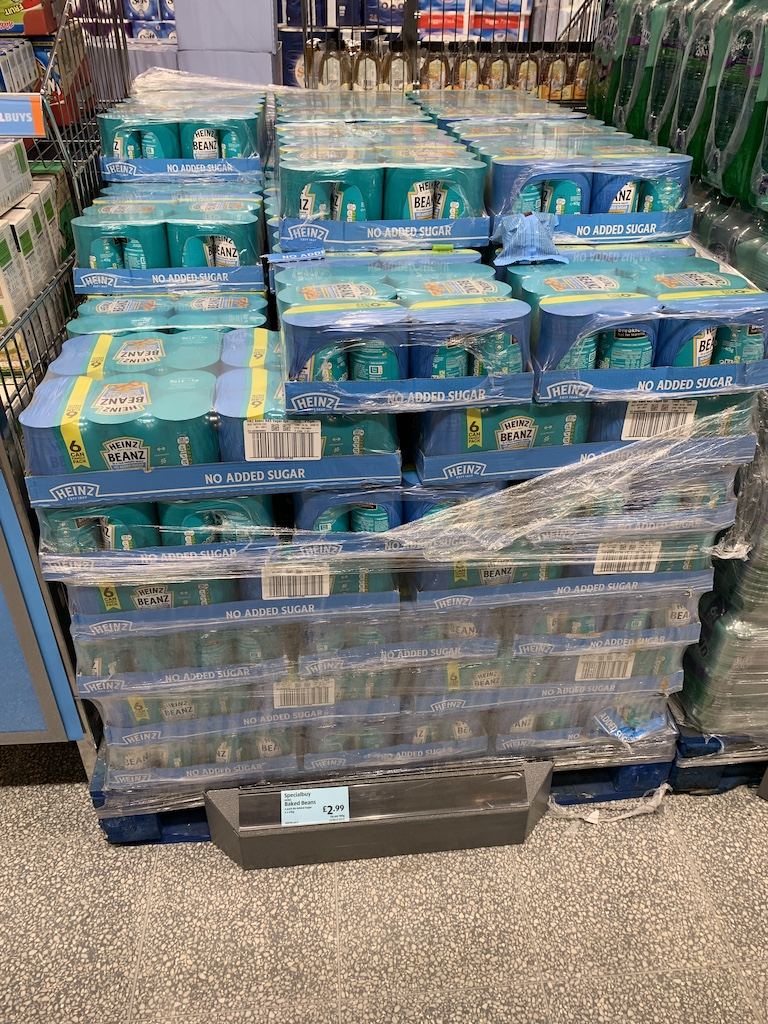
This does bring a form of 'phoney' war between Aldi and Lidl versus Home Bargains and B&M (alongside the bigger retailers of course), brands appearing in the centre of the shop in Aldi can be odd, the business spends a huge amount of time telling everyone that their product is better than branded equivalents and they're cheaper too.
Choice can help (no added sugar aiding a health campaign in January) and the branded suppliers are so busy chasing volume, they're laying their guns down and jumping into discounters with great merriment.
It's not a strategy, at all. However, it ticks enough boxes at the minute for it to happen.
But you're featured in the middle of the store, for a limited time, then you're out. Then Aldi will probably compare their product to yours with a "LOL we're cheaper" a couple of months later.
Customers like it though and discounters are able to widen their offer within the special buys, which we've seen more and more. Discounters are open for shippers and brands, online trading for Special Buys perhaps plays a part but the non-food market has died a death, even more so given the general slowdown in spending.
So there's space and ambition. But alongside this, Aldi and Lidl own label plays a part and specifically, Aldi at the weekend were pushing their XL, larger packs which nullify the bargain stores, given their strength in these key categories like Cleaning, Health, Beauty and Baby too.
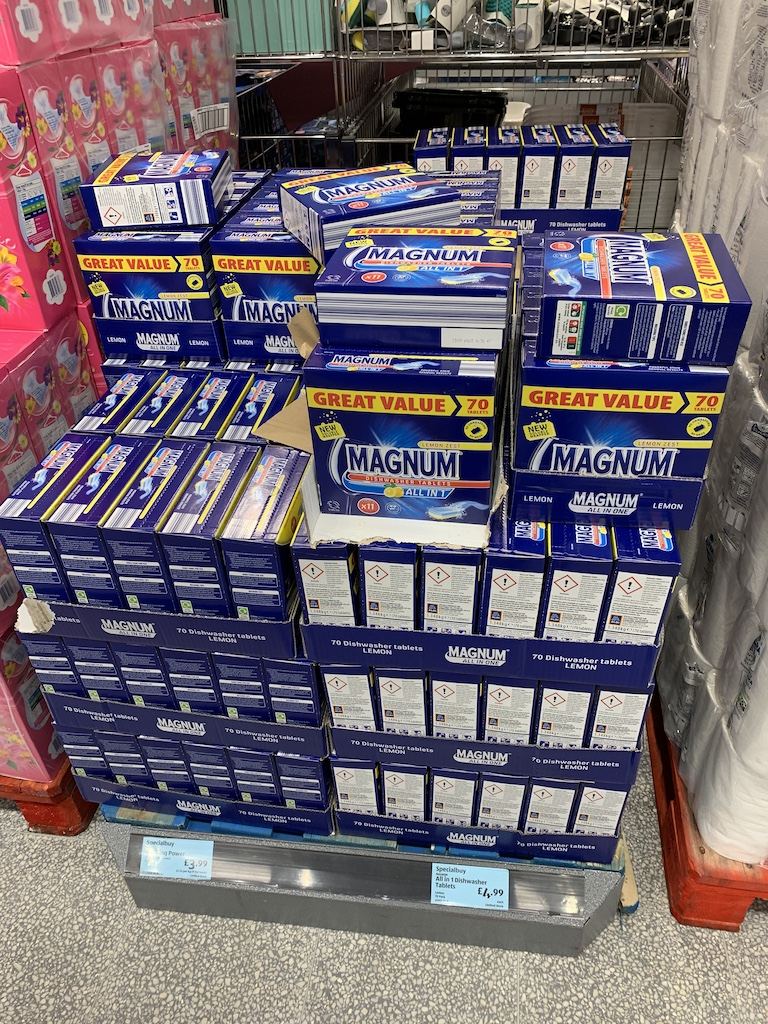
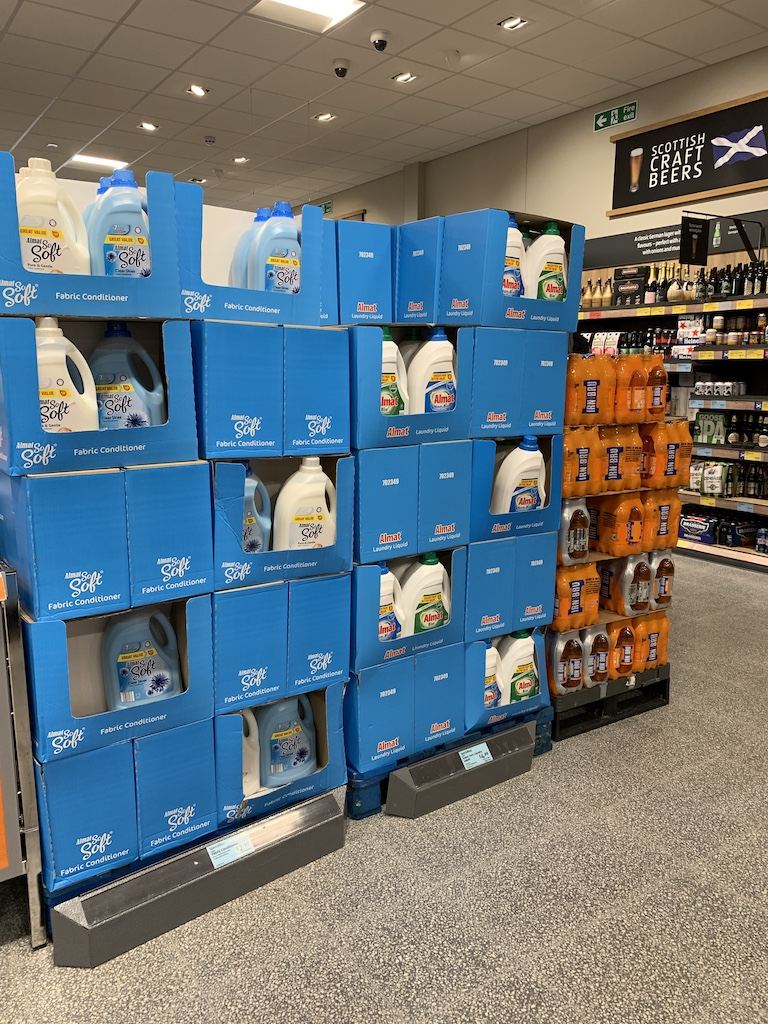
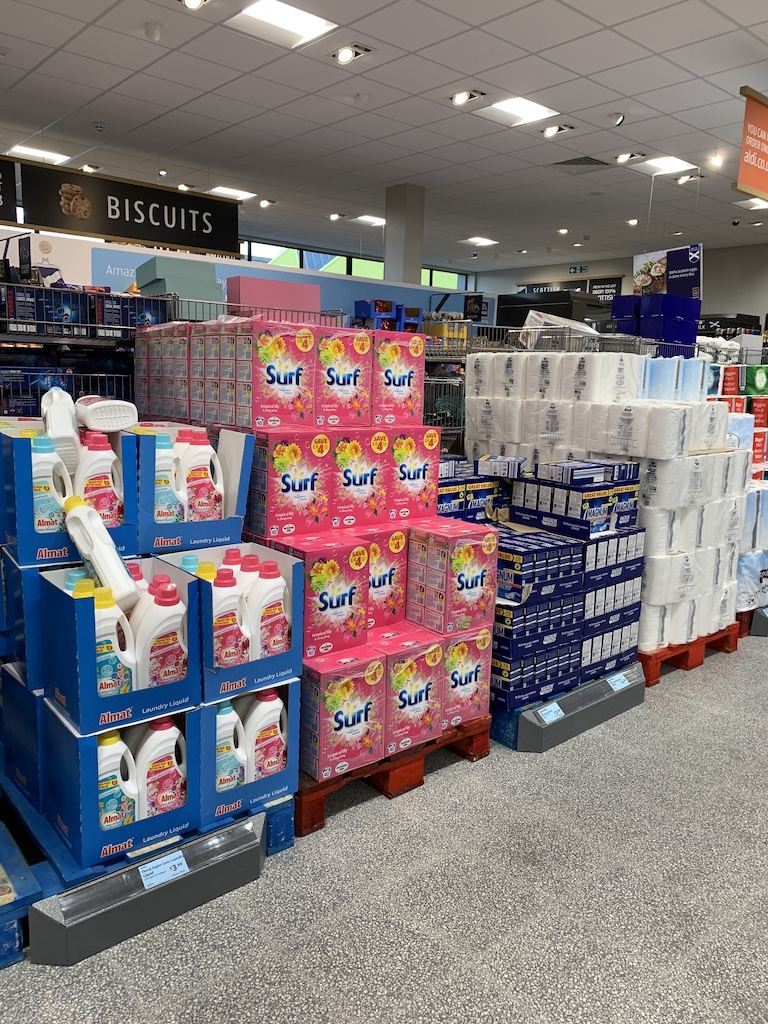
In addition, some branded special buys products were noted as well. Surf will be cheaper than the big four retailers for the most part and Almat and Magnum are Aldi own label of course, so a customer may switch spending and buy a larger pack (versus a core pack) or indeed, buy this pack whilst in-store and enable Aldi to grow sales.
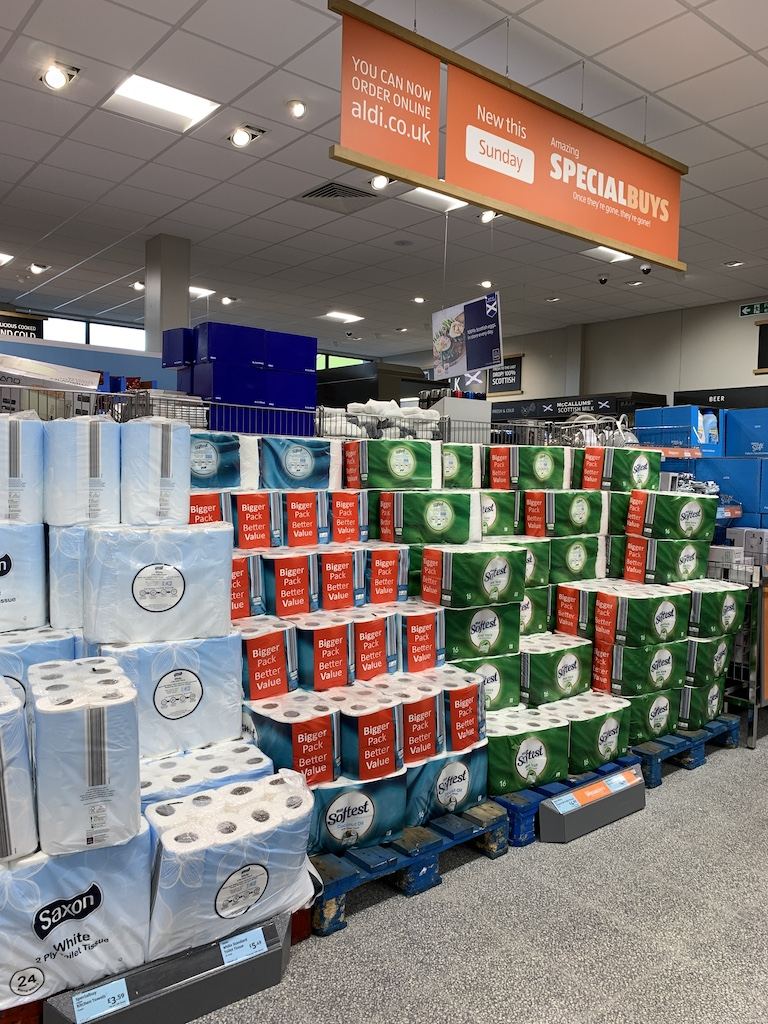
I wondered where the stockpiled product ahead of the threatened no-deal Brexit went, not necessarily here but there has been a real glut of 'paper' based products on deal everywhere, Andrex was on offer in numerous retailers and B&M had pallets of it too.
Their core low price on toilet paper is a cornerstone for Aldi but a wider range of larger packs of toilet paper means customers can grow their spend here and stock up. Alongside this, occasional shoppers / special buys shoppers may purchase here which takes share from others.
Putting larger packs on a limited buy generates 'scarcity' and people wanting to buy now because they know it may not appear again for 6 months or so. It's a change in tactic from Aldi, but Lidl has done it consistently for a number of years, often running special weekend only XXL deals too.
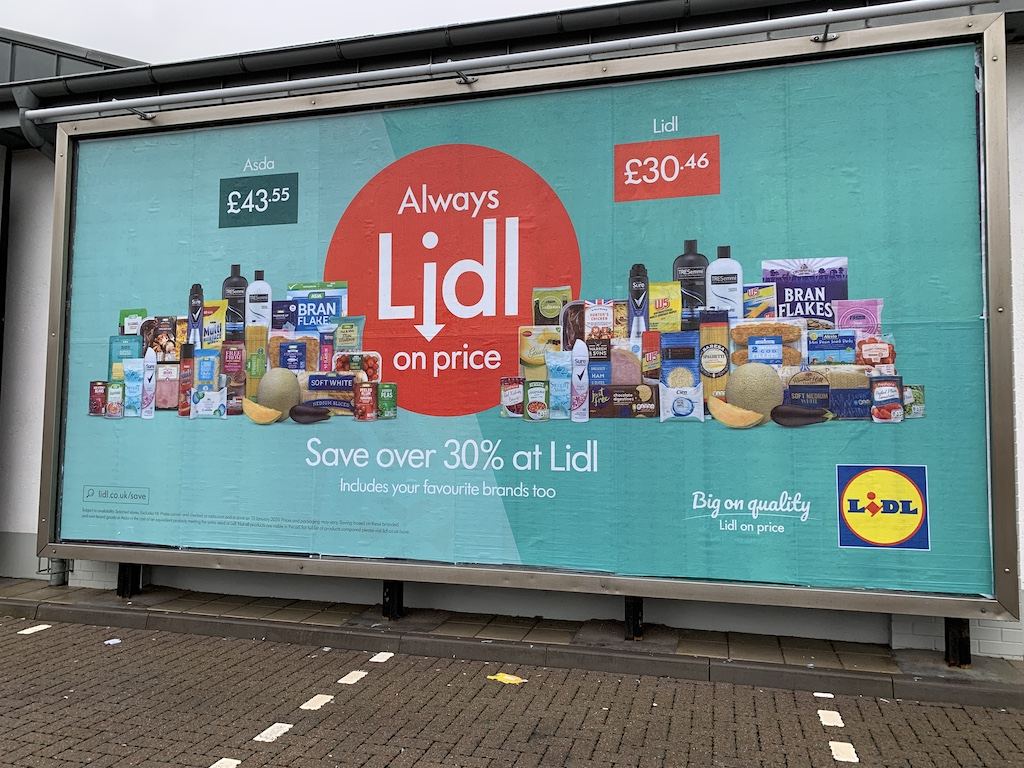
Speaking of Lidl, it was interesting to see that they turned their attention to Asda in their latest billboard based adverts outside the store. Usually, it's Tesco in the firing line.
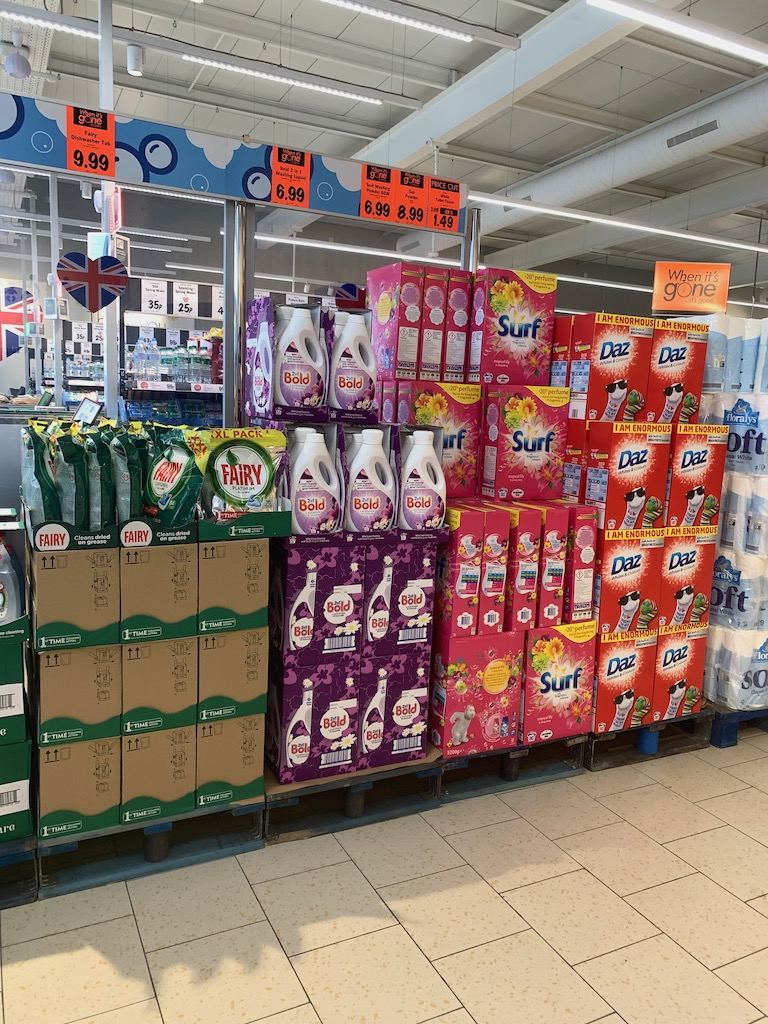
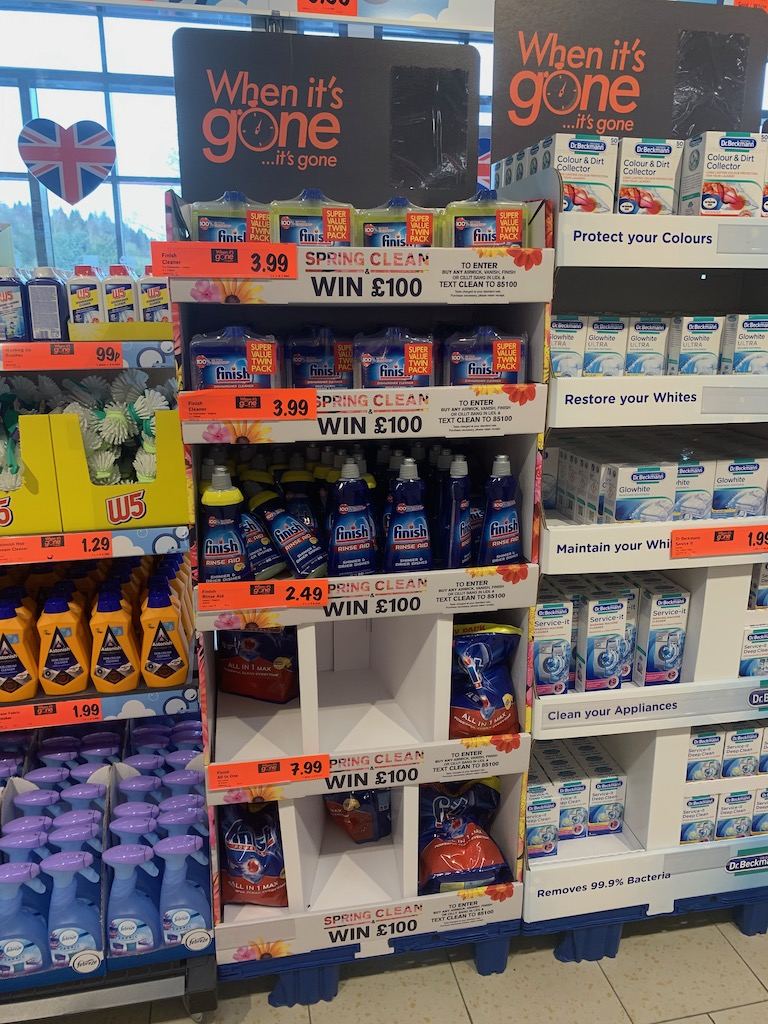
Lidl on the other hand absolutely love a shipper and suppliers are able to get all manner of products into the chain on these disposable and moveable units. They're branded but carry the 'when it's gone, it's gone' header and often carry competitions as we see on the Finish brand above.
Lidl have traditionally carried more brands than Aldi in any case, so their EDLP / everyday Lidl price campaign worked well for them, as they feature a lot of brands in their core range. However, in the middle of the store, they have a "B&M" style range (as do Aldi) with the tertiary brands like Golden Wonder crisps and the like.
However Lidl have a huge assortment of shippers too, every turn features units with all manner of brands carried, it explains their stronger showing in Kantar for branded sales but does it water down their offer?
It's valuable to grow existing sales and their stores are generally poorer than Aldi in terms of standards so they're running hard and fast too. But it's a fine balance, there's still a sizeable own label offering in Lidl and they don't want to become a house for brands on shippers.
For suppliers, another example of their lack of strategy around discount stores and how to combat them.
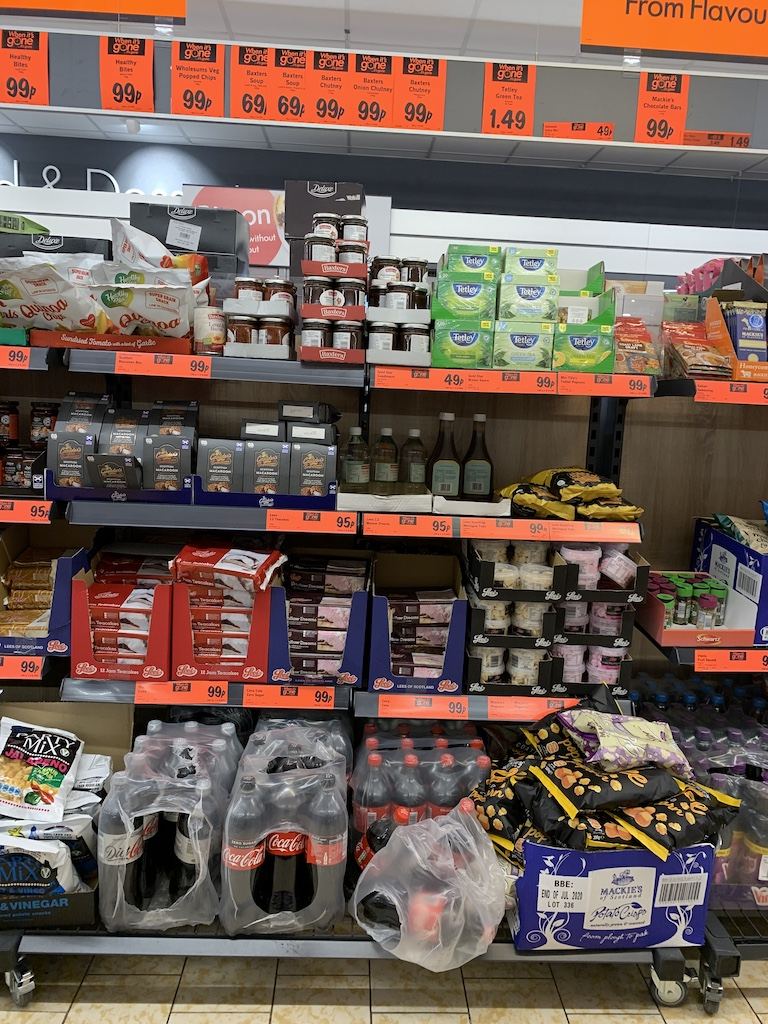
One of the better examples of merchandising that we've seen (believe it or not) but the fixture (a number of bays c.8-10 in each store in the middle of the store were added 2-3 years ago) often features all manner of products from various events and spot buys almost.
Coke in the base was questionable in any case, Scottish line adjacent to that with further shelves featuring all manner of products, some are own label (premium) to grow that range too. However, the Tetley's Tea was then questionable and it's a treasure hunt in itself.
As event pass by and sales on some lines are better than others, some fixtures in some stores end up looking like they've not been attended to for a number of weeks.
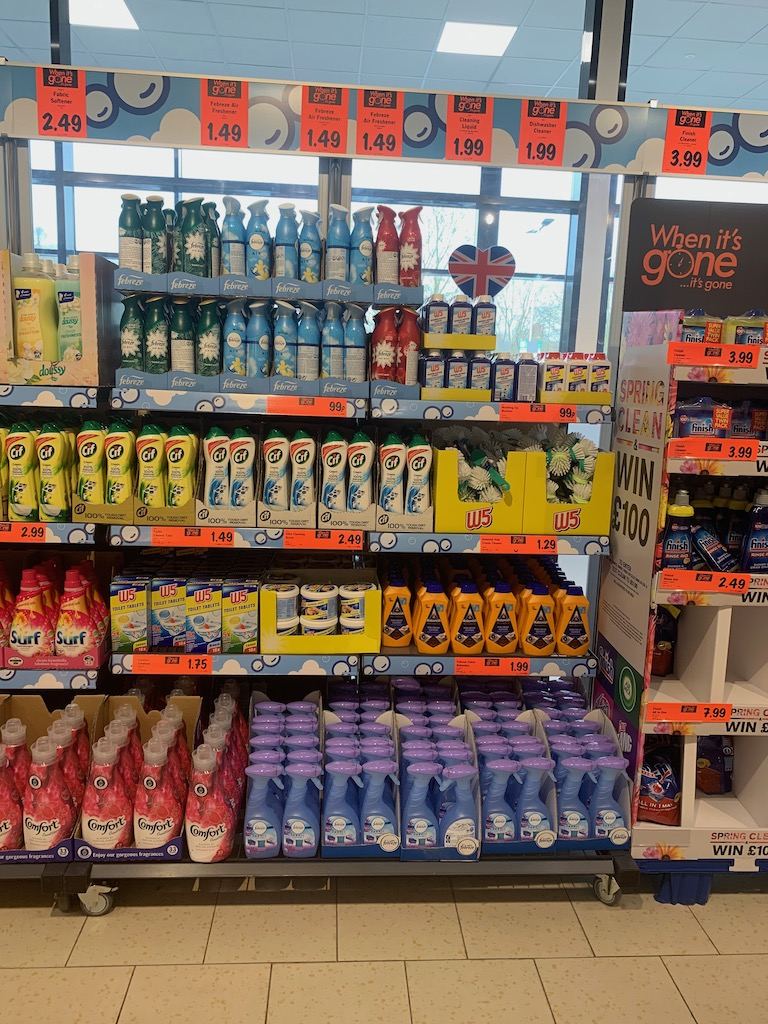
For the Lidl cleaning event (in the store entrance / seasonal area) which is added space versus former years. We see some W5 products but others are branded, all manner of lines included but on 'when it's gone, it's gone'.
Strategical by Lidl? Designed to fight against Variety stores? Larger stores? Aldi?
I do not think it's remotely strategical by the suppliers. But Steve, the volume!
But suppliers, the long term plan.....
After all, we can all sell tenners for a fiver.
Visit the Retail Bible - our new platform for imagery and insight
Contact us to have a discussion about retail
From the Grocery Insight newsletter archive, first sent to subscribers on 5 February 2020. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.