Discount category killers - 2) Nappies/Diapers
5 June 2017
We've been travelling! Back from the US where the service will have a few considerations from the US market over the coming weeks.
The challenges for Target are not unique to Target when we consider discounters in the US, and specifically, Lidl....
There are concerns for all the retailers who will face Lidl as they embark upon their American adventure, no doubt there will be mistakes around site location along the way... But broadly speaking if they can start winning awards for their own label products and push hard enough on brands vs. own label comparatives then we may see Americans start to take discount seriously.
The question is whether Aldi US will be able to ride that wave too; given their store remodels and concerted effort in the space. However they have been in the US for an number of years and haven't made many in roads... Is that down to their model? Their lack of advertising? Or that discounting doesn't work as well when the existing 'big' players are already pushing on with low prices.
As we consider what Lidl may look to do with their operation, and how they'll try to woo the US consumer. Grocery Insight have considered 'category killers' already - household is a key category where choice is abundant and discounters won't carry anywhere near that level of choice.
The next category is Nappies (or Diapers for our American friends). looking around both Wal-Mart and Target - there is a huge amount of range spanning own label and brands and not always entirely clear what is what and where the value lies.
Discounters / Lidl will come in with one type of Nappy (Toujours in the UK) which will feature across their stores. They will attempt for it to win awards or recognition and act as an anchor to bring people in to stores.
Prices will be low, pack sizes limited to one type and there won't be a range of Nappies to pick from here.
This will drive prices down and Lidl will keep the margin tight across the store, but Nappies are always somewhat of a halo product for them.
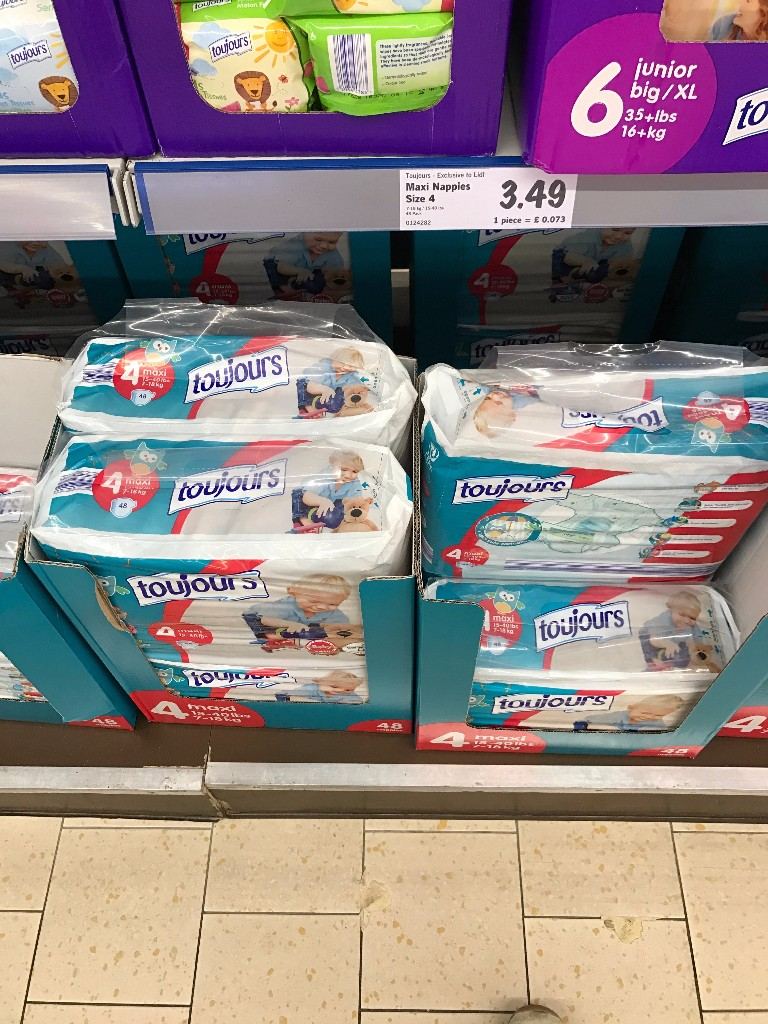
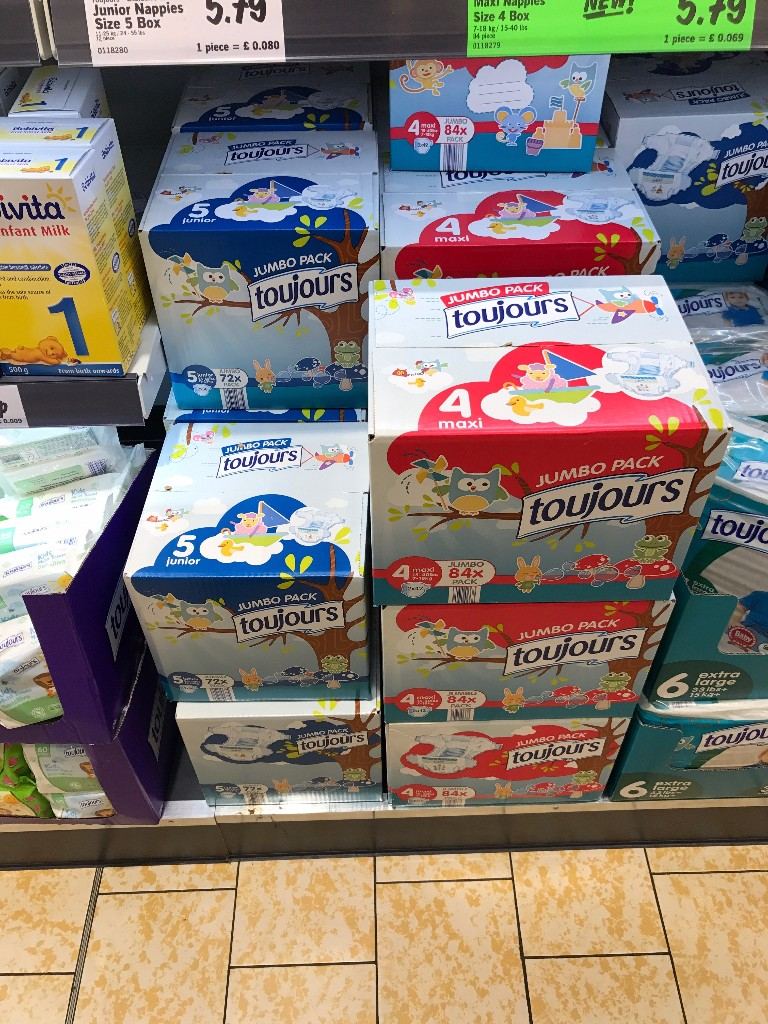
We can see here in Lidl; they offer one type / brand of Nappy and that there won't be any deviation from this, expect strong quality credentials as locking in families is a vital piece in food retail.
They have added a larger pack in recent times, as have Aldi where they capitalise on the demand for Nappies and launch larger packs to further drive savings for the customer.
So Nappies are another one to watch, and indeed the wider baby category benefits from a real focus from discount. It's a key category for them, they can bring much lower prices, encroach on branded designs and imitate their products too.
Plus a family is valuable for a retailer, they have kids, who will grow and a growing family needs more food and supplies = more sales.
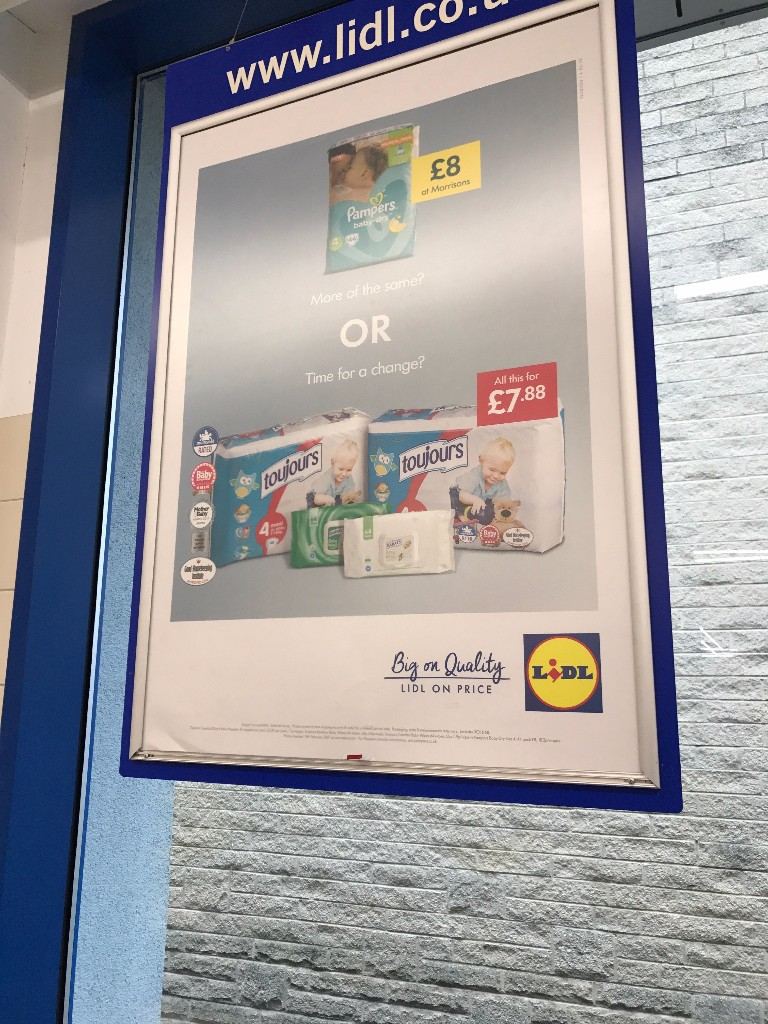
Much more of this is expected; the image depicts 1x pack of Nappies at a larger retailer for £8, or most of the wider baby range at Lidl for a lower price.
Meaning the customer is shown that some products are expensive versus discounters, where you can get much more for with less spending too.
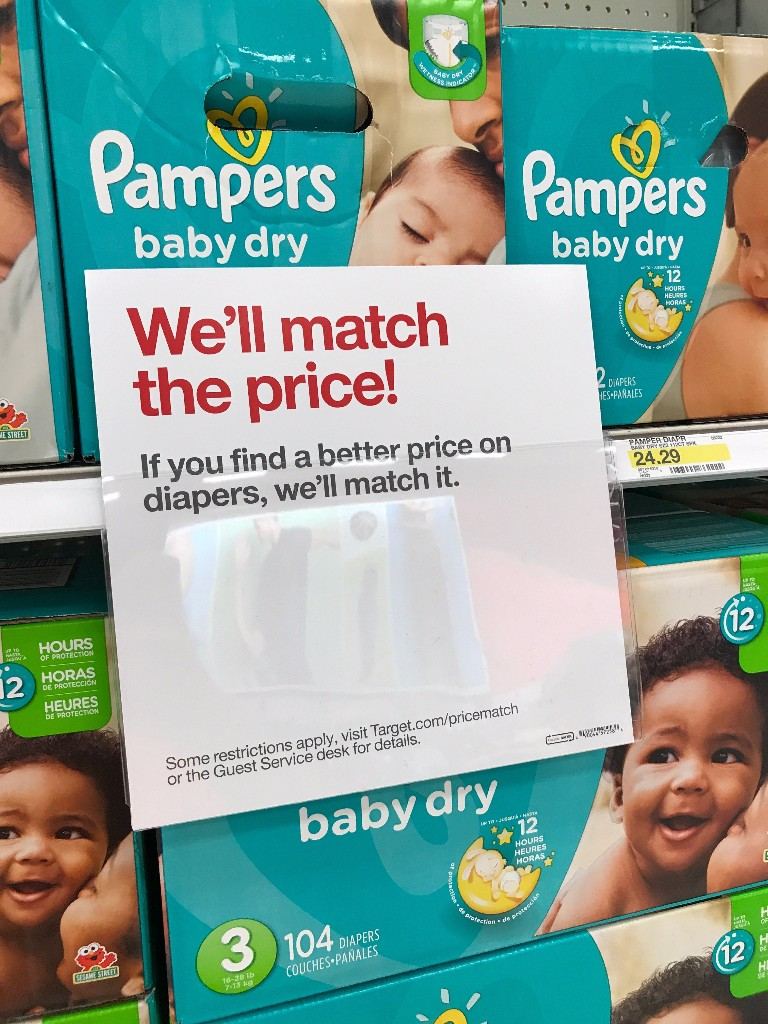
So to Target have a price match on Nappies at the minute. Again, why not just beat the price? Or invest this into a lower base price in any case?
They do have a lot of 'everyday low price' tags around the fixtures, but unclear whether it's a great price.
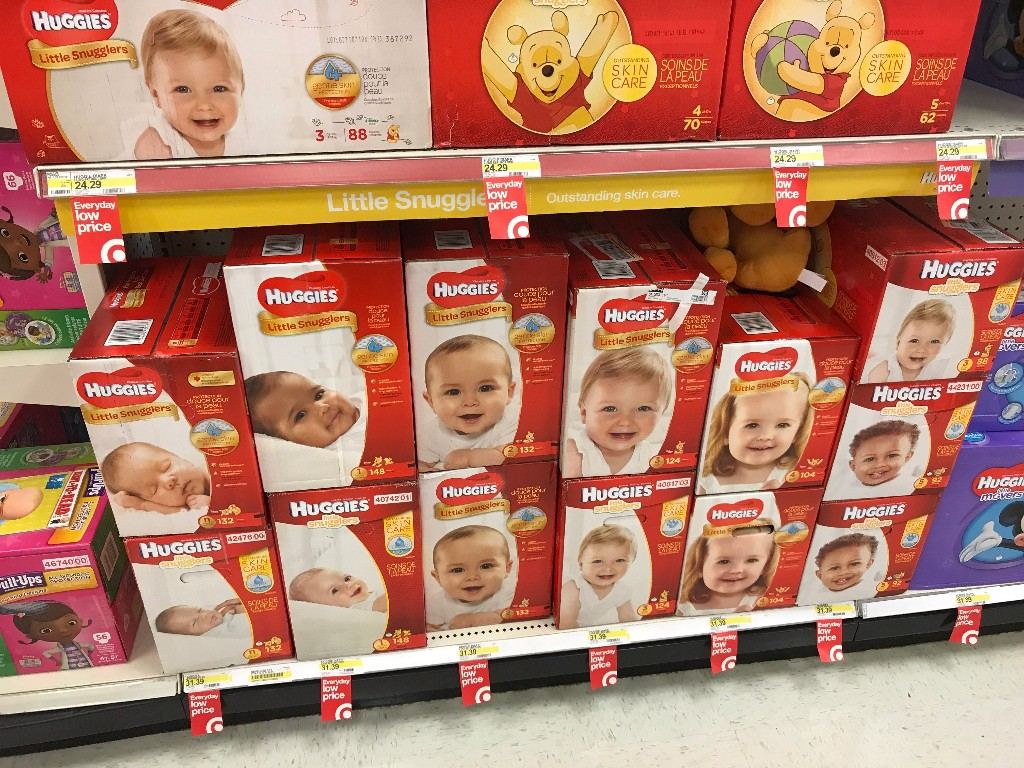
With a fair few everyday lower prices also flagged here; but are they low enough? There's so much range around, it's hard for the customer to see where the value should be.
It's not that larger retailers are inherently more expensive than their discount counterparts, but the own label, or the real value is hidden within a huge assortment of products.
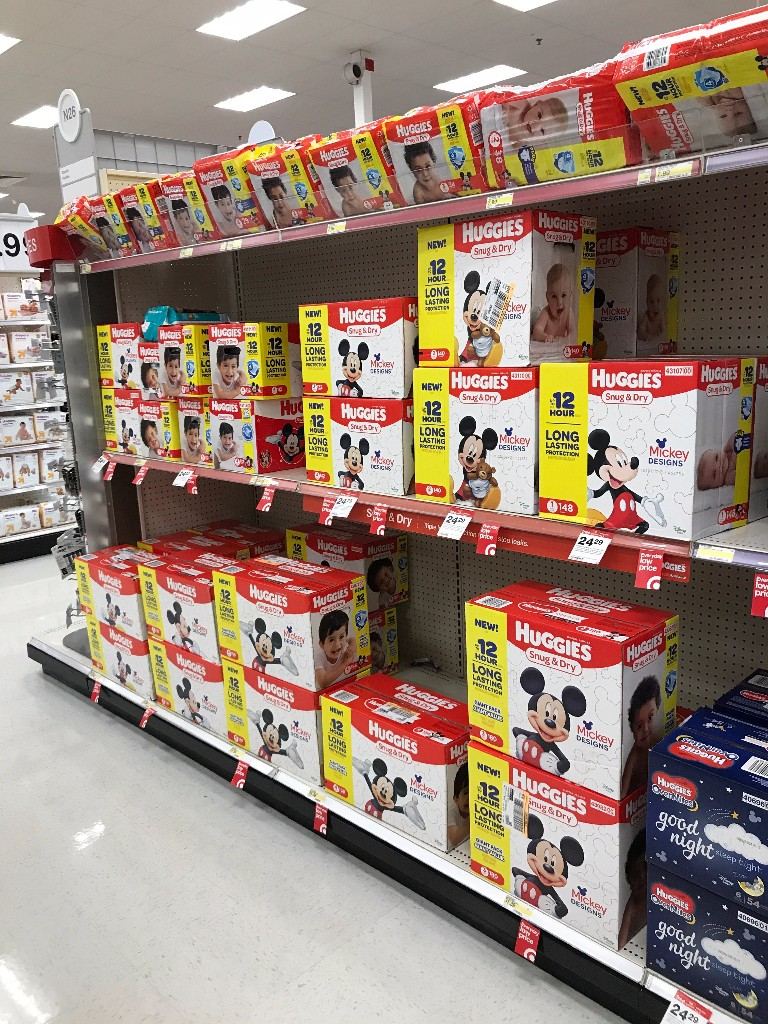
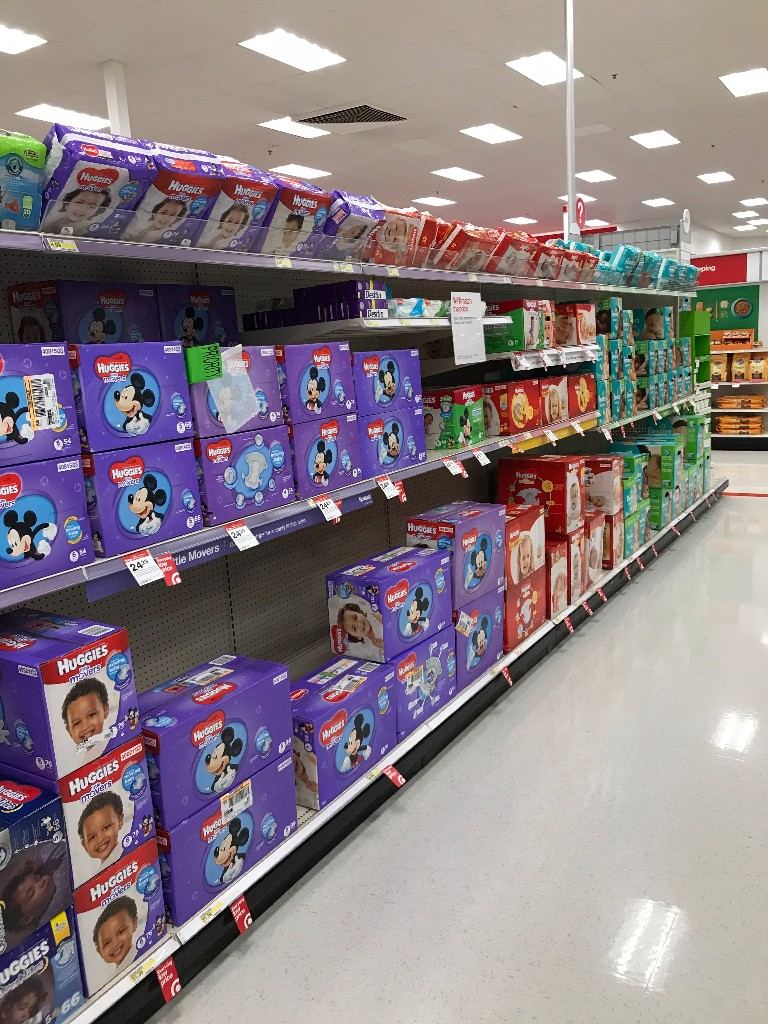
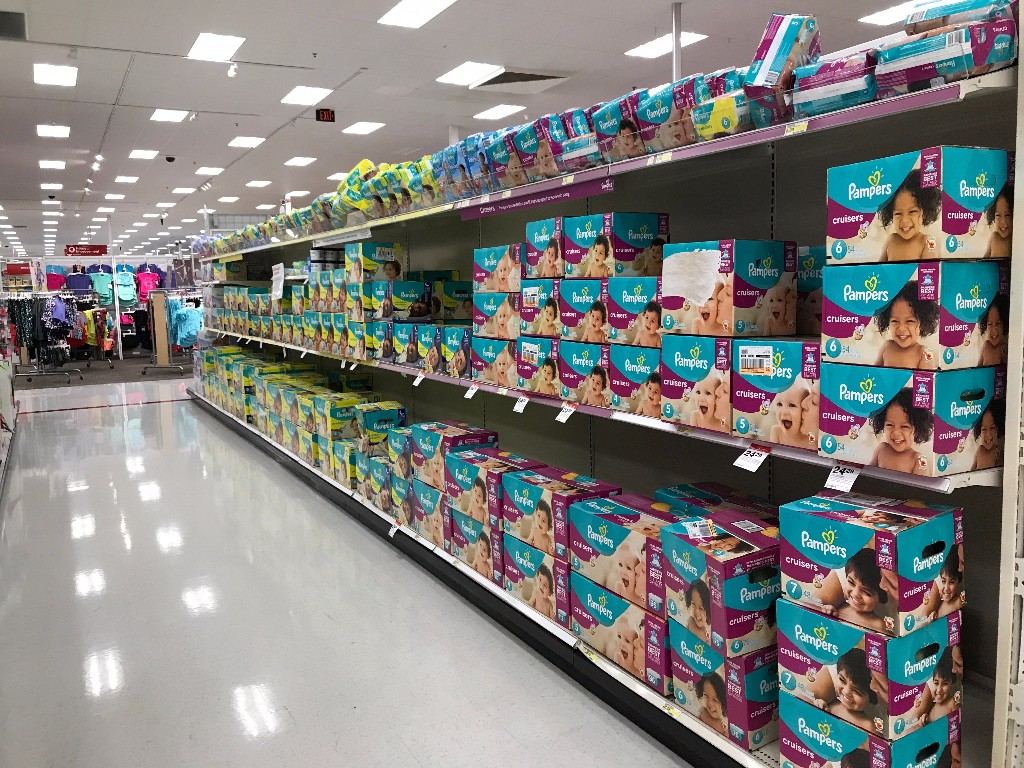
Choice is vital for any consumer, particularly the US consumer who generally have larger houses and therefore are able to buy in bulk, they have the storage to support it.
In addition, big box stores also support this mission, which means that the range stocked by Target here is understandable, but not necessarily right.
The choice is extreme, with the range going across two full aisles (the outer aisle was taken up by own label).
This is the issue; Lidl will offer just one type of 'diaper' for the US consumers and if they get that right, it will lock the customers in to shopping with the discounter.
They've done this so well in the UK, both Aldi and Lidl have made their Baby categories their 'halo'. Even seeing Aldi develop their own brand of Baby formula...
Simpler shopping, strong quality and low price. A formula for discount and Lidl will apply this relentlessly.
For any further service offerings around discounters, strategies to consider and what has / hasn't worked so well from other markets. Please don't hesitate to get in touch, we have several thousand in store images from discounters and examples of their execution and different campaigns from the years gone by.
From the Grocery Insight newsletter archive, first sent to subscribers on 5 June 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.