M&S - Concept store but more of the same?
26 February 2018

Our access options will soon change for this service, with tiered packages available to encompass various options for users who would like a little bit more content. Further details are to follow.
Another short email ahead of a wider note to come later this week on M&S, there are three notes, split across Food, Home and Clothing.
Assessing what is going on at the store level, what are the challenges that face a customer and, speaking as someone with very little fashion experience.... I was shocked as just how, at a basic level, the Clothing challenges may be just a little more than the garments / lack of trendy lines......
All to be revealed, alongside a note on Food finally. This trailer features some images from the new concept thinking seen in Marble Arch but mainly in this store in Milton Keynes.
My key thoughts (ahead of a bigger write up) were that whilst it's a lovely piece of work as a food store. With LED lettering bang on trend, their open food works well and graphics are nicely set up around the store....
However, in terms of a scalable proposition. Not really. Some locations would benefit from the open food counter but it's labour intensive.
It doesn't solve two fundamental issues for M&S - within Food at least.
1) The premium elements really do not help the wider value perception, not great with customers in their 'recessionary' mode post Brexit and squeeze on spending.
If anything, it makes it look more expensive.
2) It's still near enough impossible to get a full shop, or anything near a full shop at M&S. Of course with the price situation, customers don't want to but range gaps need filling in.
There was talk that the range would take some two years to sort out in Food. Never. It should be a priority and be relatively easy at a high level to work out where things need to be adjusted to facilitate a 'fuller' shop with better value products.
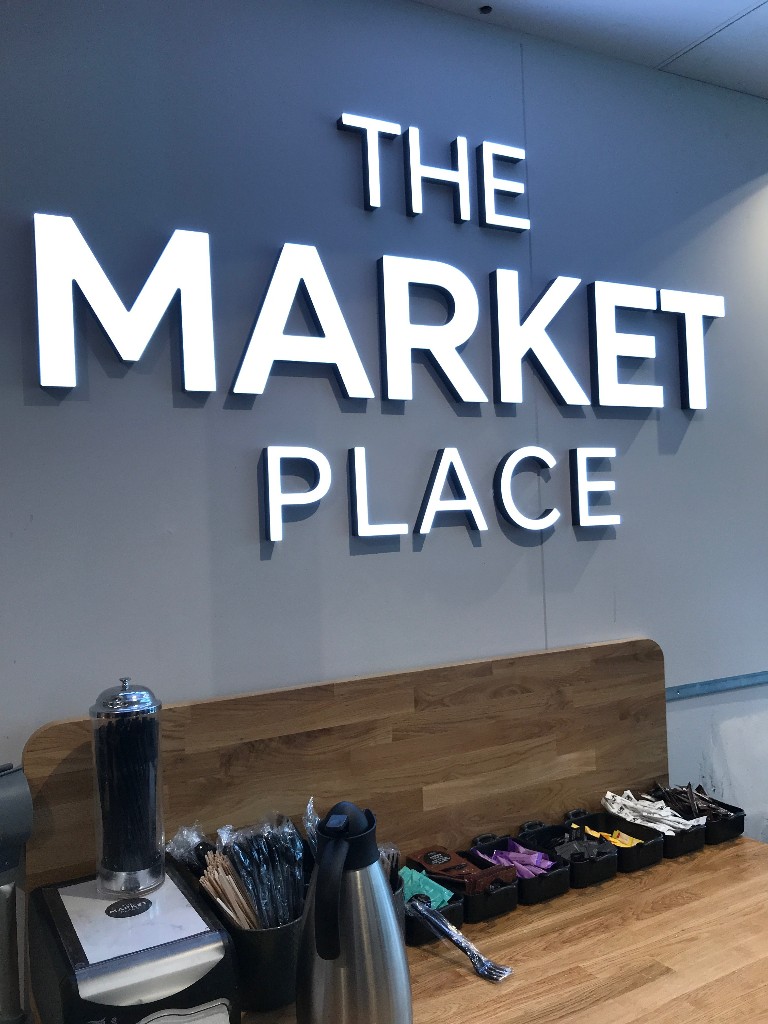
Open food to go under 'The Market Place' banner is the main message, the food to go range is also sited within this foyer area, alongside a number of self service tills.
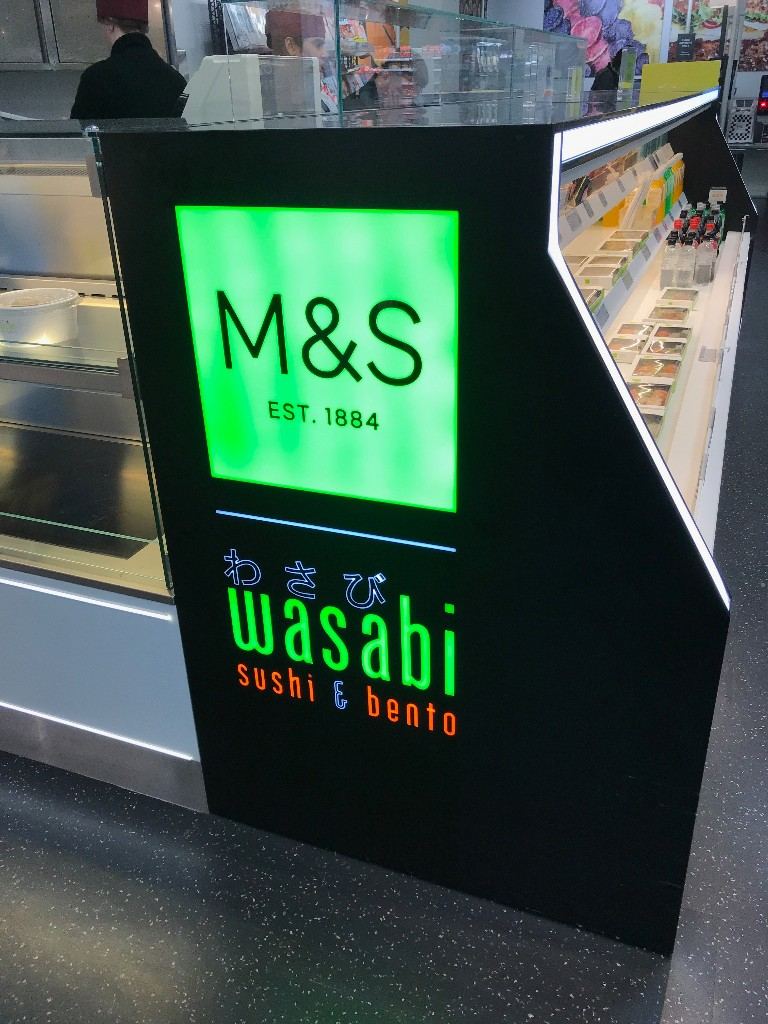
In addition, the fledgling Wasabi / M&S partnership is given another run out, however results are believed to be mixed.
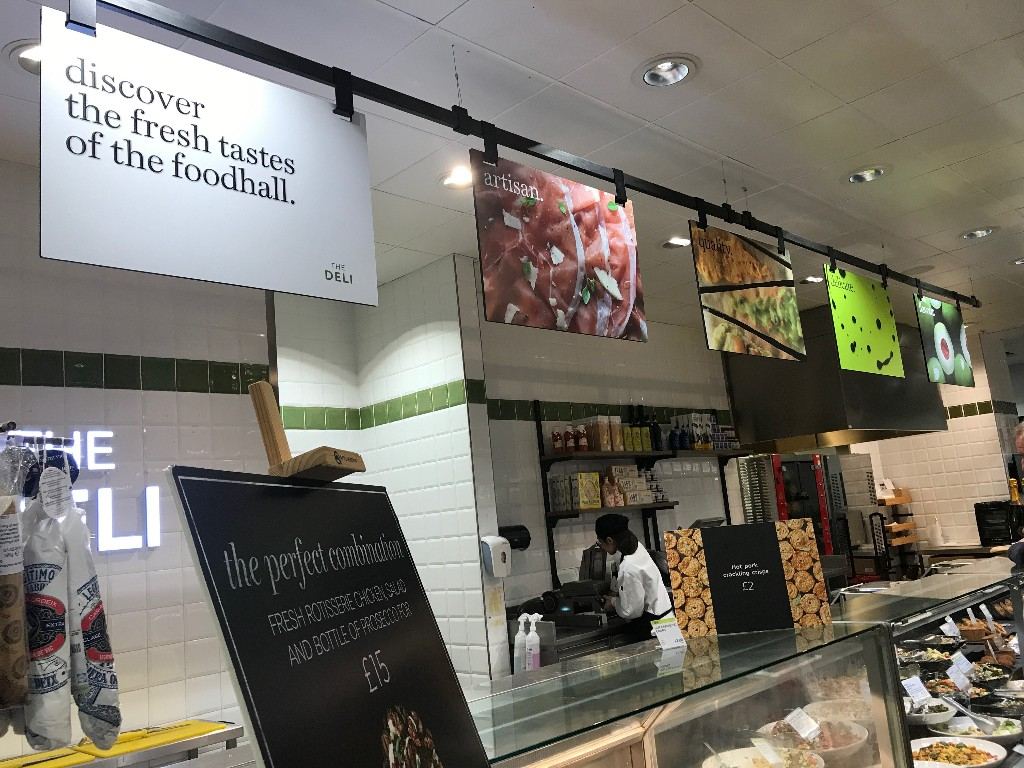
New signage over the Deli is very marketing intensive, again it doesn't talk about value, or price. Rather hanging artwork.
It does look nice though.
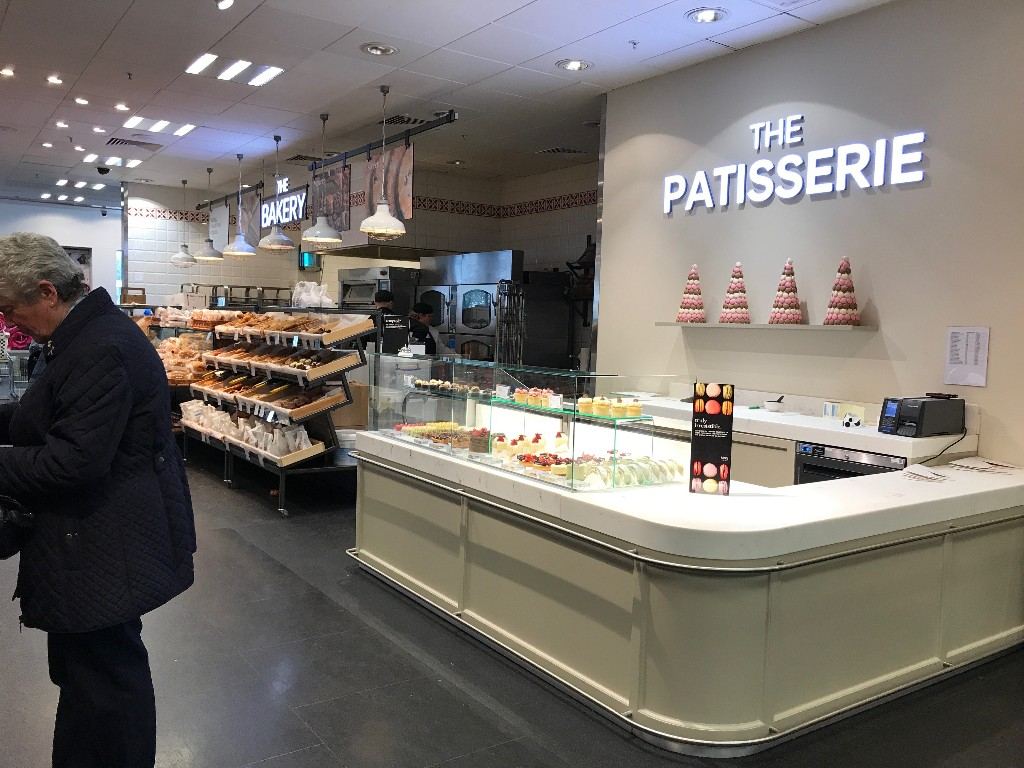
Also looking nice was the Patisserie which wasn't manned throughout my visit, I wondered if it was a trial that wouldn't go any further.
The counter itself was nice but not bold enough to bring customers in to the fixture, and the location meant it was lost a little in the store flow. It does look good, but without personalisation or other bespoke services, it doesn't serve to add any real value.
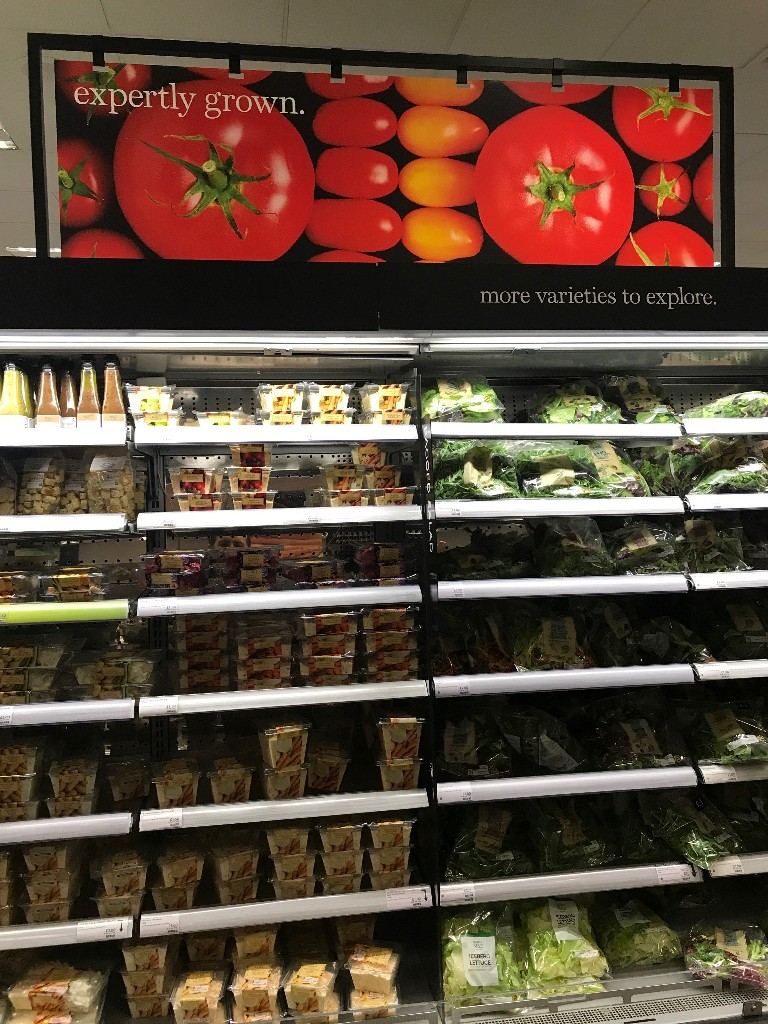
Further great signage around the store, it stands atop the chillers / display units and works well. However it is unclear what value it adds, there is nothing about M&S, provenance, quality?
Do customers already know this about M&S?
Customers already know the M&S own label is strong, their mid tier was the only tier they needed in the older days and was the benchmark for every single own label product everywhere else.
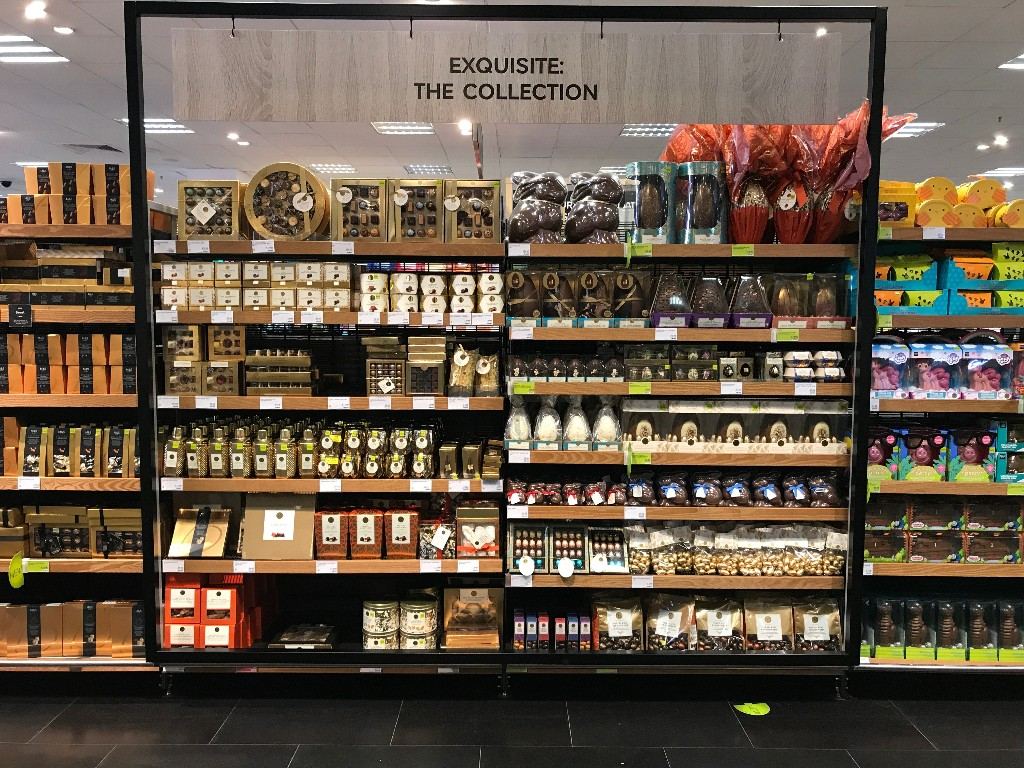
However since adding the Exquisite 'The Collection' range to the ambient assortment, it has muddied the waters a little. The range has continue to grow too, especially in Confectionery and oceans of this Gold packaged, expensive product at Christmas aligned their price messaging at too high of a level.......
Their ideal approach would have been to overlay some 50 products or so that were truly special in their respective ranges and rotate these, like Aldi do for Christmas and Easter.
As it is, they've continued to add lots of premium in to the ranges and now it looks excessive. A sea of brilliant product at brilliant prices (for the buyers) and customers see that. They think prices have gone up then decamp to Aldi, Asda or Morrisons who do strong premium ranges (let alone Tesco and Sainsbury's).
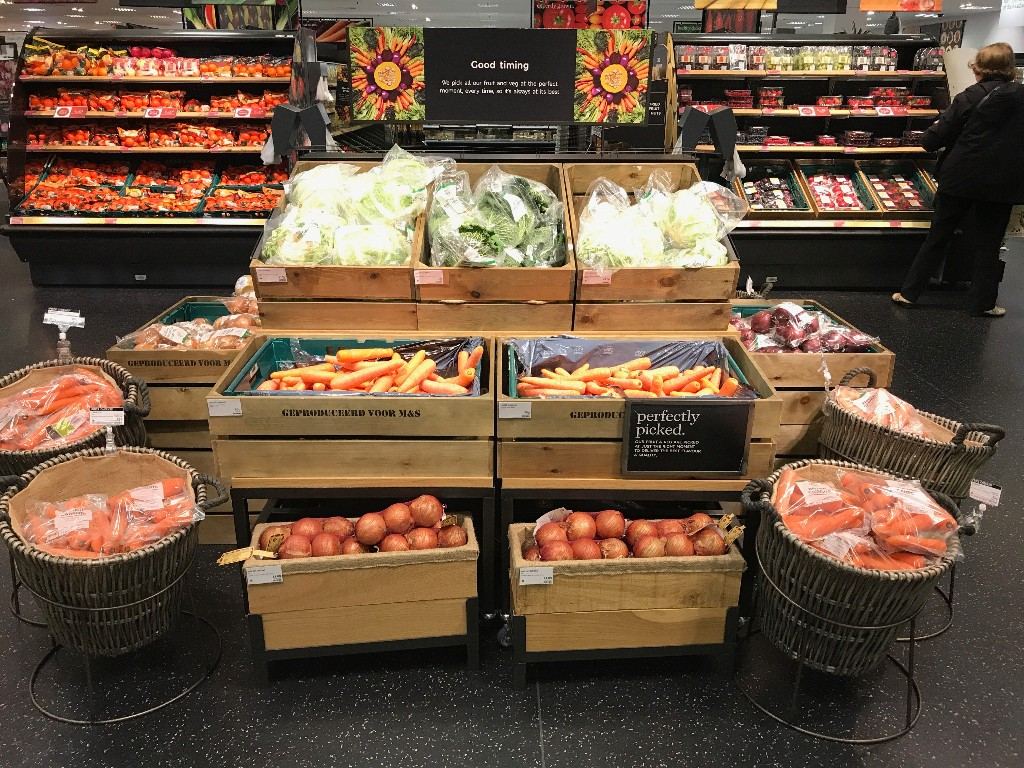
This entrance (from Clothing) display is strong, lots of Wooden kit but a decent effort and well set up for trading.
Not much on price though again, almost hidden away.
M&S price match with Sainsbury's too, although not the cheapest in the market, they're not at the Waitrose end of price points so this should be communicated in a stronger fashion also.
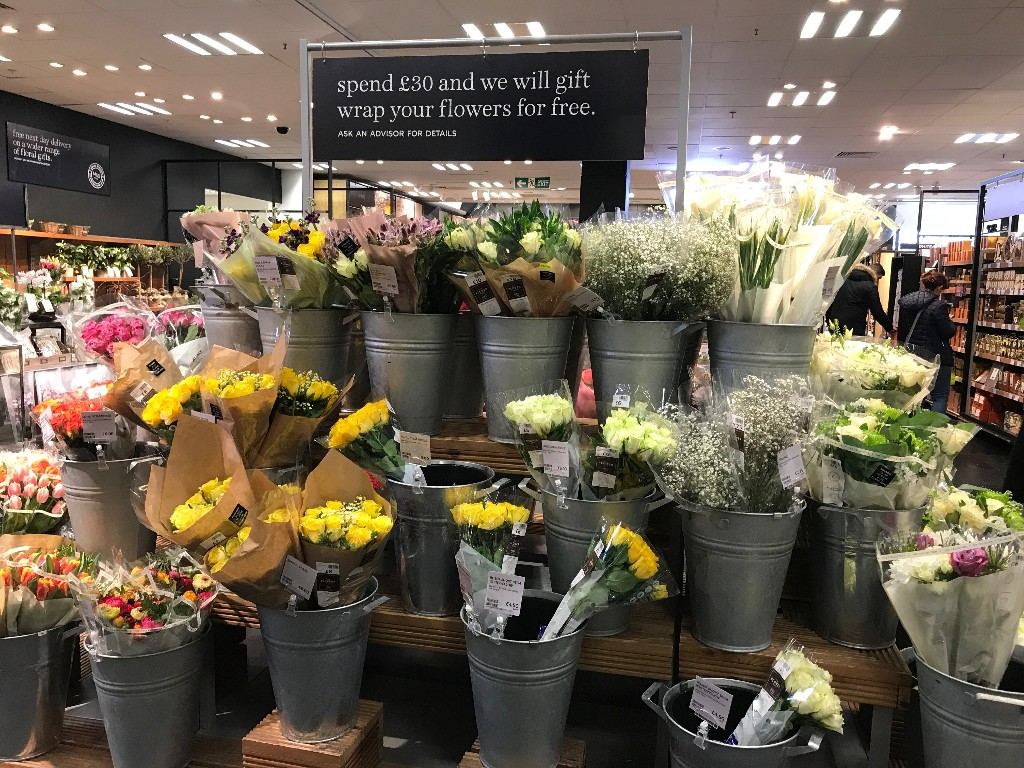
Perhaps one of the biggest indicators that the blend between value and premium is set incorrectly. Perhaps with the large Flower Shop in store (vast old space!) there should be a greater focus on Flower wrapping in any case?
Free wrapping on Flowers when spending £30 is excessive, you'd hope for a steer on what it costs for the flowers to be wrapped anyway...
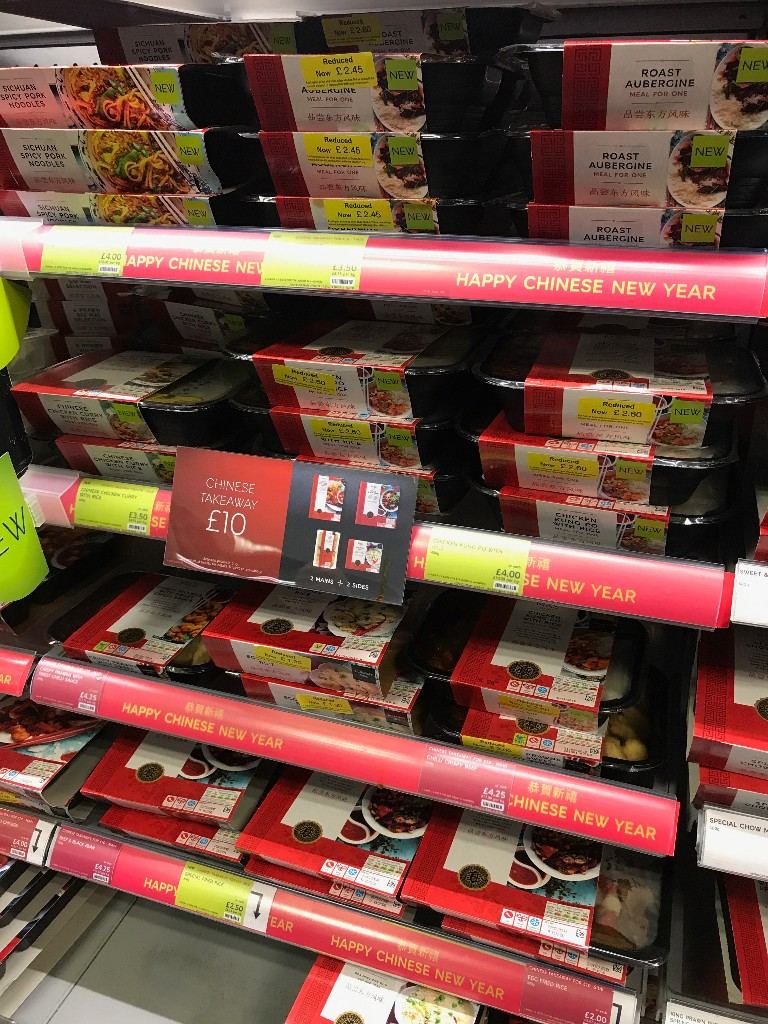
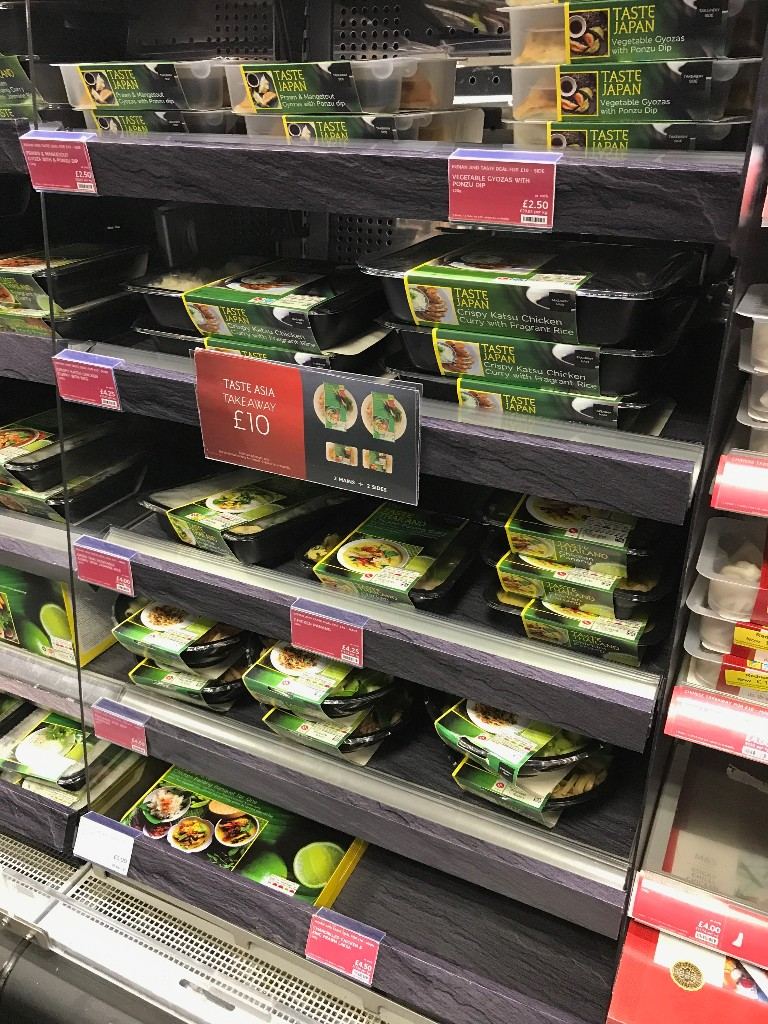
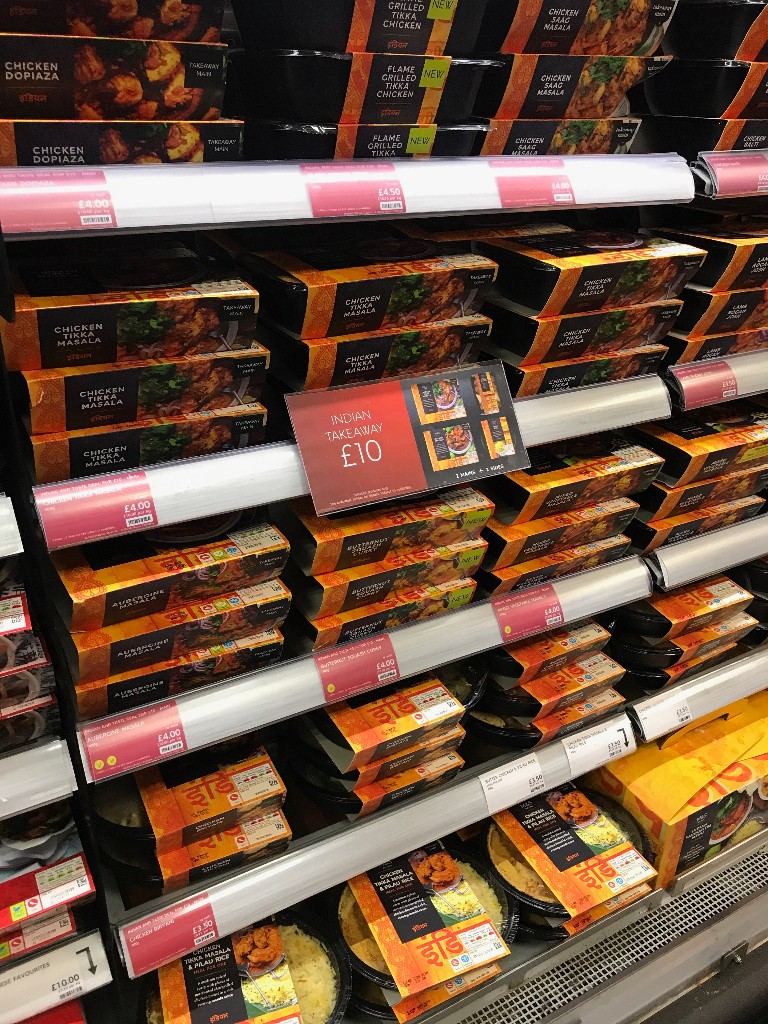
Trying to get the sales line moving in Food is challenging, they have 3/4 meal deals active (last week) and this causes numerous issues within the business.
1) Difficult for customers, who are then torn between the various deals.
2) Cannibalistic in their nature, meal deals are great but customers don't then buy anything else.
3) Waste impact, the margin takes a further hit as the stores have to supply every line to be relevant, but it's hard to forecast which lines will be picked up by customers and then, which deal will be the most popular when running multiple deals.
4) Value - any reductions applied to the products that are going out of date are then not eligible for the promotion, leading to potential issues with customers at the checkouts.
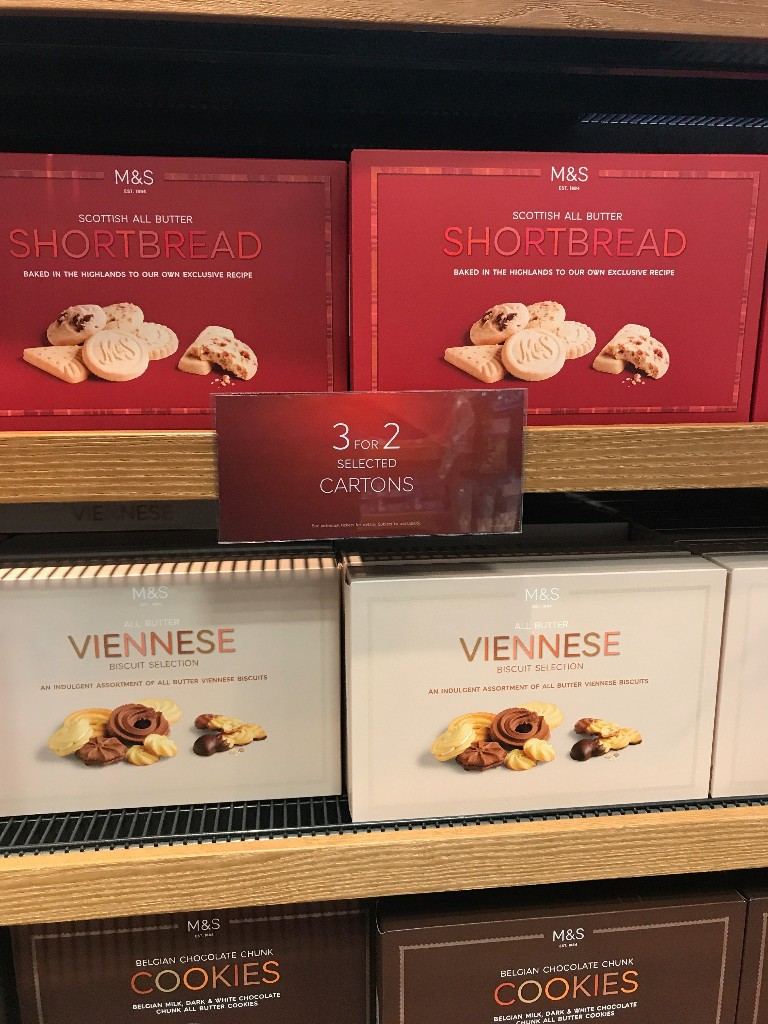
With deals around the store needing some consideration too, of course, M&S have a customer base and not everyone is counting every last penny.
But equally, 3 for 2 on Biscuits seems an excessive promotion and at worst, an expensive deal. Customers don't necessarily want to buy 2 to get a 3rd free.
Also 'Cartons' has little meaning beyond M&S......
So more to come this week, but a brief look at their newest store format, some nice touches but scalable? Hard to see.....
Also value remains a real conundrum for them, they are at the higher end of the market, with Waitrose. But unlike the last recession / slowdown, it won't be as easy for Waitrose or M&S this time.
The other players are doing a strong job in premium and own label, and just being a 'Waitrose' or 'M&S' isn't enough and differentiation alongside value is sorely needed.
Discounters get this, Morrisons are a good example of blending both value and their premium tier (The Best) well and becoming a mainstream alternative in the sector.
There is a fair amount of work ahead for M&S but nothing that can not be fixed, customers are feeling the pinch so M&S have to demonstrate value and blend quality in a genuine way......
Subscribe to this email newsletter service
From the Grocery Insight newsletter archive, first sent to subscribers on 26 February 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.