Tesco / Booker - High level overview (30 January 2017) [2]
30 January 2017
Subscribe to this service here.
Key points for the Tesco / Booker deal as I see them.... A further email will arrive shortly with a little more colour on the deal and the potential positives / negatives.
Arguably Booker weakness / areas for growth = Tesco strength
Online deliveries - have £1bn business but the logistics of the operation are far from efficient and with Tesco here, looks to be a good area to push on. Beyond poor punctuality / fulfilment scores.
Marketing / Loyalty - Allegedly poor back office systems means there is a wealth of data - 450k customers to interrogate and lock in. Grow synergies and build insights.
Further utilisation - Click / Collect sites are pushing into larger stores - many of these units are under utilised, one in central Bradford has been closed down, options to drive footfall here for secondary shop.
Online in general - basis of a good business but Tesco will want to roll together, dark store opportunity plus repurposing quieter stores for fulfilment / Click/Collect cash/carry looks likely.
Linking together the food / non food / large store offer will be noteworthy. Halo effect, drives traffic, utilise car parks etc.
Own label is the Lewis plan; so pushing the own label through more channels = higher volumes = lower buying price = better margins = lower prices for customers. Seen in core stores and now Express too...
Financial services - opportunities for credit facilities, payment via PayQwiq and likely also pushing PayQwiq via the independent sector too, thus growing share here. All linking insights.
Drive through click / collect is the future here and having the order loaded into the customer’s van / vehicle will be aided by Tesco with larger car parks to develop units etc. Utilising the 8k units for click/collect too.
Web - Each Booker centre has its own web page with the ability to order, communication about deals etc - Tesco with their renowned front end / back end IT will be able to improve this demonstrably.
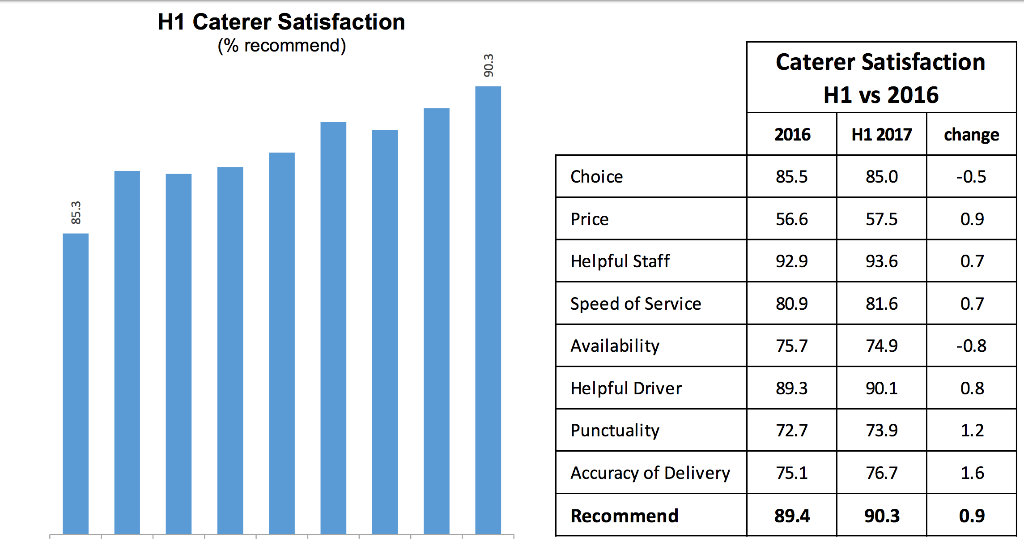
Metrics improvement - delivery satisfaction with Booker is very poor - Punctuality was rated at 73.9% in H12017. Availability was 74.9% and Accuracy of Delivery a mere 76.7%. Tesco will improve easily with .com experience.
Tesco weakness / opportunity is where Booker are strong
Food - Fresh foods particularly with the kitchen aspect / chef suppliers. Big focus on food service in Jumbo (Tesco mid/large store director is ex Jumbo) - could intersperse the two with their ‘innovation’ banner. Could well bring some better fresh ranges and innovation, linking Chef Direct / Butchery etc.
Space - Repurpose of space in some dead Exra’s with bulky cash / carry offer drives traffic, additional halo spend in core shop, plus Cash / Carry operation is space hungry. Colruyt inspired model perhaps? Discounter beater.
Footfall - Driving footfall to large Extra stores with customers buying professionally, then doing their shopping. Booker offer a real ‘pull’.
Offer - Tesco were prevented from doing cash/carry by the value crossover issues vs. core store. Operating Booker and Tesco will enable the business to run two distinctly different business units. Tertiary brands, crossover brands and drive value.
Convenience - Bit of both - Booker have a few banners that are broadly average, Budgens aside perhaps, but even then. One stop is low affluence base, enables Tesco to offer other fascias based on demographics. Could utilise.
Non Food - Booker customers will have a need for non food / kitchen / dining given food service - gives Tesco a chance to boost flagging non food business, locking customers in to more spending. Finance links etc.
There will be synergies in space - it’s clear. 230 sites are operated by Booker/Makro so any that are near larger Tesco outlets look to be potentially right sized and moved into the Tesco premises, at least some services at least.
Tesco are not renowned for food, and seem genuinely excited about the ‘leading food business’ that is being created. Having backed away from Giraffe et al, this move seems to make more sense.
Food service clients will be of interest for Tesco and the enlarged group will likely be very competitive in the space around price. However the leading brands like Prezzo are a mere £200m of their total catering business. The backbone is the core smaller catering outlets.
Despite progress, people are still unsure of Tesco around supplier agreements although huge strides have been made. Wholesaler relationship is broadly different so there will need to be some consideration for this, especially end pricing in convenience outlets. Premier outlets having to charge more than the local Express (competing retailer) despite being part of the same buying group could be interesting......
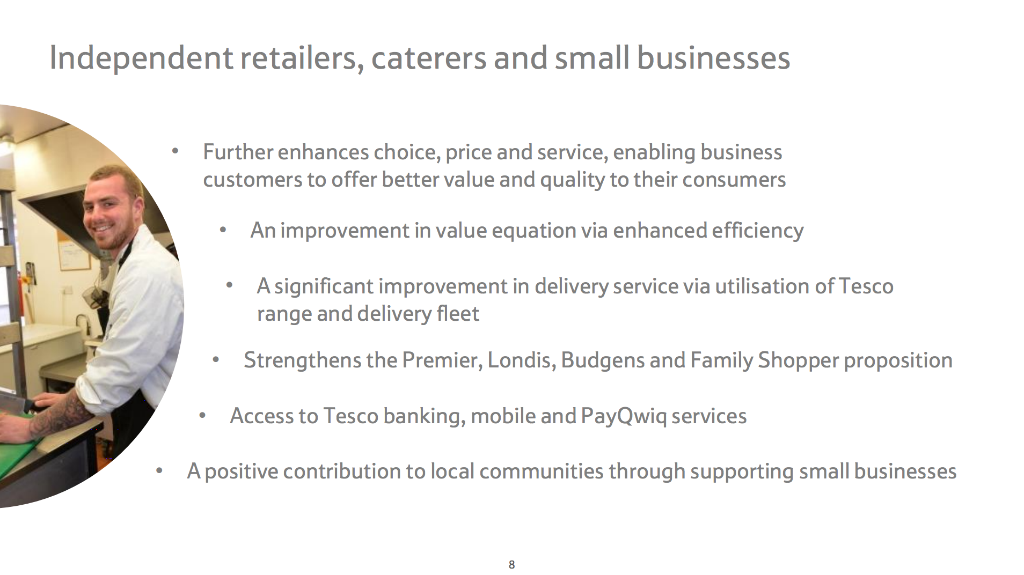
Notes on the proposition - highlighting improvements in delivery service, strengthening of the proposition for the franchisees - likely to be system based alongside marketing materials and some discipline around ranging and merchandising.
Also notable to see PayQwiq mentioned. The metrics for the Booker delivery service are below; availability, punctuality and accuracy of delivery are very disappointing.
Price also notable. Only 56% satisfied?
Notable other points
Non Exec Richard Cousins was so strongly against the move that he resigned, what does that indicate? Seriously unconvinced with the deal makeup or the Tesco recovery needs more time?
Tesco are a mere 18 months into their recovery plan and with volatile outlook in terms of inflation / consumer confidence - such a big play for a retailer already saddled with debt…. Numbers are good though on paper.
Charles Wilson staying on and joining Tesco and Exec brings some real clout to the board, Matt Davies is likely to be sidelined as a result with Wilson likely to be above him in the pecking order - a successor for Lewis?
Merger - would indicate a near 50/50% split, however Booker are a mere 16% of the new business. £49bn plays about £4bn. Takeover! But it’s a nod to the fact they’ll use a lot of know how in Booker and wider Tesco, not just a property deal a la Morrisons / Safeway.
Cost cutting remains in the core estate to attract the margin target, some stores are creaking, and this will be a concern and best people always taken for integration and various project teams..
Tesco cannot afford to take their eye off the ball in the UK..
Tesco recently closed distribution centres in the UK, they have a centre in Livingston but they will inherit a depot in the same area via Booker, alongside Booker sites in Haydock and Hatfield and the office in Wellingborough.
A major part of their business is catering, a point missed with the excitement over Wagamama and Prezzo. Nearly 500,000 customers within catering vs. only 125,000 retail customers and some average banners (Happy shopper etc) alongside some decent banners. (Budgens)
India remains important as a growth sector and Booker also have a presence here, whether this will grow further with the enlarged group / Tesco? More scale....
The core customers working with Booker will not necessarily want to remain with the enlarged group, so it will be interesting to see how those end clients view the relationship. M&S e.g.
PayQwiq payment has rolled out to all Tesco stores - the potential to roll to their 8,000 independents in the enlarged group is intriguing. Locks in Clubcard automatically which drives insight gathering and thus targeting / lock in / full offer.
Noteworthy mention of fresh food brands by Tesco in bid docs, whilst they have performed well in the Meat category / Produce category for Tesco, they have had the impact of deflating the category significantly.
Could they work on a core stable of products for the lower demographic convenience banners to take on discounters? Aldi/Lidl pop up all over and will threaten the independent like everyone else does.
Will shake up the wider independent convenience sector - the larger groups particularly will be concerned - Costcutter / Nisa / Spar etc, not renowned for great stores as it is.
Free membership for the Booker customer as things stand, although they have to be a business / charity - will that remain in future? Will there be a paid model for core customers non business? Opens up larger packs / better value? Prime esque?
The Future?
Perhaps they can leverage an Amazon Prime / Costco style offer - bringing benefits of membership for Booker with a linking for free deliveries / reduced cost deliveries / quicker deliveries with Tesco / Booker etc.
Innovation is noted; we know that Booker do a good job in food service, so it would allow appropriate innovation in fresh foods for Tesco stores - driving sales for professional customers.
Franchise is the new online / convenience; growth channel and One Stop is performing well for Tesco. Conversion to any of these fascias’s for existing independents looks possible. Big operator in the space.
Same day deliveries are possible on a greater scale; Booker were trailing this at Norwich in any case.
The Competition authority will likely have a significant input to the future make up of the wider chain, there are numerous trust / competition issues around supply and Tesco control of the wider market, particularly convenience.
Whilst there isn't any stores physically owned by Booker in the space, they are a big player with franchise and supply.
Clear focus on fresh foods and own label - the driver for the deal. Continual refinement of their virtuous circle.
More farm / food brands possible? A stable of brands developed for independents would enhance volumes to integrate into the main estate to continue to put pressure on discounters.
Hub/Spoke model - Booker to supply local Tesco with Meat / Fish etc which would reduce cost base and enhance freshness if used with Chef Direct etc.
From the Grocery Insight newsletter archive, first sent to subscribers on 30 January 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.