A brief interlude 2 - Tesco 'brands' and pricing (17 May 2018) [4]
17 May 2018

A sample subscriber email:
This was sent out to subscribers today.
This note is typical of our content and imagery.
The sector is changing all the time and store based insight is vital.
New subscribers are able to benefit from a reduction in price if signing up to the service today.
The market place is incredibly competitive and for agencies and those in the 'shopper' space. It is crucial that the market is watched, continually, for signs of retailer activity and changing behaviour as a result of their strategy, or competitive pressures.
Everyone is talking about tech and online taking over the world, but customers are still using stores in a huge way and that shows no signs of slowing down. Discounters have come to the fore in the last 7 or 8 years and that has spelt bad news for the larger retailers.
It has also hurt the brands doubly, not only are the discounters able to imitate leading products easily and sell these cheaply, they have also taken sales and share from large supermarkets who are the brands biggest customers.
How to remain relevant? What works well elsewhere? Who is developing best practise in retail and what works / doesn't work for customers? Our service covers all manner of angles in the sector and our store visit based work means we generate truly unique perspectives to provoke thought and challenge convention.
The combination of Sainsbury's / Asda will change the landscape more than Tesco and Booker, which itself kicked off mergers / acquisitions with the Co-Operative & Nisa & Costcutter within two years.
Sainsbury's / Asda makes sense on paper but there is a layer deeper that needs analysing, what about the respective companies beyond the high level consideration. Where else will savings be made? What does it realistically mean for customers? For agencies and marketeers? For brands? Can the merged organisation really use combined best terms overnight and immediately bank synergies without the Groceries adjudicator becoming involved?
Keeping abreast of the market movement at the same time is a difficult task anyway, there are two businesses who need to trade alongside the wider market movements such as Tesco putting their products in to Booker and vice versa. Morrisons continue with their recovery and discounters continue to expand into new territories in the UK and capture share from the likes of Waitrose.
Utilise our service to keep abreast of the market via stores and use our unique perspective from these store visits and extensive market knowledge to play a part in your wider decision making.
Please click the buttons below to sign up and benefit from this service at a super low price.
Just £497 for 12 months. Pay by card?
Just £497 for 12 months - Pay by invoice?
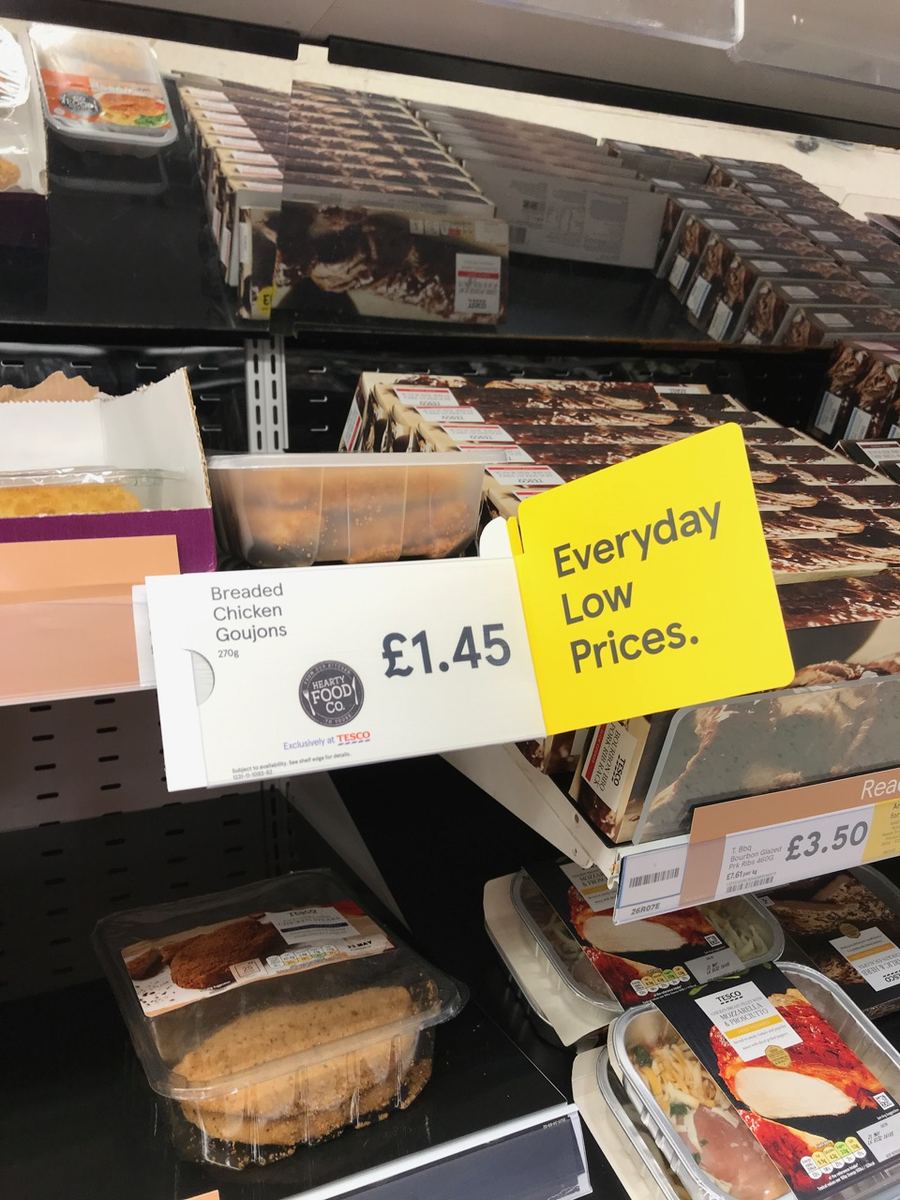
The push to change value tire products to something resembling a 'discounter style' brand a la Sir Terry many moons ago is gaining traction at Tesco.
Amongst the many strengths of Dave Lewis, he is a brand builder and the decision to bring in Farm brands, despite the negative PR, proved the business case for this expanding to a wider audience and the fignht against discounters.
There is little defence from a discounter other than them comparing themselves to branded products in stores / on advertising. Whereas Tesco can merrily bring in these discounter equivalent products and add them at the entry level, replacing value at a competitive price point vs. discount.
Own label is then cheaper than it ever was in Tesco and often, placed attractively at eye level or similar in the fixture which means customers see these products before the brands. All of which are underpinned by the price guarantee.
There has been a fair amount of investment in the pricing at Tesco across the time since Dave Lewis took over, but their (understated) work at the shelf edge has often been missed entirely.
So, as we move to these brands that are being introduced under their own steam, replacing everyday value across the store.
Just £497 for 12 months - Pay by invoice?
We offer expert, in person briefings on the Sainsbury's / Asda merger.
Just £497 for 12 months. Pay by card?
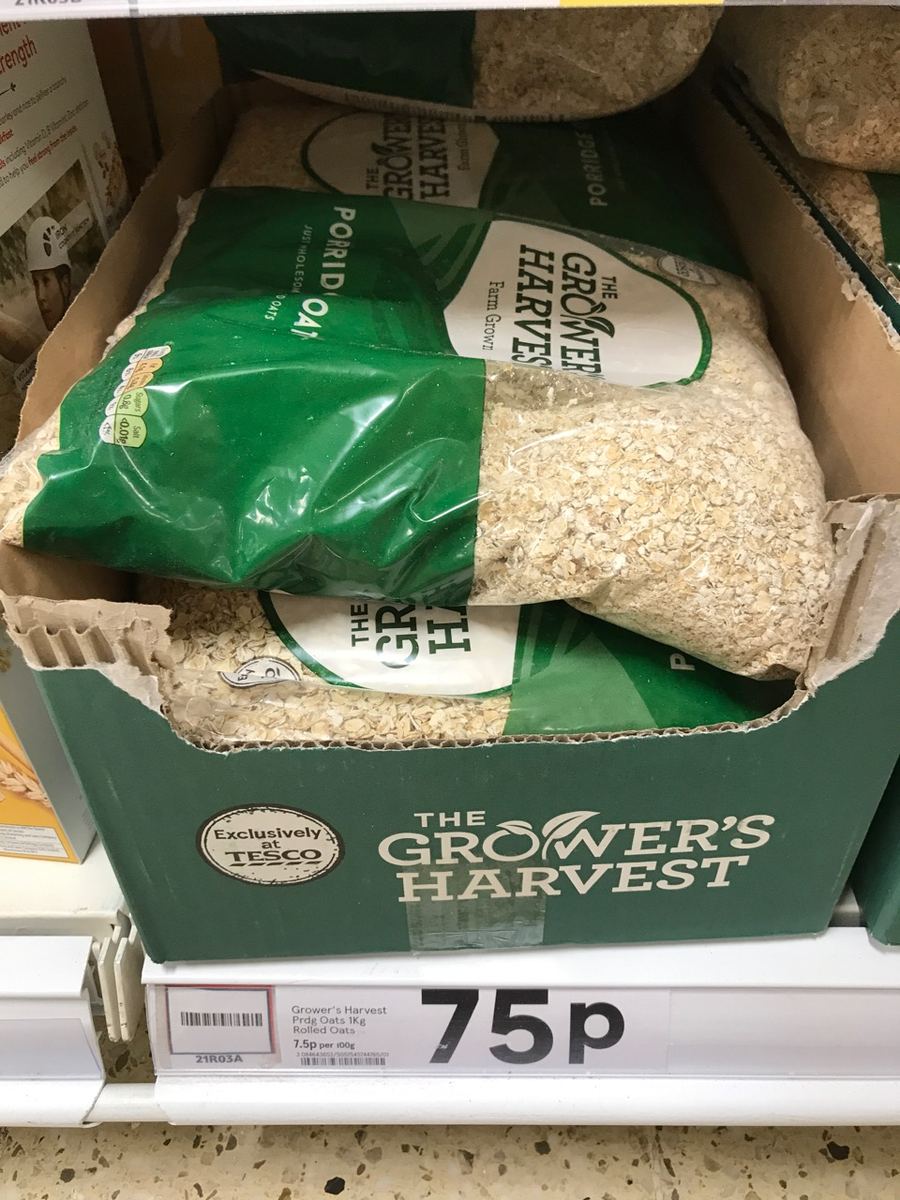
Grower's harvest is the latest addition to the stable, with a presence in Cereals (Oats) and also over in Frozen Foods too. Not to mention the other brands covered in the past, like HW Nevill's Bread and the 'farms' themselves.
So in terms of the price cuts, activity has been fierce in the sector with Sainsbury's having two goes at price cuts on Meat and Fish, Asda landing their Rolled Back / Staying Back activity and Morrisons launching their 'wonky' Fruit and Veg too.
Therefore the cuts at Tesco are potentially partly a reaction / reaffirmation of their credentials in this space, alongside a focus on highlighting their value at the shelf edge on these brands. 'Exclusive to Tesco' after all.
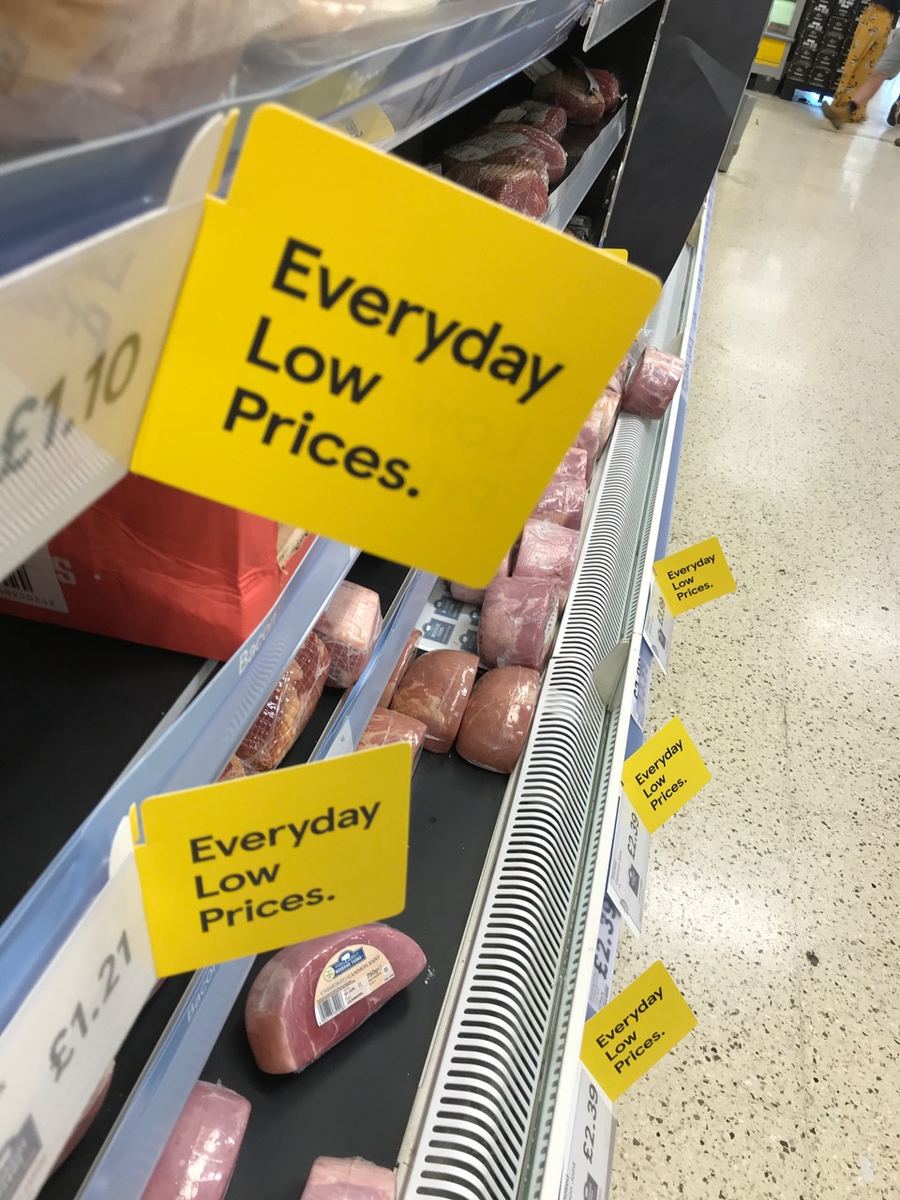
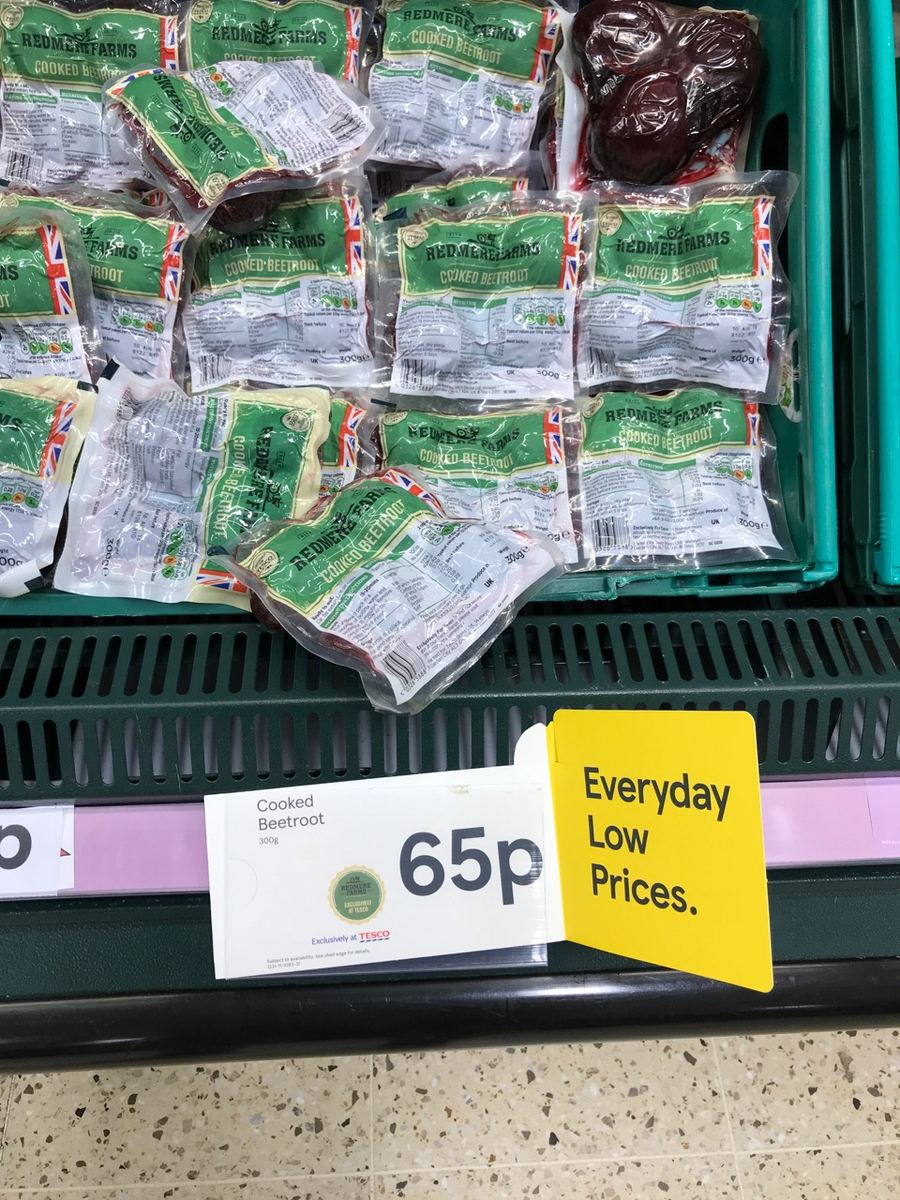
The signage itself showcases 'everyday low prices' and makes no mention of a cross out price, so can we assume that these lines generally track discounters and drop accordingly? There have been times before where Tesco have dropped the price of some Meat lines lower than the price marked on pack to compete elsewhere.
Just £497 for 12 months. Pay by card?
Just £497 for 12 months - Pay by invoice?
Just £497 for 12 months. Pay by card?
Just £497 for 12 months - Pay by invoice?
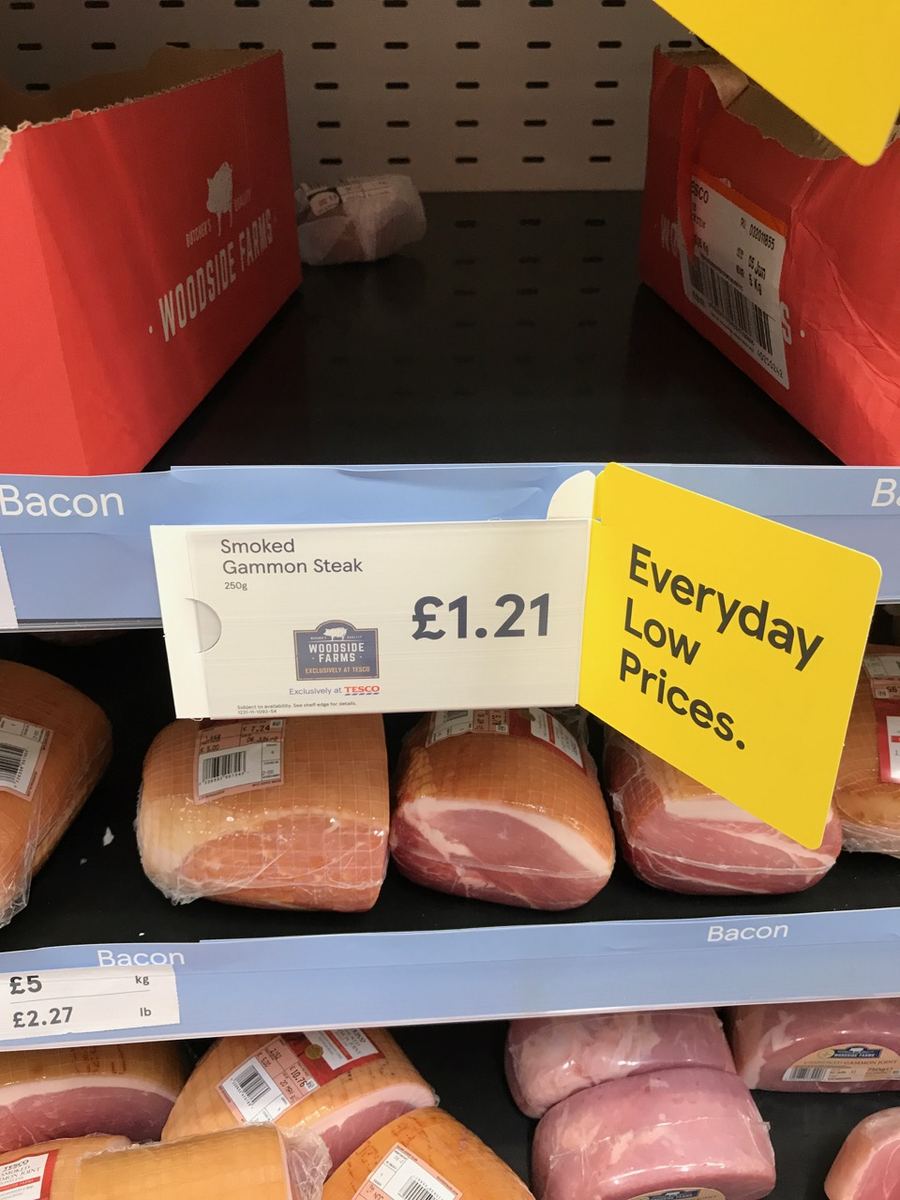
Clear signage highlights these prices, and the usage of the brands and the 'exclusive' moniker is notable.
Very effective and a shot across the bows at discount who label their 'exclusive to Aldi/Lidl' brands when comparing with Fairy and whoever else in the mainstream.
Just £497 for 12 months. Pay by card?
Just £497 for 12 months - Pay by invoice?
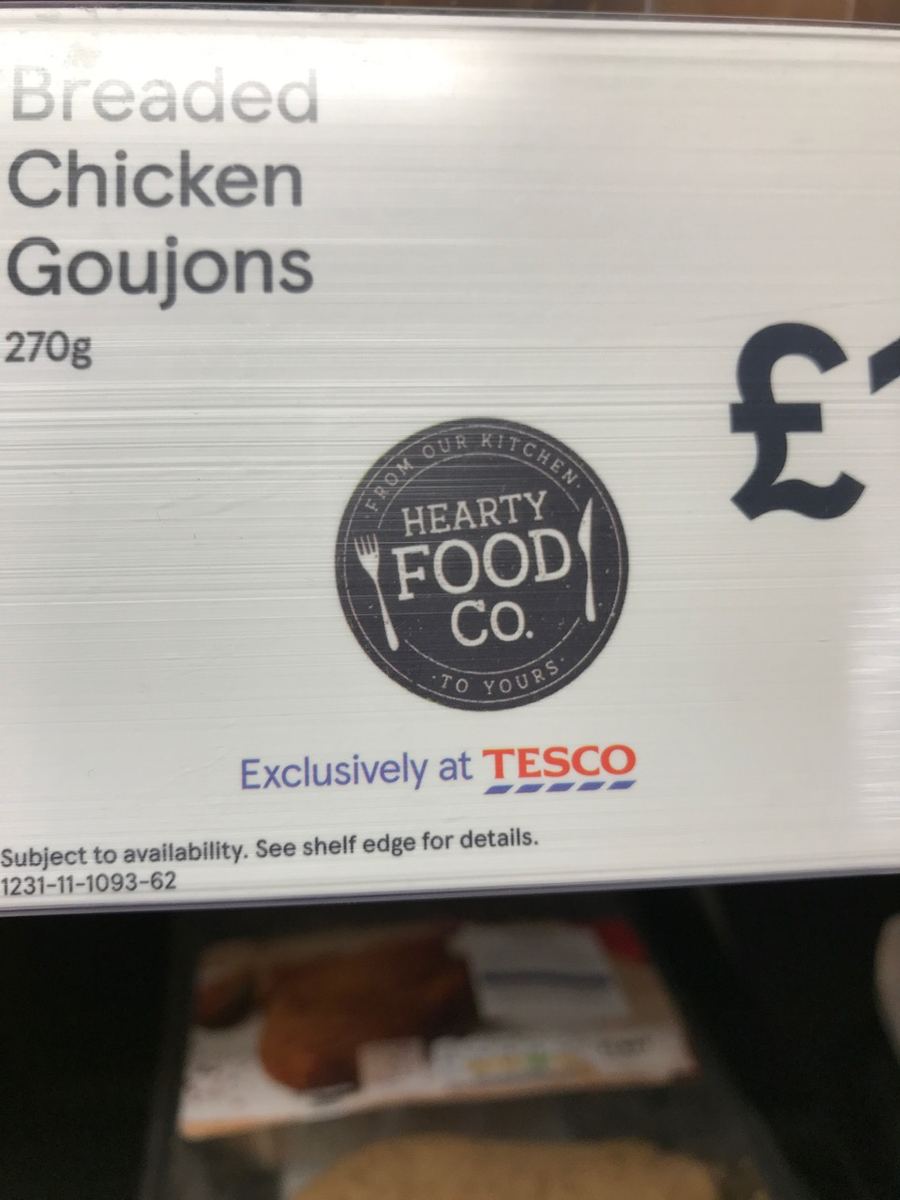
Unusually for Tesco, the execution of said labels wasn't as sharp as expected. A rush job? Or just an oversight by the office, not thinking about the end user?
Just £497 for 12 months - Pay by invoice?
Just £497 for 12 months. Pay by card?
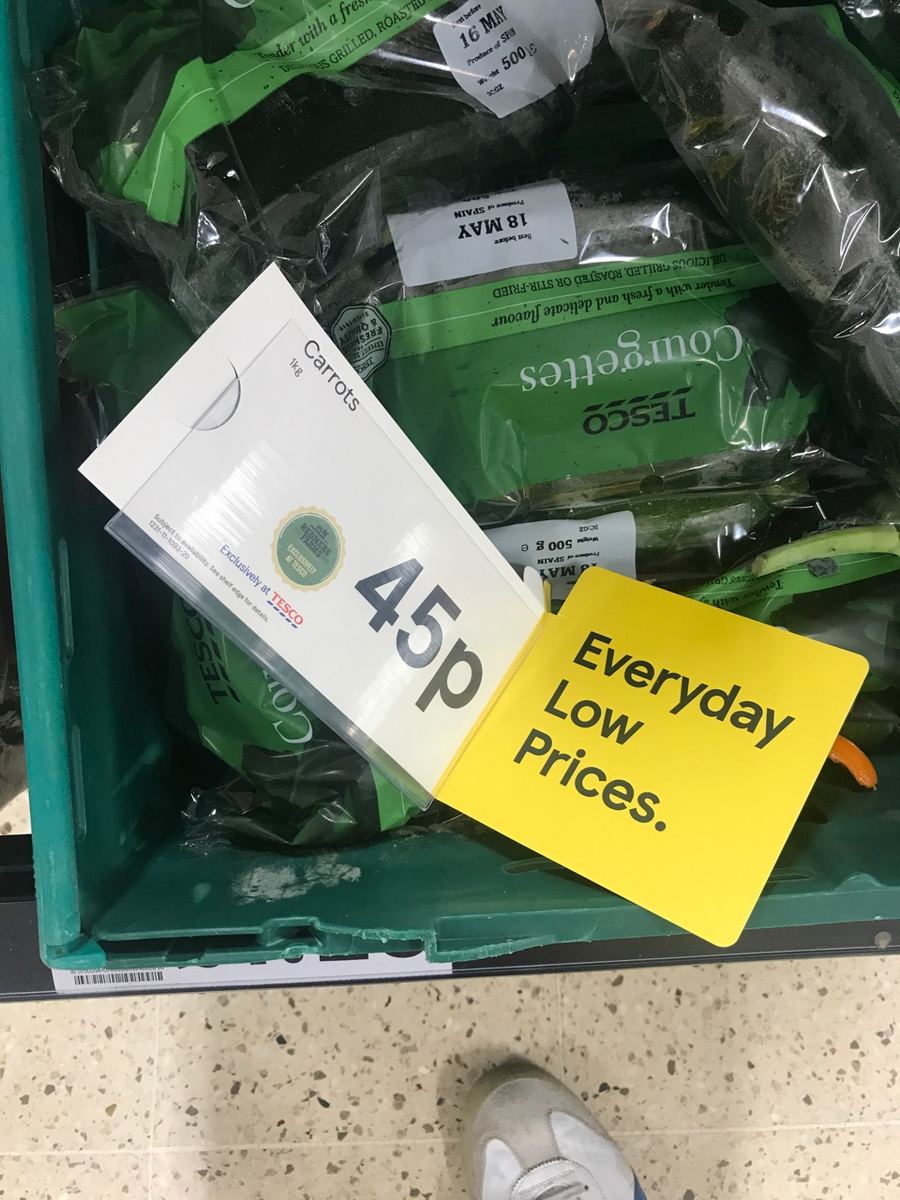
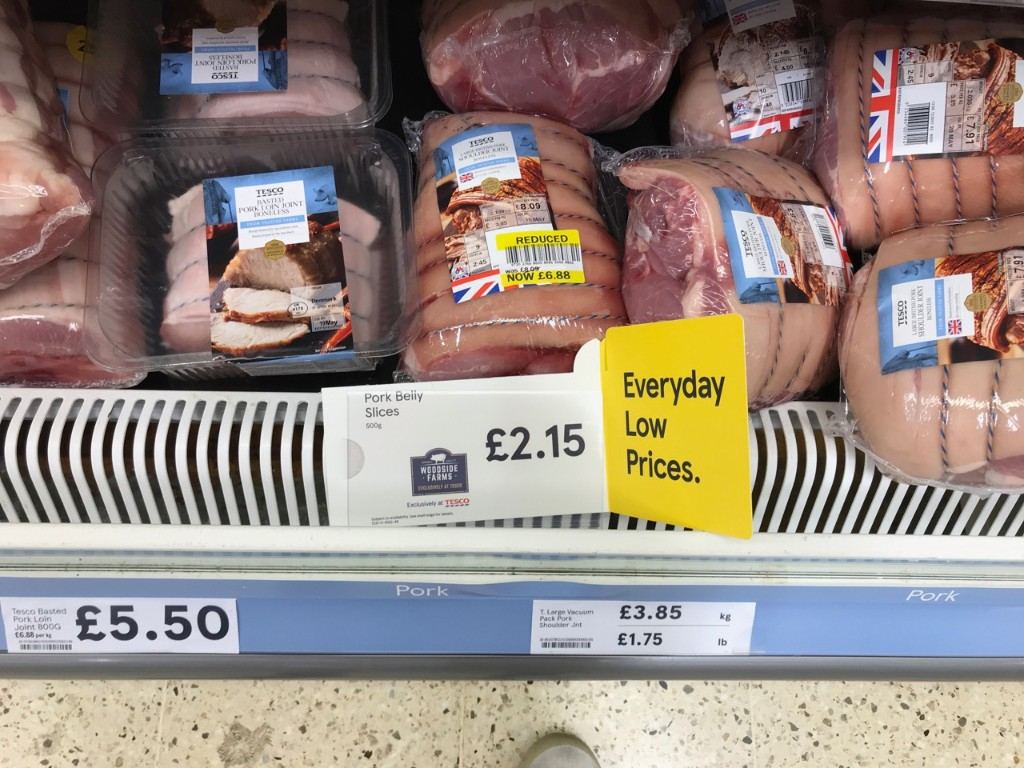
Not great examples of usage here, given two signs were not attached to the shelf edge. Never a good sign... Meat is a category that receives frequent visits from customers so the trade levels being high mean there's a lot of disruption and signs do get knocked around.
Just £497 for 12 months - Pay by invoice?
Just £497 for 12 months. Pay by card?
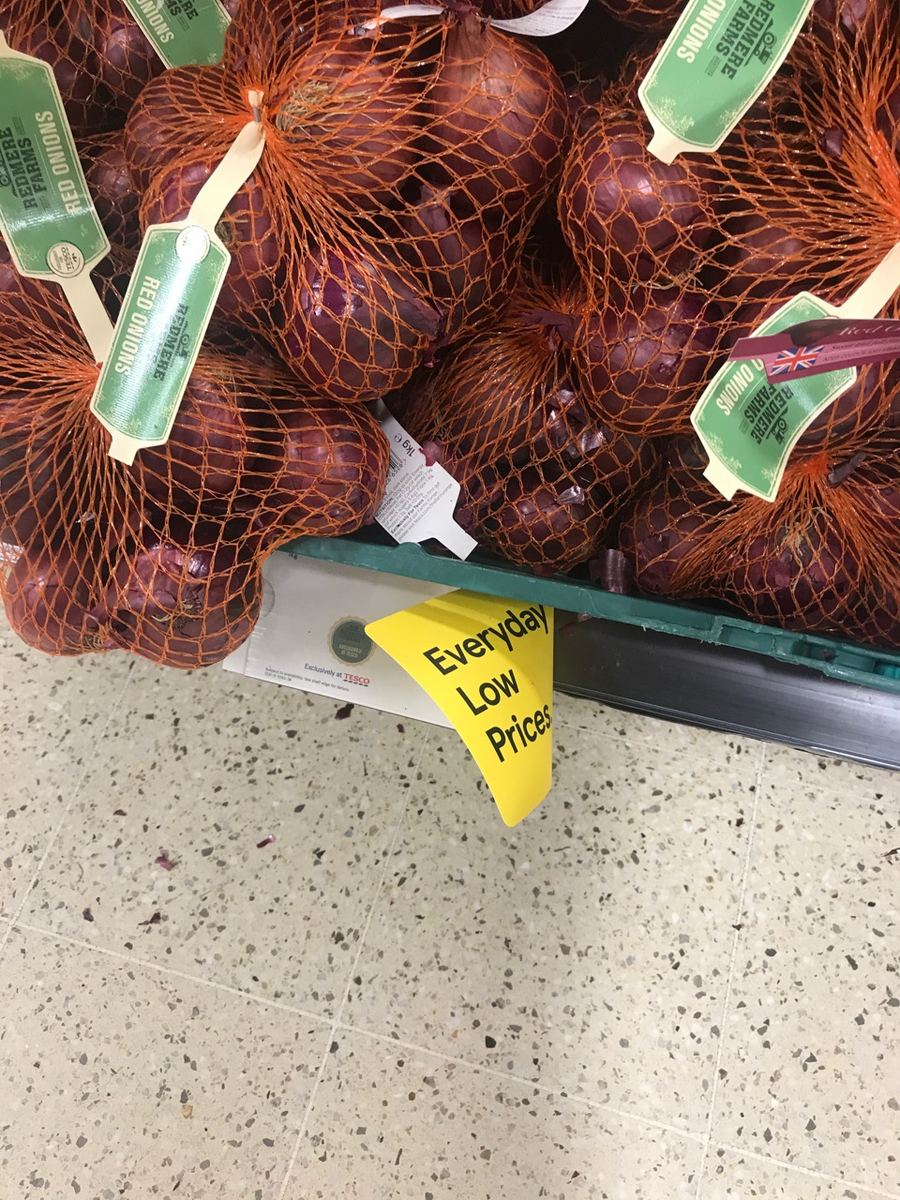
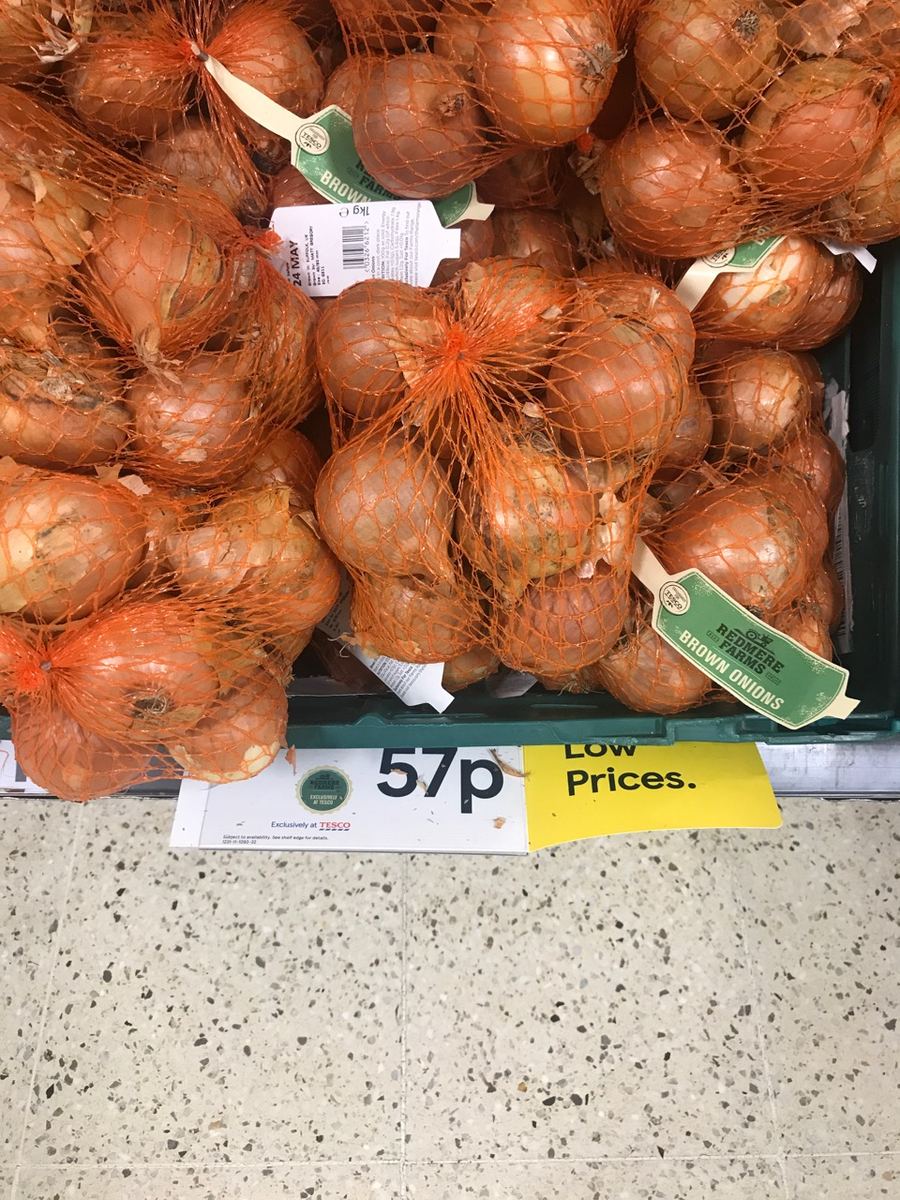
Produce fared no better with signs entirely obscured by the bulk stacking of crates themselves.
The decision to use the same signage on both Meat and Produce was flawed from the start, given the difference in the category operation.
Produce is robust, things have to be durable given heavy crates of Potatoes, onions and other lines are thrown on top and the department is continually merchandised and 'shopped'.
Therefore the signage choice meant that the message was missed by some customers, especially since there wasn't a 'cross out' price on a label to highlight a price cut.
Food for thought as ever! Retail is always in the execution at the shelf edge. Whatever the well meaning intention from head office looks like.....
Just £497 for 12 months. Pay by card?
Just £497 for 12 months - Pay by invoice?
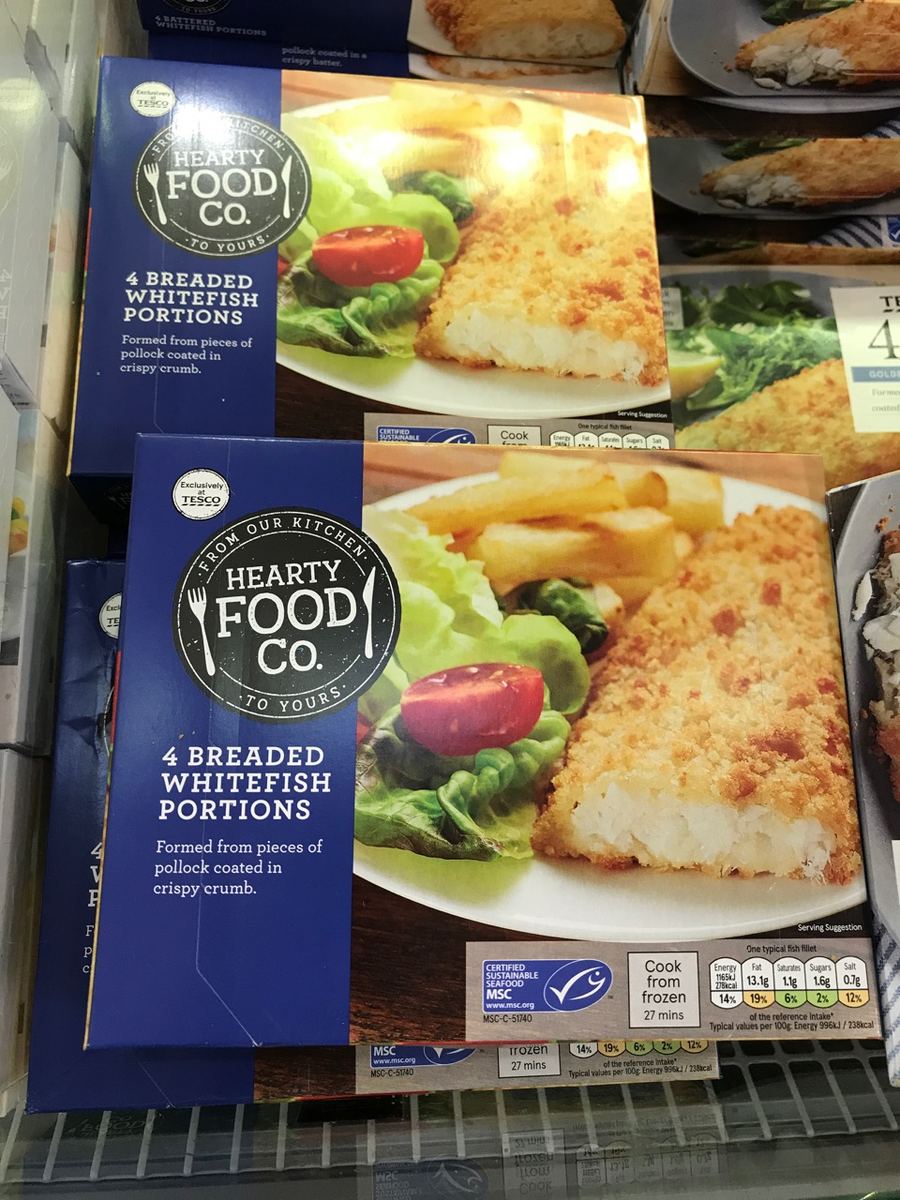
So it looks like a deliberate piece of work from Tesco, replacing their Value tier products with the 'exclusive' Tesco brand.
It works well against discounters, who operate the same principles with their core tier and the prices are near equivalent in some cases too.
Naturally it's a deflationary move by Tesco, making cheaper lines look better means customers could be attracted to 'trade down' to the cheaper product thus impacting revenues.
However if the volume swing comes, meaning more customers buy the value tier equivalent then the sums can work out. However that's harder work and means that the store is replenishing more frequently if the space isn't aligned to sales.
The end game could be that the mid tier disappears in Frozen Fish e.g. and the value tier becomes the 'main' own label offering. However that's a longer term play for sure.
What is more important is the sense of 'winning together' as one.
If the Meat, Fish and Frozen buyer takes a hit in their respective categories, deflating themselves with lower priced, value equivalent lines packaged to look better and more attractive versus mid tier lines but that means that a customer switches their entire shop to Tesco as a result.
That's a better net result for the wider business, as the margin can be regained elsewhere and Tesco takes a greater share of the wallet so to speak. This is where Clubcard, brand guarantee and other initiatives then come in to their own.
At least that is the intention, but the reality at the shelf edge remains the case that Tesco are doing the right thing by customers and that's evidenced by their margin recovery alongside their ongoing improvements to market share and profitability.
An impressive set of results for Dave Lewis and co, 3 years in. However when you look 'under the bonnet' with examples like this, their work can only be applauded for it's 'disruption' versus the norms we are used to in planograms and own label focus.
Ongoing work with Booker is of key interest going forward and it remains to be seen what the future is for these 'exclusive' brands in that format too.
Next up! We have more on the Asda / Sainsbury's bid as we dissect the bid documents themselves before a focus on Asda and Sainsbury's in isolation and what the deal means for both, and the wider market too.
Just £497 for 12 months. Pay by card?
Just £497 for 12 months - Pay by invoice?
From the Grocery Insight newsletter archive, first sent to subscribers on 17 May 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.