A brief interlude - More brands from Tesco
8 May 2018

Subscribe to our email newsletter service
We offer in depth briefings on Asda, Sainsbury's & the deal.
To summarise:
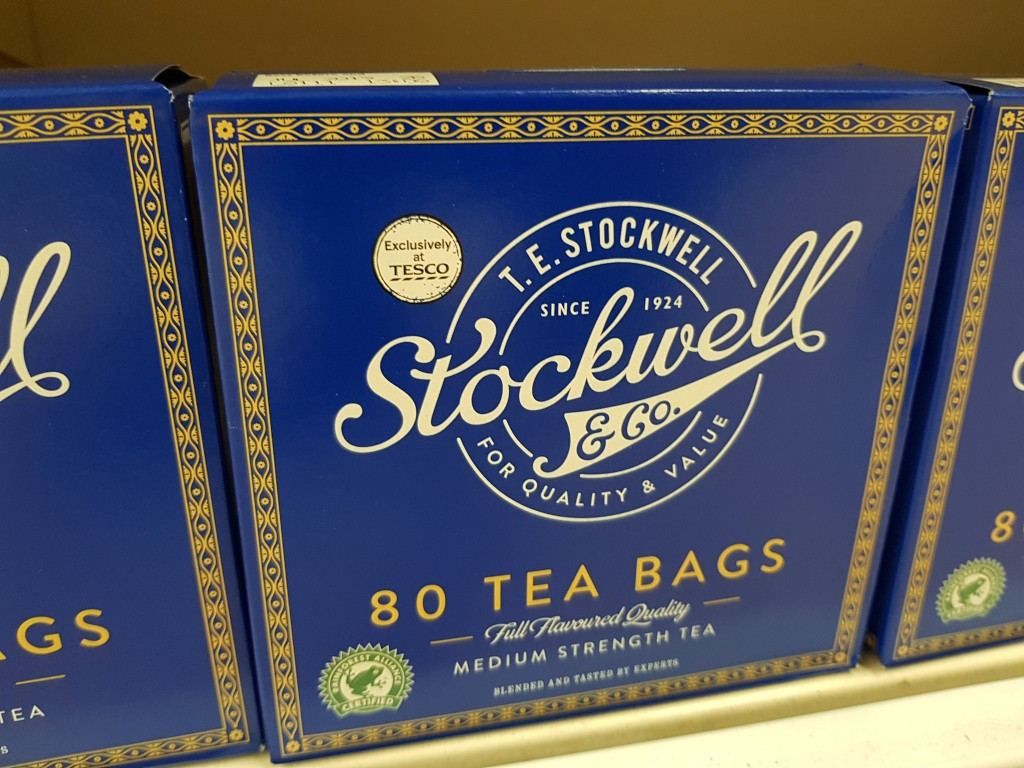
Tesco have launched another new 'value sub brand'.
"TE Stockwell" brand taps in to the heritage of the chain.
Noted on Tea so far but further roll out is likely.
The latest in the Dave Lewis strategy to launch Tesco 'brands'.
On the huge list of things that Dave Lewis has done with Tesco, one of the most divisive things (but arguably one of the most positive, long term) was the introduction of 'Farm' / Fresh Food brands in to Produce and Meat, replacing the 'Everyday value' tier in those categories.
The challenge with Value is that any comparative between that and the Aldi own label (mid tier brand equivalent) is blown out of the water, Aldi and Lidl pitch their product against the leading brand quite happily on signage and win awards regardless. Leaving value looking a bit poor all considered.
I blame the FMCG brands for the rise of discount as much as the supermarkets of that time to be honest. They've not done enough on their own brands to differentiate.
It's quite ironic that Tesco are landing their TE Stockwell brand of own label Tea, replacing Value within the same week where both Andrew Higginson and Sir Terry Leahy discussed the 'regime' of Phil Clarke where Clarke essentially drove the Tesco bus off the cliff.
Sir Terry and co landed discounter brands way back in 2007/2008 as the recession took hold and Tesco focused on Clubcard, discounter brands (to imitate Aldi/Lidl and block any price challenges) alongside a move to highlight Finest to appeal to customers staying in to reduce spending.
Certainly ahead of time but the promotional strategy was still focused on deals and was less about EDLP. However the market had not yet moved to this wider price mentality either. However, it was certainly a better strategy than Clarke's 'let's load up the Watford (and other) stores with numerous concessions'.....
"Also, why don't we, a leading supermarket, create an Android tablet?"
Sometimes...... You have to shake your head.
Anyway, Dave Lewis came in, took stock and proceeded to resolve a number of things in the first year or so and then looked at the switching data from Kantar one presumes, realising that two own label dominant categories were seeing huge growth in discount as everyone was being hammered for price and the quality message.
Both Produce and Meat saw huge numbers of customers switch out of main supermarkets and in to discounters; indeed the biggest piece of feedback when people visited discounters was that customers loved the simple, low prices of the Meat / Produce versus other supermarkets.
Whereas if you consider Apples are Apples and customers view these products as being exactly the same.... However they were significantly cheaper in discounters (quality also equivalent)...
Then as a Tesco, or whoever, you have a real issue as it doesn't take long for customers to then try other products in the range at discounters.
The value tier has somewhat of a stigma in stores, however it is a flag bearer for customers who are on incredibly tight budgets.
It isn't aspirational but a number of customers will opt to buy certain products from the range to save money, especially families. Jaffa Cakes are a good example, Rice Pudding another (indeed Aldi brought in a value tier to compete with 13p tins of value Rice Pudding elsewhere.
But you can't build a business on this range and customers were/are decamping to Aldi and Lidl to save money on 'core' groceries rather than having to buy value products where the range can be quite limited.
So farm brands (later called Fresh Food brands) were born, whilst the names of fictional farms caused upset and confusion (with some folk, allegedly). The underlying reason of these brands was to enable Tesco to provide value and Aldi/Lidl equivalent products and prices without undermining their own offer.
It would have never worked with an expansion of the Everyday value tier, as the range doesn't speak about quality, despite being perfectly acceptable product.
Therefore sub brands were born and it was the first real step towards any element of a fightback from Tesco, and the rest of the retail market versus discounters.
We have seen further sub brands that replace value in Produce, such as Sainsbury's Greengrocer selection and Morrisons landing Wonky (a Value / Food waste play).
Asda imitated the Tesco move entirely with Farm stores range replacing their Smartprice tier in Produce and Meat entirely.
It doesn't come without risk as the move by Tesco is deflationary as you are making the entry level tier look better, it's lower price so the mid tier struggles to be relevant. Not great for the buyer!
But great for volumes and crucially, great for Tesco as the customer is more inclined to spend more with the wider store. Everyone wins together.
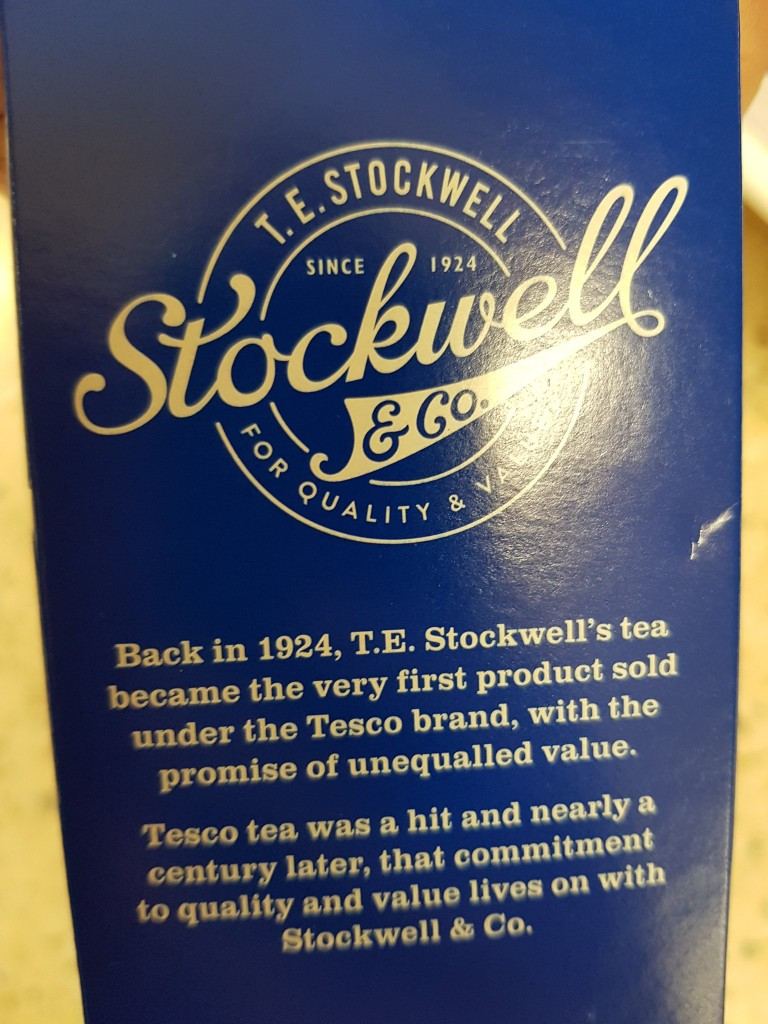
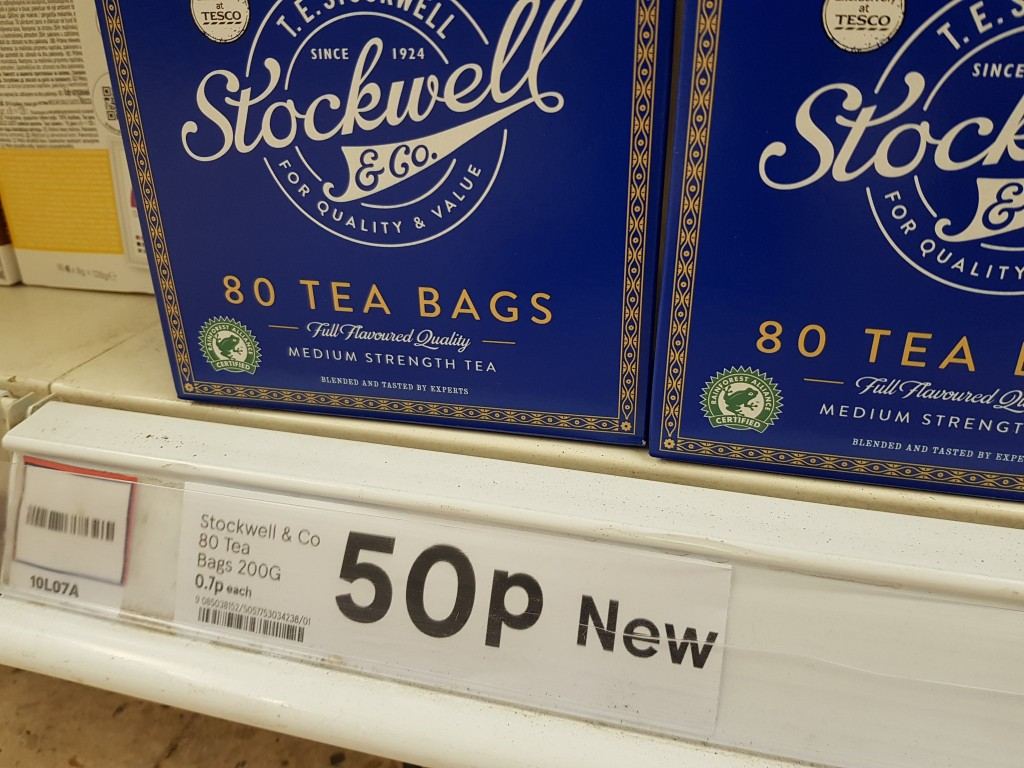
So for the Tea - TE Stockwell uses the historic heritage of the Tesco brand, the founder back in 1924 no less. The first product sold under the Tesco brand and now replacing the value tier Tea in store.
Stockwell & Co does sound rather ubiquitous though, with more products presumably in the pipeline. We have seen another "heritage" style brand in Bread H.W Nevills replacing value too.
Both do a good job of imitating an Aldi product whilst being cheaper, how do Aldi or Lidl defend against it? Hard to do so one would suspect, given their focus on the brands further up the chain.
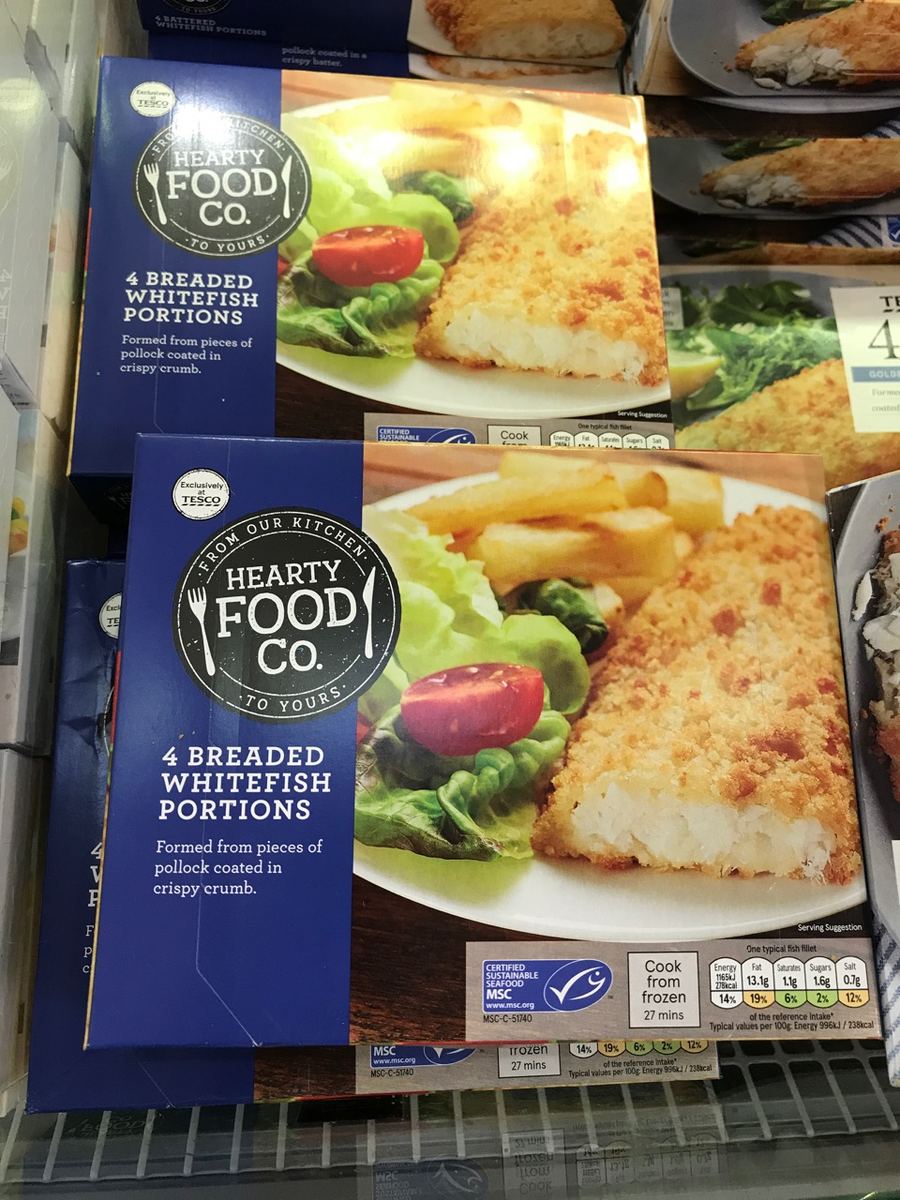
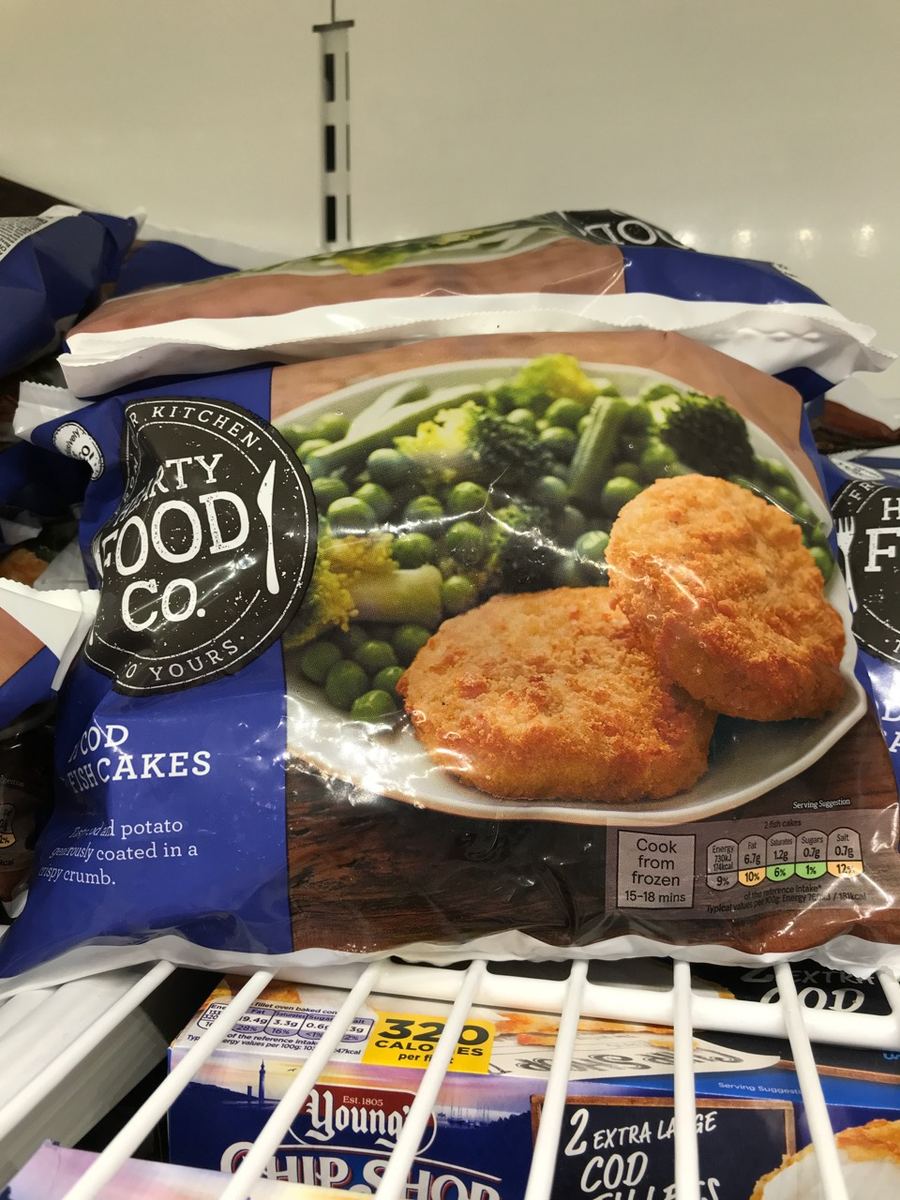
Hearty Food co has been another brand that's appeared across Poultry, Frozen Fish and Cooking sauces, replacing the value tier products in these categories.
They look better and more rounded on shelf than their Value equivalents and as brand building exercises, they are certainly useful in growing loyalty within Tesco.
The loyalty data shows customers who buy these products are value focused and likely ones who visit discounters. If those customers buy more of these products, or regularly buy value in other areas then it makes sense for Tesco to expand this new brand strategy to other areas too.
It's an impressive piece of work, especially in Tea where value will never get people banging the door down for the product, but the TE Stockwell brand could well drive some loyalty, at a low price and also, look to fend Aldi off with a decent price gap too.
There is more of this around in the industry and we'll take a closer look at these examples in the coming weeks.
It's quite a subtle way of taking on discounters now the majority have shored up their price positioning and reduced their overall reliance on deal as a sole way to provide value for customers.
Subscribe to our email newsletter service
We offer in depth reporting and briefings on Asda / Sainsbury's?
From the Grocery Insight newsletter archive, first sent to subscribers on 8 May 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.