Toy wars
26 October 2016
Halloween is upon us and the golden quarter really earns the moniker in the next 10 days with Halloween into Bonfire night then flowing directly into the run up to Christmas, and my birthday.
That aside, Toys has become a fierce old battle this year, it is most years to be fair but the acquisition of Argos by Sainsbury's has clearly woken Tesco up. Having resolved their issues in food, they are now presumably set to recover margin by focusing on non food a little more.
However their move to remove click / collect charges is an admission that the tactic hasn't really worked. Volumes fell significantly, with results at the half year showing a -12% decline in online clothing / GM which is likely due to the introduction of the C&C charge.
Waitrose and John Lewis can justify £2 given that John Lewis may not be nearby - £2 charge under £30 order is easily worth it.
However for Tesco, with larger stores everywhere - not so much. Plus Asda don't charge and carry a similar range in any case... So it was essentially akin to punching yourself in the face, Tesco Express stores will be overwhelmed with parcels once more.
In terms of Toys; Tesco chose to run a toy event in September/October time encouraging early customers to spend now to get things for Christmas. Decent package in the seasonal aisle and Mrs D with her amazon app (scanning barcodes to judge the prices) found two lines cheaper than Amazon - so purchased.
With the continued focus on toys, and indeed the Argos/JS deal which does worry Tesco given the overlap in stores and the strengthening of the wider Sainsbury's non food offer that Argos brings too, they're having a go in Toys once more.
Sainsbury's are already strong with their non food offer, having developed a compelling offer which Habitat will complement very nicely. The Argos deal will extend the click/collect opportunities and also drive footfall to stores as the Argos shops roll into the Sainsbury's estate.
The question around who is a classic Argos shopper? Would they then shop at Sainsbury's? is a very fair one. Argos is used by numerous backgrounds and demographics, not necessarily a core Sainsbury's customer but the intention will be to drop Argos into JS, then pick up secondary footfall if customers are already in store at Argos.
Given that for years, the expectation was that Asda would buy the wider Homebase/Argos chain - it was seen as a 'good fit' perhaps gives lead to the core customer that Argos attracts. However that isn't to say that Argos is all for value driven customers, it attracts numerous folk due to the ease of shopping.
In terms of the Toys, Argos typically do a big 3 for 2 extravaganza on toys which they've yet to do, although Sainsbury's have attacked toys in a major way this year.
Their event was always sharp in the early days when they first introduced it, big brand toys were half price and customers flocked in. However in recent years it's been watered down a bit and not featured the brands, or the savings that it once did.
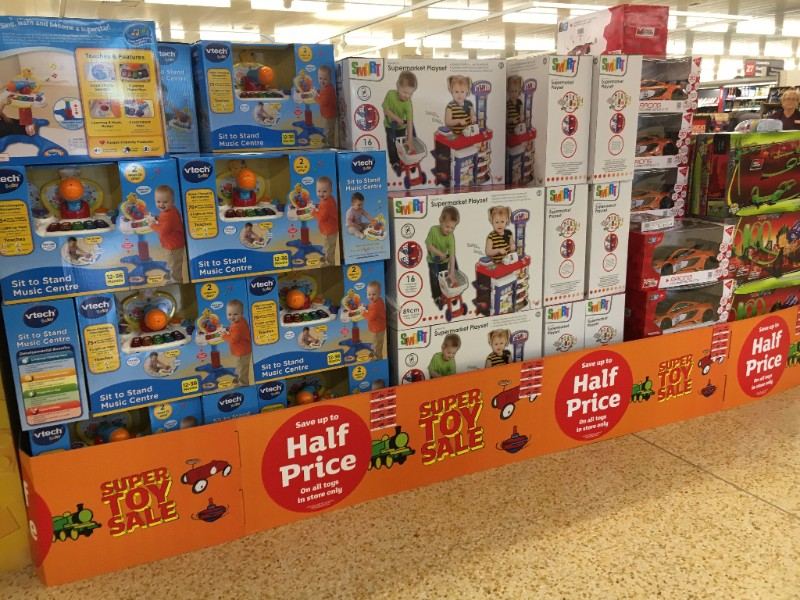
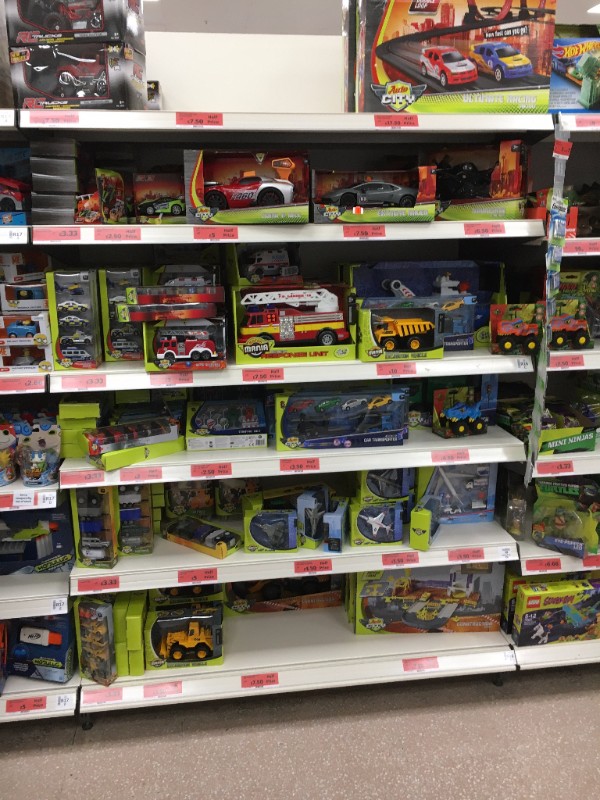
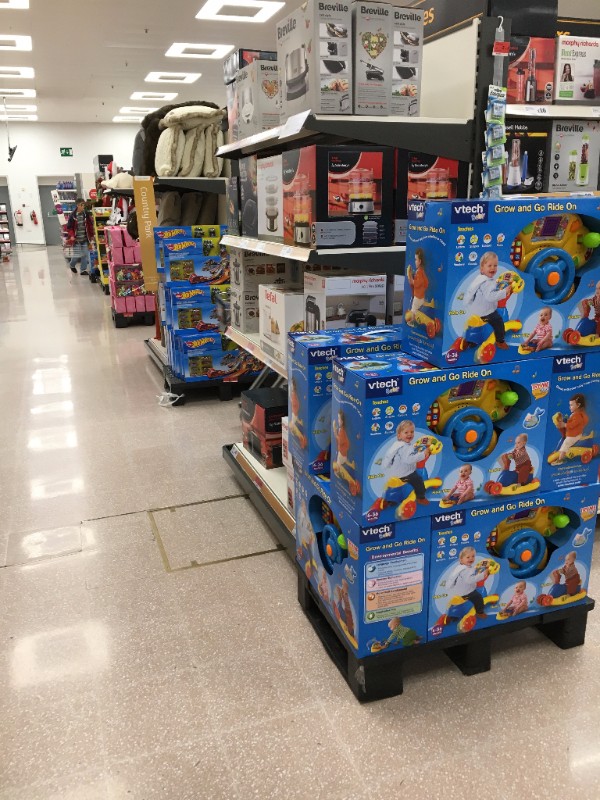
This year was a different story with the entire range on some sort of deal, it was marketed in a big way to the half price event, but most lines were 'up to' which saw Lego at 20% off for example.
Not that it stopped customers, with long queues down the aisle to view two ends in one store, with toys being taken from delivery cages as they hit the shop floor.
Sainsbury's usually trade their shop floor clean, with very few shippers and additional sites for products around the store. For the event there were numerous stacks of toys around the store which enabled customers to pick up impulse buys and not be restricted to one / two aisles.
The core aisle itself featured every line on some sort of discount too, customers will buy their toys 'once' for Christmas. So capturing spend at the right time is all important given there are varying levels to when customers are able to spend for Christmas.
Tesco perhaps went a little too early with their event, social media changes the game entirely as sites like Hot UK Deals carried the entire range and price points for Sainsbury's ahead of the event to build interest. (leaked unofficially it appears).
Customers are savvy anyway, but always know when events are due and who may / may not have run their event yet. It's likely customers knew that the Sainsbury's event was due and held spending until they had a look there.
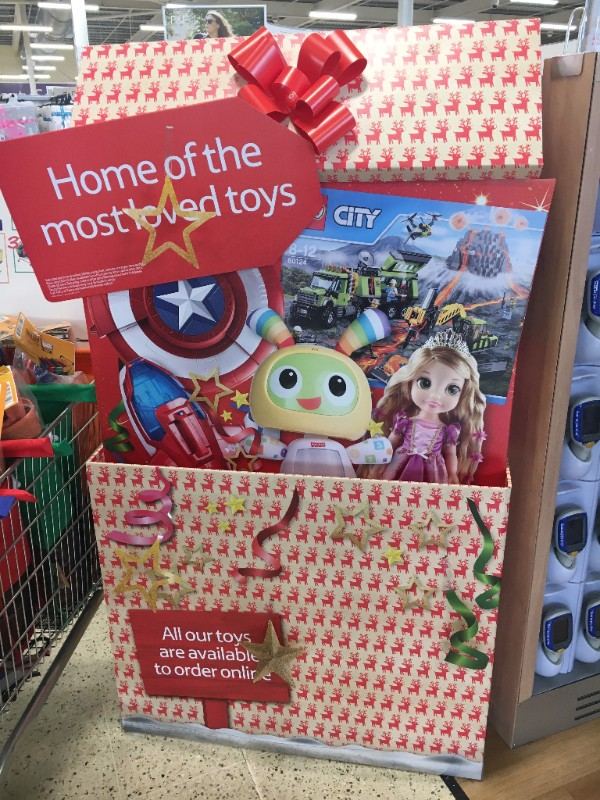
Tesco have then gone back on Toys, with the 'Home of the most loved toys' as an effective strapline with TV adverts and press releases focusing on this campaign.
Big bold claims in store from Tesco last week though, they've flagged a few lines around the aisle with price comparatives versus Argos, with 8,000 lines beaten by all accounts.
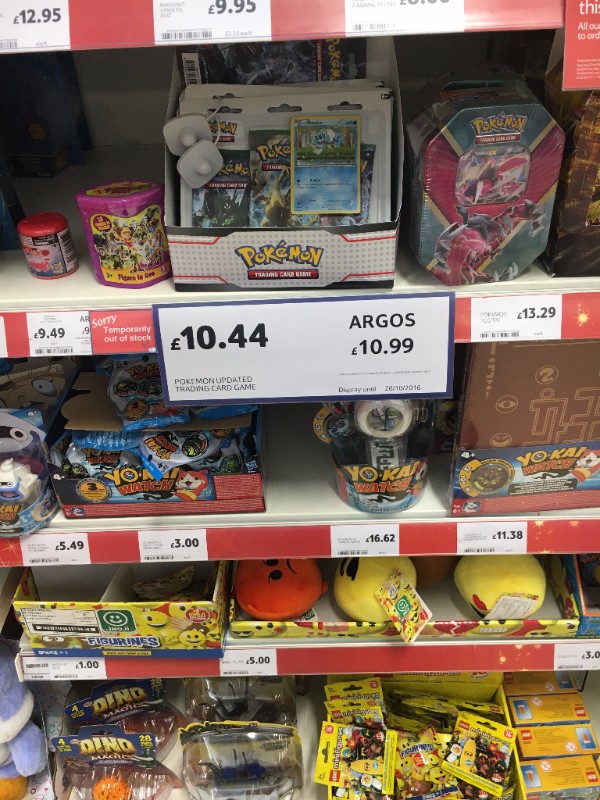
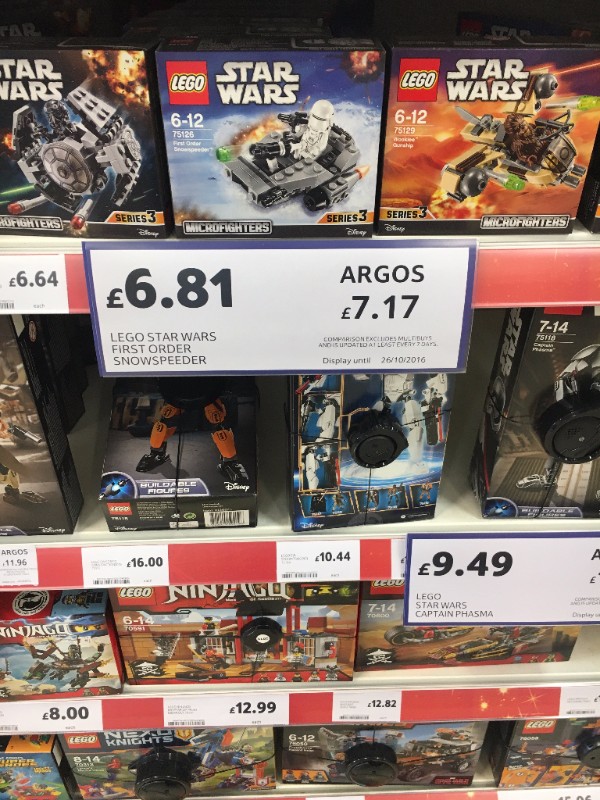
Post the toy event at Sainsbury's, Tesco had clearly felt that Argos would pose a threat to their own non food / toy sales at Christmas and embarked upon a campaign - a la Asda a couple of years back of comparing prices versus Argos and beating them by a few pence.
Flagging these cuts on barkers on the shop floor is a powerful message, but there are some lines that aren't flagged. Are Argos cheaper there?
It's clear that Tesco are viewing the Argos deal as something to defend against and fair play for doing so, it certainly makes sense and needs to be a precursor to the work in non food that will presumably take place in 2017.
Entirely unclear what their wider plan is, but looking at Sainsbury's and even Asda who have more compelling non food collections than Tesco - the inspiration is probably on their doorstep.
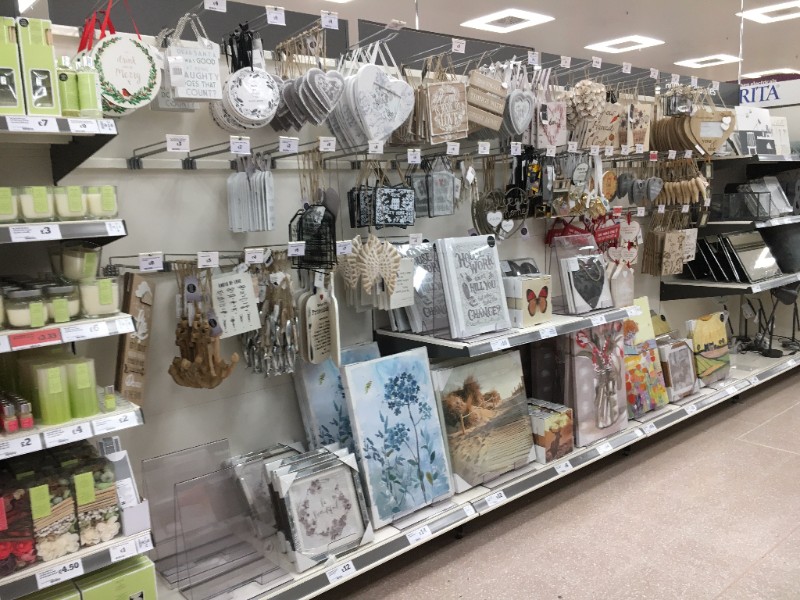
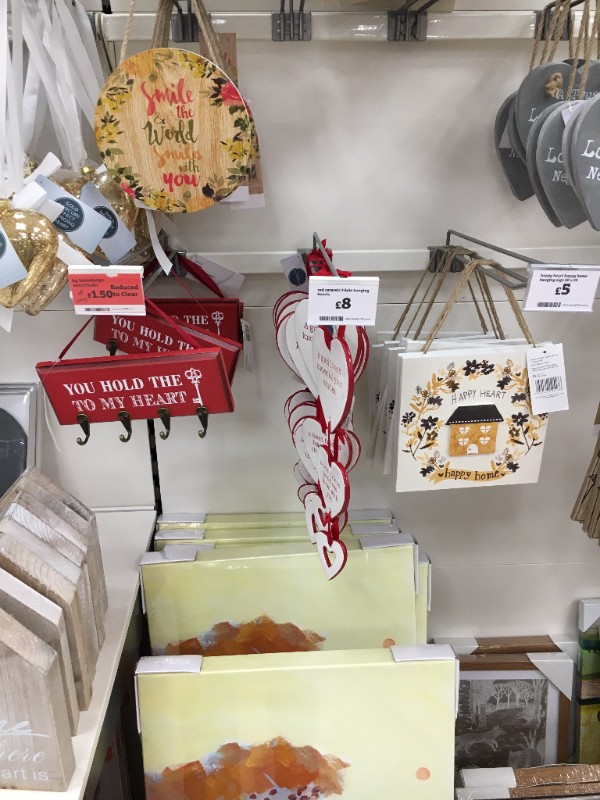
Full run of these message based signs that are regularly peddled on places like 'not on the high street' for decent sums. Sainsbury's on the trend and we all like the odd motivational message around the place.
Just one example here; there are literally hundreds of examples. The Tesco non food unit isn't completely dead, they grew volume and value of sales in the half year. Although value was significantly lower than volume, which you'd expect a pick up given the traffic to larger stores and the wider improved shopping trip.
So for Tesco, their defensive work here is noted and the fact they're trying to get on the front foot with Toys for Christmas should push sales towards their larger formats.
Extra remains in growth but only just, 0.1% rise at the last quarter, but Christmas is where the bigger shops come in to their own. Toys are a key part of this and it's notable that all the big four retailers have pushed into toys ahead of the Christmas rush.
For Tesco, building some momentum into toys and non food with the click/collect charge going and the prospect of some better ranging / store development work around non food next year will stand them in good stead.
That said, the push for profitability remains at the top of agenda, helped by a margin target too. The lack of a charge for click/collect and pushing on price vs. Argos will cost, the sales have to come to justify the spend of course.
Tesco looking towards non food is a positive step for them, they have to sharpen up here. No one wants to buy uninspiring non food from the same shelving as used for food, albeit a different colour.
The Toy war is on though, great for customers, kids and of course, Santa!
From the Grocery Insight newsletter archive, first sent to subscribers on 26 October 2016. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.