Tesco vs. Argos - Stepping up a gear
15 November 2016
Not a subscriber? Subscribe here.
Christmas is coming and we'll have a full run down of the movers and shakers for Christmas with a mini review of each set up over the next 2-3 weeks. A lot going on in the market, we have a look at M&S after the next two mails from Tesco.
M&S were covered the other week of course and it's easier to throw rocks at their clothing range, perhaps Steve Rowe recognises they're on a losing battle by pursuing a strategy that is ironically the reverse of Sainsbury's.
JS of course who have said they will repurpose some stores to feature more clothing and their non food ranges and less about just food. It's a good strategy and my local store is gaining an aisle of clothing with some of the food space being condensed down.
Sainsbury's can afford to do this, volumes have fallen in the mass market but also Sainsbury's broadly are less 'pile it high, sell it cheap' than Asda or Morrisons, their move to eliminate multibuys proves this. However they are also very efficient and able to cope with less space for their ranges, given their replenishment model and relatively low volatility within demand - thus meaning they can sacrifice some food space for the non food / clothing ranges that are performing so well for them.
M&S are going the other way, repurposing some of the stores towards Food with a closure of some units too. Makes sense really, the row(e) back from International is fair. Hardly worth bothering with unless pumping Capex in, and it's a distraction they just do not need. A franchise / licensing deal a la Waitrose / Sainsbury's for the Middle / Far East seems entirely more plausible.
Market leader Tesco must be concerned about the Argos / Sainsbury's deal and the subsequent synergies that will be derived when things are combined together. Indeed as a footfall driver, Sainsbury's plucked out that there had been a halo effect and sales rose in stores when an Argos was dropped in. Whilst people are in store picking up Argos orders, they will go around for a bit of Bread / Milk / Breakfast / whatever.
Also the Argos click/collect operation is slick (they invented it long before the internet) and non food is an arena Sainsbury's are strong in, and will seek to get stronger still. Tesco on the other hand, despite a lovely chart via Dave and Alan highlighting where the margin is(!) are struggling a little in those areas.
Sales are falling online so removing the Click/Collect charge has helped things near instantly. The problem is it then loads onto the Express network who, due to their convenient locations find themselves bombarded with parcels for numerous customers.
The issue with click/collect of course is that customers can turn up any time within that 14 day window, from open until close which puts the tight convenience staff structure under pressure. So it's right for customers that the charge has come out, but the Express network will bear the brunt of the click/collect increases, particularly with the 3 for 2 Toy event.
Do customers then receive the best level of service from Tesco? Online is a strange one, customers are very demanding yet the model doesn't benefit from scale efficiency. In fact it's the reverse, the more orders picked means more costs are incurred - more vans, people etc are required.
Delivery / fulfilment is the last point of contact, rather like a checkout after a shop. Spending £100+ (or even 50p) to be greeted by someone who clearly doesn't care, doesn't greet you and only speaks to you when confirming the amount you owe leaves a negative impression. A long wait for a click/collect order is akin to that experience - indeed in some Express stores - it's entirely unclear where you actually go in store to collect the parcels.
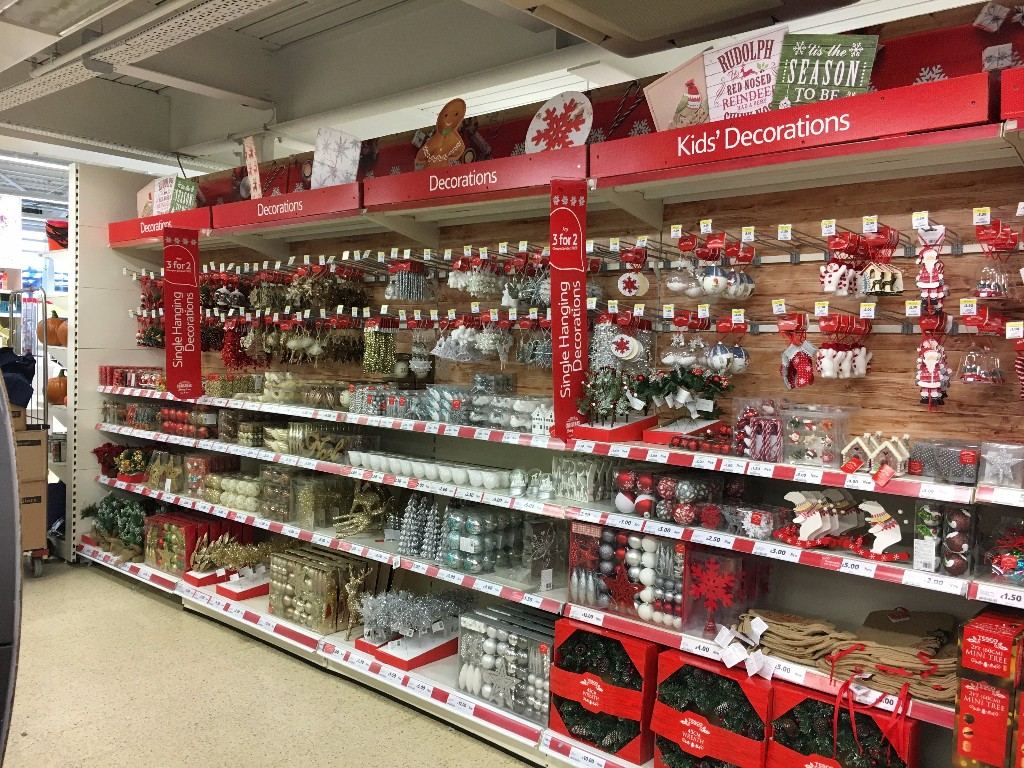
Despite good work on Food, one area where Tesco are weak in the market is the non food area of the business, they would be well just to hire whoever is running the Sainsbury's operation and put them in charge of the buying. Even Asda have a more compelling collection of lines (albeit not marketed at all), it's all about a Next style collection at lower prices, but good quality.
Sainsbury's even push seasonal collections in these days, and Habitat will only push that range on further. But Tesco struggle massively and if Dave Lewis has any fairy dust left, non food you feel will be raked over next year to try recover the margin.Their Christmas collection looks good with a tough comparative last year, they look well set with decorations but the wider non food / GM range? Entirely sterile.
Their work in food has been nothing short of stunning in all fairness, non food badly needs some work - both in product and price but also the look and feel in store. Even without bespoke display kit, it doesn't feel authentic and it's entirely confusing what they're trying to achieve.
But on price they can do something.... The Argos price comparative has been seen before and we know they were busy looking at Toys and as they landed 3 for 2, they also cut a number of prices in aisle. Big signs on the shelf which flag the Tesco vs. Argos price, some are pennies difference but one of the large Peppa Pig toys was nearly £10 cheaper at Tesco last week.
The tech aspect is quite smart, as I understand whenever Argos reduce a price, the Tesco signage system generates a new label with the updated Argos price on it. Assuming there's a match or indeed Argos go cheaper, the buyer must then get involved and invest margin as appropriate.
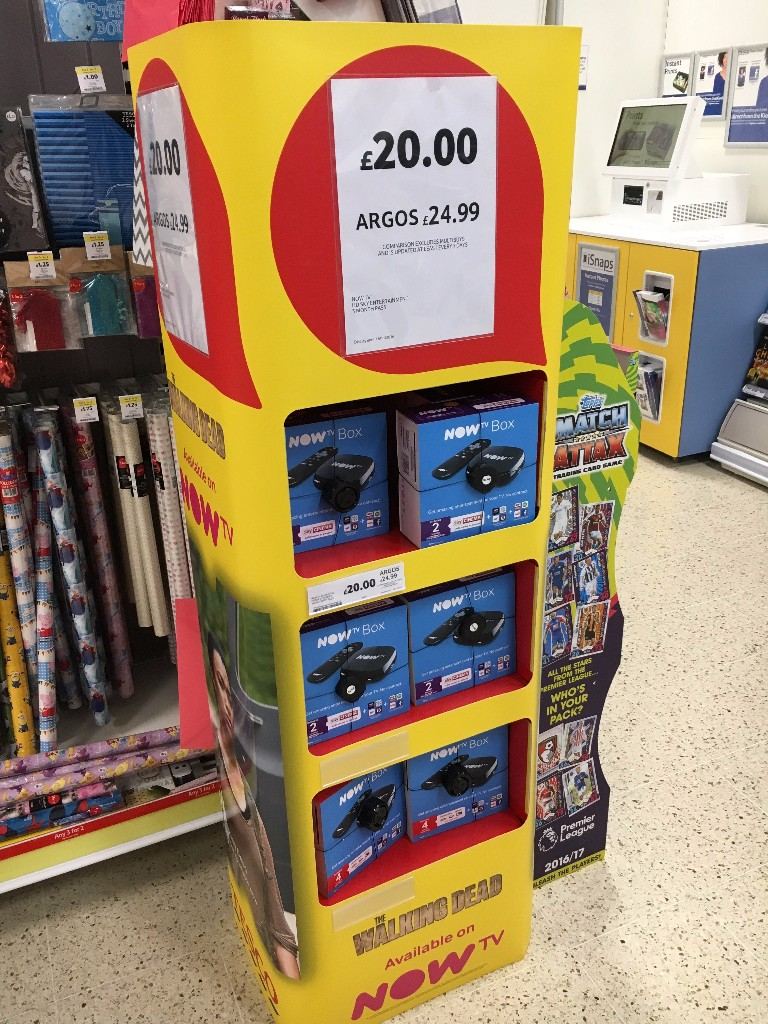
As we can now see, Tesco have moved from just Toys and into other areas of comparatives with Argos. Now TV shipper was a smart bit of work in its own right - ideal gift for someone on their own or a relative who doesn't want the burden of a monthly Sky subscription.
£4.99 cheaper at Tesco, and these price cuts will be trying to achieve footfall via Argos into the larger Tesco outlets. Of course, if they're in to save £4.99 at Tesco, or even use click/collect at the larger store - they may well (and are likely to) pick up something else given that the customer is in the store.
One would perhaps expect those order points that M&S have around the store (and Tesco do have in their click/collect areas when they existed and were staffed) to capitalise, customers may want to purchase but find the line out of stock. The pods (or even an ipad could be presumably hooked up to a pillar in store like those price checking machines) near non food to encourage orders in store.
All drives footfall and given Tesco have seemingly resolved their main store issues with some very consistent displays over the past 12-18 months. There is a chance the customer will be impressed with the own label food ranges, pricing and also the brand guarantee over-arching the strong prices within own label.
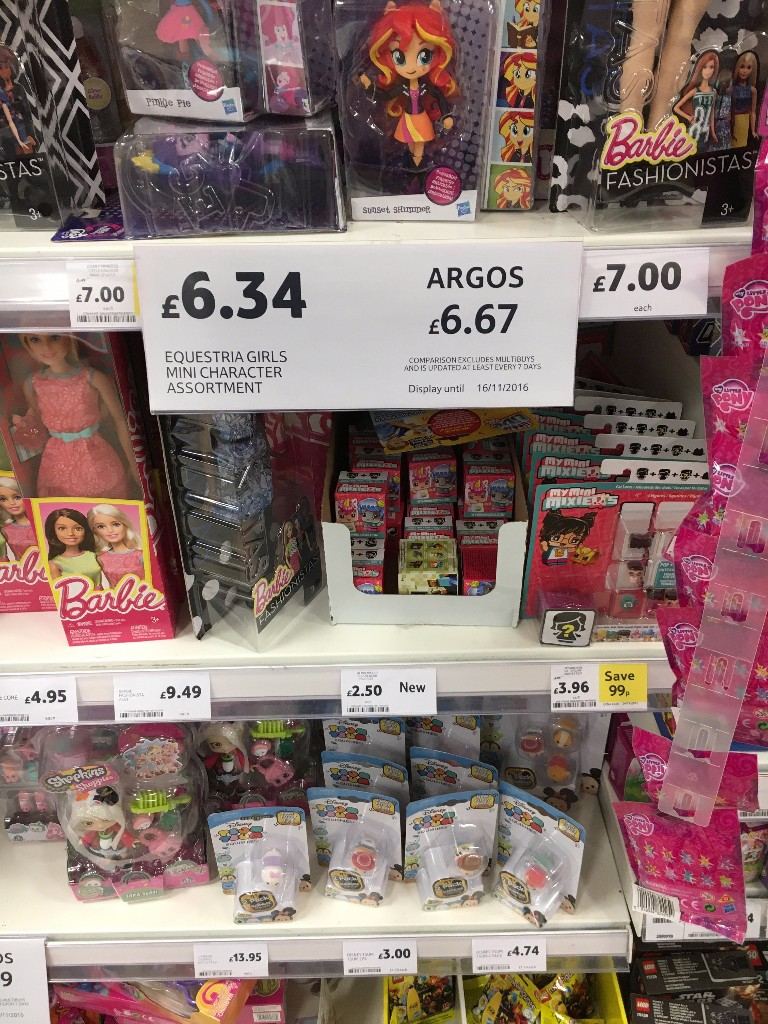
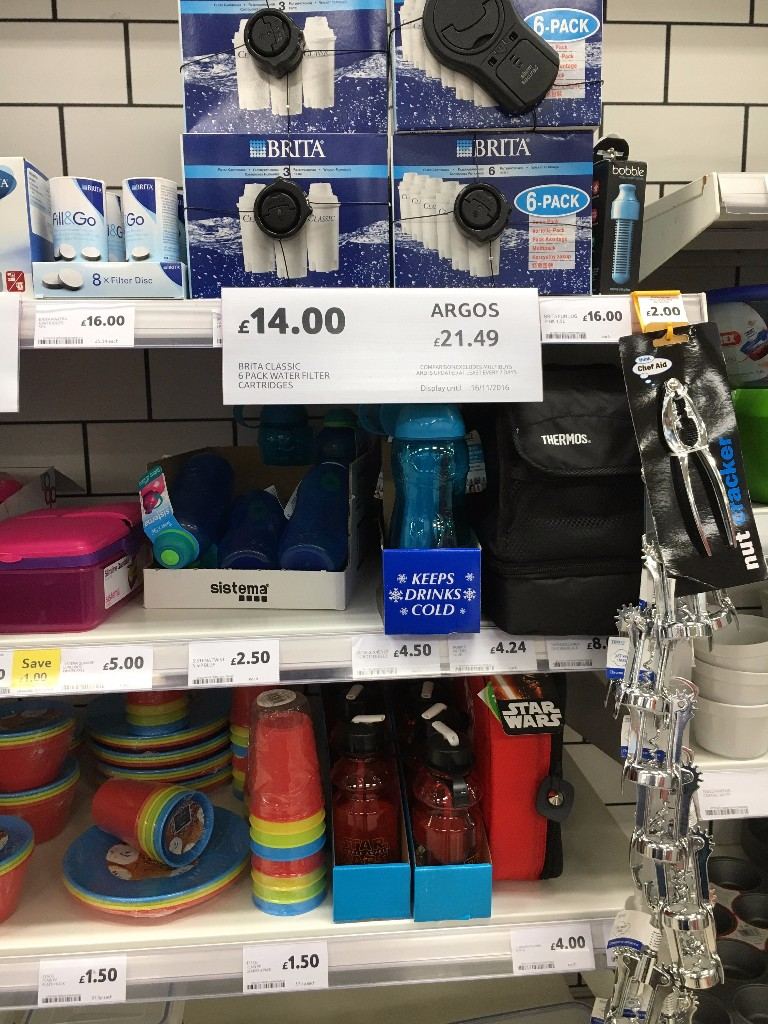
Within price vs. Argos, toys are still featured with a number of signs still flagging cheaper at shelf prices versus Argos. It seems Tesco are also looking at other areas where there is a difference between Argos and Tesco.....
Brita water filters are a line that can be bought in many stores, not just Argos or indeed Tesco. But there is a sizeable gap in price - £7.49 cheaper in Tesco yesterday, a significant gap.
It's not just footfall driving of course, core customers shopping in store will notice these price comparatives and may well bear them in mind when they're ordering / buying.
All the spadework by Dave Lewis and co has enabled them to be on the front foot versus the Sainsbury's/Argos partnership, there are some strong examples of cheaper prices in Tesco across the non food range.
It's never just about price, Asda have found that out.. But it is always about value for money - Tesco are pushing very hard with their value credentials. Non food price comparatives (on some lines, what about those with no barker, are they cheaper in Argos or the same level?) and brand guarantee is another example of providing value.
Whether it was discounters and points (Morrisons), brands and a coupon for next time (Sainsbury's) or everything and a 10% difference but log in online (Asda). The biggest price hook would be to say a retailer was cheaper than themselves and then give the difference back straight away. Very expensive (100% redemption at its instant) but very powerful. Tesco did that a year ago.
Tesco the consumer champion! Fighting back versus big brands and offering value for money. It would have never, ever happened under the Philip Clarke regime.
That's perhaps the biggest sign that the Dave Lewis to truly change Tesco is having some impact.....
Email forwarded? Click here to request a service trial.
From the Grocery Insight newsletter archive, first sent to subscribers on 15 November 2016. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.