B&M - More signs of progression
22 March 2019
Today we focus on B&M and their relatively meteoric rise in the UK retail stakes from a general hardware/bargain store to a relative power in the UK market with rapid growth and a business model that allows for low prices, variation in range and a strength in categories that, once served by specialist retailers who are now finding the going far tougher.
Namely Focus (B&M took a great number of their stores when they went in to administration) and also Homebase in recent times. In Bradford, B&M have taken over two former Homebase stores, despite having other existing outlets that are nearby.
This is interesting as it shows that B&M consider their model can serve neighbourhood based areas and that there's enough business to go around. Given they must cannibalise supermarkets effectively on ambient, impulse, household and Pet - alongside the seasonal ranges plus Toys - this is another channel that the leading retailers have to be aware of.
However; like food discounters - I am not convinced that there's an easy solution or indeed, whether retailers are even considering B&M and Home Bargains (to come next week) when they consider effective competitors and their impacts.
B&M appear to be taking a bit more care in their appearance in these newer stores that they've acquired and fitted out. Certainly versus some of the former Focus stores where, bar the new sign over the door - you'd be forgiven for thinking you were still in Focus or wherever.
Their category split is growing too; the older stores are heavily weighted towards non food and oceans of non food/ GM lines that sit in somewhat untidy displays and inspire precisely no one. In these newer stores, the GM exists but is by no means the focal point of the offering.
That accolade goes to the food range which has grown notably alongside Health/Beauty, Pet and Household lines which are also in growth. For the suppliers, B&M are a necessary evil, whilst they suppliers will tell you (no doubt) that all their products are bought on the grey market, or surplus from larger retailers (that was true, and still is in some cases)..
The reality is that the big suppliers are working with B&M and Home Bargains and they should be too, their growth and volumes on offer are clear and it makes sense. However on the flip side, their larger customers (namely the supermarkets) are then questioning why B&M et al can get lower prices and why are they not able to also benefit?
Perhaps they are; the shelf edge price is just one story of course. However there is little doubt that B&M have shaken up these categories (namely Impulse, Household and Pet, probably Health/Beauty too) where the model was all about 'hi/lo' promotions, higher prices and customers switching based on promotions, admittedly there is some loyalty too in there, but the deals are important.
Equally the discounters are strong in these categories (alongside others, but crucially strong own label) and the supplier is faced with declining volumes in leading retailers but B&M / Home Bargains offer growing volumes of their products = leading retailers left in the middle with competition from all angles.
Where Home Bargains have always felt more focused on ambient grocery, Health/Beauty and Impulse with seasonal. B&M have always felt the other way around, with their greater focus being in non food. Naturally the market (with online) means that this market is dying away somewhat, however you can not put a price on customers being able to go to a store and pick up furniture, seasonal lines, gardening equipment, DIY, Paint, Toys etc etc.
B&M offers a fair variety in these categories and increasingly their strength in DIY has (ironically) impacted Homebase who find themselves in the middle, not helped by the Australian disaster in any case.
Of note is the strength for B&M in Toys; you find leading Toys in B&M as their market share is growing all the time (they were a reason for the likes of Toys R Us going to the wall, alongside others of course...
They have a strong range of own label offerings and they generally replicate the 'top toys' under their own brands and also carry a permanent 2 for £20 deal, offering value to the customer. Bang on trend too; LOL Surprise eggs are everywhere and B&M feature numerous products around the 'on trend' items.
Combine that with the gardening, summer, outdoor toys etc and suddenly you have a retailer in a strong location (not far from me) that offers a wide range of products and is a 'one stop shop' for parents with kids alongside many other types of customer.
Interestingly this then spells a challenge for the likes of Argos, sat inside Sainsbury's a couple of miles down the road (they used to sit inside this Homebase store until the Australians removed them). However B&M are closer, have a similar range and if you're after kids toys / summer toys / weather is good - customers don't want to be travelling around either.
Therefore - B&M spells trouble on this front too. A real force to be reckoned with.
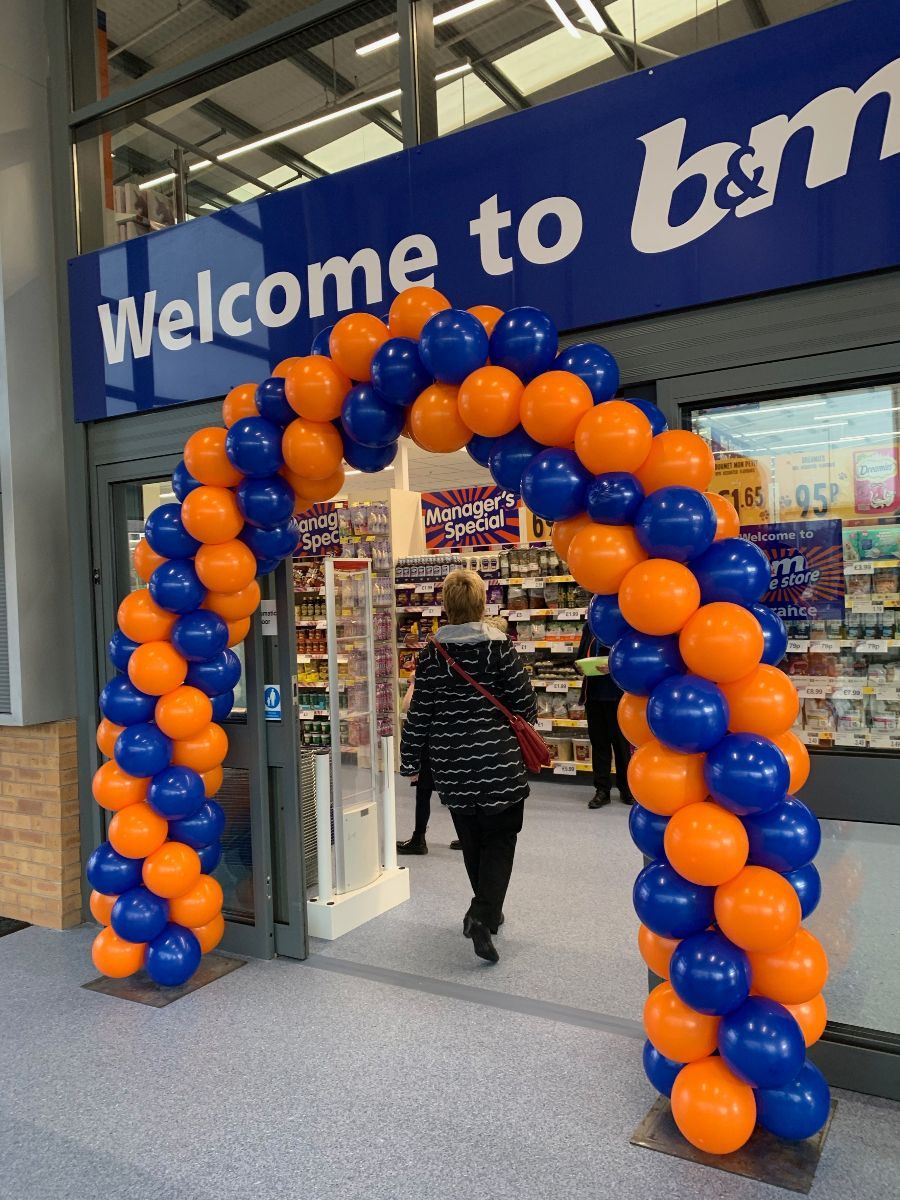
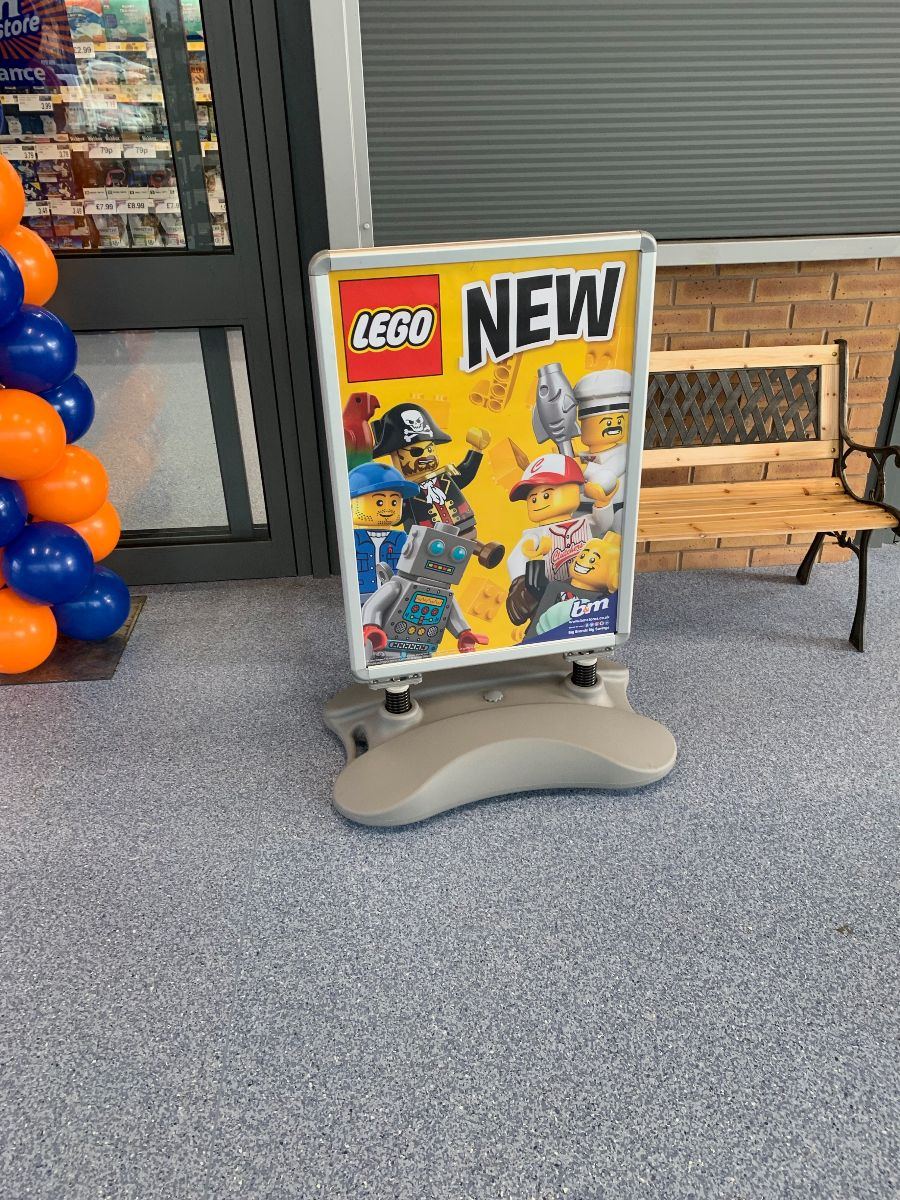
New store opening so the Balloon arch was noted; as was Lego (new in store) another sign of their growing strength in the category.
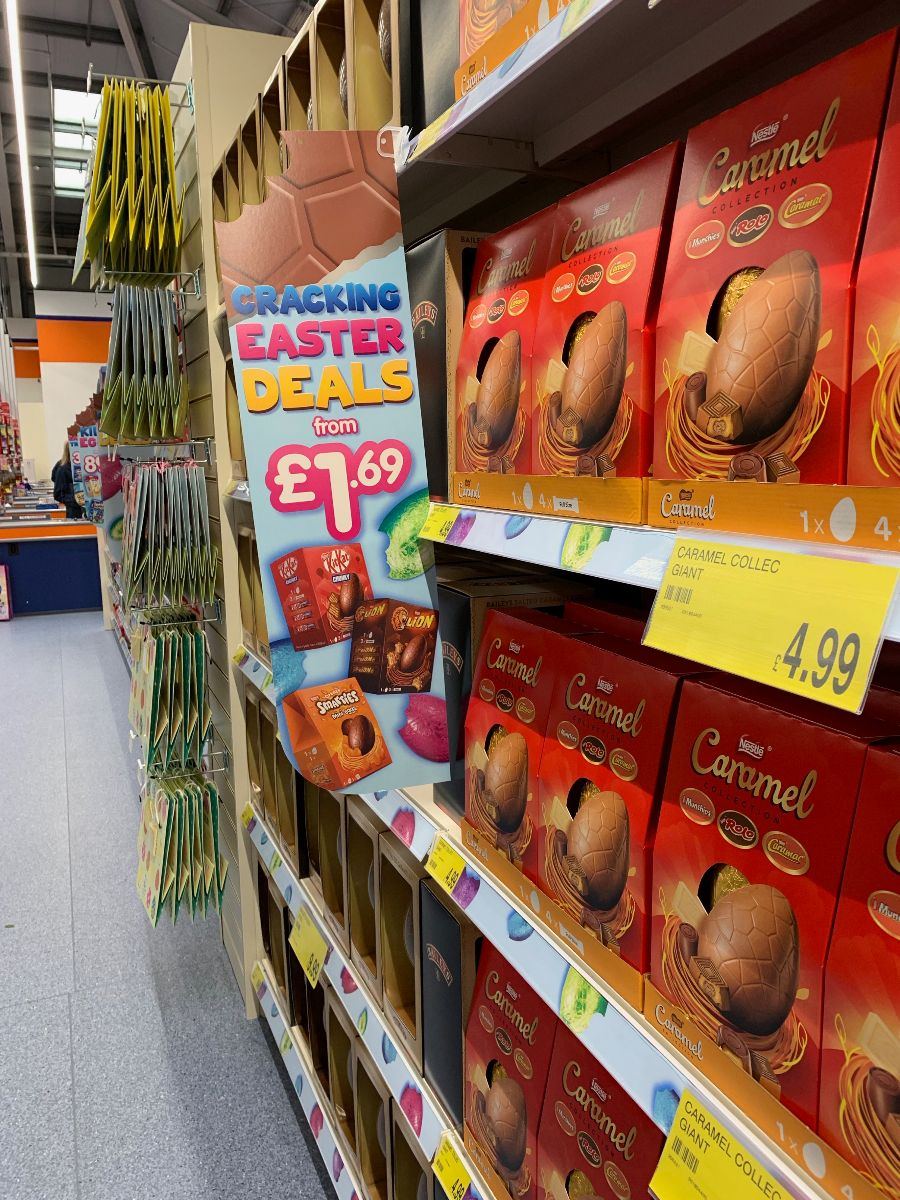
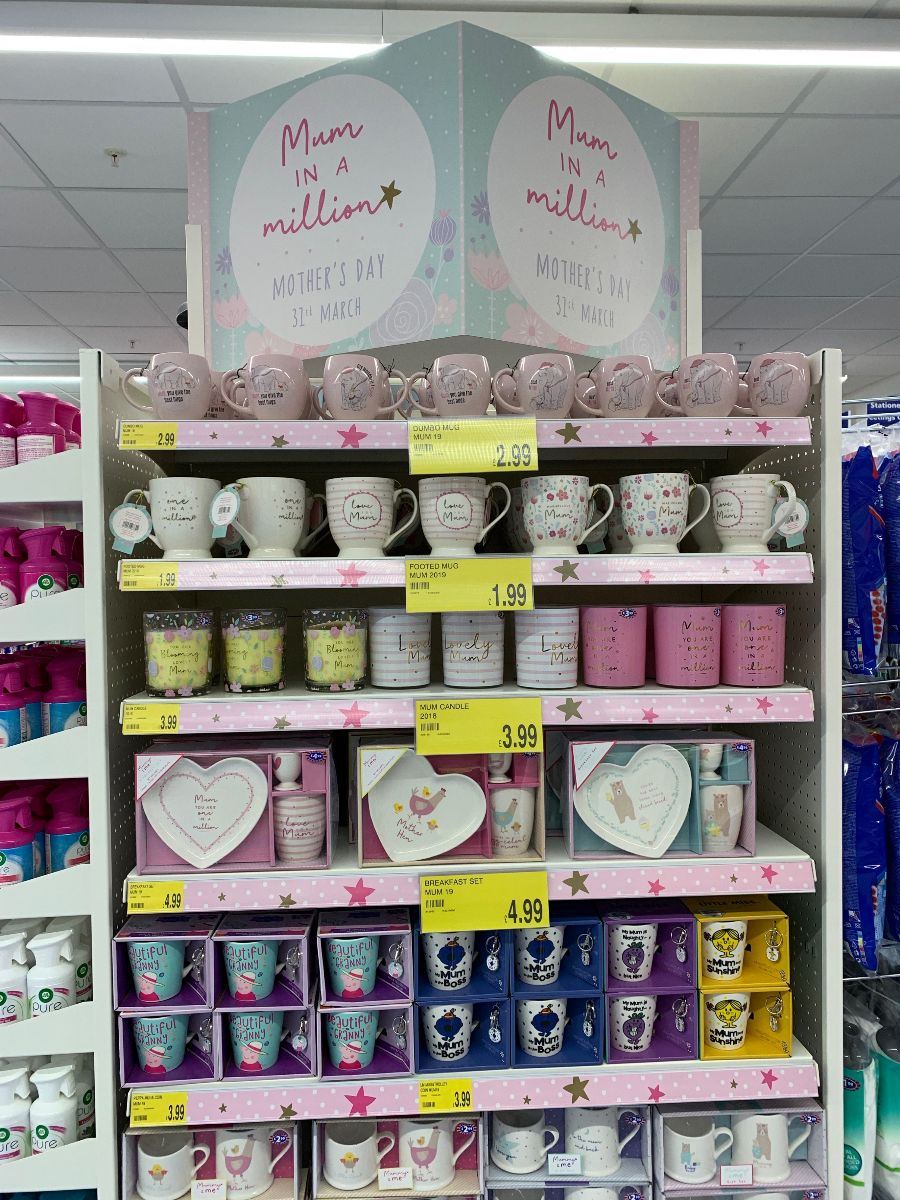
As noted - seasonal offers a great opportunity to be relevant for retailers like B&M and drive complementary sales within the store environment. It's highly unlikely they'll be primary destination for Mother's day for many - but then why shouldn't they be? I imagine their Easter share has grown purely via the footfall they generate.
Either way - it's extra sales and a way to be relevant.
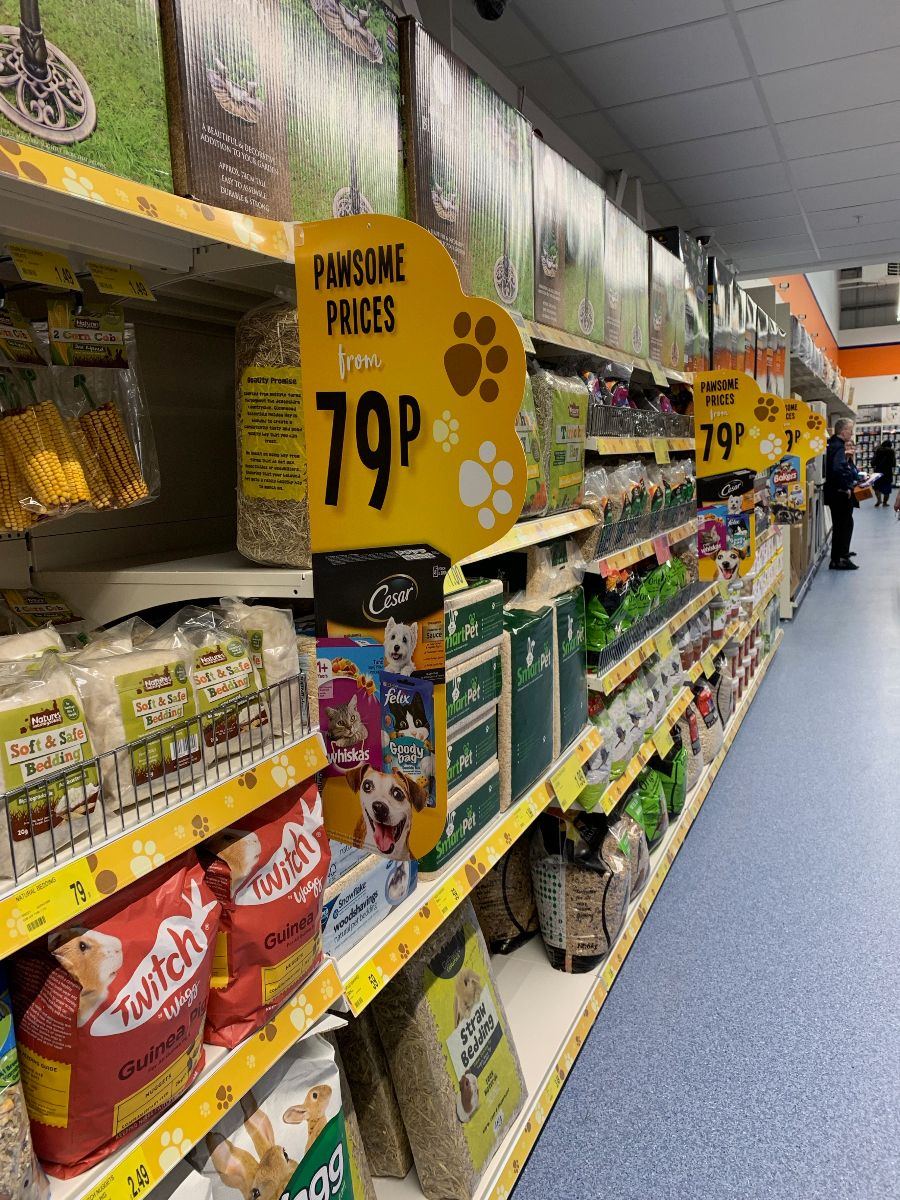
Not a Pet event in store at this time, although the signage was strong in aisle nonetheless and flagged the opening price points well.
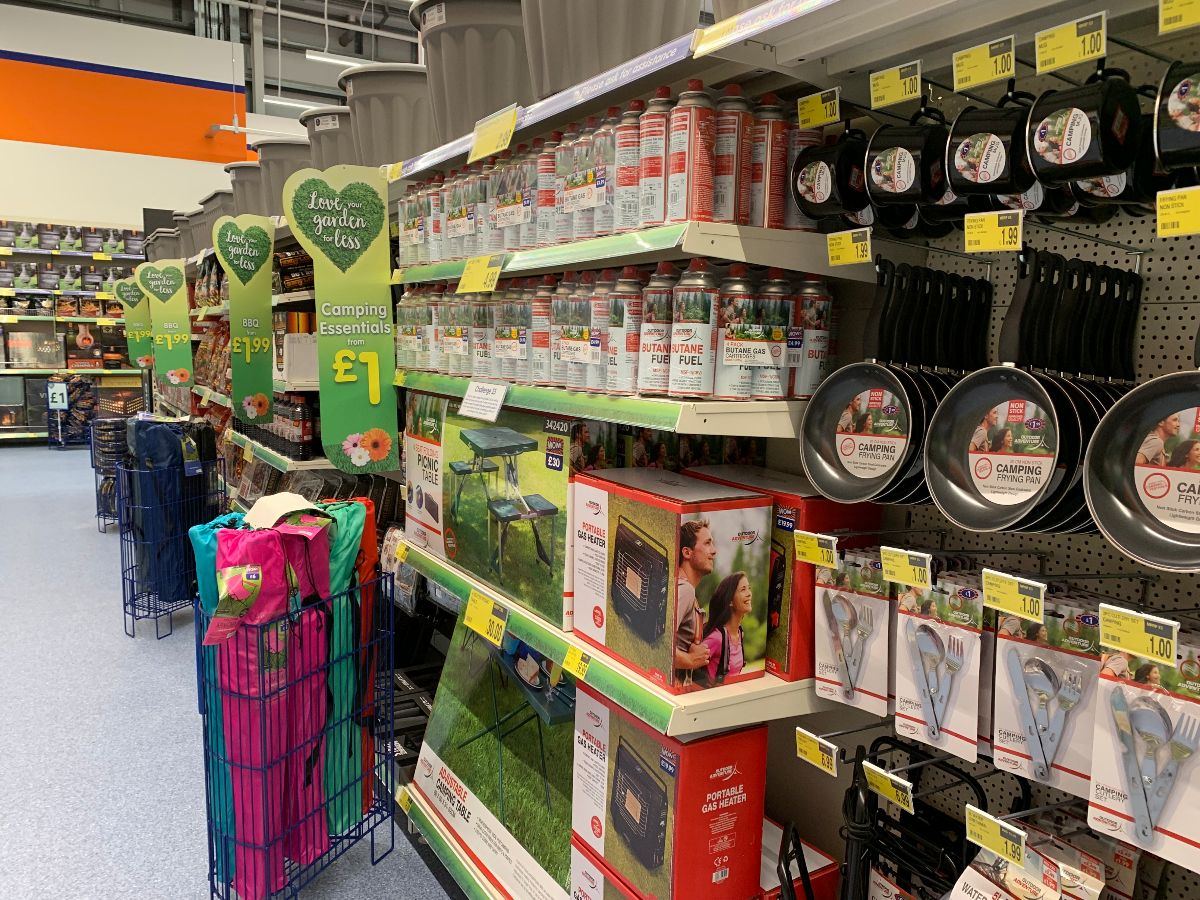
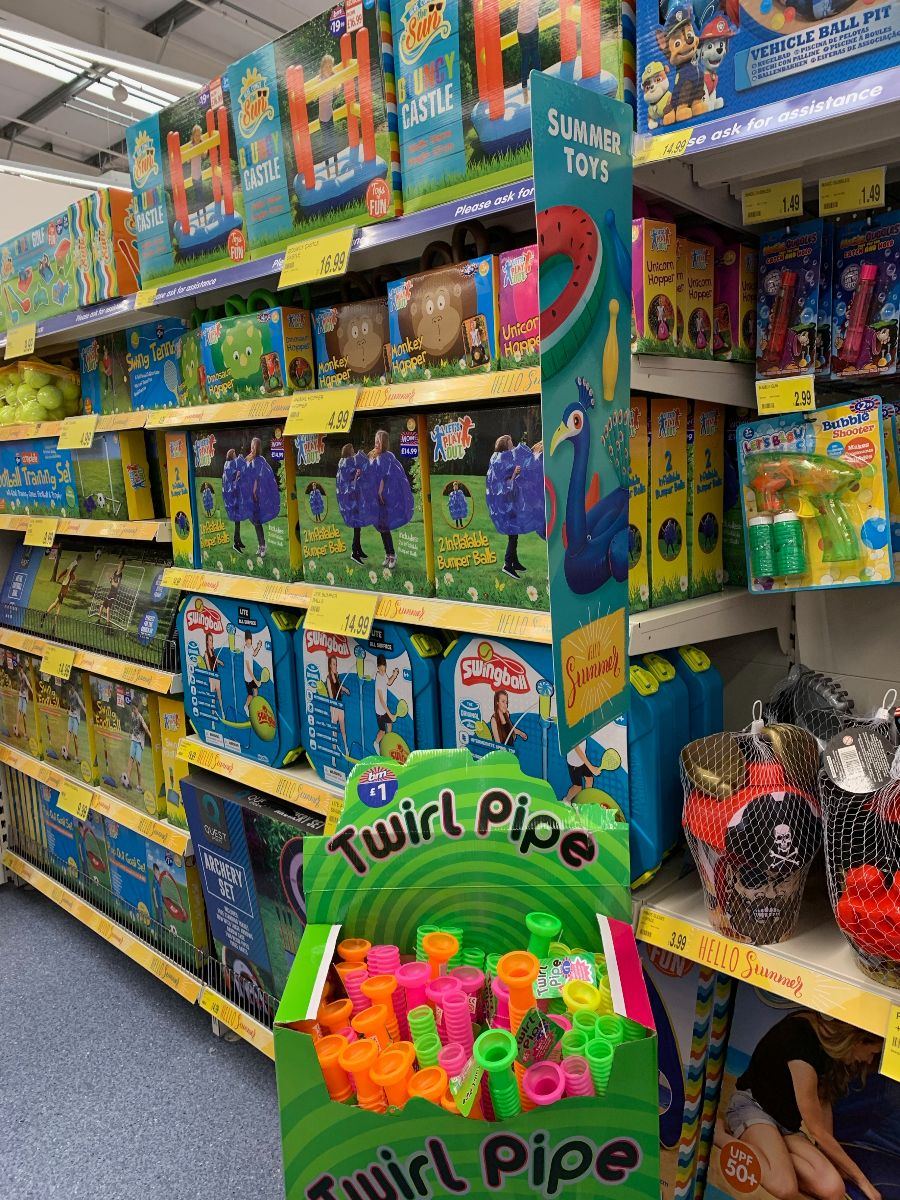
B&M will increasingly be first choice for Summer / Outdoor based toys for many customers as they may well visit for other reasons - lower priced household, grocery etc. But their range of gardening and outdoor toys is comprehensive, well merchandised and low in price.
Another way to drive sales once the customers are in the door.
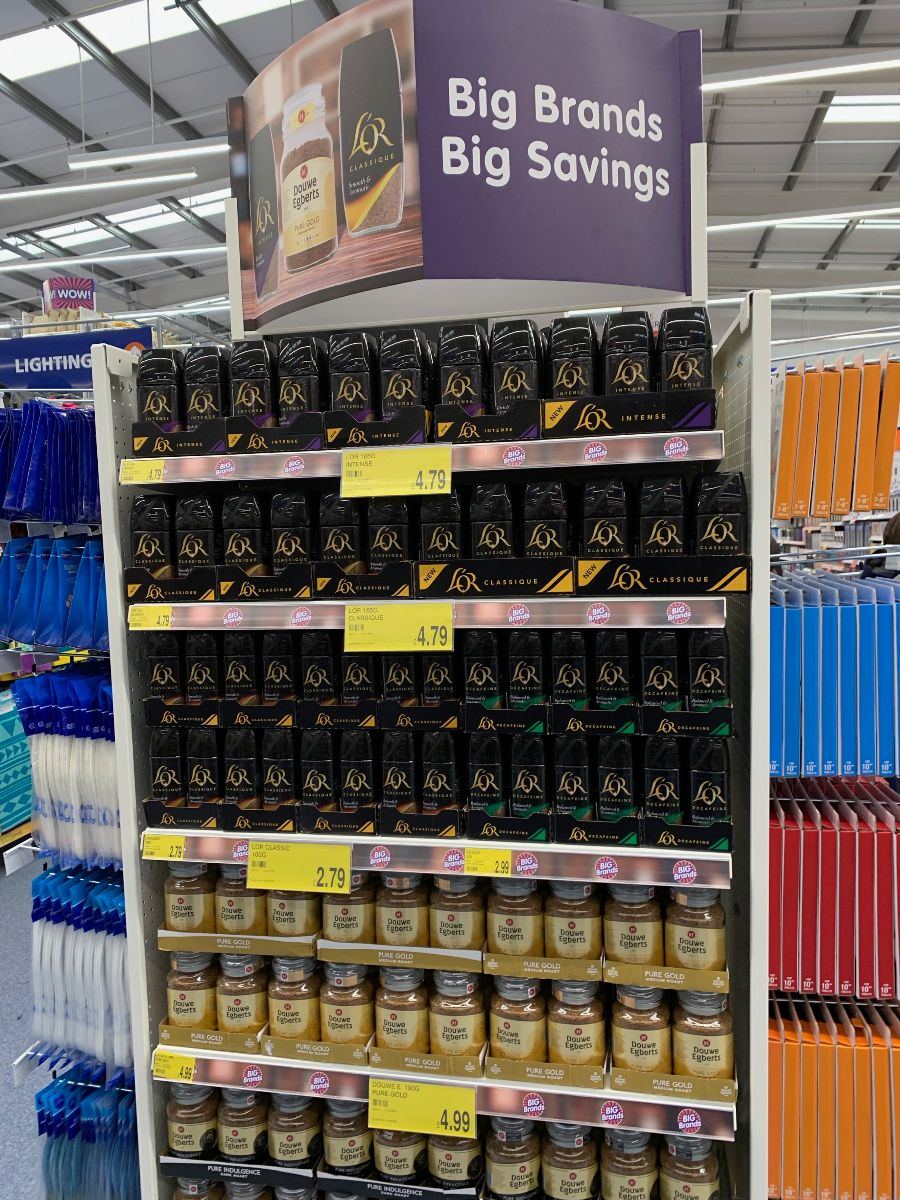
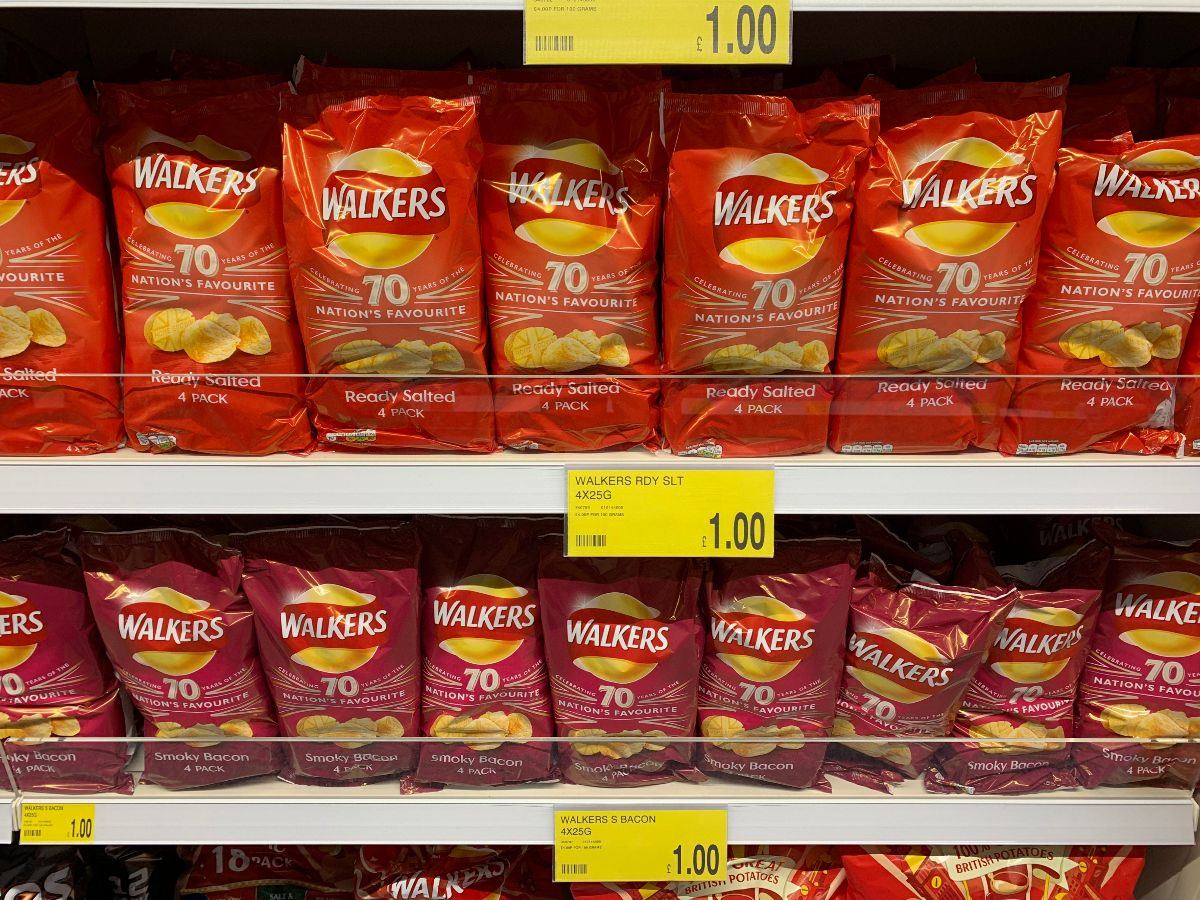
Two examples of how brands are working with B&M; certainly it's likely that the signage above the L'Or Coffee will be supplier funded as they are able to get the space featured and also display their brand in front of customers who will be in B&M looking for cheaper Coffee certainly.
Coffee, unfortunately remains quite a hi/lo product, the giant jars off deal can be as much as £8 on a core price, meaning customers are left looking for a deal. Cannibalisation then occurs (IE trade all shifts in to the promotional product(s) bar your brand loyals) and availability suffers.
So you can have a scenario where a customer visits the Coffee fixture, sees all the high price Coffee on sale (negative price perception) and then sees the deals off sale (negative perception of availability / trust with retailer) and then goes to B&M (chancing their arm that they'll have something in their price range).
Just one category can have a negative impact for customers, IE they didn't have what I really wanted (which was a deal on Coffee). Sometimes the deals aren't strong enough anyway so a customer will disappear off to B&M / Home Bargains anyway knowing they'll likely have something at the right price.
Conversely Walkers Crisps were noted at £1, yet these are just 4 packets strong. The core offer is 6 packs (generally £1.60/£1.70 - multibuy) but on a bag basis, there's not much difference here.
Occasionally the 'extra free' deals come to round it up to 6 bags but the pack size differences remain.
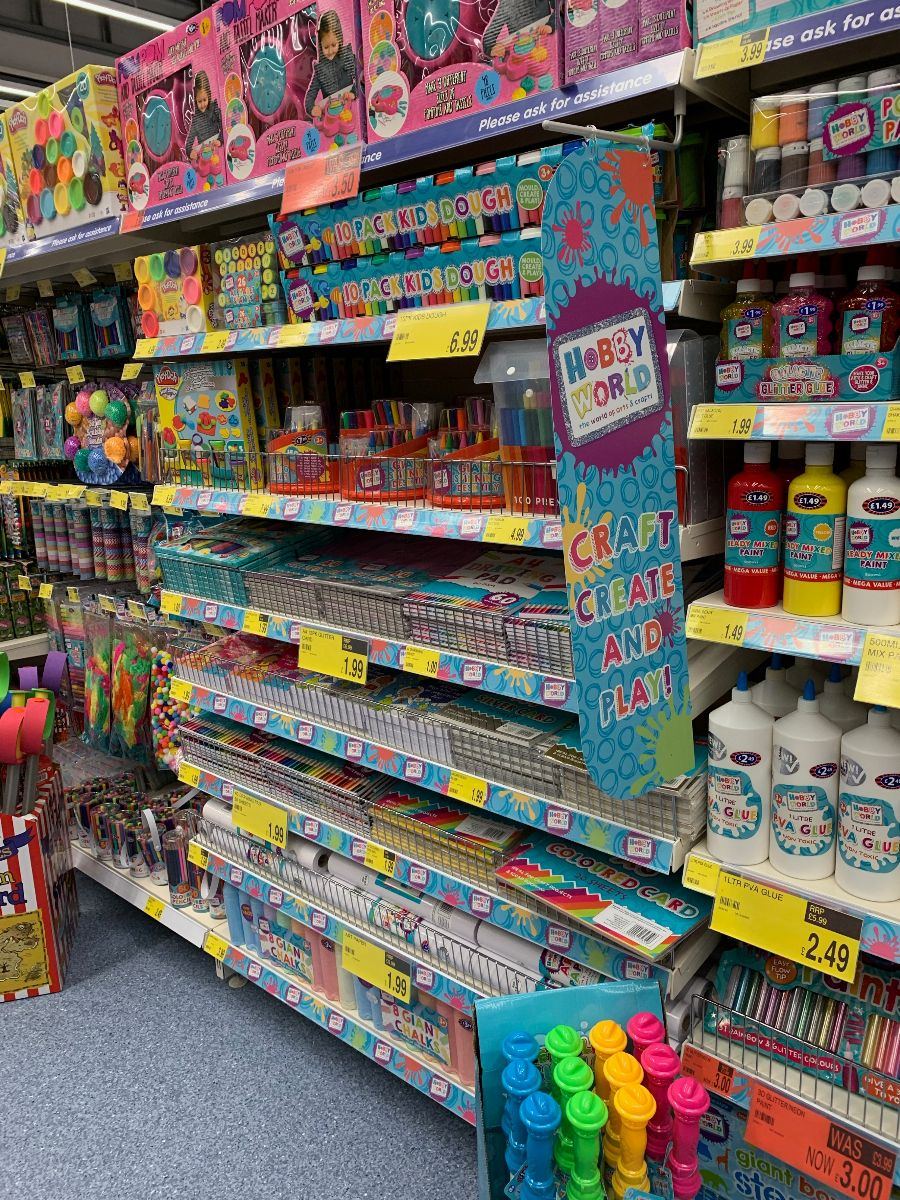
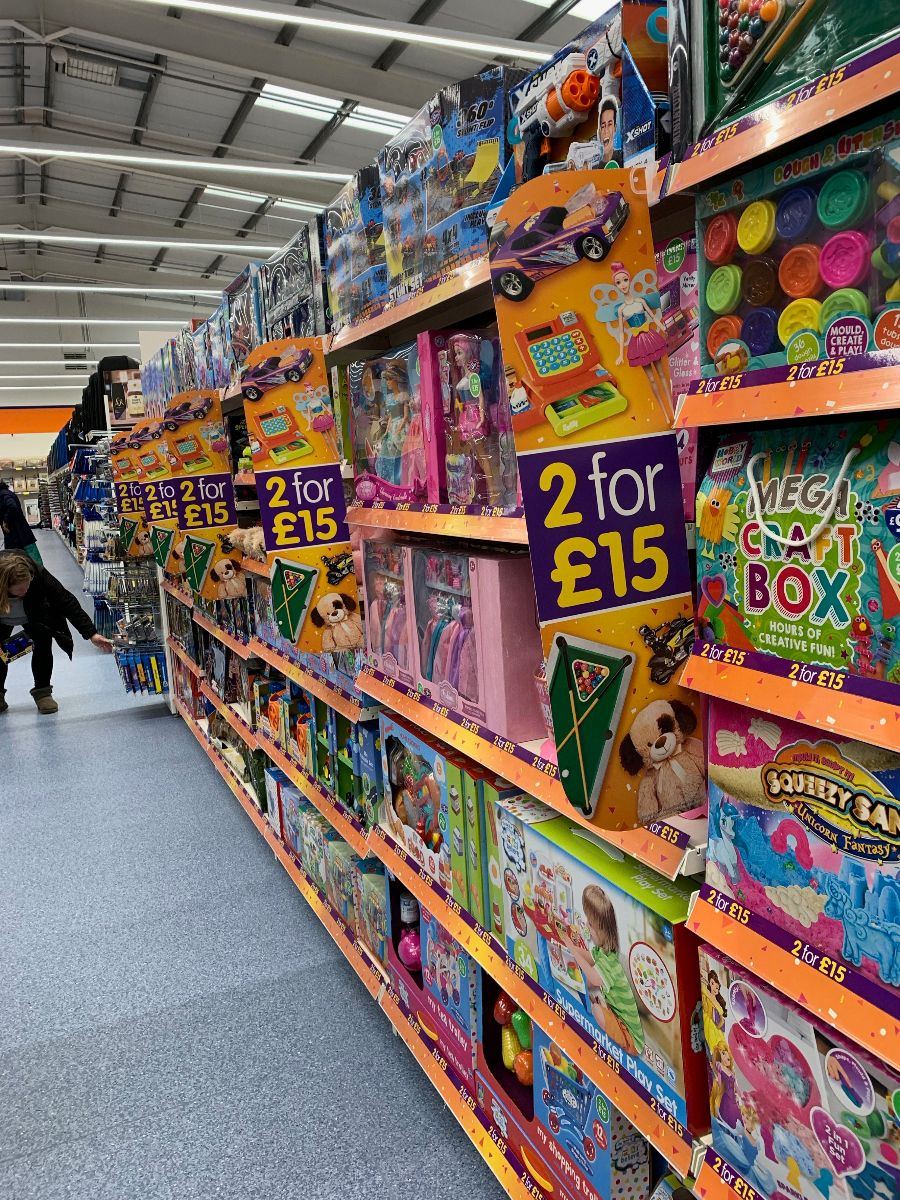
Finally -a bit on Toys (a key strength as noted) and also on trend items and Hobby World, their internal brand for the range of craft items.
All very impressive - works well and links together well. Leading toys at strong price points and then other elements such as craft based items that can drive further sales.
The challenge for B&M is to become the 'destination' in a customer's mind for these items, not just a place where you wander around and spot them. They are clearly growing in terms of destination and customers know they'll get value and quality products too.
Their reach and ability to site in all manner of store footprints is impressive and they drive great footfall, the store local to me has had a full car park each time I've driven past.
Clearly more in the tank for them too.
From the Grocery Insight newsletter archive, first sent to subscribers on 22 March 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.