Sainsbury's - More 'brands' incoming
11 March 2019
More on Sainsbury's today on our service as we consider the fate of the 2nd largest grocer in the UK; the main challenge to them, aside from the merger / CMA situation is that trading is stalling and has been for some time, especially via Kantar.
Like for likes haven't exactly set the world alight either and there is a fair chance that the merger has been distracting for them, however Asda have chugged along nicely but they do have Walmart International to aid their cause too.
However for Sainsbury's; the merger distraction is probably an easier way to deflect from the criticism that things have slowed and certainly, as covered exhaustively on here - stores have gone backwards which adds to the malaise around the chain.
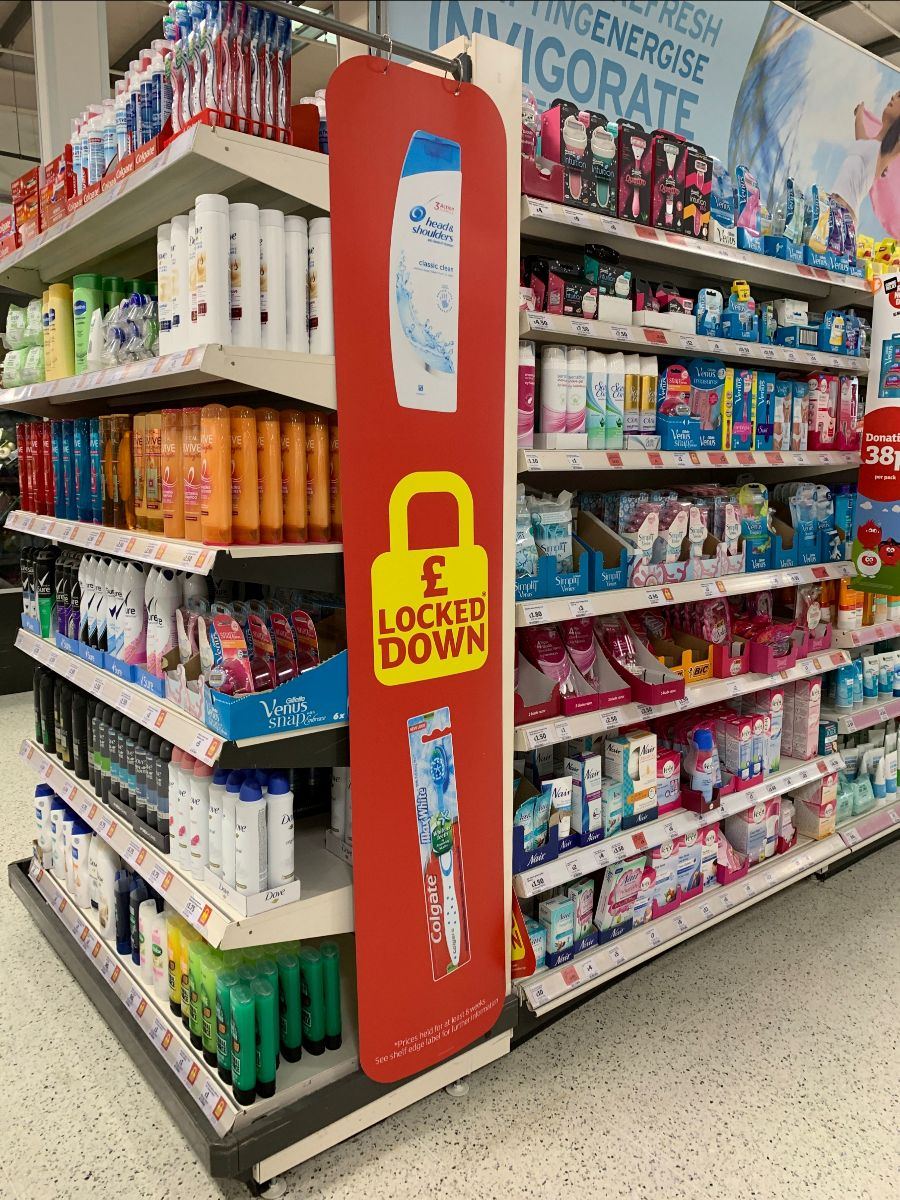
It's clear that Locked Down prices has had absolutely no impact via Kantar data, the basic reason is that it's too complex for customers to get their head around. What does it all mean? It just looks like a chance to display commercially paid for signage everywhere...
That said - their event based work has been stronger in recent times. Valentine's was good, as was their efforts around Pancake day and Chinese New Year. Bright signage, coverage across the store and some good buying on the non food side certainly helped matters.
However it's an issue if customers are buying less with you, or indeed, traffic is falling away as customers aren't thinking of Sainsbury's in the first instance. Especially if Aldi and Lidl are taking share as they have from Waitrose in those southern heartlands.
In terms of the ranges; Sainsbury's have been busy for a number of years building a number of private brands that they have worked on or exclusive tie ups (Godiva chocolate) for example.
Sainsbury's have been working hard on the discount threat and their move to remove multi buys and focus on lower, every day prices appeared to work in the first instance for them.
However it has been nullified too easily; discounters continue to get cheaper and Sainsbury's, chasing them down have let their stores become a poorer experience for the privilege of still being more expensive than Lidl.
Indeed the multibuys are permissible in Wines (Buy 6, Save 25%) but not anywhere else, which seems crazy when one considers the market (entire market) doing a meal deal for Valentine's Day bar Sainsbury's...
Looking further across the retailing landscape, Tesco have made quite a splash with their discount brands (replacing value tiers) and we have seen various reactions from Aldi and Lidl, who have either cut prices on core ranges or indeed, expanded facings of value in some categories too.
Sainsbury's seemingly like the idea of creating value from their value tier; rather than it being a 'Basics' tier with all the stigma that goes with it - rebranding the various products with category specific brands to 'anchor' value is a smart way to go about things.
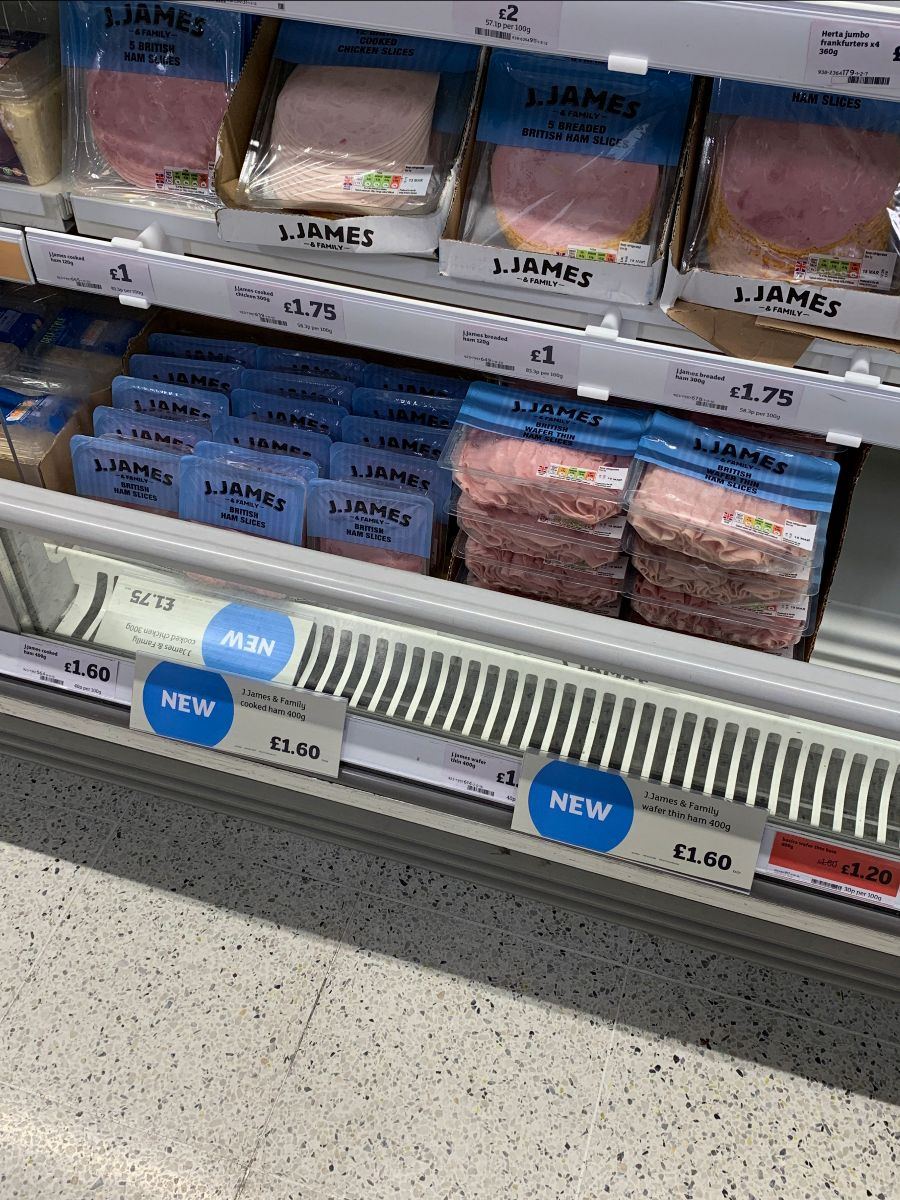
J.James has been spotted in Fish, Cooked Meats and Pork/Bacon in recent months and this forms part of a wider strategy, beyond changing selected lines on Produce to "Greengrocers Selection" as they did some two or so years ago.
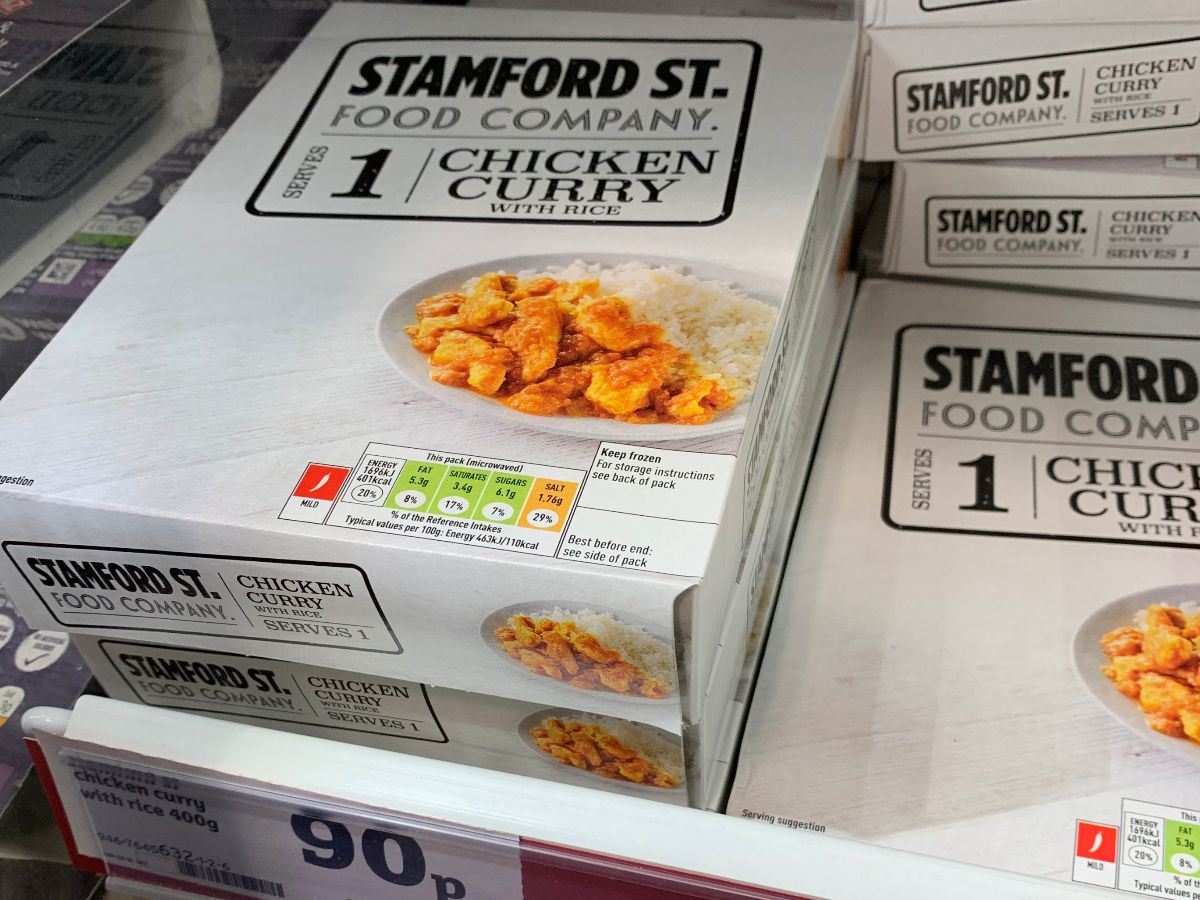
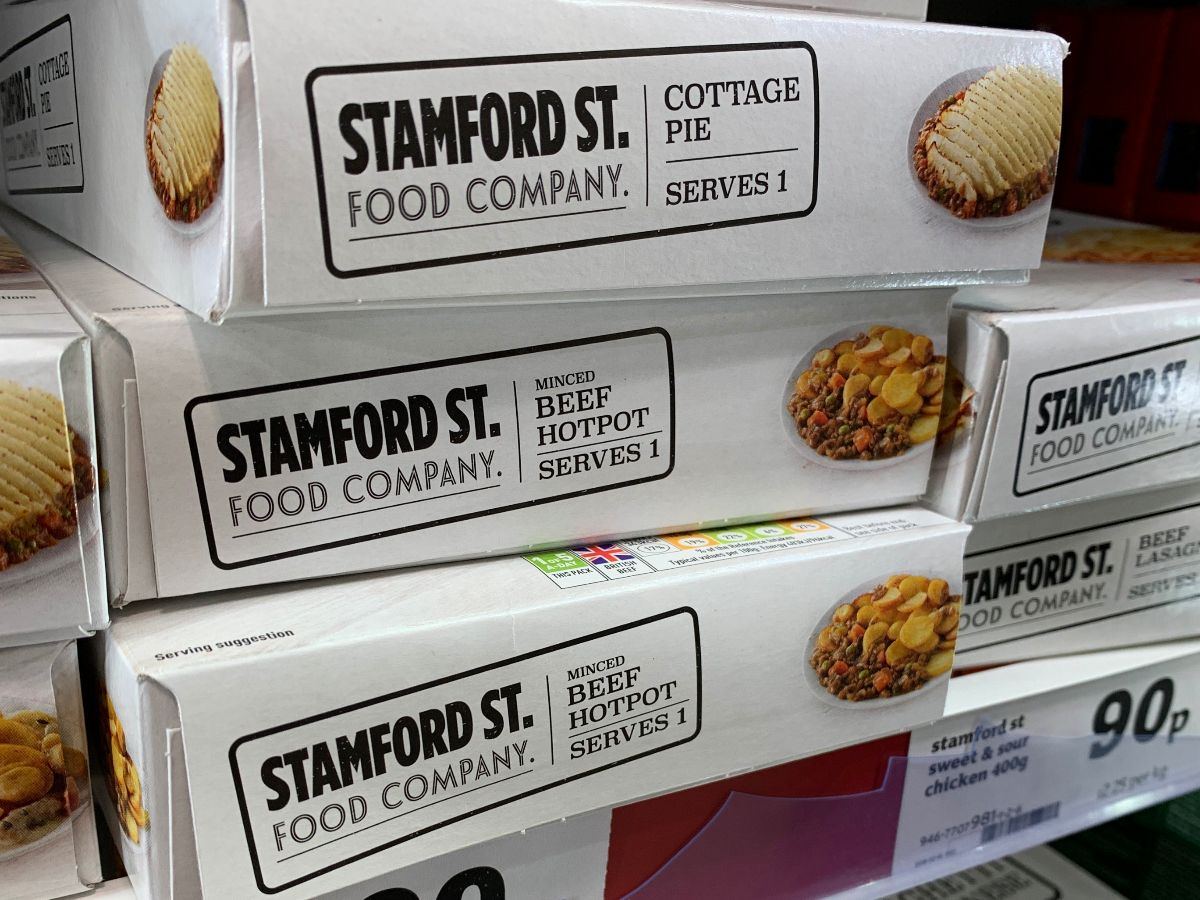
So beyond J.James - we move to Frozen and the "Stamford St" food company have appeared within frozen ready meals, replacing Basics.
Online; reviews appear from these products as far back as 2015 which is cloaking the fact that it's a new range - replacing the Basics range in this category.
For those retail historians out there; Stamford St was the location of the Sainsbury's head office for many years before the move to Holborn was made (and all the ££££ that goes with it).
Further work on their ranges continues around the store; quite an eclectic mix of tiers and private brands to be quite honest.
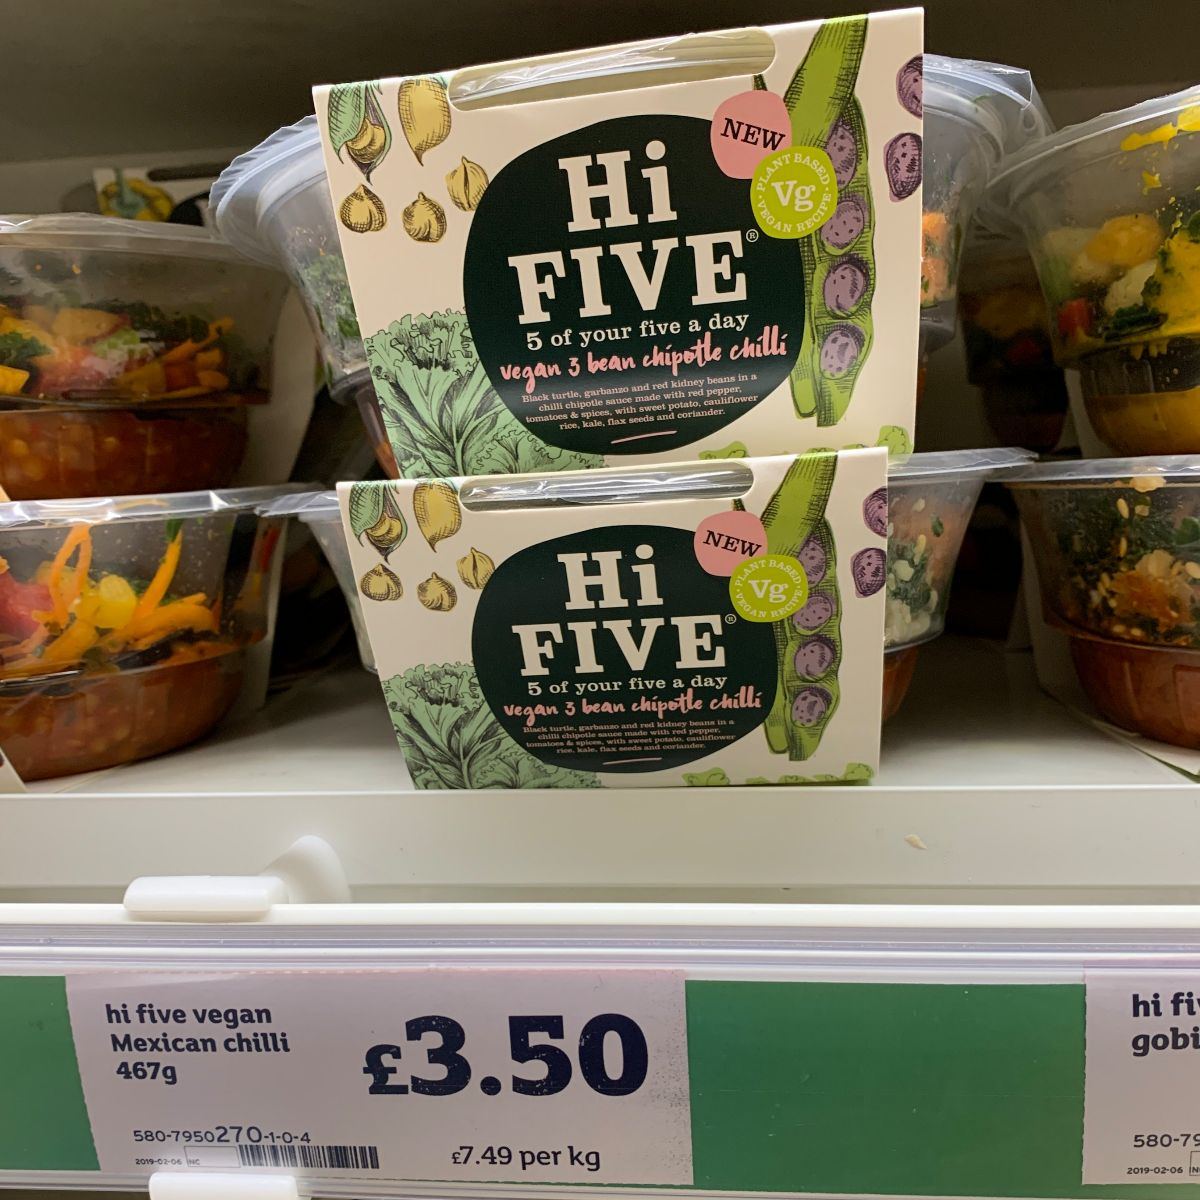
In many cases it can be difficult to work out which brands are truly private, which are Sainsbury's joint venture / exclusives and which are the less common brands.
A number of new lines are relatively hefty in price too; which is fair if that product is providing specialism and a reason to exist in the tier. However, it's not for everyone / everywhere.
Deflation is always a risk in any move to sharpen up value to enhance the wider appeal of the chain versus others (Tesco let alone discount). However you need to either grow the customer spending who currently shop with you and ensure that you don't lose more people in to buying cheaper products versus those who buy mid tier......
That's the aim of the game at least. It's not an easy equilibrium to achieve, not when you have 20,000+ items ranged in the store.....
So there we have it, more range work from Sainsbury's. The bigger question for them, perhaps via their new chairman who commences work today will be around that merger.
The deadline grows ever closer and alongside Brexit, has the potential to run and run and run........
From the Grocery Insight newsletter archive, first sent to subscribers on 11 March 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.