Happy New Year 2019
8 January 2019

Join this service to receive more insight like this
Blimey - what a year 2018 was and 2019 is already shaping up to be as interesting - Brexit will hopefully come to sort of end with a deal being struck and then we can all get on with our lives until the next general election....
Christmas 2018 was over shadowed by Brexit and the debacle around a deal, fear factors aplenty and customer spending subdued significantly with concerns over short term debt and the spending from that long hot Summer when England were oh so close.....
Anyway - we are now in January and it's the peak week for the likes of my good self as we try to piece together what went well, not so well and what to expect from the results that occur this week......
Equally it's vital to look at the current marketplace and what's occurring as we enter January, customers watching the pennies and we see price offensives from the major retailers in one form or another.
In wider news; the merger of Asda and Sainsbury's will kick off soon as the preliminary findings are released before we proceed to the next stages, if applicable. It seems with the judicial review that they really did want the extra time - however the investigation was fast tracked at their request so it was a bit puzzling in that regard.
However there will be a degree of nervousness from Sainsbury's as the gods are seeming to indicate a negative number post Christmas, which is a terrible result if one considers that Argos and their non food sales are contained within that number, they had a clearer run at it this year given Tesco have abandoned click / collect for non food too.
Naturally we have tracked their slump on this very service for a number of months so it will come as little surprise, but their pace of decline is extending to more and more areas to the confusion of more and more customers. Certainly at Christmas, it didn't feel like a place to go and enjoy a treat or two.....
I think the issue is that they have coached customers out of going in to the store; just as they coached customers in to shopping there, trusting them on welfare, availability and standards...
They have gone the other way and coached customers out of visiting as their restructure clearly impacted, but these were moves that Sainsbury's elected to make and they are responsible for the success, or otherwise of these decisions.
You can never track just what impact a store being one that doesn't look as though as it's been filled for a week has on a customer... But the perception of availability (IE low stocks, untidy shelves) being impacted can be as bad as the actual availability being poor and impacting choice.
This is not a problem that is unique to Sainsbury's, all retailers struggle with consistency across their estate but as noted time and again, there is no wider issue (such as a new ordering system or IT upgrades etc) that would cause such an acceleration in standards declining.
Whilst they have done some very solid work on value and price, their lack of x for y deals at Christmas still impacts for my money and they're delivering a demonstrably worse shopping trip but are not as cheap as their main rivals, let alone discount. It's a difficult one to square up.
They will be hoping the deal goes through as quickly and painlessly as possible as the stores feel like they're waiting for something to happen. It's a confusion as to why they are doing, what they are doing however - especially given Asda's stellar performance and whilst it will be interesting to see how the festive results play out - the set up was the best in the market for 2018.
The merger will capture attention in the first quarter of 2019, then we have the on/off will they/won't they debacle that is Brexit - rapidly turning in to the political disaster of the century. Will the future generations history iPad apps look favourably on our leaders? I doubt it.
The impact to food supply may be over hyped but if the stories around stockpiling is true then the customer will pay for that down the track, given the impact to working capital.... The stockless supply chains have revolutionised the balance sheets for retailers, alongside technology which means there is a near zero need to hold stock anywhere...
The changes to the supply chains will be interesting; any disruption will be a disaster in any case but especially given retailers have cut their supply chains / depots back as there's no need for excess space anywhere.
The wider Brexit stories have impacted confidence and that impacted the spend at Christmas; certainly in terms of the lines that were left over post Christmas. The longer Summer meant spending was depressed with customers opting to leave spending until late and indeed, not really spend in areas like Christmas decorations (numerous left over), Crackers, Christmas cards (everywhere had numerous packs left....)
Whether Christmas cards was one of those where the customer elected to join the trend to send a donation instead of sending Christmas cards, or customers went to the loft and found their 90% off cards from M&S the year before...... There was a lot of excess.
Clearly customers elected to spend late, aided by the long run up to Christmas - a standard working week for many, finishing on the 21st December and then Christmas Eve on the Monday.... However if the spending came, then all is fair in love and war - but the Brexit backdrop makes planning for Christmas 2019 (starting in earnest very soon in retailers) difficult to think about...
The first retailer to report results was Aldi, predictably on the day before the mults then start to report their figures.
As noted elsewhere; the reporting periods and quoted figures were selective as last year, they quoted the entire December month whereas this year, just the one week in the run up to Christmas.
Aldi also opened a significant number of stores in November; 8 on one day which also aids the figures of course. They were in good shape at Christmas and appeared to trade their seasonal collections well, especially in Fresh Foods.
However they had a degree of seasonal excess, much like any other retailer but it all pointed towards a slow down in spending. Their premium Mince Pies also looked a struggle versus former years where they would sell out long before Christmas.
They will have captured spending as ever at Christmas but still suffer with customers who will visit larger retailers for the range of gifting / brands / beers and then find premium products and a wider choice there.
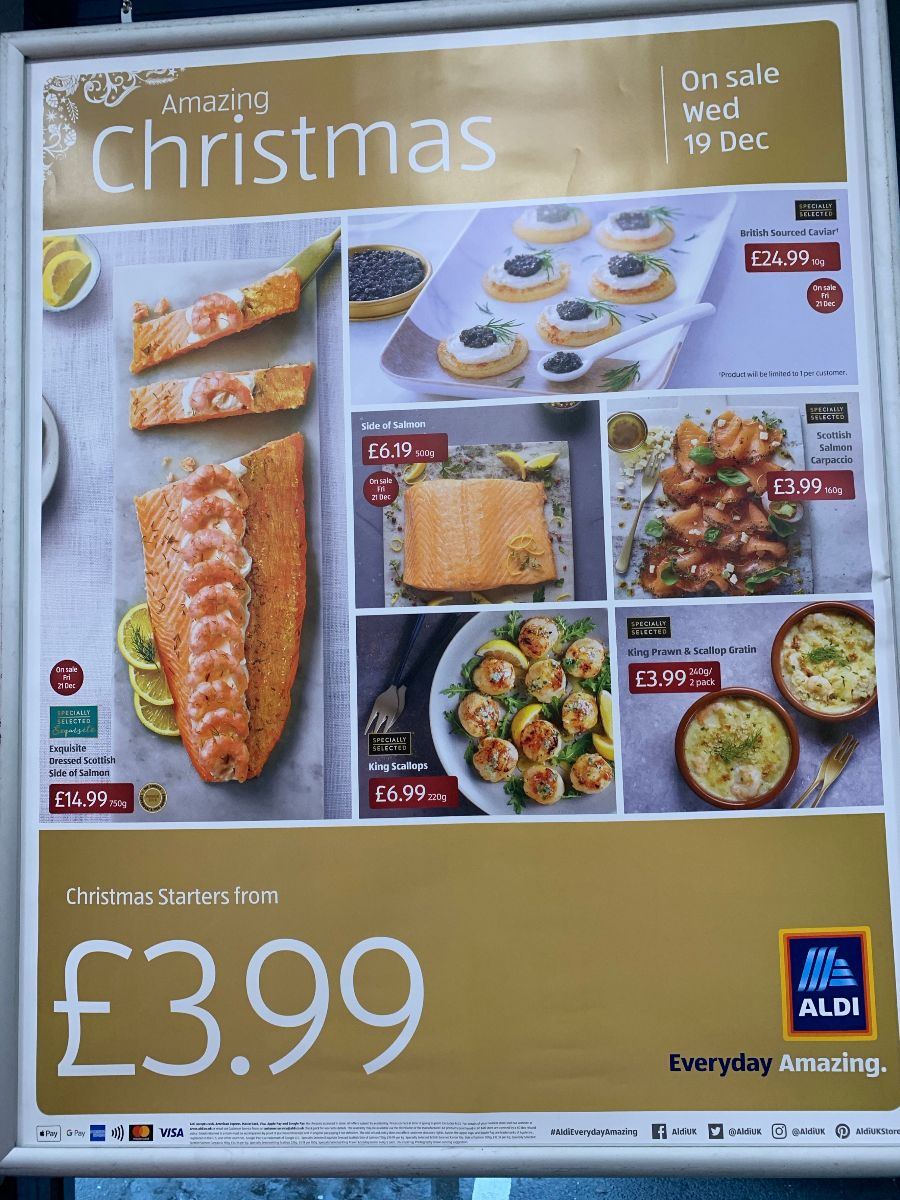
A wide range of Fish lines for Christmas shows how Aldi have grown their market share at Christmas in a meaningful way.
Arguably whilst you can level a lot at the FMCG guys for their lack of reaction to the march of the discounters, supermarkets are equally culpable when you consider that discounters have reset the price / quality benchmark on premium alongside core own label.
Indeed their expanded fresh ranges are something to behold; the sheer number of lines that Aldi and Lidl manage to add to their fresh ranges, beyond Turkeys has been a key reason for their growth at Christmas.
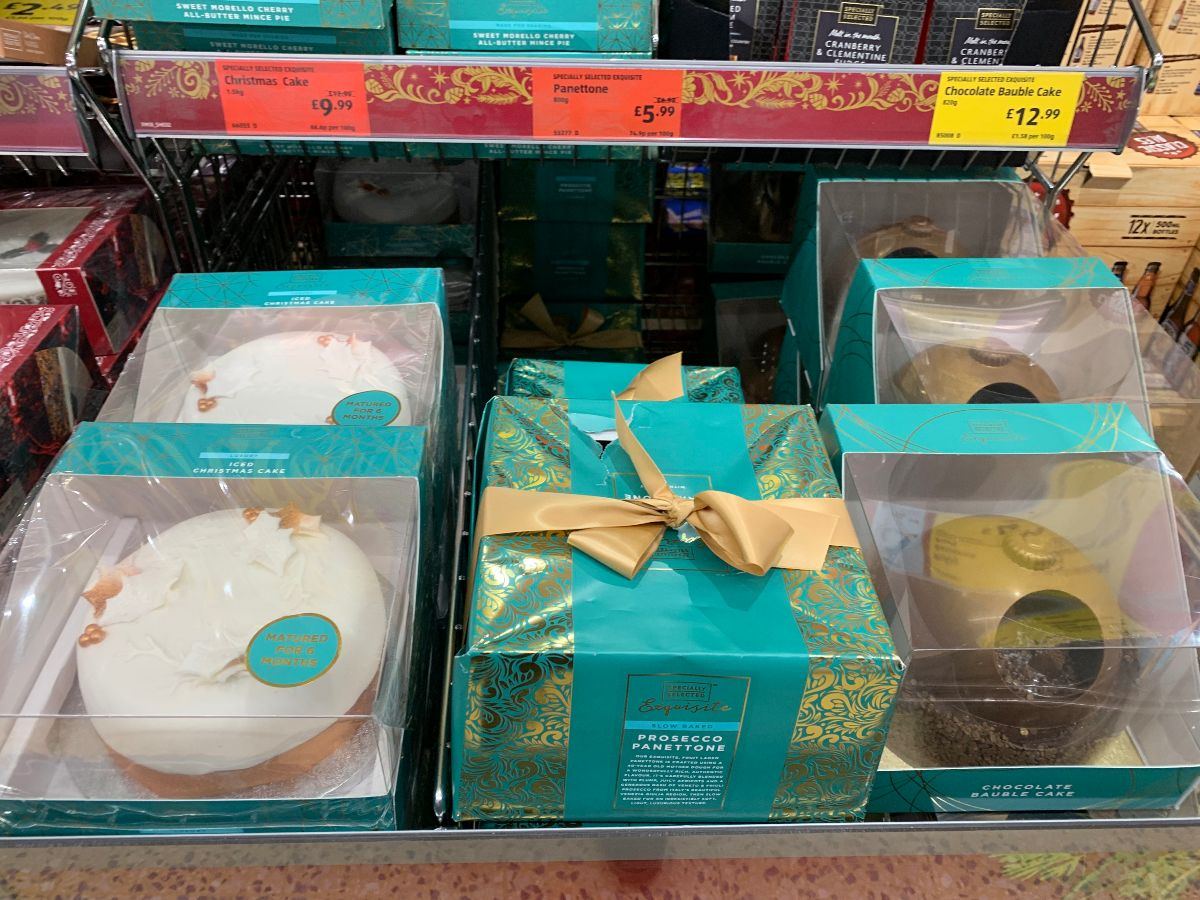
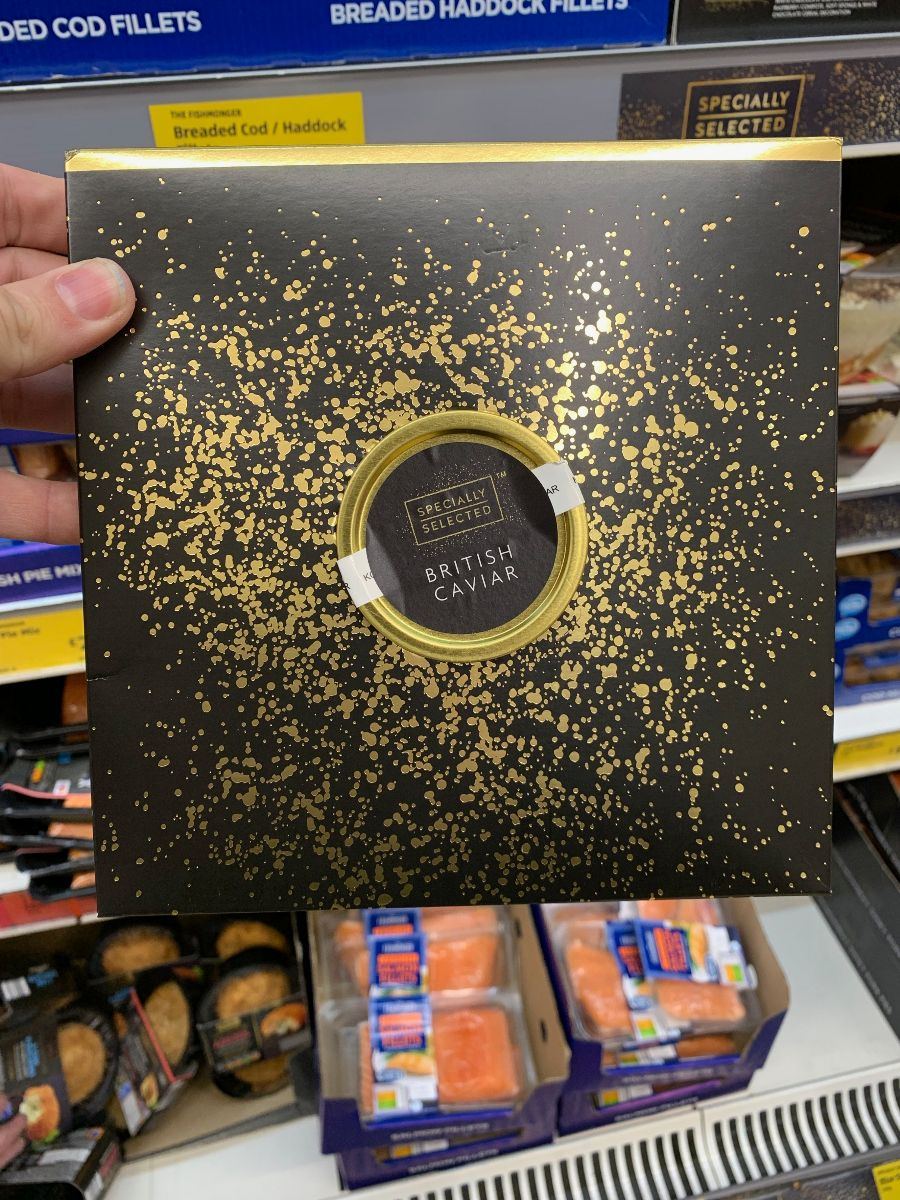
For Aldi; their Exquisite range was stepped on again with the Turquoise packaging standing out well. British caviar (from Yorkshire seemingly?) was another example of the ability to drive additional spending.
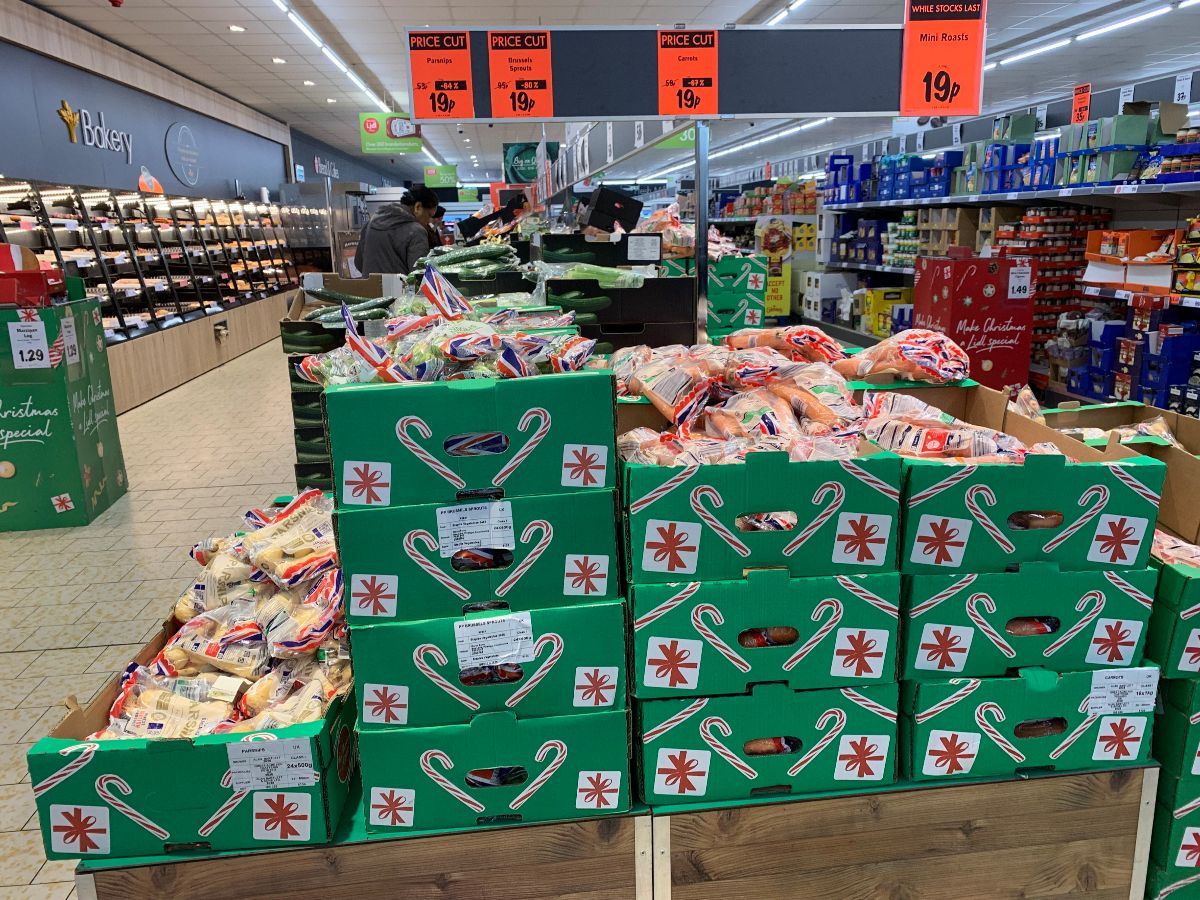
Lidl are generally run harder than Aldi in terms of staffing and often you can see the stores bereft of stock, gaps all over alongside empty cardboard and numerous shippers of branded product around the space.
Their Christmas range was equally impressive but also, laden with lots of clearance - showing that customers were guarded in 2018 and didn't overspend, reused decorations and didn't needlessly stretch themselves by over buying gifting / food / non food.
In terms of the food offer; despite the poorer shopping experience, they are keen on price in Lidl and strengthen their branded offer continuously with their "B&M week" style event which seemingly features brands galore at low prices.
Quite the strategy for branded suppliers, desperate for the volume.
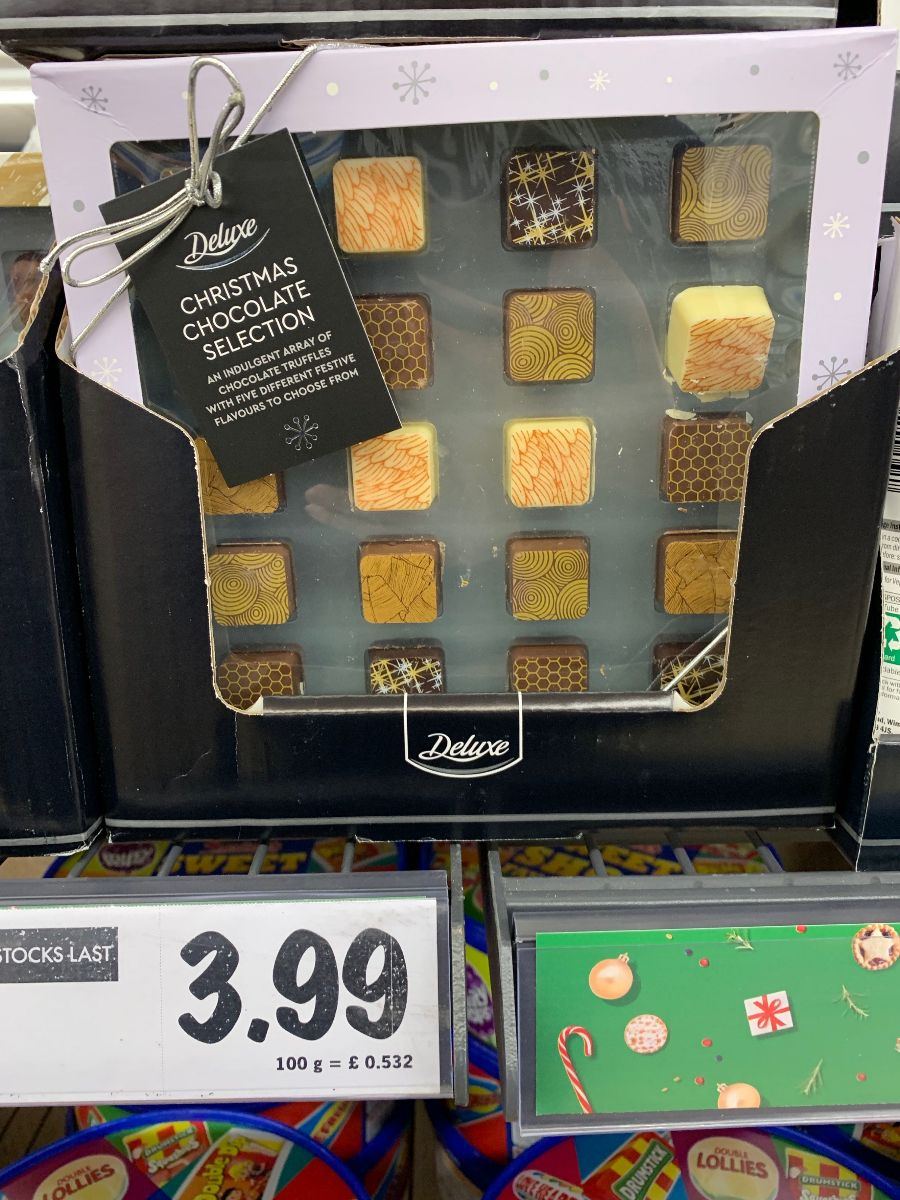
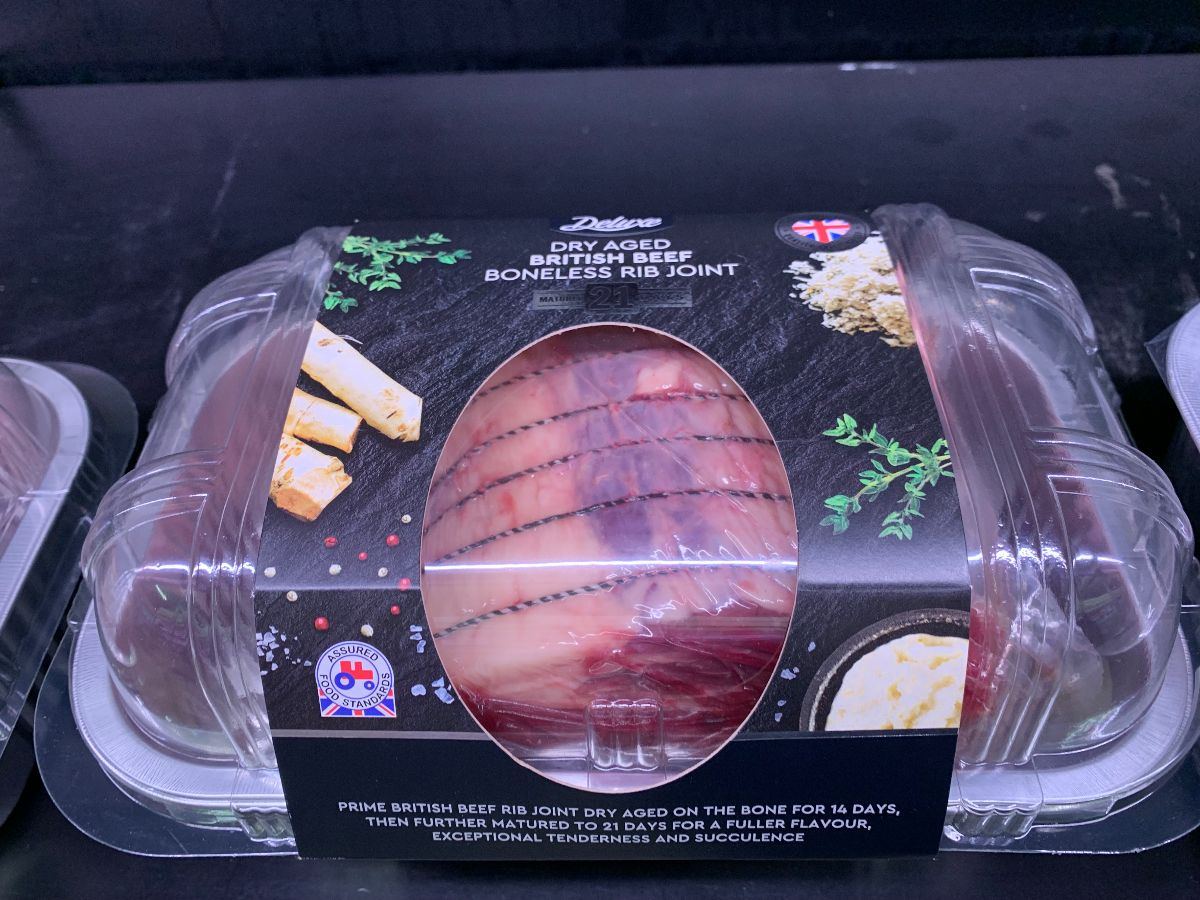
In terms of the premium ranges above; some strong work in Rib joints in Beef and their wider Turkey offer worked well too. Their Deluxe Christmas selection Chocolates was a good example of where their premium range has taken them.
19p Produce tells its own story as the lead offer too.
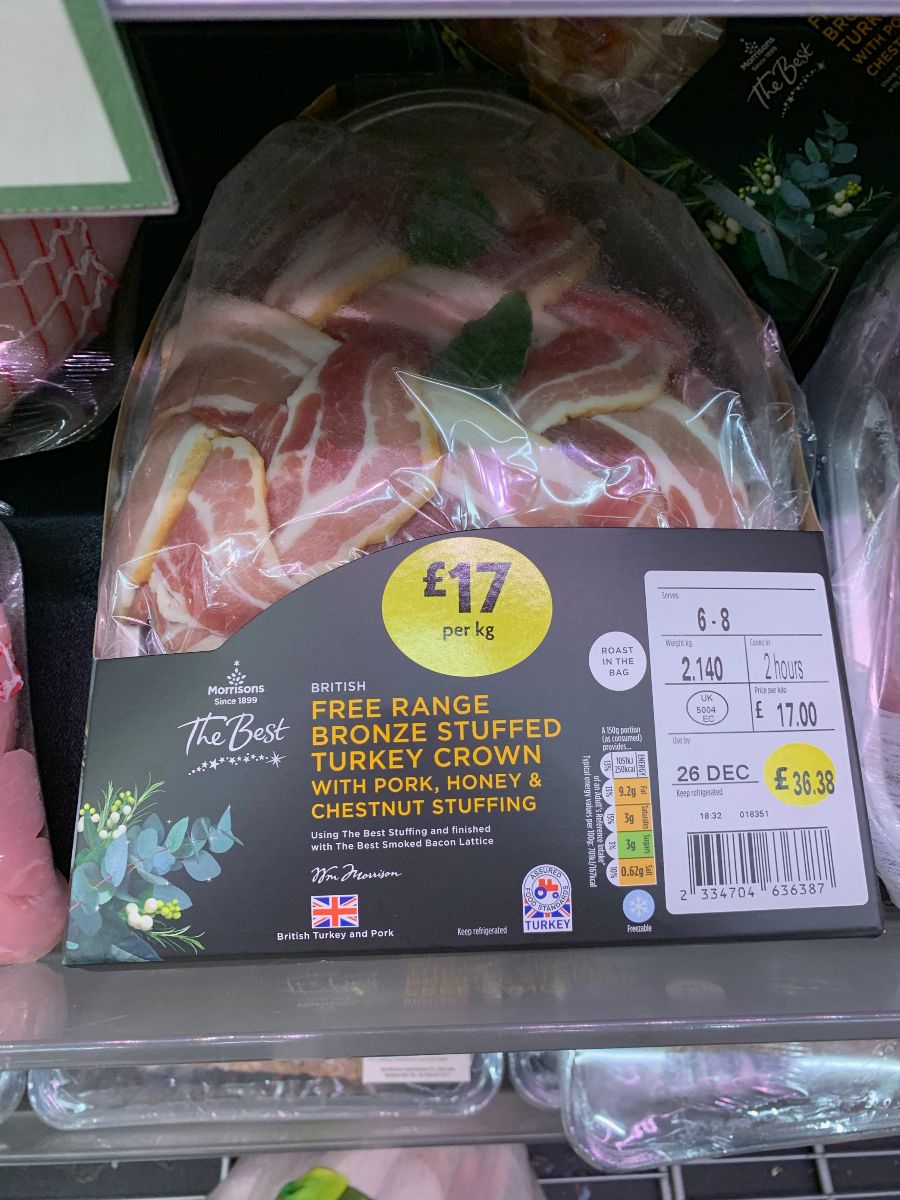
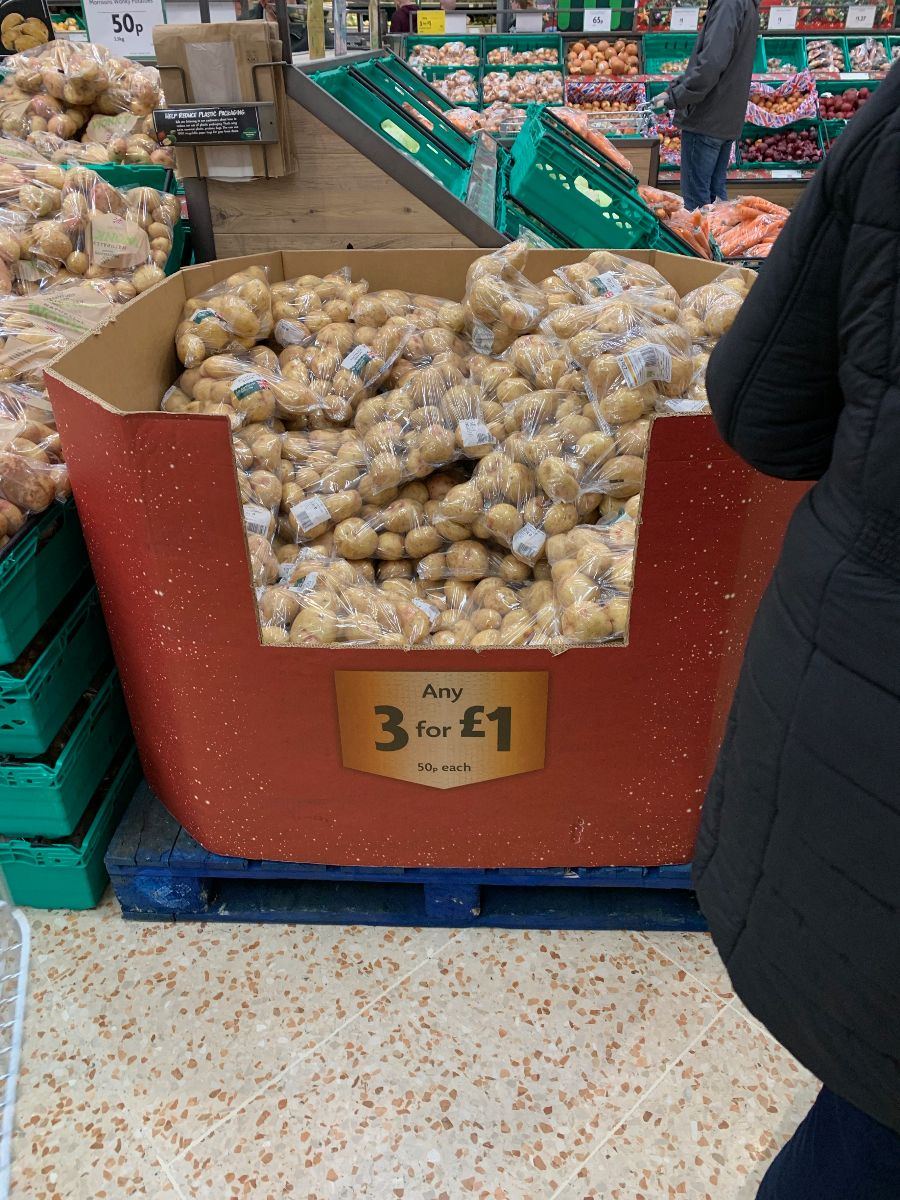
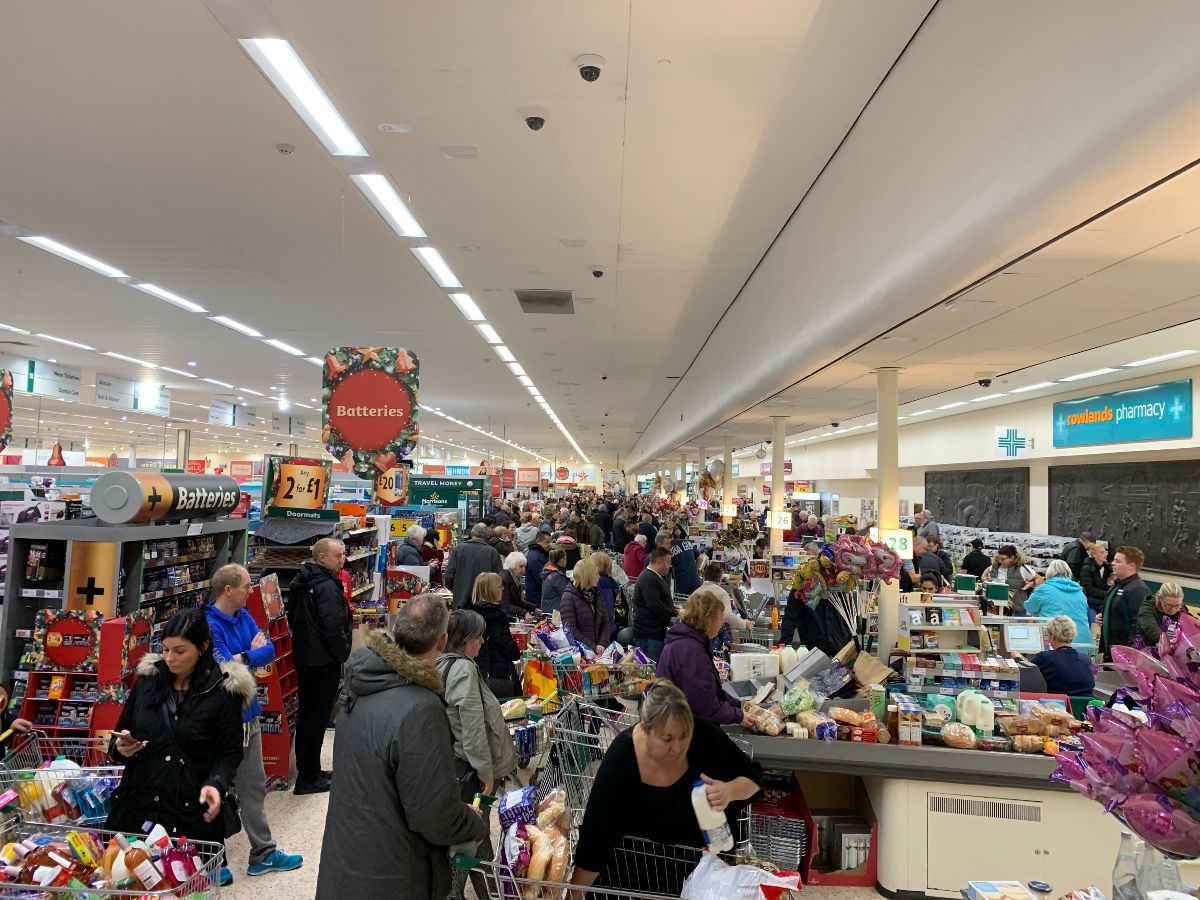
Morrisons results for Christmas are released soon (as this email is written the night before but delivered before the results announcement) and the analysts appeared to be rounding expected growth downwards over the weekend.
Wholesale separate of course as this is a separate business unit and continues to show strong growth, given the McColl's deal alongside Amazon and other efforts.
If the results are in line with expected figures, then it's a fair result for Morrisons given their like for like a year previous was way ahead of expectation at +3.7% for the 6 weeks of Christmas trading.
Growth on a strong number is still growth and with a difficult marketplace given a spending slowdown and late, late spending (when it came) meant it wasn't an easy Christmas at all.
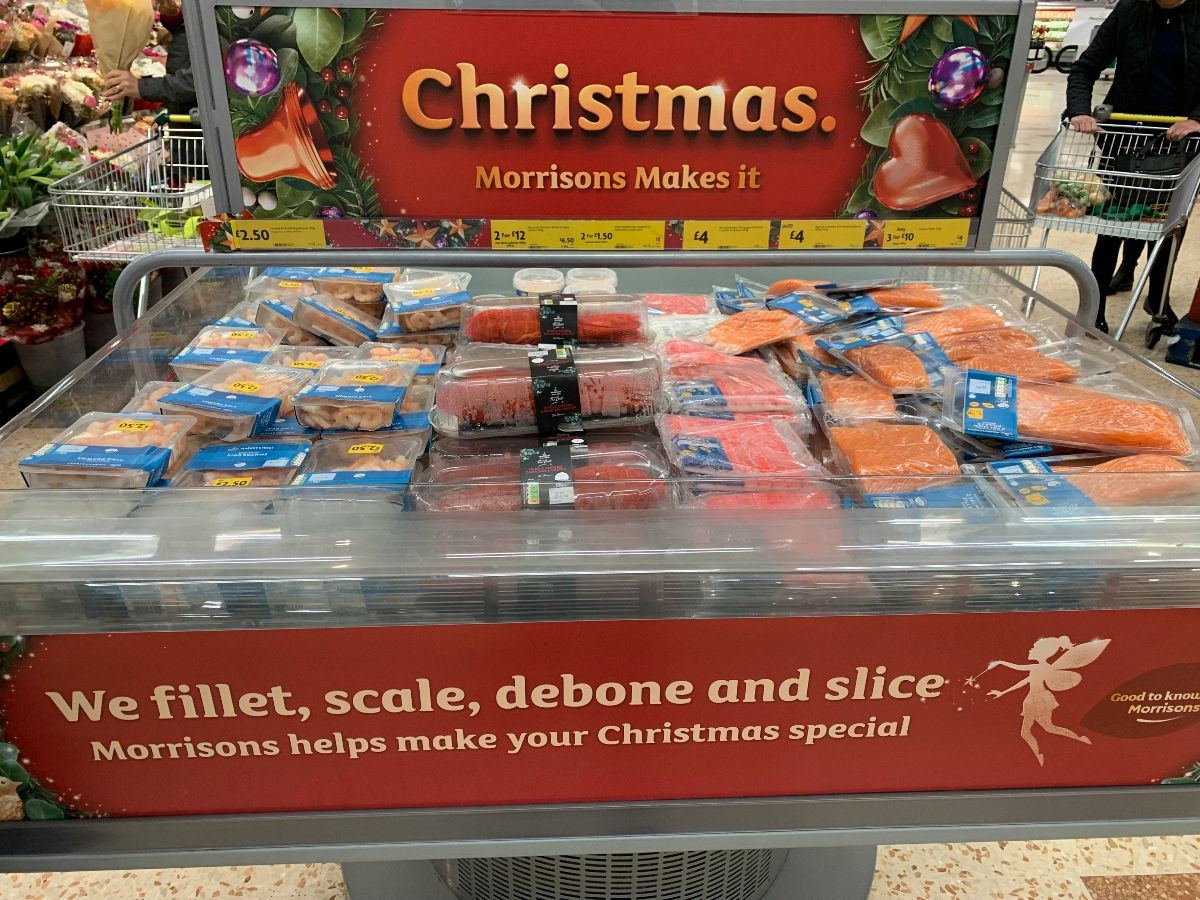
The focus on Best for Morrisons was clear in store and their improved quality was noted with Mince Pies winning the coveted Good Housekeeping award, equally "Best" Turkey crowns in the image also looked strong. Morrisons do a good job of offering the trade up option for customers at each festive period.
Big deals around the store, including Produce (3 for £1 on leading Veg) meant the value for money was there, however clearance levels in wider Christmas have been heavier than last year, like the market which is laden with Chocolates, Crackers and Christmas cards.
Ironically a year before, there was a struggle to get a Christmas card in Morrisons beyond mid December. All pointing to that spending not coming through from the customers.
Sunday trading was an issue with the day falling on the 23rd and queues up the aisles in numerous stores by 10am. Near madness and hardly helping sales, but the trade did come eventually.
However despite the trade coming; spending was tighter and clearance levels across the space are heftier than the year before.....
We all look ahead to Morrisons and their results, but they're in a good place with momentum so their figures will be a decent barometer before M&S, Tesco and Sainsbury's.... A retailer definitely without momentum....
Join our email service to receive market leading insight
From the Grocery Insight newsletter archive, first sent to subscribers on 8 January 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.