There's always a price war
10 January 2019

Join this service to receive more insight like this
There's always a price war in the market..... However in recent times there has been a continual drumbeat from Aldi and Lidl about their prices being lower, backed up by customers shifting to an EDLP based price message and understanding it.
Whatever anyone does in the market, Aldi / Lidl generally go lower by 1p to maintain leadership. It becomes a war that can not be won really by any of the big four.
However in recent times; Tesco launched their brands under the Value tier banner and aimed to match up to Aldi / Lidl on price with a degree of success.
However it is deflationary; bringing customers to cheaper options means that retailers to have to sell more to make the numbers work. There can be an impact to the like for likes as customers pay less but with the overall win in sight - you can attract customers to spend more with you as a retailer.....
Certainly Tesco had this in mind when they targeted Meat and Produce with their farm brands a while ago now and that certainly had the desired impact to bring people back from discounters.
However we now see another trend; that is customers opting for cheaper alternatives in the premium tier. Impacting Waitrose notably, Sainsbury's (although their offer is not compelling) and M&S (although more to come / they are reducing prices now so expect like for like pain before volume swings)....
Therefore ahead of results shortly for Tesco and M&S - what's in store in the wider market? Tesco have some big news of their own in the first instance - it's their birthday!
For the price war (of sorts) we start where any self respecting person starts when considering price movement - Walmart owned Asda....
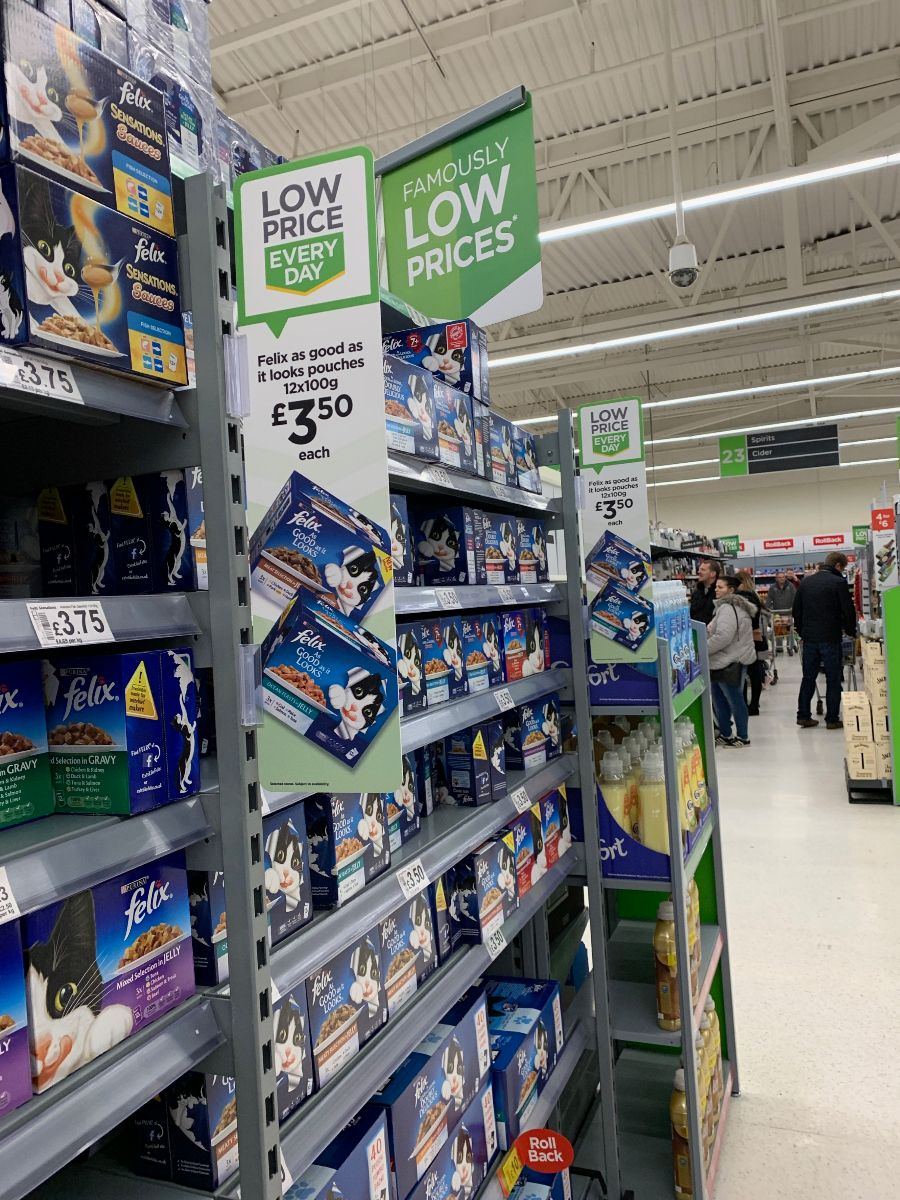
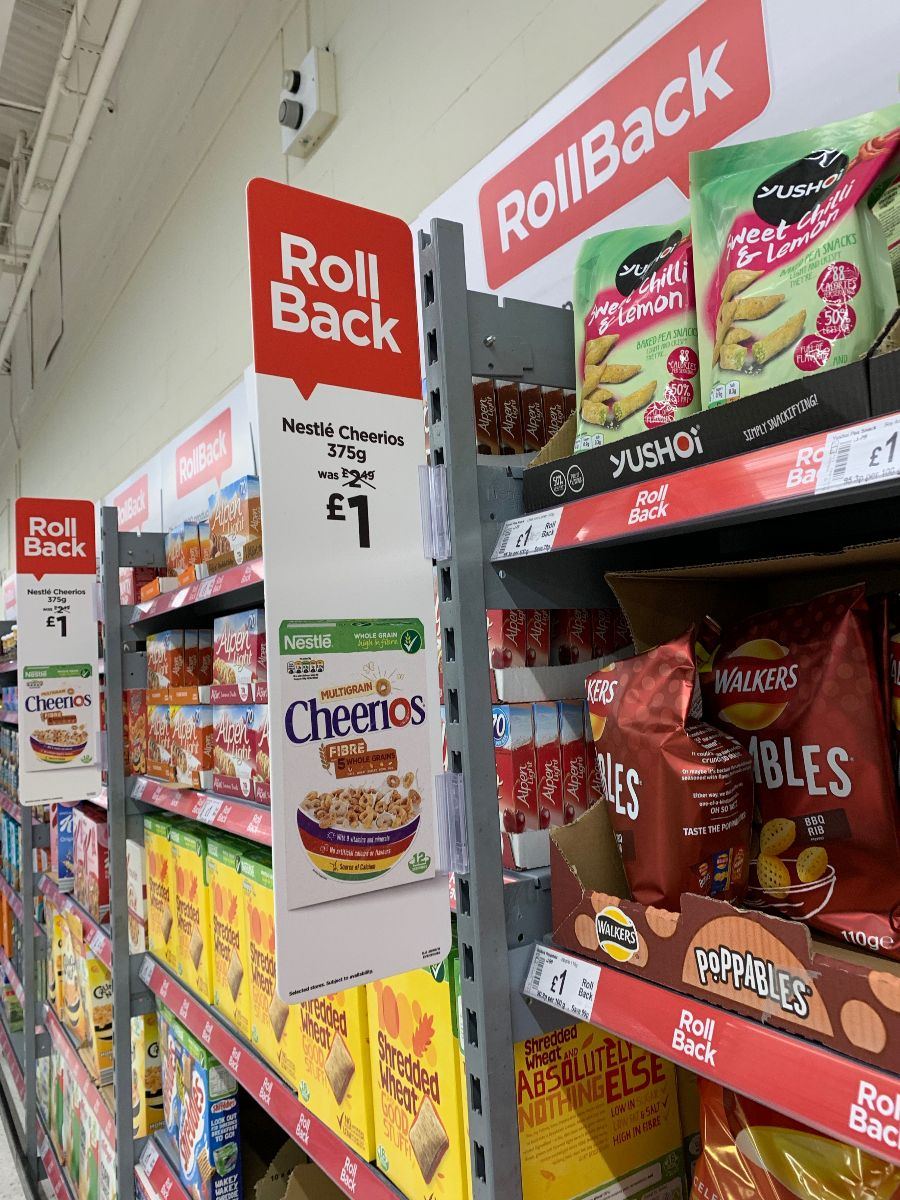
Rollback kicked off again in January; lots of focus on health and key brands of course. Always popular; their 'rolled back, staying back' campaign has worked well - locking down prices.
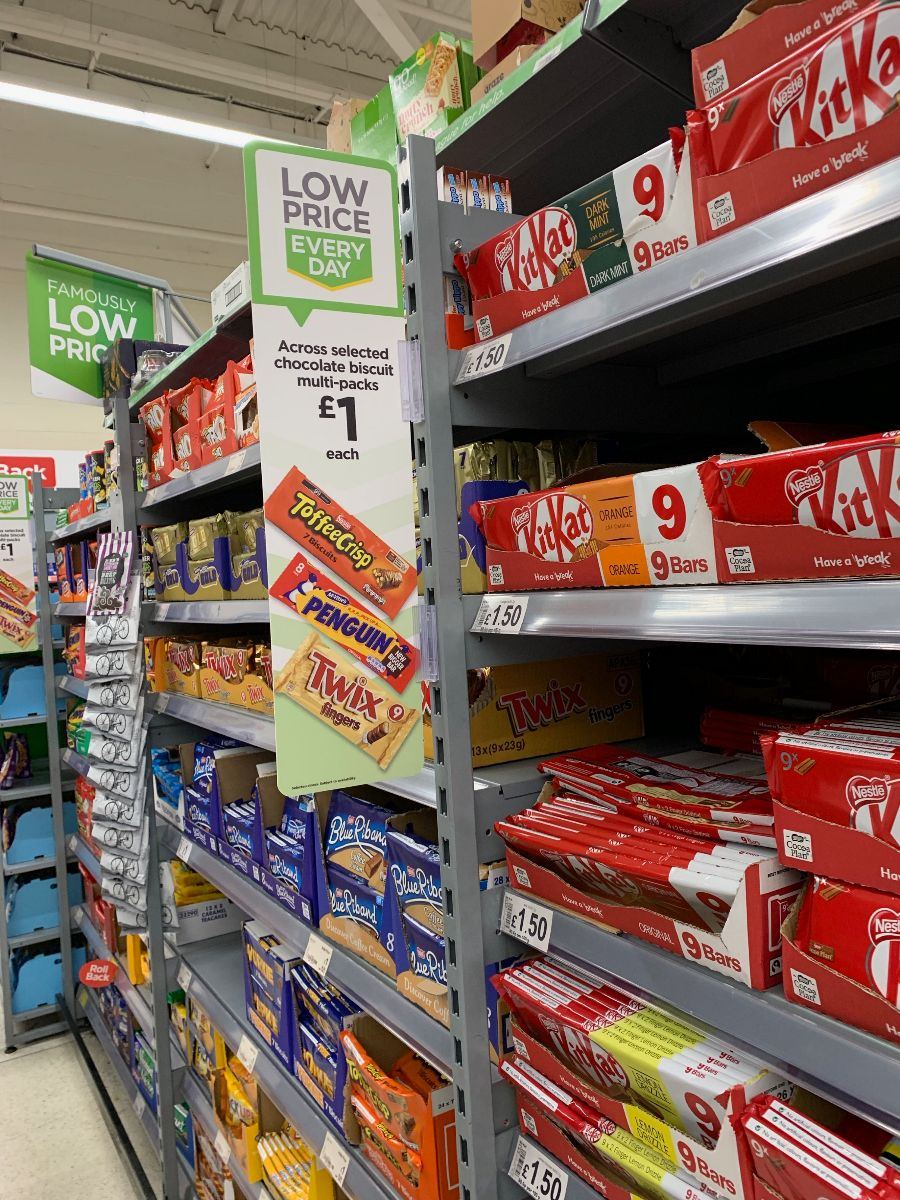
This has been replaced by a 'low price, every day' message which centres around key lines being pegged at £1 or similar.
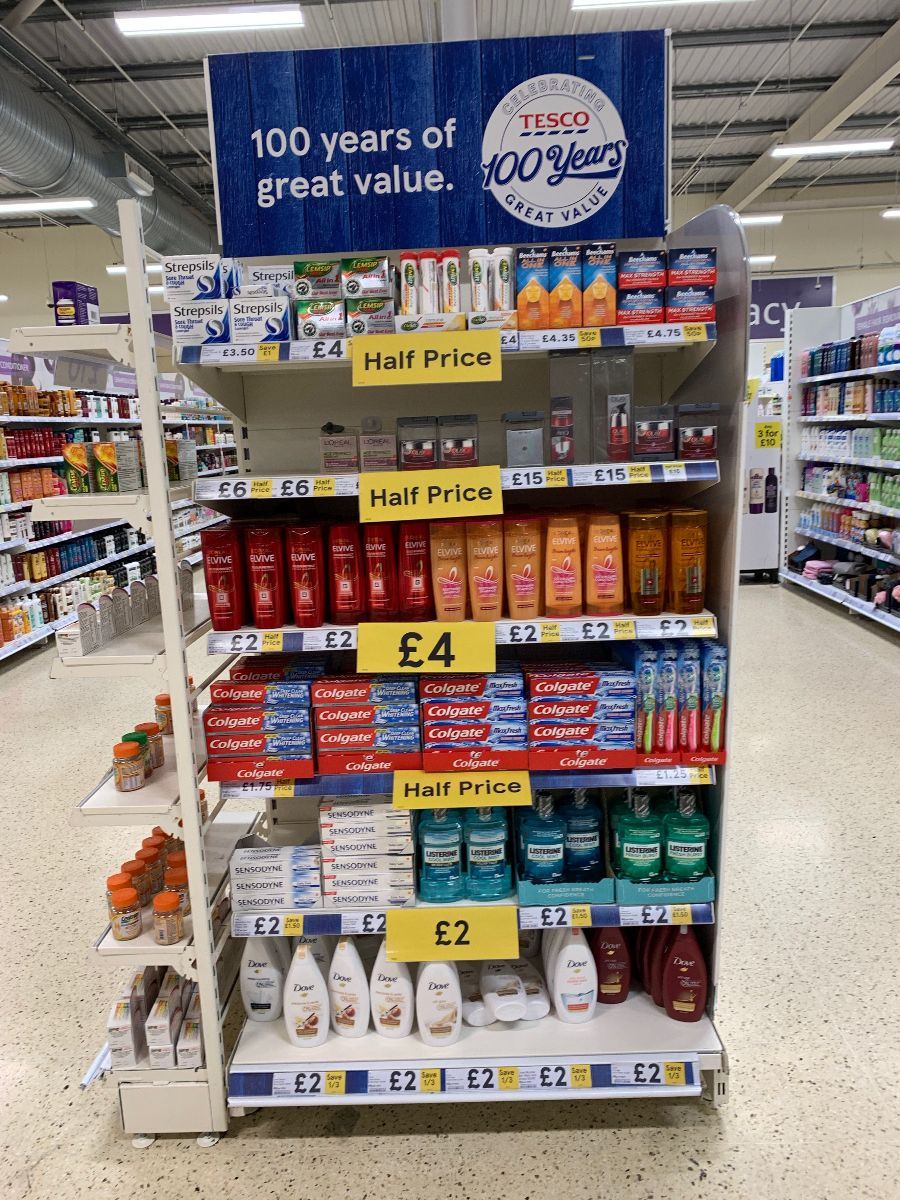
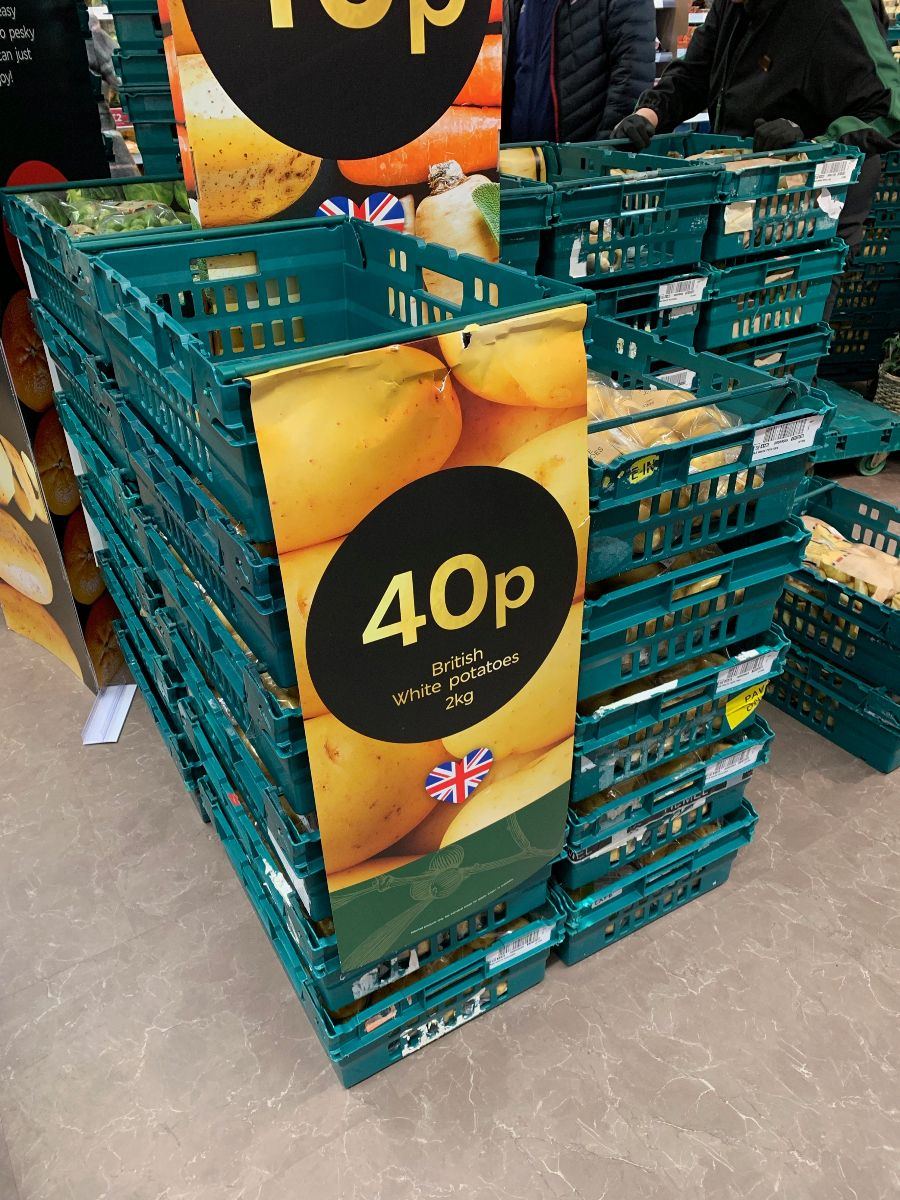
Tesco celebrate their 100th birthday this year and as part of their centenary celebrations - they have kicked off '100 years of great value' with various deals across the store - many are better than half price and offer strong prices to the customer, at a key time too.
Their Christmas appears to have been a solid one and once again, they have navigated difficult territory and seemingly grown sales if you believe Kantar and the wider market opinion.
They were well set up for my money, a close 2nd to Asda in the set up stakes and offered a strong, broad offer that merged value and quality well. They do a good job with Finest but it's not everywhere as the temptation can be sometimes at Christmas.
Equally they will be pleased with a positive result (if it comes) given that they relaunched and gave a degree of fanfare to their relaunch of the value tier under the various sub brands.
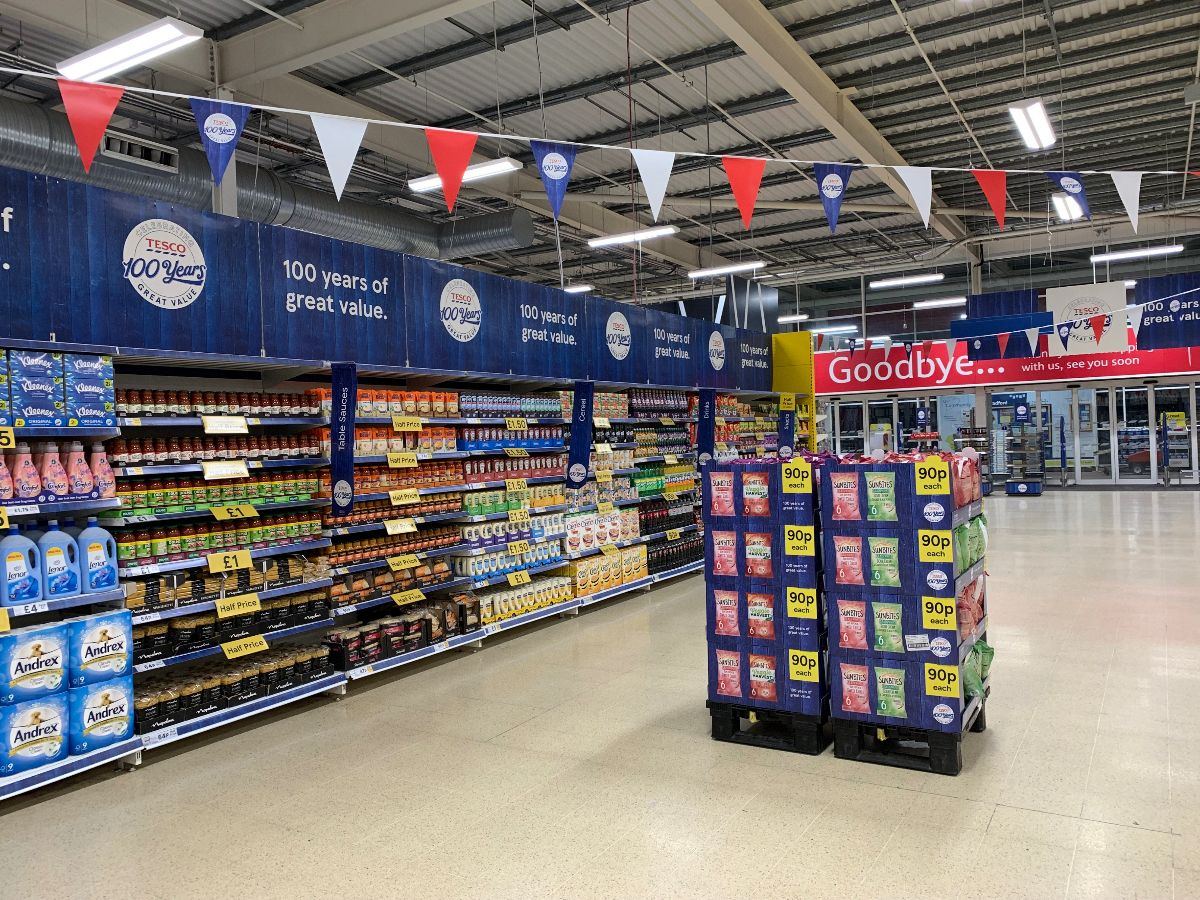
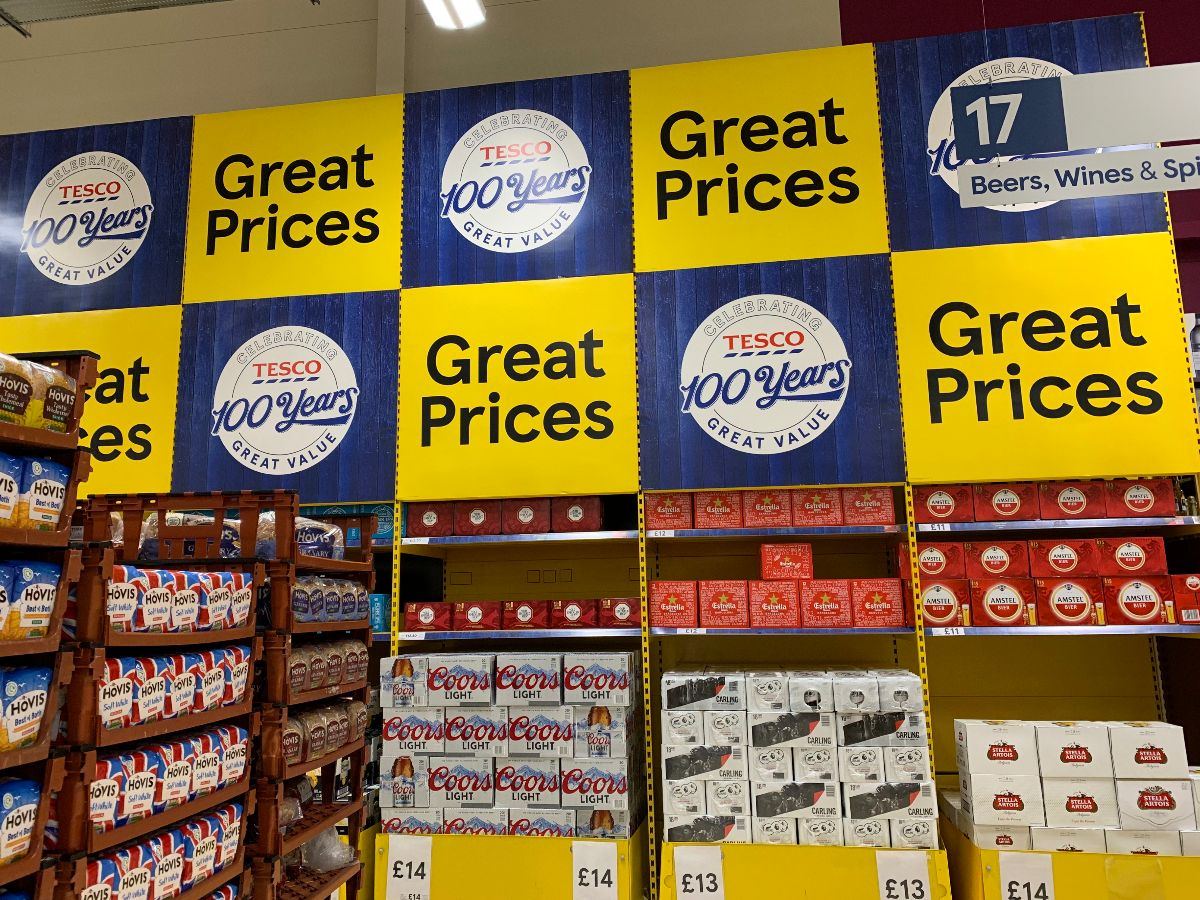
Strong signage work around the store for their campaign on price, expect an ongoing message around this throughout this year.
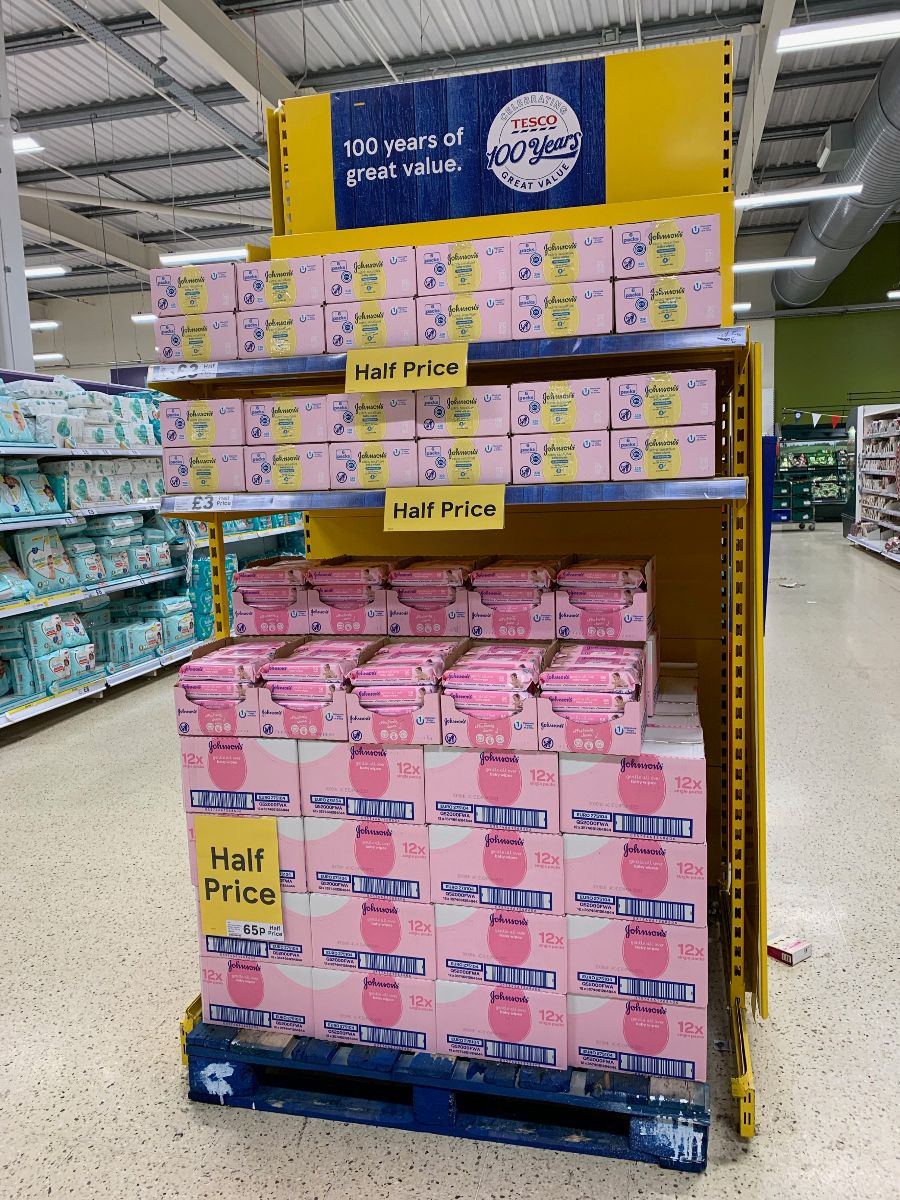
A strong focus on baby and also seasonal space is given over to Nappies - both branded and own label which is a vital piece of work these days for Tesco - giving love and presence to the own label.
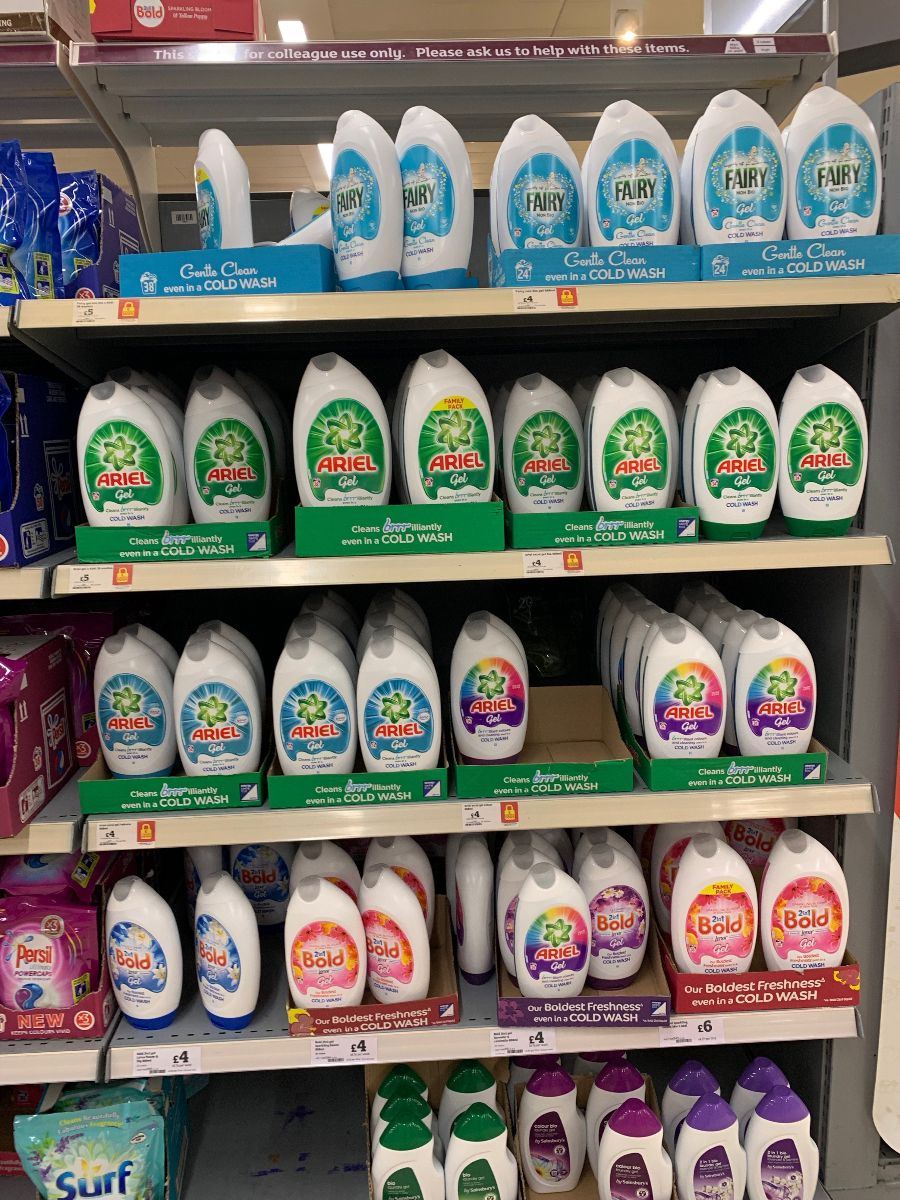
As nodded with the JS email yesterday morning, results were not great and with Argos in that number - arguably even worse. Especially when you consider that Argos stores inside a Sainsbury's were up 10% and Toys etc should see a better result for the business.....
Food wise; their down trading from premium was alarming in that it seemingly indicated that their own offer wasn't compelling enough. Where did customers go? Are they going to return any time soon?
A challenge on the horizon for Sainsbury's and the well worn phrase around 'leading service and availability' doesn't stack up with like for likes dropping for the wider business.
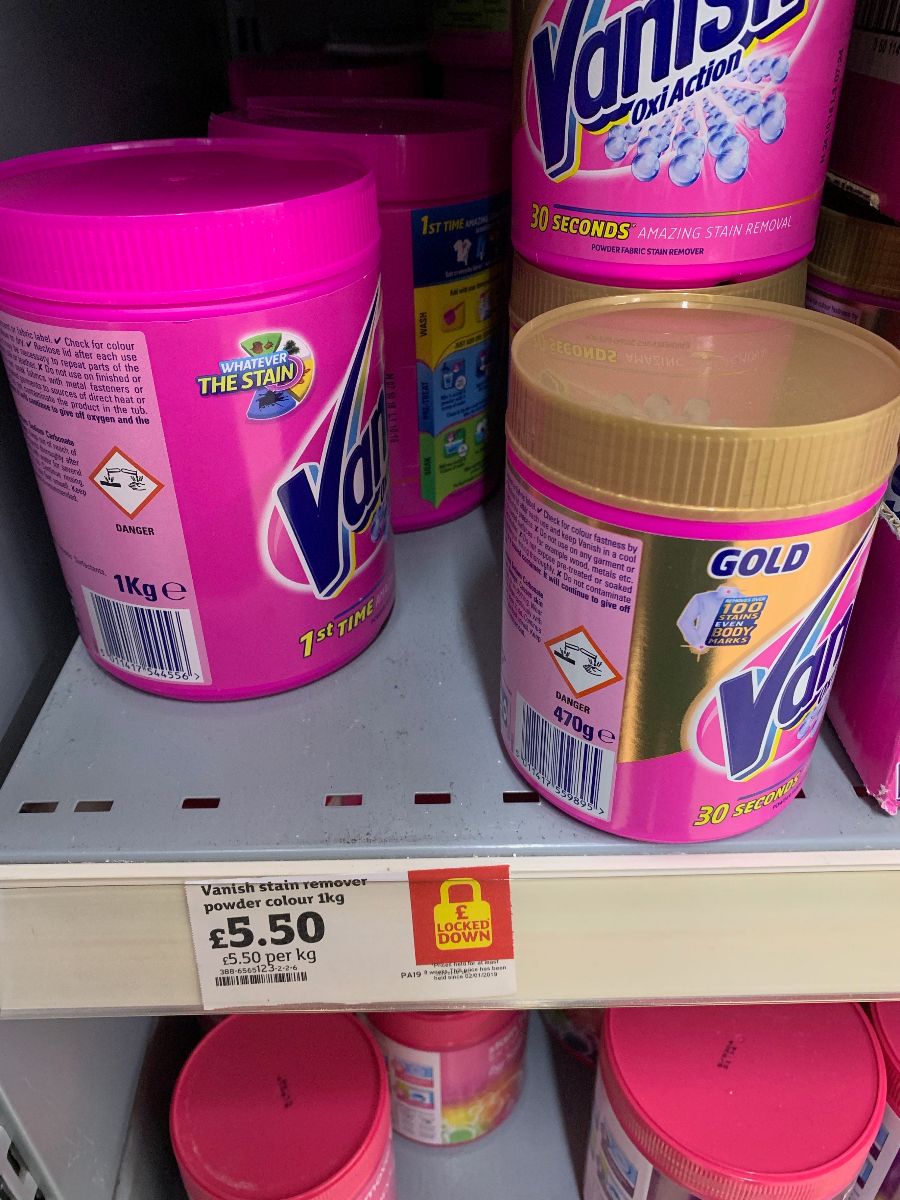
As noted, they are too in the price 'war' of sorts with a price lockdown message across numerous brands in Health/Beauty and also household.
Some are lower than the market and pledged not to rise within the next 8 weeks (which seems odd?) Week 9 = increases? But the lack of own label is a struggle to understand given the market preference for this tier in the wider world.
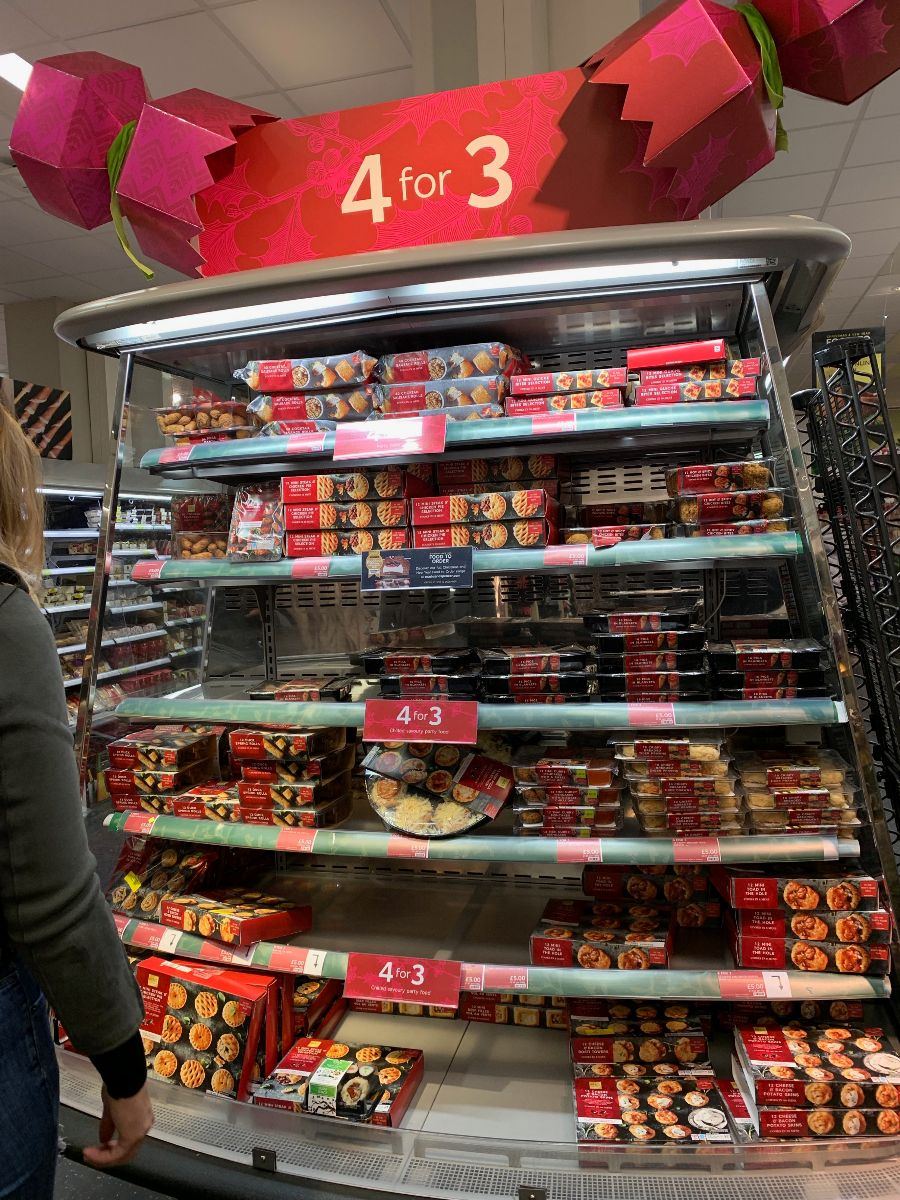
As the old saying goes "the ones who admit they have a problem are halfway to solving it" (or something)..... M&S food from afar, until maybe last Christmas were continually putting on positive like for like, always wowing us with innovation and running decent shops too.
However they started to run out of steam in Christmas 2017 when they misread the market, added even more premium range (difficult for M&S to do premium given their strong credentials anyway)....
Then sales were on the slide and this continued, more and more lines went on to a meal deal offer (virtually all cuisines from the takeaway range were on a deal) and multibuys were commonplace - ready meals hit 3 for £9 at one point with inflation and it became more and more expensive to shop there.
However this was recognised as an issue and new leadership in Food, alongside Archie Norman himself as chair have started to steer the ship in a more EDLP based direction.
Not an easy task for a business who generally sell higher quality, higher priced food from 'food halls' to start churning out volumes but it's the only game in town to play really...
They were focused at Christmas on their plan with deals around the store but price also in focus. They'll never be cheapest in town but they still have that strong quality message and resonance that customers appreciate.
The challenge is highlighting that prices are being reduced in a meaningful way (with a sense of permanency) and that the quality is worth paying that bit more for too.
4 for 3 on party food is a deal that's worth keeping on and there's no need to go down a 'no multibuys' route ever really. Why nullify yourself with imposed rules?
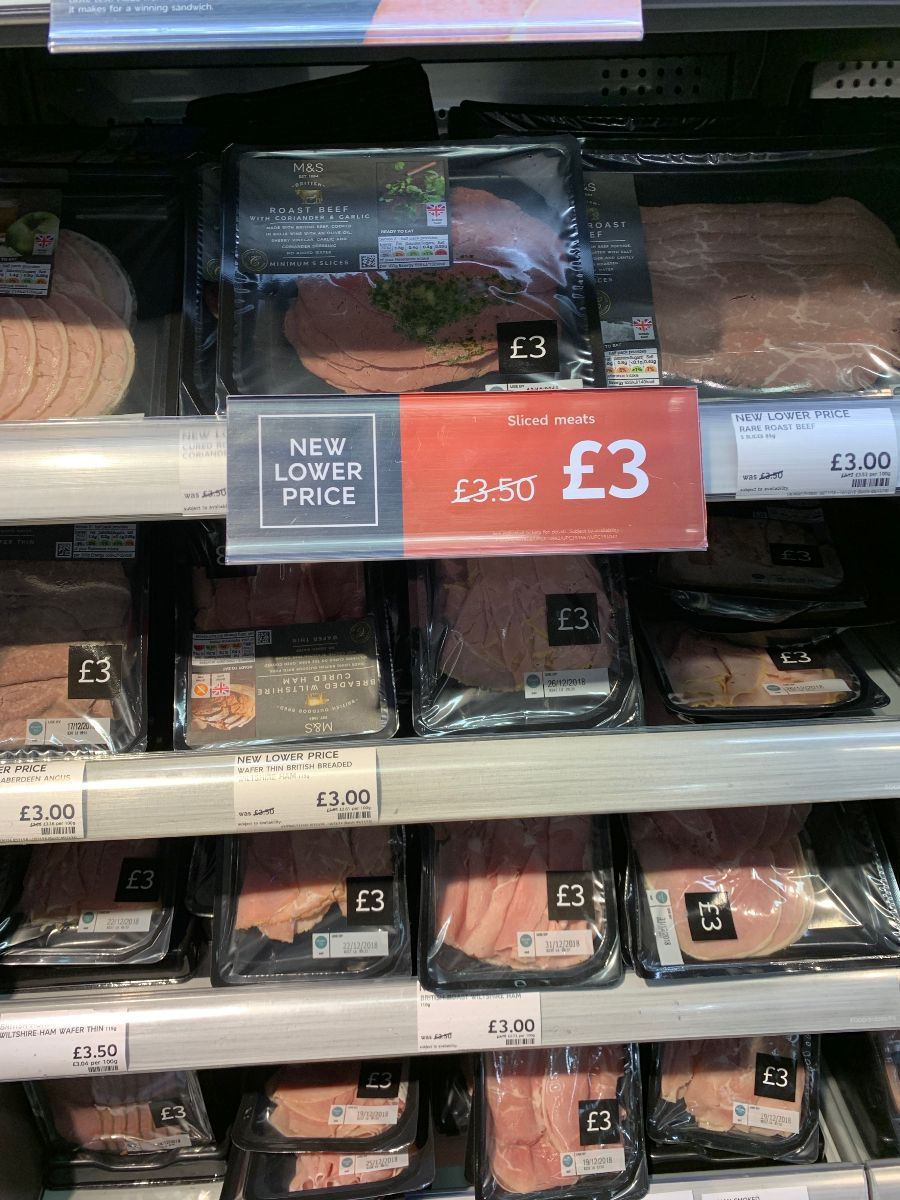
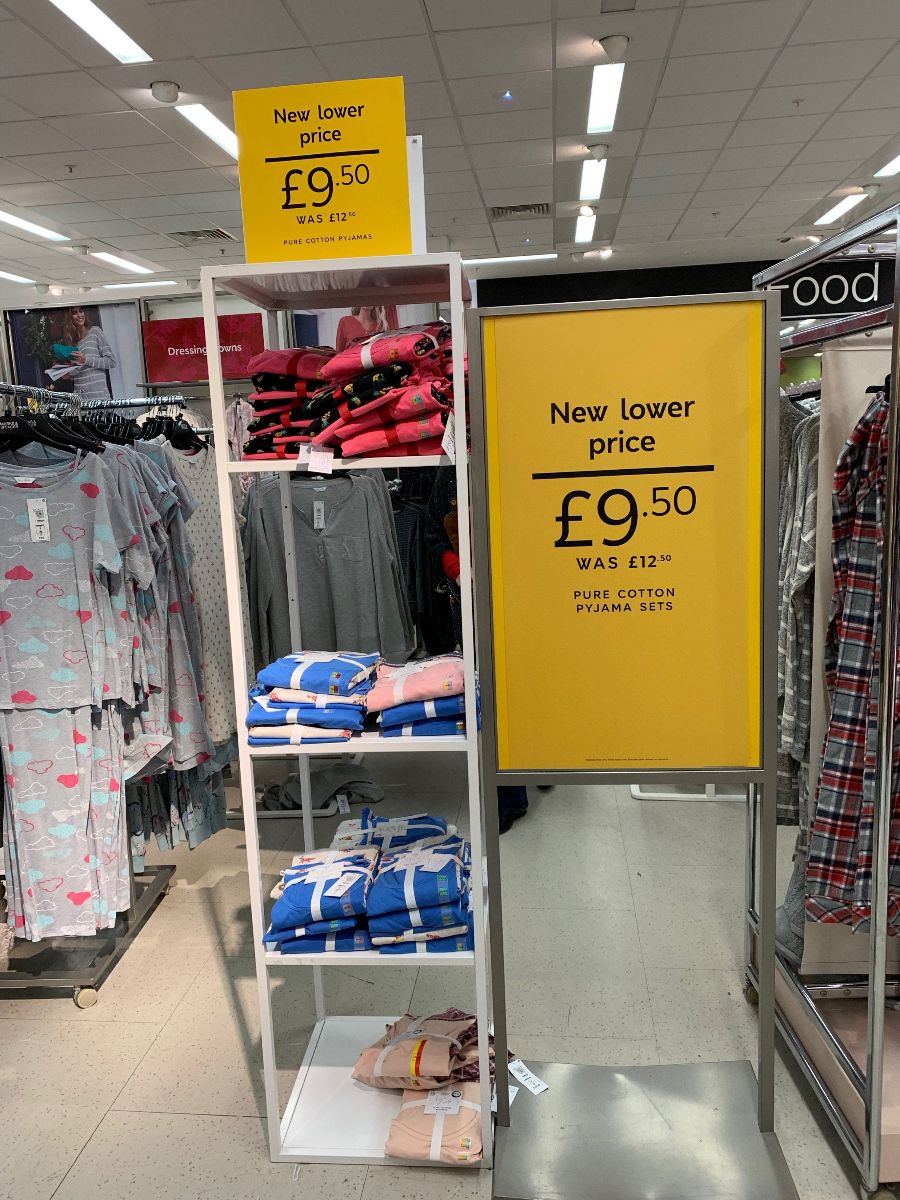
Lower prices across non food and food in a number of categories - a longer term play quite clearly and it'll be a while before the figures start to come through on the like for like....
But a longer term plan is necessary as you can't run a business on more meal deals. Not when the discounters are churning out their premium lines (and beyond) at Christmas (and year round truth be told).
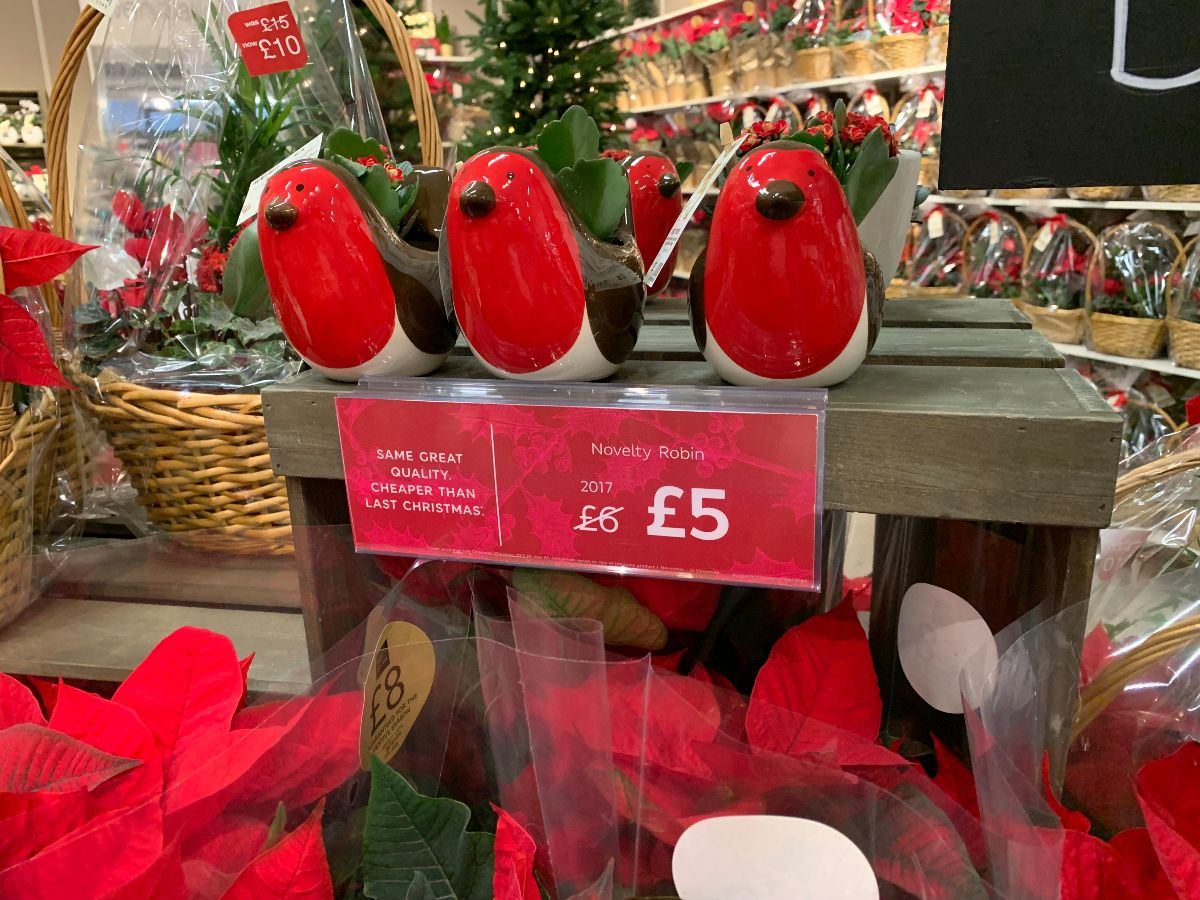
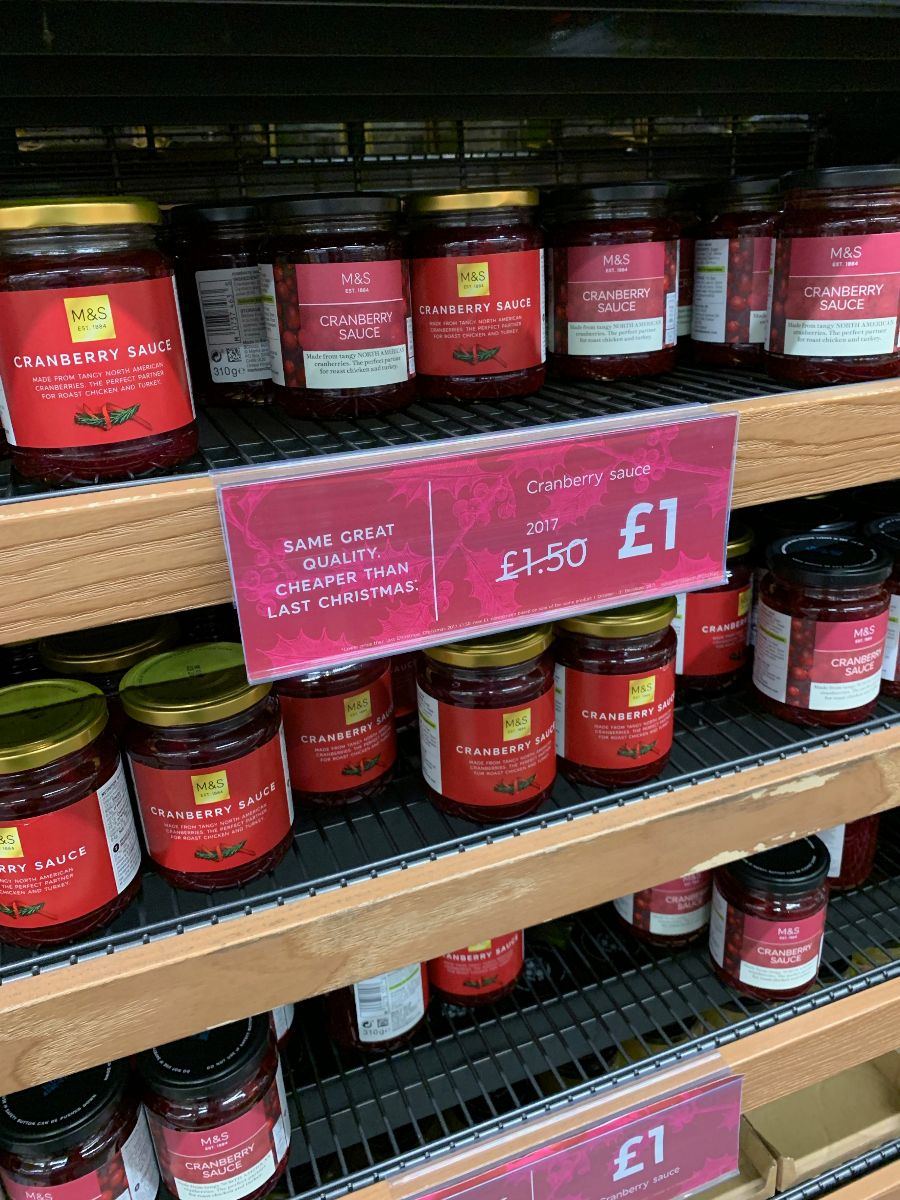
Numerous messages around the store pointed to lower prices versus last Christmas in M&S.
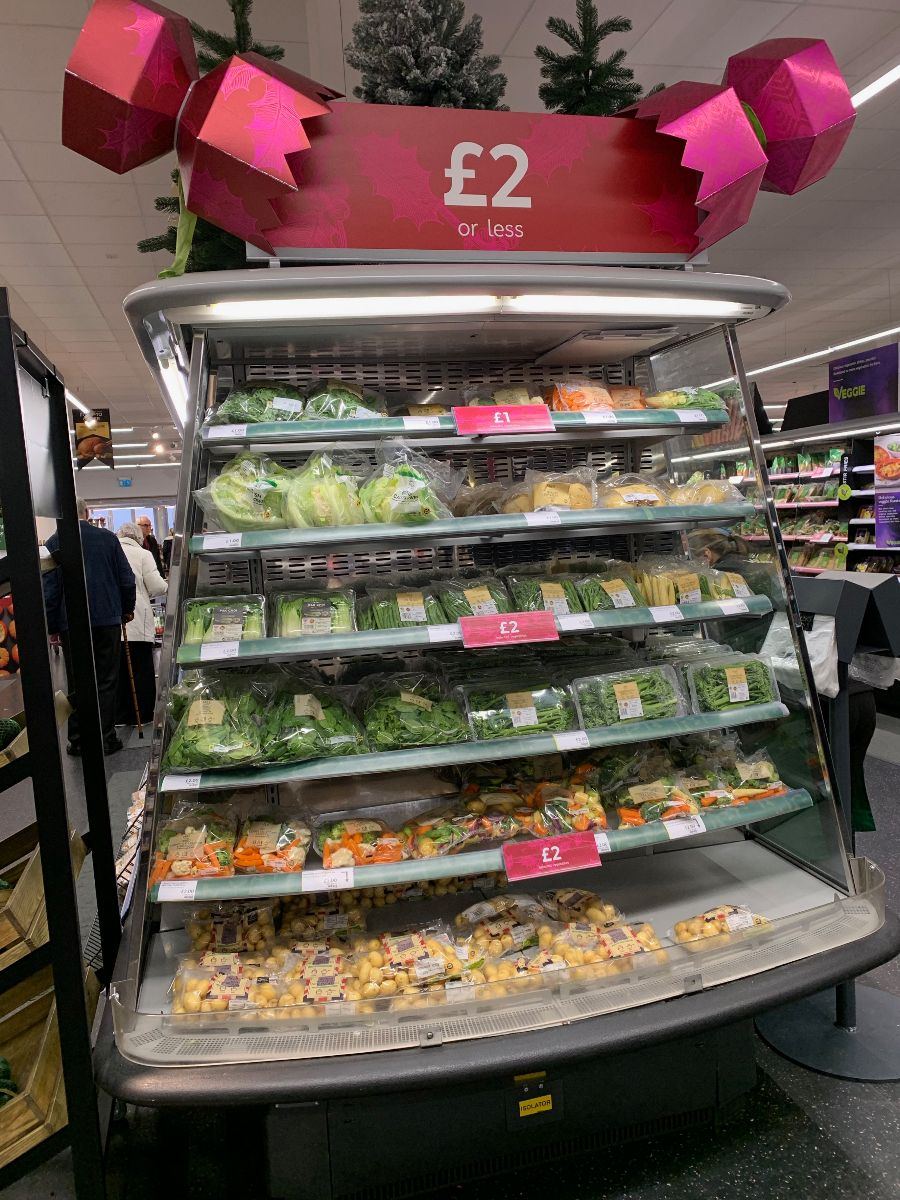
Price based ends were also noted!
M&S can be a place that is known for quality but also not insult pricing but it'll take time to turn the tanker around - anything that turns down the ease of sales via promotions and favours a low price, longer term play always does.....
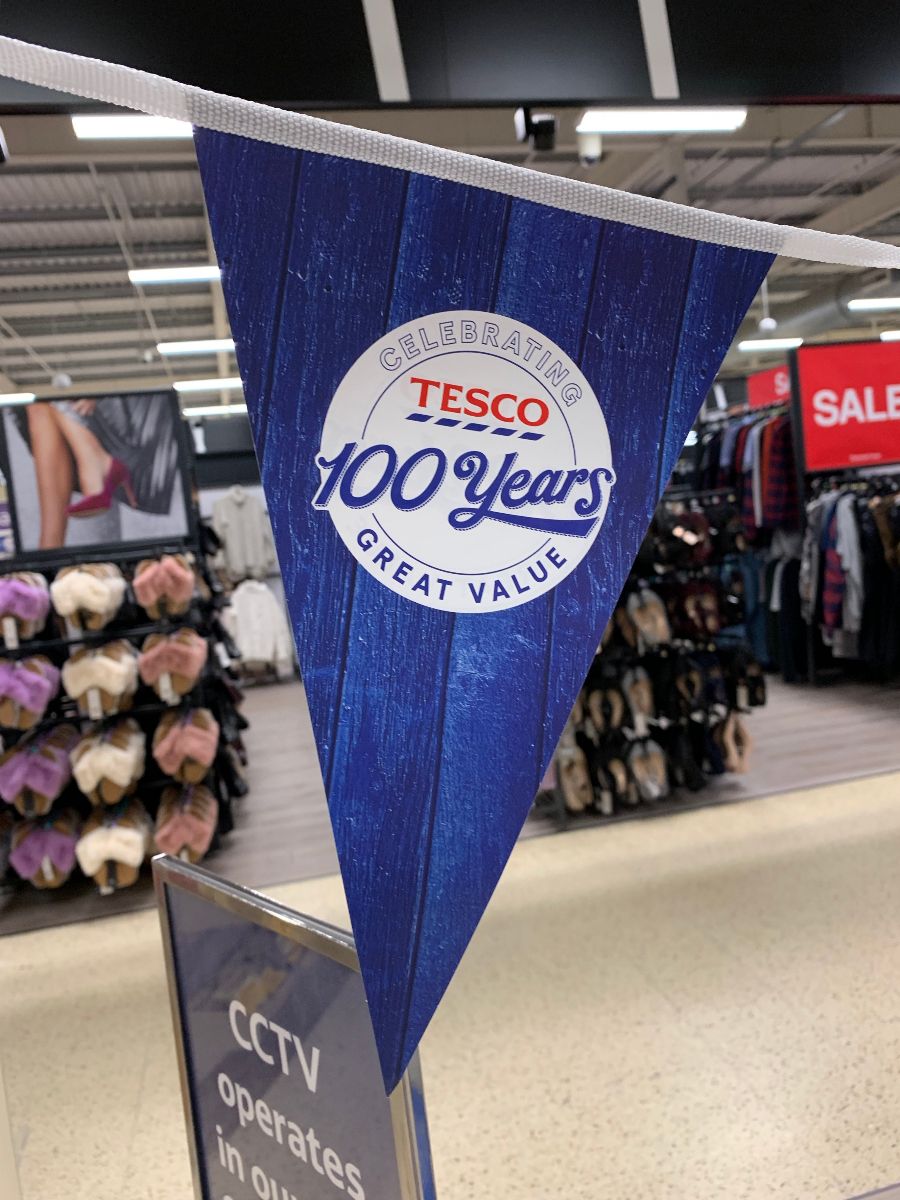
That said; whatever anyone is up to in the market. The Tesco machine looks like it's ready to have a good 100th year and celebrate with deals aplenty.......
More reviews and digests to follow once the results are out tomorrow - over the weekend there'll be a wider consideration for what we saw, particularly at the top end of the market (Waitrose and M&S) Tesco and also what about the wider question on Sainsbury's.......(?)
From the Grocery Insight newsletter archive, first sent to subscribers on 10 January 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.