Tesco - Further brands update
10 July 2018

All the best to Charles Wilson as he battles Cancer and we wish him a speedy recovery.
A brief radio silence over the past couple of weeks as the industry navigates wider stories like the Co2 supply issues, Tesco/Carrefour looks to be confidently asserting that we'll have no customs union issues with goods and supply thereof.
However the David Davis exit adds yet more custard to the already trifle based disaster.
England have progressed brilliantly in the world cup and coupled with a hot summer and some issues with co2 but not huge numbers - it looks set to be a strong Summer for all retailers. With inflation coming away slightly, those in the trade should be watching the figures very closely post Summer to see who made 'hay' whilst the Sun was indeed shining.
We'll look at Sainsbury's results later in the week but were those results, given the Argos addition to the business, the inclusion of VAT in the figures (a major deal if you're counting Non food lines) and a strong trading period thru 30th June (great weather, Easter, Mother's Day alongside the world cup) good enough?
They were trading against a strong Q1 number in 16/17 perhaps but still, one may expect more growth from Sainsbury's here. They did cut prices and that understandably has an impact, but the good weather must increase the Argos appeal given their range of outdoor toys and the usage of Fast Track et al.
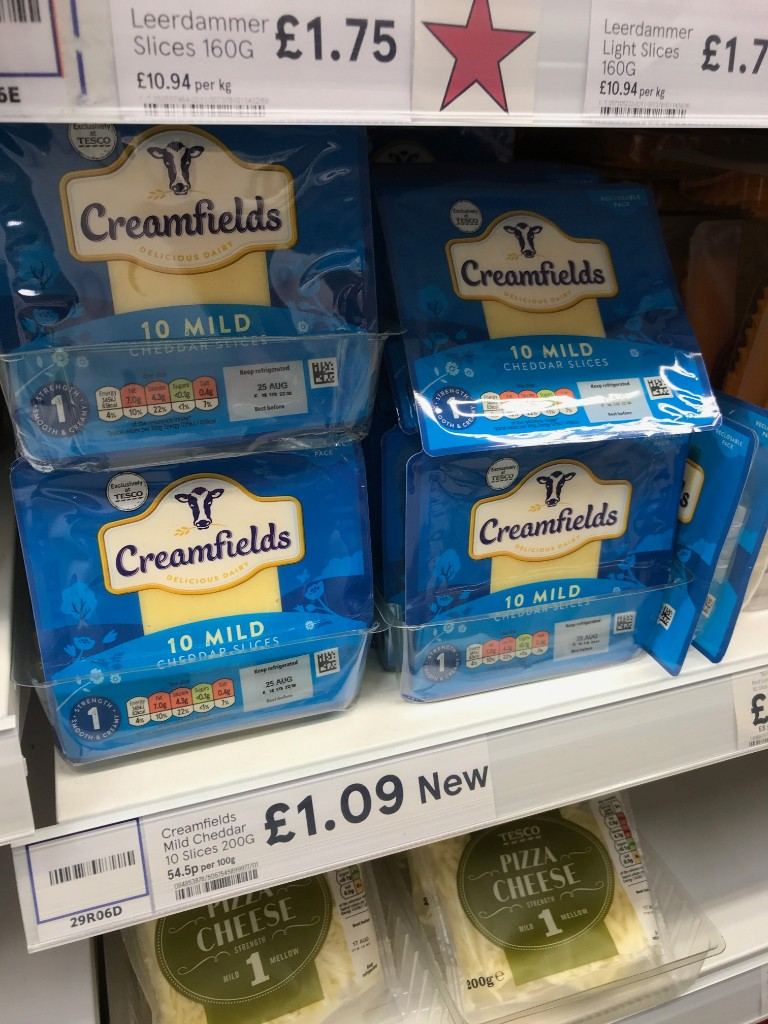
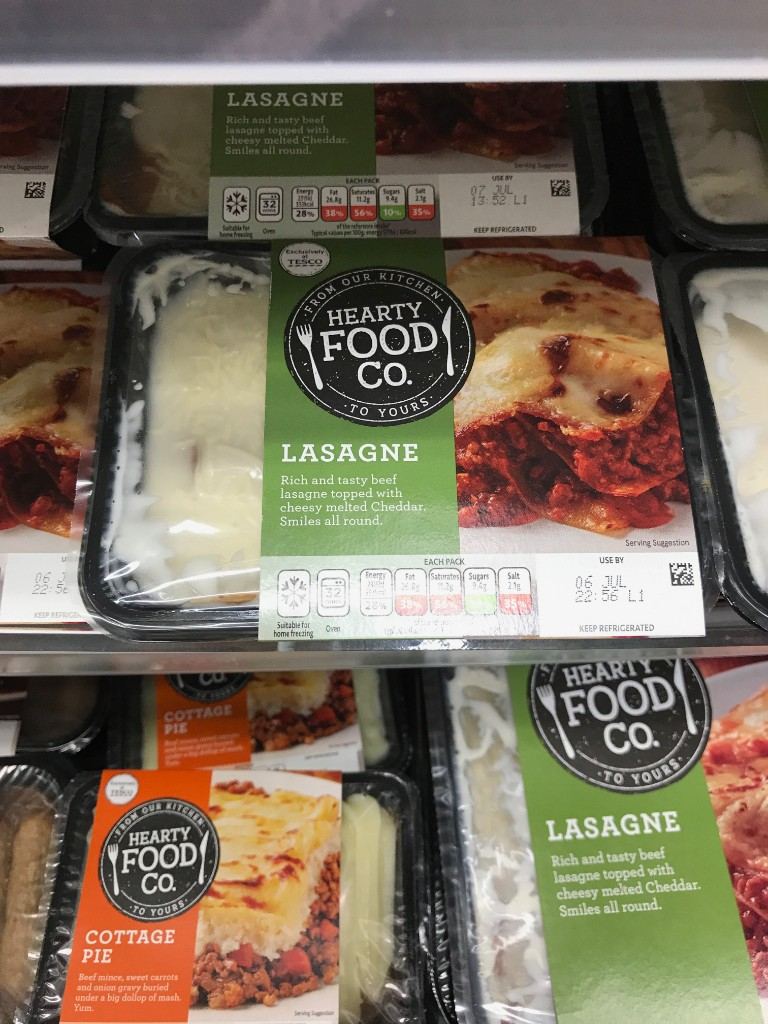
Despite those wider events, Tesco have been ploughing on regardless and have completed their value brand changes in the main.
Finalising their house brands project across a number of categories has been an innovative move, although Sir Terry was ahead of his time with the brands that appeared way back in 2007/2008.
This time, they have rolled in to key categories that presumably are key indicators versus Aldi and Lidl. Of note is the progression in Cooked Meat (Eastmans brand now very well represented) and also in areas such as Dairy (Creamfields, brand not rave reappears).
With the sad news about Charles Wilson and his illness, we note that Jason Tarry has been promoted to UK CEO (congratulations to him) and a warm welcome back to Andrew Yaxley who returns from Ireland having turned around a basket case of a business in a little over 3 years.
The question for the industry with these changes and the greater scope for more work around product, price and range. Particularly with Tarry in an elevated position and Yaxley renowned for his sterling work in Ireland and taking on discount.
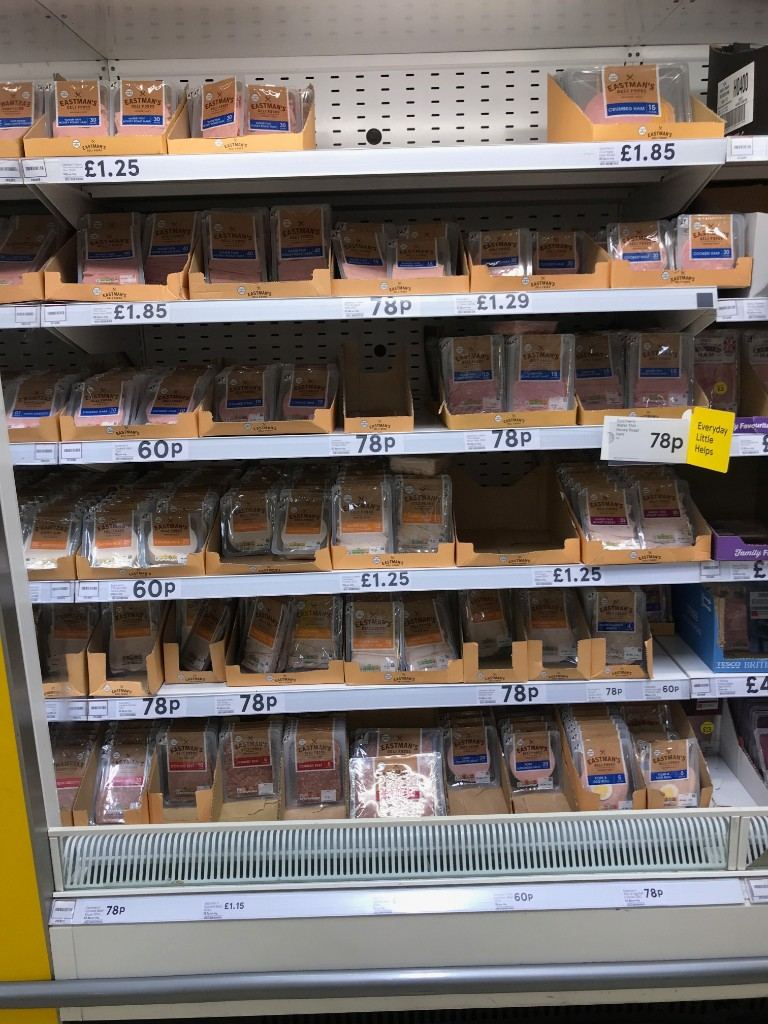
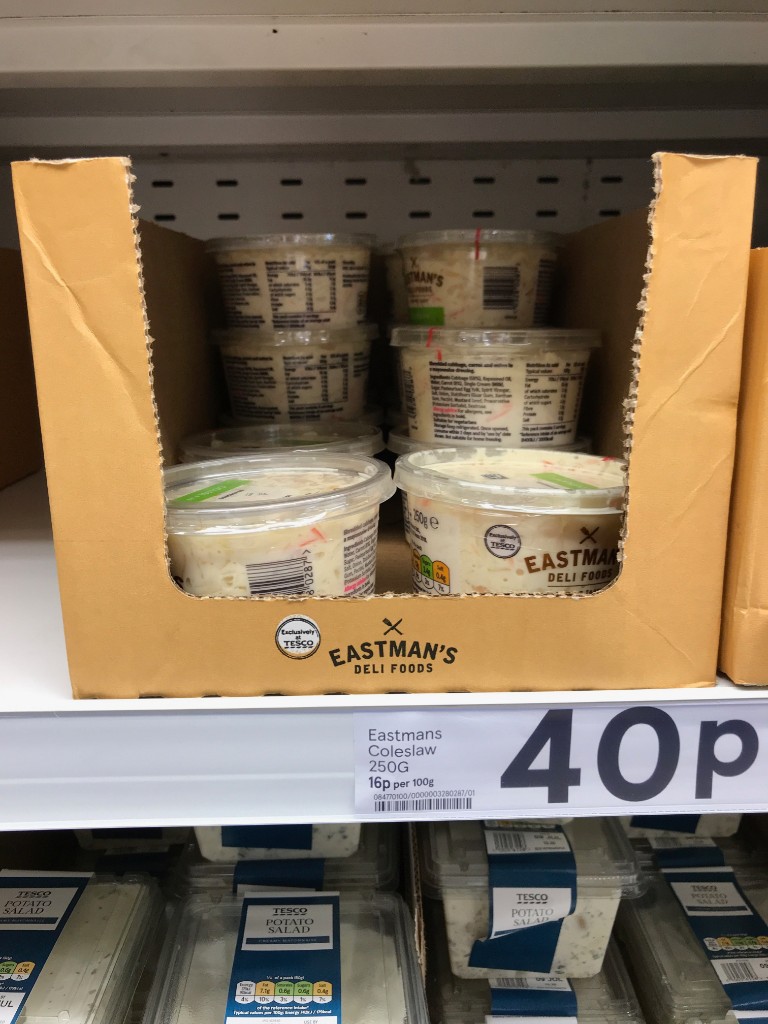
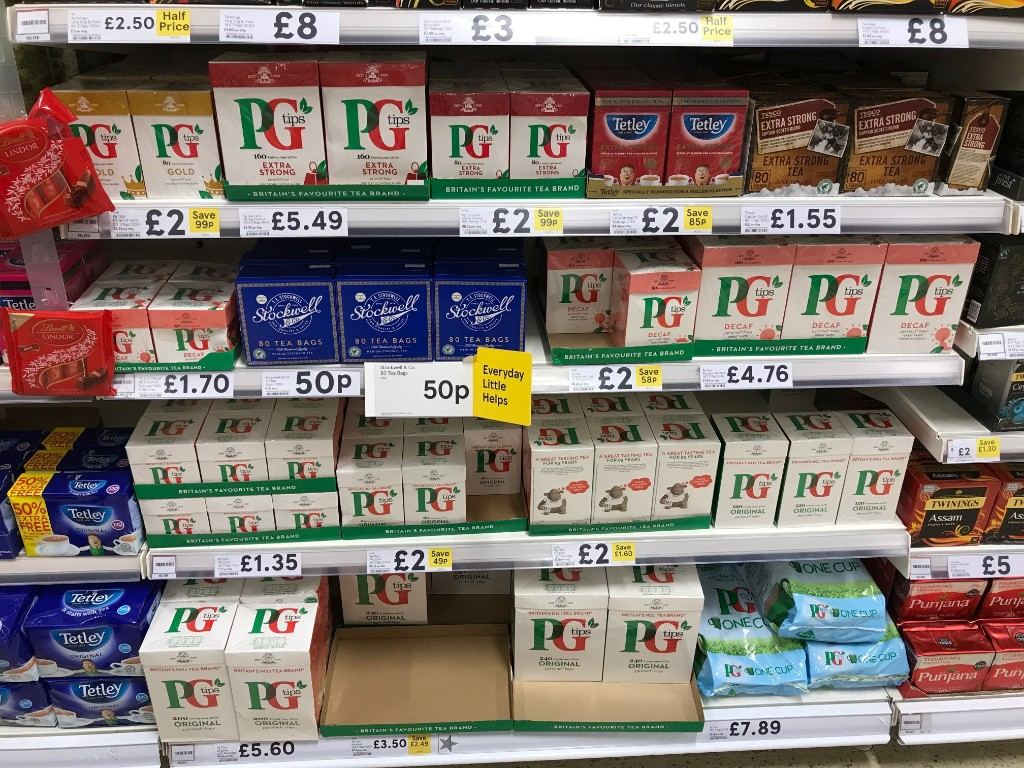
The work in some categories has seen these 'brands' overtake the core brand as the leading range for customers in terms of placement and facings.
You can see in the layouts above, just how much space and exposure "Eastmans" has in cooked meats. A good layout and first in the flow to a customer, so they're able to see the value based lines.
Also noted that the own label, TE Stockwell Tea is is sat right in the middle of the PG Tips range, with a massive "50p" barker in front. Highlighting the value of own label very well indeed.
Deflationary tactics perhaps, but like Steve Jobs once said "better to cannibalise yourself rather than someone else do it".
Again, it's part of that wider mission and there must be work looking at areas of strength for Aldi and Lidl (using Kantar data and the share of basket etc) and also linking that to the wider plan in terms of the Tesco value proposition.
Categories picked are relatively generic but they do filter down to a focus on families, (Packed lunches with Cooked meat) Frozen (Ice Cream and other lines) alongside other staples such as Beans, Flour and Jam.
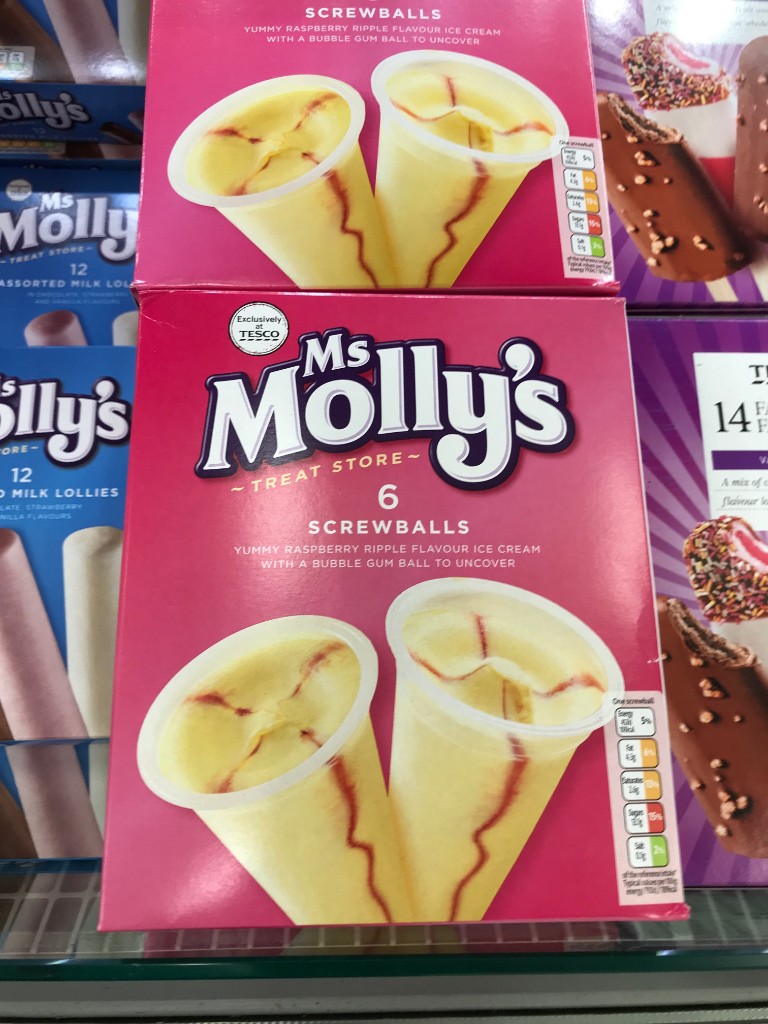
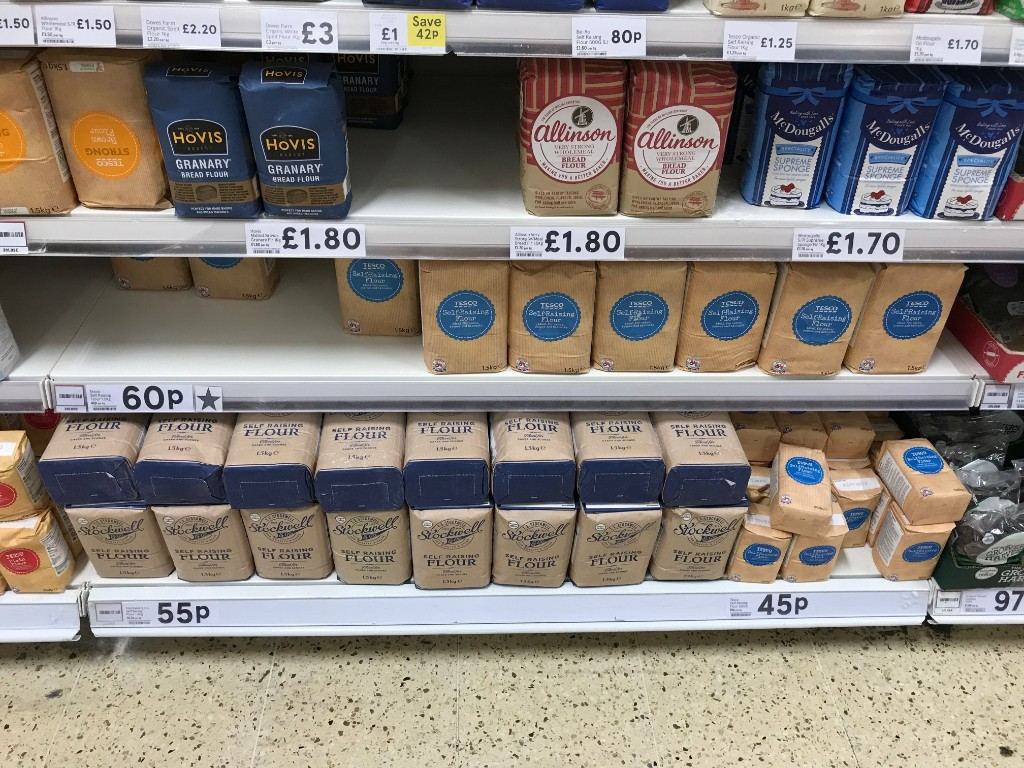
Interestingly, the newly branded value tier looks stronger than the core range at first glance.
There is a 5p gap between the two products which surely looks like Tesco will adopt the Mercadona approach and wait for Value to reach critical mass and remove the core tier mid range product.
Thus they can increase volume to then reduce that price further.
Well. that appears to be the plan.
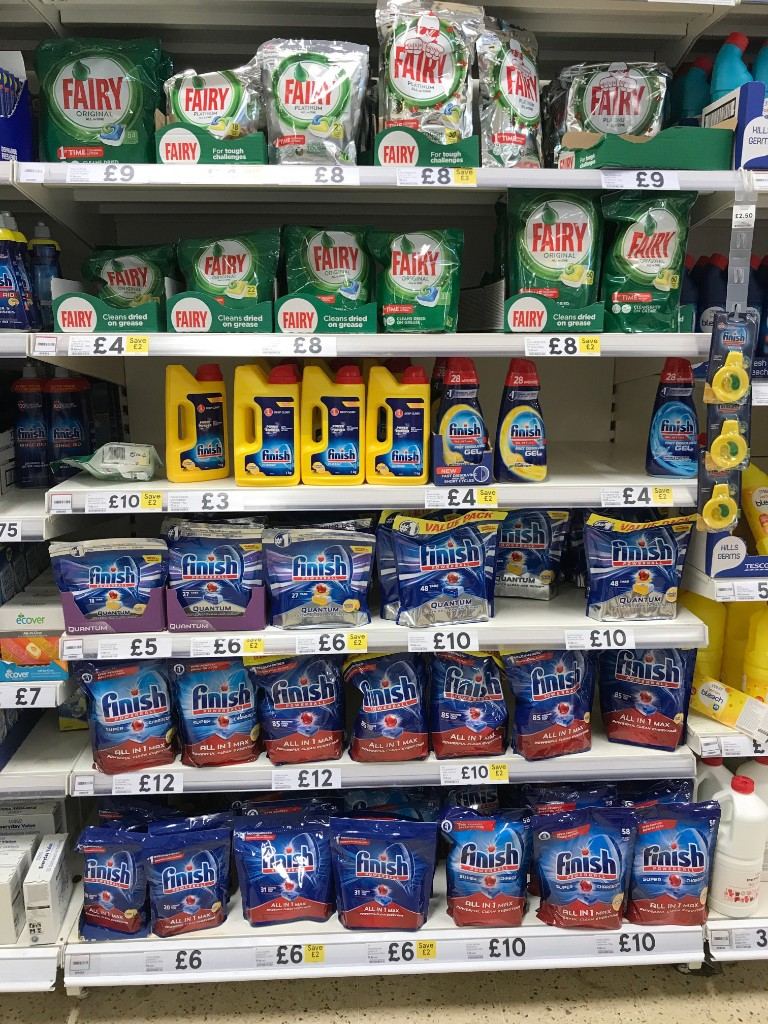
The adjacent bay features a number of dishwasher aids, such as the rinse aid, salt and other products. Tesco products get equivalence here and are merchandised alongside brand (at a lower price naturally).
Below this, Salt is cheaper and then the own label is £3 / £5 / £7 with larger pack sizes for a higher price. This means that the value can be sought from a customer who wants to buy 90 tablets for £7, and work against discount (who can only feasibly offer one pack size due to their range based model).
Value also appears in the base at £1.60. Rebrand possible? It offers a safety net for the real price sensitive customers but there is far more choice around the own label for customers here.
The key thing is that the own label then stands up to scrutiny in the same way that discounters own brands have done. Otherwise it's a pointless exercise.
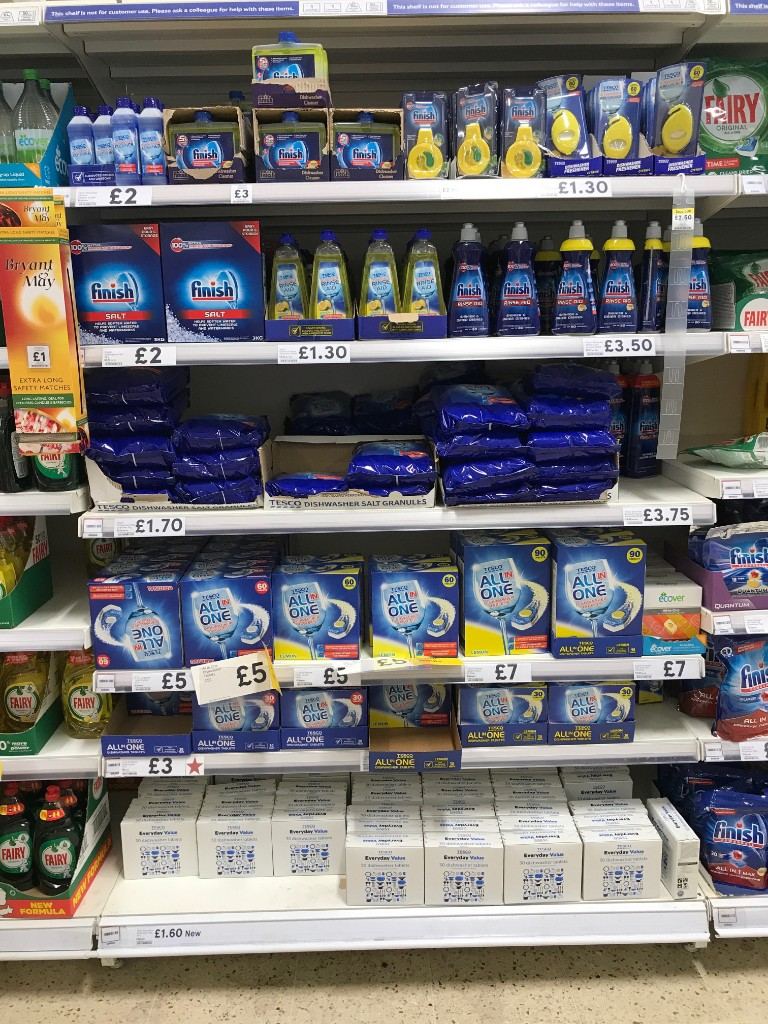
Another category where Tesco have clearly realised there's a huge gap between themselves and discount is in dishwash. It's a category that is dominated by Reckit (Finish) but also P&G (Fairy) are trying to make in roads.
It represents the 'evil' of the old world with supermarkets really and was a key reason why Aldi and Lidl, when times became hard for shoppers and cash was king some 8/9 years back gained so much ground.
Customers don't want to pay £6 for dishwasher tablets, even if they are half price. It's a necessary evil but the reliance on promotions meant that they may as well go EDLP anyway, customers generally only buy on deal and stock up when a good offer is on.
There is always a deal on, somewhere.
Sainsbury's targeted this category with their simpler pricing approach too and flattened the prices post promotions, seeing an opportunity to end the hi/lo element here.
There wasn't a great deal of movement with Tesco and dishwasher last year, a gradual move for own label but nothing that has been seen in other categories - IE own label above brand etc.
However this year, Finish is down to one bay in store and most of the lines are one wide (that is, one facing) means that any deal will ensure those lines sell out very quickly indeed. However it also serves to show how ridiculous some of the pricing is too.
Lines up at £10 for example, who buys those?
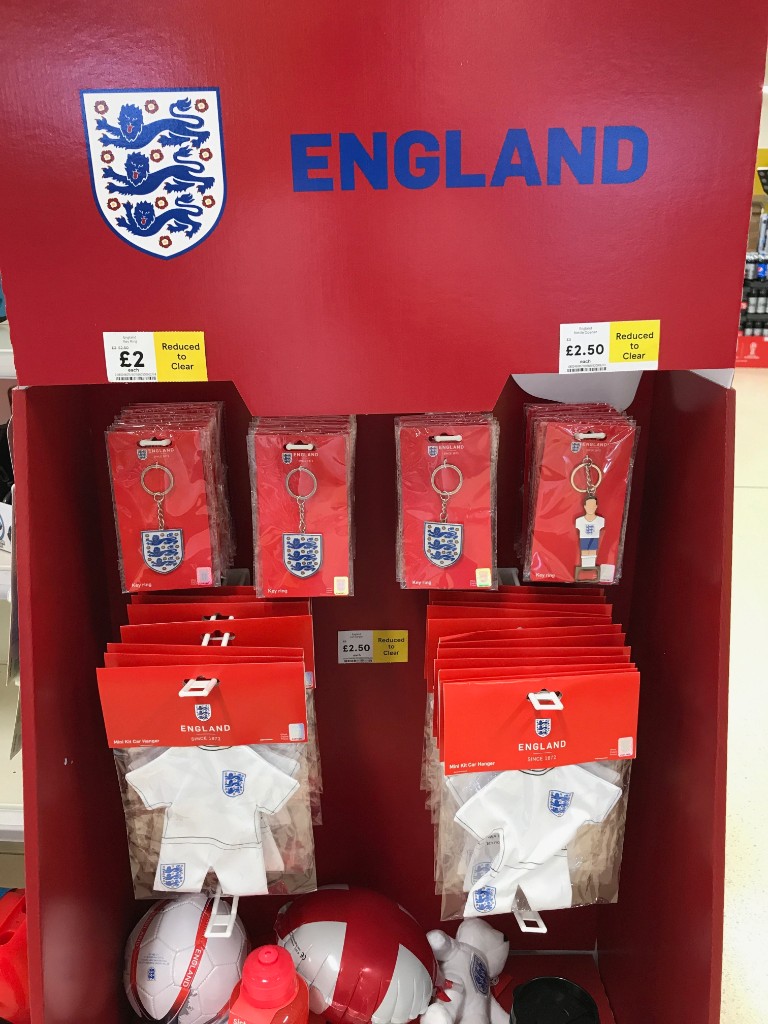
The history of the national team has not been great and these were reduced down straight after the group stages.
First loss is your best loss an' all that.... We still believe though!
From the Grocery Insight newsletter archive, first sent to subscribers on 10 July 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.