Sainsbury's results - What's in store?
3 May 2017
So today brings the results for the end of the financial year for Sainsbury's, and with it, a microscopic look at the Argos integration and how things are going with that side of the business.
Profits are expected to drift given the Argos integration and costs, falling Sterling versus USD and also food sales which are on the wane.
Food is expected to be down in terms of like for like once more too; Sainsbury's have conditioned the market to a lower decline by weathering the storm that saw Tesco, Asda and Morrisons all record between -5% and -7% quarters with some horrific quarterly performances.
Sainsbury's did have a record financial loss (only their second ever) in 2015 as they, like the market took a hit on impairment costs as they wrote down the value of existing stores and also their property pipeline too, but never a -5% sales performance on a like for like basis.
Like for like sales that were barely positive, flat, or indeed negative have broadly been acceptable for Sainsbury's given their consistent performance. They are not trading versus a 'nadir' and working their way back up, but they are on a bit of 'death by a thousand cuts' based decline.
Their performance has been brought in to the spotlight by improved performances at both Tesco and Morrisons, with Tesco having been on a steady path towards growth for a number of quarters now with overlapping growth too.
Morrisons are also overlapping growth; recording a very solid like for like number at Christmas. Their Q1 performance will be interesting to note on Thursday AM as they continue their recovery under David Potts.
Asda are still struggling but have stemmed the tide it seems, but continue to lose share. This may swing the other way with inflation returning to the market, boosting the sales value as prices rise.
Despite figures; Asda are showing signs of recovery, their premium ranges at Christmas impacted Sainsbury's who didn't get that secondary pick up via the Asda customer, who presumably found all they wanted with Asda, rather than having to go to Sainsbury's for their premium products.
As ever in retail, Sainsbury's have their food performance within their gift and it's down to them to impact the market and ensure customers are coming through their doors, not rivals.
Argos is a distraction and despite Sainsbury's being well run and featuring a strong operating model in stores, there have been signs of a degradation in their offer in recent weeks.
With Brexit and the weakening in customer sentiment (April's Kantar saw sharpest gains for discount since 2014), Sainsbury's are arguably more exposed to this shift, especially given the discounter growth in recent years taking them towards more affluent neighbourhoods and also with discount ranging more premium lines.
Justin King pointed to Lidl having an almost complimentary offer to the bigger Sainsbury's in Newcastle (I believe?) way back when. It's unlikely to be the case now, discounters are actively taking sales from everyone.
Anyway - to the stores!
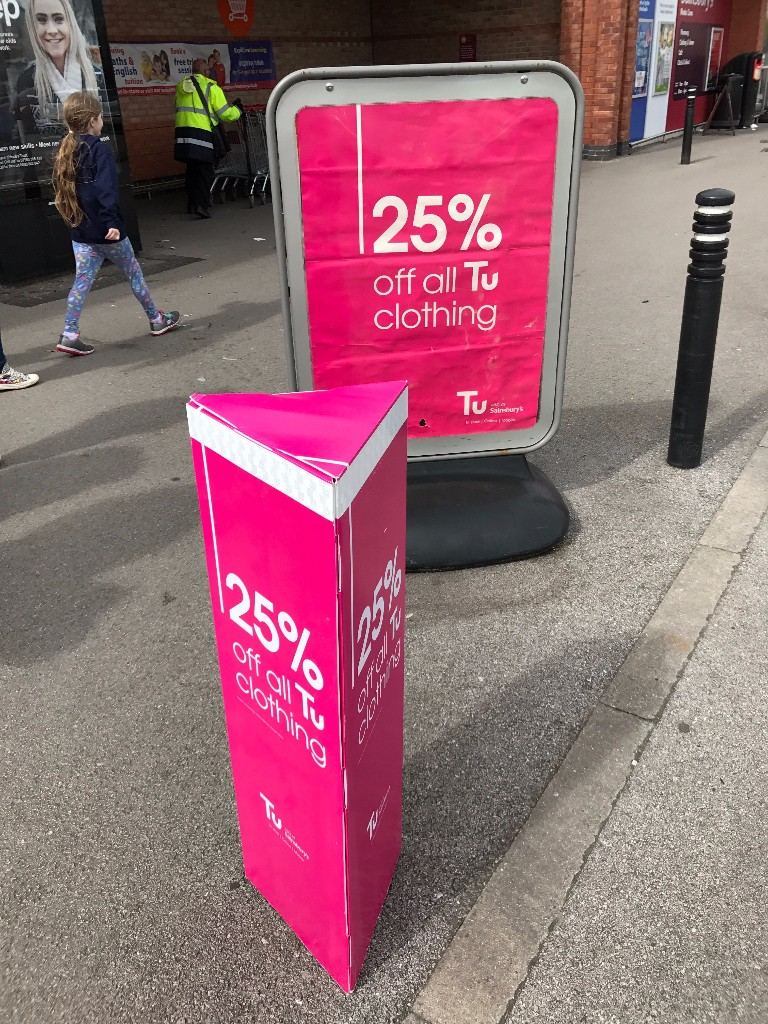
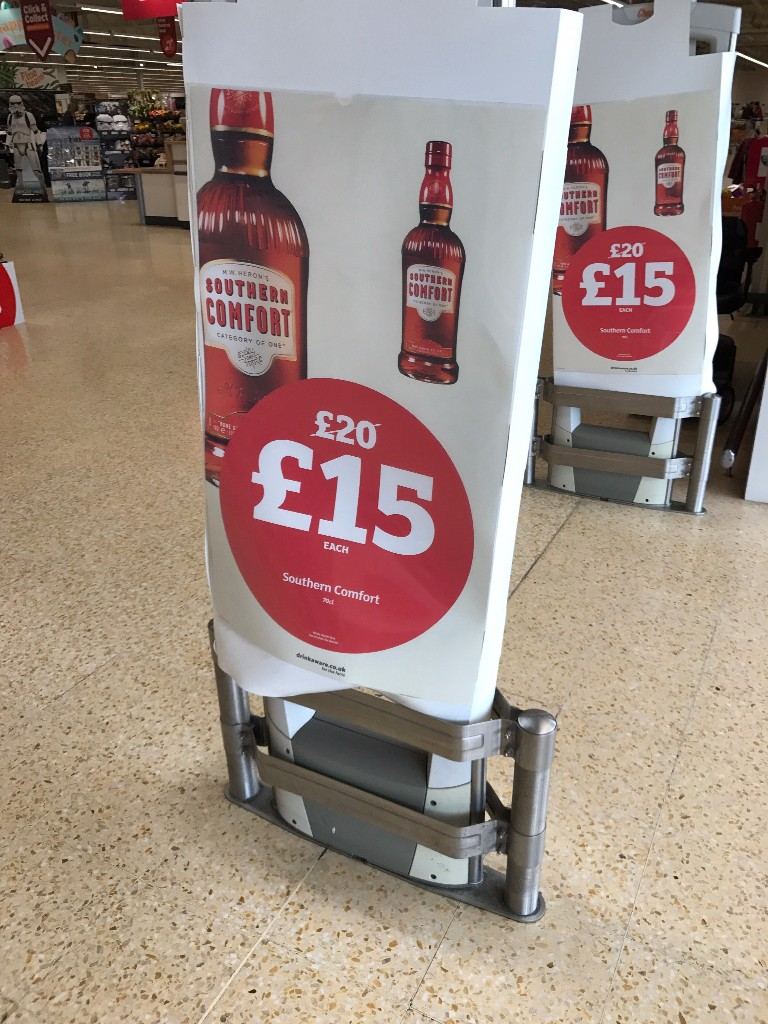
Pre Easter; doorway and entrance was dominated by Clothing sale (scheduled almost which aids footfall) in the half term holidays. Then £15 Southern Comfort were advertised on the security panels.
Not the greatest way to set the pulses racing for value within the store. There was really nothing else to shout about? Nothing around premium? Fresh? Very poor.
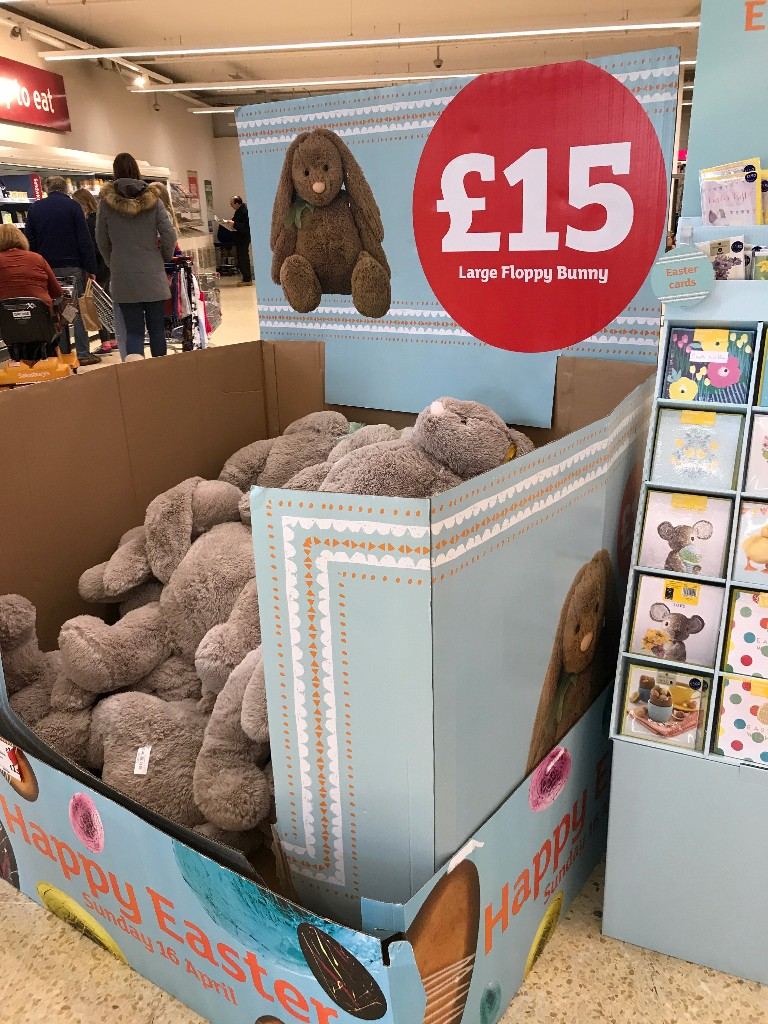
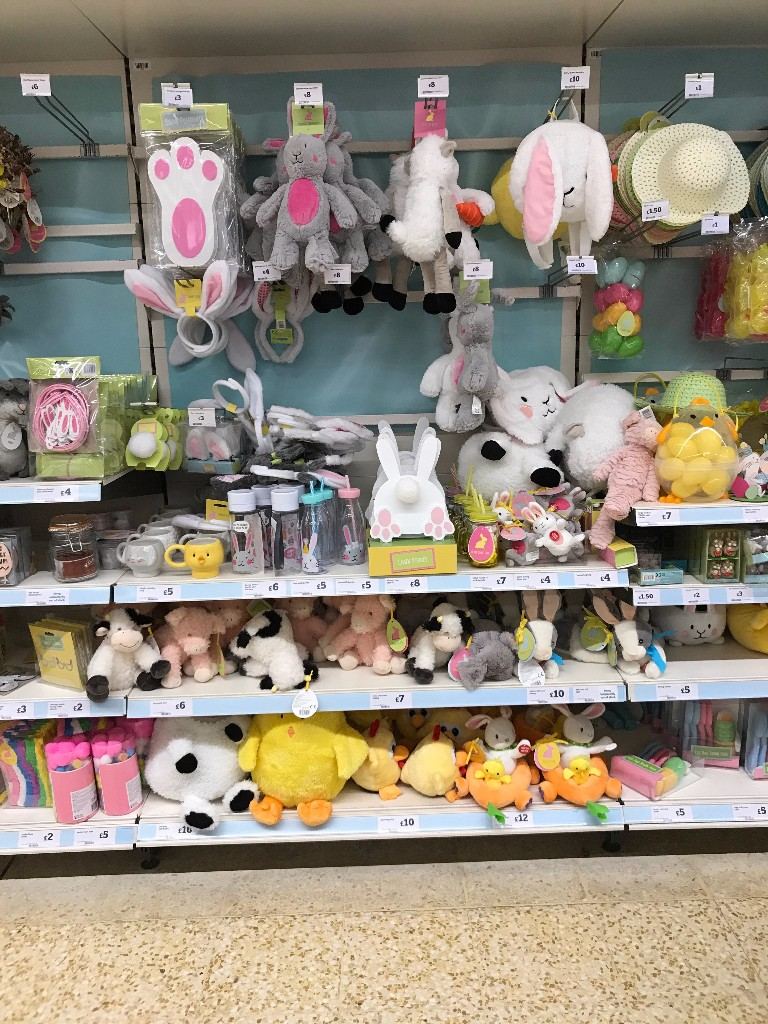
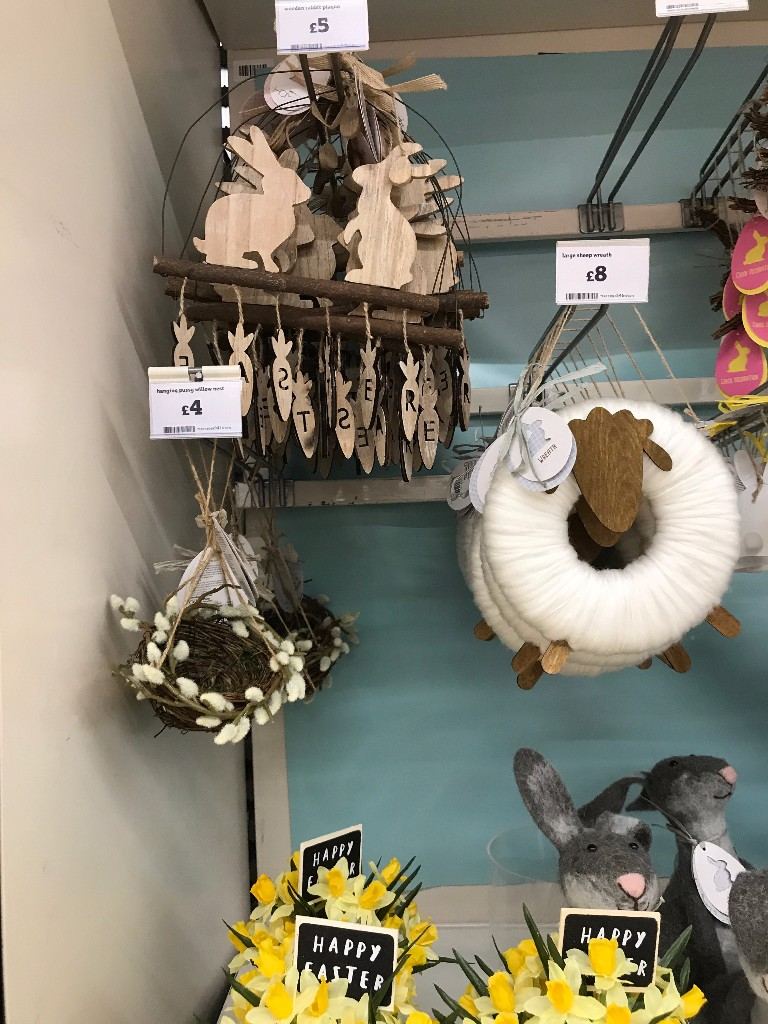
All the strength with Sainsbury's is in non-food, both with Argos and their sharpening of their own offer too.
Easter was strong for them from a non food angle, a strong range of non food products, soft toys, craft lines and Easter bonnets and associated products all worked well.
The pallet in the doorway though, for £15, for a large Bunny.
Is that value for money?
I haven't seen any around post Easter so perhaps they were gleefully picked up by customers.
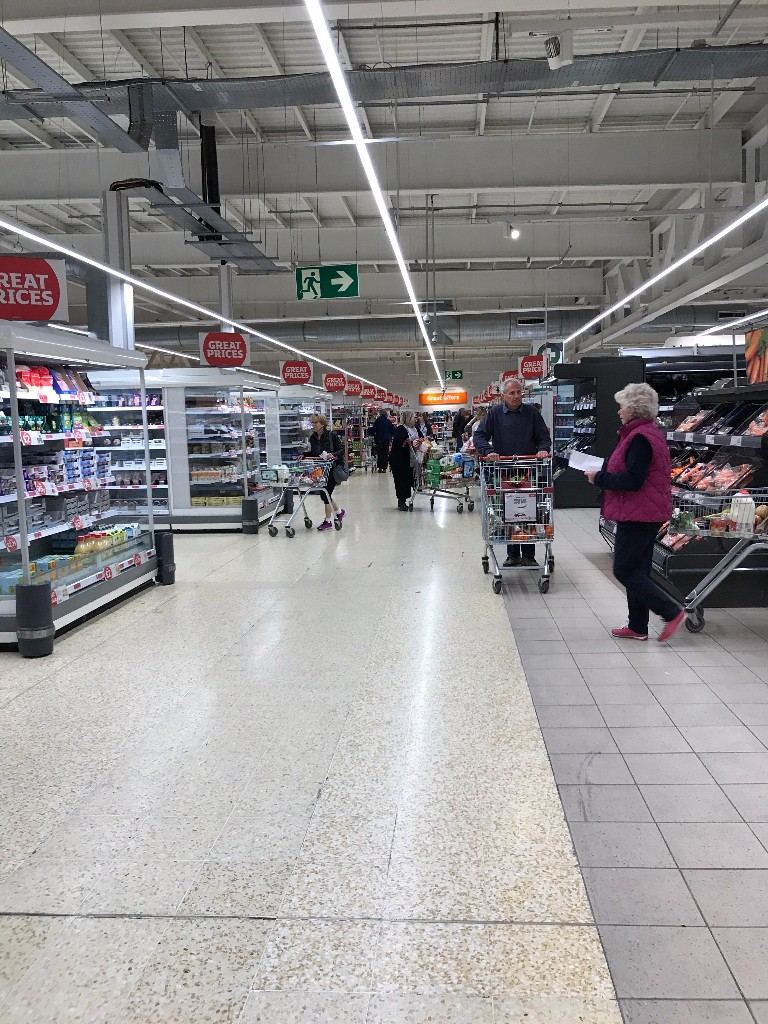
However when we move to food, even a week out before Easter, there were seemingly no levers pulled to entice further trade in to stores.
You'd be forgiven for thinking these pictures weren't the week before Easter, and were taken with 4 weeks to go.
The central aisle featured no overhead signage at all; this isn't uncommon in Sainsbury's as they don't always feature them due to questions over whether customers even see them.
However without any boards, it can have an air of the store closing down......
With Easter being a major event; there is a need for a overhead board or two, just to enhance messages or highlight hero products, or the premium tier.
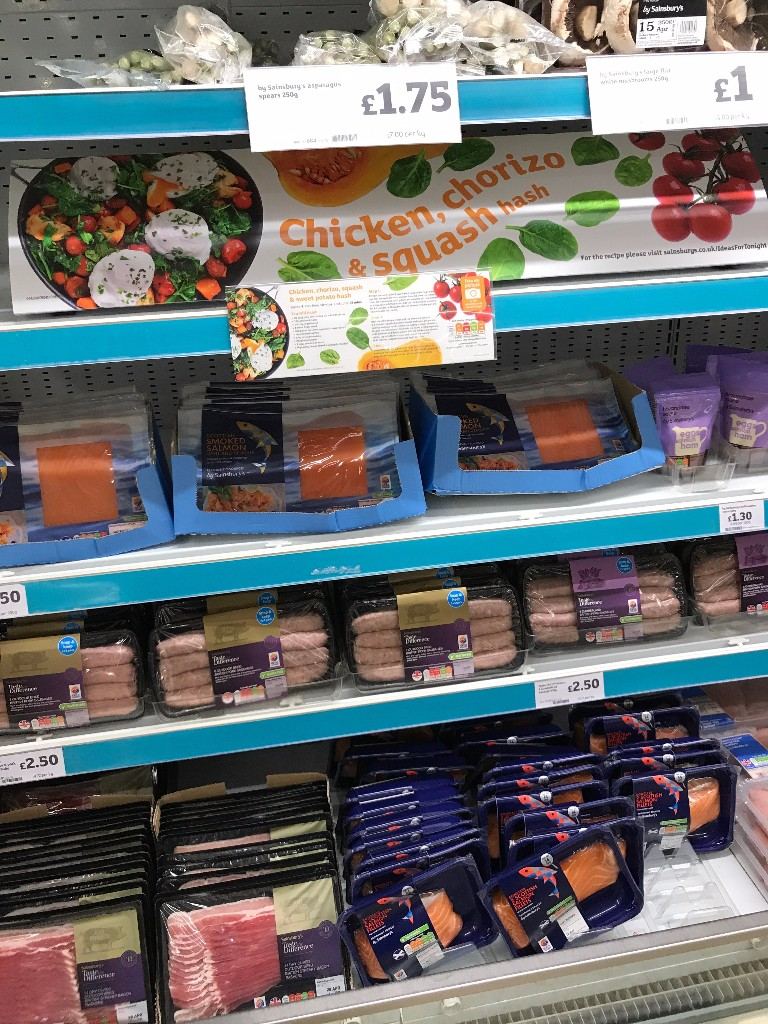
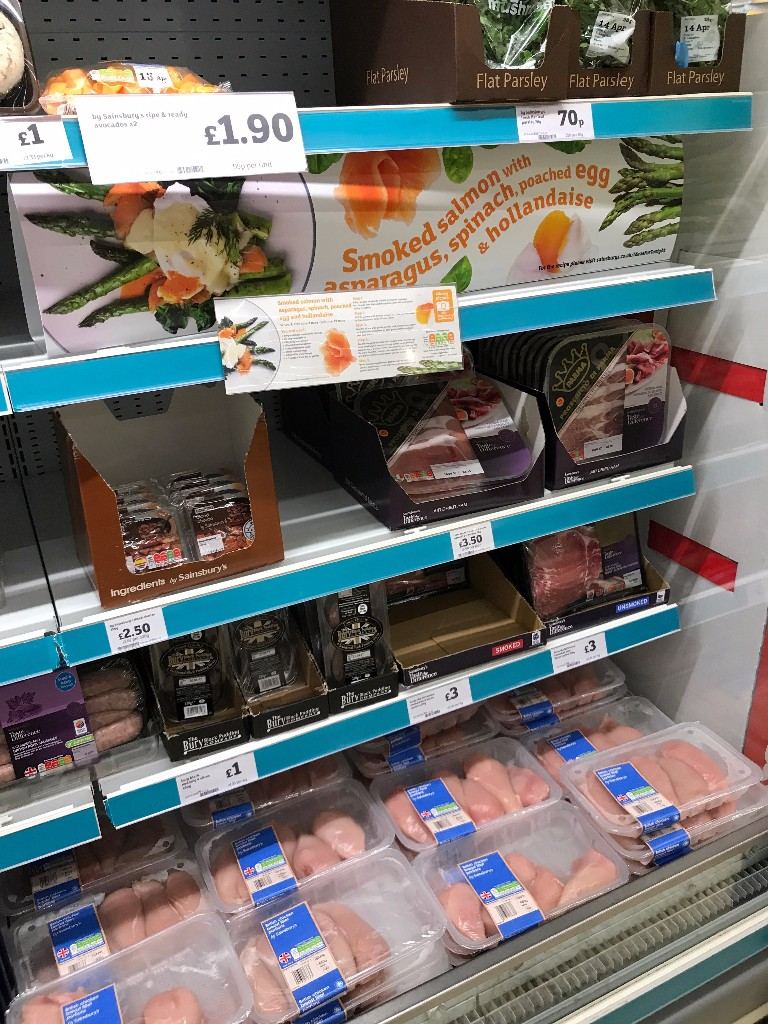
The key fresh end for Easter featured their continued recipe based ideas; however where was the Easter theme?
Salmon was featured but within a Breakfast style dish featuring Asparagus and Poached Eggs.... No overall Easter theme which was a real missing link and missed the opportunity to offer trade up solutions to customers.
The other half of this end featured Chicken, Chorizo and Squash 'hash'...... Fair enough....
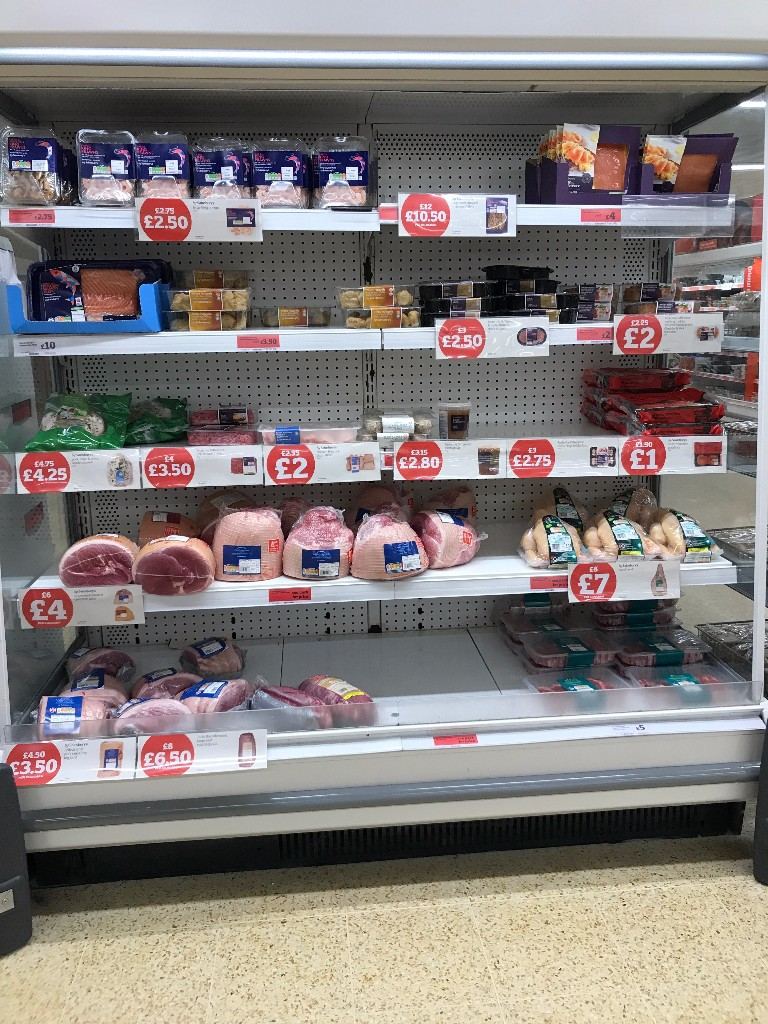
There was another end relating to Meat and Fish; but it was a challenging to say the least from a customer viewpoint.
What must a customer think here?
Where is the value?
Price points are all over; no indication of where the savings are, a mix of products too. Burgers and Lamb joints?
Not everyone wishes to eat Easter based meals but there should be no escaping the event in store, otherwise you end up looking irrelevant.
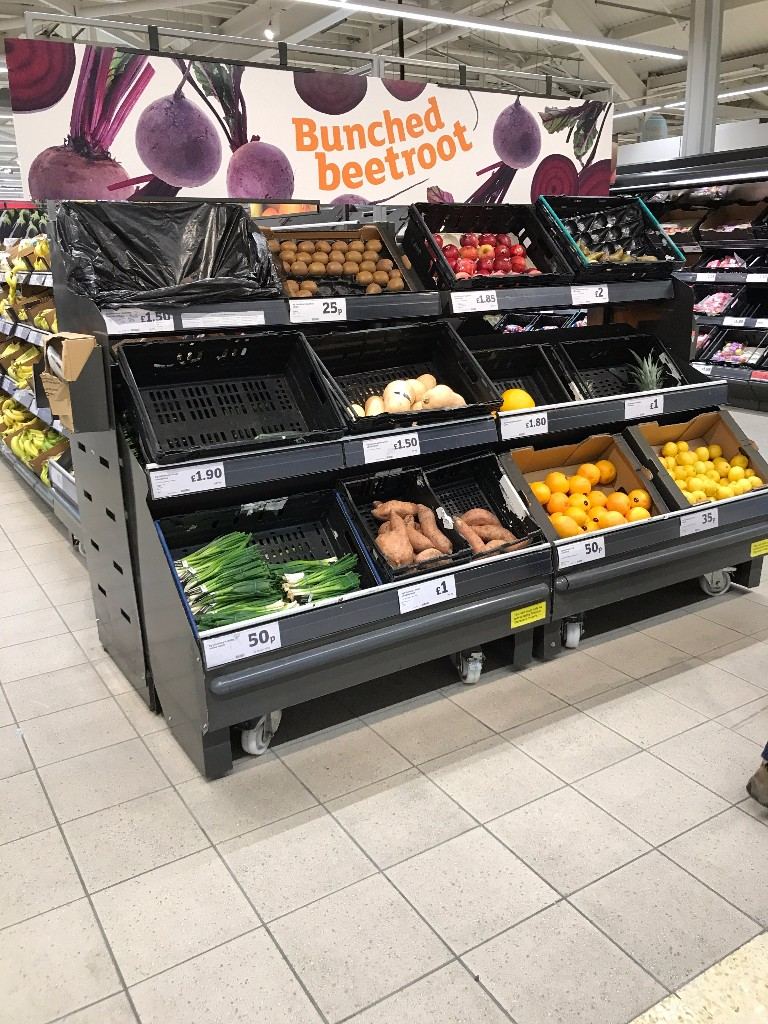
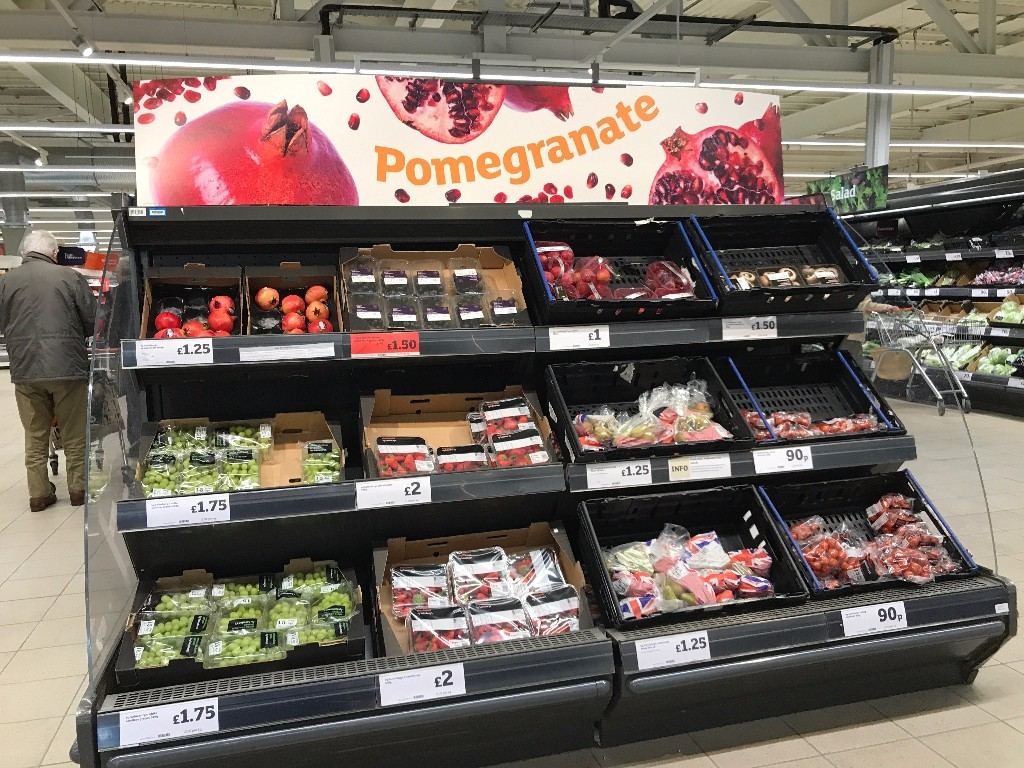
Fresh Foods ends aside; surely Produce will feature relevant lines for the trading period? Surely?
Given Asda at 20p, Tesco 49p, Morrisons with their 3 for £1 offer and Aldi / Lidl pushing on with their Super 6 / Produce offers, surely Sainsbury's will feature lines for the Easter roast?
Alas no. The ends highlighted Pomegranates, Bunched Beetroots and Fine Beans. It's entirely unclear what the purpose of this signage is......
The wider ends are a mess too; literally no discernible overlap or theme that I can see there from a Produce perspective. It's just Produce assorted in an end, with a sign relating to one of the products at the top....
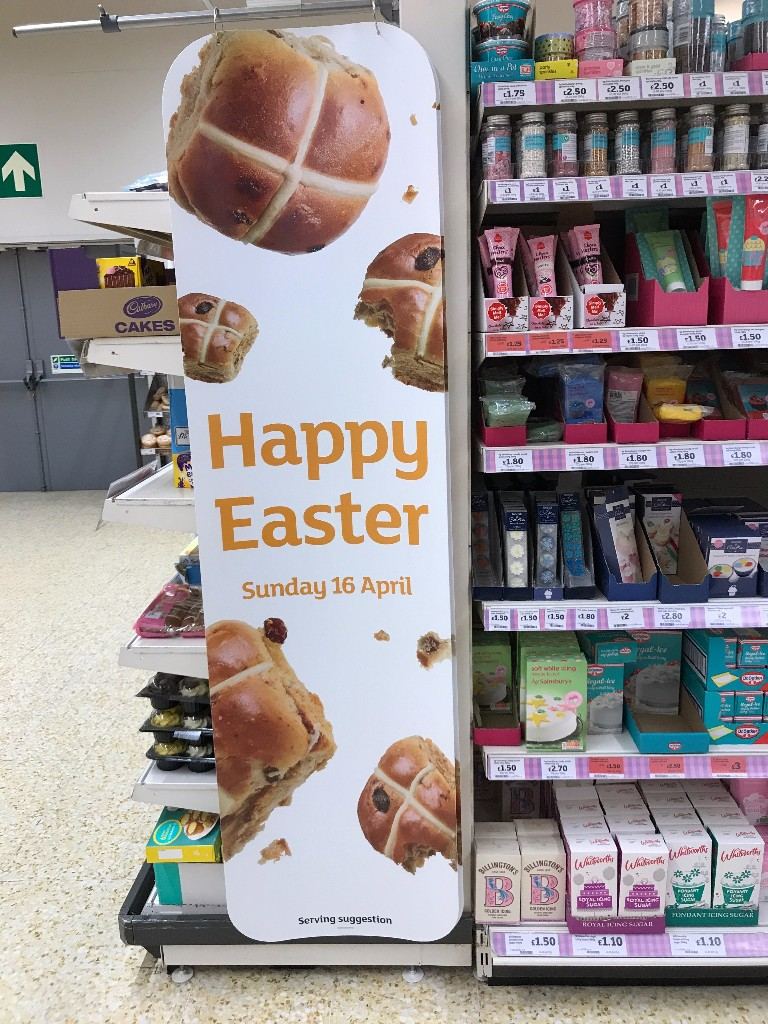
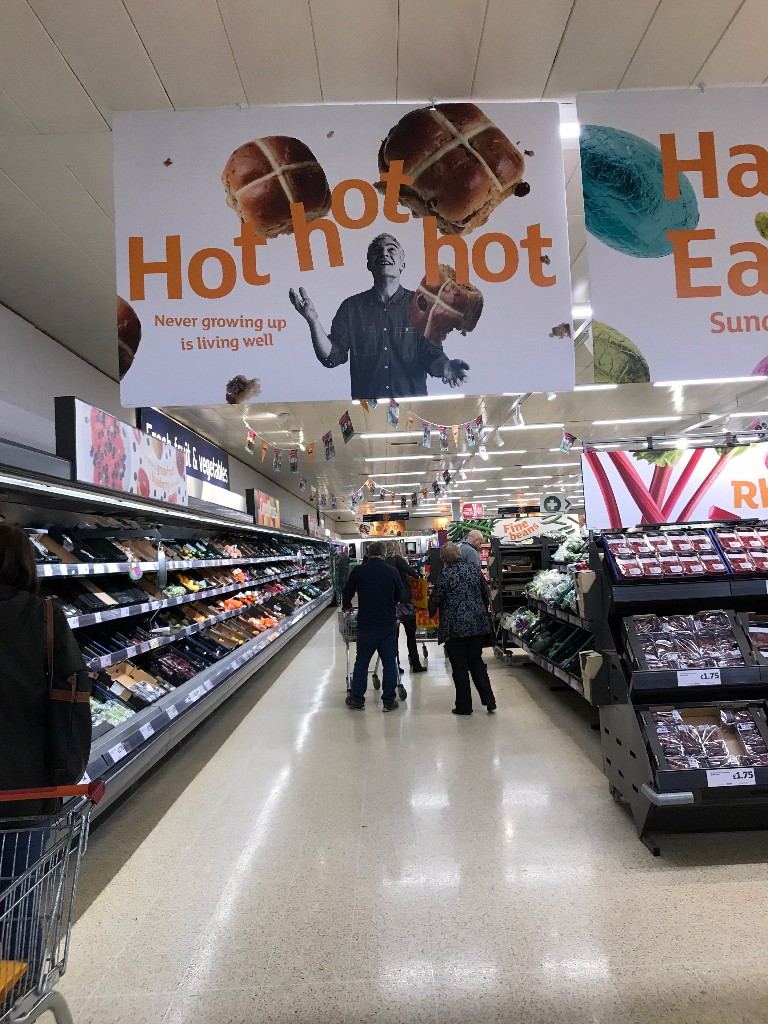
The marketing campaign has been discussed in great detail on this very email service.
I understand the differential elements in a noisy marketplace focused on price, but I can't quite grasp how this then leaps towards customers parting with more money for quality food from a retailer who know what they're doing.
The "Happy Easter" with the Hot Cross Bun side panel was one of the few mentions I saw about Easter around the store.
We all talk about the new adverts, they are being recognised and noted as being from Sainsbury's. But then what? Does it make us walk in to the stores, and part with cash?
No. It also doesn't link with quality food retailing either?
The overworking of the corporate tagline is bizarre too. "Never growing up is living well", when the opposite is true. Think of all the Chocolate and sugar you could eat, carefree when younger.
Now it's all diabetes, sugar tax, higher risks of cancer and Brexit.
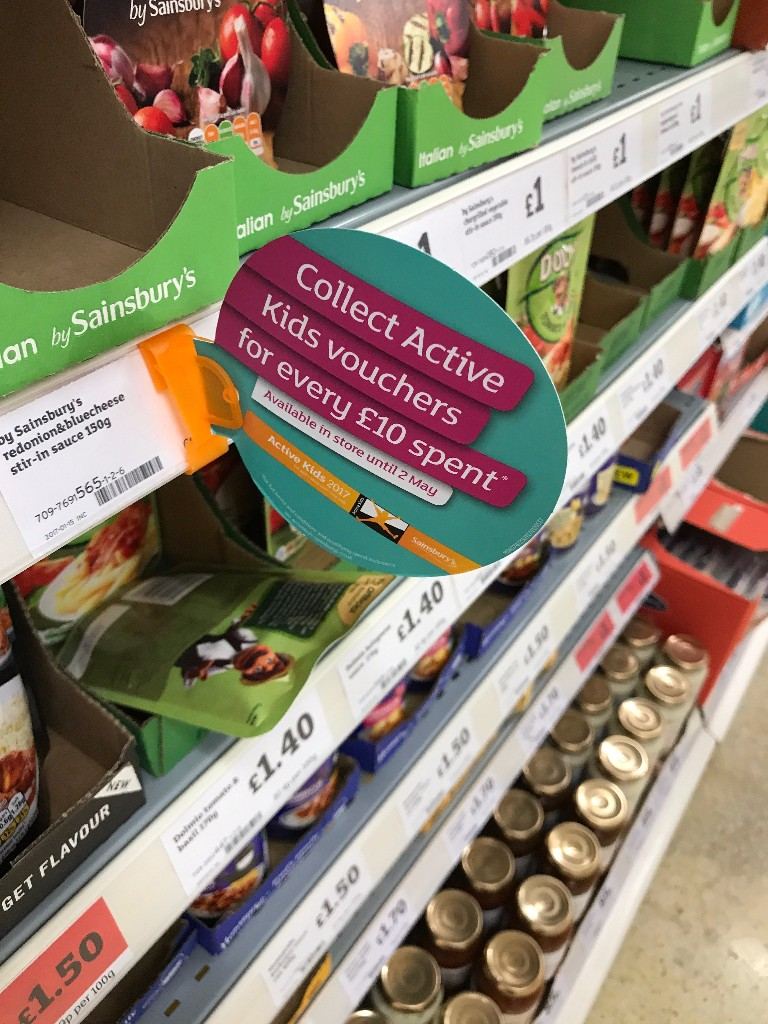
Their biggest campaign shouldn't be centred on 'living well' and overworked connotations to calendar based events.
Active Kids has been running for many years now and is very popular, enabling schools to turn vouchers in to activity based kit for the playgrounds up and down the nation. Daniel Sturridge is their ambassador! (injuries aside).
I saw nothing linking with healthy eating, offering more vouchers for purchases of Fruit&Vegetables, nothing within Kids friendly products either. Very little for what is a popular campaign and should be at the top of the agenda given childhood obesity concerns,
Save these roundels (above) and a sprinkling of bunting in some stores near the Fruit & Vegetables, there is nothing else. I didn't even know the campaign had launched until a cashier offered me the vouchers.
Despite the various campaigns around 'living well'; see below for the latest..... There has been next to nothing for Active Kids.
It ended yesterday (2nd May). What a missed opportunity.
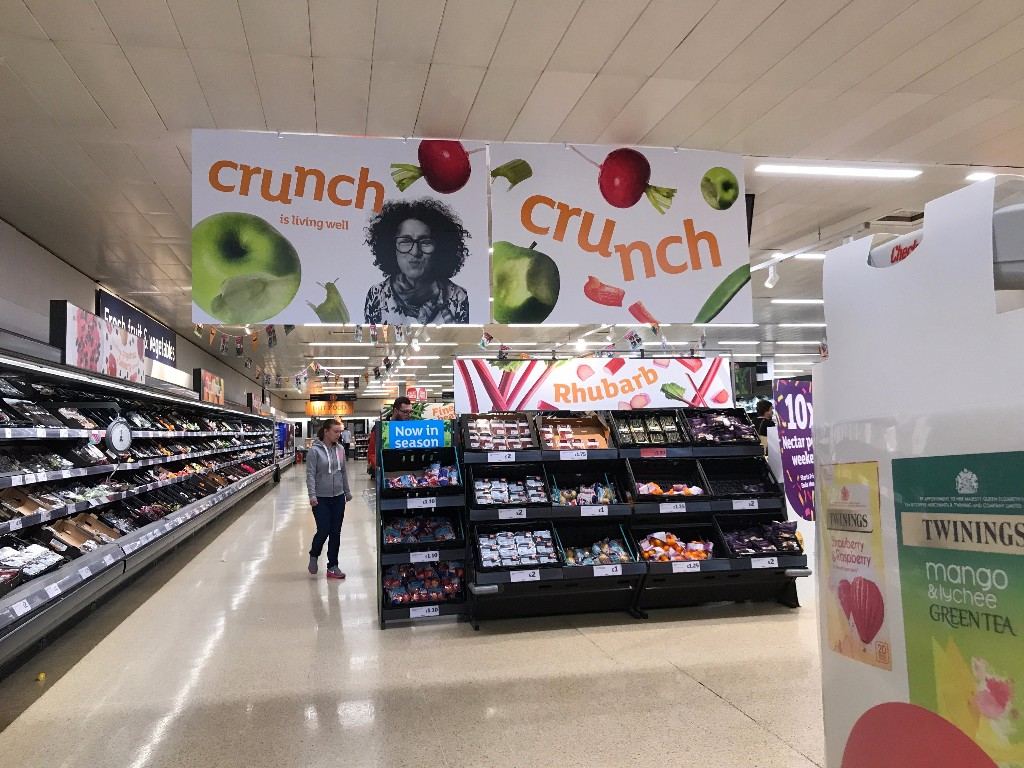
Crunch is living well. Unclear on where next for the campaign; who knows? W&K have to sharpen up, landing with food dancing jolted us all and got plenty of people talking on social media.
This presumably showed up well on the various brand indexes and all that. But where is this all going to end?
Much has been made of the Sainsbury's value perception since they ended multibuys. I can understand their mentality in going after lower prices, after all discounters have done a lot of work in conditioning the customer towards a single price.
But Sainsbury's have never been the lowest in the market on price. Asda, one can understand adopting such a strategy given their parent in the US and their lower price messaging. But the UK customer perceives value as the price paid with a direct link to quality and also in terms of the trolley 'full' they get for their money.
Especially at Christmas. It's ok doing boxes of Beer for £10, but customers like a 2 for £20. It takes the thinking out of it.
They looked to clear down Eggs nicely at Easter despite a lack of multibuys, not much clearance around post the event.
However a lack of multibuys in areas like Party Food affected them at Christmas we saw.
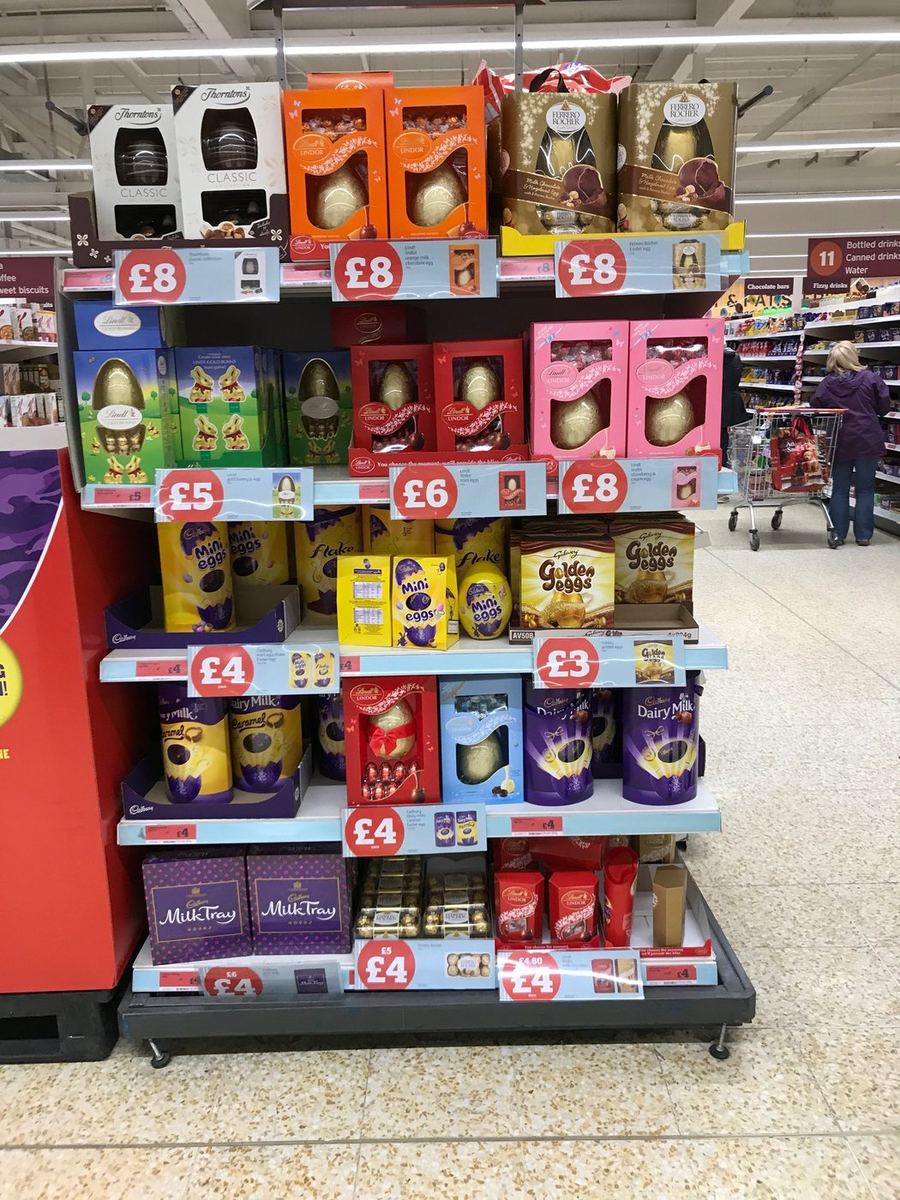
However some big old price points on there for Easter week; the decision to utilise an end for Eggs was perhaps surprising.
Given gondola ends in the central aisle are typically where the best deals are featured, removing multibuys means it can be difficult for Sainsbury's to build compelling promotional ends that appeal to the customers.
There are too many lines featured on the Easter end above; plus the price points are all over. £8, £6, £5 on the top two shelves alone.
Note that themed signage is used for the end - in Blue. The shippers were also themed in blue, yet the signage for Easter around the store is Orange / White(?)
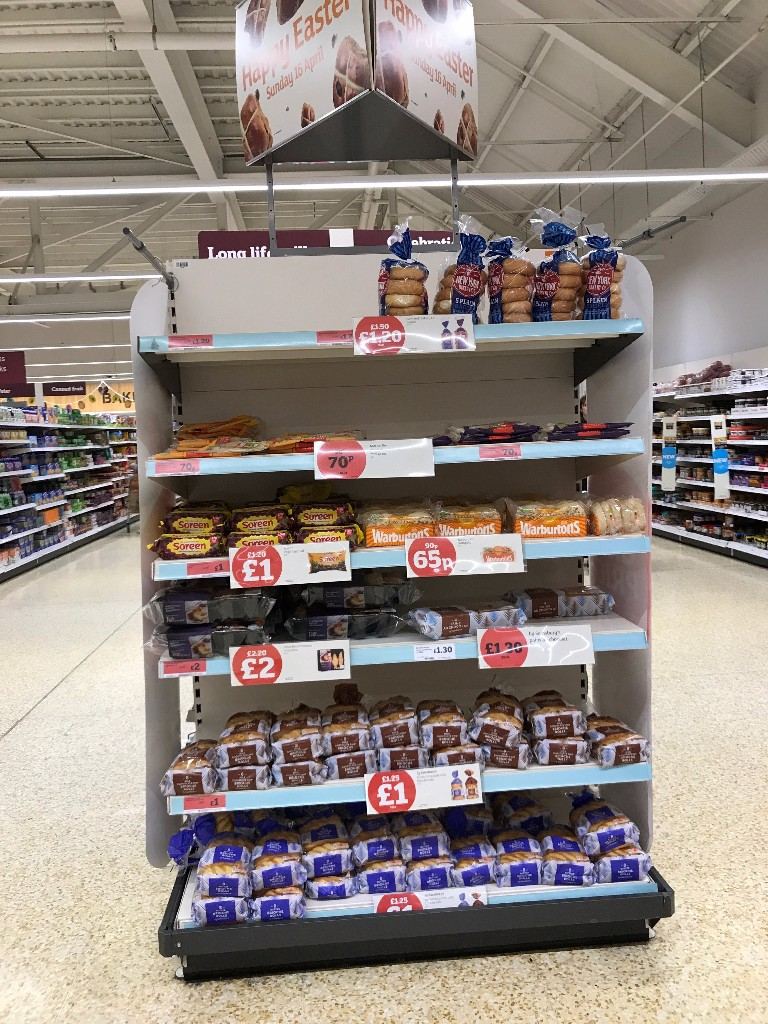
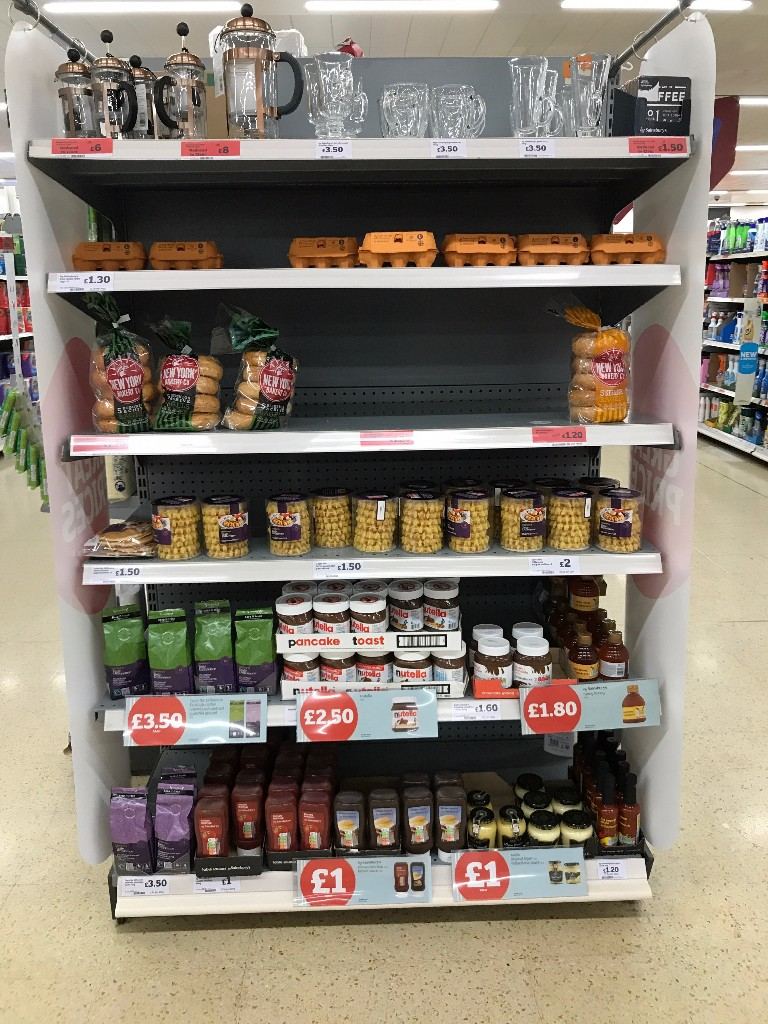
At Christmas. There were some really good examples of mission based ends, these profiles featured products that came under an event for Christmas. Be it Gifting, Hosting or Cocktails, these worked well and were a nice twist on the usual run of special offers.
Seemingly it was attempted at Easter too; but the execution was uncharacteristically poor for Sainsbury's.
The first end is breakfast / bakery I think, but no Hot Cross buns in sight here. Yet Crumpets, Soreen and Brioche were all featured.
Another end in the core run was Breakfast themed, stocks were low but this also featured Eggs, premium Waffles, Coffee and Spreads alongside Hollandaise sauce(?)
The idea at a high level is there, but it almost runs out of steam and doesn't appear to be entirely thought through by the bottom shelf. Combined with the other challenges laid out above, it does look a concern for their Easter performance.
There was also nothing in the marketing package for Taste the Difference which was a surprise, the premium range should be a must for occasions like Easter.
Their range has been overshadowed by work elsewhere in the market. Morrisons have pushed The Best significantly post relaunch and discounters do a great job with their respective ranges. Waitrose have '1' which now stands alone as their premium tier and is supported in store very well.
M&S landing their new premium tier will also increase the pressure, as their innovation record is second to none.
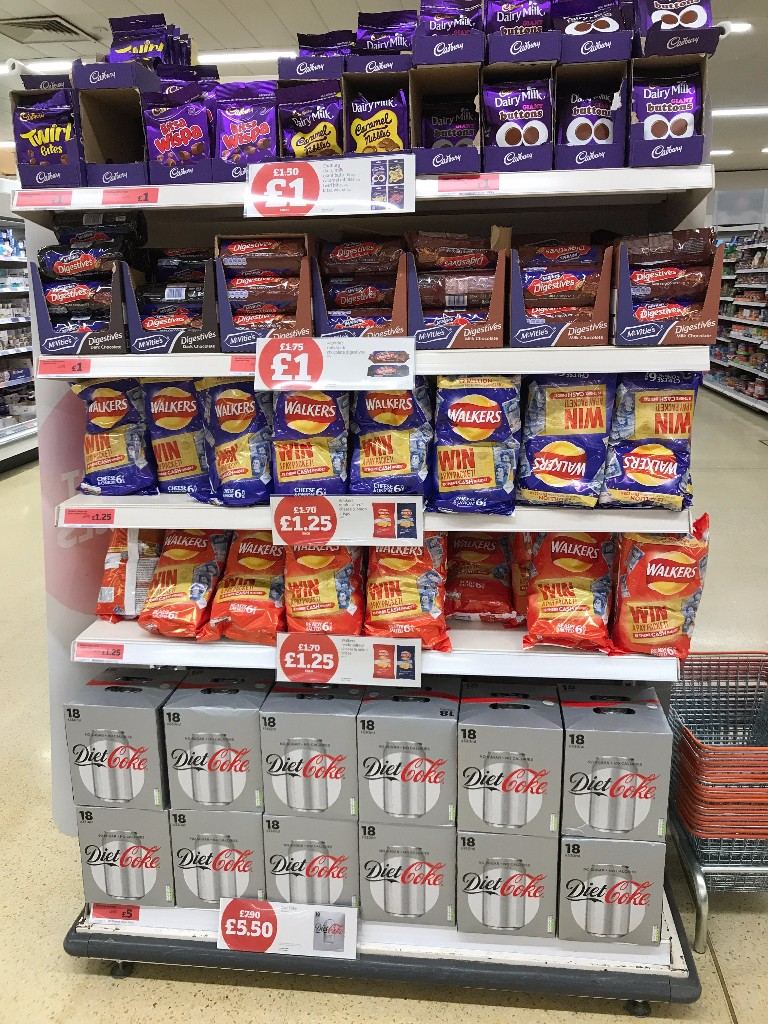
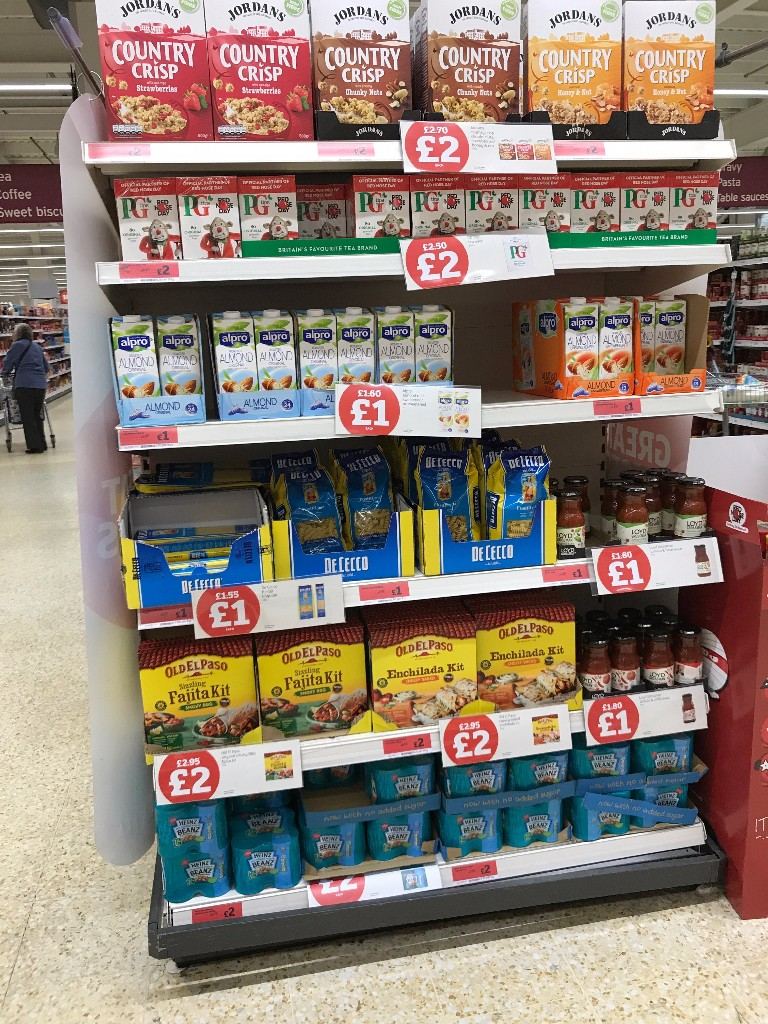
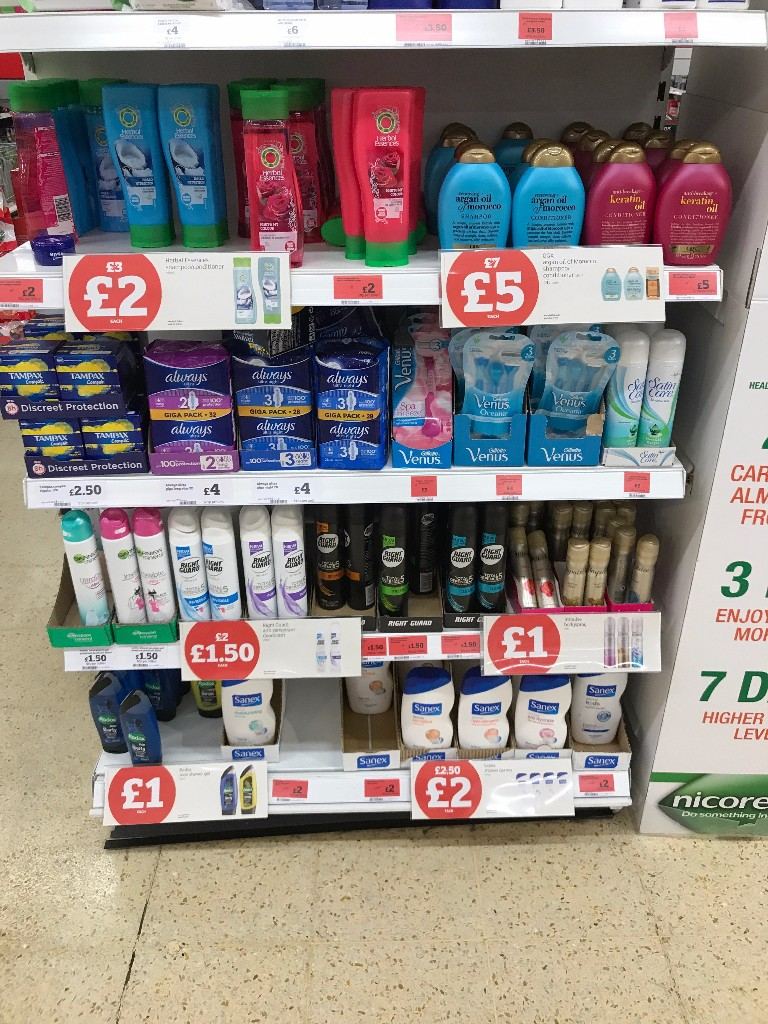
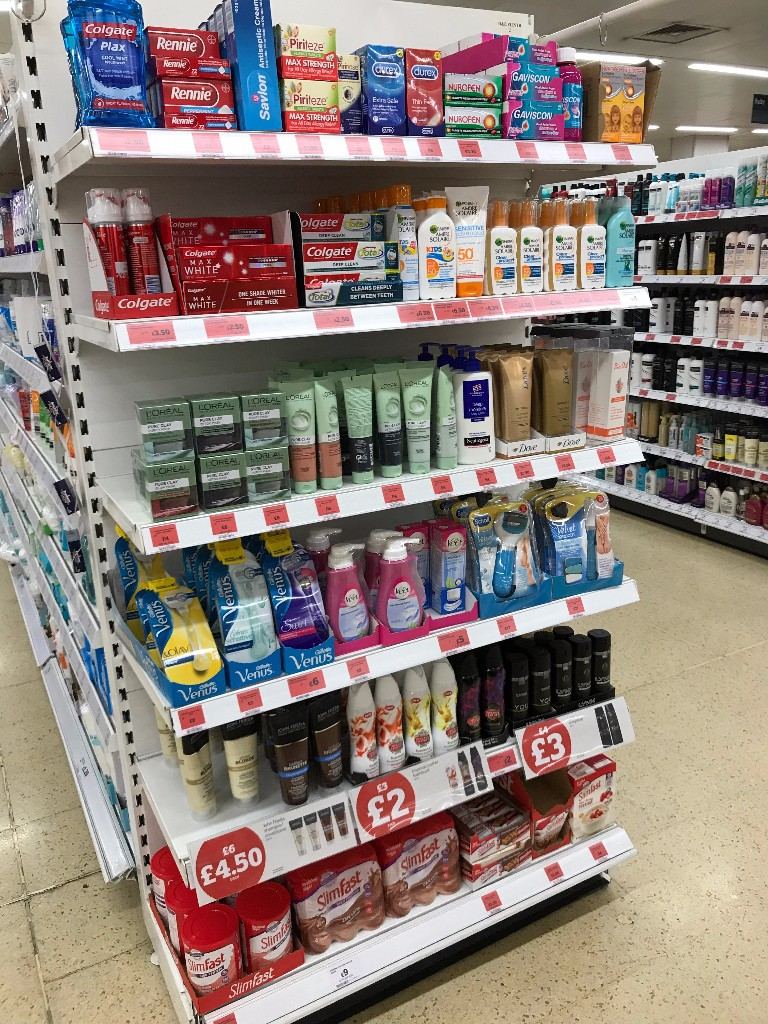
Their core ends have started to feature more and more products, which seems odd given that deals have actually reduced with their focus on price only.
A lack of multibuys does make it difficult to bring excitement to the ends sometimes, but stacking them full of product with no discernible mission doesn't feel right either.
The core end with the leading deals on Walkers, Cadbury's and McVitie's is acceptable. Decent price points too, however a Coke multipack at £5.50 then doesn't seem to fit there.
Health/Beauty ends are often bizarre and feature a plethora of lines, £5 Shampoo alongside deals at £1 / £1.50 / £2 again skews the price perception. Self inflicted issues here.
Other ends just seem to have as many deals merchandised as possible, missions and price seemingly have no bearing with Baked Beans on the same end as PG Tips and Jordan's Cereal.
Confusing.
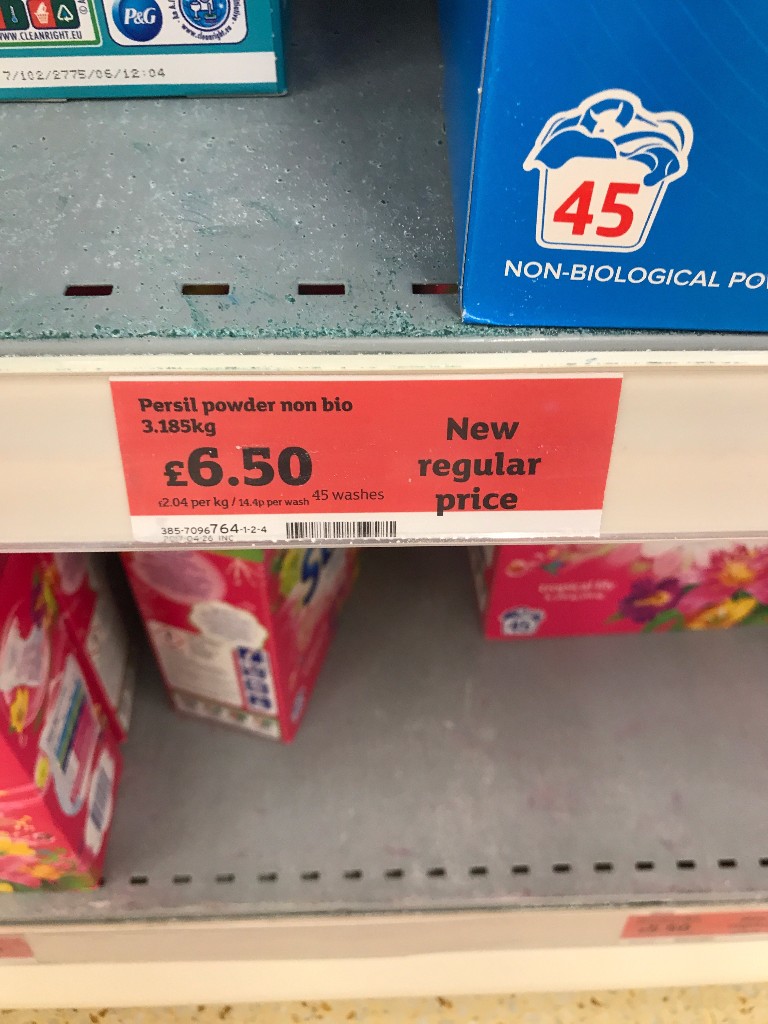
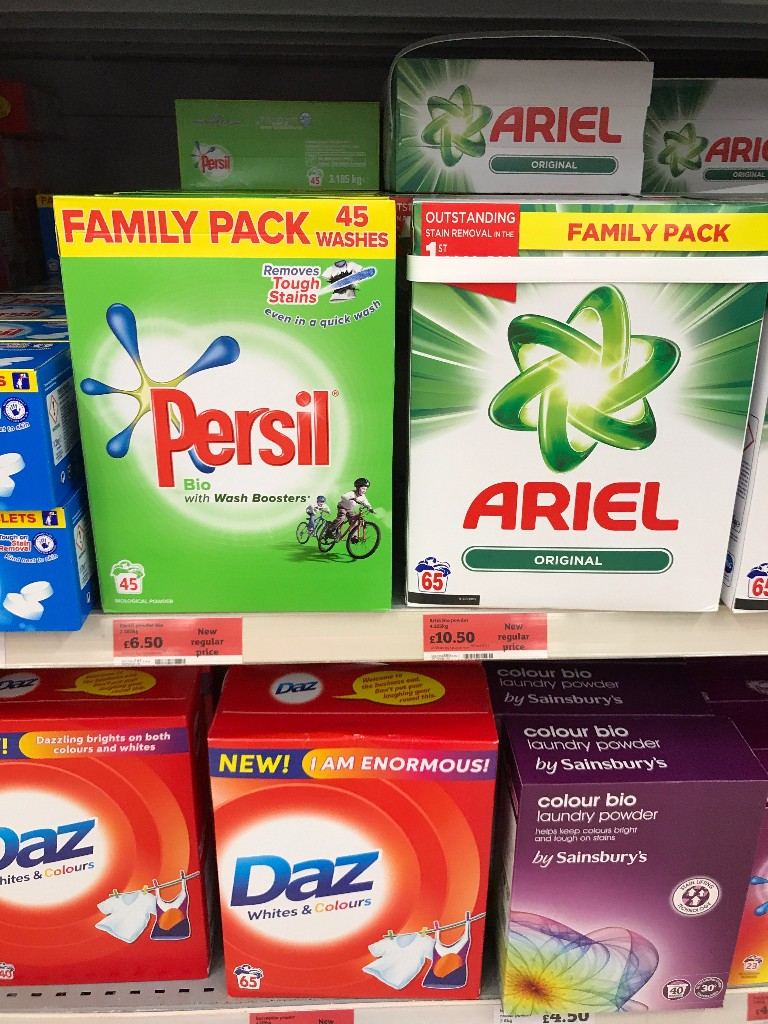
Price remains a challenge for Sainsbury's, the ending of prices in '0' or '5' continues to make things look expensive, especially where products rise to £3.10 or £3.15.
The regular price ends up looking irregular and actually flagging a rise, it's one element I don't really understand about their strategy, why would you do this?
If there's no science in the prices ending in 8's / 9's being perceived as cheaper, then why would fuel at Sainsbury's still be sold at .9, .8? For some weeks they were selling at .2 and .4 which we've not seen before in the UK either.
The images above show some more regular prices feeding through in household, however it does feel like redirected promotional spending..... It's unlikely to have a material impact on the customer though given the category (household) and the larger pack size.
The market is going towards discount, this investment would be better served at smaller pack sizes and building the value bridge to enable own label to be sharper, or medium pack sizes to feature stronger, everyday value.
Despite the 'new regular price'; £10.50 is still a lot to pay for washing powder.
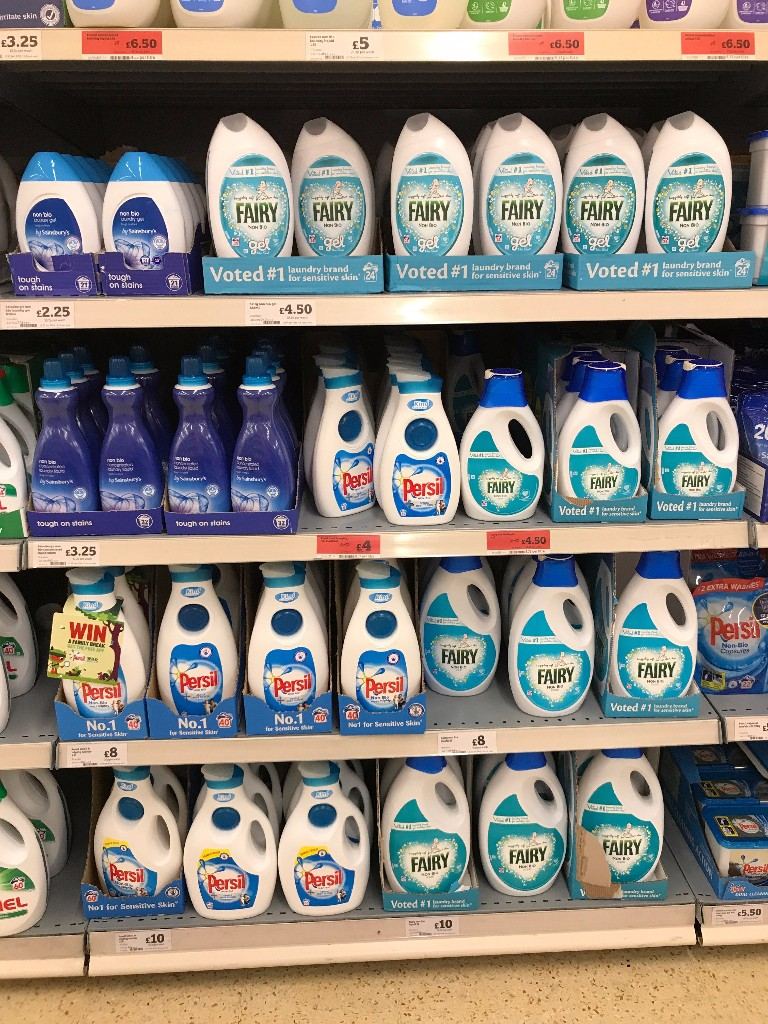
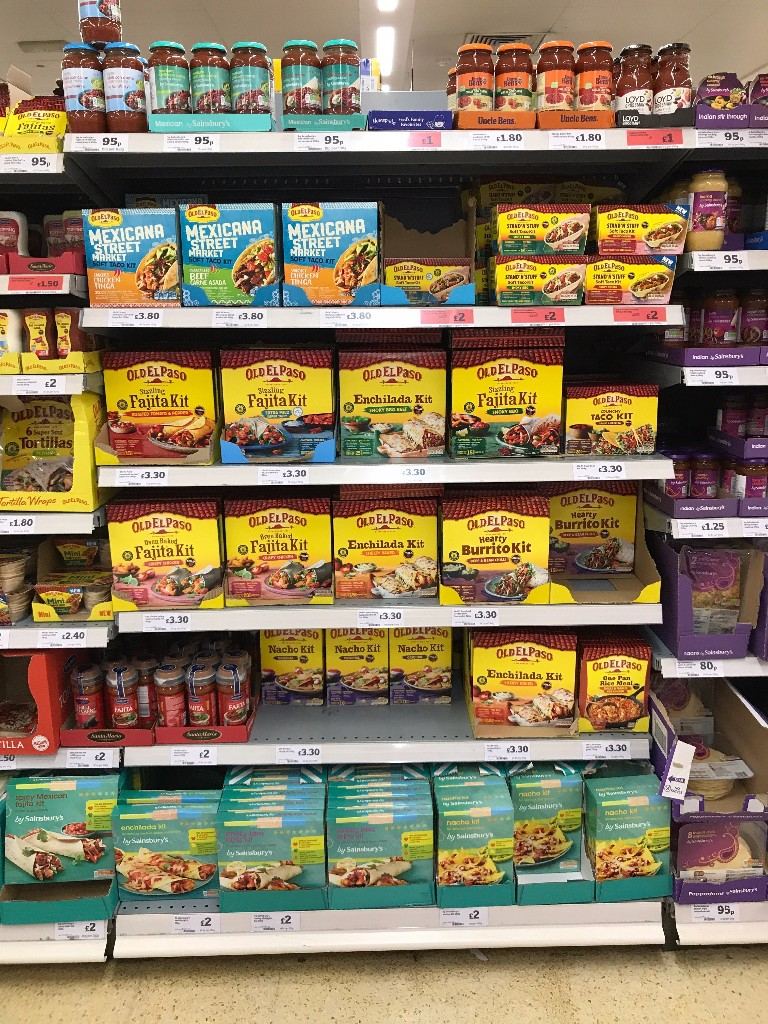
One area where you'd expect Sainsbury's to lead the way, and if not, certainly be a fast follower to Tesco is own label and the prominence it's given on shelf.
As charted on this service, Tesco have done so much work in putting their own label front and centre for customers, fixtures have become own label first and branded second in many cases.
Often the own label is interspersed within a category, occupying eye level shelf positions or indeed, a full bay adjacent to the leading brand in areas like Dishwash.
Sainsbury's haven't followed this strategy perfectly and have been far slower than one would expect given their historic focus on own label to really push the envelope. One would argue, they, more than anyone else (bar M&S) in the market have the scope and customer base to do so.
If we consider detergents in the image above, the two Sainsbury's lines are on the left of the eye level shelf and the one below, but the prominent products are Fairy and Persil.
The own label isn't given anywhere near enough oxygen here, it's merchandised on the left but the branding on pack isn't strong enough for it to stand out.
It just looks like "own label". Nothing special about it, it's likely a good product - but it's not highlighted or merchandised in that way at all. Brand wins here.
Tesco have made great strides in world foods too; mixing the cuisine based lines (Homepride sauces et al) alongside the specialist world food lines for the natives to cook as they would back home.
Even in a category like Mexican, Sainsbury's make no real effort to have their brand stand out on shelf. Bottom shelf and a little on the top shelf (top left) alongside Uncle Ben.
Old El Paso dominate, you can buy that anywhere, it's probably cheaper at Tesco and if it isn't, they'll give you the money back anyway.
Multiply this for even 4/5 categories and you're in trouble in ambient, Tesco opted for a brave, longer term strategy around own label and whilst there will be bumps in the road, it's ultimately a better place to be.
Plus, if own label is the growth engine, they have full control over that. From ingredients to pack size, promotions to price...
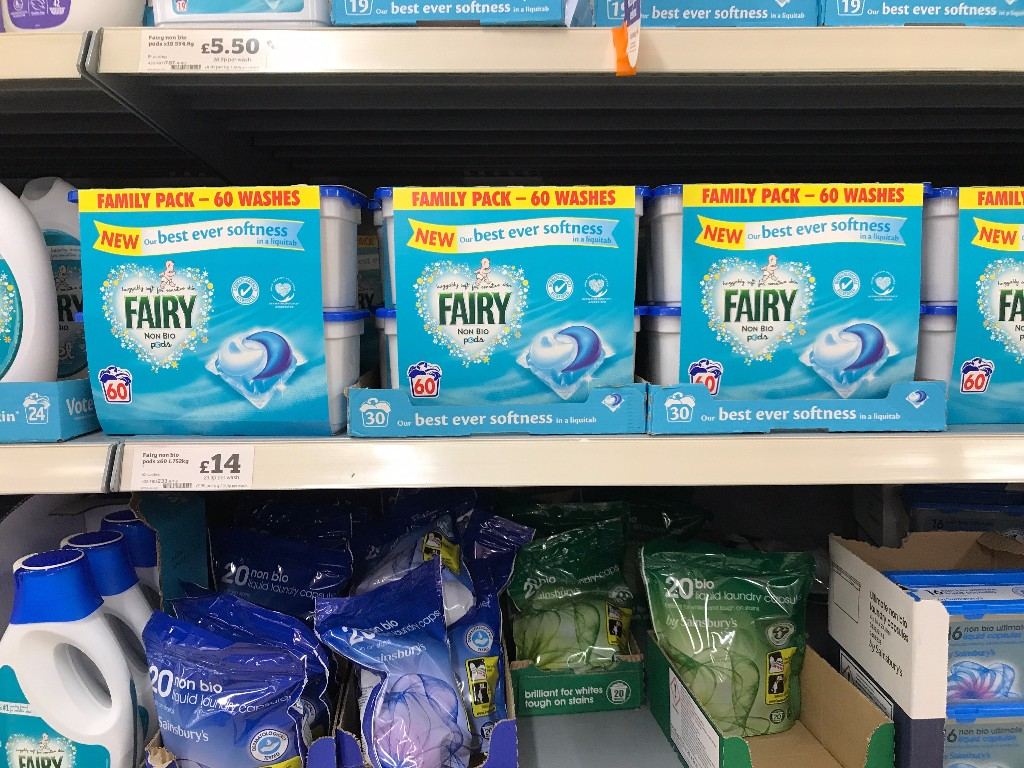
On the assortment; you have to question the rationale for the bulk packs being ranged sometimes, Fairy tablets (family pack) 60 tablets.
£14!
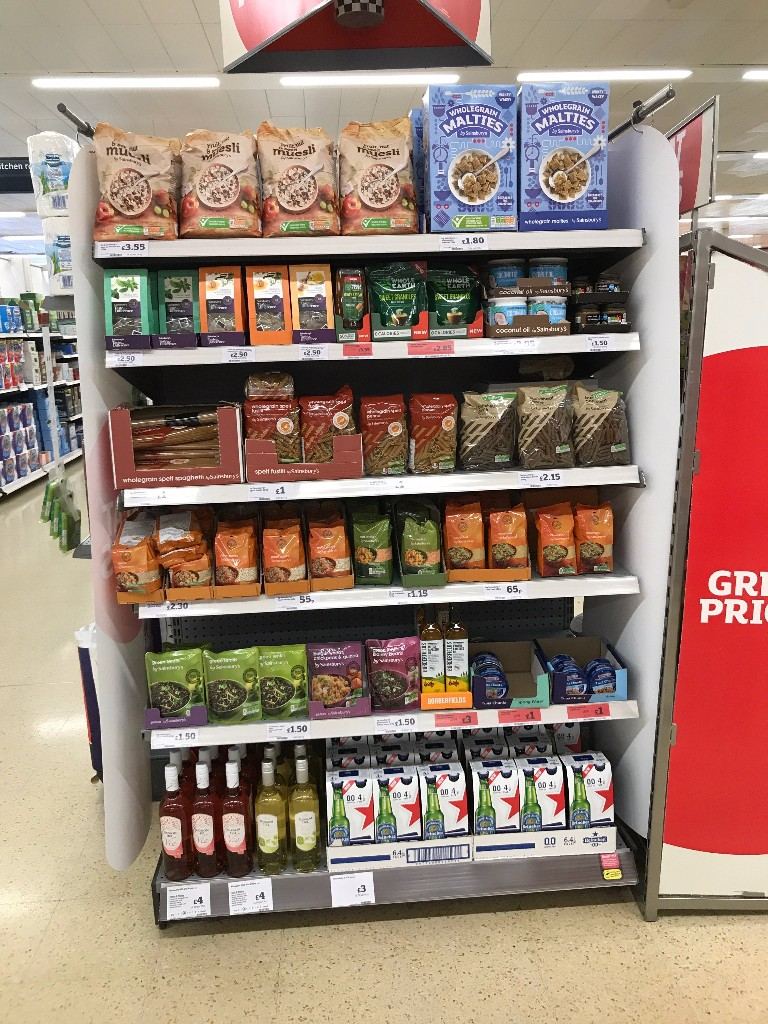
In store this week saw another gondola end stick out...
What's the idea here? I can see low alcohol lager, Wines, Fish, Oil, Lentils, Pulses, Wholegrain Pasta, Tea and Muesli.
Oh and own label Shreddies. Marvellous.
Lots of own label lines featured here, but what's the big message?
Customers need a reason to trade in to the end, what are they saying to the customer about this range? Why is it here?
Is there a health benefit to buying some of it? All of it? Will the Shreddies (own label) work magic on their own?
Another example of uncharacteristic execution issues scuppering their efforts in stores. Either central, or store, or both.
Job losses have been a running theme in the UK food retail market for a number of years now, the discounters have changed the landscape which in turn leads everyone to look at their own house and try to get things in order.
Justin King and co did a marvellous job of reshaping the business and tightening process with IT in the mid to late 'noughties' which has led to little fat to trim really.
The loss of night shifts will be interesting to monitor as a significant further number has been announced, previously stores with low sales but picking for online customers retained their night shifts.
The next wave of cuts now incorporates more stores and the impact on the shopping trip will be interesting.
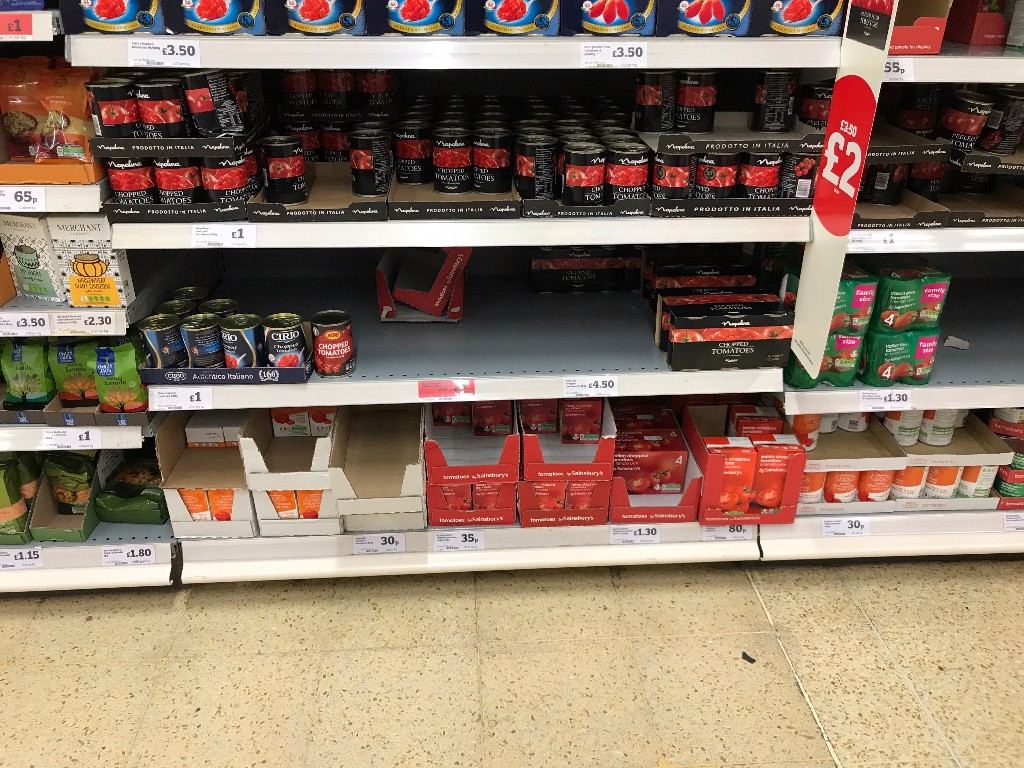
The challenge with running fewer promotions? All the trade is driven via that one product, it's now gone off sale. The customer is faced with brands at their unpromoted price, or own label.
A secondary deal would aid the fixture here; and not see the trade all go in to the one product with the inevitable sell out.
Trade in Canned Tomatoes which are historically hi/lo on brands thus lack brand loyalty, means own label can command a reasonable share here.
However too few deals leads to availability issues as we can see above. Unclear if a move from night replen has anything do with this situation, or if it's just a case of trading needing help stores and operators out.
Own label needs more of a focus and to be interspersed within the category. If there is a gap on a brand (4pk at £2) and the own label is located nearby, rather than in the next bay... It becomes attractive to the customer given the lower price and similar pack size / ingredients.
Of course, stores would ideally carry some excess of this products and replenish in day, irrespective of their replenishment methods.
Twilight fill can see customers able to buy from the fixture on the evening and then the following trading day.... They don't necessarily always open full.
Factor in online shoppers 'buying' for their customers too and you could be nearly empty before you open the next morning!
With lines like the own label Tomatoes - it's a double bonus if the customer enjoys the produce, and returns to JS as the quality of the Canned Tomatoes was good and finds other products to switch to and enjoy and save money.
An ideal world perhaps, but still..... We can dream.
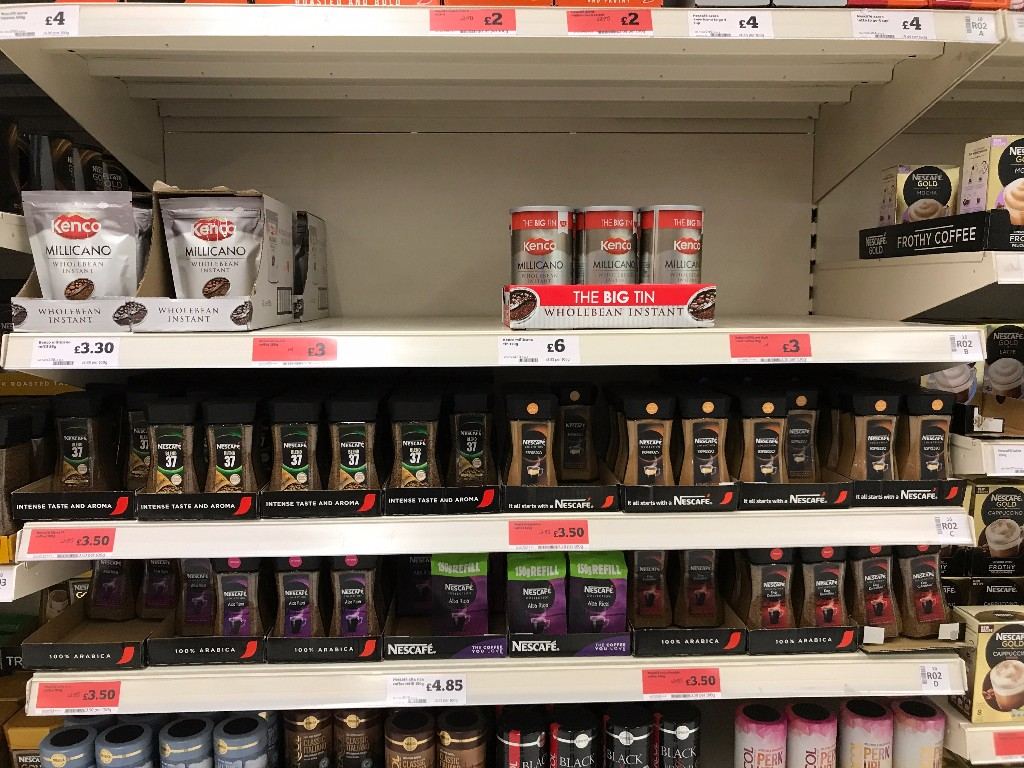
Another good example of the trade being in promotional items, and their importance to the shopping trip. Coffee is a great example of a category that is hi/low and also expensive with commodity swings, aided by Brexit too.
Two deals on Milicano, both off sale. The other packs remain in situ. Daytime replenishment needs to occur on these promotional lines as deals are so important for customers.
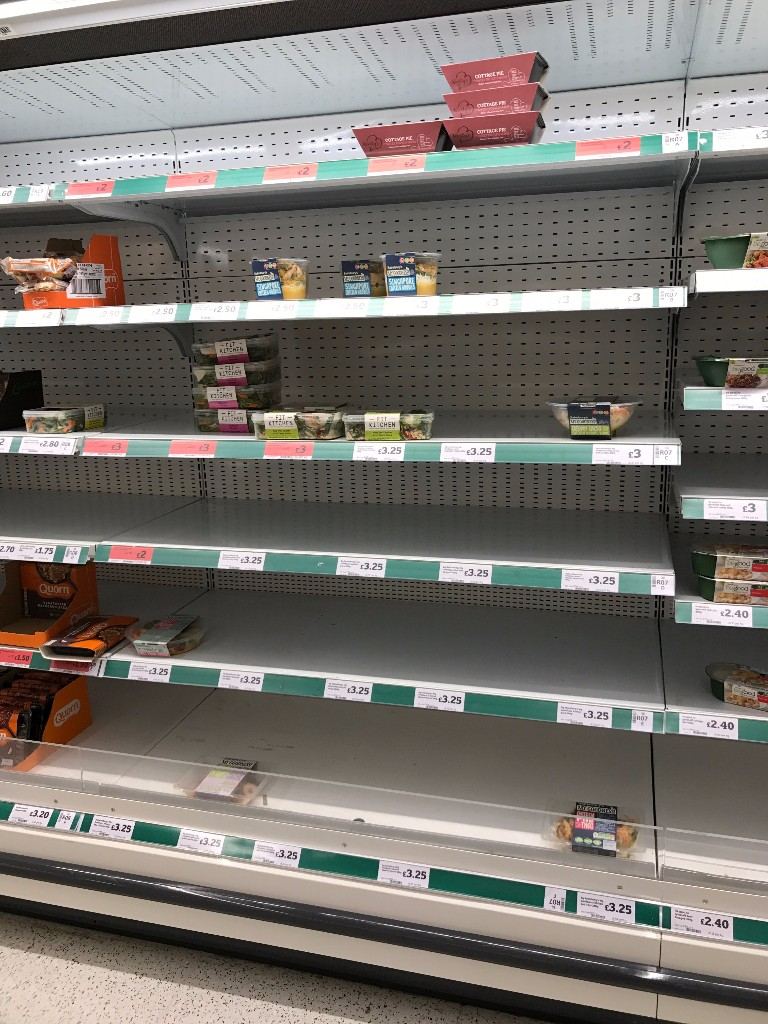
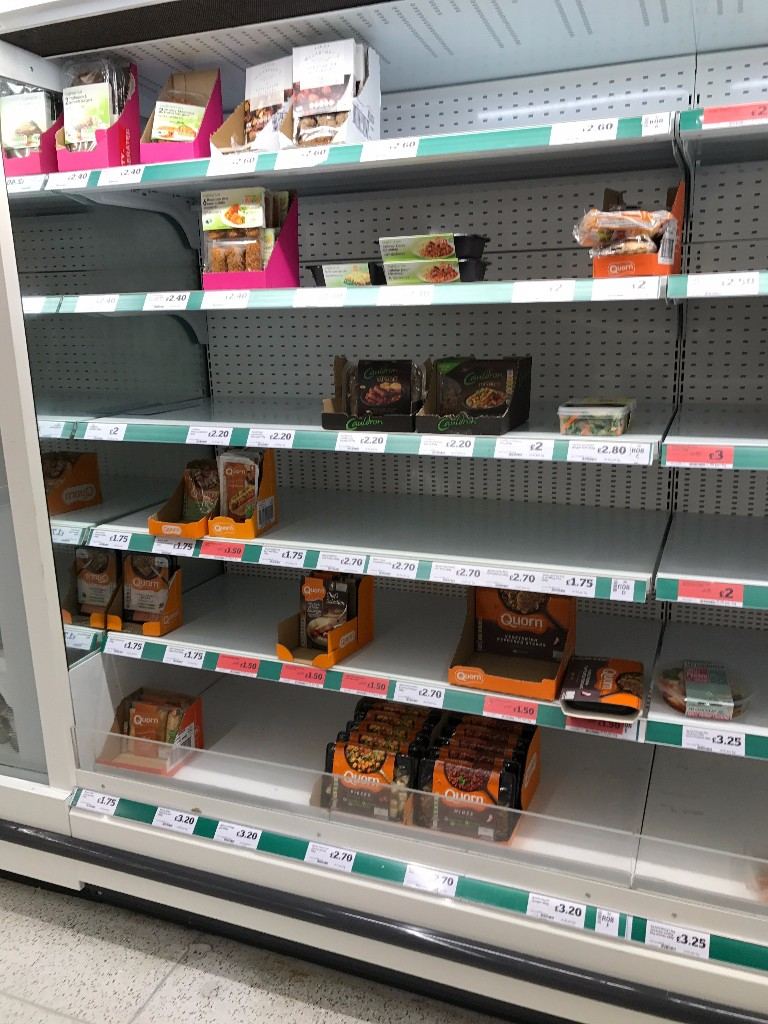
Refrigeration breakdown? Damaged stock? Better than expected sales? Very disappointing yesterday in store, with availability beyond poor in these areas.
It's about managing expectations, a note on the shelf (hard to do well admittedly) just to emphasise stock is on its way, please ask for help if you can't find anything would ease what is a pretty grim picture.
Fresh Foods can be erratic in terms of availability due to the nature of the reductions and 'losses' which impact future orders for that product. This means that availability can be harmed if a store is losing money via reductions on poor selling lines.
It's a fine balance, early week is always hard to balance up too, especially if the weekend has been both warmer and busier than expected.
I'm always reminded of the words Justin King spoke (story is 3rd hand admittedly) but there were disagreements and discussions about waste, and range. Justin would simply ask:
"Are we all agreed that to grow sales, we need great availability?"
That was it. Retail is Simple.
Fresh is typically filled up on a morning when the night shift changes to twilights, so that can be chaotic in those first few hours. One to watch as ever....
Despite these points; Sainsbury's remain broadly strong in stores, it hasn't helped that they've been without a retail director for so long, alongside the challenges with integrating Argos and the wider workstreams that impact core stores too.
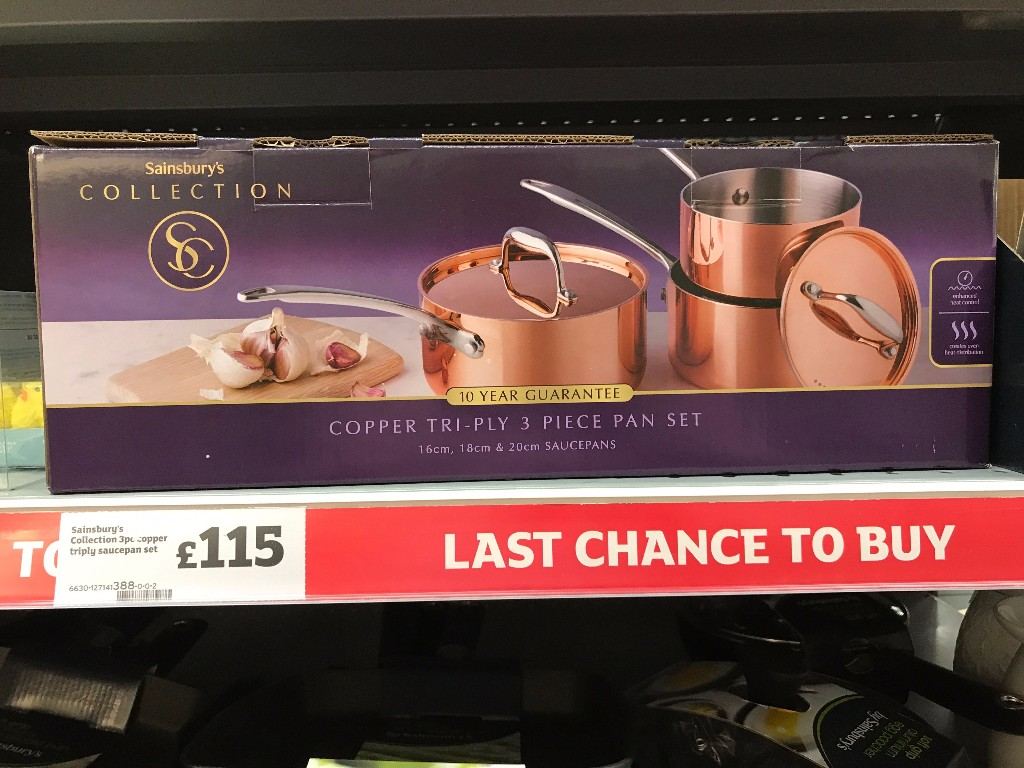
In terms of operations; clearance used to be an area of real strength for Saisnbury's. They never held on to stocks for too long, particularly in non food given the limited life span and seasonal ranges.
However they have started to restrict clearance levels and try to hold out for a higher price, rather than clear through at a lower level. This isn't necessarily true for seasonal ranges (Easter for example) but can be for individual stores who no longer range a specific range of products when Argos arrive.
These pans for example could have been listed in store, but when Argos arrive, are delisted so thus end up in the clearance area.
An error presumably, but £115. Last Chance to Buy?
I'll take my chance!....
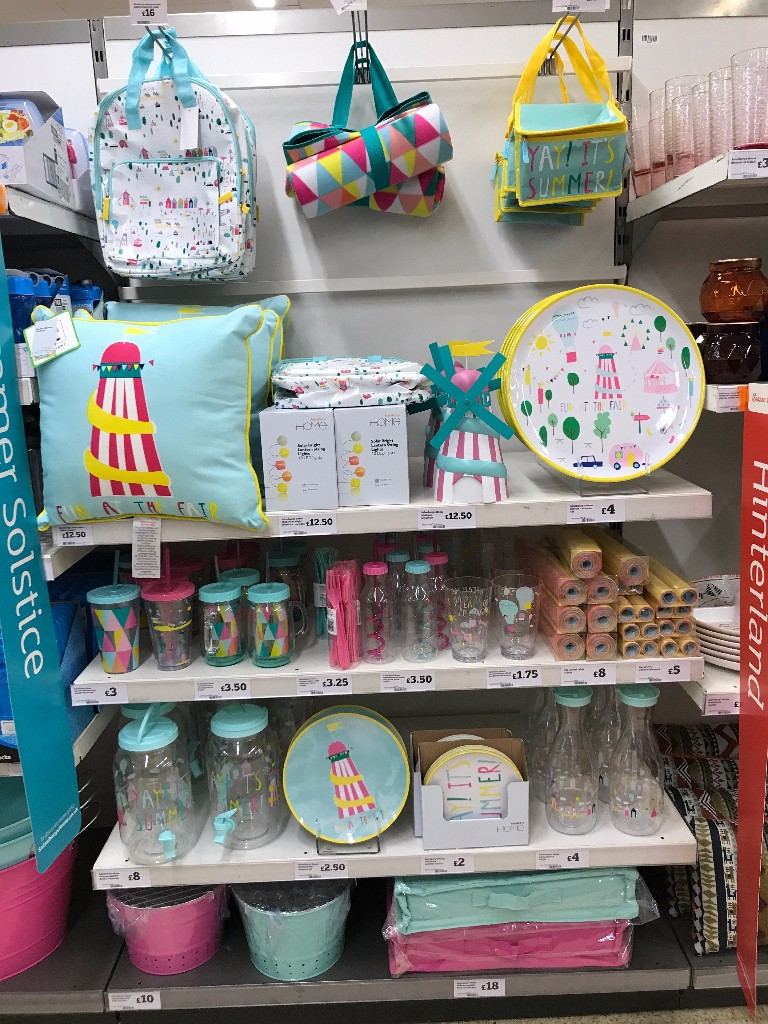
Nothing that isn't fixable at Sainsbury's, but this quarter (ending June) should be reasonably favourable for them given the trading period included Red Nose Day, Mother's Day, Easter and the start (we hope) of Summer too.
There is some good work that remains around the store; own label developments in terms of product innovations are noted. However there is much more to do in this arena given the progress in the market.
The Summer range of non food as evidenced above is striking, great range and prices aren't high either.
There are some pockets of range that are higher in price than expected though, these anomalies need to be weeded out to maintain trading focus for the business, especially in seasonal assortments.
This email does perhaps carve food up a little and there's an expected level of focus on Argos to the detriment of JS perhaps, but it does show that you can look near irrelevant if focus isn't there or even if a distraction is around.
The Argos acquisition appears to be going well and the local stores near me have had Argos come out of the Homebase and moved in to the adjacent Sainsbury's.
Habitat looks a worthwhile addition to the store offer where applicable too, the news of Patisserie Valerie and Sushi counters is perhaps released to the press so distant investors think that something is being done about space at a higher level......
These are worthwhile additions but won't solve any major space issues that Sainsbury's have, there is a challenge around Patisserie Valerie and how that interacts with Sainsbury's Bakery/Patisserie offer too.
Overall, lots more to do on Argos, and the food business needs the fire stoking. It all feels a bit transitional at the minute, almost between a rock and hard place....
That isn't living well........
Subscribe today to this service, today!
From the Grocery Insight newsletter archive, first sent to subscribers on 3 May 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.