Entry level tier changes
18 September 2019
Become a subscriber to this service, today.
Interested in our new image platform?
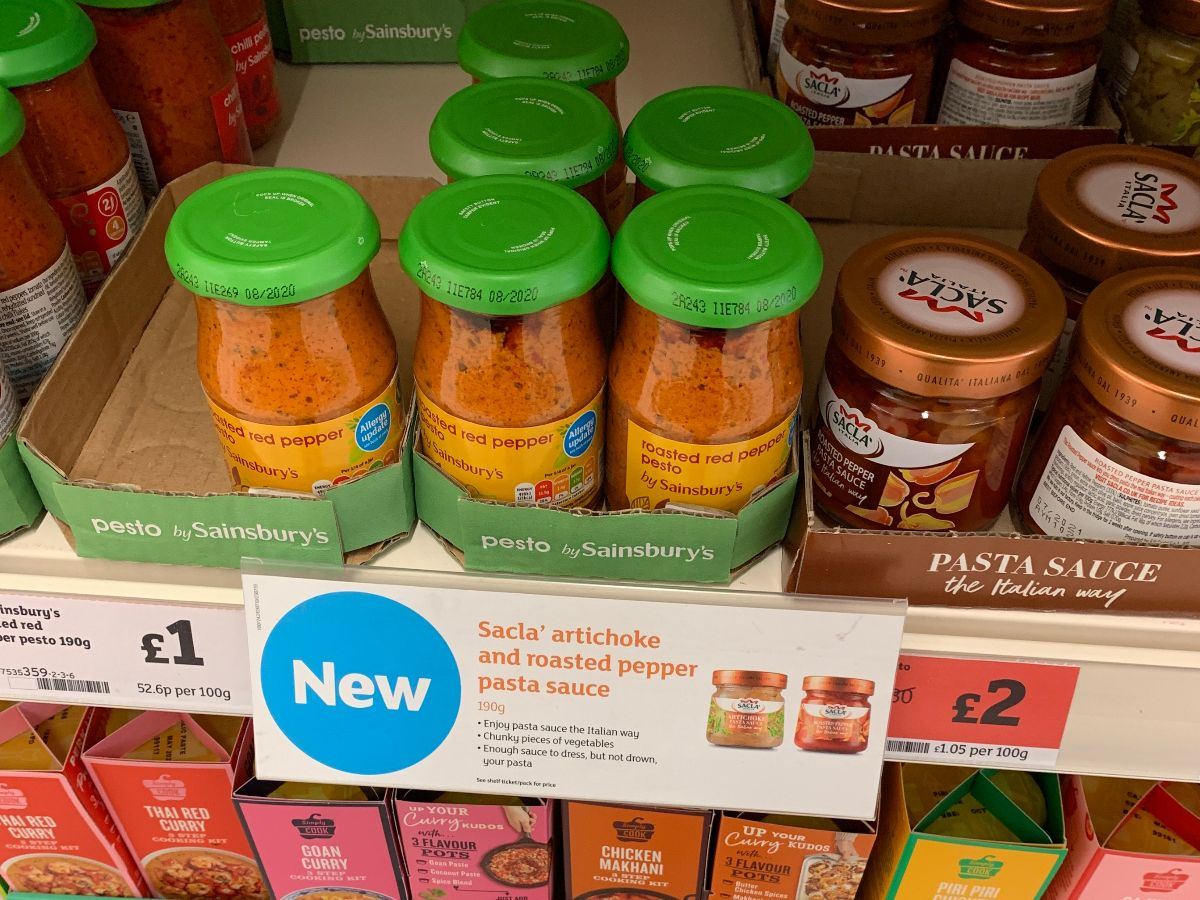
More progress from Sainsbury’s in their campaign to sort their own label out with value tier products continuing to change over to the new stable of ‘sub brands’ a la Tesco.
Even the Tesco strategy (honed in Ireland vs. Discount but on own label products, mid tier) was based around value tier products being expanded and changed to a stable of said sub brands to enhance their appeal and prevent the leakage of customers going to Aldi or Lidl for lower prices core products.
What Tesco Ireland did well was push hard on price and push discounters in to lowering prices and following them in, but also focusing on areas such as Finest (pushing higher margin products because the customer feels as though they’re ‘saving’ so can treat themselves) and also sharpening provenance in Meat, adding images of farmers and enhancing Irish credentials.
It’s never just about price, as we know.
However Tesco UK also resolved to improve their mid tier product range, working hard for a number of years on pushing own label products up to eye level versus brands and being competitive on price in this arena. This helped customers understand the value Tesco had to offer and also ensured that value stood out as the entry level tier.
The wider appeal that Tesco has is that they offer the full range proposition. Good, better and best alongside brands too. Sainsbury’s also have this, but their appeal on own label has been difficult in recent years as everyone else focuses on own label in the marketplace, notably premium tier in discounters who bring lower prices and a plethora of awards.
Even the own label gap has been narrowed and levelled and other retailers focus on own label in the new discounter world but also; this mean innovation and quality are ever important but the customer has ample choice and Sainsbury’s has to work even harder, just to stand still.
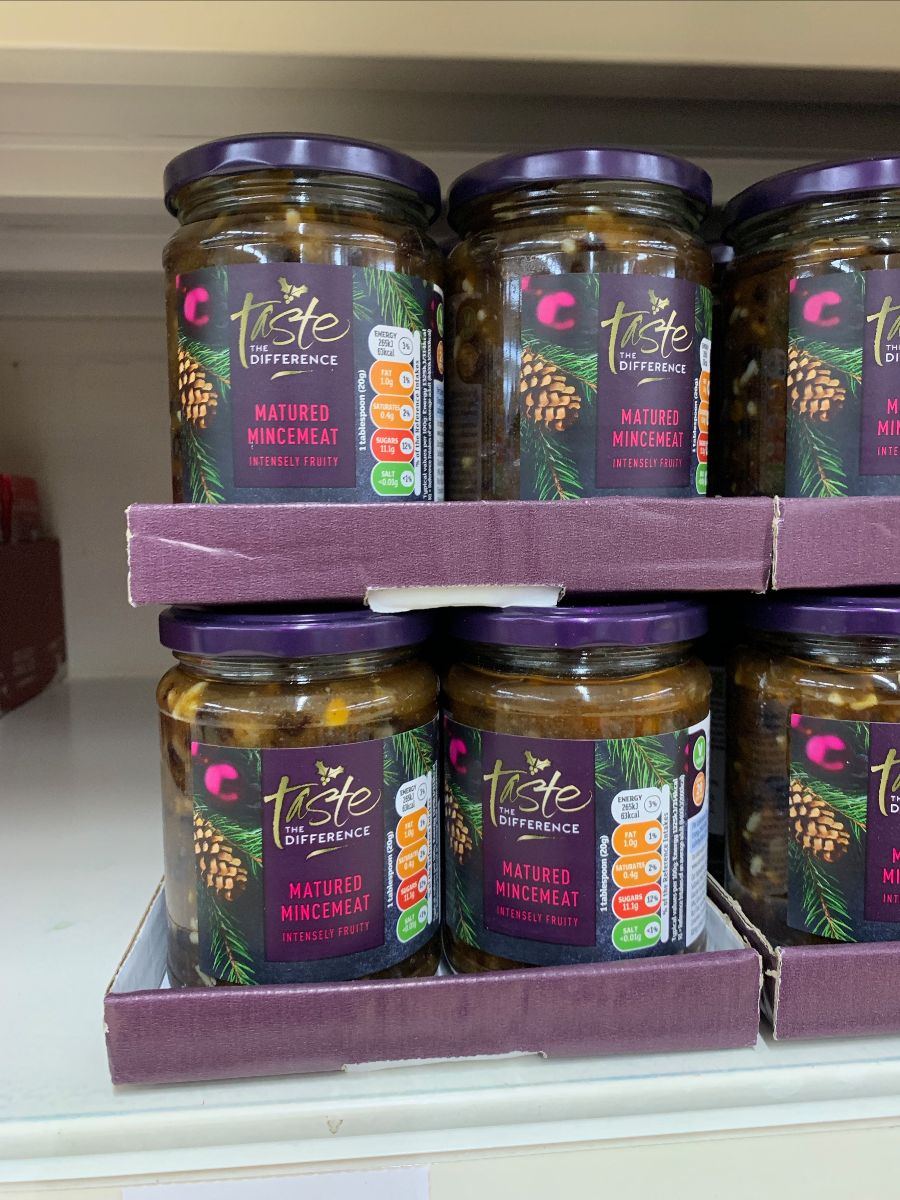
Changing their premium Taste the Difference packaging and focusing in that area recently is long overdue and the Christmas products (Mince Pies) already look better in their new packaging but this is a crowded marketplace and they have keep their focus in this area, balancing up quality, value and price.
It remains unclear with Sainsbury’s whether their approach of tightening up the value tier with newly branded products
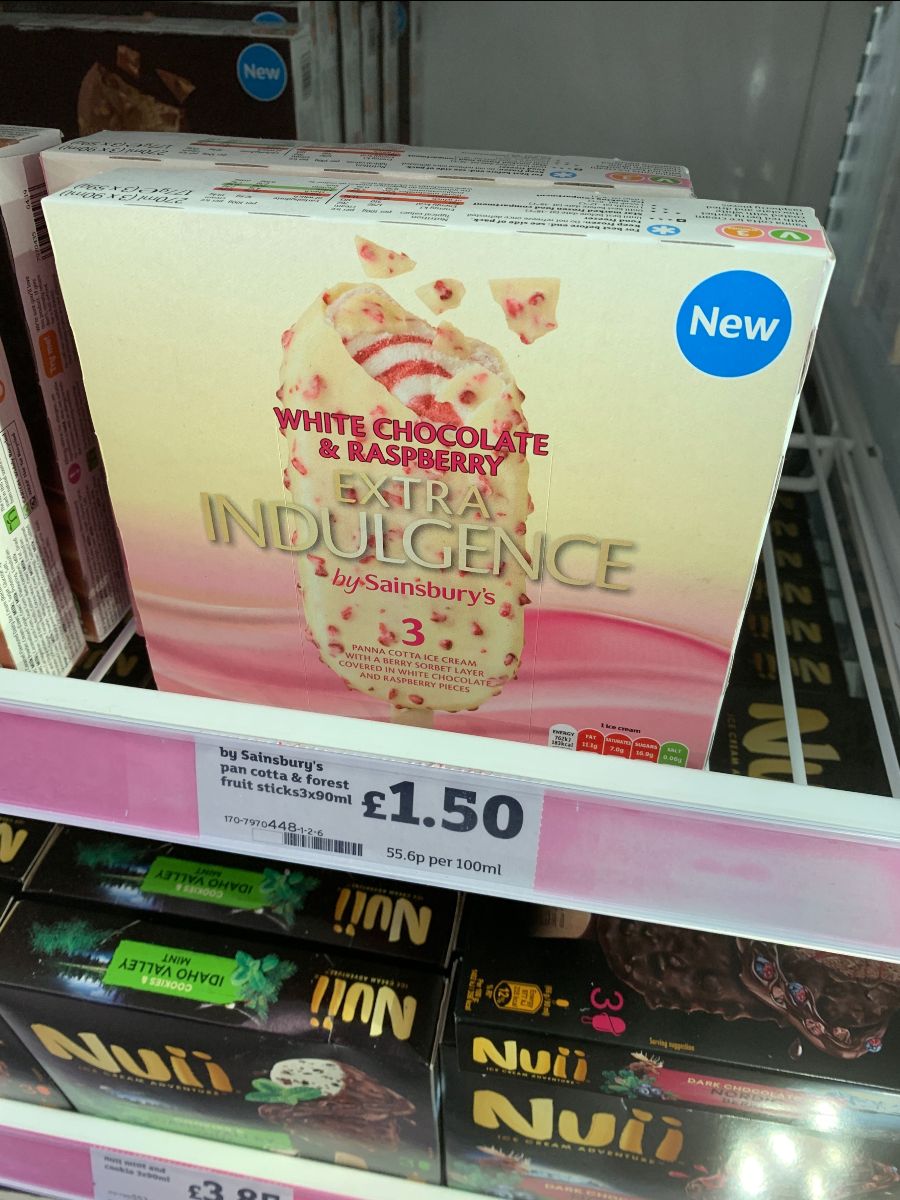
The Indulgence products in Frozen Foods (an area where JS have done well in recent times I feel) look strong and are a good example of mid tier+ where the core tier works well for customers and offers something a little different for customers.
Beyond say 'core' chocolate ice lollies. Think back to the days of Classic Cola in Sainsbury's being a 'brand' in its own right.
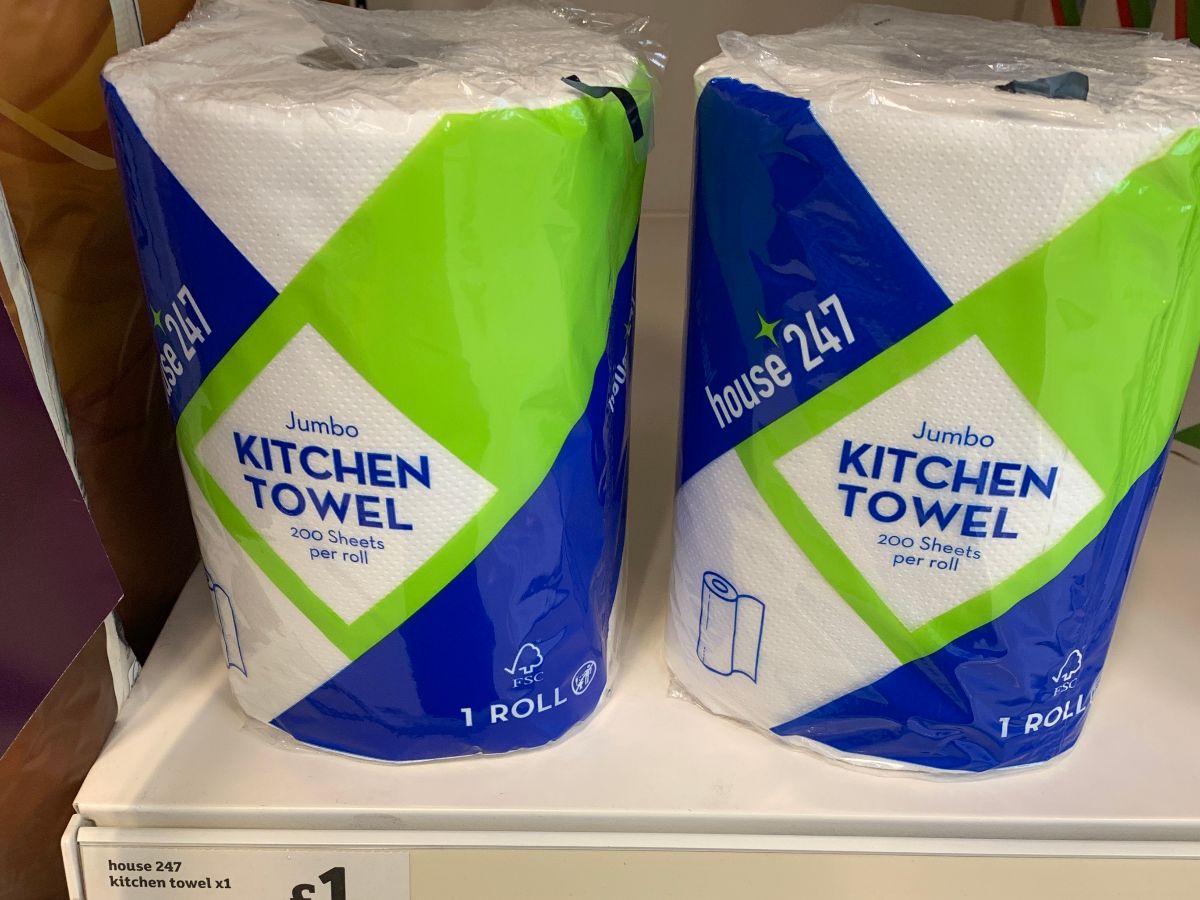
In to Household and toilet paper, in particular, has seen a huge push back on the brands with a huge space taken up by own label with the core prices strong in this arena.
Sainsbury's have a general feeling of quality here, their basics line, therefore, stood out as one that looked a poorer quality versus even the own label comparative. Given prices are low but discounters etc are lower, then it becomes a case of quality and perception.
So changing this range from Basics to "House 24/7" which in itself sounds like a TV show that would have been on "Living" with Kim and Aggie some years back is notable. The packaging is stand out and it looks a bit 'bargain' store, rather than Basics which due to the age of inception (when value brands were just that) is perhaps stigmatised.
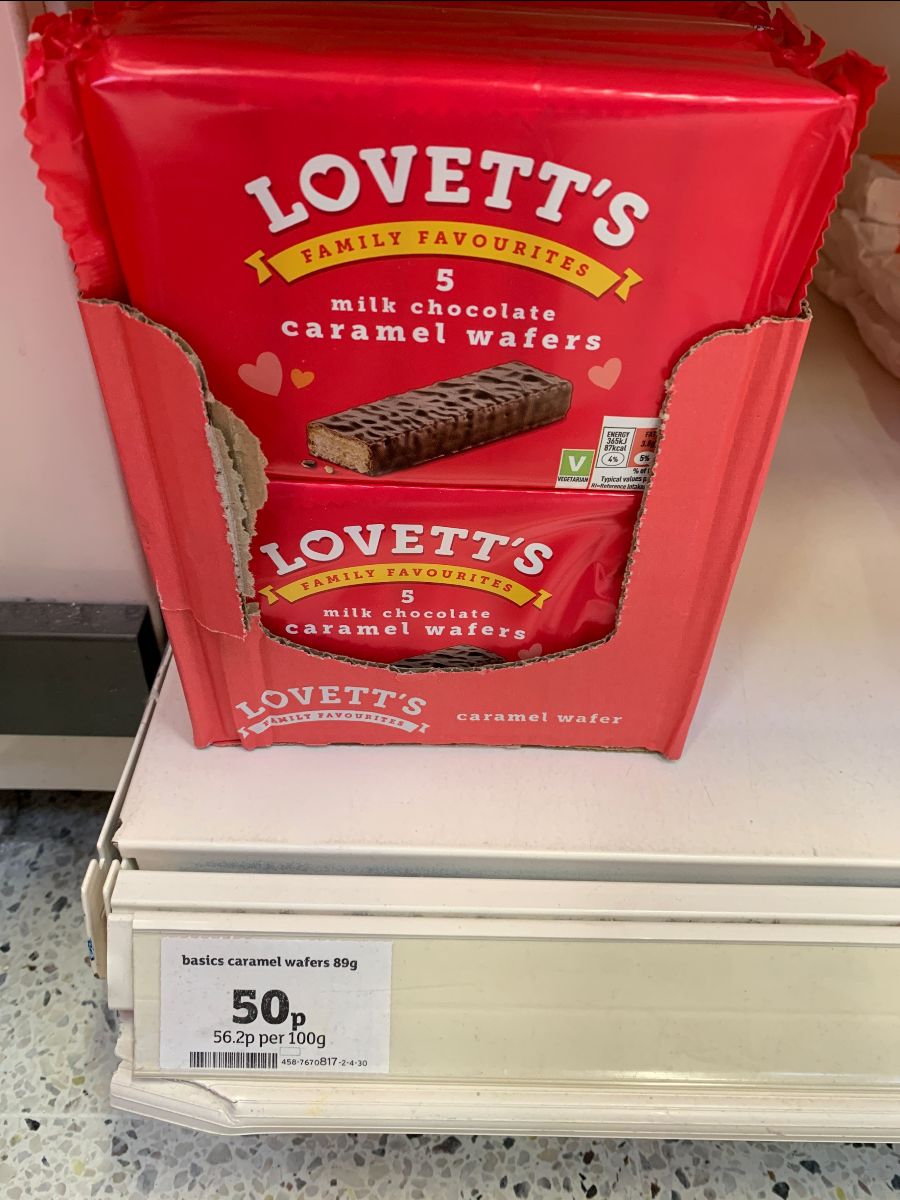
By introducing Lovett's to Biscuits (and Apple Pies in fresh foods) this range automatically looks more authoritative but the challenge then is to the mid-tier where the price gap is obviously larger.
Can Sainsbury's balance out customers switching to the cheaper, more appealing entry-level tier product with new customers coming into the store to be impressed by their general work on value?
Can they make mid tier appealing enough within the price banding to ensure customers don't feel the need to 'trade down?'
It was (and is) a tough ask for Tesco; however for Sainsbury's with a weaker margin and challenges in other areas of the business as well, it's a tougher ask and a bigger question too.
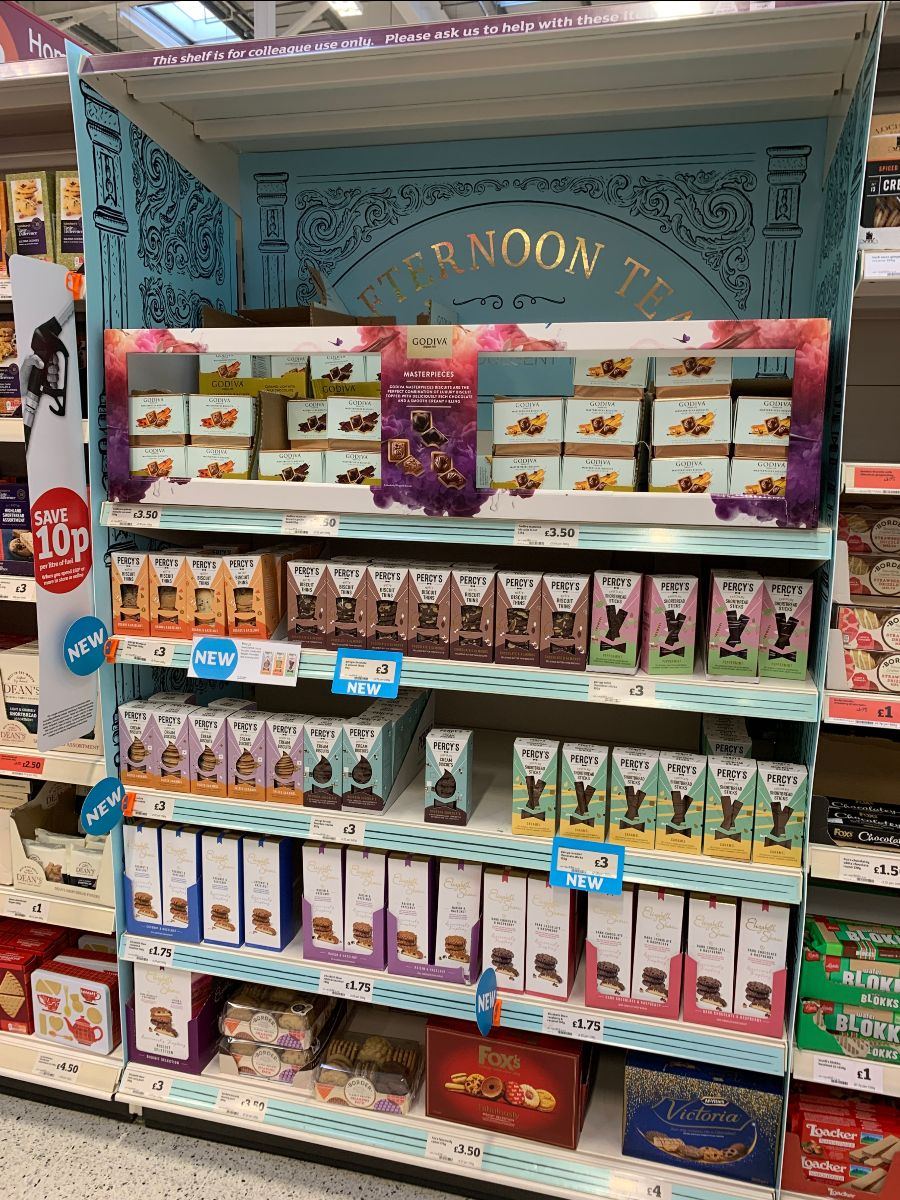
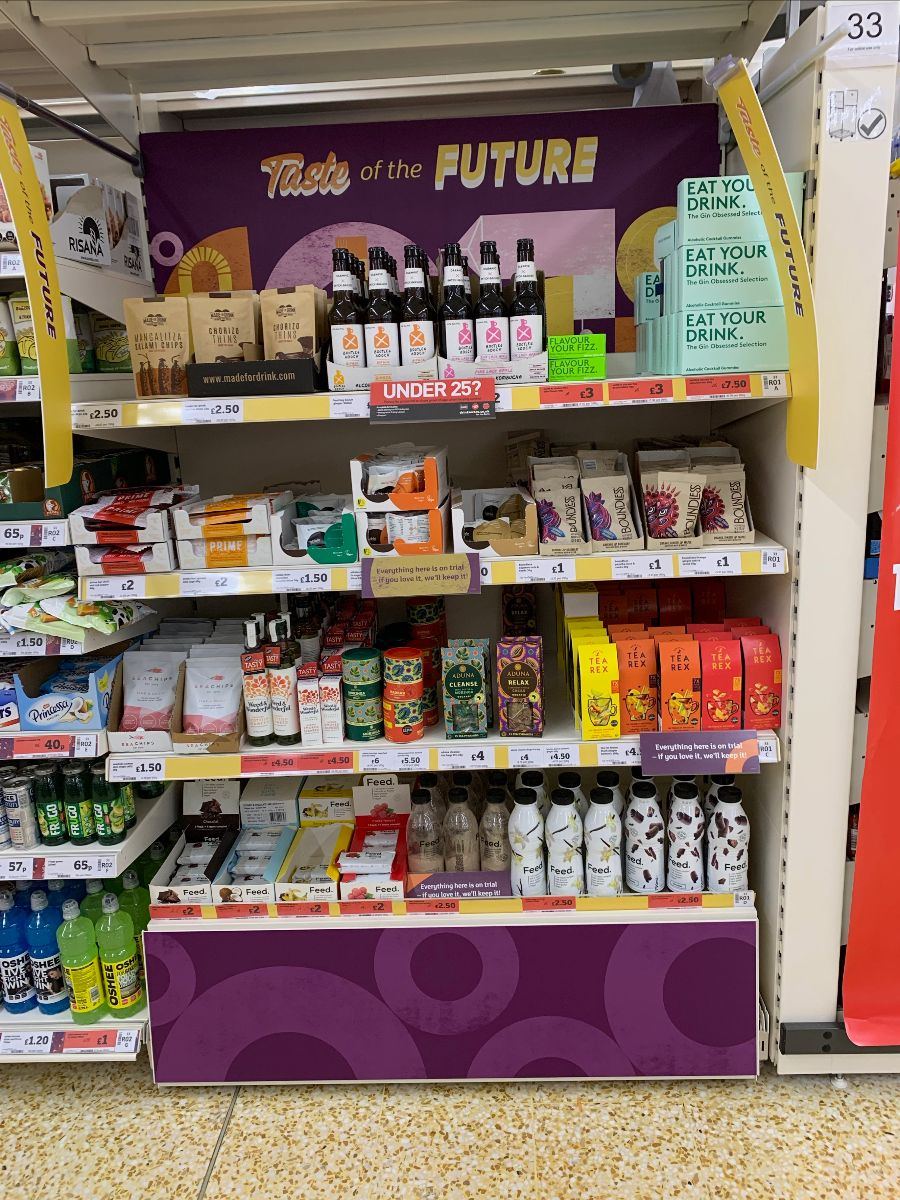
The concern I do have with Sainsbury's is that they're 'bookending' the offering, ironically as we saw with Tesco under Philip Clarke where work on 'value' (price drop etc) was offset (in the commercial minds at least) by the 'venture brands' work that meant little to anyone outside Tesco.
Choc a Blok remains a staple for Easter with their crazy Eggs but the vast majority of these margin rich products that didn't have equity, nor represent real value for money were failures and ended up highlighting how expensive Tesco had become.
The strategy of introducing these 'venture' brands around Sainsbury's stores concerns me, whether it's flagged as a 'future brand' or 'work with small suppliers', these products are expensive and there's not enough of a 'story' behind them, or how they came to be, to justify the price points.
In affluent stores (even then!) sure, but in the real world of the north and midlands, much less so. Even changing Basics around means that the top end products are still too expensive.
Indeed in 2013, Tesco went on a campaign of rebranding Finest in packaging that you could no longer read, vastly expanding the range across categories such as Oils and Fresh Foods just ahead of Christmas.
They badly misread the market, which was still value-conscious post-recession and Discounters were still evolving their offer to appeal to more customers too. Thus they had a disastrous Christmas as their advertising inadvertently made everything look very expensive and nullified any value work they may have done.
Sainsbury's must ensure that with their premium revamp, they do not do the same this Christmas. Customers like to trade up but the premium tier has been democratised by Aldi and Lidl, but also Iceland and Morrisons even, who win plenty of awards for their products every single year.
As Sir Terry noted in his excellent book, we do live in a world where just 1 price being out of line can see the entire range of 30,000 products (priced fairly and well) being seen as 'expensive' by the customer, thus the chain is seen as expensive and poor value for money.
That is quite a challenge. There are moving parts aplenty for Sainsbury's (like all the major retailers) and that is just one more reason why the discounters, with their simpler retailing model work and succeed in so many territories.
All eyes on Sainsbury's then for their upcoming capital markets day too, the refitted Hedge End store is next up on our email service. A busy store and facing similar challenges that we see across the nation (but also, in truth, across the market.)
Interested in our new image platform?
From the Grocery Insight newsletter archive, first sent to subscribers on 18 September 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.