Capital Markets Day for Sainsbury's
1 October 2019
Join our insight service, today.
Want to see all of our store images?
The Sainsbury's Capital Markets Day was last week and there were some interesting elements to come out of it, as you know, dear readers - we'd already flagged the value brands changing to a stable of sub-brands a la Tesco.
There is more to come on the day itself in terms of slides and analysis, but there wasn't a great deal of 'new' news. Their recent uptick in performance helps matters of course although there were some pushbacks around fuel savings (I.E. they've done fewer fuel days that Morrisons or Tesco) however if you split it over the year, the concentration of fuel promotions is not something I think we've ever seen in the sector.
It was literally every other week, but there we are. They have reacted and appear to be much more competitive in the market than they once were, price lockdown has grown legs and now appears to make more sense to the customer - especially in the seasonal space.
The Hedge End store is very similar to the Selly Oak store with a new cafe (no food market offer) and this was the location of the investor day and store tour. There are a few nuances in the store itself and it's interesting to see this format rolling out but there is a great focus on non-food which is perhaps at odds with the market (and wider economy)...
The links between Argos and Sainsbury's remain in evolution but the links on the shelf are still confused and the Argos own label versus the "Home" brand from Sainsbury's appears to be a war that only Sainsbury's could really win, given the equity in the brand.
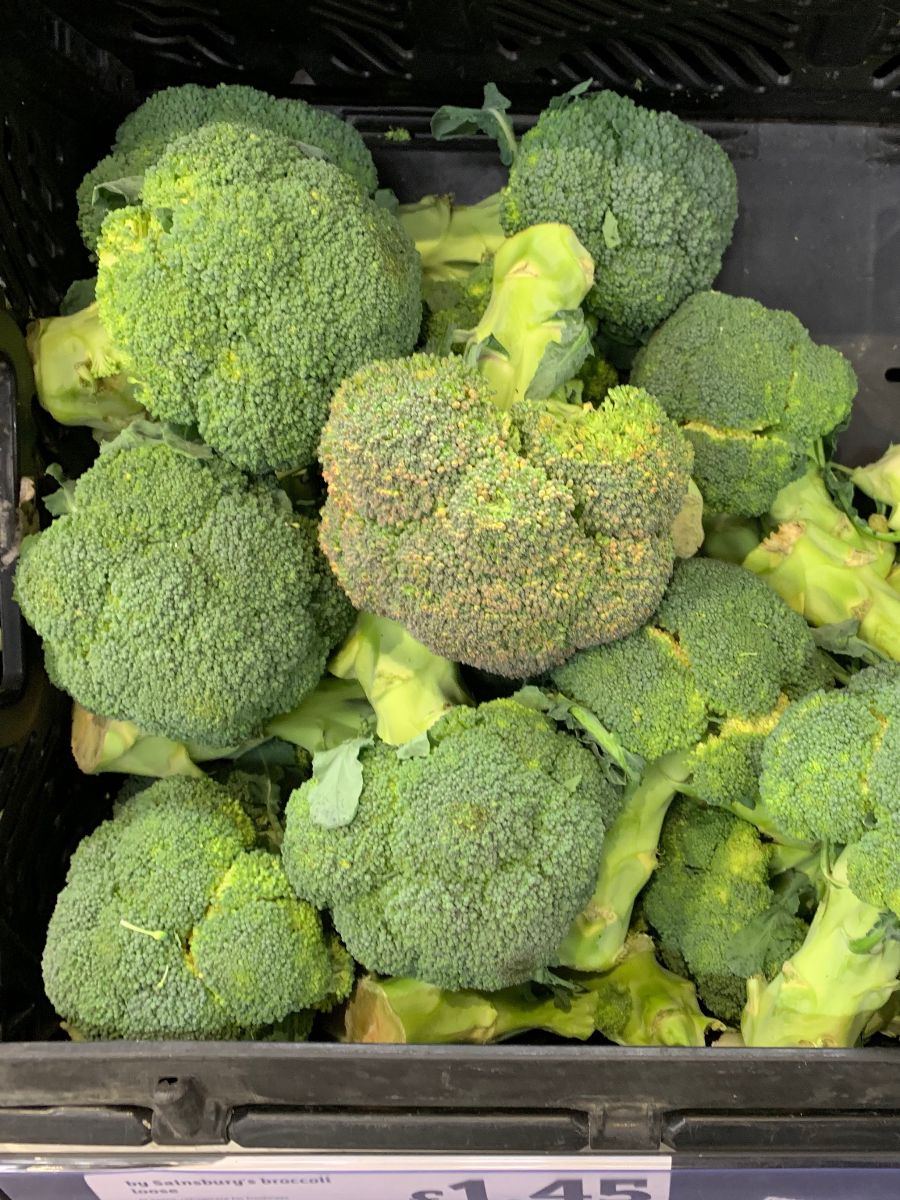
Despite the improvements pointed to by Sainsbury's - namely a better picture on Grocer 33 (although, as luck would have it, 48/100 in the week just gone), there were issues in Hedge End for a Monday.
It was a busy store though, despite it being Monday, trade levels were good. The store has 49 checkouts (manned possibility) alongside self-scan and scan and go. So a big old battleship.
Even in the 'good old days' standards would have been a battle for the store, but nonetheless, you are judged by a Monday morning as much as you are on a Friday night. Everything within the walls counts, otherwise, it wouldn't be in the store.
The challenge is to get towards that consistency, there is a sign of improvement in the business but the issues remain throughout the estate
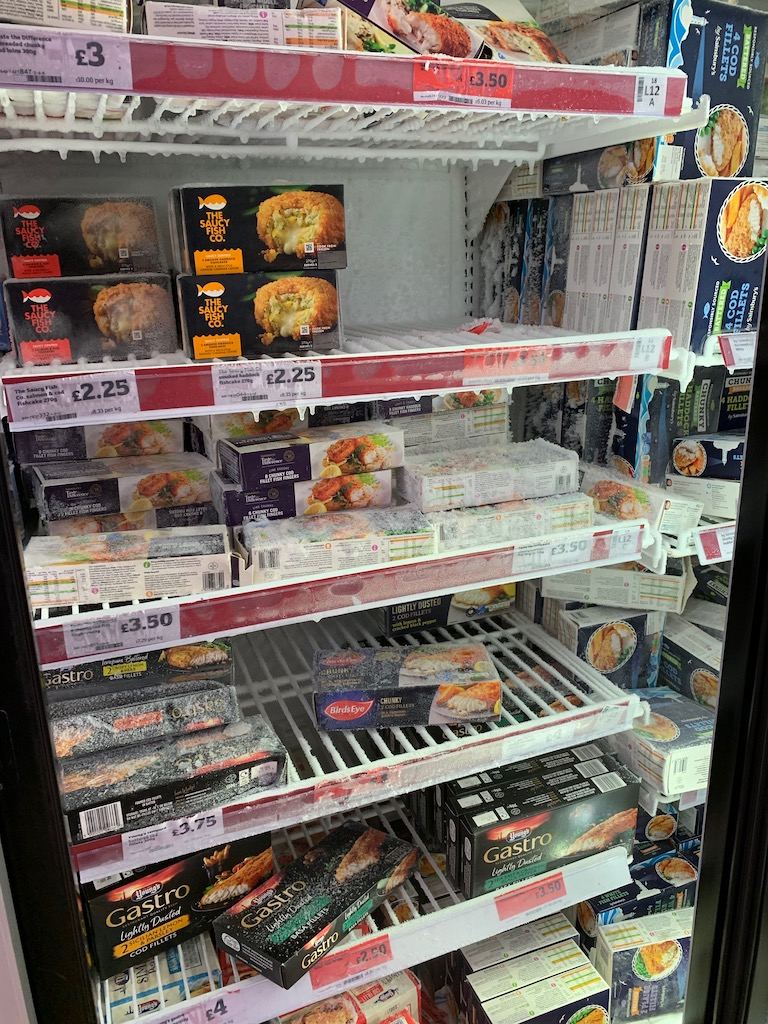
Frozen Foods were an issue in the store; this has been the case in a number of stores (not just Sainsbury's either) but the situation in Hedge End was more concerning given the refit and the fact that some freezer units were broken and not working correctly.
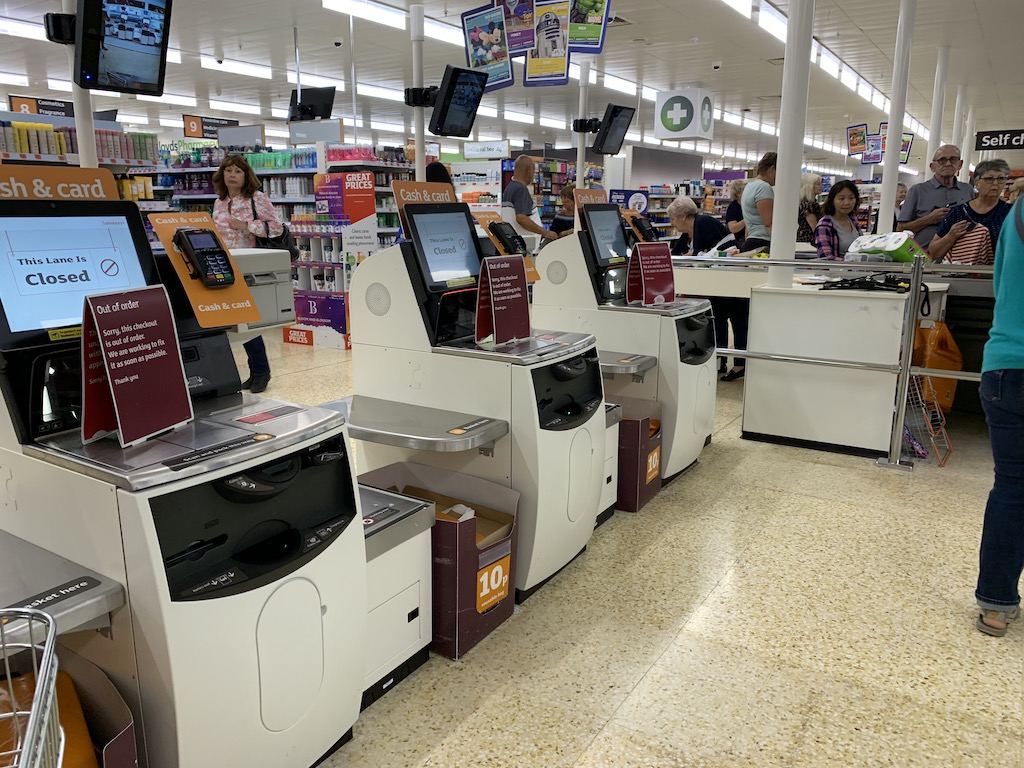
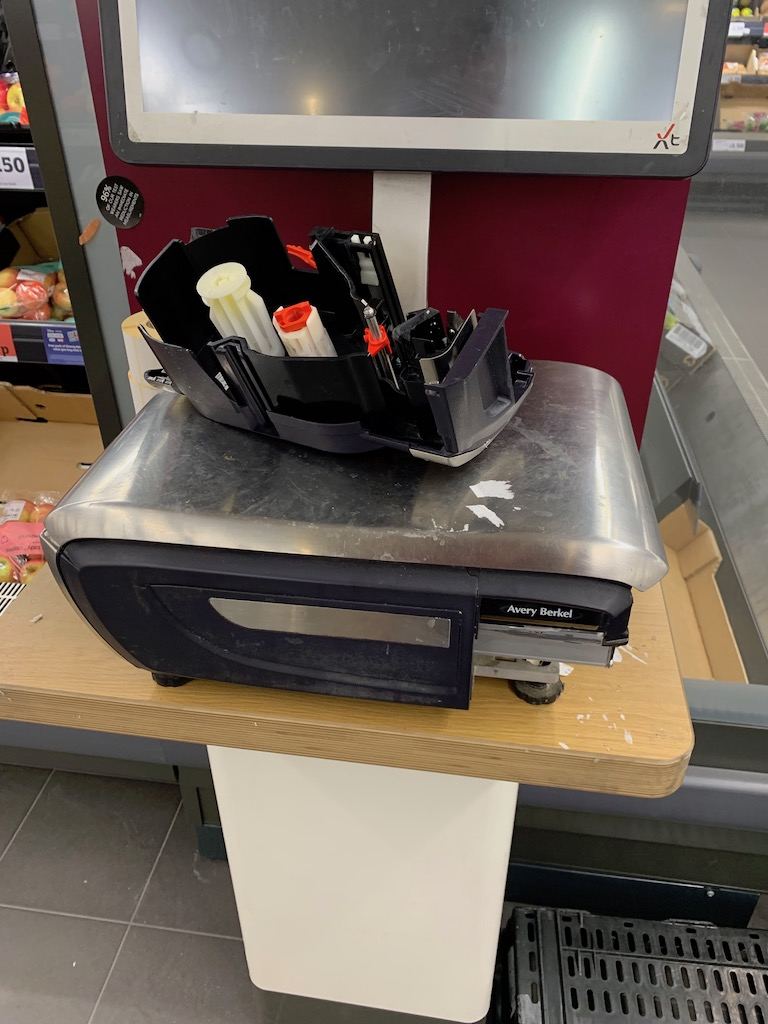
Self-checkouts were also a concern; this can happen at any other store admittedly but given the new refit, live in-store. It was a real concern that so many were out of action.
Weighing scales were broken too; not ideal.
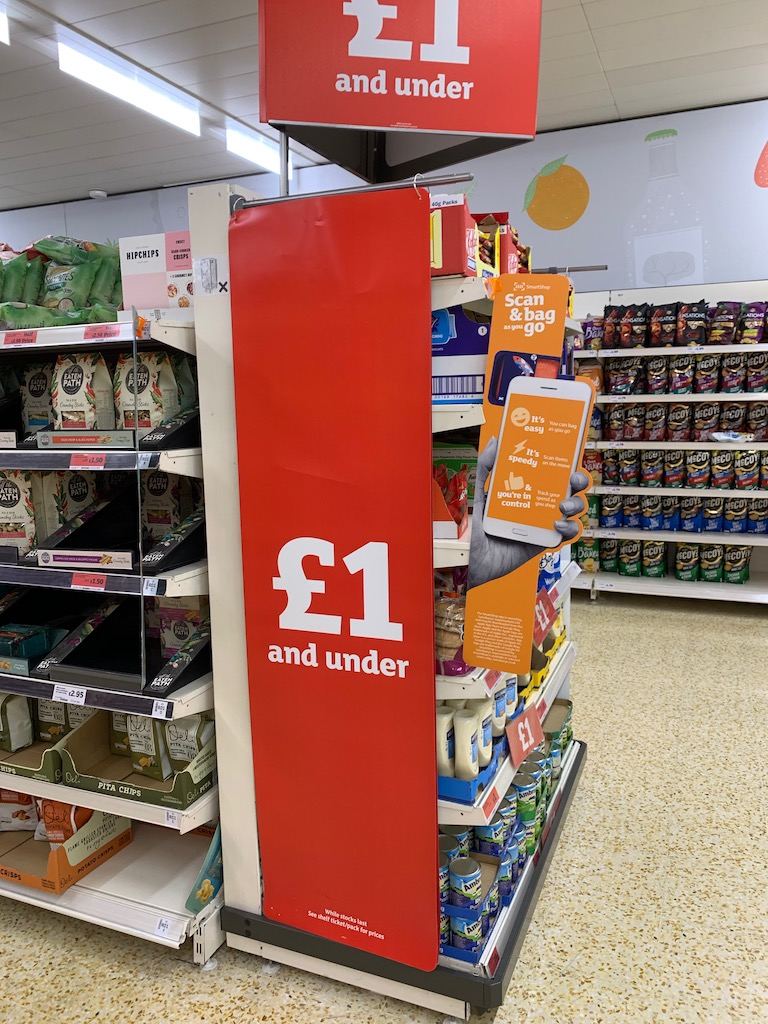
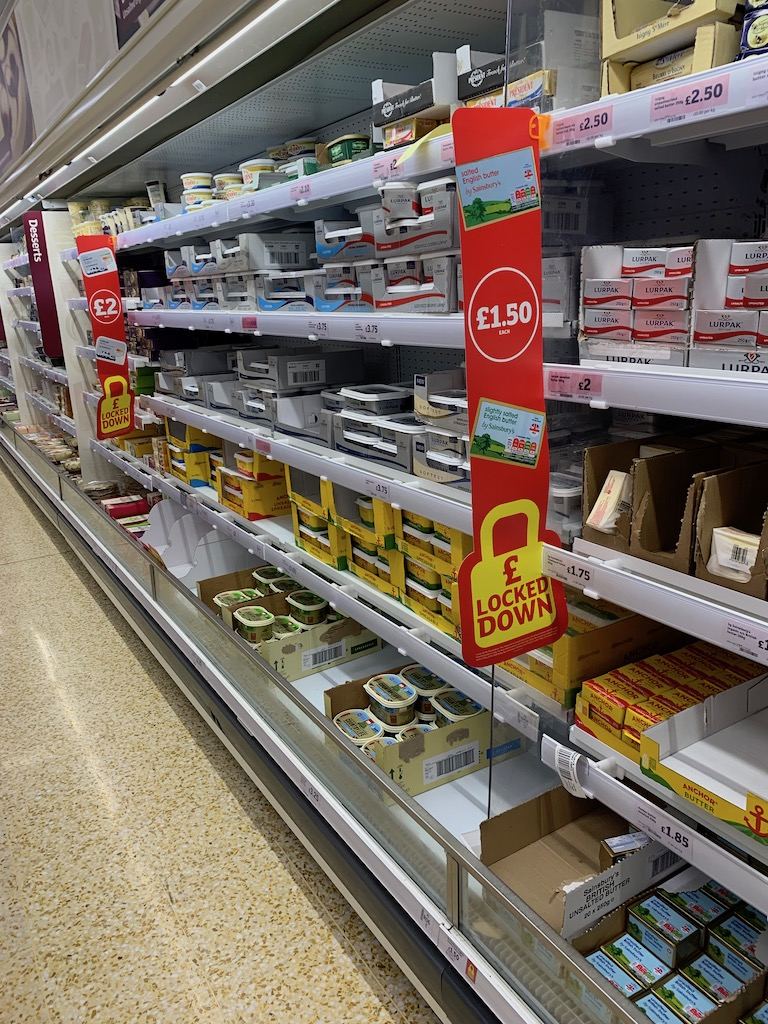
Value perception must be strengthening in Sainsbury's as their efforts have been notable, lots of work around the store, ends and seasonal space has seen stronger value cues.
However there was a time where ends wouldn't be price based, Sainsbury's didn't need to do that any more, ends would be mission-based and not price-focused.
However, this has changed and Sainsbury's have had to get into this space around value and in particular, promotions.
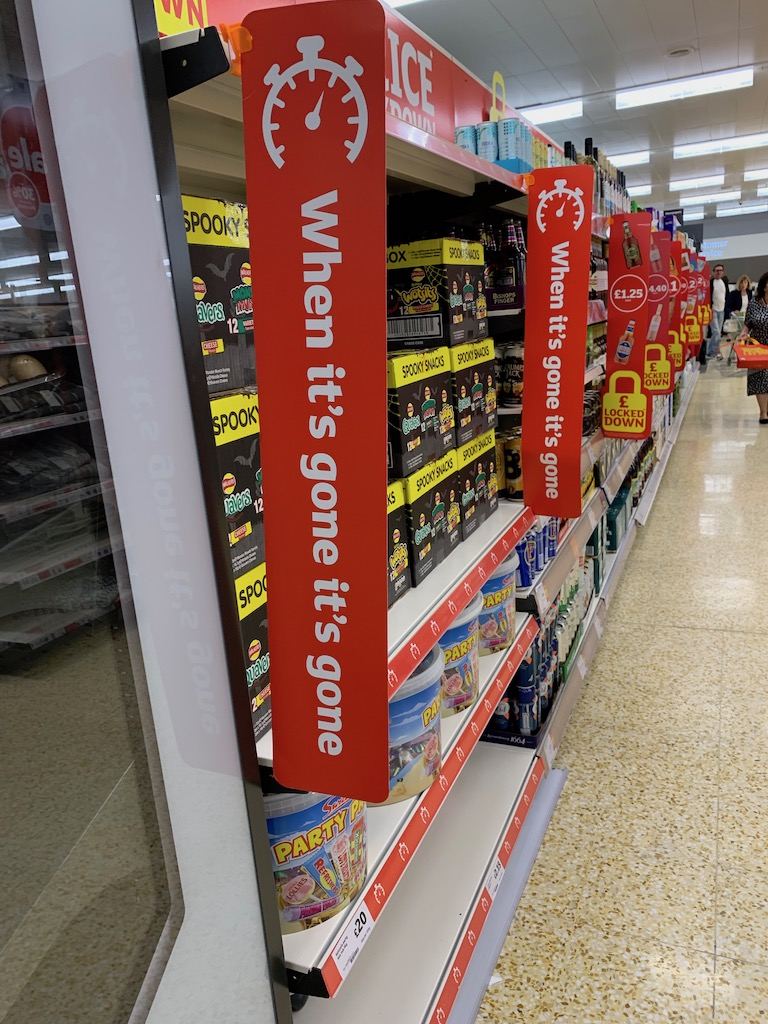
Promotions such as "when it's gone, it's gone"! Lidl has been pushing hard on this mechanic too, very hard and changing their promotional mechanics to accommodate more special buys and pushing heavily on this rotating nature of product and deal.
Sainsbury's dropped in a bay of WIGIG lines for their value/price lockdown aisle (first time they have ever done a value seasonal event), these lines are Halloween focused but it's good to see them flexing their model for larger packs - something that Tesco (for example) haven't been afraid to do.
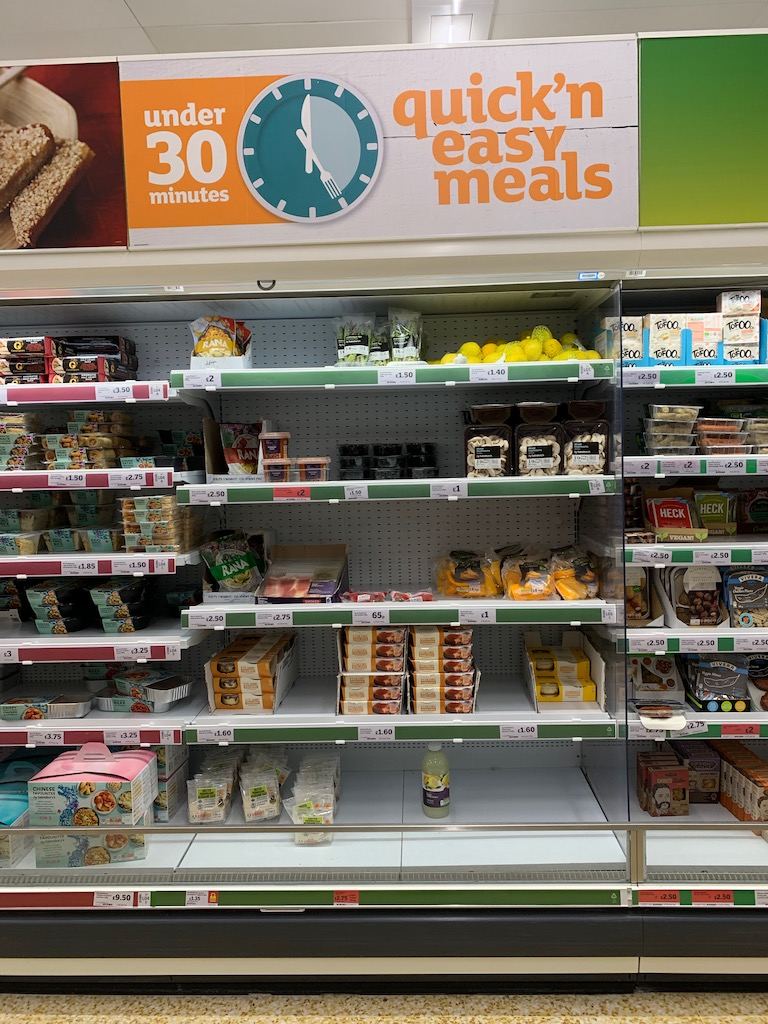
In aisle work such as the "quick and easy meals" is something that can benefit but the availability of the product wasn't really available..... Equally, there wasn't a lot of comms around what the customer should aim to make.
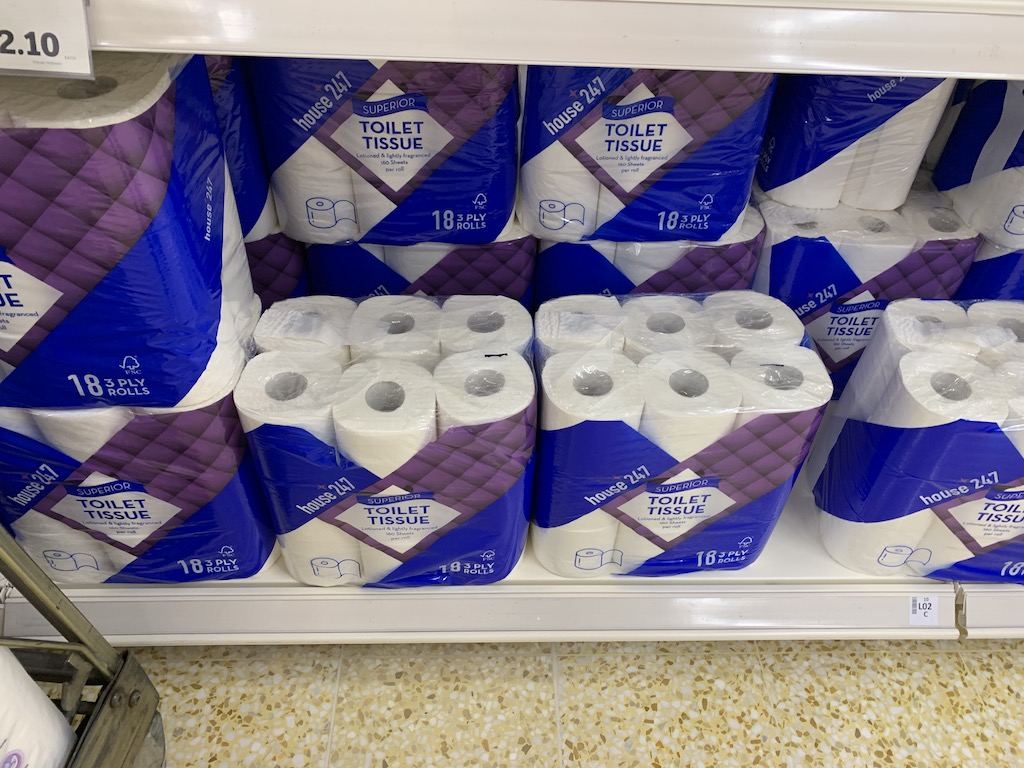
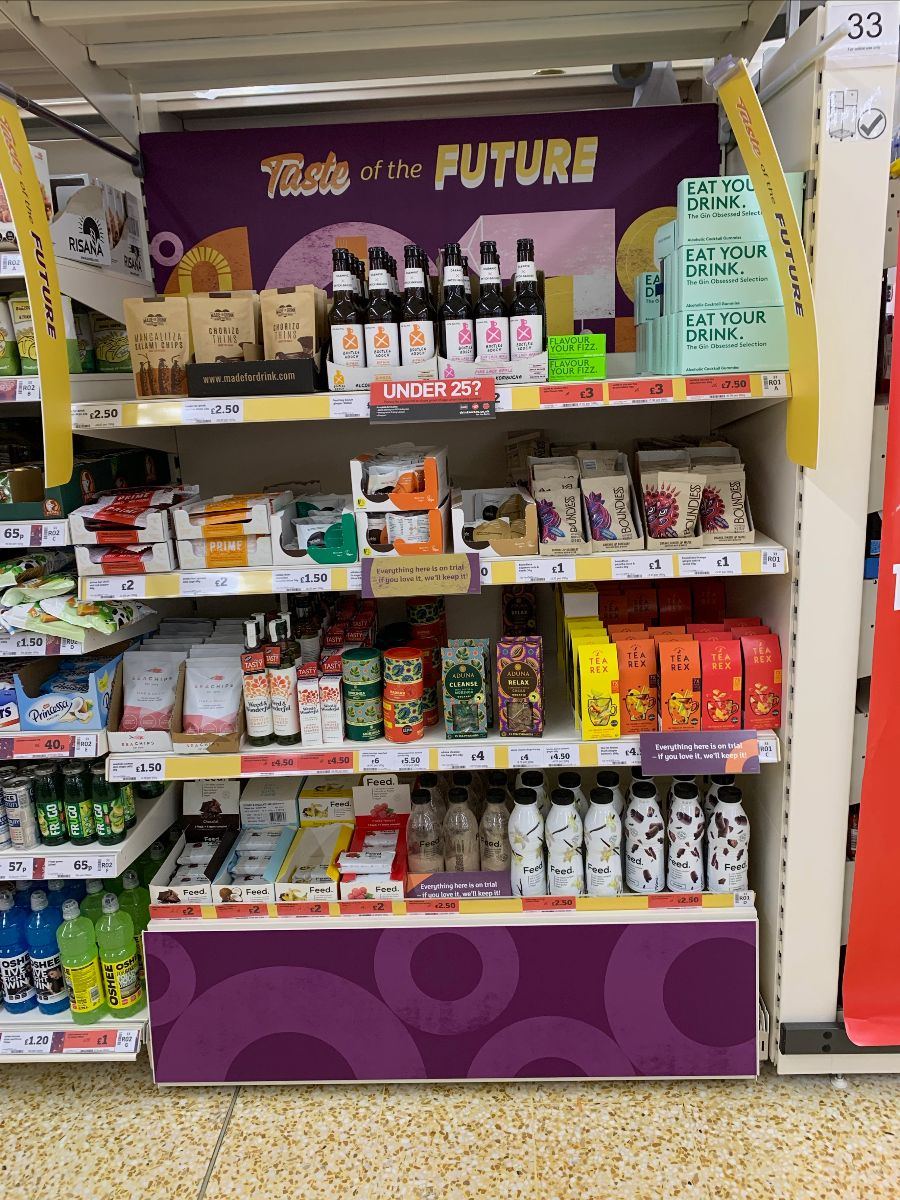
The own-label value tier was heavily trailed on here and the slide decks we'll go through later this week showcase the value tier changes that they're planning.
Whilst they counter that it isn't Tesco, rather a strategy they were planning (sure)..... But nevertheless it's better for customers with lower prices.
However, how the 'bookending' of that strategy with the future brands remains up in the air, can enough sales be derived from premium and future brands to offset any switching downwards?
Although Sainsbury's should be applauded at least for the 'winning together' element of the strategy, IE if they get more customers in for a fuller shop by losing some margin in key categories then fair enough.
Similar to the Tesco farm brands strategy ironically.
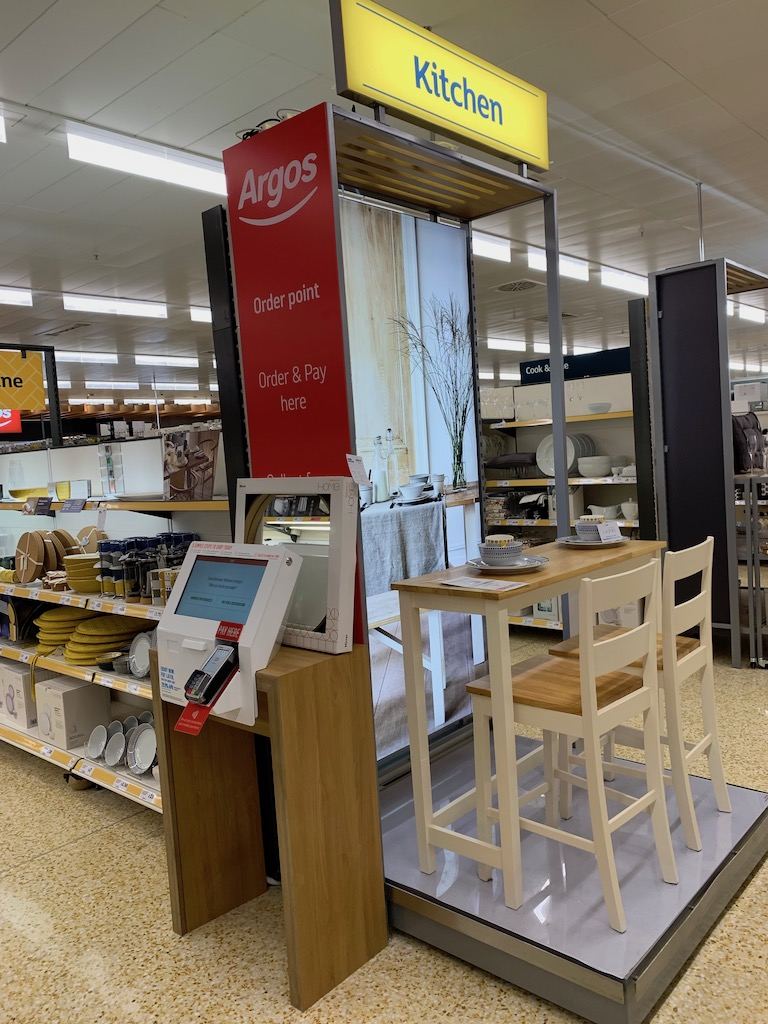
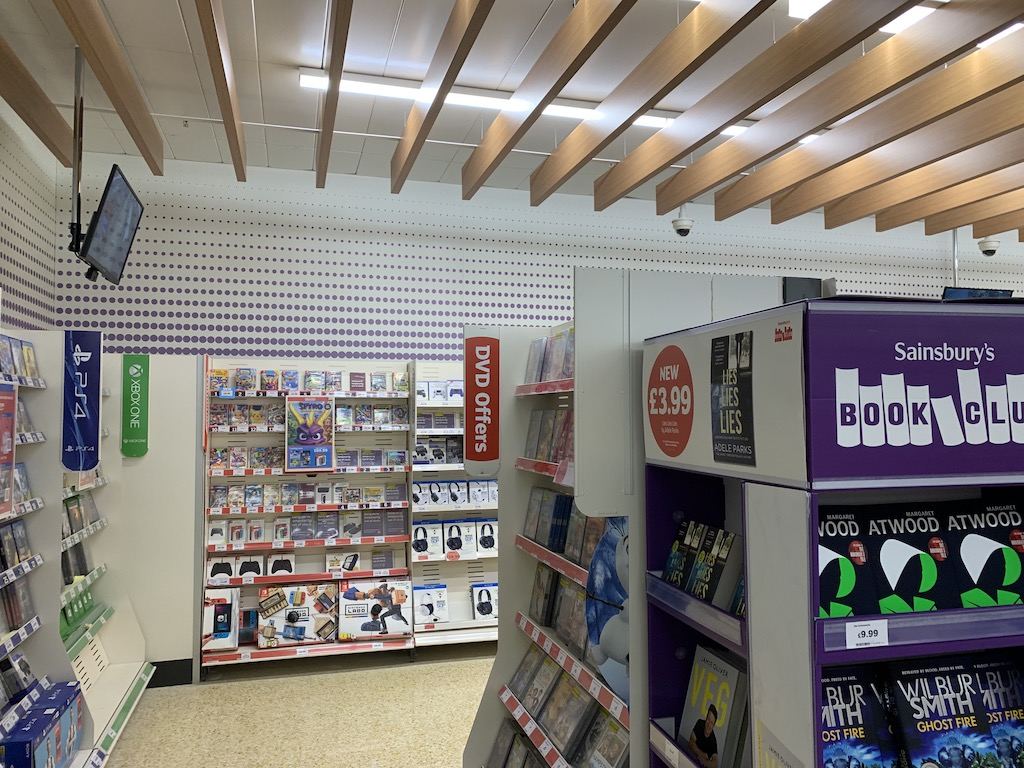
The non-food piece is interesting in-store, Selly Oak was a similar layout albeit featured more floor space (or so it felt).
There is still a confusion between Argos and Sainsbury's in terms of the non-food labels, which would the customer prefer?
The ends were notable in terms of showcasing the product and this worked well, although the digital order points (spotted around the store) were out of action in some cases. Disappointing.
The order points around the store then made the need for a sizeable Argos implant questionable.
The tech area is confused, especially with more moving online (this space is greatly reduced versus say 5 years ago e.g.) but 'tech' signage with books below made me happy.
The wider gaming area is an issue in other stores, there are a number of examples of stores with Argos being confused around how they should trade computer games.
One store had signs up saying 'buy from Argos' (despite the aisle still having empty boxes and the display) with other stores having their offering but prices differing on controllers and availability of games.
One to sort out and resolve in the future it seems, especially as the refits roll out, but they are not entire refits everywhere. Rather modular and some will receive an updated look and feel but the days of big refits for little payback are over.
More to come on Sainsbury's but it looks like they've got themselves together but their fuel promotion days, whilst less than competitors were compressed in a tight timeframe, making those comparatives next year harder........
Interested in our new image platform?
From the Grocery Insight newsletter archive, first sent to subscribers on 1 October 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.