Christmas 2017 - Sainsbury's - A re-send
9 January 2019
Did you enjoy this email? Join our service

I'd like some help with Events / Images / Insight....
We have a 'huge' Christmas report available soon
Express Checkout - Sainsbury's:
This email below was sent to you all last January, ahead of the Sainsbury's results at the time, post Christmas 2017.
The main question having re-read the note is that bar the obvious changes (IE not as many Wines deals, Turkey fixture not necessarily as full...) has anything else materially changed?
In a year - I don't think it has, in some cases things have worsened and stores have been poor in many respects which immediately sees the customer come to expect that - factoring that in to their purchasing decisions....
In terms of year on year; the dial didn't really move and there wasn't a great deal of innovation around. Some stores had challenges around availability, particularly on key lines and the general feel of the chain was disappointing really.
More competitive on Produce perhaps, but the premium range struggled to get distinction and we'll have a fuller run down on the service tomorrow, especially around execution elements.
Sainsbury's was a place that (certainly back in my day) was a retailer where you went to trade up, treat oneself and "taste the difference" stood out as a real premium tier that meant something. Sainsbury's used to perform better than the market at Christmas, such was their popularity and 'pull'.
Kantar doesn't look good for them (or Waitrose for that matter) admittedly the JS number will not include Argos, but given the Christmas strength in Toys (versus a click/collect 'less' Tesco too) there should be some positive news in that regard.
Crucially; Asda showed the strongest growth in premium own label this Christmas via Kantar....
It's a funny old world.
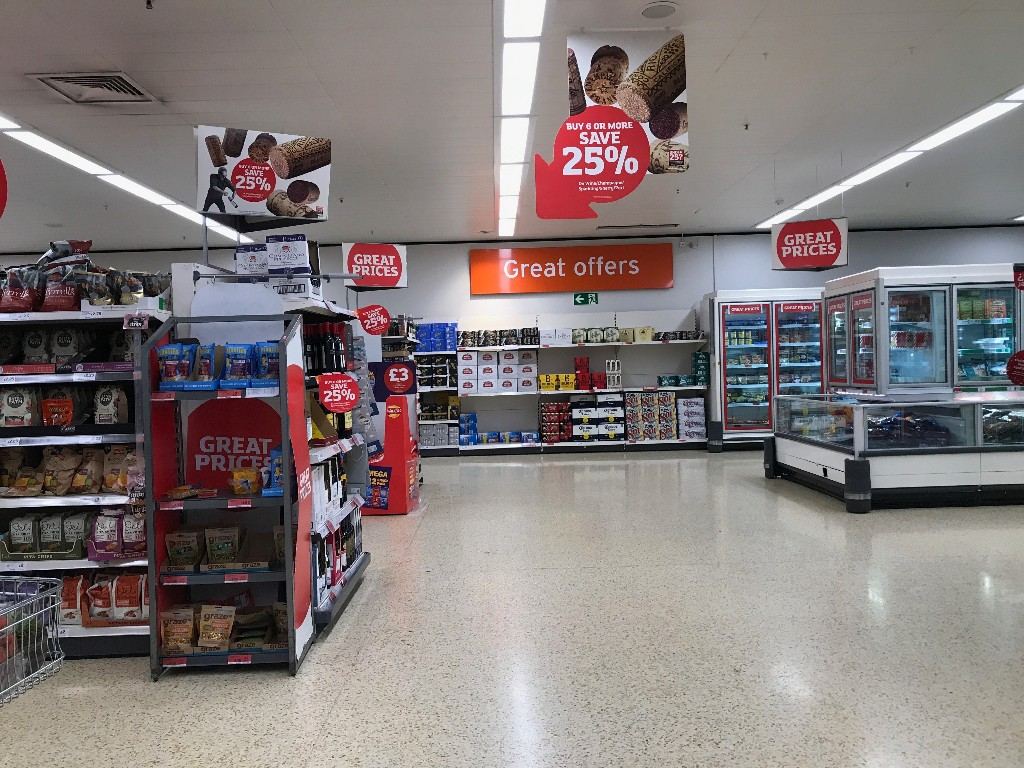
This email was originally written and sent in January 2018; post the 2017 Christmas trading period. What has changed in a year? Not a great deal, truth be told.......
So we know Sainsbury's used to report very strongly for Christmas, it was always one of their 'golden times', with growth in the Taste the Difference and their 'higher quality' own label performing well.
However the market has come around to offering all that anyway, especially discounters who are renowned for their own label quality and increasingly, pushing on the premium tier...
Which added to Aldi/Lidl's rapid expansion, including in to heartlands occupied by Sainsbury's means that they're under threat.
Sainsbury's of course have responded to this around price, working hard on regular prices and moving their prices lower, I think that's appreciated by customers but the lack of multibuys at Christmas when a retailer is chasing volumes, simply nullifies the offer.
Secondly, we have seen a marked step down in store standards in Sainsbury's, on this very service and this has continued with top stocking also variable in terms of its implementation.
For the good stores, it works well. For the bad stores, then it's another issue and well, the impact is then taken out to the shop floor for all customer to see.
For a retailer that traded so proudly on shop standards, consistently for so many years. Does the relative 'stable' (but by no means record low) prices stack up as a price to pay for the poorer store standards?
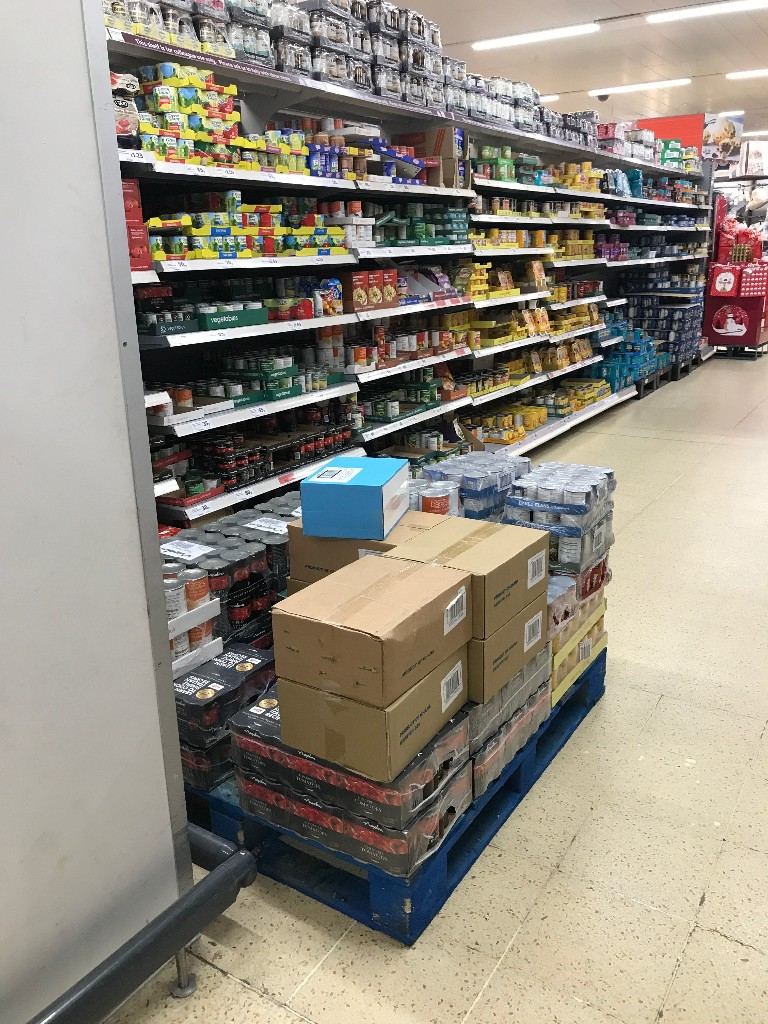
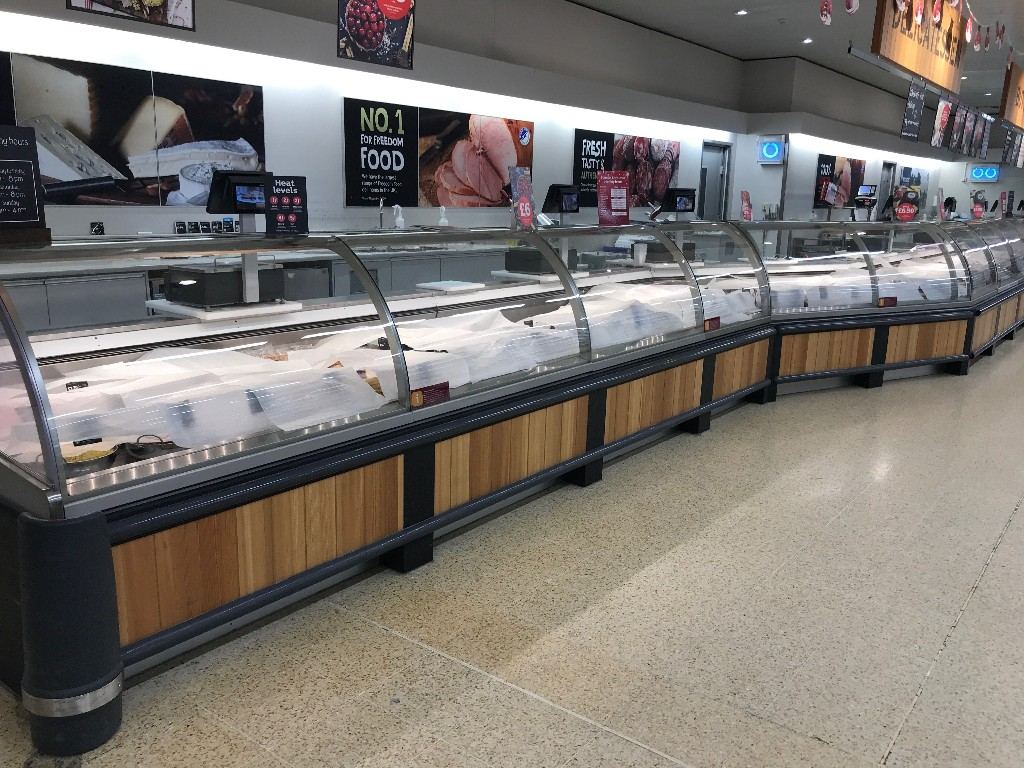
Three examples here, the evening replenishment of ambient products can lead to this - pallet boards and more aisle congestion which sorely impacts the customer flow around the store.
The Deli was closed down with a load of paper placed on top, akin to some art installation. Not great at all for a retailer priding itself on Fresh Foods...
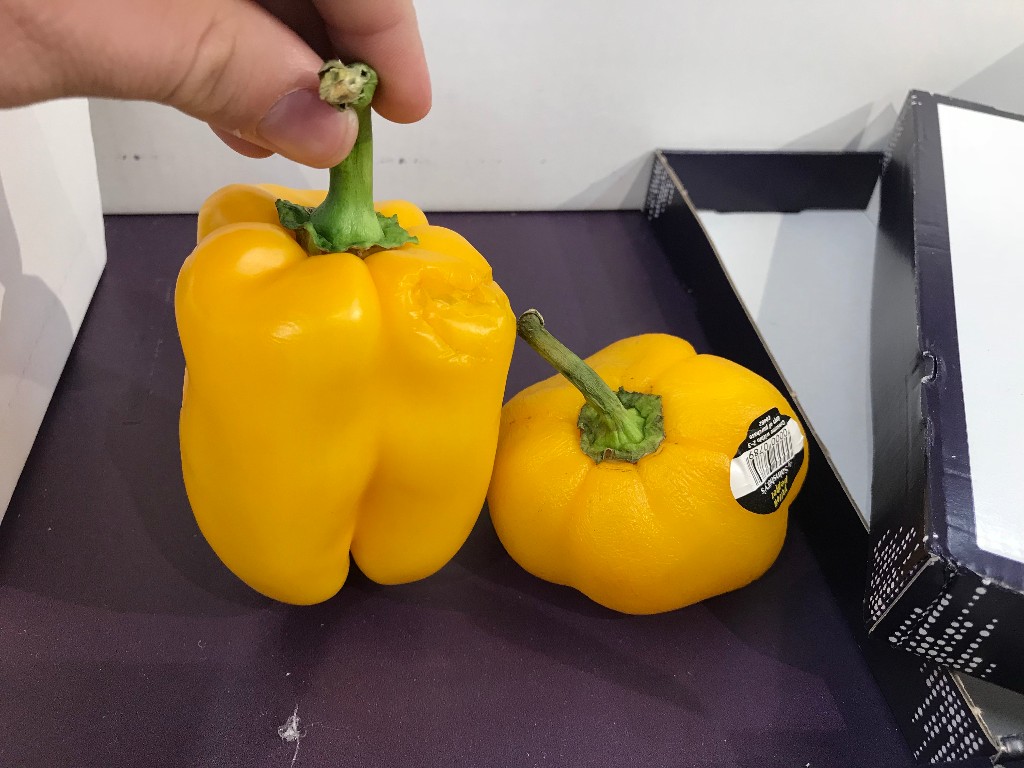
Thirdly, step down in quality? The question isn't just how are these Peppers still on sale (given their poor quality), but how are these two products equivalent? How did they pass the grading within the supply chain?
Cost cuts are one thing, savings targets understandable but there can not be a step down in quality of Produce. An isolated incident perhaps but one that isn't great for customers.
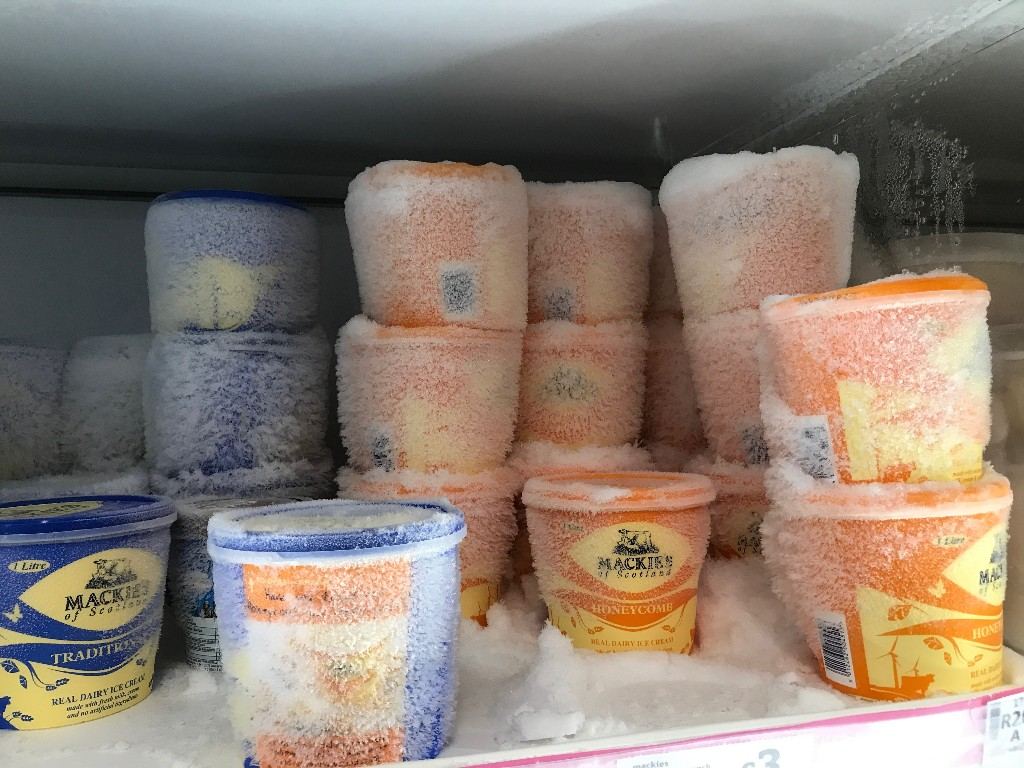
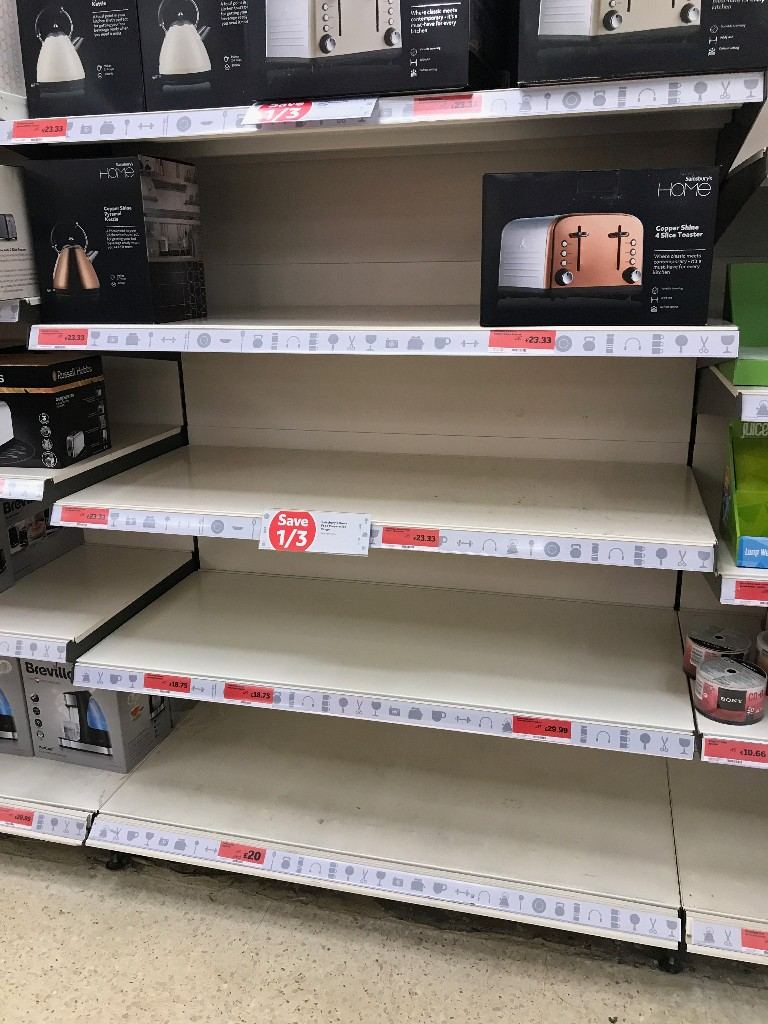
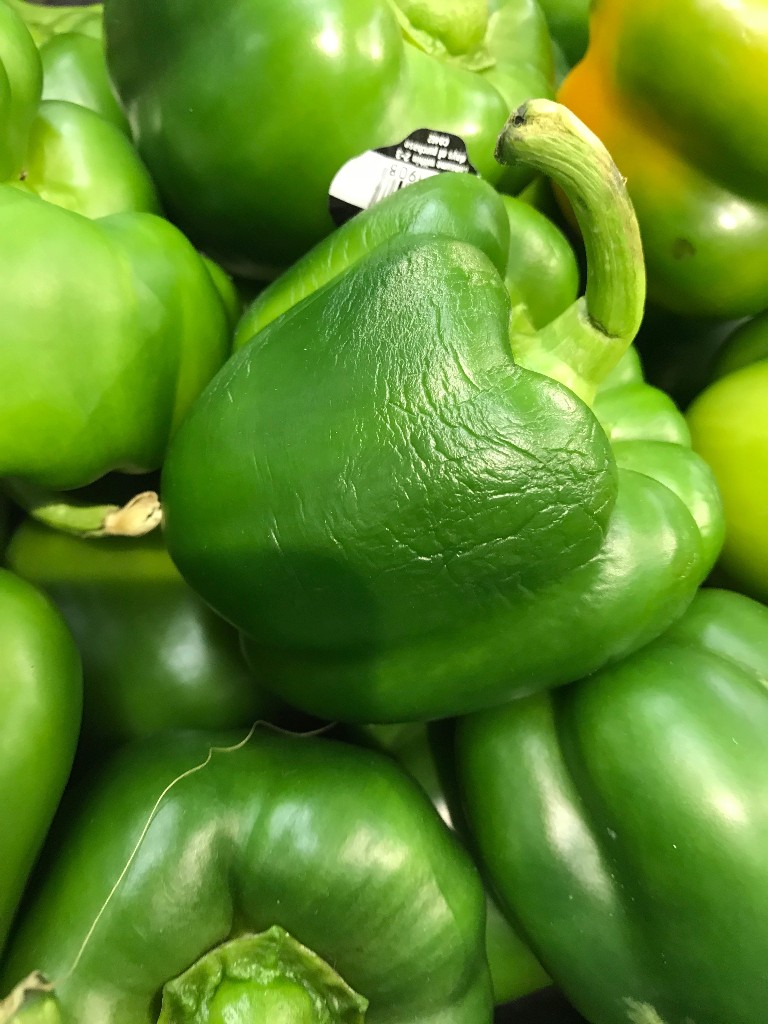
More examples of standards based challenges in the period, in the run up to Christmas, customers want to be romanticised and kept loyal as we all run up to the 'big day'.
However with some stores, it was challenging and their efforts were more likely to send them in to the arms of another retailer.
Any cost saving programme is understandable, especially in this climate and especially when you've acquired a non food chain like Argos at the wrong time (slowdown in discretionary spending and non food challenges, plus Brexit).
Therefore the impact to customers has to be minimised, they won't queue up at checkouts because the hours have been cut, whilst Sainsbury's pocket more cash for the cost savings target.
It's hard work to save money from the wider operation, especially for Sainsbury's who have banked numerous savings from their sterling work in the past. They've almost 'run out of road' before really starting to cut in to things that will ultimately lead to customer impact.
Not necessarily top stocking, not great for the in store experience but unlikely to send any customers away. Gaps on the shelves after several years of strong standards?
That will impact. We see three examples, further evidence of poor focus on Pepper / Produce quality, an Icy scene in the Freezers and 'Sale' stock very popular - gaps aplenty.
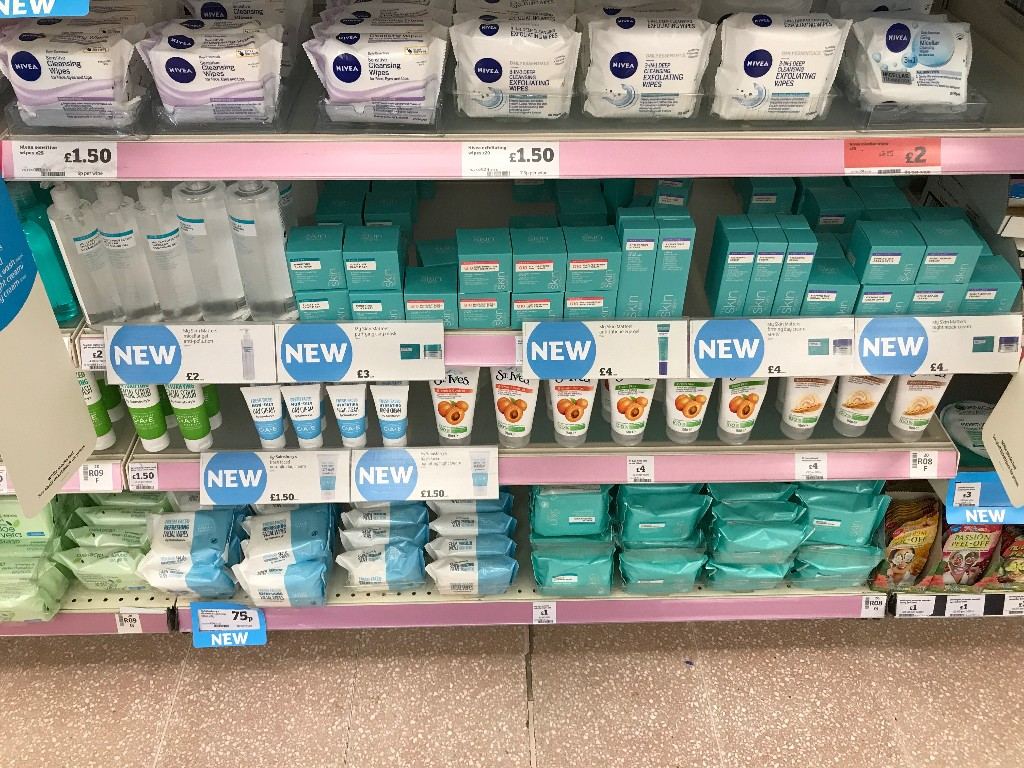
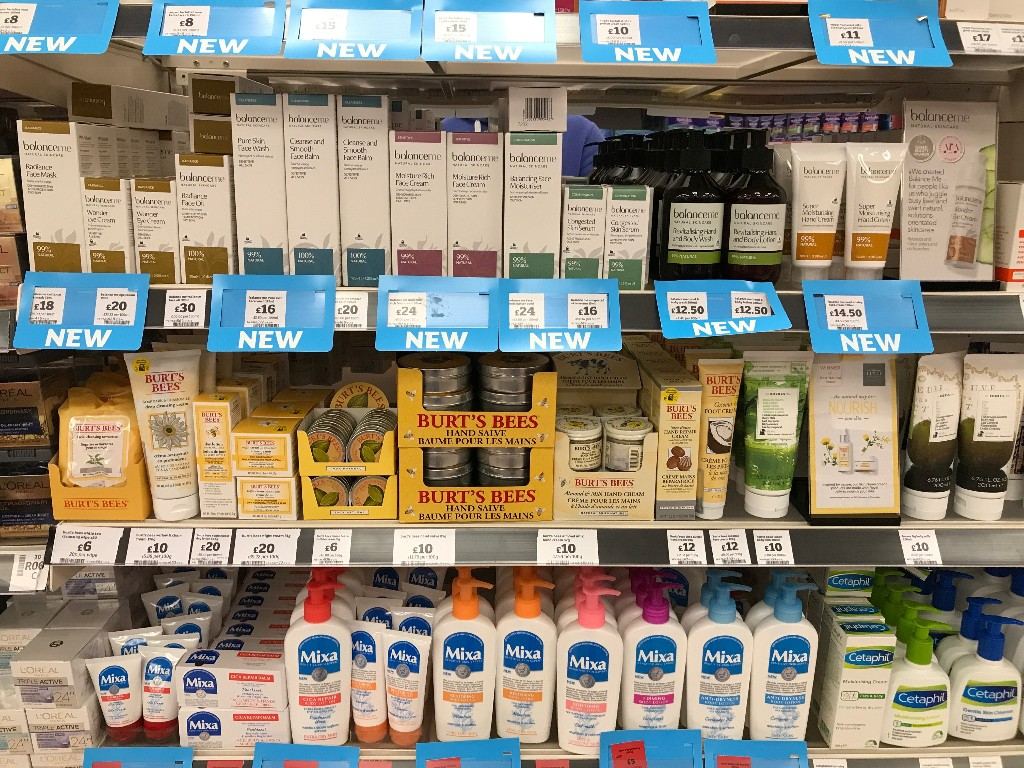
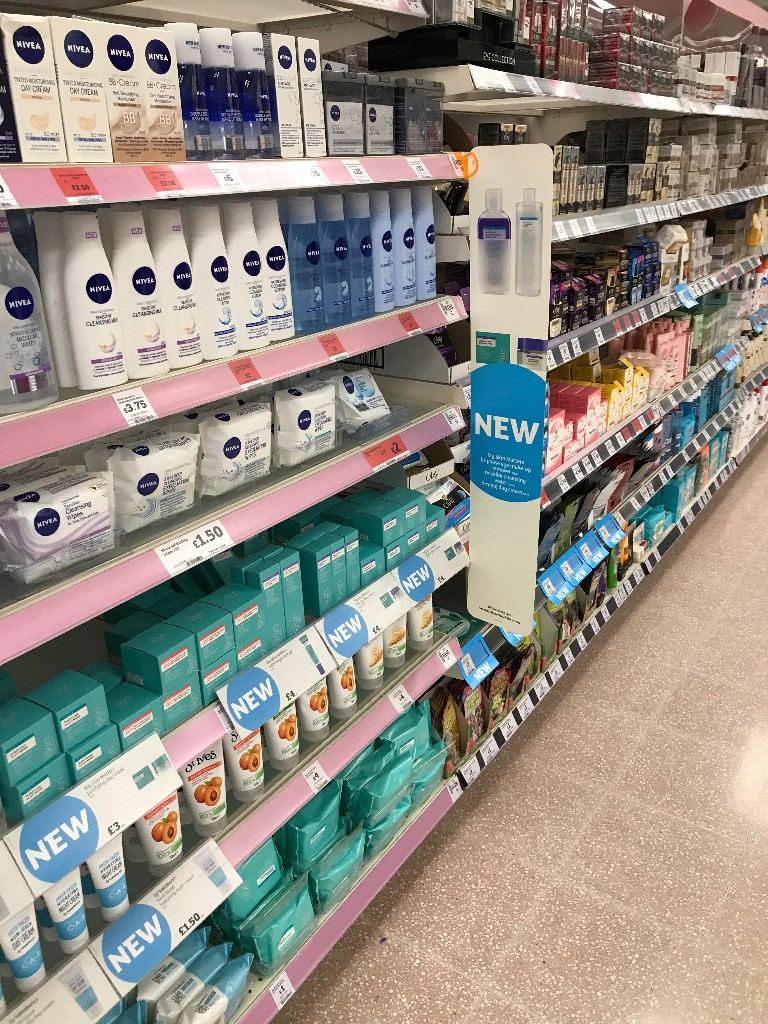
There were significant amounts of 'new' product dropped in pre Christmas, some of which formed part of category reviews, whereas others seemed to be the odd line or two, often at a higher price (Oils e.g.) to drive spend upwards and provide a quality alternative.
There has been a lot of focus on either developing sub brands, or licensing exclusive brands - like Godiva in Confectionery which does make sense.
But the core own label still has to stand for something and be 'loved' by customers I feel. Within Health/Beauty, there looked to be almost too much 'new' here for it to really resonate.
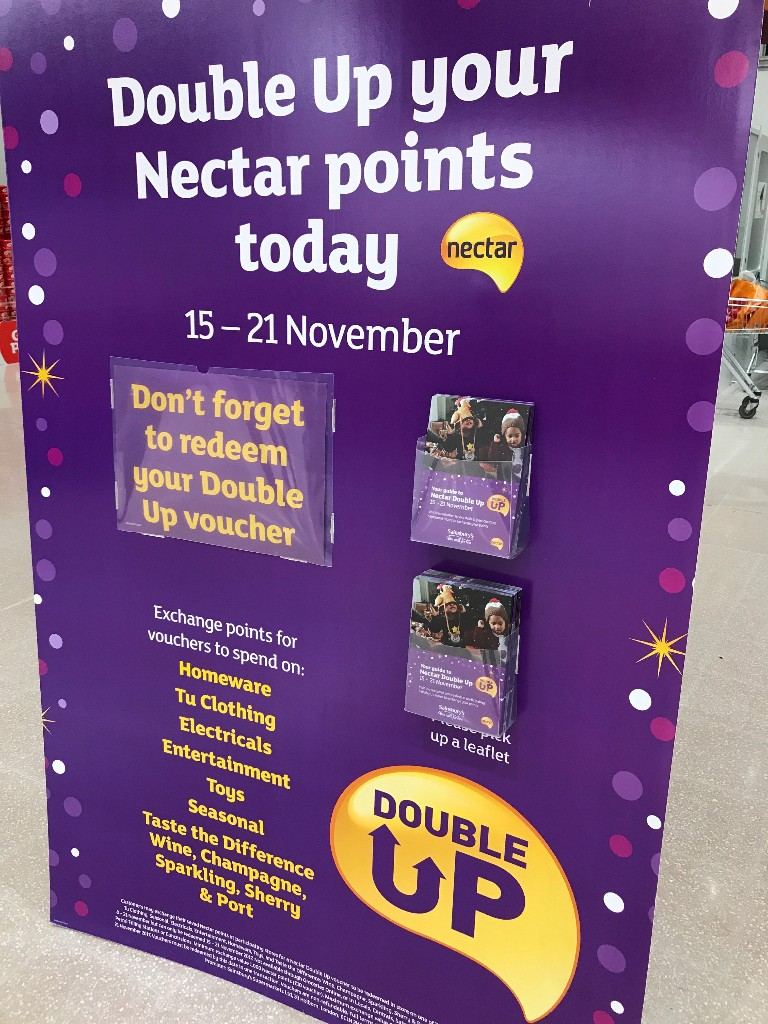
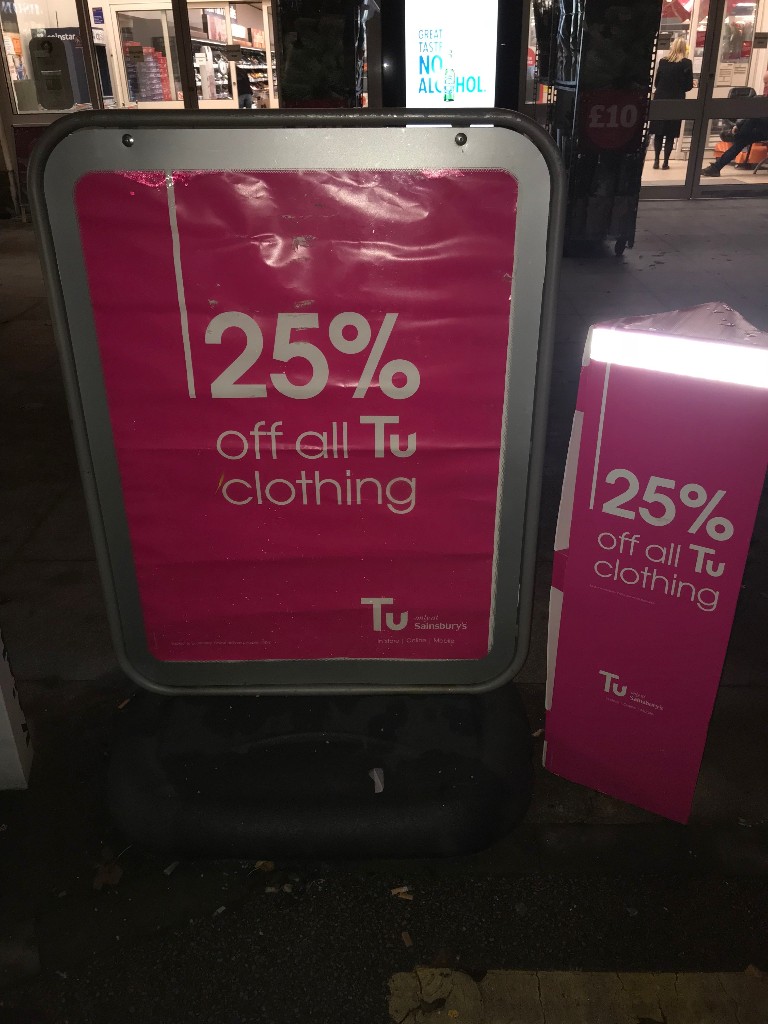
Within this trading period, Sainsbury's were certainly more aggressive on deals than they were in 2016.
Deals / lower prices on large bottles of Spirits (£15), 25% off 6 bottles of Wine that ran nearer Christmas but also more frequently than 2016, partly prompted by the efforts at Tesco.
25% off clothing also ran more frequently too, generally it's limited to within the 6 week holidays, around Easter and one again in the October half term.
But Sainsbury's then had two further periods of 25% off clothing, including a 4 day special to try and boost sales, but also reacting to events elsewhere - Tesco e.g. who ran more deals on Clothing.
Also within the cycle was the ever popular double up event that allows customers to spend their points on non food / premium Wines / Champagne and receive double the redemption value for doing so.
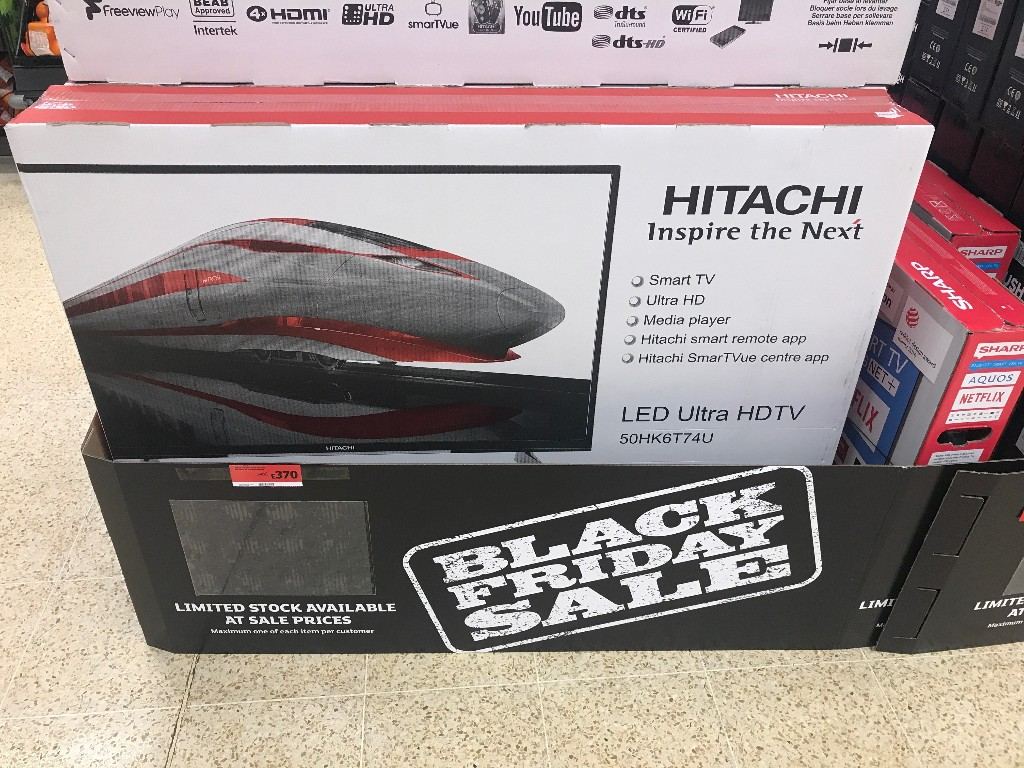
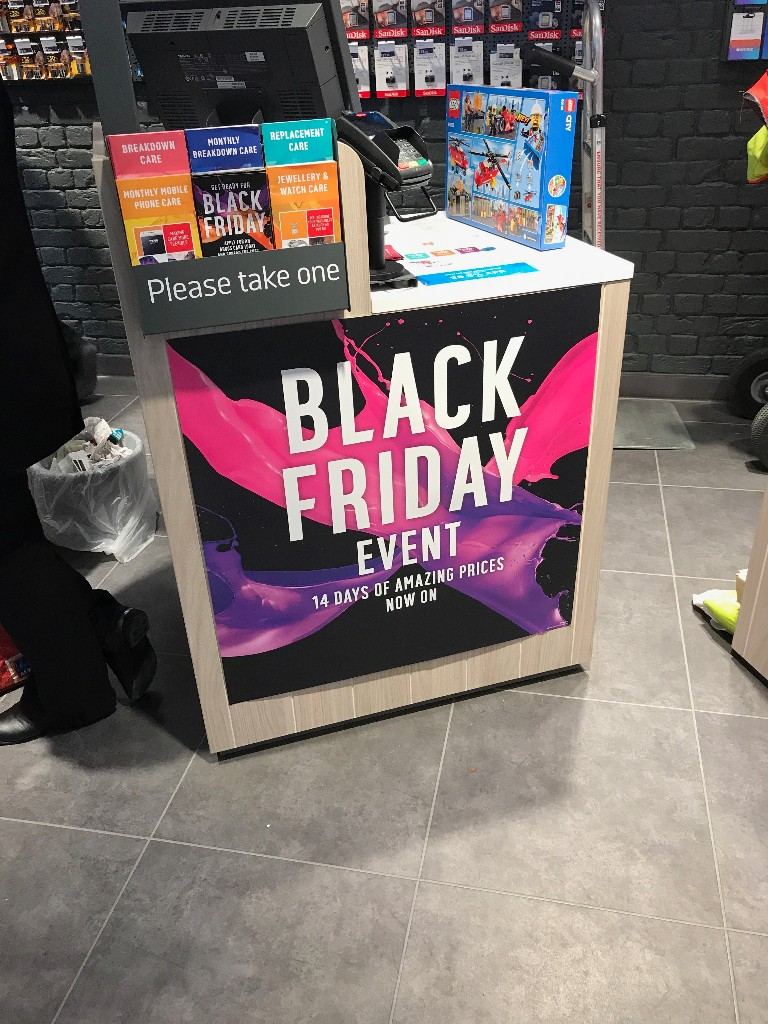
Similarly, Black Friday saw a strong package of deals at Argos, and also the core offer in Sainsbury's featured televisions alongside other electrical lines too.
A bit sales prevention squad perhaps on the television pallet, with the price on a standard label, meaning any impact was lost entirely.
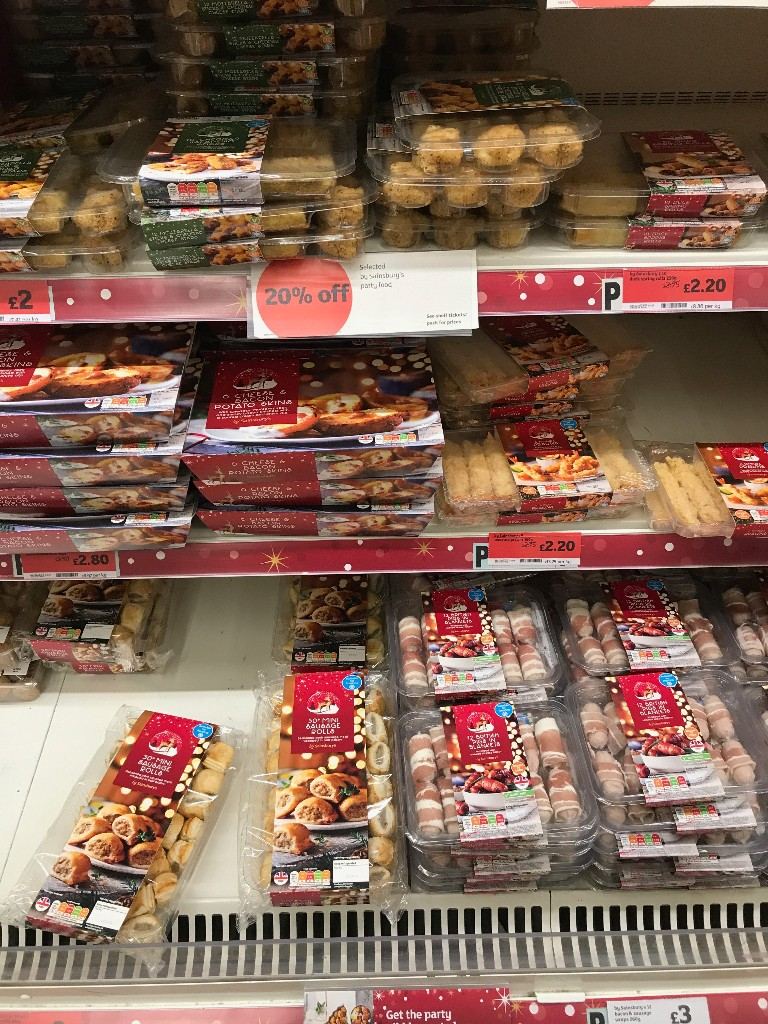
Party food is an area where I feel Sainsbury's do miss out a little without the multibuy, there is no incentive to stock up in the same way there is with a 3 for 2, or 4 for 3...
The wider reasoning from Sainsbury's I do understand, customers don't want 'more' than they need to benefit from a deal. But the emergence of two seperate periods of 20% price cuts in party food was interesting.
This didn't happen in 2016, so was it a response to the slow trade? Or part of the plan? I felt the range was respectable, premium does feel like it struggles for Sainsbury's here which is surprising....
It doesn't feel like it is 'special' enough given the strength of the core own label range.
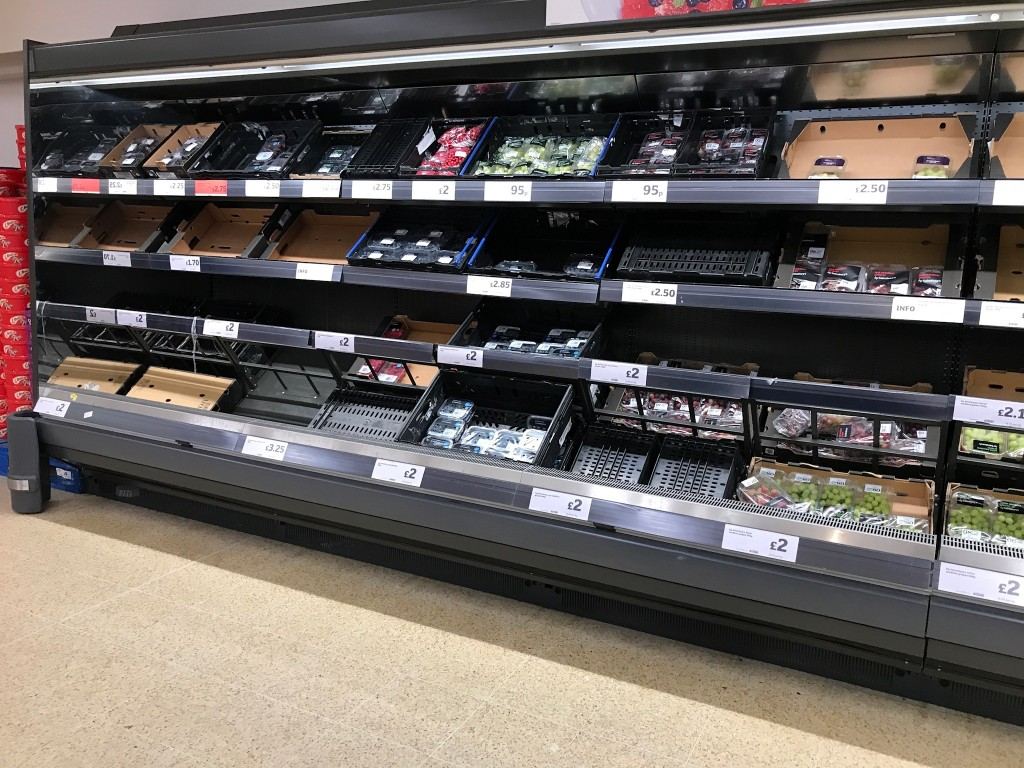
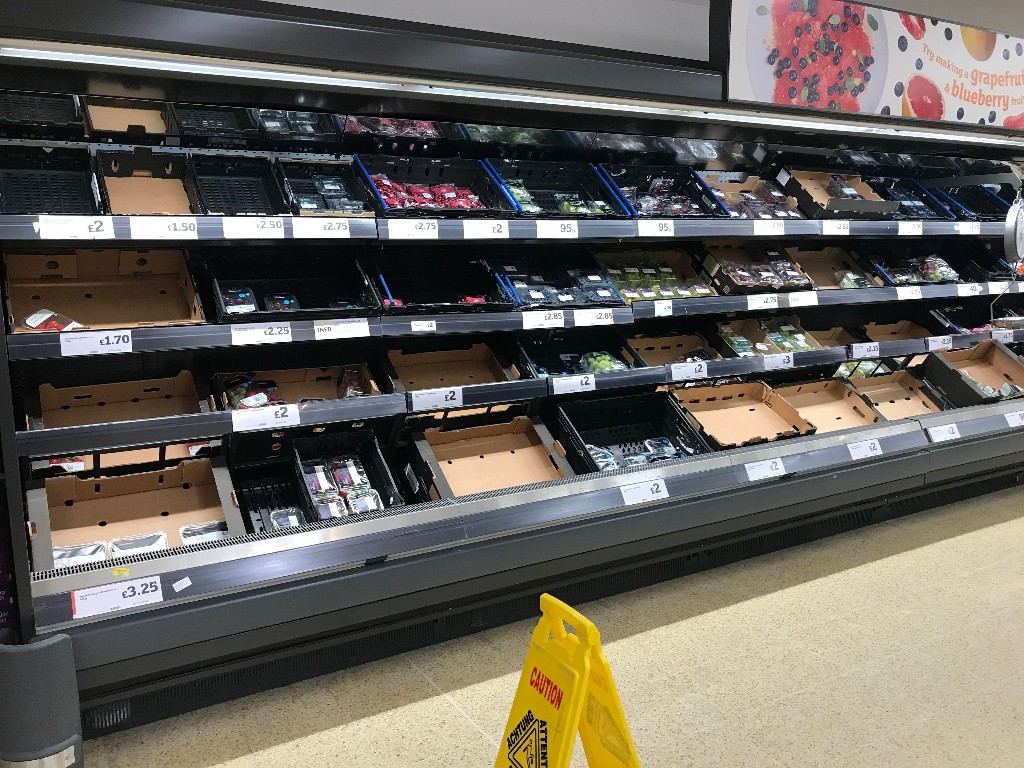
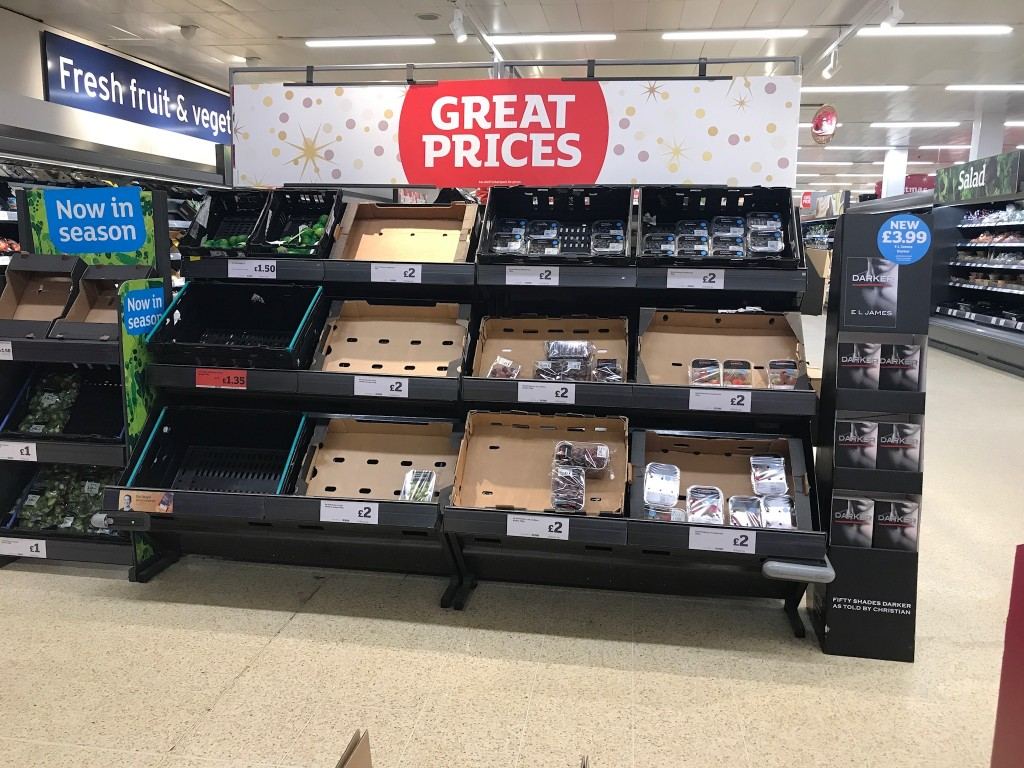
In the run up to Christmas, this store wasn't enticing anyone through the door with standards like this. 6pm on a Friday night and the Produce category was terrible.
Very disappointing and one wonders if the equilibrium between sales and waste is set correctly.
You cannot cost save your way to prosperity after all....
I felt own label was improved this year, it's not that JS have struggled with own label, or scored multiple own goals.
It's more that discounters reset the bar significantly for a customer, in terms of what they'll pay and what quality they expect. Plus then you have all other retailers then really pushing on own label, some from a low base given their former focus on brands.
It means that Sainsbury's, strong on own label anyway then have to be 'really good' to strengthen their proposition further. Their work on price has been effective on brands and own label, in some cases with the sub brands like Pastaio and Prism (dishwasher) coming through.
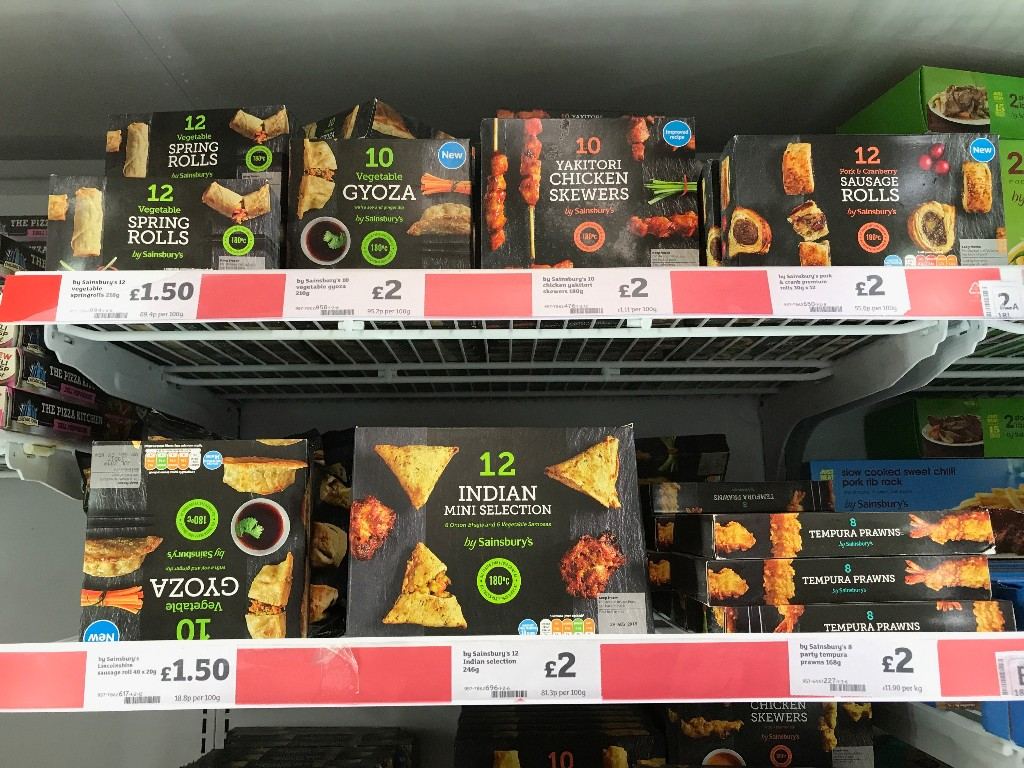
Frozen party food was greatly improved from 2016, a real step on with regard the packaging. Also cleverly adding new lines to capitalise on the seasonal trends is also good.
A Shloer own label equivalent for Christmas was clever, always a trade up on Shloer as it's non alcoholic but looks like Wine...
JS also changed / revamped their 'slow cook' range in Fresh in September, really well timed as customers start to think about digging the slow cooker out once again for heartier meals.
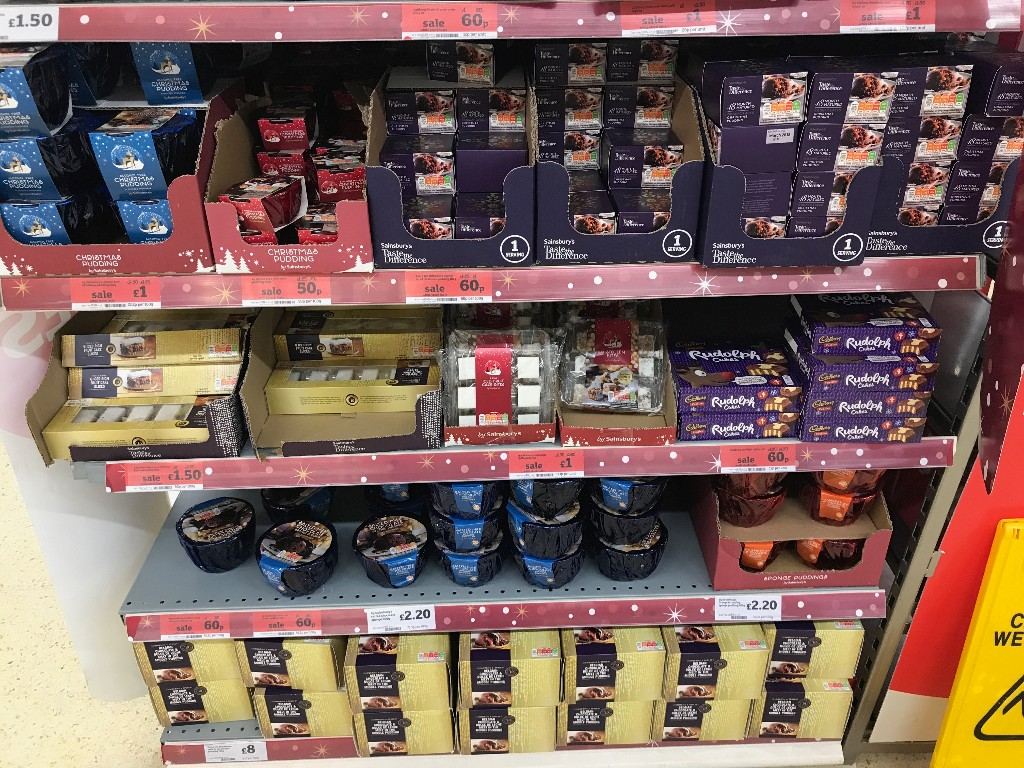
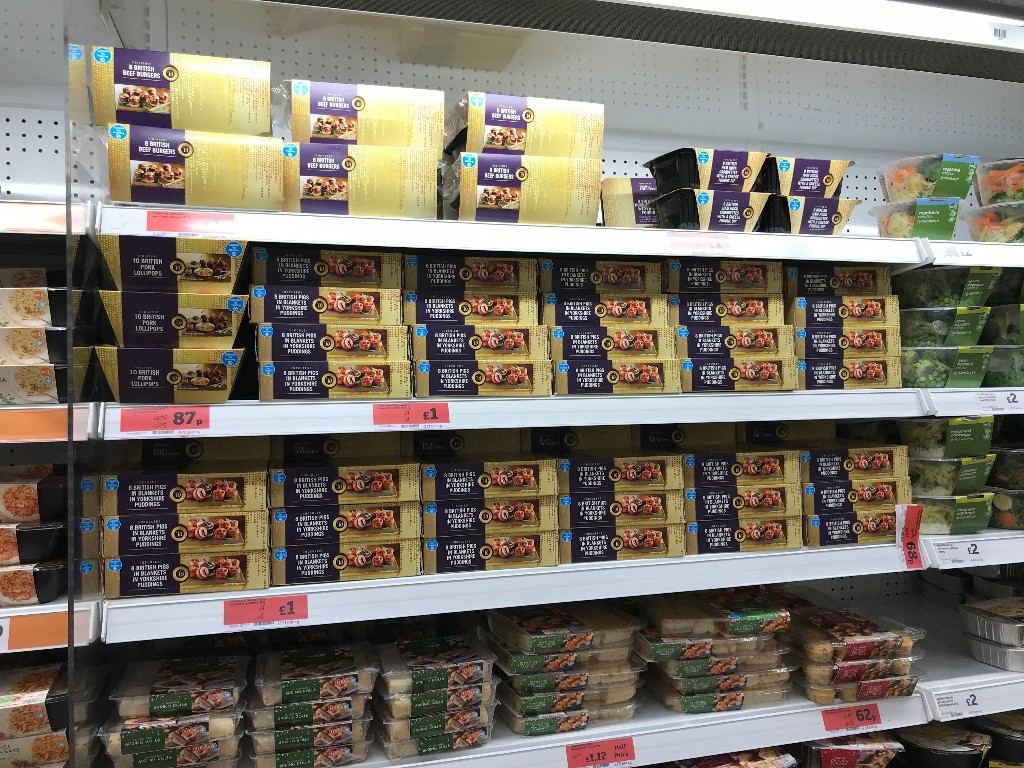
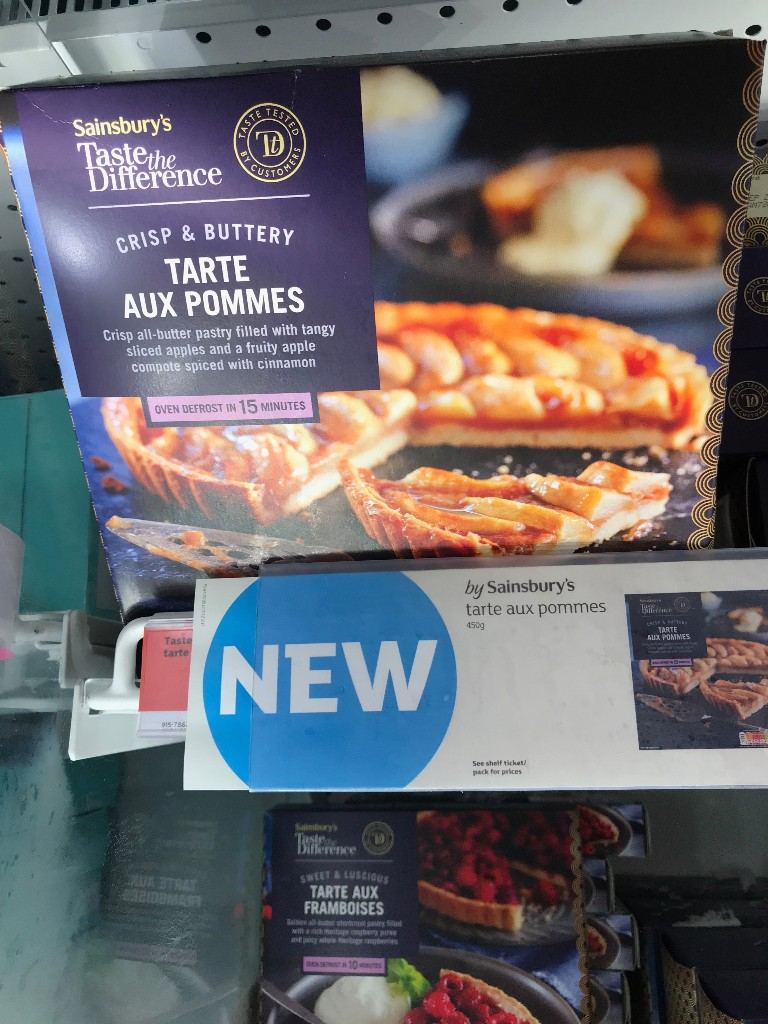
Taste the Difference is still a great brand, but is another one that is so well established, it needs to work very hard, just to stand still.
Especially in the noisy marketplace where discounters are so strong at Christmas, especially Aldi this year who were marvellous on Fresh Foods (premium) and were also lower in price than Sainsbury's.
Consider the revamp on Finest at Tesco (alongside all those awards) and Morrisons "The Best' looking like a genius move to revive that brand given the success it continues to achieve.
Even Asda, who struggle with premium are growing their Extra Special tier all the time too.
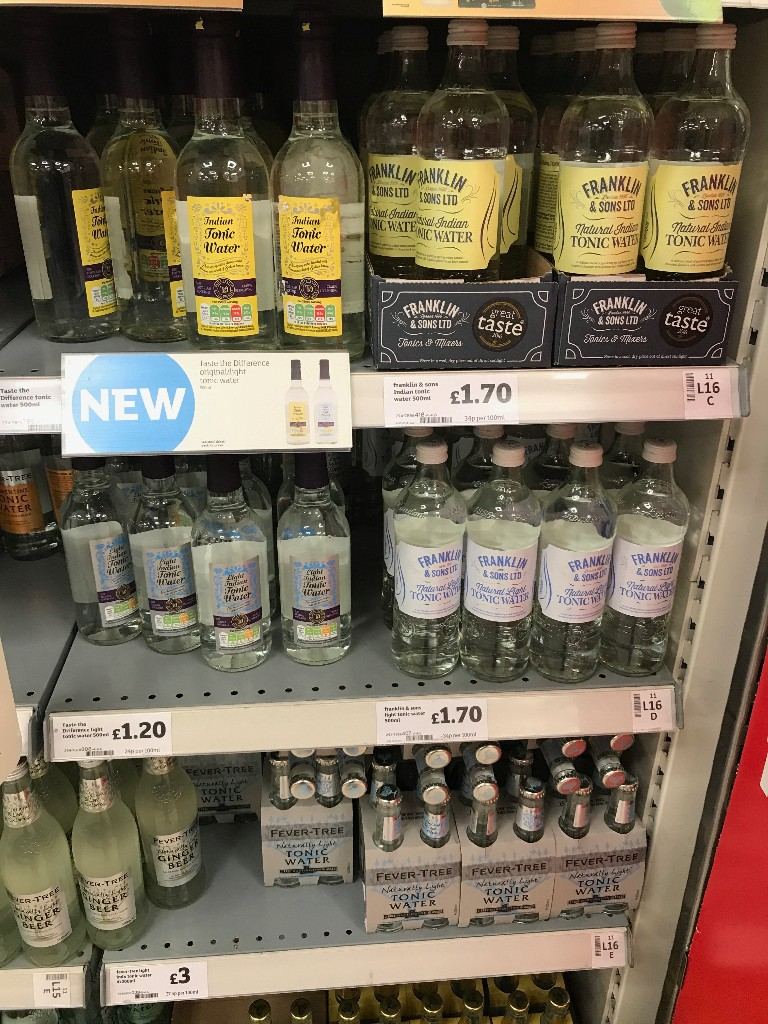
If we look at three images above, for some reason, there's now a lack of distinction for the 'famous' Purple packaging as JS chase down a 'gold' equivalent in Fresh(?)
But then have the classic Purple in Frozen, before a bizarre Bakery range of both Gold and Purple representing Taste the Difference.
Confusion reigns supreme here. Every other retailer range is distinctive and stands apart, Sainsbury's are watering down their own premium range with confused branding at the shelf edge.
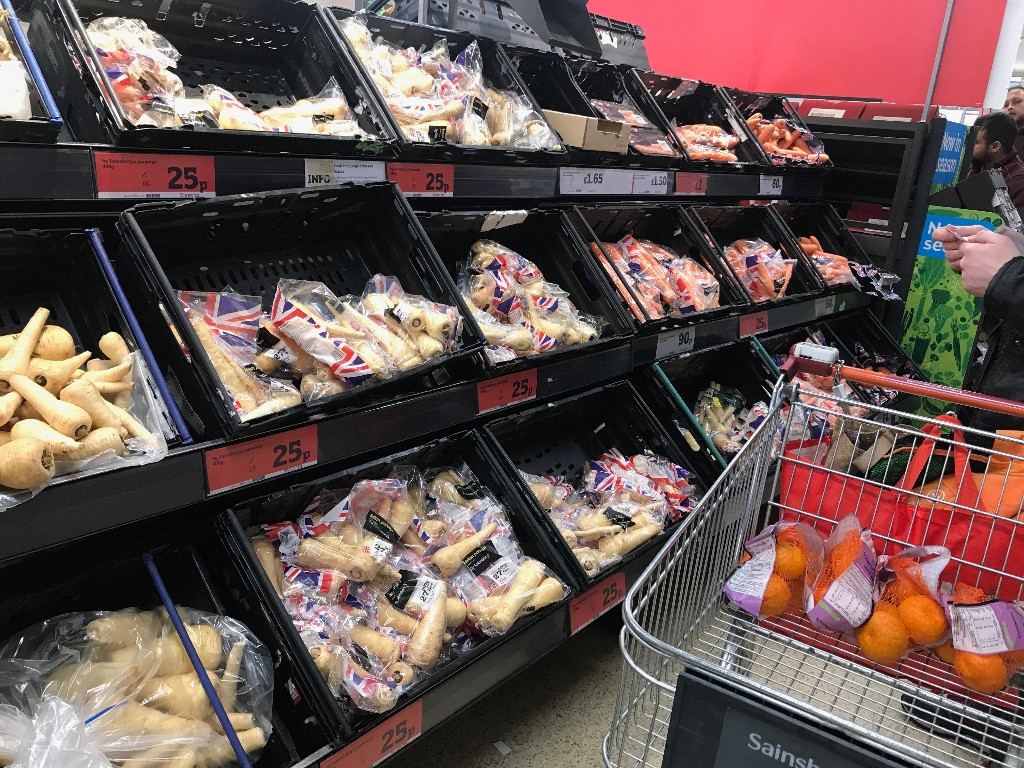
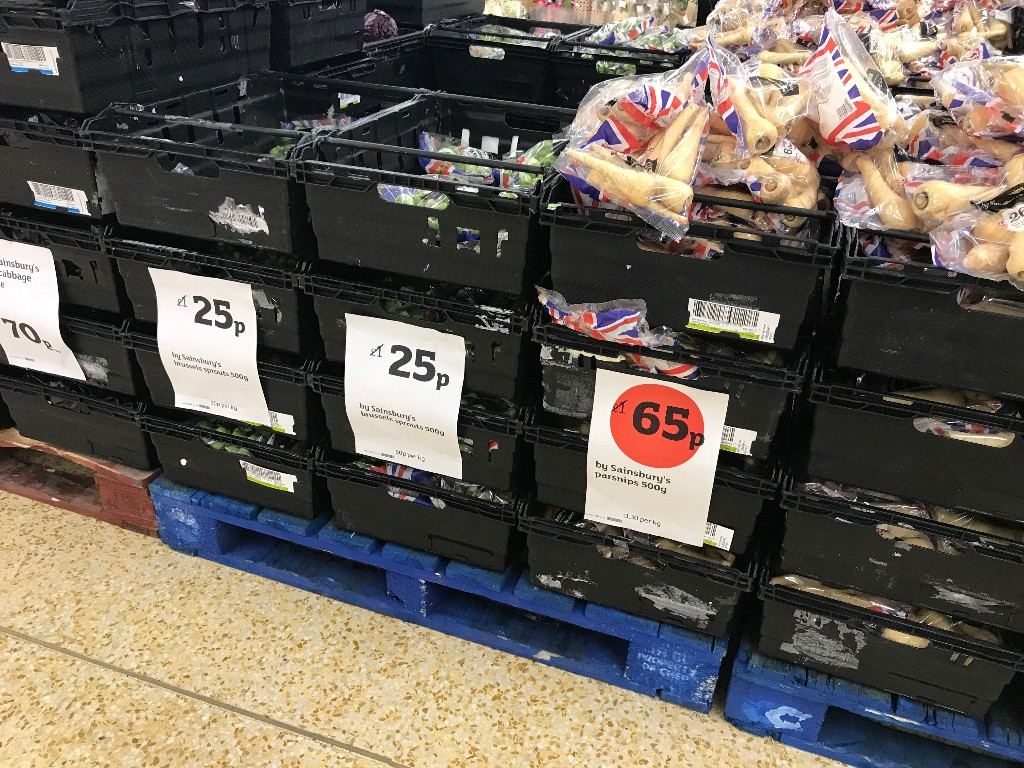
Produce was another battleground that Sainsbury's presumably identified and entered this year. Previously they've been 'steady' on price around Christmas staples without doing anything really market leading.
However they went in at 25p on some products for Christmas this year, with others, like Parsnips priced at 65p.
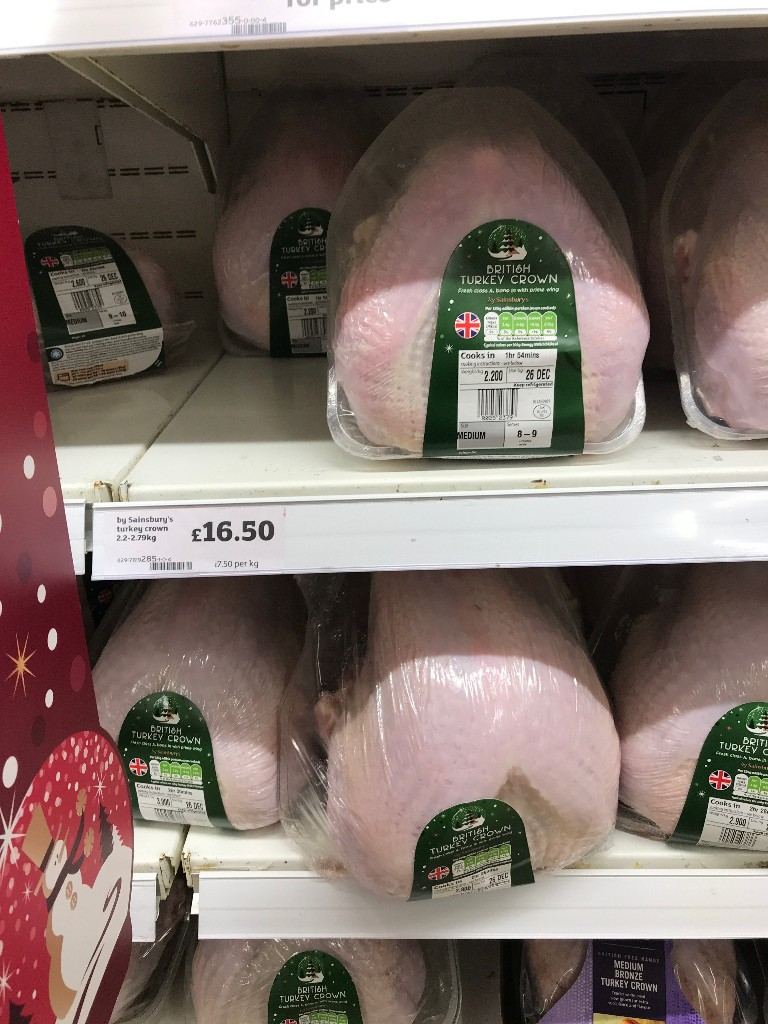
Sainsbury's were once again fixed price for Turkeys this year, and were competitive in doing so.
A strong range of premium and core own label worked well, their price competitiveness on Turkey was noted in 2016 too, however there's little point in being really strong on the price unless you advertise the fact to customers.
I don't find that customers tend to shop around for a Turkey, it's sort of within the full shop - unless they pre order it....
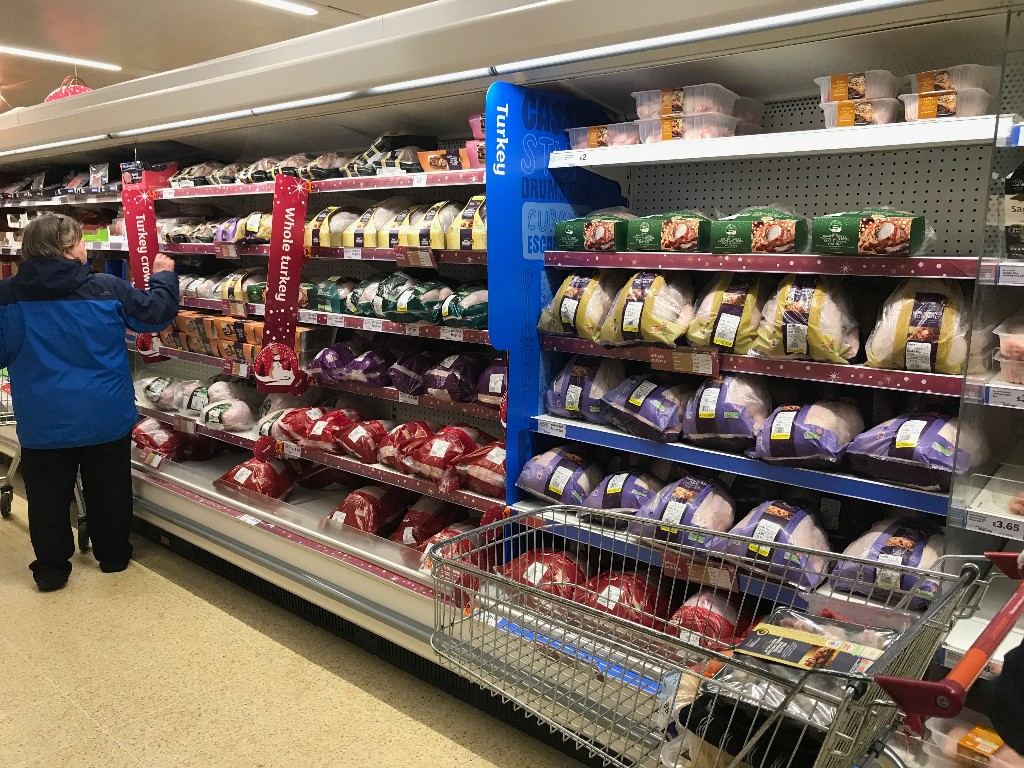
13:30 on Sunday 24th December, Christmas Eve (store closed at 4pm) showed a remarkable picture.
A near full run of Turkeys available. Not a good place to be.
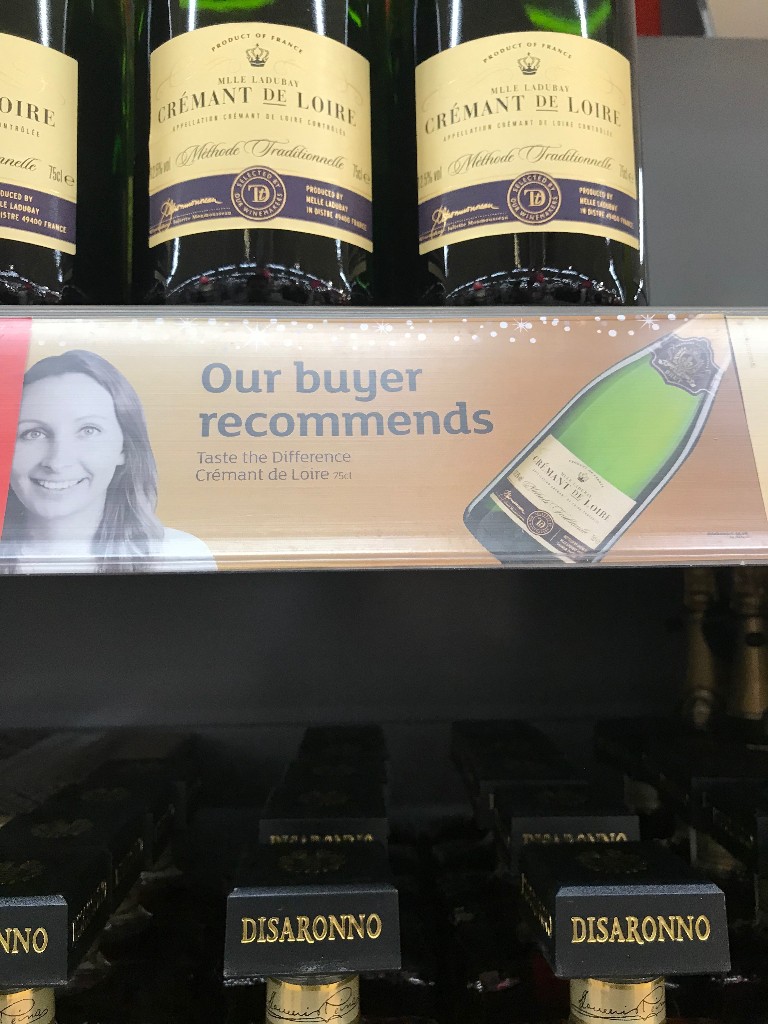
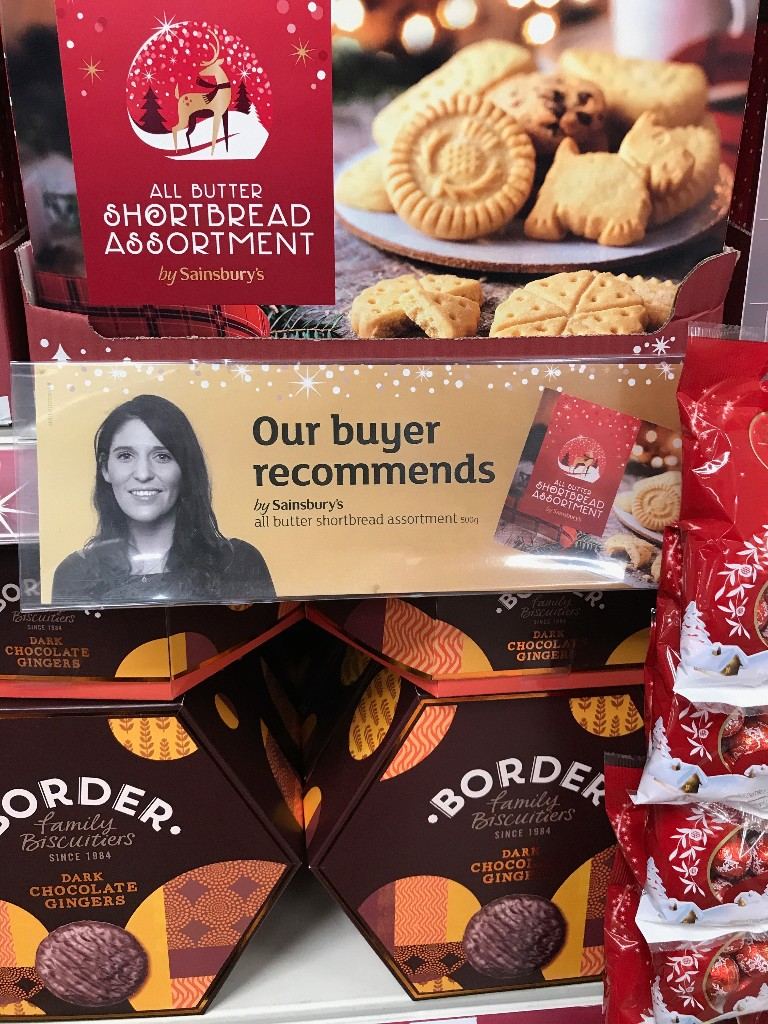
We have seen the buyer recommending various lines before, often they'll pick a high priced item to get their sales moving, in September I think there was one for the Christmas Pudding.....
However, whilst well intentioned, what do these signs add? Obvious lines have been selected - Premium Wine and Shortbread? At Christmas?!?
If this is to be used, then products should be selected and be truly special, or feature something that won't be found elsewhere.
Not Shortbread.
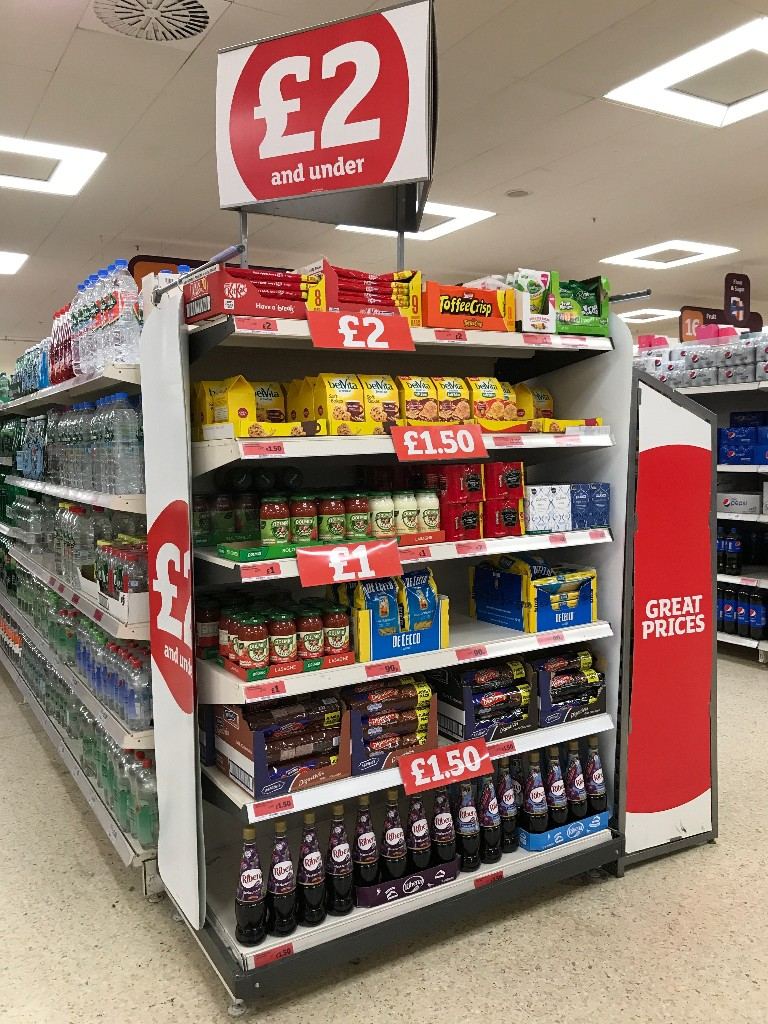
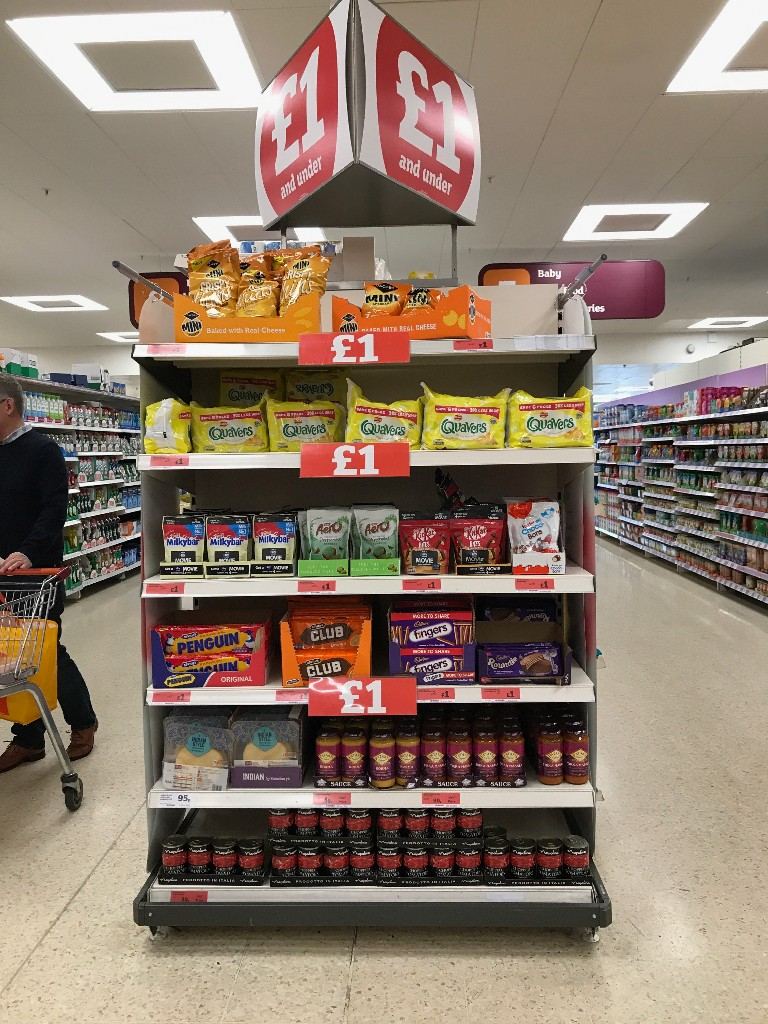
The new year has seen Sainsbury's emerge relatively 'ok' on clearance levels, they were quite sharp with discounts pre Christmas which aided the effort.
Gifting was strong for them and I felt they got the balance right, clearance again here and on decorations was solid. They were caught on Chocolate tubs seemingly, like Tesco with a fair few around.
Also some stores, with the top stock seem heavy on condiments, stuffing and other core lines. A sign of over ordering? Or just not the expected sales rates? Even 'busier' stores appear to be lumbered with Pickles, Mustard and Paxo.....
Entering the new year has seen some effort by Sainsbury's to flag value, with ends set up to be £1 / under, or £2 / under etc. Not the usual 'great prices' wallpaper which ultimately makes the central aisle irrelevant to some customers.
Sainsbury's flagging value is noteworthy, do they recognise that price perception is becoming a challenge again? Or is it a way to showcase some element of value on the ends themselves?
Either way, it seemed interesting to do so. But not a bad thing necessarily, in fact, it was better than their usual end profiles.
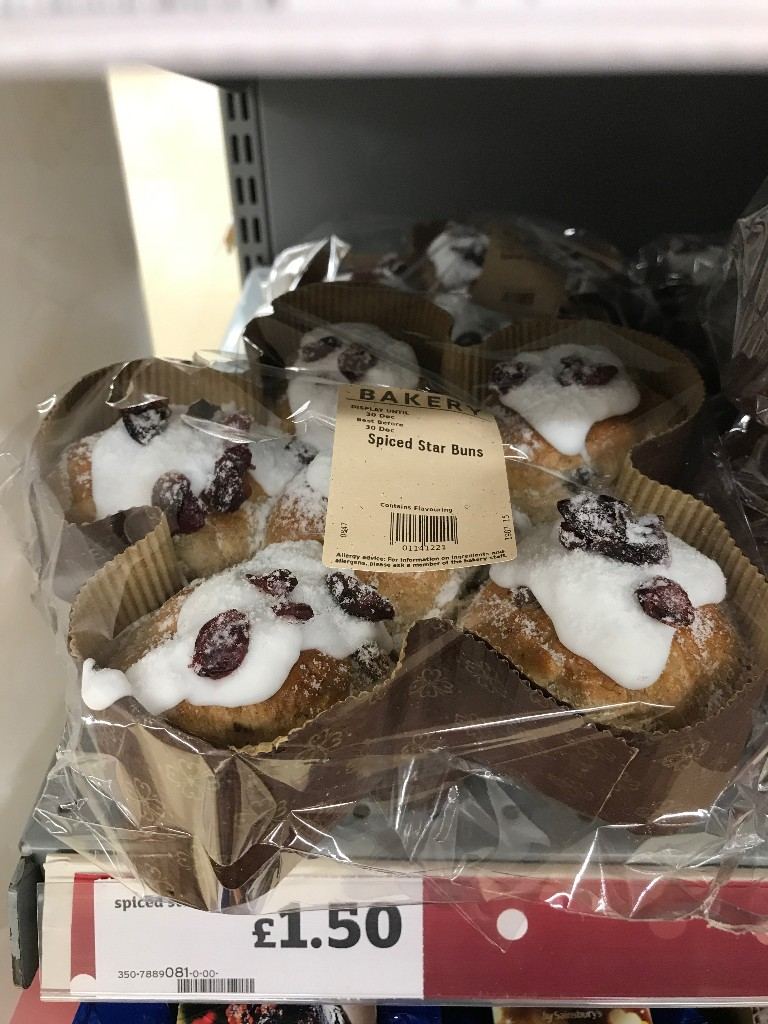
The challenge for Sainsbury's around food is perhaps best summed up by this image. I visit numerous stores and see a lot of things as you'd expect.
I had no idea Sainsbury's were doing this product, it was barely featured despite it being 'freshly made in store'. Nicely festive themed and an ideal pick up line.
There was nothing in the marketing for it, nor was it featured anywhere.
In that case, why bother doing it at all? Just seems bizarre, but a great example of a line that could do well for the business.
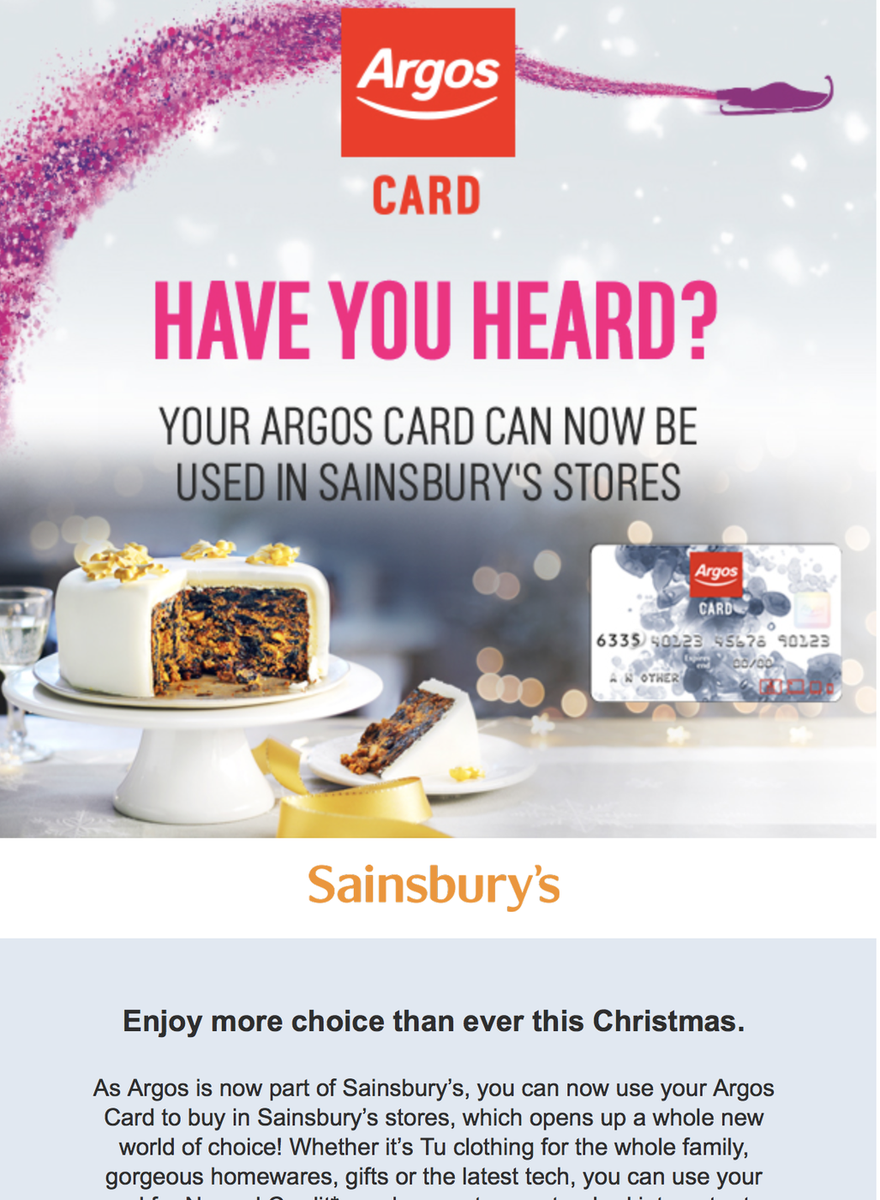
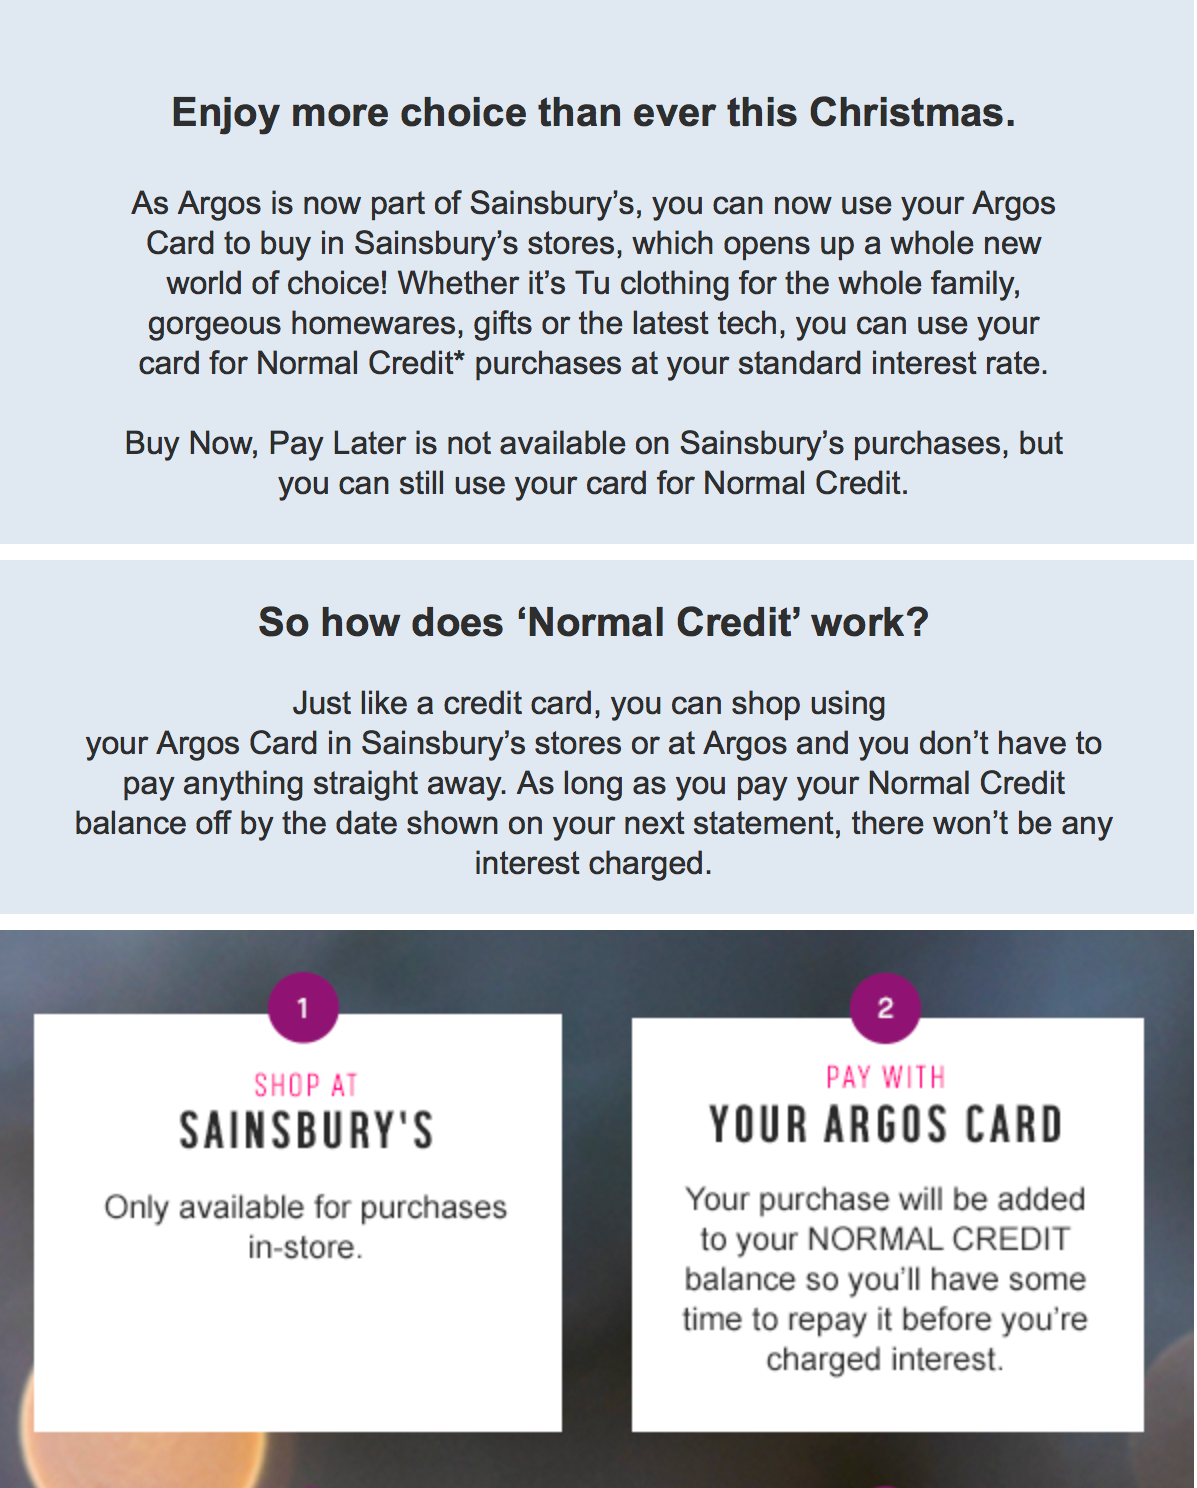
However the most interesting thing for Christmas was the ability for a customer to use their Argos card, at Sainsbury's on their food shopping.
A store card for Food. There wasn't a no interest free period either if you spent over the trigger amount. Just another way to pay at Sainsbury's....
An interesting one too.....
So there we have it, I felt some improvements in signage and 'brightness' for Christmas but real challenges on store standards which manifested itself in poorer than expected availability and also challenges around produce quality too.
That's the current challenge for Sainsbury's, focus on Argos and the wider non food numbers. Important, but the core business remains food and it's hard to grasp what the 'end game' is around store standards and presentation.
You can go so far with making stores look 'shopped' and not necessarily tidying as often, but there is a tipping point. For a business that has built its reputation on better, more consistent standards than its rivals - it seems an odd strategy.
Especially since, whilst there is some good work on lower, regular pricing, it's not enough for a customer to think that the step down in standards is justified....
Given the Morrisons results yesterday, and the Tesco results tomorrow. It brings the Sainsbury's performance in to focus and given they're incorporating Argos in to the figures now, one would expect a decent amount of sales growth given Toys etc.
Plus Argos are now rapidly appearing in Sainsbury's stores which must increase visibility, access and opening times for the chain?
We shall see, also we shall see if there's a like for like number that excludes VAT and Fuel, not just Fuel......(!)
Did you enjoy this email? Join our service
I'd like some critique of our business, or some help elsewhere
A 'huge' Christmas report is available soon - request info
From the Grocery Insight newsletter archive, first sent to subscribers on 9 January 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.