Tesco - Booker coming...
16 April 2018

Subscribe to our service, here.
This week finally sees our longer term view on M&S, given their results are coming soon and these emails have been promised for an age!
Interesting to note that notes last week from Goldman saw the shares fall as they struggled to see a longer term outlook for the chain.
Clothing is where we start and it's interesting as I'm no fashionista but retailing of clothing appears fairly rudimentary to me at least. But there is often a greater focus on the collections of Clothing, the design and whether the range lurches from good in one quarter to bad for the subsequent two quarters.
Which is all relevant. But when you actually look at the shopping experience, as I have done in detail. It's a picture of confusion and essentially M&S are somehow able to erode their value position on one single rail featuring any more than one garment.
But that is to come, Homeware follows and then Food. Of course much has been written about Food and the like for like tale there is obvious to many that there are clear issues with the chain.
The multitude of deals have actually made M&S look expensive and in some cases, then reduce the impact of the quality of food, given the deals are so plentiful.
It's all gone a bit short term to get growth, multiple meal deals and their coupons are still running too. The challenge here is then getting off this drug, so the new CEO for Food, Stuart Machin certainly has his hands full.
But, that said. He does start with a new broom so can look at this objectively and run the food business accordingly.
There has been a slight hiatus with our service, as we have been away in New York, reviewing things over the pond. Lots of movement online and this will be fed back via the email service.
If you are a subcriber and would like to know more about our services in terms of turning images to insight, and how we could help. Please do get in touch, we are able to offer a really unique insight service and have so many images of best practise and 'food for thought'.
Equally if you feel more in your organisation would benefit from subscribing to our newsletter, then we are able to offer great rates for multiple users.
Excitingly, we are beginning to sell our event insight reports and also have an historic view of events to compare and contrast. Ideal for exit reviews and plans for 2019 for key events. Our Mother's Day report stands at well over 200 pages of rich imagery and insight.
In terms of events; Easter was over and done with in early April and closes the book on a busy first quarter for retailers. A health focus in January that quickly moves to Valentine's, Mother's Day and then Easter.
This before the dreaded 'Summer' in Great Britain campaign that is often about two days of warm weather with gaps on all Salads, Burgers and Sausages before rain and reductions left, right and centre.
We'll take a look at Easter too, with a strong showing around the retailing landscape. Sainsbury's felt improved and had their price cuts to support trade, Morrisons were light on Easter Eggs by Good Friday, decent sell through(?) Aldi were very sharp on premium once more and reducing their reliance on branded Eggs.
Trends continue to emerge and it was striking at how similar the Aldi and M&S Easter Eggs were in some cases in 2018. It's also therefore striking how at odds the price points were too.
Last week of course, saw the Tesco results and their recovery continues to take hold, with growing profits, sales, customer satisfaction alongside other metrics, all pointing to a positive picture for the chain.
The real intrigue is reserved for the Booker integration now the takeover (merger) has completed. Clearly Tesco have a decent vision for the chain which is as much about driving trade and utilising space in the Tesco stores, as it is about strengthening Booker themselves.
The UK's leading food business is presumably already their title by size at least, but actually walking the walk is a longer term plan.
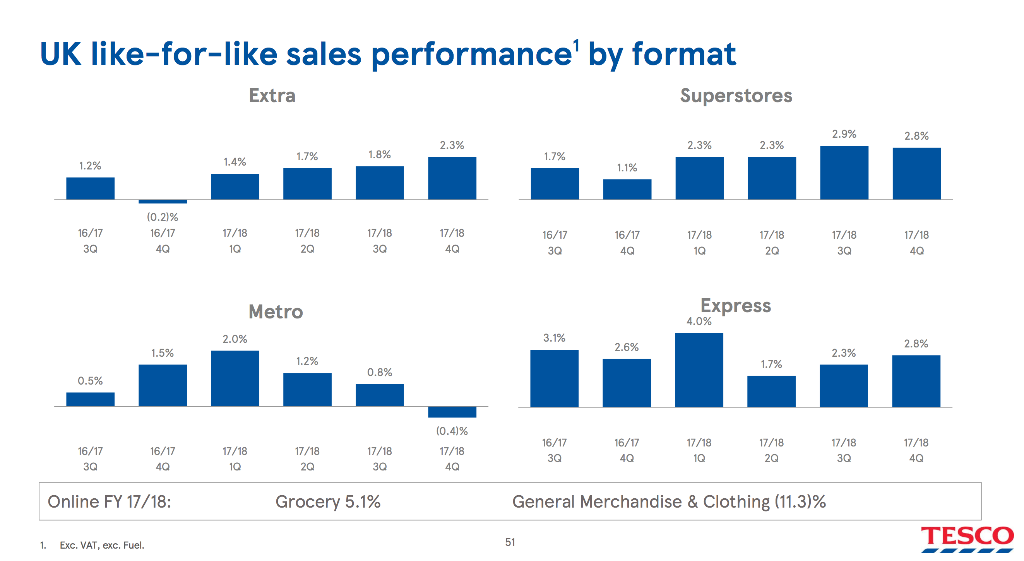
The format like for like performance is always worth a look, and the numbers continue to look good. Of course inflation plays a part and it's becoming harder and harder to use like for like as a metric given inflation. However it remain the industry core barometer, assuming everyone measures the same figures.
Sainsbury's including VAT in their figures for example, just undermines it a little. No one else includes it.
Anyway, the Superstores and Extra stores continue to perform well and the focus on non-food ranges will aid the focus here. The Metro format was the only format to be in decline for an age, with a -0.4% drop in Q4.
Why? Did the weather impact? The lack of Cigarettes / Frozen deliveries with the P&H challenges? Metro stores are few and far between and there have been rumours of this format (typically sited in busy urban city centres) being integrated in to Express or Superstores, depending on the size.
Certainly a decline does point to a concern as the sales have slipped away on a like for like basis, +2% in Q1 17/18 for example. So one to watch there.
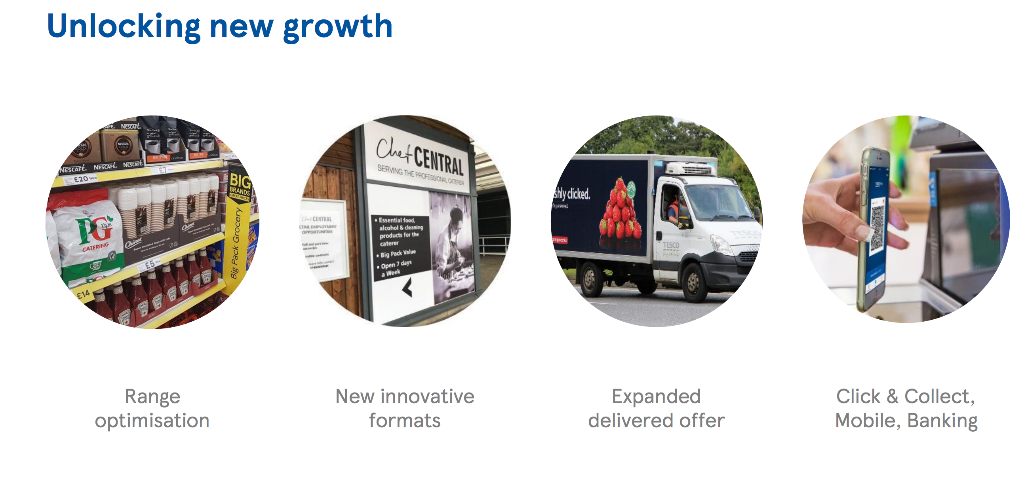
Of course, we have seen these slides / images before, either in store or via the Tesco ambition for Booker.
Range optimisation is noteworthy as we know that Tesco have landed some seasonal space with Booker products. Indeed the larger packs / better value message has been out there with these areas in store.
It's effective as a use of space, otherwise the stores end up re-merchandising space for the sake of it, with another event almost designed to keep things fresh. The longer term addition of bulk based products will drive footfall and a different type of customer to Tesco.
Innovative formats showcases the Chef Central pod in Bar Hill. Not part of the core store, rather a concession that is separate from the main store. It seems obvious that Tesco will look to land a Booker space within a main store, perhaps near counters, or in the middle of a store like Holland & Barrett would be.
Expanded delivery offer is clearly related to the geographic reach of Booker and their limited number of warehouses around the country. Using click / collect opportunities alongside the near nationwide Tesco logistics operation will improve delivery times and allow them to a) improve service to existing and b) offer delivery services to sites that may be too far for Booker to service efficiently.
As suspected, Click/Collect is to be integrated. It can work the other way too, with Tesco Direct purchases to be collected at Booker. Mobile loyalty / Clubcard and Payqwiq / digital wallets will all drive longer term loyalty one suspects.
All obvious of course, but the scale can be achieved rather quickly, and the introduction of more stores featuring a near permanent range of bigger pack sizes and the change from brand outlet to a price based aisle (£1 under / £2 under) means that Tesco can attract a new breed of customer to the stores.
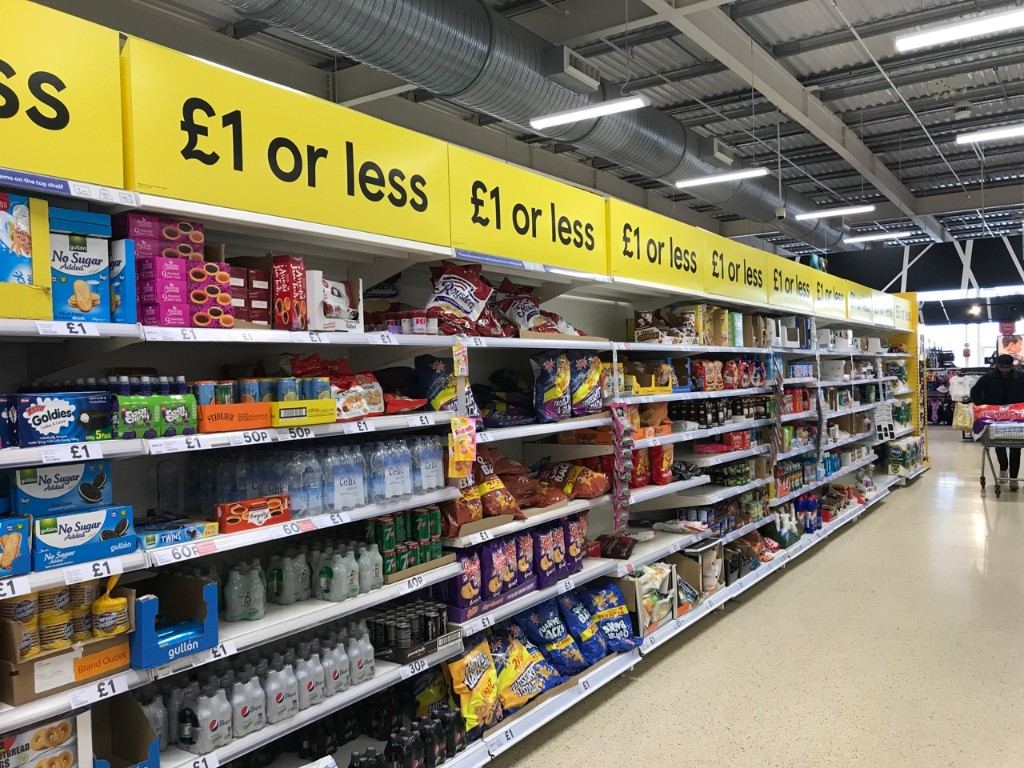
But aside from the integration of the seasonal space in selected stores, and physical roll outs of Booker in store. Their greatest opportunity appears to be adding larger pack sizes to the ranges and highlighting the value to be had, buying in this way.
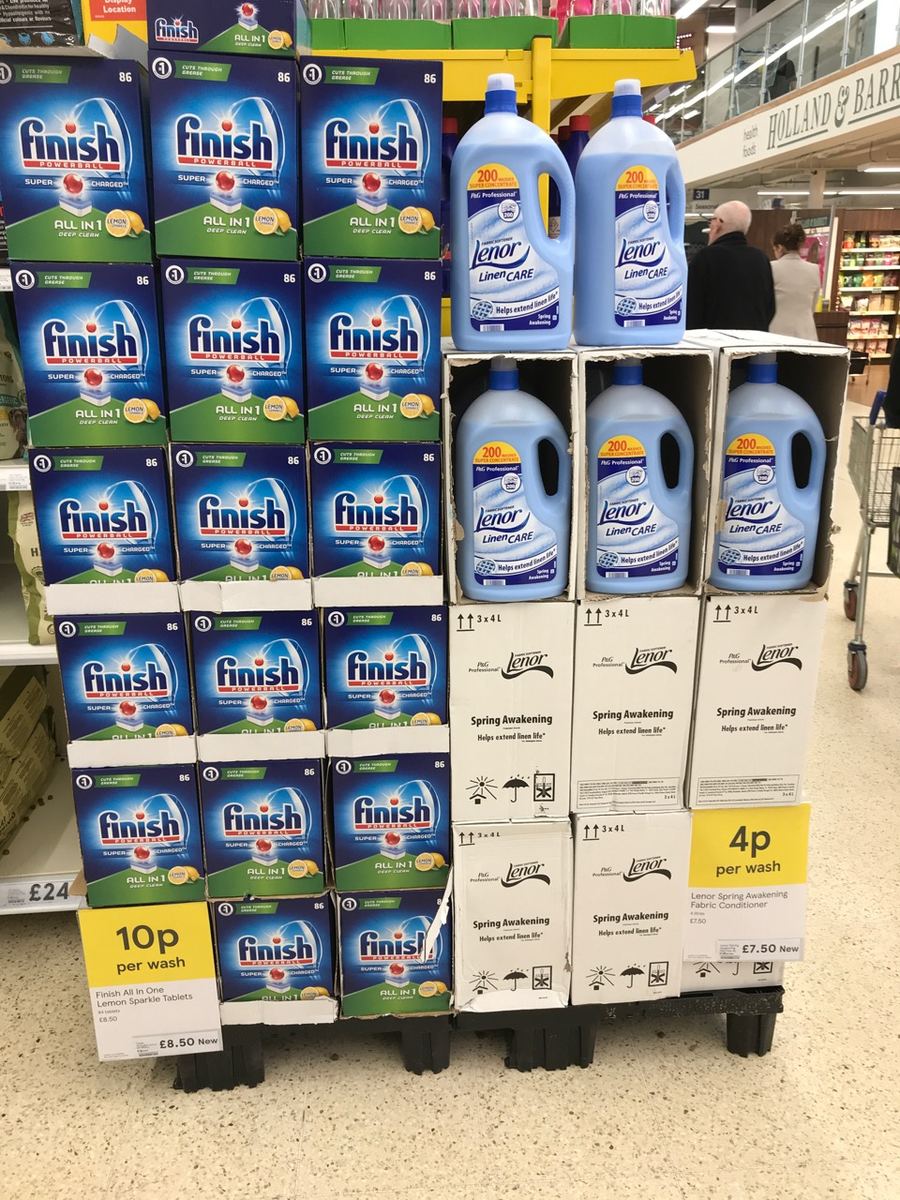
The simplified ranges play in to this of course, a clearer picture for customers who can see the range and value hierarchy clearly in Dishwasher tablets. Therefore the addition of a larger still pack size that is priced 'per wash' and therefore attracts the attention of that customers who buys in that way is far more sustainable.
It will grow volume and sales, however there has to be a consideration that the value for core customers isn't lost either.
Not to mention that the deals on the 40pk Finish don't then conflict with the overall price for the bulk buy Finish. That's the challenge, the bulk buy line always has to be the best value.
Otherwise you're just chasing hi/lo promotional sales once again.......
Our Mother's Day review is now available
Subscribe to this service, here.
From the Grocery Insight newsletter archive, first sent to subscribers on 16 April 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.