More Tesco range work
23 March 2017
Click here for a free 1 week trial to this service.
Subscribe to this service here!
More news on Tesco who are continuing to develop their offer around own label and their category resets.
It has been a bit Tesco heavy recently on the newsletter service, but they've had a lot going on. Results for their year end are due soon and they've made strong progress in the time Dave Lewis has been in charge.
However that margin target, set around the time of Brexit which we knew would throw uncertainty in to the mix is really interesting to look at some months on.
Of course there is Tesco / Booker as well that will rumble along in the background, stories out this week about pay and price disparity between Tesco and One Stop.
It will only continue as regulators get involved around Premier and Londis and whether the interpretation Tesco have around those not being 'stores' in their own right, rather the end point for their products will stand up.
In terms of their core estate, lots of work remains to be done despite solid progress in terms of them improving the shopping trip for the customers. The all round experience is good but there remain challenges around non food and what an ideal range should look like.
Ranges have been culled, prices cut and they look all together far more appealing than they did previously. However there are concerns on the horizon, non food remains a challenge given the standards on show recently.
Plus any attempts to further cut hours from stores would be a worry given their levels of service and availability that have got them back on to the front foot.
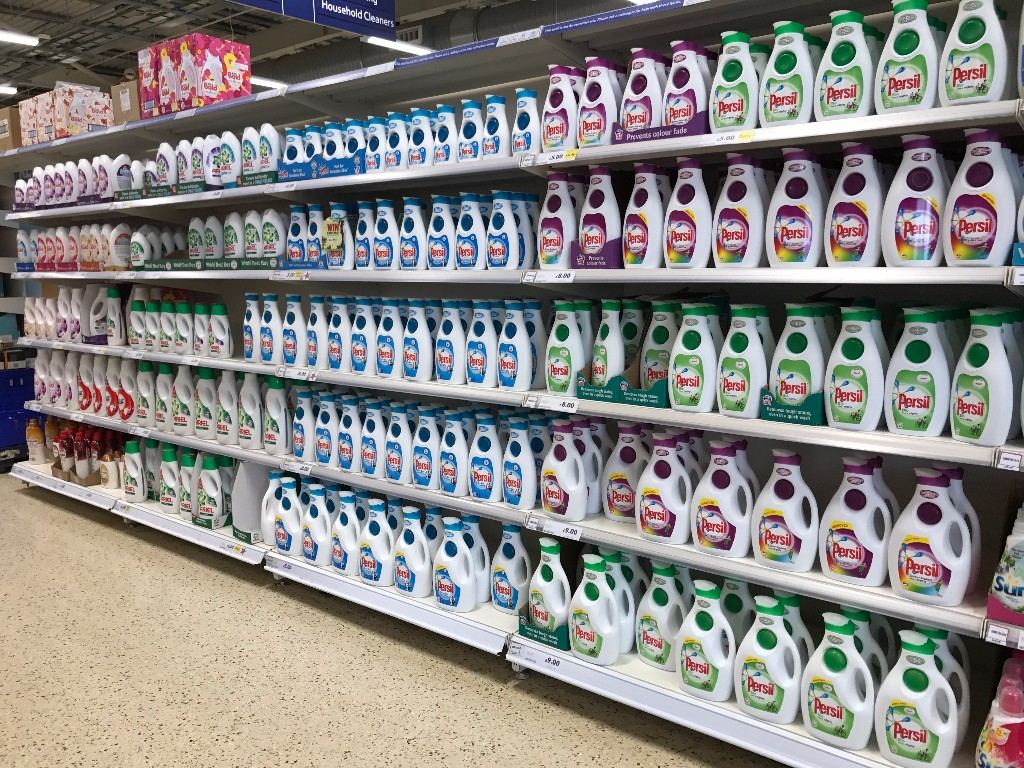
It's like the old days with a branded presence on shelf! This is from the latest range review in store, but when you consider the other work in the aisle - this is level of space for branded in a caetgory they've designed really (big suppliers want Powder to shift in to liquid, as Powder is expensive to transport, bulky etc) is perhaps fair enough.
Especially when you see that own label has demonstrable presence in the category too.
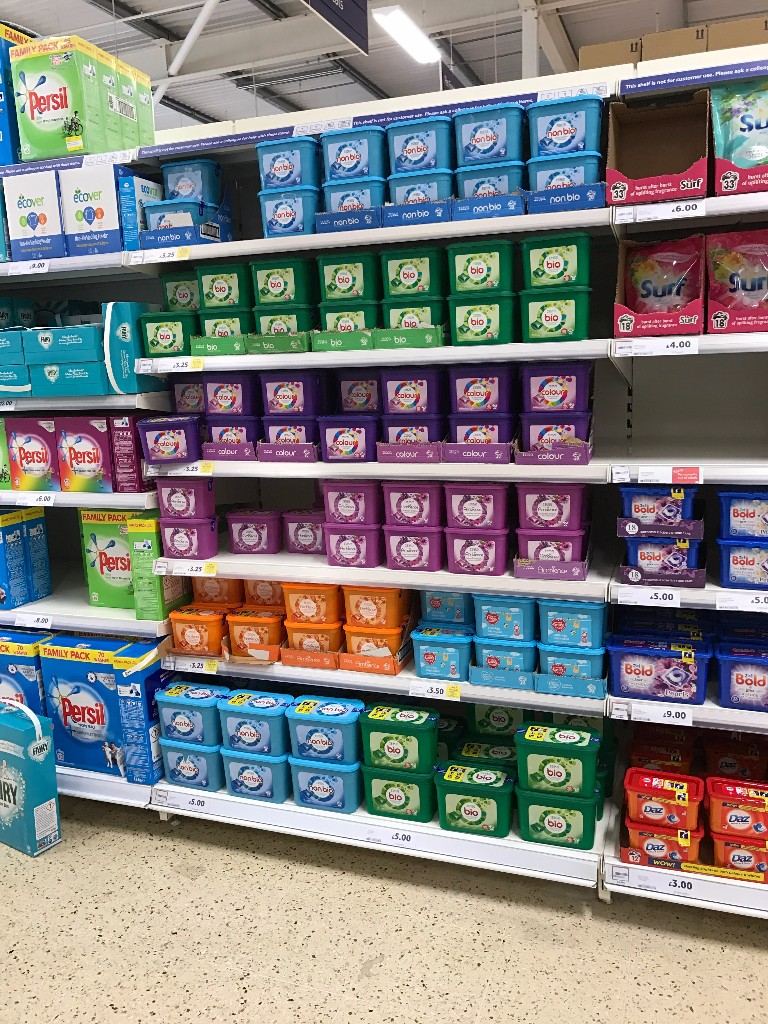
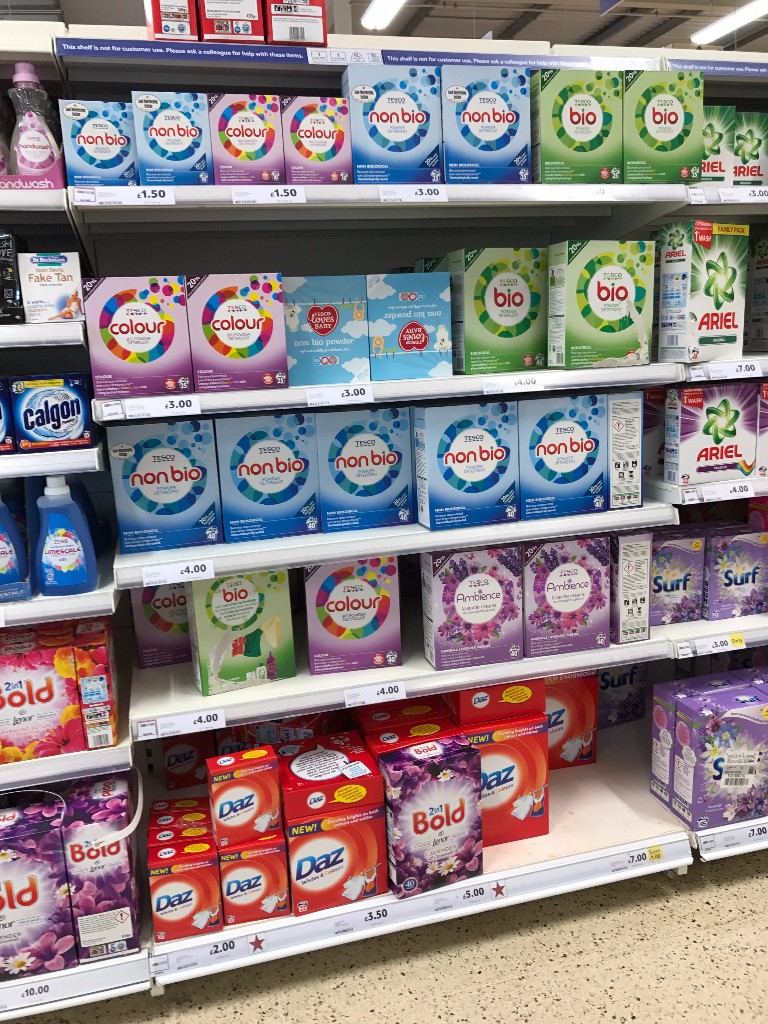
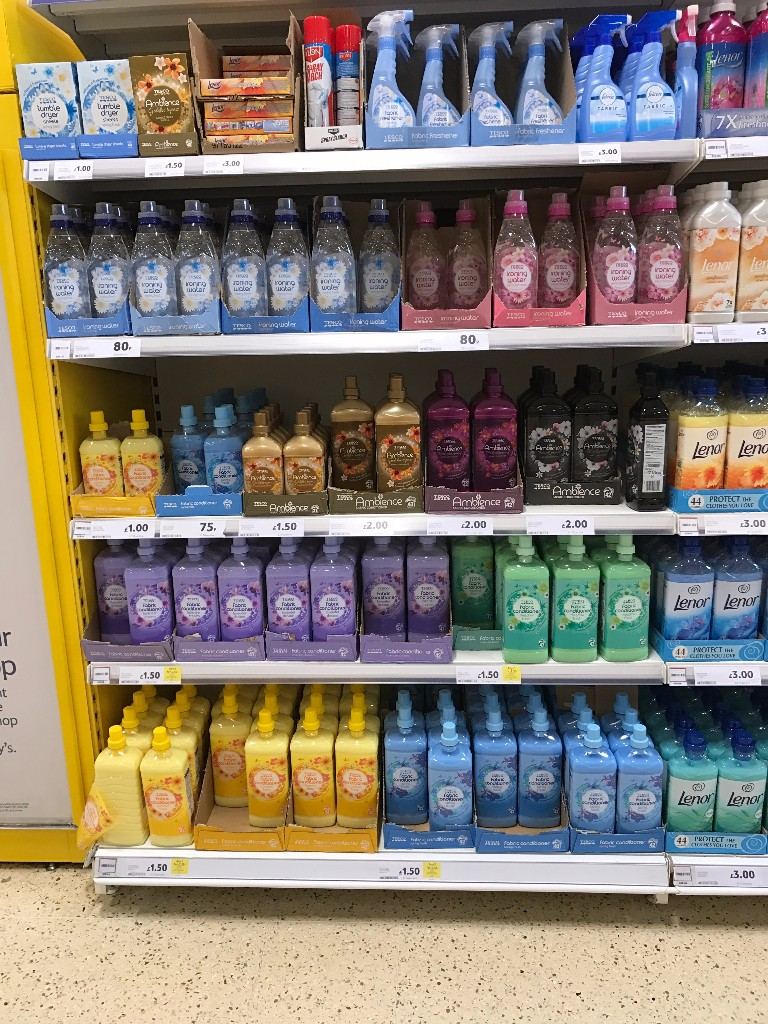
3 bays within the core range have Tesco products all located together for customers, perhaps a nod that whilst own label remains important. Brands are key for customers in this arena, so may be work to do to gain authority first....
But the location of the bays is noteworthy, the central bay in aisle features Tesco own label laundry tablets, with the first bay in Powder and then the first bay in aisle of fabric conditioners featuring Tesco products solely inside the fixture or retaining dominance in the fixture.
Strong work from Tesco; as covered before. Growing own label sales is crucial for the business, own label is exclusive to the retailer and they can control value perceptions (tighter margins to squeeze pricing but improve quality).
It's a smart move in that regard, and their work is so impressive when you consider the plethora of brands they used to have in categories like household.
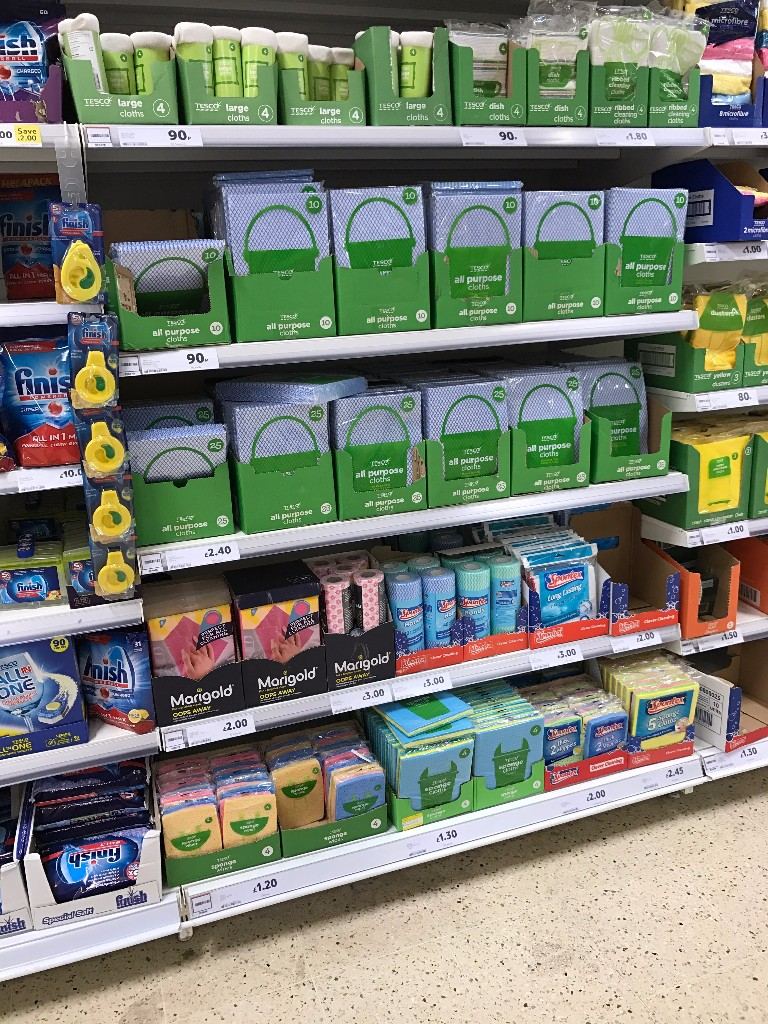
Tesco also work on changing conventions in the aisles too; perhaps this is where the fact Dave Lewis isn't predominantly a retailer helps things. Within household they have located cleaning accessories like gloves, cloths and other lines in the middle of the run.
Thus meaning that a customers shopping in the aisle (entering the aisle from either entrance) will have to pass cleaning accessories, these would otherwise be located somewhere 'out of the way' almost.
But by making it front and centre, it's a good chance to drive sales:
a) by customers seeing the fixture and being triggered in to buying as they'd forgotten they needed gloves/cloths.
b) Impulse buy, so I might as well have some as I've got x,y,z coming up and I'll need them. So it becomes an example of convenience in aisle, sharp thinking.
Retailers have tried to get these tertiary products in to the customer shopping journey for years, but have often just put all the cloths down with the bin bags and attracted shoppers who knew they needed them and knew where to find them.
But by tweaking the layout a little and allowing a focus (centre of aisle) on those cleaning accessories, it changes things entirely. Tesco tried before to enhance the wider category by locating mops in the middle island of cleaning with lots of signage from the brands around too.
It was something Philip Clarke used to trip in to Baldock to oversee every Wednesday alongside other things. You had to wonder; how did he find the time? Or justify it?
That trial ceased and never went much further, this however looks far more sustainable, is part of the category reset and also makes sense for customers.
I always think if you can see what the retailer is trying to do, then it makes things far easier for the customers to get it. Far too often, these ideas have great groundings with the shopper marketers and head office staff, but then your average customer hasn't a clue, doesn't notice or indeed, finds it bizarre....
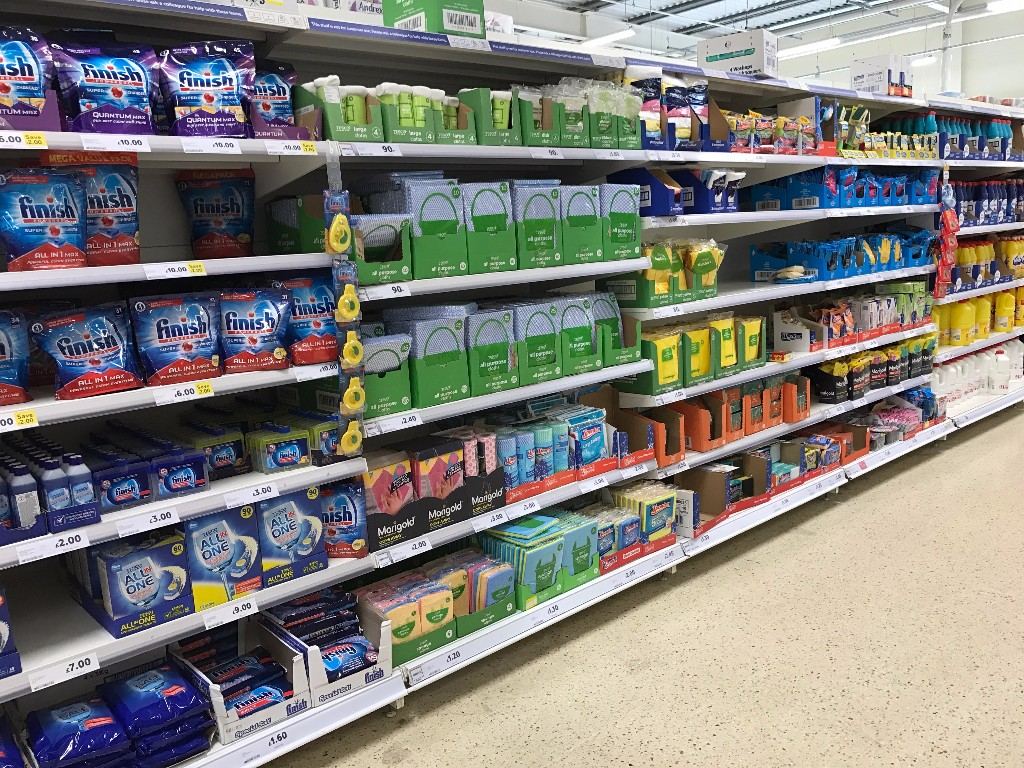
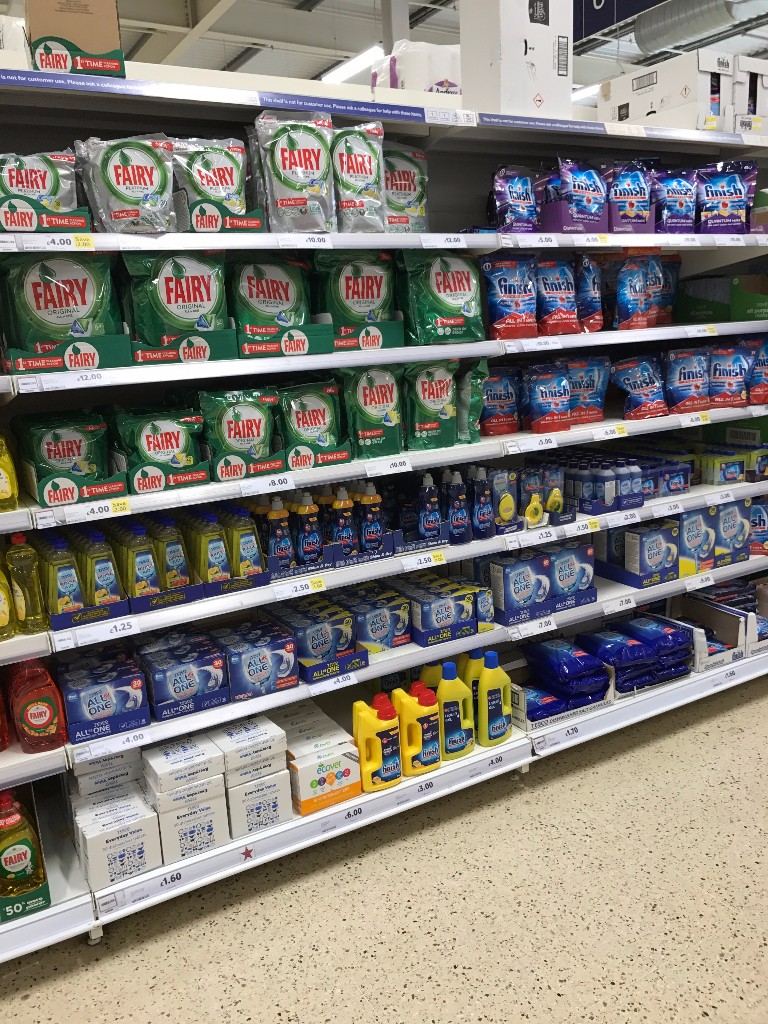
One area where they're yet to really push the agenda hard is dishwasher, Finish is a dominant brand that's fair, but Fairy?
There seemed an opportunity missed to not press on with dishwasher tablets (own label) having some presence in fixture given the hi/lo issues around promotions and core price. That's where discount get a serious foothold, £8+ for Finish or £3.29 for the Aldi equivalent.
Customer buys it, they're hooked, they're always about £3.29 and that's another reason to visit discount.....
It could be that the own label product isn't yet in a place to rival brand, which is fair enough not to really advertise it heavily... Whether that will come, or whether there are some categories where Tesco can reduce the number of branded lines and get the prices down that way...
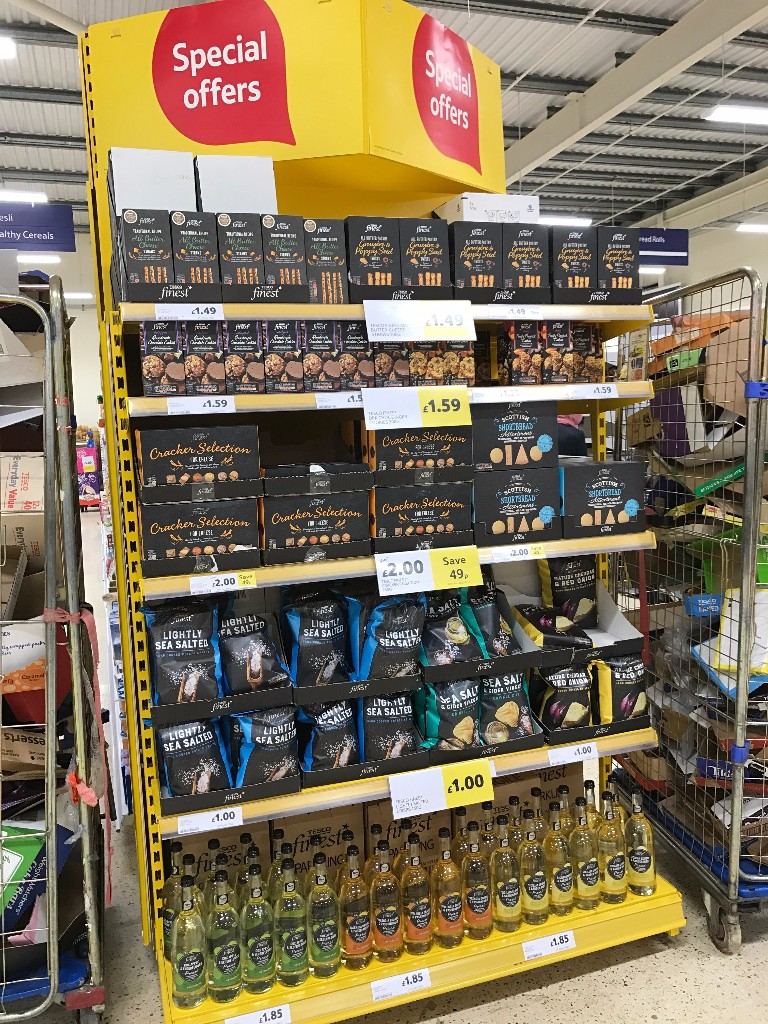
Finest continues to be featured around the store, it performs well but again, struggles with packaging and branding since the Clarke years (range expanded beyond belief, no one could read the labels on the pack and Tesco looked even more expensive).
A full end of the range here is a nice way to push the brand along, especially with core prices advertised (IE no deals). Premium is vital for events, so I expect to see a fair bit about for Mother's day and then Easter too.
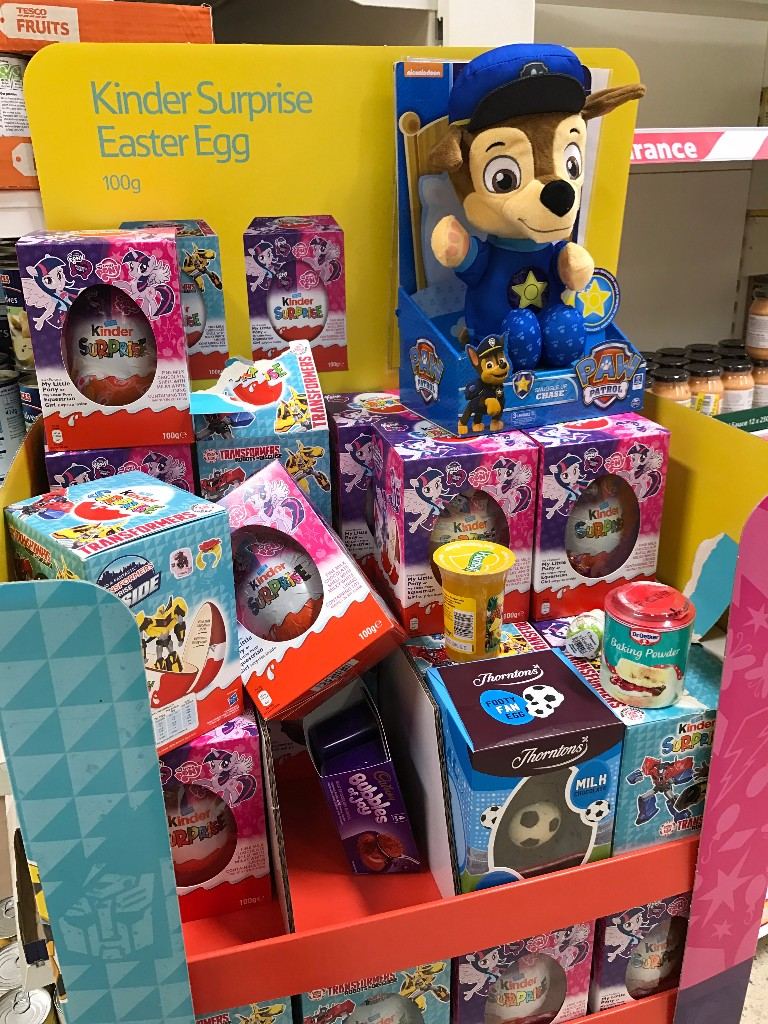
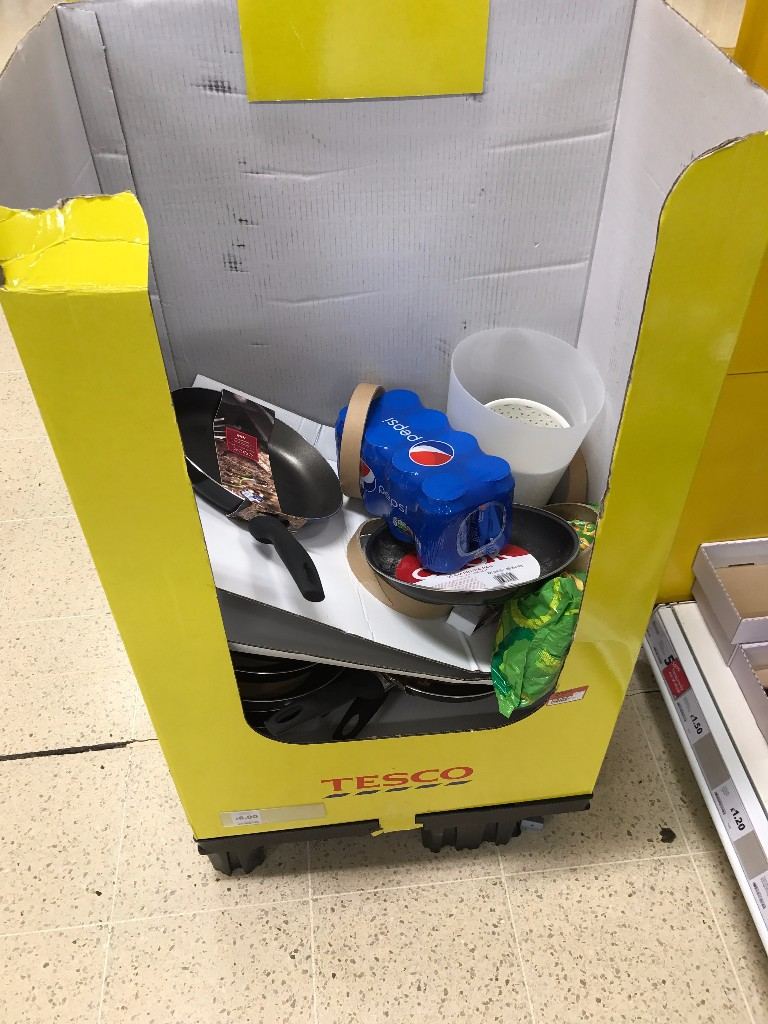
Someone's weekly shop in a shipper near enough.... The one thing Tesco need to be careful about is store hours and the standards that they stand over.
The concern for the UK business is around experience, with Tony Hoggett (UK COO) going to Asia, they're left with Matt Davies as UK CEO (not a food retailer per se). Although in his job for a fair amount of time now, not blessed with years of food experience.
Below that level - COO isn't replaced in the new world, there's Duncan Hoy (ex Jumbo, Holland) who is experienced with food retail but not within the UK. Tracey Clements heads up convenience, she has a fair amount of experience, but, not like years before where everyone within Tesco had significant food retail experience in the UK and worldwide.
All very capable people, but the wider business benefits from good UK people going to other business units, the UK has to then continue to grow and succeed regardless.
Standards have been so much sharper at Tesco since Dave Lewis came in. Of course easy to point out extra hours were needed everywhere but paying for it is another matter entirely.
They've broadly left the hours in too, however with the margin target looming large and the living wage also starting to kick in, it does become more expensive to have so many people around the stores, especially at their scale and size.
Not necessarily isolated examples here; the stores are still relatively decent but more of those own goals are creeping in.
We have seen the impact in non food of a switch in to day time replenishment, this department has been hard hit on recent visits across a number of stores.
Whilst there is a real issue with the amount of space non food has, there has to be some appetite to grow the business with new ranges and products. Whilst Sainsbury's are not doing the greatest with food at the minute, their non food business is in good health, even without Argos in the mix.
Tesco have gone down a route of old in non food, call out prices versus a competitor, be cheaper in pence but don't reward the customer with anything else. Their margin targets don't look to favour a non food push, but this seems unwise.
Competing on price and price alone, they did the same in Ireland when they lost their way, 30c cheaper than Lidl on a trolley of products at the front of store.
Yet it took the customer 3 times as long to get around, lines were off sale, the store was untidy and you had to queue to pay........
For 30c, probably more. Not difficult to see where the customer would go.
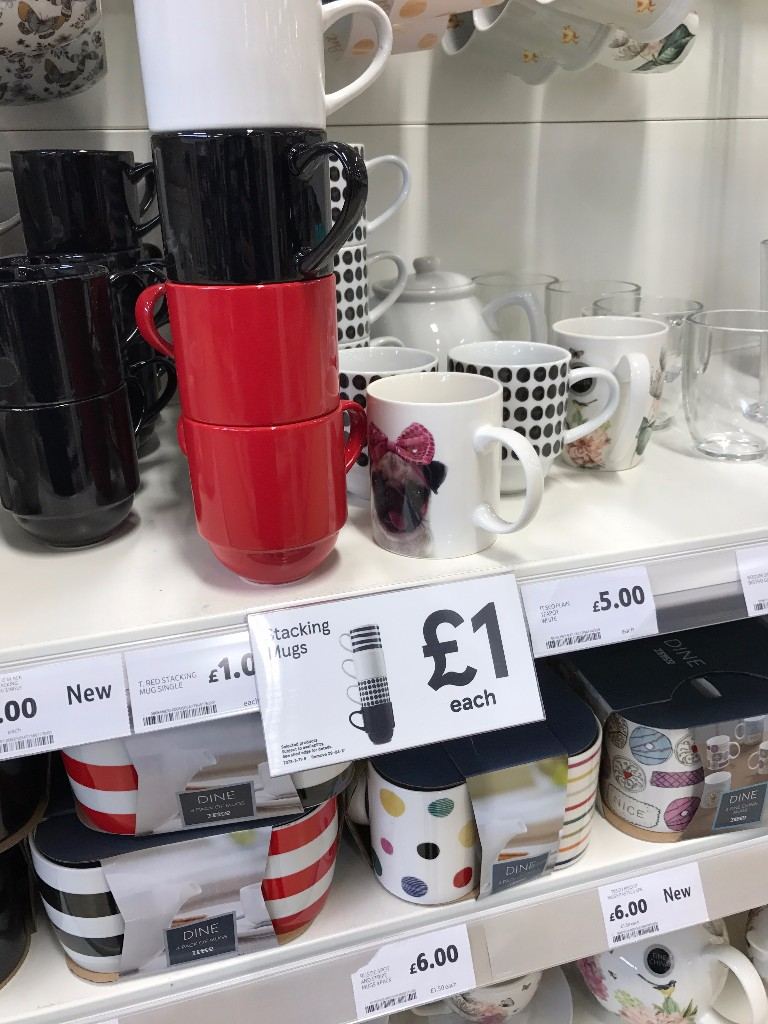
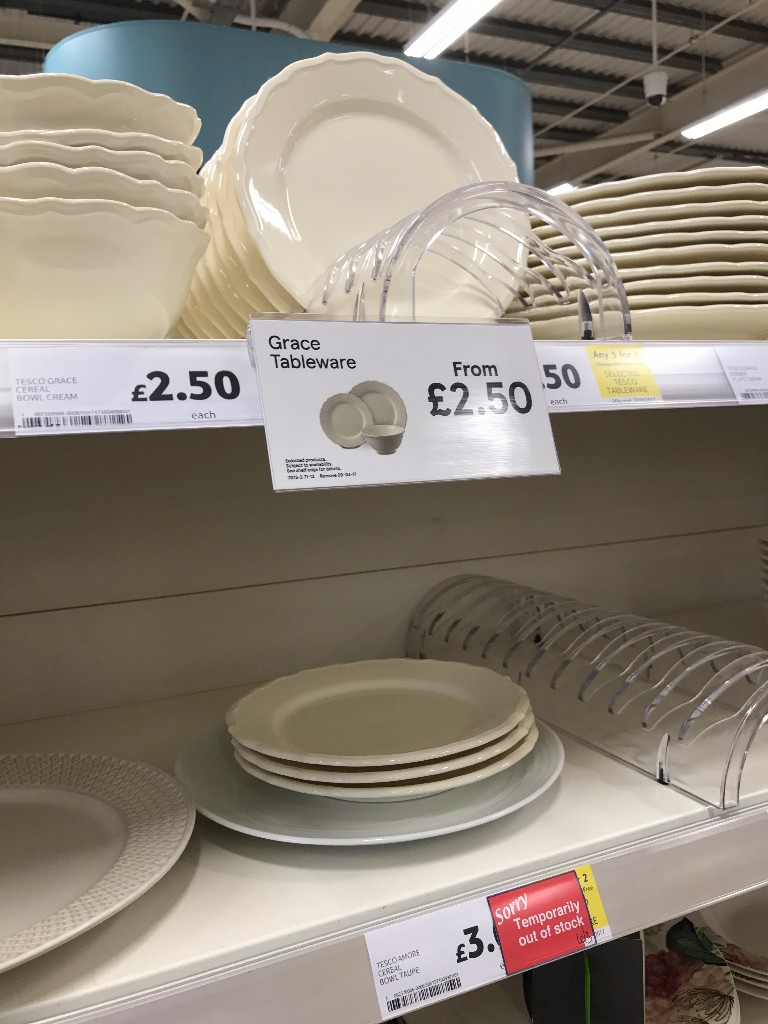
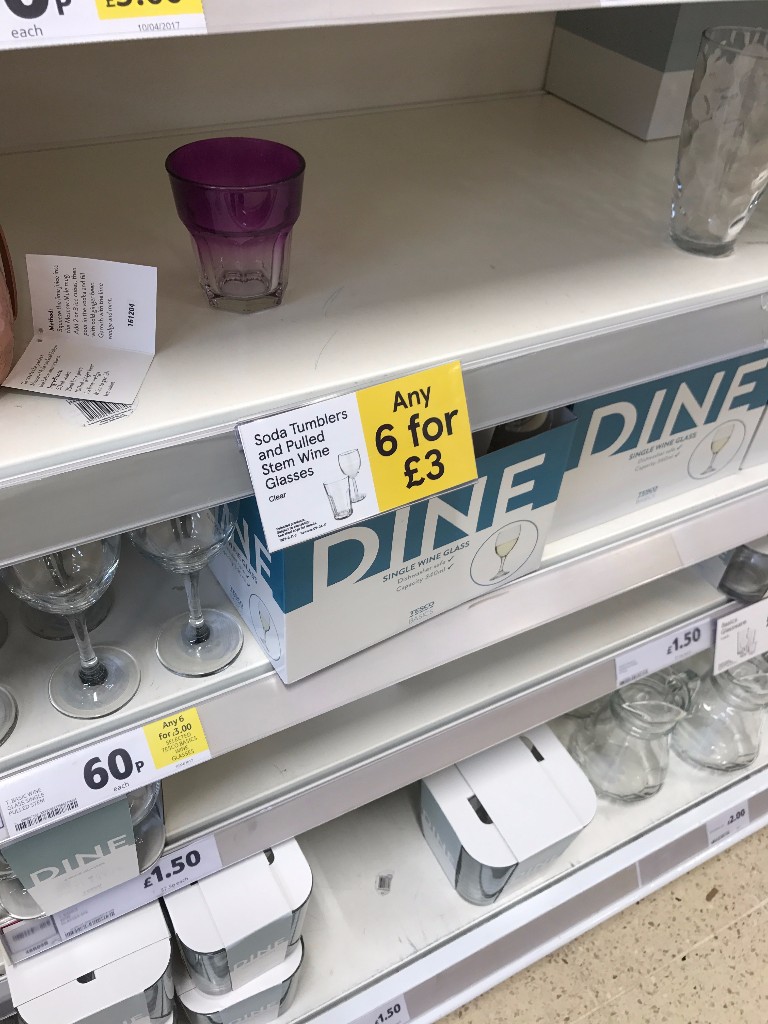
New ranges and price advertising for general merchandise it seems, unclear whether it's so patchy because they're trying to fill through the day, which obviously impacts the overall operation.
It takes more time to fill in the day and often the relays (changes to plans and what not) are carried out at night, especially where products have to move to the top / bottom of the aisle, it's always disruptive. Unclear if they still are in this case.
Put simply, it has to be more about price here. Decent offer on 6 for £3 but nothing on sale = no sale. Displays look 'ok' but they're not as crisp and clean as Sainsbury's, or even Asda.
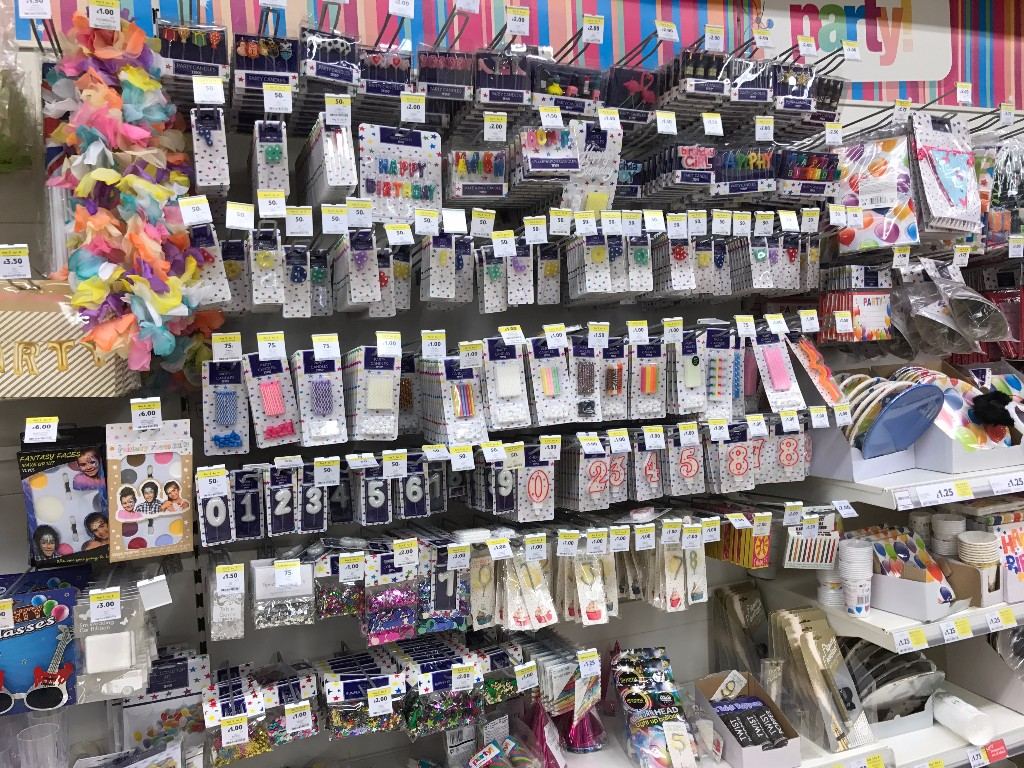
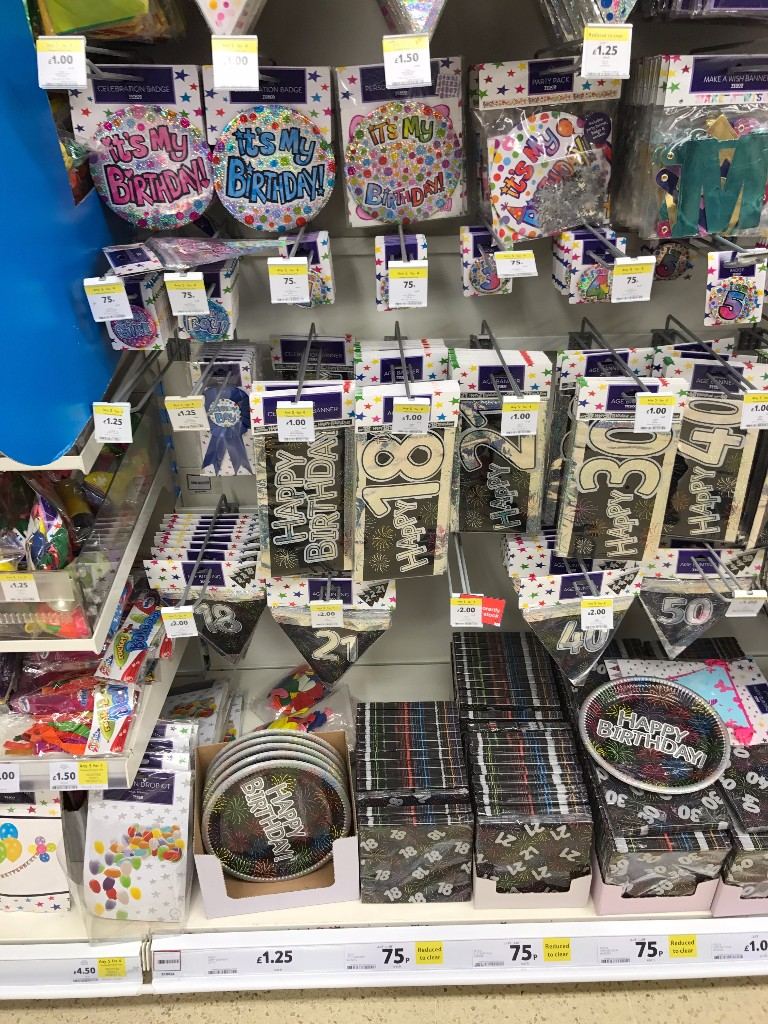
Some half decent work on party though, with an expanded range of lines on 5 for 4. Areas like this are good for growth and to drive footfall.
Not a particularly loved area of the store, some expertise is needed on replenishment as it's fiddly to fill up and lots of the products look the same, but some progress.
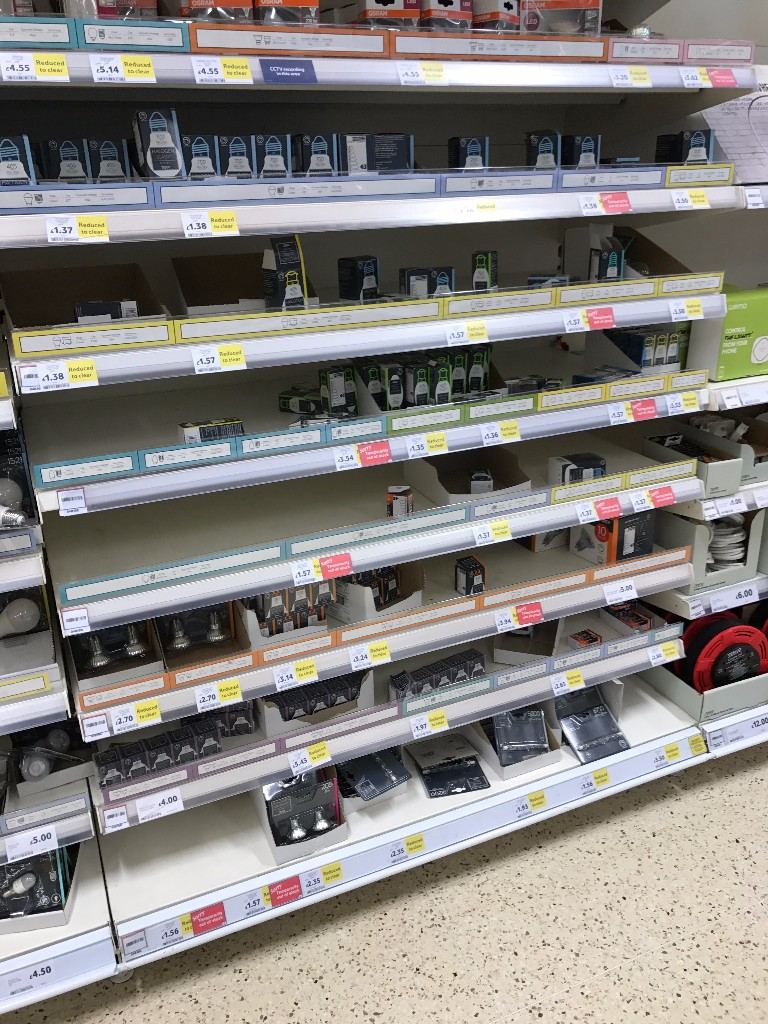
The acid test of any retailer is how they deal with range changes, particularly larger ones that Tesco have been carrying out. In an ideal world, price cuts are applied to clearance lines and they sell out in time for the new ranges and plans to be implemented.
We don't live in an ideal world though, so you can have the situation where lines sell out quickly before the new stock and plans are due to arrive. Which leads to gaps on core ranges like lightbulbs.
Not strictly non-food but equally, important for the shopping trip and customers will gravitate here, lots of dwell time in fixture as they work out what fitting they need on the bulb, what's lumen mean? What's equivalent to a 40w these days? Wondering whether the EU have forced this change etc.
So issues aplenty to tackle on this one.
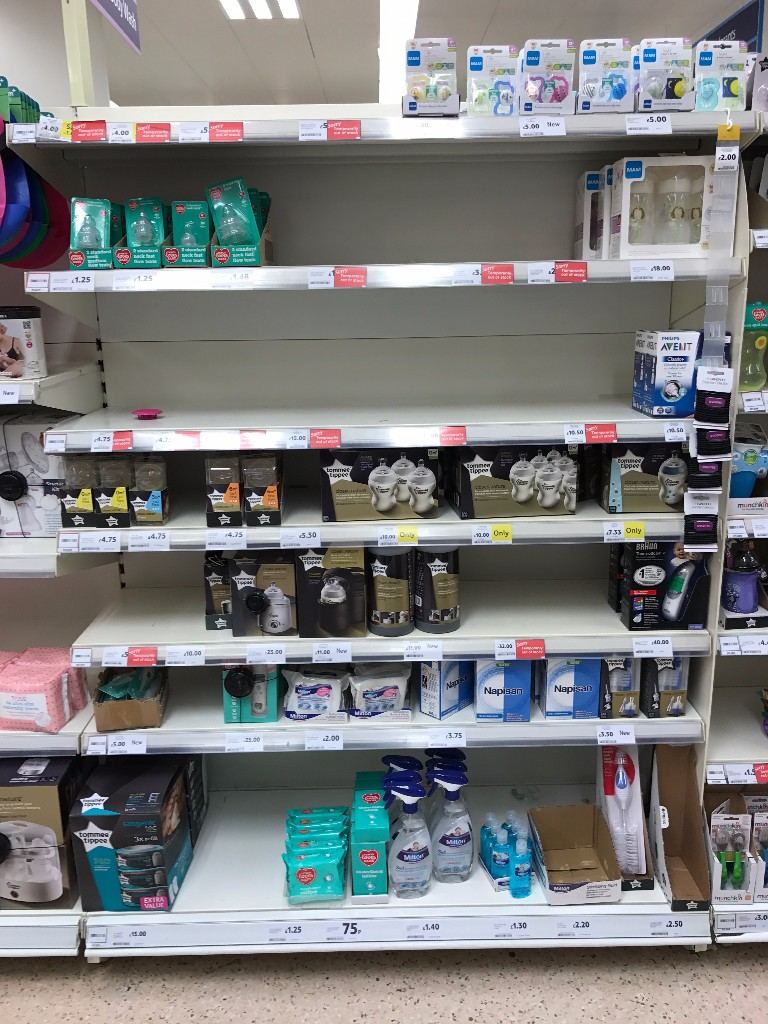
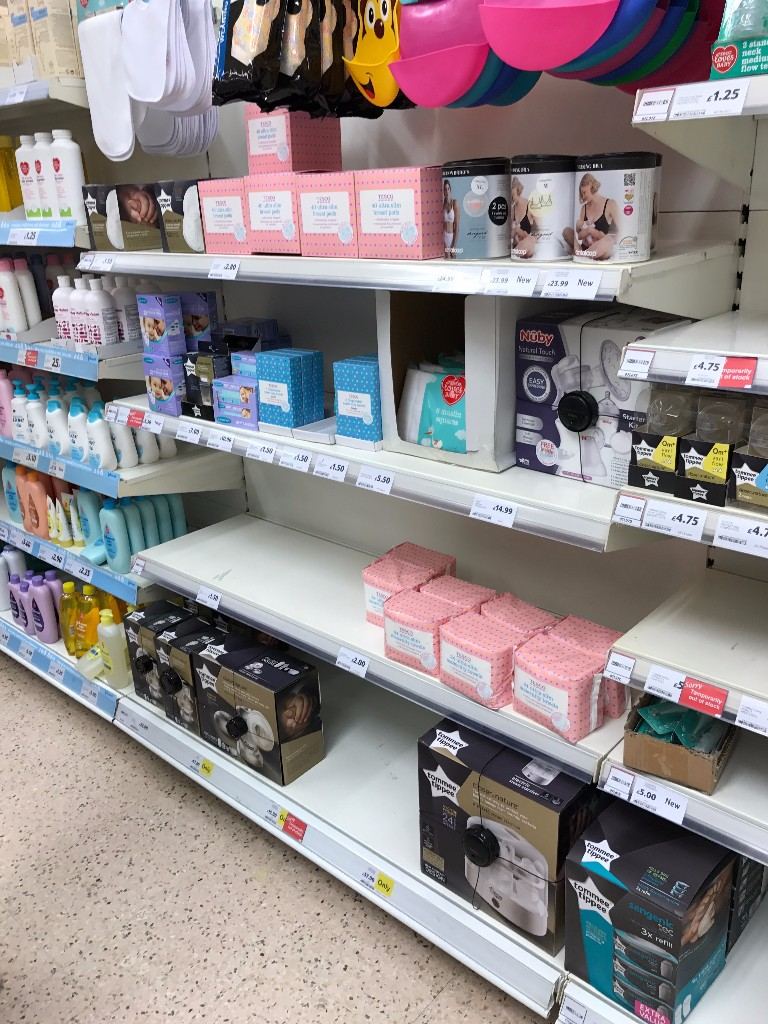
This was a different store, unclear if the range changes were impacting baby or indeed what the issue was really.... I always try to consider things and look beyond the reality of the shelf edge, in order to be fair and objective.
However, equally, your customer doesn't care a jot that there's nothing on sale as the plans are wrong, or the stock isn't coming until tomorrow as the depot fell over, or that you've not had time to implement the plan yet, or that nights are behind.....
It's all internal, important things but it impacts the customer, who doesn't want to be impacted. So the mum / dad shopping here will be ultimately disappointed for baby accessories in this store.
Which is frustrating as the rest of the store was good, and the customer may have visited here for their 'big' shop because the discounters (despite best efforts) can not carry a compelling range of baby products due to their model and size.
So it's vitally important to get right as a category.
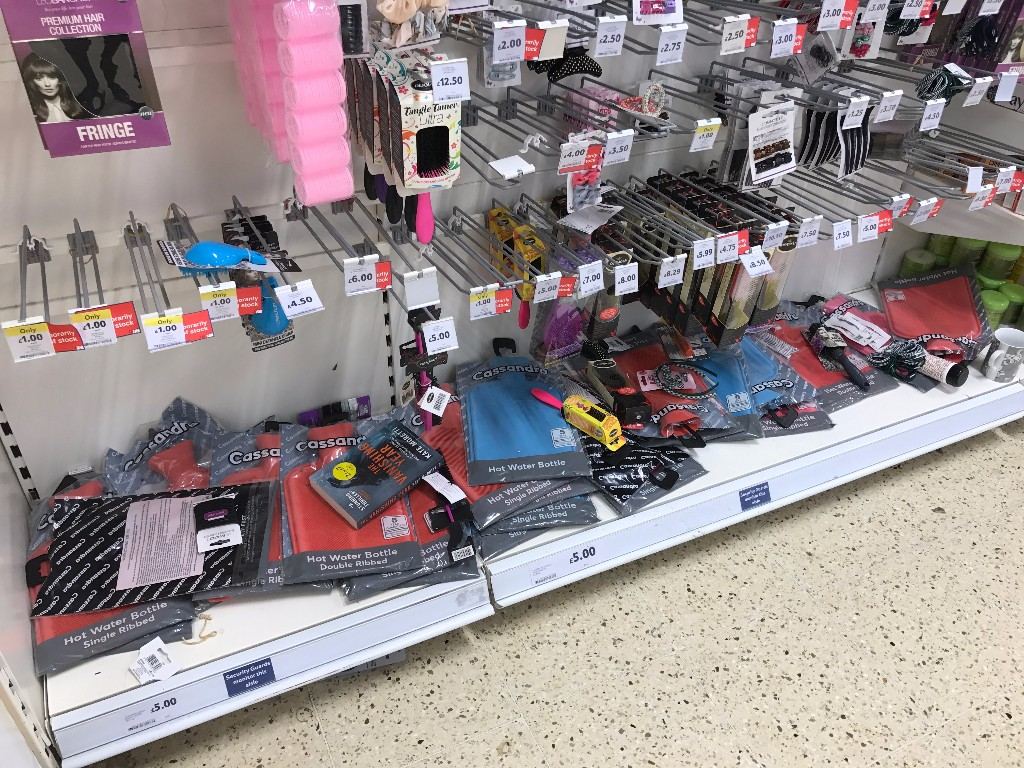
More examples of challenges in these higher margin areas; unclear what's gone on with hairbrushes in this example. Lines missing, general poor standards and another category that is hard to get right, due to the number of lines featured... But moving replenishment around adds challenges and complexity. Yes it reduces cost, but at what cost?
Also with product design, strides forward have been made by Sainsbury's with their 'Home' branding across their entire range, and Asda in fairness who do a strong job on branding non food.. More so than food one could argue.
Yet for all the brilliant work done by Tesco and the strength of Dave Lewis in branding, the non food range hasn't come along at all.
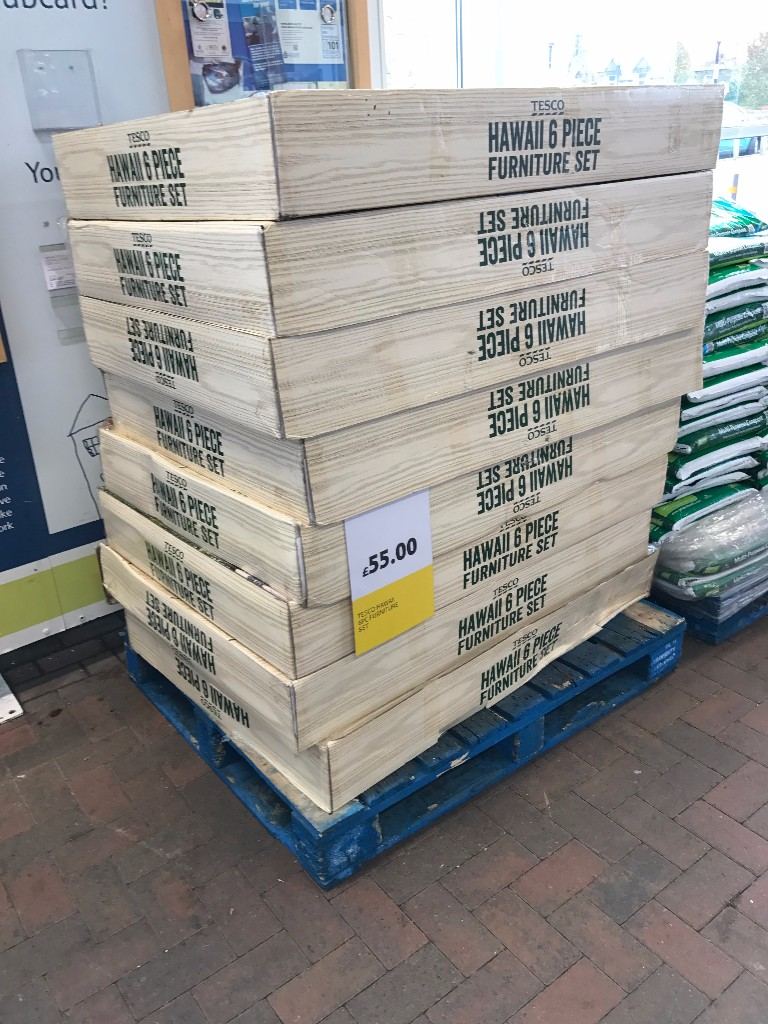
The packaging for this table / chairs hardly screams quality, it looks poor value and like it belongs to a value tier product. The likelihood is that the product inside is perfectly good and represents good value for money, however the packaging needs to back this up, not go the other way.
I think if we consider the wider margin targets for Tesco and the next phase of their plan, which we see coming to fruition in store with the range changes and layout improvements and growth in the small stores.
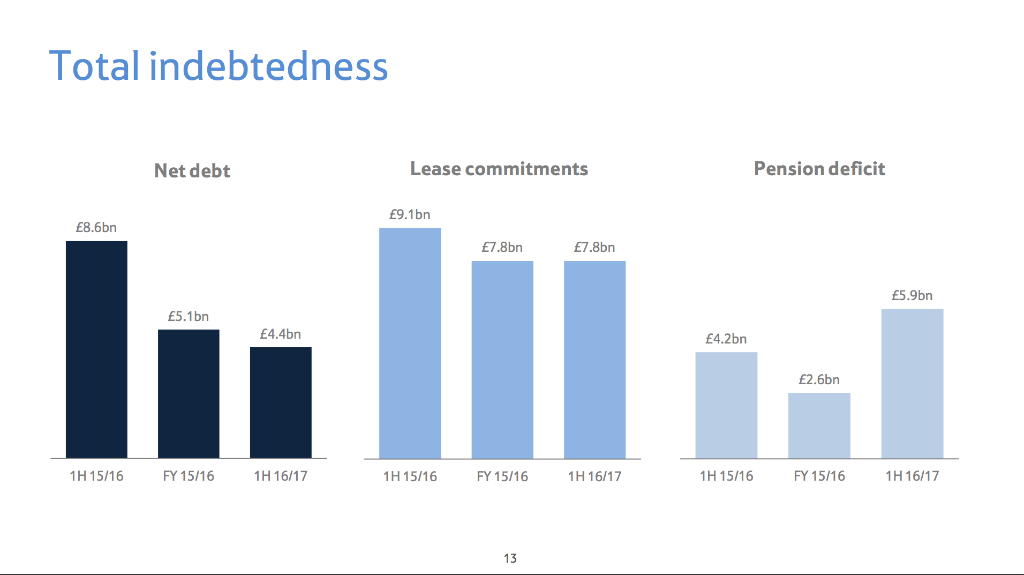
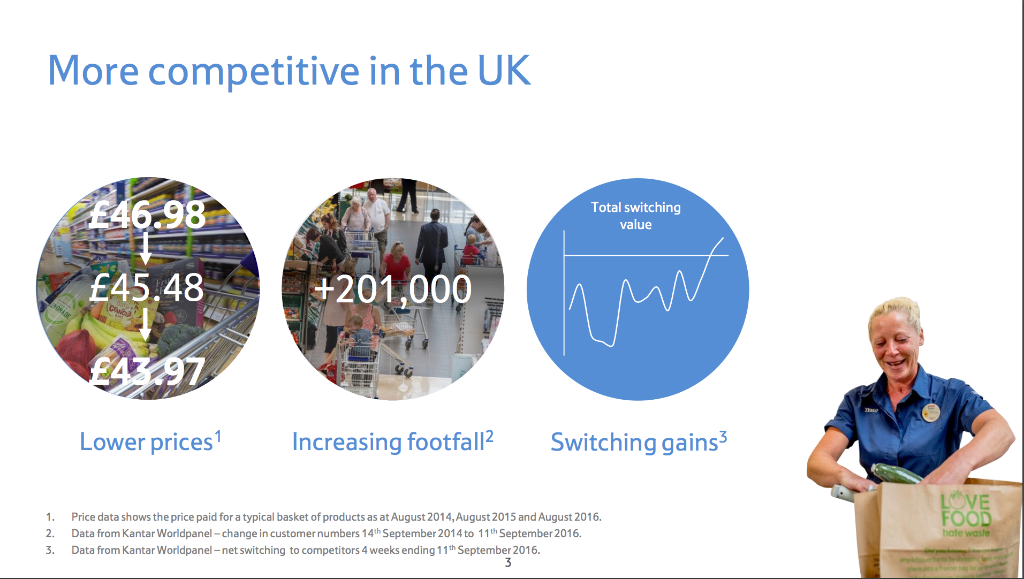
It's important to remember improvements to the core business - lower debt, lower prices and increased footfall and switching from one retailer in to Tesco. Pension deficit on the rise though.
The business was in such a poor state when Lewis arrived that they had to invest and sort the balance sheet, there was so much wrong that the stores just needed investment.
Therefore now, the pressure comes to swing the margin the other way, investment costs money.
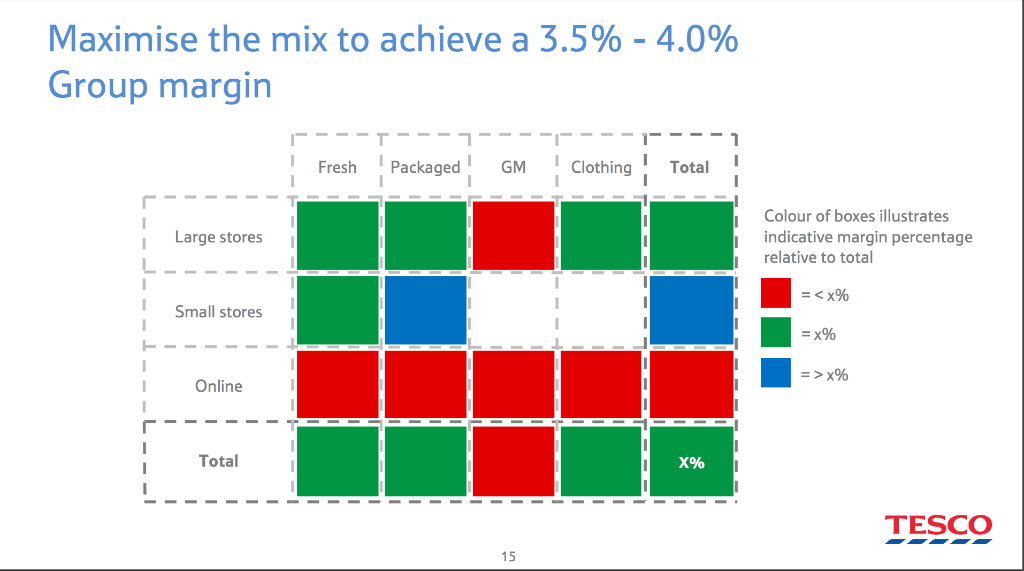
The future margin mix for Tesco doesn't seem to show a bright future for GM in their wider plan, which could explain the lack of innovation within the wider offer.
It seems odd to have such a vast department without growth being plotted or indeed, any of the thinking that has allowed the food business to move forward at pace.
Clothing margin will grow via the partnerships with Arcadia one suspects, they're being dropped in to some large store refits this year.
GM needs something in store, it currently detracts from the stronger overall offer and when customers are in store, a decent non food offer represents a chance to increase the basket spend.
Investments in the price vs. Argos and the click/collect delivery (free in to Express stores still) seem at odds with the standards on display. With online of course, free click/collect and a price that beats Argos is perhaps all you need......
Like all retailers, some good, some bad for Tesco. But it's still very much more good than bad......
From the Grocery Insight newsletter archive, first sent to subscribers on 23 March 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.