Waitrose - the longer term outlook
30 October 2018

Forwarded this email? Subscribe today for more!
Our "Jack's" report is now available!
More to come on Waitrose on the service as their sales continue to suffer in the midst of some tough competition, not just from the mainstream (such as M&S, another one to consider for their recent efforts) but also the likes of Aldi and Lidl who are sharpening up on premium (as we know) but are also opening up in those leafy locations where Waitrose are a mainstay for the customer base....
However discounters open, customers go see and before you know it, some £50/£60k has disappeared from the weekly takings and the ever increasing appeal of both Aldi and Lidl (premium lines, continental events etc) means that there is always the risk that more and more is purchased at the discounters.
This leaves Waitrose (alongside others) then scratching around, fighting over the remaining 25% of the shopping basket, rather than the 80%/90% is once was.
The challenge for Waitrose is that they are caught between a world of being mainstream and appealing to the masses, like a football team thinking back to the glory days. Waitrose Essential with Mark Price was near inspired thinking and filled a gap in the Waitrose offer at a time where they had no presence, or range in the mainstream.
So it was 'easy' growth and the recession did condition customers towards a certain way of shopping, however back when Essential came in to the mix, discounters were not the force they are now.
Certainly, they didn't have the premium range that they do now, which is one that causes Waitrose the biggest headache, alongside their low prices on comparable goods. Especially in Produce where the price gap will be significant, they are still cheaper than the "big four" are discounters...
Whereas Waitrose are regularly 15% more expensive than that mainstream in the Grocer 33 each week.... A real problem.
If you consider a product like Dried Pasta; 55p at M&S, 45p at Asda, similar or lower (depending on what work Aldi and Lidl have been up to) in discount.
Waitrose are 89p.
Unsustainable price gap, so ok, you can not be as cheap given your position in the marketplace but you have essential which is designed to capture value driven customers and then layer on top the premium lines to drive margin.
However it's often hard to find said premium products, the range has improved but often availability is a challenge and some stores are far better than others (as ever). But the picture that a customer sees of Waitrose in Otley (for example, with 3/4 refits under its belt) versus another store that hasn't been touched for a while also impacts.
A nice shiny Aldi, or Lidl with their lovely new large formats, bright lights and premium signage everywhere immediately captures customers attention and 'store environment' becomes another reason alongside the rest to not go to Waitrose as the main shop.
This is why numerous retailers now refit stores actively ahead of Aldi / Lidl based activity, as whilst it's not the only line of defence. Putting your best foot forward in terms of what the shop looks like is a good starting point.
So Waitrose need more premium, more specialism to justify their place in the market really. If they're not going to be the cheapest in the market (no one thinks they should be at 45p for Pasta) but equally you can't sit at 89p and think that customers don't form a price perception of your entire range on that one line........
There are too many deals too; branded lines are often on promotion and the number of deals must outstrip anyone else in the marketplace. They are everywhere and now the signage is 'lovely Red' - they take over the fixture and become near blinding.
It feels like Waitrose need that longer term plan and a degree of bravery in order to execute it. Innovation in store formats, such as Produce is almost a 'given' but nothing has come down the track despite having a store location / demographic portfolio that should encourage innovation and trials.
Food service trials don't appear to have progressed and in any case, these were always going to be limited without a great deal of scale. Very labour intensive when the business should be looking to refine such trials to benefit the wider estate, not just the selected few.
In terms of the business, it makes no sense to run ordinary shops without a great deal of innovation, in terms of store environment, 'reasons to believe' or indeed service (which appears to have been hit to varying degrees by various restructures).
To put yourself on that pedestal of being the Queen's grocer means that the expectation is there from customers. You can charge more for basic Pasta versus the market but you have to justify that with a wider look/feel - like somewhere like Whole Foods may do.
Otherwise you have to cut prices and hope to reclaim the margin on premium lines and other products that inspire and excite the customer. At the minute, it's the worst of both worlds and thus feels inherently defensive.
A defensive premium retailer is a contradiction in terms and it still feels like that shift in shopping isn't being addressed.
If it is being addressed (IE is known about), then there isn't a feasible strategy that appears to offer anything tangible Reducing ranges via BCG is effective work but is littered with risk, the 'tail' (IE bottom 5%) will likely be specialist lines that keep a customer coming in to the store......
Trading wise, they need to reduce reliance on deals from brands. There are too many, it impacts price perception, availability and also confuses the customer entirely...
Any rebates and supplier based monies are nice to have in the bank, but the market has shown you can not build a business from this platform in a sustainable way.....
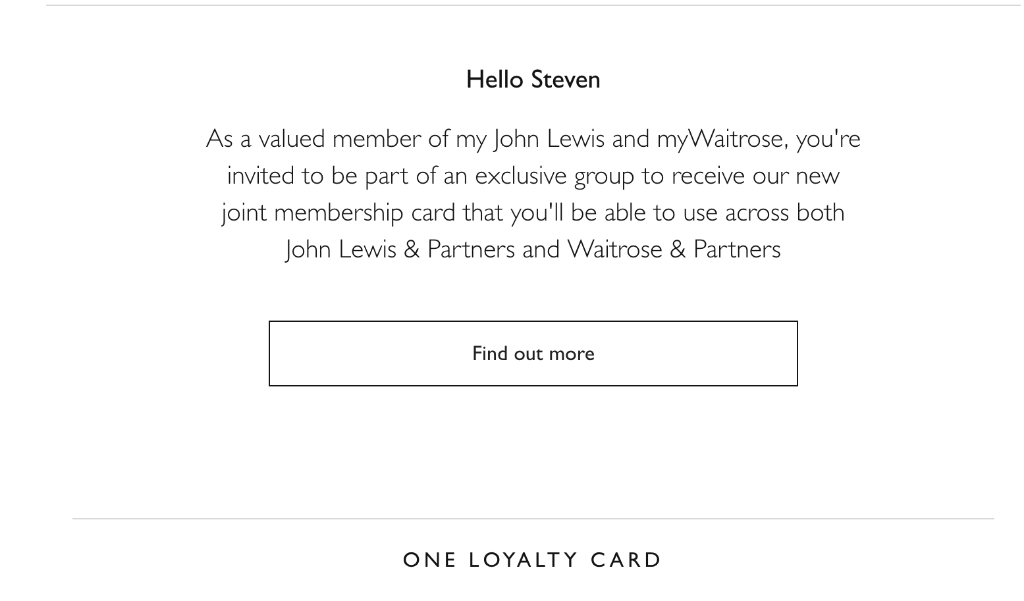
In terms of the joint work with John Lewis; there should be further work at bringing John Lewis in to the Waitrose stores, as it makes little sense to have Waitrose branded lines in some cases when the larger John Lewis brand is far more effective on non food.
An email I received yesterday tells me that the loyalty card can be used in both locations now, I tweeted the image which caused some surprise, both in the fact that you can not already do this and indeed, customers feeding back that they had tried to scan previously and were told they couldn't......
It's a nice piece of work no doubt; however why wasn't it a joint scheme anyway?
That aside, unless it's an IT test so the server doesn't fall over, why isn't this being rolled out to everyone, now? There is no need to really trial such "innovation" as it's so obvious, it should be the case anyway!
More cross selling opportunities will be positive for the chain, but it still feels like the food business needs a wider strategy (forgetting online for a minute as that dominates every conversation)....
For the Waitrose business:
How to counter discount?
What is their price position in the market?
How to get to a place of less deals and more 'lower prices'
Finally - How to be that bit more special? Give customers a 'reason to believe.'
A loyalty card isn't part of that conversation...... It's not easy, but then neither is retail!
Forwarded this email? Subscribe today for more!
Our Jack's in depth report is now available!
From the Grocery Insight newsletter archive, first sent to subscribers on 30 October 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.