Issue 489 - Lidl Prices (13 July 2023) [2]
13 July 2023
View this email in your browser
Retail by Email - Issue 489 - Lidl price(note this is subscriber only content!) Enjoy the read.
Lidl are the latest retailer to be making use of their loyalty scheme / app to offer shelf edge prices, akin to the wider market.
Lidl and their loyalty scheme have been interesting, on the face of it, it’s an additional cost that a discounter would baulk at.
However, they do use it well to drive short term trade, such as free items from the Bakery or various spend initiatives, such as £5 off £50 etc.
Their latest work appears to be centre on the fact that some products are now cheaper with the app. These are own label items and there’s little information about the saving, versus Tesco, or Sainsbury’s for example.
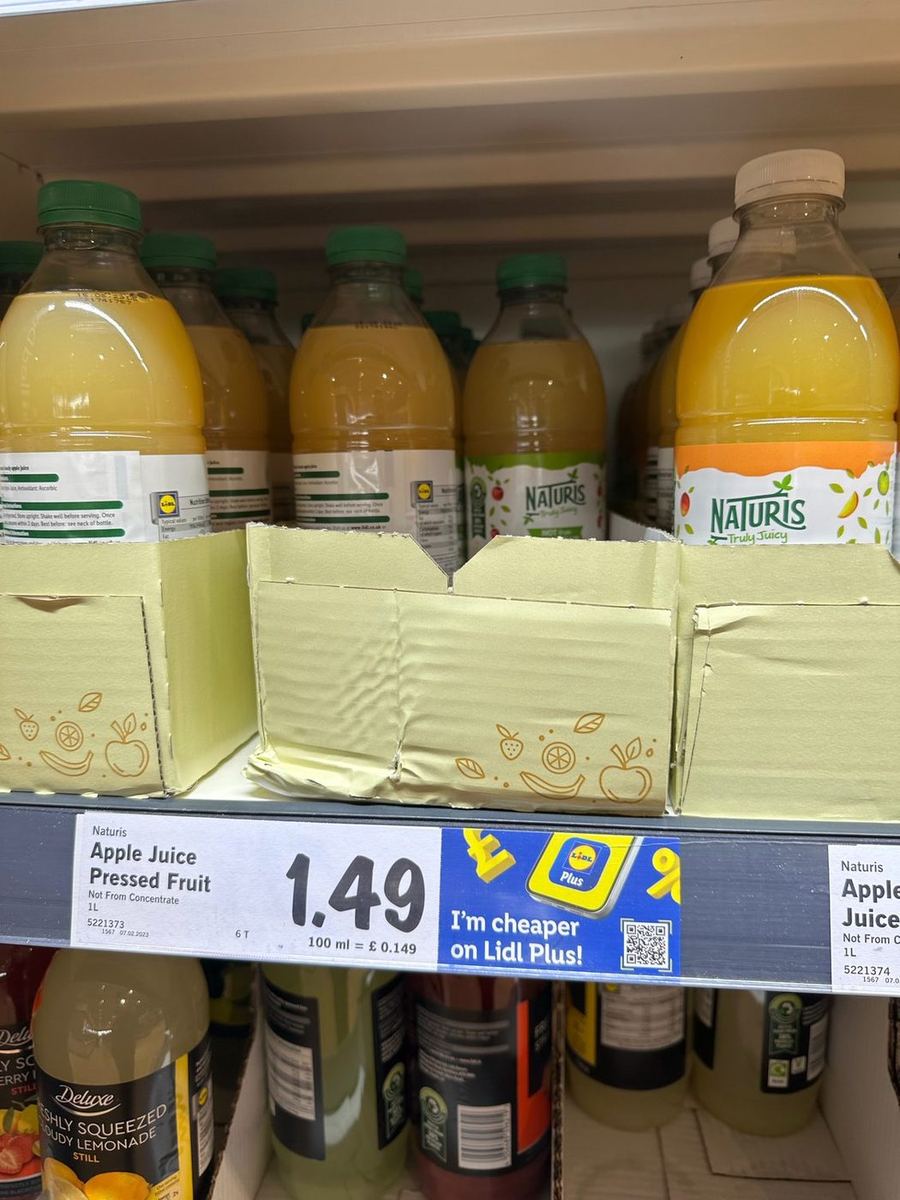
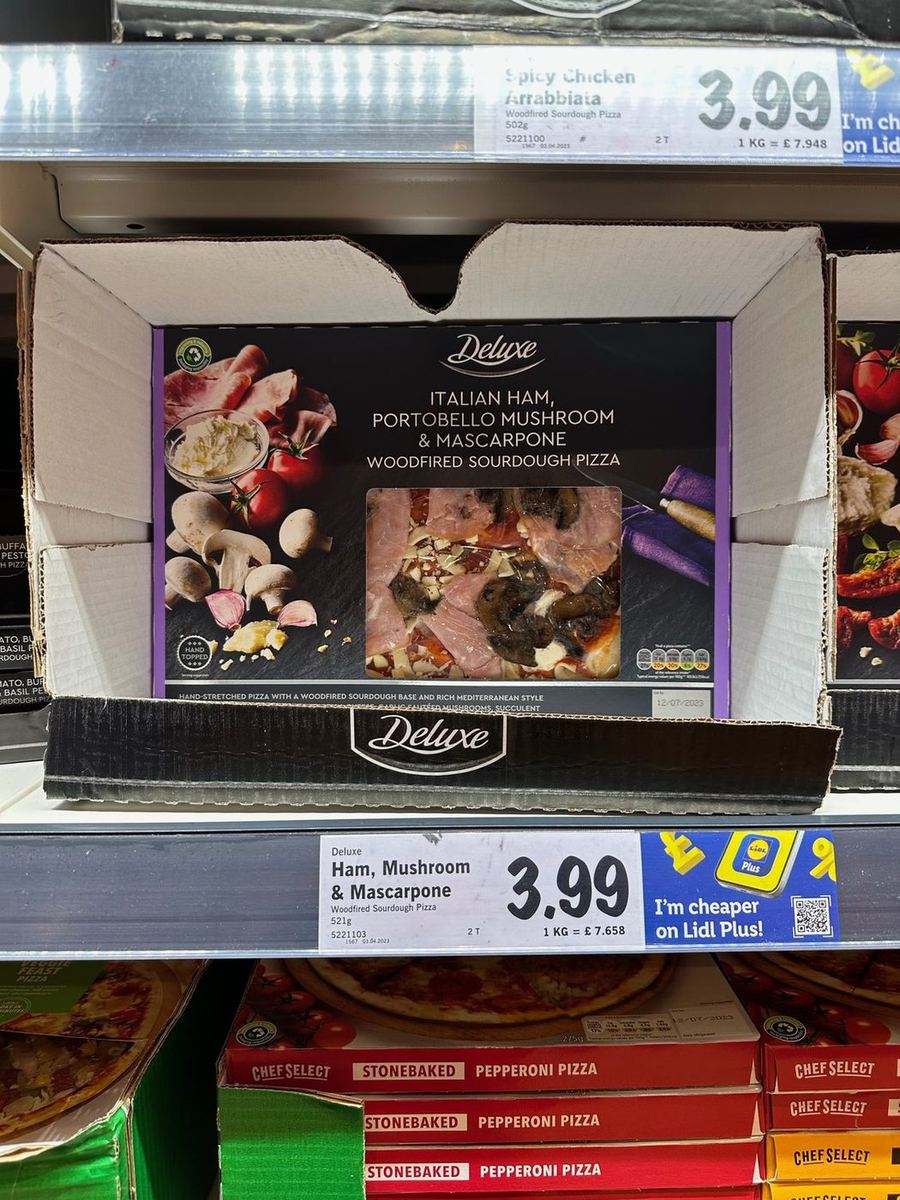
They are cheaper on Lidl Plus! The shelf edge signage is solid enough but does add cost, for a discounter famously tracking every single activity in store.
Loyalty only pricing is a useful tool and savvy customers will be enticed to use the app to see what the loyalty price is. Thus using the app more often to benefit from the scheme and drive loyalty also.
Any loyalty scheme is about the users, the more users you have, the more useful the data is. Too narrow and assumptions made about purchases could be a due to a freak in the sample size.
The Lidl app certainly has plenty of incentives for customers, and remains an interesting tactic given the focus on simplicity for discounters.
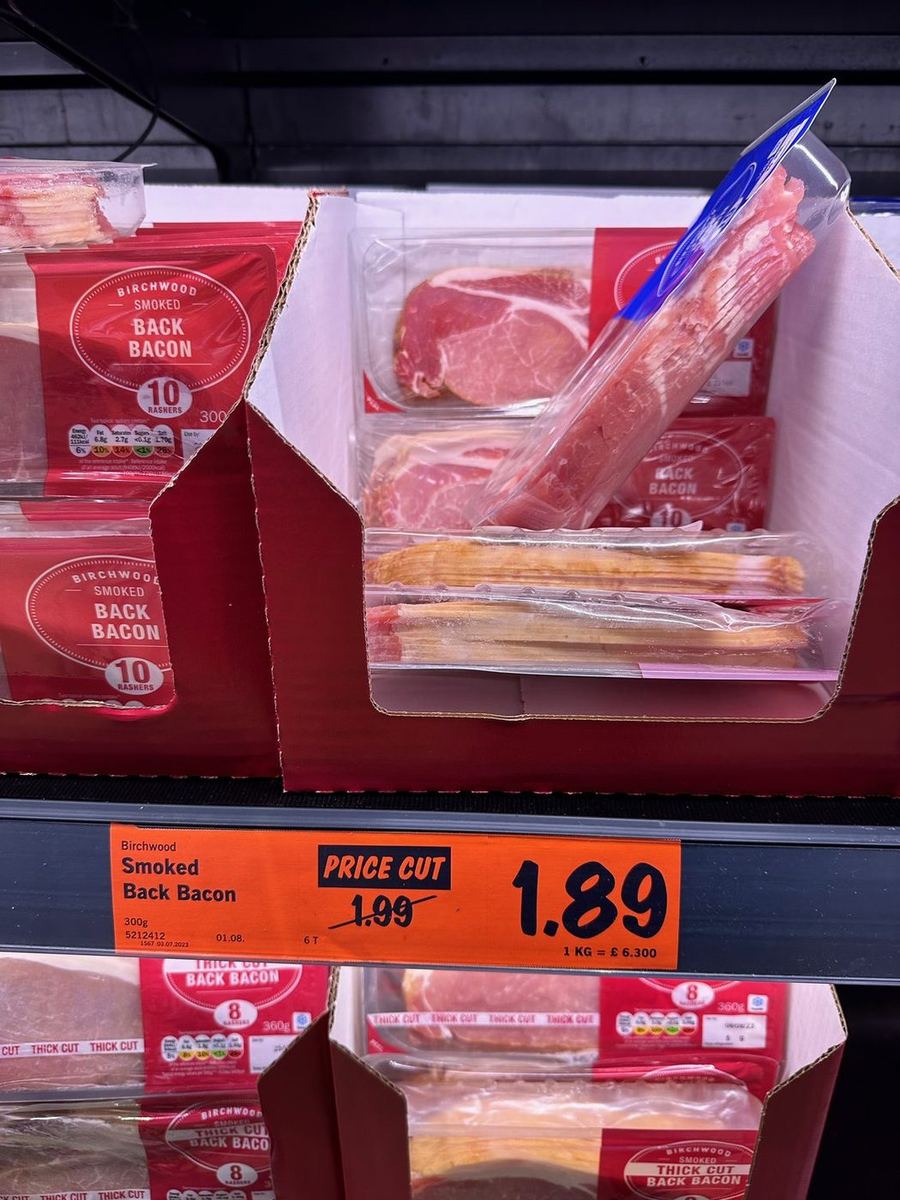
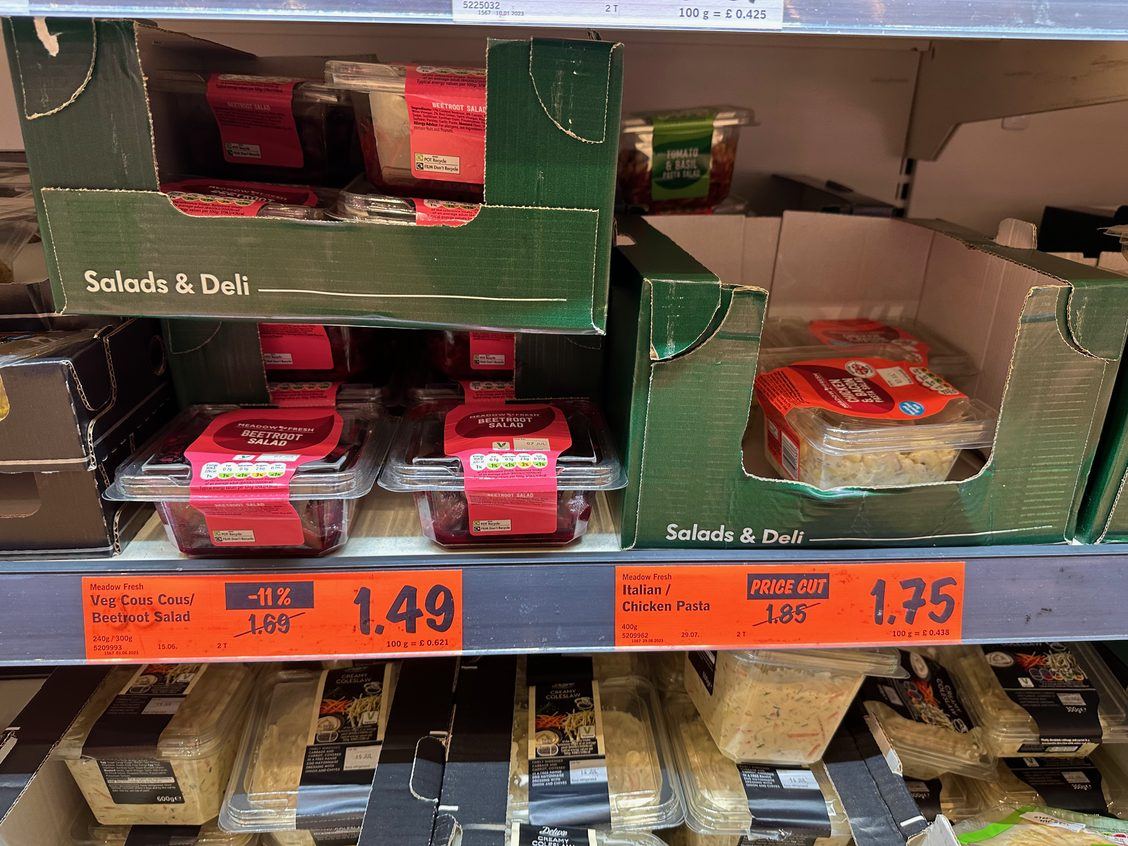
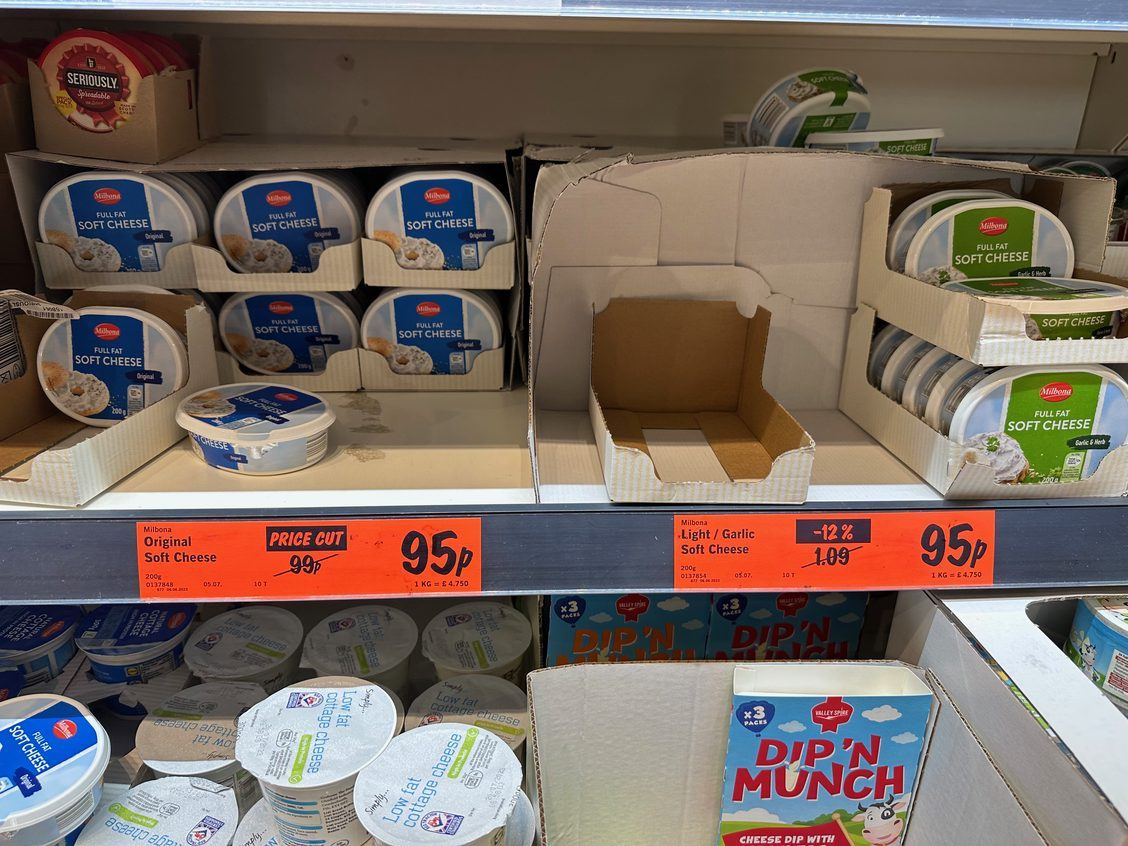
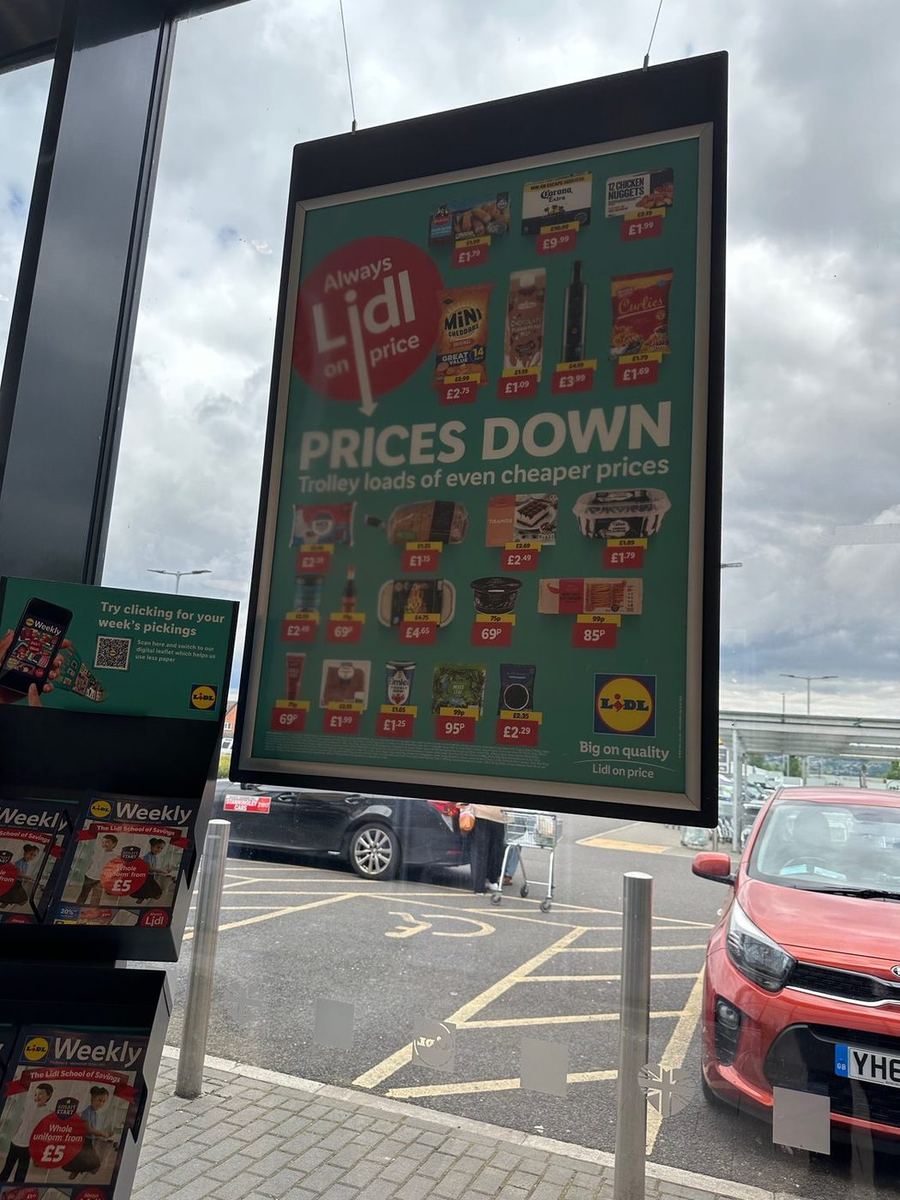
As the price war rages on in the market, inflation doesn’t feel as though it’s falling enough to have an impact on consumer spending.
Coupled with the mortgage rises that everyone is going to have to mop up in the coming months/years, it’s hard yards for everyone.
There are detectable signs of prices falling; but prices remain much higher than they were. Which in the trade makes sense, given the supply side shocks and higher input costs across the piece.
However, for the customer. They’re likely to keep feeling the pain for a number of months yet and as food falls back to a level that’s manageable. Mortgage costs, the prospect of energy price rises in the winter etc all come in to view.
It’s tough and will only get tougher for many out there. Discount remains well placed to capitalise (Kantar shows us this) but their value driving efforts will continue apace.
They’ll be desperate to be seen as the ones to first cut prices, to expect many more orange labels around aisles of Lidl.
The key difference versus the last economic slowdown; has been that both Aldi and Lidl have raised prices this time. Clearly the cost price increases have been significant, everywhere.
Whereas last time, when they were establishing themselves in the market; they were much happier to sacrifice margins. It’s a drawback of scaling to such a size of course.
Any impact on margin is multiplied significantly when you’re purchasing at the volumes they are now buying, due to their size.
 How can we help you understand the retail sector?
Subscribe to this industry leading service, today.
From the Grocery Insight newsletter archive, first sent to subscribers on 13 July 2023. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.