Apologies and Updates
13 April 2021
Enlighten your inbox, join today.
Why not visit our new website?
Firstly, apologies for the radio silence.
We have had a new baby!
Penelope Esme arrived safely back in February and, it was a strange pregnancy throughout, with lockdown bookending things and the closure of non essential meaning everything was purchased online.
Indeed, after the loss of Belle last April, it was a pregnancy where literal eggshells were walked upon, but, she arrived, finally, safe and sound and both mum and baby are doing really well.
As we circle back to retail and events within, plenty has occurred with John Lewis laying their weapons down in favour of an online offering that is anything but slick.
In addition; the opening of non essential retail today means that the high street gets a welcome boost, albeit without Debenhams (lest closing down sale), John Lewis (selected locations) and Topshop, Topman and Burton (et al).
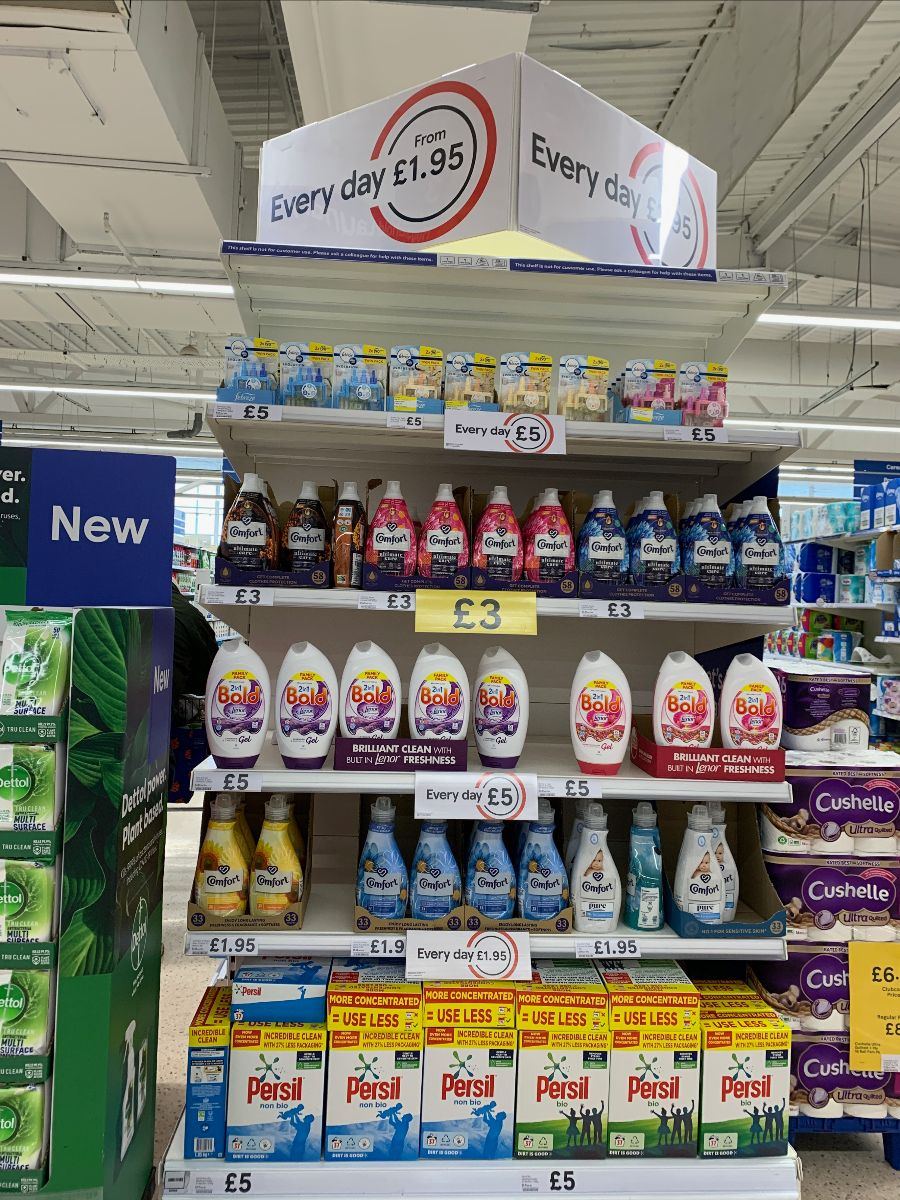
Tesco have also been making price based moves, enhancing their Aldi match by highlighting their work to combat discounters with the various price matching that has gone on for 2 years or so, indeed, their official Aldi price match launched just before COVID kicked off.
However in other branded categories, they have been reasonably desperate to get off the promotional drug and highlight their EDLP work. Indeed, the advent of Clubcard prices means that Tesco can get shoppers to give their loyalty data in exchange for special deals, this (in theory) will allow for better, more tailored deals instead of the scattergun approach that we see elsewhere.
Indeed, even the core multibuys that customers will know, and love, like 3 for £6 in ready meals are changing to be Clubcard only. Further enhancing the message that it almost defies belief for customers not to have a loyalty card with Tesco.
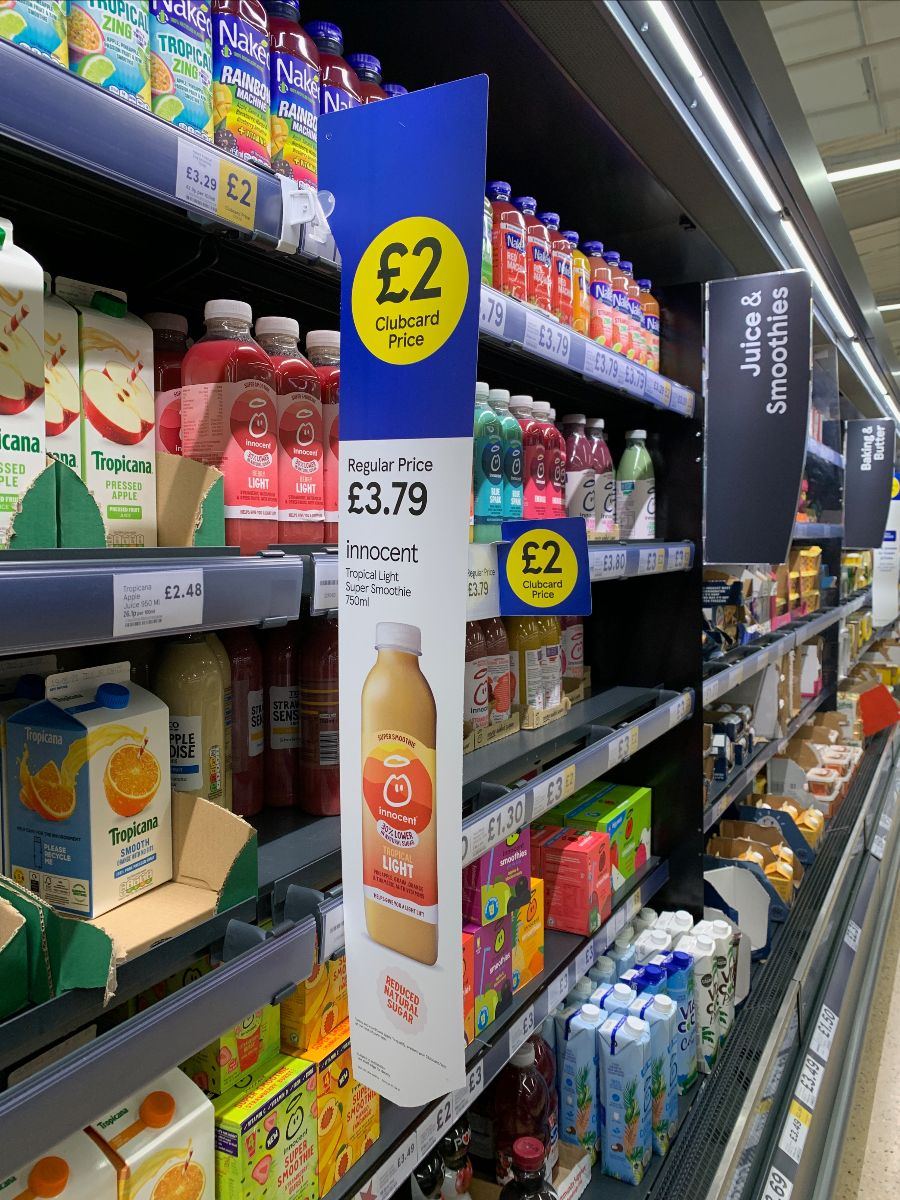
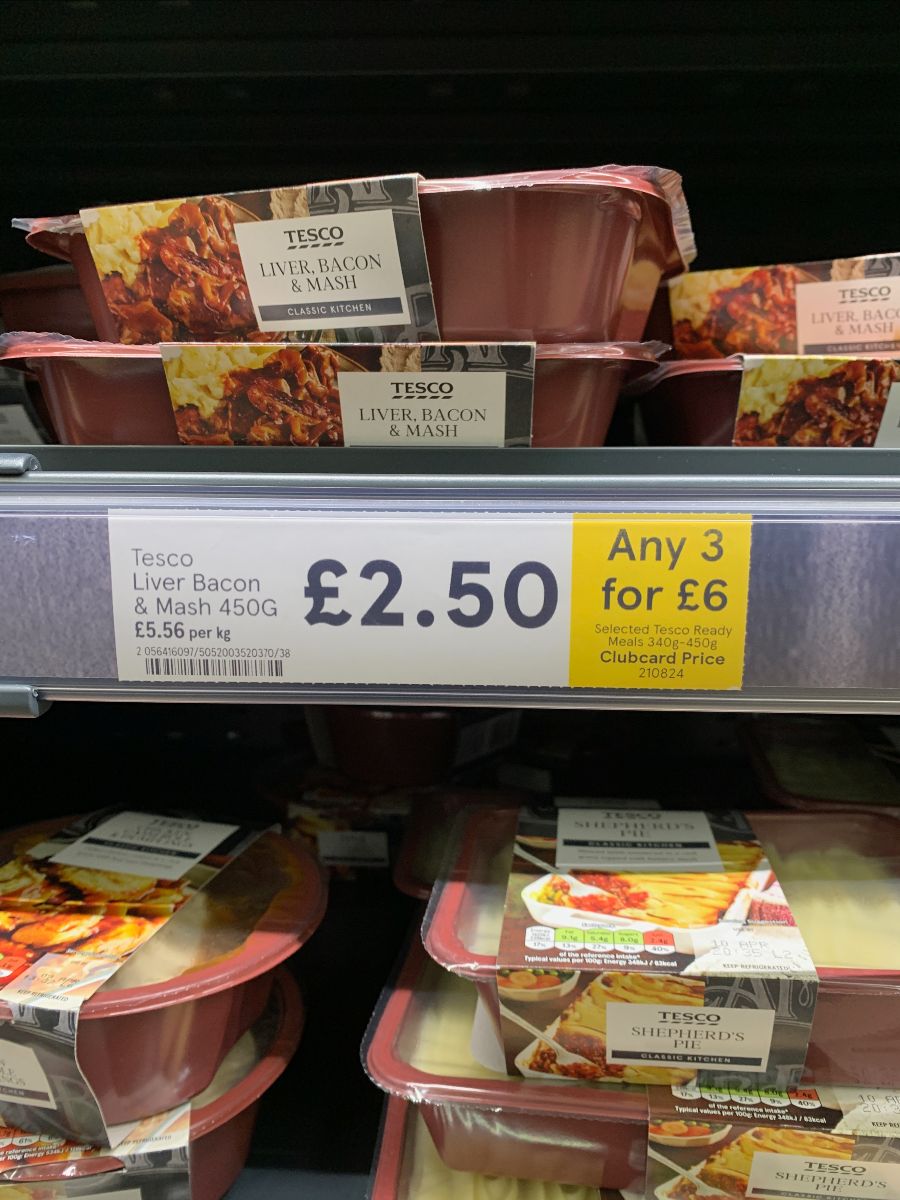
The movement of core deals to Clubcard prices, alongside everyday low prices in Household, and Pet means that there is something for everyone at Tesco. Even if you don't use a Clubcard, you can still access the low prices (generally) but also, the Aldi price matched lines.
One interesting element of the Tesco v Aldi matchup has been their development of the sub brands in value, that JS mimicked, of course before launching their own scheme in the same vein too.
If we look at Ireland, where the plan was incepted, the matching was done on core, mid tier products versus discounters, with Finest amplified to further drive margin if customers wanted to escape the price matching in mid tier.
Tesco UK went on the value tier and forced Aldi to bring their own label down to be equivalent of value, which could have caused confusion for some customers.
The latest move by Tesco has been to remove Boswell Farms (beloved by the farmers, as well, it didn't exist as a farm) and replace it (at the same Aldi price) with their own label, mid tier product.
Thus simplifying the range from a retail viewpoint and also, for customers, meaning that value is incredibly strong for the mid tier, own label product in this category, driving a halo effect for the brand, overall, one suspects.
It's interesting to note whether this aggression against the larger retailers (Asda, JS, Morrisons et al) is driven by Ken Murphy, the new CEO. Already, the decision to move first and hand the business rates back (Tesco paid a dividend due to the sale of the Far Eastern business etc) but it certainly put their biggest competitors on the back foot....
In addition, after Sainsbury's spend time and money mimicking their offer. The shift to mid tier now merely amplifies the Sainsbury's comparative price in Red Meat on these lines. Not great, at all.
All eyes to see if this strategy expands to other areas of Fresh, where, the farm brands were the biggest salvo against discount (ever) back in 2016 when they launched. Indeed, Produce, due to the seasonality changes often sees products switch in and out.
But en masse? The move in Red Meat is the first real sign of Tesco own label becoming dominant and enveloping all of the volume here. Almost a reverse of the Mercadona model - that is, where the own label and brand are ranged, once the own label reaches 60%, the brand disappears.
It stands to reason that a similar element has occurred here and the own label is the beneficiary, especially at those price points.
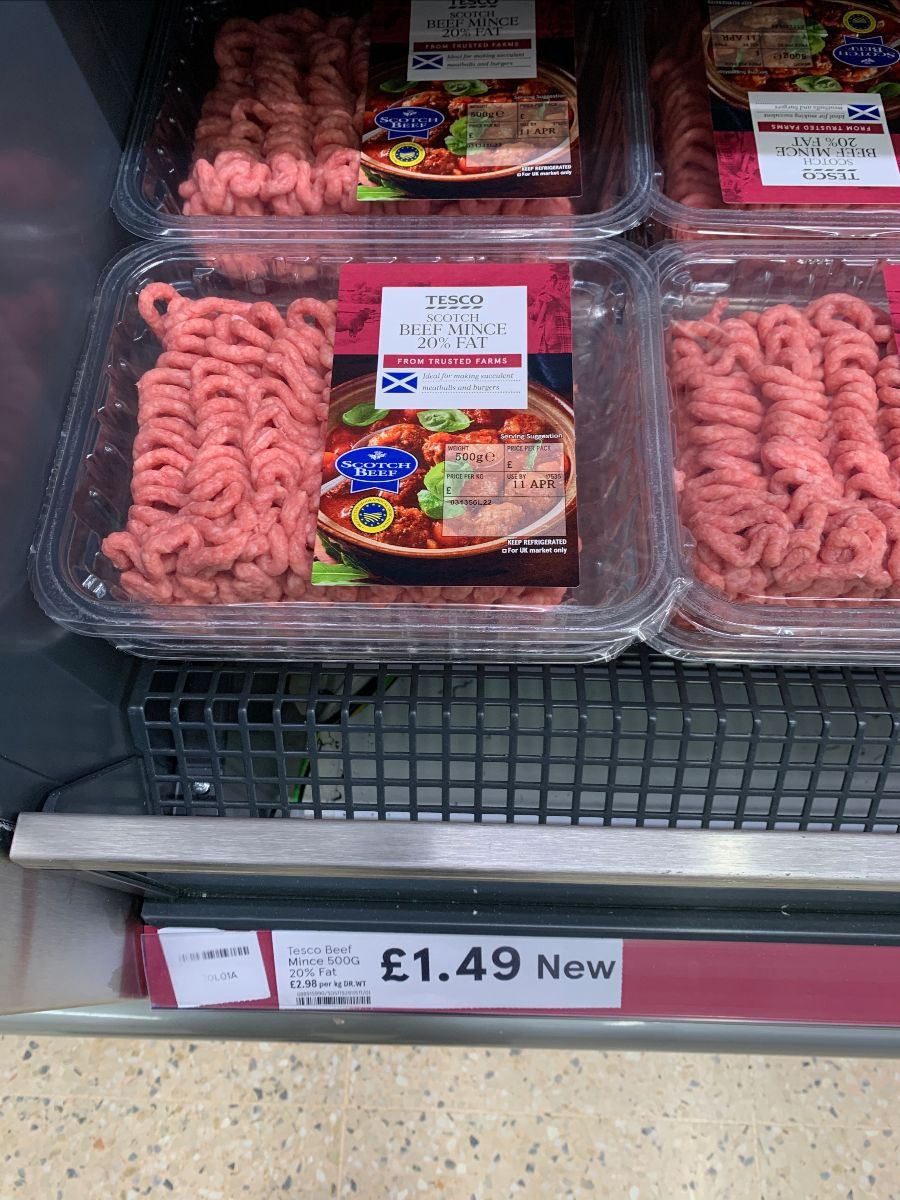
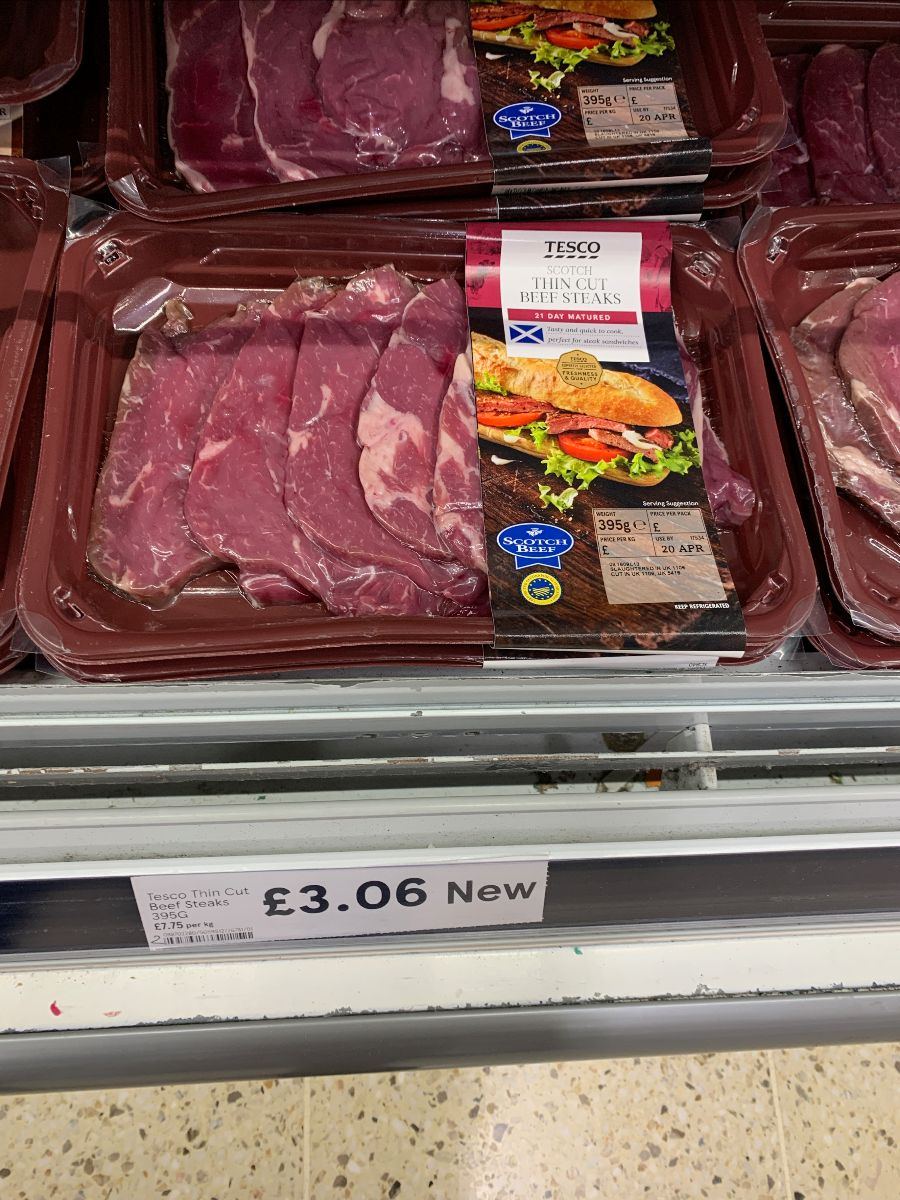
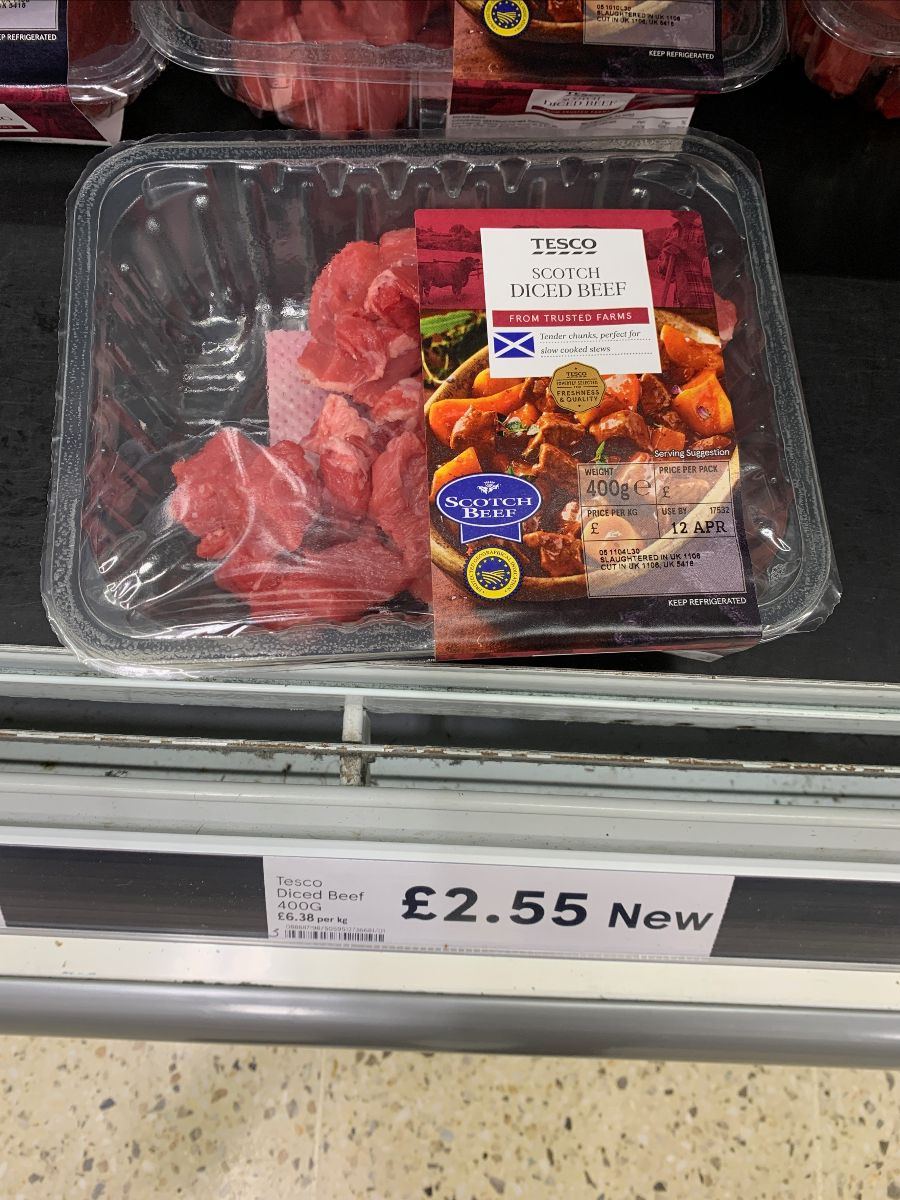
Former Boswell Farms product, now rebranded in the Tesco own label, mid tier. Same price as previously.
More interesting times ahead, but this is a strong move by Tesco and one that we will likely see more of, given their success versus Aldi on the price front.
Indeed, Kantar has played out that Aldi continue to lose out on a sales based basis, even with a meagre online offer, Lidl have zero online and continue to outstrip them (albeit, adding space too).
From the Grocery Insight newsletter archive, first sent to subscribers on 13 April 2021. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.