Asda - Takeover complete
6 October 2020
To subscribe to this service and benefit from our expertise
Asda - New Ownership
With the news that Asda have returned to British ownership after 20 years with Walmart, attention rapidly turned to the two brothers from Blackburn who were able to put a bid together, with help from TDR Capital.
As is traditional for the British, stories appeared about how their Euro Garages based business paid no tax for two years alongside several accusations of tax havens and all that goes with it.
In addition, several articles were highlighting their appreciation of debt and in particular, how much debt there was on the firm.
Not a huge issue, given debt, can mean you're able to acquire things when you want to when they're available. In which case, the Asda deal makes perfect sense. In addition, the EG group is huge and spans a number of countries too.
Consideration has to be given towards the selling party too, Walmart retains a stake and they had no interest (clearly) in selling their ownership to a company who would split the firm to an operating and property company, increase costs (over time) and then exit the business.
Thus the deal is structured as it is isn't a reflection on Asda, or the wider EG business. Rather, perhaps a reflection on the economy and the UK marketplace, which explains why Walmart was looking to reduce its stake in the first place.
The economy is not in a great place and if one recalls, the sale was actually postponed at the height of COVID given the difficulties in getting people together, alongside that, it was a lower priority than simply surviving the pandemic and all that went with it.
In addition; the market itself is not ideal for the UK. We are built out and up, as Walmart themselves noted hence the opportunity for growth is sorely limited. There is growth in online, however, this is expensive as retailers are rapidly finding out (if it wasn't known already!)
Discounters, despite flatlining (by their standards with COVID) remain the force to be reckoned with and their offer, overlapping geographically with Asda in the north (and increasingly, south) means that competition is fierce. Especially given their low price credentials versus Asda, who have a similar mentality of course.
Convenience is the major opportunity one feels for Asda, they have no presence here and it's unwise to try and build a chain from the ground up (sites just are not available en masse and there is ample competition for any that are) as Morrisons found out to their cost in previous times.
Therefore, the petrol station network is ripe for opportunity and growth, especially given the rise in service station style offerings (see Ireland for example) alongside EG's own offer which often brings Starbucks and other fast food outlets together.
EG has expertise in this area as we know, and Asda themselves have tried to expand their petrol station kiosk stores and merge click/collect offering with lockers and other services.
The more interesting element is that Asda recently landed a trial with EG to supply their products and expertise and run the store in 3x EG sites around the country. Indeed, EG had 6-7 stores on trial with Sainsbury's previously, with their 'Sainsbury's on the go' offering.
This would allow Asda to gain volume growth if such a trial grew to feature more sites, plus it would enhance the EG offer as well. The criticism of anyone who is able to pull off a deal of buying a chain like Asda, without leveraging the retailer (as many other deals would do) isn't right.
Low prices will underpin the further recovery and growth for Asda. The new owners will hope the price they paid Walmart turns out to be a bargain.
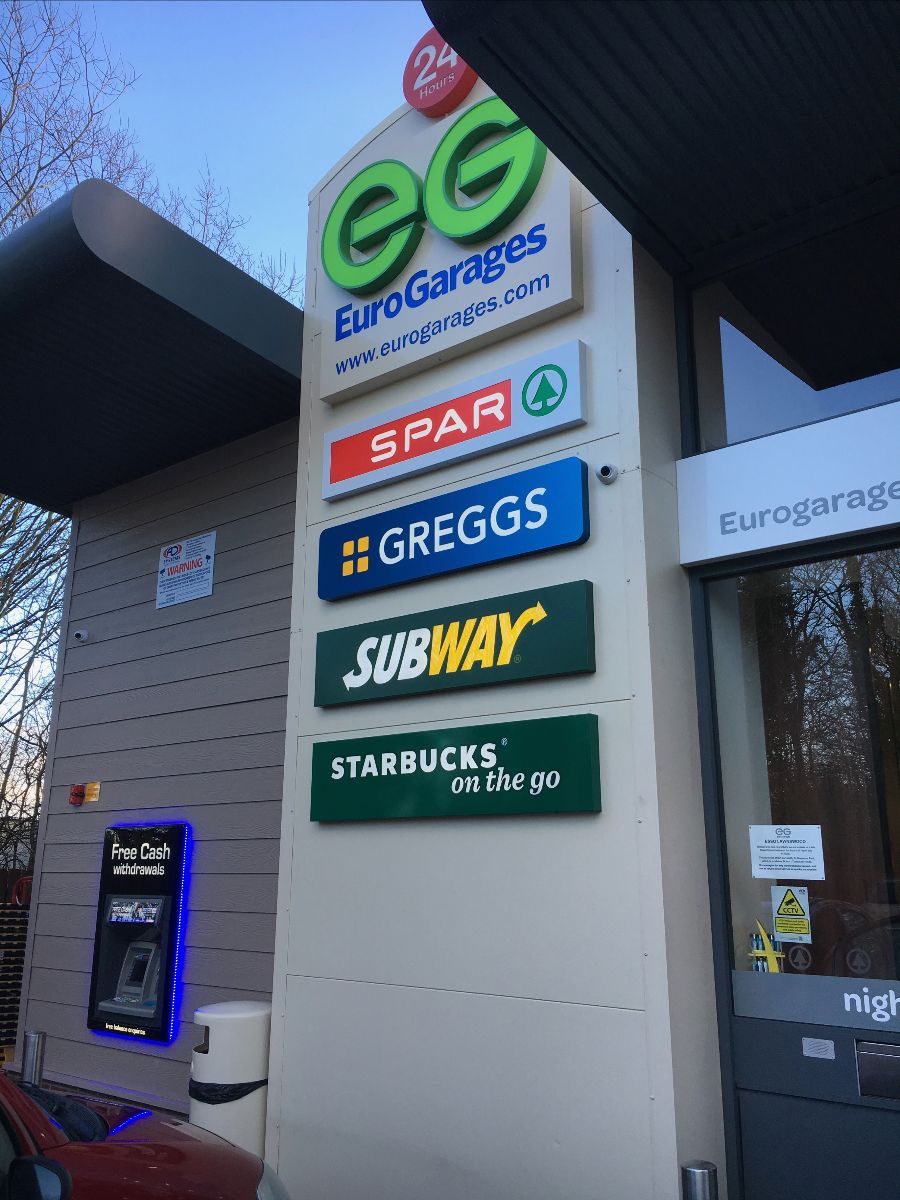
A typical Euro Garages site will share space with a number of other operators who are leading fast-food chains. This opens up huge possibilities for two things:
a) Asda to supply the stores, replacing Spar, Morrisons Daily and other franchise operators. Allowing them to benefit from the volume growth here and share expertise between the two entities.
b) Allows existing 3rd party relationships to potentially build out existing Asda petrol station kiosk stores, alongside using 3rd party fast-food operators etc to open up space in Asda stores, where it warrants it.
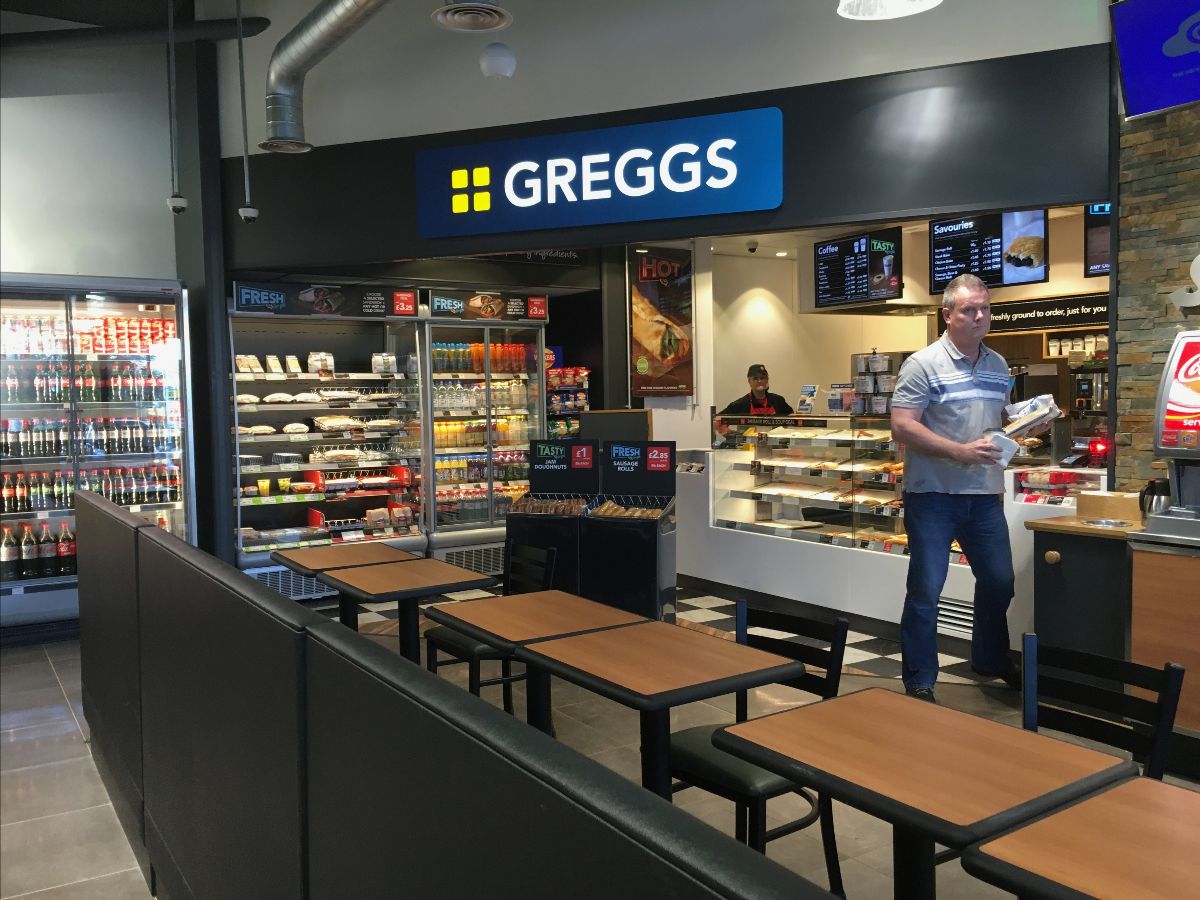
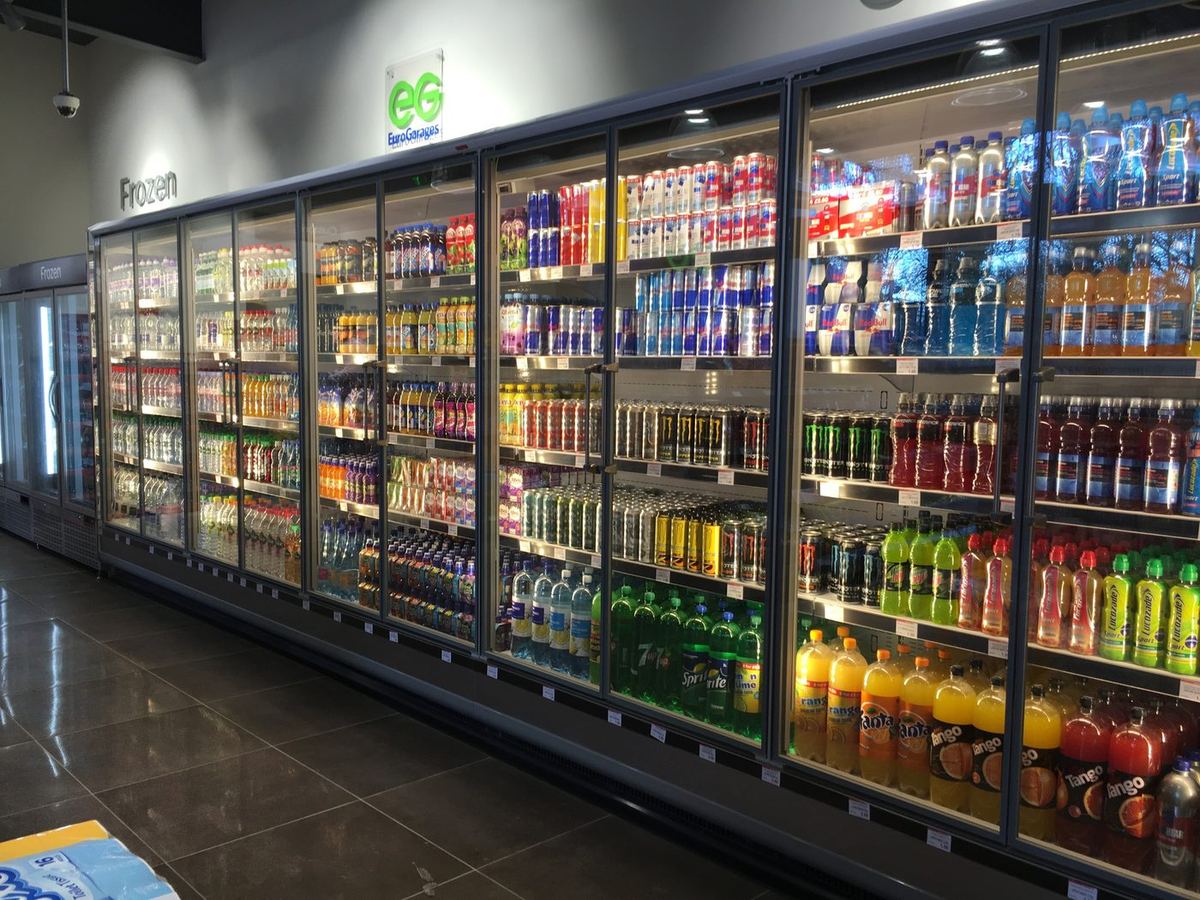
A typical Euro Garages site is well maintained and features a fair variety of services, there have also been moves in to larger operations/sites, similar to the ones in Ireland.
Considered a strong operator and there are more obvious synergies here that will grow volume and value for shareholders, and the entities within, without one party losing out. Which is perhaps the accusation that stood up when considering the Sainsbury's deal.
All eyes on the £1bn investment now, and where that is to be spent over the next three years, but a nimble Asda, freed from the Walmart shackles and requirements could well see more investment and ability to deliver more tactically based trade deals.......
More to come, no doubt, but a fascinating deal, all eyes on how this one plays out across the market, both big box but also convenience & fuel.
From the Grocery Insight newsletter archive, first sent to subscribers on 6 October 2020. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.