Shortages and wagons
23 December 2020
To subscribe to this service and benefit from our expertise
With the number of wagons growing from 150 odd at the govt press conference to over 1,000 within 12 hours, it seems we have a larger problem than we perhaps anticipated in terms of the channel crossing closure.
Of course, there is never a good time for any disruption to supply chains, well honed ones especially, aided by the single market and enabling just in time supply chains to become reality. With all the savings on waste and improvements in working capital that this brings.....
The reality is that Brexit aside, this is not good news for the sector in terms of movement of wagons, both in terms of empty wagons going back over the channel and the ones that are coming over the channel, with stock on them,
The challenge, as raised previously is that when stock finally arrives from France, it will have lost shelf life and worst case, is that the wagons arrive as stores are closed for Christmas Day, and Boxing Day too.
The volumes do remain relatively high between Christmas and New Year, but the stock needs to arrive in time for it to be picked, placed on to a wagon and then leave for the store - this takes time.
Supermarkets try, as much as they can to avoid 'milk runs' where a truck will drop off 1-2 pallets of product at each store, so time is very precious indeed.
As noted today - the empty wagons going back, but currently stacked up are as important, given their refrigerated nature and finite nature. As a driver, who is going to risk the next run to the UK, where they could be left on a disused airfield due to no deal....?
Air freighting is always an option but it's cost prohibitive in all truth, would erode margin too much to the point of pointlessness.
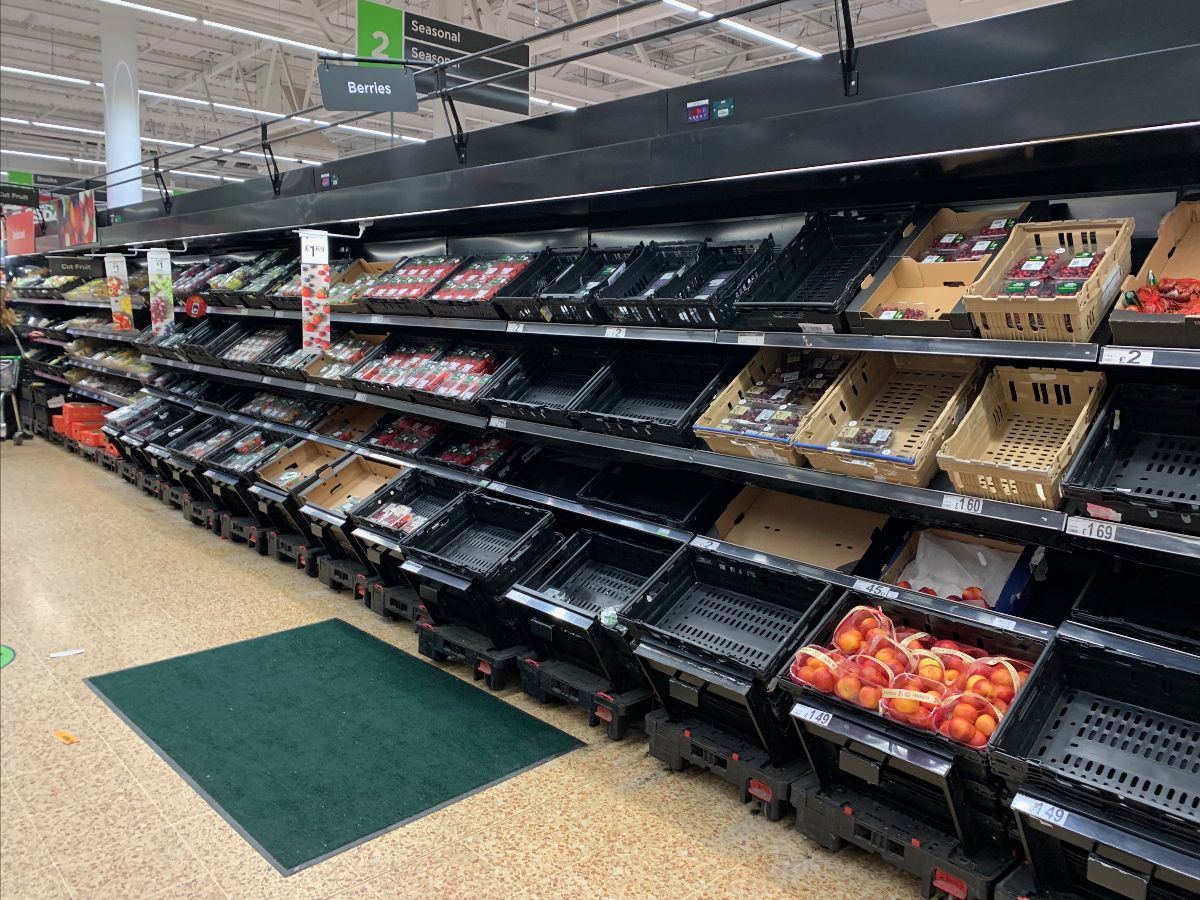
In Asda yesterday morning; only gaps that were noted were on soft fruit and stone fruit, both heavily imported, naturally, given the time of year. There were enough Strawberries and Raspberries though and the store had been through (and was still going through) some pretty intensive online picking as well.
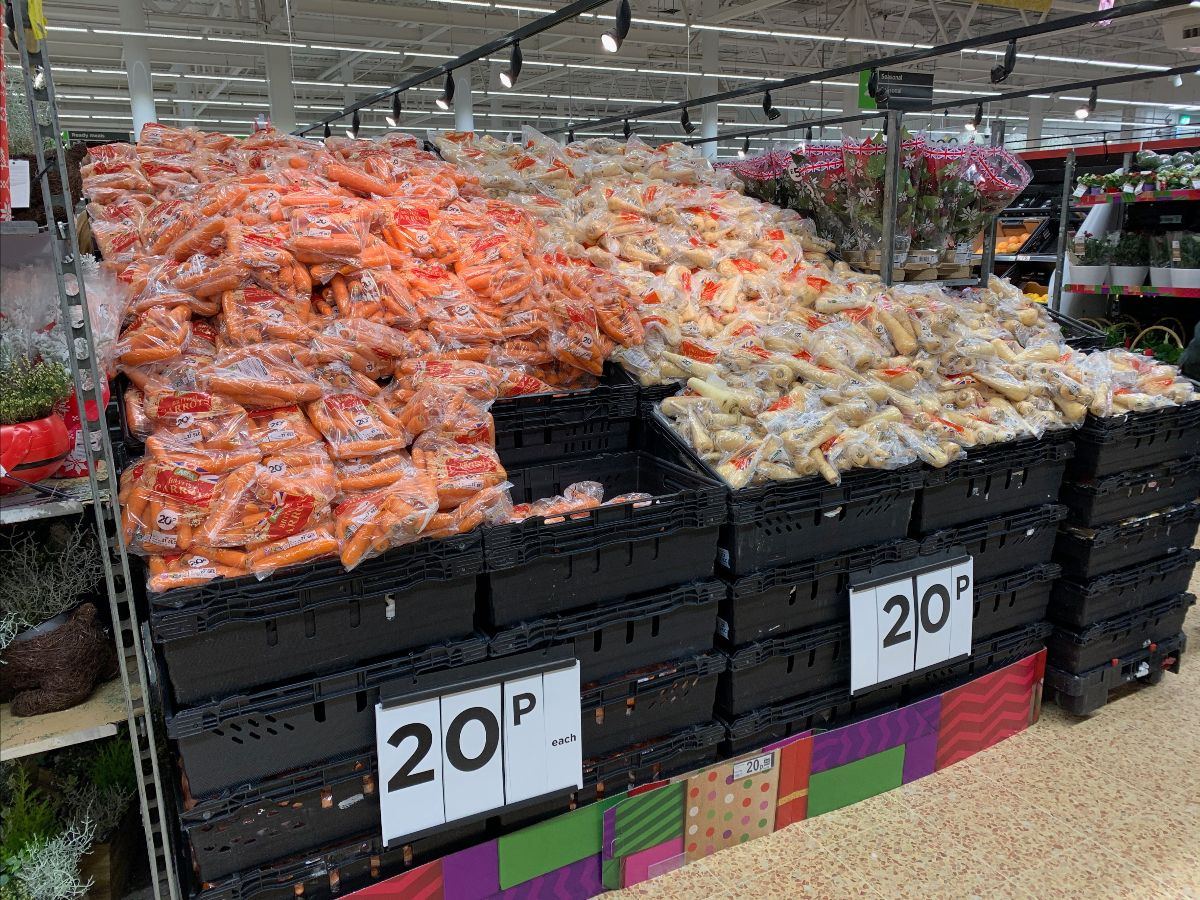
Gaps such as this near Christmas are not uncommon, even without border disruption, as other produce can be prioritised given the seasonality of Christmas and the shift in trade to other lines (namely Root Veg) which is 20p in Asda. 19p in Tesco and then 14p in Aldi and Lidl.
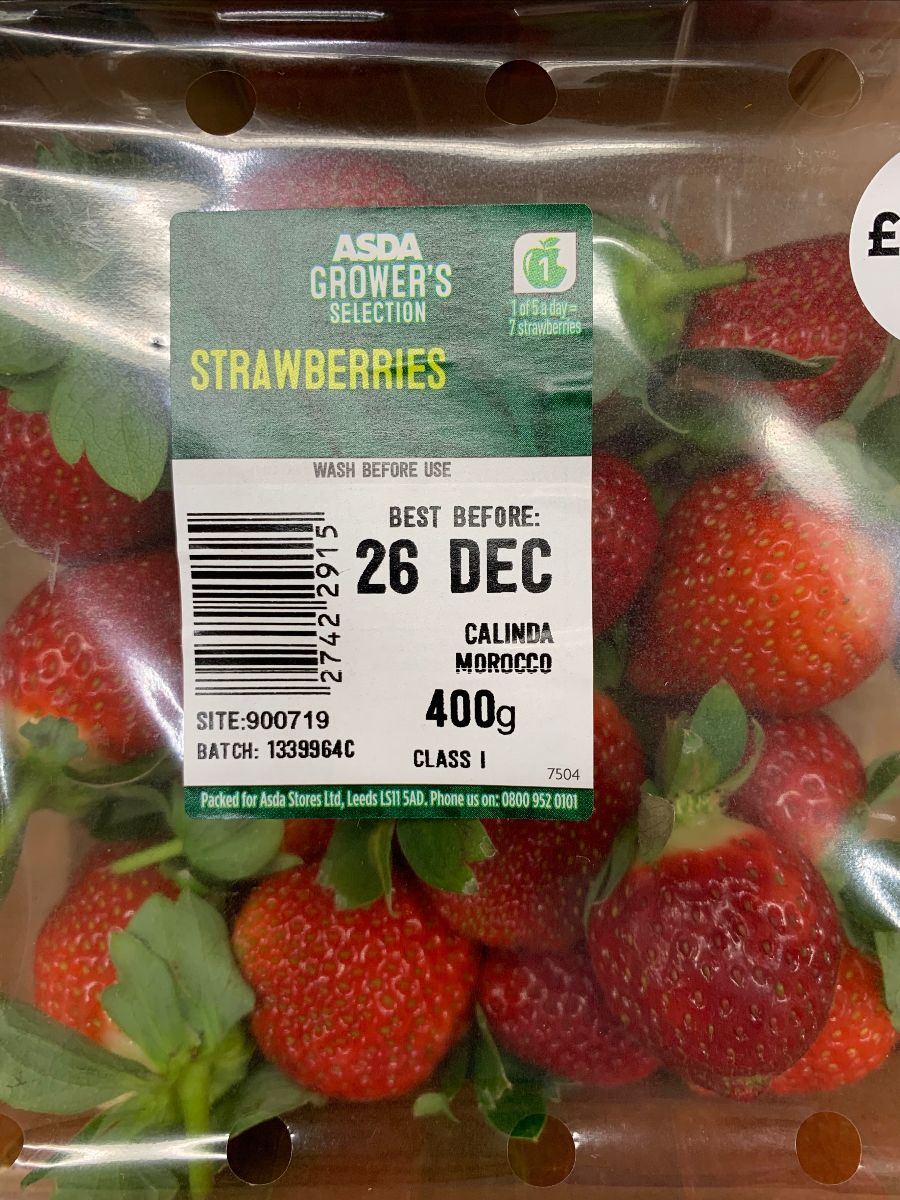
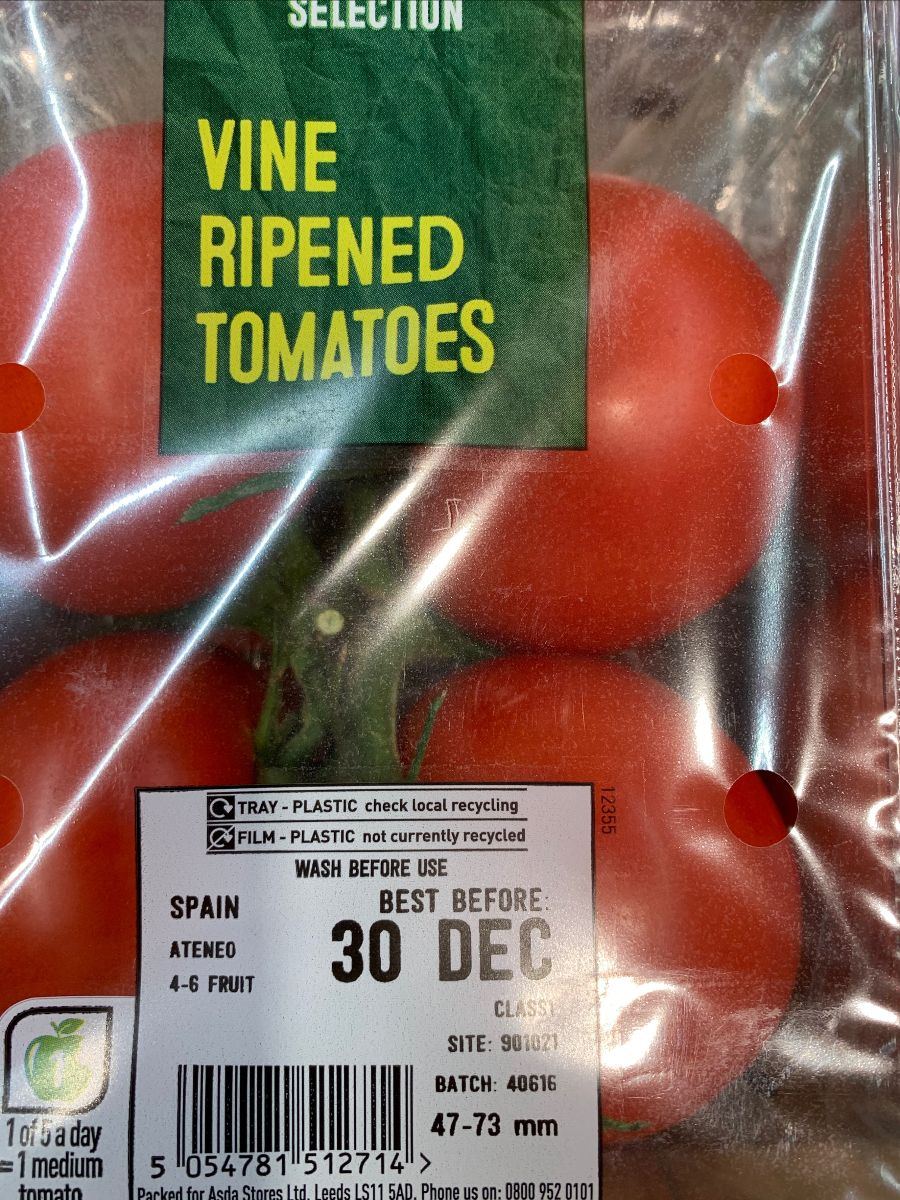
Of course we know at this time of year, we import a fair old chunk of Produce in to the UK and as such, we are relying on Spanish and Dutch imports, alongside Morocco too for Salads/Tomatoes.
One only has to look at these packs to see the sourcing situation in Asda; whilst this doesn't present a problem now, given stock levels already here. The finely balanced supply chains will mean that issues could start to occur after Christmas.
It seems likely we'll hit challenges for a day or two before things return to normal, assuming supply lines are restored. Of course, there is the prospect of a no deal Brexit further hampering supply lines
The fact that supply lines have reopened is positive, despite the issues with testing and it will take a bit of time for the backlogs to clear also. So there may be some minor disruption, but anything won't be felt until after Christmas.
It's a timely reminder of how important that France / UK sea crossing is.......
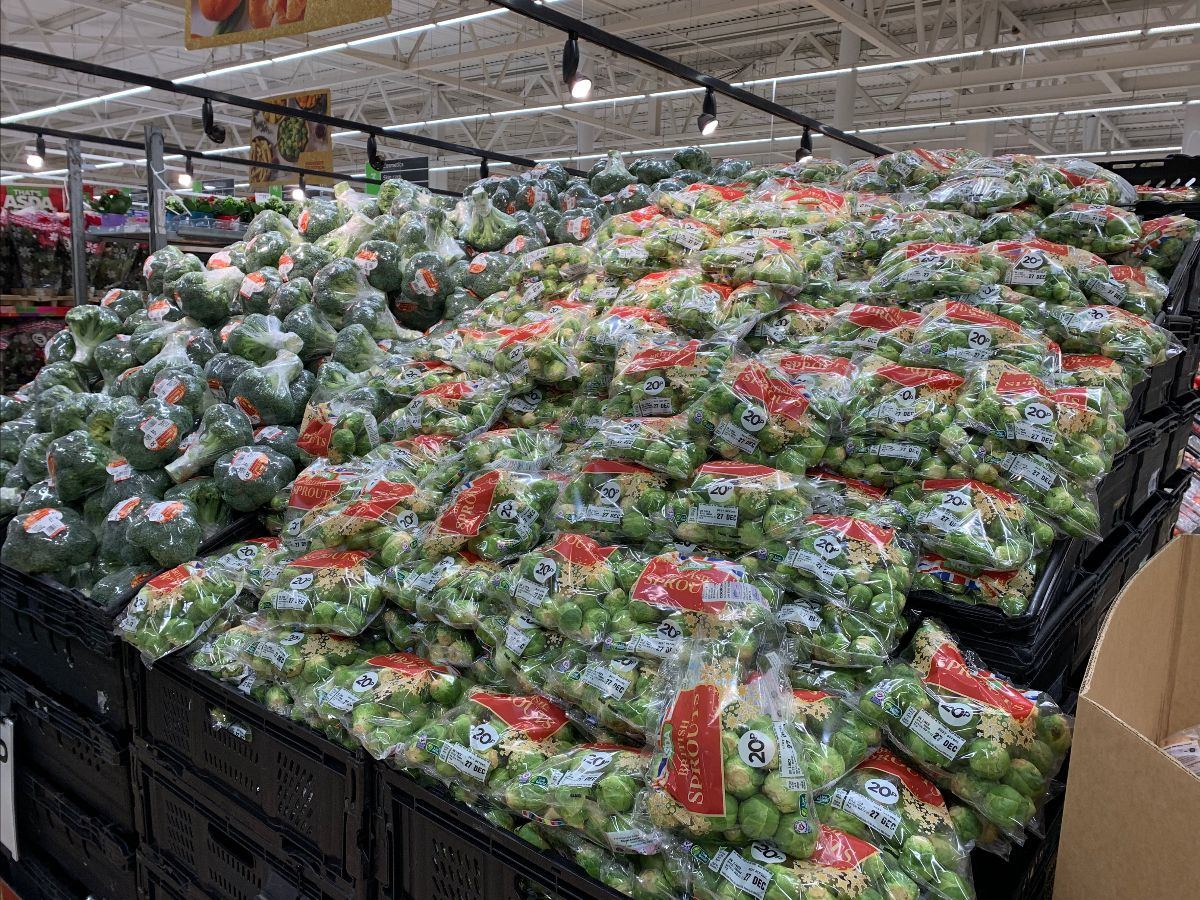
No signs of shortages at Asda yesterday; or indeed, M&S who were well set up with ample supplies all around Produce.
Whilst early, there was no signs of panic buying either, we have all seen headlines and the differing restrictions mean that the south may well see different shopping patterns. We shouldn't forget that there are a lot more people shopping this year. some who usually eat out, or go elsewhere.
Indeed, people may be wishing to buy more to 'hunker' down and avoid going out until nearer new year. It doesn't mean panic buying, per se.
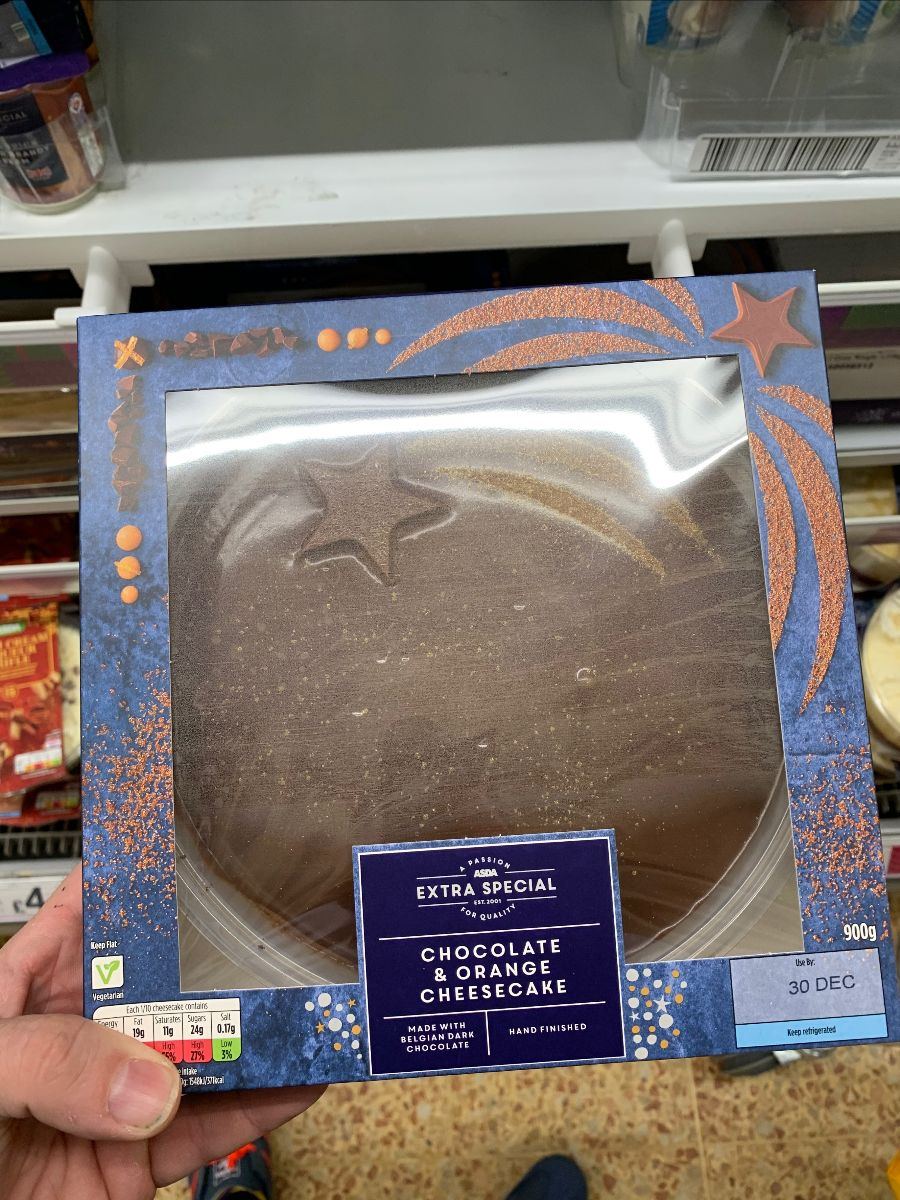
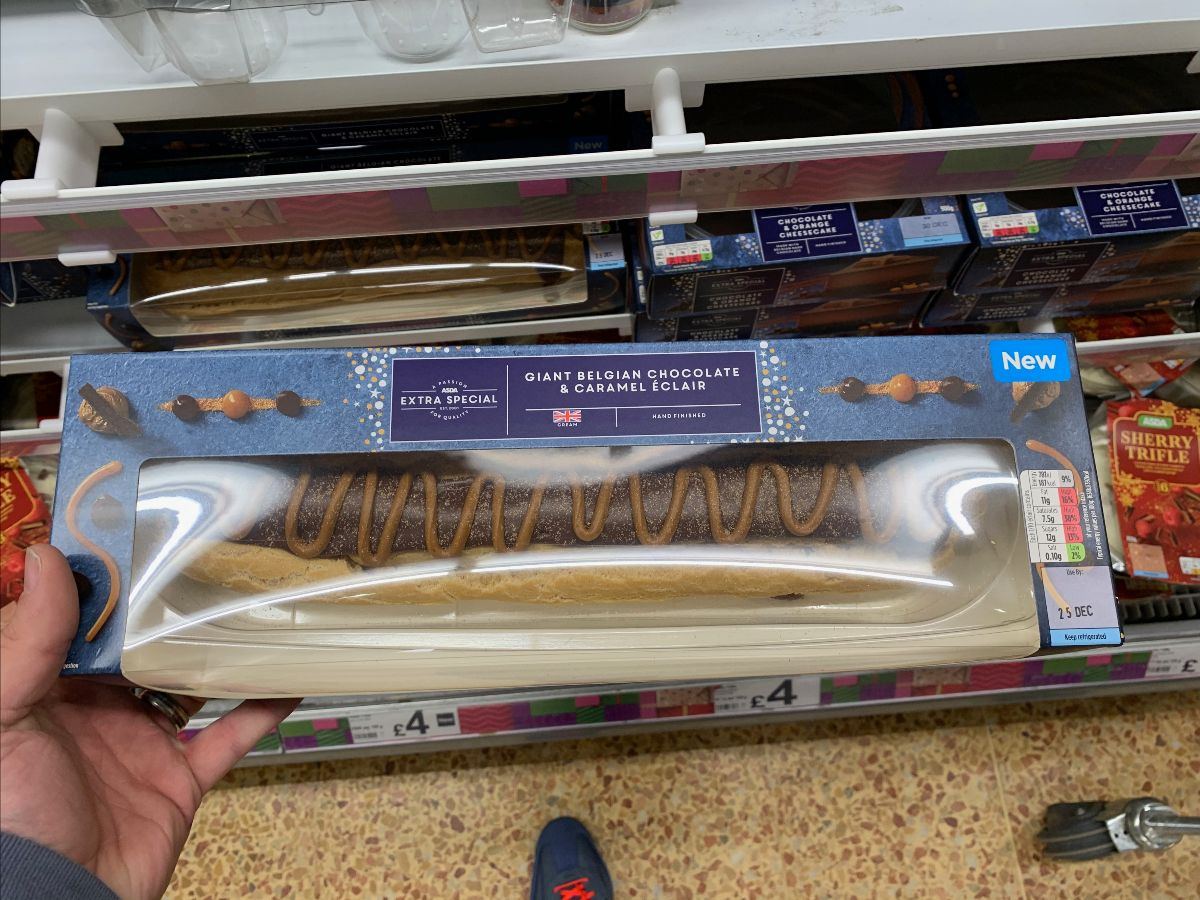
Yesterday looked like normal trade with relatively organised stores and customers taking the chance to treat themselves, such as with a giant eclair, and other premium ranges that were impressive once again via Asda.
Whilst premium can be difficult for Asda, due to their low price outlook, in recent years. it has become easier as the range becomes more present around the store, all year round. Indeed, Aldi and Lidl and their trade up mission makes it easier for it to become more about the customer awareness of own label and trade up.....
Indeed - the range at Asda is strong and offers palatable trade up options alongside innovation. like the giant eclair alongside numerous desserts and party food options.
Whilst their Kantar figures have dipped somewhat. given the huge growth in other areas of the market, but that, like the discounter growth where they open more physical space = win on Kantar, is now the same for online.
The fastest way to get online capacity on the pandemic was to turn on click and collect, if it didn't exist and turn store picking on to stores that didn't offer the facility already.
Something that Morrisons did to great effect (growing from 3 to 270+ stores with click/collect) and Sainsbury's also added a small click/collect offering to stores that didn't offer it, including turning on picking in some stores alongside that.
Tesco were pushing hard on click/collect back in the day with their expansion, which included (for reasons best known to themselves) a manned pod in the car park, which immediately negated the labour savings from having customers pick up the shopping.
Even more baffling was the lack of automated solutions as a first step, given that Asda were already installing lockers for collection back in 2012/2013. Indeed, Asda have had a well established click/collect business for a number of years, extending their parcel business to feature other retailers and allowing for returns to be processed in stores too.
So when the ability to expand rapidly came along, sure, Asda could increase slots and vans, in some cases, as their competition did. They were land locked in terms of click/collect having already built out in this area in a significant way. So whilst their slots and picking operation rose, the fulfilment was difficult to build out from a click/collect operation, given their infrastructure already existed.
IE it wasn't a build from near ground zero style growth engine. That said, if you add in their focus when the merger with Sainsbury's was going on (one only has to look at the fortunes of JS since that was announced to see how they lost their way) and then, whilst the chain was up for sale, being bid on by numerous private equity houses and working out who had what ideas for the chain...
Their focus has remained pretty constant and their growth has been there too, admirable when you consider their future has been up in the air for at least 2 years, probably longer! Always a challenge when the parent is looking to offload the chain, meaning investment plans are scrutinised and pennies count more than they ever have done, previously.
But they've done a good job and all eyes on their fortunes next year with the wider EG group and their expansion plans too. Stores nearby have had plans in for some time, to add Starbucks concessions and it's likely this, alongside fuel forecourt development will form part of their thinking going forward.
The Issa brothers run great shops and their partnerships with leading brands as franchise operators means they well understand what is required to get such big brands in to stores.
This could give Asda useful scope and scale to repurpose their counters space (closed down of course) in to other 3rd party offerings, alongside some of the work they have already started with the likes of Greggs...
From the Grocery Insight newsletter archive, first sent to subscribers on 23 December 2020. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.