Discounters and brands
8 September 2017
COMING UP
Now: Brands in discounters
Next: What about Wilko?
Later: M&S - Did the lack of a sale impact food?
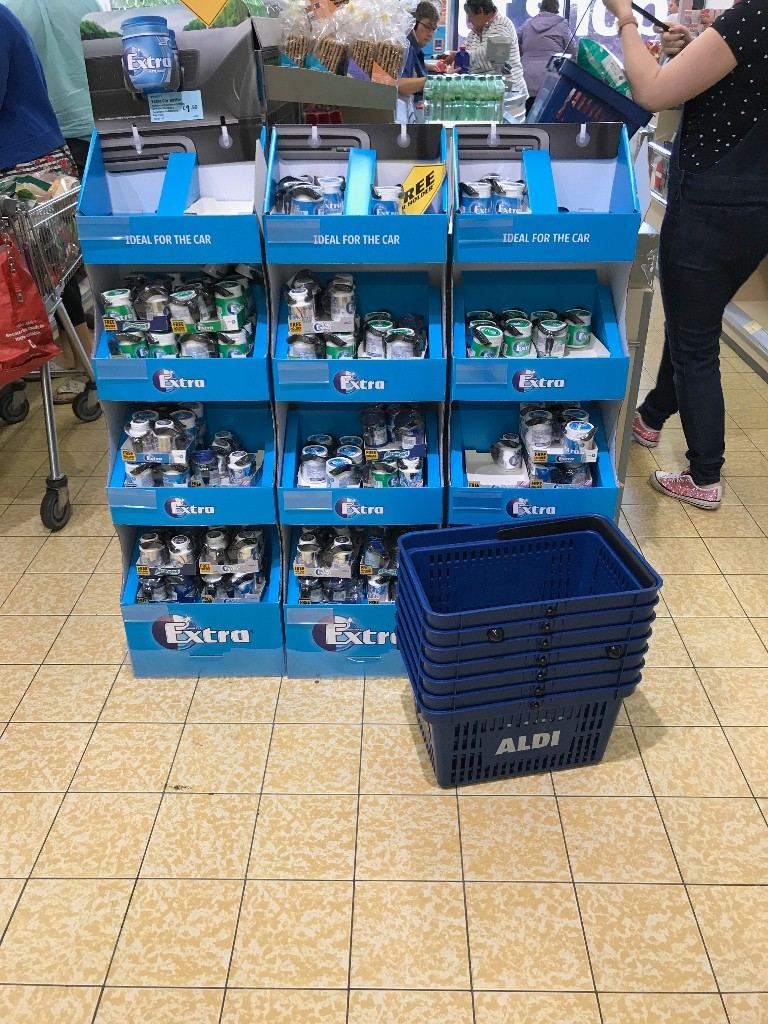
A brief note today surrounding brands within discounters, specifically Aldi given their lower exposure to branded products.
Lidl like a brand or two and have always ranged a few more products within the space... Muller yoghurts for example are a core staple alongside other leading brands dotted around the store.
Aldi haven't had a lot of brands in their assortment down the years, all bar the absolute essential brands like Marmite, or those that aren't easily replicated, or are popular - like Tunnocks Caramel Wafers.
However in recent times, we have seen a strategy either from leading suppliers, or Aldi, or both, to add leading brands in to the Health/Beauty and Confectionery. On paper it's understandable, however stores aren't run on paper, they're run in real life.
When a business builds itself on being brand equivalent within own label and centres itself on simplicity... Why would they need to add leading brands? Some of which are not in equivalent packs to further confuse. (Cadbury's bars are smaller than the core pack elsewhere).
Sure, Aldi may be concerned regarding B&M and/or Home Bargains but you should always plough your own furrow (as Ken Morrison would say).
We have seen a reversal in the Aldi branded strategy which occurred earlier this year, particularly in health/beauty, but also in Confectionery too, brands were added but it confused the offer if anything and led to more cluttered fixtures.
It's understandable that the suppliers want to do business with Aldi, the volumes and growth are there for all to see. If you're a supplier, Aldi are a business who market themselves against your own products, are significantly cheaper and imitate your branding...
See for example how long it took Pampers to realise everyone was talking about Mamia nappies and just how good they are, as Pampers stuck to flogging them on a 2 for £18 deal everywhere.
That said, it's easier for a leading brand to try get in with Aldi than actually have any strategy to combat discount. At least they can tell their bosses 'they have tried'....
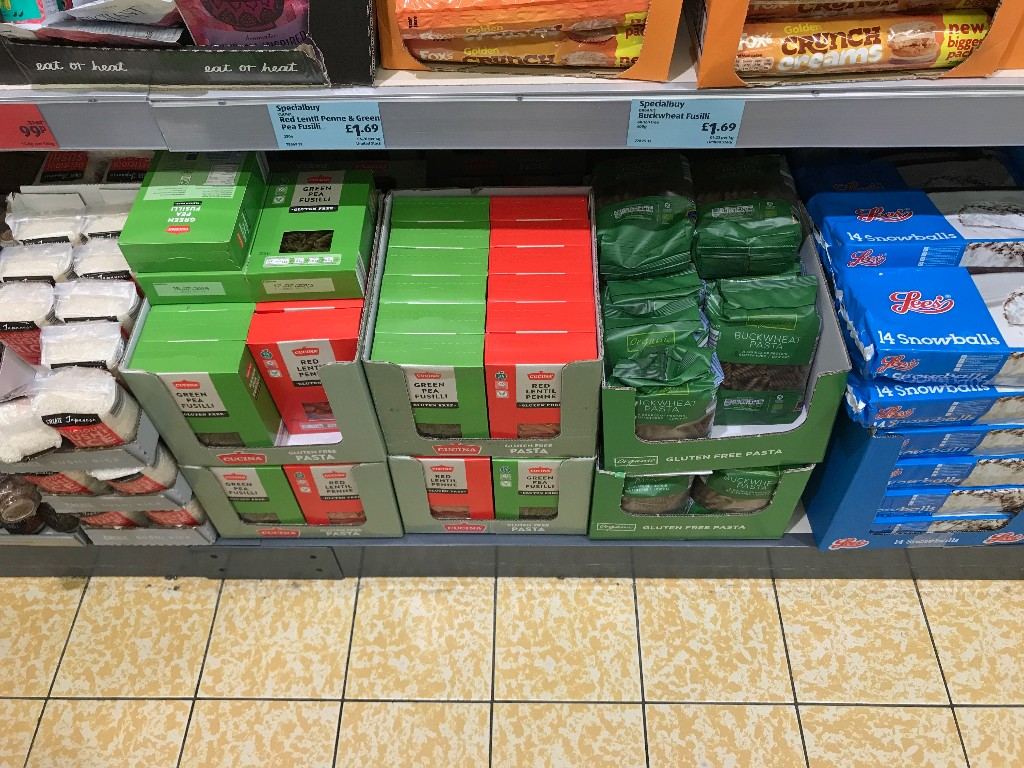
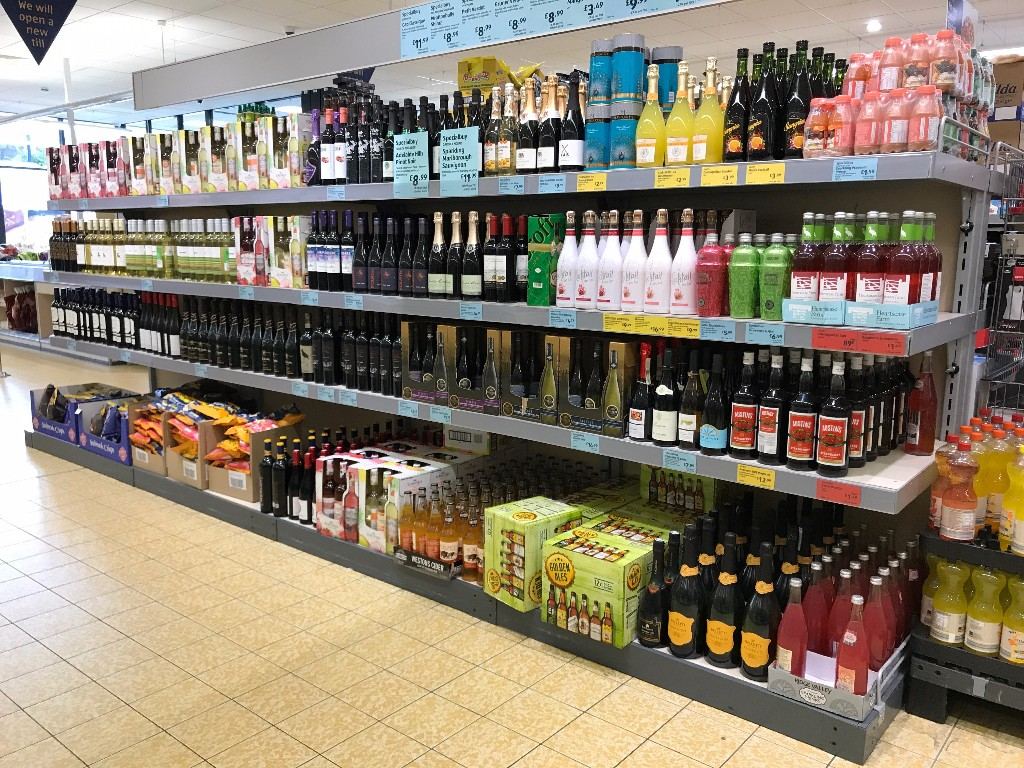
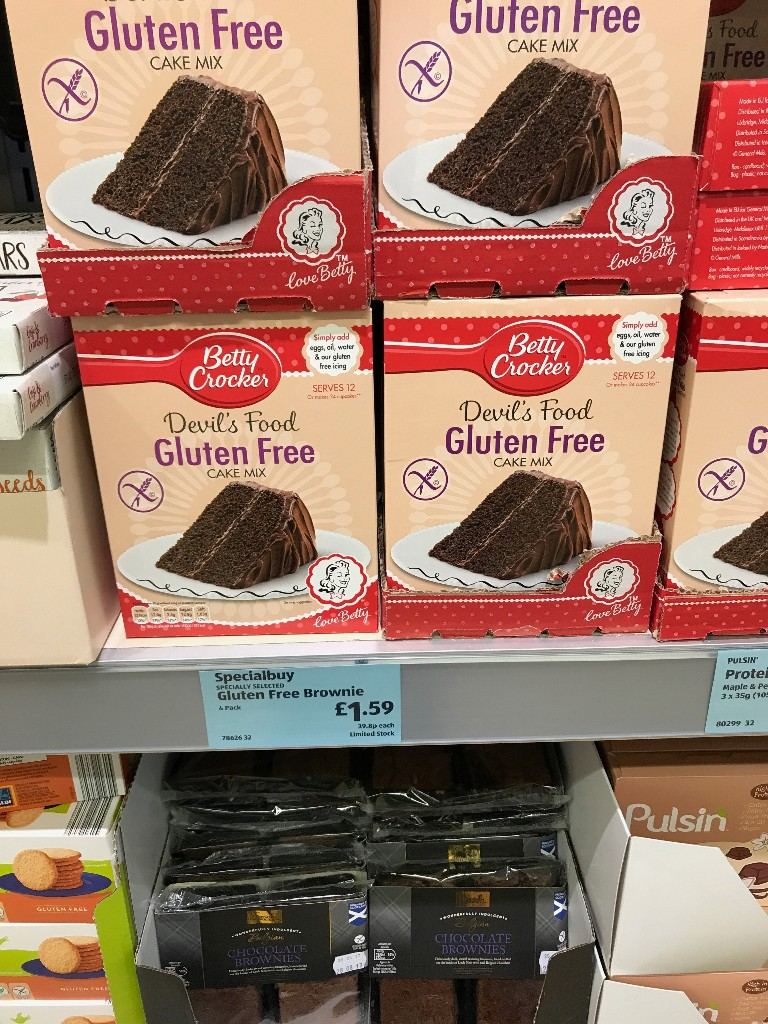
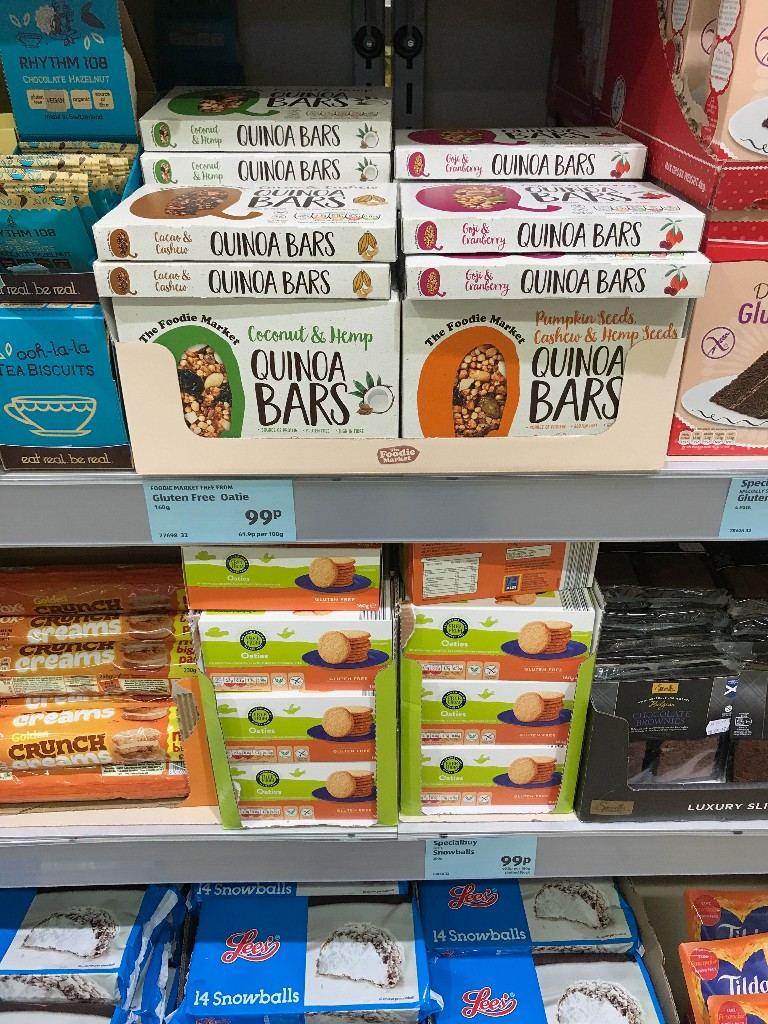
The aldi range numbers are under pressure, their 1 in, 1 out policy has returned and they're doubling down on product ranges to ensure their model isn't put under pressure.
As Aldi grow, buyers want/need more avenues to explore as it's hard work to keep the growth coming within the stable range. Especially as trends and tastes are changing all the time, the numbers are always a challenge....
Free From / health is a major trend and one that all the major supermarkets are getting involved in, from flour alternatives in home baking to various peanut butter equivalents - it's all going on.
However Aldi can't feasibly range all these in a tight fixture, however they do have some of the 'whole foods' lines inside the baking aisle. Take Cashew Butter though, the preserves space has been reduced over time as Aldi made space for faster selling categories - IE Crisps.
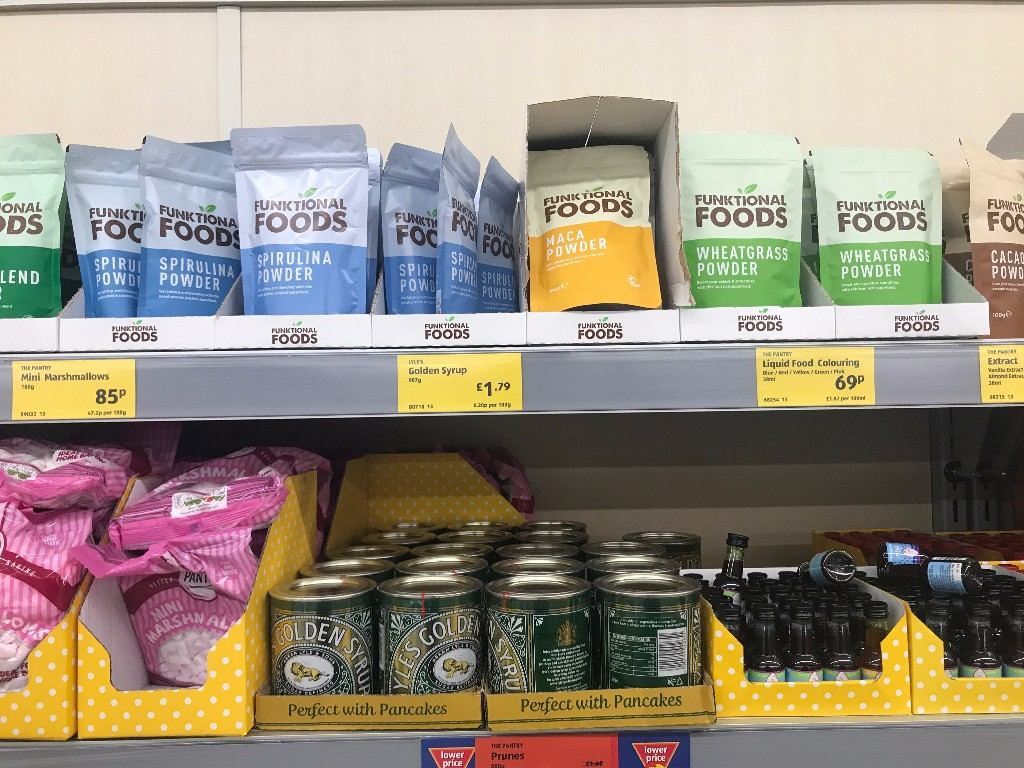
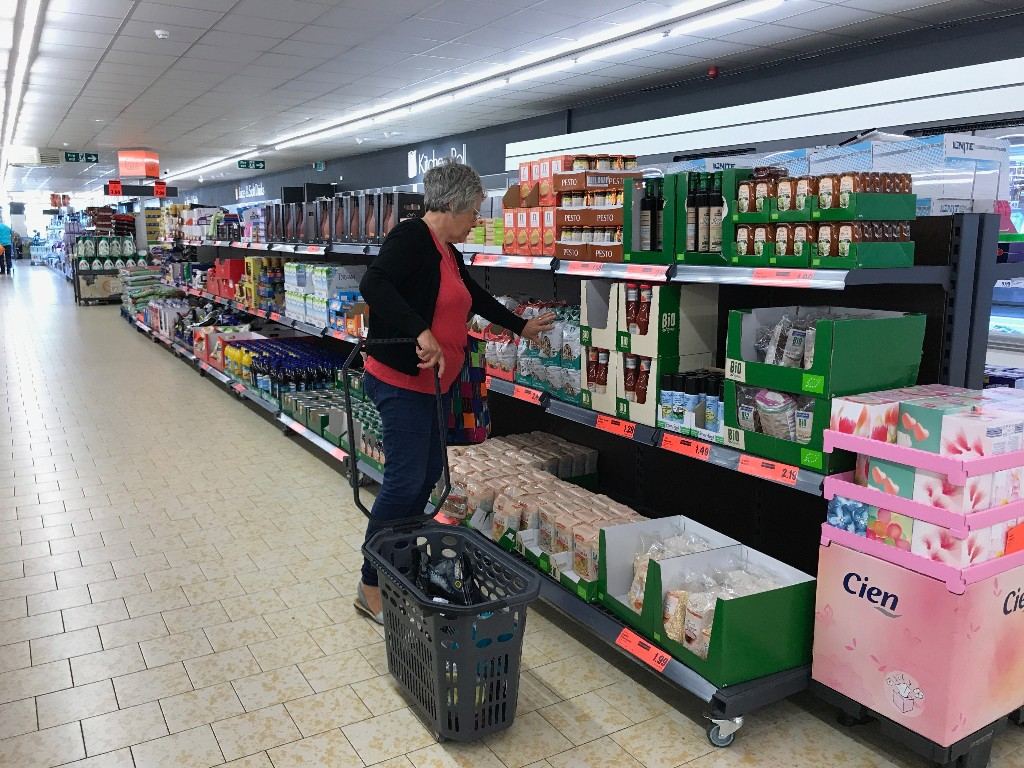
The smaller aisle at the end of the specials area has been in situ for a fair while now. It allows for core grocery lines to be stocked on a rotating basis...
A recent health event also allowed for some free from products, branded too (Betty Crocker) and also some of their own label organic Pasta and Fox's Biscuits too.
Indeed the other side of the aisle is often filled with booze, expensive spirits and cocktail based lines. Halloween will see it filled with the core grocery side of treat sized bags, Christmas confectionery etc etc.
So another example of Aldi growing ranges, albeit temporarily and seasonally but also using the leading brands too. Are brands really that desperate to get some of this volume?
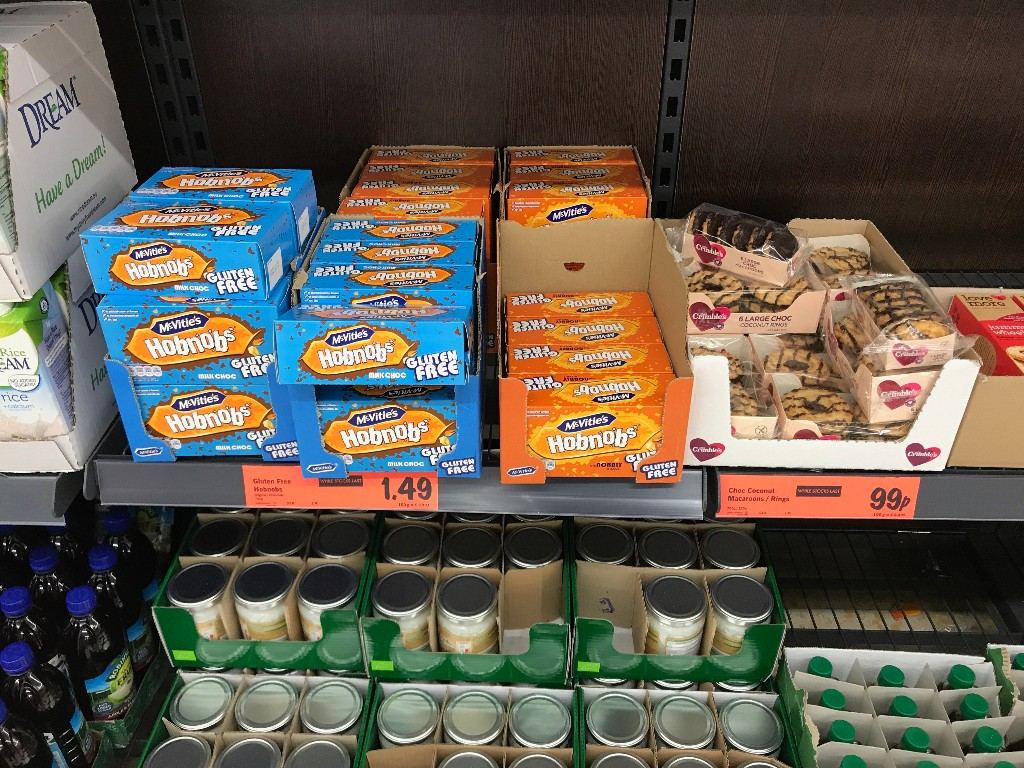
As noted before; Lidl are not exempt from this trend of a) brands in the central aisle and b) free from and other trends being out of reach on a permanent basis.
They also add rotating specials in, but generally have a fair few brands in their central 'shelving' aisle too.
I think in terms of the free from lines, perfectly acceptable to offer these to discount. There is a mutual appetite and the customers in discount appreciate lower prices on free from, the discounters want the range temporarily at least to prevent losing spend.
This works well. However it's a mutually beneficial partnership.
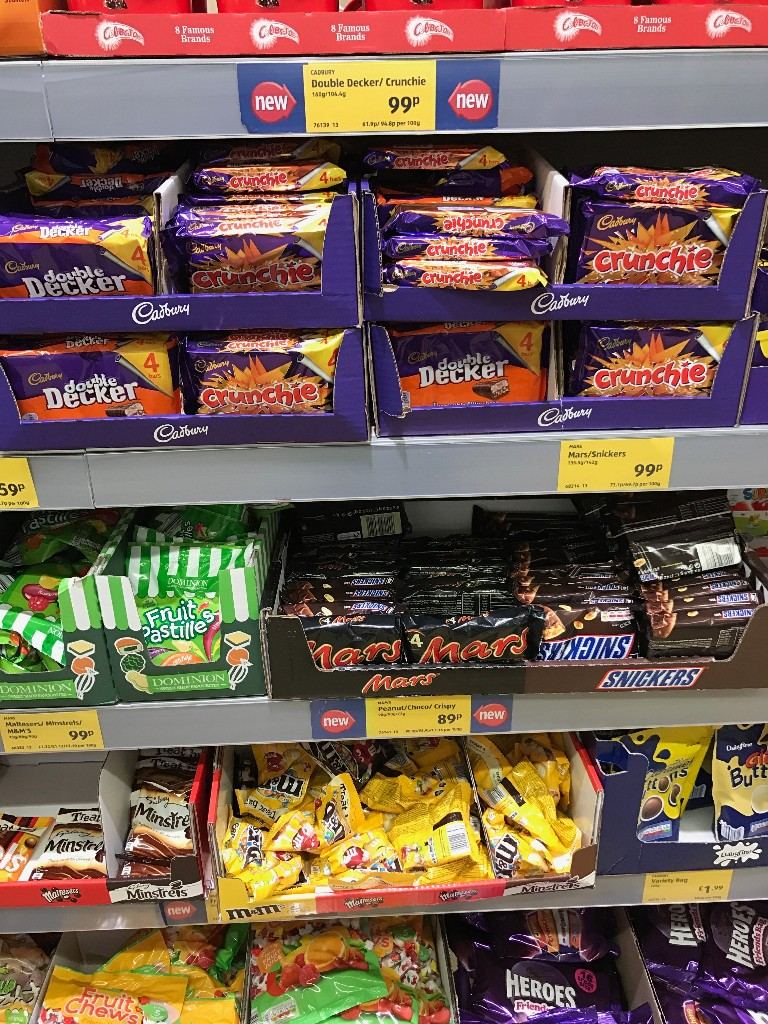
In Aldi/Lidl - what didn't work was P&G dropping numerous brands in to Health/Beauty at significant price premiums to those sourced by Aldi. Or Cadbury's doing the same with their Twirl / Mars multipacks.
Those that are imitations of your leading brand, marketed heavily and sold at lower prices.
Whilst no Crunchie equivalent in Aldi, Aldi have Mars imitators alongside their larger sharing bags too which have appeared...
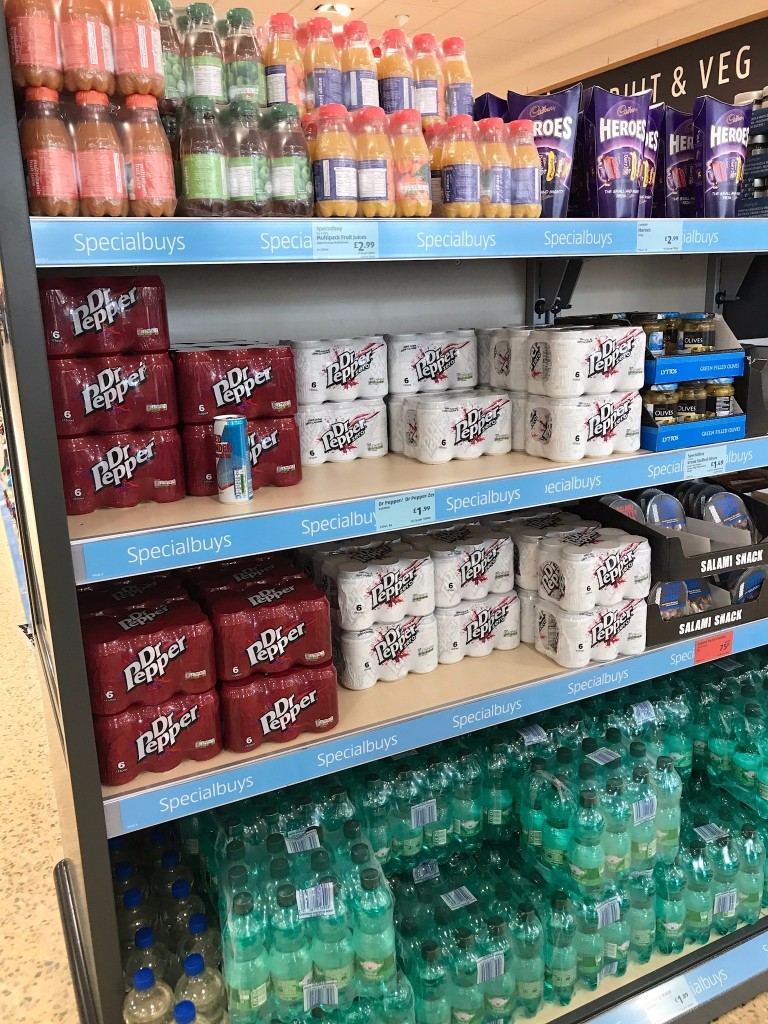
Alongside the central aisle featuring Dr Pepper on a lower price, limited buys / specials. Perhaps with one eye on B&M / Home Bargains?
So as Aldi look to come away from brands in the core aisles and ranges, or at least, reduce them to a minimum.. How can they work with suppliers who are keen to work with them, but also not compromise their model at the shelf edge?
The answer appears to be shippers.
Branded shippers have started to appear at the checkouts in many stores, offering special buys on branded shippers - Pet, household and health based foods have all been featured thus far.
It isn't a bad move per se, I think it is a happy medium, getting the brands in and exposure for their brand, but also allowing Aldi to preserve their model and the shelf edge too.
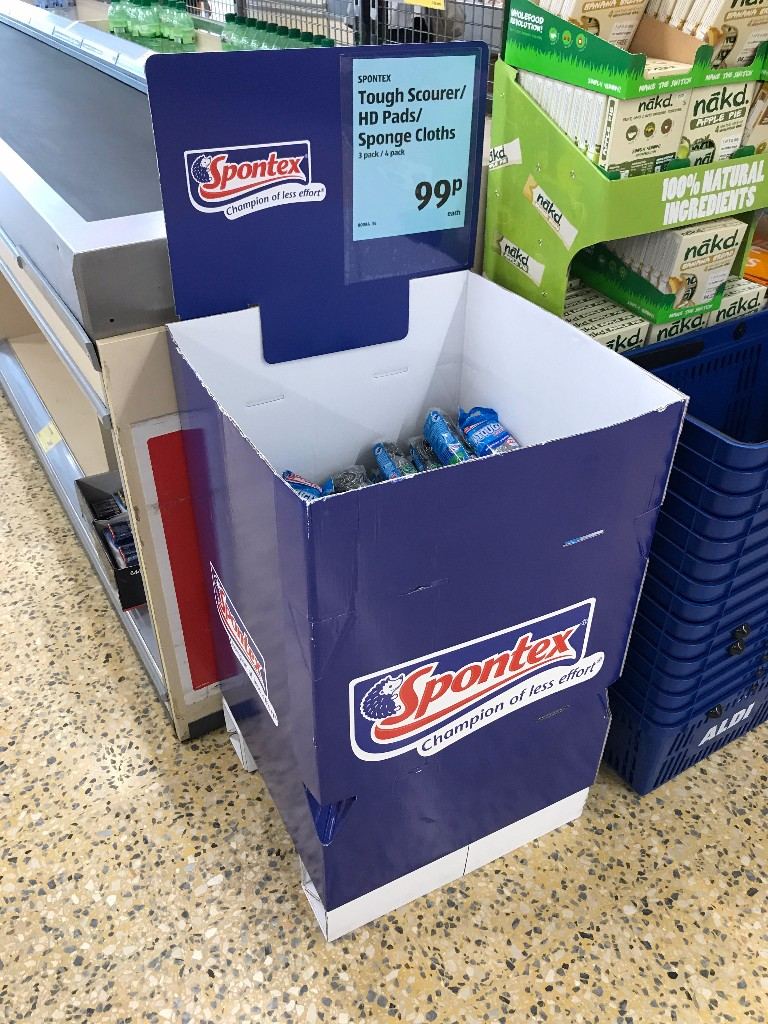
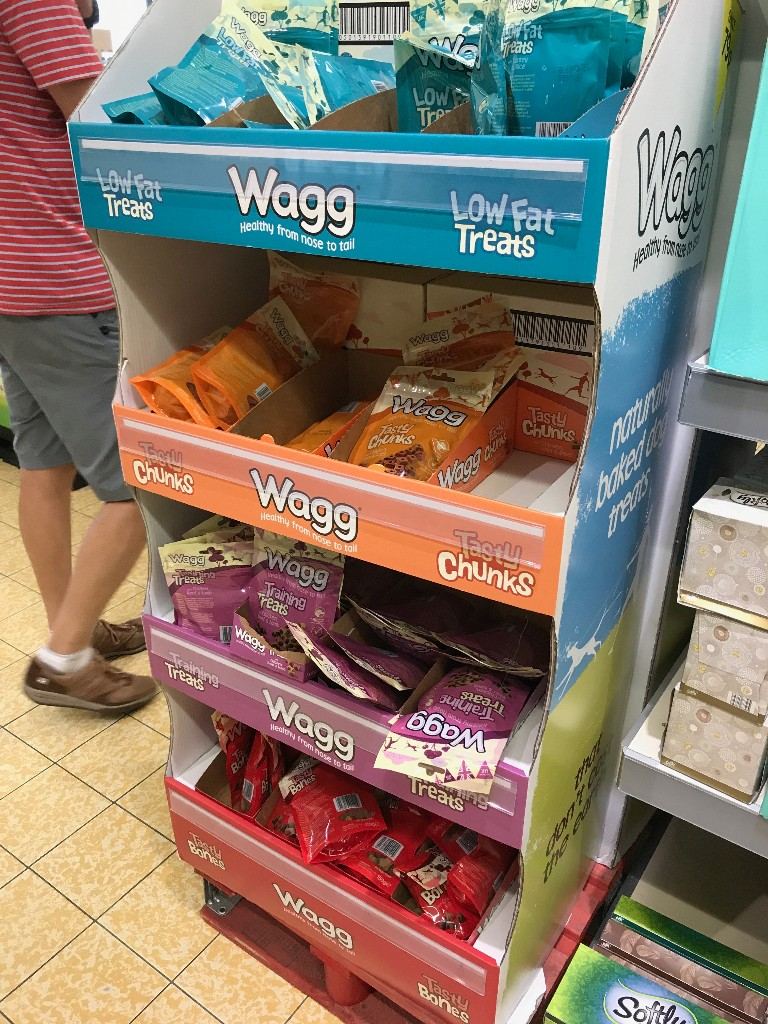
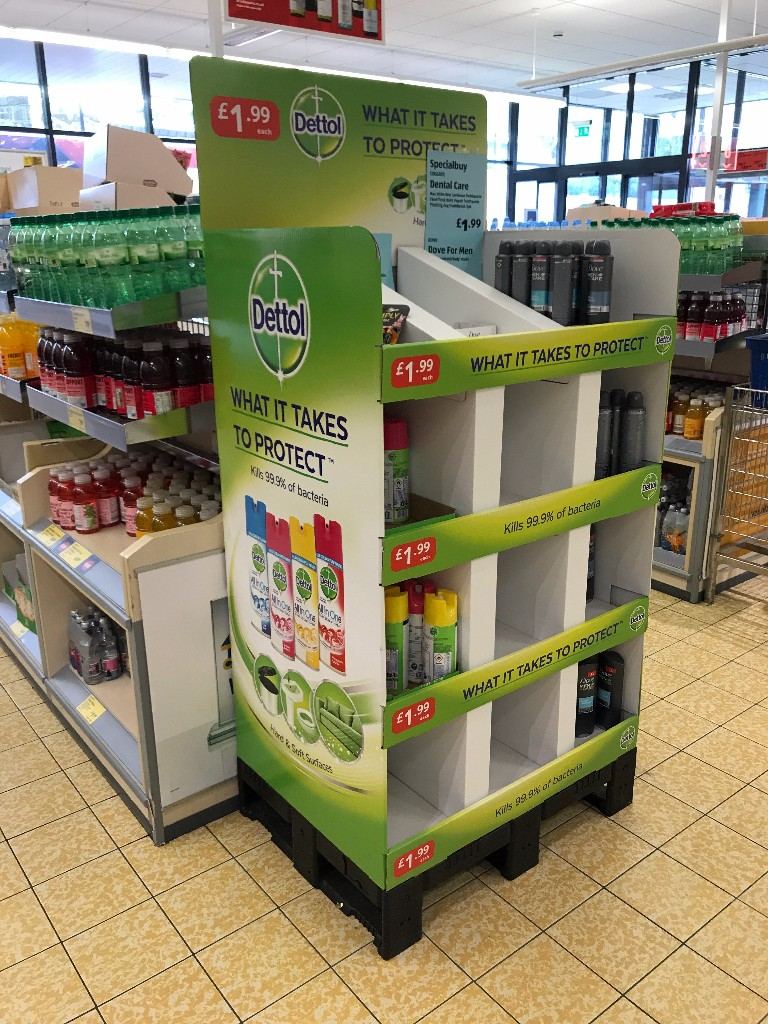
Aldi have trust on price, so the customers presumably won't have too many issues with the prices here.
However ranging these brands can put Aldi in to contact with the likes of B&M who may well be churning these lines out cheaper than Aldi.
You also have the challenge of compliance too. For some reason, this store were merchandising Dove lines (Unilever) on a Dettol (Reckit) shipper....
They were the same price at least..... An interesting move, more brands on a specials basis preserves the model, but Aldi have to balance up stock holding. Stores are heavy on Summer clearance and often do carry a lot of stock, more brands and food based specials run the risk of increasing stock holding more.
Record growth is one thing, but keeping pace with record growth is another, even with the huge swathes of space being dropped in.
From the Grocery Insight newsletter archive, first sent to subscribers on 8 September 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.