Daily's - Rebranded Basics for Sainsbury's
10 June 2019

Own label developments abound in Sainsbury's
Whether it's what we would have seen if the takeover had been ratified, or whether these own label changes were brought forward as a result is entirely unclear - however Sainsbury's have been nodding towards the fact that they were going to change things in own label for some time.
Namely in recent months, they have been making more of their 'exclusive' brands and the 'discover' ends of various products from suppliers... These suppliers are relatively small and enable Sainsbury's to offer a differentiated range without there needing to be a huge investment from Sainsbury's themselves.
However; side stepping that entirely as I believe it's a distraction from the reality of the own label (IE good, better, best) and the running of the core shop so to speak.
We have seen so much development around own label and Tesco have firmly led the way with their reshaping of value tier in to TE Stockwell et al and then squeezing the mid tier.
It kicked off with farm brands of course; tackling Produce and Meat was high on Dave's agenda as share leaks out of Tesco in to discounters on both of those categories. Why?
Own label dominant, value drivers (high purchase frequency) and they're all on EDLP. So addressing that with farm brands gave Tesco a foothold versus the discounters in these categories.
The rest of the industry has watched as Tesco continued apace with their plan and there has been some imitation of the strategy. Asda brought Farm stores back from the wilderness to replace their value tier in those categories and Sainsbury's brought their Greengrocer's selection range in to Produce.
More recently, we know Sainsbury's have introduced J.James tier in to Fish, Meat and Cooked Meats also. Sharpening Basics but the results have been broadly good in terms of volume pickup (via the JS results reported to the City at least).
However this comes at a cost; as we know to highlight lower margin, lower priced products is risky, you deflate yourself and with a mere 2.2% margin to play with. Sainsbury's have to be able to drive volume (to equalise the shift) and also to entice customers to buy other items whilst they are in store.
Clearly Argos will play a part in bringing people to the store too; but the play around changing Basics is a risk, but they are targeting this tier clearly with a family of sub brands - evidenced by "Daily's" baked goods appearing in Sliced Bread, replacing Basics.
More to come quite clearly on this, but the ambition to replace Basics with this tier is fair, however what of mid tier? It becomes squeezed and the opposite can often happen as customers actually abandon the premium tier in favour of products further down the chain.
Therefore the pricing hierarchy has to be carefully though through, otherwise the numbers make no sense and you may as well chuck a load of money in to vouchering for the good that it does....
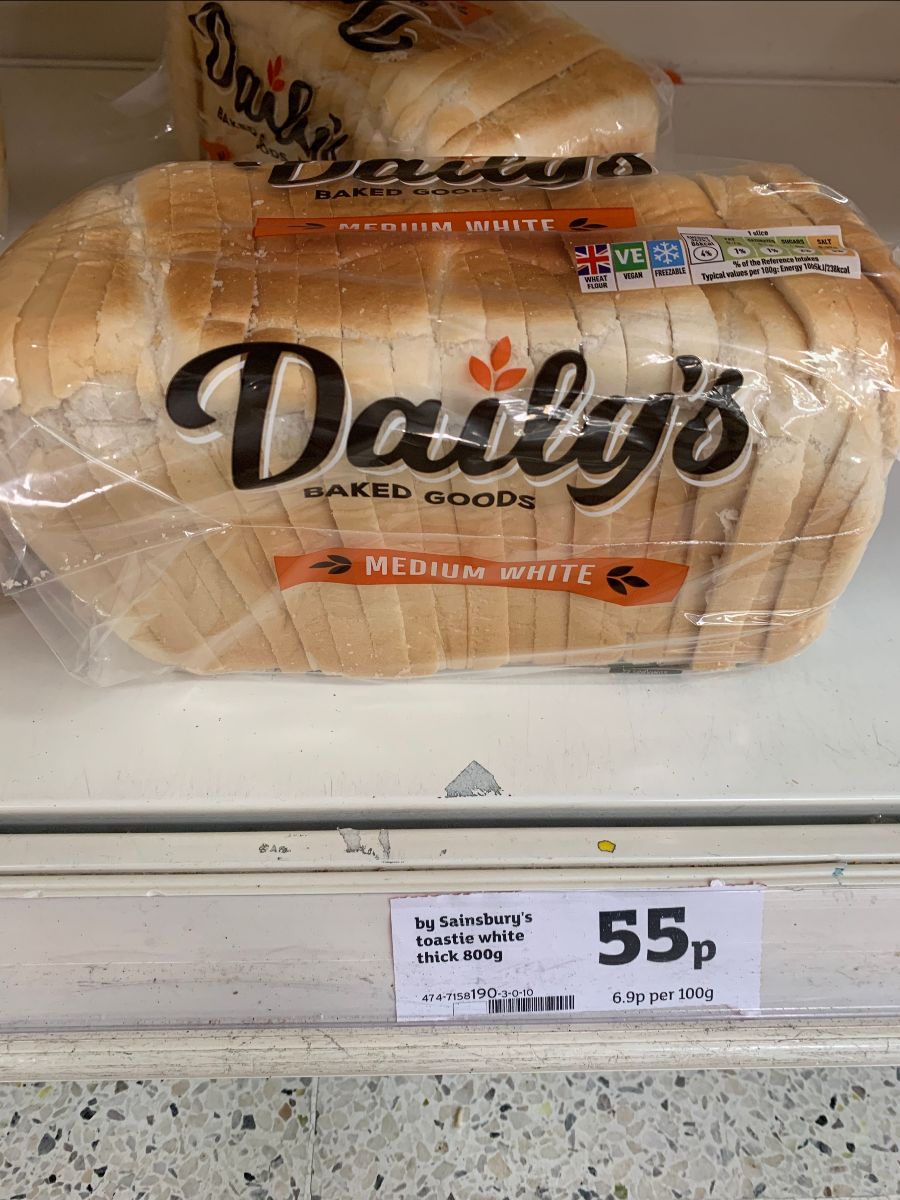
As is perhaps typical for Sainsbury's these days; the product was mis-replenished. In front of the wrong label...
The strategy in Bread is a confusion as online; the price for Daily's is 45p; yet the mid tier product is a mere 10p more expensive.
The longer term play has to be to replace one of these tiers with the leading product and convert all the volume in to that one product. Surely?
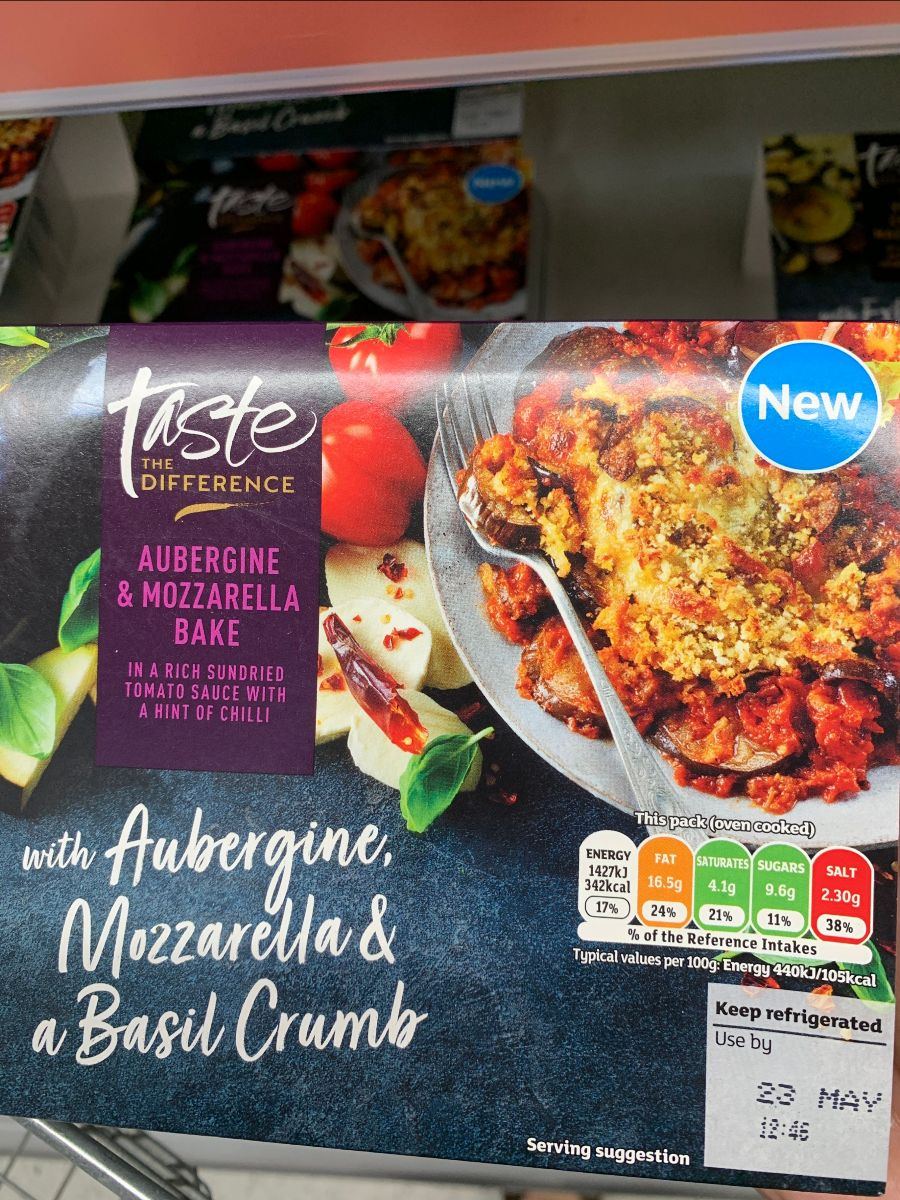
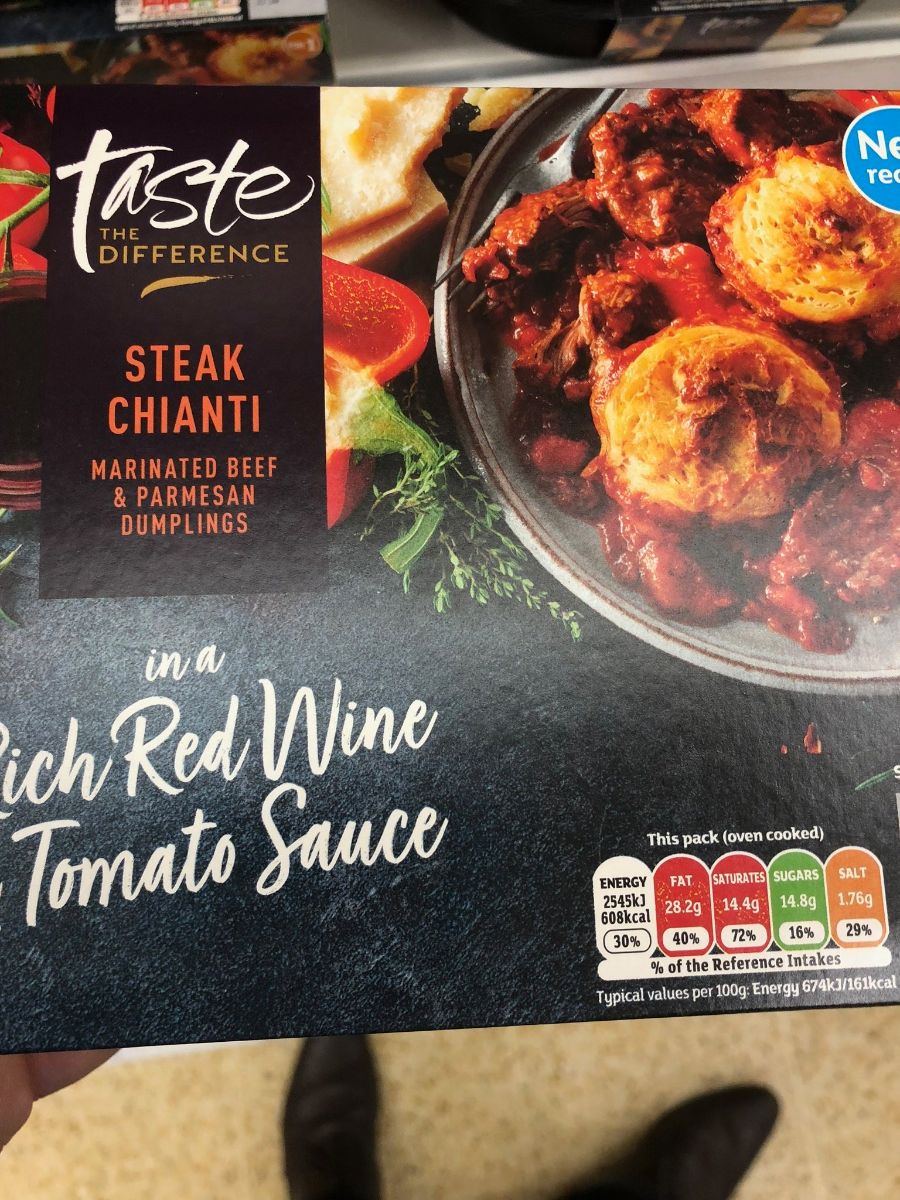
Premium (Taste the Difference) for Sainsbury's has been undergoing a change with a new look and feel displayed on ready meals (chilled) for the first time.
The packaging is striking but does it add anything to the value proposition? It goes back to the 'retro' feel for packaging perhaps and stands out well enough, however whether it adds that level of distinction to things - I am unsure.
Certainly iconic; the Purple / dark Blue of the former packaging was striking and created distinction, does this new variant? It's difficult to say.
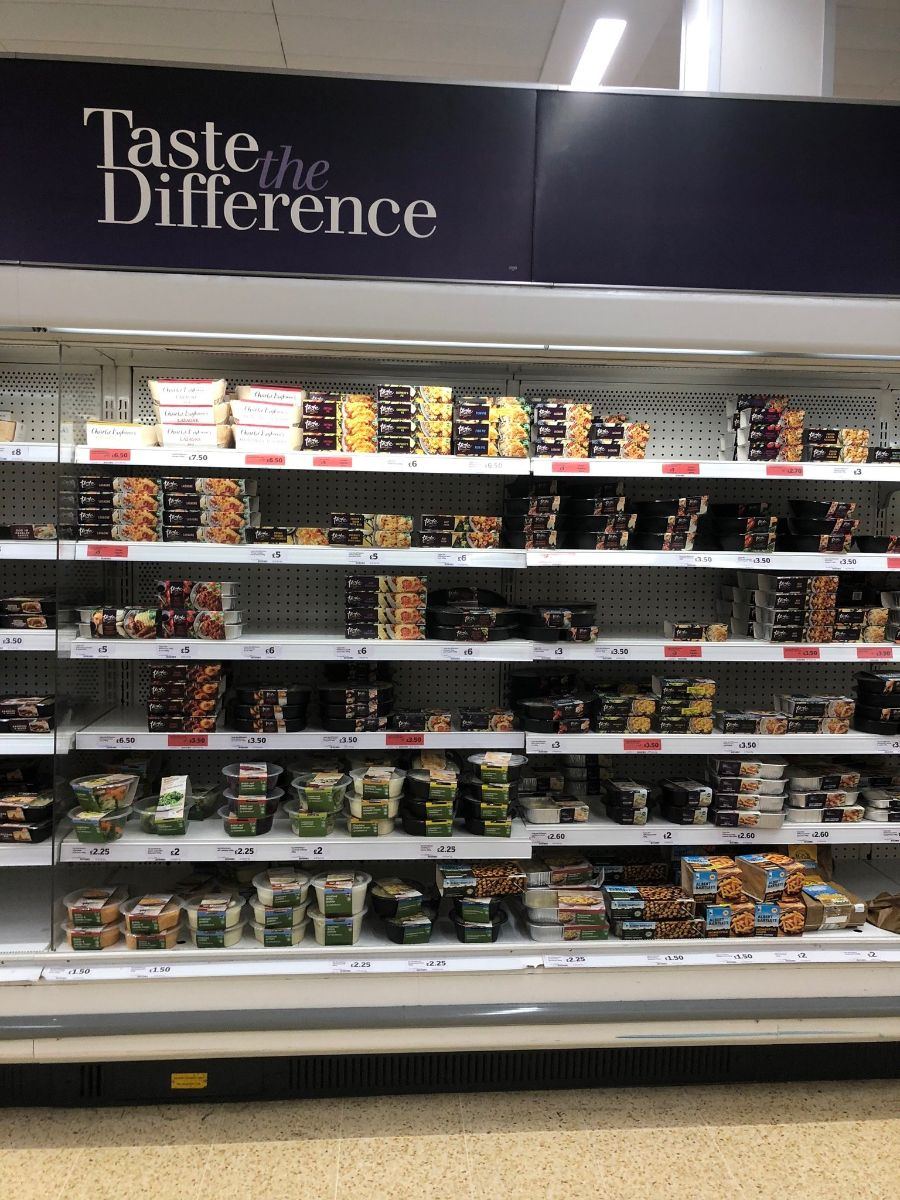
Even the launch was uncharacteristic of Sainsbury's. It could just one store, or perhaps there is a wait until further categories are rebranded..
But the overhead board still displays the old logo and design whilst the products directly below showcase the new look and feel.
Examples like this won't get the rebrand in to the hearts and minds of customers. As ever, the proof of the pudding is in the eating.
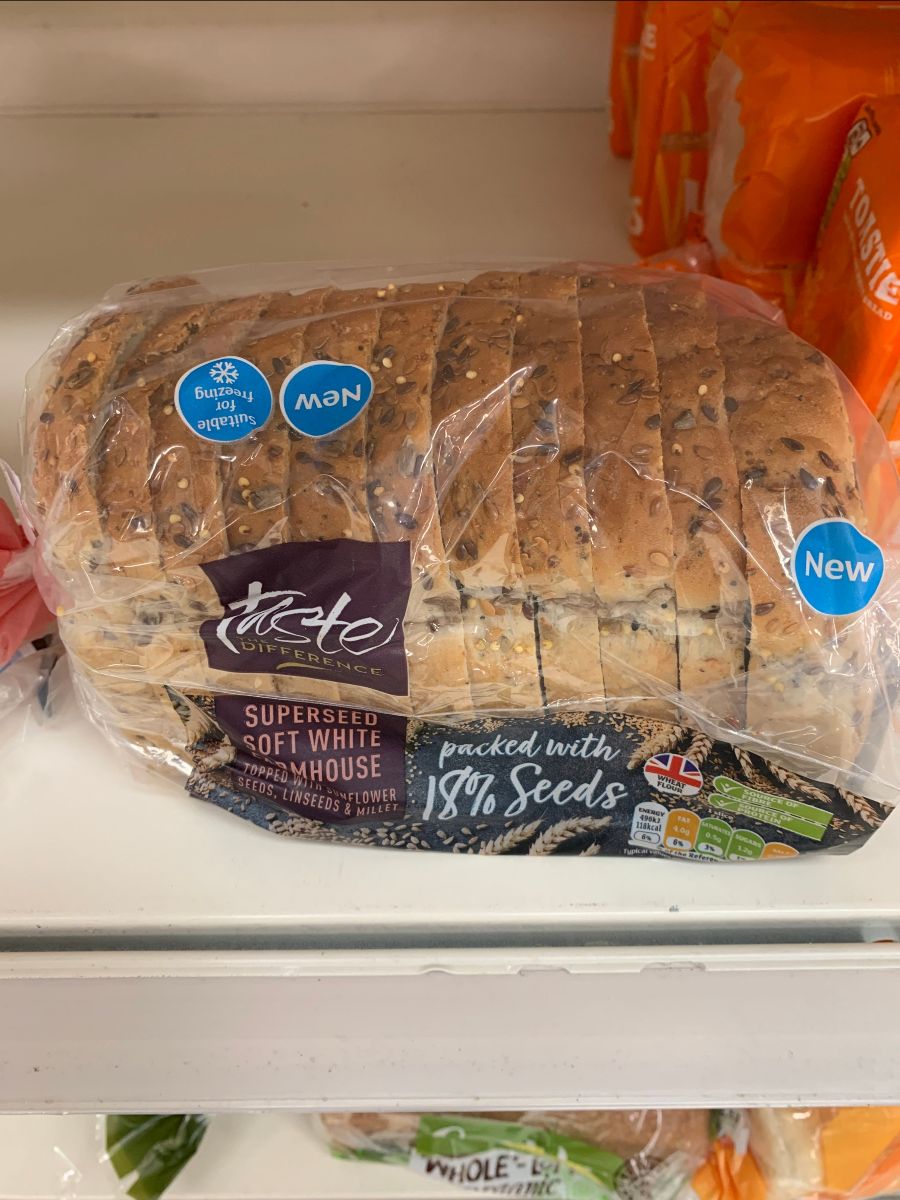
Alongside Daily's appearing in Bread, the premium equivalent has been rebranded and in some cases, new lines added in here too.
It will be interesting to watch the rise of premium SKU's in this relaunch. Sainsbury's are adding more range via those smaller, niche suppliers in any case. Those lines are generally higher in price so adding premium products is also necessary, especially own label.
However it can give the impression that the chain is becoming expensive if lots of new lines appear that are premium / high in price. It's a risky game.
Ironically it's the same mistake we saw Tesco make in 2012/2013 too. They changed Finest (with a similar swirly font) and also pushed in numerous venture brands (namely own label brands that were 'branded') a la Sainsbury's with 'my hair matters' alongside others.
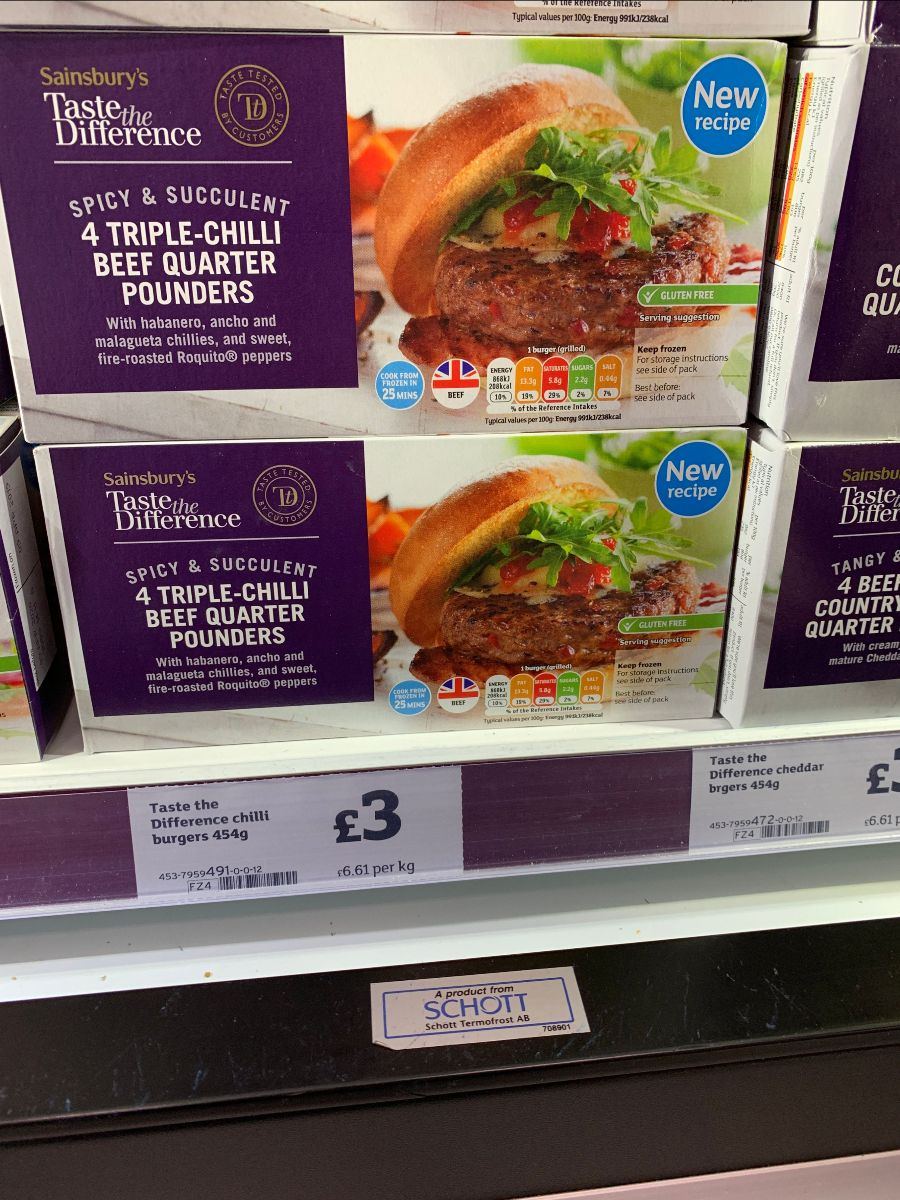
Intriguingly - perhaps pointing to longer lead times in Frozen. The rebrand for Taste the Difference hasn't hit the category despite some products being reformulated and reengineered with new recipes and some new products for Summer.
It seems curious that the packaging and launch would be so about face, not cohesive and launching in some, not others. However the lead times can be long so this packaging will likely change once the stock is sold through.
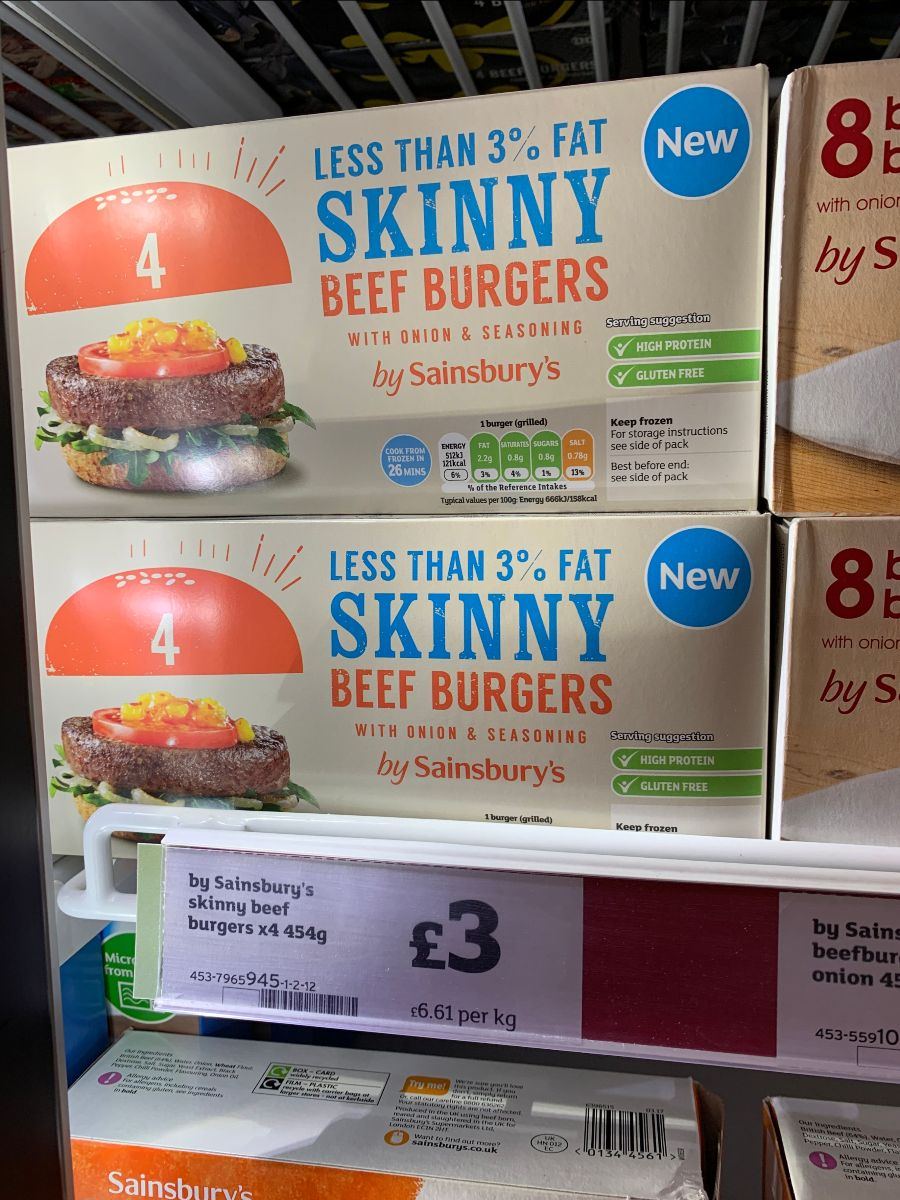
I thought this packaging stood out rather well; Skinny (less than 3% fat) burgers are on trend, especially for Summer (although the weather is against everyone at the minute).
That said - what does "Skinny" mean for "Be good to yourself"? Another tier in the Sainsbury's armoury that needs to be pushed on with, especially with the focus on health and wellbeing always a priority.
The challenge for Sainsbury's is the same as many retailers, namely discounters and how to combat them. Southern expansion from both Aldi and Lidl impacts them and generally, premium is significantly cheaper at both Aldi and Lidl.
They're able to rotate premium in Fresh, especially at events and that means there is a 'fresher' feeling for customers given that some lines are not year round.
Premium is absolutely the right place to focus for Sainsbury's - Taste the Difference (like the rest of the brands/tiers) needs to stand out from the rest, the market is noisy and Sainsbury's need to cut through that noise.
Although with store standards still challenging (although noted improvements in Grocer 33 recently) it's difficult to talk about any improvement in quality within a poorer store environment than customers were used to previously.......
A balancing act for sure!
From the Grocery Insight newsletter archive, first sent to subscribers on 10 June 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.