Retail By Email - Issue 470 - Inflation and HFSS delay
23 March 2022
View this email in your browser
Retail by Email - Issue 470 - Inflation and HFSS delay?George Eustice (Environment secretary) noted that prices are rising in a speech yesterday and that if supermarkets can absorb the rises, they should do so. (chortle).
We know that they are but equally, there are other pressures on wages, via Brexit and indeed the wider energy/fuel crisis around prices too.
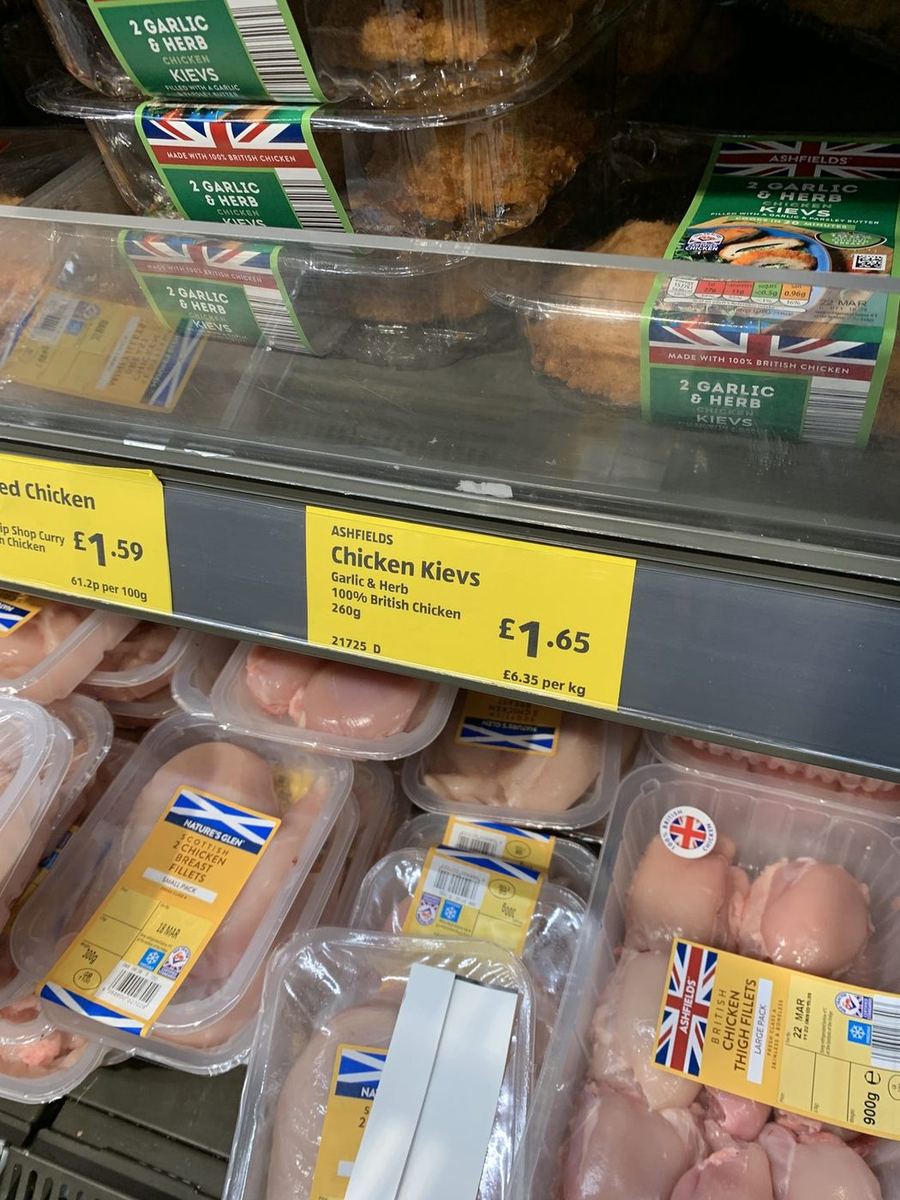
Chicken Kievs in Aldi - they were £1.19 in October, up 10p almost monthly before reaching the current price last week. Real life inflation here.
Eustice also mentioned that legislation that would drive prices northwards was being looked at too. HFSS is in that bracket given the changes to space allowances in stores for unhealthy products, but also a wholesale change on promotions and no more “extra free” on pack either.
This legislation would impact everyone but the focus has been on the space and how retailers would manage, but customers? How do retailers explain to customers that all the unhealthy product is now “in aisle” on deals and certain promotions are now no longer permissible?
There remains a number of questionable decisions in the HFSS mix too. In store produced products are permitted anywhere in store, which of course, includes Bakery items….
But fundamentally, the changes in legislation would impact hard pressed families significantly. There is no doubt.
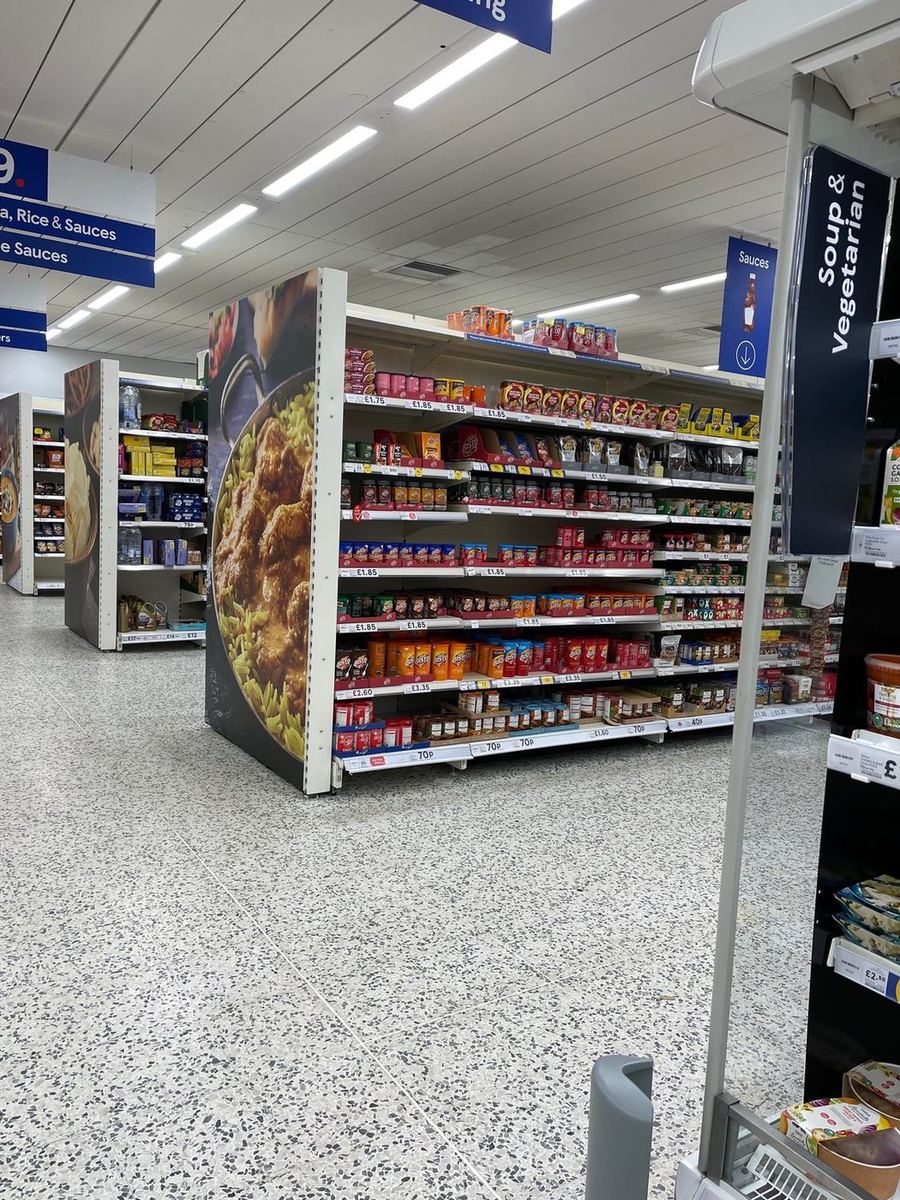
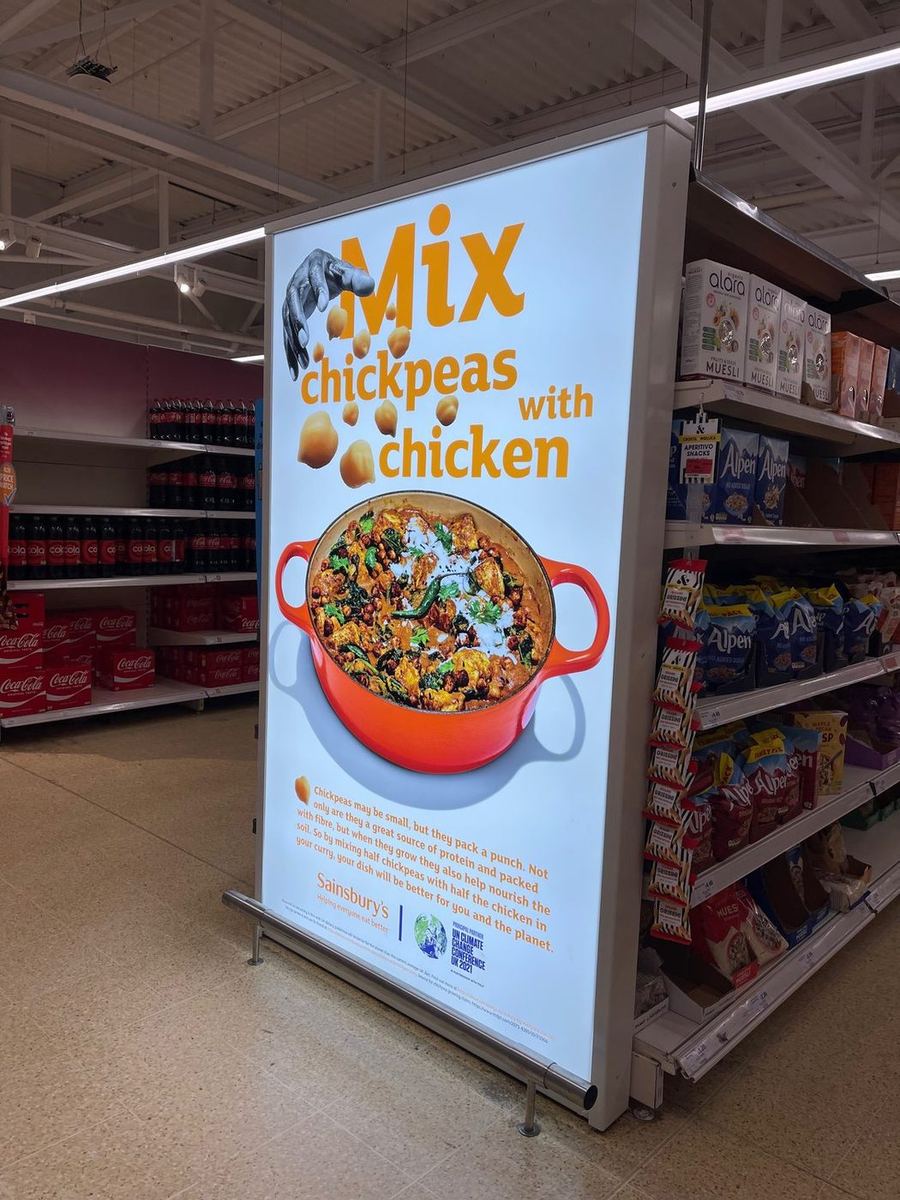
HFSS trial stores in Tesco and Sainsbury’s sees hotspots in aisle and ends replaced by advertising based “non ends”.
All eyes on Rishi Sunak today for the Spring statement that could well contain a surprise or two, given that we have had virtually no leaks of note.
Equally, it could just be more of the same with the NI rise remaining and paltry offers of support for working families and indeed, everyone else caught in the crossfire.
It’s hard to remember such a pivotal chancellor’s statement really, especially as inflation continues to rise to record levels and shows no signs of abating.
Just as you think we may have a handle on it, Russia invaded the Ukraine and the longer term effects of that on Diesel prices, Wheat imports and indeed, Fertiliser, amongst other things just adds to the uncertainty in the markets.
Action needs to be taken somewhere, as there is pressure all over. Energy is bad enough as highlighted before, but petrol/diesel rises automatically impact the spending power of customers as the price is paid at the pumps.
Not to mention the challenges for the hauliers facing in to higher costs that could never be forecast with any accuracy. Duties on fuel have been cut in Ireland and Europe and pressure will be on for this to occur in the UK too.
The pressure then shifts to retailers to see where the prices fall at the pumps and how much, how quickly.
We are tracking prices and the inflation across 2019 - to present day on the value tier product as sold, alongside fuel for the majority of 2022 onwards also, which we’ll be sharing on this email service.
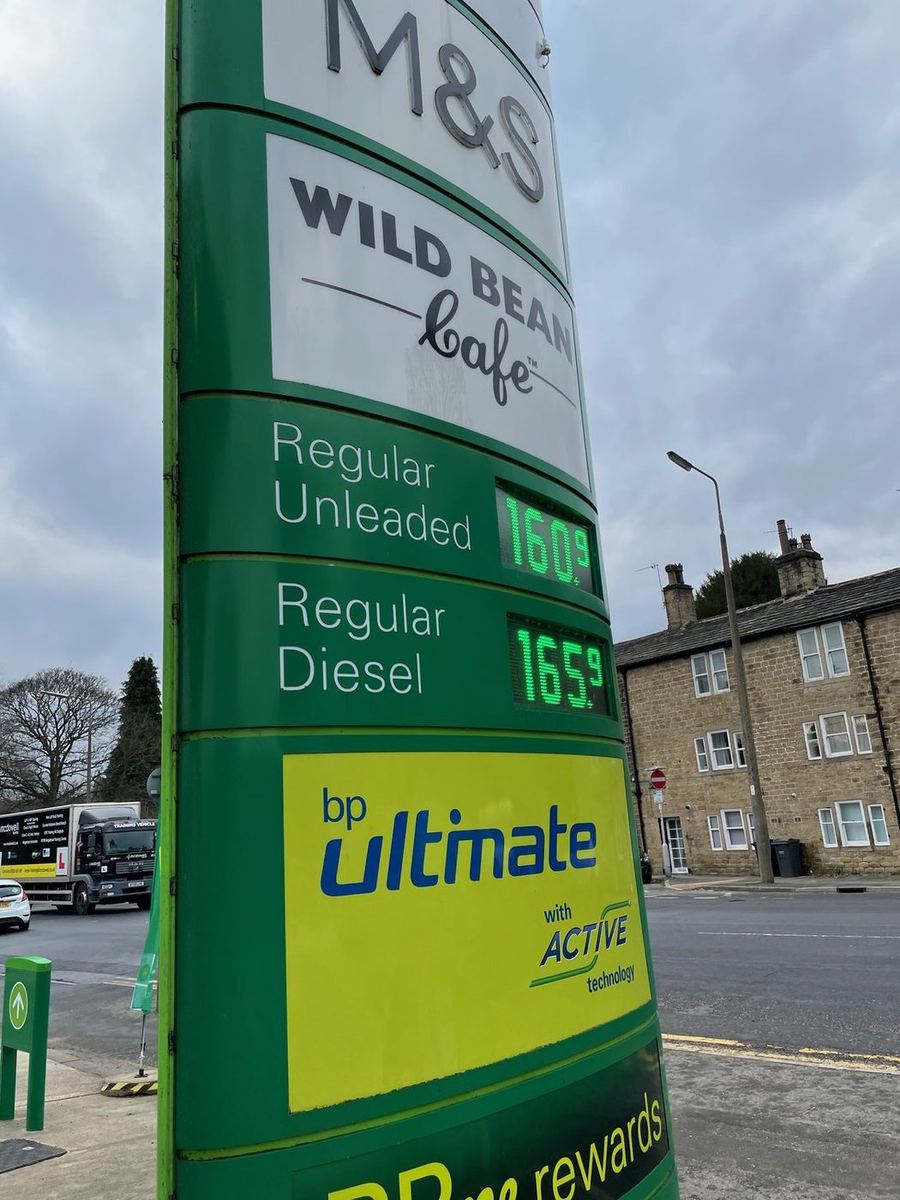
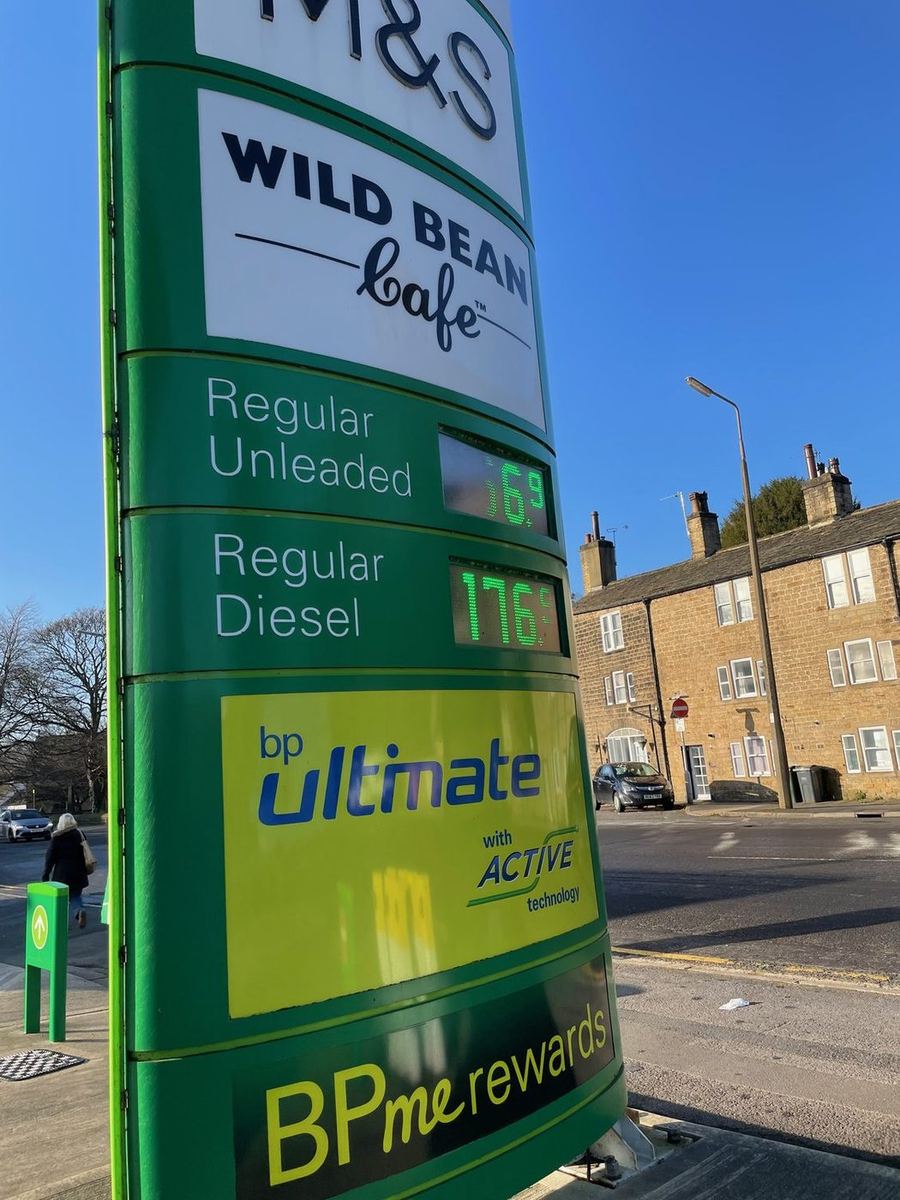
In terms of Fuel - these are two price points from my local BP garage, a mere 8 days apart. (8th and 15th March). Likely even higher now.
We have an in depth view on Asda coming later in the week, aided by the news that they are pushing on with a value tier rebrand of their Smartprice range.
Adding more products to the overall mix and ensuring that they’re following the market in terms of Tesco, and Sainsbury’s who have revamped their value tier lines of course.
It’s a quick turnaround for the work with 4 weeks mentioned; it’s clear the Issa brothers don’t hang around and their entrepreneurial focus will drive things forward quicker.
More to come on Asda but there are some positive signs around the new ownership in the early days.
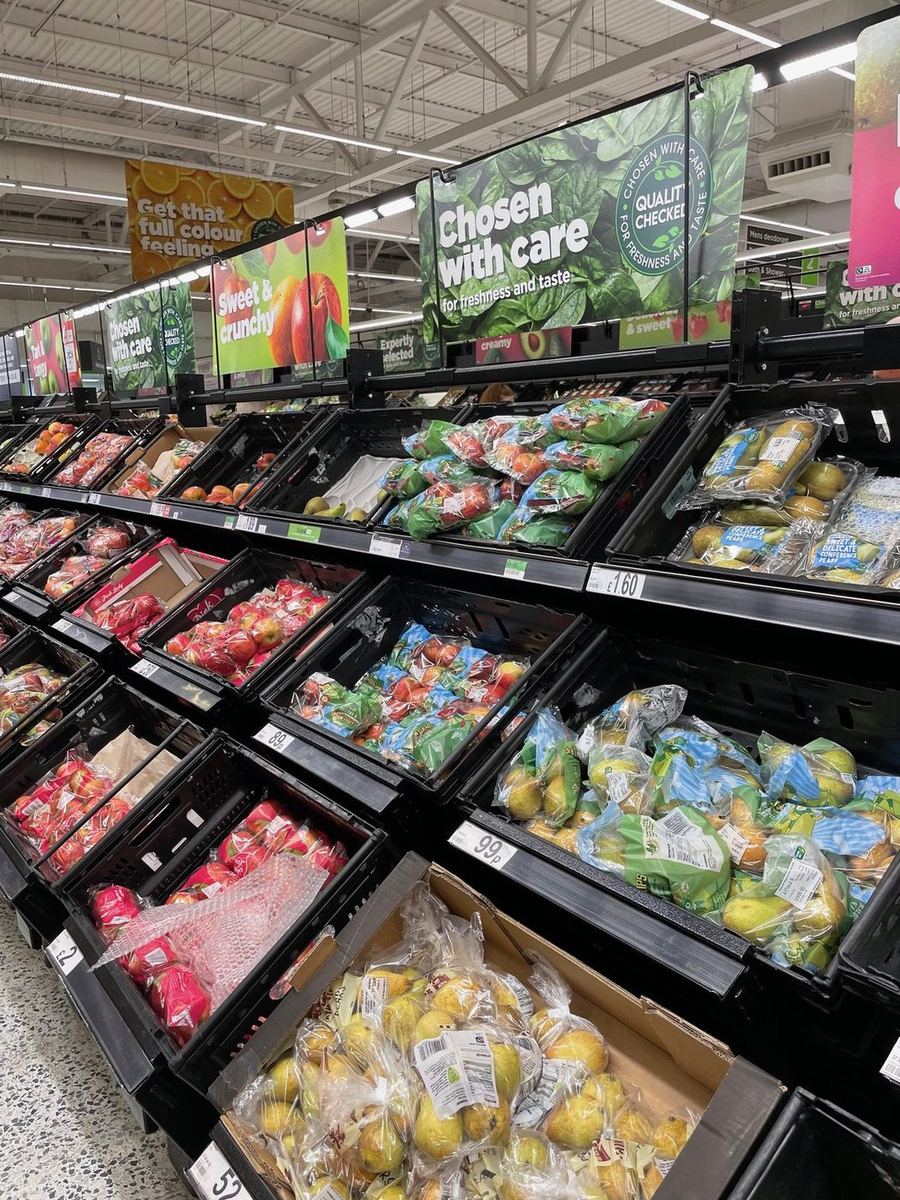
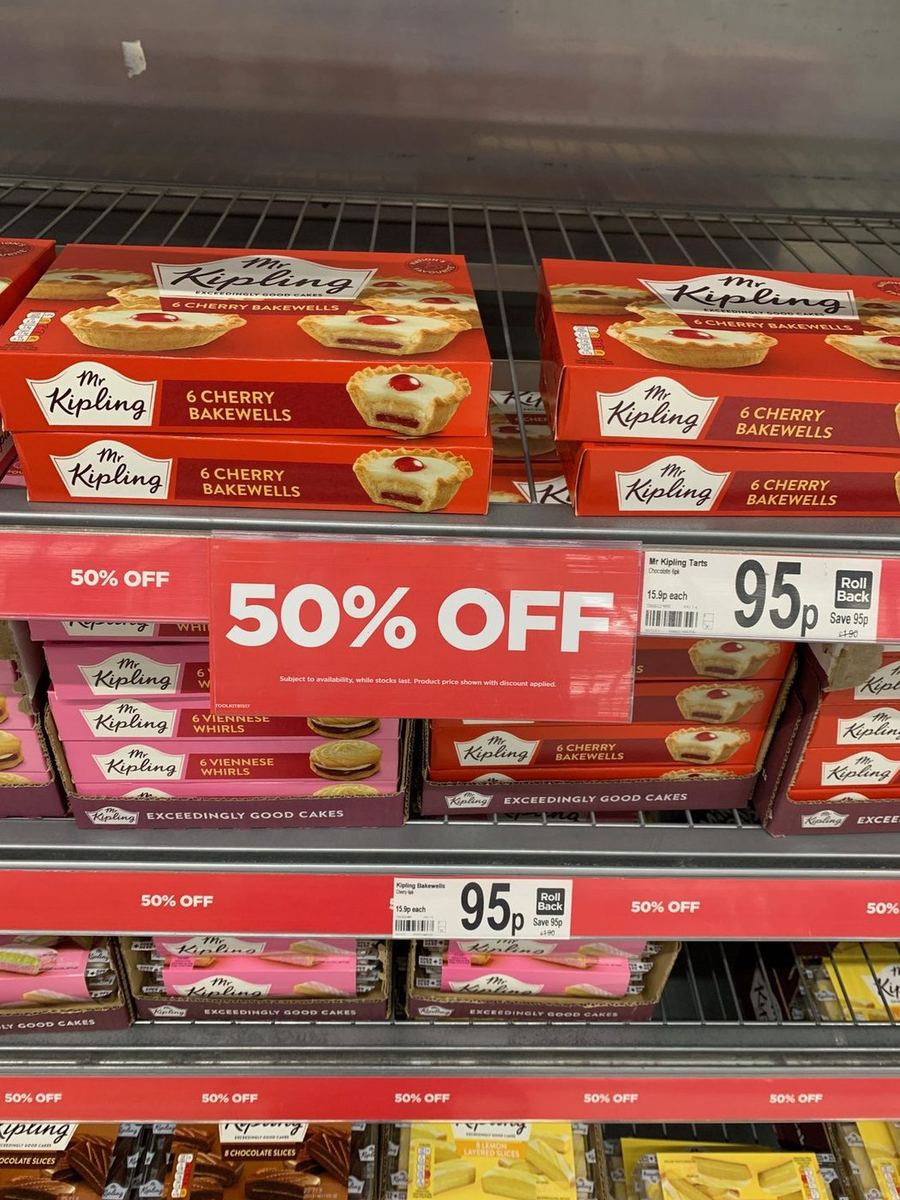
More to come on Asda with the changes seen so far and the work that needs to occur in store to drive things forward even further.
Speed is of the essence for the Issa Brothers, quite understandably given their debt pile and their work across the food service and retail space.
Want to find out more about our services and the wider retail market?Subscribe to this service and benefit from our quarterly market presentations.
From the Grocery Insight newsletter archive, first sent to subscribers on 23 March 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.