A few things we spotted in stores this week
7 April 2022
View this email in your browser
Forwarded this email? Sign up for your own copy, today.A warm welcome to“a few things we spotted in stores this week”(*)
(*It’s actually last week) but still, it is relevant and part of a new feature for you, as dear readers and subscribers to our retail newsletter service.
The aim of this email is to highlight things that are occurring in stores, what we see and our thoughts on said observations.
Our clients benefit from our observations on a periodic basis and we’d like to extend the same service level to you, so consider this email as an opportunity for us to showcase some of our thinking, too.
Of course; our emails are designed to help you keep a track on what’s occurring in the market and everything within.
But as we aim to expand our reach - Did you know that we have an image platform that features every single image we capture, split by retailer, every single week?
Not just that; but we have over 60 seasonal events collated too! These are split by relevant sub category too. So you can review Easter Eggs, by year. Or Mother’s Day Floral, even.
Subscription models can be entirely varied and we’ll even help pick out the best imagery for your requirements!
See more of our best in class image platform.Grocery Insight has a team of 3 (self included) who are out visiting stores every week and amongst the 8gb or so worth of images that we collate, decompress and use to demystify retail for our clients…
But there are numerous gems that we collate, that I want to share; to showcase the nuances that make up the retailing space, every single week.
So here we go. The good, the bad and the ugly of retailing.
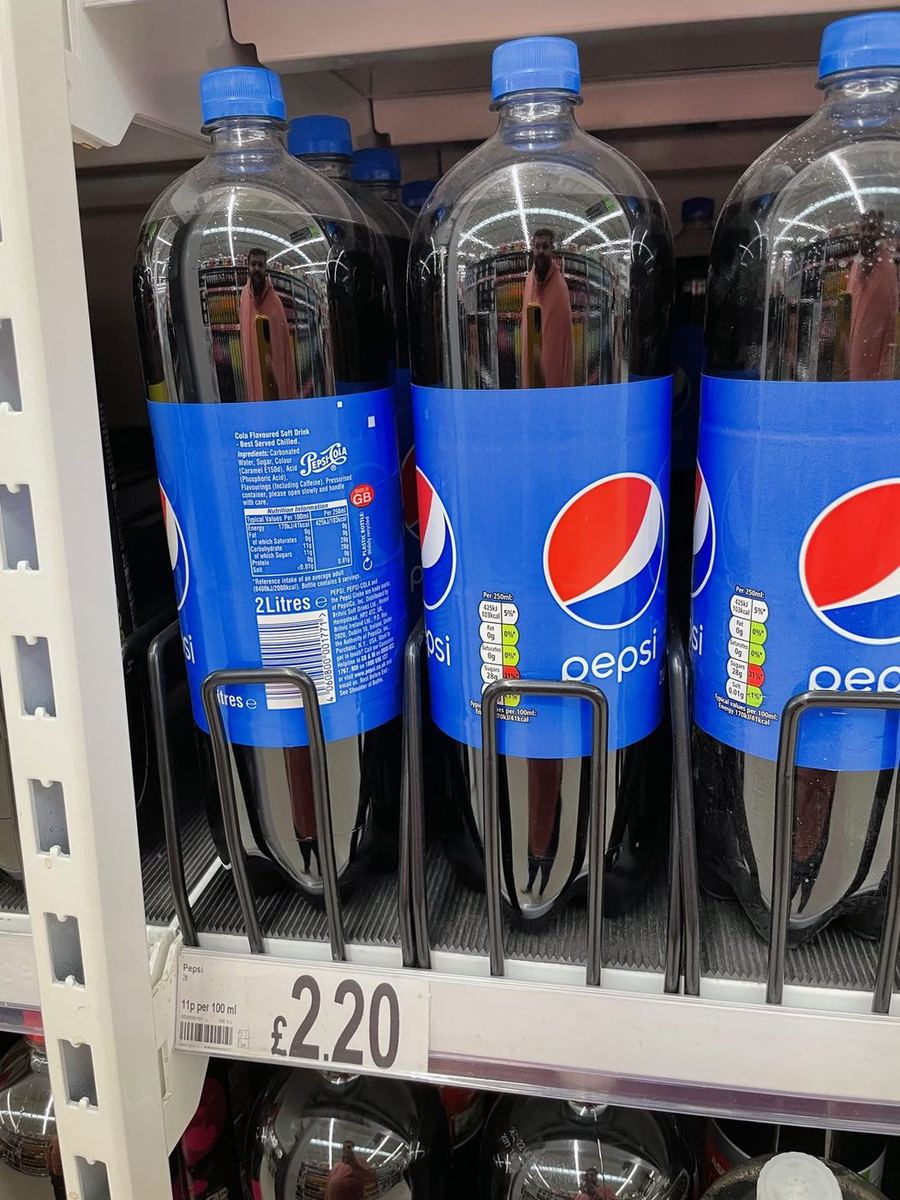
The prrice of core products:
We have our value tier tracking price spreadsheet now active which charts the movements on the value tier products since 2019 (late) and the data is very interesting indeed.
Our subscribers (more below) get access to this data alongside in depth store visit reports and general feedback on the market too.
But for the core products, prices are rising, there is no doubt and shrinkflation is another consideration also.
The core prices? Pepsi at £2.20 is hefty and stands out on shelf, badly. A reminder that even one price can harm the perception for the entire chain.
Meaning 25,000 products are all out of kilter in a customers mind.
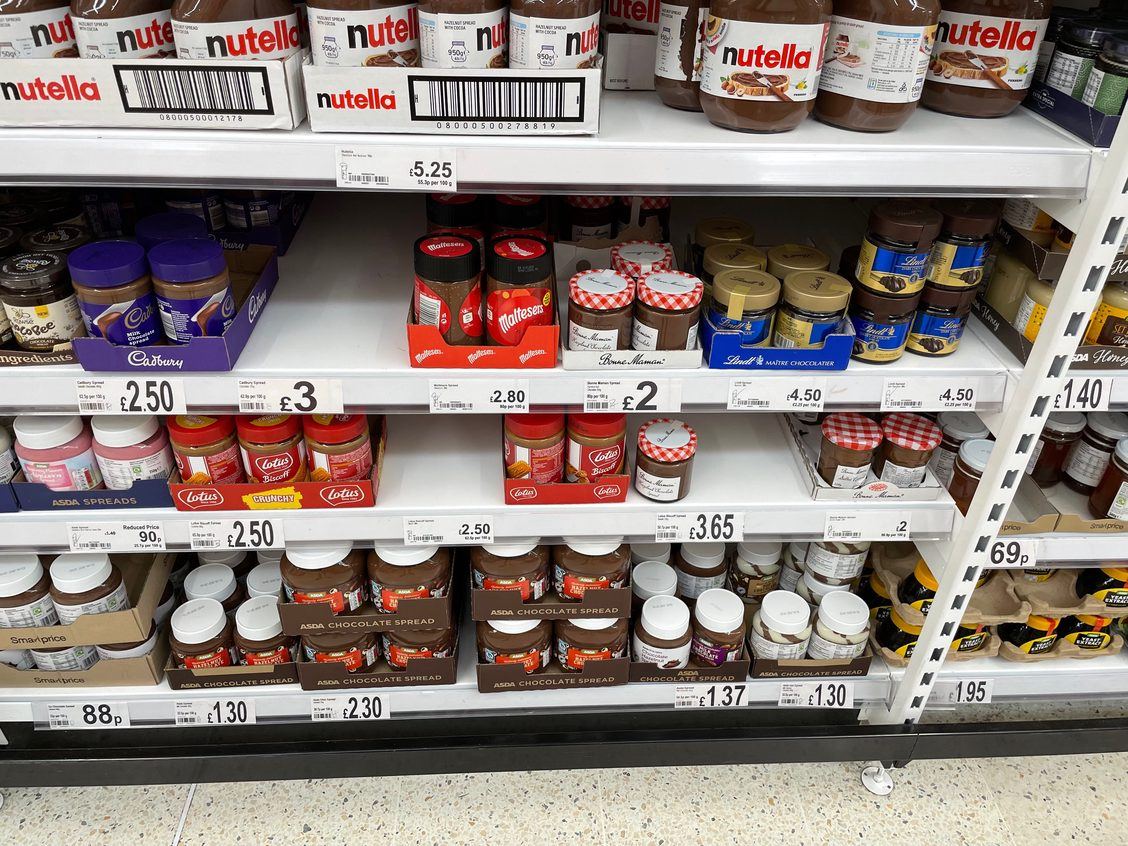
New labels in Asda:
Notable that for all the positives of the Asda machine under the Issa brothers inside their first year in charge. (subscribers long read this week)
Other changes have also been noted at the shelf edge; you’ll remember that Tesco pioneered the simple label, with a GIANT price point.
We noted this week that Asda appeared to be utilising smaller price labels with a new design (evocative of the Sainsbury’s mid 2000’s vintage) and back to what they used to within Asda.
With prices rising; it’s wise practice to change the labels so as not to highlight the prices that we are all paying, everywhere, due to inflationary pressures.
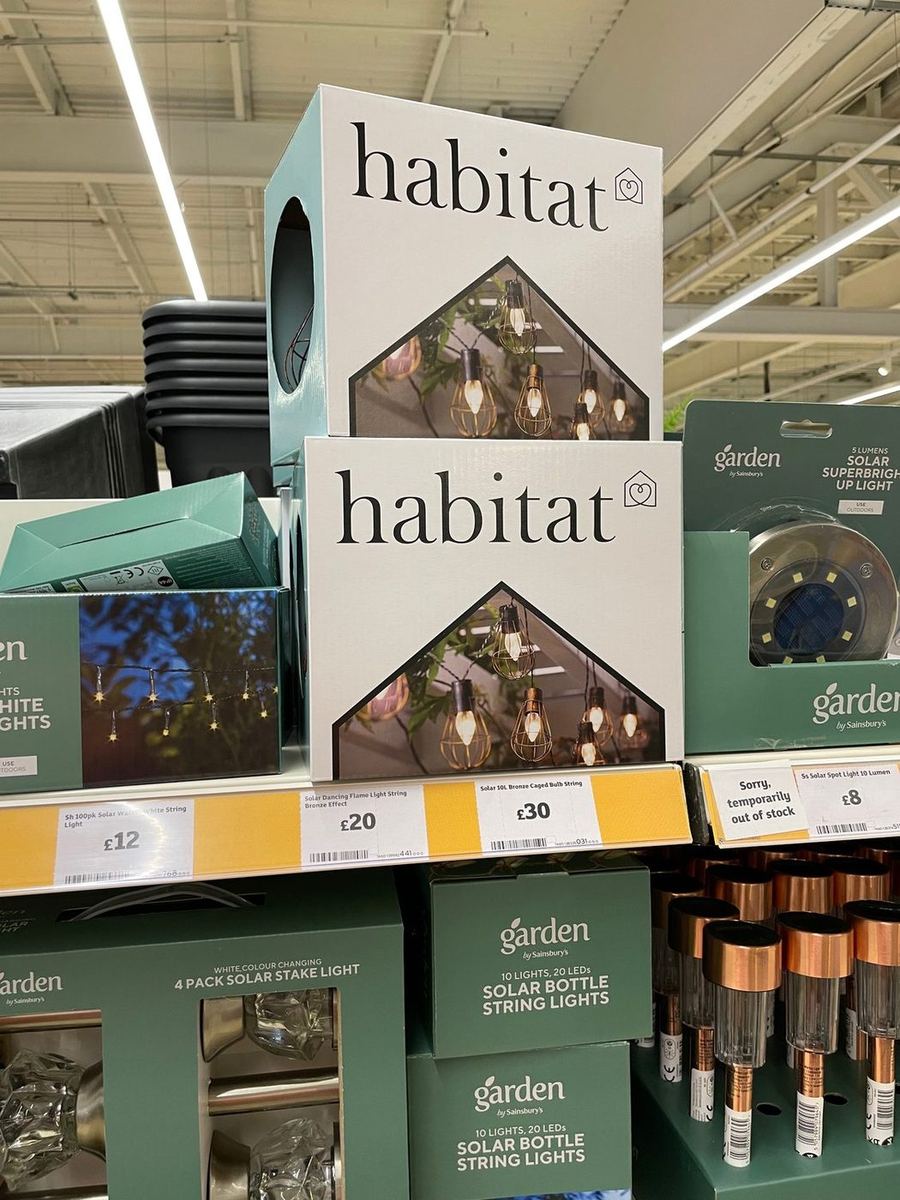
Habitat everywhere:
Sainsbury’s are rolling out their Habitat brand absolutely everywhere in an attempt to grow non-food sales, which have tanked in COVID and indeed, were on a difficult platform pre COVID anyway.
Unifying the brand with more Habitat is not a bad idea, especially for Argos who have never had a strong own label, so utilising Habitat more (versus Sainsbury’s Home) is a good move here.
In the stores; we have seen an emergence from Habitat across numerous categories, including Stationery and also in to convenience stores via the Party & Stationery ranges there too.
More recently; their Crackers were noted for Christmas and in to Gardening & Summer with Habitat branded lights.
This alongside a revamped Garden own brand too.
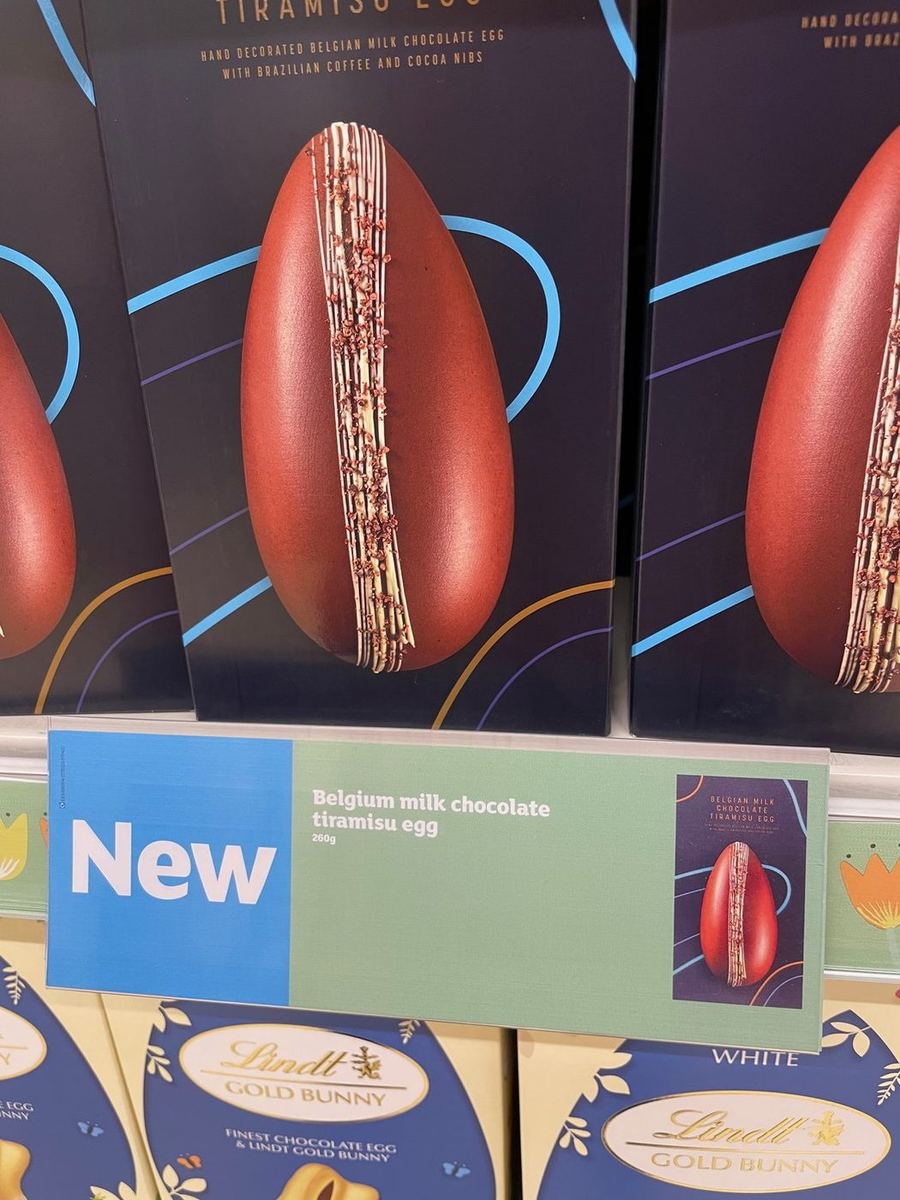
Belgium Eggs
A disproportionate amount of my time is spent highlighting things that aren’t right for customers, such as the wording on this signage.
A minor element? Perhaps.
But the reality is that; it’s not a minor element when you consider that this one sign has passed through artwork, printers, the depot network then made it to store to be sited at the shelf edge by a well meaning colleague.
Of course it matters. If not; why produce the sign in the first place?
It’s not right, is it?
Belgium Milk Chocolate like Switzerland Milk Chocolate just isn’t right.
The journey to getting better is all about examples like this being eliminated.
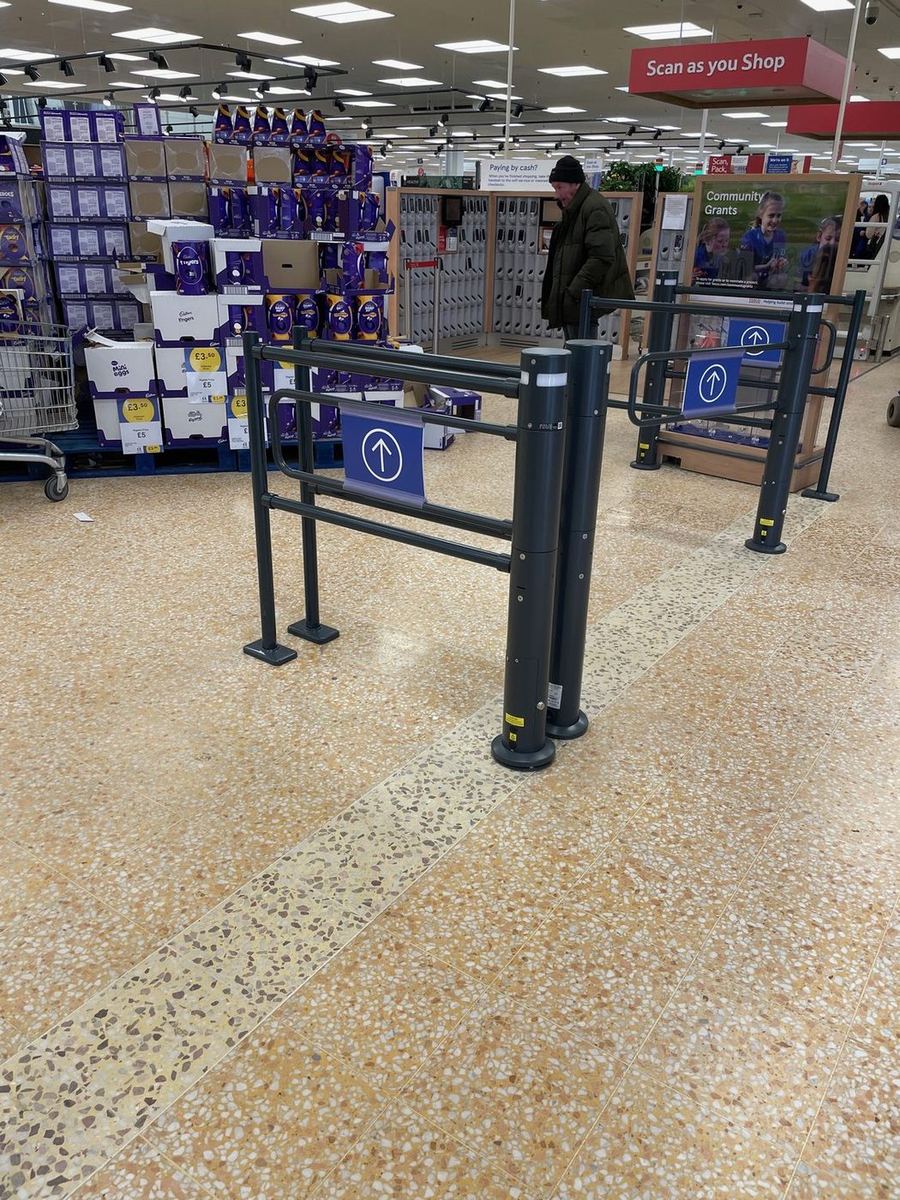
Security gates are back
Very much of the 1990 retailing vintage but then dispensed with for aesthetic purposes, security gates have started to return in an attempt to prevent trolley pushes (IE a full trolley just pushed out without checking out).
Or indeed to stop people thieving and just bypassing the front end entirely, but Tesco have started to add these back in to stores and indeed, we have seen other retailers like Morrisons do the same.
I am no fan of the over focus on shrinkage, it drives the wrong behaviour in stores and ultimately impacts the customer.
But security gates make sense, on paper at least and will have a negligible impact on the customer and help to alleviate some forms of theft.
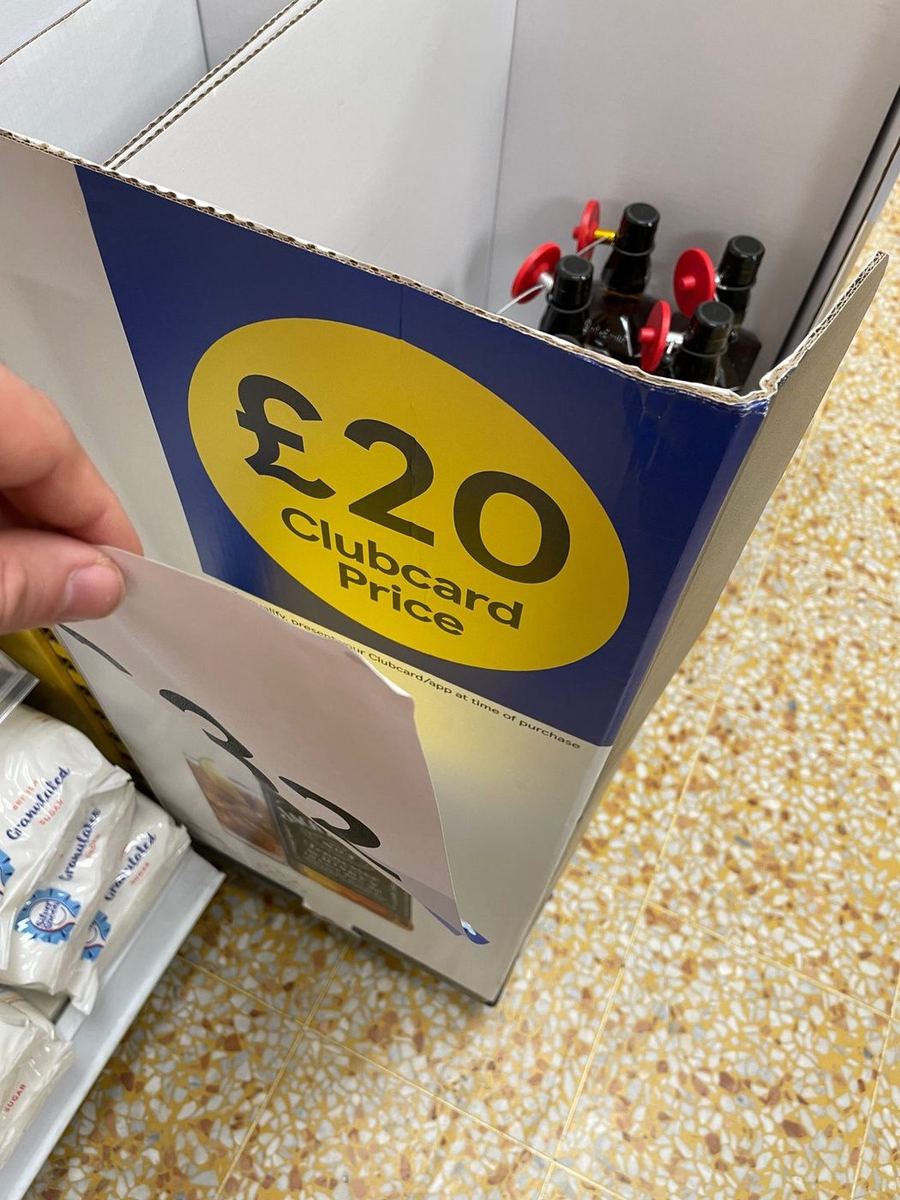
Oh dear
The practice of utilising pre filled shippers has been a major positive from the viewpoint of productivity and indeed, driving sales too.
These units are disposed of once the promotion period is completed and the stock can be then ‘fed’ back in to the overstock on shelf. However, this is not preferable due to the fact that loose stock is a nightmare to manage at a store level.
Counting becomes difficult and the stock just ends up being ‘no one’s job’ to replenish on shelf.
So it’s understandable (to a point) given that offers come and go; that the store decided to keep the unit on the shop floor.
However the higher price is now applicable so the store printed off some A4 and stuck it over the lower price. Totally wrong.
Whilst well intentioned, this generates huge negative price perception for any customer seeing that the price of a bottle of Jack Daniel’s has risen by £12.
Which again, puts the store at risk of informing customers that the price of all 25-30,000 items is similarly poor value.
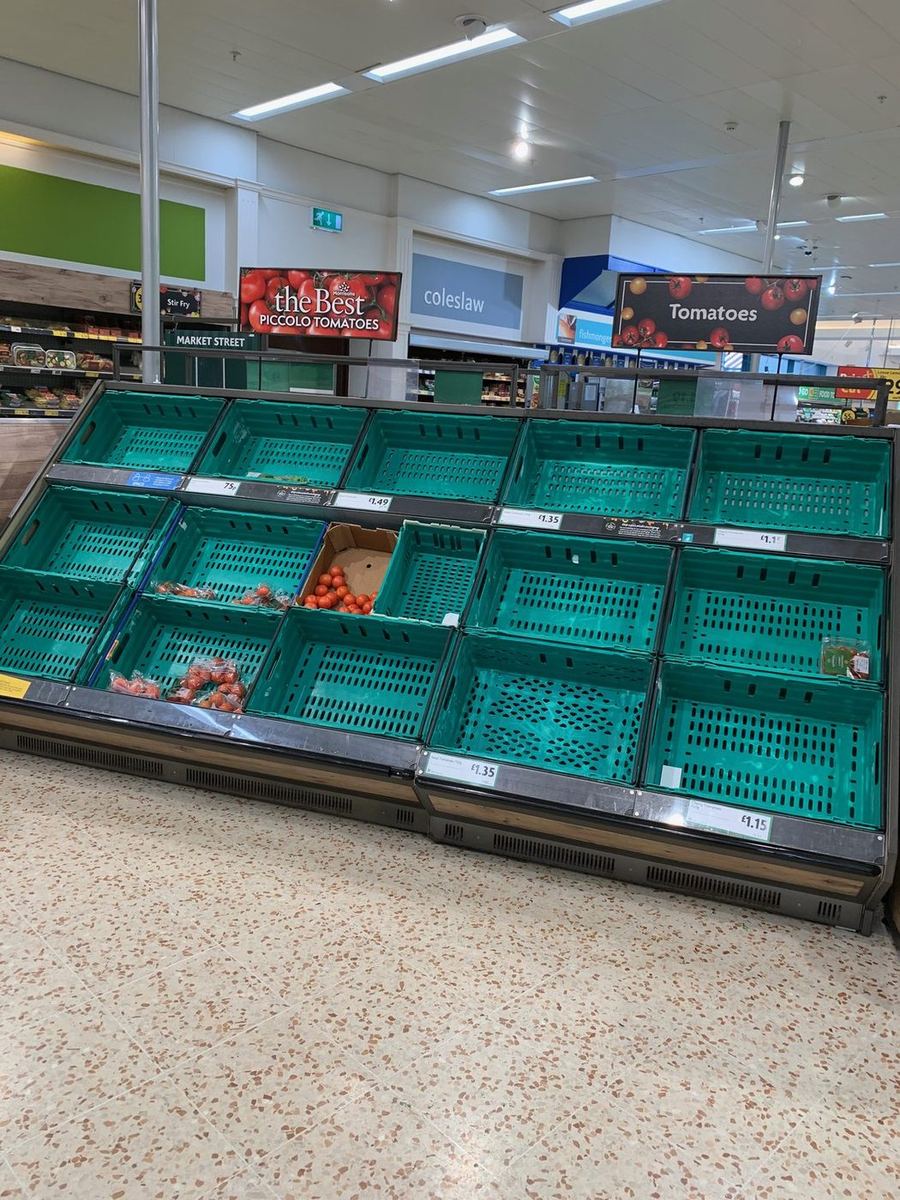
Produce availability
There have been some issues with Produce via Spain (and the Saharan dessert winds causing issues with quality) but the availability levels in Morrisons were near beyond belief here.
Really poor, but a reminder of the ever growing impact of the various challenges (COVID, Brexit and the rest) on the supply chains.
Especially for 4pm on a Wednesday.
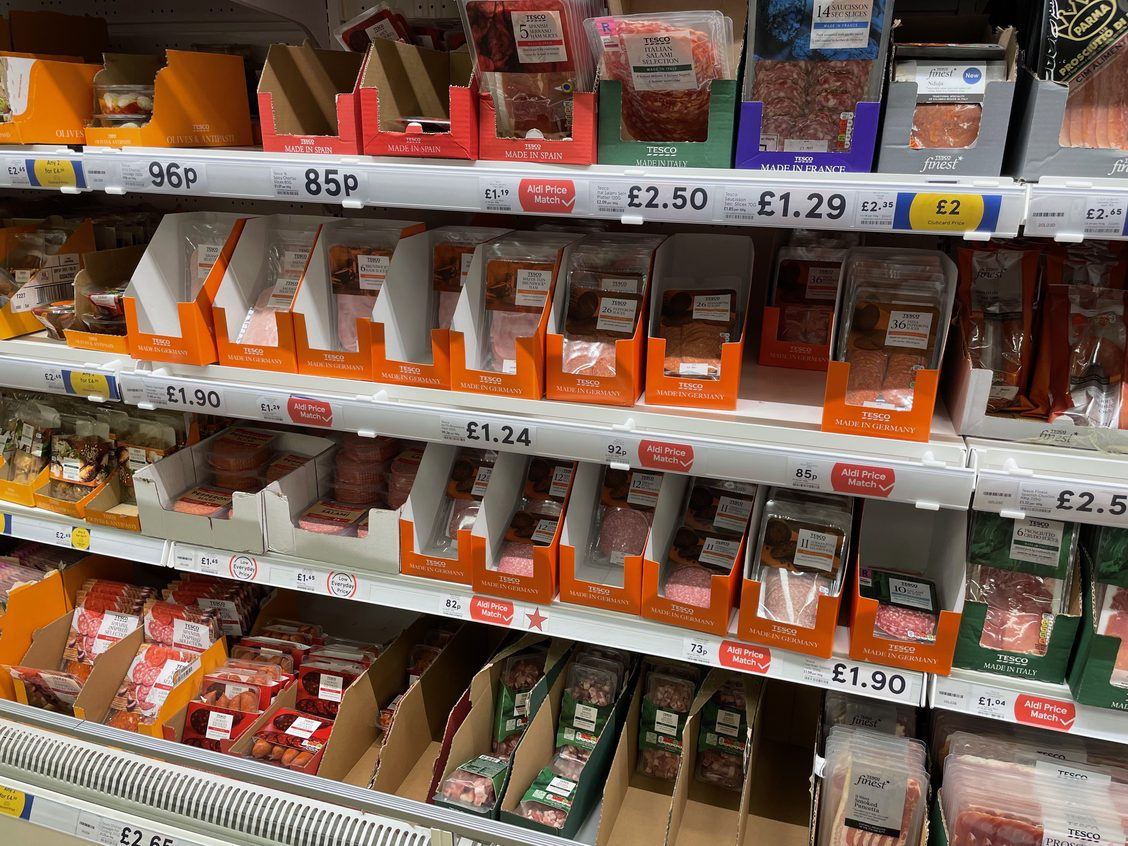
Tesco working hard on prices
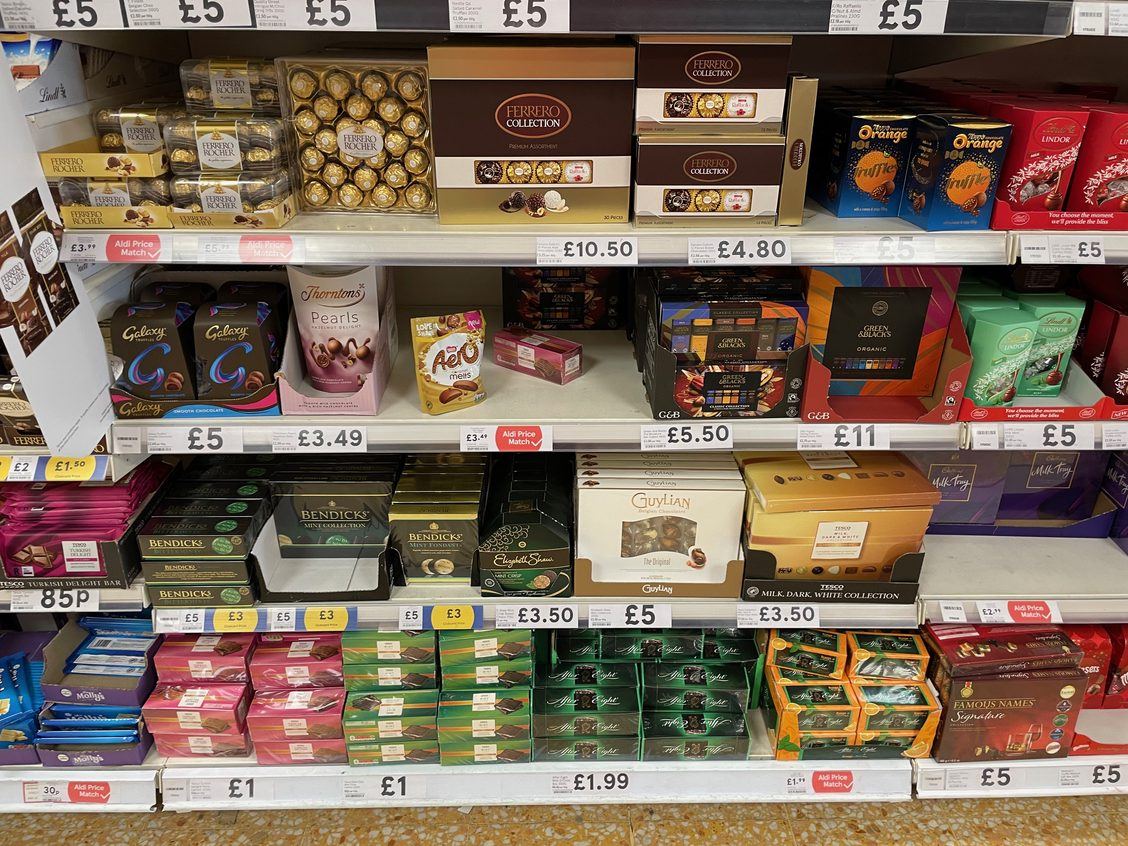
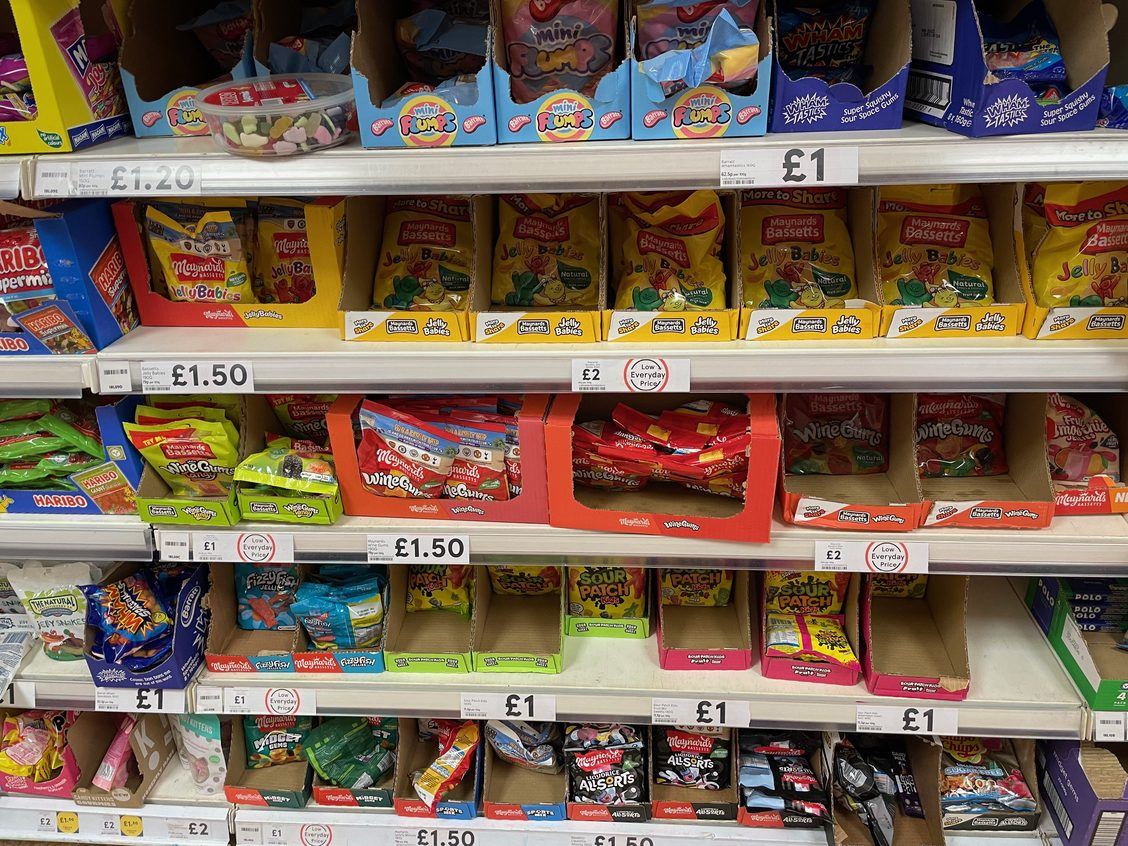
I was struck last week and just how much Tesco have expanded their price match vs. Aldi, with some categories dominated by signage (not just on value tier now, but increasingly on mid tier products too) but also brands with “low everyday prices” noted across a number of categories too.
Whether these are compared with Asda, Home Bargains, B&M or a combination of all three plus discount is unclear, but it does give a very real impression of the prices being kept in check.
However, the shipper work (further above) risks undoing all that.
Customers can see everything
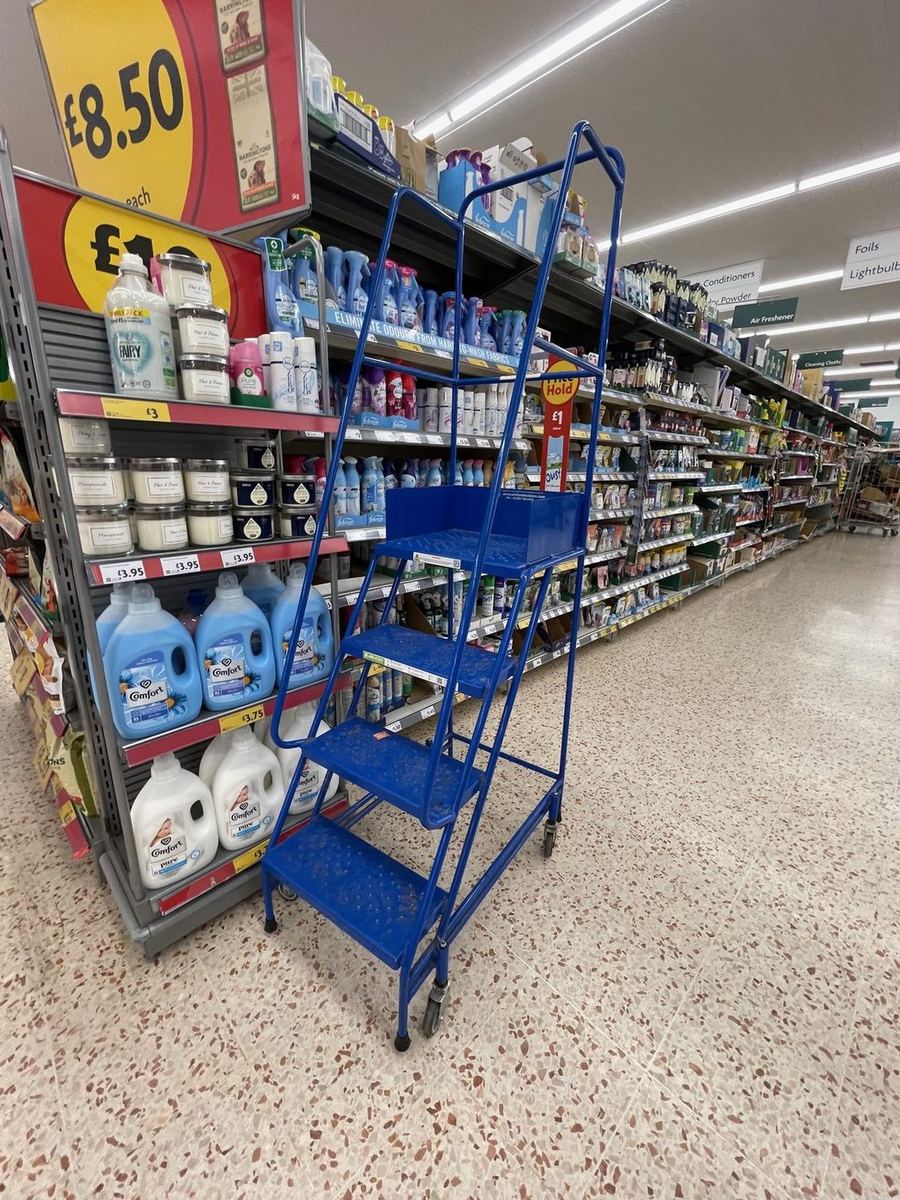
There are rules around Ladders and their usage too in stores; especially those with top stock but Morrisons were caught here leaving these in the aisle.
Customers don’t want to see these, or dodge them or have their children climbing them.
Nothing is ever so important; so these couldn’t be removed from the shop floor to safety. Plus it’s a food retailer, not a branch of B&Q.
Plant care of the week
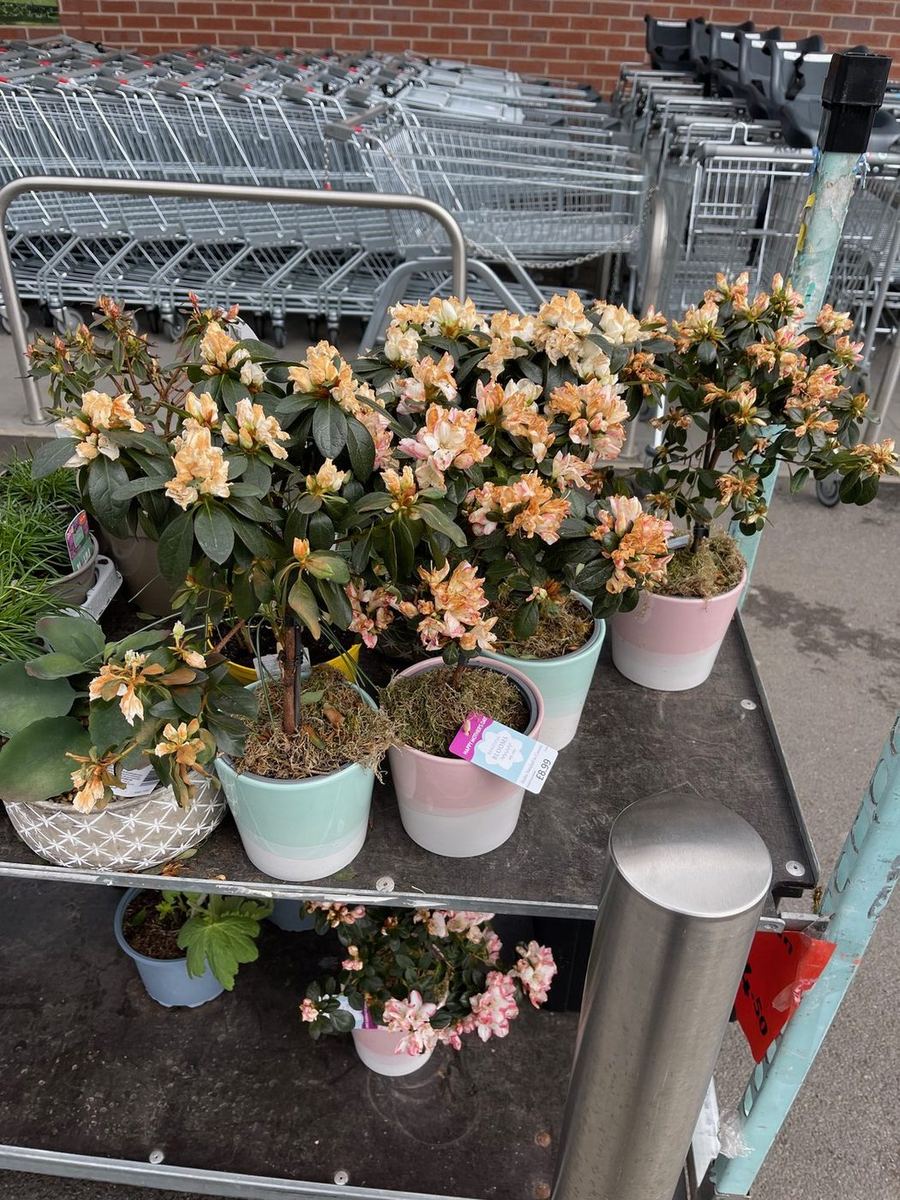
Winner = Aldi.
This ropey selection of Plants situated outside the store hardly sets the barometer for quality and freshness inside.They badly need watering.
Very poor indeed, everyone walks past these on their way to the store!
Inexcusable.
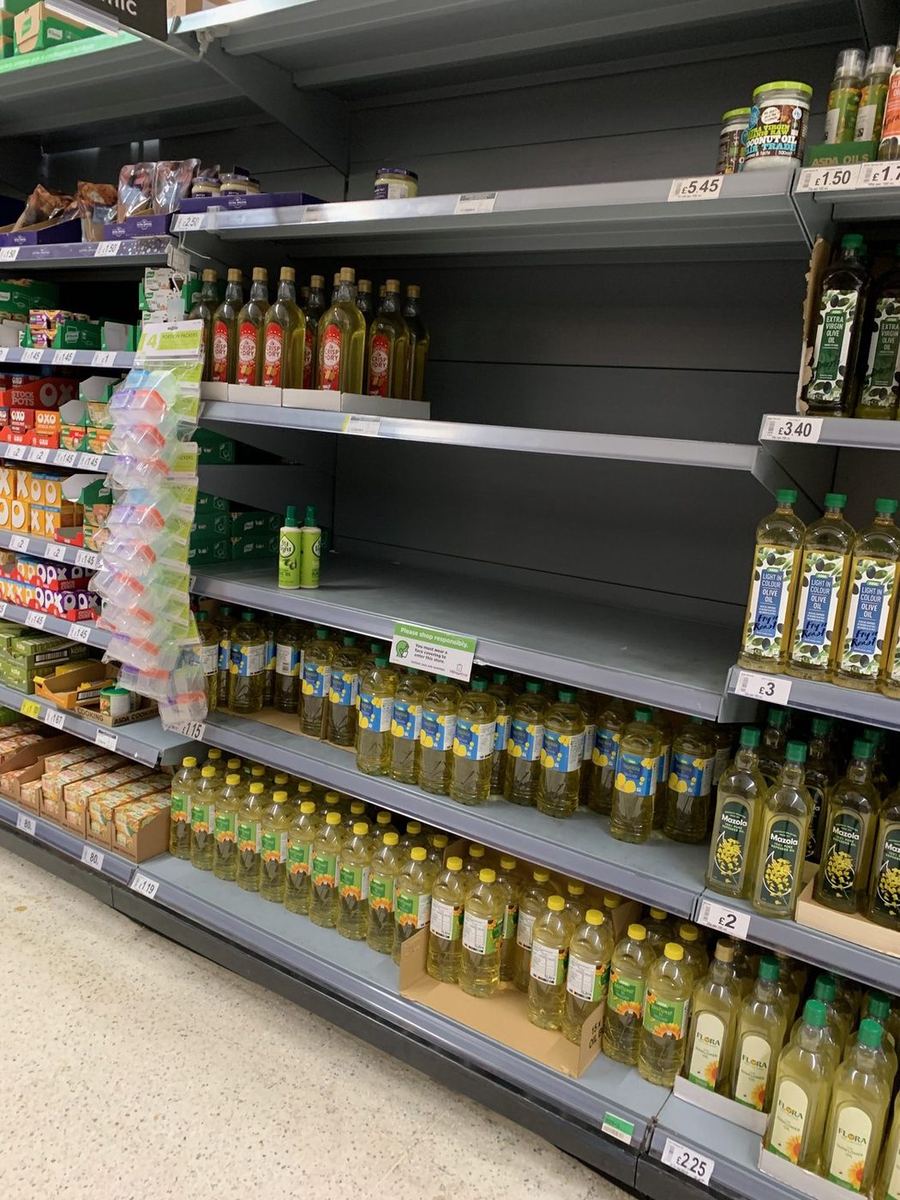
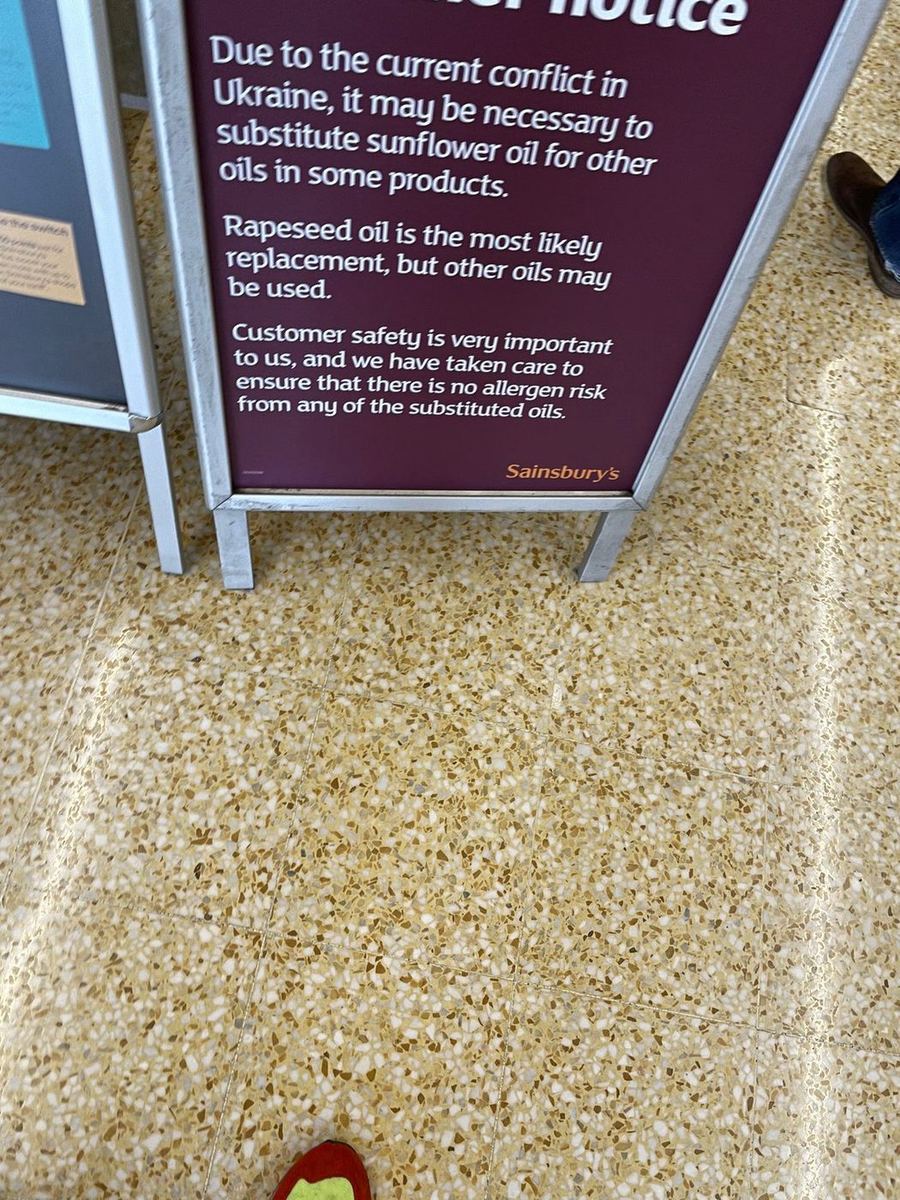
Sunflower Oil challenges
With the fallout from the Ukraine / Russia conflict starting to impact the price of Wheat and indeed the supply of Sunflower Oil via Ukraine, we are now seeing availability challenges on the shop floor too.
Sainsbury’s featured signage alerting customers to the shortage and indicating that products with Sunflower Oil would be replaced with Rapeseed oil and other types of Oil too.
Not good for customers and yet more complexity for the food industry to navigate as well.
So there we have it - a few observations from our thousands of images captured in the last week or so.
More next week. Feedback and thoughts are all welcomed.
For more in depth coverage of the retail industry alongside access to our pricing data and webinars on the sector too, why not join our retail by email service?
Don’t miss anything in retail, again.
Subscribe to our retail by email service here
From the Grocery Insight newsletter archive, first sent to subscribers on 7 April 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.