Retail By Email - Issue 472 - Tesco delivered
25 April 2022
View this email in your browser
Retail by Email - Issue 472 - TescoTesco deliveredWe were in London for Easter and there was lots to look at from a retailing perspective. Tesco also posted their results and pointed to rising inflation being a huge challenge amongst a welcome return to strong profitability.
Alongside their stated ambition to protect market share, despite inflationary pressures which has been notable with their promotional campaigns and Clubcard prices.
The sell off / fall in share price due to the guidance was near madness from the investment community, given their openness but it’s their money and the market hates uncertainty.
Interestingly if Tesco are strongly flagging the issues around inflation (and there are many) what about the rest of the market who don’t have the war chest that Tesco has?
(On that note - Asda and Morrisons have announced price campaigns today!)
Indeed, the challenge for the market is the theme of uncertainty and there’s plenty of that around.
The conflict in Ukraine impacting Sunflower oil and the price of Diesel has only made things worse for a market grappling with energy prices (rising up and up) alongside the ongoing recovery from COVID and a labour shortage / Brexit based issues too.
Tesco were entirely reasonable to guide with a fair old margin on the profit number, given that we just don’t know where we’ll be this time next year.
We never do, arguably, but the reality is that now, it’s arguably even harder to guess.
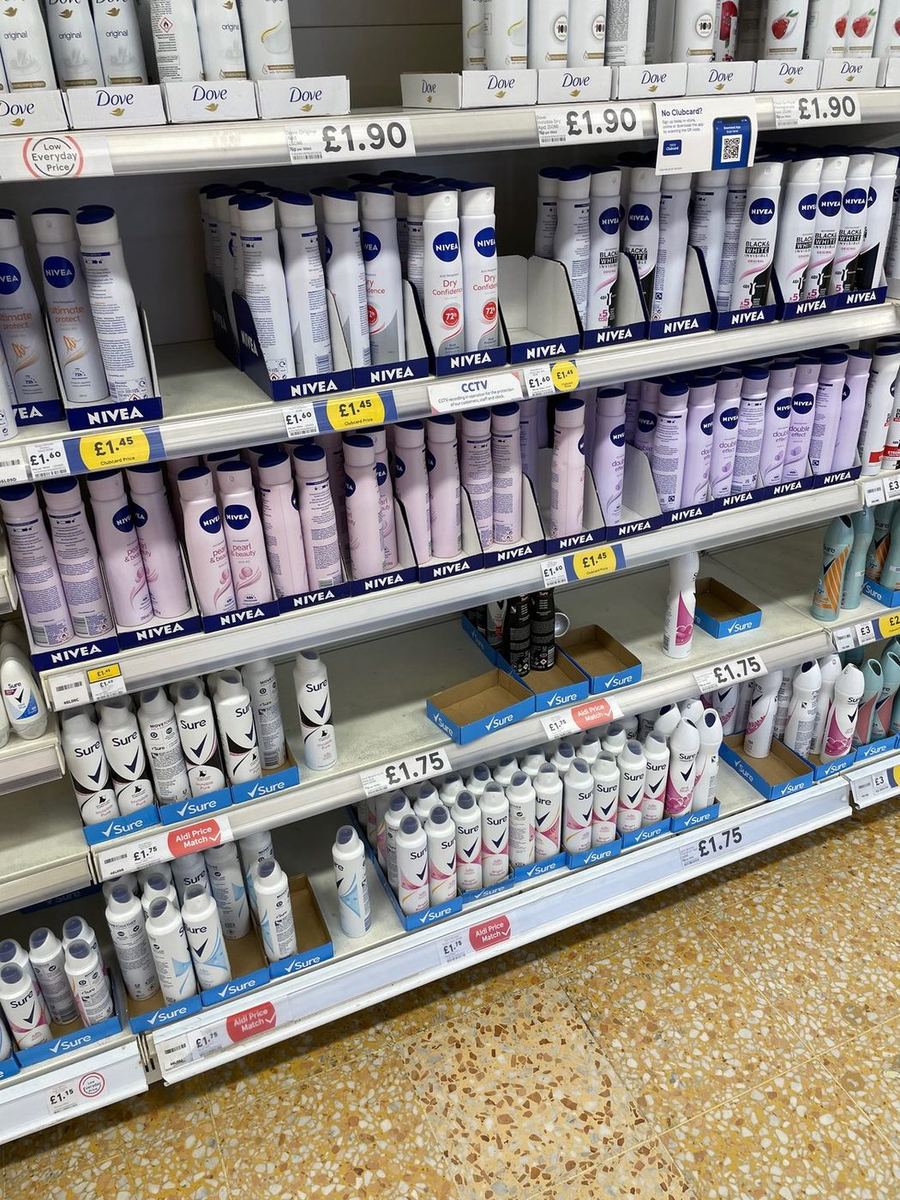
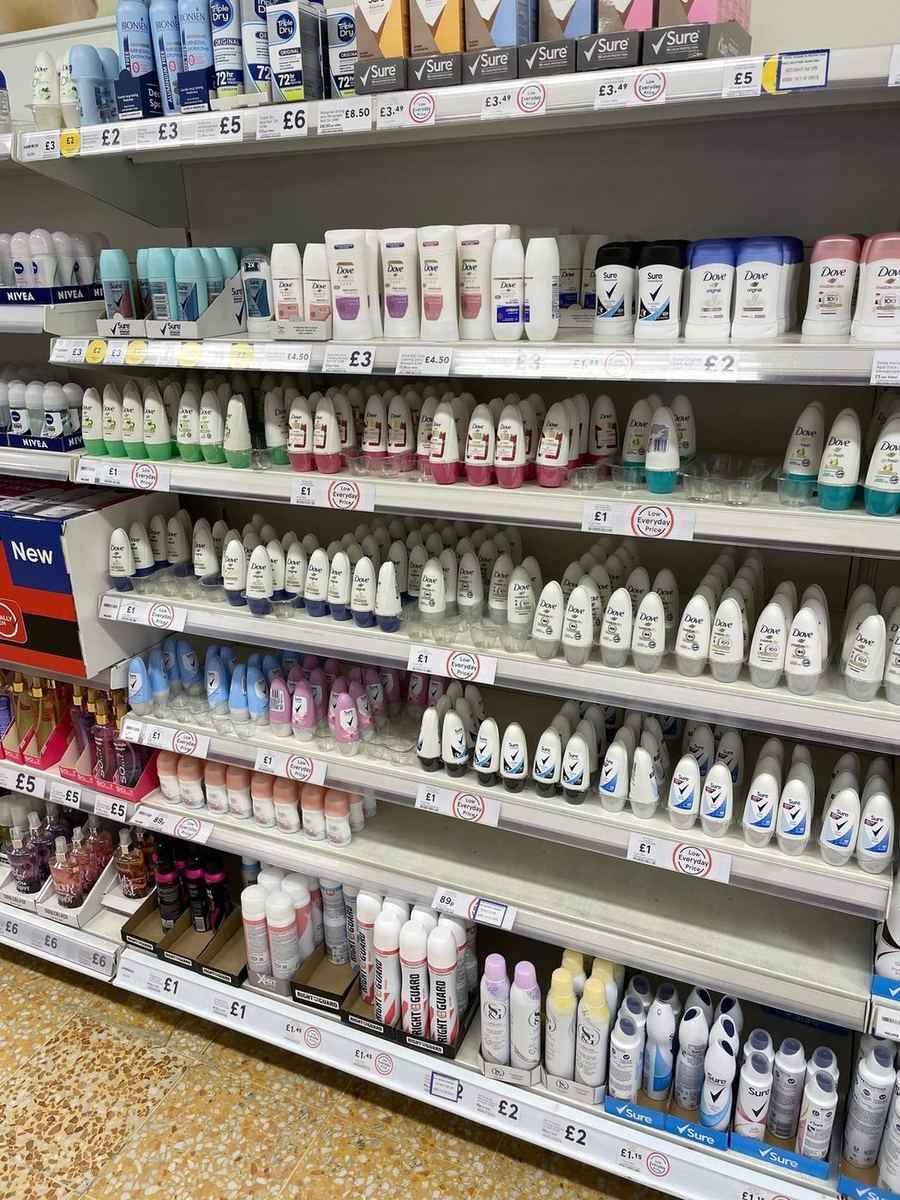
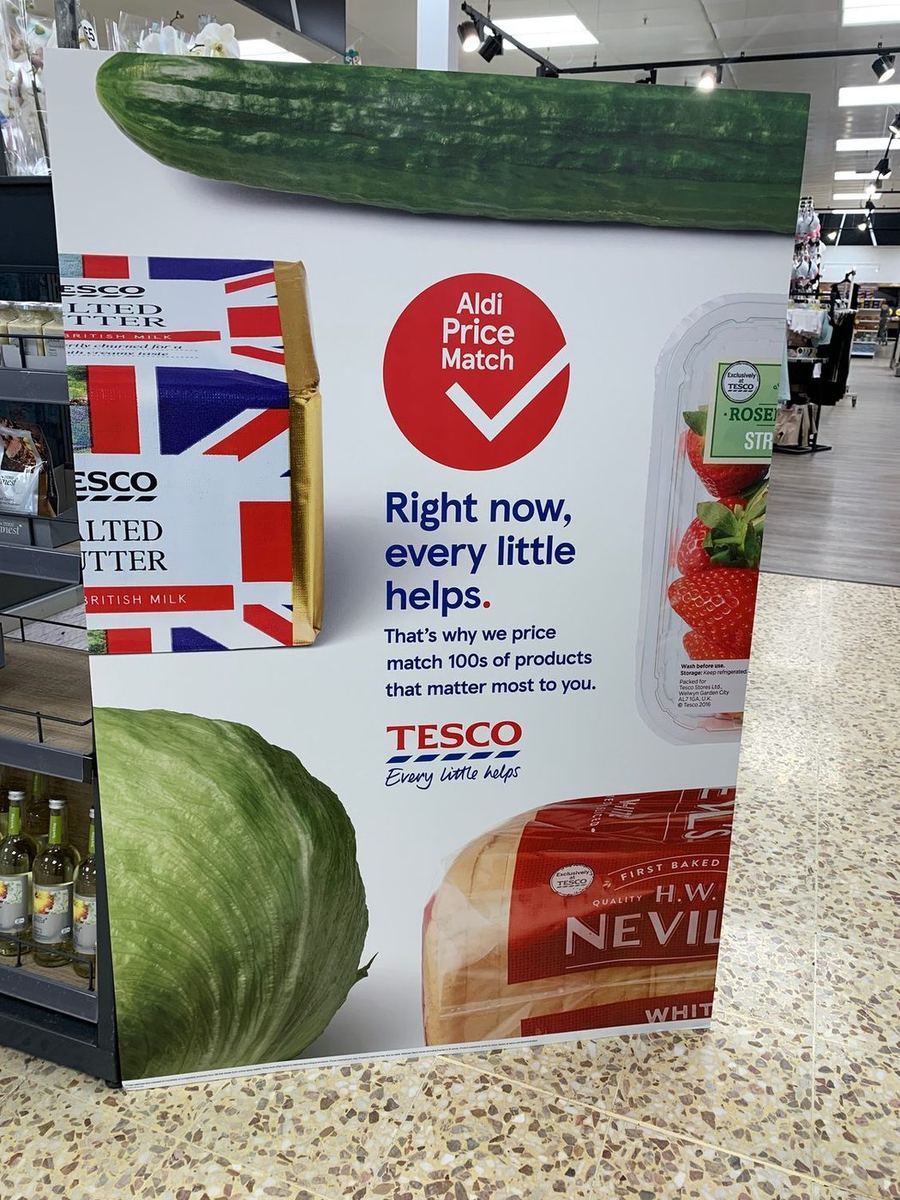
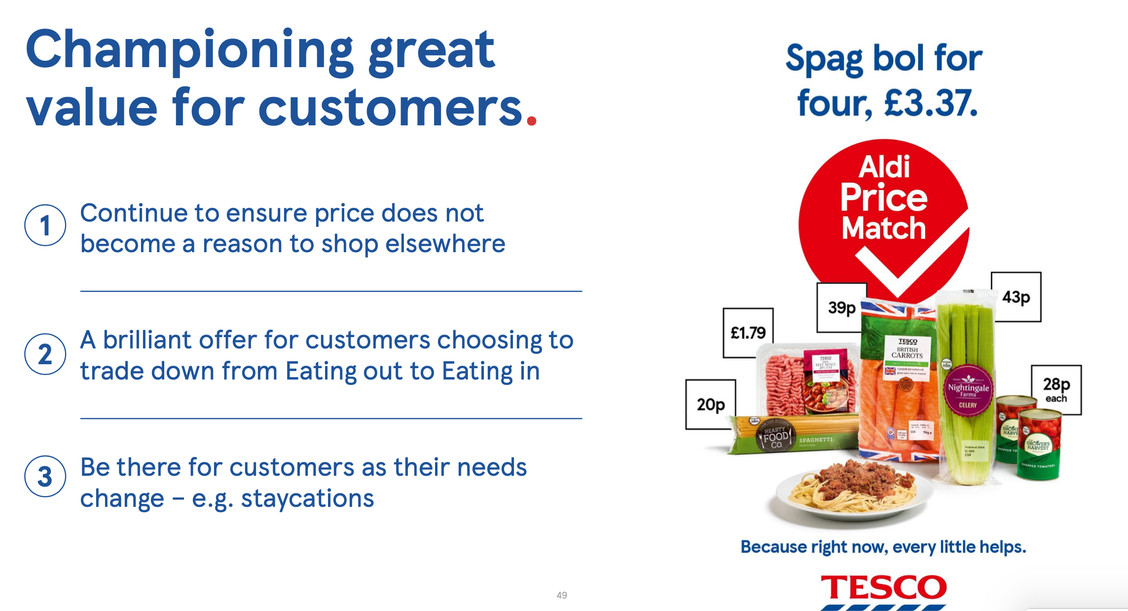
In terms of the results - I thought it interesting that Tesco highlighted their low price, everyday mechanic alongside the Aldi Price Match (further expanded now).
In stores just before Easter; it felt as though the Tesco value comms had been dialled up notably.
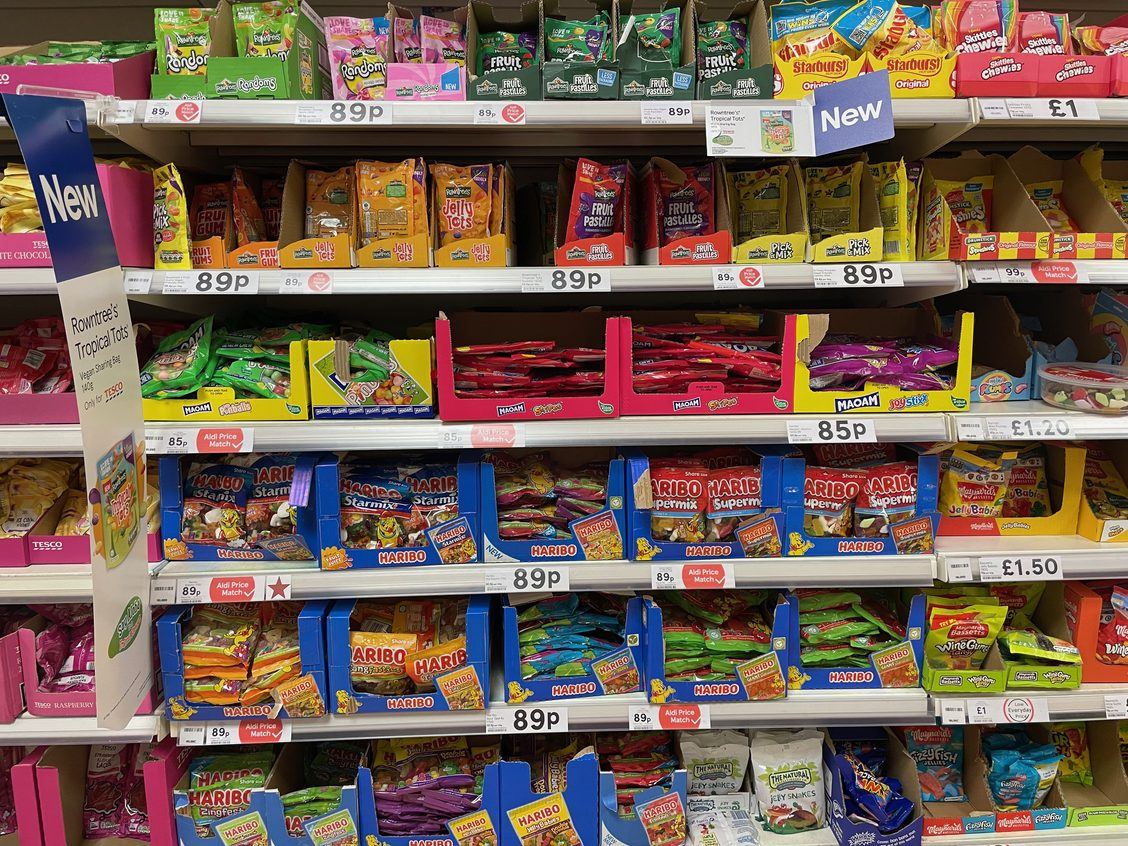
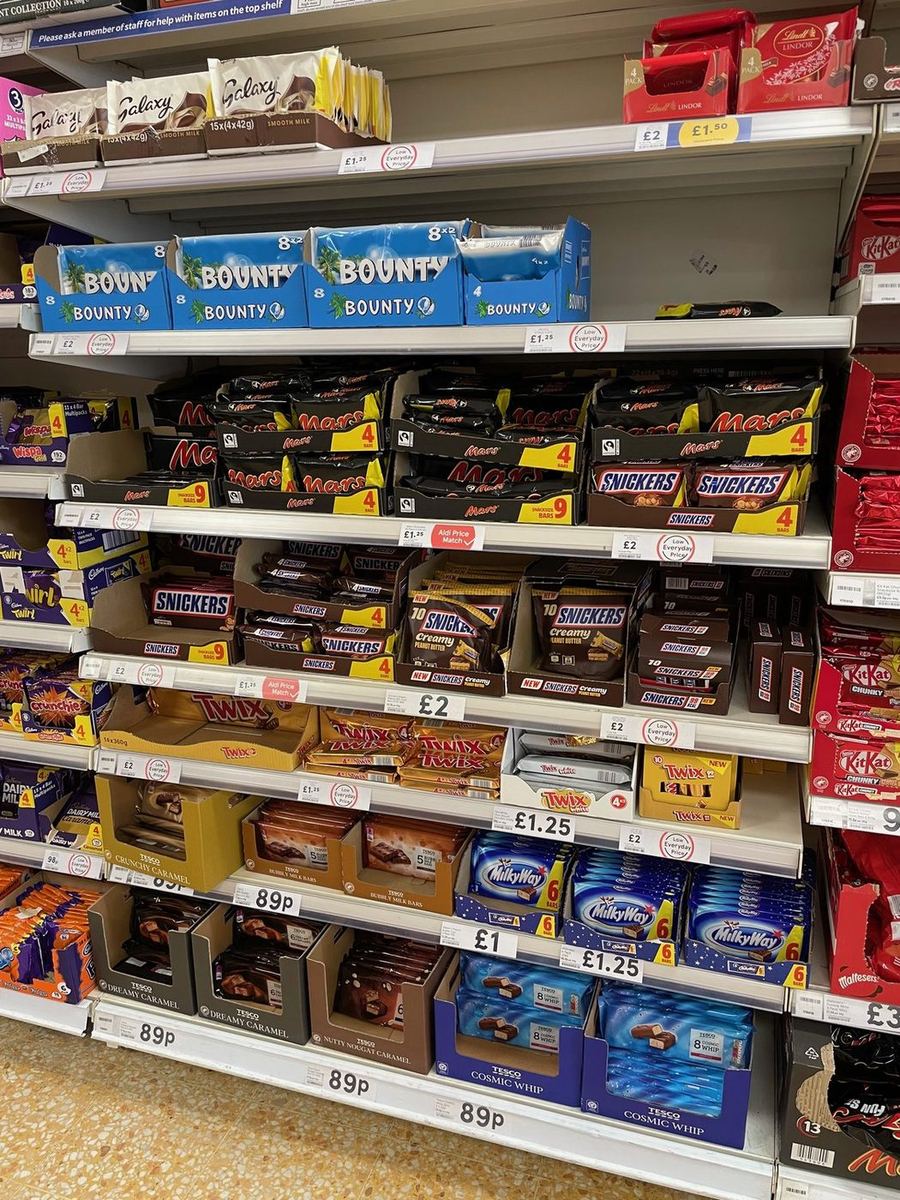
As the scheme has expanded even further in recent weeks; we have seen more signage matching up to Aldi, but also, more of their low everyday price across brands and own label.
It’s unclear who these prices are precisely matching up to, but the smart money would be on Asda alongside B&M and Home Bargains, too.
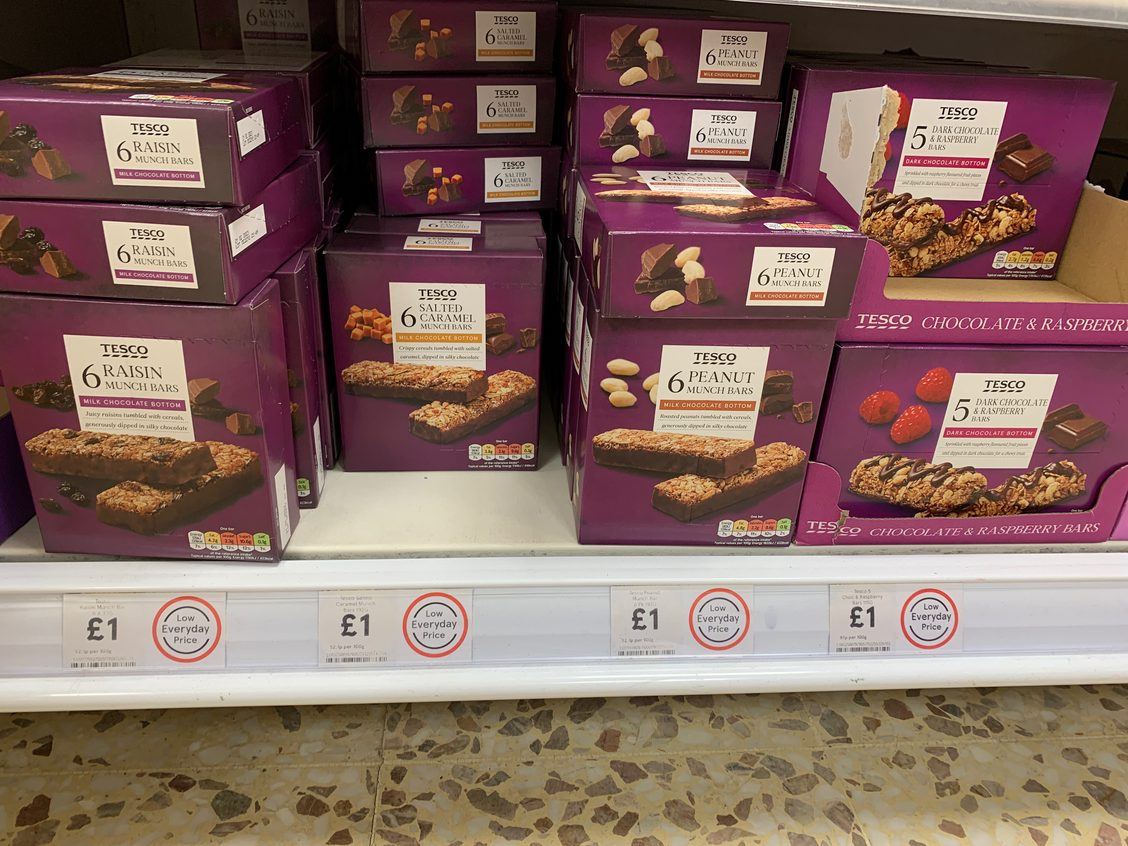
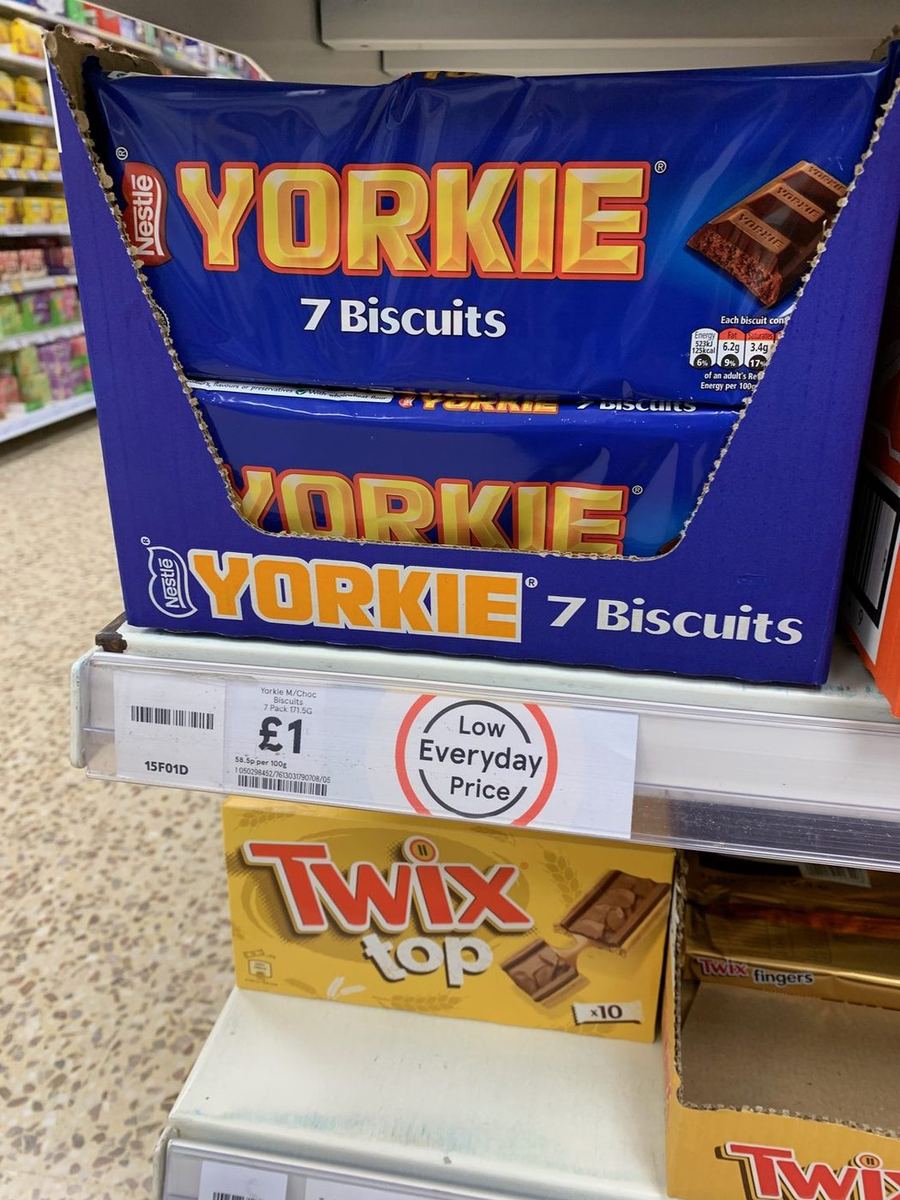
Also notable with their price comparatives is that Health & Beauty benefits from a huge number of low everyday price lines.
Given the strength of Home Bargains and B&M in this space with their lower price points this is a smart move, especially as both retailers will pick up increased basket spend given their expansive range and low prices.
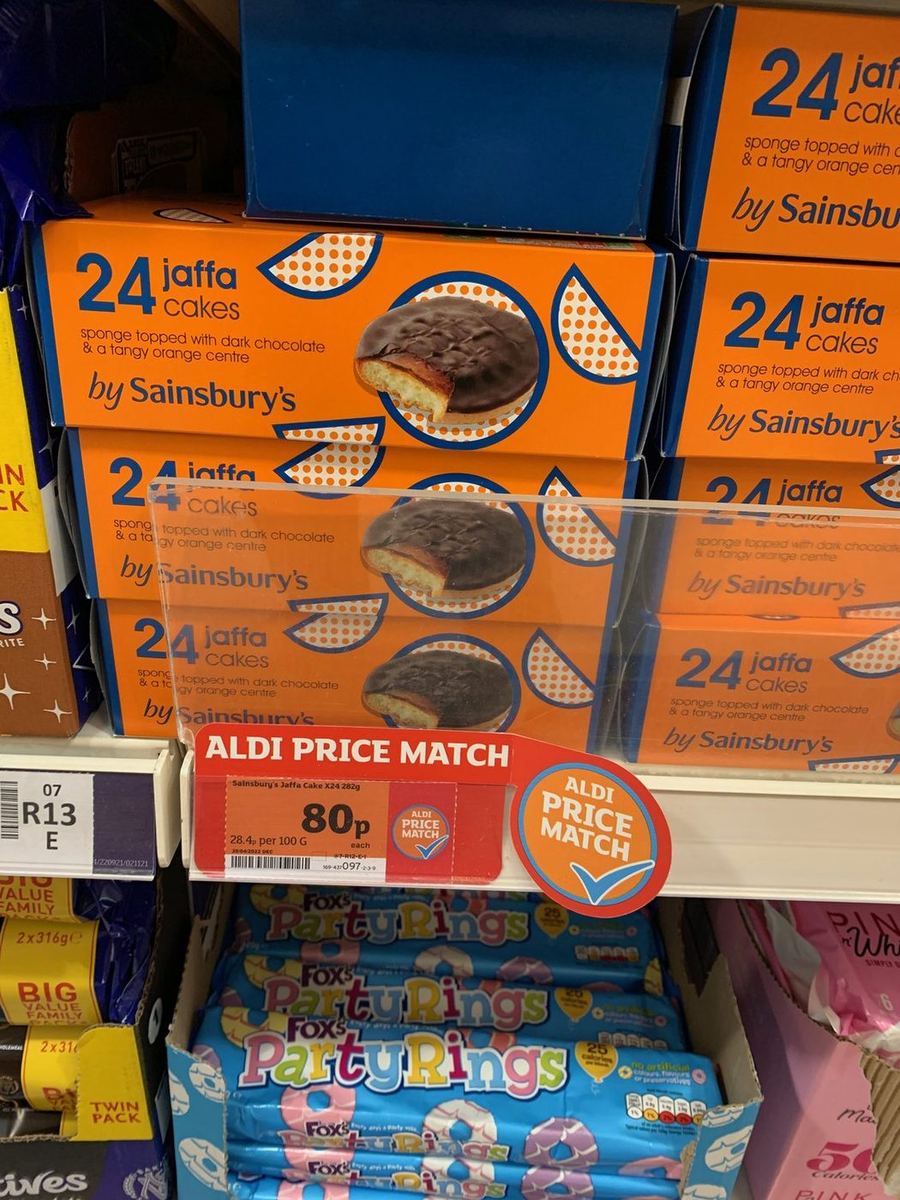
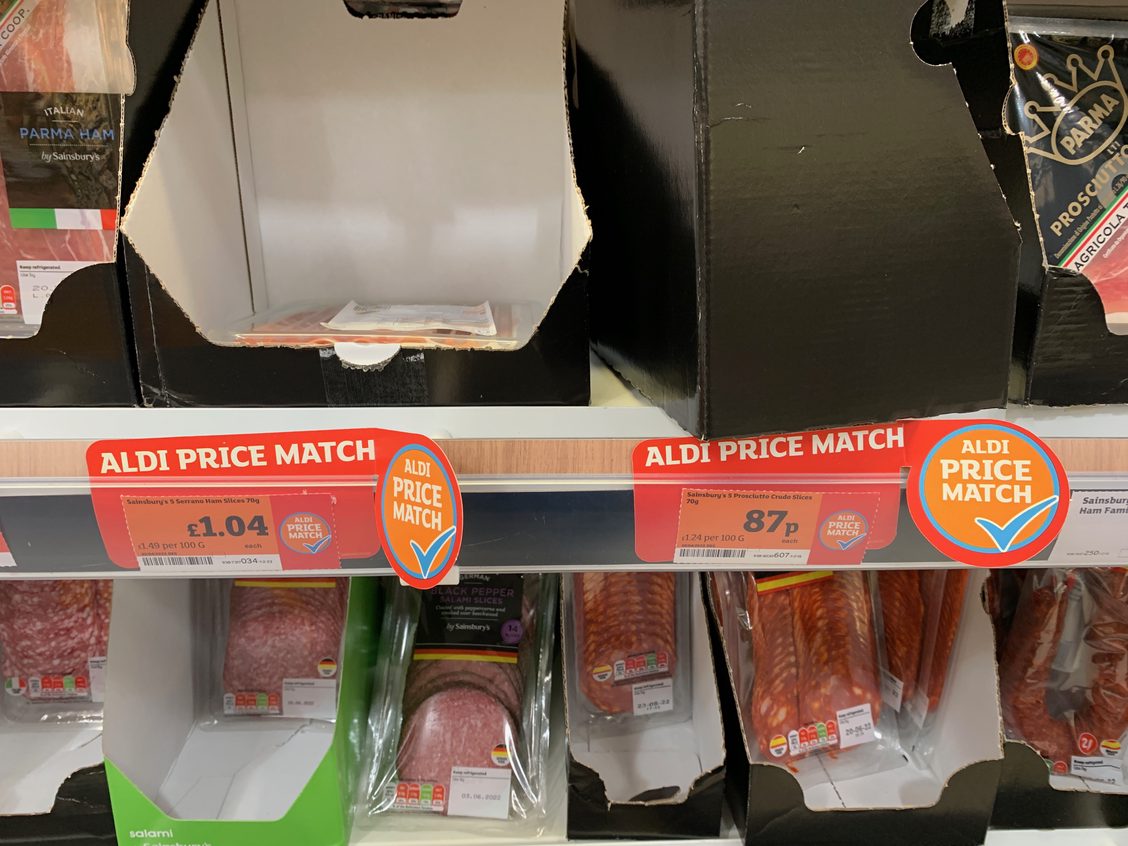
Sainsbury’s who have imitated Tesco in the recent months, with various changes to their value tier items, mimicking the price match and now have added further signage to their shelf edge.
This signage highlights products which are being price matched to Aldi, there are 150 or so of them and it’s powerful enough, allowing for stand out on the comparable lines.
Also notable in Tesco was the change in strapline from (subtle) admittedly, but their “now more than ever, every little helps” change (first seen in COVID) returned with a slight change to; ‘right now, every little helps’.
Highlighting the pressure on customer budgets and indeed how that translates to their spending power being diminished due to rising fuel and energy costs is vital.
Customers like to know their retailer of choice cares, or at least appears to care and be in line with their mood / sentiment.
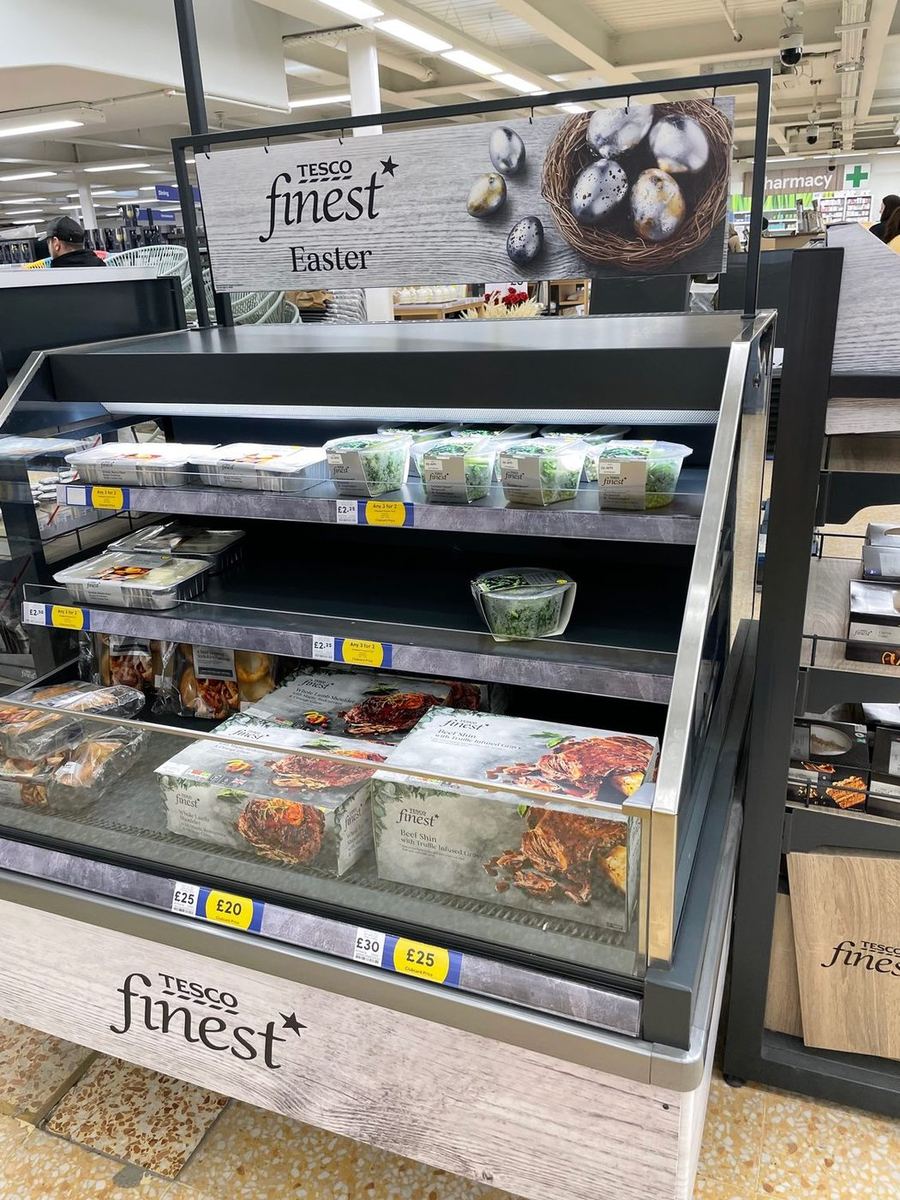
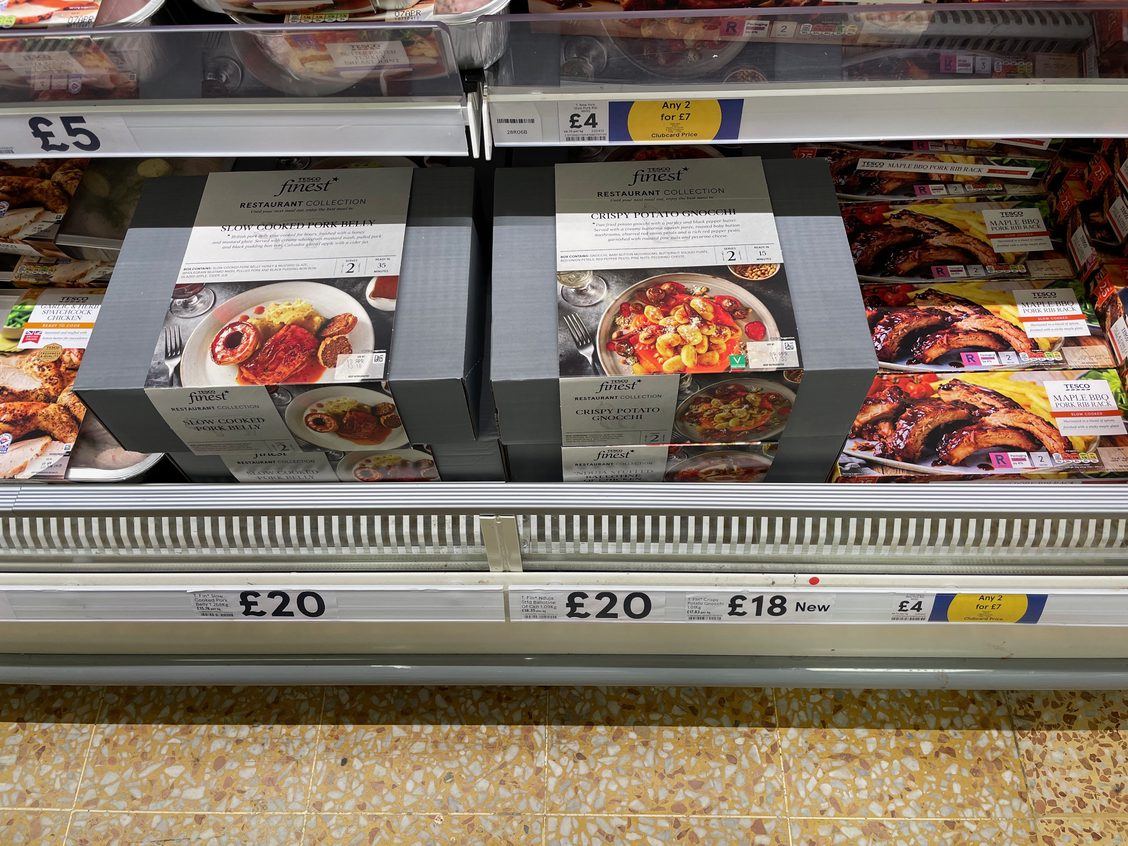
Another move by Tesco has been to solidify their Finest premium tier and move their margin on utilising Finest.
We have seen customers saving on the core ranges and then encouraged to spend on Finest, to treat themselves, almost.
A smart move and the growing exposure of Finest has been notable in recent months.
Images are to come tomorrow from the launches via both Asda and Morrisons for their latest price campaigns but the market is certainly hotting up around inflationary pressure and how retailers may look to mitigate this.
Or at least try mitigate some of it. But we can see from the Tesco slides that the market is very difficulty and inflation is unavoidable.
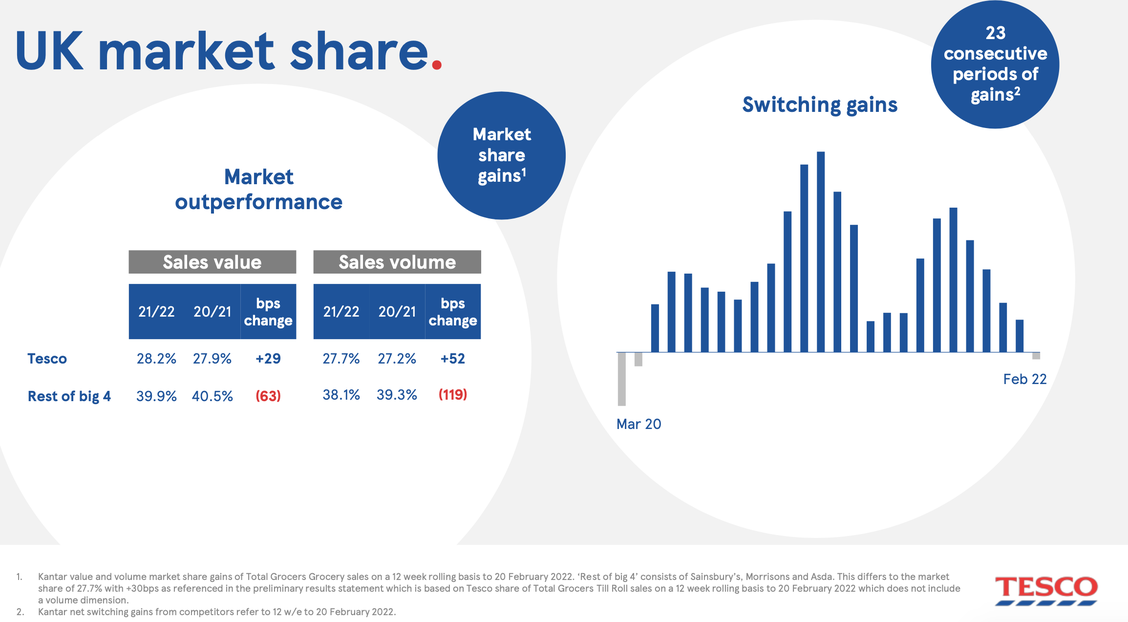
The Tesco market share has held up though, with the hard work versus Aldi for so many years now paying off.
23 consecutive periods of gains and it’s been a hard fought battle. it’s clear that where Tesco may lose customers, they also gain from their rivals.
That’s not just discounters either.
It’s clearly the case that Tesco are gaining from the wider market too, Sainsbury’s often suffer when Tesco succeed due to the geographic overlap but a well run, performing Tesco means they gain from almost everyone due to their size.
We can see that their marketing too. With low priced Spag Bol and ensuring that customers don’t need to go elsewhere, alongside Clubcard prices is becoming a solid combination for customers.
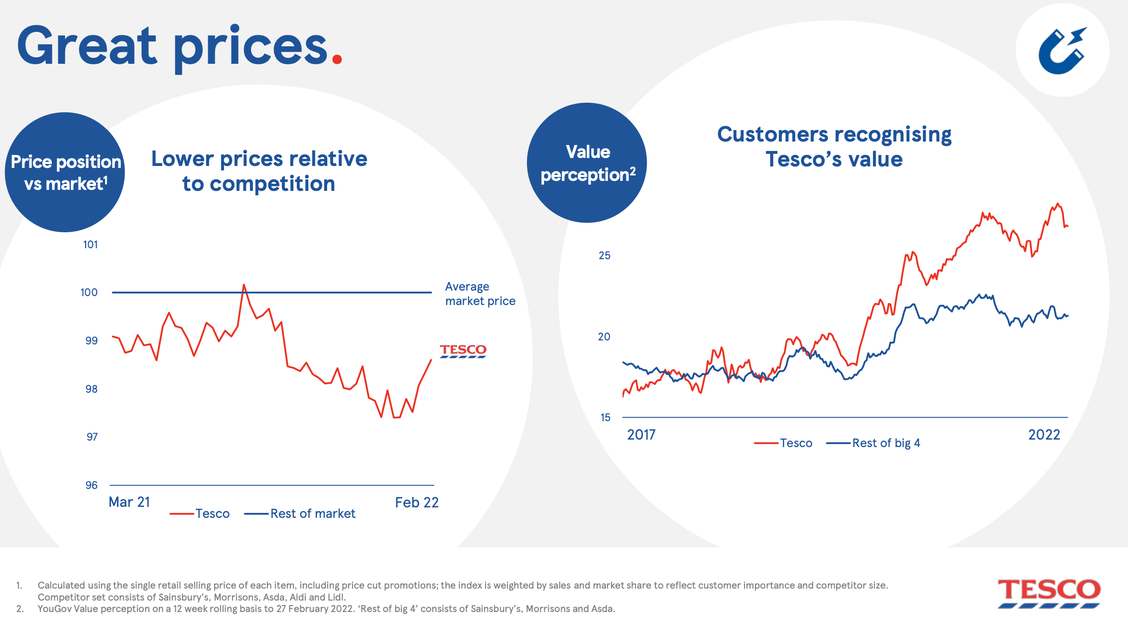
The work that has gone before Ken Murphy, kicked off by Dave Lewis with the price comparatives with Aldi alongside the revamped value tier work has really gained such a positive reaction from customers.
Tesco are some 6/7 years in to this; so they enter this period of difficult trading with inflation to battle against in great shape on a value perception perspective.
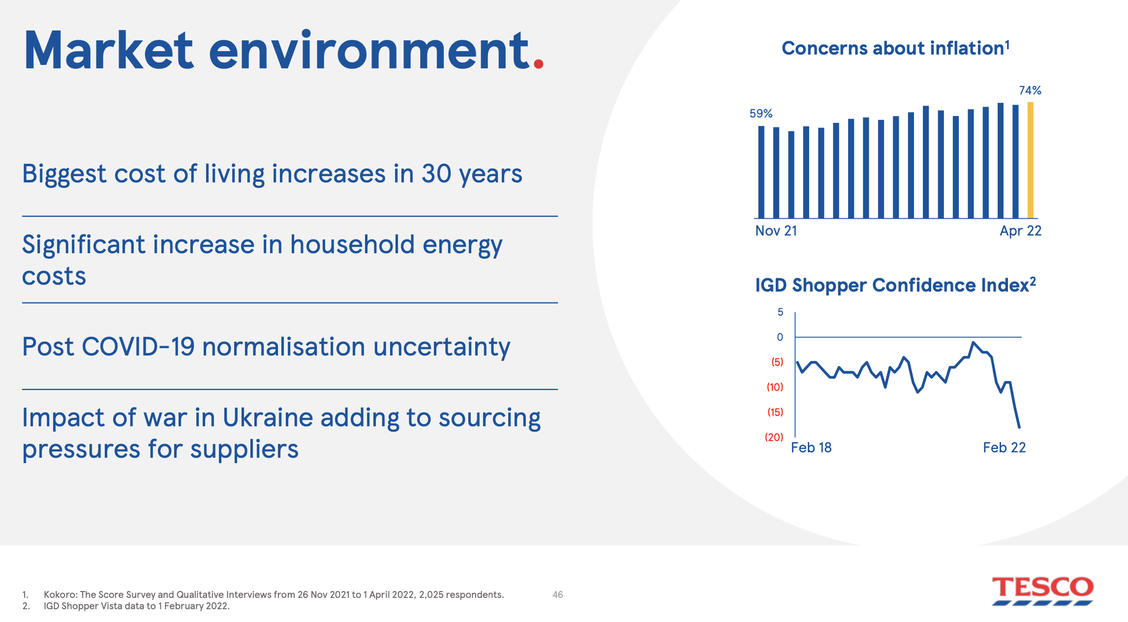
But we know that the market environment is difficult, biggest cost of living rises for 30 years tells its own story.
But the shopper confidence index tells its own story too, we see that direct impacts to spend such as petrol/diesel and then energy weighing heavily on confidence.
Especially when they see prices rising at the shelf edge, too.
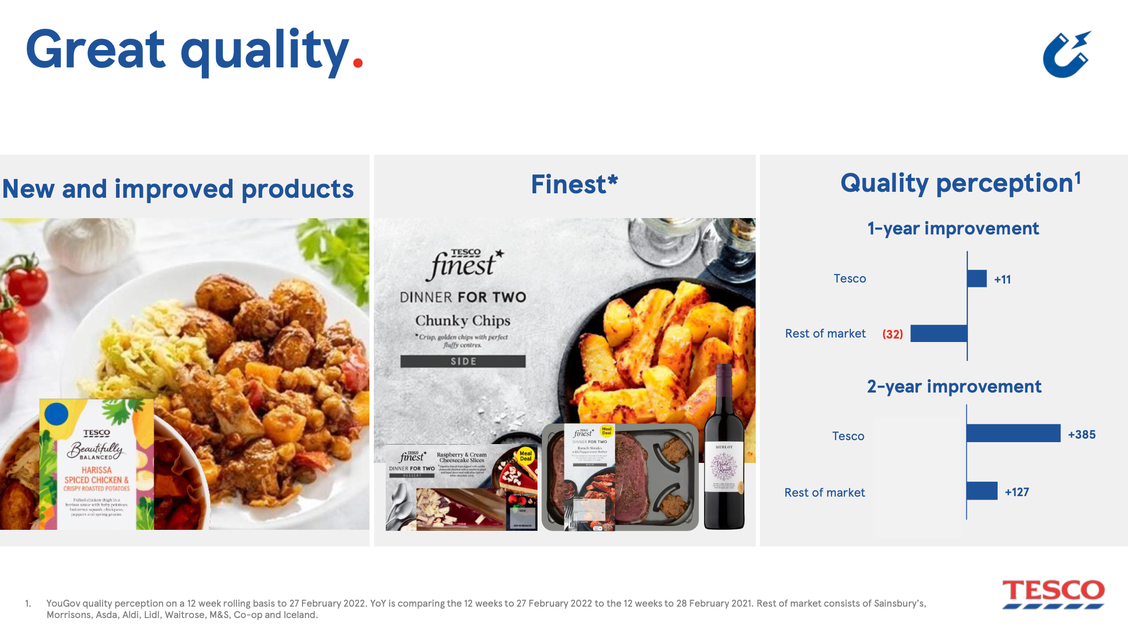
As above. Value is never just about price. Quality plays a huge part and both Tesco and Sainsbury’s are working on this angle
Quality is playing an important part too and Wicked Kitchen (Vegan) as an example is a great example of what can be done with sub brands - the range can be found in Kroger stores in the US too.
Continued improvements around quality perception only serves to further strengthen the own label.
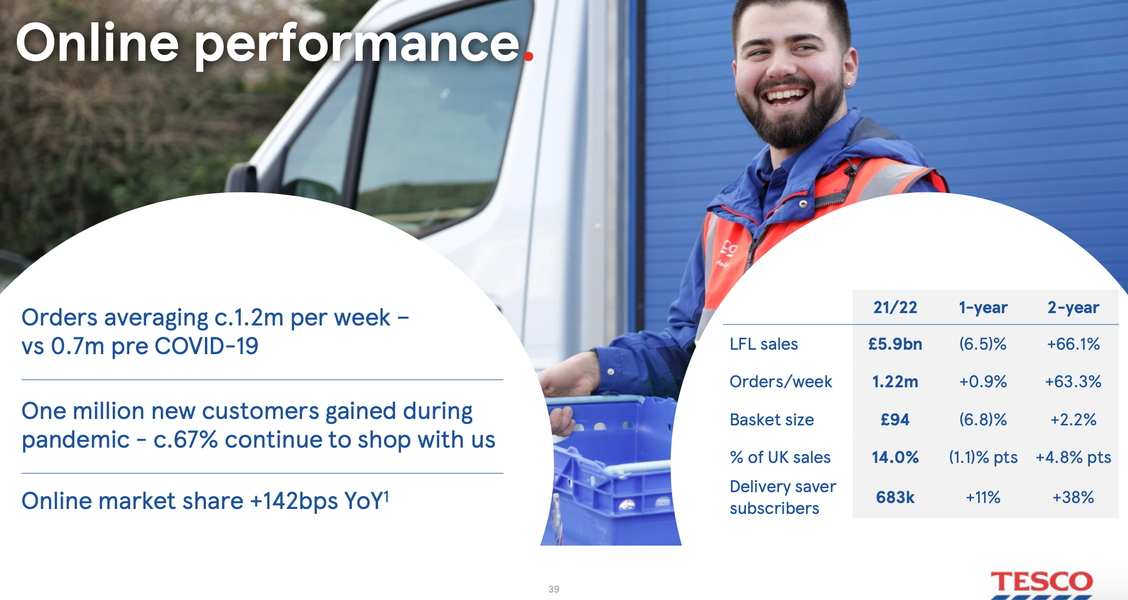
As noted - Tesco is delivering and despite the subject of the email, online was a negative but the rises seen in COVID19 were never going to be sustained over the longer term.
For anyone.
So the 2 year comp remains important here as we can see, there are significant rises in sales (+66%) but on a 1 year basis (-6.5%). 500k more orders per week than before COVID and their work with Tesco Whoosh (Express serviced) growing too.
Their tie up with Gorillas is intriguing and the q-commerce model does have legs, but justifying the silly money thrown around by VC’s? Not a chance.
Online remains a key part of the service offering, especially given that customers who shop online will likely shop with that retailer physically too (not guaranteed but generally there is a better chance of this, if they’re online customers).
There are a lot of positives for Tesco with their results, profits notably so but the underlying metrics like market share and switching gains are all strong.
Their work in store is borne out by their figures.
Their work on price comparative versus Aldi and the wider market has stood them in good stead and will only continue to do so, especially as the market hots up with various price campaigns and the rising cost of living challenges.
Notably today, with news from Asda and Morrisons about their price lock and biggest price campaign ever (respectively.)
It will only get noisier as inflation continues to bite and the cost of living becomes a political hot potato…..
Tesco are in a good place to both survive and thrive with all their hard work.
More to come on the latest price campaigns tomorrow from both Asda and Morrisons.
Find out about our periodic insight service offerings here. Never miss a thing again.Subscribe to this industry leading insight service, today.
From the Grocery Insight newsletter archive, first sent to subscribers on 25 April 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.