Lidl and the Free From category
24 April 2018

Subscribe to our service, here.
Check out our in depth research on Mother's Day
So to Lidl who perhaps fly under the radar a little these days, chugging along with their young German CEO and corporate focus being on the paused / changed US operation... It's not been too easy for the UK operation in recent times.
Certainly results continue to impress, although Kantar is basically "Discounter PR" given the number of stores they both open, it's always growing market share. However their store standards do appear to have taken a marked step backwards when compared to the tenure of Ronny Gottschlich.
Their marketing remains strong though and this has done as much as anything to change perceptions and keep the message fresh. It does feel when you consider seasonal assortments that there can be a degree of staleness that comes in.
The ranges remain the same, packaging the same and there isn't as much 'wow' in the same way that Aldi deliver for example. Certainly at Christmas I felt this.
Even Easter, a stronger package but still lagged Aldi in terms of product quality on Eggs for example.
One area where Lidl were quicker than Aldi was their 'future format store' which generally means a gargantuan outlet that is either built form scratch, or features a former store bulldozed and a much larger outlet built in its place.
These newer stores are larger, meaning more customers in the aisles, more space for special buy bins and a feeling of more range. Not too much necessarily, but there is more assortment and more space as a result for lines that sell quicker.
Also noteworthy are more checkouts (up to 7 in some stores) with others benefitting from self checkouts too. These are a must really for discounters as how many customers queue behind a full trolley as they stand there with two pastries from the Bakery?
Too many! Discounters won't open a new checkout until the queue gets that bit longer.... Which can mean customers perceive queues to be worse than they are, self checkouts remove some of this challenge but then shrinkage can go up with mis-scans and errors on the loose Bakery goods...
Those larger stores are impressive beasts though and it's a real two worlds effect when visiting an older Lidl with a Bakery almost dropped in to the store alongside the relatively 'harder' discount feel.
These new stores are bright, airy, feature better chillers, better Bakery offering and also are easier to shop. Better graphics and navigation means it's generally a happier place.
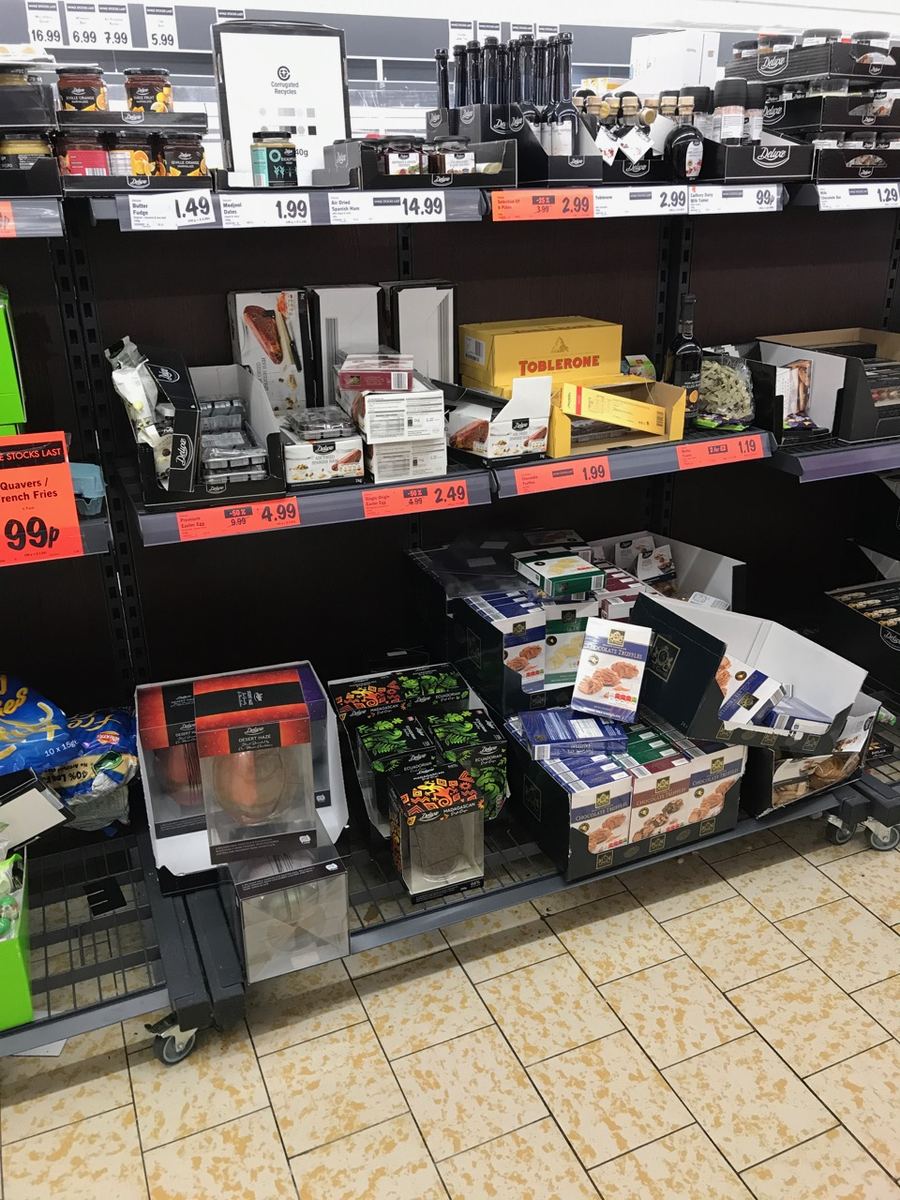
The harder, older stores are tight for space and Lidl with their current trading strategy on specials (particularly) seem to be causing some problems. The branded sales growth as flagged by Kantar becomes obvious when you visit a store or two.
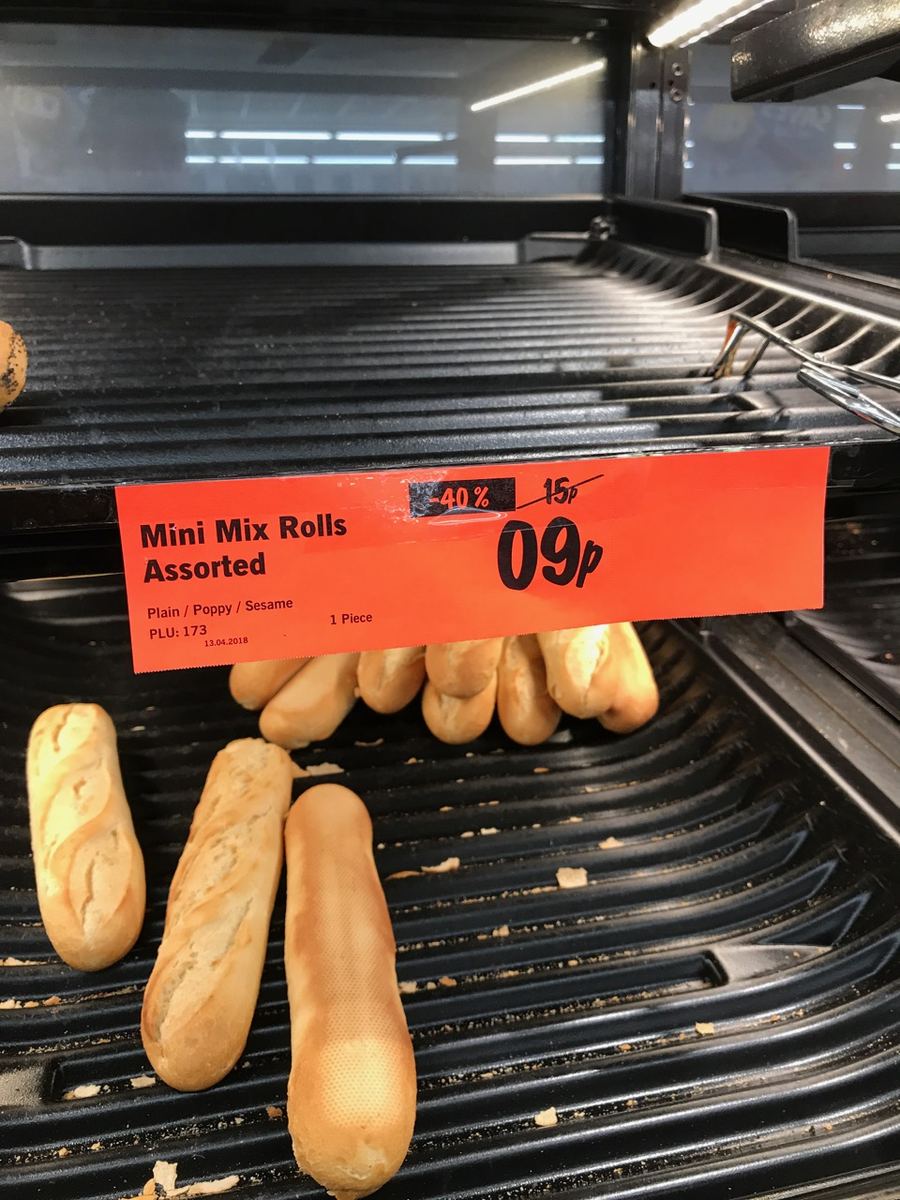
Standards are also variable, whilst Aldi (who follow their their own refitted 'fresh format' stores) broadly appear to be sharper on standards but are also seemingly running with more people around their shops. Lidl seem to have reverted back to the days of having to queue a little and expecting variable fill standards in return for lower prices on high quality product.
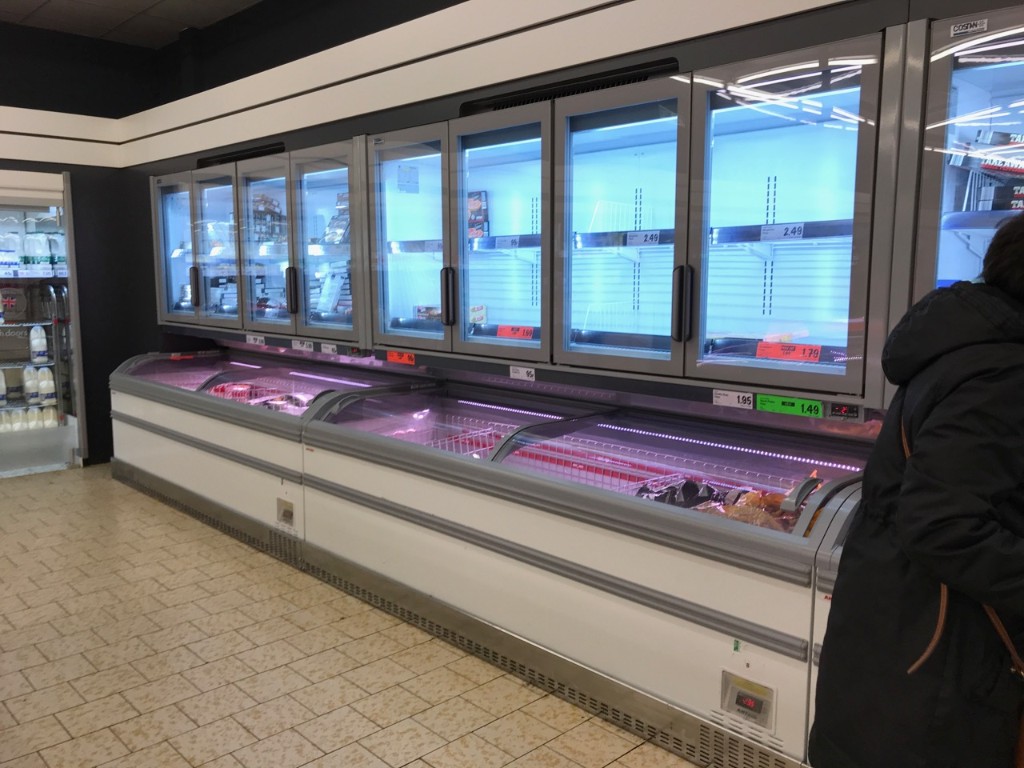
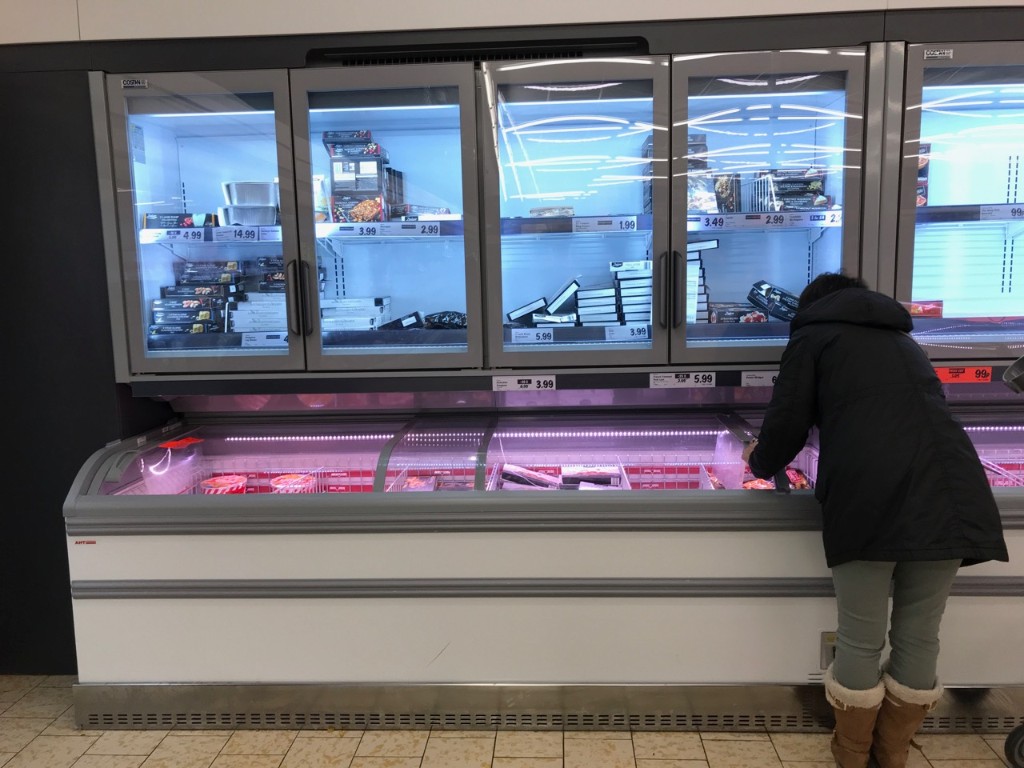
Certainly recently, one store had virtually no frozen product on sale for no discernible reason. Ultimately disappointing customers who would have had to go elsewhere.
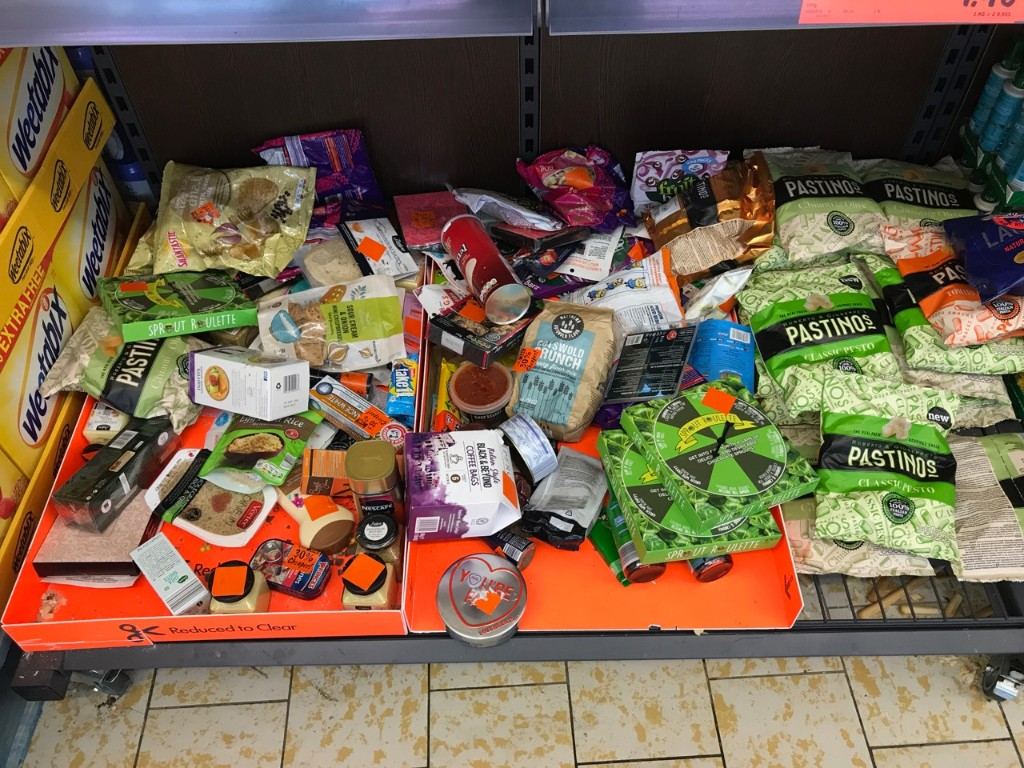
Their specials range is reasonably well managed in terms of their event and non food special buys. They are tight on stock and it can be a 'on the day' purchase for some lines to create a bit of a 'treasure hunt' element to the space.
They don't have the abundance of stock that Aldi have, often a fair amount of that is on clearance which restricts space for other, newly arriving product. Making the job of managing the central space very difficult indeed for Aldi colleagues and the customers too.
Both Lidl and Aldi have added a physical 'aisle' space at the end of their specials run to facilitate the addition of branded groceries (and own label) that feature as part of their Mexican, Greek etc events. Although that's the intention, however not all the products that arrive are linked to an event....
In Lidl, you can see that numerous products appear to be spot buys or similar, perhaps to take on B&M or others. A 'treasure hunt' here perhaps but the range is growing but it can become cumbersome, difficult to manage and also, what is the link to this versus the core range?
Customers may opt for this over the core range but then revert back to the core range when the special buy sells through. Price points can be all over the place and merchandising often difficult due to the plethora of products that are found here.
What else is the stock sited here for? Is it also suppliers wanting to get in to the discounters to get volume? It's a zero sum game, as Lidl are not even listing the brand, merely siting them in the middle of the store for a closed time period.
Not to mention the shippers that are dotted around the store, some of which can block aisles and make navigation difficult, these are also carrying brands (sometimes own label too) but predominantly branded lines for sale at a lower price.
What is the end game here? It just seems to add complexity to a model that is incredibly systematic and reliant on simplicity.
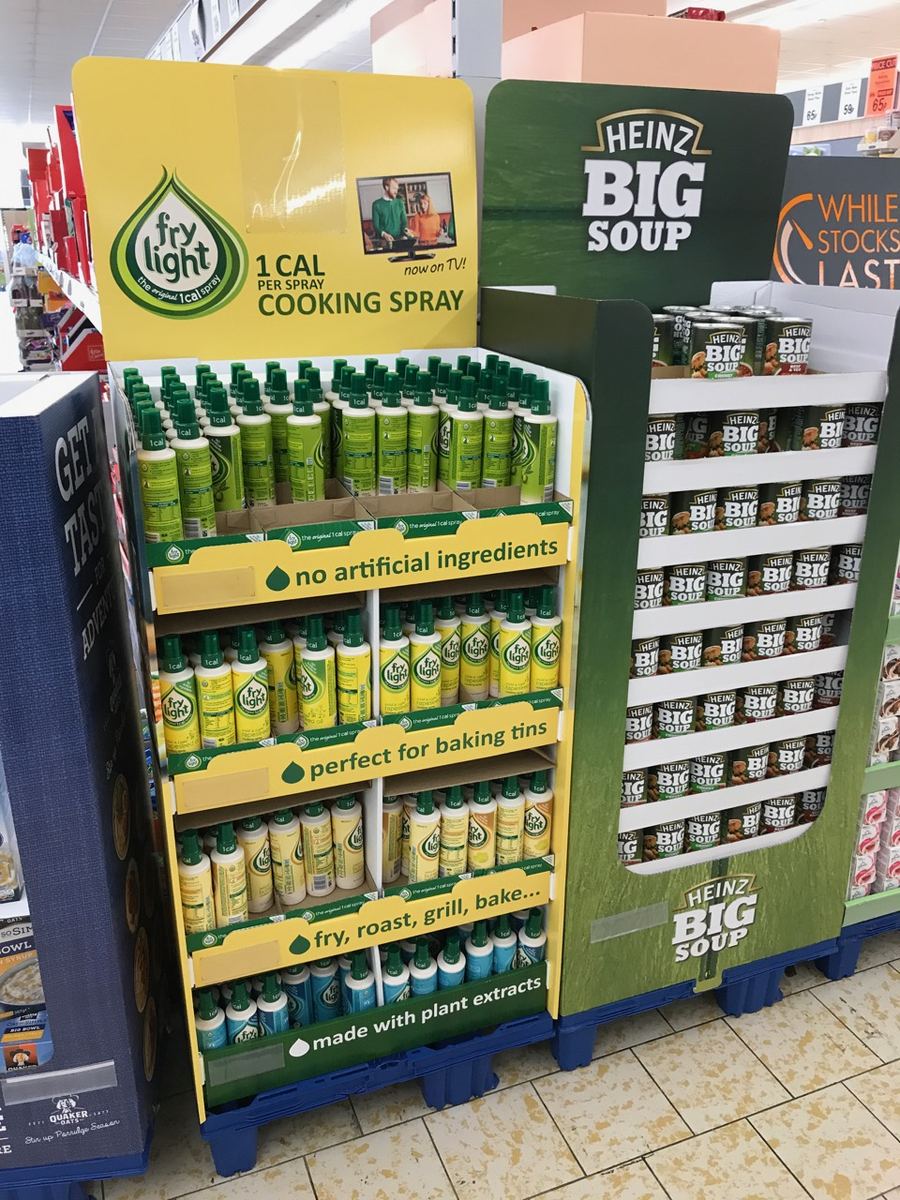
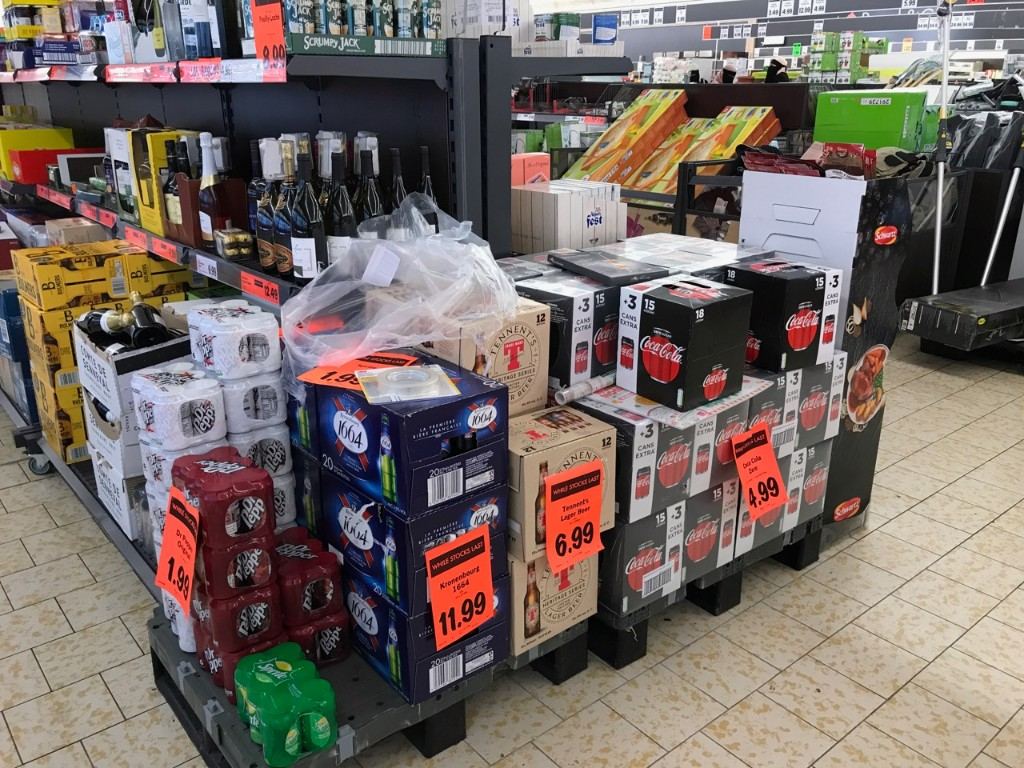
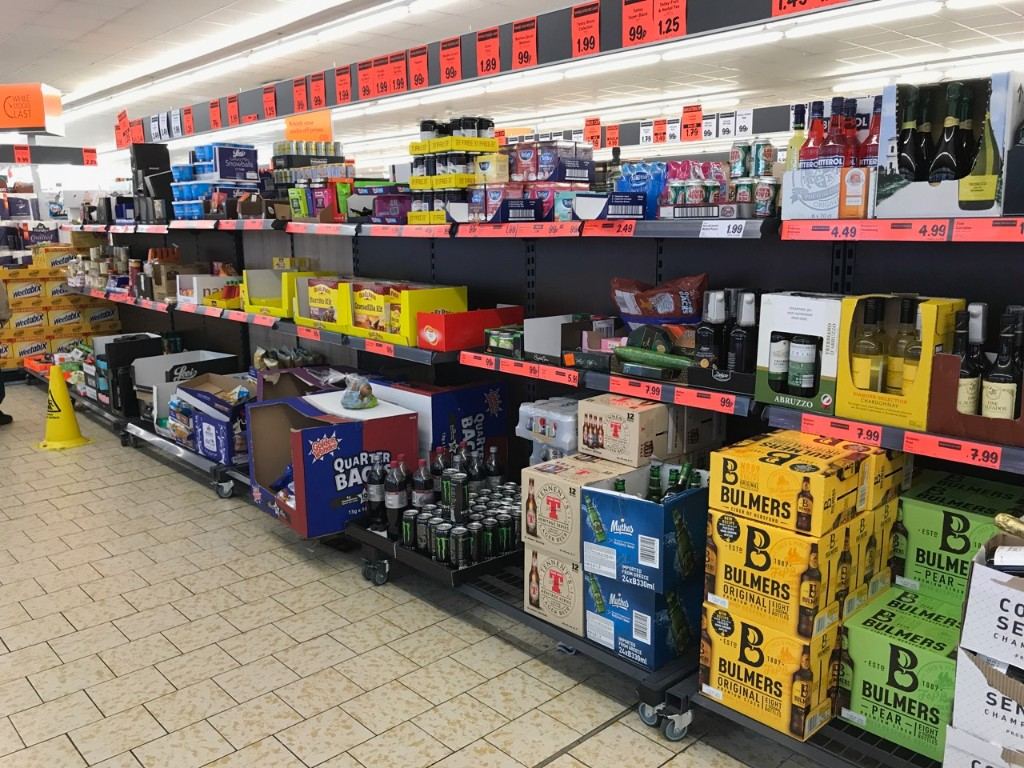
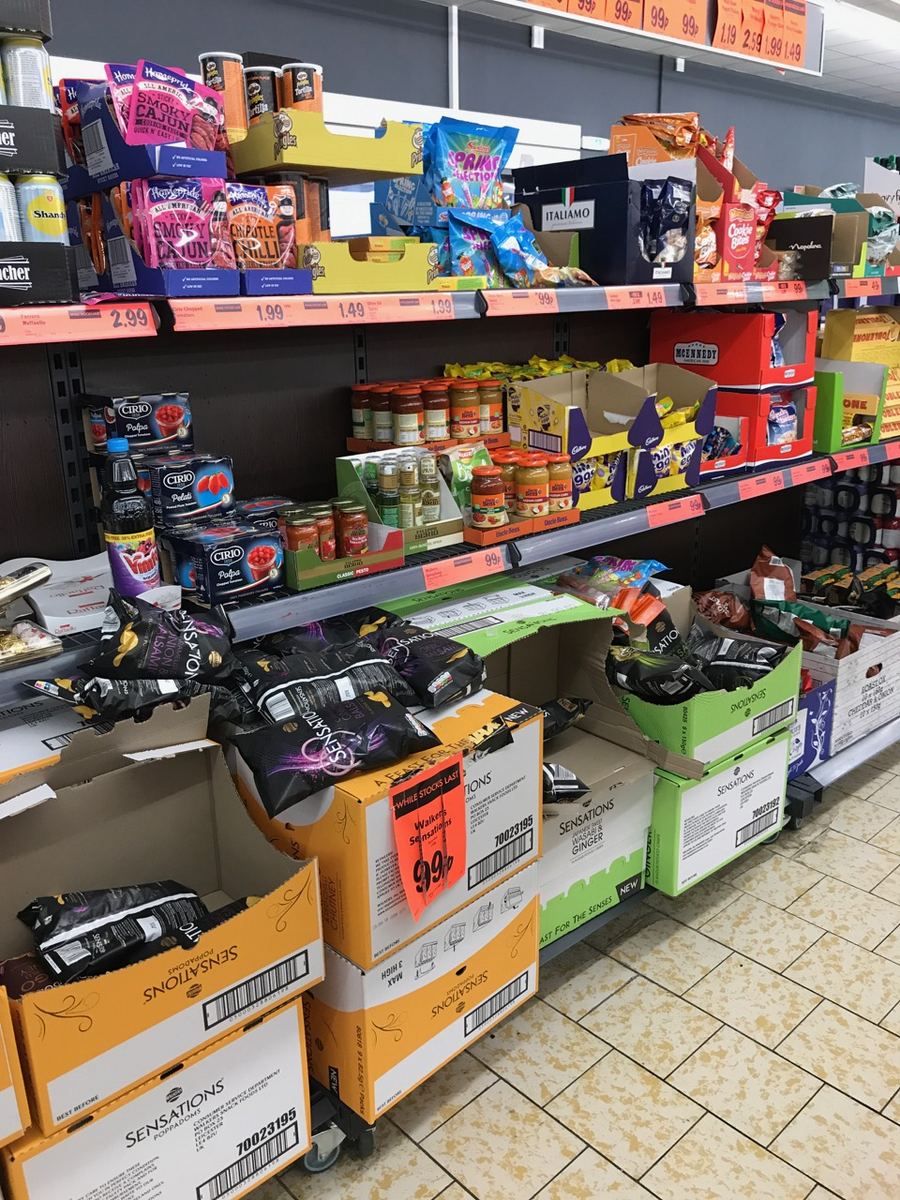
Speaking of range. Lidl were adding further range as their new range of Free From products landed in stores a couple of weeks back. It was first noted that they'd stocked a couple of the Warburton's free from lines in their core assortment.
Then they added an end (in a traditional store) near the checkouts that features a couple of branded lines (Nestle Cereals) with the rest being a fair range of own label Free From. Two premium lines were also spotted within this range.
It does grow range and perhaps some complexity but the reality is that this assortment is significant for Lidl as it aims to offer some sort of range to valuable customers (free from) who are restricted in what they can buy.
Currently, they would be unable to use discounters for many things related to their dietary needs as there isn't the range. Aldi have a range in their refitted stores that sits with health, impressive collection despite being in a small space.
Lidl have this assortment and it's effective as a stake in the ground, but the larger retailers can still go further and offer more range here. It's notable that they have done it, but the 'end game' for Free From is unclear with Lidl, it's hard to see them going further with it unless they free up space from other categories.
Certainly their best efforts are this range as an 'anchor' to get repeat purchases and then offer 'free from' food based events in store to drive further sales.
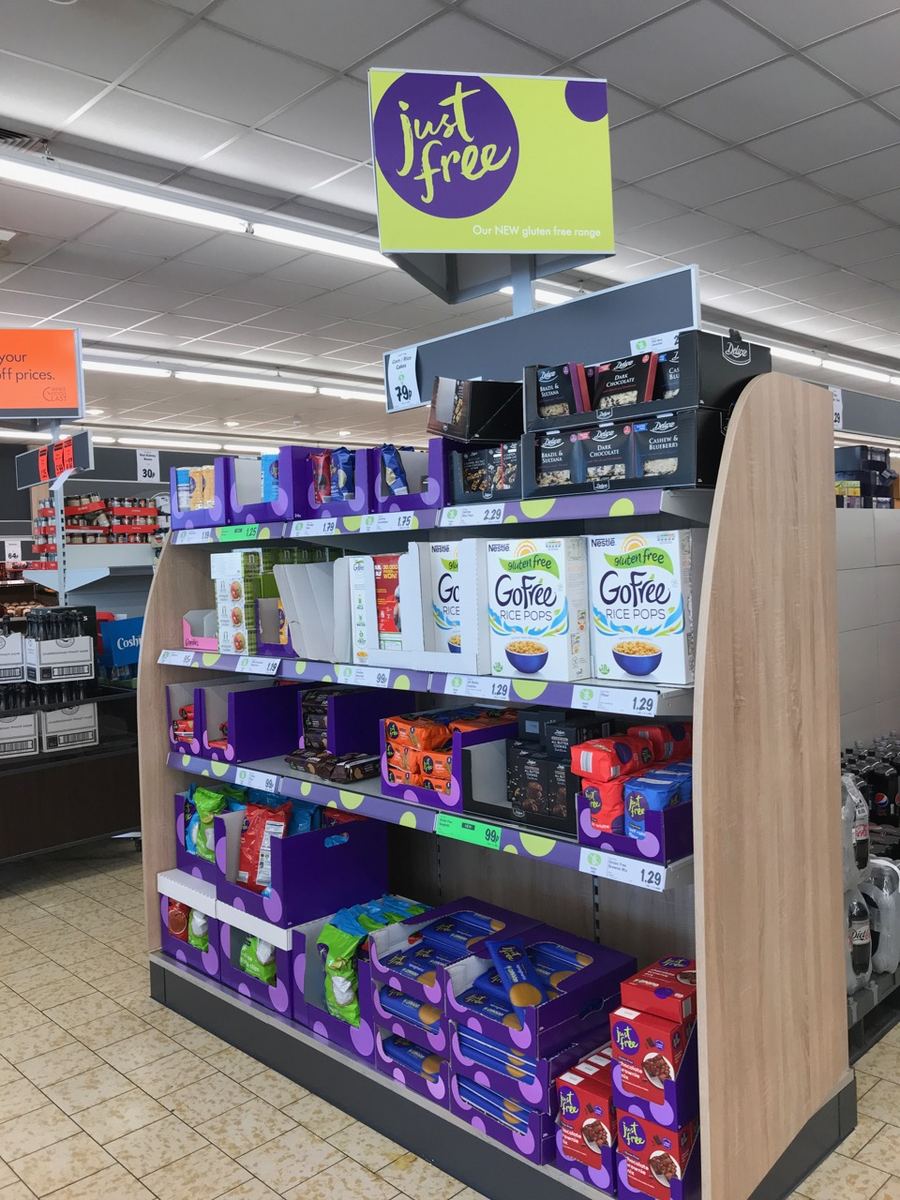
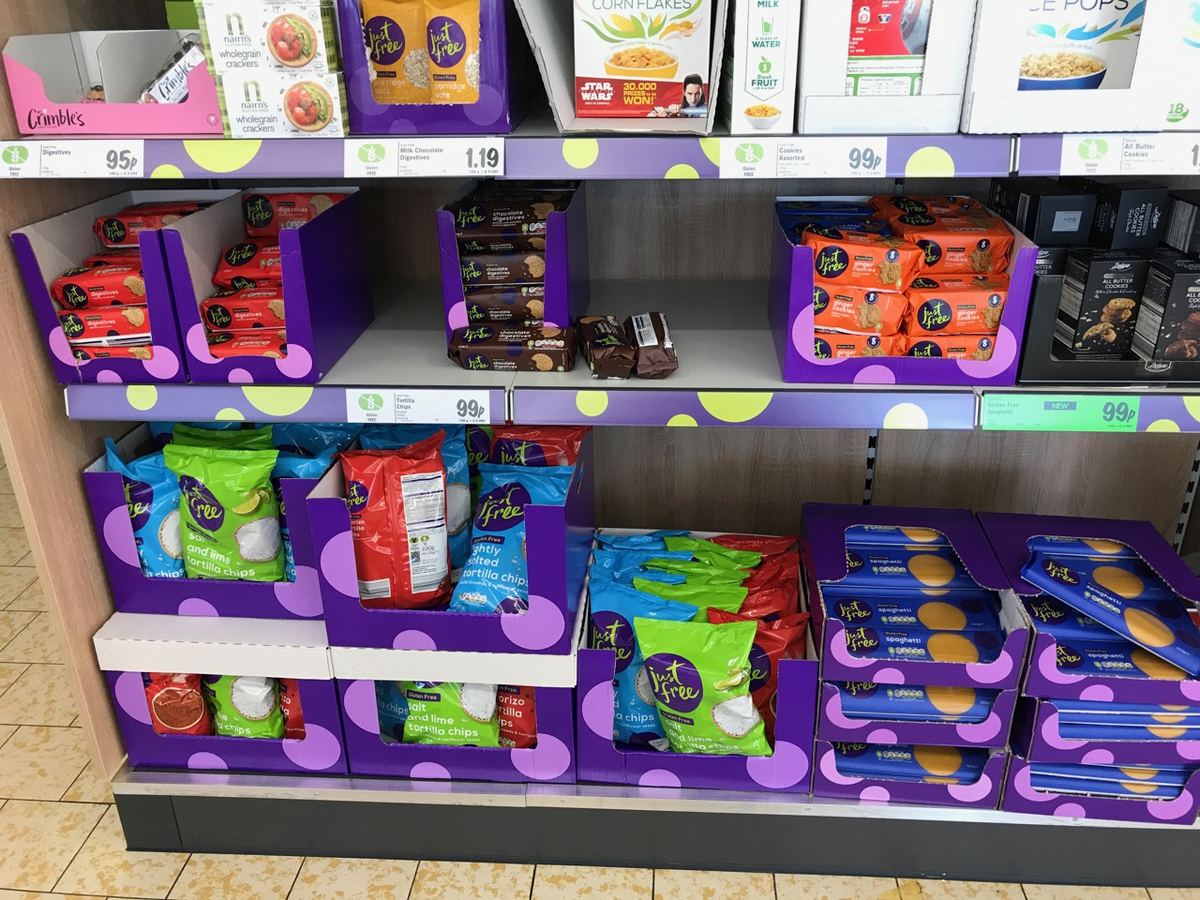
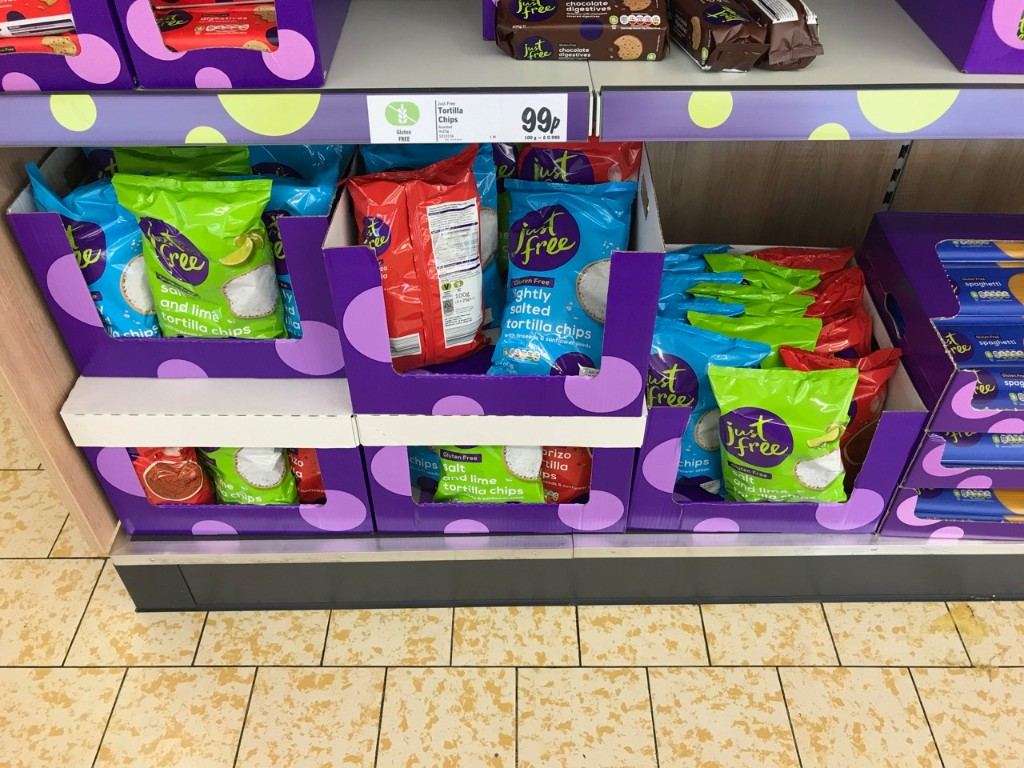
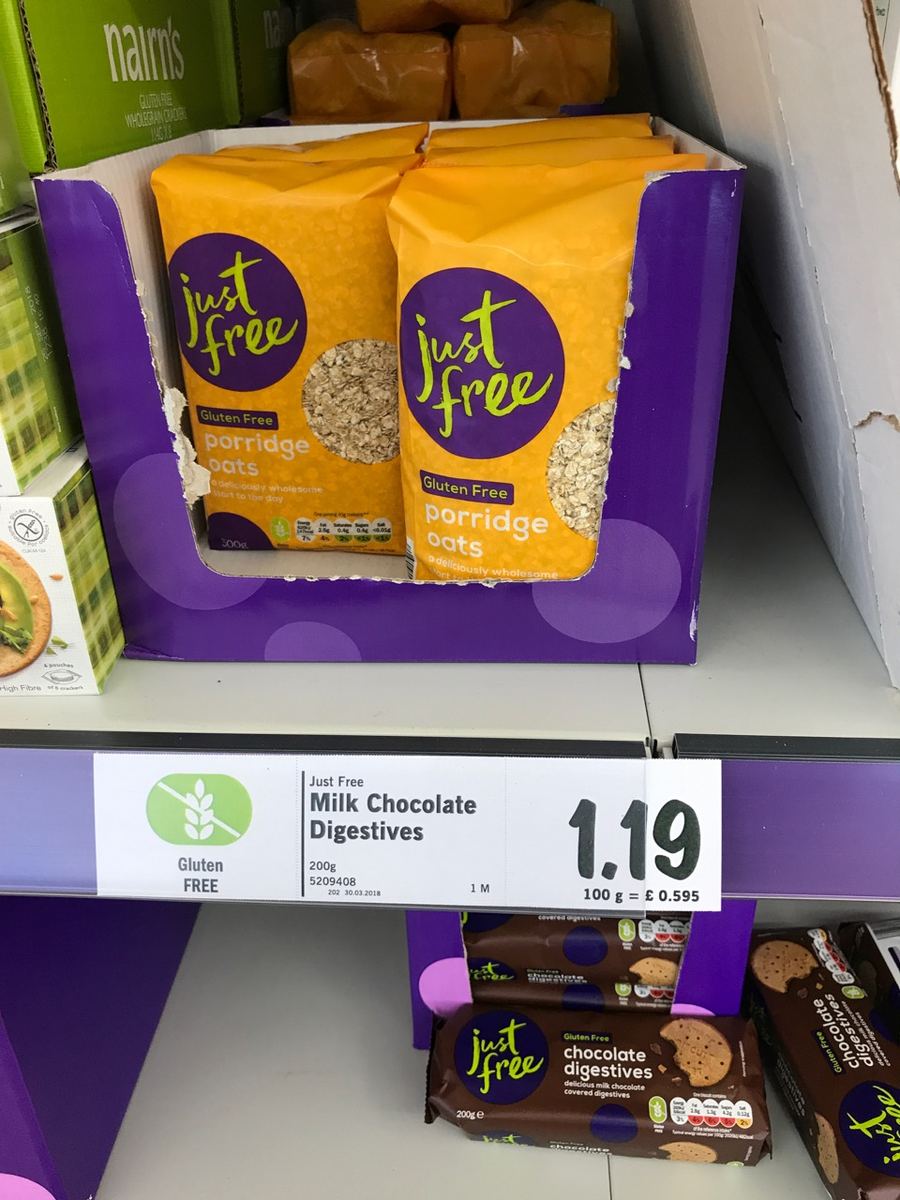
A good piece of work from Lidl, in terms of product range, price point and signage it stands out well and looks good. Quality will be strong and customers will be happy with what has been delivered.
It will be interesting in larger stores whether the range is greater, or located in the 'store' itself rather than an end.
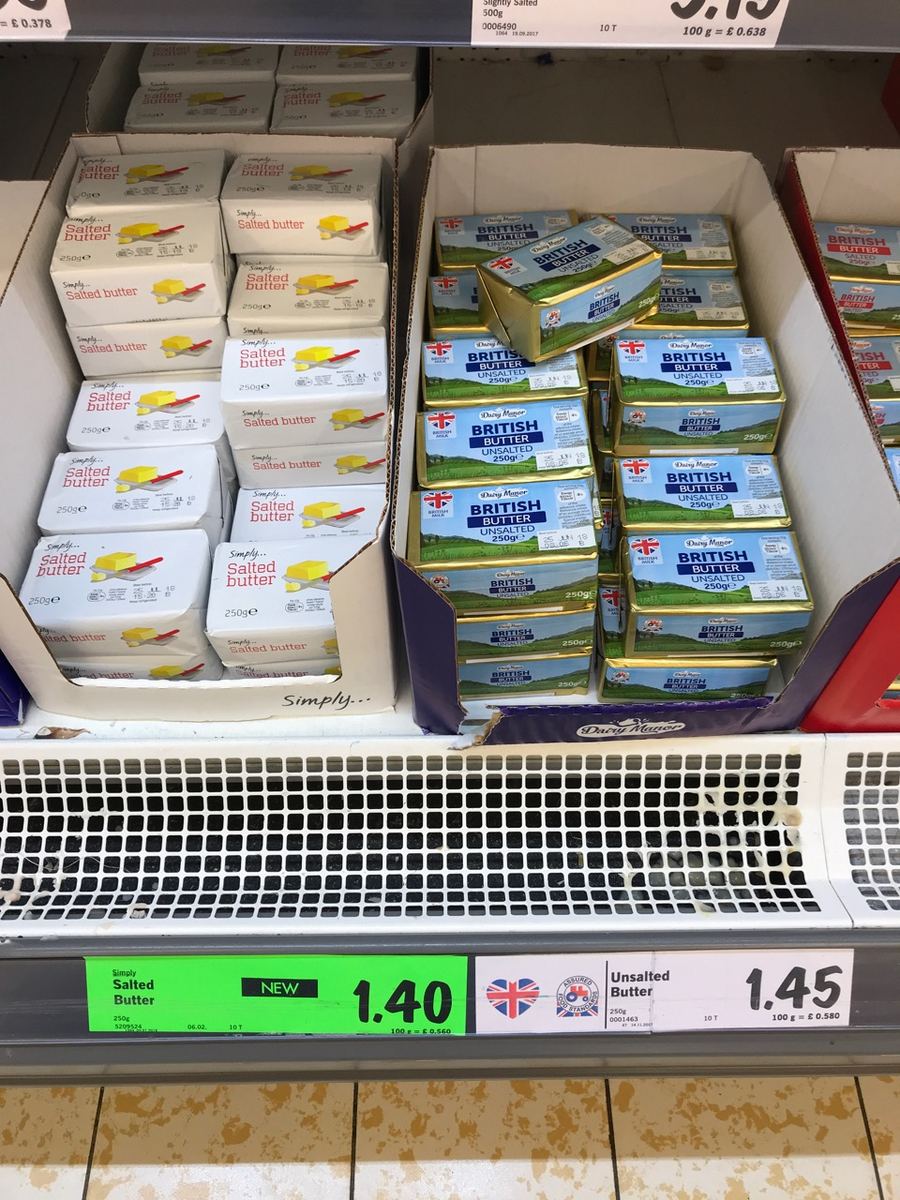
Complexity can creep back in to any retailer, even Lidl. Butter as a good example below, why is there a need for a value line when there's a 5p price difference?
More importantly. Standards and availability are a bigger impact to the customer. Gaps are generally rare in Lidl but too many missing lines and the customer will go elsewhere to complete their shopping.
There's nothing to say that they will return....
Grocery Insight cover all seasonal events in store and we are happy to launch our first report for sale covering every angle, image and perspective on Mother's Day 2018.
Coming in at over 220 slides of analysis of the retail offer by category. Best practise from the event and suggestions for 2019. It's required reading for retailers, suppliers, marketing agencies and anyone else interested in the event as a whole.
Further events will be covered in this way too, so please do get in touch if you have any specific requests and/or requirements and we'll be happy to help.
Click the button below to arrive at our landing page for the event, or simply click here.
Subscribe to our service, here.
Check out our in depth research on Mother's Day
From the Grocery Insight newsletter archive, first sent to subscribers on 24 April 2018. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.