A quick market update
11 May 2017
So with the week last week seeing Sainsbury's continue to stutter; we also saw the recovery at Morrisons continue apace with another positive sales performance at 3.4% which interestingly contained 0.4% for their wholesale division.
The notable split for their huge fresh food business (2nd biggest if an independent business today) and their activities in terms of sales contributed 0.4% towards the like for like sales, showing that the Amazon deal is starting to contribute, alongside the wider fresh food business which features a florist, a noodle manufacturer and Meat / Produce processing plants.
The future looks bright for Morrisons as they continue their turnaround efforts, there has been some talk of inflation being higher at Morrisons than peers, especially given the lower items per basket recorded.
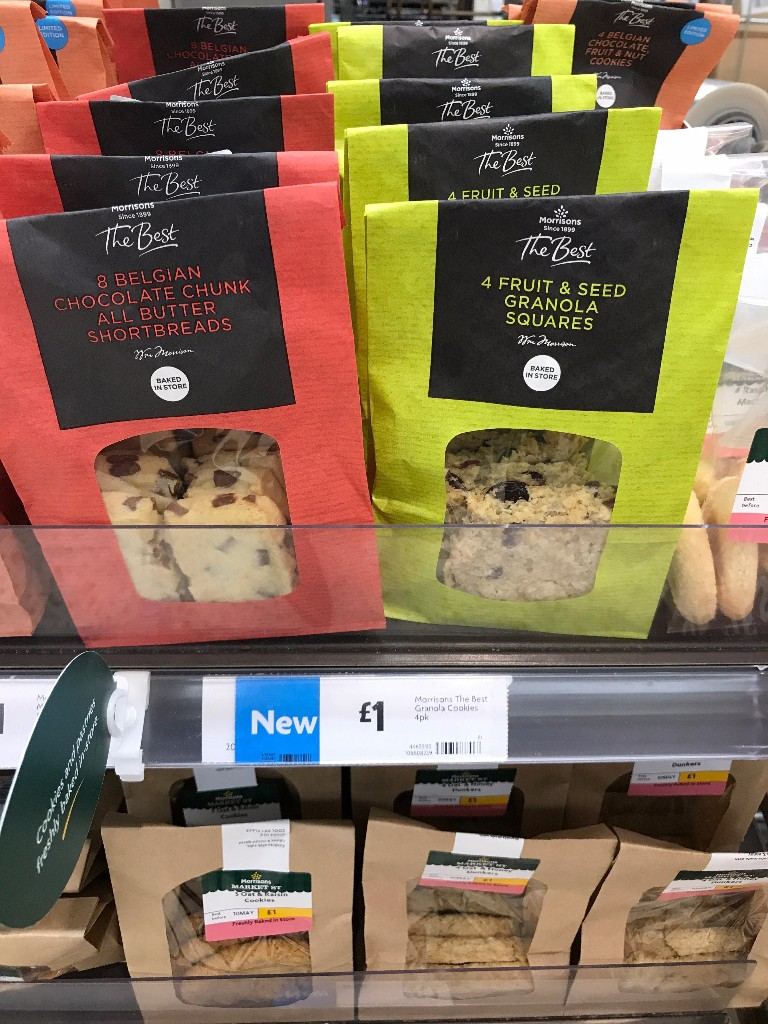
However if you consider that premium is being marketed heavily and crucially, customers are responding and purchasing. Automatically there's a degree of inflation there given wider ranges and the price premium that 'Best' et al trade with.
Similarly non-food is flagged by Kantar as having a positive impact on the like for like sales at Morrisons, another reason for growth and there's more of a mix for the customer seemingly.
Both elements can drive the overall basket northwards as there's more for customers to buy in to. Plus we know that customers of this generation and those before are conditioned by discount and the whole 'food waste' element.
There isn't the need to over buy food in the same there used to be, multibuys have been drastically reduced and it's harder to get that spending in the stores.
Like anyone else, Morrisons are open to inflation as the market adapts to a devalued sterling and rising input prices, but doesn't appear to have raised prices more than anyone else. Their performance continues to impress and their growth prospects around online look positive too.
Above all else, 3.4% is not to be sniffed at in the boom days of the market, let alone in the depressed market post discount.
So to the wider market, we have a number of emails to come out this week and next considering the general market moves as we approach Summer.
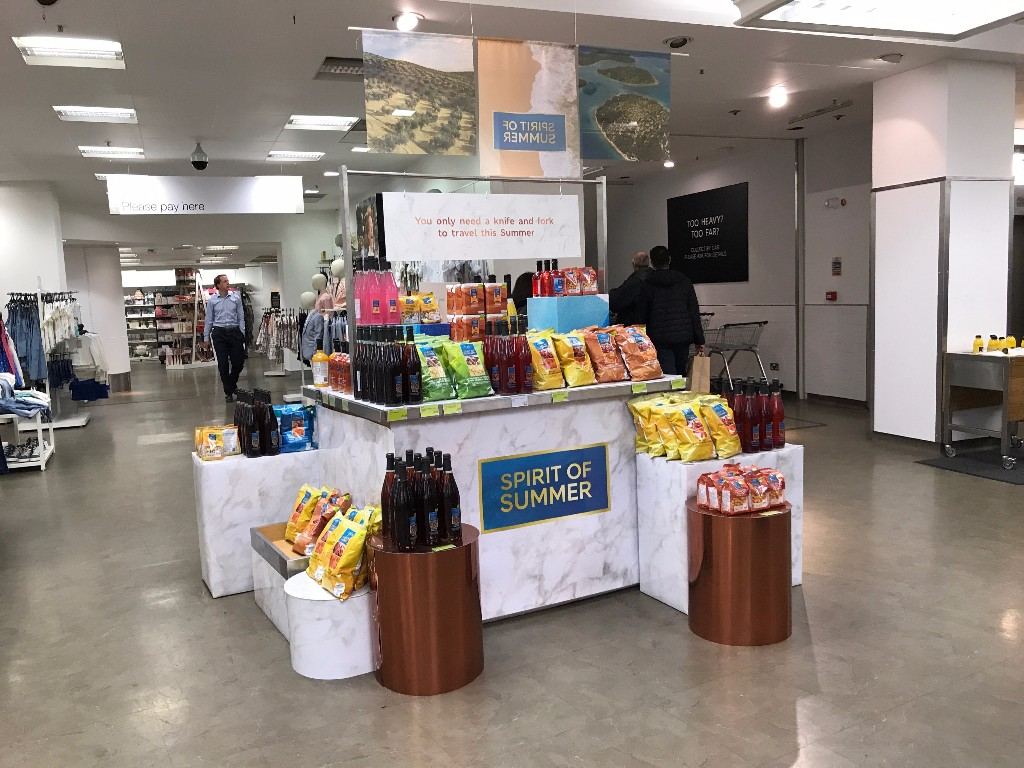
M&S are in great shape for Summer, their business is set up for a rotating range given their greater fresh food range, so they often flip ranges around for the key seasonal periods and do very well from this.
They're open to inflationary pressure though; arguably more so than most given their exposure to fresh foods and also their lower volumes versus peers. They rely on a higher basket spend given their premium stature in the market, so it's a hard balance to strike.
That said, value isn't their end game necessarily. Widely competitive yes, but customers don't head to M&S for the lowest market price on Carrots.
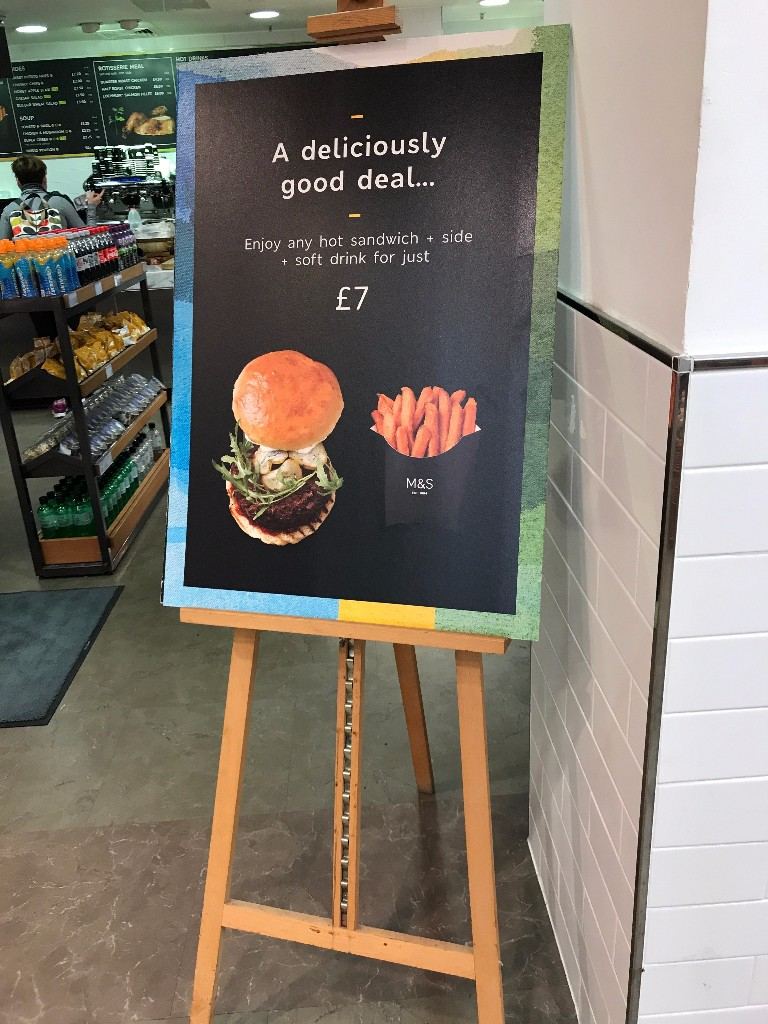
Their Marble Arch store was a real hub of activity last week with several colleagues asking me who I was and why I was in store. Not that I was recognised of course, but more I was stalking the aisles!
It's their store to test a number of things in, and there was some signs of trials and other work, but overall it was hugely impressive. Of course Marble Arch is somewhat of a 'one off' given the location and affluence, but it's always good to see a jewel in the crown.
What impresses me with M&S is their innovation, they're always best practise for new product development, everything is always so cohesive and they back events hugely.
Online is the only concern here; M&S are strong on seasonal but the operational elements of bringing lines in/out quickly and also stocking levels often being wayward given vulnerability to weather.
IE hot weather leaves stores without Salads and Burgers after 6pm when everyone takes advantage of the one day of hot weather we get per year... It's how that feeds through to a very demanding online customer.
Setting up as a secondary outlet on somewhere like Ocado would mean they went via a picking centre and were less exposed to the erratic nature of store trade perhaps....
Sainsbury's who we discussed in detail last week are still trying to get going for Summer, usually so strong here and they may well start to land this later in the month.
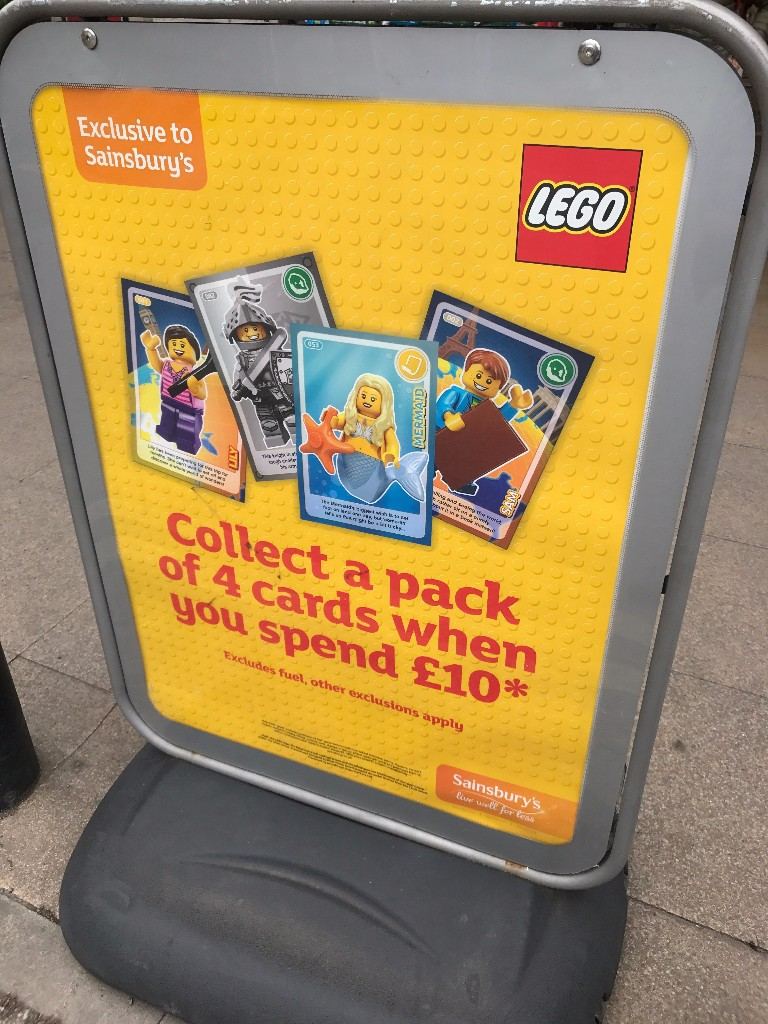
They have a Lego collector card deal at the minute in stores, £10 spend = 4 cards, with collector books available for £2.
It's a smart deal given links with Argos and the opportunity to drive spending there, but I was surprised in store to see virtually nothing around the aisles.
If you'd entered the store via the other entrance (one store I go to has two entrances, not a royal entrance mind you). You would have had no idea any promotion was active.
There was nothing inside the core aisles, which seemed odd given the £10 trigger spend, and the entire point of the promotion was around getting customers to spend more....
Whilst the deal is a good one, Lego is ever popular and great for families, I can't help but think it's a little strange in terms of the timing.
It struck me as one perfect for that promotional cycle in the 6 week holidays where inspiration is needed by parents and cash isn't exactly plentiful.
Their Q1 is a lengthy one, spanning some 15 weeks so with Red Nose day included as a "JS Only" promotion alongside this, and the calendar events like Easter - we should see a better performance on food one would suspect.
However, offers like this Lego one do make the comparatives for next year ever more difficult. Plus will customers brought in to store for Lego cards, return in Q2?....
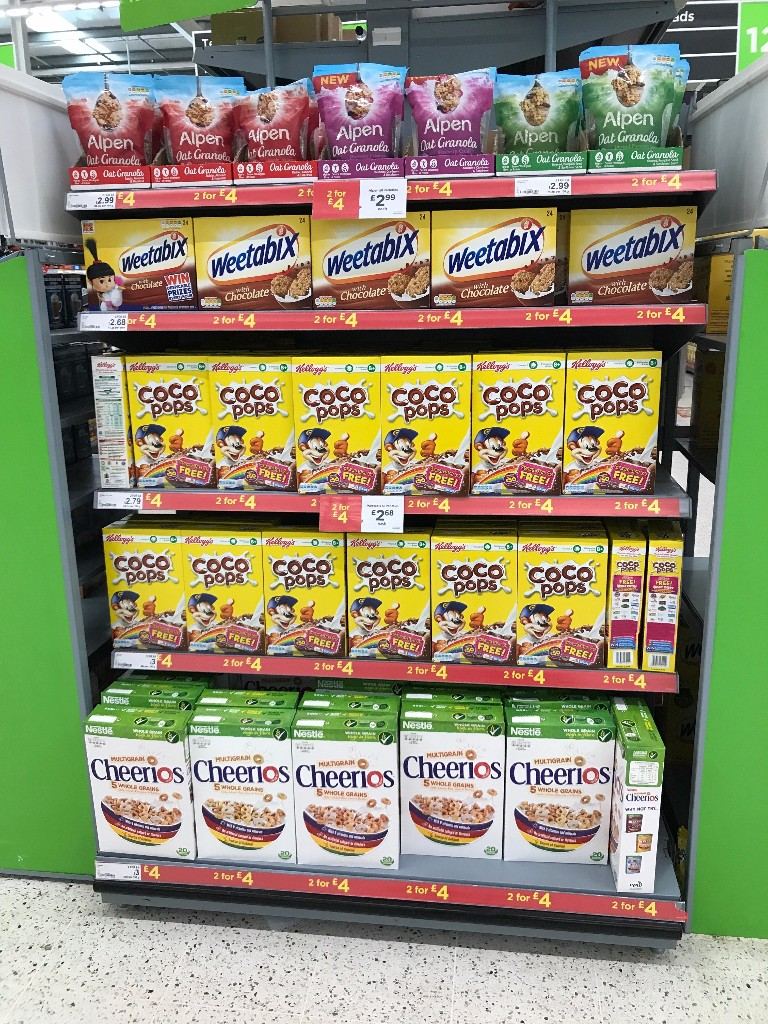
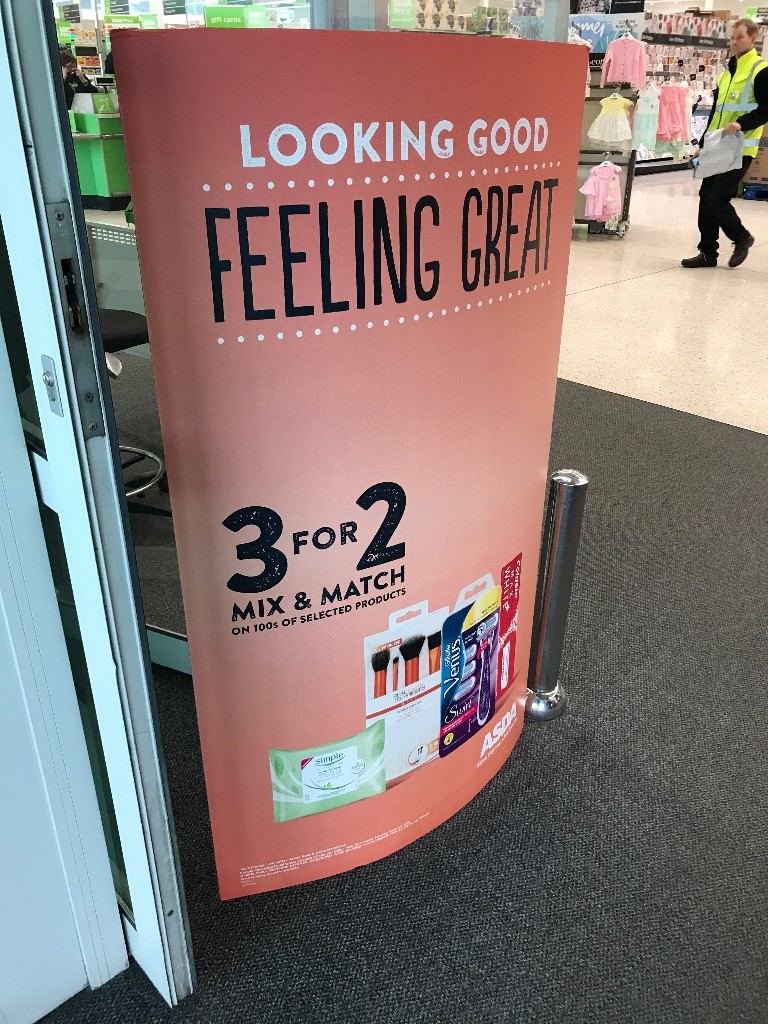
Asda are chugging along, at least looking like they have a plan for their future and sorting out core trading. The recovery hasn't been as dramatic as Tesco, or Morrisons but they are stemming the tide from significant losses.
Their push for profits came at the expense of the stores and their wider offer and reversing that takes time. There are signs of an improvement in the offer, better events certainly (Easter was one notable stand out) and better day to day deals too.
They're better when they signpost longer term value, 2 for £4 on the larger pack Cereals and a 3 for 2 on Health/Beauty event both represented good work from them.
However in this post discount world, is their core customer actually conditioned to lower, everyday prices like discounters charge?
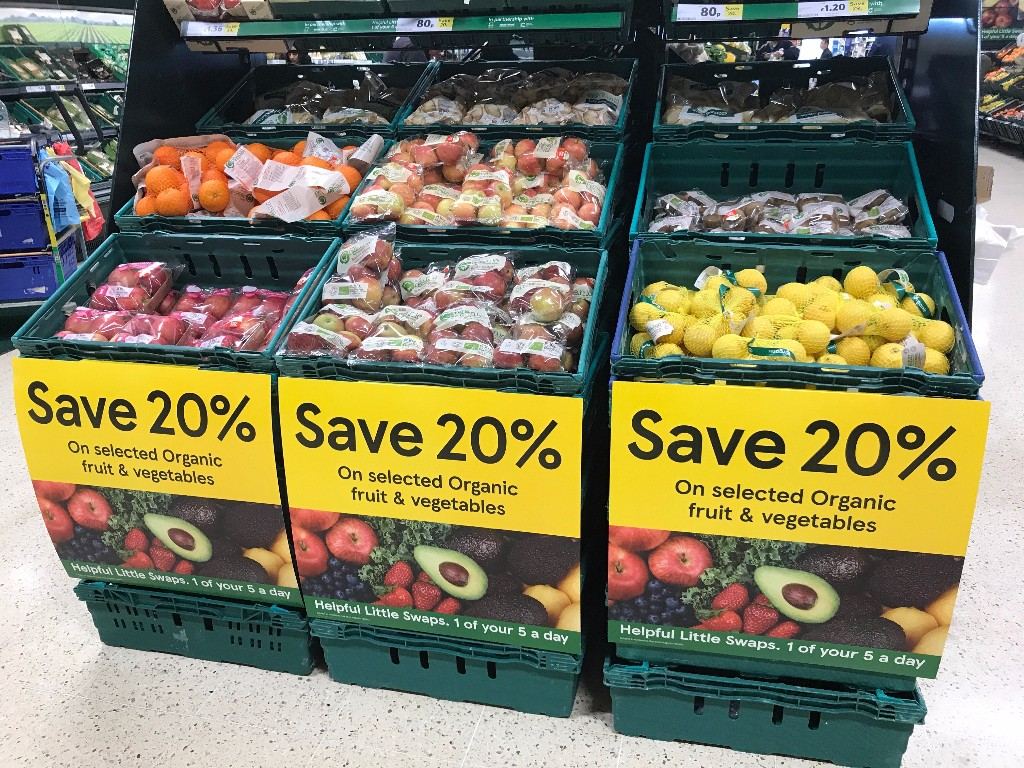
The Tesco "Healthy Swaps" campaign kicked off last week and features some good innovation within the event space, a first for the market I believe with lower sugar / diet alternatives actually cheaper than the fuller fat equivalent.
There were offers on Produce too; 20% on Organics was a clever deal given the 'friendlier' nature of the Fruit/Veg in this instance.
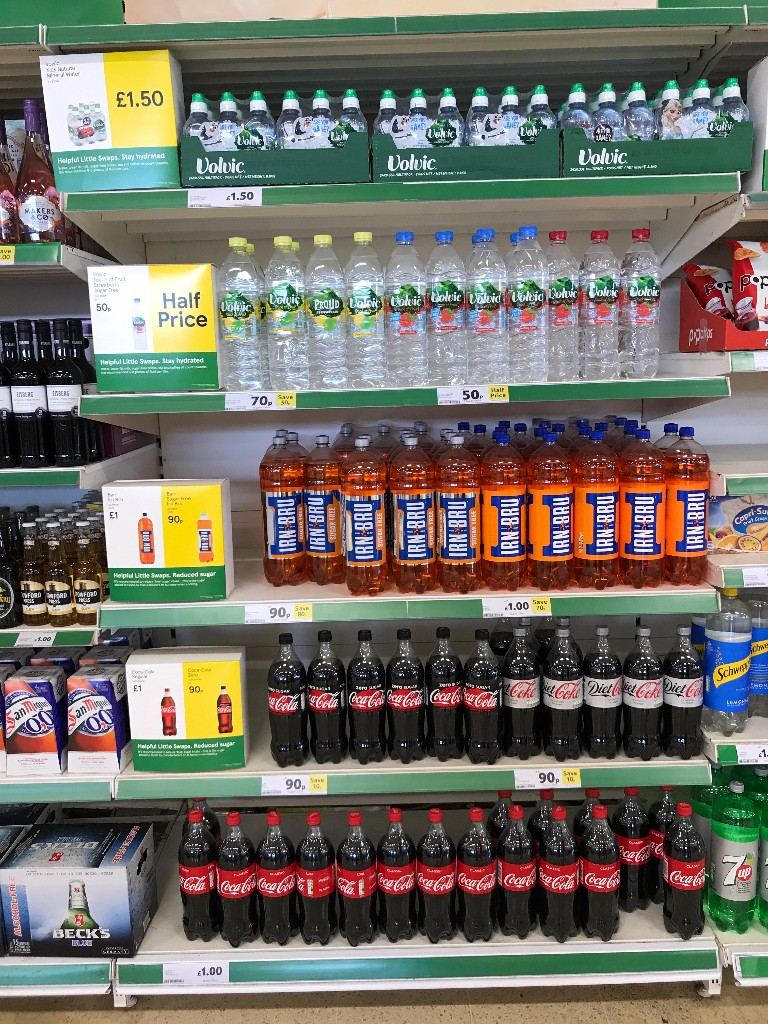
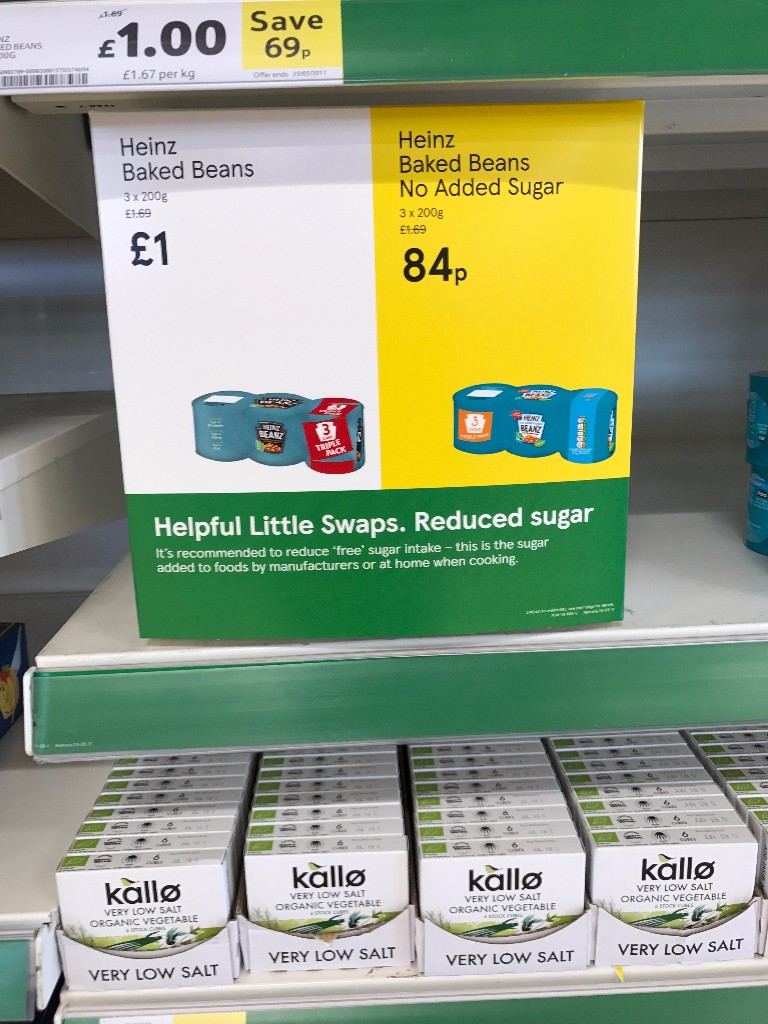
Good execution too; we're much more used to this from Tesco these days, given their sharper outlook in marketing and wider trading too.
They've done a good job on the 'voice' of this deal to the customer, no one likes being preached to by a retailer about the benefits of healthy eating whilst around the corner there's 3 ends of £1 Chocolate.
But this was done in a friendlier way, with lower price tempting customers and 'helpful little swaps' used as a strapline. It worked well and plays nicely into the 'friendlier' Tesco that we now know and love(!)
Ah the Co-Operative, still pushing along very nicely and we'll have a look at them next week and their McColl's tie up.
The McColl's news is interesting, given they're to sell Co-Op branded lines in their refitted stores (that are ex Co-Op in any case). Clearly these stores weren't future proofed for the Co-Operative as they've sold them on, many were ex Alldays stores that did little other than Cigs and Alcohol.
They're never easy to grow sales and often come with side issues around shrinkage and the like. McColl's taking them on seemingly made sense given their preference for these outlets, but to then strike a deal with the Co-Operative must indicate that sales are not progressing as expected in the new world.
Nisa are the McColl's supplier and whilst their own label has progressed, there are still issues around quality and price clearly.
It's a good move for the Co-Operative and gets them (sort of) in to the new growth engine of wholesale/franchise, there's a lot to resolve with Tesco/Booker deal and how that will impact this sector at large.
We will see more movement in the sector as everyone has one eye on the wider deals here and that Tesco impact.
Their core business continues to perform and they're often leading the way with store standards in the channel, certainly versus Express where things appear to have fallen off a cliff in recent months. Unclear why specifically, although there have been a number of changes and cuts to the operation there.
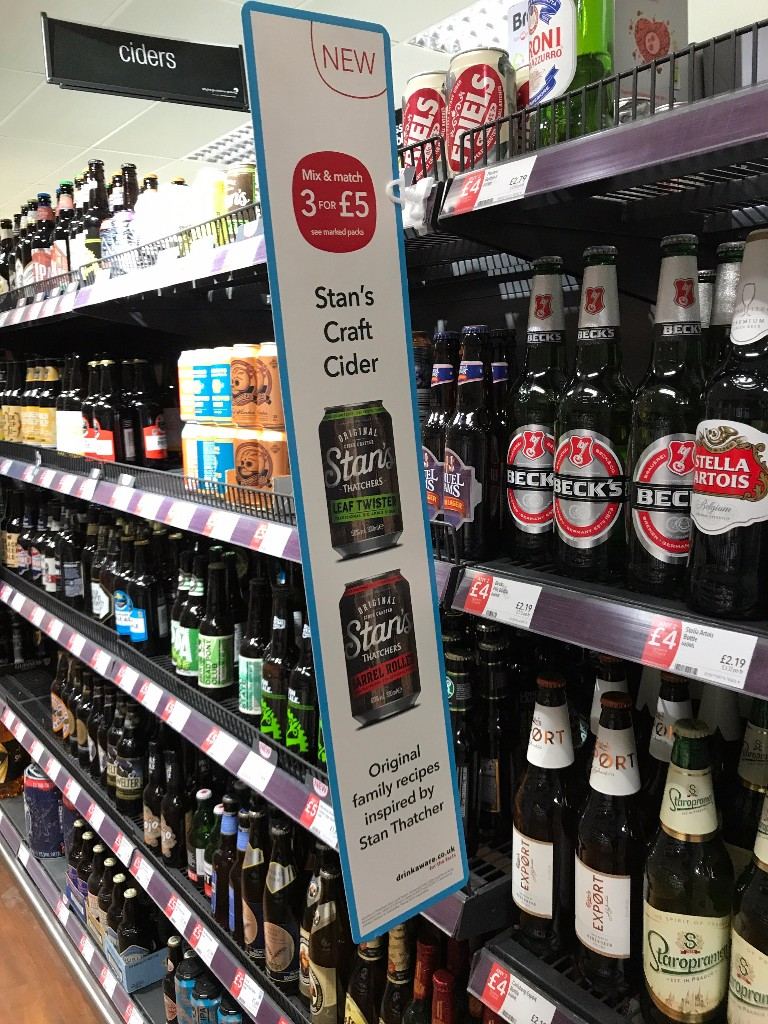
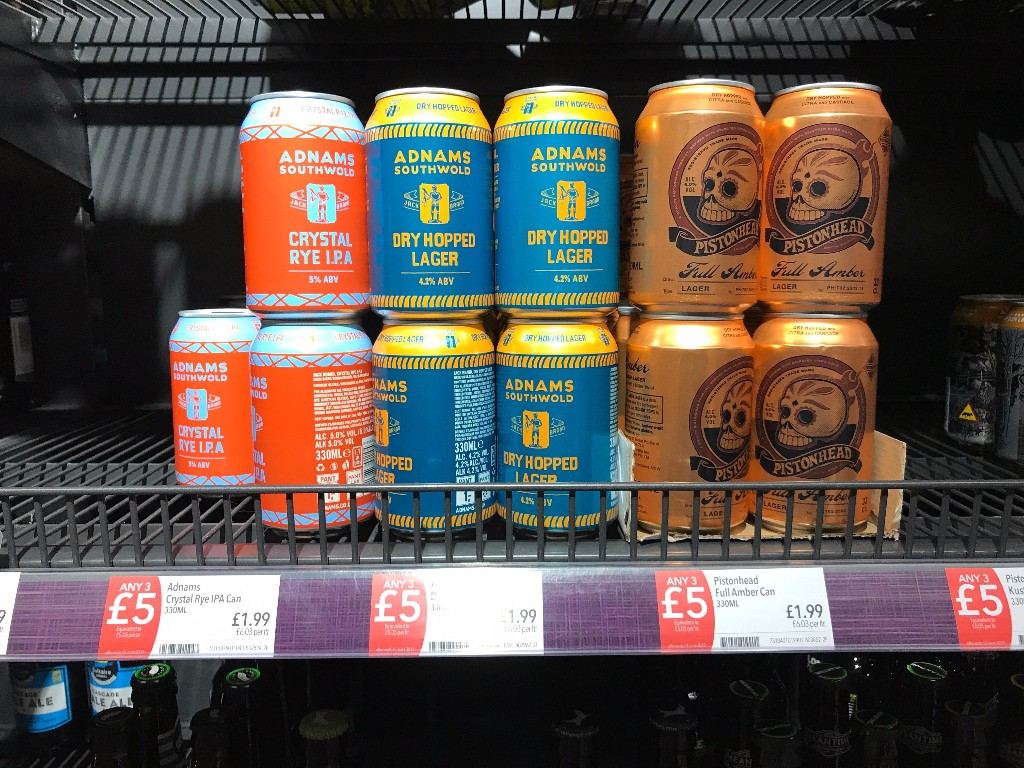
Craft ales is another growth category for everyone; every retailer is in the mix now, offering generic looking tins alongside ones that are near beauty.
The Co-Operative are bang on trend and this is great for them, a growth category, It's Beer/Alcohol so likely to be picked up by customers. A growing trend and one the Co-Operative are chasing down here.
So there we have a brief run down of the various events in the UK food market as is, not even covered discount, or Waitrose!
There's lots more to cover in the coming weeks, discounters in general, ranges, City Target (New York) and the wider future of good, better, best as well.
From the Grocery Insight newsletter archive, first sent to subscribers on 11 May 2017. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.