Retail By Email - Issue 477 - Tesco Clubcard Prices
17 June 2022
View this email in your browser
Retail by Email - Issue 477 - Tesco Clubcard PricesAre they all that?
The strategy to move all the deals to Clubcard holders only was brave and something I never thought Tesco would do, they did hold out with the Food to Go based meal deal, but even that is £3 but only to Clubcard holders.
£3.50 for everyone else.
You do feel like an absolute failure when you don’t have a Clubcard and are forced to either pay full price, or shamefully tell the colleague, or self checkout, you don’t want the item(s) that are eligible for discounts.
That said - the deals have to be worth crossing the road for and indeed, getting your Clubcard out, after all.
It’s clear that Tesco benefit significantly here with their data arm strengthened significantly by the emergence of tonnes more data for their systems to get to grips with.
It will be valuable but still, at the moment, the data will be flowing through but the scale is still yet to be properly discovered.
Loyalty does allow for customers who have “lapsed” to be targeted with money off in order for them to shop with the retailer once again. Rather than poorly targeted £5 off £40 in the paper, or via competitors (as we once saw in the UK), targeted money off can be utilised to drive customers back to the stores.
The challenge is - any issues the customers had before have to be ironed out, so if the store was poor thus the customer walked, it’s pointless sending them back in to find the same, albeit at a hit to the margin.
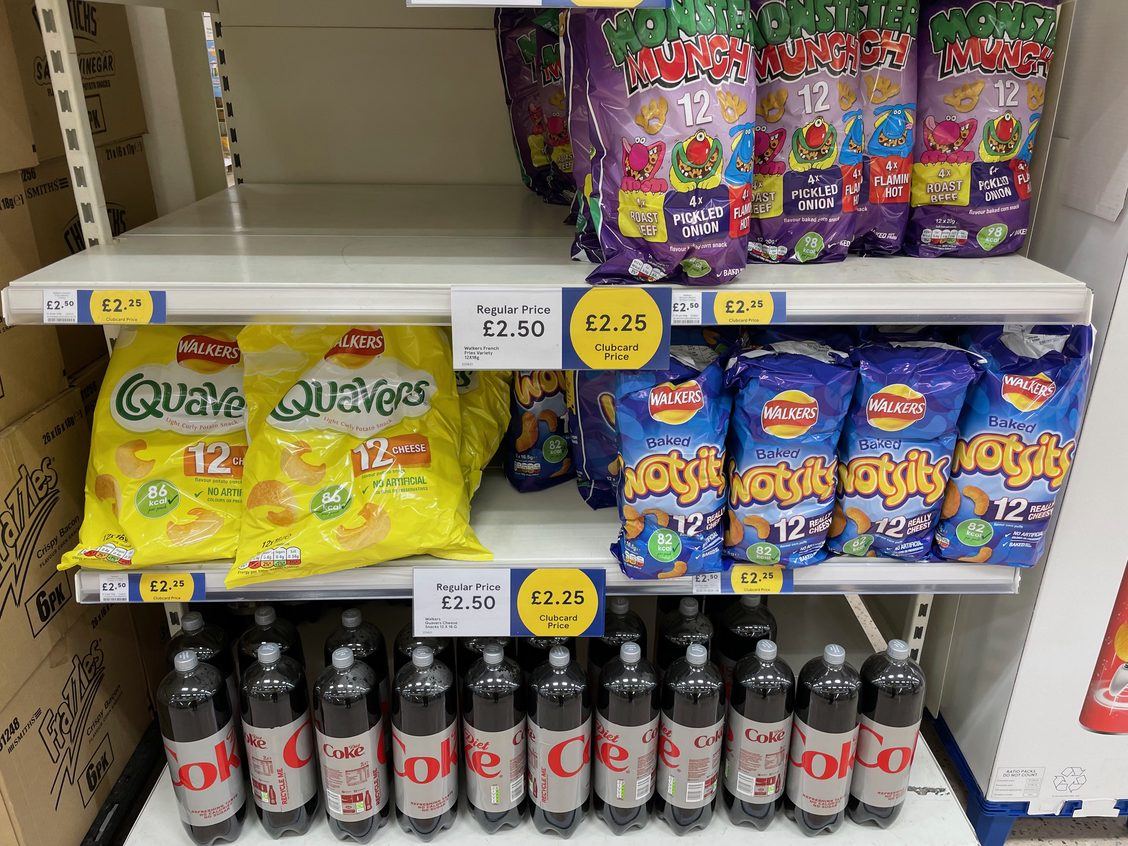
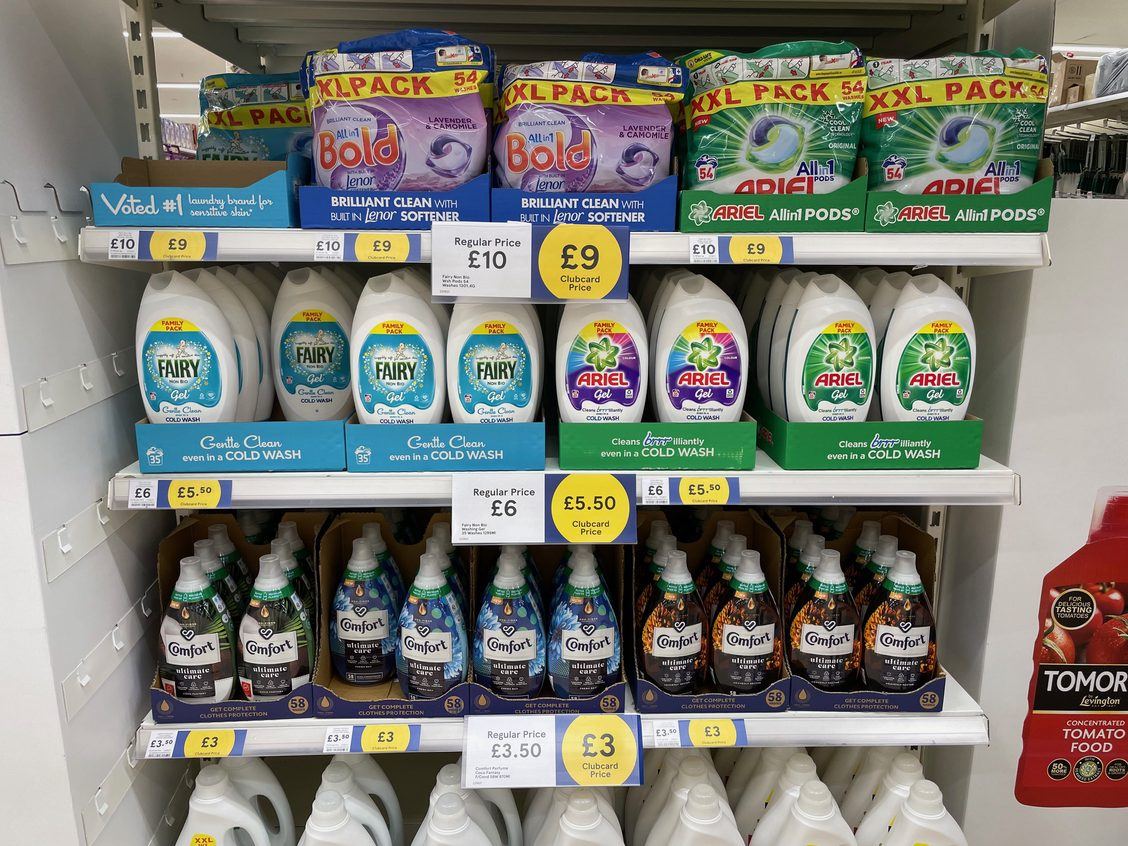
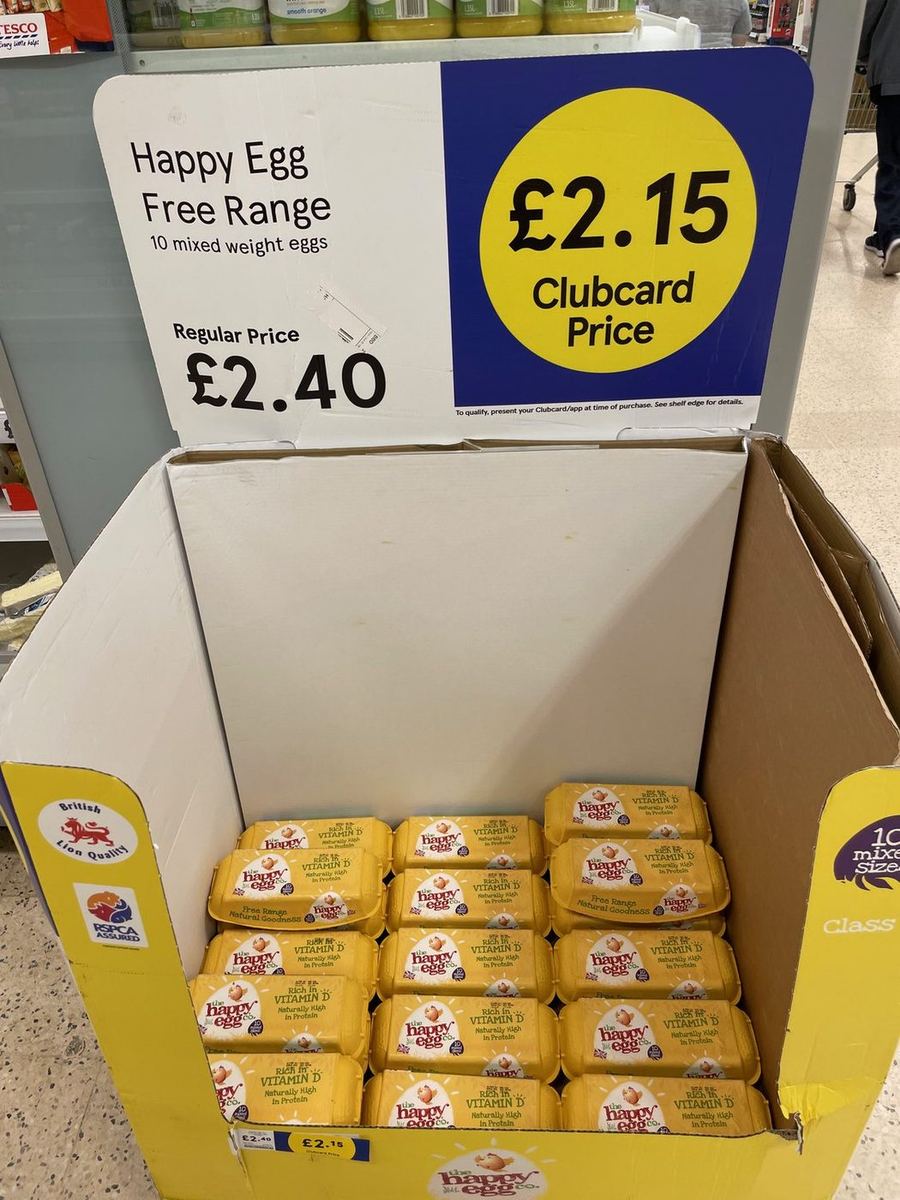
Whilst the “net, net” benefit of having a Clubcard means you’re eligible for all the deals, good or bad. The risk of having weaker ones, so prominently on display is risky for the obvious reasons.
Drawing comparatives with other retailers, especially the likes of B&M and Home Bargains who are very strong in Household areas like Laundry alongside Pet too.
Featured space is vital to advertise the key deals and to give the customer the confidence they’re saving money. Sure, EDLP does that with the Aldi price match, but nonetheless, prices are still rising across the board.
Tesco with the loyalty driver on promotions, can ill afford too many “weak” deals that could see the customer considering crossing the road.
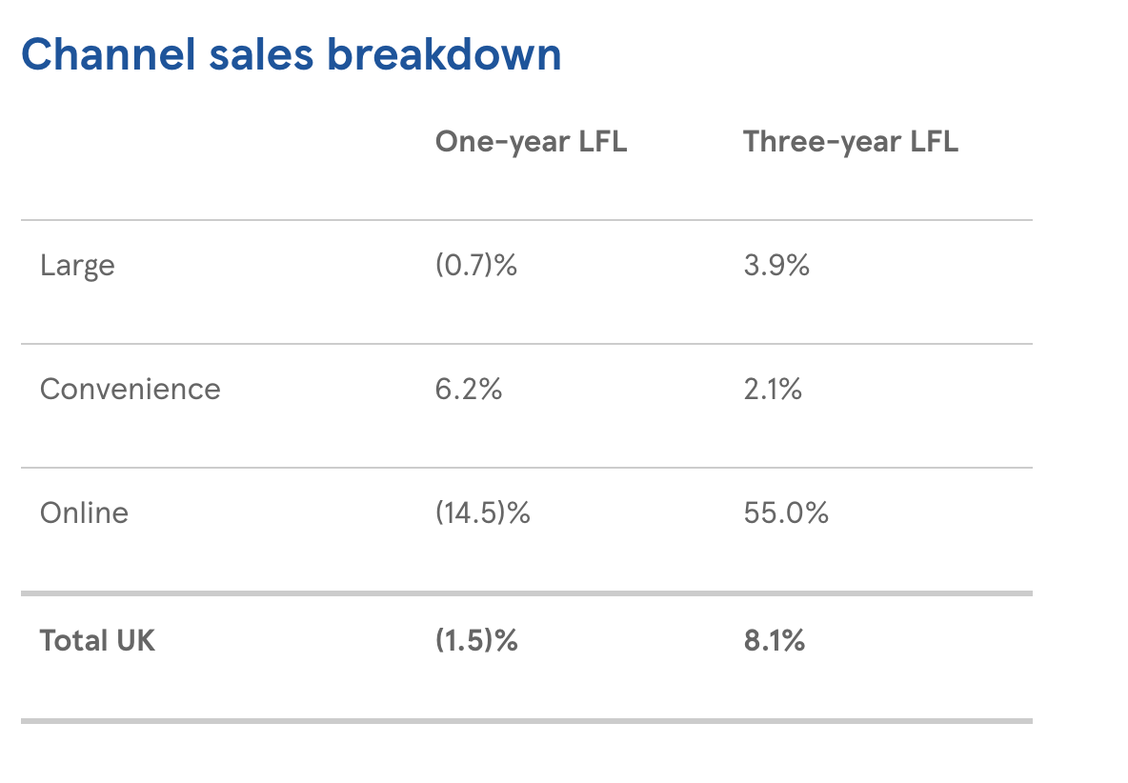
Tesco Q1 sales were out today and broadly they were in line with expectations, with sales down on the last year but considerably higher over a 3 year period (factoring in the COVID impact).
The fuel results were of interest and I erroneously thought fuel sales were -1.5% down, but that was the sales number ex VAT (on the fuel results area, I ask you). Alas they were +44% on fuel which is unsurprising given the inflationary pressure there on the pump price.
The interesting element for the sales mix in Tesco was that both UK and ROI were down but the overall results were boosted by Booker who weighed in with c. 19% rise on a like for like basis.
Clearly aided by the off trade and hospitality getting back to normal.
The noteworthy elements for Tesco in terms of the sales mix was that large stores were negative on a like for like basis and Convenience was recovering well, with +6.2% like for like on a year ago.
We have to trade more to really see if we are seeing a shift to c-stores once again, or whether this is because the city centres have opened up and people have returned to work, thus driving c-store sales northwards.
Online negative 14.5% is also not a huge surprise either and indicative of the trends here. Overall they are still 55% up on a 3 year basis, but the capacity in the chain simply won’t be required if sales keep fading away in this channel.
All in all - a solid set of results for Tesco and it remains they case they look the best insulated of the “big four” to weather the cost of living criss that’s facing many customers. That said, there’s always work to do….
Want to find out more about our services and the wider retail market?Subscribe to this industry leading insight service, today.
From the Grocery Insight newsletter archive, first sent to subscribers on 17 June 2022. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.