Tesco own label - Prioritisation continues apace
23 July 2019
Join our insight service today
Good morning,
Tesco captured the headlines last week for a series of price hikes across own label products alongside branded ones too. Perhaps surprising but then in reality, Tesco were taking the headlines in the not so distant past for barely increasing a price when inflation was rampant in the sector.
Tesco have been working hard on entry tier, farm brands and the like as part of their value proposition and trying to stop the loss of customers to Discounters. Indeed; this has been a successful strategy for them as like for like figures have stood up well and indeed, a recent note from ourselves showed Aldi reacting to this encroachment by having their mid tier own label mimic Tesco in Frozen Foods.
It's hard not to forget the inherited mess that Dave Lewis encountered when he took over, the accountancy issues and subsequent legal process often occupies the mind of many. But the core estate was in disarray and the proposition was 'confused' (to be as polite as possible....)
However some 4 years on: Booker are now part of the Tesco world, a number of closures, central restructures, sales of subsidiary businesses and introduction of industry leading initiatives (such as farm brands, now imitated by every other retailer) mean that the numbers are harder to come by.
Certainly when highlighting lower prices across the store, particularly value brands such as the 'exclusively at' means if you sell more of those lines, then customers are potentially not buying the higher margin mid tier. The idea is that customers buy some of those value tier products rather than going to Aldi, so the effect is net positive.
However there is always the risk that things do not transpire that way, customers are fickle and choice is abundant. One notable aspect of the discounter rise is their location planning which has evolved to be a small, metro/neighbourhood offer with ample car parking and low prices too.
(Note the award wins on Pizza in Aldi).
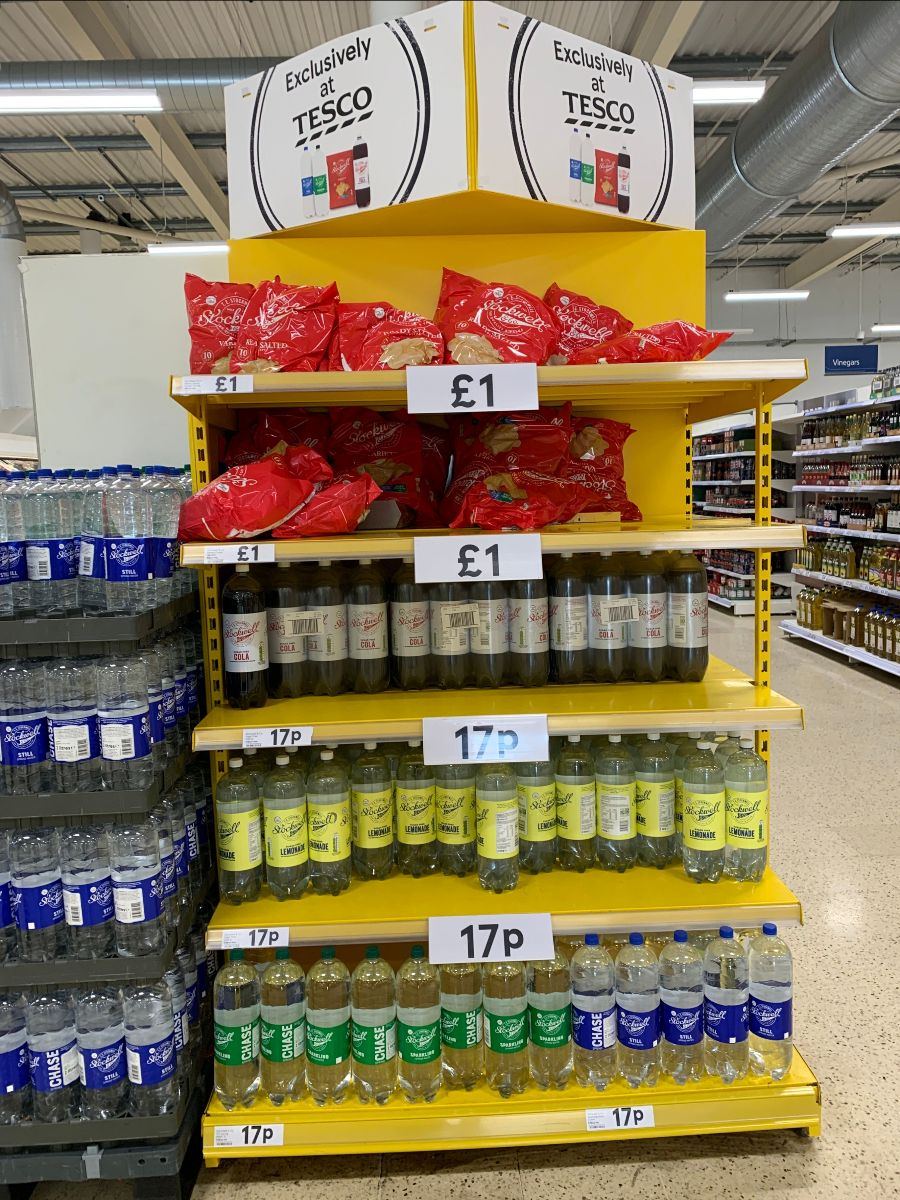
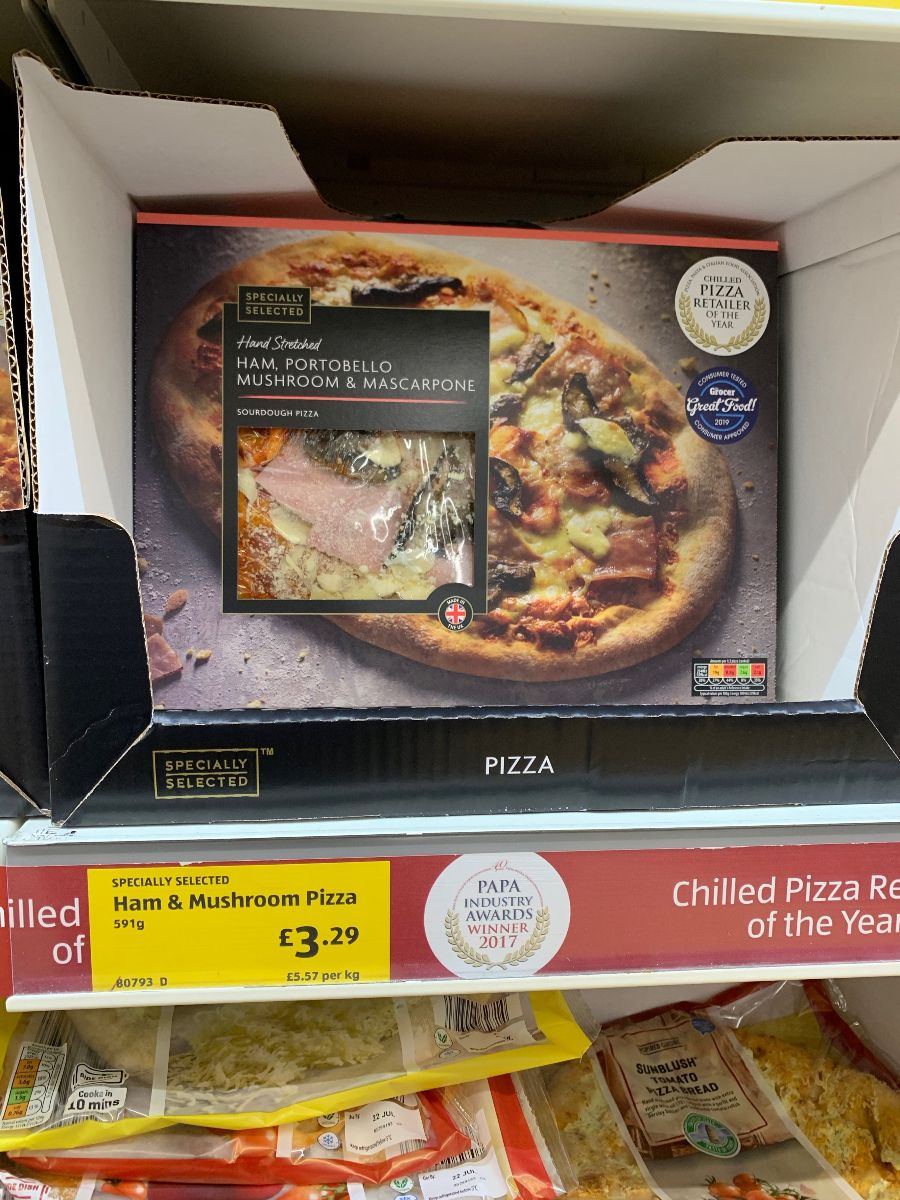
Further evidence of the Tesco strategy for value being adopted elsewhere has been noted in Sainsbury's particularly, with their J.James and Stamford St sub brands making their way in to Frozen and chilled convenience foods (IE Pizza...)
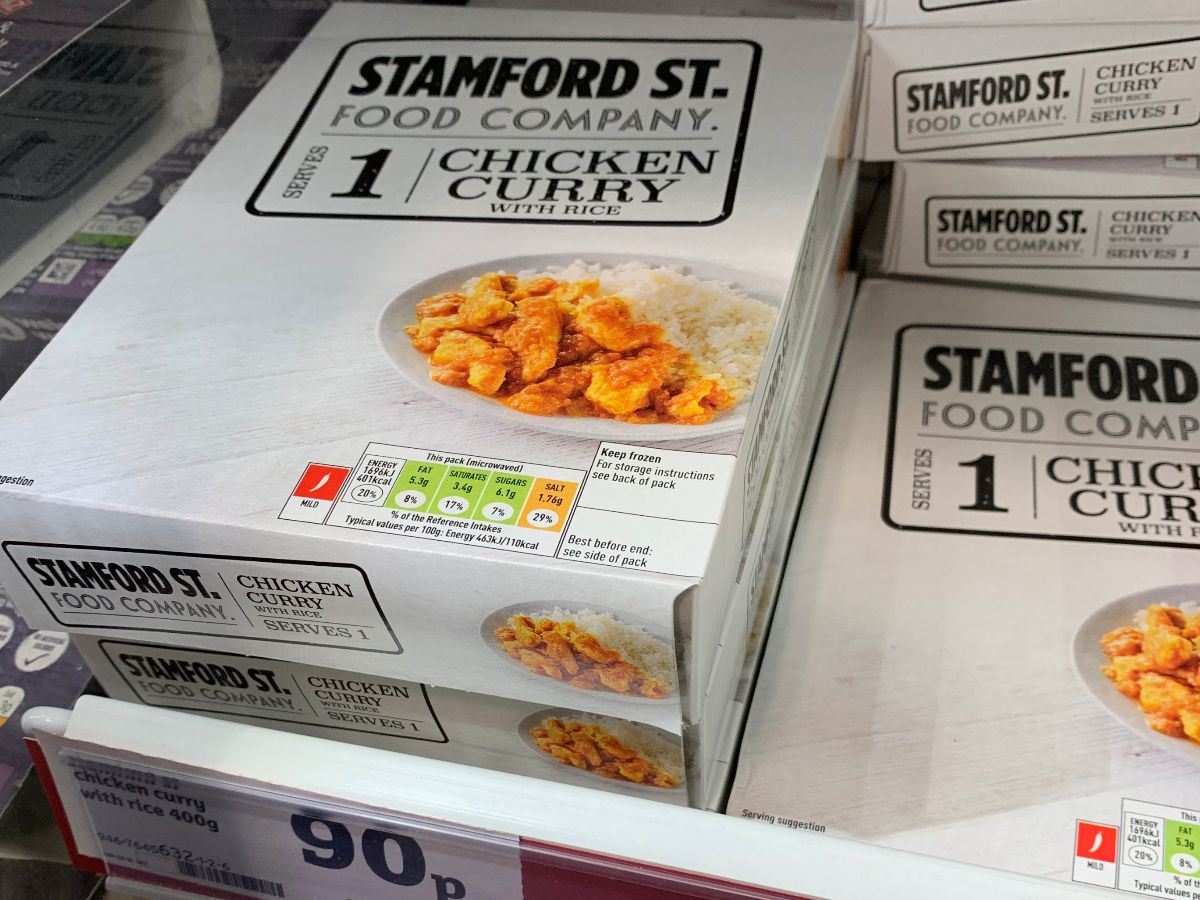
For Tesco: their work with value tier products has underlined value credentials but being mindful of that split, ensuring that core customers 'trading down' doesn't outnumber those who are still departing to a discounter....
Another interesting area of progression for Tesco is their movement around brands. For a number of years, they have ensured their layouts are preferable to their own label (exclusive to Tesco after all).
It's a good way to demonstrate value, quality and develop a business that customers will come to Tesco for... Buying more of this means the brands have to work harder to get their business moving.
As we see in both Aldi and Lidl, leading brands are trying get in on the growth by having their products sold 'off shelf' in shippers and special buys.
It's not a strategy.
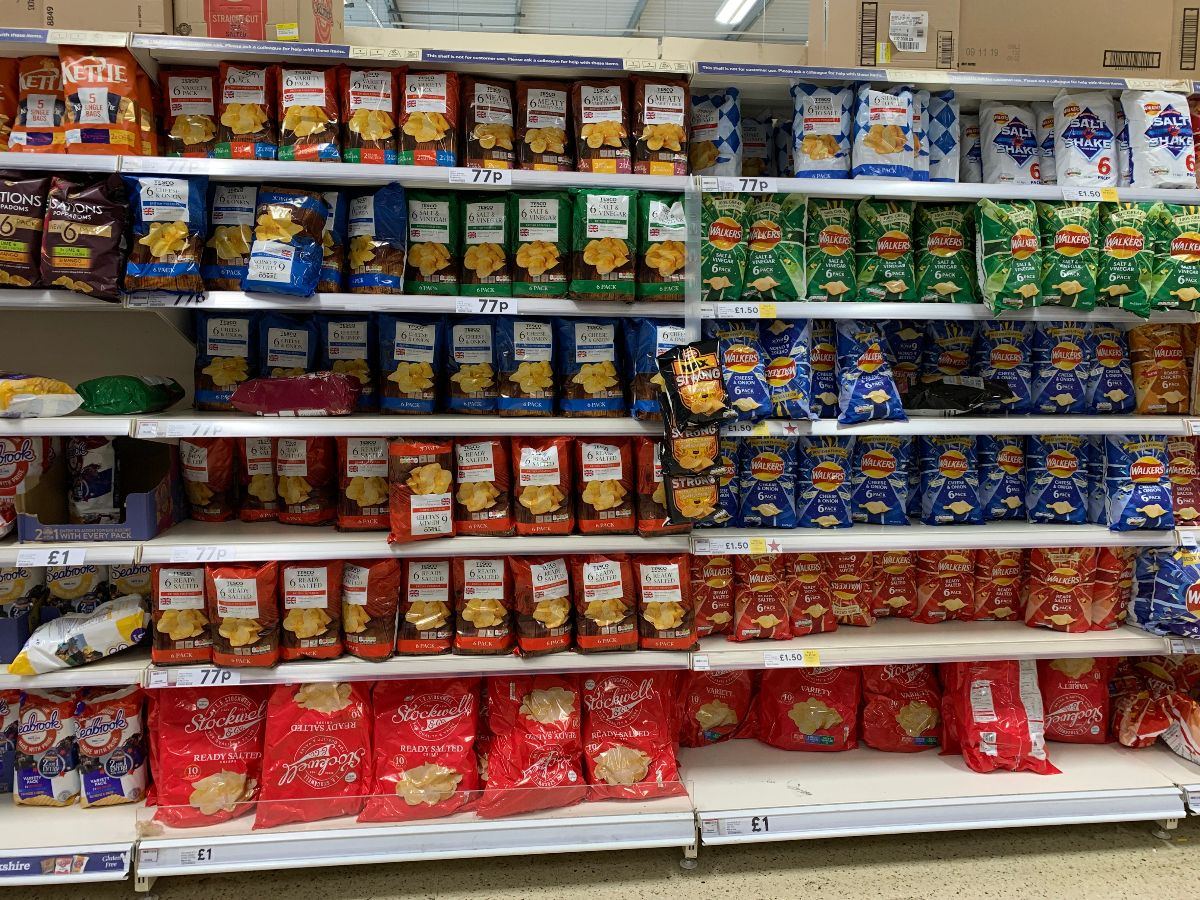
However the Tesco shift looks inherently strategical and the progression year on year continues apace. If we consider Crisps - a brand dominant area, own label always struggles but at 77p, there's great value here.
The value tier is £1 for 10 bags which seems strong too. The brand is up at £1.50 and whichever multibuy is running at that time.
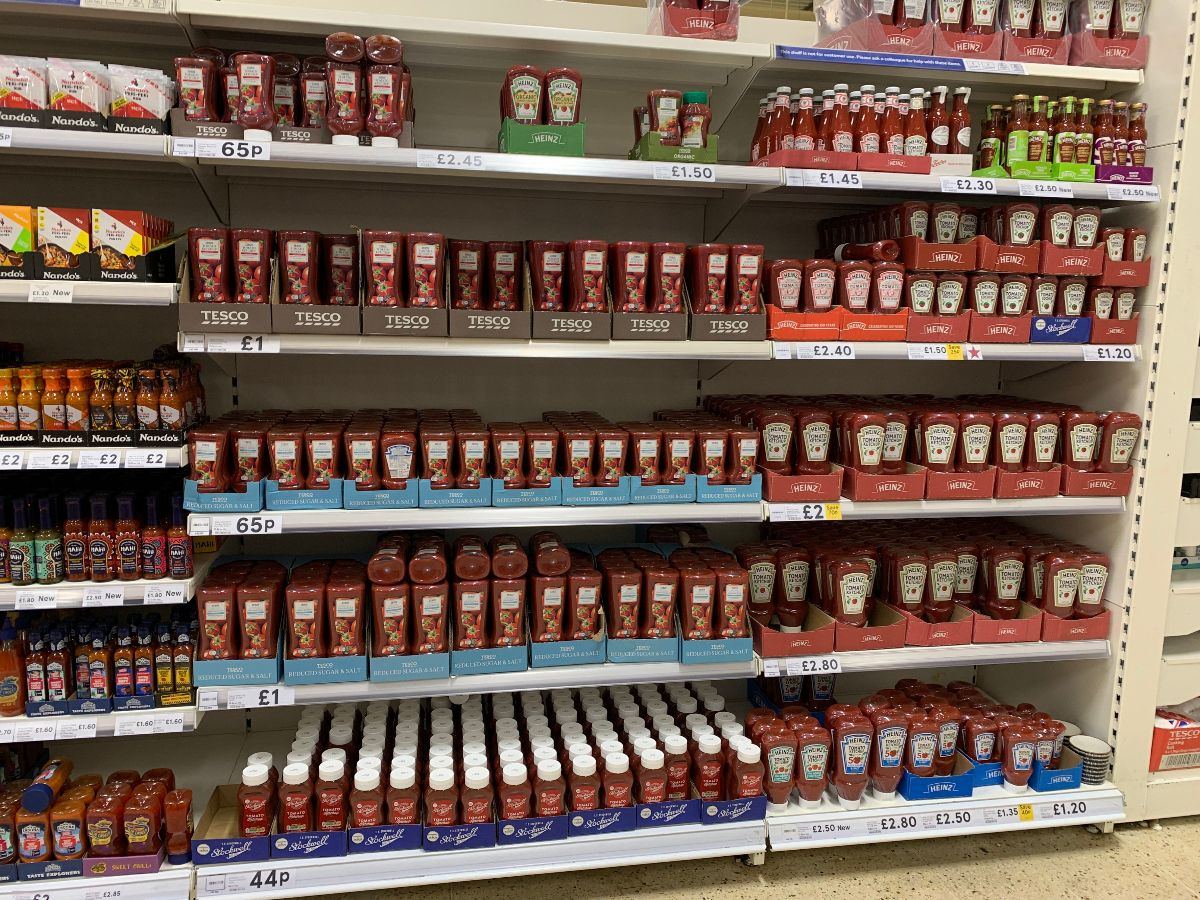
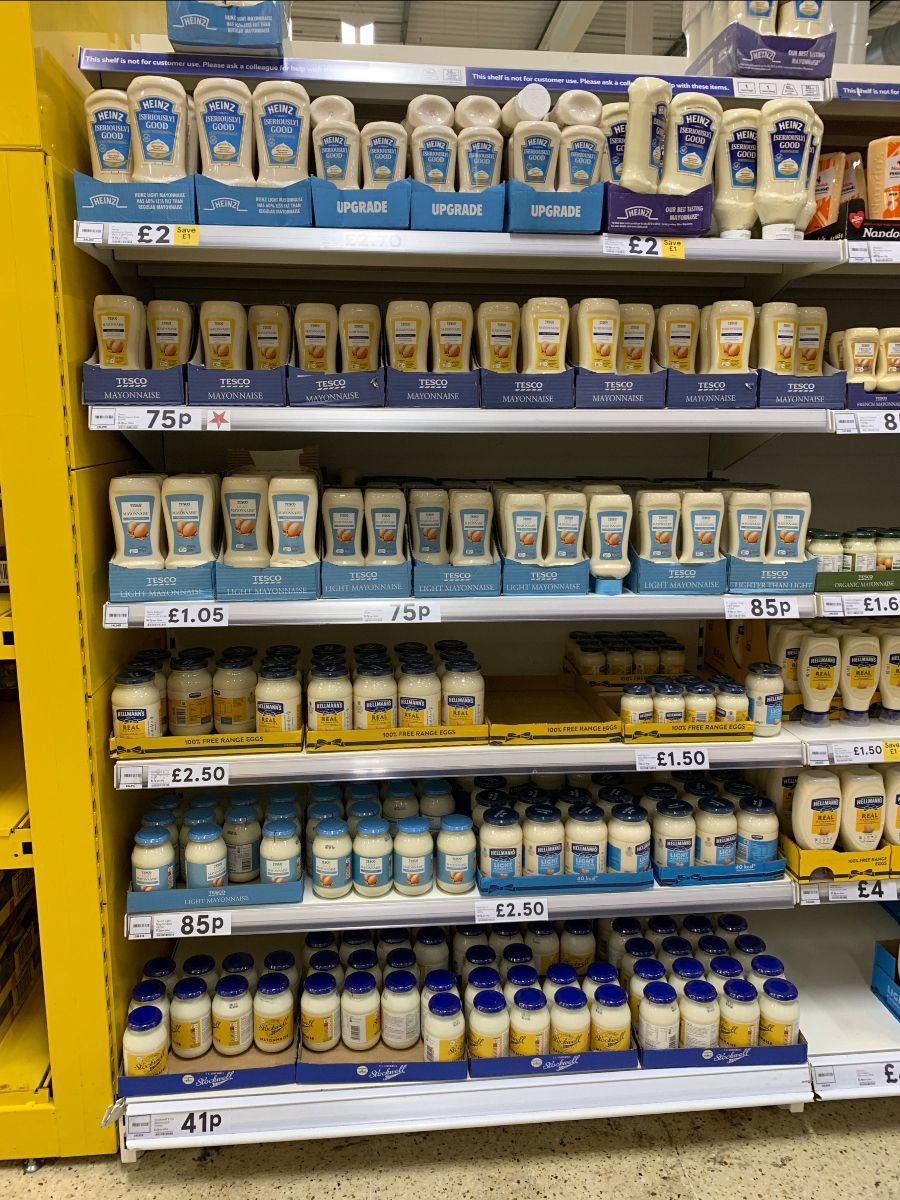
The strongest work was in Sauces and to a lesser extent, Mayonnaise.
Certainly in Tomato Sauce; just look at the space that own label is afforded. Whether this is an error in terms of space allocation, it remains unclear but the own label has a greater stand out than brand in any case.
Solid shelves of product and low prices with value at the base for just 44p.
The branded equivalents are in the smaller bay (this could be a store nuance) but the space equivalence is notable at the high level.
But the presence of own label alongside the clarity is crucial and so clear for customers too.
Value comes in many forms, but own label prioritisation has been a key one for Tesco in recent years. You can have all the exclusive brands / editions in the world.
But your own label is truly exclusive, merchandised well and priced to sell should see greater returns via a greater share of spend.
Forwarded this note? Want to subscribe?
From the Grocery Insight newsletter archive, first sent to subscribers on 23 July 2019. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.