Tesco v Aldi
5 March 2020
Visit the Retail Bible - our new platform for imagery and insight
The Bulletin
Our long read - next week will centre on price and notably, the link between Tesco and Tesco Ireland as well, especially given this campaign.
But today marks an important step for Tesco and arguably, it's as important as the first stage of farm brands, all those years ago.
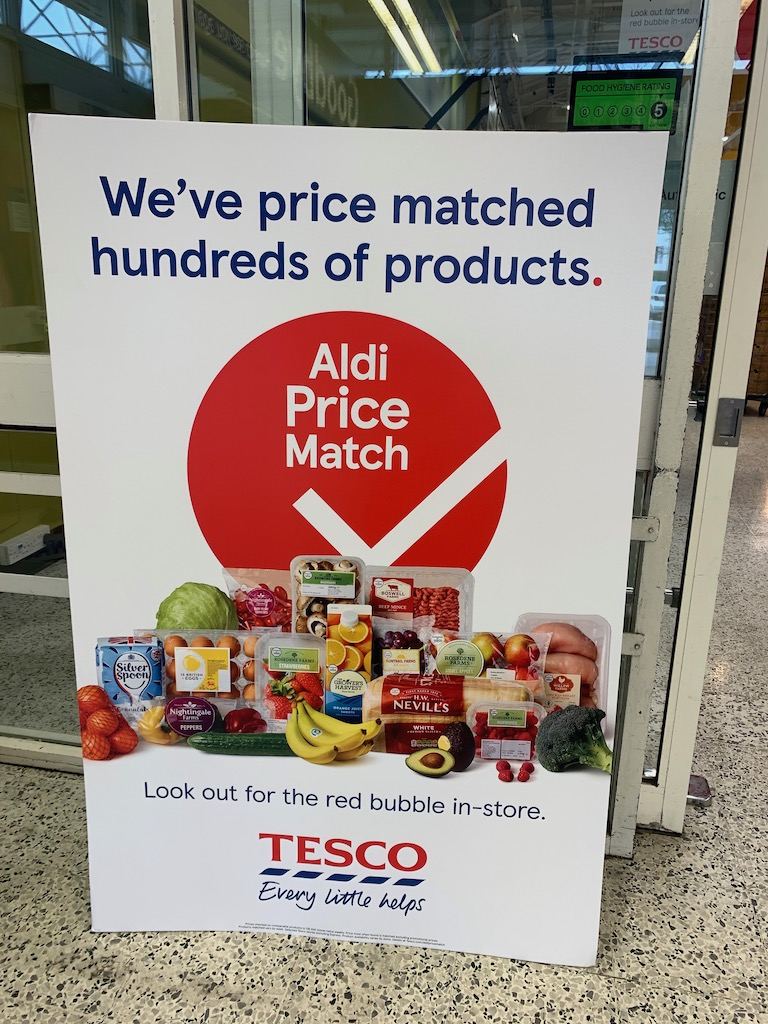
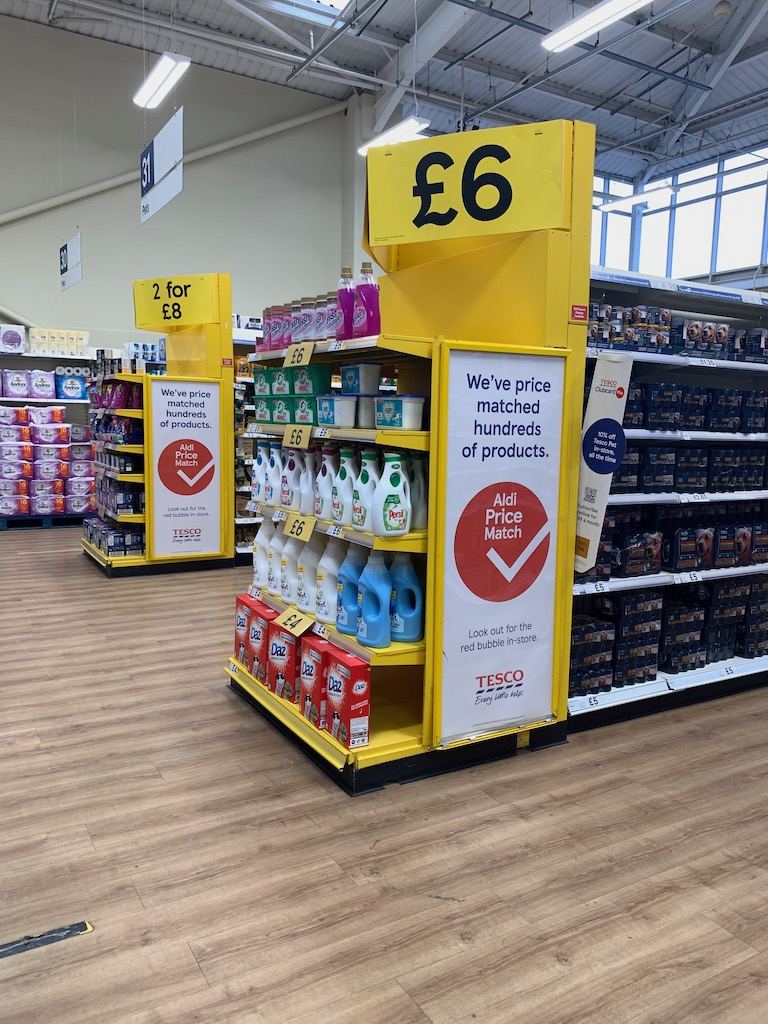
The notable element here is that value brands, the work that was undertaken previously by Tesco and imitated by Sainsbury's notably, has now made its way to the world of price matching versus Aldi.
We have tracked price for some time in the market, almost unofficially and Tesco have been 'following' Aldi on price around these value-based products week on week.
The theory is that (of course) there is a floor, which even Aldi won't go down below and thus, the 'price' remains 'as is' at that level. That is, on these products alongside branded lines (selected ones like Warburton's bread, PG Tips etc).
The spadework and baseline work has been done in the stores for over a year now, so pulling this together isn't going to put a great deal of pressure on things, given the brands exist already in-store and are already competitively priced in any case.
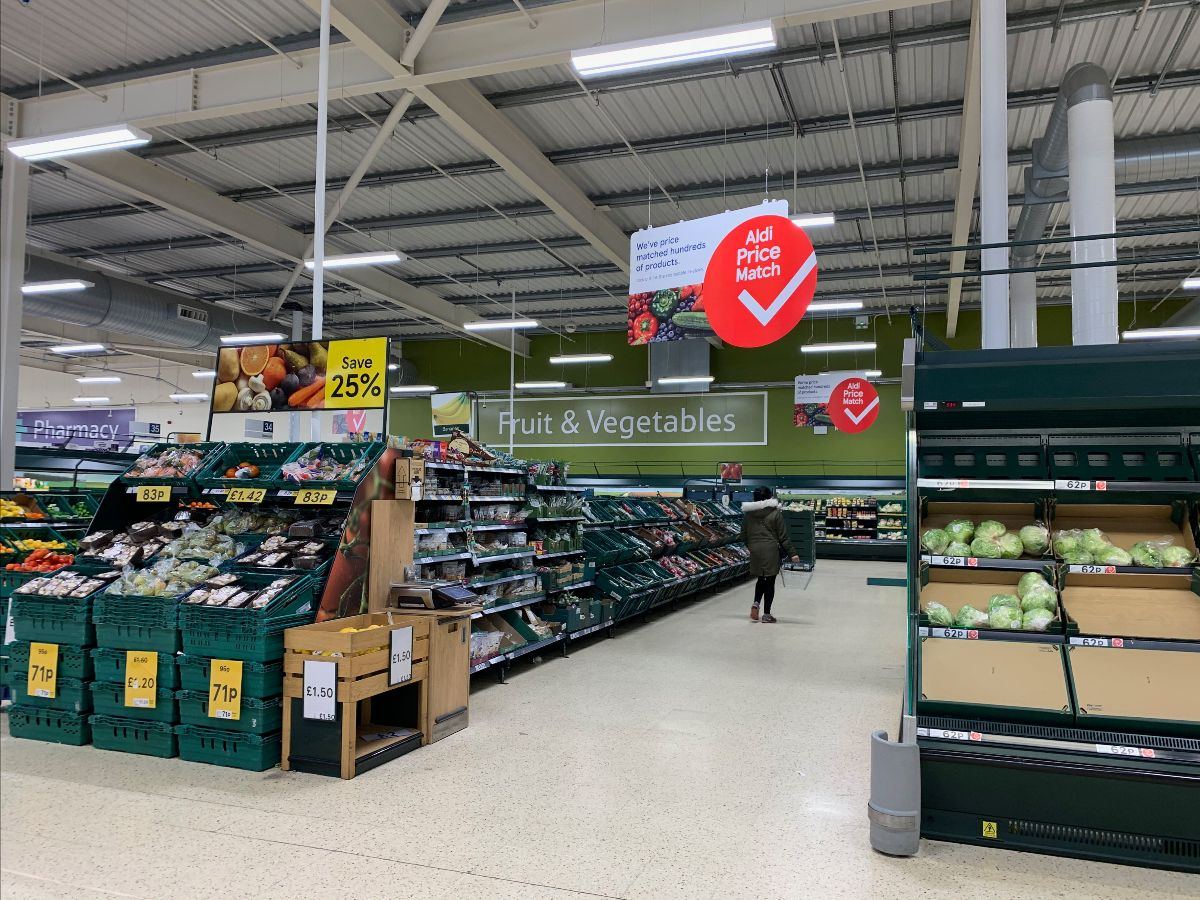
Marketing around the stores is impactful, bubbles highlight the lines that are eligible for a price match and whilst these are 'value' brands in the majority. There are other lines that are featured, such as own-label Rice Crispies and Weetabix also.
Notably, in Washing up liquid, one can see that the entire fixture almost is taken over with products that are price matched with Aldi across own label. Indeed, numerous products in household (Bleach) dominate the fixture with price matched lines.
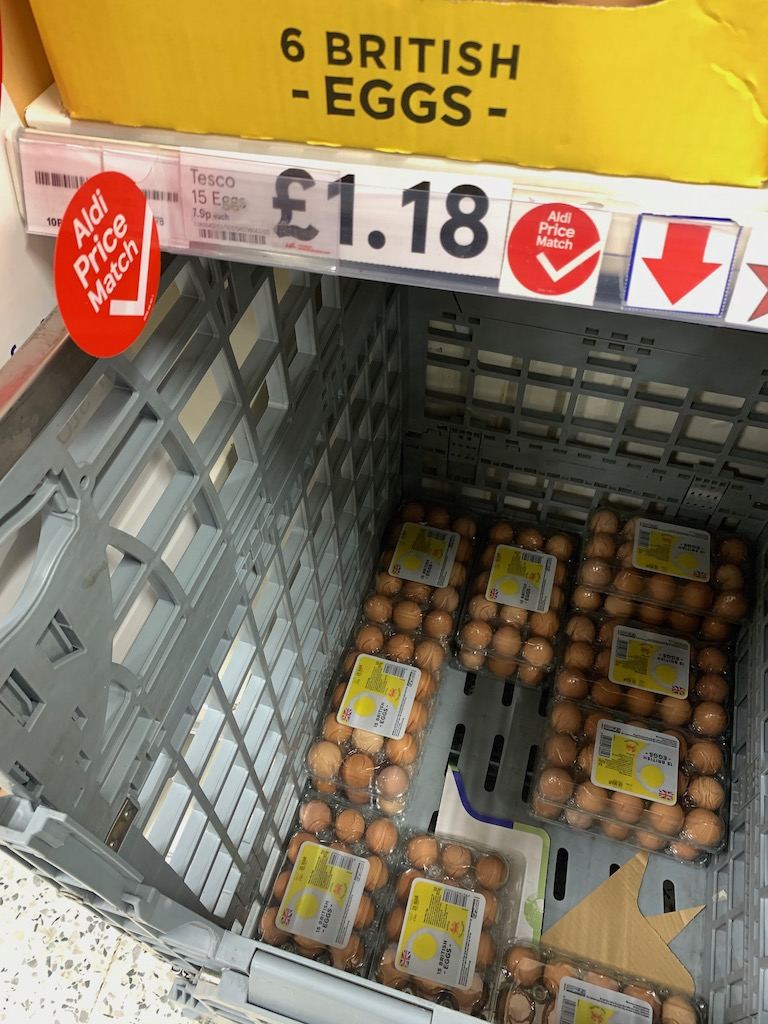
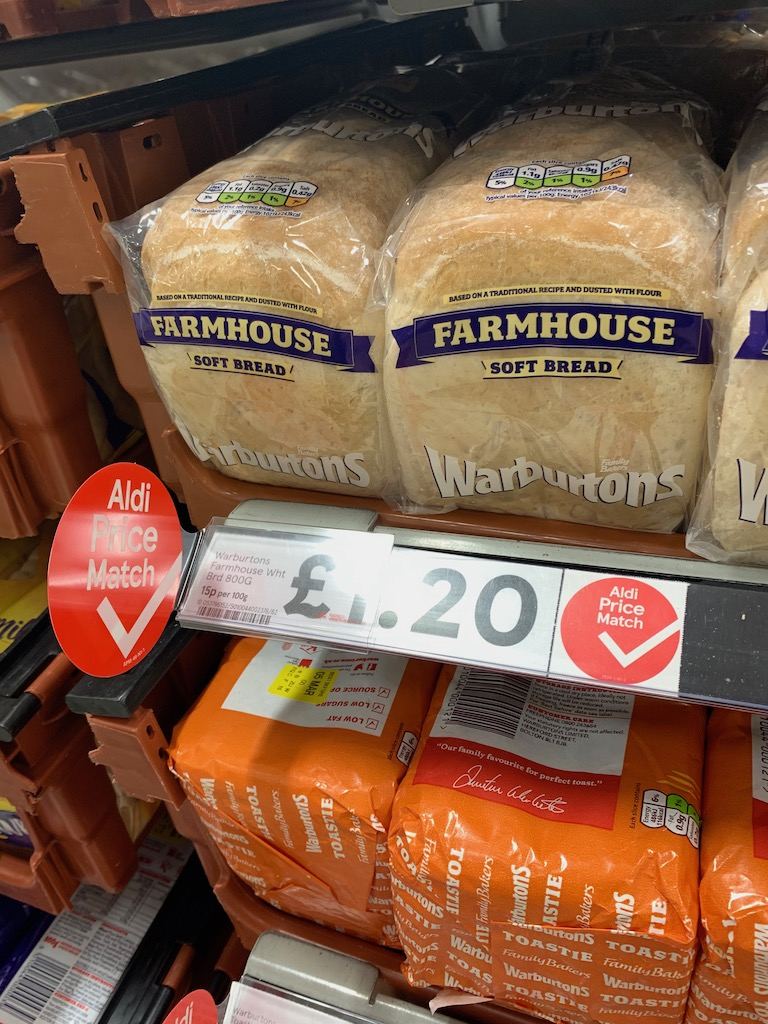
Examples of the activation in-store above, bubbles are used to highlight the products that are eligible under the price match.
there is no website (seemingly) or automatic check at the till, as we saw with a brand guarantee. The aim is that the prices will always be matched in any case, this occurred in Ireland certainly where this campaign is very similar to their work with "The 800".
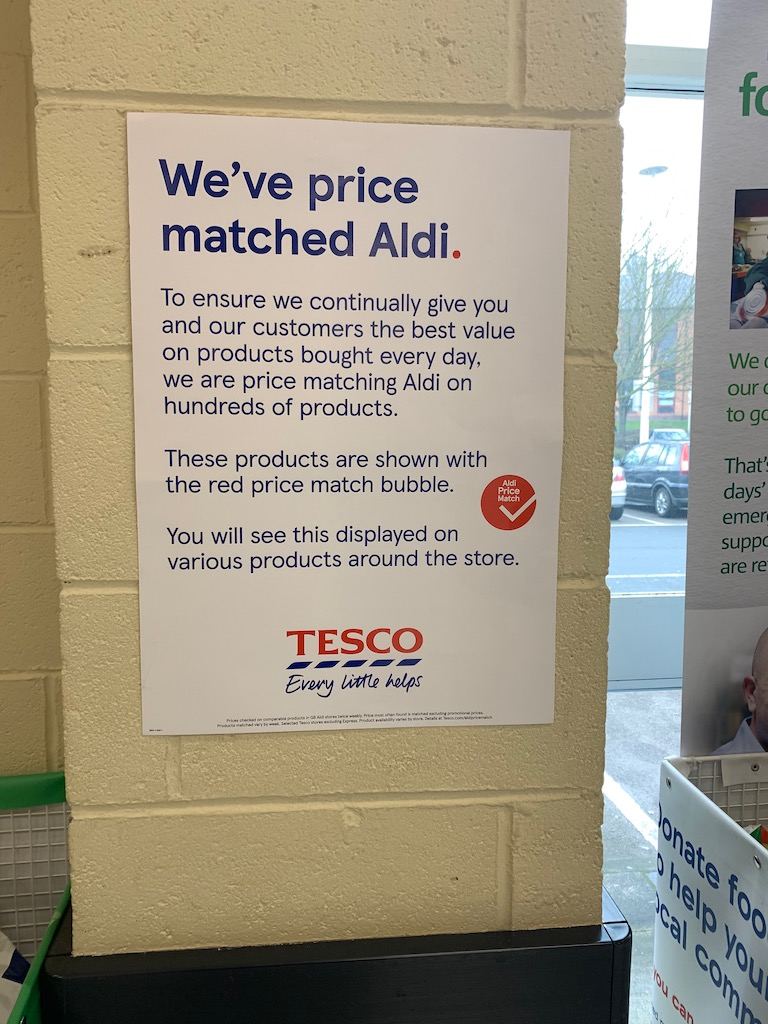
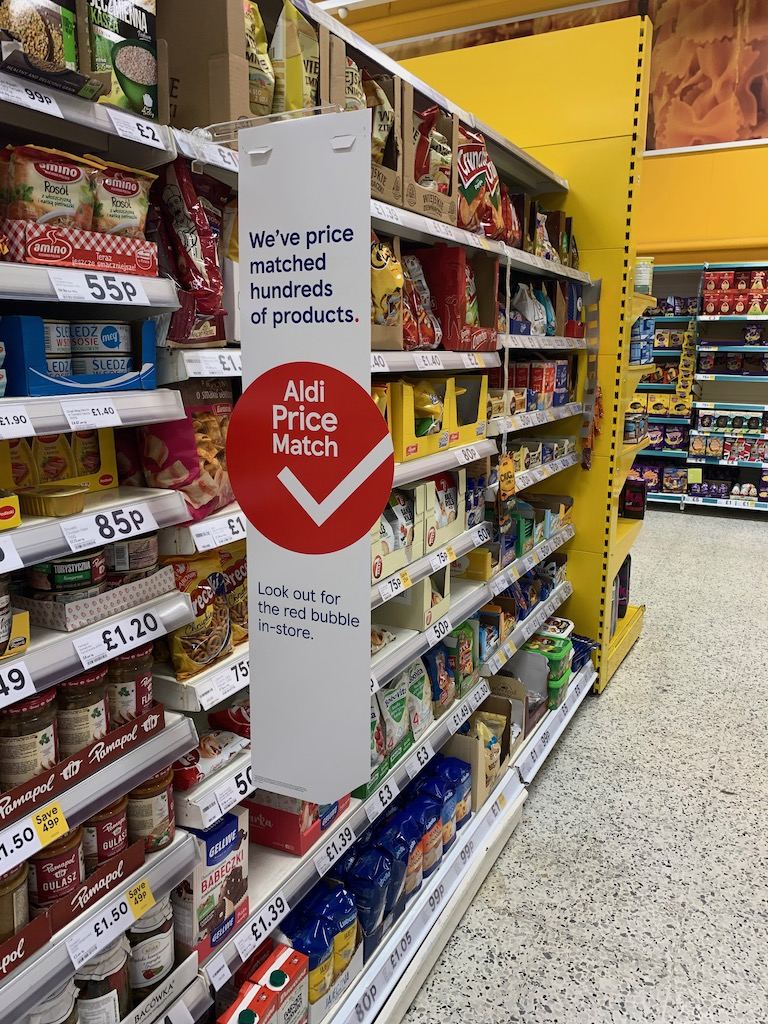
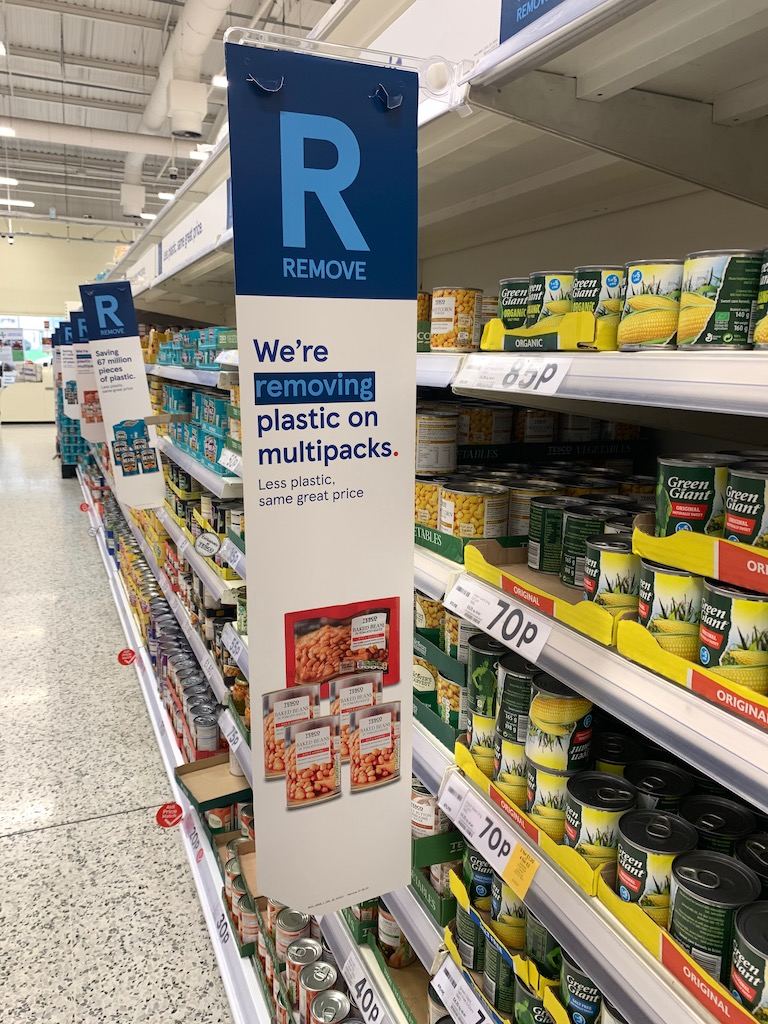
Posters in-store also highlight the scheme and overhead signage is dotted around the store, telling customers about the scheme and providing reassurance in this regard.
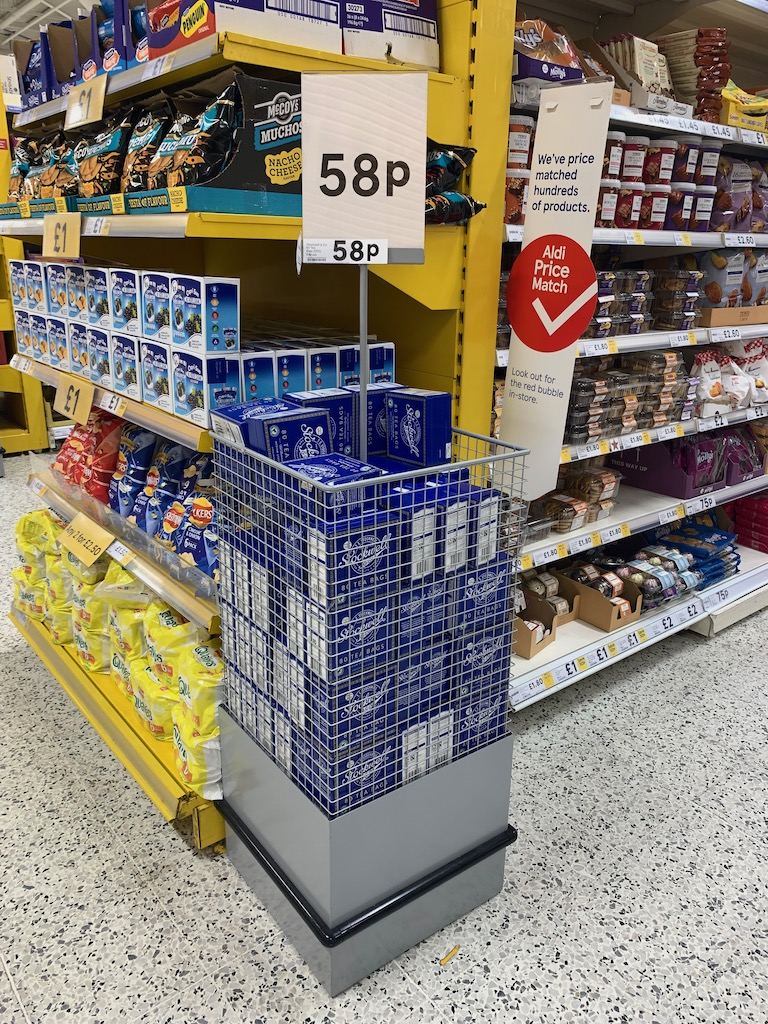
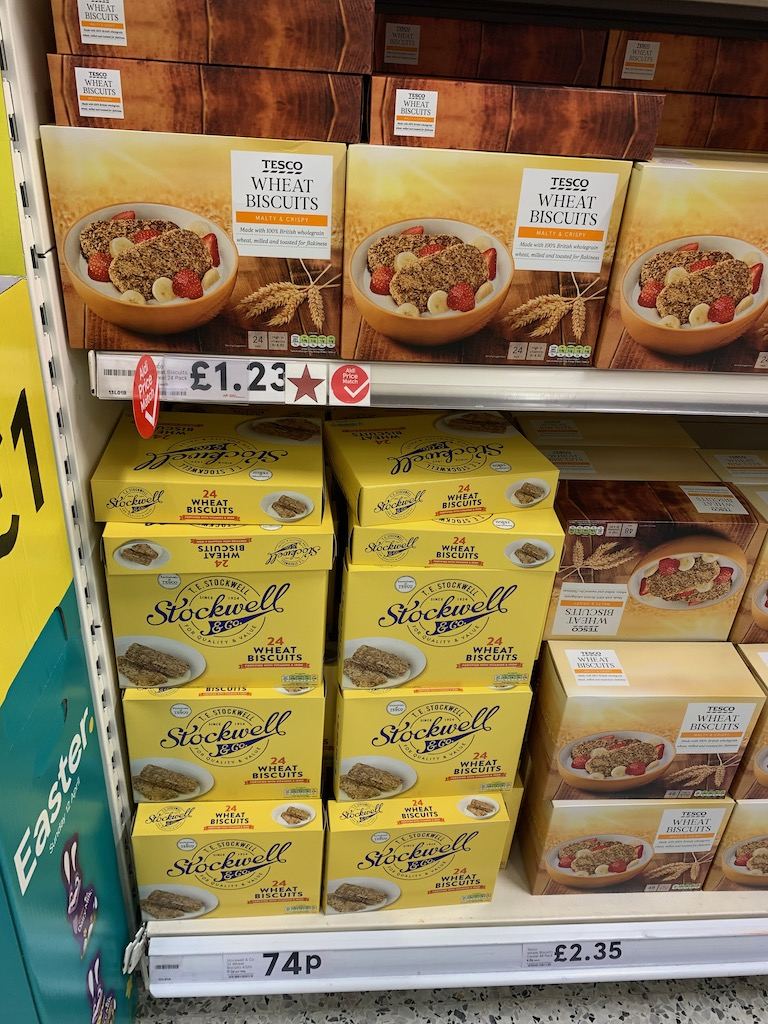
Given that value brands are centric to the campaign, additional displays have appeared around the store featuring the various value brands, like TE Stockwell.
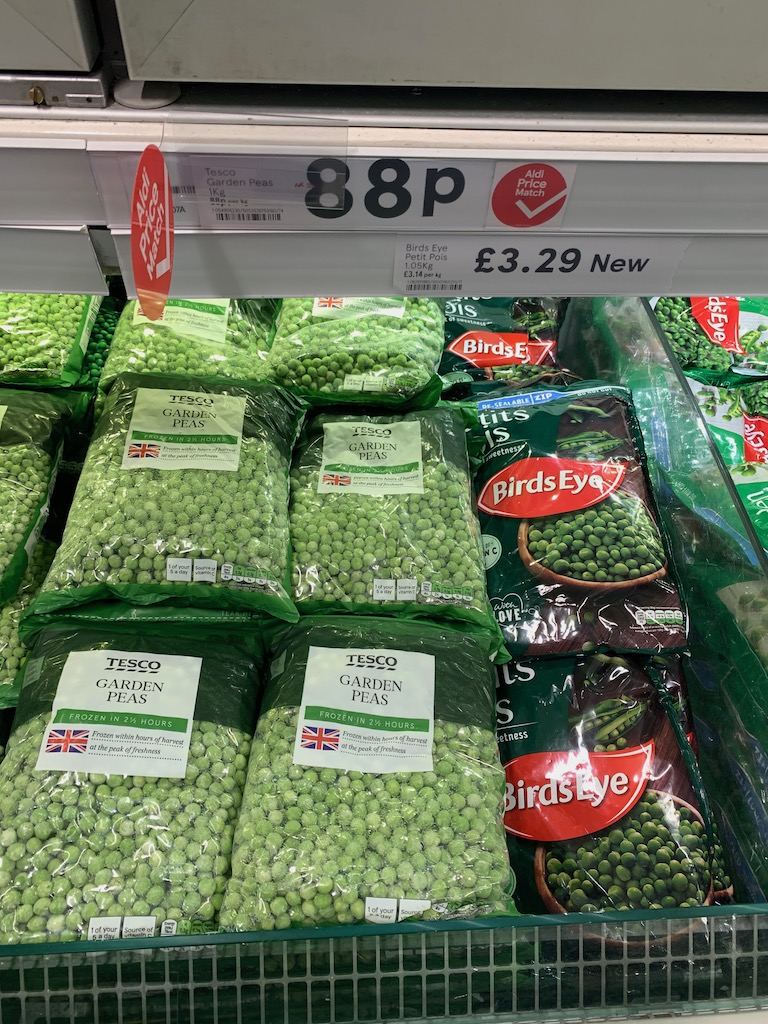
Key battlegrounds such as Frozen Foods are awash with signage that highlights lines that are being aligned versus Aldi price points.
This is of no surprise. Other categories that are key in this arena are Meat and Fish (the first farm brand category of course) and Fresh Foods where a number of bubbles can be seen highlighting price matching here too.
Of course, Fruit & Vegetables are well represented with price comparatives here too.
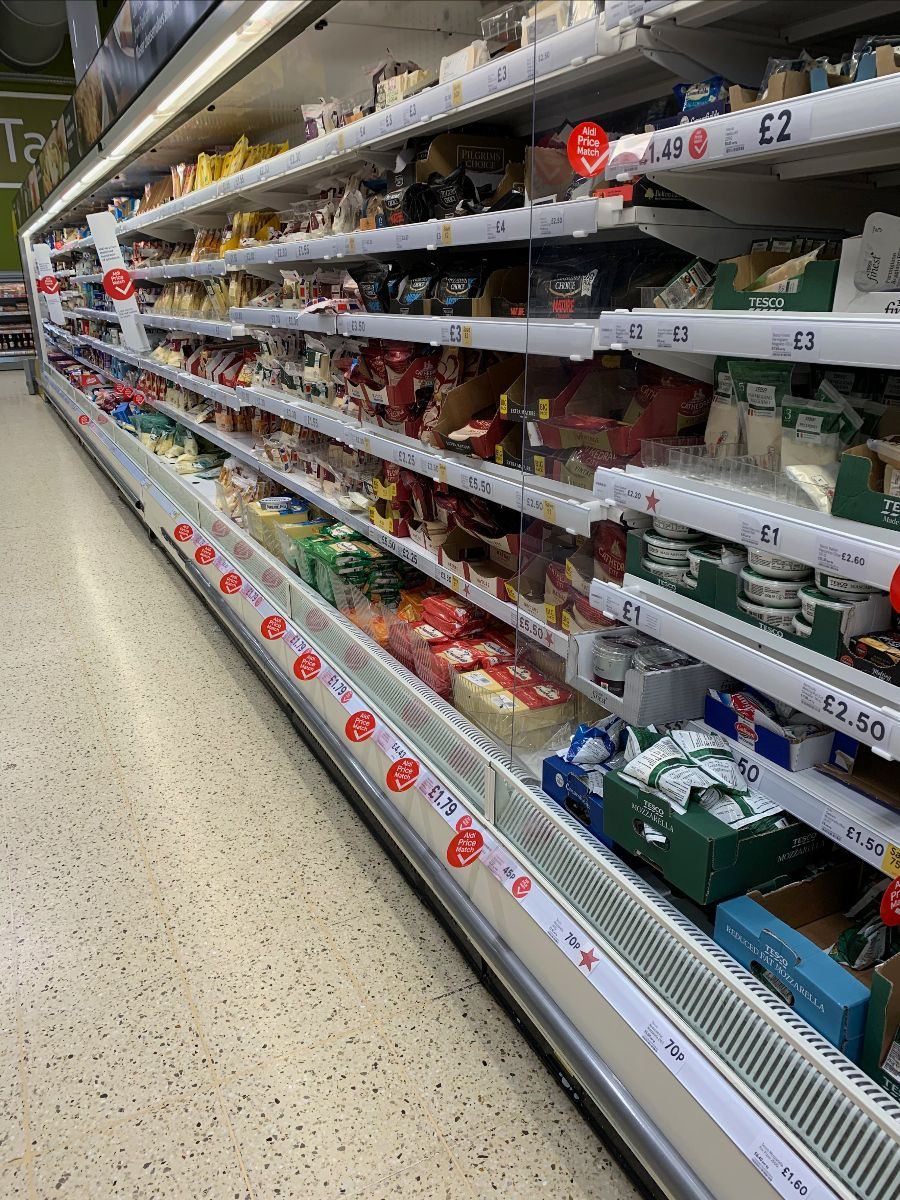
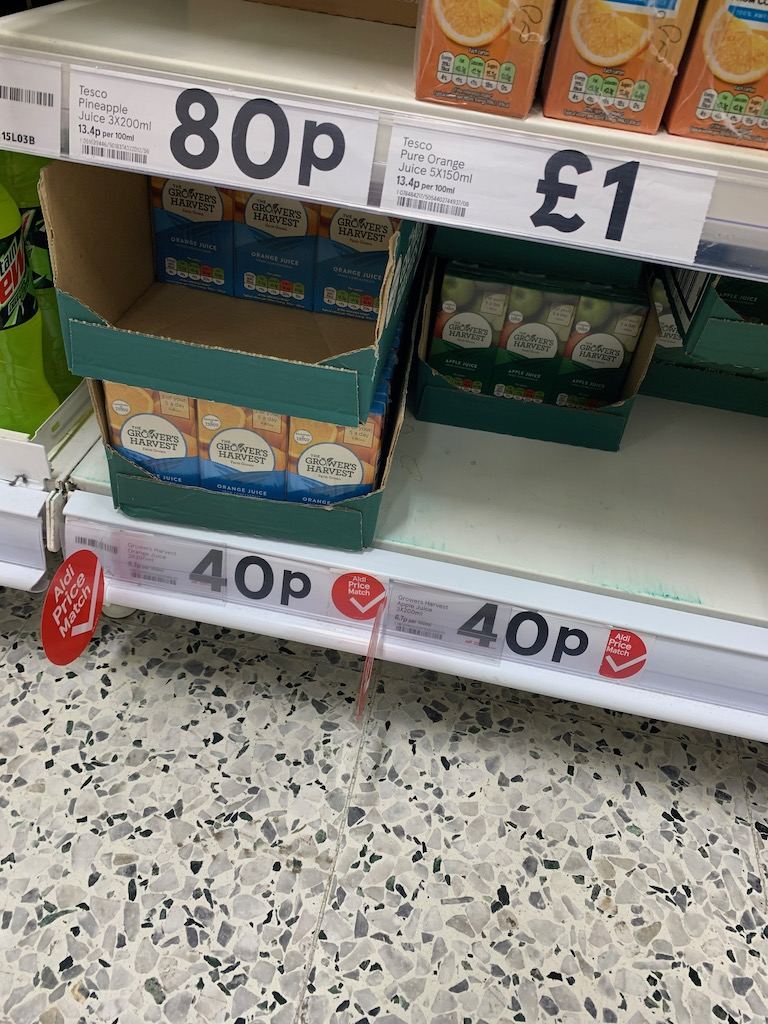
All areas of the store were touched near enough, with value tier examples in Juice, versus the Aldi 'own label' but naturally, their range is limited so by definition, their 3pk Juice would be mid-tier because of the limited range model.
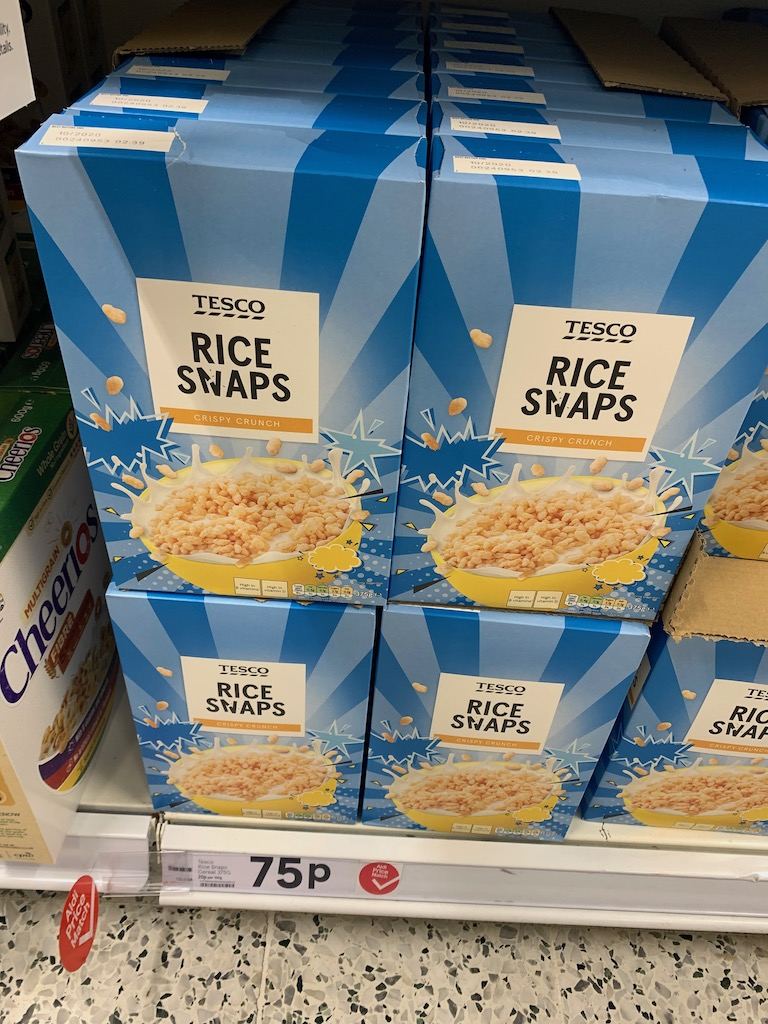
Note that in Cereals, the value tier product wasn't price matched versus discount. It was presumably based on pack sizes which meant the mid-tier was matched up with Aldi.
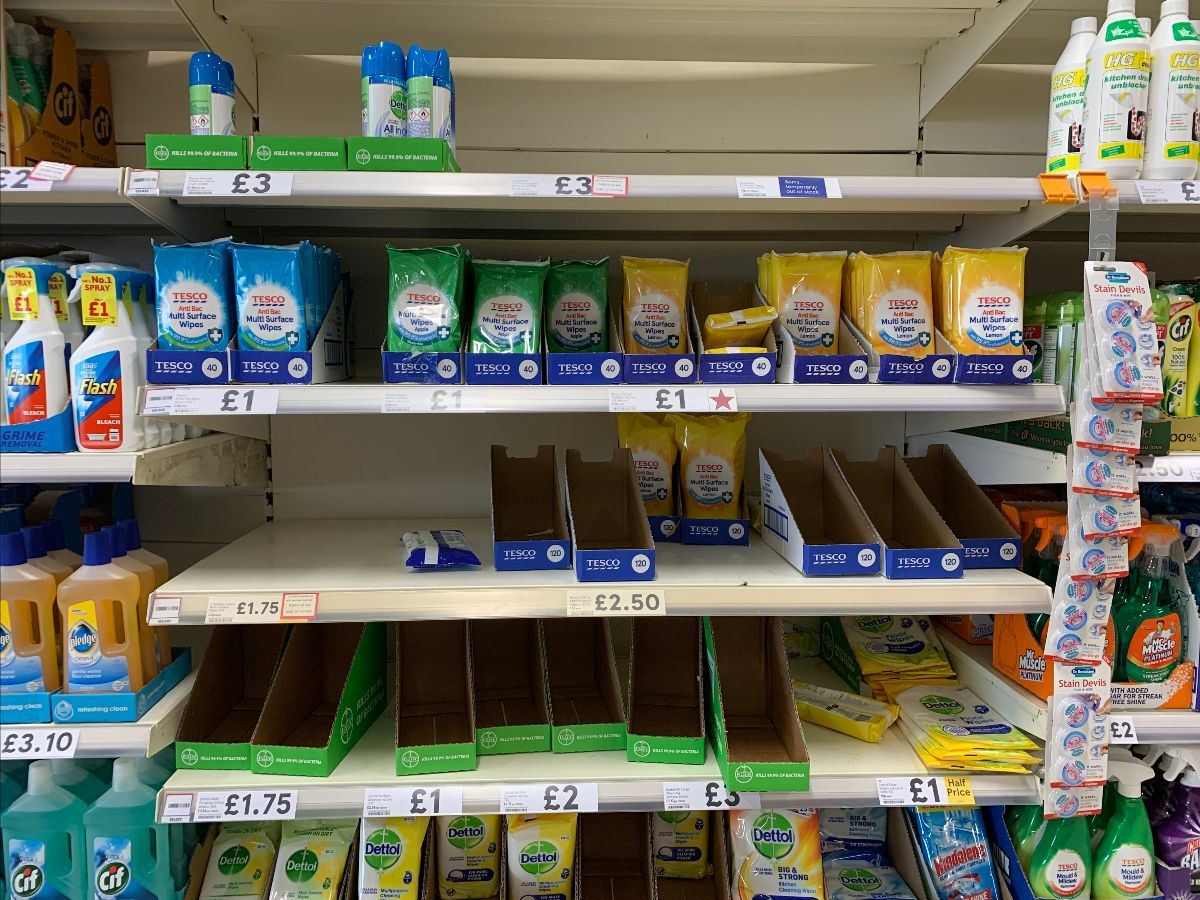
As a side Corona-virus based note, there was plenty of toilet paper in-store today and handwash had been replenished too (despite gaps).
One product consideration that had missed the headlines were anti-bacterial wipes, Dettol was out of stock (their packaging online notes that these kill Coronavirus) and the online shoppers had nearly emptied the shelves.
The future remains bright (to an extent) for brands clearly.....
However with the own-label push in Tesco, versus Aldi, indicates that the pain will continue for a little while yet.
For Tesco - their work on private label brands (entry too) means that they're in a great position to push this scheme in-store and underline their value credentials here.
They're merely advertising what they have been doing anyway; albeit under the radar. With the discounters (let's not forget Lidl here) adding more brands in their central 'special buys' space due to brands not really knowing what to do about the elephant in the room.
That is growth engines selling own-label products or cut-price branded products.
Will it be margin dilutive? Potentially, as sales may shift into Aldi matched brands but the volume swing is what we'll be looking for, to see the growth and belief in the strategy.
Whether that's switching from higher-margin products, or whether customers are switching their shopping from Aldi, or Lidl into Tesco. Which would be a win-win for Tesco.
It's a strong piece of work from Tesco and credit to them for it, they've pioneered a lot of things versus discount and have arguably been the only one to really strike back in a significant way.
Especially given the overhead signage war in store (with Aldi continually comparing their baskets and products against Tesco).
It's very interesting for sure. More on this, Ireland and price in general next week for our long read.
Want to see all the images from this launch, and 200,000 others?
From the Grocery Insight newsletter archive, first sent to subscribers on 5 March 2020. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.