Tesco prices in Health and Beauty
23 June 2020
To visit Belle's JustGiving page
The Bulletin - Tesco's latest price salvo
Firstly, thank you to all from Mrs D, and I, for your kind donations to Belle's JustGiving page, we have tipped over £2,000 for the hospital now which is tremendous and means we'll be able to do lots for the midwives and team at Airedale hospital and allow Belle's memory to live on.
Before lockdown, Tesco landed their price match campaign versus Aldi, reminiscent of the work that had gone in Tesco Ireland, matching versus Aldi and Lidl across the entire shop almost, with focus on lowering prices in line with discounters to eliminate the gap, no matter how low they go.
There were examples of Cream Crackers dropping to 14c, with Tesco following discounters in on price before the price rose again. It was expensive for the like for likes (given sales values went down, at Christmas e.g. with the 9c Produce etc) but the volume growth was there for all to see, highlighting that the strategy worked.
It's the only way to combat discounters and this, alongside a competitive market in Ireland (with Dunnes and Supervalu also differentiated) meant the discounters have found it hard going in Ireland with competition coming from all angles.
A clear strategy with a quick to understand sales pitch and marketing message means customers understand what is being said to them and crucially, they believe it when they checkout and see the savings. Since our last visit, further iterations have been made to the strapline and campaign, but the underlying message remains key and customers repay the chain with their loyalty.
But such campaigns are not made up overnight and it requires a steady hand in which to maintain the course, even when barometers such as like for like are negative (pointing to volumes rising e.g.) and we have seen some changes in the UK market towards EDLP but we are still some way from the pure message that Aldi operates (Lidl less so, with multibuys but still, broadly similar).
Images below show the Tesco Ireland campaigns that have been so effective in their performance versus discount but also against strong competition from Dunnes and Supervalu too.
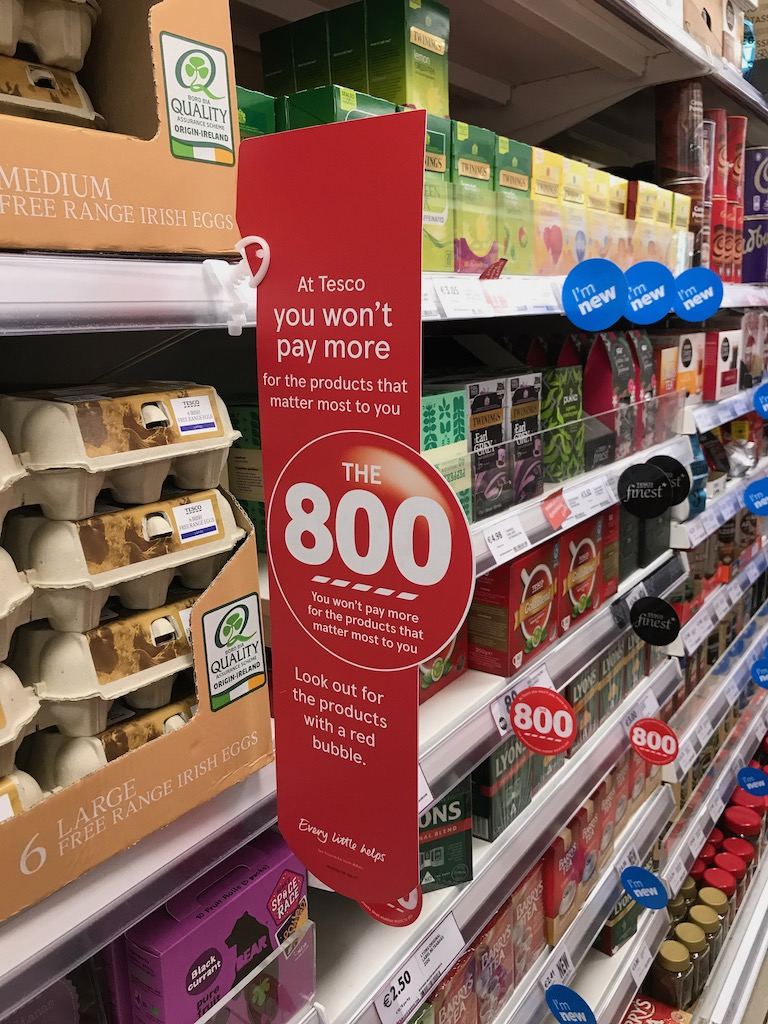
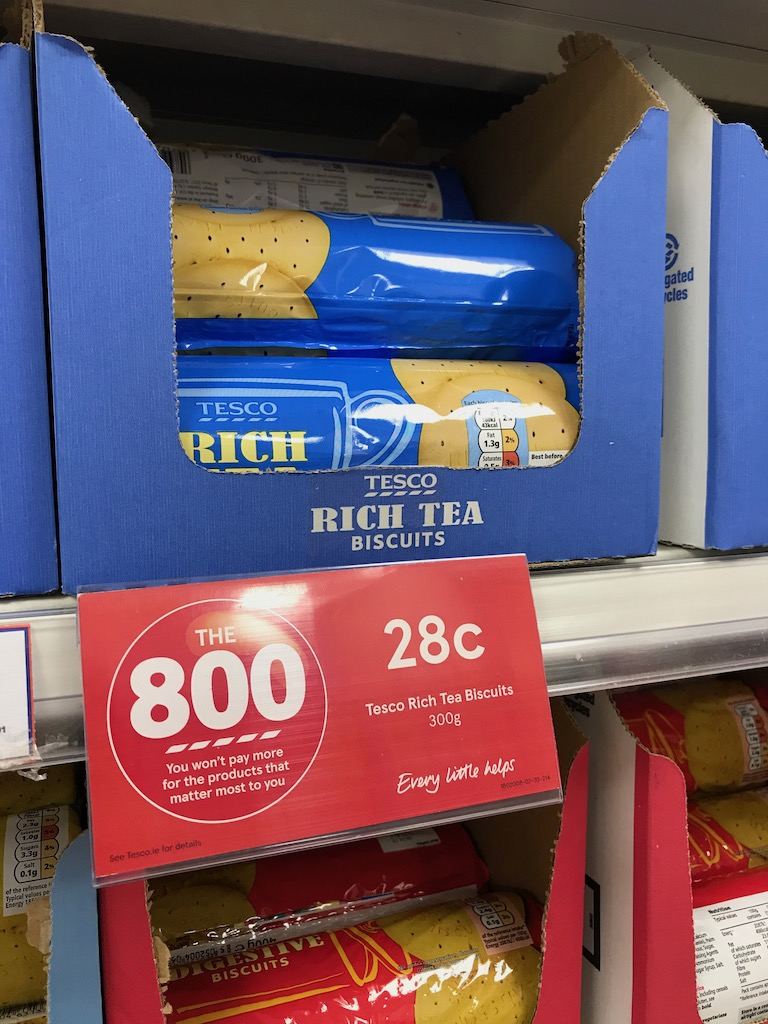
As you'll recall, Tesco has been busy building their stable of branded value items around the store with luminaries such as TE Stockwell, Creamfields (not the festival) and Growers Harvest joining the likes of Suntrail and Boswell Farm in Produce and Meat respectively. All of these replaced Everyday value across the store.
The introduction of value brands/farms in to Produce and Meat was at the time, clearly a shot against discounters who outperformed heavily in these categories when one looked at share taken from Tesco via Kantar e.g.
It's predominantly an own-label category and customers are easily able to compare a Cucumber or a Steak between Aldi and Tesco, therefore large price gaps are unforgivable and immediately put the larger retailer on the back foot for the rest of the shop. Multibuys are not permitted either and the focus is purely on price, which is why the value/farm brands came in.
Of course, it deflates the category and indeed, the own label, the mid-tier product can be lost as what does that stand for? However 'winning together' and capturing a larger share of the basket, due to lower prices in Produce and Meat means the overall game is a longer-term one.
So with value brands quietly changing over a period of 12 months or so, it was expected that a similar campaign may occur in these areas versus Aldi, and allow Tesco to compare itself with the discounters and highlight where things are perhaps not as expensive as one may consider.
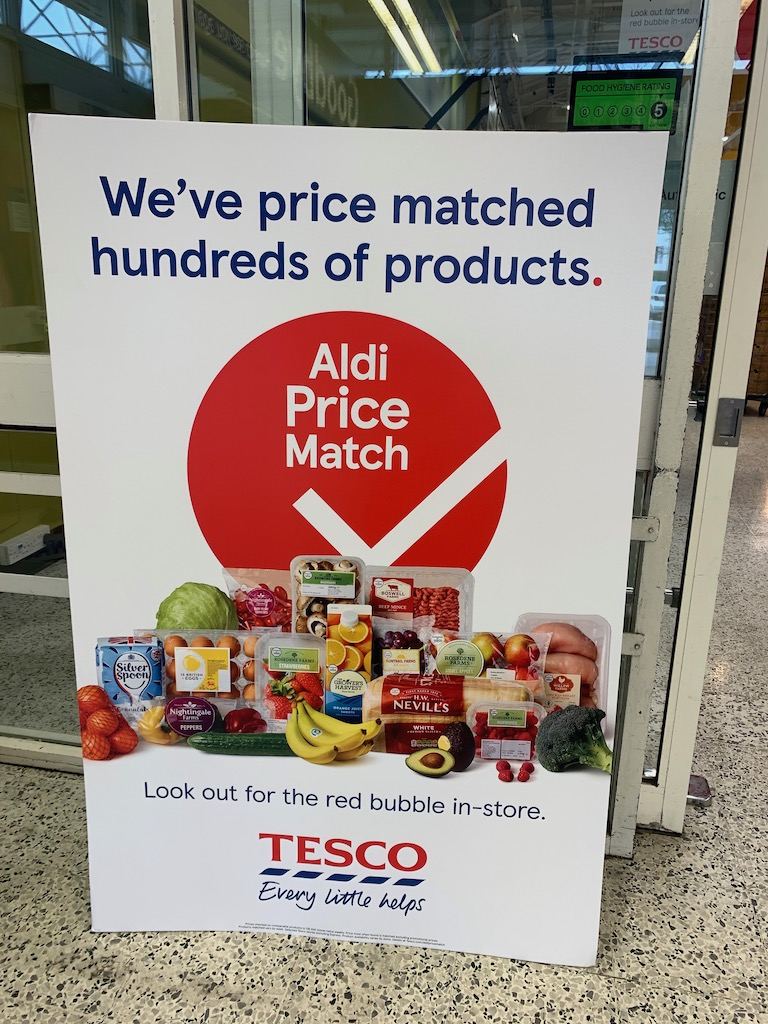
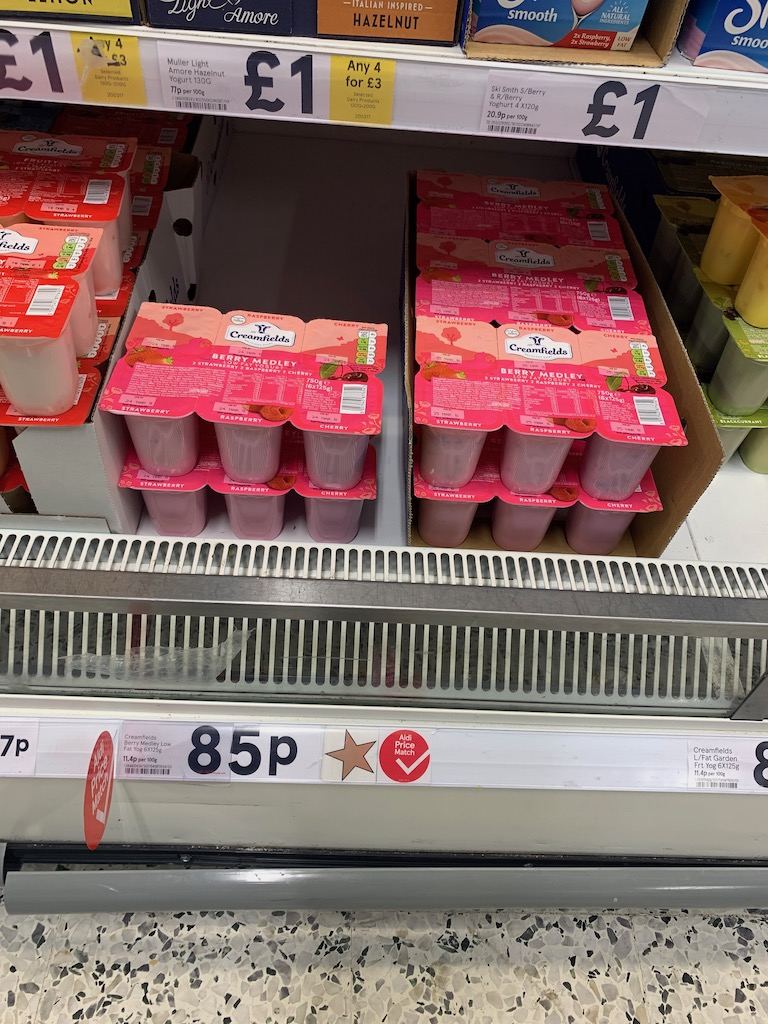
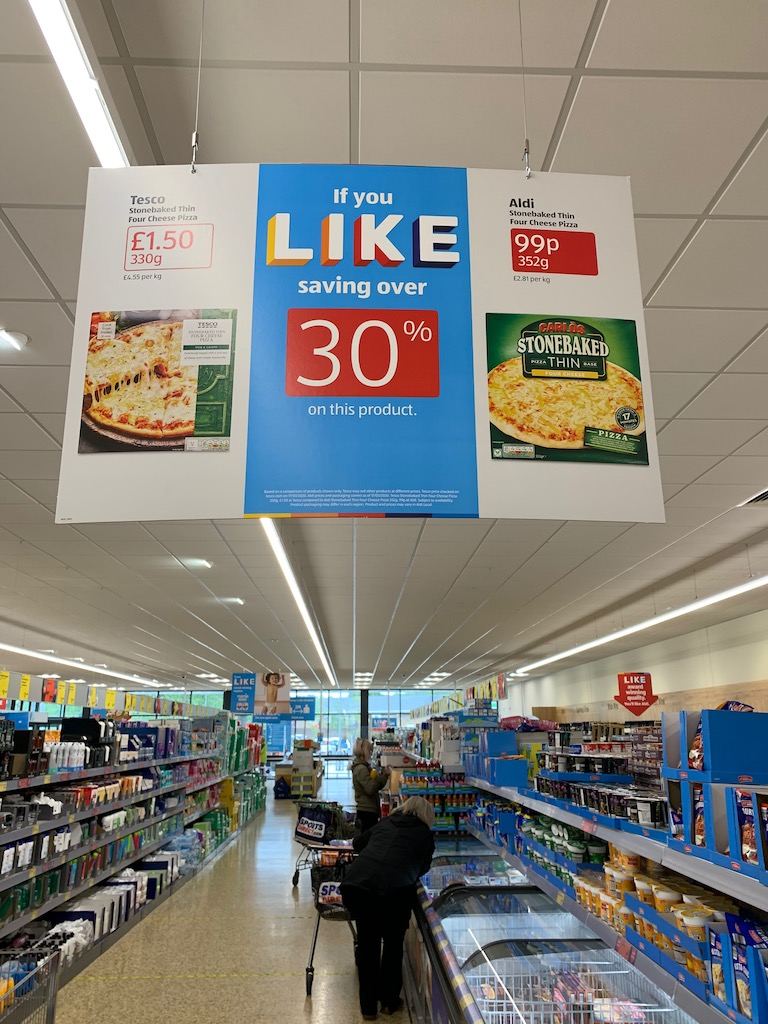
Naturally, Aldi wasn't going to take this lying down and we have seen numerous examples of signage in Aldi. comparing itself with branded products on sale in Tesco that are far more expensive than the Aldi branded product.
The ASA do get involved from time to time, but sometimes, the claims are beyond belief and customers, when looking at the detail are probably becoming aware of this. Tesco ultimately is trading their value products versus Aldi's own label mid-tier, however, the limited range from Aldi means they don't carry value tier products in many categories at all.
However when one compares a recent TV advert where a family switched shopping to Aldi from Tesco and saved over 35%, the claim (and assortment of imagery) on the TV ad required some scrutiny as it seemed high.
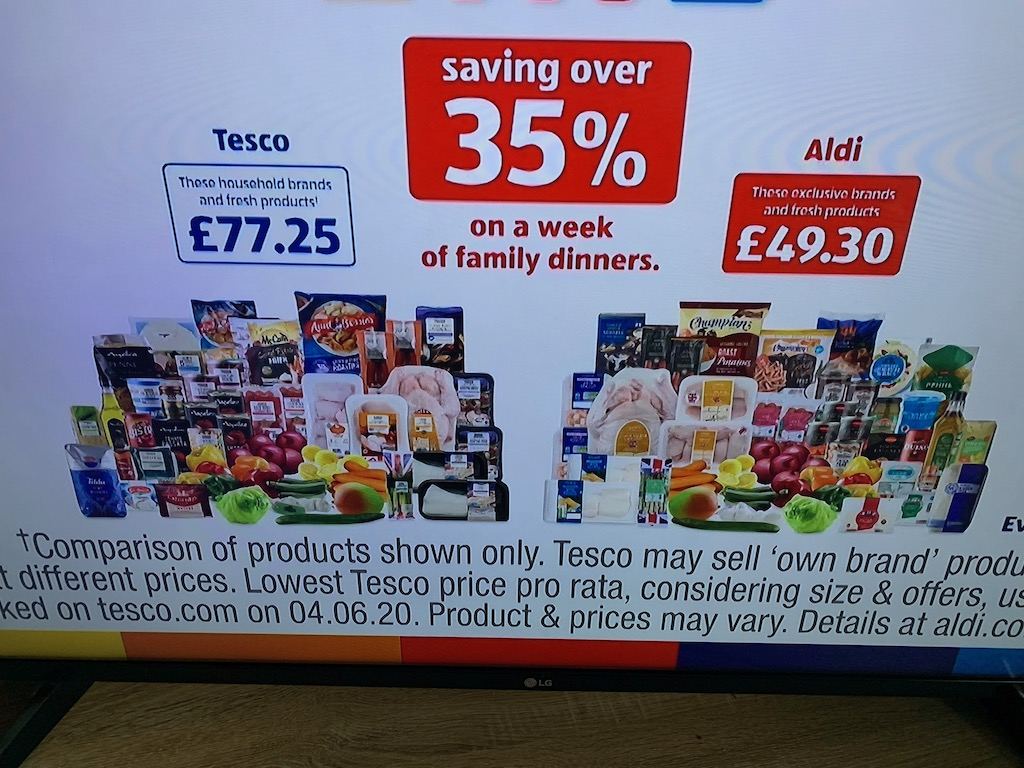
Aldi acknowledges that Tesco sell further products that are cheaper under their own brand and there's nothing materially wrong with including some brands, but the comparatives were inherently odd and it was hard to believe that a customer buying Rice, for example, would opt for Basmati Rice (Tilda) at £4.50 for 1kg when cheaper, own-label equivalents were on sale in-store.
Additionally, some of the branded items (Napolina Chopped Tomatoes e.g.) were purchased numerous times in the example which served to extend the gap, perhaps artificially so. Weights are different which can cloud things but Aldi was fair here, and on deals and included the deal price e.g. (2 for etc).
Even when including own-label equivalents, Aldi was still about £15 cheaper or so, which begs the question, why artificially increase the gap? It becomes nonsensical but the headline to a customer is 35% cheaper on a week of family dinners.
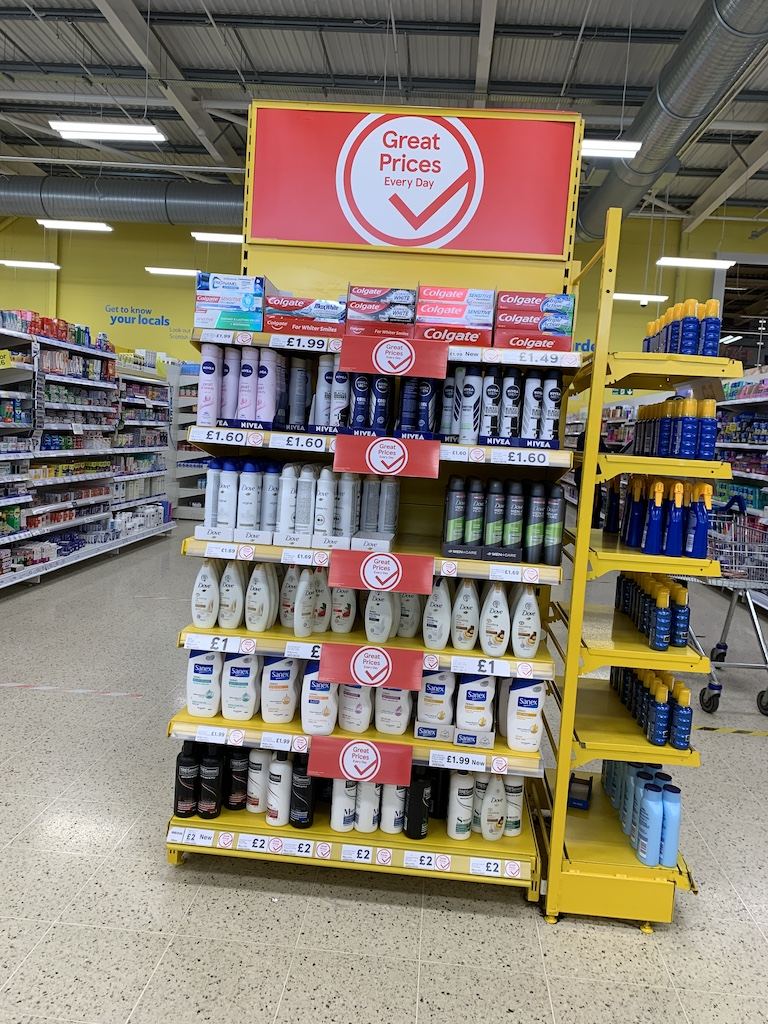
So to the Tesco price match campaign, nothing in Health & Beauty / Cosmetics etc was highlighted back in March and it was notable that this category was left out, given that both Aldi and Lidl have been adding brands to their assortment, which is madness by FMCG companies like P&G, and representative of our opinion that they have no strategy to combat discounters or variety stores.
Especially when one considers that both Aldi and Lidl imitate the leading brand in shampoo, for example, list the branded product at an EDLP price, cheaper than Asda or other retailers, but then discount put their equivalent next to it on the shelf at a lower price. Meaning the comparison is made even easier and presumably, the supplier is paying for their brand equity to be eroded as well.
Remarkable.
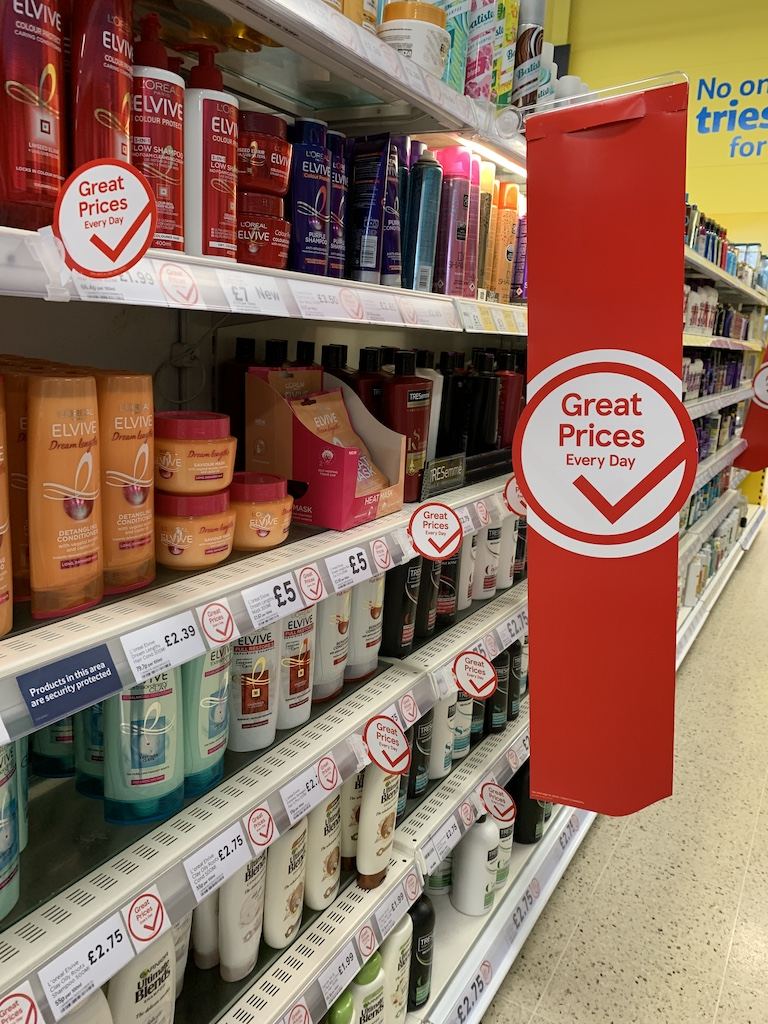
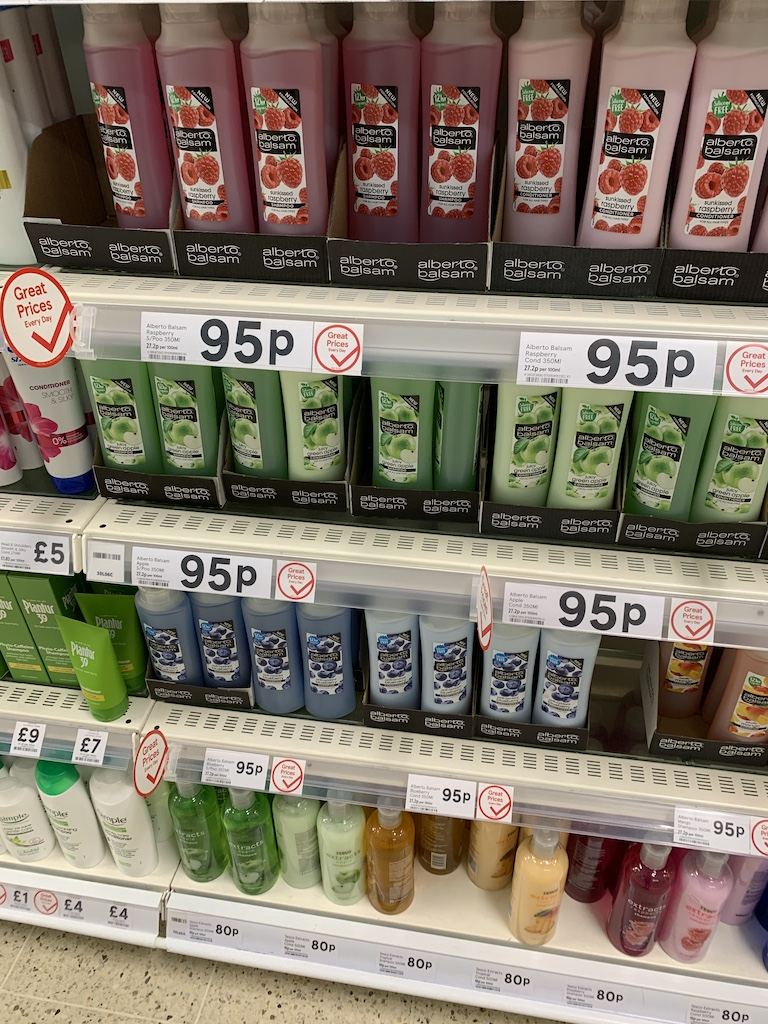
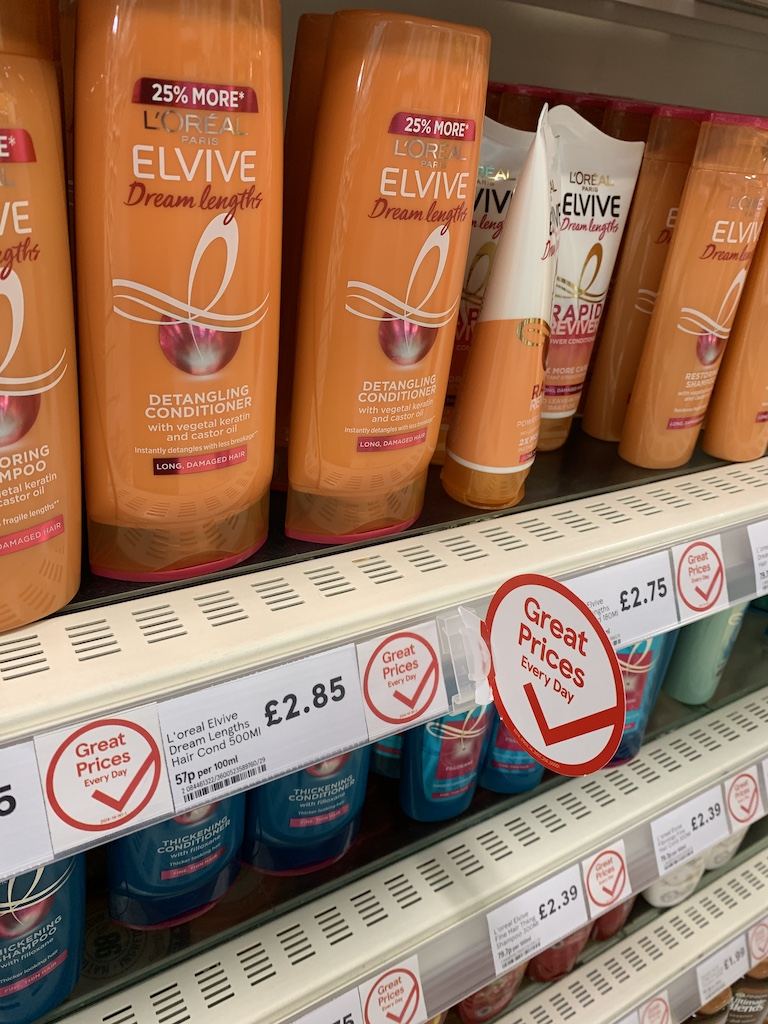
For 'great prices every day' in Health and Beauty, we are looking for the 'anchor' where Tesco are pegging their prices, it is not yet clear who it is, or whether it's general market prices. Asda is always competitive in this space (given their Walmart links) but B&M and Home Bargains especially so and it's this key category where they steal so much share and indeed, drive a better price perception on their products versus competitors.
Mainly because they stock branded lines that are easily comparable, so Tesco need to be alive in this category and one assumes, the 'great prices' campaign will mean these lines are taken out of multibuy based confusion and straight low prices.
It's another element for the customer and they'll appreciate this 'price locked' campaign almost, with health/beauty as guilty as many other categories of a high low element with promotions.
Do all roads lead to Tesco for simpler value once again? Further iterations are key as B&M et al have more in their armoury than just lower prices in Health&Beauty, but tackling this category and by the looks of it, leading brands, means that Tesco will capture more of the share in this area.
Especially as tough economic times are imminent with a date for furlough to end and a pandemic inspired recession to go through, will that keyword, "uncertainty", all around us too.
From the Grocery Insight newsletter archive, first sent to subscribers on 23 June 2020. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.