Feet on the ground - Real insight.
11 May 2014
There are other victims of a 'price drop' on core lines, whilst 3 pack Peppers suddenly become great value, the loose peppers look poor value. A further price reduction saw loose Peppers come down in price but this erodes margin without 'directing' volume to one particular product.
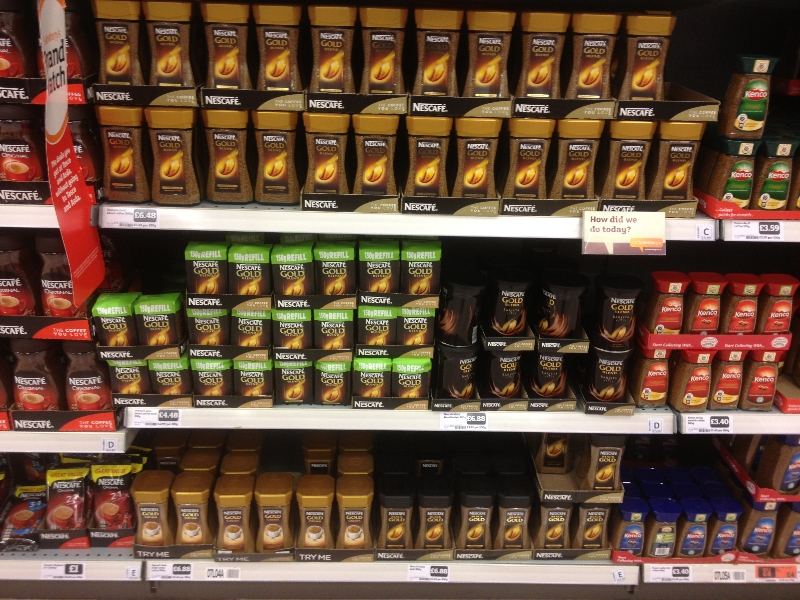
Coffee is a prime candidate for rationalisation, suppliers load in multiple pack sizes, eco refills, new products, imitation products and broadly speaking, all that sells is whatever is on promotion.
Core price of some of these lines is upwards of £6 which is too high a price when there are discount stores aplenty. Increasingly, store visits show large jars of Coffee security tagged as they are a target for shoplifters.
Space is no longer at a premium but retailers like Sainsbury's and indeed Asda should be admired for their 'less is more' approach to ranging. Backing a horse so to speak.
That said, Sainsbury's let themselves down with a completely bizarre decision to drop cans in within the main fixture. No one ever buys single cans from ambient displays, they're far better within the sandwich cabinet / impulse.
Moving on to Aldi; their seasonal / specials have become secondary to the core shop, customer flood in for the food first.
They have been relatively clever tweaking their specials too, a recent baby event effectively expanded their 'range' to incorporate core items such as Calpol and Sudocrem.
Focussing on a quick moving assortment means event such as gardening are 'in and out' within April and early May. It was noteworthy to see good reductions applied to gardening equipment to retain space.
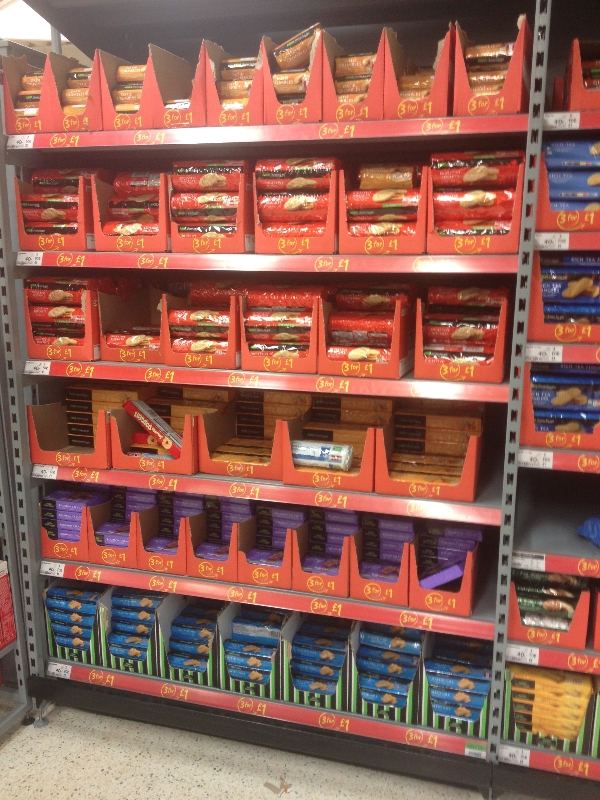
A lot of hyperbole is written about Asda and their price cuts / promotions to fight against the discounters, a store visit from some of the 'analysts' would uncover some good work to fight against the discounters.
OL Biscuits are a great example, bold PoS, shelf ready packaging and a price point mean there is real 'value' being delivered from Asda here.
Customers like it; clearly as like for likes are flat (in a declining market for the mults) and Kantar continues to look good too.
Increasingly, Asda are creating their own niche as a place to go for 'brands', away from the PL haven that is Aldi.
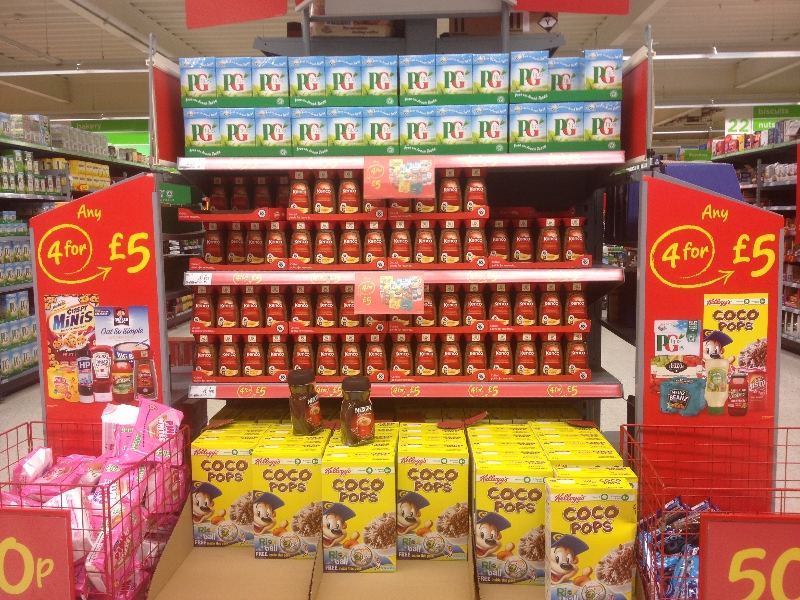
A superb 4 for £5 deal on various household items represents superb value, shows WalMart scale too via Kelloggs and Heinz.
The two 'cheaper' supermarkets; Co-Operative and Morrisons are putting their efforts behind a refined lower price campaign. This is clearly where value will be driven for them, promotions remain important for customers though.
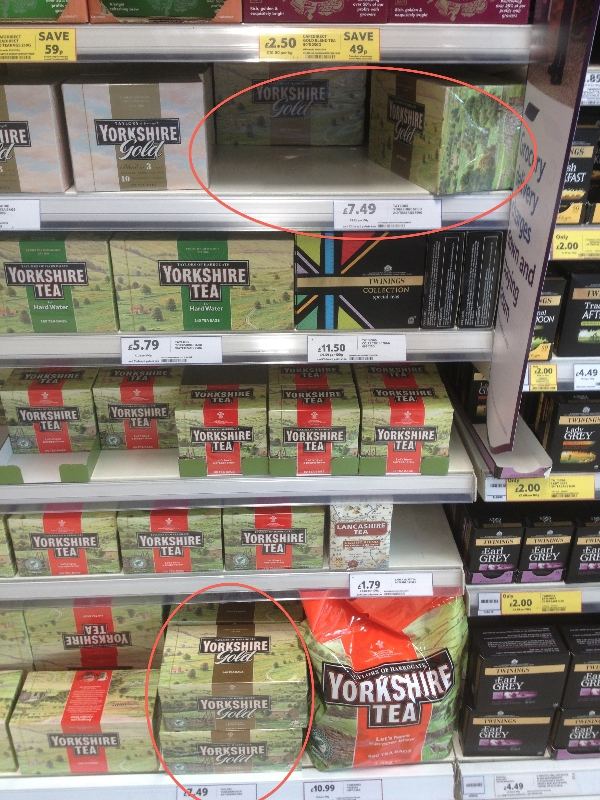
Tesco have a lot of space too, and their ranging needs work. One store has so much space, they've given Yorkshire Gold two separate facings.
On a 'ranging' note, why stock the super large bags of Tea? It just seems a complete waste of a SKU, there must be a cost attached to that within the system.
A recent range review of the Bakery from Tesco will be included within an upcoming email, (I've not forgotten about the Co-Op pricing either!) but retail moves ever quicker.
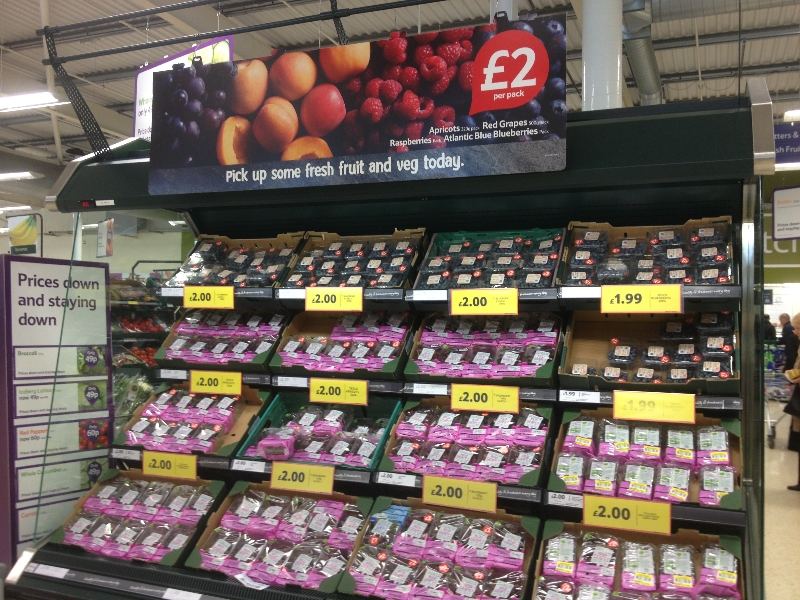
Bright Produce displays were the order of the day too, the new PoS featuring product imagery is strong and does a great job of selling the product. However, consider the £2 end; looks strong until you realise £1.99 PoS adorns two locations for Blueberries.
It's the small details.....
On Twitter there are many mentions from the Tesco army, getting behind their various initiatives around good standards, 'full and fresh' and the ubiquitous 'Making Moments Matter'.
One initiative that appears to have slowed down a little is 'One Voice' which centred around changing the tone of the in store PoS, adverts and general marketing.
Here's a free store visit report from the test bed, Bishops Stortford to review. (2.9mb for phone users).
Elements have come into store, particularly on Meat where provenance claims, pictures of farmers and the word 'British' feature.
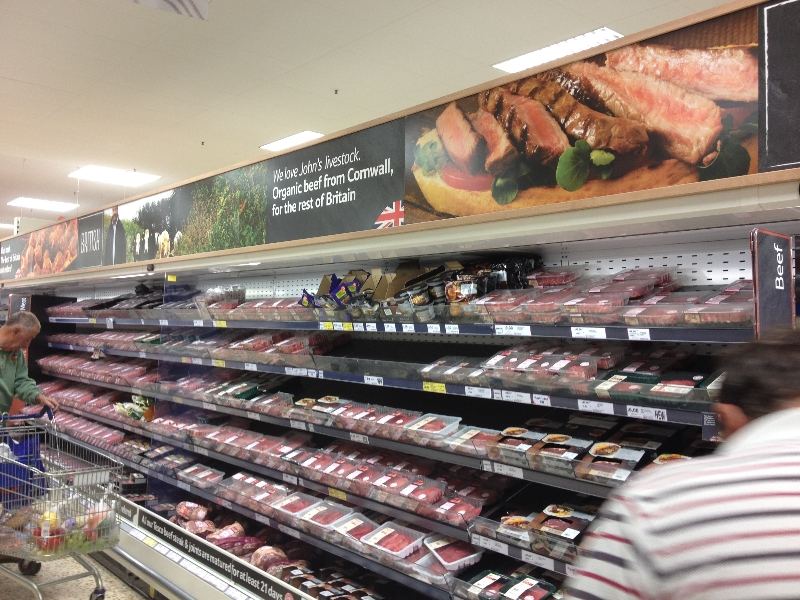
The 'look and feel' was as important as any wider 'refit' for me, the report details the developments. I felt it was a real step in the right direction, the problem is that the rollout doesn't appear to have been as widespread as one would expect.
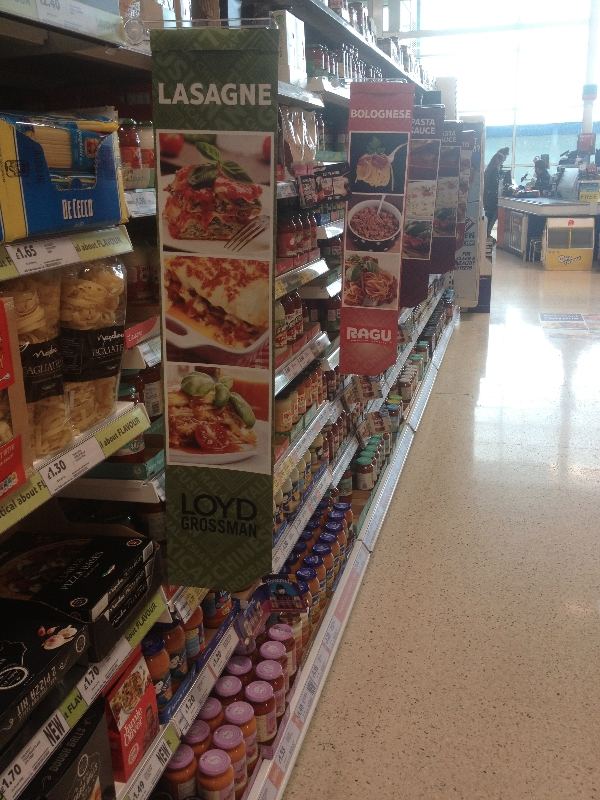
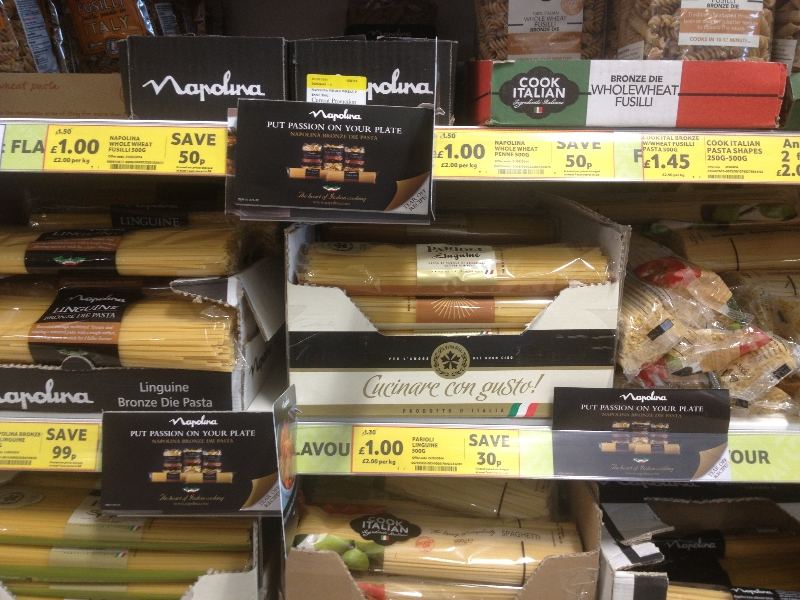
One area where 'One Voice' has been forgotten is World Foods, the customer has to be at the centre of every decision, even ahead of supplier cash for branding flags and PoS everywhere.
There is far too much noise on the aisle, it's 'all too much' for customers to take in. There is navigational signage for a category that needs some, but not all.
Customers using the World Foods aisle are likely to already cook / know what they're doing with regards to a Lasagne. Signage around country of origin helps but all this PoS isn't helpful.
Nor does it keep in line with 'one voice'. As the report shows, it's a wonderful way to communicate with customers across the shop. Supplier branded PoS on every bay, along with floor stickers, shelf edge PoS and shelf stripping isn't the way.
I know I promised this time!
The next email will consider the Co-Operative and their efforts within convenience. They're progressing very nicely and enough to suggest that unrivalled convenience growth from Tesco and Sainsbury's may come under threat from a resurgent Co-Op.
Grocery Insight offer a range of services to retailers, suppliers and investors. Looking at categories across retail to shape an upcoming range review, looking at your stores undercover to highlight areas for improvement or to provide some 'expert' insight into a project or proposal.
We can always help, our 'feet on the ground' approach means no one knows the retail market like we do.
Services range from executive / board level insight on the wider market to smaller projects covering category development or concept stores.
Don't wait for a forwarded email, get the insight delivered directly to your inbox.
From the Grocery Insight newsletter archive, first sent to subscribers on 11 May 2014. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.