Price - Not everyone can be the cheapest.
7 May 2014
Asda are unrivalled on price within the main market and their EDLP ethos wasn't fully understood, with customers seemingly preferring the raft of deals available to get a 'full trolley' elsewhere.
Again, the discounters have changed this, and one increasingly notable behaviour is that customers want stable pricing. They want to budget and know what each item costs and that there'll be little variation.
Aldi/Lidl do this very well, there are few price cuts and increases and broadly, price stability within a 1300-1500 SKU assortment is delivered well. Customers like that price stability.
The multiples are forever guilty of moving prices around, price establishment and the oft written newspaper articles about supermarkets 'ripping customers off' with 'so called deals' don't help matters.
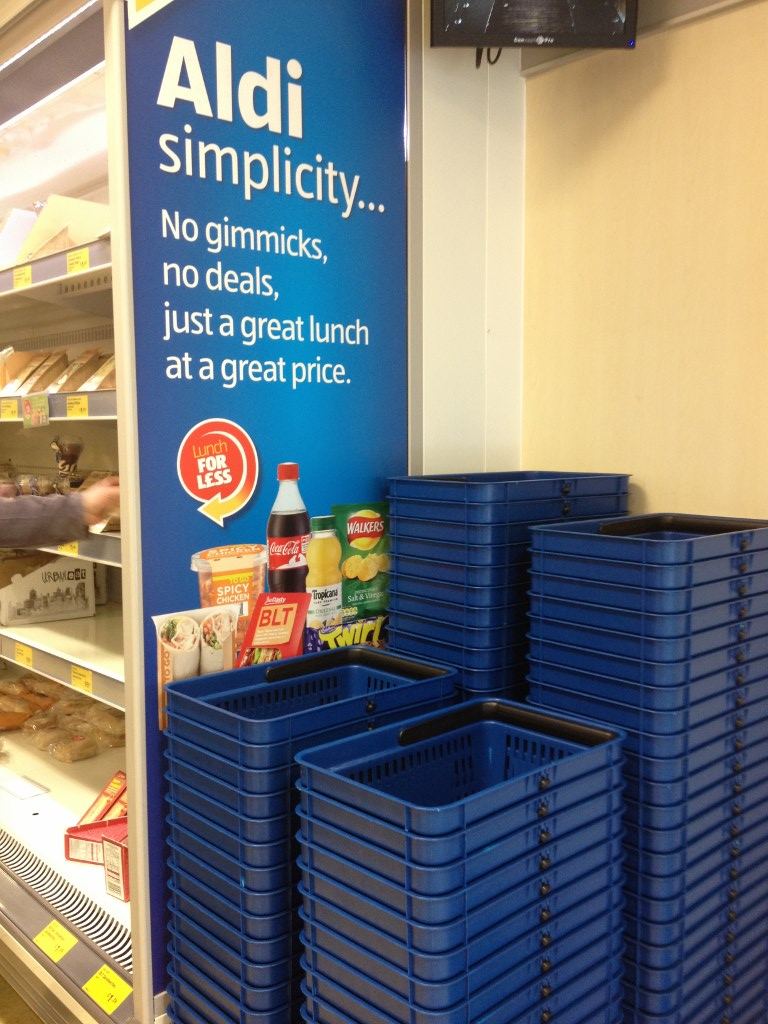
So, we are where we are. Asda being EDLP for years have now seen an upturn in their fortunes as customers prefer 'lower price', perhaps now more than ever. The discounter effect has helped them, they had to sharpen prices further which meant they widened the gap on their 3 main rivals.
Where Aldi trade on private label with very few brands, Asda is the place to go for cheaper brands and wider assortment. A bigger Aldi almost....
The preference for everyday pricing is now apparent across retail, especially given the success of the discounters.
The data analysis I conducted isn't comprehensive by any stretch, but its a sample of directly comparable lines - IE those that are available everywhere else, and are the same weight.
The results were interesting -
The lines selected saw a £21.99 reduction at Morrisons (in terms of a was / now), bringing them to be the cheapest on this selection - even including promotions.
Asda were then the next cheapest, £7 more expensive than Morrisons but £9 cheaper than Tesco and £13 from Sainsbury's. This gap will narrow as the dust settles, and Asda will respond.
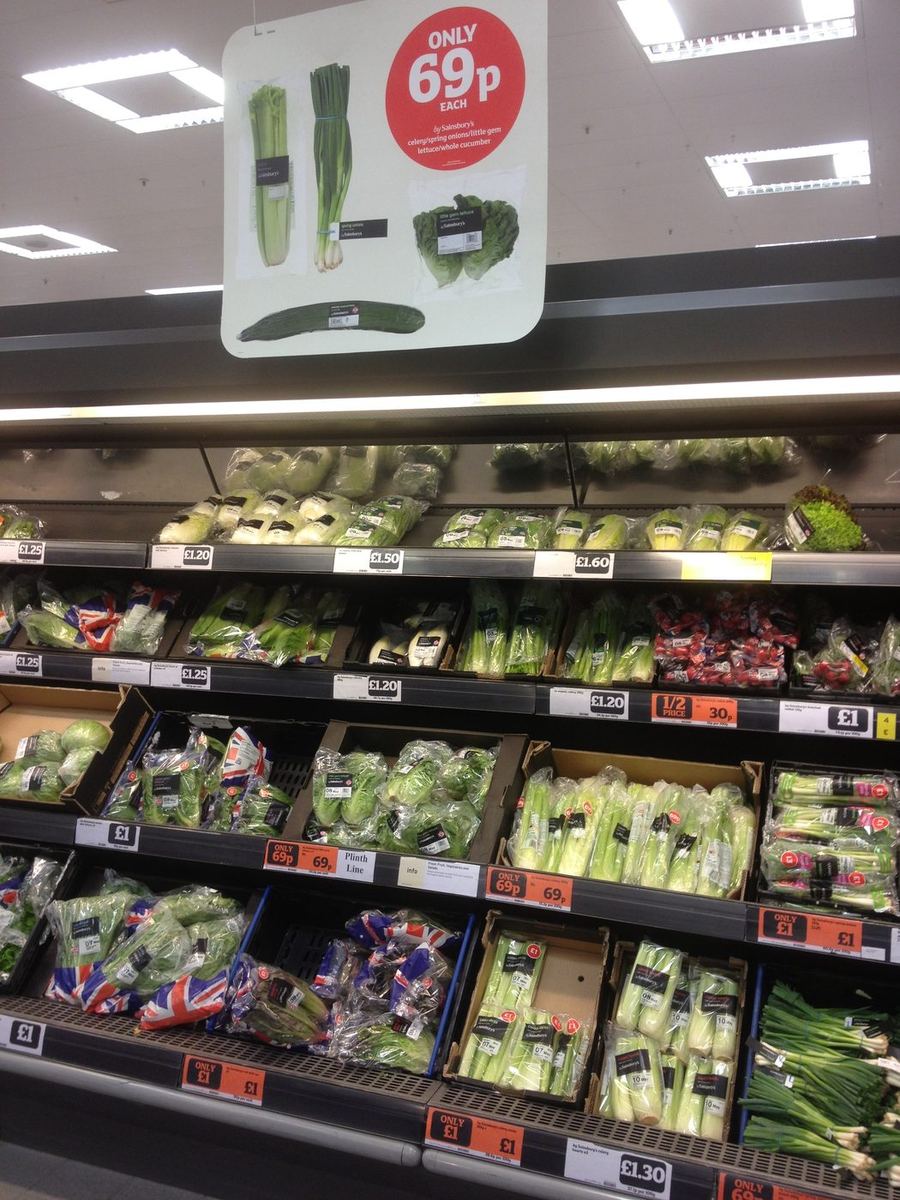
There will be detailed analysis from the likes of BrandView, and the Grocer 33 is worth keeping an eye on too. It's clear that Morrisons are trying to close the gap with Asda and their new campaign shows that initially, it's worked.
As we know price isn't everything, but it's a start. Looking at areas like Cling Film and Foil, there is no reason to be paying nearly £4 a roll of Foil, Morrisons have dropped to £1.99, with Asda following at £2. These lines are significantly cheaper elsewhere, and customers are not paying inflated prices any longer.
Tesco and Sainsbury's are (were) still pegging at £4.29 and £4 respectively and customers won't pay that. We already know customers are spreading their baskets to discounter stores as they know it's cheaper there. It's a similar tale for Health & Beauty, which is where Home Bargains / Poundland are motoring along.
There are two primary concerns for me in the market -
1) Tesco are pegging with Sainsbury's on too many lines now, they need to expand their Price Down campaign quicker and make it relevant. A £2 gap on kitchen foil is intolerable. They have to be competitive and benchmark Morrisons / Asda.
2) Sainsbury's are a mile away on own label comparisons, I know they make the case regarding their values and provenance. Morrisons control their own production facilities so their Mince is better controlled than anyone else. It's £1.01 cheaper than Sainsbury's.
Everyone now ranges British meat so whilst provenance and values are important, everyone offers it to some degree. JS are more expensive on Vegetable Oil than anyone else, that's nothing to do with values or indeed provenance.
Aldi are strong on provenance, Asda are strong on provenance so whilst it's a differentiator - it's becoming 'noisy' in this market.
Tesco famously had a go with price drop, they'll need a similar campaign to get customers believing in the price points again. Sainsbury's will view themselves as being shielded from the cut and thrust, and to an extent they are. But with price movement, they'll have to give a little to be viewed as being competitive.
They have dialled up the coupon scheme again, we got extra bonus points if we bought Milk this week. Hardly a) aspirational b) buying something out of the ordinary, is it?
Price wise - I take the point regarding the price guarantee schemes being available - why go to Morrisons when Tesco guarantee to match, Sainsbury's brand match. In fact why go anywhere else when Asda are 10% cheaper regardless?
Price is important, but customers would rather have instant savings at the checkout, they may not want a voucher for the difference. It means another trip, what if it expires? Or they lose it?
It's not all about price, it helps customers cross the road. Of course, Tesco will be aware, for customers to benefit from their price promise scheme - they have to shop with them first.
The next email will consider the Co-Operative and their efforts within convenience. They're progressing very nicely and enough to suggest that unrivalled growth from Tesco and Sainsbury's may come under threat from a resurgent Co-Op.
Grocery Insight offer a range of services to retailers, suppliers and investors. Looking at categories across retail to shape an upcoming range review, looking at your stores undercover to highlight areas for improvement or to provide some 'expert' insight into a project or proposal.
We can always help, our 'feet on the ground' approach means no one knows the retail market like we do.
Services range from executive / board level insight on the wider market to smaller projects covering category development or concept stores.
From the Grocery Insight newsletter archive, first sent to subscribers on 7 May 2014. Steve now writes at read.groceryinsight.com. See also the blog archive and briefings.